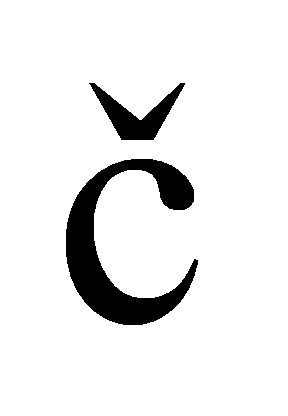
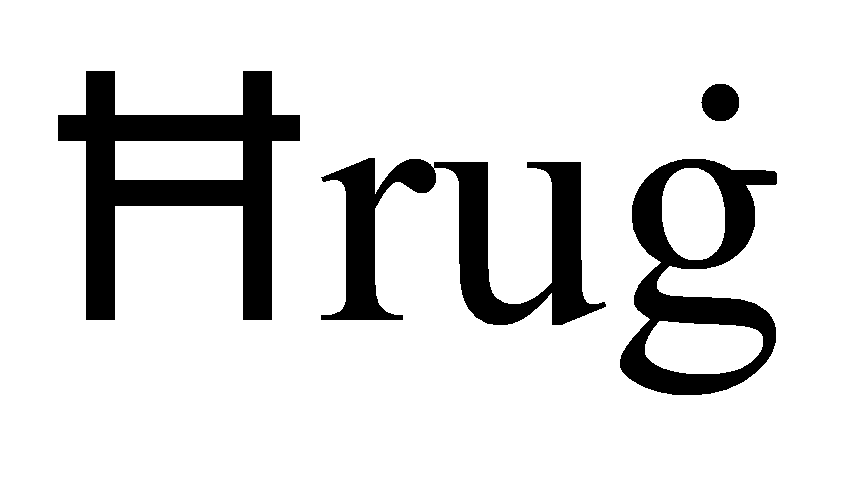
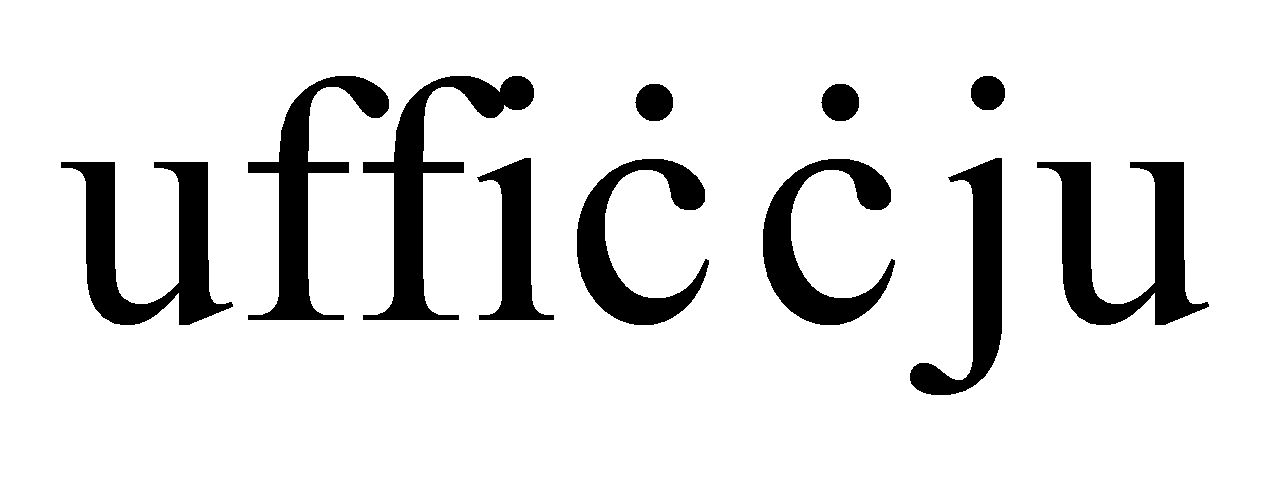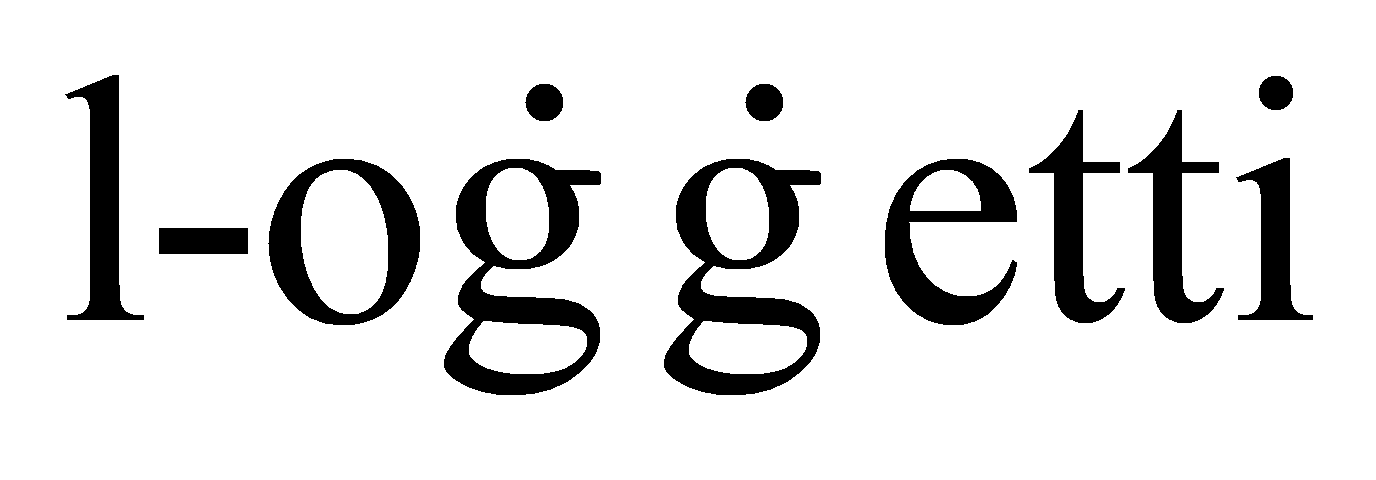---
title: "Имплементационный регламент N 2015/2447 Европейской комиссии"
number: "2015/2447"
issuer: "Европейская комиссия"
status: действует
canonical: "https://bukva.ai/docs/reglament-20152447/statya-350"
---

# Статья 350

### <a id="p102992"></a>Статья 350


<a id="p102993"></a>Настоящий Регламент вступает в силу на двадцатый день после его опубликования в Официальном Журнале Европейского Союза.
<a id="p102994"></a>Он применяется с 1 мая 2016 г.
<a id="p102995"></a>Настоящий Регламент является обязательным во всей своей полноте и непосредственно применяется во всех государствах-членах ЕС.

<a id="p102996"></a>Совершено в Брюсселе, 24 ноября 2015 г.

<a id="p102997"></a>За Европейскую Комиссию
Председатель
**JEAN-CLAUDE JUNCKER**


<a id="p102998"></a>Приложение A

<a id="p102999"></a>**ФОРМЫ И КОДЫ ТРЕБОВАНИЙ**
**К ОБЩИМ ДАННЫМ ДЛЯ ЗАЯВЛЕНИЙ И РЕШЕНИЙ**

<a id="p103000"></a>**ОБЩИЕ ПОЛОЖЕНИЯ**

1. <a id="p103001"></a>Положения, включенные в настоящие примечания, применяются ко всем Титулам настоящего Приложения.
2. <a id="p103002"></a>Формы, коды и, если это применимо, структура требований к данным, включенные в настоящее Приложение, применяются в отношении требований к данным для заявлений и решений, предусмотренных в Приложении A к Делегированному Регламенту (ЕС) 2015/2446.
3. <a id="p103003"></a>Формы и коды, определенные в настоящем Приложении, применяются к заявлениям и решениям, составленным с использованием электронной технологии обработки данных, а также к заявлениям и решениям, составленным на бумажных носителях.
4. <a id="p103004"></a>[Титул I](https://bukva.ai/docs/reglament-20152447/statya-350#p103029) включает в себя формы элементов данных.
5. <a id="p103005"></a>Когда информация в заявлении или решении, рассматриваемом в Приложении A к Делегированному Регламенту (ЕС) 2015/2446, принимает форму кодов, применяется список кодов, предусмотренный в [Титуле II](https://bukva.ai/docs/reglament-20152447/statya-350#p104030).
6. <a id="p103006"></a>Размер элемента данных не препятствует тому, чтобы заявитель представил достаточную информацию. Если необходимые сведения не подходят данной форме элементов данных, используются дополнения.
7. <a id="p103007"></a>Термин "тип/длина" в разъяснении элемента указывает на требование для типа данных и длины данных. Коды для типов данных следующие:
<a id="p103008"></a>a - буквенный;
<a id="p103009"></a>n - цифровой;
<a id="p103010"></a>an - буквенно-цифровой.
<a id="p103011"></a>Число, следующее за кодом, указывает на допустимую длину данных. Применяется следующее:
<a id="p103012"></a>Дополнительные две точки перед индикатором длины означают, что данные не имеют фиксированной длины, но они могут иметь длину до количества знаков, определенных индикатором длины. Запятая в длине данных означает, что элемент может содержать десятые доли, знаки до запятой указывают общую длину элемента, знаки после запятой указывают максимальное количество знаков после десятичного знака.
<a id="p103013"></a>Примеры длины и формы поля:
<a id="p103014"></a>a1 - 1 буквенный знак, фиксированная длина;
<a id="p103015"></a>n2 - 2 цифровых знака, фиксированная длина;
<a id="p103016"></a>an3 - 3 буквенно-цифровых знака, фиксированная длина;
<a id="p103017"></a>a..4 - до 4 буквенных знаков;
<a id="p103018"></a>n..5 - до 5 цифровых знаков;
<a id="p103019"></a>an..6 - до 6 буквенно-цифровых знаков;
<a id="p103020"></a>n..7,2 - до 7 цифровых знаков, в том числе максимально 2 десятичных знака, ограничителю разрешено "плавать".
8. <a id="p103021"></a>Аббревиатуры и сокращения, используемые в Приложении, интерпретируются следующим образом:


| <a id="p103022"></a>Аббревиатура/сокращение | <a id="p103023"></a>Значение |
| --- | --- |
| <a id="p103024"></a>D.E. | <a id="p103025"></a>Элемент данных |
| <a id="p103026"></a>n.a. | <a id="p103027"></a>Не применяется |


9. <a id="p103028"></a>Количество элементов указывает на максимально возможное количество повторений указанного элемента данных в заявлении или решении.

<a id="p103029"></a>**ТИТУЛ I. ФОРМАТЫ ТРЕБОВАНИЙ К ОБЩИМ ДАННЫМ**
**ДЛЯ ЗАЯВЛЕНИЙ И РЕШЕНИЙ**


<table>
<colgroup><col width="11%"><col width="8%"><col width="20%"><col width="23%"><col width="13%"><col width="8%"><col width="18%"></colgroup>
<tr><td><a id="p103030"></a>Ссылка на Титул в Приложении A к Делегированному Регламенту (ЕС) 2015/2446</td><td><a id="p103031"></a>Порядковый номер D.E.</td><td><a id="p103032"></a>Название D.E.</td><td><a id="p103033"></a>Формат D.E.<br>(Тип/длина)</td><td><a id="p103034"></a>Количество элементов</td><td><a id="p103035"></a>Список кодов в <a href="#p104030">Титуле II</a><br>(Y (да)/N (нет))</td><td><a id="p103036"></a>Примечания</td></tr>
<tr><td><a id="p103037"></a>Титул I</td><td><a id="p103038"></a>1/1</td><td><a id="p103039"></a>Тип кода заявления/решения</td><td><a id="p103040"></a>an..4</td><td><a id="p103041"></a>1x</td><td><a id="p103042"></a>Y</td><td></td></tr>
<tr><td><a id="p103043"></a>Титул I</td><td><a id="p103044"></a>1/2</td><td><a id="p103045"></a>Подпись/аутентификация</td><td><a id="p103046"></a>an..256</td><td><a id="p103047"></a>1x</td><td><a id="p103048"></a>N</td><td></td></tr>
<tr><td><a id="p103049"></a>Титул I</td><td><a id="p103050"></a>1/3</td><td><a id="p103051"></a>Тип заявления</td><td><a id="p103052"></a>Код: n1+ (если применяется)<br>Номер решения:<br>- код страны: a2+<br>- тип кода решения: an..4+<br>- номер: an..29</td><td><a id="p103053"></a>1x</td><td><a id="p103054"></a>Y</td><td></td></tr>
<tr><td><a id="p103055"></a>Титул I</td><td><a id="p103056"></a>1/4</td><td><a id="p103057"></a>Географическое действие - Союз</td><td><a id="p103058"></a>Код: n1+ (если применяется)<br>Код страны: a2</td><td><a id="p103059"></a>Код ценности: 1x<br>Код страны: 99x</td><td><a id="p103060"></a>Y</td><td><a id="p103061"></a>Что касается кода страны, то используется код, определенный в Регламенте (ЕС) 1106/2012 Европейской Комиссии <a href="#p104027">&lt;*&gt;</a></td></tr>
<tr><td><a id="p103062"></a>Титул I</td><td><a id="p103063"></a>1/5</td><td><a id="p103064"></a>Географическое действие - страны общего транзита</td><td><a id="p103065"></a>Код страны: a2</td><td><a id="p103066"></a>99x</td><td><a id="p103067"></a>N</td><td><a id="p103068"></a>Что касается кода страны, то используются коды ISO 3166 alpha-2.</td></tr>
<tr><td><a id="p103069"></a>Титул I</td><td><a id="p103070"></a>1/6</td><td><a id="p103071"></a>Номер решения</td><td><a id="p103072"></a>Код страны: a2+<br>Тип кода решения: an..4+<br>Номер: an..29</td><td><a id="p103073"></a>1x</td><td><a id="p103074"></a>Y</td><td><a id="p103075"></a>Структура определена в <a href="#p104030">Титуле II</a>.</td></tr>
<tr><td><a id="p103076"></a>Титул I</td><td><a id="p103077"></a>1/7</td><td><a id="p103078"></a>Таможенный орган, принимающий решение</td><td><a id="p103079"></a>Кодировано: an8<br>ИЛИ<br>Название: an..70+<br>Улица и номер: an..70+<br>Страна: a2+<br>Почтовый индекс: an..9+<br>Город: an..35</td><td><a id="p103080"></a>1x</td><td><a id="p103081"></a>N</td><td><a id="p103082"></a>Структура кодов определена в <a href="#p104030">Титуле II</a>.</td></tr>
<tr><td><a id="p103083"></a>Титул I</td><td><a id="p103084"></a>2/1</td><td><a id="p103085"></a>Другие заявления и решения, относящиеся к имеющейся обязательной информации</td><td><a id="p103086"></a>Графа для галочки: n1+<br>Страна заявления: a2+<br>Место заявления: an..35+<br>Дата заявления: n8 (ггггммдд)+<br>Номер решения: a2 (код страны) + an..4 (тип кода решения) + an..29 (номер) +<br>Дата начала решения: n8 (ггггддмм) +<br>Код товара: an..22</td><td><a id="p103087"></a>Графа для галочки: 1x<br>Другие: 99x</td><td><a id="p103088"></a>N</td><td></td></tr>
<tr><td><a id="p103089"></a>Титул I</td><td><a id="p103090"></a>2/2</td><td><a id="p103091"></a>Решения, относящиеся к обязательной информации, выданной другим пользователям</td><td><a id="p103092"></a>Графа для галочки: n1+<br>Номер решения: a2 (код страны) + an..4 (тип кода решения) + an..29 (номер) +<br>Дата начала решения: n8 (ггггддмм) +<br>Код товара: an..22</td><td><a id="p103093"></a>Графа для галочки: 1x<br>Другие: 99x</td><td><a id="p103094"></a>N</td><td></td></tr>
<tr><td><a id="p103095"></a>Титул I</td><td><a id="p103096"></a>2/3</td><td><a id="p103097"></a>Правовые или административные процедуры, ожидающие или переданные</td><td><a id="p103098"></a>Код страны: a2+<br>Название суда: an..70+<br>Адрес суда:<br>Улица и номер: an..70+<br>Страна: a2+<br>Почтовый индекс: an..9+<br>Город: an..35<br>Ссылка на правовую и/или административную процедуру: an..512</td><td><a id="p103099"></a>99x</td><td><a id="p103100"></a>N</td><td></td></tr>
<tr><td><a id="p103101"></a>Титул I</td><td><a id="p103102"></a>2/4</td><td><a id="p103103"></a>Прилагаемые документы</td><td><a id="p103104"></a>Общее количество документов: n..3+<br>Тип документа: an..70+<br>Идентификатор документа: an..35+<br>Дата документа: n8 (ггггддмм)</td><td><a id="p103105"></a>1x<br>999x</td><td></td><td></td></tr>
<tr><td><a id="p103106"></a>Титул I</td><td><a id="p103107"></a>2/5</td><td><a id="p103108"></a>Идентификационный номер склада хранения</td><td><a id="p103109"></a>an..35</td><td><a id="p103110"></a>999x</td><td><a id="p103111"></a>N</td><td></td></tr>
<tr><td><a id="p103112"></a>Титул I</td><td><a id="p103113"></a>3/1</td><td><a id="p103114"></a>Заявитель/Владелец разрешения или решения</td><td><a id="p103115"></a>Имя/название: an..70+<br>Улица и номер: an..70+<br>Страна: a2+<br>Почтовый индекс: an..9+<br>Город: an..35</td><td><a id="p103116"></a>1x</td><td><a id="p103117"></a>N</td><td></td></tr>
<tr><td><a id="p103118"></a>Титул I</td><td><a id="p103119"></a>3/2</td><td><a id="p103120"></a>Идентификация Заявителя/Владельца разрешения или решения</td><td><a id="p103121"></a>an..17</td><td><a id="p103122"></a>1x</td><td><a id="p103123"></a>N</td><td></td></tr>
<tr><td><a id="p103124"></a>Титул I</td><td><a id="p103125"></a>3/3</td><td><a id="p103126"></a>Представитель:</td><td><a id="p103127"></a>Имя/название: an..70+<br>Улица и номер: an..70+<br>Страна: a2+<br>Почтовый индекс: an..9+<br>Город: an..35</td><td><a id="p103128"></a>1x</td><td><a id="p103129"></a>N</td><td></td></tr>
<tr><td><a id="p103130"></a>Титул I</td><td><a id="p103131"></a>3/4</td><td><a id="p103132"></a>Идентификация представителя</td><td><a id="p103133"></a>an..17</td><td><a id="p103134"></a>1x</td><td><a id="p103135"></a>N</td><td></td></tr>
<tr><td><a id="p103136"></a>Титул I</td><td><a id="p103137"></a>3/5</td><td><a id="p103138"></a>Имя и сведения для контакта лица, ответственного за таможенные вопросы</td><td><a id="p103139"></a>Имя: an..70+<br>Номер телефона: an..50+<br>Номер факса: an..50+<br>Адрес эл. почты: an..50</td><td><a id="p103140"></a>1x</td><td><a id="p103141"></a>N</td><td></td></tr>
<tr><td><a id="p103142"></a>Титул I</td><td><a id="p103143"></a>3/6</td><td><a id="p103144"></a>Контактное лицо, ответственное за заявление</td><td><a id="p103145"></a>Имя: an..70+<br>Номер телефона: an..50+<br>Номер факса: an..50+<br>Адрес эл. почты: an..50</td><td><a id="p103146"></a>1x</td><td><a id="p103147"></a>N</td><td></td></tr>
<tr><td><a id="p103148"></a>Титул I</td><td><a id="p103149"></a>3/7</td><td><a id="p103150"></a>Лицо, являющееся руководителем компании заявителя или осуществляющее контроль за ее управлением</td><td><a id="p103151"></a>Имя: an..70+<br>Улица и номер: an..70+<br>Страна: a2+<br>Почтовый индекс: an..9+<br>Город: an..35+<br>Национальный идентификационный номер: an..35+<br>Дата рождения: n8 (ггггддмм)</td><td><a id="p103152"></a>99x</td><td><a id="p103153"></a>N</td><td></td></tr>
<tr><td><a id="p103154"></a>Титул I</td><td><a id="p103155"></a>3/8</td><td><a id="p103156"></a>Владелец товаров</td><td><a id="p103157"></a>Имя: an..70+<br>Улица и номер: an..70+<br>Страна: a2+<br>Почтовый индекс: an..9+<br>Город: an..35</td><td><a id="p103158"></a>99x</td><td><a id="p103159"></a>N</td><td></td></tr>
<tr><td><a id="p103160"></a>Титул I</td><td><a id="p103161"></a>4/1</td><td><a id="p103162"></a>Место</td><td><a id="p103163"></a>n.a.</td><td></td><td><a id="p103164"></a>N</td><td><a id="p103165"></a>Элемент данных, используемый только в заявлениях и решениях на бумажной основе</td></tr>
<tr><td><a id="p103166"></a>Титул I</td><td><a id="p103167"></a>4/2</td><td><a id="p103168"></a>Дата</td><td><a id="p103169"></a>n8 (ггггддмм)</td><td><a id="p103170"></a>1x</td><td><a id="p103171"></a>N</td><td></td></tr>
<tr><td><a id="p103172"></a>Титул I</td><td><a id="p103173"></a>4/3</td><td><a id="p103174"></a>Место, где ведутся или доступны основные счета для таможенных целей</td><td><a id="p103175"></a>Улица и номер: an..70+<br>Страна: a2+<br>Почтовый индекс: an..9+<br>Город: an..35<br>ИЛИ<br>UN/LOCODE: an..17</td><td><a id="p103176"></a>1x</td><td><a id="p103177"></a>N</td><td><a id="p103178"></a>Если UN/LOCODE используется для определения этого места, то структура соответствует описанию, предусмотренному в <a href="https://bukva.ai/docs/16-eek-oon-evropeyskaya">Рекомендации</a> 16 ЕЭК ООН по UN/LOCODE - Коду для портов и других мест</td></tr>
<tr><td><a id="p103179"></a>Титул I</td><td><a id="p103180"></a>4/4</td><td><a id="p103181"></a>Место, где ведется отчетность</td><td><a id="p103182"></a>Улица и номер: an..70+<br>Страна: a2+<br>Почтовый индекс: an..9+<br>Город: an..35<br>ИЛИ<br>UN/LOCODE: an..17</td><td><a id="p103183"></a>99x</td><td><a id="p103184"></a>N</td><td><a id="p103185"></a>Если UN/LOCODE используется для определения этого места, то структура соответствует описанию, предусмотренному в <a href="https://bukva.ai/docs/16-eek-oon-evropeyskaya">Рекомендации</a> 16 ЕЭК ООН по UN/LOCODE - Коду для портов и других мест</td></tr>
<tr><td colspan="7"><a id="p103186"></a><a id="p103187"></a>Титул I<br>4/5</td></tr>
<tr><td><a id="p103188"></a>Первое место использования или переработки</td><td><a id="p103189"></a>Страна: a2+</td><td>Тип кода места: a1+</td><td><a id="p103190"></a><a id="p103191"></a>Определитель идентификации: a1+<br>Кодировано:<br>Идентификация места: an..35+<br>Дополнительный идентификатор: n..3<br>ИЛИ<br>Описание в свободной форме:<br>Улица и номер: an..70+<br>Почтовый индекс: an..9+<br>Город: an..35<br>1x<br>N</td><td><a id="p103192"></a>Структура и коды, определенные в Приложении B для D.E. <a href="#p109313">5/23</a> Место товаров, используются для указания места.</td><td><a id="p103193"></a>Титул I</td><td><a id="p103194"></a>4/6</td></tr>
<tr><td><a id="p103195"></a>[По запросу] Дата начала решения</td><td><a id="p103196"></a>n8 (ггггммдд)</td><td>ИЛИ</td><td><a id="p103197"></a><a id="p103198"></a>Свободный текст: an..512<br>1x<br>N</td><td></td><td><a id="p103199"></a>Титул I</td><td><a id="p103200"></a>4/7</td></tr>
<tr><td><a id="p103201"></a>Дата истечения решения</td><td><a id="p103202"></a>n8 (ггггммдд)</td><td><a id="p103203"></a>1x</td><td><a id="p103204"></a>N</td><td></td><td><a id="p103205"></a>Титул I</td><td><a id="p103206"></a>4/8</td></tr>
<tr><td><a id="p103207"></a>Место товаров</td><td><a id="p103208"></a>Страна: a2+</td><td>Тип кода места: a1+</td><td><a id="p103209"></a><a id="p103210"></a>Определитель идентификации: a1+<br>Кодировано:<br>Идентификация места: an..35+<br>Дополнительный идентификатор: n..3<br>ИЛИ<br>Описание в свободной форме:<br>Имя/название: an..70+<br>Улица и номер: an..70+<br>Почтовый индекс: an..9+<br>Город: an..35<br>9999x<br>N</td><td><a id="p103211"></a>Структура и коды, определенные в Приложении B для D.E. <a href="#p109313">5/23</a> Место товаров, используются для указания места.</td><td><a id="p103212"></a>Титул I</td><td><a id="p103213"></a>4/9</td></tr>
<tr><td><a id="p103214"></a>Место(а) переработки или использования</td><td><a id="p103215"></a>Страна: a2+</td><td>Тип кода места: a1+</td><td><a id="p103216"></a><a id="p103217"></a>Определитель идентификации: a1+<br>Кодировано:<br>Идентификация места: an..35+<br>Дополнительный идентификатор: n..3<br>ИЛИ<br>Описание в свободной форме:<br>Имя/название: an..70+<br>Улица и номер: an..70+<br>Почтовый индекс: an..9+<br>Город: an..35<br>999x<br>N</td><td><a id="p103218"></a>Структура и коды, определенные в Приложении B для D.E. <a href="#p109313">5/23</a> Место товаров, используются для указания места.</td><td><a id="p103219"></a>Титул I</td><td><a id="p103220"></a>4/10</td></tr>
<tr><td><a id="p103221"></a>Таможенный(ые) учреждение(я) помещения</td><td><a id="p103222"></a>an8</td><td><a id="p103223"></a>999x</td><td><a id="p103224"></a>N</td><td><a id="p103225"></a>Структура и коды определены в Титуле II для D.E. <a href="#p104164">1/7</a> Таможенный орган, принимающий решение</td><td><a id="p103226"></a>Титул I</td><td><a id="p103227"></a>4/11</td></tr>
<tr><td><a id="p103228"></a>Таможенный(ые) учреждение(я) завершения</td><td><a id="p103229"></a>an8</td><td><a id="p103230"></a>999x</td><td><a id="p103231"></a>N</td><td><a id="p103232"></a>Структура и коды определены в Титуле II для D.E. <a href="#p104164">1/7</a> Таможенный орган, принимающий решение</td><td><a id="p103233"></a>Титул I</td><td><a id="p103234"></a>4/12</td></tr>
<tr><td><a id="p103235"></a>Таможенное учреждение гарантии</td><td><a id="p103236"></a>an8</td><td><a id="p103237"></a>1x</td><td><a id="p103238"></a>N</td><td><a id="p103239"></a>Структура и коды определены в Титуле II для D.E. <a href="#p104164">1/7</a> Таможенный орган, принимающий решение</td><td><a id="p103240"></a>Титул I</td><td><a id="p103241"></a>4/13</td></tr>
<tr><td><a id="p103242"></a>Надзорное таможенное учреждение</td><td><a id="p103243"></a>an8</td><td><a id="p103244"></a>1x</td><td><a id="p103245"></a>N</td><td><a id="p103246"></a>Структура и коды определены в Титуле II для D.E. <a href="#p104164">1/7</a> Таможенный орган, принимающий решение</td><td><a id="p103247"></a>Титул I</td><td><a id="p103248"></a>4/14</td></tr>
<tr><td><a id="p103249"></a>Таможенное(ые) учреждение(я) назначения</td><td><a id="p103250"></a>an8</td><td><a id="p103251"></a>999x</td><td><a id="p103252"></a>N</td><td><a id="p103253"></a>Структура и коды определены в Титуле II для D.E. <a href="#p104164">1/7</a> Таможенный орган, принимающий решение</td><td><a id="p103254"></a>Титул I</td><td><a id="p103255"></a>4/15</td></tr>
<tr><td><a id="p103256"></a>Таможенное(ые) учреждение(я) отправления</td><td><a id="p103257"></a>an8</td><td><a id="p103258"></a>999x</td><td><a id="p103259"></a>N</td><td><a id="p103260"></a>Структура и коды определены в Титуле II для D.E. <a href="#p104164">1/7</a> Таможенный орган, принимающий решение</td><td><a id="p103261"></a>Титул I</td><td><a id="p103262"></a>4/16</td></tr>
<tr><td><a id="p103263"></a>Срок</td><td><a id="p103264"></a>n..4</td><td><a id="p103265"></a>1x</td><td><a id="p103266"></a>N</td><td></td><td><a id="p103267"></a>Титул I</td><td><a id="p103268"></a>4/17</td></tr>
<tr><td><a id="p103269"></a>Срок для завершения</td><td><a id="p103270"></a>Срок: n..2+</td><td>Графа для галочки: n1+</td><td><a id="p103271"></a><a id="p103272"></a>Текст в свободной форме: an..512<br>1x<br>N</td><td></td><td><a id="p103273"></a>Титул I</td><td><a id="p103274"></a>4/18</td></tr>
<tr><td><a id="p103275"></a>Накладная</td><td><a id="p103276"></a>Графа для галочки: n1+</td><td>Срок: n2+</td><td><a id="p103277"></a><a id="p103278"></a>Текст в свободной форме: an..512<br>1x<br>N</td><td></td><td><a id="p103279"></a>Титул I</td><td><a id="p103280"></a>5/1</td></tr>
<tr><td><a id="p103281"></a>Код товара</td><td><a id="p103282"></a>1-е подразделение (код Комбинированной номенклатуры): an..8+</td><td>2-е подразделение (подзаголовок TARIC): an2+</td><td><a id="p103283"></a>3-e подразделение (дополнительный(ые) код(ы)): an4+<br>4-е подразделение (национальный(ые) дополнительны(ые) код(ы)): an4<br>999x<br>Что касается решений в отношении обязательной информации: 1x</td><td><a id="p103284"></a>N</td><td><a id="p103285"></a>Титул I</td><td><a id="p103286"></a>5/2</td></tr>
<tr><td><a id="p103287"></a>Описание товаров</td><td><a id="p103288"></a>Текст в свободной форме: an..512</td><td>Что касается заявления и решения, относящегося к обязательной тарифной информации, формат должен быть следующим: an..2560</td><td><a id="p103289"></a>999x<br>Что касается решений в отношении обязательной информации: 1x</td><td><a id="p103290"></a>N</td><td><a id="p103291"></a>Титул I</td><td><a id="p103292"></a>5/3</td></tr>
<tr><td><a id="p103293"></a>Количество товаров</td><td><a id="p103294"></a>Единица измерения: an..4+</td><td>Количество: n..16,6</td><td><a id="p103295"></a>999x<br>Что касается решений в отношении обязательной информации: 1x</td><td><a id="p103296"></a>N</td><td><a id="p103297"></a>Титул I</td><td><a id="p103298"></a>5/4</td></tr>
<tr><td><a id="p103299"></a>Стоимость товаров</td><td><a id="p103300"></a>Валюта: a3+</td><td>Сумма: n..16.2</td><td><a id="p103301"></a><a id="p103302"></a>999x<br>N</td><td><a id="p103303"></a>Для валюты используются коды ISO-alpha-3 (ISO 4217)</td><td><a id="p103304"></a>Титул I</td><td><a id="p103305"></a>5/5</td></tr>
<tr><td><a id="p103306"></a>Ставка прибыли</td><td><a id="p103307"></a>Текст в свободной форме: an..512</td><td><a id="p103308"></a>999x</td><td><a id="p103309"></a>N</td><td></td><td><a id="p103310"></a>Титул I</td><td><a id="p103311"></a>5/6</td></tr>
<tr><td><a id="p103312"></a>Эквивалентные товары</td><td><a id="p103313"></a>Код товара: an8+</td><td>Графа для галочки: n1+</td><td><a id="p103314"></a><a id="p103315"></a>Код: n1+<br>Коммерческое качество и технические характеристики товаров: an..512<br>999x<br>N</td><td><a id="p103316"></a>Могут использоваться коды, предусмотренные для D.E. <a href="#p104172">5/8</a> Идентификация товаров в Титуле II</td><td><a id="p103317"></a>Титул I</td><td><a id="p103318"></a>5/7</td></tr>
<tr><td><a id="p103319"></a>Переработанная продукция</td><td><a id="p103320"></a>Код товара: an8+</td><td>Описание товаров: an..512</td><td><a id="p103321"></a><a id="p103322"></a>999x<br>N</td><td></td><td><a id="p103323"></a>Титул I</td><td><a id="p103324"></a>5/8</td></tr>
<tr><td><a id="p103325"></a>Идентификация товаров</td><td><a id="p103326"></a>Код: n1+</td><td>Текст в свободной форме: an..512</td><td><a id="p103327"></a><a id="p103328"></a>999x<br>Y</td><td></td><td><a id="p103329"></a>Титул I</td><td><a id="p103330"></a>5/9</td></tr>
<tr><td><a id="p103331"></a>Исключенные категории или перемещение товаров</td><td><a id="p103332"></a>an6</td><td><a id="p103333"></a>999x</td><td><a id="p103334"></a>N</td><td></td><td><a id="p103335"></a>Титул I</td><td><a id="p103336"></a>6/1</td></tr>
<tr><td><a id="p103337"></a>Запреты и ограничения</td><td><a id="p103338"></a>Текст в свободной форме: an..512</td><td><a id="p103339"></a>1x</td><td><a id="p103340"></a>N</td><td></td><td><a id="p103341"></a>Титул I</td><td><a id="p103342"></a>6/2</td></tr>
<tr><td><a id="p103343"></a>Экономические условия</td><td><a id="p103344"></a>n..2+</td><td>Текст в свободной форме: an..512</td><td><a id="p103345"></a><a id="p103346"></a>999x<br>Y</td><td></td><td><a id="p103347"></a>Титул I</td><td><a id="p103348"></a>6/3</td></tr>
<tr><td><a id="p103349"></a>Общие примечания</td><td><a id="p103350"></a>Текст в свободной форме: an..512</td><td><a id="p103351"></a>1x</td><td><a id="p103352"></a>N</td><td></td><td><a id="p103353"></a>Титул I</td><td><a id="p103354"></a>7/1</td></tr>
<tr><td><a id="p103355"></a>Вид сделки</td><td><a id="p103356"></a>Графа для галочки: n1+</td><td>Вид специальной процедуры: a..70</td><td><a id="p103357"></a><a id="p103358"></a>99x<br>N</td><td></td><td><a id="p103359"></a>Титул I</td><td><a id="p103360"></a>7/2</td></tr>
<tr><td><a id="p103361"></a>Вид таможенных процедур</td><td><a id="p103362"></a>Код процедуры: an2+</td><td>Исходящий номер решения (Код страны: a2+ вид кода решения: an..4+ исходящий номер: an..29)</td><td><a id="p103363"></a><a id="p103364"></a>99x<br>N</td><td><a id="p103365"></a>Коды, предусмотренные в Приложении B, касающиеся D.E. <a href="#p109003">1/10</a> Процедура, используются для указания вида таможенной процедуры. Если разрешение предназначено для использования в контексте процедуры транзита, то используется код "80".</td><td>Если разрешение предназначено для использования для операции временного хранения, используется код "XX".</td><td><a id="p103366"></a><a id="p103367"></a>Если разрешение предназначено для использования для операции таможенного склада, то используются следующие коды:<br>- код "XR" для государственного таможенного склада типа I;<br>- код "XS" для государственного таможенного склада типа II;<br>- код "XU" для частного таможенного склада.<br>Титул I<br>7/3</td></tr>
<tr><td><a id="p103368"></a>Вид декларации</td><td><a id="p103369"></a>Вид декларации: n1+</td><td>Исходящий номер решения (Код страны: a2+ вид кода решения: an..4+ исходящий номер: an..29)</td><td><a id="p103370"></a><a id="p103371"></a>9x<br>Y</td><td></td><td><a id="p103372"></a>Титул I</td><td><a id="p103373"></a>7/4</td></tr>
<tr><td><a id="p103374"></a>Номер операций</td><td><a id="p103375"></a>n..7</td><td><a id="p103376"></a>1x</td><td><a id="p103377"></a>N</td><td></td><td><a id="p103378"></a>Титул I</td><td><a id="p103379"></a>7/5</td></tr>
<tr><td><a id="p103380"></a>Сведения о запланированной деятельности</td><td><a id="p103381"></a>Текст в свободной форме: an..512</td><td><a id="p103382"></a>1x</td><td><a id="p103383"></a>N</td><td></td><td><a id="p103384"></a>Титул I</td><td><a id="p103385"></a>8/1</td></tr>
<tr><td><a id="p103386"></a>Вид основной бухгалтерской отчетности для таможенных целей</td><td><a id="p103387"></a>Текст в свободной форме: an..512</td><td><a id="p103388"></a>1x</td><td><a id="p103389"></a>N</td><td></td><td><a id="p103390"></a>Титул I</td><td><a id="p103391"></a>8/2</td></tr>
<tr><td><a id="p103392"></a>Вид отчетов</td><td><a id="p103393"></a>Текст в свободной форме: an..512</td><td><a id="p103394"></a>99x</td><td><a id="p103395"></a>N</td><td></td><td><a id="p103396"></a>Титул I</td><td><a id="p103397"></a>8/3</td></tr>
<tr><td><a id="p103398"></a>Доступ к данным</td><td><a id="p103399"></a>Текст в свободной форме: an..512</td><td><a id="p103400"></a>1x</td><td><a id="p103401"></a>N</td><td></td><td><a id="p103402"></a>Титул I</td><td><a id="p103403"></a>8/4</td></tr>
<tr><td><a id="p103404"></a>Пробы и т.п.</td><td><a id="p103405"></a>Графа для галочки: n1</td><td><a id="p103406"></a>1x</td><td><a id="p103407"></a>N</td><td></td><td><a id="p103408"></a>Титул I</td><td><a id="p103409"></a>8/5</td></tr>
<tr><td><a id="p103410"></a>Дополнительная информация</td><td><a id="p103411"></a>Текст в свободной форме: an..512</td><td><a id="p103412"></a>1x</td><td><a id="p103413"></a>N</td><td></td><td><a id="p103414"></a>Титул I</td><td><a id="p103415"></a>8/6</td></tr>
<tr><td><a id="p103416"></a>Гарантия</td><td><a id="p103417"></a>Графа для галочки: n1</td><td>GRN: an..24</td><td><a id="p103418"></a><a id="p103419"></a>1x<br>Y</td><td></td><td><a id="p103420"></a>Титул I</td><td><a id="p103421"></a>8/7</td></tr>
<tr><td><a id="p103422"></a>Сумма гарантии</td><td><a id="p103423"></a>Валюта: a3+</td><td>Сумма: n..16.2</td><td><a id="p103424"></a><a id="p103425"></a>1x<br>N</td><td><a id="p103426"></a>Для валюты используются коды ISO-alpha-3 (ISO 4217)</td><td><a id="p103427"></a>Титул I</td><td><a id="p103428"></a>8/8</td></tr>
<tr><td><a id="p103429"></a>Передача прав и обязательств</td><td><a id="p103430"></a>Графа для галочки: n1+</td><td>Текст в свободной форме: an..512</td><td><a id="p103431"></a><a id="p103432"></a>1x<br>N</td><td></td><td><a id="p103433"></a>Титул I</td><td><a id="p103434"></a>8/9</td></tr>
<tr><td><a id="p103435"></a>Ключевые слова</td><td><a id="p103436"></a>Текст в свободной форме: an..70</td><td><a id="p103437"></a>99x</td><td><a id="p103438"></a>N</td><td></td><td><a id="p103439"></a>Титул I</td><td><a id="p103440"></a>8/10</td></tr>
<tr><td><a id="p103441"></a>Сведения о складах хранения</td><td><a id="p103442"></a>Текст в свободной форме: an..512</td><td><a id="p103443"></a>999x</td><td><a id="p103444"></a>N</td><td></td><td><a id="p103445"></a>Титул I</td><td><a id="p103446"></a>8/11</td></tr>
<tr><td><a id="p103447"></a>Хранение товаров Союза</td><td><a id="p103448"></a>Графа для галочки: n1+</td><td>Текст в свободной форме: an..512</td><td><a id="p103449"></a><a id="p103450"></a>1x<br>N</td><td></td><td><a id="p103451"></a>Титул I</td><td><a id="p103452"></a>8/12</td></tr>
<tr><td><a id="p103453"></a>Согласие на опубликование в списке владельцев разрешения</td><td><a id="p103454"></a>Графа для галочки: n1+</td><td><a id="p103455"></a>1x</td><td><a id="p103456"></a>N</td><td></td><td><a id="p103457"></a>Титул I</td><td><a id="p103458"></a>8/13</td></tr>
<tr><td><a id="p103459"></a>Расчет суммы импортной пошлины в соответствии со Статьей 86(3) Кодекса</td><td><a id="p103460"></a>Графа для галочки: n1+</td><td><a id="p103461"></a>1x</td><td><a id="p103462"></a>N</td><td></td><td><a id="p103463"></a>Титул II</td><td><a id="p103464"></a>II/1</td></tr>
<tr><td><a id="p103465"></a>Повторная выдача решения о BTI</td><td><a id="p103466"></a>Графа для галочки: n1+</td><td>Исходящий номер решения о BTI: a2 (код страны) + an..4 (вид кода решения) +an..29 (исходящий номер)</td><td><a id="p103467"></a><a id="p103468"></a>BTI Срок действия решения: n8 (ггггммдд)+<br>Код товара: an..22<br>1x<br>N</td><td></td><td><a id="p103469"></a>Титул II</td><td><a id="p103470"></a>II/2</td></tr>
<tr><td><a id="p103471"></a>Таможенная номенклатура</td><td><a id="p103472"></a>Графа для галочки: n1+</td><td>an..70</td><td><a id="p103473"></a><a id="p103474"></a>1x<br>N</td><td></td><td><a id="p103475"></a>Титул II</td><td><a id="p103476"></a>II/3</td></tr>
<tr><td><a id="p103477"></a>Коммерческое наименование и дополнительная информация</td><td><a id="p103478"></a>Текст в свободной форме: an..2560</td><td><a id="p103479"></a>1x</td><td><a id="p103480"></a>N</td><td></td><td><a id="p103481"></a>Титул II</td><td><a id="p103482"></a>II/4</td></tr>
<tr><td><a id="p103483"></a>Обоснование классификации товаров</td><td><a id="p103484"></a>Текст в свободной форме: an..2560</td><td><a id="p103485"></a>1x</td><td><a id="p103486"></a>N</td><td></td><td><a id="p103487"></a>Титул II</td><td><a id="p103488"></a>II/5</td></tr>
<tr><td><a id="p103489"></a>Материал, представленный заявителем, на основании которого было выдано решение о BTI</td><td><a id="p103490"></a>Графа для галочки: n1</td><td><a id="p103491"></a>99x</td><td><a id="p103492"></a>N</td><td></td><td><a id="p103493"></a>Титул II</td><td><a id="p103494"></a>II/6</td></tr>
<tr><td><a id="p103495"></a>Изображения</td><td><a id="p103496"></a>Графа для галочки: n1</td><td><a id="p103497"></a>1x</td><td><a id="p103498"></a>N</td><td></td><td><a id="p103499"></a>Титул II</td><td><a id="p103500"></a>II/7</td></tr>
<tr><td><a id="p103501"></a>Дата заявления</td><td><a id="p103502"></a>n8 (ггггммдд)</td><td><a id="p103503"></a>1x</td><td><a id="p103504"></a>N</td><td></td><td><a id="p103505"></a>Титул II</td><td><a id="p103506"></a>II/8</td></tr>
<tr><td><a id="p103507"></a>Конечная дата продленного использования</td><td><a id="p103508"></a>n8 (ггггммдд)</td><td><a id="p103509"></a>1x</td><td><a id="p103510"></a>N</td><td></td><td><a id="p103511"></a>Титул II</td><td><a id="p103512"></a>II/9</td></tr>
<tr><td><a id="p103513"></a>Причина недействительности</td><td><a id="p103514"></a>n2</td><td><a id="p103515"></a>1x</td><td><a id="p103516"></a>Y</td><td></td><td><a id="p103517"></a>Титул II</td><td><a id="p103518"></a>II/10</td></tr>
<tr><td><a id="p103519"></a>Регистрационный номер заявления</td><td><a id="p103520"></a>Код страны: a2+</td><td>Вид кода решения: an..4+</td><td><a id="p103521"></a>Исходящий номер: an..29<br>N</td><td><a id="p103522"></a>Используется структура, определенная в Титуле II для D.E. <a href="#p104143">1/6</a> Номер решения</td><td><a id="p103523"></a>Титул III</td><td><a id="p103524"></a>III/1</td></tr>
<tr><td><a id="p103525"></a>Правовое основание</td><td><a id="p103526"></a>n.a.</td><td></td><td><a id="p103527"></a>N</td><td></td><td><a id="p103528"></a>Титул III</td><td><a id="p103529"></a>III/2</td></tr>
<tr><td><a id="p103530"></a>Состав товаров</td><td><a id="p103531"></a>n.a.</td><td></td><td><a id="p103532"></a>N</td><td></td><td><a id="p103533"></a>Титул III</td><td><a id="p103534"></a>III/3</td></tr>
<tr><td><a id="p103535"></a>Информация, позволяющая определить происхождение</td><td><a id="p103536"></a>n.a.</td><td></td><td><a id="p103537"></a>N</td><td></td><td><a id="p103538"></a>Титул III</td><td><a id="p103539"></a>III/4</td></tr>
<tr><td><a id="p103540"></a>Указание на то, с какими данными необходимо обращаться как с конфиденциальными</td><td><a id="p103541"></a>n.a.</td><td></td><td><a id="p103542"></a>N</td><td></td><td><a id="p103543"></a>Титул III</td><td><a id="p103544"></a>III/5</td></tr>
<tr><td><a id="p103545"></a>Страна происхождения и правовые рамки</td><td><a id="p103546"></a>n.a.</td><td></td><td><a id="p103547"></a>N</td><td></td><td><a id="p103548"></a>Титул III</td><td><a id="p103549"></a>III/6</td></tr>
<tr><td><a id="p103550"></a>Обоснование оценки происхождения</td><td><a id="p103551"></a>n.a.</td><td></td><td><a id="p103552"></a>N</td><td></td><td><a id="p103553"></a>Титул III</td><td><a id="p103554"></a>III/7</td></tr>
<tr><td><a id="p103555"></a>Цена на условиях самовывоза</td><td><a id="p103556"></a>n.a.</td><td></td><td><a id="p103557"></a>N</td><td></td><td><a id="p103558"></a>Титул III</td><td><a id="p103559"></a>III/8</td></tr>
<tr><td><a id="p103560"></a>Использованные материалы, страна происхождения, код Комбинированной номенклатуры и стоимость</td><td><a id="p103561"></a>n.a.</td><td></td><td><a id="p103562"></a>N</td><td></td><td><a id="p103563"></a>Титул III</td><td><a id="p103564"></a>III/9</td></tr>
<tr><td><a id="p103565"></a>Описание переработки, необходимое для получения происхождения</td><td><a id="p103566"></a>n.a.</td><td></td><td><a id="p103567"></a>N</td><td></td><td><a id="p103568"></a>Титул III</td><td><a id="p103569"></a>III/10</td></tr>
<tr><td><a id="p103570"></a>Язык</td><td><a id="p103571"></a>a2</td><td></td><td><a id="p103572"></a>N</td><td><a id="p103573"></a>Для языка используются коды ISO-alpha-2, определенные в ISO-639-1 2002 г.</td><td><a id="p103574"></a>Титул IV</td><td><a id="p103575"></a>IV/1</td></tr>
<tr><td><a id="p103576"></a>Правовой статус заявителя</td><td><a id="p103577"></a>an..50</td><td><a id="p103578"></a>1x</td><td><a id="p103579"></a>N</td><td></td><td><a id="p103580"></a>Титул IV</td><td><a id="p103581"></a>IV/2</td></tr>
<tr><td><a id="p103582"></a>Дата учреждения</td><td><a id="p103583"></a>n8 (ггггммдд)</td><td><a id="p103584"></a>1x</td><td><a id="p103585"></a>N</td><td></td><td><a id="p103586"></a>Титул IV</td><td><a id="p103587"></a>IV/3</td></tr>
<tr><td><a id="p103588"></a>Роль(и) заявителя в международной системы поставки</td><td><a id="p103589"></a>an..3</td><td><a id="p103590"></a>99x</td><td><a id="p103591"></a>Y</td><td></td><td><a id="p103592"></a>Титул IV</td><td><a id="p103593"></a>IV/4</td></tr>
<tr><td><a id="p103594"></a>Государства-члены ЕС, в которых осуществляются деятельность, связанная с таможней</td><td><a id="p103595"></a>Страна: a2+</td><td>Улица и номер: an..70+</td><td><a id="p103596"></a><a id="p103597"></a>Почтовый индекс: an..9+<br>Город: an..35+<br>Вид предприятия: an..70 (текст в свободной форме)<br>99x<br>N</td><td></td><td><a id="p103598"></a>Титул IV</td><td><a id="p103599"></a>IV/5</td></tr>
<tr><td><a id="p103600"></a>Информация о пересечении границы</td><td><a id="p103601"></a>an8</td><td><a id="p103602"></a>99x</td><td><a id="p103603"></a>N</td><td><a id="p103604"></a>Структура кодов определена в Титуле II для D.E. <a href="#p104164">1/7</a> Таможенный орган, принимающий решение.</td><td><a id="p103605"></a>Титул IV</td><td><a id="p103606"></a>IV/6</td></tr>
<tr><td><a id="p103607"></a>Упрощения и облегчения, уже представленные, сертификаты защиты и безопасности, выданные на основании международных конвенций, международных стандартов Международной организации стандартизации или европейских стандартов Европейских органов по стандартизации или сертификаты, дающие статус, эквивалентный AEO, выданные в третьих странах и признанные по соглашению</td><td><a id="p103608"></a>Вид упрощения/облегчения an..70+</td><td>Идентификационный номер сертификата: an..35+</td><td><a id="p103609"></a><a id="p103610"></a>Код страны: a2+<br>Код таможенной процедуры: an2<br>99x<br>N</td><td><a id="p103611"></a>Коды, представленные в Приложении B, касающиеся D.E. <a href="#p109003">1/10</a> Процедура, используются для указания типа таможенной процедуры.</td><td><a id="p103612"></a>Титул IV</td><td><a id="p103613"></a>IV/7</td></tr>
<tr><td><a id="p103614"></a>Согласие на обмен информацией в разрешении AEO для обеспечения правильного функционирования системы, установленной в международных соглашениях/соглашениях с третьими странами, относящихся к взаимному признанию статуса авторизованного субъекта экономической деятельности, и мер, относящиеся к защите</td><td><a id="p103615"></a>Графа для галочки: n1+</td><td>Транслитерированное имя/название: an..70+</td><td><a id="p103616"></a><a id="p103617"></a>Транслитерированные улица и номер: an..70+<br>Транслитерированный почтовый индекс: an..9+<br>Транслитерированный город: an..35<br>1x<br>N</td><td></td><td><a id="p103618"></a>Титул IV</td><td><a id="p103619"></a>IV/8</td></tr>
<tr><td><a id="p103620"></a>Постоянное бизнес учреждение (PBE)</td><td><a id="p103621"></a>Название: an..70+</td><td>Улица и номер: an..70+</td><td><a id="p103622"></a><a id="p103623"></a>Страна: a2+<br>Почтовый индекс: an..9+<br>Город: an..35+<br>Номер VAT: an..17<br>99x<br>N</td><td></td><td><a id="p103624"></a>Титул IV</td><td><a id="p103625"></a>IV/9</td></tr>
<tr><td><a id="p103626"></a>Учреждение(я), где хранится и доступна таможенная документация</td><td><a id="p103627"></a>Название: an..70+</td><td>Улица и номер: an..70+</td><td><a id="p103628"></a><a id="p103629"></a>Страна: a2+<br>Почтовый индекс: an..9+<br>Город: an..35<br>99x<br>N</td><td></td><td><a id="p103630"></a>Титул IV</td><td><a id="p103631"></a>IV/10</td></tr>
<tr><td><a id="p103632"></a>Место, где осуществляется общая логистическая деятельность</td><td><a id="p103633"></a>Название: an..70+</td><td>Улица и номер: an..70+</td><td><a id="p103634"></a><a id="p103635"></a>Страна: a2+<br>Почтовый индекс: an..9+<br>Город: an..35<br>1x<br>N</td><td></td><td><a id="p103636"></a>Титул IV</td><td><a id="p103637"></a>IV/11</td></tr>
<tr><td><a id="p103638"></a>Деловая активность</td><td><a id="p103639"></a>an..4</td><td><a id="p103640"></a>99x</td><td><a id="p103641"></a>N</td><td><a id="p103642"></a>Используются коды, предусмотренные в Регламенте (ЕС) 1893/2006 Европейского Парламента и Совета ЕС <a href="#p104028">&lt;**&gt;</a>.</td><td><a id="p103643"></a>Титул V</td><td><a id="p103644"></a>V/1</td></tr>
<tr><td><a id="p103645"></a>Предмет и характер упрощения</td><td><a id="p103646"></a>Текст в свободной форме: an..512</td><td><a id="p103647"></a>1x</td><td><a id="p103648"></a>N</td><td></td><td><a id="p103649"></a>Титул VI</td><td><a id="p103650"></a>VI/1</td></tr>
<tr><td><a id="p103651"></a>Сумма пошлины и других сборов</td><td><a id="p103652"></a>Валюта: a3+</td><td>Сумма: n..16,2</td><td><a id="p103653"></a><a id="p103654"></a>99x<br>N</td><td><a id="p103655"></a>Для валюты используются коды ISO-alpha-3 (ISO 4217)</td><td><a id="p103656"></a>Титул VI</td><td><a id="p103657"></a>VI/2</td></tr>
<tr><td><a id="p103658"></a>Средний срок между помещением товаров на процедуру и завершением процедуры</td><td><a id="p103659"></a>Текст в свободной форме: an..35</td><td><a id="p103660"></a>99x</td><td><a id="p103661"></a>N</td><td></td><td><a id="p103662"></a>Титул VI</td><td><a id="p103663"></a>VI/3</td></tr>
<tr><td><a id="p103664"></a>Уровень гарантии</td><td><a id="p103665"></a>Код уровня гарантии: a2</td><td>Текст в свободной форме: an..512</td><td><a id="p103666"></a><a id="p103667"></a>99x<br>Y</td><td></td><td><a id="p103668"></a>Титул VI</td><td><a id="p103669"></a>VI/4</td></tr>
<tr><td><a id="p103670"></a>Форма гарантии</td><td><a id="p103671"></a>Форма гарантии: n..2+</td><td>Название: an..70+</td><td><a id="p103672"></a><a id="p103673"></a>Улица и номер: an..70+<br>Страна: a2+<br>Почтовый индекс: an..9+<br>Город: an..35+<br>Текст в свободной форме: an..512<br>1x<br>Y</td><td></td><td><a id="p103674"></a>Титул VI</td><td><a id="p103675"></a>VI/5</td></tr>
<tr><td><a id="p103676"></a>Базовая сумма</td><td><a id="p103677"></a>Валюта: a3+</td><td>Сумма: n..16,2</td><td><a id="p103678"></a><a id="p103679"></a>Текст в свободной форме: an..512<br>1x<br>N</td><td><a id="p103680"></a>Для валюты используются коды ISO-alpha-3 (ISO 4217)</td><td><a id="p103681"></a>Титул VI</td><td><a id="p103682"></a>VI/6</td></tr>
<tr><td><a id="p103683"></a>Срок оплаты</td><td><a id="p103684"></a>n1</td><td><a id="p103685"></a>1x</td><td><a id="p103686"></a>Y</td><td></td><td><a id="p103687"></a>Титул VII</td><td><a id="p103688"></a>VII/1</td></tr>
<tr><td><a id="p103689"></a>Вид отсрочки платежа</td><td><a id="p103690"></a>n1</td><td><a id="p103691"></a>1x</td><td><a id="p103692"></a>Y</td><td></td><td><a id="p103693"></a>Титул VIII</td><td><a id="p103694"></a>VIII/1</td></tr>
<tr><td><a id="p103695"></a>Право на возмещение</td><td><a id="p103696"></a>an..35</td><td><a id="p103697"></a>999x</td><td><a id="p103698"></a>N</td><td></td><td><a id="p103699"></a>Титул VIII</td><td><a id="p103700"></a>VIII/2</td></tr>
<tr><td><a id="p103701"></a>Таможенное учреждение, в котором было сделано уведомление о таможенном долге</td><td><a id="p103702"></a>an8</td><td><a id="p103703"></a>1x</td><td><a id="p103704"></a>N</td><td><a id="p103705"></a>Структура кодов определена в Титуле II для D.E. <a href="#p104164">1/7</a> Таможенный орган, принимающий решение.</td><td><a id="p103706"></a>Титул VIII</td><td><a id="p103707"></a>VIII/3</td></tr>
<tr><td><a id="p103708"></a>Таможенное учреждение, отвечающее за место, в котором находятся товары</td><td><a id="p103709"></a>an8</td><td><a id="p103710"></a>1x</td><td><a id="p103711"></a>N</td><td><a id="p103712"></a>Структура кодов определена в Титуле II для D.E. <a href="#p104164">1/7</a> Таможенный орган, принимающий решение.</td><td><a id="p103713"></a>Титул VIII</td><td><a id="p103714"></a>VIII/4</td></tr>
<tr><td><a id="p103715"></a>Комментарии таможенного учреждения, отвечающего за место, в котором находятся товары</td><td><a id="p103716"></a>Текст в свободной форме: an..512</td><td><a id="p103717"></a>1x</td><td><a id="p103718"></a>N</td><td></td><td><a id="p103719"></a>Титул VIII</td><td><a id="p103720"></a>VIII/5</td></tr>
<tr><td><a id="p103721"></a>Таможенная процедура (запрос о предварительном выполнении формальностей)</td><td><a id="p103722"></a>Код процедуры: an2+</td><td>Графа для галочки: n1+</td><td><a id="p103723"></a><a id="p103724"></a>Исходящий номер решения (Код страны: a2+ вид кода решения: an..4+ исходящий номер: an..29)<br>1x<br>N</td><td><a id="p103725"></a>Коды, представленные в Приложении B, касающиеся D.E. <a href="#p109003">1/10</a> Процедура, используются.</td><td><a id="p103726"></a>Титул VIII</td><td><a id="p103727"></a>VIII/6</td></tr>
<tr><td><a id="p103728"></a>Таможенная стоимость</td><td><a id="p103729"></a>Валюта: a3+</td><td>Сумма: n..16,2</td><td><a id="p103730"></a><a id="p103731"></a>1x<br>N</td><td><a id="p103732"></a>Для валюты используются коды ISO-alpha-3 (ISO 4217)</td><td><a id="p103733"></a>Титул VIII</td><td><a id="p103734"></a>VIII/7</td></tr>
<tr><td><a id="p103735"></a>Сумма импортной или экспортной пошлины, выплачиваемая или возмещаемая</td><td><a id="p103736"></a>Валюта: a3+</td><td>Сумма: n..16,2</td><td><a id="p103737"></a><a id="p103738"></a>1x<br>N</td><td><a id="p103739"></a>Для валюты используются коды ISO-alpha-3 (ISO 4217)</td><td><a id="p103740"></a>Титул VIII</td><td><a id="p103741"></a>VIII/8</td></tr>
<tr><td><a id="p103742"></a>Вид импортной или экспортной пошлины</td><td><a id="p103743"></a>Коды Союза: a1+n2</td><td>Национальные коды: n1+an2</td><td><a id="p103744"></a><a id="p103745"></a>99x<br>N</td><td><a id="p103746"></a>Используются коды, предусмотренные в Приложении B, касающиеся D.E. <a href="#p109187">4/3</a> Расчет налогов - вид налогов.</td><td><a id="p103747"></a>Титул VIII</td><td><a id="p103748"></a>VIII/9</td></tr>
<tr><td><a id="p103749"></a>Правовое основание</td><td><a id="p103750"></a>a1</td><td><a id="p103751"></a>1x</td><td><a id="p103752"></a>Y</td><td></td><td><a id="p103753"></a>Титул VIII</td><td><a id="p103754"></a>VIII/10</td></tr>
<tr><td><a id="p103755"></a>Использование или назначение товаров</td><td><a id="p103756"></a>Текст в свободной форме: an..512</td><td><a id="p103757"></a>1x</td><td><a id="p103758"></a>N</td><td></td><td><a id="p103759"></a>Титул VIII</td><td><a id="p103760"></a>VIII/11</td></tr>
<tr><td><a id="p103761"></a>Срок выполнения формальностей</td><td><a id="p103762"></a>n..3</td><td><a id="p103763"></a>1x</td><td><a id="p103764"></a>N</td><td></td><td><a id="p103765"></a>Титул VIII</td><td><a id="p103766"></a>VIII/12</td></tr>
<tr><td><a id="p103767"></a>Заявление таможенного органа, принимающего решение</td><td><a id="p103768"></a>Текст в свободной форме: an..512</td><td><a id="p103769"></a>1x</td><td><a id="p103770"></a>N</td><td></td><td><a id="p103771"></a>Титул VIII</td><td><a id="p103772"></a>VIII/13</td></tr>
<tr><td><a id="p103773"></a>Описание оснований выплаты или возмещения</td><td><a id="p103774"></a>Текст в свободной форме: an..512</td><td><a id="p103775"></a>1x</td><td><a id="p103776"></a>N</td><td></td><td><a id="p103777"></a>Титул VIII</td><td><a id="p103778"></a>VIII/14</td></tr>
<tr><td><a id="p103779"></a>Сведения о банке и счете</td><td><a id="p103780"></a>Текст в свободной форме: an..512</td><td><a id="p103781"></a>1x</td><td><a id="p103782"></a>N</td><td></td><td><a id="p103783"></a>Титул IX</td><td><a id="p103784"></a>IX/1</td></tr>
<tr><td><a id="p103785"></a>Перемещение товаров</td><td><a id="p103786"></a>Код правового основания: an1+</td><td>Номер EORI: an..17+</td><td><a id="p103787"></a><a id="p103788"></a>Страна: a2+<br>Код вида места: a1+<br>Определитель идентификации: a1+<br>Кодировано:<br>Идентификация места: an..35+<br>Дополнительный идентификатор: n..3<br>ИЛИ<br>Описание в свободной форме:<br>Название: an..70+<br>Улица и номер: an..70+<br>Страна: a2+<br>Почтовый индекс: an..9+<br>Город: an..35<br>999x<br>Y</td><td><a id="p103789"></a>Структура и коды, определенные в Приложении B для D.E. <a href="#p109313">5/23</a> Место товаров, используются для указания адреса склада временного хранения</td><td><a id="p103790"></a>Титул X</td><td><a id="p103791"></a>X/1</td></tr>
<tr><td><a id="p103792"></a>Государство(а)-член(ы) ЕС, связанные с услугами регулярного судоходства</td><td><a id="p103793"></a>Определитель: n1+</td><td>Код страны: a2</td><td><a id="p103794"></a><a id="p103795"></a>99x<br>Y</td><td><a id="p103796"></a>Используются коды страны, предусмотренные в Регламенте (ЕС) 1106/2012 Европейской Комиссии <a href="#p104029">&lt;***&gt;</a>.</td><td><a id="p103797"></a>Титул X</td><td><a id="p103798"></a>X/2</td></tr>
<tr><td><a id="p103799"></a>Название судов</td><td><a id="p103800"></a>Название судна: an..35+</td><td>Номер IMO (Международной морской организации) судна: IMO + n7</td><td><a id="p103801"></a><a id="p103802"></a>99x<br>N</td><td></td><td><a id="p103803"></a>Титул X</td><td><a id="p103804"></a>X/3</td></tr>
<tr><td><a id="p103805"></a>Порты захода</td><td><a id="p103806"></a>an8</td><td><a id="p103807"></a>99x</td><td><a id="p103808"></a>N</td><td><a id="p103809"></a>Структура кодов определена в Титуле II для D.E. <a href="#p104164">1/7</a> Таможенный орган, принимающий решение.</td><td><a id="p103810"></a>Титул X</td><td><a id="p103811"></a>X/4</td></tr>
<tr><td><a id="p103812"></a>Обязательство</td><td><a id="p103813"></a>Графа для галочки: n1</td><td><a id="p103814"></a>1x</td><td><a id="p103815"></a>N</td><td></td><td><a id="p103816"></a>Титул XI</td><td><a id="p103817"></a>XI/1</td></tr>
<tr><td><a id="p103818"></a>Таможенное(ые) учреждение(я), ответственные за регистрацию доказательства таможенного статуса товаров Союза</td><td><a id="p103819"></a>an8</td><td><a id="p103820"></a>999x</td><td><a id="p103821"></a>N</td><td><a id="p103822"></a>Структура кодов определена в Титуле II для D.E. <a href="#p104164">1/7</a> Таможенный орган, принимающий решение.</td><td><a id="p103823"></a>Титул XII</td><td><a id="p103824"></a>XII/1</td></tr>
<tr><td><a id="p103825"></a>Срок предоставления дополнительной декларации</td><td><a id="p103826"></a>n..2</td><td><a id="p103827"></a>1x</td><td><a id="p103828"></a>N</td><td></td><td><a id="p103829"></a>Титул XII</td><td><a id="p103830"></a>XII/2</td></tr>
<tr><td><a id="p103831"></a>Субподрядчик</td><td><a id="p103832"></a>Название/имя: an..70+</td><td>Улица и номер: an..70+</td><td><a id="p103833"></a><a id="p103834"></a>Страна: a2+<br>Почтовый индекс: an..9+<br>Город: an..35<br>1x<br>N</td><td></td><td><a id="p103835"></a>Титул XII</td><td><a id="p103836"></a>XII/3</td></tr>
<tr><td><a id="p103837"></a>Идентификация субподрядчика</td><td><a id="p103838"></a>an..17</td><td><a id="p103839"></a>1x</td><td><a id="p103840"></a>N</td><td></td><td><a id="p103841"></a>Титул XIII</td><td><a id="p103842"></a>XIII/1</td></tr>
<tr><td><a id="p103843"></a>Компании, участвующие в разрешении в других государствах-членах ЕС</td><td><a id="p103844"></a>Название: an..70+</td><td>Улица и номер: an..70+</td><td><a id="p103845"></a><a id="p103846"></a>Страна: a2+<br>Почтовый индекс: an..9+<br>Город: an..35<br>999x<br>N</td><td></td><td><a id="p103847"></a>Титул XIII</td><td><a id="p103848"></a>XIII/2</td></tr>
<tr><td><a id="p103849"></a>Идентификация компаний, участвующих в разрешении в других государствах-членах ЕС</td><td><a id="p103850"></a>an..17</td><td><a id="p103851"></a>999x</td><td><a id="p103852"></a>N</td><td></td><td><a id="p103853"></a>Титул XIII</td><td><a id="p103854"></a>XIII/3</td></tr>
<tr><td><a id="p103855"></a>Таможенное(ые) учреждение(я) места представления</td><td><a id="p103856"></a>an8</td><td><a id="p103857"></a>999x</td><td><a id="p103858"></a>N</td><td><a id="p103859"></a>Структура кодов определена в Титуле II для D.E. <a href="#p104164">1/7</a> Таможенный орган, принимающий решение.</td><td><a id="p103860"></a>Титул XIII</td><td><a id="p103861"></a>XIII/4</td></tr>
<tr><td><a id="p103862"></a>Идентификация органов НДС, акцизных и статистических органов</td><td><a id="p103863"></a>Название: an..70+</td><td>Улица и номер: an..70+</td><td><a id="p103864"></a><a id="p103865"></a>Страна: a2+<br>Почтовый индекс: an..9+<br>Город: an..35<br>999x<br>N</td><td></td><td><a id="p103866"></a>Титул XIII</td><td><a id="p103867"></a>XIII/5</td></tr>
<tr><td><a id="p103868"></a>Способ оплаты НДС</td><td><a id="p103869"></a>a1</td><td><a id="p103870"></a>1x</td><td><a id="p103871"></a>N</td><td><a id="p103872"></a>Используются коды, предусмотренные в Приложении B в отношении D.E. <a href="#p109214">4/8</a> Расчет налогов - способ оплаты</td><td><a id="p103873"></a>Титул XIII</td><td><a id="p103874"></a>XIII/6</td></tr>
<tr><td><a id="p103875"></a>Налоговый представитель</td><td><a id="p103876"></a>Название/имя: an..70+</td><td>Улица и номер: an..70+</td><td><a id="p103877"></a><a id="p103878"></a>Страна: a2+<br>Почтовый индекс: an..9+<br>Город: an..35<br>99x<br>N</td><td></td><td><a id="p103879"></a>Титул XIII</td><td><a id="p103880"></a>XIII/7</td></tr>
<tr><td><a id="p103881"></a>Идентификация налогового представителя</td><td><a id="p103882"></a>an..17</td><td><a id="p103883"></a>99x</td><td><a id="p103884"></a>N</td><td><a id="p103885"></a>Используется номер плательщика НДС</td><td><a id="p103886"></a>Титул XIII</td><td><a id="p103887"></a>XIII/8</td></tr>
<tr><td><a id="p103888"></a>Код статуса налогового представителя</td><td><a id="p103889"></a>n1</td><td><a id="p103890"></a>1x (на представителя)</td><td><a id="p103891"></a>Y</td><td></td><td><a id="p103892"></a>Титул XIII</td><td><a id="p103893"></a>XIII/9</td></tr>
<tr><td><a id="p103894"></a>Лицо, ответственное за акцизные формальности</td><td><a id="p103895"></a>Название/имя: an..70+</td><td>Улица и номер: an..70+</td><td><a id="p103896"></a><a id="p103897"></a>Страна: a2+<br>Почтовый индекс: an..9+<br>Город: an..35<br>99x<br>N</td><td></td><td><a id="p103898"></a>Титул XIII</td><td><a id="p103899"></a>XIII/10</td></tr>
<tr><td><a id="p103900"></a>Идентификация лица, ответственного за акцизные формальности</td><td><a id="p103901"></a>an..17</td><td><a id="p103902"></a>99x</td><td><a id="p103903"></a>N</td><td></td><td><a id="p103904"></a>Титул XIV</td><td><a id="p103905"></a>XIV/1</td></tr>
<tr><td><a id="p103906"></a>Отказ от уведомления о представлении</td><td><a id="p103907"></a>Графа для галочки: n1+</td><td>Текст в свободной форме: an..512</td><td><a id="p103908"></a><a id="p103909"></a>1x<br>N</td><td></td><td><a id="p103910"></a>Титул XIV</td><td><a id="p103911"></a>XIV/2</td></tr>
<tr><td><a id="p103912"></a>Отказ от декларации, предоставляемой перед отправлением</td><td><a id="p103913"></a>Текст в свободной форме: an..512</td><td><a id="p103914"></a>1x</td><td><a id="p103915"></a>N</td><td></td><td><a id="p103916"></a>Титул XIV</td><td><a id="p103917"></a>XIV/3</td></tr>
<tr><td><a id="p103918"></a>Таможенное учреждение, ответственное за место, в котором товары предоставляются для контроля</td><td><a id="p103919"></a>an8</td><td><a id="p103920"></a>1x</td><td><a id="p103921"></a>N</td><td><a id="p103922"></a>Структура кодов определена в Титуле II для D.E. <a href="#p104164">1/7</a> Таможенный орган, принимающий решение.</td><td><a id="p103923"></a>Титул XIV</td><td><a id="p103924"></a>XIV/4</td></tr>
<tr><td><a id="p103925"></a>Срок предоставления дополнительной декларации</td><td><a id="p103926"></a>n..2</td><td><a id="p103927"></a>1x</td><td><a id="p103928"></a>N</td><td></td><td><a id="p103929"></a>Титул XV</td><td><a id="p103930"></a>XV/1</td></tr>
<tr><td><a id="p103931"></a>Идентификация формальностей и контроля, которые должны быть делегированы субъекту экономической деятельности</td><td><a id="p103932"></a>Текст в свободной форме: an..512</td><td><a id="p103933"></a>1x</td><td><a id="p103934"></a>N</td><td></td><td><a id="p103935"></a>Титул XVI</td><td><a id="p103936"></a>XVI/1</td></tr>
<tr><td><a id="p103937"></a>Экономическая деятельность</td><td><a id="p103938"></a>n1</td><td><a id="p103939"></a>1x</td><td><a id="p103940"></a>Y</td><td></td><td><a id="p103941"></a>Титул XVI</td><td><a id="p103942"></a>XVI/2</td></tr>
<tr><td><a id="p103943"></a>Взвешивающее оборудование</td><td><a id="p103944"></a>Текст в свободной форме: an..512</td><td><a id="p103945"></a>1x</td><td><a id="p103946"></a>N</td><td></td><td><a id="p103947"></a>Титул XVI</td><td><a id="p103948"></a>XVI/3</td></tr>
<tr><td><a id="p103949"></a>Дополнительные гарантии</td><td><a id="p103950"></a>Текст в свободной форме: an..512</td><td><a id="p103951"></a>1x</td><td><a id="p103952"></a>N</td><td></td><td><a id="p103953"></a>Титул XVI</td><td><a id="p103954"></a>XVI/4</td></tr>
<tr><td><a id="p103955"></a>Заблаговременное уведомление таможенных органов</td><td><a id="p103956"></a>Текст в свободной форме: an..512</td><td><a id="p103957"></a>1x</td><td><a id="p103958"></a>N</td><td></td><td><a id="p103959"></a>Титул XVII</td><td><a id="p103960"></a>XVII/1</td></tr>
<tr><td><a id="p103961"></a>Предварительный экспорт (IP EX/IM)</td><td><a id="p103962"></a>Графа для галочки: n1+</td><td>Срок: n..2</td><td><a id="p103963"></a><a id="p103964"></a>1x<br>N</td><td></td><td><a id="p103965"></a>Титул XVII</td><td><a id="p103966"></a>XVII/2</td></tr>
<tr><td><a id="p103967"></a>Выпуск в свободное обращение посредством использования свидетельства о завершении</td><td><a id="p103968"></a>Графа для галочки: n1</td><td><a id="p103969"></a>1x</td><td><a id="p103970"></a>N</td><td></td><td><a id="p103971"></a>Титул XVIII</td><td><a id="p103972"></a>XVIII/1</td></tr>
<tr><td><a id="p103973"></a>Система стандартного обмена</td><td><a id="p103974"></a>Графа для галочки: n1+</td><td>Вид системы стандартного обмена: n1+</td><td><a id="p103975"></a><a id="p103976"></a>Текст в свободной форме: an..512<br>1x<br>Y</td><td></td><td><a id="p103977"></a>Титул XVIII</td><td><a id="p103978"></a>XVIII/2</td></tr>
<tr><td><a id="p103979"></a>Заменяющая продукция</td><td><a id="p103980"></a>Код товара: an..8+</td><td>Описание: an..512+</td><td><a id="p103981"></a><a id="p103982"></a>Код: n1<br>999x<br>Y</td><td></td><td><a id="p103983"></a>Титул XVIII</td><td><a id="p103984"></a>XVIII/3</td></tr>
<tr><td><a id="p103985"></a>Предварительный импорт заменяющей продукции</td><td><a id="p103986"></a>Графа для галочки: n1+</td><td>Срок: n..2</td><td><a id="p103987"></a><a id="p103988"></a>1x<br>N</td><td></td><td><a id="p103989"></a>Титул XVIII</td><td><a id="p103990"></a>XVIII/4</td></tr>
<tr><td><a id="p103991"></a>Предварительный импорт переработанной продукции (OP IM/EX)</td><td><a id="p103992"></a>Графа для галочки: n1+</td><td>Срок: n..2</td><td><a id="p103993"></a><a id="p103994"></a>1x<br>N</td><td></td><td><a id="p103995"></a>Титул XIX</td><td><a id="p103996"></a>XIX/1</td></tr>
<tr><td><a id="p103997"></a>Временное извлечение</td><td><a id="p103998"></a>Графа для галочки: n1+</td><td>Текст в свободной форме: an..512</td><td><a id="p103999"></a><a id="p104000"></a>1x<br>N</td><td></td><td><a id="p104001"></a>Титул XIX</td><td><a id="p104002"></a>XIX/2</td></tr>
<tr><td><a id="p104003"></a>Уровень потерь</td><td><a id="p104004"></a>Текст в свободной форме: an..512</td><td><a id="p104005"></a>1x</td><td><a id="p104006"></a>N</td><td></td><td><a id="p104007"></a>Титул XX</td><td><a id="p104008"></a>XX/1</td></tr>
<tr><td><a id="p104009"></a>Идентификационные меры</td><td><a id="p104010"></a>Текст в свободной форме: an..512</td><td>Исходящий номер решения (Код страны: a2+</td><td><a id="p104011"></a><a id="p104012"></a>Вид кода решения: an..4+<br>Исходящий номер: an..29<br>1x<br>N</td><td><a id="p104013"></a>Структура разрешений для использования специальных пломб должна соответствовать структуре, определенной в Титуле II в отношении D.E. <a href="#p104143">1/6</a> Исходящий номер решения.</td><td><a id="p104014"></a>Титул XX</td><td><a id="p104015"></a>XX/2</td></tr>
<tr><td><a id="p104016"></a>Полная гарантия</td><td><a id="p104017"></a>Графа для галочки: n1+</td><td>Исходящий номер решения (Код страны: a2+</td><td><a id="p104018"></a><a id="p104019"></a>Вид кода решения: an..4+<br>Исходящий номер: an..29<br>1x<br>N</td><td><a id="p104020"></a>Структура разрешения для предоставления полной гарантии или отказа от гарантии должна соответствовать структуре, определенной в Титуле II в отношении D.E. <a href="#p104143">1/6</a> Исходящий номер решения.</td><td><a id="p104021"></a>Титул XXI</td><td><a id="p104022"></a>XXI/1</td></tr>
<tr><td><a id="p104023"></a>Вид пломбы</td><td><a id="p104024"></a>Текст в свободной форме: an..512</td><td><a id="p104025"></a>1x</td><td><a id="p104026"></a>N</td><td></td><td><a id="p104027"></a>&lt;*&gt; Регламент (ЕС) 1106/2012 Европейской Комиссии от 27 ноября 2012 г. об имплементации Регламента (ЕС) 471/2009 Европейского Парламента и Совета ЕС о статистике Сообщества в отношении внешней торговли с государствами, не являющимися членами ЕС, в отношении обновления номенклатуры стран и территорий. Действие Регламента распространяется на Европейское экономическое пространство (ОЖ N L 328, 28.11.2012, стр. 7).</td><td><a id="p104028"></a>&lt;**&gt; Регламент (ЕС) 1893/2006 Европейского Парламента и Совета ЕС от 20 декабря 2006 г. об установлении статистической классификации видов экономической деятельности Редакции 2 NACE и об изменении Регламента (ЕЭС) 3037/90 Совета ЕС, а также отдельных Регламентов ЕС по определенным статистическим областям (ОЖ N L 393, 30.12.2006, стр. 1).</td></tr>
<tr><td colspan="7"><a id="p104029"></a><a id="p104030"></a>&lt;***&gt; Регламент (ЕС) 1106/2012 Европейской Комиссии от 27 ноября 2012 г. об имплементации Регламента (ЕС) 471/2009 Европейского Парламента и Совета ЕС о статистике Сообщества в отношении внешней торговли с государствами, не являющимися членами ЕС, в отношении обновления номенклатуры стран и территорий. Действие Регламента распространяется на Европейское экономическое пространство (ОЖ N L 328, 28.11.2012, стр. 7).<br>ТИТУЛ II. КОДЫ В ОТНОШЕНИИ ТРЕБОВАНИЙ</td></tr>
</table>

**К ОБЩИМ ДАННЫМ ДЛЯ ЗАЯВЛЕНИЙ И РЕШЕНИЙ**

<a id="p104031"></a>**1. ВВЕДЕНИЕ**

<a id="p104032"></a>Данный титул содержит коды, используемые в заявлениях и решениях.

<a id="p104033"></a>**2. КОДЫ**

<a id="p104034"></a>1/1. Вид кода заявления/решения
<a id="p104035"></a>Используются следующие коды:


| <a id="p104036"></a>Код | <a id="p104037"></a>Вид заявления/решения | <a id="p104038"></a>Заголовок колонки в таблице в Приложении A к Делегированному Регламенту (ЕС) 2015/2446 |
| --- | --- | --- |
| <a id="p104039"></a>BTI | <a id="p104040"></a>Заявление или решение, относящееся к обязательной тарифной информации | <a id="p104041"></a>1a |
| <a id="p104042"></a>BOI | <a id="p104043"></a>Заявление или решение, относящееся к обязательной информации о происхождении | <a id="p104044"></a>1b |
| <a id="p104045"></a>AEOC | <a id="p104046"></a>Заявление или разрешение на статус авторизованного субъекта экономической деятельности - Таможенные упрощения | <a id="p104047"></a>2 |
| <a id="p104048"></a>AEOS | <a id="p104049"></a>Заявление или разрешение на статус авторизованного субъекта экономической деятельности - Защита и безопасность | <a id="p104050"></a>2 |
| <a id="p104051"></a>AEOF | <a id="p104052"></a>Заявление или разрешение на статус авторизованного субъекта экономической деятельности - Таможенные упрощения/Защита и безопасность | <a id="p104053"></a>2 |
| <a id="p104054"></a>CVA | <a id="p104055"></a>Заявление или разрешение на упрощение определения сумм, являющихся частью таможенной стоимости товаров | <a id="p104056"></a>3 |
| <a id="p104057"></a>CGU | <a id="p104058"></a>Заявление или разрешение на предоставление полной гарантии, включая возможное уменьшение или отказ | <a id="p104059"></a>4a |
| <a id="p104060"></a>DPO | <a id="p104061"></a>Заявление или разрешение на отсрочку платежа | <a id="p104062"></a>4b |
| <a id="p104063"></a>REP | <a id="p104064"></a>Заявление или решение о возмещении сумм импортной или экспортной пошлины | <a id="p104065"></a>4c |
| <a id="p104066"></a>REM | <a id="p104067"></a>Заявление или решение на освобождение от сумм импортной или экспортной пошлины | <a id="p104068"></a>4c |
| <a id="p104069"></a>TST | <a id="p104070"></a>Заявление или разрешение на операцию хранения на складе для временного хранения товаров | <a id="p104071"></a>5 |
| <a id="p104072"></a>RSS | <a id="p104073"></a>Заявление или разрешение на учреждение услуг регулярного судоходства | <a id="p104074"></a>6a |
| <a id="p104075"></a>ACP | <a id="p104076"></a>Заявление или разрешение на статус авторизированного выдающего лица для установления доказательства таможенного статуса товаров Союза | <a id="p104077"></a>6b |
| <a id="p104078"></a>SDE | <a id="p104079"></a>Заявление или разрешение на использование упрощенной декларации | <a id="p104080"></a>7a |
| <a id="p104081"></a>CCL | <a id="p104082"></a>Заявление или разрешение на централизованную очистку | <a id="p104083"></a>7b |
| <a id="p104084"></a>EIR | <a id="p104085"></a>Заявление или разрешение на составление таможенной декларации через ввод данных в отчеты декларанта, включая экспортную процедуру | <a id="p104086"></a>7c |
| <a id="p104087"></a>SAS | <a id="p104088"></a>Заявление или разрешение на самооценку | <a id="p104089"></a>7d |
| <a id="p104090"></a>AWB | <a id="p104091"></a>Заявление или разрешение на статус авторизованного взвешивания бананов | <a id="p104092"></a>7e |
| <a id="p104093"></a>IPO | <a id="p104094"></a>Заявление или разрешение на использование процедуры внутренней переработки | <a id="p104095"></a>8a |
| <a id="p104096"></a>OPO | <a id="p104097"></a>Заявление или разрешение на использование процедуры внешней переработки | <a id="p104098"></a>8b |
| <a id="p104099"></a>EUS | <a id="p104100"></a>Заявление или разрешение на использование конечного использования | <a id="p104101"></a>8c |
| <a id="p104102"></a>TEA | <a id="p104103"></a>Заявление или разрешение на использование временного допуска | <a id="p104104"></a>8d |
| <a id="p104105"></a>CWP | <a id="p104106"></a>Заявление или разрешение на операцию хранения на складе для таможенного хранения товаров на частном таможенном складе | <a id="p104107"></a>8e |
| <a id="p104108"></a>CW1 | <a id="p104109"></a>Заявление или разрешение на операцию хранения на складе для таможенного хранения товаров на государственном таможенном складе тира I | <a id="p104110"></a>8e |
| <a id="p104111"></a>CW2 | <a id="p104112"></a>Заявление или разрешение на операцию хранения на складе для таможенного хранения товаров на государственном таможенном складе тира II | <a id="p104113"></a>8e |
| <a id="p104114"></a>ACT | <a id="p104115"></a>Заявление или разрешение на статус авторизованного грузополучателя для процедуры TIR | <a id="p104116"></a>9a |
| <a id="p104117"></a>ACR | <a id="p104118"></a>Заявление или разрешение на статус авторизованного грузоотправителя для транзита Союза | <a id="p104119"></a>9b |
| <a id="p104120"></a>ACE | <a id="p104121"></a>Заявление или разрешение на статус авторизованного грузополучателя для транзита Союза | <a id="p104122"></a>9c |
| <a id="p104123"></a>SSE | <a id="p104124"></a>Заявление или разрешение на использование пломб специального вида | <a id="p104125"></a>9d |
| <a id="p104126"></a>TRD | <a id="p104127"></a>Заявление или разрешение на использование транзитной декларации с сокращенным комплектом данных | <a id="p104128"></a>9e |
| <a id="p104129"></a>ETD | <a id="p104130"></a>Заявление на использование электронного транспортного документа в качестве таможенной декларации | <a id="p104131"></a>9f |


<a id="p104132"></a>1/3. Вид заявления
<a id="p104133"></a>Используются следующие коды:
<a id="p104134"></a>1 первое заявление
<a id="p104135"></a>2 заявление об изменении решения
<a id="p104136"></a>3 заявление об обновлении разрешения
<a id="p104137"></a>4 заявление об отзыве решения

<a id="p104138"></a>1/4 Географическое действие
<a id="p104139"></a>Используются следующие коды:
<a id="p104140"></a>1 заявление или разрешение, действующее во всех государствах-членах ЕС
<a id="p104141"></a>2 заявление или разрешение, действующее в отдельных государствах-членах ЕС
<a id="p104142"></a>3 заявление или разрешение, ограниченное одним государством-членом ЕС

<a id="p104143"></a>1/6 Исходящий номер решения
<a id="p104144"></a>Исходящий номер решения имеет следующую структуру:


| <a id="p104145"></a>Поле | <a id="p104146"></a>Содержание | <a id="p104147"></a>Формат | <a id="p104148"></a>Примеры |
| --- | --- | --- | --- |
| <a id="p104149"></a>1 | <a id="p104150"></a>Идентификатор государства-члена ЕС, в котором принято решение (код страны alpha 2) | <a id="p104151"></a>a2 | <a id="p104152"></a>PT |
| <a id="p104153"></a>2 | <a id="p104154"></a>Вид кода решения | <a id="p104155"></a>an..4 | <a id="p104156"></a>SSE |
| <a id="p104157"></a>3 | <a id="p104158"></a>Уникальный идентификатор для решения по стране | <a id="p104159"></a>an..29 | <a id="p104160"></a>1234XYZ12345678909876543210AB |


<a id="p104161"></a>[Поле 1](https://bukva.ai/docs/reglament-20152447/statya-350#p104149), как объясняется выше
<a id="p104162"></a>[Поле 2](https://bukva.ai/docs/reglament-20152447/statya-350#p104153) заполняется кодом решения, как определено для D.E. [1/1](https://bukva.ai/docs/reglament-20152447/statya-350#p104034) Вид кода решения в настоящем Титуле.
<a id="p104163"></a>[Поле 3](https://bukva.ai/docs/reglament-20152447/statya-350#p104157) заполняется идентификатором решения. Способ, с помощью которого используется данное [поле](https://bukva.ai/docs/reglament-20152447/statya-350#p104157), является ответственностью национальных администраций, но каждое решение, принятое в данной стране, должно иметь уникальный номер в отношении определенного вида решения.

<a id="p104164"></a>1/7. Таможенный орган, принимающий решение
<a id="p104165"></a>Коды имеют следующую структуру:
- <a id="p104166"></a>первые два знака (a2) служат для идентификации страны посредством кода страны, определенного в Регламенте (ЕС) 1106/2012 Европейской Комиссии;
- <a id="p104167"></a>следующие шесть знаков (an6) означают рассматриваемое учреждение в указанной стране. Предполагается, что принимается следующая структура:
<a id="p104168"></a>Первые три знаки (an3) могут быть указаны посредством UN/LOCODE <*> названия места, а последние три - посредством национального буквенно-цифрового подраздела (an3). Если этот подраздел не используется, необходимо указать "000".

<a id="p104169"></a>

---

<a id="p104170"></a><*> [Рекомендация](https://bukva.ai/docs/16-eek-oon-evropeyskaya) 16 по UN/LOCODE - КОД ДЛЯ ПОРТОВ И ДРУГИХ МЕСТ.

<a id="p104171"></a>Пример: BEBRU000: BE = ISO 3166 для Бельгии, BRU = UN/LOCODE названия места для города Брюсселя, 000 - для неиспользуемого подраздела.

<a id="p104172"></a>5/8. Идентификация товаров
<a id="p104173"></a>Следующие коды используются для идентификации товаров:
<a id="p104174"></a>1 серийный номер или номер производителя
<a id="p104175"></a>2 крепление пломб, опечатывания, зажимов или других отличительных знаков
<a id="p104176"></a>4 взятие проб, иллюстрации или технические описания
<a id="p104177"></a>5 выполнение анализов
<a id="p104178"></a>6 информационный документ для содействия временному экспорту товаров, направленных из одной страны для производства, переработки или ремонта в другую (подходит только для внешней переработки)
<a id="p104179"></a>7 другие средства идентификации (предоставить объяснение по средствам используемой идентификации)
<a id="p104180"></a>8 без мер идентификации согласно [Статье 250(2)(b)](https://bukva.ai/docs/reglament-9522013/statya-1#p102046) Кодекса (подходит только для временного допуска)

<a id="p104181"></a>6/2. Экономические условия
<a id="p104182"></a>Коды, используемые для случаев, в которых экономические условия считаются выполненными для внутренней переработки:
<a id="p104183"></a>Код 1 - переработка товаров, не указанных в Приложении 71-02 к Делегированному Регламенту (ЕС) 2015/2446;
<a id="p104184"></a>Код 2 - ремонт;
<a id="p104185"></a>Код 3 - переработка товаров, прямо или косвенно представленных в распоряжение владельца разрешения, выполняемая согласно спецификациям от имени лица, учрежденного за пределами таможенной территории Союза, обычно после оплаты одних затрат на переработку;
<a id="p104186"></a>Код 4 - переработка твердой пшеницы в макаронные изделия;
<a id="p104187"></a>Код 5 - помещение товаров на внутреннюю переработку в пределах количества, определенного на основании остатка в соответствии со [Статьей 18](https://bukva.ai/docs/reglament-5102014/statya-18#p100272) <*>;

<a id="p104188"></a>

---

<a id="p104189"></a><*> [Регламент](https://bukva.ai/docs/reglament-5102014/statya-1) (ЕС) 510/2014 Европейского Парламента и Совета ЕС от 16 апреля 2014 г., устанавливающий режим торговли в отношении некоторых товаров, полученных в результате переработки сельскохозяйственных продуктов, и отменяющий Регламенты (ЕС) 1216/2009 и 614/2009 Совета ЕС (ОЖ N L 150, 20.5.2014, стр. 1).

<a id="p104190"></a>Код 6 - переработка товаров, которые указаны в Приложении 71-02 к Делегированному Регламенту (ЕС) 2015/2446, в случае отсутствия в наличии товаров, произведенных в Союзе, имеющих такой же восьмизначный код Комбинированной номенклатуры, такое же коммерческое качество и технические характеристики, что и товары, предназначенные для импорта на предполагаемые операции переработки;
<a id="p104191"></a>Код 7 - переработка товаров, указанных в Приложении 71-02 к Делегированному Регламенту (ЕС) 2015/2446, при условии, что имеются различия в цене между товарами, произведенными в Союзе, и товарами, предназначенными для импорта, если сравнимые товары не могут использоваться, так как их цена не может сделать предполагаемую коммерческую операцию экономически выгодной;
<a id="p104192"></a>Код 8 - переработка товаров, которые указаны в Приложении 71-02 к Делегированному Регламенту (ЕС) 2015/2446, при условии, что существуют договорные обязательства, если сравнимые товары не соответствуют договорным требованиям покупателя переработанной продукции из третьей страны, или если в соответствии с договором переработанная продукция должна быть получена из товаров, предназначенных для размещения на внутреннюю переработку для выполнения положений о защите промышленных или коммерческих имущественных прав;
<a id="p104193"></a>Код 9 - переработка товаров, которые указаны в Приложении 71-02 к Делегированному Регламенту (ЕС) 2015/2446, при условии, что совокупная стоимость товаров, помещаемых на процедуру внутренней переработки на заявителя и календарный год для каждого восьмизначного кода Объединенной номенклатуры, не превышает 150 000 евро;
<a id="p104194"></a>Код 10 - переработка товаров для обеспечения их соответствия техническим требованиям для их выпуска в свободное обращение;
<a id="p104195"></a>Код 11 - переработка товаров некоммерческого характера;
<a id="p104196"></a>Код 12 - переработка товаров, полученных по предыдущему разрешению, выдача которого подлежала изучению экономических условий;
<a id="p104197"></a>Код 13 - переработка твердых и жидких фракций пальмового масла, кокосового масла, жидких фракций кокосового масла, пальмоядрового масла, жидких фракций пальмоядрового масла, масла бабассу или касторового масла в продукцию, которая не направляется для пищевого сектора;
<a id="p104198"></a>Код 14 - переработка в продукцию, которая является частью или используется в воздушных судах гражданской авиации, для которых был выдан утвержденный сертификат летной годности EASA или эквивалентный сертификат;
<a id="p104199"></a>Код 15 - переработка в продукцию, пользующуюся льготами от автономной приостановки импортной пошлины на определенное оружие и военное оборудование в соответствии с Регламентом (ЕС) 150/2003 Совета ЕС <*>;

<a id="p104200"></a>

---

<a id="p104201"></a><*> Регламент (ЕС) 150/2003 Совета ЕС от 21 января 2003 г. о приостановке импортных пошлин на отдельное вооружение и военное оборудование (ОЖ N L 25, 30.1.2003, стр. 1).

<a id="p104202"></a>Код 16 - переработка товаров в образцы;
<a id="p104203"></a>Код 17 - переработка всех видов электронных компонентов, частей, приспособлений или любых других материалов в продукцию информационной технологии;
<a id="p104204"></a>Код 18 - переработка товаров, подпадающих под коды 2707 или 2710 Комбинированной номенклатуры, в товары, подпадающие под коды 2707, 2710 или 2902 Комбинированной номенклатуры;
<a id="p104205"></a>Код 19 - превращение в отходы и скрап, уничтожение, извлечение частей или компонентов;
<a id="p104206"></a>Код 20 - денатурация;
<a id="p104207"></a>Код 21 - обычные формы обработки, указанные в [Статье 220](https://bukva.ai/docs/reglament-9522013/statya-220#p101832) Кодекса;
<a id="p104208"></a>Код 22 - совокупная стоимость товаров, помещаемых на процедуру внутренней переработки на заявителя и календарный год для каждого восьмизначного кода Комбинированной номенклатуры, не превышает 150 000 евро в отношении товаров, на которые распространяется Приложение 71-02 к Делегированному Регламенту (ЕС) 2015/2446, и 300 000 евро для других товаров, кроме случаев, когда товары, предназначенные для помещения на процедуру внутренней переработки, могут подлежать предварительным или окончательным антидемпинговым пошлинам, компенсационным пошлинам, защитным мерам или дополнительным пошлинам в результате приостановки уступок, если они были продекларированы на выпуск в свободное обращение.

<a id="p104209"></a>7/3. Вид декларации
<a id="p104210"></a>Следующие коды используются для видов декларации:
<a id="p104211"></a>1 Стандартная декларация (в соответствии со [Статьей 162](https://bukva.ai/docs/reglament-9522013/statya-162#p101455) Кодекса)
<a id="p104212"></a>2 Упрощенная декларация (в соответствии со [Статьей 166](https://bukva.ai/docs/reglament-9522013/statya-166#p101473) Кодекса)
<a id="p104213"></a>3 Внесение в отчеты декларанта (в соответствии со [Статьей 182](https://bukva.ai/docs/reglament-9522013/statya-182#p101580) Кодекса)

<a id="p104214"></a>8/6. Гарантия
<a id="p104215"></a>Используются следующие коды:
<a id="p104216"></a>0 Гарантия не требуется
<a id="p104217"></a>1 Гарантия требуется

<a id="p104218"></a>II/9. Причина недействительности
<a id="p104219"></a>Ввести один из следующих кодов
<a id="p104220"></a>55 Аннулировано
<a id="p104221"></a>61 Недействительно из-за изменений кода таможенной номенклатуры
<a id="p104222"></a>62 Недействительно из-за меры Союза
<a id="p104223"></a>63 Недействительно из-за национальной правовой меры
<a id="p104224"></a>64 Отзыв из-за неправильной классификации
<a id="p104225"></a>65 Отзыв по другим причинам, кроме классификации
<a id="p104226"></a>66 Недействительно из-за ограниченного действия кода номенклатуры во время выдачи

<a id="p104227"></a>IV/3. Роль(и) заявителя в международной системе поставки
<a id="p104228"></a>Используются следующие коды:


| <a id="p104229"></a>Код | <a id="p104230"></a>Роль | <a id="p104231"></a>Описание |
| --- | --- | --- |
| <a id="p104232"></a>MF | <a id="p104233"></a>Производитель товаров | <a id="p104234"></a>Лицо, которое производит товары.<br>Данный код должен использоваться, только если субъект экономической деятельности производит товары. Он не распространяется на случаи, когда субъект экономической деятельности участвует только в торговле товарами (например, экспорт, импорт). |
| <a id="p104235"></a>IM | <a id="p104236"></a>Импортер | <a id="p104237"></a>Лицо, которое составляет или от имени которого таможенный агент или другое авторизованное лицо составляет декларацию на импорт. Может включать в себя лицо, которое владеет товарами или которому товары отгружены. |
| <a id="p104238"></a>EX | <a id="p104239"></a>Экспортер | <a id="p104240"></a>Лицо, которое составляет или от имени которого составляется декларация на экспорт и которое является владельцем товаров или имеет такие же права на распоряжение ими в то время, когда принимается декларация. |
| <a id="p104241"></a>CB | <a id="p104242"></a>Таможенный брокер | <a id="p104243"></a>Агент, или представитель, или профессиональный таможенный агент, который контактирует напрямую с таможней от имени импортера или экспортера.<br>Код может использоваться также для субъектов экономической деятельности, которые действуют в качестве агентов/представителей также для других целей (например, агент перевозчика). |
| <a id="p104244"></a>CA | <a id="p104245"></a>Перевозчик | <a id="p104246"></a>Лицо, выполняющее или организующее перевозку товаров между обозначенными пунктами. |
| <a id="p104247"></a>FW | <a id="p104248"></a>Экспедитор | <a id="p104249"></a>Лицо, организующее доставку товаров. |
| <a id="p104250"></a>CS | <a id="p104251"></a>Посредник | <a id="p104252"></a>Лицо, объединяющее различные партии, платежи и т.п. |
| <a id="p104253"></a>TR | <a id="p104254"></a>Оператор терминала | <a id="p104255"></a>Лицо, которое занимается погрузкой и разгрузкой морских судов. |
| <a id="p104256"></a>WH | <a id="p104257"></a>Управляющий склада | <a id="p104258"></a>Лицо, отвечающее за товары, поступившие на склад.<br>Данный код должен использоваться субъектами экономической деятельности, которые управляют другими видами складских мощностей (например, временного хранения, свободной зоны и т.п.). |
| <a id="p104259"></a>CF | <a id="p104260"></a>Контейнерный оператор | <a id="p104261"></a>Лицо, которому владение определенным имуществом (например, контейнером) было передано на определенный срок в обмен на арендные платежи. |
| <a id="p104262"></a>DEP | <a id="p104263"></a>Стивидор | <a id="p104264"></a>Лицо, которое управляет погрузкой и разгрузкой морских судов из нескольких терминалов. |
| <a id="p104265"></a>HR | <a id="p104266"></a>Служба судоходных линий | <a id="p104267"></a>Определяет организацию службы судоходных линий. |
| <a id="p104268"></a>999 | <a id="p104269"></a>Другое |  |


<a id="p104270"></a>VI/3. Уровень гарантии
<a id="p104271"></a>Для уровня гарантии должны использоваться следующие коды:
<a id="p104272"></a>Распространяются на существующие таможенные долги и, если это применимо, на другие сборы:
<a id="p104273"></a>AA - 100% соответствующей части базовой суммы
<a id="p104274"></a>AB - 30% соответствующей части базовой суммы
<a id="p104275"></a>Распространяются на потенциальные таможенные долги и, если это применимо, на другие платежи:
<a id="p104276"></a>BA - 100% соответствующей части базовой суммы
<a id="p104277"></a>BB - 50% соответствующей части базовой суммы
<a id="p104278"></a>BC - 30% соответствующей части базовой суммы
<a id="p104279"></a>BD - 0% соответствующей части базовой суммы

<a id="p104280"></a>VI/4. Форма гарантии
<a id="p104281"></a>Следующие коды используются для формы гарантии:
<a id="p104282"></a>1 Депозит наличными
<a id="p104283"></a>2 Обязательство, данное гарантом
<a id="p104284"></a>3* Другие формы, определенные в Статье 83 Делегированного Регламента (ЕС) 2015/2446
<a id="p104285"></a>31 - создание ипотеки, залога на землю, антихреза или другого права, которое считается равным праву, относящемуся к недвижимому имуществу;
<a id="p104286"></a>32 - уступка иска, залог с передачей владения, товаров, ценных бумаг или требований или сберегательной книжки или внесения в реестр национального долга либо без передачи;
<a id="p104287"></a>33 - принятие совместной договорной ответственности за полную сумму долга третьим лицом, утвержденным для данных целей таможенными органами, или подача переводного векселя, оплата которого гарантирована этим третьим лицом;
<a id="p104288"></a>34 - депозит наличными или средства платежа, которые считаются равными им, кроме средств платежа в евро или в валюте государства-члена ЕС, в котором требуется гарантия;
<a id="p104289"></a>35 - участие после оплаты взноса в общей схеме гарантии, управляемой таможенными органами.

<a id="p104290"></a>VI/6. Срок оплаты
<a id="p104291"></a>Следующие коды используются для срока:
<a id="p104292"></a>1 Нормальный срок до платежа, т.е. максимально 10 дней после уведомления должника о таможенном долге в соответствии со [Статьей 108](https://bukva.ai/docs/reglament-9522013/statya-108#p101040) Кодекса
<a id="p104293"></a>2 Отсроченный платеж ([Статья 110](https://bukva.ai/docs/reglament-9522013/statya-110#p101055) Кодекса)

<a id="p104294"></a>VII/1. Вид отсроченного платежа
<a id="p104295"></a>Для отсроченного платежа используются следующие коды:
<a id="p104296"></a>1 [Статья 110(b)](https://bukva.ai/docs/reglament-9522013/statya-1#p101059) Кодекса, т.е. глобально в отношении каждой суммы импортной или экспортной пошлины, внесенной в счета в соответствии с [первым подпараграфом Статьи 105(1)](https://bukva.ai/docs/reglament-9522013/statya-1#p101024) в установленный срок, который не превышает 31 дня
<a id="p104297"></a>2 [Статья 110(c)](https://bukva.ai/docs/reglament-9522013/statya-1#p101060) Кодекса, т.е. глобально в отношении всех сумм импортной или экспортной пошлины, образующих единую запись в соответствии со [вторым подпараграфом Статьи 105(1)](https://bukva.ai/docs/reglament-9522013/statya-1#p101025)

<a id="p104298"></a>VIII/9. Правовое основание
<a id="p104299"></a>Следующие коды используются в качестве правового основания:


| <a id="p104300"></a>Код | <a id="p104301"></a>Описание | <a id="p104302"></a>Правовое основание |
| --- | --- | --- |
| <a id="p104303"></a>A | <a id="p104304"></a>Переплаченные суммы импортной или экспортной пошлины | <a id="p104305"></a>[Статья 117](https://bukva.ai/docs/reglament-9522013/statya-117#p101120) Кодекса |
| <a id="p104306"></a>B | <a id="p104307"></a>Дефектные товары или товары, которые не соответствуют условиям договора | <a id="p104308"></a>[Статья 118](https://bukva.ai/docs/reglament-9522013/statya-118#p101126) Кодекса |
| <a id="p104309"></a>C | <a id="p104310"></a>Ошибка компетентных органов | <a id="p104311"></a>[Статья 119](https://bukva.ai/docs/reglament-9522013/statya-119#p101136) Кодекса |
| <a id="p104312"></a>D | <a id="p104313"></a>В интересах справедливости | <a id="p104314"></a>[Статья 120](https://bukva.ai/docs/reglament-9522013/statya-120#p101146) Кодекса |
| <a id="p104315"></a>E | <a id="p104316"></a>Сумма импортной или экспортной пошлины, выплаченной в отношении таможенной декларации, признанной недействительной в соответствии со [Статьей 174](https://bukva.ai/docs/reglament-9522013/statya-174#p101530) Кодекса | <a id="p104317"></a>[Статья 116(1)](https://bukva.ai/docs/reglament-9522013/statya-1#p101096) Кодекса |


<a id="p104318"></a>IX/1. Перемещение товаров
<a id="p104319"></a>Следующие коды используются для правового основания перемещения:
<a id="p104320"></a>Для товаров, находящихся на временном хранении:
<a id="p104321"></a>A - [Статья 148(5)(a)](https://bukva.ai/docs/reglament-9522013/statya-1#p101378) Кодекса
<a id="p104322"></a>B - [Статья 148(5)(b)](https://bukva.ai/docs/reglament-9522013/statya-1#p101379) Кодекса
<a id="p104323"></a>C - [Статья 148(5)(c)](https://bukva.ai/docs/reglament-9522013/statya-1#p101380) Кодекса

<a id="p104324"></a>X/1. Государство(а)-член(ы) ЕС, связанные с услугами регулярного судоходства
<a id="p104325"></a>Следующие коды используются в качестве определителя:
<a id="p104326"></a>0 участвующие государства-члены ЕС;
<a id="p104327"></a>1 потенциально участвующие государства-члены ЕС.

<a id="p104328"></a>XIII/8. Код статуса налогового представителя
<a id="p104329"></a>Используются следующие коды:
<a id="p104330"></a>1 заявитель действует под своим собственным именем и от своего собственного имени;
<a id="p104331"></a>2 налоговый представитель действует от имени заявителя.

<a id="p104332"></a>XVI/1. Экономическая деятельность
<a id="p104333"></a>Следующие коды используются для деятельности:
<a id="p104334"></a>1 импорт
<a id="p104335"></a>2 перевозка
<a id="p104336"></a>3 хранение
<a id="p104337"></a>4 обработка

<a id="p104338"></a>XVIII/1. Система стандартного обмена
<a id="p104339"></a>Используются следующие коды:
<a id="p104340"></a>1 Система стандартного обмена без предварительного импорта замещающей продукции
<a id="p104341"></a>2 Система стандартного обмена с предварительным импортом замещающей продукции

<a id="p104342"></a>XVIII/2. Замещающая продукция
<a id="p104343"></a>Используются следующие коды:
<a id="p104344"></a>4 Взятие проб, иллюстрации или технические описания
<a id="p104345"></a>5 Выполнение анализов
<a id="p104346"></a>7 Другие средства идентификации


<a id="p104347"></a>Приложение B

<a id="p104348"></a>**ФОРМЫ И КОДЫ**
**ТРЕБОВАНИЙ К ОБЩИМ ДАННЫМ ДЛЯ ДЕКЛАРАЦИЙ, УВЕДОМЛЕНИЙ**
**И ДОКАЗАТЕЛЬСТВА ТАМОЖЕННОГО СТАТУСА ТОВАРОВ СОЮЗА**
[(СТАТЬЯ 2(2))](https://bukva.ai/docs/reglament-20152447/statya-2#p100126)

<a id="p104349"></a>**ВВЕДЕНИЕ**

<a id="p104350"></a>(1) Формы, коды и, если это применимо, структура элементов данных, включенных в настоящее Приложение, применяются в отношении требований к данным для деклараций, уведомлений и доказательства таможенного статуса товаров Союза, предусмотренных в Приложении B к Делегированному Регламенту (ЕС) 2015/2446.
<a id="p104351"></a>(2) Формы, коды и, если это применимо, структура элементов данных, включенных в настоящее Приложение, применяются к декларациям, уведомлениям и доказательству таможенного статуса товаров Союза, составленным посредством использования электронных технологий обработки данных.
<a id="p104352"></a>(3) Количество элементов на уровне заголовка декларации (D), включенное в [таблицу](https://bukva.ai/docs/reglament-20152447/statya-350#p104417) в Титуле I настоящего Приложения, показывает, сколько раз элемент данных можно использовать на уровне заголовка декларации внутри декларации, уведомления или доказательства таможенного статуса товаров Союза.
<a id="p104353"></a>(4) Количество элементов на уровне мастер-коносамента (MC), включенное в [таблицу](https://bukva.ai/docs/reglament-20152447/statya-350#p104417) в Титуле I настоящего Приложения, показывает, сколько раз элемент данных можно использовать на уровне мастер-коносамента (MC).
<a id="p104354"></a>(5) Количество элементов на уровне пунктов товаров мастер-коносамента (MI), включенное в [таблицу](https://bukva.ai/docs/reglament-20152447/statya-350#p104417) в Титуле I настоящего Приложения, показывает, сколько раз элемент данных можно использовать на уровне пунктов товаров мастер-коносамента.
<a id="p104355"></a>(6) Количество элементов на уровне домашнего коносамента (HC), включенное в [таблицу](https://bukva.ai/docs/reglament-20152447/statya-350#p104417) в Титуле I настоящего Приложения, показывает, сколько раз элемент данных можно использовать на уровне домашнего коносамента.
<a id="p104356"></a>(7) Количество элементов на уровне пунктов товаров домашнего коносамента (HI), включенное в [таблицу](https://bukva.ai/docs/reglament-20152447/statya-350#p104417) в Титуле I настоящего Приложения, показывает, сколько раз элемент данных можно использовать на уровне пунктов товаров домашнего коносамента.
<a id="p104357"></a>(8) Кардинальное число на уровне отгрузки товаров (GS), включенное в [таблицу](https://bukva.ai/docs/reglament-20152447/statya-350#p104417) в Титуле I настоящего Приложения, показывает сколько раз элемент данных можно использовать на уровне отгрузки товаров.
<a id="p104358"></a>(9) Количество элементов на уровне пунктов товаров правительственного агентства (SI), включенное в [таблицу](https://bukva.ai/docs/reglament-20152447/statya-350#p104417) в Титуле I настоящего Приложения, показывает, сколько раз элемент данных можно использовать на уровне пунктов товаров правительственного агентства.
<a id="p104359"></a>(10) Если информация в декларации, уведомлении или доказательстве таможенного статуса товаров Союза, рассматриваемая в Приложении B к Делегированному Регламенту (ЕС) 2015/2446, принимает форму кодов, применяется список кодов, предусмотренный в [Титуле II](https://bukva.ai/docs/reglament-20152447/statya-350#p107545).
<a id="p104360"></a>(11) Национальные коды могут использоваться государствами-членами ЕС для элементов данных [11 10 000 000](https://bukva.ai/docs/reglament-20152447/statya-350#p104474) Дополнительная процедура, [12 01 000 000](https://bukva.ai/docs/reglament-20152447/statya-350#p104479) Предыдущий документ (подэлемент [12 01 005 000](https://bukva.ai/docs/reglament-20152447/statya-350#p104500) единица измерения и спецификатор), [12 02 000 000](https://bukva.ai/docs/reglament-20152447/statya-350#p104517) Дополнительная информация (подэлемент [12 02 008 000](https://bukva.ai/docs/reglament-20152447/statya-350#p104520) код), [12 03 000 000](https://bukva.ai/docs/reglament-20152447/statya-350#p104529) Подтверждающий документ (подэлементы [12 03 002 000](https://bukva.ai/docs/reglament-20152447/statya-350#p104536) Тип и [12 03 005 000](https://bukva.ai/docs/reglament-20152447/statya-350#p104545)), [12 04 000 000](https://bukva.ai/docs/reglament-20152447/statya-350#p104577) Дополнительная ссылка (подэлемент [12 04 002 000](https://bukva.ai/docs/reglament-20152447/statya-350#p104584) Тип), [14 03 000 000](https://bukva.ai/docs/reglament-20152447/statya-350#p105483) Пошлины и налоги (подэлемент [14 03 039 000](https://bukva.ai/docs/reglament-20152447/statya-350#p105486) Тип налога и подэлемент [14 03 040 005](https://bukva.ai/docs/reglament-20152447/statya-350#p105506) Единица измерения и спецификатор), [18 09 000 000](https://bukva.ai/docs/reglament-20152447/statya-350#p106018) Код товара (подэлемент [18 09 060 000](https://bukva.ai/docs/reglament-20152447/statya-350#p106039) Национальный дополнительный код), [16 04 000 000](https://bukva.ai/docs/reglament-20152447/statya-350#p105669) Регион места назначения и [16 10 000 000](https://bukva.ai/docs/reglament-20152447/statya-350#p105711) Регион отправки. Государства-члены ЕС уведомляют Европейскую Комиссию о списке национальных кодов, используемых для данных элементов данных. Европейская Комиссия опубликовывает список указанных кодов.
<a id="p104361"></a>(12) Термин "тип/длина" в разъяснении элемента указывает на требование для типа данных и длины данных. Коды для типов данных следующие:
<a id="p104362"></a>a - буквенный;
<a id="p104363"></a>n - цифровой;
<a id="p104364"></a>an - буквенно-цифровой.
<a id="p104365"></a>Число, следующее за кодом, указывает на допустимую длину данных.
<a id="p104366"></a>Применяется следующее.
<a id="p104367"></a>Дополнительные две точки перед индикатором длины означают, что данные не имеют фиксированной длины, но они могут иметь длину до количества знаков, определенных индикатором длины. Запятая в длине данных означает, что элемент может содержать десятые доли, знаки до запятой указывают общую длину элемента, знаки после запятой указывают максимальное количество знаков после десятичного знака.
<a id="p104368"></a>Примеры длины и формы поля:
<a id="p104369"></a>a1 - 1 буквенный знак, фиксированная длина;
<a id="p104370"></a>n2 - 2 цифровых знака, фиксированная длина;
<a id="p104371"></a>an3 - 3 буквенно-цифровых знака, фиксированная длина;
<a id="p104372"></a>a..4 - до 4 буквенных знаков;
<a id="p104373"></a>n..5 - до 5 цифровых знаков;
<a id="p104374"></a>an..6 - до 6 буквенно-цифровых знаков;
<a id="p104375"></a>n..7,2 - до 7 цифровых знаков, в том числе максимально 2 десятичных знака, ограничителю разрешено "плавать".
<a id="p104376"></a>(13) Используются следующие ссылки на списки кодов, определенные в международных стандартах или в правовых актах ЕС:


<table>
<colgroup><col width="4%"><col width="23%"><col width="20%"><col width="52%"></colgroup>
<tr><td></td><td><a id="p104377"></a>Краткое наименование</td><td><a id="p104378"></a>Источник</td><td><a id="p104379"></a>Определение</td></tr>
<tr><td><a id="p104380"></a>1</td><td><a id="p104381"></a>Код типа упаковки</td><td><a id="p104382"></a>Рекомендация UN/ECE 21</td><td><a id="p104383"></a>Код типа упаковки, определенный в самой последней версии Приложения IV к Рекомендации UN/ECE 21</td></tr>
<tr><td><a id="p104384"></a>2</td><td><a id="p104385"></a>Код валюты</td><td><a id="p104386"></a>ISO 4217</td><td><a id="p104387"></a>Трехбуквенный код, определенный Международным стандартом ISO 4217</td></tr>
<tr><td><a id="p104388"></a>3</td><td><a id="p104389"></a>Код GEONOM</td><td><a id="p104390"></a>Регламент (ЕС) Европейской Комиссии</td><td><a id="p104391"></a>Буквенные коды Союза для стран и территорий основываются на текущих двухбуквенных кодах ISO (a2), насколько они соответствуют требованиям Имплементационного Регламента (ЕС) 2020/1470 от 12 октября 2020 г. о номенклатуре стран и территорий для европейской статистики по международной торговле товарами и географической разбивке для статистики по другим видам бизнеса (ОЖ N L 334, 13.10.2020, стр. 2 - 21).<br>В контексте транзитных операций должен использоваться код страны ISO 3166 alpha-2, и код "XI" должен использоваться для Северной Ирландии.</td></tr>
<tr><td><a id="p104392"></a>4</td><td><a id="p104393"></a>UN/LOCODE</td><td><a id="p104394"></a><a href="https://bukva.ai/docs/16-eek-oon-evropeyskaya">Рекомендация</a> UNECE 16</td><td><a id="p104395"></a>UN/LOCODE, определенный в <a href="https://bukva.ai/docs/16-eek-oon-evropeyskaya">Рекомендации</a> UNECE 16</td></tr>
<tr><td><a id="p104396"></a>5</td><td><a id="p104397"></a>Номер UN</td><td><a id="p104398"></a><a href="https://bukva.ai/docs/evropeyskoe-soglashenie-o-mezhdunarodnoy-3/statya-1">Соглашение</a> ADR</td><td><a id="p104399"></a>Номер UN, определенный в Приложении A Части 3, Таблице A (Список опасных товаров) к Европейскому <a href="https://bukva.ai/docs/evropeyskoe-soglashenie-o-mezhdunarodnoy-3/statya-1">соглашению</a> о международной перевозке опасных товаров железнодорожным транспортом</td></tr>
<tr><td><a id="p104400"></a>6</td><td><a id="p104401"></a>Код для типов транспортных средств</td><td><a id="p104402"></a><a href="https://bukva.ai/docs/28-eek-oon-evropeyskaya">Рекомендация</a> UNECE 28</td><td><a id="p104403"></a>Коды для типов транспортных средств, определенные в <a href="https://bukva.ai/docs/28-eek-oon-evropeyskaya">Рекомендации</a> UNECE 28</td></tr>
<tr><td colspan="4"><a id="p104404"></a><a id="p104405"></a>7<br>Код для характера сделки</td></tr>
<tr><td><a id="p104406"></a>Регламент (ЕС) 113/2010 Европейской Комиссии</td><td><a id="p104407"></a>Код для характера сделки, определенный в Приложении II к Регламенту (ЕС) 113/20120 Европейской Комиссии</td><td><a id="p104408"></a>8</td><td><a id="p104409"></a>Коды указания характера пункта UPU</td></tr>
<tr><td><a id="p104410"></a>Список кодов UPU136</td><td><a id="p104411"></a>Коды указания характера пункта UPU (Международный почтовый союз)</td><td><a id="p104412"></a>9</td><td><a id="p104413"></a>Коды CUS</td></tr>
<tr><td><a id="p104414"></a>ECICS (Европейская таможенная классификация химических веществ)</td><td><a id="p104415"></a>Номер таможенного союза и статистики (CUS), присвоенный в Европейской таможенной классификации химических веществ (ECICS) основным химическим веществам и препаратам.</td><td></td><td><a id="p104416"></a>ТИТУЛ I. ФОРМЫ И КОЛИЧЕСТВО ЭЛЕМЕНТОВ ТРЕБОВАНИЙ</td></tr>
</table>

**К ОБЩИМ ДАННЫМ ДЛЯ ДЕКЛАРАЦИЙ И УВЕДОМЛЕНИЙ**


| <a id="p104417"></a>Номер элемента данных/подэлемента данных класса/подэлемента данных подкласса | <a id="p104418"></a>Название элемента/класса данных | <a id="p104419"></a>Название элемента/класса данных | <a id="p104420"></a>Название подкласса/подэлемента данных | <a id="p104421"></a>Формат | <a id="p104422"></a>Список кодов в [Титуле II](https://bukva.ai/docs/reglament-20152447/statya-350#p107545)<br>(Y (да)/N (нет)) | <a id="p104423"></a>Примечания |
| --- | --- | --- | --- | --- | --- | --- |
| <a id="p104424"></a>11 01 000 000 | <a id="p104425"></a>Вид декларации |  |  | <a id="p104426"></a>a2 | <a id="p104427"></a>Y |  |
| <a id="p104428"></a>11 02 000 000 | <a id="p104429"></a>Вид дополнительной декларации |  |  | <a id="p104430"></a>a1 | <a id="p104431"></a>Y |  |
| <a id="p104432"></a>11 03 000 000 | <a id="p104433"></a>Номер пунктов товаров |  |  | <a id="p104434"></a>n..5 | <a id="p104435"></a>N |  |
| <a id="p104436"></a>11 04 00 000 | <a id="p104437"></a>Индикатор особого обстоятельства |  |  | <a id="p104438"></a>an3 | <a id="p104439"></a>Y |  |
| <a id="p104440"></a>11 05 000 000 | <a id="p104441"></a>Индикатор повторного ввоза |  |  | <a id="p104442"></a>n1 | <a id="p104443"></a>Y |  |
| <a id="p104444"></a>11 06 000 000 | <a id="p104445"></a>Разделенный груз |  |  |  | <a id="p104446"></a>N |  |
| <a id="p104447"></a>11 06 001 000 |  | <a id="p104448"></a>Индикатор разделенного груза |  | <a id="p104449"></a>n1 | <a id="p104450"></a>Y |  |
| <a id="p104451"></a>11 06 002 000 |  | <a id="p104452"></a>Предыдущий MRN |  | <a id="p104453"></a>an18 | <a id="p104454"></a>N |  |
| <a id="p104455"></a>11 07 000 000 | <a id="p104456"></a>Безопасность |  |  | <a id="p104457"></a>n1 | <a id="p104458"></a>Y |  |
| <a id="p104459"></a>11 08 000 000 | <a id="p104460"></a>Индикатор сокращенного комплекта данных |  |  | <a id="p104461"></a>n1 | <a id="p104462"></a>Y |  |
| <a id="p104463"></a>11 09 000 000 | <a id="p104464"></a>Процедура |  |  |  | <a id="p104465"></a>N |  |
| <a id="p104466"></a>11 09 001 000 |  | <a id="p104467"></a>Запрошенная процедура |  | <a id="p104468"></a>an | <a id="p104469"></a>Y |  |
| <a id="p104470"></a>11 09 002 000 |  | <a id="p104471"></a>Предыдущая процедура |  | <a id="p104472"></a>an | <a id="p104473"></a>Y |  |
| <a id="p104474"></a>11 10 000 000 | <a id="p104475"></a>Дополнительная процедура |  |  | <a id="p104476"></a>an3 | <a id="p104477"></a>Y | <a id="p104478"></a>Коды Союза далее определены в [Титуле II](https://bukva.ai/docs/reglament-20152447/statya-350#p107545).<br>Государства-члены ЕС могут определить национальные коды. Национальные коды должны иметь формат n1an2. |
| <a id="p104479"></a>12 01 000 000 | <a id="p104480"></a>Предыдущие документы |  |  |  | <a id="p104481"></a>N |  |
| <a id="p104482"></a>12 01 001 000 |  | <a id="p104483"></a>Исходящий номер |  | <a id="p104484"></a>an..70 | <a id="p104485"></a>N |  |
| <a id="p104486"></a>12 01 002 000 |  | <a id="p104487"></a>Тип |  | <a id="p104488"></a>an4 | <a id="p104489"></a>N | <a id="p104490"></a>Коды можно найти в базе данных TARIC |
| <a id="p104491"></a>12 01 003 000 |  | <a id="p104492"></a>Тип упаковки |  | <a id="p104493"></a>an..2 | <a id="p104494"></a>N | <a id="p104495"></a>Код типа упаковки, указанный во [вводной части 13, номер 1](https://bukva.ai/docs/reglament-20152447/statya-350#p104380) |
| <a id="p104496"></a>12 01 004 000 |  | <a id="p104497"></a>Количество упаковок |  | <a id="p104498"></a>n..8 | <a id="p104499"></a>N |  |
| <a id="p104500"></a>12 01 005 000 |  | <a id="p104501"></a>Единица измерения и спецификатор |  | <a id="p104502"></a>an..4 | <a id="p104503"></a>N | <a id="p104504"></a>Необходимо использовать единицы измерения и спецификаторы, определенные в TARIC. В таких случаях формат единиц измерения и спецификаторов должен быть an..4, а не n..4, который зарезервирован для национальных единиц измерения и спецификаторов.<br>Если в TARIC нет таких единиц измерения и спецификаторов, могут использоваться национальные единицы измерения и спецификаторы. Их формат должен быть n..4. |
| <a id="p104505"></a>12 01 006 000 |  | <a id="p104506"></a>Количество |  | <a id="p104507"></a>n..16,6 | <a id="p104508"></a>N |  |
| <a id="p104509"></a>12 01 079 000 |  | <a id="p104510"></a>Дополнение информации |  | <a id="p104511"></a>an..35 | <a id="p104512"></a>N |  |
| <a id="p104513"></a>12 01 007 000 |  | <a id="p104514"></a>Идентификатор пунктов товаров |  | <a id="p104515"></a>n..5 | <a id="p104516"></a>N |  |
| <a id="p104517"></a>12 02 000 000 | <a id="p104518"></a>Дополнительная информация |  |  |  | <a id="p104519"></a>N |  |
| <a id="p104520"></a>12 02 008 000 |  | <a id="p104521"></a>Код |  | <a id="p104522"></a>an5 | <a id="p104523"></a>Y | <a id="p104524"></a>Коды Союза далее определены в [Титуле II](https://bukva.ai/docs/reglament-20152447/statya-350#p107545).<br>Государства-члены ЕС могут определить национальные коды. Национальные коды должны иметь формат a1an4. |
| <a id="p104525"></a>12 02 009 000 |  | <a id="p104526"></a>Текст |  | <a id="p104527"></a>an..512 | <a id="p104528"></a>N |  |
| <a id="p104529"></a>12 03 000 000 | <a id="p104530"></a>Подтверждающие документы |  |  |  | <a id="p104531"></a>N |  |
| <a id="p104532"></a>12 03 001 000 |  | <a id="p104533"></a>Исходящий номер |  | <a id="p104534"></a>an..70 | <a id="p104535"></a>N |  |
| <a id="p104536"></a>12 03 002 000 |  | <a id="p104537"></a>Тип |  | <a id="p104538"></a>an4 | <a id="p104539"></a>N | <a id="p104540"></a>Коды Союза или международных документов, сертификатов и разрешений можно найти в базе данных TARIC. Их формат a1an3.<br>Для национальных документов, сертификатов и разрешений государства-члены ЕС могут определить национальные коды. Национальные коды должны иметь формат a1an3. |
| <a id="p104541"></a>12 03 010 000 |  | <a id="p104542"></a>Название выдающего органа |  | <a id="p104543"></a>an..70 | <a id="p104544"></a>N |  |
| <a id="p104545"></a>12 03 005 000 |  | <a id="p104546"></a>Единица измерения и спецификатор | <a id="p104547"></a>- | <a id="p104548"></a>an..4 | <a id="p104549"></a>N | <a id="p104550"></a>Необходимо использовать единицы измерения и спецификаторы, определенные в TARIC. В таких случаях формат единиц измерения и спецификаторов должен быть an..4, а не n..4, который зарезервирован для национальных единиц измерения и спецификаторов.<br>Если в TARIC нет таких единиц измерения и спецификаторов, могут использоваться национальные единицы измерения и спецификаторы. Их формат должен быть n..4. |
| <a id="p104551"></a>12 03 006 000 |  | <a id="p104552"></a>Количество | <a id="p104553"></a>- | <a id="p104554"></a>n..16,6 | <a id="p104555"></a>N |  |
| <a id="p104556"></a>12 03 011 000 |  | <a id="p104557"></a>Дата срока действия |  | <a id="p104558"></a>an..19 | <a id="p104559"></a>N |  |
| <a id="p104560"></a>12 03 012 000 |  | <a id="p104561"></a>Валюта |  | <a id="p104562"></a>a3 | <a id="p104563"></a>N | <a id="p104564"></a>Код валюты, указанный во [введении 13, номер 2](https://bukva.ai/docs/reglament-20152447/statya-350#p104384). |
| <a id="p104565"></a>12 03 013 000 |  | <a id="p104566"></a>Номер строки документа |  | <a id="p104567"></a>n..5 | <a id="p104568"></a>N |  |
| <a id="p104569"></a>12 03 014 000 |  | <a id="p104570"></a>Сумма |  | <a id="p104571"></a>n..16,2 | <a id="p104572"></a>N |  |
| <a id="p104573"></a>12 03 079 000 |  | <a id="p104574"></a>Дополнение информации |  | <a id="p104575"></a>an..35 | <a id="p104576"></a>N |  |
| <a id="p104577"></a>12 04 000 000 | <a id="p104578"></a>Дополнительная ссылка |  |  |  | <a id="p104579"></a>N |  |
| <a id="p104580"></a>12 04 001 000 |  | <a id="p104581"></a>Исходящий номер |  | <a id="p104582"></a>an..70 | <a id="p104583"></a>N |  |
| <a id="p104584"></a>12 04 002 000 |  | <a id="p104585"></a>Тип |  | <a id="p104586"></a>an4 | <a id="p104587"></a>N | <a id="p104588"></a>Коды Союза можно найти в базе данных TARIC. Их формат a1an3.<br>Государства-члены ЕС могут определить национальные коды. Национальные коды должны иметь формат a1an3. |
| <a id="p104589"></a>12 05 000 000 | <a id="p104590"></a>Транспортный документ |  |  |  | <a id="p104591"></a>N |  |
| <a id="p104592"></a>12 05 001 000 |  | <a id="p104593"></a>Исходящий номер |  | <a id="p104594"></a>an..70 | <a id="p104595"></a>N |  |
| <a id="p104596"></a>12 05 002 000 |  | <a id="p104597"></a>Тип |  | <a id="p104598"></a>an4 | <a id="p104599"></a>N | <a id="p104600"></a>Коды можно найти в базе данных TARIC. |
| <a id="p104601"></a>12 06 000 000 | <a id="p104602"></a>Номер [карнета](https://bukva.ai/docs/tamozhennaya-konventsiya-o-mezhdunarodnoy-2/statya-64#p100621) TIR |  |  | <a id="p104603"></a>an..12 | <a id="p104604"></a>N |  |
| <a id="p104605"></a>12 07 000 000 | <a id="p104606"></a>Ссылка на запрос документов |  |  | <a id="p104607"></a>an..17 | <a id="p104608"></a>N |  |
| <a id="p104609"></a>12 08 000 000 | <a id="p104610"></a>Исходящий номер/UCR (уникальный номер груза) |  |  | <a id="p104611"></a>an..35 | <a id="p104612"></a>N |  |
| <a id="p104613"></a>12 09 000 000 | <a id="p104614"></a>LRN |  |  | <a id="p104615"></a>an..22 | <a id="p104616"></a>N |  |
| <a id="p104617"></a>12 10 000 000 | <a id="p104618"></a>Отсроченный платеж |  |  | <a id="p104619"></a>an..35 | <a id="p104620"></a>N |  |
| <a id="p104621"></a>12 11 000 000 | <a id="p104622"></a>Склад |  |  |  | <a id="p104623"></a>N |  |
| <a id="p104624"></a>12 11 002 000 |  | <a id="p104625"></a>Тип |  | <a id="p104626"></a>a1 | <a id="p104627"></a>Y |  |
| <a id="p104628"></a>12 11 015 000 |  | <a id="p104629"></a>Идентификатор |  | <a id="p104630"></a>an..35 | <a id="p104631"></a>N |  |
| <a id="p104632"></a>12 12 000 000 | <a id="p104633"></a>Разрешение |  |  |  | <a id="p104634"></a>N |  |
| <a id="p104635"></a>12 12 002 000 |  | <a id="p104636"></a>Тип |  | <a id="p104637"></a>an..4 | <a id="p104638"></a>N | <a id="p104639"></a>Коды можно найти в базе данных TARIC. |
| <a id="p104640"></a>12 12 001 000 |  | <a id="p104641"></a>Исходящий номер |  | <a id="p104642"></a>an..35 | <a id="p104643"></a>N |  |
| <a id="p104644"></a>12 12 080 000 |  | <a id="p104645"></a>Владелец разрешения |  | <a id="p104646"></a>an..17 | <a id="p104647"></a>N | <a id="p104648"></a>Структура номера EORI определена в [Титуле II](https://bukva.ai/docs/reglament-20152447/statya-350#p110681) Приложения 12-01. |
| <a id="p104649"></a>13 01 000 000 | <a id="p104650"></a>Экспортер |  |  |  | <a id="p104651"></a>N |  |
| <a id="p104652"></a>13 01 016 000 |  | <a id="p104653"></a>Имя/название |  | <a id="p104654"></a>an..70 | <a id="p104655"></a>N |  |
| <a id="p104656"></a>13 01 017 000 |  | <a id="p104657"></a>Идентификационный номер |  | <a id="p104658"></a>an..17 | <a id="p104659"></a>N | <a id="p104660"></a>Структура номера EORI определена в [Титуле II](https://bukva.ai/docs/reglament-20152447/statya-350#p110681) Приложения 12-01.<br>Структура уникального идентификационного номера третьей страны, признанной Союзом, определена в [Титуле II](https://bukva.ai/docs/reglament-20152447/statya-350#p104030). |
| <a id="p104661"></a>13 01 018 000 |  | <a id="p104662"></a>Адрес |  |  | <a id="p104663"></a>N |  |
| <a id="p104664"></a>13 01 018 019 |  |  | <a id="p104665"></a>Улица и номер | <a id="p104666"></a>an..70 | <a id="p104667"></a>N |  |
| <a id="p104668"></a>13 01 018 020 |  |  | <a id="p104669"></a>Страна | <a id="p104670"></a>a2 | <a id="p104671"></a>N | <a id="p104672"></a>Код GEONOM, указанный во [вводной части 13, номер 3](https://bukva.ai/docs/reglament-20152447/statya-350#p104388). |
| <a id="p104673"></a>13 01 018 021 |  |  | <a id="p104674"></a>Почтовый индекс | <a id="p104675"></a>an..17 | <a id="p104676"></a>N |  |
| <a id="p104677"></a>13 01 018 022 |  |  | <a id="p104678"></a>Город | <a id="p104679"></a>an..35 | <a id="p104680"></a>N |  |
| <a id="p104681"></a>13 02 000 000 | <a id="p104682"></a>Грузоотправитель |  |  |  | <a id="p104683"></a>N | <a id="p104684"></a>Используется код страны, определенный для D.E. [3/1](https://bukva.ai/docs/reglament-20152447/statya-350#p109057) Экспортер. |
| <a id="p104685"></a>13 02 016 000 |  | <a id="p104686"></a>Имя/Название |  | <a id="p104687"></a>an..70 | <a id="p104688"></a>N |  |
| <a id="p104689"></a>13 02 017 000 |  | <a id="p104690"></a>Идентификационный номер |  | <a id="p104691"></a>an..17 | <a id="p104692"></a>N | <a id="p104693"></a>Структура номера EORI определена в [Титуле II](https://bukva.ai/docs/reglament-20152447/statya-350#p110681) Приложения 12-01.<br>Структура уникального идентификационного номера третьей страны, признанной Союзом, определена в Титуле II для D.E. [1 301 017 000](https://bukva.ai/docs/reglament-20152447/statya-350#p108431) Идентификационный номер. |
| <a id="p104694"></a>13 02 028 000 |  | <a id="p104695"></a>Тип лица |  | <a id="p104696"></a>n1 | <a id="p104697"></a>Y |  |
| <a id="p104698"></a>13 02 018 000 |  | <a id="p104699"></a>Адрес |  |  | <a id="p104700"></a>N |  |
| <a id="p104701"></a>13 02 018 019 |  |  | <a id="p104702"></a>Улица и номер | <a id="p104703"></a>an..70 | <a id="p104704"></a>N |  |
| <a id="p104705"></a>13 02 018 023 |  |  | <a id="p104706"></a>Улица | <a id="p104707"></a>an..70 | <a id="p104708"></a>N |  |
| <a id="p104709"></a>13 02 018 024 |  |  | <a id="p104710"></a>Дополнительная строка для улицы | <a id="p104711"></a>an..70 | <a id="p104712"></a>N |  |
| <a id="p104713"></a>13 02 018025 |  |  | <a id="p104714"></a>Номер | <a id="p104715"></a>an..35 | <a id="p104716"></a>N |  |
| <a id="p104717"></a>13 02 018 026 |  |  | <a id="p104718"></a>Почтовый ящик | <a id="p104719"></a>an..70 | <a id="p104720"></a>N |  |
| <a id="p104721"></a>13 02 018 027 |  |  | <a id="p104722"></a>Подразделение | <a id="p104723"></a>an..35 | <a id="p104724"></a>N |  |
| <a id="p104725"></a>13 02 018 020 |  |  | <a id="p104726"></a>Страна | <a id="p104727"></a>a2 | <a id="p104728"></a>N | <a id="p104729"></a>Код GEONOM, указанный во [вводной части 13, номер 3](https://bukva.ai/docs/reglament-20152447/statya-350#p104388). |
| <a id="p104730"></a>13 02 018 021 |  |  | <a id="p104731"></a>Почтовый индекс | <a id="p104732"></a>an..17 | <a id="p104733"></a>N |  |
| <a id="p104734"></a>13 02 018 022 |  |  | <a id="p104735"></a>Город | <a id="p104736"></a>an..35 | <a id="p104737"></a>N |  |
| <a id="p104738"></a>13 02 029 000 |  | <a id="p104739"></a>Сообщение |  |  | <a id="p104740"></a>N |  |
| <a id="p104741"></a>13 02 029 015 |  |  | <a id="p104742"></a>Определитель | <a id="p104743"></a>an..512 | <a id="p104744"></a>N |  |
| <a id="p104745"></a>13 02 029 002 |  |  | <a id="p104746"></a>Тип | <a id="p104747"></a>an..3 | <a id="p104748"></a>Y |  |
| <a id="p104749"></a>13 02 074 000 |  | <a id="p104750"></a>Лицо для контакта |  |  |  |  |
| <a id="p104751"></a>13 02 074 016 |  |  | <a id="p104752"></a>Имя | <a id="p104753"></a>an..70 | <a id="p104754"></a>N |  |
| <a id="p104755"></a>13 02 074 075 |  |  | <a id="p104756"></a>Номер телефона | <a id="p104757"></a>an..35 | <a id="p104758"></a>N |  |
| <a id="p104759"></a>13 02 074 076 |  |  | <a id="p104760"></a>Адрес электронной почты | <a id="p104761"></a>an..256 | <a id="p104762"></a>N |  |
| <a id="p104763"></a>13 03 000 000 | <a id="p104764"></a>Грузополучатель |  |  | <a id="p104765"></a>an..35 | <a id="p104766"></a>N |  |
| <a id="p104767"></a>13 03 016 000 |  | <a id="p104768"></a>Имя/Название |  | <a id="p104769"></a>an..70 | <a id="p104770"></a>N |  |
| <a id="p104771"></a>13 03 017 000 |  | <a id="p104772"></a>Идентификационный номер |  | <a id="p104773"></a>an..17 | <a id="p104774"></a>N | <a id="p104775"></a>Структура номера EORI определена в [Титуле II](https://bukva.ai/docs/reglament-20152447/statya-350#p110681) Приложения 12-01.<br>Структура уникального идентификационного номера третьей страны, признанной Союзом, определена в Титуле II для D.E. [1 301 017 000](https://bukva.ai/docs/reglament-20152447/statya-350#p108431) Идентификационный номер. |
| <a id="p104776"></a>13 03 017 000 |  | <a id="p104777"></a>Тип лица |  | <a id="p104778"></a>n1 | <a id="p104779"></a>Y | <a id="p104780"></a>Код типа лица, определенный в [титуле II](https://bukva.ai/docs/reglament-20152447/statya-350#p104030) для D.E.<br>Должен использоваться [13 02 028 000](https://bukva.ai/docs/reglament-20152447/statya-350#p108444) (Тип лица грузоотправителя). |
| <a id="p104781"></a>13 03 018 000 |  | <a id="p104782"></a>Адрес |  |  | <a id="p104783"></a>N |  |
| <a id="p104784"></a>13 03 018 019 |  |  | <a id="p104785"></a>Улица и номер | <a id="p104786"></a>an..70 | <a id="p104787"></a>N |  |
| <a id="p104788"></a>13 03 018 023 |  |  | <a id="p104789"></a>Улица | <a id="p104790"></a>an..70 | <a id="p104791"></a>N |  |
| <a id="p104792"></a>13 03 018 024 |  |  | <a id="p104793"></a>Дополнительная строка для улицы | <a id="p104794"></a>an..70 | <a id="p104795"></a>N |  |
| <a id="p104796"></a>13 03 018 025 |  |  | <a id="p104797"></a>Номер | <a id="p104798"></a>an..35 | <a id="p104799"></a>N |  |
| <a id="p104800"></a>13 03 018 026 |  |  | <a id="p104801"></a>Почтовый ящик | <a id="p104802"></a>an..70 | <a id="p104803"></a>N |  |
| <a id="p104804"></a>13 03 018 027 |  |  | <a id="p104805"></a>Подразделение | <a id="p104806"></a>an..35 | <a id="p104807"></a>N |  |
| <a id="p104808"></a>13 03 018 020 |  |  | <a id="p104809"></a>Страна | <a id="p104810"></a>a2 | <a id="p104811"></a>N | <a id="p104812"></a>Код GEONOM, указанный во [вводной части 13, номер 3](https://bukva.ai/docs/reglament-20152447/statya-350#p104388). |
| <a id="p104813"></a>13 03 018 021 |  |  | <a id="p104814"></a>Почтовый индекс | <a id="p104815"></a>an..17 | <a id="p104816"></a>N |  |
| <a id="p104817"></a>13 03 018 022 |  |  | <a id="p104818"></a>Город | <a id="p104819"></a>an..35 | <a id="p104820"></a>N |  |
| <a id="p104821"></a>13 03 029 000 |  | <a id="p104822"></a>Сообщение |  |  | <a id="p104823"></a>N |  |
| <a id="p104824"></a>13 03 029 015 |  |  | <a id="p104825"></a>Определитель | <a id="p104826"></a>an..512 | <a id="p104827"></a>N |  |
| <a id="p104828"></a>13 03 029 002 |  |  | <a id="p104829"></a>Тип | <a id="p104830"></a>an..3 | <a id="p104831"></a>Y | <a id="p104832"></a>Используется код типа сообщения, определенный в Титуле II для D.E. [13 02 029 002](https://bukva.ai/docs/reglament-20152447/statya-350#p108450) (Тип сообщения грузоотправителя). |
| <a id="p104833"></a>13 04 000 000 | <a id="p104834"></a>Импортер |  |  |  | <a id="p104835"></a>N |  |
| <a id="p104836"></a>13 04 016 000 |  | <a id="p104837"></a>Имя/Название |  | <a id="p104838"></a>an..70 | <a id="p104839"></a>N |  |
| <a id="p104840"></a>13 04 017 000 |  | <a id="p104841"></a>Идентификационный номер |  | <a id="p104842"></a>an..17 | <a id="p104843"></a>N | <a id="p104844"></a>Структура номера EORI определена в [Титуле II](https://bukva.ai/docs/reglament-20152447/statya-350#p110681) Приложения 12-01. |
| <a id="p104845"></a>13 04 018 000 |  | <a id="p104846"></a>Адрес |  |  | <a id="p104847"></a>N |  |
| <a id="p104848"></a>13 04 018 019 |  |  | <a id="p104849"></a>Улица и номер | <a id="p104850"></a>an..70 | <a id="p104851"></a>N |  |
| <a id="p104852"></a>13 04 018 029 |  |  | <a id="p104853"></a>Страна | <a id="p104854"></a>a2 | <a id="p104855"></a>N | <a id="p104856"></a>Код GEONOM, указанный во [вводной части 13, номер 3](https://bukva.ai/docs/reglament-20152447/statya-350#p104388) |
| <a id="p104857"></a>13 04 018 021 |  |  | <a id="p104858"></a>Почтовый индекс | <a id="p104859"></a>an..17 | <a id="p104860"></a>N |  |
| <a id="p104861"></a>13 04 018 022 |  |  | <a id="p104862"></a>Город | <a id="p104863"></a>an..35 | <a id="p104864"></a>N |  |
| <a id="p104865"></a>13 05 000 000 | <a id="p104866"></a>Декларант |  |  |  | <a id="p104867"></a>N |  |
| <a id="p104868"></a>13 05 016 000 |  | <a id="p104869"></a>Имя/Название |  | <a id="p104870"></a>an..70 | <a id="p104871"></a>N |  |
| <a id="p104872"></a>13 05 017 000 |  | <a id="p104873"></a>Идентификационный номер |  | <a id="p104874"></a>an..17 | <a id="p104875"></a>N | <a id="p104876"></a>Структура номера EORI определена в [Титуле II](https://bukva.ai/docs/reglament-20152447/statya-350#p110681) Приложения 12-01. |
| <a id="p104877"></a>13 05 018 000 |  | <a id="p104878"></a>Адрес |  |  | <a id="p104879"></a>N |  |
| <a id="p104880"></a>13 05 018 019 |  |  | <a id="p104881"></a>Улица и номер | <a id="p104882"></a>an..70 | <a id="p104883"></a>N |  |
| <a id="p104884"></a>13 05 018 023 |  |  | <a id="p104885"></a>Улица | <a id="p104886"></a>an..70 | <a id="p104887"></a>N |  |
| <a id="p104888"></a>13 05 018 024 |  |  | <a id="p104889"></a>Дополнительная строка для улицы | <a id="p104890"></a>an..70 | <a id="p104891"></a>N |  |
| <a id="p104892"></a>13 05 018 025 |  |  | <a id="p104893"></a>Номер | <a id="p104894"></a>an..35 | <a id="p104895"></a>N |  |
| <a id="p104896"></a>13 05 018 026 |  |  | <a id="p104897"></a>Почтовый ящик | <a id="p104898"></a>an..70 | <a id="p104899"></a>N |  |
| <a id="p104900"></a>13 05 018 027 |  |  | <a id="p104901"></a>Подразделение | <a id="p104902"></a>an..35 | <a id="p104903"></a>N |  |
| <a id="p104904"></a>13 05 018 020 |  |  | <a id="p104905"></a>Страна | <a id="p104906"></a>a2 | <a id="p104907"></a>N | <a id="p104908"></a>Код GEONOM, указанный во [вводной части 13, номер 3](https://bukva.ai/docs/reglament-20152447/statya-350#p104388). |
| <a id="p104909"></a>13 05 018 021 |  |  | <a id="p104910"></a>Почтовый индекс | <a id="p104911"></a>an..17 | <a id="p104912"></a>N |  |
| <a id="p104913"></a>13 05 018 022 |  |  | <a id="p104914"></a>Город | <a id="p104915"></a>an..35 | <a id="p104916"></a>N |  |
| <a id="p104917"></a>13 05 029 000 |  | <a id="p104918"></a>Сообщение |  |  | <a id="p104919"></a>N |  |
| <a id="p104920"></a>13 05 029 015 |  |  | <a id="p104921"></a>Определитель | <a id="p104922"></a>an..512 | <a id="p104923"></a>N |  |
| <a id="p104924"></a>13 05 029 002 |  |  | <a id="p104925"></a>Тип | <a id="p104926"></a>an..3 | <a id="p104927"></a>N | <a id="p104928"></a>Используется код типа сообщения, определенный в Титуле II для D.E. [13 02 029 002](https://bukva.ai/docs/reglament-20152447/statya-350#p108450) (Тип сообщения грузоотправителя). |
| <a id="p104929"></a>13 05 074 000 |  | <a id="p104930"></a>Лицо для контакта |  |  | <a id="p104931"></a>N |  |
| <a id="p104932"></a>13 05 074 016 |  |  | <a id="p104933"></a>Имя | <a id="p104934"></a>an..70 | <a id="p104935"></a>N |  |
| <a id="p104936"></a>13 05 074 075 |  |  | <a id="p104937"></a>Номер телефона | <a id="p104938"></a>an..35 | <a id="p104939"></a>N |  |
| <a id="p104940"></a>13 05 074 076 |  |  | <a id="p104941"></a>Адрес электронной почты | <a id="p104942"></a>an..256 | <a id="p104943"></a>N |  |
| <a id="p104944"></a>13 06 000 000 | <a id="p104945"></a>Представитель |  |  |  | <a id="p104946"></a>N |  |
| <a id="p104947"></a>13 06 016 000 |  | <a id="p104948"></a>Имя/Название |  | <a id="p104949"></a>an..70 | <a id="p104950"></a>N |  |
| <a id="p104951"></a>13 06 017 000 |  | <a id="p104952"></a>Идентификационный номер |  | <a id="p104953"></a>an..17 | <a id="p104954"></a>N | <a id="p104955"></a>Структура номера EORI определена в [Титуле II](https://bukva.ai/docs/reglament-20152447/statya-350#p110681) Приложения 12-01. Структура уникального идентификационного номера третьей страны, признанной Союзом, определена в Титуле II для D.E. [1 301 017 000](https://bukva.ai/docs/reglament-20152447/statya-350#p108431) Идентификационный номер. |
| <a id="p104956"></a>13 06 030 000 |  | <a id="p104957"></a>Статус |  | <a id="p104958"></a>n1 | <a id="p104959"></a>Y |  |
| <a id="p104960"></a>13 06 018 000 |  | <a id="p104961"></a>Адрес |  |  | <a id="p104962"></a>N |  |
|  |  |  |  |  |  |  |
| <a id="p104963"></a>13 06 018 023 |  |  | <a id="p104964"></a>Улица | <a id="p104965"></a>an..70 | <a id="p104966"></a>N |  |
| <a id="p104967"></a>13 06 018 024 |  |  | <a id="p104968"></a>Дополнительная строка для улицы | <a id="p104969"></a>an..70 | <a id="p104970"></a>N |  |
| <a id="p104971"></a>13 06 018 025 |  |  | <a id="p104972"></a>Номер | <a id="p104973"></a>an..35 | <a id="p104974"></a>N |  |
| <a id="p104975"></a>13 06 018 026 |  |  | <a id="p104976"></a>Почтовый ящик | <a id="p104977"></a>an..70 | <a id="p104978"></a>N |  |
| <a id="p104979"></a>13 06 018 027 |  |  | <a id="p104980"></a>Подразделение | <a id="p104981"></a>an..35 | <a id="p104982"></a>N |  |
| <a id="p104983"></a>13 06 018 020 |  |  | <a id="p104984"></a>Страна | <a id="p104985"></a>a2 | <a id="p104986"></a>N | <a id="p104987"></a>Код GEONOM, указанный во [вводной части 13, номер 3](https://bukva.ai/docs/reglament-20152447/statya-350#p104388). |
| <a id="p104988"></a>13 06 018 021 |  |  | <a id="p104989"></a>Почтовый индекс | <a id="p104990"></a>an..17 | <a id="p104991"></a>N |  |
| <a id="p104992"></a>13 06 018 022 |  |  | <a id="p104993"></a>Город | <a id="p104994"></a>an..35 | <a id="p104995"></a>N |  |
| <a id="p104996"></a>13 06 029028 |  | <a id="p104997"></a>Сообщение |  |  | <a id="p104998"></a>N |  |
| <a id="p104999"></a>13 06 029 015 |  |  | <a id="p105000"></a>Определитель | <a id="p105001"></a>an..512 | <a id="p105002"></a>N |  |
| <a id="p105003"></a>13 06 029 002 |  |  | <a id="p105004"></a>Тип | <a id="p105005"></a>an..3 | <a id="p105006"></a>Y | <a id="p105007"></a>Используется код типа сообщения, определенный в Титуле II для D.E. [13 02 029 002](https://bukva.ai/docs/reglament-20152447/statya-350#p108450) (тип сообщения грузоотправителя). |
| <a id="p105008"></a>13 06 074 00 |  | <a id="p105009"></a>Лицо для контакта |  |  | <a id="p105010"></a>N |  |
| <a id="p105011"></a>13 06 074 016 |  |  | <a id="p105012"></a>Имя | <a id="p105013"></a>an..70 | <a id="p105014"></a>N |  |
| <a id="p105015"></a>13 06 074 075 |  |  | <a id="p105016"></a>Номер телефона | <a id="p105017"></a>an..35 | <a id="p105018"></a>N |  |
| <a id="p105019"></a>13 06 074 076 |  |  | <a id="p105020"></a>Адрес электронной почты | <a id="p105021"></a>an..256 | <a id="p105022"></a>N |  |
| <a id="p105023"></a>13 07 000 000 | <a id="p105024"></a>Владелец процедуры транзита |  |  |  | <a id="p105025"></a>N |  |
| <a id="p105026"></a>13 07 016 000 |  | <a id="p105027"></a>Имя/Название |  | <a id="p105028"></a>an..70 | <a id="p105029"></a>N |  |
| <a id="p105030"></a>13 07 017 000 |  | <a id="p105031"></a>Идентификационный номер |  | <a id="p105032"></a>an..17 | <a id="p105033"></a>N | <a id="p105034"></a>Структура номера EORI определена в [Титуле II](https://bukva.ai/docs/reglament-20152447/statya-350#p110681) Приложения 12-01. |
| <a id="p105035"></a>13 07 078 000 |  | <a id="p105036"></a>Идентификационный номер владельца TIR |  | <a id="p105037"></a>an..17 | <a id="p105038"></a>N | <a id="p105039"></a>Структура номера EORI определена в [Титуле II](https://bukva.ai/docs/reglament-20152447/statya-350#p110681) Приложения 12-01. |
| <a id="p105040"></a>13 07 018 000 |  | <a id="p105041"></a>Адрес |  |  | <a id="p105042"></a>N |  |
| <a id="p105043"></a>13 07 019 019 |  |  | <a id="p105044"></a>Улица и номер | <a id="p105045"></a>an..70 | <a id="p105046"></a>N |  |
| <a id="p105047"></a>13 07 020 020 |  |  | <a id="p105048"></a>Страна | <a id="p105049"></a>a2 | <a id="p105050"></a>N | <a id="p105051"></a>Код GEONOM, указанный во [вводной части 13, номер 3](https://bukva.ai/docs/reglament-20152447/statya-350#p104388). |
| <a id="p105052"></a>13 07 021 021 |  |  | <a id="p105053"></a>Почтовый индекс | <a id="p105054"></a>an..17 | <a id="p105055"></a>N |  |
| <a id="p105056"></a>13 07 022 022 |  |  | <a id="p105057"></a>Страна | <a id="p105058"></a>a2 | <a id="p105059"></a>N |  |
| <a id="p105060"></a>13 07 074 000 |  | <a id="p105061"></a>Лицо для контакта |  |  | <a id="p105062"></a>N |  |
| <a id="p105063"></a>13 07 074 016 |  |  | <a id="p105064"></a>Имя | <a id="p105065"></a>an..70 | <a id="p105066"></a>N |  |
| <a id="p105067"></a>13 07 074 075 |  |  | <a id="p105068"></a>Номер телефона | <a id="p105069"></a>an..35 | <a id="p105070"></a>N |  |
| <a id="p105071"></a>13 07 074 076 |  |  | <a id="p105072"></a>Адрес электронной почты | <a id="p105073"></a>an..256 | <a id="p105074"></a>N |  |
| <a id="p105075"></a>13 08 000 000 | <a id="p105076"></a>Продавец |  |  |  | <a id="p105077"></a>N |  |
| <a id="p105078"></a>13 08 016 000 |  | <a id="p105079"></a>Имя/Название |  |  | <a id="p105080"></a>N |  |
| <a id="p105081"></a>13 08 017 000 |  | <a id="p105082"></a>Идентификационный номер |  | <a id="p105083"></a>an..17 | <a id="p105084"></a>N | <a id="p105085"></a>Структура номера EORI определена в [Титуле II](https://bukva.ai/docs/reglament-20152447/statya-350#p110681) Приложения 12-01 для.<br>Структура уникального идентификационного номера третьей страны, признанной Союзом, определена в Титуле II для D.E. [13 01 017 000](https://bukva.ai/docs/reglament-20152447/statya-350#p108431) Идентификационный номер |
| <a id="p105086"></a>13 08 028 000 |  | <a id="p105087"></a>Тип лица |  | <a id="p105088"></a>n1 | <a id="p105089"></a>Y | <a id="p105090"></a>Код типа лица, определенный в Титуле II для D.E.<br>Используется [13 02 028 000](https://bukva.ai/docs/reglament-20152447/statya-350#p108444) (Тип лица грузоотправителя) |
| <a id="p105091"></a>13 08 018 000 |  | <a id="p105092"></a>Адрес |  |  | <a id="p105093"></a>N |  |
| <a id="p105094"></a>13 08 018 019 |  |  | <a id="p105095"></a>Улица и номер | <a id="p105096"></a>an..70 | <a id="p105097"></a>N |  |
| <a id="p105098"></a>13 08 018 023 |  |  | <a id="p105099"></a>Улица | <a id="p105100"></a>an..70 | <a id="p105101"></a>N |  |
| <a id="p105102"></a>13 08 018 024 |  |  | <a id="p105103"></a>Дополнительная строка для улицы | <a id="p105104"></a>an..70 | <a id="p105105"></a>N |  |
| <a id="p105106"></a>13 08 018 025 |  |  | <a id="p105107"></a>Номер | <a id="p105108"></a>an..35 | <a id="p105109"></a>N |  |
| <a id="p105110"></a>13 08 018 026 |  |  | <a id="p105111"></a>Почтовый ящик | <a id="p105112"></a>an..70 | <a id="p105113"></a>N |  |
| <a id="p105114"></a>13 08 018 027 |  |  | <a id="p105115"></a>Подразделение | <a id="p105116"></a>an..35 | <a id="p105117"></a>N |  |
| <a id="p105118"></a>13 08 018 020 |  |  | <a id="p105119"></a>Страна | <a id="p105120"></a>a2 | <a id="p105121"></a>N | <a id="p105122"></a>Код GEONOM, указанный во [вводной части 13, номер 3](https://bukva.ai/docs/reglament-20152447/statya-350#p104388). |
| <a id="p105123"></a>13 08 017 021 |  |  | <a id="p105124"></a>Почтовый индекс | <a id="p105125"></a>an..17 | <a id="p105126"></a>N |  |
| <a id="p105127"></a>13 08 018 022 |  |  | <a id="p105128"></a>Город | <a id="p105129"></a>an..35 | <a id="p105130"></a>N |  |
| <a id="p105131"></a>13 08 029 000 |  | <a id="p105132"></a>Сообщение |  |  | <a id="p105133"></a>N |  |
| <a id="p105134"></a>13 08 029 015 |  |  | <a id="p105135"></a>Определитель | <a id="p105136"></a>an..512 | <a id="p105137"></a>N |  |
| <a id="p105138"></a>13 08 029 002 |  |  | <a id="p105139"></a>Тип | <a id="p105140"></a>an..3 | <a id="p105141"></a>Y | <a id="p105142"></a>Код типа сообщения, определенный в Титуле II для D.E.<br>Используется [13 02 029 000](https://bukva.ai/docs/reglament-20152447/statya-350#p108444) (Тип лица грузоотправителя) |
| <a id="p105143"></a>13 09 000 000 | <a id="p105144"></a>Покупатель |  |  |  | <a id="p105145"></a>N | <a id="p105146"></a>Используется код страны, определенный для D.E. [3/1](https://bukva.ai/docs/reglament-20152447/statya-350#p109057) Экспортер |
| <a id="p105147"></a>13 09 016 000 |  | <a id="p105148"></a>Имя/Название |  | <a id="p105149"></a>an..70 | <a id="p105150"></a>N |  |
| <a id="p105151"></a>13 09 017 000 | <a id="p105152"></a>Идентификационный номер |  |  | <a id="p105153"></a>an..17 | <a id="p105154"></a>N | <a id="p105155"></a>Структура номера EORI определена в [Титуле II](https://bukva.ai/docs/reglament-20152447/statya-350#p110681) Приложения 12-01 Структура уникального идентификационного номера третьей страны, признанной Союзом, определена в Титуле II для D.E. [13 01 017 000](https://bukva.ai/docs/reglament-20152447/statya-350#p108431) Идентификационный номер. |
| <a id="p105156"></a>13 09 028 000 |  | <a id="p105157"></a>Тип лица |  | <a id="p105158"></a>n1 | <a id="p105159"></a>Y | <a id="p105160"></a>Необходимо использовать код типа лица, определенный в Титуле II для D.E. [13 02 028 000](https://bukva.ai/docs/reglament-20152447/statya-350#p108444) (Тип лица грузоотправителя). |
| <a id="p105161"></a>13 09 018 000 |  | <a id="p105162"></a>Адрес |  |  | <a id="p105163"></a>N |  |
| <a id="p105164"></a>13 09 018 019 |  |  | <a id="p105165"></a>Улица и номер | <a id="p105166"></a>an..70 | <a id="p105167"></a>N |  |
| <a id="p105168"></a>13 09 018 023 |  |  | <a id="p105169"></a>Улица | <a id="p105170"></a>an..70 | <a id="p105171"></a>N |  |
| <a id="p105172"></a>13 09 018 024 |  |  | <a id="p105173"></a>Дополнительная строка для улицы | <a id="p105174"></a>an..70 | <a id="p105175"></a>N |  |
| <a id="p105176"></a>13 09 018 025 |  |  | <a id="p105177"></a>Номер | <a id="p105178"></a>an..35 | <a id="p105179"></a>N |  |
| <a id="p105180"></a>13 09 018 026 |  |  | <a id="p105181"></a>Почтовый ящик | <a id="p105182"></a>an..70 | <a id="p105183"></a>N |  |
| <a id="p105184"></a>13 09 018 027 |  |  | <a id="p105185"></a>Подразделение | <a id="p105186"></a>an..35 | <a id="p105187"></a>N |  |
| <a id="p105188"></a>13 09 018 020 |  |  | <a id="p105189"></a>Страна | <a id="p105190"></a>a2 | <a id="p105191"></a>N | <a id="p105192"></a>Код GEONOM, указанный во [вводной части 13 номер 3](https://bukva.ai/docs/reglament-20152447/statya-350#p104388). |
| <a id="p105193"></a>13 09 018 021 |  |  | <a id="p105194"></a>Почтовый индекс | <a id="p105195"></a>an..17 | <a id="p105196"></a>N |  |
| <a id="p105197"></a>13 09 018 022 |  |  | <a id="p105198"></a>Город | <a id="p105199"></a>an..35 | <a id="p105200"></a>N |  |
| <a id="p105201"></a>13 09 029 000 |  | <a id="p105202"></a>Сообщение |  |  | <a id="p105203"></a>N |  |
| <a id="p105204"></a>13 09 029 015 |  |  | <a id="p105205"></a>Определитель | <a id="p105206"></a>an..512 | <a id="p105207"></a>N |  |
| <a id="p105208"></a>13 09 029 002 |  |  | <a id="p105209"></a>Тип | <a id="p105210"></a>an..3 | <a id="p105211"></a>Y | <a id="p105212"></a>Используется код типа сообщения, определенный в Титуле II для D.E. [13 02 029 002](https://bukva.ai/docs/reglament-20152447/statya-350#p108450) (Тип сообщения грузоотправителя). |
| <a id="p105213"></a>13 10 000 000 | <a id="p105214"></a>Лицо, уведомляющее о прибытии |  |  |  | <a id="p105215"></a>N |  |
| <a id="p105216"></a>13 10 017 000 |  | <a id="p105217"></a>Идентификационный номер |  | <a id="p105218"></a>an..17 | <a id="p105219"></a>N | <a id="p105220"></a>Структура номера EORI определена в [Титуле II](https://bukva.ai/docs/reglament-20152447/statya-350#p110681) Приложения 12-01. |
| <a id="p105221"></a>13 10 029 000 |  | <a id="p105222"></a>Сообщение |  |  | <a id="p105223"></a>N |  |
| <a id="p105224"></a>13 10 029 015 |  |  | <a id="p105225"></a>Определитель | <a id="p105226"></a>an..512 | <a id="p105227"></a>N |  |
| <a id="p105228"></a>13 10 029 002 |  |  | <a id="p105229"></a>Тип | <a id="p105230"></a>an..3 | <a id="p105231"></a>N | <a id="p105232"></a>Используется код типа сообщения, определенный в Титуле II для D.E. [13 02 029 002](https://bukva.ai/docs/reglament-20152447/statya-350#p108450) (Тип сообщения грузоотправителя). |
| <a id="p105233"></a>13 11 000 000 | <a id="p105234"></a>Лицо, представляющее товары |  |  |  | <a id="p105235"></a>N |  |
| <a id="p105236"></a>13 11 017 00 |  | <a id="p105237"></a>Идентификационный номер |  | <a id="p105238"></a>an..17 | <a id="p105239"></a>N | <a id="p105240"></a>Структура номера EORI определена в [Титуле II](https://bukva.ai/docs/reglament-20152447/statya-350#p110681) Приложения 12-01. |
| <a id="p105241"></a>13 12 000 000 | <a id="p105242"></a>Перевозчик |  |  |  | <a id="p105243"></a>N |  |
| <a id="p105244"></a>13 12 016 000 |  | <a id="p105245"></a>Имя/Название |  | <a id="p105246"></a>an..70 | <a id="p105247"></a>N |  |
| <a id="p105248"></a>13 12 017 000 |  | <a id="p105249"></a>Идентификационный номер |  | <a id="p105250"></a>an..17 | <a id="p105251"></a>N | <a id="p105252"></a>Структура номера EORI определена в [Титуле II](https://bukva.ai/docs/reglament-20152447/statya-350#p110681) Приложения 12-01.<br>Структура уникального идентификационного номера третьей страны, признанной Союзом, определена в Титуле II для D.E. [13 01 017 000](https://bukva.ai/docs/reglament-20152447/statya-350#p108431) Идентификационный номер. |
| <a id="p105253"></a>13 12 018 000 |  | <a id="p105254"></a>Адрес |  |  | <a id="p105255"></a>N |  |
| <a id="p105256"></a>13 12 018 023 |  |  | <a id="p105257"></a>Улица | <a id="p105258"></a>an..70 | <a id="p105259"></a>N |  |
| <a id="p105260"></a>13 12 018 024 |  |  | <a id="p105261"></a>Дополнительная строка для улицы | <a id="p105262"></a>an..70 | <a id="p105263"></a>N |  |
| <a id="p105264"></a>13 12 018 025 |  |  | <a id="p105265"></a>Номер | <a id="p105266"></a>an..35 | <a id="p105267"></a>N |  |
| <a id="p105268"></a>13 12 018 026 |  |  | <a id="p105269"></a>Почтовый ящик | <a id="p105270"></a>an..70 | <a id="p105271"></a>N |  |
| <a id="p105272"></a>13 12 018 020 |  |  | <a id="p105273"></a>Подразделение | <a id="p105274"></a>an..35 | <a id="p105275"></a>N |  |
| <a id="p105276"></a>13 12 018 020 |  |  | <a id="p105277"></a>Страна | <a id="p105278"></a>a2 | <a id="p105279"></a>N | <a id="p105280"></a>Код GEONOM, указанный во [вводной части 13, номер 3](https://bukva.ai/docs/reglament-20152447/statya-350#p104388). |
| <a id="p105281"></a>13 12 018 021 |  |  | <a id="p105282"></a>Почтовый индекс | <a id="p105283"></a>an..17 | <a id="p105284"></a>N |  |
| <a id="p105285"></a>13 12 018 022 |  |  | <a id="p105286"></a>Город | <a id="p105287"></a>an..35 | <a id="p105288"></a>N |  |
| <a id="p105289"></a>13 12 029 000 |  | <a id="p105290"></a>Сообщение |  |  | <a id="p105291"></a>N |  |
| <a id="p105292"></a>13 12 029 015 |  |  | <a id="p105293"></a>Определитель | <a id="p105294"></a>an..512 | <a id="p105295"></a>N |  |
| <a id="p105296"></a>13 12 029 002 |  |  | <a id="p105297"></a>Тип | <a id="p105298"></a>an..3 | <a id="p105299"></a>N | <a id="p105300"></a>Используется код типа сообщения, определенный в Титуле II для D.E. [13 02 029 002](https://bukva.ai/docs/reglament-20152447/statya-350#p108450) (Тип сообщения грузоотправителя). |
| <a id="p105301"></a>13 12 074 000 |  | <a id="p105302"></a>Лицо для контакта |  |  | <a id="p105303"></a>N |  |
| <a id="p105304"></a>13 12 074 016 |  |  | <a id="p105305"></a>Имя | <a id="p105306"></a>an..70 | <a id="p105307"></a>N |  |
| <a id="p105308"></a>13 12 074 075 |  |  | <a id="p105309"></a>Номер телефона | <a id="p105310"></a>an..35 | <a id="p105311"></a>N |  |
| <a id="p105312"></a>13 12 074 076 |  |  | <a id="p105313"></a>Адрес электронной почты | <a id="p105314"></a>an..256 | <a id="p105315"></a>N |  |
| <a id="p105316"></a>13 13 000 000 | <a id="p105317"></a>Уведомляющее лицо |  |  | <a id="p105318"></a>an..50 | <a id="p105319"></a>N |  |
| <a id="p105320"></a>13 13 016 000 |  | <a id="p105321"></a>Имя/Название |  | <a id="p105322"></a>an..70 | <a id="p105323"></a>N |  |
| <a id="p105324"></a>13 13 017 000 |  | <a id="p105325"></a>Идентификационный номер |  | <a id="p105326"></a>an..17 | <a id="p105327"></a>N | <a id="p105328"></a>Структура номера EORI соответствует структуре, определенной в Титуле II Приложения 12-01 для D.E. [3/2](https://bukva.ai/docs/reglament-20152447/statya-350#p109064) Идентификационный номер экспортера.<br>Структура уникального идентификационного номера третьей страны, признанной Союзом, соответствует структуре, определенной в Титуле II для D.E. 3/2 [13 01 017 000](https://bukva.ai/docs/reglament-20152447/statya-350#p108431) Идентификационный номер экспортера. |
| <a id="p105329"></a>13 13 028 000 |  | <a id="p105330"></a>Тип лица |  | <a id="p105331"></a>n1 | <a id="p105332"></a>Y | <a id="p105333"></a>Используется код типа лица, определенный в Титуле II для D.E. 13 02 028 000<br>[13 02 028 000](https://bukva.ai/docs/reglament-20152447/statya-350#p108444) (Тип лица грузоотправителя) |
| <a id="p105334"></a>13 13 018 000 |  | <a id="p105335"></a>Адрес |  |  | <a id="p105336"></a>N |  |
| <a id="p105337"></a>13 13 018 023 |  |  | <a id="p105338"></a>Улица | <a id="p105339"></a>an..70 | <a id="p105340"></a>N |  |
| <a id="p105341"></a>13 13 018 024 |  |  | <a id="p105342"></a>Дополнительная строка для улицы | <a id="p105343"></a>an..70 | <a id="p105344"></a>N |  |
| <a id="p105345"></a>13 13 018 025 |  |  | <a id="p105346"></a>Номер | <a id="p105347"></a>an..35 | <a id="p105348"></a>N |  |
| <a id="p105349"></a>13 13 018 026 |  |  | <a id="p105350"></a>Почтовый ящик | <a id="p105351"></a>an..70 | <a id="p105352"></a>N |  |
| <a id="p105353"></a>13 13 018 027 |  |  | <a id="p105354"></a>Подразделение | <a id="p105355"></a>an..35 | <a id="p105356"></a>N |  |
| <a id="p105357"></a>13 13 018 020 |  |  | <a id="p105358"></a>Страна | <a id="p105359"></a>a2 | <a id="p105360"></a>N | <a id="p105361"></a>Код GEONOM, указанный во [вводной части 13, номер 3](https://bukva.ai/docs/reglament-20152447/statya-350#p104388). |
| <a id="p105362"></a>13 13 018 021 |  |  | <a id="p105363"></a>Почтовый индекс | <a id="p105364"></a>an..17 | <a id="p105365"></a>N |  |
| <a id="p105366"></a>13 13 018 022 |  |  | <a id="p105367"></a>Город | <a id="p105368"></a>an..35 | <a id="p105369"></a>N |  |
| <a id="p105370"></a>13 13 029 000 |  | <a id="p105371"></a>Сообщение |  |  | <a id="p105372"></a>N |  |
| <a id="p105373"></a>13 13 029 015 |  |  | <a id="p105374"></a>Определитель | <a id="p105375"></a>an..512 | <a id="p105376"></a>N |  |
| <a id="p105377"></a>13 13 029 002 |  |  | <a id="p105378"></a>Тип | <a id="p105379"></a>an..3 | <a id="p105380"></a>Y |  |
| <a id="p105381"></a>13 14 000 000 | <a id="p105382"></a>Дополнительный участник системы поставки |  |  |  | <a id="p105383"></a>N |  |
| <a id="p105384"></a>13 14 031 000 |  | <a id="p105385"></a>Роль |  | <a id="p105386"></a>a..3 | <a id="p105387"></a>Y |  |
| <a id="p105388"></a>13 14 017 000 |  | <a id="p105389"></a>Идентификационный номер |  | <a id="p105390"></a>an..17 | <a id="p105391"></a>N | <a id="p105392"></a>Структура номера EORI определена в [Титуле II](https://bukva.ai/docs/reglament-20152447/statya-350#p110681) Приложения 12-01.<br>Структура уникального идентификационного номера третьей страны, признанной Союзом, определена в Титуле II для D.E. 3/2 [13 01 017 000](https://bukva.ai/docs/reglament-20152447/statya-350#p108431) Идентификационный номер. |
| <a id="p105393"></a>13 15 000 000 | <a id="p105394"></a>Дополнительный декларант |  |  |  | <a id="p105395"></a>N |  |
| <a id="p105396"></a>13 15 017 000 |  | <a id="p105397"></a>Идентификационный номер |  | <a id="p105398"></a>an..17 | <a id="p105399"></a>N | <a id="p105400"></a>Структура номера EORI определена в [Титуле II](https://bukva.ai/docs/reglament-20152447/statya-350#p110681) Приложения 12-01. |
| <a id="p105401"></a>13 15 032 000 |  | <a id="p105402"></a>Тип дополнительного дела |  | <a id="p105403"></a>an..3 | <a id="p105404"></a>Y |  |
| <a id="p105405"></a>13 16 000 000 | <a id="p105406"></a>Дополнительные фискальные ссылки |  |  |  | <a id="p105407"></a>N |  |
| <a id="p105408"></a>13 16 031 000 |  | <a id="p105409"></a>Роль |  | <a id="p105410"></a>an3 | <a id="p105411"></a>Y |  |
| <a id="p105412"></a>13 16 034 000 |  | <a id="p105413"></a>Идентификационный номер НДС |  | <a id="p105414"></a>an..17 | <a id="p105415"></a>N |  |
| <a id="p105416"></a>13 17 000 000 | <a id="p105417"></a>Лицо, подающее грузовой таможенный манифест |  |  |  | <a id="p105418"></a>N |  |
| <a id="p105419"></a>13 17 017 000 |  | <a id="p105420"></a>Идентификационный номер |  | <a id="p105421"></a>an..17 | <a id="p105422"></a>N | <a id="p105423"></a>Структура номера EORI определена в [Титуле II](https://bukva.ai/docs/reglament-20152447/statya-350#p104030) Приложении 12-01. |
| <a id="p105424"></a>13 18 000 000 | <a id="p105425"></a>Лицо, запрашивающее доказательство таможенного статуса товаров Союза |  |  |  | <a id="p105426"></a>N |  |
| <a id="p105427"></a>13 18 017 000 |  | <a id="p105428"></a>Идентификационный номер |  | <a id="p105429"></a>an..17 | <a id="p105430"></a>N | <a id="p105431"></a>Структура номера EORI определена в [Титуле II](https://bukva.ai/docs/reglament-20152447/statya-350#p104030) Приложении 12-01. |
| <a id="p105432"></a>13 19 000 000 | <a id="p105433"></a>Лицо, уведомляющее о прибытии товаров после перемещения на внутреннем хранении |  |  |  | <a id="p105434"></a>N |  |
| <a id="p105435"></a>13 19 017 000 |  | <a id="p105436"></a>Идентификационный номер |  | <a id="p105437"></a>an..17 | <a id="p105438"></a>N | <a id="p105439"></a>Структура номера EORI определена в [Титуле II](https://bukva.ai/docs/reglament-20152447/statya-350#p104030) Приложении 12-01. |
| <a id="p105440"></a>13 20 000 000 | <a id="p105441"></a>Лицо, предоставляющее гарантию |  |  |  | <a id="p105442"></a>N |  |
| <a id="p105443"></a>13 20 017 000 |  | <a id="p105444"></a>Идентификационный номер |  | <a id="p105445"></a>an..17 |  | <a id="p105446"></a>Структура номера EORI определена в [Титуле II](https://bukva.ai/docs/reglament-20152447/statya-350#p104030) Приложении 12-01. |
| <a id="p105447"></a>13 21 000 000 | <a id="p105448"></a>Лицо, оплачивающее таможенную пошлину |  |  |  | <a id="p105449"></a>N |  |
| <a id="p105450"></a>13 21 017 000 |  | <a id="p105451"></a>Идентификационный номер |  | <a id="p105452"></a>an..17 |  | <a id="p105453"></a>Структура номера EORI определена в [Титуле II](https://bukva.ai/docs/reglament-20152447/statya-350#p104030) Приложении 12-01. |
| <a id="p105454"></a>14 01 000 000 | <a id="p105455"></a>Условия поставки |  |  |  | <a id="p105456"></a>N |  |
| <a id="p105457"></a>14 01 035 000 |  | <a id="p105458"></a>Код INCOTERM |  | <a id="p105459"></a>a3 | <a id="p105460"></a>Y | <a id="p105461"></a>Коды и заголовки, описывающие коммерческий договор, определены в [Титуле II](https://bukva.ai/docs/reglament-20152447/statya-350#p104030). |
| <a id="p105462"></a>14 01 036 000 |  | <a id="p105463"></a>Код UN/LOCODE |  | <a id="p105464"></a>an..17 | <a id="p105465"></a>N | <a id="p105466"></a>Код UN/LOCODE, указанный во [вводной части 13, номер 4](https://bukva.ai/docs/reglament-20152447/statya-350#p104392). |
| <a id="p105467"></a>14 01 020 000 |  | <a id="p105468"></a>Страна |  | <a id="p105469"></a>a2 | <a id="p105470"></a>N | <a id="p105471"></a>Код GEONOM, указанный во [вводной части 13, номер 3](https://bukva.ai/docs/reglament-20152447/statya-350#p104388). |
| <a id="p105472"></a>14 01 037 000 |  | <a id="p105473"></a>Место |  | <a id="p105474"></a>an..35 | <a id="p105475"></a>N |  |
| <a id="p105476"></a>14 02 000 000 | <a id="p105477"></a>Транспортные сборы |  |  |  | <a id="p105478"></a>N |  |
| <a id="p105479"></a>14 02 038 000 |  | <a id="p105480"></a>Способ оплаты |  | <a id="p105481"></a>a1 | <a id="p105482"></a>Y |  |
| <a id="p105483"></a>14 03 000 000 | <a id="p105484"></a>Пошлины и налоги |  |  |  | <a id="p105485"></a>N |  |
| <a id="p105486"></a>14 03 039 000 |  | <a id="p105487"></a>Тип налога |  | <a id="p105488"></a>an3 | <a id="p105489"></a>Y | <a id="p105490"></a>Коды Союза далее определены в [Титуле II](https://bukva.ai/docs/reglament-20152447/statya-350#p104030). Государства-члены ЕС могут определить национальные коды. Национальные коды должны иметь формат n1an2. |
| <a id="p105491"></a>14 03 038 000 |  | <a id="p105492"></a>Метод оплаты |  | <a id="p105493"></a>a1 | <a id="p105494"></a>Y |  |
| <a id="p105495"></a>14 03 042 000 |  | <a id="p105496"></a>Сумма выплачиваемого налога |  | <a id="p105497"></a>n..16,2 | <a id="p105498"></a>N |  |
| <a id="p105499"></a>14 03 040 000 |  | <a id="p105500"></a>Налоговая база |  |  | <a id="p105501"></a>N |  |
| <a id="p105502"></a>14 03 040 041 |  |  | <a id="p105503"></a>Налоговая ставка | <a id="p105504"></a>n..17,3 | <a id="p105505"></a>N |  |
| <a id="p105506"></a>14 03 040 005 |  |  | <a id="p105507"></a>Единица измерения и классификатор | <a id="p105508"></a>an..4 | <a id="p105509"></a>N | <a id="p105510"></a>Используются единицы измерения и классификаторы, определенные в TARIC. В таких случаях формат единиц измерения и классификаторов должен быть an..4, но не должен быть n..4, который зарезервирован для национальных единиц измерения и классификаторов. Если в TARIC нет таких единиц измерения и классификаторов, могут использоваться национальные единицы измерения и классификаторы. Их формат должен быть n..4. |
| <a id="p105511"></a>14 03 040 006 |  |  | <a id="p105512"></a>Количество | <a id="p105513"></a>n..16,6 | <a id="p105514"></a>N |  |
| <a id="p105515"></a>14 03 040 014 |  |  | <a id="p105516"></a>Сумма | <a id="p105517"></a>n..16,2 | <a id="p105518"></a>N |  |
| <a id="p105519"></a>14 03 040 043 |  |  | <a id="p105520"></a>Сумма налога | <a id="p105521"></a>n..16,6 | <a id="p105522"></a>N |  |
| <a id="p105523"></a>14 16 000 000 | <a id="p105524"></a>Общая сумма пошлин и налогов |  |  | <a id="p105525"></a>n..16,2 | <a id="p105526"></a>N |  |
| <a id="p105527"></a>14 17 000 000 | <a id="p105528"></a>Единица внутренней валюты |  |  | <a id="p105529"></a>a3 | <a id="p105530"></a>N | <a id="p105531"></a>Код валюты, указанный во [вводной части 13, номер 2](https://bukva.ai/docs/reglament-20152447/statya-350#p104384). |
| <a id="p105532"></a>14 04 008 000 | <a id="p105533"></a>Надбавки и вычеты |  |  |  | <a id="p105534"></a>N |  |
| <a id="p105535"></a>14 04 008 000 |  | <a id="p105536"></a>Код |  | <a id="p105537"></a>a2 | <a id="p105538"></a>N |  |
| <a id="p105539"></a>14 04 014 000 |  | <a id="p105540"></a>Сумма |  | <a id="p105541"></a>n..16,2 | <a id="p105542"></a>N |  |
| <a id="p105543"></a>14 05 000 000 | <a id="p105544"></a>Валюта инвойса |  |  | <a id="p105545"></a>a3 | <a id="p105546"></a>N | <a id="p105547"></a>Код валюты, указанный во [вводной части 13, номер 2](https://bukva.ai/docs/reglament-20152447/statya-350#p104384). |
| <a id="p105548"></a>14 06 000 000 | <a id="p105549"></a>Общая сумма выставленных счетов |  |  | <a id="p105550"></a>n..16,2 | <a id="p105551"></a>N |  |
| <a id="p105552"></a>14 07 000 000 | <a id="p105553"></a>Показатели оценки |  |  | <a id="p105554"></a>an4 | <a id="p105555"></a>Y |  |
| <a id="p105556"></a>14 08 000 000 | <a id="p105557"></a>Цена/сумма наименования |  |  | <a id="p105558"></a>n..16,2 | <a id="p105559"></a>N |  |
| <a id="p105560"></a>14 09 000 000 | <a id="p105561"></a>Курс обмена |  |  | <a id="p105562"></a>n..12,5 | <a id="p105563"></a>N |  |
| <a id="p105564"></a>14 10 000 000 | <a id="p105565"></a>Способ оценки |  |  | <a id="p105566"></a>n1 | <a id="p105567"></a>Y |  |
| <a id="p105568"></a>14 11 000 000 | <a id="p105569"></a>Преференция |  |  | <a id="p105570"></a>n3 | <a id="p105571"></a>Y |  |
| <a id="p105572"></a>14 12 000 000 | <a id="p105573"></a>Почтовая стоимость |  |  |  | <a id="p105574"></a>N |  |
| <a id="p105575"></a>14 12 012 000 |  | <a id="p105576"></a>Код валюты |  | <a id="p105577"></a>a3 | <a id="p105578"></a>N | <a id="p105579"></a>Код валюты, указанный во [вводной части 13, номер 2](https://bukva.ai/docs/reglament-20152447/statya-350#p104384). |
| <a id="p105580"></a>14 12 0140 00 |  | <a id="p105581"></a>Сумма |  | <a id="p105582"></a>n..16,2 | <a id="p105583"></a>N |  |
| <a id="p105584"></a>14 13 000 000 | <a id="p105585"></a>Почтовые сборы |  |  |  | <a id="p105586"></a>N |  |
| <a id="p105587"></a>14 13 012 000 |  | <a id="p105588"></a>Код валюты |  | <a id="p105589"></a>a3 | <a id="p105590"></a>N | <a id="p105591"></a>Код валюты, указанный во [вводной части 13, номер 2](https://bukva.ai/docs/reglament-20152447/statya-350#p104384). |
| <a id="p105592"></a>14 14 014 000 |  | <a id="p105593"></a>Сумма |  | <a id="p105594"></a>n..16,2 | <a id="p105595"></a>N |  |
| <a id="p105596"></a>14 14 000 000 | <a id="p105597"></a>Внутренняя стоимость |  |  |  | <a id="p105598"></a>N |  |
| <a id="p105599"></a>14 14 012 000 |  | <a id="p105600"></a>Код валюты |  | <a id="p105601"></a>a3 | <a id="p105602"></a>N | <a id="p105603"></a>Код валюты, указанный во [вводной части 13, номер 2](https://bukva.ai/docs/reglament-20152447/statya-350#p104384). |
| <a id="p105604"></a>14 14 014 000 |  | <a id="p105605"></a>Сумма |  | <a id="p105606"></a>n..16,2 | <a id="p105607"></a>N |  |
| <a id="p105608"></a>14 15 000 000 | <a id="p105609"></a>Транспортные и страховые расходы до места назначения |  |  |  | <a id="p105610"></a>N |  |
| <a id="p105611"></a>14 15 012 000 |  | <a id="p105612"></a>Код валюты |  | <a id="p105613"></a>a3 | <a id="p105614"></a>N | <a id="p105615"></a>Код валюты, указанный во [вводной части 13, номер 2](https://bukva.ai/docs/reglament-20152447/statya-350#p104384). |
| <a id="p105616"></a>14 15 014 000 |  | <a id="p105617"></a>Сумма |  | <a id="p105618"></a>n..16,2 | <a id="p105619"></a>N |  |
| <a id="p105620"></a>15 01 000 000 | <a id="p105621"></a>Предполагаемая дата и время отправления |  |  | <a id="p105622"></a>n..19 | <a id="p105623"></a>N |  |
| <a id="p105624"></a>15 02 000 000 | <a id="p105625"></a>Фактическая дата и время отправления |  |  | <a id="p105626"></a>n..19 | <a id="p105627"></a>N |  |
| <a id="p105628"></a>15 03 000 000 | <a id="p105629"></a>Предполагаемая дата и время прибытия в первое место прибытия |  |  | <a id="p105630"></a>an..19 | <a id="p105631"></a>N |  |
| <a id="p105632"></a>15 04 000 000 | <a id="p105633"></a>Предполагаемая дата и время прибытия в порт разгрузки |  |  | <a id="p105634"></a>an..19<br>(ггггммддччммззз) | <a id="p105635"></a>N |  |
| <a id="p105636"></a>15 05 000 000 | <a id="p105637"></a>Фактическая дата и время прибытия |  |  | <a id="p105638"></a>an..19 | <a id="p105639"></a>N |  |
| <a id="p105640"></a>15 06 000 000 | <a id="p105641"></a>Дата декларации |  |  | <a id="p105642"></a>an..19 | <a id="p105643"></a>N |  |
| <a id="p105644"></a>15 07 000 000 | <a id="p105645"></a>Запрошенное действие доказательства |  |  | <a id="p105646"></a>n..3 | <a id="p105647"></a>N |  |
| <a id="p105648"></a>15 08 000 000 | <a id="p105649"></a>Дата и время представления товаров |  |  | <a id="p105650"></a>an..19 | <a id="p105651"></a>N |  |
| <a id="p105652"></a>15 09 000 000 | <a id="p105653"></a>Дата приемки |  |  | <a id="p105654"></a>an..19 | <a id="p105655"></a>N |  |
| <a id="p105656"></a>16 02 000 000 | <a id="p105657"></a>Государство-член ЕС, в которое адресованы товары |  |  |  | <a id="p105658"></a>N |  |
| <a id="p105659"></a>16 02 020 000 |  | <a id="p105660"></a>Страна |  | <a id="p105661"></a>a2 | <a id="p105662"></a>N | <a id="p105663"></a>Код GEONOM, указанный во [вводной части 13, номер 3](https://bukva.ai/docs/reglament-20152447/statya-350#p104388). |
| <a id="p105664"></a>16 03 000 000 | <a id="p105665"></a>Страна места назначения |  |  | <a id="p105666"></a>a2 | <a id="p105667"></a>N | <a id="p105668"></a>Код GEONOM, указанный во [вводной части 13, номер 3](https://bukva.ai/docs/reglament-20152447/statya-350#p104388).<br>В контексте транзитных операций используется код страны ISO 3166 alpha-2. |
| <a id="p105669"></a>16 04 000 000 | <a id="p105670"></a>Регион места назначения |  |  | <a id="p105671"></a>an..35 | <a id="p105672"></a>N | <a id="p105673"></a>Коды определены заинтересованным государством-членом ЕС. |
| <a id="p105674"></a>16 05 000 000 | <a id="p105675"></a>Место поставки |  |  |  | <a id="p105676"></a>N |  |
| <a id="p105677"></a>16 05 036 000 |  | <a id="p105678"></a>UN/CODE |  | <a id="p105679"></a>an..17 | <a id="p105680"></a>N | <a id="p105681"></a>UN/LOCODE, указанный во [вводной части 13, номер 4](https://bukva.ai/docs/reglament-20152447/statya-350#p104392). |
| <a id="p105682"></a>16 05 020 000 |  | <a id="p105683"></a>Страна |  | <a id="p105684"></a>a2 | <a id="p105685"></a>N | <a id="p105686"></a>Код GEONOM, указанный во [вводной части 13, номер 3](https://bukva.ai/docs/reglament-20152447/statya-350#p104388). |
| <a id="p105687"></a>16 05 037 000 |  | <a id="p105688"></a>Место |  | <a id="p105689"></a>an..17 | <a id="p105690"></a>N |  |
| <a id="p105691"></a>16 06 000 000 | <a id="p105692"></a>Страна отправления |  |  | <a id="p105693"></a>a2 | <a id="p105694"></a>N | <a id="p105695"></a>Код GEONOM, указанный во [вводной части 13, номер 3](https://bukva.ai/docs/reglament-20152447/statya-350#p104388). |
| <a id="p105696"></a>16 07 000 000 | <a id="p105697"></a>Страна экспорта |  |  | <a id="p105698"></a>a2 | <a id="p105699"></a>N | <a id="p105700"></a>Код GEONOM, указанный во [вводной части 13, номер 3](https://bukva.ai/docs/reglament-20152447/statya-350#p104388). |
| <a id="p105701"></a>16 08 000 000 | <a id="p105702"></a>Страна происхождения |  |  | <a id="p105703"></a>a2 | <a id="p105704"></a>N | <a id="p105705"></a>Код GEONOM, указанный во [вводной части 13, номер 3](https://bukva.ai/docs/reglament-20152447/statya-350#p104388). |
| <a id="p105706"></a>16 09 000 000 | <a id="p105707"></a>Страна преференциального происхождения |  |  | <a id="p105708"></a>an..4 | <a id="p105709"></a>N | <a id="p105710"></a>Код GEONOM, указанный во [вводной части 13, номер 3](https://bukva.ai/docs/reglament-20152447/statya-350#p104388).<br>Если доказательство происхождения относится к группе стран/регионов, используются цифровые коды идентификатора, определенные в интегрированном тарифе, установленном в соответствии со Статьей 2 Регламента (ЕЭС) 2658/87 Совета ЕС. |
| <a id="p105711"></a>16 10 000 000 | <a id="p105712"></a>Регион отправления |  |  | <a id="p105713"></a>an..9 | <a id="p105714"></a>N | <a id="p105715"></a>Коды определены заинтересованными государствами-членами ЕС. |
| <a id="p105716"></a>16 11 000 000 | <a id="p105717"></a>Страны маршрута транспортных средств |  |  |  | <a id="p105718"></a>N |  |
| <a id="p105719"></a>16 11 020 000 |  | <a id="p105720"></a>Страна |  | <a id="p105721"></a>a2 | <a id="p105722"></a>N | <a id="p105723"></a>Код GEONOM, указанный во [вводной части 13, номер 3](https://bukva.ai/docs/reglament-20152447/statya-350#p104388). |
| <a id="p105724"></a>16 12 000 000 | <a id="p105725"></a>Страна маршрута груза |  |  |  | <a id="p105726"></a>N |  |
| <a id="p105727"></a>16 12 020 000 |  | <a id="p105728"></a>Страна |  | <a id="p105729"></a>a2 | <a id="p105730"></a>N | <a id="p105731"></a>Код GEONOM, указанный во [вводной части 13, номер 3](https://bukva.ai/docs/reglament-20152447/statya-350#p104388). |
| <a id="p105732"></a>16 13 000 000 | <a id="p105733"></a>Место погрузки |  |  | <a id="p105734"></a>Кодированное: an..17<br>ИЛИ<br>Описание в свободной форме: a2 (код страны) + an..35 (место) | <a id="p105735"></a>N |  |
| <a id="p105736"></a>16 13 036 000 |  | <a id="p105737"></a>Код UN/LOCODE |  | <a id="p105738"></a>an..17 | <a id="p105739"></a>N | <a id="p105740"></a>Код UN/LOCODE, указанный во [вводной части 13, номер 4](https://bukva.ai/docs/reglament-20152447/statya-350#p104392). |
| <a id="p105741"></a>16 13 020 000 |  | <a id="p105742"></a>Страна |  | <a id="p105743"></a>a2 | <a id="p105744"></a>N | <a id="p105745"></a>Если место погрузки не закодировано согласно коду UN/LOCODE, страна, где расположено место погрузки, идентифицируется кодом GEONOM, указанным во [вводной части 13, номер 3](https://bukva.ai/docs/reglament-20152447/statya-350#p104388). |
| <a id="p105746"></a>16 13 037 000 |  | <a id="p105747"></a>Место |  | <a id="p105748"></a>an..35 | <a id="p105749"></a>N |  |
| <a id="p105750"></a>16 14 000 000 | <a id="p105751"></a>Место разгрузки |  |  |  | <a id="p105752"></a>N |  |
| <a id="p105753"></a>16 14 036 000 |  | <a id="p105754"></a>Код UN/LOCODE |  | <a id="p105755"></a>an..17 | <a id="p105756"></a>N | <a id="p105757"></a>Код UN/LOCODE, указанный во [вводной части 13, номер 4](https://bukva.ai/docs/reglament-20152447/statya-350#p104392). |
| <a id="p105758"></a>16 14 020 000 |  | <a id="p105759"></a>Страна |  | <a id="p105760"></a>a2 | <a id="p105761"></a>N | <a id="p105762"></a>Если место разгрузки не закодировано согласно коду UN/LOCODE, страна, где место разгрузки расположено, идентифицируется кодом GEONOM, указанным во [вводной части 13, номер 3](https://bukva.ai/docs/reglament-20152447/statya-350#p104388). |
| <a id="p105763"></a>16 14 037 000 |  | <a id="p105764"></a>Место |  | <a id="p105765"></a>an..35 | <a id="p105766"></a>N |  |
| <a id="p105767"></a>16 15 000 000 | <a id="p105768"></a>Местонахождение товаров |  |  |  | <a id="p105769"></a>N | <a id="p105770"></a>Может использоваться только один тип местонахождения товаров. |
| <a id="p105771"></a>16 15 045 000 |  | <a id="p105772"></a>Тип местонахождения |  | <a id="p105773"></a>a1 | <a id="p105774"></a>Y |  |
| <a id="p105775"></a>16 15 046 000 |  | <a id="p105776"></a>Классификатор идентификации |  | <a id="p105777"></a>a1 | <a id="p105778"></a>Y |  |
| <a id="p105779"></a>16 15 036 000 |  | <a id="p105780"></a>Код UN/LOCODE |  | <a id="p105781"></a>an..17 | <a id="p105782"></a>N | <a id="p105783"></a>Код UN/LOCODE, указанный во [вводной части 13, номер 4](https://bukva.ai/docs/reglament-20152447/statya-350#p104392). |
| <a id="p105784"></a>16 15 047 000 |  | <a id="p105785"></a>Таможенное учреждение |  |  | <a id="p105786"></a>N |  |
| <a id="p105787"></a>16 15 047 001 |  |  | <a id="p105788"></a>Исходящий номер | <a id="p105789"></a>an8 | <a id="p105790"></a>N | <a id="p105791"></a>Идентификатор таможенного учреждения должен следовать за структурой, определенной для D.E. [17 01 001 000](https://bukva.ai/docs/reglament-20152447/statya-350#p108727) Исходящий номер |
| <a id="p105792"></a>16 15 048 000 |  | <a id="p105793"></a>ГНСС (GNSS) |  |  | <a id="p105794"></a>N |  |
| <a id="p105795"></a>16 15 048 049 |  |  | <a id="p105796"></a>Широта | <a id="p105797"></a>an..17 | <a id="p105798"></a>N |  |
| <a id="p105799"></a>16 15 048 050 |  |  | <a id="p105800"></a>Долгота | <a id="p105801"></a>an..17 | <a id="p105802"></a>N |  |
| <a id="p105803"></a>16 15 051 000 |  | <a id="p105804"></a>Субъект экономической деятельности |  |  | <a id="p105805"></a>N |  |
| <a id="p105806"></a>16 15 051 017 |  |  | <a id="p105807"></a>Идентификационный номер | <a id="p105808"></a>an..17 | <a id="p105809"></a>N | <a id="p105810"></a>Структура номера EORI определена в [Титуле II](https://bukva.ai/docs/reglament-20152447/statya-350#p110681) Приложения 12-01. |
| <a id="p105811"></a>16 15 052 000 |  | <a id="p105812"></a>Номер разрешения |  | <a id="p105813"></a>an..35 | <a id="p105814"></a>N |  |
| <a id="p105815"></a>16 15 053 000 |  | <a id="p105816"></a>Дополнительный идентификатор |  | <a id="p105817"></a>an..4 | <a id="p105818"></a>N |  |
| <a id="p105819"></a>16 15 018 000 |  | <a id="p105820"></a>Адрес |  |  | <a id="p105821"></a>N |  |
| <a id="p105822"></a>16 15 018 019 |  |  | <a id="p105823"></a>Улица и номер | <a id="p105824"></a>an..70 | <a id="p105825"></a>N |  |
| <a id="p105826"></a>16 15 018 021 |  |  | <a id="p105827"></a>Почтовый индекс | <a id="p105828"></a>an..17 | <a id="p105829"></a>N |  |
| <a id="p105830"></a>16 15 018 022 |  |  | <a id="p105831"></a>Город | <a id="p105832"></a>an..35 | <a id="p105833"></a>N | <a id="p105834"></a>Код GEONOM, указанный во [вводной части 13, номер 3](https://bukva.ai/docs/reglament-20152447/statya-350#p104388). |
| <a id="p105835"></a>16 15 018 020 |  |  | <a id="p105836"></a>Страна | <a id="p105837"></a>a2 | <a id="p105838"></a>N |  |
| <a id="p105839"></a>16 15 081 000 |  | <a id="p105840"></a>Адрес почтового индекса |  |  |  |  |
| <a id="p105841"></a>16 15 081 021 |  |  | <a id="p105842"></a>Почтовый индекс | <a id="p105843"></a>an..17 | <a id="p105844"></a>N |  |
| <a id="p105845"></a>16 15 081 025 |  |  | <a id="p105846"></a>Номер дома | <a id="p105847"></a>an..35 | <a id="p105848"></a>N |  |
| <a id="p105849"></a>16 15 081 020 |  |  | <a id="p105850"></a>Страна | <a id="p105851"></a>a2 | <a id="p105852"></a>N |  |
| <a id="p105853"></a>16 15 074 000 |  | <a id="p105854"></a>Лицо для контакта |  |  | <a id="p105855"></a>N |  |
| <a id="p105856"></a>16 15 074 016 |  |  | <a id="p105857"></a>Имя | <a id="p105858"></a>an..70 | <a id="p105859"></a>N |  |
| <a id="p105860"></a>16 15 074 075 |  |  | <a id="p105861"></a>Номер телефона | <a id="p105862"></a>an..35 | <a id="p105863"></a>N |  |
| <a id="p105864"></a>16 15 074 076 |  |  | <a id="p105865"></a>Адрес электронной почты | <a id="p105866"></a>an..256 | <a id="p105867"></a>N |  |
| <a id="p105868"></a>16 16 000 000 | <a id="p105869"></a>Место приемки |  |  |  | <a id="p105870"></a>N |  |
| <a id="p105871"></a>16 16 036 000 |  | <a id="p105872"></a>Код UN/LOCODE |  | <a id="p105873"></a>an..17 | <a id="p105874"></a>N | <a id="p105875"></a>Код UN/LOCODE, указанный во [вводной части 13, номер 4](https://bukva.ai/docs/reglament-20152447/statya-350#p104392). |
| <a id="p105876"></a>16 16 020 000 |  | <a id="p105877"></a>Страна |  | <a id="p105878"></a>a2 | <a id="p105879"></a>N | <a id="p105880"></a>Если место приемки не закодировано согласно коду UN/LOCODE, страна, в которой находится место приемки, идентифицируется кодом GEONOM, указанным во [вводной части 13, номер 3](https://bukva.ai/docs/reglament-20152447/statya-350#p104388). |
| <a id="p105881"></a>16 16 037 000 |  | <a id="p105882"></a>Место |  | <a id="p105883"></a>an..35 | <a id="p105884"></a>N |  |
| <a id="p105885"></a>16 17 000 000 | <a id="p105886"></a>Обязательный журнал |  |  | <a id="p105887"></a>n1 | <a id="p105888"></a>Y |  |
| <a id="p105889"></a>17 01 000 000 | <a id="p105890"></a>Таможенное учреждение вывоза |  |  |  | <a id="p105891"></a>N |  |
| <a id="p105892"></a>17 01 001 000 |  | <a id="p105893"></a>Исходящий номер |  | <a id="p105894"></a>an8 | <a id="p105895"></a>N | <a id="p105896"></a>Структура идентификатора таможенного учреждения определена в [Титуле II](https://bukva.ai/docs/reglament-20152447/statya-350#p104030). |
| <a id="p105897"></a>17 02 000 000 | <a id="p105898"></a>Таможенное учреждение экспорта |  |  |  | <a id="p105899"></a>N |  |
| <a id="p105900"></a>17 02 001 000 |  | <a id="p105901"></a>Исходящий номер |  | <a id="p105902"></a>an8 | <a id="p105903"></a>N | <a id="p105904"></a>Идентификатор таможенного учреждения следует за структурой, определенной для D.E. [17 01 001 000](https://bukva.ai/docs/reglament-20152447/statya-350#p108727) Исходящий номер. |
| <a id="p105905"></a>17 03 000 000 | <a id="p105906"></a>Таможенное учреждение отправления |  |  |  | <a id="p105907"></a>N |  |
| <a id="p105908"></a>17 03 001 000 |  | <a id="p105909"></a>Исходящий номер |  | <a id="p105910"></a>an8 | <a id="p105911"></a>N | <a id="p105912"></a>Идентификатор таможенного учреждения следует за структурой, определенной для D.E. [17 01 001 000](https://bukva.ai/docs/reglament-20152447/statya-350#p108727) Исходящий номер. |
| <a id="p105913"></a>17 04 000 000 | <a id="p105914"></a>Таможенное учреждение транзита |  |  |  | <a id="p105915"></a>N |  |
| <a id="p105916"></a>17 04 001 000 |  | <a id="p105917"></a>Исходящий номер |  | <a id="p105918"></a>an8 | <a id="p105919"></a>N | <a id="p105920"></a>Идентификатор таможенного учреждения следует за структурой, определенной для D.E. [17 01 001 000](https://bukva.ai/docs/reglament-20152447/statya-350#p108727) Исходящий номер. |
| <a id="p105921"></a>17 05 000 000 | <a id="p105922"></a>Таможенное учреждение места назначения |  |  |  | <a id="p105923"></a>N |  |
| <a id="p105924"></a>17 05 001 000 |  | <a id="p105925"></a>Исходящий номер |  | <a id="p105926"></a>an8 | <a id="p105927"></a>N | <a id="p105928"></a>Идентификатор таможенного учреждения следует за структурой, определенной для D.E. [17 01 001 000](https://bukva.ai/docs/reglament-20152447/statya-350#p108727) Исходящий номер. |
| <a id="p105929"></a>17 06 000 000 | <a id="p105930"></a>Таможенное учреждение вывоза для транзита |  |  |  | <a id="p105931"></a>N |  |
| <a id="p105932"></a>17 06 001 000 |  | <a id="p105933"></a>Исходящий номер |  | <a id="p105934"></a>an8 | <a id="p105935"></a>N | <a id="p105936"></a>Идентификатор таможенного учреждения следует за структурой, определенной для D.E. [17 01 001 000](https://bukva.ai/docs/reglament-20152447/statya-350#p108727) Исходящий номер. |
| <a id="p105937"></a>17 07 000 000 | <a id="p105938"></a>Таможенное учреждение места первого ввоза |  |  |  | <a id="p105939"></a>N |  |
| <a id="p105940"></a>17 07 001 000 |  | <a id="p105941"></a>Исходящий номер |  | <a id="p105942"></a>an8 | <a id="p105943"></a>N | <a id="p105944"></a>Идентификатор таможенного учреждения следует за структурой, определенной для D.E. [17 01 001 000](https://bukva.ai/docs/reglament-20152447/statya-350#p108727) Исходящий номер. |
| <a id="p105945"></a>17 08 000 000 | <a id="p105946"></a>Фактическое таможенное учреждение места первого ввоза |  |  |  | <a id="p105947"></a>N |  |
| <a id="p105948"></a>17 08 001 000 |  | <a id="p105949"></a>Исходящий номер |  | <a id="p105950"></a>an8 | <a id="p105951"></a>N | <a id="p105952"></a>Идентификатор таможенного учреждения следует за структурой, определенной для D.E. [17 01 001 000](https://bukva.ai/docs/reglament-20152447/statya-350#p108727) Исходящий номер. |
| <a id="p105953"></a>17 09 000 000 | <a id="p105954"></a>Таможенное учреждение места представления |  |  |  | <a id="p105955"></a>N |  |
|  |  |  |  |  |  |  |
| <a id="p105956"></a>17 09 001 000 |  | <a id="p105957"></a>Исходящий номер |  | <a id="p105958"></a>an8 | <a id="p105959"></a>N | <a id="p105960"></a>Идентификатор таможенного учреждения следует за структурой, определенной для D.E. [17 01 001 000](https://bukva.ai/docs/reglament-20152447/statya-350#p108727) Исходящий номер. |
| <a id="p105961"></a>17 10 000 000 | <a id="p105962"></a>Надзорное таможенное учреждение |  |  |  | <a id="p105963"></a>N |  |
| <a id="p105964"></a>17 10 001 000 |  | <a id="p105965"></a>Исходящий номер |  | <a id="p105966"></a>an8 | <a id="p105967"></a>N | <a id="p105968"></a>Идентификатор таможенного учреждения следует за структурой, определенной для D.E. [17 01 001 000](https://bukva.ai/docs/reglament-20152447/statya-350#p108727) Исходящий номер. |
| <a id="p105969"></a>18 01 000 000 | <a id="p105970"></a>Масса нетто |  |  | <a id="p105971"></a>n..16,6 | <a id="p105972"></a>N |  |
| <a id="p105973"></a>18 02 000 000 | <a id="p105974"></a>Дополнительные единицы |  |  | <a id="p105975"></a>n..16,6 | <a id="p105976"></a>N |  |
| <a id="p105977"></a>18 03 000 000 | <a id="p105978"></a>Общая масса брутто |  |  | <a id="p105979"></a>n..16,6 | <a id="p105980"></a>N |  |
| <a id="p105981"></a>18 04 000 000 | <a id="p105982"></a>Масса брутто |  |  | <a id="p105983"></a>n..16,6 | <a id="p105984"></a>N |  |
| <a id="p105985"></a>18 05 000 000 | <a id="p105986"></a>Описание товаров |  |  | <a id="p105987"></a>an..512 | <a id="p105988"></a>N |  |
| <a id="p105989"></a>18 06 000 000 | <a id="p105990"></a>Упаковка |  |  |  | <a id="p105991"></a>N |  |
| <a id="p105992"></a>18 06 003 000 |  | <a id="p105993"></a>Вид упаковки |  | <a id="p105994"></a>an2 | <a id="p105995"></a>N | <a id="p105996"></a>Код вида упаковки, определенный во [вводной части 13 номер 1](https://bukva.ai/docs/reglament-20152447/statya-350#p104380). |
| <a id="p105997"></a>18 06 004 000 |  | <a id="p105998"></a>Количество упаковок |  | <a id="p105999"></a>n..8 | <a id="p106000"></a>N |  |
| <a id="p106001"></a>18 06 054 000 |  | <a id="p106002"></a>Грузовая маркировка |  | <a id="p106003"></a>an..512 | <a id="p106004"></a>N |  |
| <a id="p106005"></a>18 07 000 000 | <a id="p106006"></a>Опасные товары |  |  |  | <a id="p106007"></a>N |  |
| <a id="p106008"></a>18 07 055 000 |  | <a id="p106009"></a>Номер UN |  | <a id="p106010"></a>an4 | <a id="p106011"></a>N | <a id="p106012"></a>Номер UN, указанный во [вводной части 13 номер 5](https://bukva.ai/docs/reglament-20152447/statya-350#p104396). |
| <a id="p106013"></a>18 08 000 000 | <a id="p106014"></a>Код CUS |  |  | <a id="p106015"></a>an9 | <a id="p106016"></a>N | <a id="p106017"></a>Код CUS, указанный во [вводной части 13 номер 9](https://bukva.ai/docs/reglament-20152447/statya-350#p104412). |
| <a id="p106018"></a>18 09 000 000 | <a id="p106019"></a>Код товара |  |  | <a id="p106020"></a>an..8 | <a id="p106021"></a>N |  |
| <a id="p106022"></a>18 09 056 000 |  | <a id="p106023"></a>Код подзаголовка гармонизированной системы |  | <a id="p106024"></a>an6 | <a id="p106025"></a>N |  |
| <a id="p106026"></a>18 09 057 000 |  | <a id="p106027"></a>Код объединенной номенклатуры |  | <a id="p106028"></a>an2 | <a id="p106029"></a>NN |  |
| <a id="p106030"></a>18 09 058 000 |  | <a id="p106031"></a>Код TARIC |  | <a id="p106032"></a>an2 |  | <a id="p106033"></a>Для заполнения в соответствии с кодом TARIC (два знака для применения специальных мер Союза в отношении заполняемых формальностей в месте назначения). |
| <a id="p106034"></a>18 09 059 000 |  | <a id="p106035"></a>Дополнительный код TARIC |  | <a id="p106036"></a>an4 | <a id="p106037"></a>N | <a id="p106038"></a>Для заполнения в соответствии с кодом TARIC (дополнительные коды) |
| <a id="p106039"></a>18 09 060 000 |  | <a id="p106040"></a>Национальные дополнительные коды |  | <a id="p106041"></a>an..4 | <a id="p106042"></a>N | <a id="p106043"></a>Коды, адаптируемые заинтересованным государством-членом ЕС. |
| <a id="p106044"></a>18 10 000 000 | <a id="p106045"></a>Вид товаров |  |  | <a id="p106046"></a>a..3 | <a id="p106047"></a>N | <a id="p106048"></a>Коды указания характера пункта UPU, указанные во [вводной части 13 номер 8](https://bukva.ai/docs/reglament-20152447/statya-350#p104408) |
| <a id="p106049"></a>19 01 000 000 | <a id="p106050"></a>Индикатор контейнера |  |  | <a id="p106051"></a>n1 | <a id="p106052"></a>Y |  |
| <a id="p106053"></a>19 02 000 000 | <a id="p106054"></a>Номер ссылки на перевозку |  |  | <a id="p106055"></a>an..17 | <a id="p106056"></a>N |  |
| <a id="p106057"></a>19 03 000 000 | <a id="p106058"></a>Вид транспорта на границе |  |  | <a id="p106059"></a>n1 | <a id="p106060"></a>Y |  |
| <a id="p106061"></a>19 04 000 000 | <a id="p106062"></a>Внутренний вид транспорта |  |  | <a id="p106063"></a>n1 | <a id="p106064"></a>Y | <a id="p106065"></a>Используются коды, предусмотренные в Титуле II в отношении D.E. [19 03 000 000](https://bukva.ai/docs/reglament-20152447/statya-350#p108738) Вид транспорта на границе |
| <a id="p106066"></a>19 05 000 000 | <a id="p106067"></a>Транспортное средство в месте отправления |  |  |  | <a id="p106068"></a>N |  |
| <a id="p106069"></a>19 05 061 000 |  | <a id="p106070"></a>Тип идентификации |  | <a id="p106071"></a>n2 | <a id="p106072"></a>Y |  |
| <a id="p106073"></a>19 05 017 000 |  | <a id="p106074"></a>Идентификационный номер |  | <a id="p106075"></a>an..35 | <a id="p106076"></a>N |  |
| <a id="p106077"></a>19 05 062 000 |  | <a id="p106078"></a>Национальность |  | <a id="p106079"></a>a2 | <a id="p106080"></a>N | <a id="p106081"></a>Код GEONOM, указанный во [вводной части 13, номер 3](https://bukva.ai/docs/reglament-20152447/statya-350#p104388) |
| <a id="p106082"></a>19 06 000 000 | <a id="p106083"></a>Транспортное средство в месте прибытия |  |  |  | <a id="p106084"></a>- |  |
| <a id="p106085"></a>19 06 061 000 |  | <a id="p106086"></a>Тип идентификации |  | <a id="p106087"></a>n2 | <a id="p106088"></a>Y | <a id="p106089"></a>Для типа идентификации используются коды, определенные в Титуле II для D.E. [19 05 061 000](https://bukva.ai/docs/reglament-20152447/statya-350#p108759) Тип идентификации. |
| <a id="p106090"></a>19 06 017 000 |  | <a id="p106091"></a>Идентификационный номер |  | <a id="p106092"></a>an..35 | <a id="p106093"></a>N |  |
| <a id="p106094"></a>19 07 000 000 | <a id="p106095"></a>Транспортное оборудование |  |  |  | <a id="p106096"></a>N |  |
| <a id="p106097"></a>19 07 063 000 |  | <a id="p106098"></a>Идентификационный номер контейнера |  | <a id="p106099"></a>an..17 | <a id="p106100"></a>N |  |
| <a id="p106101"></a>19 07 044 000 |  | <a id="p106102"></a>Ссылка на товары |  | <a id="p106103"></a>n..5 | <a id="p106104"></a>N |  |
| <a id="p106105"></a>19 07 064 000 |  | <a id="p106106"></a>Размер контейнера и тип идентификации |  | <a id="p106107"></a>an..10 | <a id="p106108"></a>Y |  |
| <a id="p106109"></a>19 07 065 000 |  | <a id="p106110"></a>Состояние упакованного контейнера |  | <a id="p106111"></a>an..3 | <a id="p106112"></a>Y |  |
| <a id="p106113"></a>19 07 066 000 |  | <a id="p106114"></a>Код вида поставщика контейнера |  | <a id="p106115"></a>an..3 | <a id="p106116"></a>Y |  |
| <a id="p106117"></a>19 08 000 000 | <a id="p106118"></a>Активное транспортное средство, пересекающее границу |  |  |  | <a id="p106119"></a>N |  |
| <a id="p106120"></a>19 08 061 000 |  | <a id="p106121"></a>Вид идентификации |  | <a id="p106122"></a>n2 | <a id="p106123"></a>Y | <a id="p106124"></a>Для вида идентификации используются коды, определенные в Титуле II для D.E. [19 05 061 000](https://bukva.ai/docs/reglament-20152447/statya-350#p108759) Вид идентификации. |
| <a id="p106125"></a>19 08 017 000 |  | <a id="p106126"></a>Идентификационный номер |  | <a id="p106127"></a>an..35 | <a id="p106128"></a>N |  |
| <a id="p106129"></a>19 08 062 000 |  | <a id="p106130"></a>Национальность |  | <a id="p106131"></a>a2 | <a id="p106132"></a>N | <a id="p106133"></a>Код GEONOM, указанный во [вводной части 13, номер 3](https://bukva.ai/docs/reglament-20152447/statya-350#p104388). |
| <a id="p106134"></a>19 08 067 000 |  | <a id="p106135"></a>Тип транспортного средства |  | <a id="p106136"></a>an..4 | <a id="p106137"></a>N | <a id="p106138"></a>Код для типа транспортного средства, указанный во [вводной части 13 номер 6](https://bukva.ai/docs/reglament-20152447/statya-350#p104400). |
| <a id="p106139"></a>19 09 000 000 | <a id="p106140"></a>Пассивное транспортное средство, пересекающее границу |  |  |  | <a id="p106141"></a>N |  |
| <a id="p106142"></a>19 09 061 000 |  | <a id="p106143"></a>Вид идентификации |  | <a id="p106144"></a>n2 | <a id="p106145"></a>Y | <a id="p106146"></a>Для вида идентификации используются коды, определенные в Титуле II для D.E. [19 05 061 000](https://bukva.ai/docs/reglament-20152447/statya-350#p108759) Вид идентификации |
| <a id="p106147"></a>19 09 017 000 |  | <a id="p106148"></a>Идентификационный номер |  | <a id="p106149"></a>an..35 | <a id="p106150"></a>N |  |
| <a id="p106151"></a>19 09 062 000 |  | <a id="p106152"></a>Национальность |  | <a id="p106153"></a>a2 | <a id="p106154"></a>N | <a id="p106155"></a>Код GEONOM, указанный во [вводной части 13 номер 3](https://bukva.ai/docs/reglament-20152447/statya-350#p104388). |
| <a id="p106156"></a>19 09 067 000 |  | <a id="p106157"></a>Тип транспортного средства |  | <a id="p106158"></a>an..4 | <a id="p106159"></a>N | <a id="p106160"></a>Код для типа транспортного средства, указанный во [вводной части 13 номер 6](https://bukva.ai/docs/reglament-20152447/statya-350#p104400). |
| <a id="p106161"></a>19 10 000 000 | <a id="p106162"></a>Пломба |  |  |  | <a id="p106163"></a>N |  |
| <a id="p106164"></a>19 10 068 000 |  | <a id="p106165"></a>Количество пломб |  | <a id="p106166"></a>n..4 | <a id="p106167"></a>N |  |
| <a id="p106168"></a>19 10 015 000 |  | <a id="p106169"></a>Идентификатор |  | <a id="p106170"></a>an..20 | <a id="p106171"></a>N |  |
| <a id="p106172"></a>19 11 000 000 | <a id="p106173"></a>Идентификационный номер хранилища |  |  | <a id="p106174"></a>an..35 | <a id="p106175"></a>N |  |
| <a id="p106176"></a>99 01 000 000 | <a id="p106177"></a>Порядковый номер квоты |  |  | <a id="p106178"></a>an6 | <a id="p106179"></a>N |  |
| <a id="p106180"></a>99 02 000 000 | <a id="p106181"></a>Вид гарантии |  |  | <a id="p106182"></a>Вид гарантии: an 1 | <a id="p106183"></a>Y |  |
| <a id="p106184"></a>99 03 000 000 | <a id="p106185"></a>Ссылка на гарантию |  |  |  | <a id="p106186"></a>N |  |
| <a id="p106187"></a>99 03 069 000 |  | <a id="p106188"></a>GRN |  | <a id="p106189"></a>an..24 | <a id="p106190"></a>N |  |
| <a id="p106191"></a>99 03 070 000 |  | <a id="p106192"></a>Код доступа |  | <a id="p106193"></a>an..4 | <a id="p106194"></a>N |  |
| <a id="p106195"></a>99 03 012 000 |  | <a id="p106196"></a>Валюта |  | <a id="p106197"></a>a3 | <a id="p106198"></a>N | <a id="p106199"></a>Код валюты, указанный во [вводной части 13, номер 2](https://bukva.ai/docs/reglament-20152447/statya-350#p104384). |
| <a id="p106200"></a>99 03 071 000 |  | <a id="p106201"></a>Покрываемая сумма |  | <a id="p106202"></a>n..16,2 | <a id="p106203"></a>N |  |
| <a id="p106204"></a>99 03 072 000 |  | <a id="p106205"></a>Таможенное учреждение гарантии |  | <a id="p106206"></a>an8 | <a id="p106207"></a>N | <a id="p106208"></a>Идентификатор таможенного учреждения следует после структуры, определенной для D.E. [17 01 001 00](https://bukva.ai/docs/reglament-20152447/statya-350#p108727) Исходящий номер |
| <a id="p106209"></a>99 03 073 000 |  | <a id="p106210"></a>Ссылка на другие гарантии |  | <a id="p106211"></a>an..35 | <a id="p106212"></a>N |  |
| <a id="p106213"></a><a id="p106214"></a>99 04 000 000<br>Гарантия не действует в |  |  |  |  |  |  |
|  |  | <a id="p106215"></a>a2 | <a id="p106216"></a>N | <a id="p106217"></a>Код GEONOM, указанный во [вводной части 163 номер 3](https://bukva.ai/docs/reglament-20152447/statya-350#p104388). | <a id="p106218"></a>99 05 000 000 | <a id="p106219"></a>Характер сделки |
|  |  | <a id="p106220"></a>n..2 | <a id="p106221"></a>N | <a id="p106222"></a>Код для характера сделки, указанный во [вводной части 13 номер 7](https://bukva.ai/docs/reglament-20152447/statya-350#p104404). | <a id="p106223"></a>99 06 000 000 | <a id="p106224"></a>Статистическое значение |
|  |  | <a id="p106225"></a>n..16,2 | <a id="p106226"></a>N |  |  | <a id="p106227"></a>Глава 2. КОЛИЧЕСТВА ЭЛЕМЕНТОВ |


<a id="p106228"></a>Количества элементов для уровней декларации


| <a id="p106229"></a>MC | <a id="p106230"></a>1x (на декларацию) |
| --- | --- |
| <a id="p106231"></a>MI | <a id="p106232"></a>9,999x (на MC) |
| <a id="p106233"></a>HC | <a id="p106234"></a>99,999x (на MC для строки) |
| <a id="p106235"></a>HI | <a id="p106236"></a>999x (на MC для транзита) |
| <a id="p106237"></a>GS | <a id="p106238"></a>1x (на декларацию при экспорте и импорте) |
| <a id="p106239"></a>GS | <a id="p106240"></a>9,999x (для краткой дополнительной декларации) |
| <a id="p106241"></a>GS | <a id="p106242"></a>1x (на HC) |
| <a id="p106243"></a>SI | <a id="p106244"></a>9,999 (на GS) |


<a id="p106245"></a>Количества элементов для классов данных


| <a id="p106246"></a>Элемент данных/подэлемент данных класса/подэлемент данных подкласса | <a id="p106247"></a>Название элемента/класса данных | <a id="p106248"></a>Название подэлемента/подкласса данных | <a id="p106249"></a>Декларация количества элементов | <a id="p106250"></a>Количество элементов MC | <a id="p106251"></a>Количество элементов MI | <a id="p106252"></a>Количество элементов HC | <a id="p106253"></a>Количество элементов HI | <a id="p106254"></a>Количество элементов GS | <a id="p106255"></a>Количество элементов SI |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| <a id="p106256"></a>11 01 000 000 | <a id="p106257"></a>Вид декларации |  | <a id="p106258"></a>1x |  |  |  | <a id="p106259"></a>1x |  |  |
| <a id="p106260"></a>11 02 000 000 | <a id="p106261"></a>Вид дополнительной декларации |  | <a id="p106262"></a>1x |  |  |  |  |  |  |
| <a id="p106263"></a>11 03 000 000 | <a id="p106264"></a>Номер пунктов товаров |  |  |  | <a id="p106265"></a>1x |  | <a id="p106266"></a>1x |  | <a id="p106267"></a>1x |
| <a id="p106268"></a>11 04 00 000 | <a id="p106269"></a>Индикатор особого обстоятельства |  | <a id="p106270"></a>1x |  |  |  |  |  |  |
| <a id="p106271"></a>11 05 000 000 | <a id="p106272"></a>Индикатор повторного ввоза |  | <a id="p106273"></a>1x |  |  |  |  |  |  |
| <a id="p106274"></a>11 06 000 000 | <a id="p106275"></a>Разделенный груз |  | <a id="p106276"></a>1x |  |  |  |  |  |  |
| <a id="p106277"></a>11 06 001 000 |  | <a id="p106278"></a>Индикатор разделенного груза | <a id="p106279"></a>1x |  |  |  |  |  |  |
| <a id="p106280"></a>11 06 002 000 |  | <a id="p106281"></a>Предыдущий MRN | <a id="p106282"></a>1x |  |  |  |  |  |  |
| <a id="p106283"></a>11 07 000 000 | <a id="p106284"></a>Безопасность |  | <a id="p106285"></a>1x |  |  |  |  |  |  |
| <a id="p106286"></a>11 08 000 000 | <a id="p106287"></a>Индикатор сокращенного комплекта данных |  | <a id="p106288"></a>1x |  |  |  |  |  |  |
| <a id="p106289"></a>11 09 000 000 | <a id="p106290"></a>Процедура |  |  |  |  |  |  |  | <a id="p106291"></a>1x |
| <a id="p106292"></a>11 09 001 000 |  | <a id="p106293"></a>Запрошенная процедура |  |  |  |  |  |  | <a id="p106294"></a>1x |
| <a id="p106295"></a>11 09 002 000 |  | <a id="p106296"></a>Предыдущая процедура |  |  |  |  |  |  | <a id="p106297"></a>1x |
| <a id="p106298"></a>11 10 000 000 | <a id="p106299"></a>Дополнительная процедура |  |  |  |  |  |  |  | <a id="p106300"></a>99x |
| <a id="p106301"></a>12 01 000 000 | <a id="p106302"></a>Предыдущие документы |  | <a id="p106303"></a>9,999x | <a id="p106304"></a>9,999x | <a id="p106305"></a>99x | <a id="p106306"></a>99x | <a id="p106307"></a>99x | <a id="p106308"></a>99x | <a id="p106309"></a>99x |
| <a id="p106310"></a>12 01 001 000 |  | <a id="p106311"></a>Исходящий номер | <a id="p106312"></a>1x | <a id="p106313"></a>1x | <a id="p106314"></a>1x | <a id="p106315"></a>1x | <a id="p106316"></a>1x | <a id="p106317"></a>1x | <a id="p106318"></a>1x |
| <a id="p106319"></a>12 01 002 000 |  | <a id="p106320"></a>Тип | <a id="p106321"></a>1x | <a id="p106322"></a>1x | <a id="p106323"></a>1x | <a id="p106324"></a>1x | <a id="p106325"></a>1x | <a id="p106326"></a>1x | <a id="p106327"></a>1x |
| <a id="p106328"></a>12 01 003 000 |  | <a id="p106329"></a>Тип упаковки |  |  | <a id="p106330"></a>1x |  | <a id="p106331"></a>1x |  | <a id="p106332"></a>1x |
| <a id="p106333"></a>12 01 004 000 |  | <a id="p106334"></a>Количество упаковок |  |  | <a id="p106335"></a>1x |  | <a id="p106336"></a>1x |  | <a id="p106337"></a>1x |
| <a id="p106338"></a>12 01 005 000 |  | <a id="p106339"></a>Единица измерения и спецификатор |  |  | <a id="p106340"></a>1x |  | <a id="p106341"></a>1x |  | <a id="p106342"></a>1x |
| <a id="p106343"></a>12 01 006 000 |  | <a id="p106344"></a>Количество |  |  | <a id="p106345"></a>1x |  | <a id="p106346"></a>1x |  | <a id="p106347"></a>1x |
| <a id="p106348"></a>12 01 079 000 |  | <a id="p106349"></a>Дополнение информации |  | <a id="p106350"></a>1x |  | <a id="p106351"></a>1x | <a id="p106352"></a>1x |  |  |
| <a id="p106353"></a>12 01 007 000 |  | <a id="p106354"></a>Идентификатор пунктов товаров |  | <a id="p106355"></a>1x | <a id="p106356"></a>1x | <a id="p106357"></a>1x | <a id="p106358"></a>1x |  | <a id="p106359"></a>1x |
| <a id="p106360"></a>12 02 000 000 | <a id="p106361"></a>Дополнительная информация |  |  | <a id="p106362"></a>99x | <a id="p106363"></a>99x | <a id="p106364"></a>99x | <a id="p106365"></a>99x | <a id="p106366"></a>99x | <a id="p106367"></a>99x |
| <a id="p106368"></a>12 02 008 000 |  | <a id="p106369"></a>Код |  | <a id="p106370"></a>1x | <a id="p106371"></a>1x | <a id="p106372"></a>1x | <a id="p106373"></a>1x | <a id="p106374"></a>1x | <a id="p106375"></a>1x |
| <a id="p106376"></a>12 02 009 000 |  | <a id="p106377"></a>Текст |  | <a id="p106378"></a>1x | <a id="p106379"></a>1x | <a id="p106380"></a>1x | <a id="p106381"></a>1x | <a id="p106382"></a>1x | <a id="p106383"></a>1x |
| <a id="p106384"></a>12 03 000 000 | <a id="p106385"></a>Подтверждающие документы |  |  | <a id="p106386"></a>99x | <a id="p106387"></a>99x | <a id="p106388"></a>99x | <a id="p106389"></a>99x | <a id="p106390"></a>99x | <a id="p106391"></a>99x |
| <a id="p106392"></a>12 03 001 000 |  | <a id="p106393"></a>Исходящий номер |  | <a id="p106394"></a>1x | <a id="p106395"></a>1x | <a id="p106396"></a>1x | <a id="p106397"></a>1x | <a id="p106398"></a>1x | <a id="p106399"></a>1x |
| <a id="p106400"></a>12 03 002 000 |  | <a id="p106401"></a>Тип |  | <a id="p106402"></a>1x | <a id="p106403"></a>1x | <a id="p106404"></a>1x | <a id="p106405"></a>1x | <a id="p106406"></a>1x | <a id="p106407"></a>1x |
| <a id="p106408"></a>12 03 010 000 |  | <a id="p106409"></a>Название выдающего органа |  |  |  |  |  | <a id="p106410"></a>1x | <a id="p106411"></a>1x |
| <a id="p106412"></a>12 03 005 000 |  | <a id="p106413"></a>Единица измерения и спецификатор |  |  |  |  |  |  | <a id="p106414"></a>1x |
| <a id="p106415"></a>12 03 006 000 |  | <a id="p106416"></a>Количество |  |  |  |  |  |  | <a id="p106417"></a>1x |
| <a id="p106418"></a>12 03 011 000 |  | <a id="p106419"></a>Дата срока действия |  |  |  |  |  | <a id="p106420"></a>1x | <a id="p106421"></a>1x |
| <a id="p106422"></a>12 03 012 000 |  | <a id="p106423"></a>Валюта |  |  |  |  |  |  | <a id="p106424"></a>1x |
| <a id="p106425"></a>12 03 013 000 |  | <a id="p106426"></a>Номер строки документа |  | <a id="p106427"></a>1x |  |  | <a id="p106428"></a>1x | <a id="p106429"></a>1x | <a id="p106430"></a>1x |
| <a id="p106431"></a>12 03 014 000 |  | <a id="p106432"></a>Сумма |  |  |  |  |  |  | <a id="p106433"></a>1x |
| <a id="p106434"></a>12 03 079 000 |  | <a id="p106435"></a>Дополнение информации |  | <a id="p106436"></a>1x |  |  | <a id="p106437"></a>1x |  |  |
| <a id="p106438"></a>12 04 000 000 | <a id="p106439"></a>Дополнительная ссылка |  |  | <a id="p106440"></a>99x | <a id="p106441"></a>99x | <a id="p106442"></a>99x | <a id="p106443"></a>99x | <a id="p106444"></a>99x | <a id="p106445"></a>99x |
| <a id="p106446"></a>12 04 001 000 |  | <a id="p106447"></a>Исходящий номер |  | <a id="p106448"></a>1x |  | <a id="p106449"></a>1x | <a id="p106450"></a>1x | <a id="p106451"></a>1x | <a id="p106452"></a>1x |
| <a id="p106453"></a>12 04 002 000 |  | <a id="p106454"></a>Тип |  | <a id="p106455"></a>1x | <a id="p106456"></a>1x | <a id="p106457"></a>1x | <a id="p106458"></a>1x | <a id="p106459"></a>1x | <a id="p106460"></a>1x |
| <a id="p106461"></a>12 05 000 000 | <a id="p106462"></a>Транспортный документ |  | <a id="p106463"></a>9,999x | <a id="p106464"></a>99x |  | <a id="p106465"></a>99x |  | <a id="p106466"></a>99x | <a id="p106467"></a>99x |
| <a id="p106468"></a>12 05 001 000 |  | <a id="p106469"></a>Исходящий номер | <a id="p106470"></a>1x | <a id="p106471"></a>1x |  | <a id="p106472"></a>1x |  | <a id="p106473"></a>1x | <a id="p106474"></a>1x |
| <a id="p106475"></a>12 05 002 000 |  | <a id="p106476"></a>Тип | <a id="p106477"></a>1x | <a id="p106478"></a>1x |  | <a id="p106479"></a>1x |  | <a id="p106480"></a>1x | <a id="p106481"></a>1x |
| <a id="p106482"></a>12 06 000 000 | <a id="p106483"></a>Номер [карнета](https://bukva.ai/docs/tamozhennaya-konventsiya-o-mezhdunarodnoy-2/statya-64#p100621) TIR |  | <a id="p106484"></a>1x |  |  |  |  |  |  |
| <a id="p106485"></a>12 07 000 000 | <a id="p106486"></a>Ссылка на запрос документов |  | <a id="p106487"></a>1x |  |  |  |  |  |  |
| <a id="p106488"></a>12 08 000 000 | <a id="p106489"></a>Исходящий номер/UCR (уникальный номер груза) |  |  | <a id="p106490"></a>1x | <a id="p106491"></a>1x | <a id="p106492"></a>1x | <a id="p106493"></a>1x | <a id="p106494"></a>1x | <a id="p106495"></a>1x |
| <a id="p106496"></a>12 09 000 000 | <a id="p106497"></a>LRN |  | <a id="p106498"></a>1x |  |  |  |  |  |  |
| <a id="p106499"></a>12 10 000 000 | <a id="p106500"></a>Отсроченный платеж |  | <a id="p106501"></a>9x |  |  |  |  |  |  |
| <a id="p106502"></a>12 11 000 000 | <a id="p106503"></a>Склад |  |  | <a id="p106504"></a>1x |  |  |  | <a id="p106505"></a>1x |  |
| <a id="p106506"></a>12 11 002 000 |  | <a id="p106507"></a>Тип |  | <a id="p106508"></a>1x |  |  |  | <a id="p106509"></a>1x |  |
| <a id="p106510"></a>12 11 015 000 |  | <a id="p106511"></a>Идентификатор |  | <a id="p106512"></a>1x |  |  |  | <a id="p106513"></a>1x |  |
| <a id="p106514"></a>12 12 000 000 | <a id="p106515"></a>Разрешение |  | <a id="p106516"></a>99x |  |  |  |  |  | <a id="p106517"></a>99x |
| <a id="p106518"></a>12 12 002 000 |  | <a id="p106519"></a>Тип | <a id="p106520"></a>1x |  |  |  |  |  | <a id="p106521"></a>1x |
| <a id="p106522"></a>12 12 001 000 |  | <a id="p106523"></a>Исходящий номер | <a id="p106524"></a>1x |  |  |  |  |  | <a id="p106525"></a>1x |
| <a id="p106526"></a>12 12 080 000 |  | <a id="p106527"></a>Владелец разрешения | <a id="p106528"></a>1x |  |  |  |  |  | <a id="p106529"></a>1x |
| <a id="p106530"></a>13 01 000 000 | <a id="p106531"></a>Экспортер |  | <a id="p106532"></a>1x |  |  |  |  | <a id="p106533"></a>1x | <a id="p106534"></a>1x |
| <a id="p106535"></a>13 01 016 000 |  | <a id="p106536"></a>Имя/название | <a id="p106537"></a>1x |  |  |  |  | <a id="p106538"></a>1x | <a id="p106539"></a>1x |
| <a id="p106540"></a>13 01 017 000 |  | <a id="p106541"></a>Идентификационный номер | <a id="p106542"></a>1x |  |  |  |  | <a id="p106543"></a>1x | <a id="p106544"></a>1x |
| <a id="p106545"></a>13 01 018 000 |  | <a id="p106546"></a>Адрес | <a id="p106547"></a>1x |  |  |  |  | <a id="p106548"></a>1x | <a id="p106549"></a>1x |
| <a id="p106550"></a>13 02 000 000 | <a id="p106551"></a>Грузоотправитель |  |  | <a id="p106552"></a>1x | <a id="p106553"></a>1x | <a id="p106554"></a>1x |  | <a id="p106555"></a>1x | <a id="p106556"></a>1x |
| <a id="p106557"></a>13 02 016 000 |  | <a id="p106558"></a>Имя/Название |  | <a id="p106559"></a>1x | <a id="p106560"></a>1x | <a id="p106561"></a>1x |  | <a id="p106562"></a>1x | <a id="p106563"></a>1x |
| <a id="p106564"></a>13 02 017 000 |  | <a id="p106565"></a>Идентификационный номер |  | <a id="p106566"></a>1x | <a id="p106567"></a>1x | <a id="p106568"></a>1x |  | <a id="p106569"></a>1x | <a id="p106570"></a>1x |
| <a id="p106571"></a>13 02 028 000 |  | <a id="p106572"></a>Тип лица |  | <a id="p106573"></a>1x | <a id="p106574"></a>1x | <a id="p106575"></a>1x |  | <a id="p106576"></a>1x | <a id="p106577"></a>1x |
| <a id="p106578"></a>13 02 018 000 |  | <a id="p106579"></a>Адрес |  | <a id="p106580"></a>1x | <a id="p106581"></a>1x | <a id="p106582"></a>1x |  | <a id="p106583"></a>1x | <a id="p106584"></a>1x |
| <a id="p106585"></a>13 02 029 000 |  | <a id="p106586"></a>Сообщение |  | <a id="p106587"></a>9x |  | <a id="p106588"></a>9x |  |  |  |
| <a id="p106589"></a>13 02 074 000 |  | <a id="p106590"></a>Лицо для контакта |  | <a id="p106591"></a>9x |  | <a id="p106592"></a>9x | <a id="p106593"></a>9x |  |  |
| <a id="p106594"></a>13 03 000 000 | <a id="p106595"></a>Грузополучатель |  | <a id="p106596"></a>1x | <a id="p106597"></a>1x | <a id="p106598"></a>1x | <a id="p106599"></a>1x | <a id="p106600"></a>1x | <a id="p106601"></a>1x | <a id="p106602"></a>1x |
| <a id="p106603"></a>13 03 016 000 |  | <a id="p106604"></a>Имя/Название | <a id="p106605"></a>1x | <a id="p106606"></a>1x | <a id="p106607"></a>1x | <a id="p106608"></a>1x | <a id="p106609"></a>1x | <a id="p106610"></a>1x | <a id="p106611"></a>1x |
| <a id="p106612"></a>13 03 017 000 |  | <a id="p106613"></a>Идентификационный номер | <a id="p106614"></a>1x | <a id="p106615"></a>1x | <a id="p106616"></a>1x | <a id="p106617"></a>1x | <a id="p106618"></a>1x | <a id="p106619"></a>1x | <a id="p106620"></a>1x |
| <a id="p106621"></a>13 03 017 000 |  | <a id="p106622"></a>Тип лица |  | <a id="p106623"></a>1x |  | <a id="p106624"></a>1x |  |  |  |
| <a id="p106625"></a>13 03 018 000 |  | <a id="p106626"></a>Адрес | <a id="p106627"></a>1x | <a id="p106628"></a>1x | <a id="p106629"></a>1x | <a id="p106630"></a>1x | <a id="p106631"></a>1x | <a id="p106632"></a>1x | <a id="p106633"></a>1x |
| <a id="p106634"></a>13 03 029 000 |  | <a id="p106635"></a>Сообщение |  | <a id="p106636"></a>9x |  | <a id="p106637"></a>9x |  |  |  |
| <a id="p106638"></a>13 04 000 000 | <a id="p106639"></a>Импортер |  | <a id="p106640"></a>1x |  |  |  |  |  |  |
| <a id="p106641"></a>13 04 016 000 |  | <a id="p106642"></a>Имя/Название | <a id="p106643"></a>1x |  |  |  |  |  |  |
| <a id="p106644"></a>13 04 017 000 |  | <a id="p106645"></a>Идентификационный номер | <a id="p106646"></a>1x |  |  |  |  |  |  |
| <a id="p106647"></a>1304 018 000 |  | <a id="p106648"></a>Адрес | <a id="p106649"></a>1x |  |  |  |  |  |  |
| <a id="p106650"></a>13 05 000 000 | <a id="p106651"></a>Декларант |  | <a id="p106652"></a>1x |  |  |  |  |  |  |
| <a id="p106653"></a>13 05 016 000 |  | <a id="p106654"></a>Имя/Название | <a id="p106655"></a>1x |  |  |  |  |  |  |
| <a id="p106656"></a>13 05 017 000 |  | <a id="p106657"></a>Идентификационный номер | <a id="p106658"></a>1x |  |  |  |  |  |  |
| <a id="p106659"></a>13 05 018 000 |  | <a id="p106660"></a>Адрес | <a id="p106661"></a>1x |  |  |  |  |  |  |
| <a id="p106662"></a>13 05 029 000 |  | <a id="p106663"></a>Сообщение | <a id="p106664"></a>9x |  |  |  |  |  |  |
| <a id="p106665"></a>13 05 074 000 |  | <a id="p106666"></a>Лицо для контакта | <a id="p106667"></a>9x |  |  |  |  |  |  |
| <a id="p106668"></a>13 06 000 000 | <a id="p106669"></a>Представитель |  | <a id="p106670"></a>1x |  |  |  |  |  |  |
| <a id="p106671"></a>13 06 016 000 |  | <a id="p106672"></a>Имя/название | <a id="p106673"></a>1x |  |  |  |  |  |  |
| <a id="p106674"></a>13 06 017 000 |  | <a id="p106675"></a>Идентификационный номер | <a id="p106676"></a>1x |  |  |  |  |  |  |
| <a id="p106677"></a>13 06 030 000 |  | <a id="p106678"></a>Статус | <a id="p106679"></a>1x |  |  |  |  |  |  |
| <a id="p106680"></a>13 06 018 000 |  | <a id="p106681"></a>Адрес | <a id="p106682"></a>1x |  |  |  |  |  |  |
| <a id="p106683"></a>13 06 029 028 |  | <a id="p106684"></a>Сообщение | <a id="p106685"></a>9x |  |  |  |  |  |  |
| <a id="p106686"></a>13 06 074 000 |  | <a id="p106687"></a>Лицо для контакта | <a id="p106688"></a>9x |  |  |  |  |  |  |
| <a id="p106689"></a>13 07 000 000 | <a id="p106690"></a>Владелец процедуры транзита |  | <a id="p106691"></a>1x |  |  |  |  |  |  |
| <a id="p106692"></a>13 07 016 000 |  | <a id="p106693"></a>Имя/Название | <a id="p106694"></a>1x |  |  |  |  |  |  |
| <a id="p106695"></a>13 07 017 000 |  | <a id="p106696"></a>Идентификационный номер | <a id="p106697"></a>1x |  |  |  |  |  |  |
| <a id="p106698"></a>13 07 078 000 |  | <a id="p106699"></a>Идентификационный номер владельца TIR | <a id="p106700"></a>1x |  |  |  |  |  |  |
| <a id="p106701"></a>13 07 018 000 |  | <a id="p106702"></a>Адрес | <a id="p106703"></a>1x |  |  |  |  |  |  |
| <a id="p106704"></a>13 07 074 000 |  | <a id="p106705"></a>Лицо для контакта | <a id="p106706"></a>1x |  |  |  |  |  |  |
| <a id="p106707"></a>13 08 000 000 | <a id="p106708"></a>Продавец |  |  |  |  |  |  | <a id="p106709"></a>1x | <a id="p106710"></a>1x |
| <a id="p106711"></a>13 08 016 000 |  | <a id="p106712"></a>Имя/Название |  |  |  |  |  | <a id="p106713"></a>1x | <a id="p106714"></a>1x |
| <a id="p106715"></a>13 08 017 000 |  | <a id="p106716"></a>Идентификационный номер |  |  |  |  |  | <a id="p106717"></a>1x | <a id="p106718"></a>1x |
| <a id="p106719"></a>13 08 028 000 |  | <a id="p106720"></a>Тип лица |  |  |  |  |  | <a id="p106721"></a>1x | <a id="p106722"></a>1x |
| <a id="p106723"></a>13 08 018 000 |  | <a id="p106724"></a>Адрес |  |  |  |  |  | <a id="p106725"></a>1x | <a id="p106726"></a>1x |
| <a id="p106727"></a>13 08 029 000 |  | <a id="p106728"></a>Сообщение |  |  |  |  |  | <a id="p106729"></a>9x |  |
| <a id="p106730"></a>13 09 000 000 | <a id="p106731"></a>Покупатель |  |  |  |  |  |  | <a id="p106732"></a>1x | <a id="p106733"></a>1x |
| <a id="p106734"></a>13 09 016 000 |  | <a id="p106735"></a>Имя/Название |  |  |  |  |  | <a id="p106736"></a>1x | <a id="p106737"></a>1x |
| <a id="p106738"></a>13 09 017 000 |  | <a id="p106739"></a>Идентификационный номер |  |  |  |  |  | <a id="p106740"></a>1x | <a id="p106741"></a>1x |
| <a id="p106742"></a>13 09 028 000 |  | <a id="p106743"></a>Тип лица |  |  |  |  |  | <a id="p106744"></a>1x | <a id="p106745"></a>1x |
| <a id="p106746"></a>13 09 018 000 |  | <a id="p106747"></a>Адрес |  |  |  |  |  | <a id="p106748"></a>1x | <a id="p106749"></a>1x |
| <a id="p106750"></a>13 09 029 000 |  | <a id="p106751"></a>Сообщение |  |  |  |  |  | <a id="p106752"></a>9x |  |
| <a id="p106753"></a>13 10 000 000 | <a id="p106754"></a>Лицо, уведомляющее о прибытии |  | <a id="p106755"></a>1x |  |  |  |  |  |  |
| <a id="p106756"></a>13 10 017 000 |  | <a id="p106757"></a>Идентификационный номер | <a id="p106758"></a>1x |  |  |  |  |  |  |
| <a id="p106759"></a>13 10 029 000 |  | <a id="p106760"></a>Сообщение | <a id="p106761"></a>9x |  |  |  |  |  |  |
| <a id="p106762"></a>13 11 000 000 | <a id="p106763"></a>Лицо, представляющее товары |  | <a id="p106764"></a>1x |  |  |  |  |  |  |
| <a id="p106765"></a>13 11 017 00 |  | <a id="p106766"></a>Идентификационный номер | <a id="p106767"></a>1x |  |  |  |  |  |  |
| <a id="p106768"></a>13 12 000 000 | <a id="p106769"></a>Перевозчик |  |  | <a id="p106770"></a>1x |  | <a id="p106771"></a>1x |  |  |  |
| <a id="p106772"></a>13 12 016 000 |  | <a id="p106773"></a>Имя/Название |  | <a id="p106774"></a>1x |  |  |  |  |  |
| <a id="p106775"></a>13 12 017 000 |  | <a id="p106776"></a>Идентификационный номер |  | <a id="p106777"></a>1x |  | <a id="p106778"></a>1x |  |  |  |
| <a id="p106779"></a>13 12 018 000 |  | <a id="p106780"></a>Адрес |  | <a id="p106781"></a>1x |  |  |  |  |  |
| <a id="p106782"></a>13 12 029 000 |  | <a id="p106783"></a>Сообщение |  | <a id="p106784"></a>9x |  |  |  |  |  |
| <a id="p106785"></a>13 12 074 000 |  | <a id="p106786"></a>Лицо для контакта |  | <a id="p106787"></a>9x |  |  |  |  |  |
| <a id="p106788"></a>13 13 000 000 | <a id="p106789"></a>Уведомляющее лицо |  |  | <a id="p106790"></a>1x |  | <a id="p106791"></a>1x |  |  |  |
| <a id="p106792"></a>13 13 016 000 |  | <a id="p106793"></a>Имя/Название |  | <a id="p106794"></a>1x |  | <a id="p106795"></a>1x |  |  |  |
| <a id="p106796"></a>13 13 017 000 |  | <a id="p106797"></a>Идентификационный номер |  | <a id="p106798"></a>1x |  | <a id="p106799"></a>1x |  |  |  |
| <a id="p106800"></a>13 13 028 000 |  | <a id="p106801"></a>Тип лица |  | <a id="p106802"></a>1x |  | <a id="p106803"></a>1x |  |  |  |
| <a id="p106804"></a>13 13 018 000 |  | <a id="p106805"></a>Адрес |  | <a id="p106806"></a>1x |  | <a id="p106807"></a>1x |  |  |  |
| <a id="p106808"></a>13 13 029 000 |  | <a id="p106809"></a>Сообщение |  | <a id="p106810"></a>9x |  | <a id="p106811"></a>9x |  |  |  |
| <a id="p106812"></a>13 14 000 000 | <a id="p106813"></a>Дополнительный участок системы поставки |  |  | <a id="p106814"></a>99x | <a id="p106815"></a>99x | <a id="p106816"></a>99x | <a id="p106817"></a>99x | <a id="p106818"></a>99x | <a id="p106819"></a>99x |
| <a id="p106820"></a>13 14 031 000 |  | <a id="p106821"></a>Роль |  | <a id="p106822"></a>1x | <a id="p106823"></a>1x | <a id="p106824"></a>1x | <a id="p106825"></a>1x | <a id="p106826"></a>1x | <a id="p106827"></a>1x |
| <a id="p106828"></a>13 14 017 000 |  | <a id="p106829"></a>Идентификационный номер |  | <a id="p106830"></a>1x | <a id="p106831"></a>1x | <a id="p106832"></a>1x | <a id="p106833"></a>1x | <a id="p106834"></a>1x | <a id="p106835"></a>1x |
| <a id="p106836"></a>13 15 000 000 | <a id="p106837"></a>Дополнительный декларант |  |  | <a id="p106838"></a>1x |  | <a id="p106839"></a>1x |  |  |  |
| <a id="p106840"></a>13 15 017 000 |  | <a id="p106841"></a>Идентификационный номер |  | <a id="p106842"></a>1x |  | <a id="p106843"></a>1x |  |  |  |
| <a id="p106844"></a>13 15 032 000 |  | <a id="p106845"></a>Тип дополнительного дела |  | <a id="p106846"></a>1x |  | <a id="p106847"></a>1x |  |  |  |
| <a id="p106848"></a>13 16 000 000 | <a id="p106849"></a>Дополнительные фискальные ссылки |  |  |  |  |  |  | <a id="p106850"></a>99x | <a id="p106851"></a>99x |
| <a id="p106852"></a>13 16 031 000 |  | <a id="p106853"></a>Роль |  |  |  |  |  | <a id="p106854"></a>1x | <a id="p106855"></a>1x |
| <a id="p106856"></a>13 16 034 000 |  | <a id="p106857"></a>Идентификационный номер НДС |  |  |  |  |  | <a id="p106858"></a>1x | <a id="p106859"></a>1x |
| <a id="p106860"></a>13 17 000 000 | <a id="p106861"></a>Лицо, подающее грузовой таможенный манифест |  | <a id="p106862"></a>1x |  |  |  |  |  |  |
| <a id="p106863"></a>13 17 017 000 |  | <a id="p106864"></a>Идентификационный номер | <a id="p106865"></a>1x |  |  |  |  |  |  |
| <a id="p106866"></a>13 18 000 000 | <a id="p106867"></a>Лицо, запрашивающее доказательство таможенного статуса товаров Союза |  | <a id="p106868"></a>1x |  |  |  |  |  |  |
| <a id="p106869"></a>13 18 017 000 |  | <a id="p106870"></a>Идентификационный номер | <a id="p106871"></a>1x |  |  |  |  |  |  |
| <a id="p106872"></a>13 19 000 000 | <a id="p106873"></a>Лицо, уведомляющее о прибытии товаров после перемещения на внутреннем хранении |  | <a id="p106874"></a>1x |  |  |  |  |  |  |
| <a id="p106875"></a>13 19 017 000 |  | <a id="p106876"></a>Идентификационный номер | <a id="p106877"></a>1x |  |  |  |  |  |  |
| <a id="p106878"></a>13 20 000 000 | <a id="p106879"></a>Лицо, предоставляющее гарантию |  | <a id="p106880"></a>1x |  |  |  |  |  |  |
| <a id="p106881"></a>13 20 017 000 |  | <a id="p106882"></a>Идентификационный номер | <a id="p106883"></a>1x |  |  |  |  |  |  |
| <a id="p106884"></a>13 21 000 000 | <a id="p106885"></a>Лицо, оплачивающее таможенную пошлину |  | <a id="p106886"></a>1x |  |  |  |  |  |  |
| <a id="p106887"></a>13 21 017 000 |  | <a id="p106888"></a>Идентификационный номер | <a id="p106889"></a>1x |  |  |  |  |  |  |
| <a id="p106890"></a>14 01 000 000 | <a id="p106891"></a>Условия поставки |  |  |  |  |  |  | <a id="p106892"></a>1x |  |
| <a id="p106893"></a>14 01 035 000 |  | <a id="p106894"></a>Код INCOTERM |  |  |  |  |  | <a id="p106895"></a>1x |  |
| <a id="p106896"></a>14 01 036 000 |  | <a id="p106897"></a>Код UN/LOCODE |  |  |  |  |  | <a id="p106898"></a>1x |  |
| <a id="p106899"></a>14 01 020 000 |  | <a id="p106900"></a>Страна |  |  |  |  |  | <a id="p106901"></a>1x |  |
| <a id="p106902"></a>14 01 037 000 |  | <a id="p106903"></a>Место |  |  |  |  |  | <a id="p106904"></a>1x |  |
| <a id="p106905"></a>14 02 000 000 | <a id="p106906"></a>Транспортные сборы |  |  | <a id="p106907"></a>1x | <a id="p106908"></a>1x | <a id="p106909"></a>1x |  |  |  |
| <a id="p106910"></a>14 02 038 000 |  | <a id="p106911"></a>Способ оплаты |  | <a id="p106912"></a>1x | <a id="p106913"></a>1x | <a id="p106914"></a>1x |  |  |  |
| <a id="p106915"></a>14 03 000 000 | <a id="p106916"></a>Пошлины и налоги |  |  |  |  |  |  |  | <a id="p106917"></a>99x |
| <a id="p106918"></a>14 03 039 000 |  | <a id="p106919"></a>Тип налога |  |  |  |  |  |  | <a id="p106920"></a>1x |
| <a id="p106921"></a>14 03 038 000 |  | <a id="p106922"></a>Метод оплаты |  |  |  |  |  |  | <a id="p106923"></a>99x |
| <a id="p106924"></a>14 03 042 000 |  | <a id="p106925"></a>Сумма выплачиваемого налога |  |  |  |  |  |  | <a id="p106926"></a>1x |
| <a id="p106927"></a>14 03 040 000 |  | <a id="p106928"></a>Налоговая база |  |  |  |  |  |  | <a id="p106929"></a>99x |
| <a id="p106930"></a>14 16 000 000 |  | <a id="p106931"></a>Общая сумма пошлин и налогов |  |  |  |  |  |  | <a id="p106932"></a>1x |
| <a id="p106933"></a>14 17 000 000 | <a id="p106934"></a>Единица внутренней валюты |  | <a id="p106935"></a>1x |  |  |  |  |  |  |
| <a id="p106936"></a>14 04 008 000 | <a id="p106937"></a>Надбавки и вычеты |  |  |  |  |  |  | <a id="p106938"></a>99x | <a id="p106939"></a>99x |
| <a id="p106940"></a>14 04 008 000 |  | <a id="p106941"></a>Код |  |  |  |  |  | <a id="p106942"></a>1x | <a id="p106943"></a>1x |
| <a id="p106944"></a>14 04 014 000 |  | <a id="p106945"></a>Сумма |  |  |  |  |  | <a id="p106946"></a>1x | <a id="p106947"></a>1x |
| <a id="p106948"></a>14 05 000 000 | <a id="p106949"></a>Валюта инвойса |  | <a id="p106950"></a>1x |  |  |  |  | <a id="p106951"></a>1x |  |
| <a id="p106952"></a>14 06 000 000 | <a id="p106953"></a>Общая сумма выставленных счетов |  | <a id="p106954"></a>1x |  |  |  |  | <a id="p106955"></a>1x |  |
| <a id="p106956"></a>14 07 000 000 | <a id="p106957"></a>Показатели оценки |  |  |  |  |  |  |  | <a id="p106958"></a>1x |
| <a id="p106959"></a>14 08 000 000 | <a id="p106960"></a>Цена/сумма наименования |  |  |  |  |  |  |  | <a id="p106961"></a>1x |
| <a id="p106962"></a>14 09 000 000 | <a id="p106963"></a>Курс обмена |  | <a id="p106964"></a>1x |  |  |  |  |  |  |
| <a id="p106965"></a>14 10 000 000 | <a id="p106966"></a>Способ оценки |  |  |  |  |  |  |  | <a id="p106967"></a>1x |
| <a id="p106968"></a>14 11 000 000 | <a id="p106969"></a>Преференция |  |  |  |  |  |  |  | <a id="p106970"></a>1x |
| <a id="p106971"></a>14 12 000 000 | <a id="p106972"></a>Почтовая стоимость |  |  |  |  |  | <a id="p106973"></a>1x |  | <a id="p106974"></a>1x |
| <a id="p106975"></a>14 12 012 000 |  | <a id="p106976"></a>Код валюты |  |  |  |  | <a id="p106977"></a>1x |  | <a id="p106978"></a>1x |
| <a id="p106979"></a>14 12 0140 00 |  | <a id="p106980"></a>Сумма |  |  |  |  | <a id="p106981"></a>1x |  | <a id="p106982"></a>1x |
| <a id="p106983"></a>14 13 000 000 | <a id="p106984"></a>Почтовые сборы |  | <a id="p106985"></a>1x |  |  | <a id="p106986"></a>1x |  |  |  |
| <a id="p106987"></a>14 13 012 000 |  | <a id="p106988"></a>Код валюты | <a id="p106989"></a>1x |  |  | <a id="p106990"></a>1x |  |  |  |
| <a id="p106991"></a>14 14 014 000 |  | <a id="p106992"></a>Сумма | <a id="p106993"></a>1x |  |  | <a id="p106994"></a>1x |  |  |  |
| <a id="p106995"></a>14 14 000 000 | <a id="p106996"></a>Внутренняя стоимость |  |  |  |  |  |  |  | <a id="p106997"></a>1x |
| <a id="p106998"></a>14 14 012 000 |  | <a id="p106999"></a>Код валюты |  |  |  |  |  |  | <a id="p107000"></a>1x |
| <a id="p107001"></a>14 14 014 000 |  | <a id="p107002"></a>Сумма |  |  |  |  |  |  | <a id="p107003"></a>1x |
| <a id="p107004"></a>14 15 000 000 | <a id="p107005"></a>Транспортные и страховые расходы до места назначения |  |  |  |  |  |  | <a id="p107006"></a>1x | <a id="p107007"></a>1x |
| <a id="p107008"></a>14 15 012 000 |  | <a id="p107009"></a>Код валюты |  |  |  |  |  | <a id="p107010"></a>1x | <a id="p107011"></a>1x |
| <a id="p107012"></a>14 15 014 000 |  | <a id="p107013"></a>Сумма |  |  |  |  |  | <a id="p107014"></a>1x | <a id="p107015"></a>1x |
| <a id="p107016"></a>15 01 000 000 | <a id="p107017"></a>Предполагаемая дата и время отправления |  | <a id="p107018"></a>1x |  |  |  |  |  |  |
| <a id="p107019"></a>15 02 000 000 | <a id="p107020"></a>Фактическая дата и время отправления |  | <a id="p107021"></a>1x |  |  |  |  |  |  |
| <a id="p107022"></a>15 03 000 000 | <a id="p107023"></a>Предполагаемая дата и время прибытия |  | <a id="p107024"></a>1x |  |  |  |  |  |  |
| <a id="p107025"></a>15 04 000 000 | <a id="p107026"></a>Предполагаемая дата и время прибытия в порт разгрузки |  | <a id="p107027"></a>1x | <a id="p107028"></a>1x |  |  |  |  |  |
| <a id="p107029"></a>15 05 000 000 | <a id="p107030"></a>Фактическая дата и время прибытия |  | <a id="p107031"></a>1x |  |  |  |  |  |  |
| <a id="p107032"></a>15 06 000 000 | <a id="p107033"></a>Дата декларации |  | <a id="p107034"></a>1x |  |  |  |  |  |  |
| <a id="p107035"></a>15 07 000 000 | <a id="p107036"></a>Запрошенное действие доказательства |  | <a id="p107037"></a>1x |  |  |  |  |  |  |
| <a id="p107038"></a>15 08 000 000 | <a id="p107039"></a>Дата и время представления товаров |  | <a id="p107040"></a>1x |  |  |  |  |  |  |
| <a id="p107041"></a>15 09 000 000 | <a id="p107042"></a>Дата приемки |  |  |  |  |  |  | <a id="p107043"></a>1x | <a id="p107044"></a>1x |
| <a id="p107045"></a>16 02 000 000 | <a id="p107046"></a>Государство-член ЕС, в которое адресованы товары |  |  |  |  |  |  |  |  |
| <a id="p107047"></a>16 02 000 000 | <a id="p107048"></a>Государство-член ЕС, в которое адресованы товары |  | <a id="p107049"></a>1x |  |  |  |  |  |  |
| <a id="p107050"></a>16 02 020 000 |  | <a id="p107051"></a>Страна | <a id="p107052"></a>1x |  |  |  |  |  |  |
| <a id="p107053"></a>16 03 000 000 | <a id="p107054"></a>Страна места назначения |  |  | <a id="p107055"></a>1x |  |  | <a id="p107056"></a>1x | <a id="p107057"></a>1x | <a id="p107058"></a>1x |
| <a id="p107059"></a>16 04 000 000 | <a id="p107060"></a>Регион места назначения |  |  |  |  |  |  | <a id="p107061"></a>1x | <a id="p107062"></a>1x |
| <a id="p107063"></a>16 05 000 000 | <a id="p107064"></a>Место поставки |  |  | <a id="p107065"></a>1x |  | <a id="p107066"></a>1x |  |  |  |
| <a id="p107067"></a>16 05 036 000 |  | <a id="p107068"></a>UN/CODE |  | <a id="p107069"></a>1x |  | <a id="p107070"></a>1x |  |  |  |
| <a id="p107071"></a>16 05 020 000 |  | <a id="p107072"></a>Страна |  | <a id="p107073"></a>1x |  | <a id="p107074"></a>1x |  |  |  |
| <a id="p107075"></a>16 05 037 000 |  | <a id="p107076"></a>Место |  | <a id="p107077"></a>1x |  | <a id="p107078"></a>1x |  |  |  |
| <a id="p107079"></a>16 06 000 000 | <a id="p107080"></a>Страна отправления |  |  | <a id="p107081"></a>1x |  | <a id="p107082"></a>1x | <a id="p107083"></a>1x | <a id="p107084"></a>1x | <a id="p107085"></a>1x |
| <a id="p107086"></a>16 07 000 000 | <a id="p107087"></a>Страна экспорта |  |  |  |  |  |  | <a id="p107088"></a>1x | <a id="p107089"></a>1x |
| <a id="p107090"></a>16 08 000 000 | <a id="p107091"></a>Страна происхождения |  |  |  |  |  | <a id="p107092"></a>1x |  | <a id="p107093"></a>1x |
| <a id="p107094"></a>16 09 000 000 | <a id="p107095"></a>Страна преференциального происхождения |  |  |  |  |  |  |  | <a id="p107096"></a>1x |
| <a id="p107097"></a>16 10 000 000 | <a id="p107098"></a>Регион отправления |  |  |  |  |  |  |  | <a id="p107099"></a>1x |
| <a id="p107100"></a>16 11 000 000 | <a id="p107101"></a>Страны маршрута транспортных средств |  | <a id="p107102"></a>99x |  |  |  |  |  |  |
| <a id="p107103"></a>16 11 020 000 |  | <a id="p107104"></a>Страна | <a id="p107105"></a>1x |  |  |  |  |  |  |
| <a id="p107106"></a>16 12 000 000 | <a id="p107107"></a>Страна маршрута груза |  |  | <a id="p107108"></a>99x |  | <a id="p107109"></a>99x |  |  |  |
| <a id="p107110"></a>16 12 020 000 |  | <a id="p107111"></a>Страна |  | <a id="p107112"></a>1x |  | <a id="p107113"></a>1x |  |  |  |
| <a id="p107114"></a>16 13 000 000 | <a id="p107115"></a>Место погрузки |  |  | <a id="p107116"></a>1x |  |  |  |  |  |
| <a id="p107117"></a>16 13 036 000 |  | <a id="p107118"></a>Код UN/LOCODE |  | <a id="p107119"></a>1x |  |  |  |  |  |
| <a id="p107120"></a>16 13 020 000 |  | <a id="p107121"></a>Страна |  | <a id="p107122"></a>1x |  |  |  |  |  |
| <a id="p107123"></a>16 13 037 000 |  | <a id="p107124"></a>Место |  | <a id="p107125"></a>1x |  |  |  |  |  |
| <a id="p107126"></a>16 14 000 000 | <a id="p107127"></a>Место разгрузки |  |  | <a id="p107128"></a>1x |  |  |  |  |  |
| <a id="p107129"></a>16 14 036 000 |  | <a id="p107130"></a>Код UN/LOCODE |  | <a id="p107131"></a>1x |  |  |  |  |  |
| <a id="p107132"></a>16 14 020 000 |  | <a id="p107133"></a>Страна |  | <a id="p107134"></a>1x |  |  |  |  |  |
| <a id="p107135"></a>16 14 037 000 |  | <a id="p107136"></a>Место |  | <a id="p107137"></a>1x |  |  |  |  |  |
| <a id="p107138"></a>16 15 000 000 | <a id="p107139"></a>Местонахождение товаров |  |  | <a id="p107140"></a>1x |  |  |  | <a id="p107141"></a>1x |  |
| <a id="p107142"></a>16 15 045 000 |  | <a id="p107143"></a>Тип местонахождения |  | <a id="p107144"></a>1x |  |  |  | <a id="p107145"></a>1x |  |
| <a id="p107146"></a>16 15 046 000 |  | <a id="p107147"></a>Классификатор идентификации |  | <a id="p107148"></a>1x |  |  |  | <a id="p107149"></a>1x |  |
| <a id="p107150"></a>16 15 036 000 |  | <a id="p107151"></a>Код UN/LOCODE |  | <a id="p107152"></a>1x |  |  |  | <a id="p107153"></a>1x |  |
| <a id="p107154"></a>16 15 047 000 |  | <a id="p107155"></a>Таможенное учреждение |  | <a id="p107156"></a>1x |  |  |  | <a id="p107157"></a>1x |  |
| <a id="p107158"></a>16 15 048 000 |  | <a id="p107159"></a>GNSS |  | <a id="p107160"></a>1x |  |  |  | <a id="p107161"></a>1x |  |
| <a id="p107162"></a>16 15 051 000 |  | <a id="p107163"></a>Субъект экономической деятельности |  | <a id="p107164"></a>1x |  |  |  | <a id="p107165"></a>1x |  |
| <a id="p107166"></a>16 15 051 017 |  | <a id="p107167"></a>Номер разрешения |  | <a id="p107168"></a>1x |  |  |  | <a id="p107169"></a>1x |  |
| <a id="p107170"></a>16 15 052 000 |  | <a id="p107171"></a>Номер разрешения |  | <a id="p107172"></a>1x |  |  |  | <a id="p107173"></a>1x |  |
| <a id="p107174"></a>16 15 053 000 |  | <a id="p107175"></a>Дополнительный идентификатор |  | <a id="p107176"></a>1x |  |  |  | <a id="p107177"></a>1x |  |
| <a id="p107178"></a>16 15 018 000 |  | <a id="p107179"></a>Адрес |  | <a id="p107180"></a>1x |  |  |  | <a id="p107181"></a>1x |  |
| <a id="p107182"></a>16 15 081 000 |  | <a id="p107183"></a>Адрес почтового индекса |  | <a id="p107184"></a>1x |  |  |  | <a id="p107185"></a>1x |  |
| <a id="p107186"></a>16 15 074 000 |  | <a id="p107187"></a>Лицо для контакта |  | <a id="p107188"></a>9x |  |  |  | <a id="p107189"></a>9x |  |
| <a id="p107190"></a>16 16 000 000 | <a id="p107191"></a>Место приемки |  |  | <a id="p107192"></a>1x |  | <a id="p107193"></a>1x |  |  |  |
| <a id="p107194"></a>16 16 036 000 |  | <a id="p107195"></a>Код UN/LOCODE |  | <a id="p107196"></a>1x |  | <a id="p107197"></a>1x |  |  |  |
| <a id="p107198"></a>16 16 020 000 |  | <a id="p107199"></a>Страна |  | <a id="p107200"></a>1x |  | <a id="p107201"></a>1x |  |  |  |
| <a id="p107202"></a>16 16 037 000 |  | <a id="p107203"></a>Место |  | <a id="p107204"></a>1x |  | <a id="p107205"></a>1x |  |  |  |
| <a id="p107206"></a>16 17 000 000 | <a id="p107207"></a>Обязательный журнал |  | <a id="p107208"></a>1x |  |  |  |  |  |  |
| <a id="p107209"></a>17 01 000 000 | <a id="p107210"></a>Таможенное учреждение вывоза |  | <a id="p107211"></a>1x |  |  |  |  |  |  |
| <a id="p107212"></a>17 01 001 000 |  | <a id="p107213"></a>Исходящий номер | <a id="p107214"></a>1x |  |  |  |  |  |  |
| <a id="p107215"></a>17 02 000 000 | <a id="p107216"></a>Таможенное учреждение экспорта |  | <a id="p107217"></a>1x |  |  |  |  |  |  |
| <a id="p107218"></a>17 02 001 000 |  | <a id="p107219"></a>Исходящий номер | <a id="p107220"></a>1x |  |  |  |  |  |  |
| <a id="p107221"></a>17 03 000 000 | <a id="p107222"></a>Таможенное учреждение отправления |  | <a id="p107223"></a>1x |  |  |  |  |  |  |
| <a id="p107224"></a>17 03 001 000 |  | <a id="p107225"></a>Исходящий номер | <a id="p107226"></a>1x |  |  |  |  |  |  |
| <a id="p107227"></a>17 04 000 000 | <a id="p107228"></a>Таможенное учреждение транзита |  | <a id="p107229"></a>9x |  |  |  |  |  |  |
| <a id="p107230"></a>17 04 001 000 |  | <a id="p107231"></a>Исходящий номер | <a id="p107232"></a>1x |  |  |  |  |  |  |
| <a id="p107233"></a>17 05 000 000 | <a id="p107234"></a>Таможенное учреждение места назначения |  | <a id="p107235"></a>1x |  |  |  |  |  |  |
| <a id="p107236"></a>17 05 001 000 |  | <a id="p107237"></a>Исходящий номер | <a id="p107238"></a>1x |  |  |  |  |  |  |
| <a id="p107239"></a>17 06 000 000 | <a id="p107240"></a>Таможенное учреждение вывоза для транзита |  | <a id="p107241"></a>9x |  |  |  |  |  |  |
| <a id="p107242"></a>17 06 001 000 |  | <a id="p107243"></a>Исходящий номер | <a id="p107244"></a>1x |  |  |  |  |  |  |
| <a id="p107245"></a>17 07 000 000 | <a id="p107246"></a>Таможенное учреждение места первого ввоза |  | <a id="p107247"></a>1x |  |  |  |  |  |  |
| <a id="p107248"></a>17 07 001 000 |  | <a id="p107249"></a>Исходящий номер | <a id="p107250"></a>1x |  |  |  |  |  |  |
| <a id="p107251"></a>17 08 000 000 | <a id="p107252"></a>Фактическое таможенное учреждение места первого ввоза |  | <a id="p107253"></a>1x |  |  |  |  |  |  |
| <a id="p107254"></a>17 08 001 000 |  | <a id="p107255"></a>Исходящий номер | <a id="p107256"></a>1x |  |  |  |  |  |  |
| <a id="p107257"></a>17 09 000 000 | <a id="p107258"></a>Таможенное учреждение места представления |  | <a id="p107259"></a>1x |  |  |  |  |  |  |
| <a id="p107260"></a>17 09 001 000 |  | <a id="p107261"></a>Исходящий номер | <a id="p107262"></a>1x |  |  |  |  |  |  |
| <a id="p107263"></a>17 10 000 000 | <a id="p107264"></a>Надзорное таможенное учреждение |  | <a id="p107265"></a>1x |  |  |  |  |  |  |
| <a id="p107266"></a>17 10 001 000 |  | <a id="p107267"></a>Исходящий номер | <a id="p107268"></a>1x |  |  |  |  |  |  |
| <a id="p107269"></a>18 01 000 000 | <a id="p107270"></a>Масса нетто |  |  |  |  |  | <a id="p107271"></a>1x |  | <a id="p107272"></a>1x |
| <a id="p107273"></a>18 02 000 000 | <a id="p107274"></a>Дополнительные единицы |  |  |  |  |  |  |  | <a id="p107275"></a>1x |
| <a id="p107276"></a>18 03 000 000 | <a id="p107277"></a>Общая масса брутто |  | <a id="p107278"></a>1x | <a id="p107279"></a>1x |  | <a id="p107280"></a>1x |  |  |  |
| <a id="p107281"></a>18 04 000 000 | <a id="p107282"></a>Масса брутто |  |  | <a id="p107283"></a>1x | <a id="p107284"></a>1x | <a id="p107285"></a>1x | <a id="p107286"></a>1x | <a id="p107287"></a>1x | <a id="p107288"></a>1x |
| <a id="p107289"></a>18 05 000 000 | <a id="p107290"></a>Описание товаров |  |  |  | <a id="p107291"></a>1x |  | <a id="p107292"></a>1x |  | <a id="p107293"></a>1x |
| <a id="p107294"></a>18 06 000 000 | <a id="p107295"></a>Упаковка |  |  |  | <a id="p107296"></a>99x |  | <a id="p107297"></a>99x |  | <a id="p107298"></a>99x |
| <a id="p107299"></a>18 06 003 000 |  | <a id="p107300"></a>Вид упаковки |  |  | <a id="p107301"></a>1x |  | <a id="p107302"></a>1x |  | <a id="p107303"></a>1x |
| <a id="p107304"></a>18 06 004 000 |  | <a id="p107305"></a>Количество упаковок |  |  | <a id="p107306"></a>1x |  | <a id="p107307"></a>1x |  | <a id="p107308"></a>1x |
| <a id="p107309"></a>18 06 054 000 |  | <a id="p107310"></a>Грузовая маркировка |  |  | <a id="p107311"></a>1x |  | <a id="p107312"></a>1x |  | <a id="p107313"></a>1x |
| <a id="p107314"></a>18 07 000 000 | <a id="p107315"></a>Опасные товары |  |  |  | <a id="p107316"></a>99x |  | <a id="p107317"></a>99x |  |  |
| <a id="p107318"></a>18 07 055 000 |  | <a id="p107319"></a>Номер UN |  |  | <a id="p107320"></a>1x |  | <a id="p107321"></a>1x |  |  |
| <a id="p107322"></a>18 08 000 000 | <a id="p107323"></a>Код CUS |  |  |  | <a id="p107324"></a>1x |  | <a id="p107325"></a>1x |  | <a id="p107326"></a>1x |
| <a id="p107327"></a>18 09 000 000 | <a id="p107328"></a>Код товара |  |  |  | <a id="p107329"></a>1x |  | <a id="p107330"></a>1x |  | <a id="p107331"></a>1x |
| <a id="p107332"></a>18 09 056 000 |  | <a id="p107333"></a>Код подзаголовка гармонизированной системы |  |  | <a id="p107334"></a>1x |  | <a id="p107335"></a>1x |  | <a id="p107336"></a>1x |
| <a id="p107337"></a>18 09 057 000 |  | <a id="p107338"></a>Код объединенной номенклатуры |  |  | <a id="p107339"></a>1x |  | <a id="p107340"></a>1x |  | <a id="p107341"></a>1x |
| <a id="p107342"></a>18 09 058 000 |  | <a id="p107343"></a>Код TARIC |  |  |  |  |  |  | <a id="p107344"></a>1x |
| <a id="p107345"></a>18 09 059 000 |  | <a id="p107346"></a>Дополнительный код TARIC |  |  |  |  |  |  | <a id="p107347"></a>99x |
| <a id="p107348"></a>18 09 060 000 |  | <a id="p107349"></a>Национальные дополнительные коды |  |  |  |  |  |  | <a id="p107350"></a>99x |
| <a id="p107351"></a>18 10 000 000 | <a id="p107352"></a>Вид товаров |  |  |  |  |  | <a id="p107353"></a>1x |  | <a id="p107354"></a>1x |
| <a id="p107355"></a>19 01 000 000 | <a id="p107356"></a>Индикатор контейнера |  |  | <a id="p107357"></a>1x |  | <a id="p107358"></a>1x |  | <a id="p107359"></a>1x |  |
| <a id="p107360"></a>19 02 000 000 | <a id="p107361"></a>Номер ссылки на перевозку |  | <a id="p107362"></a>9x |  |  |  |  |  |  |
| <a id="p107363"></a>19 03 000 000 | <a id="p107364"></a>Вид транспорта на границе |  | <a id="p107365"></a>1x | <a id="p107366"></a>1x |  |  |  | <a id="p107367"></a>1x |  |
| <a id="p107368"></a>19 04 000 000 | <a id="p107369"></a>Внутренний вид транспорта |  |  | <a id="p107370"></a>1x |  |  |  | <a id="p107371"></a>1x |  |
| <a id="p107372"></a>19 05 000 000 | <a id="p107373"></a>Транспортное средство в месте отправления |  |  | <a id="p107374"></a>999x |  | <a id="p107375"></a>999x |  | <a id="p107376"></a>999x |  |
| <a id="p107377"></a>19 05 061 000 |  | <a id="p107378"></a>Тип идентификации |  | <a id="p107379"></a>1x |  |  |  | <a id="p107380"></a>1x |  |
| <a id="p107381"></a>19 05 017 000 |  | <a id="p107382"></a>Идентификационный номер |  | <a id="p107383"></a>1x |  |  |  | <a id="p107384"></a>1x |  |
| <a id="p107385"></a>19 05 062 000 |  | <a id="p107386"></a>Национальность |  | <a id="p107387"></a>1x |  |  |  | <a id="p107388"></a>1x |  |
| <a id="p107389"></a>19 06 000 000 | <a id="p107390"></a>Транспортное средство в месте прибытия |  |  | <a id="p107391"></a>1x |  |  |  | <a id="p107392"></a>1x |  |
| <a id="p107393"></a>19 06 061 000 |  | <a id="p107394"></a>Тип идентификации |  | <a id="p107395"></a>1x |  |  | <a id="p107396"></a>1x |  |  |
| <a id="p107397"></a>19 06 017 000 |  | <a id="p107398"></a>Идентификационный номер |  | <a id="p107399"></a>1x |  |  | <a id="p107400"></a>1x |  |  |
| <a id="p107401"></a>19 07 000 000 | <a id="p107402"></a>Транспортное оборудование |  |  | <a id="p107403"></a>9,999x | <a id="p107404"></a>9,999x | <a id="p107405"></a>9,999x | <a id="p107406"></a>9,999x | <a id="p107407"></a>9,999x |  |
| <a id="p107408"></a>19 07 063 000 |  | <a id="p107409"></a>Идентификационный номер контейнера |  | <a id="p107410"></a>1x | <a id="p107411"></a>1x | <a id="p107412"></a>1x | <a id="p107413"></a>1x | <a id="p107414"></a>1x |  |
| <a id="p107415"></a>19 07 044 000 |  | <a id="p107416"></a>Ссылка на товары |  | <a id="p107417"></a>9,999x |  |  |  | <a id="p107418"></a>9,999x |  |
| <a id="p107419"></a>19 07 064 000 |  | <a id="p107420"></a>Размер контейнера и тип идентификации |  | <a id="p107421"></a>1x | <a id="p107422"></a>1x | <a id="p107423"></a>1x | <a id="p107424"></a>1x |  |  |
| <a id="p107425"></a>19 07 065 000 |  | <a id="p107426"></a>Состояние упакованного контейнера |  | <a id="p107427"></a>1x | <a id="p107428"></a>1x | <a id="p107429"></a>1x | <a id="p107430"></a>1x |  |  |
| <a id="p107431"></a>19 07 066 000 |  | <a id="p107432"></a>Код вида поставщика контейнера |  | <a id="p107433"></a>1x | <a id="p107434"></a>1x | <a id="p107435"></a>1x | <a id="p107436"></a>1x |  |  |
| <a id="p107437"></a>19 08 000 000 | <a id="p107438"></a>Активное транспортное средство, пересекающее границу |  | <a id="p107439"></a>1x | <a id="p107440"></a>9x |  |  |  | <a id="p107441"></a>1x |  |
| <a id="p107442"></a>19 08 061 000 |  | <a id="p107443"></a>Вид идентификации | <a id="p107444"></a>1x | <a id="p107445"></a>1x |  |  |  | <a id="p107446"></a>1x |  |
| <a id="p107447"></a>19 08 017 000 |  | <a id="p107448"></a>Идентификационный номер | <a id="p107449"></a>1x | <a id="p107450"></a>1x |  |  |  | <a id="p107451"></a>1x |  |
| <a id="p107452"></a>19 08 062 000 |  | <a id="p107453"></a>Национальность | <a id="p107454"></a>1x | <a id="p107455"></a>1x |  |  |  | <a id="p107456"></a>1x |  |
| <a id="p107457"></a>19 08 067 000 |  | <a id="p107458"></a>Тип транспортного средства | <a id="p107459"></a>1x |  |  |  |  |  |  |
| <a id="p107460"></a>19 09 000 000 | <a id="p107461"></a>Пассивное транспортное средство, пересекающее границу |  |  | <a id="p107462"></a>999x |  | <a id="p107463"></a>999x | <a id="p107464"></a>999x |  |  |
| <a id="p107465"></a>19 09 061 000 |  | <a id="p107466"></a>Вид идентификации |  | <a id="p107467"></a>1x |  | <a id="p107468"></a>1x | <a id="p107469"></a>1x |  |  |
| <a id="p107470"></a>19 09 017 000 |  | <a id="p107471"></a>Идентификационный номер |  | <a id="p107472"></a>1x |  | <a id="p107473"></a>1x | <a id="p107474"></a>1x |  |  |
| <a id="p107475"></a>19 09 062 000 |  | <a id="p107476"></a>Национальность |  | <a id="p107477"></a>1x |  | <a id="p107478"></a>1x | <a id="p107479"></a>1x |  |  |
| <a id="p107480"></a>19 09 067 000 |  | <a id="p107481"></a>Тип транспортного средства |  | <a id="p107482"></a>1x |  | <a id="p107483"></a>1x | <a id="p107484"></a>1x |  |  |
| <a id="p107485"></a>19 10 000 000 | <a id="p107486"></a>Пломба |  |  | <a id="p107487"></a>99x | <a id="p107488"></a>99x | <a id="p107489"></a>99x | <a id="p107490"></a>99x |  |  |
| <a id="p107491"></a>19 10 068 000 |  | <a id="p107492"></a>Количество пломб |  | <a id="p107493"></a>1x [<*>](https://bukva.ai/docs/reglament-20152447/statya-350#p107544) | <a id="p107494"></a>1x [<*>](https://bukva.ai/docs/reglament-20152447/statya-350#p107544) | <a id="p107495"></a>1x [<*>](https://bukva.ai/docs/reglament-20152447/statya-350#p107544) | <a id="p107496"></a>1x [<*>](https://bukva.ai/docs/reglament-20152447/statya-350#p107544) |  |  |
| <a id="p107497"></a>19 10 015 000 |  | <a id="p107498"></a>Идентификатор |  | <a id="p107499"></a>1x | <a id="p107500"></a>1x | <a id="p107501"></a>1x | <a id="p107502"></a>1x |  |  |
| <a id="p107503"></a>19 11 000 000 | <a id="p107504"></a>Идентификационный номер хранилища |  |  | <a id="p107505"></a>9,999x | <a id="p107506"></a>9,999x |  |  |  |  |
| <a id="p107507"></a>99 01 000 000 | <a id="p107508"></a>Порядковый номер квоты |  |  |  |  |  |  |  | <a id="p107509"></a>1x |
| <a id="p107510"></a>99 02 000 000 | <a id="p107511"></a>Вид гарантии |  | <a id="p107512"></a>9x |  |  |  |  |  |  |
| <a id="p107513"></a>99 03 000 000 | <a id="p107514"></a>Ссылка на гарантию |  | <a id="p107515"></a>99x |  |  |  |  |  |  |
| <a id="p107516"></a>99 03 069 000 |  | <a id="p107517"></a>GRN | <a id="p107518"></a>1x |  |  |  |  |  |  |
| <a id="p107519"></a>99 03 070 000 |  | <a id="p107520"></a>Код доступа | <a id="p107521"></a>1x |  |  |  |  |  |  |
| <a id="p107522"></a>99 03 012 000 |  | <a id="p107523"></a>Валюта | <a id="p107524"></a>1x |  |  |  |  |  |  |
| <a id="p107525"></a>99 03 071 000 |  | <a id="p107526"></a>Покрываемая сумма | <a id="p107527"></a>1x |  |  |  |  |  |  |
| <a id="p107528"></a>99 03 072 000 |  | <a id="p107529"></a>Таможенное учреждение гарантии | <a id="p107530"></a>1x |  |  |  |  |  |  |
| <a id="p107531"></a>99 03 073 000 |  | <a id="p107532"></a>Ссылка на другие гарантии | <a id="p107533"></a>1x |  |  |  |  |  |  |
| <a id="p107534"></a>99 04 000 000 | <a id="p107535"></a>Гарантия не действует в |  | <a id="p107536"></a>99x |  |  |  |  |  |  |
| <a id="p107537"></a>99 05 000 000 | <a id="p107538"></a>Характер сделки |  |  |  |  |  |  | <a id="p107539"></a>1x | <a id="p107540"></a>1x |
| <a id="p107541"></a>99 06 000 000 | <a id="p107542"></a>Статистическое значение |  |  |  |  |  |  |  | <a id="p107543"></a>1x |
| <a id="p107544"></a><*> Количество элементов для количества пломб необходимо рассчитывать по отношению к транспортному оборудованию, т.е. 1x на контейнер. |  |  |  |  |  |  |  |  |  |


<a id="p107545"></a>**ТИТУЛ II. КОДЫ В ОТНОШЕНИИ ТРЕБОВАНИЙ**
**К ОБЩИМ ДАННЫМ ДЛЯ ДЕКЛАРАЦИЙ И УВЕДОМЛЕНИЙ**

<a id="p107546"></a>**(1) ВВЕДЕНИЕ**

<a id="p107547"></a>Настоящий Титул содержит коды, используемые в электронных декларациях и уведомлениях.

<a id="p107548"></a>**(2) КОДЫ**

<a id="p107549"></a>11 01 000 000 Вид декларации


| <a id="p107550"></a>Код | <a id="p107551"></a>Описание | <a id="p107552"></a>Комплект данных в таблице требований к данным в Титуле I Приложения B к Делегированному Регламенту (ЕС) 2015/2446 |
| --- | --- | --- |
| <a id="p107553"></a>C | <a id="p107554"></a>Товары Союза, не помещенные на процедуру транзита | <a id="p107555"></a>D3 |
| <a id="p107556"></a>CO | <a id="p107557"></a>Товары Союза, подлежащие применению специальных мер в переходный период после присоединения новых государств-членов ЕС.<br>Помещение товаров Союза на процедуру таможенного хранения, указанную в колонке B3 таблицы требований к данным в Титуле I Приложения B к Делегированному Регламенту (ЕС) 2015/2446 для получения платежа возмещения специального экспорта до экспорта или производства под таможенным надзором и под таможенным контролем до экспорта и выплаты экспортного возмущения.<br>Товары Союза в контексте торговли между частями таможенной территории Союза, к которым применяются положения [Директивы](https://bukva.ai/docs/direktiva-2006112es/statya-1) (ЕС) 2006/112/ЕС Совета ЕС [<*>](https://bukva.ai/docs/reglament-20152447/statya-350#p107599) или [Директивы](https://bukva.ai/docs/direktiva-2008118es/statya-1) 2008/118/ЕС Совета ЕС [<**>](https://bukva.ai/docs/reglament-20152447/statya-350#p107600), и частями указанной территории, к которой указанные положения не применяются, или в контексте торговли между частями указанной территории, где указанные положения не применяются, как указано в колонках B4 и H5 таблицы требований к данным в Титуле I Приложения B к Делегированному Регламенту (ЕС) 2015/2446. | <a id="p107558"></a>B3, B4, H1, H5, I1 |
| <a id="p107559"></a>EX | <a id="p107560"></a>Для торговли со странами и территориями, расположенными за пределами таможенной территории Союза.<br>Для помещения товаров на таможенную процедуру, указанную в колонках B1, B2 и C1, и для реэкспорта, указанного в колонке B1 таблицы требований к данным в Титуле I Приложения B к Делегированному Регламенту (ЕС) 2015/2446. | <a id="p107561"></a>B1, B2, C1 |
| <a id="p107562"></a>IM | <a id="p107563"></a>Для торговли со странами и территориями, расположенными за пределами таможенной территории Союза.<br>Для помещения товаров на таможенную процедуру, указанную в колонках H1 - H4, H6 и I1 Таблицы требований к данным в Титуле I Приложения B к Делегированному Регламенту (ЕС) 2015/2446.<br>Для помещения товаров не из Союза на таможенную процедуру в контексте торговли между государствами-членами ЕС. | <a id="p107564"></a>H1, H2, H3, H4, H5, H6, H7, I1 |
| <a id="p107565"></a>T | <a id="p107566"></a>Смешанные партии, состоящие из товаров, которые должны быть помещены на внешнюю процедуру транзита Союза, и товаров, которые должны быть помещены на внутреннюю процедуру транзита Союза, подпадающие под [Статью 294](https://bukva.ai/docs/reglament-20152447/statya-294#p102500) настоящего Регламента | <a id="p107567"></a>D1, D2, D3 |
| <a id="p107568"></a>T1 | <a id="p107569"></a>Товары, помещенные на внешнюю процедуру транзита Союза | <a id="p107570"></a>D1, D2, D3 |
| <a id="p107571"></a>T2 | <a id="p107572"></a>Товары, помещенные на внутреннюю процедуру транзита Союза в соответствии со [Статьей 227](https://bukva.ai/docs/reglament-9522013/statya-227#p101892) Кодекса, если не применяется [Статья 293(2)](https://bukva.ai/docs/reglament-20152447/statya-293#p102499) | <a id="p107573"></a>D1, D2, D3 |
| <a id="p107574"></a>T2F | <a id="p107575"></a>Товары, помещенные на внутреннюю процедуру транзита Союза в соответствии со Статьей 188 Делегированного Регламента (ЕС) 2015/2446 | <a id="p107576"></a>D1, D2, D3 |
| <a id="p107577"></a>T2L | <a id="p107578"></a>Доказательство, устанавливающее таможенный статус товаров Союза | <a id="p107579"></a>E1, E2 |
| <a id="p107580"></a>T2LF | <a id="p107581"></a>Доказательство, устанавливающее таможенный статус товаров Союза, отгруженных в специальные фискальные территории, из них или между ними | <a id="p107582"></a>E1, E2 |
| <a id="p107583"></a>T2LSM | <a id="p107584"></a>Доказательство, устанавливающее таможенный статус товаров, направленных для Сан-Марино при применении Статьи 2 Решения 4/92 Комитета сотрудничества ЕЭС-Сан-Марино от 22 декабря 1992 г. | <a id="p107585"></a>E1 |
| <a id="p107586"></a>T2SM | <a id="p107587"></a>Товары, помещенные на внутреннюю процедуру транзита при применении Статьи 2 Решения 4/92 Комитета сотрудничества ЕЭС-Сан-Марино от 22 декабря 1992 г. | <a id="p107588"></a>D1, D2 |
| <a id="p107589"></a>TD | <a id="p107590"></a>Товары, уже помещенные на процедуру транзита или перевозимые на внутреннюю переработку, таможенное хранение или временную процедуру допуска в контексте применения [Статьи 233(4)](https://bukva.ai/docs/reglament-9522013/statya-1#p101930) Кодекса | <a id="p107591"></a>D3 |
| <a id="p107592"></a>TIR | <a id="p107593"></a>Товары, помещенные на процедуру TIR (Transport Internationaux Routiers) | <a id="p107594"></a>D1, D2 |
| <a id="p107595"></a>X | <a id="p107596"></a>Товары Союза, экспортируемые, не помещенные на процедуру Союза в контексте применения [Статьи 233(4)(e)](https://bukva.ai/docs/reglament-9522013/statya-1#p101935) Кодекса | <a id="p107597"></a>D3 |


<a id="p107598"></a>

---

<a id="p107599"></a><*> [Директива](https://bukva.ai/docs/direktiva-2006112es/statya-1) 2006/112/ЕС Совета ЕС от 28 ноября 2006 г. об общей системе налога на добавленную стоимость (ОЖ N L 347, 11.12.2006, стр. 1).
<a id="p107600"></a><**> [Директива](https://bukva.ai/docs/direktiva-2008118es/statya-1) 2008/118/ЕС Совета ЕС от 16 декабря 2008 г. об общих условиях взимания акцизов и об отмене Директивы 92/12/ЕЭС (ОЖ N L 9, 14.1.2009, стр. 12).

<a id="p107601"></a>11 02 000 000 Вид дополнительной декларации
<a id="p107602"></a>A - для стандартной таможенной декларации (согласно [Статье 162](https://bukva.ai/docs/reglament-9522013/statya-162#p101455) Кодекса);
<a id="p107603"></a>B - для упрощенной декларации на случайной основе (согласно [Статье 166(1)](https://bukva.ai/docs/reglament-9522013/statya-1#p101475) Кодекса);
<a id="p107604"></a>C - для упрощенной таможенной декларации, используемой регулярно (согласно [Статье 166(2)](https://bukva.ai/docs/reglament-9522013/statya-1#p101476) Кодекса);
<a id="p107605"></a>D - для подачи стандартной таможенной декларации (той, которая указана под [кодом A](https://bukva.ai/docs/reglament-20152447/statya-350#p107602)) в соответствии со [Статьей 171](https://bukva.ai/docs/reglament-9522013/statya-171#p101515) Кодекса;
<a id="p107606"></a>E - для подачи упрощенной декларации (той, которая указана под [кодом B](https://bukva.ai/docs/reglament-20152447/statya-350#p107603)) в соответствии со [Статьей 171](https://bukva.ai/docs/reglament-9522013/statya-171#p101515) Кодекса;
<a id="p107607"></a>F - для подачи упрощенной декларации (той, которая указана под [кодом C](https://bukva.ai/docs/reglament-20152447/statya-350#p107604)) в соответствии со [Статьей 171](https://bukva.ai/docs/reglament-9522013/statya-171#p101515) Кодекса;
<a id="p107608"></a>R - ретроспективная подача экспортной или реэкспортной декларации в соответствии со Статьей 249 Делегированного Регламента (ЕС) 2015/2446 и [Статьей 337](https://bukva.ai/docs/reglament-20152447/statya-337#p102903) Имплементационного Регламента (ЕС) 2015/2447
<a id="p107609"></a>X - для дополнительной декларации упрощенных деклараций, на которую распространяются [коды B](https://bukva.ai/docs/reglament-20152447/statya-350#p107603) и [E](https://bukva.ai/docs/reglament-20152447/statya-350#p107606);
<a id="p107610"></a>Y - для дополнительной декларации общего или периодического характера упрощенных деклараций, на которую распространяются [коды C](https://bukva.ai/docs/reglament-20152447/statya-350#p107604) и [F](https://bukva.ai/docs/reglament-20152447/statya-350#p107607);
<a id="p107611"></a>Z - для дополнительной декларации общего или периодического характера по процедуре, на которую распространяется [Статья 182](https://bukva.ai/docs/reglament-9522013/statya-182#p101580) Кодекса;
<a id="p107612"></a>U - для дополнительной краткой декларации упрощенных деклараций, на которую распространяются [коды C](https://bukva.ai/docs/reglament-20152447/statya-350#p107604) и [F](https://bukva.ai/docs/reglament-20152447/statya-350#p107607);
<a id="p107613"></a>V - для дополнительной краткой декларации по процедуре, подпадающей под действие [Статьи 182](https://bukva.ai/docs/reglament-9522013/statya-182#p101580) Кодекса.

<a id="p107614"></a>11 04 000 000 Показатель специального обстоятельства
<a id="p107615"></a>Используются следующие коды:


| <a id="p107616"></a>Код | <a id="p107617"></a>Описание [<*>](https://bukva.ai/docs/reglament-20152447/statya-350#p107683) |
| --- | --- |
| <a id="p107618"></a>A20 | <a id="p107619"></a>Сводная вывозная декларация - Экспресс-грузы |
| <a id="p107620"></a>F10 | <a id="p107621"></a>Морские и внутренние водные пути - Полный комплект данных - Именной коносамент, содержащий необходимую информацию от грузополучателя |
| <a id="p107622"></a>F11 | <a id="p107623"></a>Морские и внутренние водные пути - Полный комплект данных - Главный коносамент с базовым(и) внутренним(ими) коносаментом(ами), содержащий необходимую информацию от грузополучателя на уровне самого низкого внутреннего коносамента |
| <a id="p107624"></a>F12 | <a id="p107625"></a>Морские и внутренние водные пути - Частичный комплект данных - Только главный коносамент |
| <a id="p107626"></a>F13 | <a id="p107627"></a>Морские и внутренние водные пути - Частичный комплект данных - Только именной коносамент |
| <a id="p107628"></a>F14 | <a id="p107629"></a>Морские и внутренние водные пути - Частичный комплект данных - Только внутренний коносамент |
| <a id="p107630"></a>F15 | <a id="p107631"></a>Морские и внутренние водные пути - Частичный комплект данных - внутренний коносамент с необходимой информацией от грузополучателя |
| <a id="p107632"></a>F16 | <a id="p107633"></a>Морские и внутренние водные пути - Частичный комплект данных - Необходимая информация, требуемая для предоставления грузополучателем на самом низком уровне транспортного договора (самый низкий внутренний коносамент, где главный коносамент не является именным коносаментом) |
| <a id="p107634"></a>F20 | <a id="p107635"></a>Воздушный груз (общий) - Полный комплект данных, поданный до погрузки |
| <a id="p107636"></a>F21 | <a id="p107637"></a>Воздушный груз (общий) - Частичный комплект данных - Главная авианакладная, поданная до прибытия |
| <a id="p107638"></a>F22 | <a id="p107639"></a>Воздушный груз (общий) - Частичный комплект данных - Внутренняя авианакладная, поданная до прибытия - Частичный комплект данных, представленный лицом согласно [Статье 127(6)](https://bukva.ai/docs/reglament-9522013/statya-1#p101223) Кодекса и в соответствии со Статьей 113(1) Делегированного Регламента (ЕС) 2015/2446 |
| <a id="p107640"></a>F23 | <a id="p107641"></a>Воздушный груз (общий) - Частичный комплект данных - Минимальный комплект данных, поданный до погрузки в соответствии со Статьей 106(1), вторым подпараграфом Делегированного Регламента (ЕС) 2015/2446 без исходящего номера главной авианакладной |
| <a id="p107642"></a>F24 | <a id="p107643"></a>Воздушный груз (общий) - Частичный комплект данных - Минимальный комплект данных, поданный до погрузки в соответствии со Статьей 106(1), вторым подпараграфом Делегированного Регламента (ЕС) 2015/2446 с исходящим номером главной авианакладной |
| <a id="p107644"></a>F25 | <a id="p107645"></a>Воздушный груз (общий) - Частичный комплект данных - Исходящий номер главной авианакладной, поданной до погрузки в соответствии со Статьей 106(1), вторым подпараграфом Делегированного Регламента (ЕС) 2015/2446 |
| <a id="p107646"></a>F26 | <a id="p107647"></a>Воздушный груз (общий) - Частичный комплект данных - Минимальный комплект данных, поданный до погрузки в соответствии со Статьей 106(1), вторым подпараграфом Делегированного Регламента (ЕС) 2015/2446, и содержащий дополнительную информацию внутренней авианакладной |
| <a id="p107648"></a>F27 | <a id="p107649"></a>Воздушный груз (общий) - Полный комплект данных, поданный до прибытия |
| <a id="p107650"></a>F28 | <a id="p107651"></a>Воздушный груз (общий) - Полный комплект данных, поданный до погрузки - Прямая авианакладная |
| <a id="p107652"></a>F29 | <a id="p107653"></a>Воздушный груз (общий) - Полный комплект данных, поданный до прибытия - Прямая авианакладная |
| <a id="p107654"></a>F30 | <a id="p107655"></a>Экспресс-грузы - Полный комплект данных, поданный до прибытия |
| <a id="p107656"></a>F31 | <a id="p107657"></a>Экспресс-грузы при общих воздушных перевозках - Полный комплект данных, поданных до прибытия оператором экспресс доставки |
| <a id="p107658"></a>F32 | <a id="p107659"></a>Сводная ввозная декларация - Экспресс-грузы - Минимальный комплект данных, поданный до погрузки в отношении ситуаций, определенных в Статье 106(1), втором подпараграфе |
| <a id="p107660"></a>F33 | <a id="p107661"></a>Экспресс-грузы при общих воздушных перевозках - Частичный комплект данных - Внутренняя авианакладная, поданная до прибытия - Частичный комплект данных, представленный лицом согласно [Статье 127(6)](https://bukva.ai/docs/reglament-9522013/statya-1#p101223) Кодекса и в соответствии со Статьей 113(1) Делегированного Регламента (ЕС) 2015/2446 |
| <a id="p107662"></a>F40 | <a id="p107663"></a>Почтовые грузы - Частичный комплект данных - Информация главного дорожного транспортного документа |
| <a id="p107664"></a>F41 | <a id="p107665"></a>Почтовые грузы - Частичный комплект данных - Информация главного железнодорожного транспортного документа |
| <a id="p107666"></a>F42 | <a id="p107667"></a>Почтовые грузы - Частичный комплект данных - Главная авианакладная, содержащая необходимую информацию почтового воздушного коносамента, поданного в соответствии со сроком, применяемым для данного вида транспортных средств |
| <a id="p107668"></a>F43 | <a id="p107669"></a>Почтовые грузы - Частичный комплект данных - Минимальный комплект данных, поданный до погрузки в соответствии со Статьей 106(1), вторым подпараграфом и в соответствии со Статьей 113(2) Делегированного Регламента (ЕС) 2015/2446 |
| <a id="p107670"></a>F44 | <a id="p107671"></a>Почтовые грузы - Частичный комплект данных - Идентификационный номер емкости, поданный до погрузки в соответствии со Статьей 106(1), вторым подпараграфом и в соответствии со Статьей 113(2) Делегированного Регламента (ЕС) 2015/24461 |
| <a id="p107672"></a>F45 | <a id="p107673"></a>Почтовые грузы - Частичный комплект данных - Только главная накладная |
| <a id="p107674"></a>F50 | <a id="p107675"></a>Вид дорожного транспорта |
| <a id="p107676"></a>F51 | <a id="p107677"></a>Вид железнодорожного транспорта |
| <a id="p107678"></a>G4 | <a id="p107679"></a>Декларация временного хранения |
| <a id="p107680"></a>G5 | <a id="p107681"></a>Уведомление о прибытии в случае перемещения товаров на временном хранении |


<a id="p107682"></a>

---

<a id="p107683"></a><*> Из таблицы удален третий столбец - прим. ред.

<a id="p107684"></a>11 05 000 000 Показатель повторного ввоза
<a id="p107685"></a>Соответствующие коды даны ниже:
<a id="p107686"></a>0 - Нет (Сводная ввозная декларация, поданная для товаров, которые ввозятся на таможенную территорию Союза в первый раз)
<a id="p107687"></a>1 - Да (Сводная ввозная декларация, поданная для товаров, которые повторно ввозятся на таможенную территорию Союза после того, как они были вывезены)

<a id="p107688"></a>11 06 001 000 Показатель разделенного груза
<a id="p107689"></a>Соответствующие коды даны ниже:
<a id="p107690"></a>0 - Нет (Сводная ввозная декларация, поданная для полной главной накладной)
<a id="p107691"></a>1 - Да (Сводная ввозная декларация, поданная для разделенной главной накладной)

<a id="p107692"></a>11 07 000 000 Безопасность
<a id="p107693"></a>Соответствующие коды даны ниже:


| <a id="p107694"></a>Код | <a id="p107695"></a>Описание | <a id="p107696"></a>Разъяснение |
| --- | --- | --- |
| <a id="p107697"></a>0 | <a id="p107698"></a>No | <a id="p107699"></a>Декларация не объединена со сводной вывозной декларацией или сводной ввозной декларацией |
| <a id="p107700"></a>1 | <a id="p107701"></a>ENS | <a id="p107702"></a>Декларация объединена со сводной ввозной декларацией |
| <a id="p107703"></a>2 | <a id="p107704"></a>EXS | <a id="p107705"></a>Декларация объединена со сводной вывозной декларацией |
| <a id="p107706"></a>3 | <a id="p107707"></a>ENS и EXS | <a id="p107708"></a>Декларация объединена со сводной вывозной декларацией или сводной ввозной декларацией |


<a id="p107709"></a>11 08 000 000 Показатель сокращенного комплекта данных
<a id="p107710"></a>Соответствующие коды даны ниже:
<a id="p107711"></a>0 - Нет (Товары не декларируются с использованием сокращенного комплекта данных)
<a id="p107712"></a>1 - Да (Товары декларируются с использованием сокращенного комплекта данных)

<a id="p107713"></a>11 09 000 000 Процедура
<a id="p107714"></a>Коды, вносимые в данный подраздел, являются четырехзначными, состоящими из двузначного кода, представляющего запрашиваемую процедуру, после которого следует второй двухзначный код, представляющий предыдущую процедуру. Список двузначных кодов дан ниже.
<a id="p107715"></a>"Предыдущая процедура" - процедура, на которую товары были помещены до помещения на запрашиваемую процедуру.
<a id="p107716"></a>Необходимо отметить, что если предыдущей процедурой является таможенное хранение или временный допуск, или если товары пришли из свободной зоны, то соответствующий код должен использоваться, только если товары не были помещены на внутреннюю или внешнюю переработку или конечное использование.
<a id="p107717"></a>Например: реэкспорт товаров, импортированных согласно внутренней переработке и впоследствии помещенных на таможенное хранение = 3151 (не 3171). (Первая операция = 5100; вторая операция = 7151: третья операция реэкспорта = 3151).
<a id="p107718"></a>Таким же образом, если товары, ранее временно экспортированные, реимпортируются и выпускаются в свободное обращение после того, как они были помещены на таможенное хранение, временный допуск или в свободную зону, то это считается простым реимпортом после временного экспорта.
<a id="p107719"></a>Например: ввоз для внутреннего использования с одновременным ввозом для свободного обращения товаров, экспортированных по внешней переработке и помещенных на таможенное хранение при реимпорте = 6121 (не 6171). (Первая операция: временный экспорт по внешней переработке = 2100; вторая операция: хранение на таможенном складе = 7121; третья операция: ввоз для внутреннего использования + ввоз для свободного обращения = 6121).
<a id="p107720"></a>Коды, указанные в [списке](https://bukva.ai/docs/reglament-20152447/statya-350#p107722) ниже с буквой (a), не могут использоваться в качестве первых двух знаков кода процедуры, а только указывают на предыдущую процедуру.
<a id="p107721"></a>Например: 4054 = ввоз для свободного обращения и внутреннего использования товаров, ранее помещенных на внутреннюю переработку в другом государстве-члене ЕС.

<a id="p107722"></a>Список процедур для целей кодирования
<a id="p107723"></a>Два из этих основных элементов должны быть объединены для получения четырехзначного кода.
<a id="p107724"></a>00 - Данный код используется для того, чтобы показать, что не было предыдущей процедуры (a);
<a id="p107725"></a>01 - Выпуск в свободное обращение товаров, одновременно перенаправленных в контексте торговли между частями таможенной территории Союза, в которых применяются положения [Директивы](https://bukva.ai/docs/direktiva-2006112es/statya-1) 2006/11/ЕС или [Директивы](https://bukva.ai/docs/direktiva-2008118es/statya-1) 2008/118/ЕС, и частями указанной территории, в которых данные положения не применяются, или в контексте торговли между частями указанной территории, где данные положения не применяются.
<a id="p107726"></a>Пример: Товары не из Союза, прибывающие из третьей страны, выпущенные в свободное обращение в Германии и направленные на Канарские острова.
<a id="p107727"></a>07 - Выпуск товаров для свободного обращения, одновременно помещенных на другую процедуру хранения, кроме процедуры таможенного хранения, если ни НДС, ни (если применимо) акцизные сборы не были выплачены.
<a id="p107728"></a>Разъяснение: Данный код должен использоваться, если товары выпускаются в свободное обращение, но если НДС и акцизные сборы не были выплачены.
<a id="p107729"></a>Примеры: Импортированный сахар-сырец выпускается в свободное обращение, но НДС не был выплачен. Если товары помещены на склад или в утвержденное место, кроме таможенного склада, то выплата НДС приостанавливается.
<a id="p107730"></a>Импортированные минеральные масла выпускаются в свободное обращение, и НДС не был выплачен. Если товары хранятся на налоговом складе, выплата НДС и акцизных сборов приостанавливается.
<a id="p107731"></a>10 - Постоянный экспорт
<a id="p107732"></a>Пример: Экспорт товаров Союза в третью страну, а также отправление товаров Союза в те части таможенной территории Союза, к которым не применяются положения [Директивы](https://bukva.ai/docs/direktiva-2006112es/statya-1) 2006/112/ЕС или [Директивы](https://bukva.ai/docs/direktiva-2008118es/statya-1) 2008/118/ЕС Совета ЕС.
<a id="p107733"></a>11 - Экспорт переработанной продукции, полученной из эквивалентных товаров по внутренней переработке до помещения товаров не из Союза на внутреннюю переработку.
<a id="p107734"></a>Разъяснение: Предварительный экспорт (EX-IM) в соответствии со [Статьей 223(2) c)](https://bukva.ai/docs/reglament-9522013/statya-1#p101854) Кодекса.
<a id="p107735"></a>Пример: Экспорт сигарет, произведенных из листьев табака Союза, до помещения листьев табака не из Союза на внутреннюю переработку.
<a id="p107736"></a>21 - Временный экспорт по процедуре внешней переработки, если на процедуру не распространяется [код 22](https://bukva.ai/docs/reglament-20152447/statya-350#p107738).
<a id="p107737"></a>Пример: Процедура внешней переработки согласно [Статьям 259](https://bukva.ai/docs/reglament-9522013/statya-259#p102110) - [262](https://bukva.ai/docs/reglament-9522013/statya-262#p102131) Кодекса. На одновременное применение к текстильной продукции процедуры внешней переработки и процедуры экономической внешней переработки (Регламент (ЕС) 3036/94 Совета ЕС) данный код не распространяется.
<a id="p107738"></a>22 - Временный экспорт, кроме того, который указан в [кодах 21](https://bukva.ai/docs/reglament-20152447/statya-350#p107736) и [23](https://bukva.ai/docs/reglament-20152447/statya-350#p107744).
<a id="p107739"></a>Данный код распространяется на следующие ситуации:
- <a id="p107740"></a>Одновременное применение к текстильной продукции процедуры внешней переработки и процедуры экономической внешней переработки (Регламент (ЕС) 3036/94 <*>);

<a id="p107741"></a>

---

<a id="p107742"></a><*> Регламент (ЕС) 3036/94 Совета ЕС от 8 декабря 1994 г. об установлении соглашений об экономической внешней переработке, применяемых к отдельной текстильной продукции и одежде, реимпортированной в Сообщество после обработки или переработки в определенных третьих странах (ОЖ N L 322, 15.12.1994, стр. 1).

- <a id="p107743"></a>Временный экспорт товаров из Союза для ремонта, переработки, адаптации, сборки или обработки, если при реимпорте не взимаются никакие таможенные пошлины.
<a id="p107744"></a>23 - Временный экспорт для возврата в неизмененном состоянии.
<a id="p107745"></a>Пример: Временный экспорт на выставки изделий, таких как образцы, профессиональное оборудование и т.п.
<a id="p107746"></a>31 - Реэкспорт
<a id="p107747"></a>Разъяснение: Реэкспорт товаров не из Союза после специальной процедуры.
<a id="p107748"></a>Пример: Товары помещаются на таможенное хранение и впоследствии декларируются на реэкспорт.
<a id="p107749"></a>40 - Одновременный выпуск в свободное обращение и внутреннее использование товаров.
<a id="p107750"></a>Ввоз для внутреннего использования товаров в контексте торговли между Союзом и странами, с которыми он образует таможенный союз.
<a id="p107751"></a>Ввоз для внутреннего использования товаров в контексте торговли, указанной в [Статье 1(3)](https://bukva.ai/docs/reglament-9522013/statya-1#p100107) Кодекса.
<a id="p107752"></a>Примеры:
- <a id="p107753"></a>Товары, прибывающие из Японии с оплатой таможенной пошлины, НДС и, если применяются, акцизных сборов.
- <a id="p107754"></a>Товары, прибывающие из Андорры и ввозимые для внутреннего использования в Германии.
- <a id="p107755"></a>Товары, прибывающие из Мартиники и ввозимые для внутреннего использования в Бельгии.
<a id="p107756"></a>42 - Одновременный выпуск в свободное обращение и внутреннее использование товаров, которые подлежат освобождению от НДС при поставке в другое государство-член ЕС и, если применяется, приостановке акцизных сборов.
<a id="p107757"></a>Ввоз для внутреннего использования товаров Союза в контексте торговли между частями таможенной территории Союза, в которых положения [Директивы](https://bukva.ai/docs/direktiva-2006112es/statya-1) 2006/112/ЕС и [Директивы](https://bukva.ai/docs/direktiva-2008118es/statya-1) 2008/118/ЕС не применяются, и частями указанной территории, в которых эти положения применяются, которые подлежат освобождению от НДС при поставке в другое государство-член ЕС и, если применяется, приостановке акцизного сбора.
<a id="p107758"></a>Разъяснение: Освобождение от оплаты НДС и, если применяется, приостановка акцизного сбора предоставляются в связи с тем, что после импорта следует поставка внутри Союза или передача товаров в другое государство-член ЕС. В этом случае НДС и, если применяется, акцизная пошлина должны быть оплачены в государстве-члене ЕС окончательного места назначения. Для использования данной процедуры лица должны выполнить и другие условия, указанные в [Статье 143(2)](https://bukva.ai/docs/direktiva-2006112es/statya-1#p100881) Директивы 2006/112/ЕС и, если это применимо, условия, указанные в [Статье 17(1)(b)](https://bukva.ai/docs/direktiva-2008118es/statya-17#p100219) Директивы 2008/118/ЕС. Информация, требуемая согласно [Статье 143(2)](https://bukva.ai/docs/direktiva-2006112es/statya-1#p100881) Директивы 2006/112/ЕС, вносится в D.E. [13 16 034 000](https://bukva.ai/docs/reglament-20152447/statya-350#p108510) Идентификационный номер плательщика НДС.
<a id="p107759"></a>Примеры: Товары не из Союза выпускаются в свободное обращение в одном государстве-члене ЕС и подлежат освобождению от НДС при поставке в другое государство-член ЕС. Оформление НДС выполняется таможенным агентом, который является налоговым представителем, с использованием внутрисоюзной системы НДС.
<a id="p107760"></a>Товары не из Союза, в отношении которых взымаются акцизные сборы, импортированные из третьей страны, которые выпускаются в свободное обращение и подлежат освобождению от НДС при поставке в другое государство-член ЕС. Выпуск в свободное обращение немедленно сопровождается перемещением под режимом приостановки акцизного сбора из места импорта, инициированным зарегистрированным грузоотправителем в соответствии со [Статьей 17(1)(b)](https://bukva.ai/docs/direktiva-2008118es/statya-17#p100219) Директивы 2008/118/ЕС.
<a id="p107761"></a>43 - Одновременный выпуск в свободное обращение и внутреннее использование товаров, подлежащих применению специальных мер, связанных со сбором суммы в переходный период после присоединения государств-членов ЕС.
<a id="p107762"></a>Пример: Выпуск в свободное обращение сельскохозяйственной продукции, подлежащей в течение специального переходного периода после присоединения новых государств-членов ЕС специальной таможенной процедуре или специальным мерам между новыми государствами-членами ЕС и остальным Союзом.
<a id="p107763"></a>44 - Конечное использование
<a id="p107764"></a>Выпуск в свободное обращение и внутреннее использование при освобождении от пошлины или по сниженной ставке пошлины в случае специального использования.
<a id="p107765"></a>Пример: Выпуск в свободное обращение двигателей не из Союза для использования в создании судов гражданской авиации в Европейском Союзе.
<a id="p107766"></a>Товары не из Союза для использования в отдельных категориях кораблей, лодок и других судов и для буровых или производственных платформ.
<a id="p107767"></a>45 - Выпуск товаров в свободное обращение и частичный ввоз для внутреннего использования для либо НДС, либо акцизных сборов, и их частичное помещение на другой склад, кроме таможенного склада.
<a id="p107768"></a>Разъяснение: Данный код должен использоваться для товаров, которые облагаются и НДС, и акцизными сборами, и если только одна из этих категории налогов оплачивается, когда товары выпущены в свободное обращение.
<a id="p107769"></a>Примеры: Сигареты не из Союза выпускаются в свободное обращение, и НДС был оплачен. Если товары находятся на налоговом складе, то оплата акцизных сборов приостановлена.
<a id="p107770"></a>Акцизные товары, импортированные из третьей страны или из третьей территории, указанной в [Статье 5(3)](https://bukva.ai/docs/direktiva-2008118es/statya-5#p100109) Директивы 2008/118/ЕС, выпускаются в свободное обращение. За выпуском в свободное обращение сразу же следует перемещение согласно приостановке акцизных сборов, инициированной зарегистрированным грузоотправителем в месте импорта в соответствии со [Статьей 17(1)(b)](https://bukva.ai/docs/direktiva-2008118es/statya-17#p100219) Директивы 2008/118/ЕС, на налоговой склад в том же государстве-члене ЕС.
<a id="p107771"></a>46 - Импорт переработанной продукции, полученной из эквивалентных товаров в процедуре внешней переработки перед экспортом товаров, которые они замещают.
<a id="p107772"></a>Разъяснение: Предварительный импорт в соответствии со [Статьей 223(2)d)](https://bukva.ai/docs/reglament-9522013/statya-1#p101855) Кодекса.
<a id="p107773"></a>Пример: Импорт столов, произведенных из леса не из Союза до помещения леса Союза на внешнюю переработку.
<a id="p107774"></a>48 - Ввоз для внутреннего использования с одновременным выпуском в свободное обращение заменяющей продукции, находящейся на внешней переработке до экспорта дефектных товаров.
<a id="p107775"></a>Разъяснение: Система стандартного обмена (IM-EX), предварительный импорт в соответствии со [Статьей 262(1)](https://bukva.ai/docs/reglament-9522013/statya-1#p102133) Кодекса.
<a id="p107776"></a>51 - Помещение товаров на процедуру внутренней переработки
<a id="p107777"></a>Разъяснение: Внутренняя переработка в соответствии со [Статьей 256](https://bukva.ai/docs/reglament-9522013/statya-256#p102086) Кодекса.
<a id="p107778"></a>53 - Помещение товаров на временный допуск.
<a id="p107779"></a>Разъяснение: Помещение товаров не из Союза, предназначенных для реэкспорта на процедуру временного допуска.
<a id="p107780"></a>Может использоваться на таможенной территории Союза с общим или частичным освобождением от импортных пошлин в соответствии со [Статьей 250](https://bukva.ai/docs/reglament-9522013/statya-250#p102039) Кодекса.
<a id="p107781"></a>Пример: Временный допуск, например, для выставки.
<a id="p107782"></a>54 - Внутренняя переработка в другом государстве-члене ЕС (без выпуска их в свободное обращение в указанном государстве-члене ЕС) (a).
<a id="p107783"></a>Разъяснение: Данный код используется для записи операции в целях статистики по торговле внутри Союза.
<a id="p107784"></a>Пример: Товары не из Союза помещаются на внутреннюю переработку в Бельгии (5100). После прохождения внутренней переработки они направляются в Германию для выпуска в свободное обращение (4054) или на дальнейшую переработку (5154).
<a id="p107785"></a>61 - Реимпорт с одновременным выпуском в свободное обращение и внутреннее использование товаров.
<a id="p107786"></a>Разъяснение: Товары, реимпортированные из третьей страны с оплатой таможенных пошлин и НДС.
<a id="p107787"></a>63 - Реимпорт с одновременным выпуском в свободное обращение и внутреннее использование товаров, которые подлежат освобождению от НДС при поставке в другое государство-член ЕС и, если применяется, приостановке акцизного сбора.
<a id="p107788"></a>Разъяснение: Освобождение от оплаты НДС и, если применяется, приостановка акцизного сбора предоставляются, так как за реимпортом следует поставка внутри Союза или передача товаров другому государству-члену ЕС. В таком случае НДС и, если применяется, акцизный сбор будут оплачены в государстве-члене ЕС окончательного места назначения. Для использования данной процедуры лицо должно выполнять другие условия, указанные в [Статье 143(2)](https://bukva.ai/docs/direktiva-2006112es/statya-1#p100881) Директивы 2006/112/ЕС и, если это применимо, условия, указанные в [Статье 17(1)(b)](https://bukva.ai/docs/direktiva-2008118es/statya-17#p100219) Директивы 2008/118/ЕС. Информация, требуемая в соответствии со [Статьей 143(2)](https://bukva.ai/docs/direktiva-2006112es/statya-1#p100881) Директивы 2006/112/ЕС, вносится в D.E. [13 16 034 000](https://bukva.ai/docs/reglament-20152447/statya-350#p108510) Идентификационный номер плательщика НДС.
<a id="p107789"></a>Примеры: Реимпорт после внешней переработки или временного экспорта, все долги по НДС взимаются с налогового представителя.
<a id="p107790"></a>Акцизные товары, реимпортированные после внешней переработки и выпущенные в свободное обращение, которые подлежат освобождению от НДС при поставке в другое государство-член ЕС. За выпуском в свободное обращение сразу же следует перемещение согласно приостановке акцизного сбора из места реимпорта, инициированное зарегистрированным грузоотправителем в соответствии со [Статьей 17(1)(b)](https://bukva.ai/docs/direktiva-2008118es/statya-17#p100219) Директивы 2008/118/ЕС.
<a id="p107791"></a>68 - Реимпорт с частичным вводом для внутреннего использования и одновременный выпуск в свободное обращение и помещение товаров на другую процедуру хранения, кроме процедуры таможенного хранения.
<a id="p107792"></a>Разъяснение: Данный код должен использоваться для товаров, которые облагаются и НДС, и акцизными сборами, и если только одна из этих категорий налогов оплачивается, когда товары выпускаются в свободное обращение.
<a id="p107793"></a>Пример: Переработанные спиртные напитки реимпортируются и помещаются на налоговый склад.
<a id="p107794"></a>71 - Помещение товаров на процедуру таможенного хранения.
<a id="p107795"></a>76 - Помещение товаров Союза на процедуру таможенного хранения в соответствии со [Статьей 237(2)](https://bukva.ai/docs/reglament-9522013/statya-1#p101961) Кодекса.
<a id="p107796"></a>Пример: Обваленное мясо крупного рогатого скота, помещенное на таможенное хранение до экспорта (Статья 4 Регламента (ЕС) 1741/2006 Европейской Комиссии от 24 ноября 2006 г. об установлении условий для выдачи специального экспортного возмещения на обваленное мясо крупного рогатого скота, помещенного на процедуру таможенного хранения до экспорта (ОЖ N L 329, 25.11.2006, стр. 7)).
<a id="p107797"></a>После выпуска в свободное обращение, заявление на возмещение импортной пошлины или освобождение от нее, основанное на товарах, дефектных или не соответствующих условиям договора ([Статья 118](https://bukva.ai/docs/reglament-9522013/statya-118#p101126) Кодекса).
<a id="p107798"></a>В соответствии со [Статьей 118(4)](https://bukva.ai/docs/reglament-9522013/statya-1#p101135) Кодекса указанные товары могут быть помещены на процедуру таможенного хранения вместо вывоза с таможенной территории Союза для предоставления возмещения или освобождения.
<a id="p107799"></a>77 - Производство товаров Союза под таможенным надзором таможенных органов и под таможенным контролем (в значении [Статья 5(27)](https://bukva.ai/docs/reglament-9522013/statya-1#p100196) и [(3)](https://bukva.ai/docs/reglament-9522013/statya-1#p100163) Кодекса) до экспорта и выплаты экспортного возмещения.
<a id="p107800"></a>Пример: Консервированная продукция из говядины и телятины, произведенная под надзором таможенных органов и под таможенным контролем до экспорта (Статьи 2 и 3 Регламента (ЕС) 1731/2006 Европейской Комиссии от 23 ноября 2006 г. о специальных подробных правилах для применения экспортного возмещения за консервированную продукцию из говядины и телятины (ОЖ N L 325, 24.11.2006, стр. 12)).
<a id="p107801"></a>78 - Помещение товаров в свободную зону. (a)
<a id="p107802"></a>95 - Помещение товаров Союза на другую процедуру хранения, кроме процедуры таможенного хранения, если не были оплачены ни НДС, ни (если это применимо) акцизные сборetrospettivamenы.
<a id="p107803"></a>Разъяснение: Данный код должен использоваться в контексте торговли, указанной в [Статье 1(3)](https://bukva.ai/docs/reglament-9522013/statya-1#p100107) Кодекса, а также торговли между Союзом и странами, с которыми он образовал таможенный союз, и если не были оплачены ни НДС, ни акцизные сборы.
<a id="p107804"></a>Пример: Сигареты с Канарских островов привезены в Бельгию и хранятся на налоговом складе; выплата НДС и акцизных сборов приостановлена.
<a id="p107805"></a>96 - Помещение товаров Союза на другую процедуру хранения, кроме процедуры таможенного хранения, если либо НДС, либо, если применяется, акцизные сборы были оплачены, а оплата другого налога приостановлена.
<a id="p107806"></a>Разъяснение: Данный код должен использоваться в контексте торговли, указанной в [Статье 1(3)](https://bukva.ai/docs/reglament-9522013/statya-1#p100107) Кодекса, а также торговли между Союзом и странами, с которыми он образовал таможенный союз, и если либо НДС, либо акцизные сборы были оплачены, а выплата другого налога приостановлена.
<a id="p107807"></a>Пример: Сигареты с Канарских островов привезены во Францию и хранятся на налоговом складе; НДС был оплачен, а выплата акцизных сборов приостановлена.

<a id="p107808"></a>Коды процедуры в контексте таможенных деклараций


| <a id="p107809"></a>Колонки (Заголовок таблицы в Приложении B к Делегированному Регламенту (ЕС) 2015/2446 | <a id="p107810"></a>Декларации | <a id="p107811"></a>Коды процедуры Союза, для соответствующих случаев |
| --- | --- | --- |
| <a id="p107812"></a>B1 | <a id="p107813"></a>Экспортная декларация и реэкспортная декларация | <a id="p107814"></a>[10](https://bukva.ai/docs/reglament-20152447/statya-350#p107731), [11](https://bukva.ai/docs/reglament-20152447/statya-350#p107733), [23](https://bukva.ai/docs/reglament-20152447/statya-350#p107744), [31](https://bukva.ai/docs/reglament-20152447/statya-350#p107746) |
| <a id="p107815"></a>B2 | <a id="p107816"></a>Специальная процедура - переработка - декларация внешней переработки | <a id="p107817"></a>[21](https://bukva.ai/docs/reglament-20152447/statya-350#p107736), [22](https://bukva.ai/docs/reglament-20152447/statya-350#p107738) |
| <a id="p107818"></a>B3 | <a id="p107819"></a>Декларация таможенного хранения товаров Союза | <a id="p107820"></a>[76](https://bukva.ai/docs/reglament-20152447/statya-350#p107795), [77](https://bukva.ai/docs/reglament-20152447/statya-350#p107799) |
| <a id="p107821"></a>B4 | <a id="p107822"></a>Декларация отправления товаров в контексте торговли со специальными фискальными территориями | <a id="p107823"></a>[10](https://bukva.ai/docs/reglament-20152447/statya-350#p107731) |
| <a id="p107824"></a>C1 | <a id="p107825"></a>Экспортная упрощенная декларация | <a id="p107826"></a>[10](https://bukva.ai/docs/reglament-20152447/statya-350#p107731), [11](https://bukva.ai/docs/reglament-20152447/statya-350#p107733), [23](https://bukva.ai/docs/reglament-20152447/statya-350#p107744), [31](https://bukva.ai/docs/reglament-20152447/statya-350#p107746) |
| <a id="p107827"></a>H1 | <a id="p107828"></a>Декларация на выпуск в свободное обращение и специальную процедуру - специальное использование - декларация таможенного хранения | <a id="p107829"></a>[01](https://bukva.ai/docs/reglament-20152447/statya-350#p107725), [07](https://bukva.ai/docs/reglament-20152447/statya-350#p107727), [40](https://bukva.ai/docs/reglament-20152447/statya-350#p107749), [42](https://bukva.ai/docs/reglament-20152447/statya-350#p107756), [43](https://bukva.ai/docs/reglament-20152447/statya-350#p107761), [44](https://bukva.ai/docs/reglament-20152447/statya-350#p107763), [45](https://bukva.ai/docs/reglament-20152447/statya-350#p107767), [46](https://bukva.ai/docs/reglament-20152447/statya-350#p107771), [48](https://bukva.ai/docs/reglament-20152447/statya-350#p107774), [61](https://bukva.ai/docs/reglament-20152447/statya-350#p107785), [63](https://bukva.ai/docs/reglament-20152447/statya-350#p107787), [68](https://bukva.ai/docs/reglament-20152447/statya-350#p107791) |
| <a id="p107830"></a>H2 | <a id="p107831"></a>Специальная процедура - хранение - декларация таможенного хранения | <a id="p107832"></a>[71](https://bukva.ai/docs/reglament-20152447/statya-350#p107794) |
| <a id="p107833"></a>H3 | <a id="p107834"></a>Специальная процедура - специальное использование - декларация временного допуска | <a id="p107835"></a>[53](https://bukva.ai/docs/reglament-20152447/statya-350#p107778) |
| <a id="p107836"></a>H4 | <a id="p107837"></a>Специальная процедура - переработка - декларация внутренней переработки | <a id="p107838"></a>[51](https://bukva.ai/docs/reglament-20152447/statya-350#p107776) |
| <a id="p107839"></a>H5 | <a id="p107840"></a>Декларация на ввоз товаров в контексте торговли со специальными фискальными территориями | <a id="p107841"></a>[40](https://bukva.ai/docs/reglament-20152447/statya-350#p107749), [42](https://bukva.ai/docs/reglament-20152447/statya-350#p107756), [61](https://bukva.ai/docs/reglament-20152447/statya-350#p107785), [63](https://bukva.ai/docs/reglament-20152447/statya-350#p107787), [95](https://bukva.ai/docs/reglament-20152447/statya-350#p107802), [96](https://bukva.ai/docs/reglament-20152447/statya-350#p107805) |
| <a id="p107842"></a>H6 | <a id="p107843"></a>Таможенная декларация в почтовом перемещении на выпуск в свободное обращение | <a id="p107844"></a>[01](https://bukva.ai/docs/reglament-20152447/statya-350#p107725), [07](https://bukva.ai/docs/reglament-20152447/statya-350#p107727), [40](https://bukva.ai/docs/reglament-20152447/statya-350#p107749) |
| <a id="p107845"></a>H7 | <a id="p107846"></a>Таможенная декларация на выпуск в свободное обращение в отношении грузов, которые пользуются освобождением от импортной пошлины в соответствии со [Статьей 23(1)](https://bukva.ai/docs/reglament-11862009/statya-23#p100133) или [Статьей 25(1)](https://bukva.ai/docs/reglament-11862009/statya-25#p100143) Регламента (ЕС) 1186/2009 | <a id="p107847"></a>4000 |
| <a id="p107848"></a>I1 | <a id="p107849"></a>Импортная упрощенная декларация | <a id="p107850"></a>[01](https://bukva.ai/docs/reglament-20152447/statya-350#p107725), [07](https://bukva.ai/docs/reglament-20152447/statya-350#p107727), [40](https://bukva.ai/docs/reglament-20152447/statya-350#p107749), [42](https://bukva.ai/docs/reglament-20152447/statya-350#p107756), [43](https://bukva.ai/docs/reglament-20152447/statya-350#p107761), [44](https://bukva.ai/docs/reglament-20152447/statya-350#p107763), [45](https://bukva.ai/docs/reglament-20152447/statya-350#p107767), [46](https://bukva.ai/docs/reglament-20152447/statya-350#p107771), [48](https://bukva.ai/docs/reglament-20152447/statya-350#p107774), [51](https://bukva.ai/docs/reglament-20152447/statya-350#p107776), [53](https://bukva.ai/docs/reglament-20152447/statya-350#p107778), [61](https://bukva.ai/docs/reglament-20152447/statya-350#p107785), [63](https://bukva.ai/docs/reglament-20152447/statya-350#p107787), [68](https://bukva.ai/docs/reglament-20152447/statya-350#p107791) |


<a id="p107851"></a>11 10 000 000 Дополнительная процедура
<a id="p107852"></a>Если этот элемент данных используется для определения процедуры Союза, то первый знак кода определяет категорию мер следующим образом:


| <a id="p107853"></a>Axx | <a id="p107854"></a>Внутренняя переработка ([Статья 256](https://bukva.ai/docs/reglament-9522013/statya-256#p102086) Кодекса) |
| --- | --- |
| <a id="p107855"></a>Bxx | <a id="p107856"></a>Внешняя переработка ([Статья 259](https://bukva.ai/docs/reglament-9522013/statya-259#p102110) Кодекса) |
| <a id="p107857"></a>Cxx | <a id="p107858"></a>Освобождение ([Регламент](https://bukva.ai/docs/reglament-11862009/statya-1) (ЕС) 1186/2009 Совета ЕС <*>) |
| <a id="p107859"></a>Dxx | <a id="p107860"></a>Временный допуск (Делегированный Регламент (ЕС) 2015/2446) |
| <a id="p107861"></a>Exx | <a id="p107862"></a>Сельскохозяйственная продукция |
| <a id="p107863"></a>Fxx | <a id="p107864"></a>Другие |


<a id="p107865"></a>

---

<a id="p107866"></a><*> [Регламент](https://bukva.ai/docs/reglament-11862009/statya-1) (ЕС) 1186/2009 Совета ЕС от 16 ноября 2009 г., устанавливающий систему освобождения от уплаты таможенных пошлин на территории стран Сообщества (ОЖ N L 324, 10.12.2009, стр. 23).

<a id="p107867"></a>Внутренняя переработка ([Статья 256](https://bukva.ai/docs/reglament-9522013/statya-256#p102086) Кодекса)


| <a id="p107868"></a>Код | <a id="p107869"></a>Процедура |
| --- | --- |
|  | <a id="p107870"></a>Импорт |
| <a id="p107871"></a>A04 | <a id="p107872"></a>Товары, которые помещены на процедуру внутренней переработки (только НДС) |
| <a id="p107873"></a>A10 | <a id="p107874"></a>Уничтожение товаров на внутренней переработке |


<a id="p107875"></a>Внешняя переработка ([Статья 259](https://bukva.ai/docs/reglament-9522013/statya-259#p102110) Кодекса)


| <a id="p107876"></a>Код | <a id="p107877"></a>Процедура |
| --- | --- |
|  | <a id="p107878"></a>Импорт |
| <a id="p107879"></a>B02 | <a id="p107880"></a>Переработанная продукция, возвращающаяся после ремонта по гарантии в соответствии со [Статьей 260](https://bukva.ai/docs/reglament-9522013/statya-260#p102119) Кодекса (товары, отремонтированные бесплатно) |
| <a id="p107881"></a>B03 | <a id="p107882"></a>Переработанная продукция, возвращающаяся после замены по гарантии в соответствии со [Статьей 261](https://bukva.ai/docs/reglament-9522013/statya-261#p102123) Кодекса (стандартная система обмена) |
| <a id="p107883"></a>B06 | <a id="p107884"></a>Переработанная продукция, возвращающаяся - только НДС |
|  | <a id="p107885"></a>Экспорт |
| <a id="p107886"></a>B51 | <a id="p107887"></a>Товары, импортированные для внутренней переработки, экспортированные для ремонта по внешней переработке |
| <a id="p107888"></a>B52 | <a id="p107889"></a>Товары, импортированные для внутренней переработки, экспортированные для замены по гарантии |
| <a id="p107890"></a>B53 | <a id="p107891"></a>Внешняя переработка по соглашению с третьими странами, возможна объединенная с НДС внешняя переработка |
| <a id="p107892"></a>B54 | <a id="p107893"></a>Только внешняя переработка с НДС |


<a id="p107894"></a>Освобождение от импортных пошлин ([Регламент](https://bukva.ai/docs/reglament-11862009/statya-1) (ЕС) 1186/2009 Совета ЕС <*>)


<a id="p107895"></a>

---

<a id="p107896"></a><*> [Регламент](https://bukva.ai/docs/reglament-11862009/statya-1) (ЕС) 1186/2009 Совета ЕС от 16 ноября 2009 г., устанавливающий в Сообществе систему освобождения от таможенных пошлин (ОЖ N L 324, 10.12.2009, стр. 23).


<table>
<colgroup><col width="12%"><col width="71%"><col width="16%"></colgroup>
<tr><td></td><td><a id="p107897"></a>Освобождение от импортных пошлин</td><td></td></tr>
<tr><td><a id="p107898"></a>Код</td><td><a id="p107899"></a>Описание</td><td><a id="p107900"></a>Статья N</td></tr>
<tr><td><a id="p107901"></a>C01</td><td><a id="p107902"></a>Личная собственность, принадлежащая физическим лицам, переезжающим на постоянное место жительства на таможенную территорию Союза</td><td><a id="p107903"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-3#p100049">3</a></td></tr>
<tr><td><a id="p107904"></a>C02</td><td><a id="p107905"></a>Приданое и домашние вещи, импортированные по случаю заключения брака</td><td><a id="p107906"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-12#p100085">12(1)</a></td></tr>
<tr><td><a id="p107907"></a>C03</td><td><a id="p107908"></a>Подарки, которые обычно дарят по случаю заключения брака</td><td><a id="p107909"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-12#p100086">12(2)</a></td></tr>
<tr><td><a id="p107910"></a>C04</td><td><a id="p107911"></a>Личное имущество, приобретенное по наследству физическим лицом, имеющим свое постоянное место жительства на таможенной территории Союза</td><td><a id="p107912"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-17#p100103">17</a></td></tr>
<tr><td><a id="p107913"></a>C06</td><td><a id="p107914"></a>Школьные принадлежности, школьные материалы и другие школьные домашние вещи</td><td><a id="p107915"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-21#p100122">21</a></td></tr>
<tr><td><a id="p107916"></a>C07</td><td><a id="p107917"></a>Грузы, имеющие ничтожную стоимость</td><td><a id="p107918"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-23#p100132">23</a></td></tr>
<tr><td><a id="p107919"></a>C08</td><td><a id="p107920"></a>Грузы, направленные от одного частного лица другому</td><td><a id="p107921"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-25#p100142">25</a></td></tr>
<tr><td><a id="p107922"></a>C09</td><td><a id="p107923"></a>Основные средства и другое оборудование, импортированные при переводе деятельности из третьей страны в Союз</td><td><a id="p107924"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-28#p100169">28</a></td></tr>
<tr><td><a id="p107925"></a>C10</td><td><a id="p107926"></a>Основные средства и другое оборудование, принадлежащие лицам, имеющим свободную профессию, и юридическим лицам, вовлеченным в деятельность, не связанную с получением прибыли</td><td><a id="p107927"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-34#p100192">34</a></td></tr>
<tr><td><a id="p107928"></a>C11</td><td><a id="p107929"></a>Образовательные, научные и культурные материалы; научные инструменты и аппаратура, указанные в <a href="https://bukva.ai/docs/reglament-11862009/statya-1#p100673">Приложении I</a> к Регламенту (ЕС) 1186/2009)</td><td><a id="p107930"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-42#p100224">42</a></td></tr>
<tr><td><a id="p107931"></a>C12</td><td><a id="p107932"></a>Образовательные, научные и культурные материалы; научные инструменты и аппаратура, указанные в <a href="https://bukva.ai/docs/reglament-11862009/statya-1#p100720">Приложении II</a> к Регламенту (ЕС) 1186/2009</td><td><a id="p107933"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-43#p100226">43</a></td></tr>
<tr><td><a id="p107934"></a>C13</td><td><a id="p107935"></a>Образовательные, научные и культурные материалы; научные инструменты и аппаратура, импортированные исключительно для некоммерческих целей (в том числе запасные части, компоненты, приспособления и инструменты)</td><td><a id="p107936"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-44#p100230">44</a> - <a href="https://bukva.ai/docs/reglament-11862009/statya-45#p100235">45</a></td></tr>
<tr><td><a id="p107937"></a>C14</td><td><a id="p107938"></a>Оборудование, импортированное для некоммерческих целей научно-исследовательскими учреждениями или организациями, базирующимися за пределами Союза, или от их имени</td><td><a id="p107939"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-51#p100258">51</a></td></tr>
<tr><td><a id="p107940"></a>C15</td><td><a id="p107941"></a>Лабораторные животные, а также биологические или химические вещества, предназначенные для исследований</td><td><a id="p107942"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-53#p100275">53</a></td></tr>
<tr><td><a id="p107943"></a>C16</td><td><a id="p107944"></a>Терапевтические вещества человеческого происхождения и реагенты определения группы крови и совместимости тканей</td><td><a id="p107945"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-54#p100285">54</a></td></tr>
<tr><td><a id="p107946"></a>C17</td><td><a id="p107947"></a>Инструменты и аппаратура, используемые в медицинских исследованиях, устанавливающие медицинские диагнозы или выполняющие медицинское лечение</td><td><a id="p107948"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-57#p100303">57</a></td></tr>
<tr><td><a id="p107949"></a>C18</td><td><a id="p107950"></a>Эталонные вещества для контроля качества медицинской продукции</td><td><a id="p107951"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-59#p100315">59</a></td></tr>
<tr><td><a id="p107952"></a>C19</td><td><a id="p107953"></a>Фармацевтическая продукция, используемая для международных спортивных мероприятий</td><td><a id="p107954"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-60#p100319">60</a></td></tr>
<tr><td><a id="p107955"></a>C20</td><td><a id="p107956"></a>Товары для благотворительных организаций или филантропов - предметы первой необходимости, импортированные государственными организациями или другими одобренными организациями</td><td><a id="p107957"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-61#p100326">61 (1)(a)</a></td></tr>
<tr><td colspan="3"><a id="p107958"></a><a id="p107959"></a>C21<br>Изделия, указанные в <a href="https://bukva.ai/docs/reglament-11862009/statya-1#p100781">Приложении III</a> к Регламенту (ЕС) 186/2009, предназначенные для слепых</td></tr>
<tr><td><a id="p107960"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-66#p100348">66</a></td><td><a id="p107961"></a>C22</td><td><a id="p107962"></a>Изделия, указанные в <a href="https://bukva.ai/docs/reglament-11862009/statya-1#p100798">Приложении IV</a> к Регламенту (ЕС) 1186/2009, предназначенные для слепых, импортированные самими слепыми для их собственного использования (в том числе запасные части, компоненты, приспособления и инструменты)</td></tr>
<tr><td><a id="p107963"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-67#p100352">67 (1)(a)</a> и <a href="https://bukva.ai/docs/reglament-11862009/statya-67#p100354">67 (2)</a></td><td><a id="p107964"></a>C23</td><td><a id="p107965"></a>Изделия, указанные в <a href="https://bukva.ai/docs/reglament-11862009/statya-1#p100798">Приложении IV</a> к Регламенту (ЕС) 1186/2009, предназначенные для слепых, импортированные определенными учреждениями или организациями (в том числе запасные части, компоненты, приспособления и инструменты)</td></tr>
<tr><td><a id="p107966"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-67#p100353">67 (1)(b)</a> и <a href="https://bukva.ai/docs/reglament-11862009/statya-67#p100354">67 (2)</a></td><td><a id="p107967"></a>C24</td><td><a id="p107968"></a>Изделия, предназначенные для других лиц с ограниченными возможностями (кроме слепых лиц), импортированные самими лицами с ограниченными возможностями для своего собственного использования (в том числе запасные части, компоненты, приспособления и инструменты)</td></tr>
<tr><td><a id="p107969"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-68#p100358">68 (1)(a)</a> и <a href="https://bukva.ai/docs/reglament-11862009/statya-68#p100360">68 (2)</a></td><td><a id="p107970"></a>C25</td><td><a id="p107971"></a>Изделия, предназначенные для других лиц с ограниченными возможностями (кроме слепых лиц), импортированные определенными учреждениями или организациями (в том числе запасные части, компоненты, приспособления и инструменты)</td></tr>
<tr><td><a id="p107972"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-68#p100359">68 (1)(b)</a> и <a href="https://bukva.ai/docs/reglament-11862009/statya-68#p100360">68 (2)</a></td><td><a id="p107973"></a>C26</td><td><a id="p107974"></a>Товары, импортированные для жертв катастроф</td></tr>
<tr><td><a id="p107975"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-74#p100380">74</a></td><td><a id="p107976"></a>C27</td><td><a id="p107977"></a>Награды, присваиваемые правительствами третьих стран лицам, чье постоянное место жительства находится на таможенной территории Союза</td></tr>
<tr><td><a id="p107978"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-81#p100408">81(a)</a></td><td><a id="p107979"></a>C28</td><td><a id="p107980"></a>Товары, импортированные на таможенную территорию Союза лицами, которые прибыли с официальным визитом в третью страну или которые получили их в связи с этим как подарок от принимающих органов</td></tr>
<tr><td><a id="p107981"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-82#p100416">82(a)</a></td><td><a id="p107982"></a>C29</td><td><a id="p107983"></a>Товары, которые должны быть использованы монархами или главами государств</td></tr>
<tr><td><a id="p107984"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-85#p100428">85</a></td><td><a id="p107985"></a>C30</td><td><a id="p107986"></a>Образцы товаров ничтожной стоимости, импортированные в целях продвижения торговли</td></tr>
<tr><td><a id="p107987"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-86#p100436">86</a></td><td><a id="p107988"></a>C31</td><td><a id="p107989"></a>Печатные рекламные материалы</td></tr>
<tr><td><a id="p107990"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-87#p100441">87</a></td><td><a id="p107991"></a>C32</td><td><a id="p107992"></a>Мелкие репрезентативные образцы товаров, произведенных за пределами таможенной территории Союза, предназначенные для торговых ярмарок или подобных мероприятиях</td></tr>
<tr><td><a id="p107993"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-90#p100455">90(a)</a></td><td><a id="p107994"></a>C33</td><td><a id="p107995"></a>Товары, импортированные для изучения, анализа или испытания</td></tr>
<tr><td><a id="p107996"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-95#p100489">95</a></td><td><a id="p107997"></a>C34</td><td><a id="p107998"></a>Грузы, направленные организациям, защищающим авторские права или промышленные или коммерческие патентные права</td></tr>
<tr><td><a id="p107999"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-102#p100510">102</a></td><td><a id="p108000"></a>C35</td><td><a id="p108001"></a>Информационная литература для туристов</td></tr>
<tr><td><a id="p108002"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-103#p100514">103</a></td><td><a id="p108003"></a>C36</td><td><a id="p108004"></a>Различные документы и статьи</td></tr>
<tr><td><a id="p108005"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-104#p100521">104</a></td><td><a id="p108006"></a>C37</td><td><a id="p108007"></a>Вспомогательные материалы для складирования и защиты товаров во время их перевозки</td></tr>
<tr><td><a id="p108008"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-105#p100542">105</a></td><td><a id="p108009"></a>C38</td><td><a id="p108010"></a>Подстилки, корм для скота и пища для животных во время их перевозки</td></tr>
<tr><td><a id="p108011"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-106#p100546">106</a></td><td><a id="p108012"></a>C39</td><td><a id="p108013"></a>Топлива и масла, представленные в наземных моторных транспортных средствах и специальных контейнерах</td></tr>
<tr><td><a id="p108014"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-107#p100550">107</a></td><td><a id="p108015"></a>C40</td><td><a id="p108016"></a>Материалы для строительства, обслуживания или украшения кладбищ и для мемориалов жертвам войны</td></tr>
<tr><td><a id="p108017"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-112#p100582">112</a></td><td><a id="p108018"></a>C41</td><td><a id="p108019"></a>Гробы, урны с прахом и похоронные принадлежности</td></tr>
<tr><td><a id="p108020"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-113#p100586">113</a></td><td><a id="p108021"></a>C42</td><td><a id="p108022"></a>Личная собственность, ввезенная для свободного обращения до того, как соответствующее лицо переедет на постоянное место жительства на таможенной территории Союза (освобождение от пошлины согласно обязательству)</td></tr>
<tr><td><a id="p108023"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-9#p100072">9(1)</a></td><td><a id="p108024"></a>C43</td><td><a id="p108025"></a>Личное имущество, ввезенное для свободного обращения, принадлежащее физическому лицу, имеющему намерение переехать на постоянное место жительства на таможенную территорию Союза (беспошлинный допуск согласно обязательству)</td></tr>
<tr><td><a id="p108026"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-10#p100074">10</a></td><td><a id="p108027"></a>C44</td><td><a id="p108028"></a>Личное имущество, приобретенное по наследству юридическими лицами, вовлеченными в деятельность, не связанную с получением прибыли, которые учреждены на таможенной территории Союза</td></tr>
<tr><td><a id="p108029"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-20#p100118">20</a></td><td><a id="p108030"></a>C45</td><td><a id="p108031"></a>Сельскохозяйственная, животноводческая, пчеловодческая, садоводческая и лесная продукция с объектов, расположенных в третьей стране, прилегающих к таможенной территории Союза</td></tr>
<tr><td><a id="p108032"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-35#p100196">35</a></td><td><a id="p108033"></a>C46</td><td><a id="p108034"></a>Продукция рыболовства или рыбоводства, осуществляемого на озерах или водных объектах, граничащих с государством-членом ЕС и третьей страной, рыбаками Союза, и продукция охотничьей деятельности, осуществляемой на таких озерах и водных объектах спортсменами Союза</td></tr>
<tr><td><a id="p108035"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-38#p100203">38</a></td><td><a id="p108036"></a>C47</td><td><a id="p108037"></a>Семена, удобрения и продукция для обработки почвы и культур, предназначенные для использования на объектах, расположенных на таможенной территории Союза, прилегающих к третьей стране</td></tr>
<tr><td><a id="p108038"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-39#p100207">39</a></td><td><a id="p108039"></a>C48</td><td><a id="p108040"></a>Товары, содержащиеся в личном багаже и освобожденные от НДС</td></tr>
<tr><td><a id="p108041"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-41#p100215">41</a></td><td><a id="p108042"></a>C49</td><td><a id="p108043"></a>Товары для благотворительных организаций или филантропов - товары каждого описания, которые были направлены бесплатно и которые должны использоваться для привлечения средств на случайных благотворительных мероприятиях для нуждающихся лиц</td></tr>
<tr><td><a id="p108044"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-61#p100327">61 (1)(b)</a></td><td><a id="p108045"></a>C50</td><td><a id="p108046"></a>Товары для благотворительных организаций или филантропов - оборудование и офисные материалы, направленные бесплатно</td></tr>
<tr><td><a id="p108047"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-61#p100328">61 (1)(c)</a></td><td><a id="p108048"></a>C51</td><td><a id="p108049"></a>Кубки, медали и подобные предметы, имеющие существенный символический характер, которыми были награждены в третьих странах лица, имеющие постоянное место жительства на таможенной территории Союза</td></tr>
<tr><td><a id="p108050"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-81#p100409">81(b)</a></td><td><a id="p108051"></a>C52</td><td><a id="p108052"></a>Кубки, медали и подобные предметы, имеющие существенный символический характер, которые были вручены бесплатно органами или лицами, учрежденными в третьей стране для предоставления на таможенной территории Союза</td></tr>
<tr><td><a id="p108053"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-81#p100410">81(c)</a></td><td><a id="p108054"></a>C53</td><td><a id="p108055"></a>Награды, трофеи и сувениры символического характера и ограниченной стоимости, предназначенные для бесплатного распространения лицам, имеющим постоянное место жительства в третьих странах на бизнес конференциях или подобных международных мероприятиях</td></tr>
<tr><td><a id="p108056"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-81#p100411">81(d)</a></td><td><a id="p108057"></a>C54</td><td><a id="p108058"></a>Товары, импортированные на таможенную территорию Союза лицами, приехавшими с официальным визитом на таможенную территорию Союза и которые намерены вручить их по этому случаю, в качестве подарка принимающим органам</td></tr>
<tr><td><a id="p108059"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-82#p100417">82(b)</a></td><td><a id="p108060"></a>C55</td><td><a id="p108061"></a>Товары, направленные в качестве подарков в знак дружбы или доброй воли официальным органом, публичным органом или группой, осуществляющими деятельность в общественных интересах, которые расположены в третьей стране, официальному органу, государственному органу или группе, осуществляющим деятельность в общественных интересах, которые расположены на таможенной территории Союза, и одобренные компетентными органами для получения этих изделий без оплаты пошлины</td></tr>
<tr><td><a id="p108062"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-82#p100418">82(c)</a></td><td><a id="p108063"></a>C56</td><td><a id="p108064"></a>Изделия для рекламных целей, без внутренней коммерческой стоимости, направленные бесплатно поставщиками своим потребителям, которые кроме своей рекламной функции не могут быть использованы иным способом</td></tr>
<tr><td><a id="p108065"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-89#p100450">89</a></td><td><a id="p108066"></a>C57</td><td><a id="p108067"></a>Товары, импортированные исключительно для того, чтобы они были продемонстрированы, или для демонстрации машин и аппаратов, произведенных за пределами таможенной территории Союза, и показа на торговых ярмарках или подобных мероприятиях</td></tr>
<tr><td><a id="p108068"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-90#p100456">90(1) (b)</a></td><td><a id="p108069"></a>C58</td><td><a id="p108070"></a>Различные материалы небольшой стоимости, такие как краски, лаки, обои и т.п., используемые в строительстве, оснащении и отделке временных стендов, занятых представителями третьих стран на торговых ярмарках или подобных мероприятиях, которые разрушаются после использования</td></tr>
<tr><td><a id="p108071"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-90#p100457">90(1) (c)</a></td><td><a id="p108072"></a>C59</td><td><a id="p108073"></a>Печатные материалы, каталоги, проспекты, прайс-листы, рекламные постеры, календари, иллюстрированные или неиллюстрированные, фотографии без рамок и другие изделия, поставленные бесплатно для рекламы товаров, произведенных за пределами таможенной территории Союза и показанные на торговых ярмарках идти подобных мероприятиях</td></tr>
<tr><td><a id="p108074"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-90#p100458">90(1) (d)</a></td><td><a id="p108075"></a>C60</td><td><a id="p108076"></a>Приданное и домашние вещи, импортированные по случаю заключения брака, ввозимые для свободного обращения в первые два месяца до свадьбы (освобождение от пошлины при подаче соответствующего обеспечения)</td></tr>
<tr><td><a id="p108077"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-12#p100085">12(1)</a>, <a href="https://bukva.ai/docs/reglament-11862009/statya-15#p100095">15(1)(a)</a></td><td><a id="p108078"></a>C61</td><td><a id="p108079"></a>Подарки, которые обычно дарят по случаю заключения брака, ввезенные для свободного обращения в первые два месяца до свадьбы (освобождение от пошлины при подаче соответствующего обеспечения)</td></tr>
<tr><td><a id="p108080"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-12#p100086">12(2)</a>, <a href="https://bukva.ai/docs/reglament-11862009/statya-15#p100095">15(1)(a)</a></td><td></td><td><a id="p108081"></a>Освобождение от экспортных пошлин</td></tr>
<tr><td></td><td><a id="p108082"></a>C71</td><td><a id="p108083"></a>Домашние животные, экспортированные во время перевода сельскохозяйственной деятельности из Союза в третью страну</td></tr>
<tr><td><a id="p108084"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-115#p100597">115</a></td><td><a id="p108085"></a>C72</td><td><a id="p108086"></a>Корма и пища, сопровождающие животных во время их экспорта</td></tr>
<tr><td><a id="p108087"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-121#p100617">121</a></td><td><a id="p108088"></a>C73</td><td><a id="p108089"></a>Грузы с ничтожной стоимостью</td></tr>
<tr><td><a id="p108090"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-114#p100593">114</a></td><td><a id="p108091"></a>C74</td><td><a id="p108092"></a>Сельскохозяйственная или животноводческая продукция, полученная на таможенной территории Союза с собственности, прилегающей к третьей стране, используемой в качестве собственности или на праве аренды, лицами, имеющими свое основное предприятие в третьей стране, прилегающей к таможенной территории Союза</td></tr>
<tr><td><a id="p108093"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-116#p100602">116</a></td><td><a id="p108094"></a>C75</td><td><a id="p108095"></a>Семена для использования на собственности, расположенной в третьей стране, прилегающей к таможенной территории Союза, используемой в качестве собственности или на праве аренды, лицами, имеющими свое основное предприятие в названной таможенной территории в непосредственной близости к этой третьей стране</td></tr>
<tr><td><a id="p108096"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-119#p100611">119</a></td><td></td><td><a id="p108097"></a>Временный допуск</td></tr>
</table>


| <a id="p108098"></a>Код |  | <a id="p108099"></a>Статья N |
| --- | --- | --- |
| <a id="p108100"></a>D01 | <a id="p108101"></a>Паллеты (в том числе запасные части, принадлежности и оборудование паллет) | <a id="p108102"></a>208 и 209 |
| <a id="p108103"></a>D02 | <a id="p108104"></a>Контейнеры (в том числе запасные части, принадлежности и оборудование контейнеров) | <a id="p108105"></a>210 и 211 |
| <a id="p108106"></a>D03 | <a id="p108107"></a>Средства дорожного, железнодорожного, воздушного, морского и внутреннего водного транспорта | <a id="p108108"></a>212 |
| <a id="p108109"></a>D04 | <a id="p108110"></a>Личные предметы и товары для спортивных целей, импортируемые туристами | <a id="p108111"></a>219 |
| <a id="p108112"></a>D05 | <a id="p108113"></a>Бытовые вещи моряков | <a id="p108114"></a>220 |
| <a id="p108115"></a>D06 | <a id="p108116"></a>Материалы для помощи при катастрофах | <a id="p108117"></a>221 |
| <a id="p108118"></a>D07 | <a id="p108119"></a>Медицинское, хирургическое и лабораторное оборудование | <a id="p108120"></a>222 |
| <a id="p108121"></a>D08 | <a id="p108122"></a>Животные (12 месяцев или старше) | <a id="p108123"></a>223 |
| <a id="p108124"></a>D09 | <a id="p108125"></a>Товары для использования в приграничной зоне | <a id="p108126"></a>224 |
| <a id="p108127"></a>D10 | <a id="p108128"></a>Товары, несущие звуковую информацию, изображения или данные | <a id="p108129"></a>225 |
| <a id="p108130"></a>D11 | <a id="p108131"></a>Публичные материалы | <a id="p108132"></a>225 |
| <a id="p108133"></a>D12 | <a id="p108134"></a>Профессиональное оборудование | <a id="p108135"></a>226 |
| <a id="p108136"></a>D13 | <a id="p108137"></a>Педагогические материалы и научное оборудование | <a id="p108138"></a>227 |
| <a id="p108139"></a>D14 | <a id="p108140"></a>Упаковки, полные | <a id="p108141"></a>228 |
| <a id="p108142"></a>D15 | <a id="p108143"></a>Упаковки, пустые | <a id="p108144"></a>228 |
| <a id="p108145"></a>D16 | <a id="p108146"></a>Формы, штампы, блочные конструкции, чертежи, эскизы, измерительные, проверочные и испытательные инструменты и другие подобные изделия | <a id="p108147"></a>229 |
| <a id="p108148"></a>D17 | <a id="p108149"></a>Специальные приборы и инструменты | <a id="p108150"></a>230 |
| <a id="p108151"></a>D18 | <a id="p108152"></a>Товары, подлежащие испытаниям, экспериментам или демонстрации | <a id="p108153"></a>231(a) |
| <a id="p108154"></a>D19 | <a id="p108155"></a>Товары, импортированные согласно удовлетворительно принятым испытаниям в связи с договорами на продажу | <a id="p108156"></a>231(b) |
| <a id="p108157"></a>D20 | <a id="p108158"></a>Товары, используемые для выполнения испытаний, экспериментов или демонстраций без получения дохода (шесть месяцев) | <a id="p108159"></a>231(c) |
| <a id="p108160"></a>D21 | <a id="p108161"></a>Образцы | <a id="p108162"></a>232 |
| <a id="p108163"></a>D22 | <a id="p108164"></a>Средства замены производства (шесть месяцев) | <a id="p108165"></a>233 |
| <a id="p108166"></a>D23 | <a id="p108167"></a>Товары для мероприятий или для продажи | <a id="p108168"></a>234(1) |
| <a id="p108169"></a>D24 | <a id="p108170"></a>Товары для утверждения (шесть месяцев) | <a id="p108171"></a>234(2) |
| <a id="p108172"></a>D25 | <a id="p108173"></a>Произведения искусства, предметы коллекционеров и антиквариат | <a id="p108174"></a>234(3)(a) |
| <a id="p108175"></a>D26 | <a id="p108176"></a>Товары, кроме вновь произведенных, импортированные с целью их продажи на аукционе | <a id="p108177"></a>234(3)(b) |
| <a id="p108178"></a>D27 | <a id="p108179"></a>Запасные части, принадлежности и оборудование | <a id="p108180"></a>235 |
| <a id="p108181"></a>D28 | <a id="p108182"></a>Товары, импортированные в отдельных ситуациях, не имеющих экономического значения | <a id="p108183"></a>236(b) |
| <a id="p108184"></a>D29 | <a id="p108185"></a>Товары, импортированные на срок, не превышающий трех месяцев | <a id="p108186"></a>236(a) |
| <a id="p108187"></a>D30 | <a id="p108188"></a>Транспортные средства для лиц, учрежденных за пределами таможенной территории Союза, или для лиц, готовящихся к переезду на постоянное место жительства за пределами указанной территории | <a id="p108189"></a>216 |
| <a id="p108190"></a>D51 | <a id="p108191"></a>Временный допуск с частичным освобождением от импортных пошлин | <a id="p108192"></a>206 |


<a id="p108193"></a>Сельскохозяйственная продукция


<table>
<colgroup><col width="10%"><col width="90%"></colgroup>
<tr><td><a id="p108194"></a>Код</td><td><a id="p108195"></a>Описание</td></tr>
<tr><td></td><td><a id="p108196"></a>Импорт</td></tr>
<tr><td><a id="p108197"></a>E01</td><td><a id="p108198"></a>Использование цены за единицу для определения таможенной стоимости для отдельных скоропортящихся товаров <a href="https://bukva.ai/docs/reglament-9522013/statya-1#p100775">(Статья 74(2)(c)</a> Кодекса и <a href="#p101368">Статья 142(6))</a></td></tr>
<tr><td><a id="p108199"></a>E02</td><td><a id="p108200"></a>Стандартная стоимость импорта (например: Регламент (ЕС) 543/2011 <a href="#p108220">&lt;*&gt;</a>)</td></tr>
<tr><td></td><td><a id="p108201"></a>Экспорт</td></tr>
<tr><td><a id="p108202"></a>E51</td><td><a id="p108203"></a>Сельскохозяйственная продукция, указанная в <a href="https://bukva.ai/docs/dogovor-o-funktsionirovanii-evropeyskogo-soyuza/statya-358#p102397">Приложении I</a> к Договору о функционировании Европейского Союза, для которой было запрошено возмещение по экспортному сертификату</td></tr>
<tr><td><a id="p108204"></a>E52</td><td><a id="p108205"></a>Сельскохозяйственная продукция, указанная в <a href="https://bukva.ai/docs/dogovor-o-funktsionirovanii-evropeyskogo-soyuza/statya-358#p102397">Приложении I</a> к Договору о функционировании Европейского Союза, для которой было запрошено возмещение, не требующая экспортного сертификата</td></tr>
<tr><td><a id="p108206"></a>E53</td><td><a id="p108207"></a>Сельскохозяйственная продукция, указанная в <a href="https://bukva.ai/docs/dogovor-o-funktsionirovanii-evropeyskogo-soyuza/statya-358#p102397">Приложении I</a> к Договору о функционировании Европейского Союза, для которой было запрошено возмещение, экспортированная в небольших количествах, не требующая экспортного сертификата</td></tr>
<tr><td><a id="p108208"></a>E61</td><td><a id="p108209"></a>Переработанная сельскохозяйственная продукция, не указанная в <a href="https://bukva.ai/docs/dogovor-o-funktsionirovanii-evropeyskogo-soyuza/statya-358#p102397">Приложении I</a> к Договору о функционировании Европейского Союза, для которой было запрошено возмещение по сертификату возмещения</td></tr>
<tr><td><a id="p108210"></a>E62</td><td><a id="p108211"></a>Переработанная сельскохозяйственная продукция, не указанная в <a href="https://bukva.ai/docs/dogovor-o-funktsionirovanii-evropeyskogo-soyuza/statya-358#p102397">Приложении I</a> к Договору о функционировании Европейского Союза, для которой было запрошено возмещение, не требующая сертификата возмещения</td></tr>
<tr><td><a id="p108212"></a>E63</td><td><a id="p108213"></a>Переработанная сельскохозяйственная продукция, не указанная в <a href="https://bukva.ai/docs/dogovor-o-funktsionirovanii-evropeyskogo-soyuza/statya-358#p102397">Приложении I</a> к Договору о функционировании Европейского Союза, для которой было запрошено возмещение, экспортированная в небольших количествах, не требующая сертификата возмещения</td></tr>
<tr><td><a id="p108214"></a>E64</td><td><a id="p108215"></a>Снабжение продовольственными товарами, в отношении которых имеется право на возмещение (Статья 33 Регламента (ЕС) 612/2009 <a href="#p108221">&lt;**&gt;</a>)</td></tr>
<tr><td><a id="p108216"></a>E65</td><td><a id="p108217"></a>Ввоз на продовольственный склад (Статья 37 (ЕС) 612/2009)</td></tr>
<tr><td><a id="p108218"></a>E71</td><td><a id="p108219"></a>Сельскохозяйственная продукция, для которой запрашивается возмещение, экспортированная в небольших количествах без учета расчета минимальных ставок проверок</td></tr>
<tr><td colspan="2"><a id="p108220"></a><a id="p108221"></a>&lt;*&gt; Имплементационный Регламент (ЕС) 543/2011 Европейской Комиссии от 7 июня 2011 г., устанавливающий подробные правила применения Регламента (ЕС) 1234/2007 Совета ЕС в отношении секторов фруктов и овощей, а также переработанных фруктов и овощей (ОЖ N L 157, 15.6.2011, стр. 1).<br>&lt;**&gt; Регламент (ЕС) 612/2009 Европейской Комиссии от 7 июля 2009 г. об установлении подробных правил применения системы возмещения экспорта сельскохозяйственной продукции (ОЖ N L 186, 17.7.2009, стр. 1).</td></tr>
</table>


<a id="p108222"></a>Прочее


<table>
<colgroup><col width="10%"><col width="90%"></colgroup>
<tr><td><a id="p108223"></a>Код</td><td><a id="p108224"></a>Описание</td></tr>
<tr><td></td><td><a id="p108225"></a>Импорт</td></tr>
<tr><td><a id="p108226"></a>F01</td><td><a id="p108227"></a>Освобождение от импортных пошлин для возвращенных товаров (<a href="https://bukva.ai/docs/reglament-9522013/statya-203#p101721">Статья 203</a> Кодекса)</td></tr>
<tr><td><a id="p108228"></a>F02</td><td><a id="p108229"></a>Освобождение от импортных пошлин для возвращенных товаров (Специальные обстоятельства, предусмотренные в Статье 159 Делегированного Регламента (ЕС) 2015/2446: сельскохозяйственные товары)</td></tr>
<tr><td><a id="p108230"></a>F03</td><td><a id="p108231"></a>Освобождение от импортных пошлин для возвращенных товаров (Специальные обстоятельства, предусмотренные в Статье 158(3) Делегированного Регламента (ЕС) 2015/2446: ремонт или реставрация)</td></tr>
<tr><td><a id="p108232"></a>F04</td><td><a id="p108233"></a>Переработанная продукция, которая возвращается в Европейский Союз после того, как она была ранее реэкспортирована после процедуры внутренней переработки <a href="https://bukva.ai/docs/reglament-9522013/statya-1#p101736">(Статья 205(1)</a> Кодекса)</td></tr>
<tr><td><a id="p108234"></a>F05</td><td><a id="p108235"></a>Освобождение от импортных пошлин и от НДС и/или акцизных сборов для возвращенных товаров (<a href="https://bukva.ai/docs/reglament-9522013/statya-203#p101721">Статья 203</a> Кодекса и <a href="https://bukva.ai/docs/direktiva-2006112es/statya-1#p100871">Статья 143(1)(e)</a> (Директивы 2006/112/ЕС)</td></tr>
<tr><td colspan="2"><a id="p108236"></a><a id="p108237"></a>F06<br>Перемещение акцизных товаров по соглашению о приостановке акцизной пошлины с места импорта в соответствии со <a href="https://bukva.ai/docs/direktiva-2008118es/statya-17#p100219">Статьей 17(1)(b)</a> Директивы 2008/11/ЕС</td></tr>
<tr><td><a id="p108238"></a>F07</td><td><a id="p108239"></a>Переработанная продукция, которая возвращается в Европейский Союз после того, как она была ранее реэкспортирована после процедуры внутренней переработки, если импортная пошлина определяется в соответствии со <a href="https://bukva.ai/docs/reglament-9522013/statya-1#p100873">Статьей 86(3)</a> Кодекса <a href="https://bukva.ai/docs/reglament-9522013/statya-1#p101737">(Статья 205(2)</a> Кодекса)</td></tr>
<tr><td><a id="p108240"></a>F15</td><td><a id="p108241"></a>Товары, ввезенные в контексте торговли со специальными фискальными территориями <a href="https://bukva.ai/docs/reglament-9522013/statya-1#p100107">(Статья 1(3)</a> Кодекса)</td></tr>
<tr><td><a id="p108242"></a>F16</td><td><a id="p108243"></a>Товары, ввезенные в контексте торговли между Союзом и странами, с которыми он образовал таможенный союз</td></tr>
<tr><td><a id="p108244"></a>F21</td><td><a id="p108245"></a>Освобождение от импортных пошлин продукции морского рыболовства и другой продукции, выловленной из территориального моря страны или территории за пределами таможенной территории Союза судами, зарегистрированными или записанными исключительно в государстве-члене ЕС и плавающими под флагом этого государства</td></tr>
<tr><td><a id="p108246"></a>F22</td><td><a id="p108247"></a>Освобождение от импортных пошлин продукции, полученной из продукции морского рыболовства и другой продукции, выловленной из территориального моря страны или территории за пределами таможенной территории Союза на борту плавучего рыбозавода, зарегистрированного или записанного в государстве-члене ЕС и плавающего под флагом государства</td></tr>
<tr><td><a id="p108248"></a>F44</td><td><a id="p108249"></a>Выпуск в свободное обращение переработанной продукции, если должна применяться <a href="https://bukva.ai/docs/reglament-9522013/statya-1#p100873">Статья 86(3)</a> Кодекса</td></tr>
<tr><td><a id="p108250"></a>F45</td><td><a id="p108251"></a>Освобождение от налога на добавленную стоимость при окончательном импорте отдельных товаров (Директива 2009/132/ЕС Совета ЕС <a href="#p108267">&lt;*&gt;</a>)</td></tr>
<tr><td><a id="p108252"></a>F46</td><td><a id="p108253"></a>Использование первоначальной тарифной классификации товаров в ситуациях, предусмотренных в <a href="https://bukva.ai/docs/reglament-9522013/statya-1#p100872">Статье 86(2)</a> Кодекса</td></tr>
<tr><td><a id="p108254"></a>F47</td><td><a id="p108255"></a>Упрощение составления таможенных деклараций для товаров, подпадающих под различные тарифные подзаголовки, предусмотренные в <a href="https://bukva.ai/docs/reglament-9522013/statya-177#p101548">Статье 177</a> Кодекса</td></tr>
<tr><td><a id="p108256"></a>F48</td><td><a id="p108257"></a>Импорт по специальной схеме для удаленной торговли товарами, импортированными из третьих стран или третьих территорий, установленных в <a href="https://bukva.ai/docs/direktiva-2006112es/statya-1#p102020">Титуле XII Главы 6 Раздела 4</a> Директивы 2006/112/ЕС</td></tr>
<tr><td><a id="p108258"></a>F49</td><td><a id="p108259"></a>Импорт согласно специальным соглашениям для декларирования и оплаты импорта с НДС, установленным в <a href="https://bukva.ai/docs/direktiva-2006112es/statya-1#p102107">Титуле XII Главе 7</a> Директивы 2006/112/ЕС</td></tr>
<tr><td></td><td><a id="p108260"></a>Экспорт</td></tr>
<tr><td><a id="p108261"></a>F61</td><td><a id="p108262"></a>Снабжение продовольствием и заправка топливом</td></tr>
<tr><td><a id="p108263"></a>F65</td><td><a id="p108264"></a>Упрощение составления таможенных деклараций для товаров, подпадающих под различные тарифные подзаголовки, предусмотренные в <a href="https://bukva.ai/docs/reglament-9522013/statya-177#p101548">Статье 177</a> Кодекса</td></tr>
<tr><td><a id="p108265"></a>F75</td><td><a id="p108266"></a>Товары, отправленные в контексте торговли со специальными фискальными территориями <a href="https://bukva.ai/docs/reglament-9522013/statya-1#p100107">(Статья 1(3)</a> Кодекса)</td></tr>
<tr><td><a id="p108267"></a>&lt;*&gt; Директива 2009/132/ЕС Совета ЕС от 19 октября 2009 г. об определении сферы действия <a href="https://bukva.ai/docs/direktiva-2006112es/statya-1#p100863">Статьи 143(b)</a> и <a href="https://bukva.ai/docs/direktiva-2006112es/statya-1#p100868">(c)</a> Директивы 2006/112/ЕС в отношении освобождения от налога на добавленную стоимость при окончательном импорте отдельных товаров (ОЖ N L 292, 10.11.2009, стр. 5).</td><td></td></tr>
<tr><td colspan="2"><a id="p108268"></a>12 01 000 000 Предыдущий документ</td></tr>
</table>


<a id="p108269"></a>12 01 001 000 Исходящий номер
<a id="p108270"></a>Идентификационный номер или другой признанный номер документа вносится сюда.
<a id="p108271"></a>В случае если в качестве предварительного документа указан MRN, исходящий номер должен иметь следующую структуру:


| <a id="p108272"></a>Поле | <a id="p108273"></a>Содержание | <a id="p108274"></a>Формат | <a id="p108275"></a>Примеры |
| --- | --- | --- | --- |
| <a id="p108276"></a>1 | <a id="p108277"></a>Последние две цифры года официального принятия декларации (ГГ) | <a id="p108278"></a>n2 | <a id="p108279"></a>21 |
| <a id="p108280"></a>2 | <a id="p108281"></a>Идентификатор страны, в которой подана декларация/доказательство таможенного статуса товаров Союза/уведомление (буквенный 2-значный код страны) | <a id="p108282"></a>a2 | <a id="p108283"></a>RO |
| <a id="p108284"></a>3 | <a id="p108285"></a>Уникальный идентификатор для сообщения по году и по стране | <a id="p108286"></a>an12 | <a id="p108287"></a>9876AB889012 |
| <a id="p108288"></a>4 | <a id="p108289"></a>Идентификатор процедуры | <a id="p108290"></a>a1 | <a id="p108291"></a>B |
| <a id="p108292"></a>5 | <a id="p108293"></a>Проверочная цифра | <a id="p108294"></a>an1 | <a id="p108295"></a>1 |


<a id="p108296"></a>[Поле 1](https://bukva.ai/docs/reglament-20152447/statya-350#p108276) и [2](https://bukva.ai/docs/reglament-20152447/statya-350#p108280) - как разъяснено выше.
<a id="p108297"></a>В [поле 3](https://bukva.ai/docs/reglament-20152447/statya-350#p108284) вносится идентификатор соответствующего сообщения. Вопрос о том, каким образом используется это [поле](https://bukva.ai/docs/reglament-20152447/statya-350#p108284), входит в компетенцию национальных администраций, но каждое сообщение, обрабатываемое в течение года в данной стране, должно иметь уникальный номер в отношении рассматриваемой процедуры.
<a id="p108298"></a>Национальные администрации, которые хотят включить в MRN номер компетентного таможенного учреждения, могут использовать до 6 первых знаков для его представления.
<a id="p108299"></a>В [поле 4](https://bukva.ai/docs/reglament-20152447/statya-350#p108288) вносится идентификатор процедуры, определенный в [таблице](https://bukva.ai/docs/reglament-20152447/statya-350#p108304) ниже.
<a id="p108300"></a>В [поле 5](https://bukva.ai/docs/reglament-20152447/statya-350#p108292) вносится значение, которое является проверочной цифрой для всего MRN. Это [поле](https://bukva.ai/docs/reglament-20152447/statya-350#p108292) позволяет определить ошибку при вводе всего MRN.
<a id="p108301"></a>Коды, используемые в [поле 4](https://bukva.ai/docs/reglament-20152447/statya-350#p108288) - Идентификатор процедуры <*>:

<a id="p108302"></a>

---

<a id="p108303"></a><*> Из таблицы удален третий столбец - прим. ред.


| <a id="p108304"></a>Код | <a id="p108305"></a>Процедура |
| --- | --- |
| <a id="p108306"></a>A | <a id="p108307"></a>Только экспорт |
| <a id="p108308"></a>B | <a id="p108309"></a>Экспортная и сводная вывозная декларация |
| <a id="p108310"></a>C | <a id="p108311"></a>Только сводная вывозная декларация |
| <a id="p108312"></a>D | <a id="p108313"></a>Реэкспортное уведомление |
| <a id="p108314"></a>E | <a id="p108315"></a>Отправка товаров в отношении специальных фискальных территорий |
| <a id="p108316"></a>J | <a id="p108317"></a>Только транзитная декларация |
| <a id="p108318"></a>K | <a id="p108319"></a>Транзитная декларация и сводная вывозная декларация |
| <a id="p108320"></a>L | <a id="p108321"></a>Транзитная декларация и сводная ввозная декларация |
| <a id="p108322"></a>M | <a id="p108323"></a>Транзитная декларация и сводная вывозная декларация и сводная ввозная декларация |
| <a id="p108324"></a>P | <a id="p108325"></a>Доказательство таможенного статуса товаров Союза/Манифест товаров Союза |
| <a id="p108326"></a>R | <a id="p108327"></a>Только импортная декларация |
| <a id="p108328"></a>S | <a id="p108329"></a>Импортная декларация и сводная ввозная декларация |
| <a id="p108330"></a>T | <a id="p108331"></a>Только сводная ввозная декларация |
| <a id="p108332"></a>U | <a id="p108333"></a>Декларация временного хранения |
| <a id="p108334"></a>V | <a id="p108335"></a>Ввоз товаров в отношении специальных фискальных территорий |
| <a id="p108336"></a>W | <a id="p108337"></a>Декларация временного хранения и сводная ввозная декларация |
| <a id="p108338"></a>Z | <a id="p108339"></a>Уведомление о прибытии |


<a id="p108340"></a>12 01 002 000 Тип
<a id="p108341"></a>Предыдущие документы должны быть внесены в форме кода, определенного в [Титуле I](https://bukva.ai/docs/reglament-20152447/statya-350#p104416). Список документов и их соответствующие коды можно найти в базе данных TARIC.

<a id="p108342"></a>12 02 000 000 Дополнительная информация

<a id="p108343"></a>12 02 008 000 Код
<a id="p108344"></a>Пятизначный код используется для кодирования дополнительной информации таможенного характера:
<a id="p108345"></a>Код 0xxxx - Общая категория
<a id="p108346"></a>Код 1xxxx - На импорте
<a id="p108347"></a>Код 2xxxx - На транзите
<a id="p108348"></a>Код 3xxxx - На экспорте
<a id="p108349"></a>Код 4xxxx - Прочее


<table>
<colgroup><col width="9%"><col width="31%"><col width="36%"><col width="24%"></colgroup>
<tr><td><a id="p108350"></a>Код</td><td><a id="p108351"></a>Правовое основание</td><td><a id="p108352"></a>Предмет</td><td><a id="p108353"></a>Дополнительная информация</td></tr>
<tr><td><a id="p108354"></a>00100</td><td><a id="p108355"></a>Статья 163 Делегированного Регламента (ЕС) 2015/2446</td><td><a id="p108356"></a>Заявление на разрешение использования специальной процедуры, кроме транзита, основанное на таможенной декларации</td><td><a id="p108357"></a>"Упрощенное разрешение"</td></tr>
<tr><td><a id="p108358"></a>00700</td><td><a id="p108359"></a>Статья 176(1)(c) и Статья 241(1) первый подпараграф Делегированного Регламента (ЕС) 2015/2446</td><td><a id="p108360"></a>Завершение внутренней переработки</td><td><a id="p108361"></a>"IP" и соответствующий номер разрешения или номер INF</td></tr>
<tr><td><a id="p108362"></a>00800</td><td><a id="p108363"></a>Статья 241(1) второй подпараграф Делегированного Регламента (ЕС) 2015/2446</td><td><a id="p108364"></a>Завершение внутренней переработки (меры специальной коммерческой политики)</td><td><a id="p108365"></a>"IP CPM"</td></tr>
<tr><td><a id="p108366"></a>00900</td><td><a id="p108367"></a>Статья 238 Делегированного Регламента (ЕС) 2015/2446</td><td><a id="p108368"></a>Завершение временного допуска</td><td><a id="p108369"></a>"TA" и соответствующий номер разрешения</td></tr>
<tr><td><a id="p108370"></a>01000</td><td><a id="p108371"></a><a href="https://bukva.ai/docs/venskaya-konventsiya-o-diplomaticheskih-oon-organizatsiya-obedinennyh/statya-36#p100151">Статья 36(2)</a> Венской конвенции о дипломатических отношениях 1961 г.</td><td><a id="p108372"></a>Личный багаж дипломатического агента должен быть исключен из досмотра</td><td><a id="p108373"></a>"Дипломатические товары - Исключены из досмотра"</td></tr>
<tr><td><a id="p108374"></a>10600</td><td><a id="p108375"></a>Титул II Приложения B к Делегированному Регламенту (ЕС) 2015/2446</td><td><a id="p108376"></a>Ситуации, когда рассматриваются оборотные коносаменты "заказать заполненный бланк", в случае сводных ввозных деклараций, если сведения о грузополучателе неизвестны.</td><td><a id="p108377"></a>"Грузополучатель неизвестен"</td></tr>
<tr><td><a id="p108378"></a>20100</td><td><a id="p108379"></a><a href="https://bukva.ai/docs/konventsiya-tc10/statya-18#p100188">Статья 18</a> "процедуры общего транзита" <a href="#p108408">&lt;*&gt;</a></td><td><a id="p108380"></a>Экспорт из одной страны общего транзита, подлежащий ограничению, или экспорт из Союза, подлежащий ограничению</td><td></td></tr>
<tr><td><a id="p108381"></a>20200</td><td><a id="p108382"></a><a href="https://bukva.ai/docs/konventsiya-tc10/statya-18#p100188">Статья 18</a> "процедуры общего транзита" <a href="#p108408">&lt;*&gt;</a></td><td><a id="p108383"></a>Экспорт из одной страны общего транзита, подлежащий оплате пошлин, или экспорт из Союза, подлежащий оплате пошлин</td><td></td></tr>
<tr><td><a id="p108384"></a>20300</td><td><a id="p108385"></a><a href="https://bukva.ai/docs/konventsiya-tc10/statya-18#p100188">Статья 18</a> "процедуры общего транзита"</td><td><a id="p108386"></a>Экспорт</td><td><a id="p108387"></a>"Экспорт"</td></tr>
<tr><td><a id="p108388"></a>30300</td><td><a id="p108389"></a><a href="https://bukva.ai/docs/reglament-9522013/statya-1#p102073">Статья 254(4)(b)</a> Кодекса</td><td><a id="p108390"></a>Экспорт товаров, подлежащих конечному использованию</td><td><a id="p108391"></a>"E-U"</td></tr>
<tr><td><a id="p108392"></a>30500</td><td><a id="p108393"></a><a href="#p102830">Статья 329(7)</a></td><td><a id="p108394"></a>Запрос, чтобы таможенное учреждение, компетентное для места, в котором товары вывезены по одному транспортному договору на перевозку товаров с таможенной территории Союза, было таможенным учреждением вывоза</td><td><a id="p108395"></a>Таможенное учреждение вывоза</td></tr>
<tr><td><a id="p108396"></a>30600</td><td><a id="p108397"></a>Титул II Приложения B к Делегированному Регламенту (ЕС) 2015/2446</td><td><a id="p108398"></a>Ситуации, когда рассматриваются оборотные коносаменты "заказать заполненный бланк", в случае сводных вывозных деклараций, если сведения о грузополучателе неизвестны.</td><td><a id="p108399"></a>"Грузополучатель неизвестен"</td></tr>
<tr><td><a id="p108400"></a>30700</td><td><a id="p108401"></a>Статья 160 Делегированного Регламента (ЕС) 2015/2446</td><td><a id="p108402"></a>Запрос о наличии информационного листа INF3</td><td><a id="p108403"></a>"INF3"</td></tr>
<tr><td><a id="p108404"></a>40100</td><td><a id="p108405"></a>Статья 123 Делегированного Регламента (ЕС) 2015/2446</td><td><a id="p108406"></a>Запрос по продлению срока действия доказательства таможенного статуса товаров Союза</td><td><a id="p108407"></a>"Продление периода срока действия доказательства таможенного статуса товаров Союза"</td></tr>
<tr><td colspan="4"><a id="p108408"></a>&lt;*&gt; <a href="https://bukva.ai/docs/konventsiya-tc10/statya-1">Конвенция</a> о процедуре общего транзита от 20 мая 1987 г. (ОЖ N L 226, 13.8.1987, стр. 2).</td></tr>
</table>


<a id="p108409"></a>13 03 000 000 Подтверждающий документ

<a id="p108410"></a>12 03 002 000 Тип
<a id="p108411"></a>(a) Документы Союза или международные документы, сертификаты и разрешения, составленные в подтверждение декларации, должны быть внесены в форму посредством кода, определенного в [Титуле I](https://bukva.ai/docs/reglament-20152447/statya-350#p104416), после которого следует или идентификационный номер, или другая признанная ссылка. Список документов, сертификатов и разрешений и их соответствующие коды можно найти в базе данных TARIC.
<a id="p108412"></a>(b) Национальные документы, сертификаты и разрешения, составленные для подтверждения декларации, должны быть внесены в форму посредством кода, определенного в [Титуле I](https://bukva.ai/docs/reglament-20152447/statya-350#p104416) (Ex: 2123, 34d5), после которого может следовать либо идентификационный номер, либо другая признанная ссылка. Четыре знака представляют коды, основанные на собственной номенклатуре государства-члена ЕС.

<a id="p108413"></a>12 04 000 000 Дополнительная ссылка

<a id="p108414"></a>12 04 002 000 Тип
<a id="p108415"></a>(a) Дополнительные ссылки должны быть внесены в форму посредством кода, определенного в [Титуле I](https://bukva.ai/docs/reglament-20152447/statya-350#p104416). Список дополнительных ссылок и их соответствующие коды можно найти в базе данных TARIC.
<a id="p108416"></a>(b) Дополнительные ссылки должны быть внесены в форму посредством кода, определенного в [Титуле I](https://bukva.ai/docs/reglament-20152447/statya-350#p104416), после которого может следовать либо идентификационный номер, либо другая признанная ссылка. Четыре знака представляют коды, основанные на собственной номенклатуре государства-члена ЕС.

<a id="p108417"></a>12 05 000 000 Транспортный документ

<a id="p108418"></a>12 05 002 000 Тип
<a id="p108419"></a>Транспортный документ должен быть внесен в форму посредством кода, определенного в [Титуле I](https://bukva.ai/docs/reglament-20152447/statya-350#p104416). Список дополнительных ссылок и их соответствующие коды можно найти в базе данных TARIC.

<a id="p108420"></a>12 11 000 000 Склад

<a id="p108421"></a>12 11 002 000 Тип
<a id="p108422"></a>Знак, идентифицирующий тип склада:
<a id="p108423"></a>R - Государственный таможенный склад вида I;
<a id="p108424"></a>S - Государственный таможенный склад вида II;
<a id="p108425"></a>T - Государственный таможенный склад вида III;
<a id="p108426"></a>U - Частный таможенный склад;
<a id="p108427"></a>V - Склад хранения для временного хранения товаров;
<a id="p108428"></a>Y - Нетаможенный склад;
<a id="p108429"></a>Z - Свободная зона.

<a id="p108430"></a>13 01 000 000 Экспортер

<a id="p108431"></a>13 01 017 000 Идентификационный номер
<a id="p108432"></a>Структура уникального идентификационного номера третьей страны, который был представлен Союзу, является следующей:


| <a id="p108433"></a>Поле | <a id="p108434"></a>Содержание | <a id="p108435"></a>Формат |
| --- | --- | --- |
| <a id="p108436"></a>1 | <a id="p108437"></a>Код страны | <a id="p108438"></a>a2 |
| <a id="p108439"></a>2 | <a id="p108440"></a>Уникальный идентификационный номер в третьей стране | <a id="p108441"></a>an..15 |


<a id="p108442"></a>Код страны: Используется код страны, определенный в Титуле I для D.E. [13 01 018 020](https://bukva.ai/docs/reglament-20152447/statya-350#p104668) (Адрес в стране экспортера).

<a id="p108443"></a>13 02 000 000 Грузоотправитель

<a id="p108444"></a>13 02 028 000 Тип лица
<a id="p108445"></a>Используются следующие коды:
<a id="p108446"></a>1 - Физическое лицо
<a id="p108447"></a>2 - Юридическое лицо
<a id="p108448"></a>3 - Ассоциация лиц, которая не является юридическим лицом, но которая признана законодательством Союза или национальным законодательством как имеющая право выполнять правовые акты.

<a id="p108449"></a>12 09 029 000 Сообщение

<a id="p108450"></a>13 02 029 002 Тип
<a id="p108451"></a>Используются следующие коды:
<a id="p108452"></a>EM - электронная почта
<a id="p108453"></a>TE - телефон

<a id="p108454"></a>13 06 000 000 Представитель

<a id="p108455"></a>13 06 030 000 Статус
<a id="p108456"></a>Вставьте один из следующих кодов перед полным наименованием/именем и адресом для определения статуса представителя:
<a id="p108457"></a>2 - Представитель (прямое представительство в значении [Статьи 18(1)](https://bukva.ai/docs/reglament-9522013/statya-1#p100306) Кодекса);
<a id="p108458"></a>3 - Представитель (косвенное представительство в значении [Статьи 18(1)](https://bukva.ai/docs/reglament-9522013/statya-1#p100306) Кодекса).

<a id="p108459"></a>13 14 000 000 Дополнительный участник системы поставки

<a id="p108460"></a>13 14 031 000 Роль
<a id="p108461"></a>Могут быть продекларированы следующие лица:


| <a id="p108462"></a>Код роли | <a id="p108463"></a>Лицо | <a id="p108464"></a>Описание |
| --- | --- | --- |
| <a id="p108465"></a>CS | <a id="p108466"></a>Посредник | <a id="p108467"></a>Экспедитор, объединяющий индивидуальные мелкие грузы в одну более крупную партию (в процессе консолидации), которая направляется другому лицу, которое зеркально отражает деятельность посредника и разделяет объединенную партию на первоначальные грузы |
| <a id="p108468"></a>FW | <a id="p108469"></a>Экспедитор | <a id="p108470"></a>Лицо, осуществляющее отправление товаров |
| <a id="p108471"></a>MF | <a id="p108472"></a>Производитель | <a id="p108473"></a>Лицо, которое производит товары |
| <a id="p108474"></a>WH | <a id="p108475"></a>Владелец склада | <a id="p108476"></a>Лицо, принимающее ответственность за товары, поступившие на склад |


<a id="p108477"></a>13 15 000 00 Дополнительный декларант

<a id="p108478"></a>13 15 032 000 Тип дополнительного дела
<a id="p108479"></a>Используются следующие типы дела:


| <a id="p108480"></a>Тип | <a id="p108481"></a>Описание |
| --- | --- |
| <a id="p108482"></a>1 | <a id="p108483"></a>Дело на внутреннем уровне |
| <a id="p108484"></a>2 | <a id="p108485"></a>Дело на подвнутреннем уровне |


<a id="p108486"></a>13 16 000 000 Дополнительные фискальные ссылки

<a id="p108487"></a>13 16 031 000 Роль
<a id="p108488"></a>Могут быть продекларированы следующие лица:


| <a id="p108489"></a>Код роли | <a id="p108490"></a>Лицо | <a id="p108491"></a>Описание |
| --- | --- | --- |
| <a id="p108492"></a>FR1 | <a id="p108493"></a>Импортер | <a id="p108494"></a>Лицо или лица, назначенные или признанные ответственными за оплату налога на добавленную стоимость государством-членом ЕС импорта в соответствии со [Статьей 201](https://bukva.ai/docs/direktiva-2006112es/statya-201#p101262) Директивы 2006/112/ЕС |
| <a id="p108495"></a>FR2 | <a id="p108496"></a>Потребитель | <a id="p108497"></a>Лицо, ответственное за оплату налога на добавленную стоимость при внутрисоюзном приобретении товаров в соответствии со [Статьей 200](https://bukva.ai/docs/direktiva-2006112es/statya-200#p101260) Директивы 2006/112/ЕС |
| <a id="p108498"></a>FR3 | <a id="p108499"></a>Налоговый представитель | <a id="p108500"></a>Налоговый представитель, ответственный за оплату налога на добавленную стоимость в государстве-члене ЕС импорта, назначенный импортером |
| <a id="p108501"></a>FR4 | <a id="p108502"></a>Владелец разрешения отсроченного платежа | <a id="p108503"></a>Лицо, имеющее статус налогоплательщика, или лицо, ответственное за оплату, или другое лицо, которое получило отсрочку платежа в соответствии со [Статьей 211](https://bukva.ai/docs/direktiva-2006112es/statya-211#p101290) Директивы 2006/112/ЕС |
| <a id="p108504"></a>FR5 | <a id="p108505"></a>Поставщик (IOSS) | <a id="p108506"></a>Лицо, облагаемое налогом, использующее специальную схему удаленной торговли товарами, импортированными из третьих стран или третьих территорий, установленных в [Титуле XII Главе 6 Разделе 4](https://bukva.ai/docs/direktiva-2006112es/statya-1#p102020) Директивы 2006/112/ЕС, и владелец идентификационного номера плательщика НДС, указанный в [Статье 369q](https://bukva.ai/docs/direktiva-2006112es/statya-1#p102066) Директивы |
| <a id="p108507"></a>FR7 | <a id="p108508"></a>Налогоплательщик или лицо, обязанное платить НДС | <a id="p108509"></a>Идентификационный номер плательщика НДС или лица, обязанного платить НДС, если оплата НДС отсрочена в соответствии со [Статьей 211, вторым подпараграфом](https://bukva.ai/docs/direktiva-2006112es/statya-1#p101292) Директивы 2006/112/ЕС. |


<a id="p108510"></a>13 16 034 000 Идентификационный номер налога на добавленную стоимость
<a id="p108511"></a>Идентификационный номер налога на добавленную стоимость структурируется следующим образом:


| <a id="p108512"></a>Поле | <a id="p108513"></a>Содержание | <a id="p108514"></a>Формат |
| --- | --- | --- |
| <a id="p108515"></a>1 | <a id="p108516"></a>Идентификатор государства-члена ЕС выдачи (код ISO 3166 - alpha 2-; Греция может использовать EL) | <a id="p108517"></a>a2 |
| <a id="p108518"></a>2 | <a id="p108519"></a>Индивидуальный номер, присвоенный государством-членом ЕС для идентификации налогоплательщика, указанный в [Статье 214](https://bukva.ai/docs/direktiva-2006112es/statya-214#p101301) Директивы 2006/112/ЕС | <a id="p108520"></a>an..15 |


<a id="p108521"></a>Если товары декларируются на выпуск в свободное обращение по специальной схеме для удаленной торговли товарами, импортированными из третьих стран или третьих территорий, установленных в [Титуле XII Главы 6 Раздела 4](https://bukva.ai/docs/direktiva-2006112es/statya-1#p102020) Директивы 2006/112/ЕС, то должен быть представлен специальный номер НДС, присвоенный для использования данной схемы.

<a id="p108522"></a>14 01 000 000 Условия поставки

<a id="p108523"></a>14 01 035 000 Код ИНКОТЕРМС
<a id="p108524"></a>Вносимые коды и заявления являются следующими:


<table>
<colgroup><col width="33%"><col width="36%"><col width="31%"></colgroup>
<tr><td><a id="p108525"></a>Код Инкотермс</td><td><a id="p108526"></a>Инкотермс - ICC/ECE</td><td><a id="p108527"></a>Место, которое должно быть определено</td></tr>
<tr><td colspan="3"><a id="p108528"></a>Коды, применяемые для всех видов транспорта</td></tr>
<tr><td><a id="p108529"></a>EXW (Инкотермс 2020)</td><td><a id="p108530"></a>Франко завод</td><td><a id="p108531"></a>Названное место поставки</td></tr>
<tr><td><a id="p108532"></a>FCA (Инкотермс 2020)</td><td><a id="p108533"></a>Франко перевозчик</td><td><a id="p108534"></a>Названное место поставки</td></tr>
<tr><td><a id="p108535"></a>CPT (Инкотермс 2020)</td><td><a id="p108536"></a>Перевозка оплачена до</td><td><a id="p108537"></a>Названное место назначения</td></tr>
<tr><td><a id="p108538"></a>CIP (Инкотермс 2020)</td><td><a id="p108539"></a>Перевозка и страхование оплачены до</td><td><a id="p108540"></a>Названное место назначения</td></tr>
<tr><td><a id="p108541"></a>DPU (Инкотермс 2020)</td><td><a id="p108542"></a>Поставка в место разгрузки</td><td><a id="p108543"></a>Названное место назначения</td></tr>
<tr><td><a id="p108544"></a>DAP (Инкотермс 2020)</td><td><a id="p108545"></a>Поставка в месте</td><td><a id="p108546"></a>Названное место назначения</td></tr>
<tr><td><a id="p108547"></a>DDP (Инкотермс 2020)</td><td><a id="p108548"></a>Поставка с оплатой пошлин</td><td><a id="p108549"></a>Названное место назначения</td></tr>
<tr><td><a id="p108550"></a>DAT (Инкотермс 2020)</td><td><a id="p108551"></a>Поставка на терминале</td><td><a id="p108552"></a>Названные терминал в порту или в месте назначения</td></tr>
<tr><td colspan="3"><a id="p108553"></a>Коды, применяемые для морского и внутреннего водного транспорта</td></tr>
<tr><td><a id="p108554"></a>FAS (Инкотермс 2020)</td><td><a id="p108555"></a>Свободно вдоль борта судна</td><td><a id="p108556"></a>Названный порт отгрузки</td></tr>
<tr><td><a id="p108557"></a>FOB (Инкотермс 2020)</td><td><a id="p108558"></a>Свободно на борту</td><td><a id="p108559"></a>Названный порт отгрузки</td></tr>
<tr><td><a id="p108560"></a>CFR (Инкотермс 2020)</td><td><a id="p108561"></a>Стоимость и фрахт</td><td><a id="p108562"></a>Названный порт назначения</td></tr>
<tr><td><a id="p108563"></a>CIF (Инкотермс 2020)</td><td><a id="p108564"></a>Стоимость, страхование и фрахт</td><td><a id="p108565"></a>Названный порт назначения</td></tr>
<tr><td><a id="p108566"></a>XXX</td><td><a id="p108567"></a>Другие условия поставки, кроме условий, указанных выше</td><td><a id="p108568"></a>Описание условий поставки, данное в договоре</td></tr>
</table>


<a id="p108569"></a>14 02 000 000 Транспортные сборы
<a id="p108570"></a>Должны использоваться следующие коды:
<a id="p108571"></a>A - Оплата наличными
<a id="p108572"></a>B - Оплата кредитной картой
<a id="p108573"></a>C - Оплата чеком
<a id="p108574"></a>D - Другой (например, прямой дебет денежного счета)
<a id="p108575"></a>H - Электронный перевод средств
<a id="p108576"></a>Y - Владелец счета с перевозчиком
<a id="p108577"></a>Z - Без предварительной оплаты

<a id="p108578"></a>14 03 000 000 Пошлины и налоги

<a id="p108579"></a>14 03 039 000 Вид налога
<a id="p108580"></a>Применяемые коды даны ниже:


| <a id="p108581"></a>A00 | <a id="p108582"></a>Импортная пошлина |
| --- | --- |
| <a id="p108583"></a>A30 | <a id="p108584"></a>Окончательные антидемпинговые пошлины |
| <a id="p108585"></a>A35 | <a id="p108586"></a>Предварительные антидемпинговые пошлины |
| <a id="p108587"></a>A40 | <a id="p108588"></a>Окончательные антидемпинговые пошлины |
| <a id="p108589"></a>A45 | <a id="p108590"></a>Предварительные компенсационные пошлины |
| <a id="p108591"></a>B00 | <a id="p108592"></a>НДС |
| <a id="p108593"></a>C00 | <a id="p108594"></a>Экспортная пошлина |
| <a id="p108595"></a>E00 | <a id="p108596"></a>Пошлины, собранные от имени других стран |


<a id="p108597"></a>14 03 038 000 Способ оплаты
<a id="p108598"></a>Следующие коды могут использоваться государствами-членами ЕС:
<a id="p108599"></a>A - Оплата наличными
<a id="p108600"></a>B - Оплата кредитной картой
<a id="p108601"></a>C - Оплата чеком
<a id="p108602"></a>D - Другой (например, прямой дебет денежного счета агента)
<a id="p108603"></a>E - Отсроченный или отложенный платеж
<a id="p108604"></a>G - Отложенный платеж - система НДС ([Статья 211](https://bukva.ai/docs/direktiva-2006112es/statya-211#p101290) Директивы 2006/112/ЕС)
<a id="p108605"></a>H - Электронный перевод средств
<a id="p108606"></a>J - Оплата через почтовое отделение (почтовые товары) или другой государственный сектор или правительственный департамент
<a id="p108607"></a>K - Акцизный кредит или скидка
<a id="p108608"></a>O - Гарантия, поданная Агентством по оказанию помощи
<a id="p108609"></a>P - С кассового счета агента
<a id="p108610"></a>R - Гарантия оплачиваемой суммы
<a id="p108611"></a>S - Индивидуальный гарантийный счет
<a id="p108612"></a>T - С гарантийного счета агента
<a id="p108613"></a>U - Из гарантии агента - постоянный орган
<a id="p108614"></a>V - Из гарантии агента - индивидуальный орган

<a id="p108615"></a>14 04 000 000 Надбавки и вычеты
<a id="p108616"></a>Надбавки (Определенные согласно [Статьям 70](https://bukva.ai/docs/reglament-9522013/statya-70#p100720) и [71](https://bukva.ai/docs/reglament-9522013/statya-71#p100732) Кодекса):
<a id="p108617"></a>AB: Комиссионные и брокерская комиссия, кроме комиссионных за покупку
<a id="p108618"></a>AD: Контейнеры и упаковка
<a id="p108619"></a>AE: Материалы, компоненты, части и подобные предметы, включенные в импортированные товары
<a id="p108620"></a>AF: Инструменты, штампы, формы и подобные предметы, использованные в производстве импортированных товаров
<a id="p108621"></a>AG: Материалы, потребленные в производстве импортированных товаров
<a id="p108622"></a>AH: Инженерно-конструкторские работы, разработки, художественные работы, проектные работы, а также планы и наброски, выполненные в других местах, кроме Европейского Союза, и необходимые для производства импортированных товаров
<a id="p108623"></a>AI: Роялти и сборы за лицензию
<a id="p108624"></a>AJ: Доходы от последующей перепродажи, распоряжения или использования, причитающиеся продавцу
<a id="p108625"></a>AK: Транспортные расходы, сборы на погрузку и обработку и затраты на страхование до места ввоза в Европейский Союз
<a id="p108626"></a>AL: Косвенные платежи и другие выплаты ([Статья 70](https://bukva.ai/docs/reglament-9522013/statya-70#p100720) Кодекса)
<a id="p108627"></a>AN: Надбавки на основании решения, выданного в соответствии со Статьей 71 Делегированного Регламента (ЕС) 2015/2446
<a id="p108628"></a>Вычеты (Определенные согласно [Статье 72](https://bukva.ai/docs/reglament-9522013/statya-72#p100751) Кодекса):
<a id="p108629"></a>BA: Затраты на перевозку после прибытия в место ввоза
<a id="p108630"></a>BB: Затраты на строительство, сборку, монтаж, техническое обслуживание или техническую помощь, выполненные после импорта
<a id="p108631"></a>BC: Импортные пошлины или другие сборы, выплачиваемые в Союзе по причине импорта или продажи товаров
<a id="p108632"></a>BD: Проценты
<a id="p108633"></a>BE: Сборы за право воспроизводить импортированные товары в Европейском Союзе
<a id="p108634"></a>BF: Комиссионные за покупку
<a id="p108635"></a>BG: Вычеты на основании решения, выданного в соответствии со Статьей 71 Делегированного Регламента (ЕС) 2015/2446

<a id="p108636"></a>14 07 000 000 Показатели оценки
<a id="p108637"></a>Код состоит из четырех знаков, каждый из которых либо "0", либо "1".
<a id="p108638"></a>Каждая цифра "1" или "0" отражает, является ли индикатор оценки релевантным для оценки соответствующих товаров или нет.
<a id="p108639"></a>1-й знак: Отношение сторон, влияет ли цена или нет.
<a id="p108640"></a>2-й знак: Ограничения распоряжения или использования товаров покупателем в соответствии со [Статьей 70(3)(a)](https://bukva.ai/docs/reglament-9522013/statya-1#p100725) Кодекса
<a id="p108641"></a>3-й знак: Продажа или цена зависят от условий или от рассмотрения в соответствии со [Статьей 70(3)(b)](https://bukva.ai/docs/reglament-9522013/statya-1#p100729) Кодекса
<a id="p108642"></a>4-й знак: Продажа определяется соглашением, согласно которому часть доходов от последующей перепродажи, распоряжения или использования причитается прямо или косвенно продавцу
<a id="p108643"></a>Пример:
<a id="p108644"></a>Для товаров, зависящих от отношения сторон, но не относящихся ни одной из ситуаций, определенных под 2-м, 3-м и 4-м знаком, можно использовать комбинацию кода "1000".

<a id="p108645"></a>14 10 000 000 Способ оценки
<a id="p108646"></a>Положения, используемые для определения таможенной стоимости импортированных товаров, должны быть кодированы следующим образом:


| <a id="p108647"></a>Код | <a id="p108648"></a>Соответствующая Статья [Кодекса](https://bukva.ai/docs/reglament-9522013/statya-1) | <a id="p108649"></a>Способ |
| --- | --- | --- |
| <a id="p108650"></a>1 | <a id="p108651"></a>[70](https://bukva.ai/docs/reglament-9522013/statya-70#p100720) | <a id="p108652"></a>Стоимость сделки с импортированными товарами |
| <a id="p108653"></a>2 | <a id="p108654"></a>[74(2)a)](https://bukva.ai/docs/reglament-9522013/statya-1#p100773) | <a id="p108655"></a>Стоимость сделки с идентичными товарами |
| <a id="p108656"></a>3 | <a id="p108657"></a>[74(2)b)](https://bukva.ai/docs/reglament-9522013/statya-1#p100774) | <a id="p108658"></a>Стоимость сделки с подобными товарами |
| <a id="p108659"></a>4 | <a id="p108660"></a>[74(2)c)](https://bukva.ai/docs/reglament-9522013/statya-1#p100775) | <a id="p108661"></a>Метод вычитания стоимости |
| <a id="p108662"></a>5 | <a id="p108663"></a>[74(2)d)](https://bukva.ai/docs/reglament-9522013/statya-1#p100776) | <a id="p108664"></a>Способ расчетного значения |
| <a id="p108665"></a>6 | <a id="p108666"></a>[74(3)](https://bukva.ai/docs/reglament-9522013/statya-1#p100780) | <a id="p108667"></a>Стоимость на основании имеющихся данных ("резервный" метод) |


<a id="p108668"></a>14 11 000 000 Преференция
<a id="p108669"></a>Данная информация включает в себя трехзначные коды, состоящие из однозначного компонента из [пункта 1](https://bukva.ai/docs/reglament-20152447/statya-350#p108671)) и двузначного компонента из [пункта 2](https://bukva.ai/docs/reglament-20152447/statya-350#p108676)).
<a id="p108670"></a>Соответствующие коды даны ниже:
<a id="p108671"></a>(1). Первый знак кода:
<a id="p108672"></a>1 - Тарифное соглашение erga omnes
<a id="p108673"></a>2 - Генеральная система преференций (GSP)
<a id="p108674"></a>3 - Другие тарифные преференции, кроме тех, которые указаны под [кодом 2](https://bukva.ai/docs/reglament-20152447/statya-350#p108673)
<a id="p108675"></a>4 - Таможенные пошлины согласно положениям соглашений таможенного союза, заключенных Европейским Союзом
<a id="p108676"></a>(2) Следующие два знака кода
<a id="p108677"></a>00 - Ничего из следующего
<a id="p108678"></a>10 - Приостановка тарифов
<a id="p108679"></a>18 - Приостановка тарифов с сертификатом, подтверждающим специальный характер продукции
<a id="p108680"></a>19 - Временная приостановка для продукции, импортированной с сертификатом летной пригодности формы 1 или эквивалентным сертификатом
<a id="p108681"></a>20 - Тарифная квота <*>

<a id="p108682"></a>

---

<a id="p108683"></a><*> Если запрошенная тарифная квота исчерпана, то государства-члены ЕС могут разрешить запрос действия для любой другой существующей преференции.

<a id="p108684"></a>25 - Тарифная квота с сертификатом, подтверждающим специальный характер продукции <*>
<a id="p108685"></a>28 - Тарифная квота после внешней переработки <*>
<a id="p108686"></a>50 - Сертификат, подтверждающий специальный характер продукции

<a id="p108687"></a>16 15 000 000 Местонахождение товаров
<a id="p108688"></a>Используйте код GEONOM, указанный во [вводной части 13, номер 3](https://bukva.ai/docs/reglament-20152447/statya-350#p104388).

<a id="p108689"></a>16 15 045 000 Тип местонахождения
<a id="p108690"></a>Для видов местонахождения используйте коды, определенные ниже:
<a id="p108691"></a>A - Назначенное место
<a id="p108692"></a>B - Разрешенное место
<a id="p108693"></a>C - Одобренное место
<a id="p108694"></a>D - Прочее

<a id="p108695"></a>16 15 046 000 000 Классификатор идентификации
<a id="p108696"></a>Для идентификации места используйте один из идентификаторов, указанных ниже:


| <a id="p108697"></a>Определитель | <a id="p108698"></a>Идентификатор | <a id="p108699"></a>Описание |
| --- | --- | --- |
| <a id="p108700"></a>T | <a id="p108701"></a>Почтовый индекс | <a id="p108702"></a>Используйте почтовый индекс с номером дома или без него для рассматриваемого места |
| <a id="p108703"></a>U | <a id="p108704"></a>UN/LOCODE | <a id="p108705"></a>Используйте коды UN/LOCODE, указанные во [вводной части 13 номер 4](https://bukva.ai/docs/reglament-20152447/statya-350#p104392) |
| <a id="p108706"></a>V | <a id="p108707"></a>Идентификатор таможенного учреждения | <a id="p108708"></a>Используйте коды, определенные для D.E. [17 01 000 000](https://bukva.ai/docs/reglament-20152447/statya-350#p108726) Таможенное учреждение вывоза |
| <a id="p108709"></a>W | <a id="p108710"></a>Координаты GNSS | <a id="p108711"></a>Десятичные градусы с отрицательными значениями для юга и запада.<br>Примеры: 44.424896°/8.774792° или 50.838068°/4.381508° |
| <a id="p108712"></a>X | <a id="p108713"></a>Номер EORI | <a id="p108714"></a>Используйте идентификационный номер, определенный в описании для D.E. [13 01 017 000](https://bukva.ai/docs/reglament-20152447/statya-350#p108431) Идентификационный номер экспортера. Если субъект экономической деятельности имеет несколько предприятий, номер EORI должен быть заполнен идентификатором, уникальным для этого места. |
| <a id="p108715"></a>Y | <a id="p108716"></a>Номер разрешения | <a id="p108717"></a>Введите номер разрешения рассматриваемого места, т.е. склад, в котором товары могут быть досмотрены. Если разрешение касается нескольких предприятий, номер разрешения должен быть заполнен идентификатором, уникальным для этого места. |
| <a id="p108718"></a>Z | <a id="p108719"></a>Адрес | <a id="p108720"></a>Введите адрес рассматриваемого места. |


<a id="p108721"></a>Если код "X" (номер EORI) или "Y" (номер разрешения) используется для идентификации места, и существует несколько мест, связанных с номером EORI или с номером разрешения, может использоваться дополнительный идентификатор, позволяющий точно определить место.

<a id="p108722"></a>16 17 000 000 Обязательный журнал
<a id="p108723"></a>Соответствующие коды даны ниже:
<a id="p108724"></a>0 - Товары не перемещаются из таможенного учреждения отправления в таможенное учреждение места назначения согласно экономически обоснованному журналу
<a id="p108725"></a>1 - Товары будут перемещаться из таможенного учреждения отправления в таможенное учреждение места назначения согласно экономически обоснованному журналу

<a id="p108726"></a>17 01 000 000 Таможенное учреждение вывоза

<a id="p108727"></a>17 01 001 000 Исходящий номер
<a id="p108728"></a>Используйте (an8) код, структурированный следующим образом:
- <a id="p108729"></a>первые два знака (a2) служат для идентификации страны посредством кода GEONOM, указанного во [вводной части 13, номер 3](https://bukva.ai/docs/reglament-20152447/statya-350#p104388);
- <a id="p108730"></a>следующие шесть знаков (an6) относятся к этому учреждению в указанной стране. Предполагается, что должна быть принята следующая структура:
<a id="p108731"></a>Первые три знака (an3) могут быть заполнены названием места UN/LOCODE, а последние три знака - национальным буквенно-цифровым подразделением (an3). Если это подразделение не используется, должно быть внесены знаки "000".
<a id="p108732"></a>Показатель контейнера
<a id="p108733"></a>Соответствующие коды даны ниже:


| <a id="p108734"></a>0 | <a id="p108735"></a>Товары не перевозятся в контейнерах |
| --- | --- |
| <a id="p108736"></a>1 | <a id="p108737"></a>Товары перевозятся в контейнерах |


<a id="p108738"></a>19 03 000 000 Вид транспорта на границе
<a id="p108739"></a>Применяемые коды даны ниже:


| <a id="p108740"></a>Код | <a id="p108741"></a>Описание |
| --- | --- |
| <a id="p108742"></a>1 | <a id="p108743"></a>Морской транспорт |
| <a id="p108744"></a>2 | <a id="p108745"></a>Железнодорожный транспорт |
| <a id="p108746"></a>3 | <a id="p108747"></a>Дорожный транспорт |
| <a id="p108748"></a>4 | <a id="p108749"></a>Воздушный транспорт |
| <a id="p108750"></a>5 | <a id="p108751"></a>Почта (Активный вид транспорта не известен) |
| <a id="p108752"></a>7 | <a id="p108753"></a>Смешанные транспортные установки |
| <a id="p108754"></a>8 | <a id="p108755"></a>Внутренний водный транспорт |
| <a id="p108756"></a>9 | <a id="p108757"></a>Вид неизвестен (т.е. собственная двигательная установка) |


<a id="p108758"></a>19 15 000 000 Транспортное средство в месте отправления

<a id="p108759"></a>19 05 061 000 Тип идентификации
<a id="p108760"></a>Применяемые коды даны ниже:


| <a id="p108761"></a>Код | <a id="p108762"></a>Описание |
| --- | --- |
| <a id="p108763"></a>10 | <a id="p108764"></a>Идентификационный номер судна Международной морской организации (IMO) |
| <a id="p108765"></a>11 | <a id="p108766"></a>Название морского судна |
| <a id="p108767"></a>20 | <a id="p108768"></a>Номер вагона |
| <a id="p108769"></a>21 | <a id="p108770"></a>Номер поезда |
| <a id="p108771"></a>30 | <a id="p108772"></a>Регистрационный номер дорожного транспортного средства |
| <a id="p108773"></a>40 | <a id="p108774"></a>Номер рейса Международной организации воздушного транспорта (IATA) |
| <a id="p108775"></a>41 | <a id="p108776"></a>Регистрационный номер воздушного судна |
| <a id="p108777"></a>80 | <a id="p108778"></a>Идентификационный номер Европейского судна (код ENI) |
| <a id="p108779"></a>81 | <a id="p108780"></a>Название судна внутреннего водного транспорта |


<a id="p108781"></a>19 07 000 000 Транспортное оборудование

<a id="p108782"></a>19 07 064 000 Размер контейнера и тип идентификации
<a id="p108783"></a>Используются следующие коды:


| <a id="p108784"></a>Код | <a id="p108785"></a>Описание |
| --- | --- |
| <a id="p108786"></a>1 | <a id="p108787"></a>Покрытый резервуар |
| <a id="p108788"></a>2 | <a id="p108789"></a>Резервуар с эпоксидным покрытием |
| <a id="p108790"></a>6 | <a id="p108791"></a>Герметичный резервуар |
| <a id="p108792"></a>7 | <a id="p108793"></a>Резервуар-рефрижератор |
| <a id="p108794"></a>9 | <a id="p108795"></a>Резервуар из нержавеющей стали |
| <a id="p108796"></a>10 | <a id="p108797"></a>Неработающий рефрижераторный контейнер 40 футов |
| <a id="p108798"></a>12 | <a id="p108799"></a>Европаллета - 80 x 120 см |
| <a id="p108800"></a>13 | <a id="p108801"></a>Скандинавская паллета - 100 x 120 см |
| <a id="p108802"></a>14 | <a id="p108803"></a>Прицеп |
| <a id="p108804"></a>15 | <a id="p108805"></a>Неработающий рефрижераторный контейнер 20 футов |
| <a id="p108806"></a>16 | <a id="p108807"></a>Сменяемая паллета |
| <a id="p108808"></a>17 | <a id="p108809"></a>Полуприцеп |
| <a id="p108810"></a>18 | <a id="p108811"></a>Контейнер для жидких грузов 20 футов |
| <a id="p108812"></a>19 | <a id="p108813"></a>Контейнер для жидких грузов 30 футов |
| <a id="p108814"></a>20 | <a id="p108815"></a>Контейнер для жидких грузов 40 футов |
| <a id="p108816"></a>21 | <a id="p108817"></a>Контейнер IC 20 футов, принадлежащий InterContainer, дочернему предприятию Европейских железных дорог |
| <a id="p108818"></a>22 | <a id="p108819"></a>Контейнер IC 30 футов, принадлежащий InterContainer, дочернему предприятию Европейских железных дорог |
| <a id="p108820"></a>23 | <a id="p108821"></a>Контейнер IC 40 футов, принадлежащий InterContainer, дочернему предприятию Европейских железных дорог |
| <a id="p108822"></a>24 | <a id="p108823"></a>Резервуар - рефрижератор 20 футов |
| <a id="p108824"></a>25 | <a id="p108825"></a>Резервуар - рефрижератор 30 футов |
| <a id="p108826"></a>26 | <a id="p108827"></a>Резервуар - рефрижератор 40 футов |
| <a id="p108828"></a>27 | <a id="p108829"></a>Резервуар-контейнер IC 20 футов, принадлежащий InterContainer, дочернему предприятию Европейских железных дорог |
| <a id="p108830"></a>28 | <a id="p108831"></a>Резервуар-контейнер IC 30 футов, принадлежащий InterContainer, дочернему предприятию Европейских железных дорог |
| <a id="p108832"></a>29 | <a id="p108833"></a>Резервуар-контейнер IC 40 футов, принадлежащий InterContainer, дочернему предприятию Европейских железных дорог |
| <a id="p108834"></a>30 | <a id="p108835"></a>Рефрижератор-резервуар IC 20 футов, принадлежащий InterContainer, дочернему предприятию Европейских железных дорог |
| <a id="p108836"></a>31 | <a id="p108837"></a>Контейнер с контролируемой температурой 30 футов |
| <a id="p108838"></a>32 | <a id="p108839"></a>Рефрижератор-резервуар IC 40 футов, принадлежащий InterContainer, дочернему предприятию Европейских железных дорог |
| <a id="p108840"></a>33 | <a id="p108841"></a>Подвижной корпус длиной менее 6,15 метров |
| <a id="p108842"></a>34 | <a id="p108843"></a>Подвижной корпус длиной от 6,15 до 7,82 метров |
| <a id="p108844"></a>35 | <a id="p108845"></a>Подвижной корпус длиной от 7,82 до 9,15 метров |
| <a id="p108846"></a>36 | <a id="p108847"></a>Подвижной корпус длиной от 9,15 до 10,90 метров |
| <a id="p108848"></a>37 | <a id="p108849"></a>Подвижной корпус длиной от 10,90 до 13,75 метров |
| <a id="p108850"></a>38 | <a id="p108851"></a>Тара для перевозки |
| <a id="p108852"></a>39 | <a id="p108853"></a>Контейнер с контролируемой температурой 20 футов |
| <a id="p108854"></a>40 | <a id="p108855"></a>Контейнер с контролируемой температурой 40 футов |
| <a id="p108856"></a>41 | <a id="p108857"></a>Неработающий рефрижераторный контейнер 30 футов |
| <a id="p108858"></a>42 | <a id="p108859"></a>Двойные прицепы |
| <a id="p108860"></a>43 | <a id="p108861"></a>Контейнер IL 20 футов (открытый верх) |
| <a id="p108862"></a>44 | <a id="p108863"></a>Контейнер IL 20 футов (закрытый верх) |
| <a id="p108864"></a>45 | <a id="p108865"></a>Контейнер IL 40 футов (закрытый верх) |


<a id="p108866"></a>19 07 0065 000 Состояние упакованного контейнера
<a id="p108867"></a>Используются следующие коды:


| <a id="p108868"></a>Код | <a id="p108869"></a>Описание | <a id="p108870"></a>Значение |
| --- | --- | --- |
| <a id="p108871"></a>A | <a id="p108872"></a>Пустой | <a id="p108873"></a>Указывает, что контейнер пустой. |
| <a id="p108874"></a>B | <a id="p108875"></a>Непустой | <a id="p108876"></a>Указывает, что контейнер не пустой. |


<a id="p108877"></a>19 07 066 000 Код вида поставщика оборудования
<a id="p108878"></a>Используются следующие коды:


| <a id="p108879"></a>Код | <a id="p108880"></a>Описание |
| --- | --- |
| <a id="p108881"></a>1 | <a id="p108882"></a>Поставлено грузоотправителем |
| <a id="p108883"></a>2 | <a id="p108884"></a>Поставлено перевозчиком |


<a id="p108885"></a>99 02 000 000 Вид гарантии
<a id="p108886"></a>Применяемые коды даны ниже:


<table>
<colgroup><col width="7%"><col width="93%"></colgroup>
<tr><td><a id="p108887"></a>Код</td><td><a id="p108888"></a>Описание</td></tr>
<tr><td><a id="p108889"></a>0</td><td><a id="p108890"></a>Для отказа от гарантии (<a href="https://bukva.ai/docs/reglament-9522013/statya-1#p100949">Статья 95(2)</a> Кодекса)</td></tr>
<tr><td><a id="p108891"></a>1</td><td><a id="p108892"></a>Для полной гарантии (<a href="https://bukva.ai/docs/reglament-9522013/statya-1#p100906">Статья 89(5)</a> Кодекса)</td></tr>
<tr><td><a id="p108893"></a>2</td><td><a id="p108894"></a>Для индивидуальной гарантии в форме обязательства гаранта (<a href="https://bukva.ai/docs/reglament-9522013/statya-1#p100929">Статья 92(1)(b)</a> Кодекса)</td></tr>
<tr><td><a id="p108895"></a>3</td><td><a id="p108896"></a>Для индивидуальной гарантии наличными или другим средством платежа, признанным таможенными органами в качестве эквивалентного вкладу наличными, выполненному в евро или в валюте государства-члена ЕС, в котором требуется гарантия (<a href="https://bukva.ai/docs/reglament-9522013/statya-1#p100928">Статья 92(1)(a)</a> Кодекса)</td></tr>
<tr><td><a id="p108897"></a>4</td><td><a id="p108898"></a>Для индивидуальной гарантии в форме расписок (<a href="https://bukva.ai/docs/reglament-9522013/statya-1#p100929">Статья 92(1)(b)</a> Кодекса и <a href="#p101484">Статья 160</a>)</td></tr>
<tr><td><a id="p108899"></a>5</td><td><a id="p108900"></a>Для отказа от гарантии, если сумма импортной или экспортной пошлины, которая должна быть обеспечена, не превышает предела статистической стоимости для деклараций, указанных в соответствии со Статьей 3(4) Регламента (ЕС) 471/2009 Европейского Парламента и Совета ЕС <a href="#p108923">&lt;*&gt;</a> (<a href="https://bukva.ai/docs/reglament-9522013/statya-1#p100914">Статья 89(9)</a> Кодекса)</td></tr>
<tr><td><a id="p108901"></a>8</td><td><a id="p108902"></a>Для гарантии, не требуемой для отдельных государственных органов (<a href="https://bukva.ai/docs/reglament-9522013/statya-1#p100908">Статья 89(7)</a> Кодекса)</td></tr>
<tr><td><a id="p108903"></a>B</td><td><a id="p108904"></a>Для гарантии, предоставленной для товаров, отправленных согласно процедуре TIR</td></tr>
<tr><td><a id="p108905"></a>R</td><td><a id="p108906"></a>Для гарантии, не требующейся для товаров, перевозимых по Рейну, водным путям Рейна, Дунаю или водным путям Дуная (<a href="https://bukva.ai/docs/reglament-9522013/statya-1#p100910">Статья 89(8)(a)</a> Кодекса)</td></tr>
<tr><td><a id="p108907"></a>C</td><td><a id="p108908"></a>Для гарантии, не требующейся для товаров, перевозимых на стационарных транспортных установках (<a href="https://bukva.ai/docs/reglament-9522013/statya-1#p100911">Статья 89(8)(b)</a> Кодекса)</td></tr>
<tr><td><a id="p108909"></a>D</td><td><a id="p108910"></a>Для гарантии, не требующейся для товаров, помещенных на процедуру временного допуска в соответствии со Статьей 81(a) Делегированного Регламента (ЕС) 2015/2446 (<a href="https://bukva.ai/docs/reglament-9522013/statya-1#p100912">Статья 89(8)(c)</a> Кодекса)</td></tr>
<tr><td><a id="p108911"></a>E</td><td><a id="p108912"></a>Для гарантии, не требующейся для товаров, помещенных на процедуру временного допуска в соответствии со Статьей 81(b) Делегированного Регламента (ЕС) 2015/2446 (<a href="https://bukva.ai/docs/reglament-9522013/statya-1#p100912">Статья 89(8)(c)</a> Кодекса)</td></tr>
<tr><td><a id="p108913"></a>F</td><td><a id="p108914"></a>Для гарантии, не требующейся для товаров, помещенных на процедуру временного допуска в соответствии со Статьей 81(c) Делегированного Регламента (ЕС) 2015/2446 (<a href="https://bukva.ai/docs/reglament-9522013/statya-1#p100912">Статья 89(8)(c)</a> Кодекса)</td></tr>
<tr><td><a id="p108915"></a>G</td><td><a id="p108916"></a>Для гарантии, не требующейся для товаров, помещенных на процедуру временного допуска в соответствии со Статьей 81(d) Делегированного Регламента (ЕС) 2015/2446 (<a href="https://bukva.ai/docs/reglament-9522013/statya-1#p100912">Статья 89(8)(c)</a> Кодекса)</td></tr>
<tr><td><a id="p108917"></a>H</td><td><a id="p108918"></a>Для гарантии, не требующейся для товаров, помещенных на транзитную процедуру Союза в соответствии со <a href="https://bukva.ai/docs/reglament-9522013/statya-1#p100913">Статьей 89(8)(d)</a> Кодекса</td></tr>
<tr><td><a id="p108919"></a>I</td><td><a id="p108920"></a>Для индивидуальной гарантии в другой форме, которая предусматривает, что будет выплачено эквивалентное обеспечение указанной суммы импортной или экспортной пошлины, соответствующей таможенному долгу и другим сборам (<a href="https://bukva.ai/docs/reglament-9522013/statya-1#p100930">Статья 92(1)(c)</a> Кодекса)</td></tr>
<tr><td><a id="p108921"></a>J</td><td><a id="p108922"></a>Гарантия, не требующаяся для поездки между таможенным учреждением места отправления и таможенным учреждением транзита - <a href="https://bukva.ai/docs/konventsiya-tc10/statya-10#p100120">Статья 10(2)(b)</a> Конвенции от 20 мая 1987 г. об общей процедуре транзита</td></tr>
<tr><td colspan="2"><a id="p108923"></a>&lt;*&gt; Регламент (ЕС) 471/2009 Европейского Парламента и Совета ЕС от 6 мая 2009 г. о статистике Сообщества в отношении внешней торговли со странами, не являющимися членами ЕС и об отмене Регламента (ЕС) 1172/95 Совета ЕС (ОЖ N L 152, 16.6.2009, стр. 23).</td></tr>
</table>


<a id="p108924"></a>**ТИТУЛ III. ЛИНГВИСТИЧЕСКИЕ ССЫЛКИ И ИХ КОДЫ**

<a id="p108925"></a>Таблица лингвистических ссылок и их кодов


| <a id="p108926"></a>Лингвистические ссылки | <a id="p108927"></a>Коды |
| --- | --- |
| <a id="p108928"></a>- BG Ограничена валидност<br>- CS Omezená platnost<br>- DA Begrænset gyldighed<br>- DE Beschränkte Geltung<br>- EE Piiratud kehtivus<br>- EL $\iota\sigma\chi\text{ύ}\varsigma$ $\Pi\epsilon\rho\iota o\rho\iota\sigma\mu\text{έ}\nu\eta$<br>- ES Validez limitada<br>- FR limitée Validité<br>- HR Ogranièena valjanost<br>- IT Validità limitata<br>- LV derîgums Ierobežots<br>- LT Galiojimas apribotas<br>- HU érvényû Korlátozott<br>- MT Validità limitata<br>- NL Beperkte geldigheid<br>- PL Ograniczona $wa¿noœæ$<br>- PT Validade limitada<br>- RO Validitate limitatã<br>- SL Omejena veljavnost<br>- SK Obmedzená platnost'<br>- FI Voimassa rajoitetusti<br>- SV Begränsad giltighet<br>- EN Limited validity | <a id="p108929"></a>Ограниченное действие - 99200 |
| <a id="p108930"></a>- BG Освободено<br>- CS Osvobození<br>- DA Fritaget<br>- DE Befreiung<br>- EE Loobutud<br>- EL $\text{Α}\pi\alpha\lambda\lambda\alpha\gamma\text{ή}$<br>- ES Dispensa<br>- FR Dispense<br>- HR Osloboðeno<br>- IT Dispensa<br>- LV Derîgs bez zîmoga<br>- LT Leista neplombuoti<br>- HU Mentesség<br>- MT Tne - h - hija<br>- NL Vrijstelling<br>- PL Zwolnienie<br>- PT Dispensa<br>- RO Dispensã<br>- SL Opustitev<br>- SK Upustenie<br>- FI Vapautettu<br>- SV Befrielse<br>- EN Waiver | <a id="p108931"></a>Отказ - 99201 |
| <a id="p108932"></a>- BG Алтернативно доказателство<br>- CS dùkaz Alternativní<br>- DA Alternativt bevis<br>- DE Alternativnachweis<br>- EE Alternatiivsed tõendid<br>- EL $\alpha\pi\text{ό}\delta\epsilon\iota\xi\eta$ $\text{Ε}\nu\alpha\lambda\lambda\alpha\kappa\tau\iota\kappa\text{ή}$<br>- ES Prueba alternative<br>- FR Preuve alternative<br>- HR Alternativni dokaz<br>- IT Prova alternativa<br>- LV pierâdîjums Alternatîvs<br>- LT Alternatyvusis árodymas<br>- HU igazolás Alternatív<br>- MT Prova alternattiva<br>- NL Alternatief bewijs<br>- PL Alternatywny dowód<br>- PT Prova alternativa<br>- RO alternativã Probã<br>- SL Alternativno dokazilo<br>- SK dôkaz Alternatívny<br>- FI Vaihtoehtoinen todiste<br>- SV Alternativt bevis<br>- EN Alternative proof | <a id="p108933"></a>Альтернативное доказательство - 99202 |
| <a id="p108934"></a>- BG Различия: митническо учреждение, където са представени стоките...... (наименование и държава)<br>- CS Nesrovnalosti: ъøad , kterému bylo zboží pøedloženo ...... ( název a zemì )<br>- DA Forskelle: det sted, hvor varerne blev frembudt...... (navn og land)<br>- DE Unstimmigkeiten: Stelle, bei der die Gestellung erfolgte...... (Name und Land)<br>- EE Erinevused: asutus, kuhu kaup esitati....... (nimi ja riik)<br>- EL $\Delta\iota\alpha\phi o\rho\text{έ}\varsigma$ : $\epsilon\mu\pi o\rho\epsilon\text{ύ}\mu\alpha\tau\alpha$ $\pi\rho o\sigma\kappa o\mu\iota\sigma\theta\text{έ}\nu\tau\alpha$ $\sigma\tau o$ $\tau\epsilon\lambda\omega\nu\epsilon\text{ί}o$ ...... ( $Ό\nu o\mu\alpha$ $\kappa\alpha\iota$ $\chi\text{ώ}\rho\alpha$ )<br>- ES Diferencias: mercancías presentadas en la oficina...... (nombre y país )<br>- FR Différences : marchandises présentées au bureau...... (nom et pays)<br>- HR Razlike: carinarnica kojoj je roba podnesena... (naziv i zemlja)<br>- IT Differenze: ufficio al quale sono state presentate le merci...... (nome e paese)<br>- LV Atšíirîbas : muitas iestâde , kurâ preces tika uzrâdîtas ...... (nosaukums un valsts)<br>- LT Skirtumai: ástaiga , kuriai pateiktos prekës ...... (pavadinimas ir valstybë )<br>- HU Eltérések : hivatal, ahol az áruk bemutatása megtörtént ...... ( név és ország )<br>- MT Differenzi: $uffi\dot{c}\dot{c}ju$ fejn $l - o\dot{g}\dot{g}etti$ kienu $ppre¿entati$ ...... (isem u $pajji¿$ )<br>- NL Verschillen: kantoor waar de goederen zijn aangebracht...... (naam en land)<br>- PL Niezgodnoœci : urz¹d , w którym przedstawiono towar...... (nazwa i kraj)<br>- PT Diferenças : mercadorias apresentadas na estãncia ...... (nome e país )<br>- RO Diferenþe : mãrfuri prezentate la biroul vamal...... (nume ºi þara )<br>- SL Razlike: urad, pri katerem je bilo blago predloženo ...... (naziv in država )<br>- SK Rozdiely: úrad , ktorému bol tovar predložený ...... ( názov a krajina).<br>- FI Muutos: toimipaikka, jossa tavarat esitetty...... (nimi ja maa)<br>- SV Avvikelse: tullkontor där varorna anmäldes ...... (namn och land)<br>- EN Differences: office where goods were presented...... (name and country) | <a id="p108935"></a>Различия: учреждение, в котором товары были представлены... (название и страна) - 99203 |
| <a id="p108936"></a>- BG Извеждането от ............... подлежи на ограничения или такси съгласно Регламент/Директива/Решение N...,<br>- CS Výstup ze............... podléhá omezením nebo dávkám podle naøízení / smìrnice / rozhodnutí ![формула](https://i.bukva.ai/sakP7uTQ/img_1.png) ...<br>- DA Udpassage fra............... undergivet restriktioner eller afgifter i henhold til forordning/direktiv/ afgørelse nr....<br>- DE Ausgang aus ...............- gemäß Verordnung/Richtlinie/ Beschluss Nr.... Beschränkungen oder Abgaben unterworfen.<br>- EE... territooriumilt väljumise suhtes kohaldatakse piiranguid ja makse vastavalt määrusele /direktiivile/otsusele nr...<br>- EL H $\text{έ}\xi o\delta o\varsigma$ $\alpha\pi\text{ό}$ ............... $\upsilon\pi o\beta\text{ά}\lambda\lambda\epsilon\tau\alpha\iota$ $\sigma\epsilon$ $\pi\epsilon\rho\iota o\rho\iota\sigma\mu o\text{ύ}\varsigma$ $\text{ή}$ $\sigma\epsilon$ $\epsilon\pi\iota\beta\alpha\rho\text{ύ}\nu\sigma\epsilon\iota\varsigma$ $\alpha\pi\text{ό}$ $\tau o\nu$ $\text{Κ}\alpha\nu o\nu\iota\sigma\mu\text{ό}$ / $\tau\eta\nu$ $\text{Ο}\delta\eta\gamma\text{ί}\alpha$ / $\tau\eta\nu$ $\text{Α}\pi\text{ό}\phi\alpha\sigma\eta$ $\alpha\rho\iota\theta.$ ....<br>- ES Salida de............... sometida a restricciones o imposiciones en virtud del (de la) Reglamento/Directiva/ Decisión no...<br>- FR Sortie de............... soumise $\text{а}$ des restrictions ou $\text{а}$ des impositions par le règlement ou la directive/ décision no...<br>- HR Izlaz iz... podliježe ogranièenjima ili pristojbama na temelju Uredbe/Direktive/Odluke br....<br>- IT Uscita dalla...............soggetta a restrizioni o ad imposizioni a norma del(la) regolamento/direttiva/ decisione n....<br>- LV Izvešana no............... piemçrojot ierobežojumus vai maksâjumus saskaòâ ar Regulu/ Direktîvu / Lçmumu Nr....,<br>- LT Išvežimui iš ............... taikomi apribojimai arba mokesèiai , nustatytiReglamentu/ Direktyva/Sprendimu Nr....,<br>- HU A kilépés ............... területérõl a... rendelet/ irányelv / határozat szerinti korlátozás vagy teher megfizetésének kötelezettsége alá esik<br>- MT ![_Hrug&](https://i.bukva.ai/sakP7uTQ/img_2.png) mill-............... $su\dot{g}\dot{g}ett$ g - hall - restrizzjonijiet jew - hlasijiet tah - t Regola/ Direttiva/ $De\dot{c}i¿joni$ Nru...<br>- NL Bij uitgang uit de..................zijn de beperkingen of heffingen van Verordening/ Richtlijn/Besluit nr.... van toepassing.<br>- PL Wyprowadzenie z............... podlega ograniczeniom lub op³atom zgodnie z rozporz¹dzeniem / dyrektyw¹ / decyzj¹ nr...<br>- PT Saída da............... sujeita a restrições ou a imposições pelo(a) Regulamento/ Directiva/ Decisão n.o...<br>- RO Ieºire din............... supusã restricþiilor sau impozitelor prin Regulamentul/ Directiva/Decizia nr... - SL Iznos iz............... zavezan omejitvam ali obveznim dajatvam na podlagi Uredbe/Direktive/ Odloèbe št ....<br>- SK Výstup z...............podlieha obmedzeniam alebo platbám podl'a nariadenia/ smernice/rozhodnutia ![формула](https://i.bukva.ai/sakP7uTQ/img_3.png) ....<br>- FI............... vientiin sovelletaan asetuksen/direktiivin/ päätöksen N:o... mukaisia rajoituksia tai maksuja<br>- EN Exit from............... subject to restrictions or charges under Regulation/Directive/Decision No... | <a id="p108937"></a>Вывоз из .... согласно ограничениям или сборам в соответствии с Регламентом/Директивой/Решением... - 99204 |
| <a id="p108938"></a>- BG Одобрен изпращач<br>- CS odesílatel Schválený<br>- DA Godkendt afsender<br>- DE Zugelassener Versender<br>- EE Volitatud kaubasaatja<br>- EL $\alpha\pi o\sigma\tau o\lambda\text{έ}\alpha\varsigma$ $\text{Ε}\gamma\kappa\epsilon\kappa\rho\iota\mu\text{έ}\nu o\varsigma$<br>- ES Expedidor autorizado<br>- FR agréé Expéditeur<br>- HR pošiljatelj Ovlašteni<br>- IT Speditore autorizzato<br>- LV nosûtîtâjs Atzîtais<br>- LT gavëjas Ágaliotasis<br>- HU feladó Engedélyezett<br>- MT Awtorizzat li jibg - hat<br>- NL Toegelaten afzender<br>- PL $Upowa¿niony$ nadawca<br>- PT Expedidor autorizado<br>- RO Expeditor agreat<br>- SL pošiljatelj Pooblašèeni<br>- SK Schválený odosielatel'<br>- FI Valtuutettu lähettäjä<br>- SV avsändare Godkänd<br>- EN Authorised consignor | <a id="p108939"></a>Авторизованный грузоотправитель - 99206 |
| <a id="p108940"></a>- BG Освободен от подпис<br>- CS Podpis se nevyžaduje<br>- DA Fritaget for underskrift<br>- DE Freistellung von der Unterschriftsleistung<br>- EE Allkirjanõudest loobutud<br>- EL $\upsilon\pi o\gamma\rho\alpha\phi\text{ή}$ $\alpha\pi\alpha\iota\tau\epsilon\text{ί}\tau\alpha\iota$ $\Delta\epsilon\nu$<br>- ES Dispensa de firma<br>- FR Dispense de signature<br>- HR Osloboðeno potpisa<br>- IT Dispensa dalla firma<br>- LV Derîgs bez paraksta<br>- LT Leista nepasirašyti<br>- HU mentesítve alól Aláírás<br>- MT Firma mhux $meh - tie\dot{g}a$<br>- NL Van ondertekening vrijgesteld<br>- PL Zwolniony ze sk³adania podpisu<br>- PT Dispensada a assinatura<br>- RO Dispensã de semnãturã<br>- SL Opustitev podpisa<br>- SK Upustenie od podpisu<br>- FI Vapautettu allekirjoituksesta<br>- SV Befrielse från underskrift<br>- EN Signature waived | <a id="p108941"></a>Подпись отменена - 99207 |
| <a id="p108942"></a>- BG ЗАБРАНЕНО ОБЩО ОБЕЗПЕЧЕНИЕ<br>- CS ZÁKAZ SOUBORNÉ JISTOTY<br>- DA FORBUD MOD SAMLET SIKKERHEDSSTILLELSE<br>- DE GESAMTBÜRGSCHAFT UNTERSAGT<br>- EE ÜLDTAGATISE KASUTAMINE KEELATUD<br>- EL H АПАГОРЕYЕТАI $\text{Ε}\Gamma\Gamma\text{ΥΗ}\Sigma\text{Η}$ $\Sigma\text{ΥΝΟ}\Lambda\text{ΙΚΗ}$<br>- ES GARANTÍA GLOBAL PROHIBIDA<br>- FR GARANTIE GLOBALE INTERDITE<br>- HR ZABRANJENO ZAJEDNIÈKO JAMSTVO<br>- IT GARANZIA GLOBALE VIETATA<br>- LV VISPÂRÇJS GALVOJUMS AIZLIEGTS<br>- LT NAUDOTI UŽDRAUSTA $GARANTIJ¥$ $BENDR¥J¥$<br>- HU ÖSSZKEZESSÉG TILOS<br>- MT MHUX PERMESSA GARANZIJA KOMPRENSIVA<br>- NL DOORLOPENDE ZEKERHEID VERBODEN<br>- PL ZAKAZ KORZYSTANIA Z ZABEZPIECZENIA GENERALNEGO<br>- PT GARANTIA GLOBAL PROIBIDA<br>- RO INTERZISÃ GLOBALÃ GARANÞIA<br>- SL PREPOVEDANO SKUPNO ZAVAROVANJE<br>- SK ZÁKAZ CELKOVEJ ZÁRUKY<br>- FI YLEISVAKUUDEN KÄYTTÖ KIELLETTY<br>- SV SAMLAD FÖRBJUDEN SÄKERHET<br>- EN COMPREHENSIVE GUARANTEE PROHIBITED | <a id="p108943"></a>ПОЛНАЯ ГАРАНТИЯ ЗАПРЕЩЕНА - 99208 |
| <a id="p108944"></a>- BG ИЗПОЛЗВАНЕ БЕЗ ОГРАНИЧЕНИЯ<br>- CS POUŽITÍ NEOMEZENÉ<br>- DA UBEGRÆNSET ANVENDELSE<br>- DE UNBESCHRÄNKTE VERWENDUNG<br>- EE PIIRAMATU KASUTAMINE<br>- EL $\text{ΧΡΗ}\Sigma\text{Η}$ $\text{Α}\Pi\text{ΕΡΙΟΡΙ}\Sigma\text{ΤΗ}$<br>- ES UTILIZACIÓN NO LIMITADA<br>- FR UTILISATION NON LIMITÉE<br>- HR NEOGRANIÈENA UPORABA<br>- IT UTILIZZAZIONE NON LIMITATA<br>- LV NEIEROBEŽOTS IZMANTOJUMS<br>- LT NEAPRIBOTAS NAUDOJIMAS<br>- HU KORLÁTOZÁS ALÁ NEM HASZNÁLAT ESÕ<br>- MT $U¯U$ MHUX RISTRETT<br>- NL GEBRUIK ONBEPERKT<br>- PL NIEOGRANICZONE KORZYSTANIE<br>- PT UTILIZAÇÃO ILIMITADA<br>- RO UTILIZARE NELIMITATÃ<br>- SL NEOMEJENA UPORABA<br>- SK POUŽITIE NEOBMEDZENÉ<br>- FI KÄYTTÖÄ EI RAJOITETTU<br>- SV ANVÄNDNING OBEGRÄNSAD<br>- EN UNRESTRICTED USE | <a id="p108945"></a>НЕОГРАНИЧЕННОЕ ИСПОЛЬЗОВАНИЕ - 99209 |
| <a id="p108946"></a>- BG Разни<br>- CS Rùzní<br>- DA Diverse<br>- DE Verschiedene<br>- EE Erinevad<br>- EL $\Delta\iota\text{ά}\phi o\rho\alpha$<br>- ES Varios<br>- FR Divers<br>- HR Razni<br>- IT Vari<br>- LV Dažâdi<br>- LT Ávairûs<br>- HU Többféle<br>- MT Diversi<br>- NL Diverse<br>- PL $Ró¿ne$<br>- PT Diversos<br>- RO Diverºi<br>- SL Razno<br>- SK Rôzne<br>- FI Useita<br>- SV Flera<br>- EN Various | <a id="p108947"></a>Разное - 99211 |
| <a id="p108948"></a>- BG Насипно<br>- CS loženo Volnì<br>- DA Bulk<br>- DE Lose<br>- EE Pakendamata<br>- EL $\text{Χύ}\mu\alpha$<br>- ES A granel<br>- FR Vrac<br>- HR Rasuto<br>- IT Alla rinfusa<br>- LV Berams (lejams)<br>- LT Nesupakuota<br>- HU Ömlesztett<br>- MT Bil - kwantità<br>- NL Los gestort<br>- PL Luzem<br>- PT A granel<br>- RO Vrac<br>- SL Razsuto<br>- SK Vol'ne ložené<br>- FI Irtotavaraa<br>- SV Bulk<br>- EN Bulk | <a id="p108949"></a>Навалом - 99212 |
| <a id="p108950"></a>- BG Изпращач<br>- CS Odesílatel<br>- DA Afsender<br>- DE Versender<br>- EE Saatja<br>- EL $\text{Α}\pi o\sigma\tau o\lambda\text{έ}\alpha\varsigma$<br>- ES Expedidor<br>- FR Expéditeur<br>- HR Pošiljatelj<br>- IT Speditore<br>- LV Nosûtîtâjs<br>- LT Siuntëjas<br>- HU Feladó<br>- MT Min jikkonsenja<br>- NL Afzender<br>- PL Nadawca<br>- PT Expedidor<br>- RO Expeditor<br>- SL Pošiljatelj<br>- SK Odosielatel'<br>- FI Lähettäjä<br>- SV Avsändare<br>- EN Consignor | <a id="p108951"></a>Грузоотправитель - 99213 |


<a id="p108952"></a>Приложение C

<a id="p108953"></a>**ФОРМЫ И КОДЫ ТРЕБОВАНИЙ**
**К ОБЩИМ ДАННЫМ ДЛЯ ДЕКЛАРАЦИЙ, УВЕДОМЛЕНИЙ И ДОКАЗАТЕЛЬСТВА**
ТАМОЖЕННОГО СТАТУСА ТОВАРОВ СОЮЗА [(СТАТЬЯ 2(4a))](https://bukva.ai/docs/reglament-20152447/statya-2#p100130)

<a id="p108954"></a>**ВВЕДЕНИЕ**

1. <a id="p108955"></a>Формы, коды и, если это применимо, структура элементов данных, включенные в настоящее Приложение, применяются в отношении требований к данным для деклараций, уведомлений и доказательства таможенного статуса товаров Союза, предусмотренных в Приложении D к Делегированному Регламенту (ЕС) 2015/2446.
2. <a id="p108956"></a>Формы, коды, и, если это применимо, структуры элементов данных, определенные в настоящем Приложении, применяются к декларациям, уведомлениям и доказательству таможенного статуса товаров Союза, составленным с использованием технологий электронной обработки данных, а также к декларациям, уведомлениям и доказательству таможенного статуса товаров Союза на бумажной основе.
3. <a id="p108957"></a>[Титул I](https://bukva.ai/docs/reglament-20152447/statya-350#p108976) включает в себя формы элементов данных.
4. <a id="p108958"></a>Когда информация в декларации, уведомлении или доказательстве таможенного статуса товаров Союза, связанных с Приложением D к Делегированному Регламенту (ЕС) 2015/2446, принимает форму кодов, применяется список кодов, предусмотренный в [Титуле II](https://bukva.ai/docs/reglament-20152447/statya-350#p109479).
5. <a id="p108959"></a>Термин "тип/длина" в разъяснении элемента указывает на требование для типа данных и длины данных. Коды для типов данных следующие:
<a id="p108960"></a>a - буквенный;
<a id="p108961"></a>n - цифровой;
<a id="p108962"></a>an - буквенно-цифровой.
<a id="p108963"></a>Число, следующее за кодом, указывает на допустимую длину данных. Применяется следующее.
<a id="p108964"></a>Дополнительные две точки перед индикатором длины означают, что данные не имеют фиксированной длины, но они могут иметь длину до количества знаков, определенных индикатором длины. Запятая в длине данных означает, что элемент может содержать десятые доли, знаки до запятой указывают общую длину элемента, знаки после запятой указывают максимальное количество знаков после десятичного знака.
<a id="p108965"></a>Примеры длины и формы поля:
<a id="p108966"></a>a1 - 1 буквенный знак, фиксированная длина;
<a id="p108967"></a>n2 - 2 цифровых знака, фиксированная длина;
<a id="p108968"></a>an3 - 3 буквенно-цифровых знака, фиксированная длина;
<a id="p108969"></a>a..4 - до 4 буквенных знаков;
<a id="p108970"></a>n..5 - до 5 цифровых знаков;
<a id="p108971"></a>an..6 - до 6 буквенно-цифровых знаков;
<a id="p108972"></a>n..7,2 - до 7 цифровых знаков, в том числе максимально 2 десятичных знака, ограничителю разрешено "плавать".
6. <a id="p108973"></a>Количество элементов на уровне заголовка, включенное в [таблицу](https://bukva.ai/docs/reglament-20152447/statya-350#p108976) в Титуле I настоящего Приложения, указывает, сколько раз элемент данных может использоваться на уровне заголовка внутри декларации, уведомления или доказательства таможенного статуса товаров Союза.
7. <a id="p108974"></a>Количество элементов на уровне пункта, включенное в [таблицу](https://bukva.ai/docs/reglament-20152447/statya-350#p108976) в Титуле I настоящего Приложения, указывает, сколько раз элемент данных может использоваться в отношении пункта этой декларации.
8. <a id="p108975"></a>Национальные коды могут использоваться государствами-членами ЕС для элементов данных [1/11](https://bukva.ai/docs/reglament-20152447/statya-350#p108984) Дополнительная процедура, [2/2](https://bukva.ai/docs/reglament-20152447/statya-350#p109021) Дополнительная информация, [2/3](https://bukva.ai/docs/reglament-20152447/statya-350#p109028) Документы, составленные, сертификаты и разрешения, дополнительные ссылки, [4/3](https://bukva.ai/docs/reglament-20152447/statya-350#p109187) Расчет налогов (Тип налогов), [4/4](https://bukva.ai/docs/reglament-20152447/statya-350#p109193) Расчет налогов (Налоговая база) и [6/17](https://bukva.ai/docs/reglament-20152447/statya-350#p109397) Код товара (национальные дополнительные коды). Государства-члены ЕС должны уведомить Европейскую Комиссию о списке национальных кодов, используемых для указанных элементов данных. Европейская Комиссия должна опубликовать список указанных кодов.

<a id="p108976"></a>**ТИТУЛ I. ФОРМАТЫ И КОЛИЧЕСТВО ЭЛЕМЕНТОВ ТРЕБОВАНИЙ**
**ДЛЯ РЕГИСТРАЦИИ СУБЪЕКТОВ ЭКОНОМИЧЕСКОЙ ДЕЯТЕЛЬНОСТИ**
**И ДРУГИХ ЛИЦ**


<table>
<colgroup><col width="6%"><col width="18%"><col width="27%"><col width="7%"><col width="10%"><col width="10%"><col width="21%"></colgroup>
<tr><td><a id="p108977"></a>Порядковый номер D.E.</td><td><a id="p108978"></a>Название D.E.</td><td><a id="p108979"></a>Формат D.E.<br>(Тип/длина)</td><td><a id="p108980"></a>Список кодов в <a href="#p109479">Титуле II</a> (Y(да)/N(нет))</td><td><a id="p108981"></a>Количество элементов на уровне заголовка</td><td><a id="p108982"></a>Количество элементов на уровне пункта</td><td><a id="p108983"></a>Примечания</td></tr>
<tr><td><a id="p108984"></a>1/1</td><td><a id="p108985"></a>Тип декларации</td><td><a id="p108986"></a>a2</td><td><a id="p108987"></a>Y</td><td><a id="p108988"></a>1x</td><td></td><td></td></tr>
<tr><td><a id="p108989"></a>1/2</td><td><a id="p108990"></a>Тип дополнительной декларации</td><td><a id="p108991"></a>a1</td><td><a id="p108992"></a>Y</td><td><a id="p108993"></a>1x</td><td></td><td></td></tr>
<tr><td><a id="p108994"></a>1/6</td><td><a id="p108995"></a>Количество пунктов товаров</td><td><a id="p108996"></a>n..5</td><td><a id="p108997"></a>N</td><td></td><td><a id="p108998"></a>1x</td><td></td></tr>
<tr><td><a id="p108999"></a>1/8</td><td><a id="p109000"></a>Подпись/удостоверение</td><td></td><td><a id="p109001"></a>N</td><td><a id="p109002"></a>1x</td><td></td><td></td></tr>
<tr><td><a id="p109003"></a>1/10</td><td><a id="p109004"></a>Процедура</td><td><a id="p109005"></a>Код запрошенной процедуры: an2+<br>Код предыдущей процедуры: an2</td><td><a id="p109006"></a>Y</td><td></td><td><a id="p109007"></a>1x</td><td></td></tr>
<tr><td><a id="p109008"></a>1/11</td><td><a id="p109009"></a>Дополнительная процедура</td><td><a id="p109010"></a>Коды Союза: a1 + an2<br>ИЛИ<br>Национальные коды: n1 + an2</td><td><a id="p109011"></a>Y</td><td></td><td><a id="p109012"></a>99x</td><td><a id="p109013"></a>Коды Союза далее определены в <a href="#p109479">Титуле II</a></td></tr>
<tr><td><a id="p109014"></a>2/1</td><td><a id="p109015"></a>Упрощенная декларация/Предыдущие документы</td><td><a id="p109016"></a>Тип предыдущего документа: an..3+<br>Ссылка на предыдущий документ: an..35+<br>Идентификатор пункта товара: n..5+<br>Тип упаковок: an..2<br>Количество упаковок: n..8<br>Единица измерения и классификатор, если применяется: ab..4+<br>Количество: n..16,6</td><td><a id="p109017"></a>Y</td><td><a id="p109018"></a>9,999x</td><td><a id="p109019"></a>99x</td><td><a id="p109020"></a>Должны использоваться единицы измерения и классификаторы, определенные в TARIC. В таком случае формат единиц измерения и классификаторов должен быть an..4, но не n..4, зарезервированный для национальных единиц измерений и классификаторов.<br>Если таких единиц измерений и классификаторов нет в TARIC, то могут использоваться национальные единицы измерения и классификаторы. Их формат должен быть n..4.</td></tr>
<tr><td><a id="p109021"></a>2/2</td><td><a id="p109022"></a>Дополнительная информация</td><td><a id="p109023"></a>Закодированная версия<br>(Коды Союза): n1+ an4<br>ИЛИ<br>(национальные коды): a1+an4<br>ИЛИ<br>Описание в свободной текстовой форме: an..512</td><td><a id="p109024"></a>Y</td><td><a id="p109025"></a>99x</td><td><a id="p109026"></a>99x</td><td><a id="p109027"></a>Коды Союза далее определены в <a href="#p109479">Титуле II</a></td></tr>
<tr><td><a id="p109028"></a>2/3</td><td><a id="p109029"></a>Документы, составленные, сертификаты и разрешения, дополнительные ссылки</td><td><a id="p109030"></a>Тип документа (Коды Союза): a1+ an3 + (если применяется)<br>Идентификатор документа: an..35<br>ИЛИ<br>Тип документа (национальные коды): n1+an3 + (если применяется)<br>Идентификатор документа: an..35 + (если применяется)<br>Название выдающего органа: an..70 +<br>Дата срока действия: n8 ггггммдд) +<br>Единица измерения и классификатор, если применяется: an..4 +<br>Количество: n..16,6 +<br>Код валюты: a3 +<br>Сумма: n..16,2</td><td><a id="p109031"></a>Y</td><td><a id="p109032"></a>99x</td><td><a id="p109033"></a>99x</td><td><a id="p109034"></a>Должны использоваться единицы измерения и классификаторы, определенные в TARIC. В таком случае формат единиц измерения и классификаторов должен быть an..4, но не n..4, зарезервированный для национальных единиц измерений и классификаторов.<br>Если таких единиц измерений и классификаторов нет в TARIC, то могут использоваться национальные единицы измерения и классификаторы. Их формат должен быть n..4.<br>Для валюты должны использоваться 3-буквенных-ISO коды валют (ISO 4217).</td></tr>
<tr><td><a id="p109035"></a>2/4</td><td><a id="p109036"></a>Исходящий номер/UCR</td><td><a id="p109037"></a>an..35</td><td><a id="p109038"></a>N</td><td><a id="p109039"></a>1x</td><td><a id="p109040"></a>1x</td><td><a id="p109041"></a>Указанный элемент данных может принимать форму кодов WCO (ISO 15459) или эквивалентных кодов.</td></tr>
<tr><td><a id="p109042"></a>2/5</td><td><a id="p109043"></a>LRN</td><td><a id="p109044"></a>an..22</td><td><a id="p109045"></a>N</td><td><a id="p109046"></a>1x</td><td></td><td></td></tr>
<tr><td><a id="p109047"></a>2/6</td><td><a id="p109048"></a>Отсроченный платеж</td><td><a id="p109049"></a>an..35</td><td><a id="p109050"></a>N</td><td><a id="p109051"></a>1x</td><td></td><td></td></tr>
<tr><td><a id="p109052"></a>2/7</td><td><a id="p109053"></a>Идентификация склада</td><td><a id="p109054"></a>Тип склада: a1+<br>Идентификатор склада: an..35</td><td><a id="p109055"></a>Y</td><td><a id="p109056"></a>1x</td><td></td><td></td></tr>
<tr><td><a id="p109057"></a>3/1</td><td><a id="p109058"></a>Экспортер</td><td><a id="p109059"></a>Имя/название: an..70+<br>Улица и номер: an..70+<br>Страна: a2+<br>Почтовый индекс: an..9+<br>Город: an..35</td><td><a id="p109060"></a>N</td><td><a id="p109061"></a>1x</td><td><a id="p109062"></a>1x</td><td><a id="p109063"></a>Код страны:<br>Алфавитные коды Союза стран и территорий основываются на текущих 2-буквенных кодах ISO (a2) настолько, насколько они совместимы с требованиями Регламента (ЕС) 2020/1470 Европейской Комиссии от 12 октября 2020 г. о номенклатуре стран и территорий <a href="#p109477">&lt;1&gt;</a> для европейской статистики по международной торговле товарами и по географической разбивке для другой статистики по бизнесу (ОЖ N L334, 13.10.2020, стр. 2 - 21). Европейская Комиссия регулярно публикует регламенты, обновляющие список кодов стран.<br>В случае групповых партий, если используются декларации на бумажных носителях, код "00200" может использоваться вместе со списком экспортеров в соответствии с примечаниями, описанными для D.E. 3/1 Экспортер в Титуле II Приложения D к Делегированному Регламенту (ЕС) 2015/2446.</td></tr>
<tr><td><a id="p109064"></a>3/2</td><td><a id="p109065"></a>Идентификационный номер экспортера</td><td><a id="p109066"></a>an..17</td><td><a id="p109067"></a>N</td><td><a id="p109068"></a>1x</td><td><a id="p109069"></a>1x</td><td><a id="p109070"></a>Структура номера EORI определена в <a href="#p109479">Титуле II</a>.<br>Структура уникального идентификационного номера третьей страны, признанной Союзом, определена в <a href="#p109479">Титуле II</a>.</td></tr>
<tr><td><a id="p109071"></a>3/15</td><td><a id="p109072"></a>Импортер</td><td><a id="p109073"></a>Имя/название: an..70+<br>Улица и номер: an..70+<br>Страна: a2+<br>Почтовый индекс: an..9+<br>Город: an..35</td><td><a id="p109074"></a>N</td><td><a id="p109075"></a>1x</td><td></td><td><a id="p109076"></a>Должен использоваться код страны, определенный для D.E. <a href="#p109057">3/1</a> Экспортер.</td></tr>
<tr><td><a id="p109077"></a>3/16</td><td><a id="p109078"></a>Идентификационный номер импортера</td><td><a id="p109079"></a>an..17</td><td><a id="p109080"></a>N</td><td><a id="p109081"></a>1x</td><td><a id="p109082"></a>1x</td><td><a id="p109083"></a>Номер EORI должен следовать структуре, определенной в Титуле II для D.E. <a href="#p110213">3/2</a> Идентификационный номер экспортера.</td></tr>
<tr><td><a id="p109084"></a>3/17</td><td><a id="p109085"></a>Декларант</td><td><a id="p109086"></a>Имя/название: an..70+<br>Улица и номер: an..70+<br>Страна: a2+<br>Почтовый индекс: an..9<br>Город: an..35</td><td><a id="p109087"></a>N</td><td><a id="p109088"></a>1x</td><td></td><td><a id="p109089"></a>Должен использоваться код страны, определенный для D.E. <a href="#p109057">3/1</a> Экспортер.</td></tr>
<tr><td><a id="p109090"></a>3/18</td><td><a id="p109091"></a>Идентификационный номер декларанта</td><td><a id="p109092"></a>an..17</td><td><a id="p109093"></a>N</td><td><a id="p109094"></a>1x</td><td><a id="p109095"></a>1x</td><td><a id="p109096"></a>Номер EORI должен следовать структуре, определенной в Титуле II для D.E. <a href="#p110213">3/2</a> Идентификационный номер экспортера.</td></tr>
<tr><td><a id="p109097"></a>3/19</td><td><a id="p109098"></a>Представитель</td><td><a id="p109099"></a>Имя/название: an..70+<br>Улица и номер: an..70+<br>Страна: a2+<br>Почтовый индекс: an..9<br>Город: an..35</td><td><a id="p109100"></a>N</td><td><a id="p109101"></a>1x</td><td></td><td><a id="p109102"></a>Должен использоваться код страны, определенный для D.E. <a href="#p109057">3/1</a> Экспортер.</td></tr>
<tr><td><a id="p109103"></a>3/20</td><td><a id="p109104"></a>Идентификационный номер представителя</td><td><a id="p109105"></a>an..17</td><td><a id="p109106"></a>N</td><td><a id="p109107"></a>1x</td><td><a id="p109108"></a>1x</td><td><a id="p109109"></a>Номер EORI должен следовать структуре, определенной в Титуле II для D.E. <a href="#p110213">3/2</a> Идентификационный номер экспортера.</td></tr>
<tr><td><a id="p109110"></a>3/21</td><td><a id="p109111"></a>Код статуса представителя</td><td><a id="p109112"></a>n1</td><td><a id="p109113"></a>Y</td><td><a id="p109114"></a>1x</td><td></td><td></td></tr>
<tr><td><a id="p109115"></a>3/24</td><td><a id="p109116"></a>Продавец</td><td><a id="p109117"></a>Имя/название: an..70+<br>Улица и номер: an..70+<br>Страна: a2+<br>Почтовый индекс: an..9+<br>Город: an..35+<br>Телефонный номер: an..50</td><td><a id="p109118"></a>N</td><td><a id="p109119"></a>1x</td><td><a id="p109120"></a>1x</td><td><a id="p109121"></a>Должен использоваться код страны, определенный для D.E. <a href="#p109057">3/1</a> Экспортер.</td></tr>
<tr><td><a id="p109122"></a>3/25</td><td><a id="p109123"></a>Идентификационный номер продавца</td><td><a id="p109124"></a>an..17</td><td><a id="p109125"></a>N</td><td><a id="p109126"></a>1x</td><td><a id="p109127"></a>1x</td><td><a id="p109128"></a>Номер EORI должен следовать структуре, определенной в Титуле II для D.E. <a href="#p110213">3/2</a> Идентификационный номер экспортера.<br>Структура уникального идентификационного номера третьей страны должна следовать структуре, определенной в Титуле II для D.E. <a href="#p110213">3/2</a> Идентификационный номер экспортера.</td></tr>
<tr><td><a id="p109129"></a>3/26</td><td><a id="p109130"></a>Покупатель</td><td><a id="p109131"></a>Имя/название: an..70+<br>Улица и номер: an..70+<br>Страна: a2+<br>Почтовый индекс: an..9+<br>Город: an..35+<br>Телефонный номер: an..50</td><td><a id="p109132"></a>N</td><td><a id="p109133"></a>1x</td><td><a id="p109134"></a>1x</td><td><a id="p109135"></a>Должен использоваться код страны, определенный для D.E. <a href="#p109057">3/1</a> Экспортер.</td></tr>
<tr><td><a id="p109136"></a>3/27</td><td><a id="p109137"></a>Идентификационный номер покупателя</td><td><a id="p109138"></a>an..17</td><td><a id="p109139"></a>N</td><td><a id="p109140"></a>1x</td><td><a id="p109141"></a>1x</td><td><a id="p109142"></a>Номер EORI должен следовать структуре, определенной в Титуле II для D.E. <a href="#p110213">3/2</a> Идентификационный номер экспортера.<br>Структура уникального идентификационного номера третьей страны должна следовать структуре, определенной в Титуле II для D.E. <a href="#p110213">3/2</a> Идентификационный номер экспортера.</td></tr>
<tr><td><a id="p109143"></a>3/37</td><td><a id="p109144"></a>Идентификационный номер дополнительного(ых) участника(ов) системы поставки</td><td><a id="p109145"></a>Код роли: a..3+<br>Идентификатор: an..7</td><td><a id="p109146"></a>Y</td><td><a id="p109147"></a>99x</td><td><a id="p109148"></a>99x</td><td><a id="p109149"></a>Коды роли для дополнительных участников системы поставки определены в <a href="#p109479">Титуле II</a>.<br>Номер EORI соответствует структуре, определенной в Титуле II для D.E. <a href="#p110213">3/2</a> Идентификационный номер экспортера.<br>Структура уникального идентификационного номера третьей страны соответствует структуре, определенной в Титуле II для D.E. <a href="#p110213">3/2</a> Идентификационный номер экспортера.</td></tr>
<tr><td><a id="p109150"></a>3/39</td><td><a id="p109151"></a>Идентификационный номер владельца разрешения</td><td><a id="p109152"></a>Код вида разрешения: an..4+<br>Идентификатор: an..17</td><td><a id="p109153"></a>N</td><td><a id="p109154"></a>99x</td><td></td><td><a id="p109155"></a>Коды, определенные в Приложении A для D.E. <a href="#p104034">1/1</a> Заявление/Тип кода решения используются для кода вида разрешения.<br>Номер EORI соответствует структуре, определенной в Титуле II для D.E. <a href="#p110213">3/2</a> Идентификационный номер экспортера.</td></tr>
<tr><td><a id="p109156"></a>3/40</td><td><a id="p109157"></a>Идентификационный номер дополнительных фискальных ссылок</td><td><a id="p109158"></a>Код роли: an3+<br>Идентификационный номер плательщика НДС: an..17</td><td><a id="p109159"></a>Y</td><td><a id="p109160"></a>99x</td><td><a id="p109161"></a>99x</td><td><a id="p109162"></a>Коды роли для дополнительных фискальных ссылок определены в <a href="#p109479">Титуле II</a>.</td></tr>
<tr><td><a id="p109163"></a>3/41</td><td><a id="p109164"></a>Идентификационный номер лица, представляющего товары таможне в случае внесения в отчеты декларанта или предварительно поданных таможенных деклараций</td><td><a id="p109165"></a>an..17</td><td><a id="p109166"></a>N</td><td><a id="p109167"></a>1x</td><td></td><td><a id="p109168"></a>Номер EORI соответствует структуре, определенной в Титуле II для D.E. <a href="#p110213">3/2</a> Идентификационный номер экспортера.</td></tr>
<tr><td><a id="p109169"></a>3/45</td><td><a id="p109170"></a>Идентификационный номер лица, представляющего гарантию</td><td><a id="p109171"></a>an..17</td><td><a id="p109172"></a>N</td><td><a id="p109173"></a>1x</td><td></td><td><a id="p109174"></a>Номер EORI соответствует структуре, определенной в Титуле II для D.E. <a href="#p110213">3/2</a> Идентификационный номер экспортера.</td></tr>
<tr><td><a id="p109175"></a>3/46</td><td><a id="p109176"></a>Идентификационный номер лица, оплачивающего таможенную пошлину</td><td><a id="p109177"></a>an..17</td><td><a id="p109178"></a>N</td><td><a id="p109179"></a>1x</td><td></td><td><a id="p109180"></a>Номер EORI соответствует структуре, определенной в Титуле II для D.E. <a href="#p110213">3/2</a> Идентификационный номер экспортера.</td></tr>
<tr><td><a id="p109181"></a>4/1</td><td><a id="p109182"></a>Условия поставки</td><td><a id="p109183"></a>Кодированная версия: INCOTERM<br>код: a3 +<br>UN/LOCODE: an..17<br>ИЛИ<br>Описание в свободной форме:<br>Код: INCOTERM: a3+<br>Код страны: a2+<br>Название места: an..35</td><td><a id="p109184"></a>Y</td><td><a id="p109185"></a>1x</td><td></td><td><a id="p109186"></a>Коды и заголовки, описывающие коммерческий договор, определены в <a href="#p109479">Титуле II</a>. Код, предусмотренный для описания места, соответствует образцу UN/LOCODE. Если UN/LOCODE нет в наличии для места, используйте код страны, предусмотренный для D.E. <a href="#p109057">3/1</a> экспортер, после которого идет название места.</td></tr>
<tr><td><a id="p109187"></a>4/3</td><td><a id="p109188"></a>Расчет налогов - вид налога</td><td><a id="p109189"></a>Коды Союза: a1+n2<br>ИЛИ<br>Национальные коды: n1+an2</td><td><a id="p109190"></a>Y</td><td></td><td><a id="p109191"></a>99x</td><td><a id="p109192"></a>Коды Союза далее определены в <a href="#p109479">Титуле II</a></td></tr>
<tr><td><a id="p109193"></a>4/4</td><td><a id="p109194"></a>Расчет налогов - налоговая база</td><td><a id="p109195"></a>Единица измерения и определитель, если применяется: an..6+<br>Количество: n..16,6<br>ИЛИ<br>Сумма: n..16,2</td><td><a id="p109196"></a>N</td><td></td><td><a id="p109197"></a>99x</td><td><a id="p109198"></a>Должны использоваться единицы измерения и определители, определенные в TARIC. В таких случаях формат единиц измерения и определителей будет an..6, но они никогда не должны иметь форматы n..6, предназначенные для национальных единиц измерения и определителей.<br>Если таких единиц измерений и определителей нет в TARIC, можно использовать национальные единицы измерения и определители. Их формат будет n..6.</td></tr>
<tr><td><a id="p109199"></a>4/5</td><td><a id="p109200"></a>Расчет налогов - ставка налога</td><td><a id="p109201"></a>n..17,3</td><td><a id="p109202"></a>N</td><td></td><td><a id="p109203"></a>99x</td><td></td></tr>
<tr><td><a id="p109204"></a>4/6</td><td><a id="p109205"></a>Расчет налогов - сумма выплачиваемого налога</td><td><a id="p109206"></a>n..16,2</td><td><a id="p109207"></a>N</td><td></td><td><a id="p109208"></a>99x</td><td></td></tr>
<tr><td><a id="p109209"></a>4/7</td><td><a id="p109210"></a>Расчет налогов - Итого</td><td><a id="p109211"></a>n..16,2</td><td><a id="p109212"></a>N</td><td></td><td><a id="p109213"></a>1x</td><td></td></tr>
<tr><td><a id="p109214"></a>4/8</td><td><a id="p109215"></a>Расчет налогов - способ оплаты</td><td><a id="p109216"></a>a1</td><td><a id="p109217"></a>Y</td><td></td><td><a id="p109218"></a>99x</td><td></td></tr>
<tr><td><a id="p109219"></a>4/9</td><td><a id="p109220"></a>Надбавки и вычеты</td><td><a id="p109221"></a>Код: a2+<br>Сумма: n..16,2</td><td><a id="p109222"></a>Y</td><td><a id="p109223"></a>99x</td><td><a id="p109224"></a>99x</td><td></td></tr>
<tr><td><a id="p109225"></a>4/10</td><td><a id="p109226"></a>Валюта инвойса</td><td><a id="p109227"></a>a3</td><td><a id="p109228"></a>N</td><td><a id="p109229"></a>1x</td><td></td><td><a id="p109230"></a>Для валюты используются коды валюты ISO-alpha-3 (ISO 4217).</td></tr>
<tr><td><a id="p109231"></a>4/11</td><td><a id="p109232"></a>Общая сумма выставленных счетов</td><td><a id="p109233"></a>n..16,2</td><td><a id="p109234"></a>N</td><td><a id="p109235"></a>1х</td><td></td><td></td></tr>
<tr><td><a id="p109236"></a>4/12</td><td><a id="p109237"></a>Единица внутренней валюты</td><td><a id="p109238"></a>a3</td><td><a id="p109239"></a>N</td><td><a id="p109240"></a>1x</td><td></td><td><a id="p109241"></a>Для валюты используются коды валюты ISO-alpha-3 (ISO 4217).</td></tr>
<tr><td><a id="p109242"></a>4/13</td><td><a id="p109243"></a>Показатели оценки</td><td><a id="p109244"></a>an4</td><td><a id="p109245"></a>Y</td><td></td><td><a id="p109246"></a>1х</td><td></td></tr>
<tr><td><a id="p109247"></a>4/14</td><td><a id="p109248"></a>Цена/сумма наименования</td><td><a id="p109249"></a>n..16,2</td><td><a id="p109250"></a>N</td><td></td><td><a id="p109251"></a>1x</td><td></td></tr>
<tr><td><a id="p109252"></a>4/15</td><td><a id="p109253"></a>Курс обмена</td><td><a id="p109254"></a>n..12,5</td><td><a id="p109255"></a>N</td><td><a id="p109256"></a>1x</td><td></td><td></td></tr>
<tr><td><a id="p109257"></a>4/16</td><td><a id="p109258"></a>Способ оценки</td><td><a id="p109259"></a>n1</td><td><a id="p109260"></a>Y</td><td></td><td><a id="p109261"></a>1x</td><td></td></tr>
<tr><td><a id="p109262"></a>4/17</td><td><a id="p109263"></a>Преференция</td><td><a id="p109264"></a>n3 (n1+n2)</td><td><a id="p109265"></a>Y</td><td></td><td><a id="p109266"></a>1x</td><td><a id="p109267"></a>Европейская Комиссия публикует через регулярные интервалы список используемых комбинаций кодов вместе с примерами и примечаниями.</td></tr>
<tr><td><a id="p109268"></a>4/18</td><td><a id="p109269"></a>Стоимость</td><td><a id="p109270"></a>Код страны: a3+<br>Стоимость: n..16,2</td><td><a id="p109271"></a>N</td><td></td><td><a id="p109272"></a>1x</td><td><a id="p109273"></a>Для валюты используются коды валюты ISO-alpha-3 (ISO 4217).</td></tr>
<tr><td><a id="p109274"></a>4/19</td><td><a id="p109275"></a>Транспортные расходы до окончательного места назначения</td><td><a id="p109276"></a>Код страны: a3+<br>Стоимость: n..16,2</td><td><a id="p109277"></a>N</td><td><a id="p109278"></a>1x</td><td></td><td><a id="p109279"></a>Для валюты используются коды валюты ISO-alpha-3 (ISO 4217).</td></tr>
<tr><td><a id="p109280"></a>5/8</td><td><a id="p109281"></a>Страна места назначения</td><td><a id="p109282"></a>a2</td><td><a id="p109283"></a>N</td><td><a id="p109284"></a>1x</td><td><a id="p109285"></a>1x</td><td><a id="p109286"></a>Используется код страны, определенный для D.E. <a href="#p109057">3/1</a> Экспортер.<br>В контексте транзитных операций используется код страны ISO 3166 alpha-2.</td></tr>
<tr><td><a id="p109287"></a>5/9</td><td><a id="p109288"></a>Код региона места назначения</td><td><a id="p109289"></a>an..9</td><td><a id="p109290"></a>N</td><td><a id="p109291"></a>1x</td><td><a id="p109292"></a>1x</td><td><a id="p109293"></a>Коды определены заинтересованным государством-членом ЕС.</td></tr>
<tr><td><a id="p109294"></a>5/14</td><td><a id="p109295"></a>Код страны отправления/экспорта</td><td><a id="p109296"></a>a2</td><td><a id="p109297"></a>N</td><td><a id="p109298"></a>1x</td><td><a id="p109299"></a>1x</td><td><a id="p109300"></a>Используется код страны, определенный для D.E. <a href="#p109057">3/1</a> Экспортер.</td></tr>
<tr><td><a id="p109301"></a>5/15</td><td><a id="p109302"></a>Код страны происхождения</td><td><a id="p109303"></a>a2</td><td><a id="p109304"></a>N</td><td></td><td><a id="p109305"></a>1x</td><td><a id="p109306"></a>Используется код страны, определенный для D.E. <a href="#p109057">3/1</a> Экспортер.</td></tr>
<tr><td><a id="p109307"></a>5/16</td><td><a id="p109308"></a>Код страны преференциального происхождения</td><td><a id="p109309"></a>an..4</td><td><a id="p109310"></a>N</td><td></td><td><a id="p109311"></a>1x</td><td><a id="p109312"></a>Используется код страны, определенный для D.E. <a href="#p109057">3/1</a> Экспортер.<br>Если доказательство происхождения относится к группе стран, используются цифровые коды идентификатора, определенные в интегрированном тарифе, установленном в соответствии со Статьей 2 Регламента (ЕЭС) 2658/87 Совета ЕС.</td></tr>
<tr><td><a id="p109313"></a>5/23</td><td><a id="p109314"></a>Местонахождение товаров</td><td><a id="p109315"></a>Страна: a2+<br>Вид местонахождения: a1+<br>Определитель идентификации: a1+<br>Кодировано<br>Идентификация местонахождения: an..35+<br>Дополнительный идентификатор: n..3<br>ИЛИ<br>Описание в свободной форме<br>Улица и номер: an..70+<br>Почтовый индекс: an..9+<br>Город: an..35</td><td><a id="p109316"></a>Y</td><td><a id="p109317"></a>1x</td><td></td><td><a id="p109318"></a>Структура кода определена в <a href="#p109479">Титуле II</a>.</td></tr>
<tr><td><a id="p109319"></a>5/26</td><td><a id="p109320"></a>Таможенное учреждение места представления</td><td><a id="p109321"></a>an8</td><td><a id="p109322"></a>N</td><td><a id="p109323"></a>1x</td><td></td><td><a id="p109324"></a>Идентификатор таможенного учреждения соответствует структуре, определенной для D.E. 5/6 Учреждение места назначения (и страна).</td></tr>
<tr><td><a id="p109325"></a>5/27</td><td><a id="p109326"></a>Надзорное таможенное учреждение</td><td><a id="p109327"></a>an8</td><td><a id="p109328"></a>N</td><td><a id="p109329"></a>1x</td><td></td><td><a id="p109330"></a>Идентификатор таможенного учреждения соответствует структуре, определенной для D.E. 5/6 Учреждение места назначения (и страна).</td></tr>
<tr><td><a id="p109331"></a>5/31</td><td><a id="p109332"></a>Дата приемки</td><td><a id="p109333"></a>n8 (ггггммдд)</td><td><a id="p109334"></a>N</td><td><a id="p109335"></a>1x</td><td><a id="p109336"></a>1x</td><td></td></tr>
<tr><td><a id="p109337"></a>6/1</td><td><a id="p109338"></a>Масса нетто (кг)</td><td><a id="p109339"></a>n..16,6</td><td><a id="p109340"></a>N</td><td></td><td><a id="p109341"></a>1x</td><td></td></tr>
<tr><td><a id="p109342"></a>6/2</td><td><a id="p109343"></a>Дополнительные единицы</td><td><a id="p109344"></a>n..16,6</td><td><a id="p109345"></a>N</td><td></td><td><a id="p109346"></a>1x</td><td></td></tr>
<tr><td><a id="p109347"></a>6/5</td><td><a id="p109348"></a>Масса брутто (кг)</td><td><a id="p109349"></a>n..16,6</td><td><a id="p109350"></a>N</td><td><a id="p109351"></a>1x</td><td><a id="p109352"></a>1x</td><td></td></tr>
<tr><td><a id="p109353"></a>6/8</td><td><a id="p109354"></a>Описание товаров</td><td><a id="p109355"></a>an..512</td><td><a id="p109356"></a>N</td><td></td><td><a id="p109357"></a>1x</td><td></td></tr>
<tr><td><a id="p109358"></a>6/9</td><td><a id="p109359"></a>Вид упаковки</td><td><a id="p109360"></a>an..2</td><td><a id="p109361"></a>N</td><td></td><td><a id="p109362"></a>99x</td><td><a id="p109363"></a>Список кодов соответствует последней редакции Рекомендаций UN/ECE N 21.</td></tr>
<tr><td><a id="p109364"></a>6/10</td><td><a id="p109365"></a>Количество упаковок</td><td><a id="p109366"></a>n..8</td><td><a id="p109367"></a>N</td><td></td><td><a id="p109368"></a>99x</td><td></td></tr>
<tr><td><a id="p109369"></a>6/11</td><td><a id="p109370"></a>Грузовая маркировка</td><td><a id="p109371"></a>an..512</td><td><a id="p109372"></a>N</td><td></td><td><a id="p109373"></a>99x</td><td></td></tr>
<tr><td><a id="p109374"></a>6/13</td><td><a id="p109375"></a>Код CUS</td><td><a id="p109376"></a>an8</td><td><a id="p109377"></a>N</td><td></td><td><a id="p109378"></a>1x</td><td><a id="p109379"></a>Код CUS, присвоенный в Европейской таможенной классификации химических веществ (ECICS).</td></tr>
<tr><td><a id="p109380"></a>6/14</td><td><a id="p109381"></a>Код товара - код Комбинированной номенклатуры</td><td><a id="p109382"></a>an..8</td><td><a id="p109383"></a>N</td><td></td><td><a id="p109384"></a>1x</td><td></td></tr>
<tr><td><a id="p109385"></a>6/15</td><td><a id="p109386"></a>Код товара - код TARIC</td><td><a id="p109387"></a>an2</td><td><a id="p109388"></a>N</td><td></td><td><a id="p109389"></a>1x</td><td><a id="p109390"></a>Заполняется в соответствии с кодом TARIC (два знака для применения специальных мер Союза в отношении формальностей, выполняемых в месте назначения).</td></tr>
<tr><td><a id="p109391"></a>6/16</td><td><a id="p109392"></a>Код товара - дополнительный(ые) код(ы) TARIC</td><td><a id="p109393"></a>an4</td><td><a id="p109394"></a>N</td><td></td><td><a id="p109395"></a>99x</td><td><a id="p109396"></a>Заполняется в соответствии с кодами (TARIC) (дополнительные коды).</td></tr>
<tr><td><a id="p109397"></a>6/17</td><td><a id="p109398"></a>Код товара - Национальный(ые) дополнительный(ые) код(ы)</td><td><a id="p109399"></a>an..4</td><td><a id="p109400"></a>N</td><td></td><td><a id="p109401"></a>99x</td><td><a id="p109402"></a>Коды, которые должны быть приняты заинтересованными государствами-членами ЕС.</td></tr>
<tr><td><a id="p109403"></a>6/18</td><td><a id="p109404"></a>Всего упаковок</td><td><a id="p109405"></a>n..8</td><td><a id="p109406"></a>N</td><td><a id="p109407"></a>1x</td><td></td><td></td></tr>
<tr><td><a id="p109408"></a>6/19</td><td><a id="p109409"></a>Вид товаров</td><td><a id="p109410"></a>an..3</td><td><a id="p109411"></a>N</td><td></td><td><a id="p109412"></a>1x</td><td><a id="p109413"></a>Используется список кодов UPU</td></tr>
<tr><td><a id="p109414"></a>7/2</td><td><a id="p109415"></a>Контейнер</td><td><a id="p109416"></a>n1</td><td><a id="p109417"></a>Y</td><td><a id="p109418"></a>1x</td><td></td><td></td></tr>
<tr><td><a id="p109419"></a>7/4</td><td><a id="p109420"></a>Вид транспорта на границе</td><td><a id="p109421"></a>n1</td><td><a id="p109422"></a>Y</td><td><a id="p109423"></a>1x</td><td></td><td></td></tr>
<tr><td><a id="p109424"></a>7/5</td><td><a id="p109425"></a>Внутренний вид транспорта</td><td><a id="p109426"></a>n1</td><td><a id="p109427"></a>N</td><td><a id="p109428"></a>1x</td><td></td><td><a id="p109429"></a>Используются коды, предусмотренные в Титуле II в отношении D.E. <a href="#p110492">7/4</a> Вид транспорта на границе</td></tr>
<tr><td><a id="p109430"></a>7/9</td><td><a id="p109431"></a>Название транспортного средства в месте прибытия</td><td><a id="p109432"></a>Вид идентификации: n2+<br>Идентификационный номер: an..35</td><td><a id="p109433"></a>N</td><td><a id="p109434"></a>1x</td><td></td><td><a id="p109435"></a>Коды, определенные в <a href="#p109479">Титуле II</a> для D.E. 7/7 Название транспортного средства в месте отправления, используется для вида идентификации.</td></tr>
<tr><td><a id="p109436"></a>7/10</td><td><a id="p109437"></a>Идентификационный номер контейнера</td><td><a id="p109438"></a>an..17</td><td><a id="p109439"></a>N</td><td><a id="p109440"></a>9999x</td><td><a id="p109441"></a>9999x</td><td></td></tr>
<tr><td><a id="p109442"></a>7/15</td><td><a id="p109443"></a>Национальность активного транспортного средства, пересекающего границу</td><td><a id="p109444"></a>a2</td><td><a id="p109445"></a>N</td><td><a id="p109446"></a>1x</td><td><a id="p109447"></a>1x</td><td><a id="p109448"></a>Используется код страны, определенный для D.E. <a href="#p109057">3/1</a> Экспортер.</td></tr>
<tr><td><a id="p109449"></a>8/1</td><td><a id="p109450"></a>Порядковый номер квоты</td><td><a id="p109451"></a>an6</td><td><a id="p109452"></a>N</td><td></td><td><a id="p109453"></a>1x</td><td></td></tr>
<tr><td><a id="p109454"></a>8/2</td><td><a id="p109455"></a>Вид гарантии</td><td><a id="p109456"></a>Вид гарантии: an 1</td><td><a id="p109457"></a>Y</td><td><a id="p109458"></a>9x</td><td></td><td></td></tr>
<tr><td><a id="p109459"></a>8/3</td><td><a id="p109460"></a>Ссылка на гарантию</td><td><a id="p109461"></a>Ссылки на гарантию (GRN): an..24+<br>Код доступа: an..4+<br>Код валюты: a3+<br>Сумма импортной или экспортной пошлины и, если применяется <a href="https://bukva.ai/docs/reglament-9522013/statya-1#p100898">первый подпараграф Статьи 89(2)</a> Кодекса, другие сборы: n..16,2+<br>Таможенное учреждение гарантии: an8<br>ИЛИ<br>Другая ссылка на гарантию: an..35+<br>Код доступа: an..4+<br>Код валюты: a3+<br>Сумма импортной или экспортной пошлины и, если применяется <a href="https://bukva.ai/docs/reglament-9522013/statya-1#p100898">первый подпараграф Статьи 89(2)</a> Кодекса, другие сборы: n..16,2+<br>Таможенное учреждение гарантии: an8</td><td><a id="p109462"></a>N</td><td><a id="p109463"></a>99x</td><td></td><td><a id="p109464"></a>Для валюты используются коды валюты ISO-alpha-3 (ISO 4217).<br>Идентификатор таможенного учреждения соответствует структуре, определенной для D.E. 5/6 Учреждение места назначения (и страна).</td></tr>
<tr><td><a id="p109465"></a>8/5</td><td><a id="p109466"></a>Характер сделки</td><td><a id="p109467"></a>n..2</td><td><a id="p109468"></a>N</td><td><a id="p109469"></a>1x</td><td><a id="p109470"></a>1x</td><td><a id="p109471"></a>Используются однозначные коды, указанные в колонке A таблицы, предусмотренные согласно Статье 10(2) Регламента (ЕС) 113/2010 Европейской Комиссии <a href="#p109478">&lt;2&gt;</a>. Если используются декларации на бумажном носителе, это значение вносится в левую часть графы 24.<br>Государства-члены ЕС могут также предусмотреть выбор второго знака из списка в колонке B этой таблицы. Если используются декларации на бумажном носителе, второе значение должно быть внесено в правую часть графы 24.</td></tr>
<tr><td><a id="p109472"></a>8/6</td><td><a id="p109473"></a>Статистическое значение</td><td><a id="p109474"></a>n..16,2</td><td><a id="p109475"></a>N</td><td></td><td><a id="p109476"></a>1x</td><td></td></tr>
<tr><td colspan="7"><a id="p109477"></a><a id="p109478"></a>&lt;1&gt; ОЖ N L 328, 28.11.2012, стр. 7 - 15.<br>&lt;2&gt; Регламент (ЕС) 113/2010 Европейской Комиссии от 9 февраля 2010 г. об имплементации Регламента (ЕС) 471/2009 Европейского Парламента и Совета ЕС о статистике Сообщества по внешней торговле с государствами, не являющимися членами ЕС, в отношении охвата торговлей, определения данных, свода статистики по торговле, по характеристикам бизнеса и валюте выставленных счетов, а также по специальным товарам и обращении (ОЖ N L 37, 10.2.2010, стр. 1)</td></tr>
</table>


<a id="p109479"></a>**ТИТУЛ II. КОДЫ В ОТНОШЕНИИ ТРЕБОВАНИЙ К ОБЩИМ ДАННЫМ**
**ДЛЯ ДЕКЛАРАЦИЙ И УВЕДОМЛЕНИЙ**

<a id="p109480"></a>**КОДЫ**

<a id="p109481"></a>**1. ВВЕДЕНИЕ**

<a id="p109482"></a>Данный Титул содержит коды, которые используются в стандартных электронных и бумажных декларациях и уведомлениях.

<a id="p109483"></a>**2. КОДЫ**

<a id="p109484"></a>1/1. Вид декларации


| <a id="p109485"></a>IM: | <a id="p109486"></a>Для торговли со странами и территориями, расположенными за пределами таможенной территории Союза.<br>Для помещения товаров на таможенную процедуру, указанную в колонках H1 - H4, H6 и I1 Таблицы требований к данным в Титуле I Приложения B к Делегированному Регламенту (ЕС) 2015/2446.<br>Для помещения товаров не из Союза на таможенную процедуру в контексте торговли между государствами-членами ЕС. |
| --- | --- |
| <a id="p109487"></a>CO: | <a id="p109488"></a>- Товары Союза, подлежащие применению специальных мер в переходный период после присоединения новых государств-членов ЕС.<br>- Товары Союза в контексте торговли между частями таможенной территории Союза, к которым применяются положения [Директивы](https://bukva.ai/docs/direktiva-2006112es/statya-1) (ЕС) 2006/112/ЕС Совета ЕС <*> или [Директивы](https://bukva.ai/docs/direktiva-2008118es/statya-1) 2008/118/ЕС Совета ЕС <**>, и частями указанной территории, к которой указанные положения не применяются, или в контексте торговли между частями указанной территории, где указанные положения не применяются, как указано в колонке H5 таблицы требований к данным в Титуле I Приложения D к Делегированному Регламенту (ЕС) 2015/2446. |


<a id="p109489"></a>

---

<a id="p109490"></a><*> [Директива](https://bukva.ai/docs/direktiva-2006112es/statya-1) 2006/112/ЕС Совета ЕС от 28 ноября 2006 г. об общей системе налога на добавленную стоимость (ОЖ N L 347, 11.12.2006, стр. 1).
<a id="p109491"></a><**> [Директива](https://bukva.ai/docs/direktiva-2008118es/statya-1) 2008/118/ЕС Совета ЕС от 16 декабря 2008 г. об общих условиях взимания акцизов и отмене Директивы 92/12/ЕЭС (ОЖ N L 9, 14.1.2009, стр. 12).

<a id="p109492"></a>1/2. Вид дополнительной декларации
<a id="p109493"></a>A - для стандартной таможенной декларации (согласно [Статье 162](https://bukva.ai/docs/reglament-9522013/statya-162#p101455) Кодекса);
<a id="p109494"></a>B - для упрощенной декларации на случайной основе (согласно [Статье 166(1)](https://bukva.ai/docs/reglament-9522013/statya-1#p101475) Кодекса);
<a id="p109495"></a>C - для упрощенной таможенной декларации, используемой регулярно (согласно [Статье 166(2)](https://bukva.ai/docs/reglament-9522013/statya-1#p101476) Кодекса);
<a id="p109496"></a>D - для подачи стандартной таможенной декларации (той, которая указана под [кодом A](https://bukva.ai/docs/reglament-20152447/statya-350#p109493)) в соответствии со [Статьей 171](https://bukva.ai/docs/reglament-9522013/statya-171#p101515) Кодекса;
<a id="p109497"></a>E - для подачи упрощенной декларации (той, которая указана под [кодом B](https://bukva.ai/docs/reglament-20152447/statya-350#p109494)) в соответствии со [Статьей 171](https://bukva.ai/docs/reglament-9522013/statya-171#p101515) Кодекса;
<a id="p109498"></a>F - для подачи упрощенной декларации (той, которая указана под [кодом C](https://bukva.ai/docs/reglament-20152447/statya-350#p109495)) в соответствии со [Статьей 171](https://bukva.ai/docs/reglament-9522013/statya-171#p101515) Кодекса;
<a id="p109499"></a>R - ретроспективная подача экспортной или реэкспортной декларации в соответствии со Статьей 249 Делегированного Регламента (ЕС) 2015/2446 и [Статьей 337](https://bukva.ai/docs/reglament-20152447/statya-337#p102903) Имплементационного Регламента (ЕС) 2015/2447
<a id="p109500"></a>X - для дополнительной декларации упрощенных деклараций, на которую распространяются коды [B](https://bukva.ai/docs/reglament-20152447/statya-350#p109494) и [E](https://bukva.ai/docs/reglament-20152447/statya-350#p109497);
<a id="p109501"></a>Y - для дополнительной декларации упрощенных деклараций, на которую распространяются коды [C](https://bukva.ai/docs/reglament-20152447/statya-350#p109495) и [F](https://bukva.ai/docs/reglament-20152447/statya-350#p109498);
<a id="p109502"></a>Z - для дополнительной декларации по процедуре, на которую распространяется [Статья 182](https://bukva.ai/docs/reglament-9522013/statya-182#p101580) Кодекса.

<a id="p109503"></a>1/10. Процедура
<a id="p109504"></a>Коды, вносимые в данный подраздел, являются четырехзначными, состоящими из двузначного кода, представляющего запрашиваемую процедуру, после которого следует второй двухзначный код, представляющий предыдущую процедуру. Список двузначных кодов дан ниже.
<a id="p109505"></a>"Предыдущая процедура" - процедура, на которую товары были помещены до помещения на запрашиваемую процедуру.
<a id="p109506"></a>Необходимо отметить, что если предыдущей процедурой является таможенное хранение или временный допуск или если товары пришли из свободной зоны, то соответствующий код должен использоваться, только если товары не были помещены на внутреннюю или внешнюю переработку или конечное использование.
<a id="p109507"></a>Таким же образом, если товары, ранее временно экспортированные, реимпортируются и выпускаются в свободное обращение после того, как они были помещены на таможенное хранение, временный допуск или в свободную зону, то это считается простым реимпортом после временного экспорта.
<a id="p109508"></a>Например: ввоз для внутреннего использования с одновременным ввозом для свободного обращения товаров, экспортированных по внешней переработке и помещенных на таможенное хранение при реимпорте = 6121 (не 6171). (Первая операция: временный экспорт по внешней переработке = 2100; вторая операция: хранение на таможенном складе = 7121; третья операция: ввоз для внутреннего использования + ввоз для свободного обращения = 6121).
<a id="p109509"></a>Коды, указанные в списке ниже с буквой (a), не могут использоваться в качестве первых двух знаков кода процедуры, а только указывают на предыдущую процедуру.
<a id="p109510"></a>Например: 4054 = ввоз для свободного обращения и внутреннего использования товаров, ранее помещенных на внутреннюю переработку в другом государстве-члене ЕС.
<a id="p109511"></a>Список процедур для целей кодирования
<a id="p109512"></a>Два из этих основных элементов должны быть объединены для получения четырехзначного кода.
<a id="p109513"></a>00 - Данный код используется для того, чтобы показать, что не было предыдущей процедуры (a);
<a id="p109514"></a>01 - Выпуск в свободное обращение товаров, одновременно перенаправленных в контексте торговли между частями таможенной территории Союза, в которых применяются положения [Директивы](https://bukva.ai/docs/direktiva-2006112es/statya-1) 2006/11/ЕС или [Директивы](https://bukva.ai/docs/direktiva-2008118es/statya-1) 2008/118/ЕС, и частями указанной территории, в которых данные положения не применяются, или в контексте торговли между частями указанной территории, где данные положения не применяются.
<a id="p109515"></a>Примеры: Товары не из Союза, прибывающие из третьей страны, выпущенные в свободное обращение в Германии и направленные на Канарские острова.
<a id="p109516"></a>07 - Выпуск товаров для свободного обращения, одновременно помещенных на другую процедуру хранения, кроме процедуры таможенного хранения, если ни НДС, ни (если это применимо) акцизные сборы не были выплачены.
<a id="p109517"></a>Разъяснение: Данный код должен использоваться, если товары выпускаются в свободное обращение, но если НДС и акцизные сборы не были выплачены.
<a id="p109518"></a>Примеры: Импортированный сахар-сырец выпускается в свободное обращение, но НДС не был выплачен. Если товары помещены на склад или в утвержденное место, кроме таможенного склада, то выплата НДС приостанавливается.
<a id="p109519"></a>Импортированные минеральные масла выпускаются в свободное обращение, и НДС не был выплачен. Если товары хранятся на налоговом складе, выплата НДС и акцизных сборов приостанавливается.
<a id="p109520"></a>40 - Одновременный выпуск в свободное обращение и внутреннее использование товаров.
<a id="p109521"></a>Ввоз для внутреннего использования товаров в контексте торговли между Союзом и странами, с которыми он образует таможенный союз.
<a id="p109522"></a>Ввоз для внутреннего использования товаров в контексте торговли, указанной в [Статье 1(3)](https://bukva.ai/docs/reglament-9522013/statya-1#p100107) Кодекса.
<a id="p109523"></a>Примеры:
- <a id="p109524"></a>Товары, прибывающие из Японии с оплатой таможенной пошлины, НДС и, если это применимо, акцизных сборов.
- <a id="p109525"></a>Товары, прибывающие из Андорры и ввозимые для внутреннего использования в Германии.
- <a id="p109526"></a>Товары, прибывающие из Мартиники и ввозимые для внутреннего использования в Бельгии.
<a id="p109527"></a>42 - Одновременный выпуск в свободное обращение и внутреннее использование товаров, которые подлежат освобождению от НДС при поставке в другое государство-член ЕС и, если это применимо, приостановке акцизных сборов.
<a id="p109528"></a>Ввоз для внутреннего использования товаров Союза в контексте торговли между частями таможенной территории Союза, в которых положения [Директивы](https://bukva.ai/docs/direktiva-2006112es/statya-1) 2006/112/ЕС и [Директивы](https://bukva.ai/docs/direktiva-2008118es/statya-1) 2008/118/ЕС не применяются, и частями указанной территории, в которых эти положения применяются, которые подлежат освобождению от НДС при поставке в другое государство-член ЕС и, если это применимо, приостановке акцизного сбора.
<a id="p109529"></a>Разъяснение: Освобождение от оплаты НДС и, если это применимо, приостановка акцизного сбора предоставляются в связи с тем, что после импорта следует поставка внутри Союза или передача товаров в другое государство-член ЕС. В этом случае НДС и, если это применимо, акцизная пошлина должны быть оплачены в государстве-члене ЕС окончательного места назначения. Для использования данной процедуры лица должны выполнить и другие условия, указанные в [Статье 143(2)](https://bukva.ai/docs/direktiva-2006112es/statya-1#p100881) Директивы 2006/112/ЕС, и, если это применимо, условия, указанные в [Статье 17(1)(b)](https://bukva.ai/docs/direktiva-2008118es/statya-17#p100219) Директивы 2008/118/ЕС. Информация, требуемая согласно [Статье 143(2)](https://bukva.ai/docs/direktiva-2006112es/statya-1#p100881) Директивы 2006/112/ЕС, вносится в D.E. [3/40](https://bukva.ai/docs/reglament-20152447/statya-350#p110261) Идентификационный номер дополнительных фискальных ссылок.
<a id="p109530"></a>Примеры: Товары не из Союза выпускаются в свободное обращение в одном государстве-члене ЕС и подлежат освобождению от НДС при поставке в другое государство-член ЕС. Оформление НДС выполняется таможенным агентом, который является налоговым представителем, с использованием внутрисоюзной системы НДС.
<a id="p109531"></a>Товары не из Союза, в отношении которых взымаются акцизные сборы, импортированные из третьей страны, которые выпускаются в свободное обращение и подлежат освобождению от НДС при поставке в другое государство-член ЕС. Выпуск в свободное обращение немедленно сопровождается перемещением под режимом приостановки акцизного сбора из места импорта, инициированным зарегистрированным грузоотправителем в соответствии со [Статьей 17(1)(b)](https://bukva.ai/docs/direktiva-2008118es/statya-17#p100219) Директивы 2008/118/ЕС.
<a id="p109532"></a>43 - Одновременный выпуск в свободное обращение и внутреннее использование товаров, подлежащих применению специальных мер, связанных со сбором суммы в переходный период после присоединения государств-членов ЕС.
<a id="p109533"></a>Пример: Выпуск в свободное обращение сельскохозяйственной продукции, подлежащей в течение специального переходного периода после присоединения новых государств-членов ЕС специальной таможенной процедуре или специальным мерам между новыми государствами-членами ЕС и остальным Союзом.
<a id="p109534"></a>44 - Конечное использование
<a id="p109535"></a>Выпуск в свободное обращение и внутреннее использование при освобождении от пошлины или по сниженной ставке пошлины в случае специального использования.
<a id="p109536"></a>Пример: Выпуск в свободное обращение двигателей не из Союза для использования в создании судов гражданской авиации в Европейском Союзе.
<a id="p109537"></a>Товары не из Союза для использования в отдельных категориях кораблей, лодок и других судов и для буровых или производственных платформ.
<a id="p109538"></a>45 - Выпуск товаров в свободное обращение и частичный ввоз для внутреннего использования для либо НДС, либо акцизных сборов, и их частичное помещение на другой склад, кроме таможенного склада.
<a id="p109539"></a>Разъяснение: Данный код должен использоваться для товаров, которые облагаются и НДС, и акцизными сборами, если только одна из этих категорий налогов оплачивается, когда товары выпущены в свободное обращение.
<a id="p109540"></a>Примеры: Сигареты не из Союза выпускаются в свободное обращение, и НДС был оплачен. Если товары находятся на налоговом складе, то оплата акцизных сборов приостанавливается.
<a id="p109541"></a>Акцизные товары, импортированные из третьей страны или из третьей территории, указанной в [Статье 5(3)](https://bukva.ai/docs/reglament-9522013/statya-1#p100163) Директивы 2008/118/ЕС, выпускаются в свободное обращение. За выпуском в свободное обращение сразу же следует перемещение согласно приостановке акцизных сборов, инициированной зарегистрированным грузоотправителем в месте импорта в соответствии со [Статьей 17(1)(b)](https://bukva.ai/docs/direktiva-2008118es/statya-17#p100219) Директивы 2008/118/ЕС, на налоговой склад в том же государстве-члене ЕС.
<a id="p109542"></a>46 - Импорт переработанной продукции, полученной из эквивалентных товаров в процедуре внешней переработки перед экспортом товаров, которые они замещают.
<a id="p109543"></a>Разъяснение: Предварительный импорт в соответствии со [Статьей 223(2)d)](https://bukva.ai/docs/reglament-9522013/statya-1#p101855) Кодекса.
<a id="p109544"></a>Пример: Импорт столов, произведенных из леса не из Союза до помещения леса Союза на внешнюю переработку.
<a id="p109545"></a>48 - Ввоз для внутреннего использования с одновременным выпуском в свободное обращение заменяющей продукции, находящейся на внешней переработке до экспорта дефектных товаров.
<a id="p109546"></a>Разъяснение: Система стандартного обмена (IM-EX), предварительный импорт в соответствии со [Статьей 262(1)](https://bukva.ai/docs/reglament-9522013/statya-1#p102133) Кодекса.
<a id="p109547"></a>51 - Помещение товаров на процедуру внутренней переработки
<a id="p109548"></a>Разъяснение: Внутренняя переработка в соответствии со [Статьей 256](https://bukva.ai/docs/reglament-9522013/statya-256#p102086) Кодекса.
<a id="p109549"></a>53 - Помещение товаров на временный допуск.
<a id="p109550"></a>Разъяснение: Помещение товаров не из Союза, предназначенных для реэкспорта на процедуру временного допуска.
<a id="p109551"></a>Может использоваться на таможенной территории Союза с общим или частичным освобождением от импортных пошлин в соответствии со [Статьей 250](https://bukva.ai/docs/reglament-9522013/statya-250#p102039) Кодекса.
<a id="p109552"></a>Пример: Временный допуск, например для выставки.
<a id="p109553"></a>48 - Ввоз для внутреннего использования с одновременным выпуском в свободное обращение заменяющей продукции, находящейся на внешней переработке до экспорта дефектных товаров.
<a id="p109554"></a>Разъяснение: Система стандартного обмена (IM-EX), предварительный импорт в соответствии со [Статьей 262(1)](https://bukva.ai/docs/reglament-9522013/statya-1#p102133) Кодекса.
<a id="p109555"></a>51 - Помещение товаров на процедуру внутренней переработки
<a id="p109556"></a>Разъяснение: Внутренняя переработка в соответствии со [Статьей 256](https://bukva.ai/docs/reglament-9522013/statya-256#p102086) Кодекса.
<a id="p109557"></a>53 - Помещение товаров на временный допуск.
<a id="p109558"></a>Разъяснение: Помещение товаров не из Союза, предназначенных для реэкспорта, на процедуру временного допуска.
<a id="p109559"></a>Может использоваться на таможенной территории Союза с общим или частичным освобождением от импортных пошлин в соответствии со [Статьей 250](https://bukva.ai/docs/reglament-9522013/statya-250#p102039) Кодекса.
<a id="p109560"></a>Пример: Временный допуск, например, для выставки.
<a id="p109561"></a>54 - Внутренняя переработка в другом государстве-члене ЕС (без выпуска их в свободное обращение в указанном государстве-члене ЕС) (a).
<a id="p109562"></a>Разъяснение: Данный код используется для записи операции в целях статистики по торговле внутри Союза.
<a id="p109563"></a>Пример: Товары не из Союза помещаются на внутреннюю переработку в Бельгии (5100). После прохождения внутренней переработки они направляются в Германию для выпуска в свободное обращение (4054) или на дальнейшую переработку (5154).
<a id="p109564"></a>61 - Реимпорт с одновременным выпуском в свободное обращение и внутреннее использование товаров.
<a id="p109565"></a>Разъяснение: Товары, реимпортированные из третьей страны, с оплатой таможенных пошлин и НДС.
<a id="p109566"></a>63 - Реимпорт с одновременным выпуском в свободное обращение и внутреннее использование товаров, которые подлежат освобождению от НДС при поставке в другое государство-член ЕС и, если это применимо, приостановке акцизного сбора.
<a id="p109567"></a>Разъяснение: Освобождение от оплаты НДС и, если это применимо, приостановка акцизного сбора предоставляются, так как за реимпортом следует поставка внутри Союза или передача товаров другому государству-члену ЕС. В таком случае НДС и, если это применимо, акцизный сбор будут оплачены в государстве-члене ЕС окончательного места назначения. Для использования данной процедуры лицо должно выполнять другие условия, указанные в [Статье 143(2)](https://bukva.ai/docs/direktiva-2006112es/statya-1#p100881) Директивы 2006/112/ЕС, и, если это применимо, условия, указанные в [Статье 17(1)(b)](https://bukva.ai/docs/direktiva-2008118es/statya-17#p100219) Директивы 2008/118/ЕС. Информация, требуемая в соответствии со [Статьей 143(2)](https://bukva.ai/docs/direktiva-2006112es/statya-1#p100881) Директивы 2006/112/ЕС, вносится в D.E. [3/40](https://bukva.ai/docs/reglament-20152447/statya-350#p110261) Идентификационный номер дополнительных фискальных ссылок.
<a id="p109568"></a>Примеры: Реимпорт после внешней переработки или временного экспорта, все долги по НДС взимаются с налогового представителя.
<a id="p109569"></a>Акцизные товары, реимпортированные после внешней переработки и выпущенные в свободное обращение, которые подлежат освобождению от НДС при поставке в другое государство-член ЕС. За выпуском в свободное обращение сразу же следует перемещение согласно приостановке акцизного сбора из места реимпорта, инициированное зарегистрированным грузоотправителем в соответствии со [Статьей 17(1)(b)](https://bukva.ai/docs/direktiva-2008118es/statya-17#p100219) Директивы 2008/118/ЕС.
<a id="p109570"></a>68 - Реимпорт с частичным ввозом для внутреннего использования и одновременный выпуск в свободное обращение, и помещение товаров на другую процедуру хранения, кроме процедуры таможенного хранения.
<a id="p109571"></a>Разъяснение: Данный код должен использоваться для товаров, которые облагаются и НДС, и акцизными сборами, если только одна из этих категорий налогов оплачивается, когда товары выпускаются в свободное обращение.
<a id="p109572"></a>Пример: Переработанные спиртные напитки реимпортируются и помещаются на налоговый склад.
<a id="p109573"></a>71 - Помещение товаров на процедуру таможенного хранения.
<a id="p109574"></a>76 - Помещение товаров Союза на процедуру таможенного хранения в соответствии со [Статьей 237(2)](https://bukva.ai/docs/reglament-9522013/statya-1#p101961) Кодекса.
<a id="p109575"></a>Пример: Обваленное мясо крупного рогатого скота, помещенное на таможенное хранение до экспорта (Статья 4 Регламента (ЕС) 1741/2006 Европейской Комиссии от 24 ноября 2006 г. об установлении условий для выдачи специального экспортного возмещения на обваленное мясо крупного рогатого скота, помещенного на процедуру таможенного хранения до экспорта (ОЖ N L 329, 25.11.2006, стр. 7)).
<a id="p109576"></a>После выпуска в свободное обращение подается заявление на возмещение импортной пошлины или освобождение от нее, основанное на товарах, дефектных или не соответствующих условиям договора ([Статья 118](https://bukva.ai/docs/reglament-9522013/statya-118#p101126) Кодекса).
<a id="p109577"></a>В соответствии со [Статьей 118(4)](https://bukva.ai/docs/reglament-9522013/statya-1#p101135) Кодекса указанные товары могут быть помещены на процедуру таможенного хранения вместо вывоза с таможенной территории Союза для предоставления возмещения или освобождения.
<a id="p109578"></a>77 - Производство товаров Союза под таможенным надзором таможенных органов и под таможенным контролем (в значении [Статьи 5(27)](https://bukva.ai/docs/reglament-9522013/statya-1#p100196) и [(3)](https://bukva.ai/docs/reglament-9522013/statya-1#p100163) Кодекса) до экспорта и выплаты экспортного возмещения.
<a id="p109579"></a>Пример: Консервированная продукция из говядины и телятины, произведенная под надзором таможенных органов и под таможенным контролем до экспорта (Статьи 2 и 3 Регламента (ЕС) 1731/2006 Европейской Комиссии от 23 ноября 2006 г. о специальных подробных правилах для применения экспортного возмещения за консервированную продукцию из говядины и телятины (ОЖ N L 325, 24.11.2006, стр. 12)).
<a id="p109580"></a>78 - Помещение товаров в свободную зону. (a)
<a id="p109581"></a>95 - Помещение товаров Союза на другую процедуру хранения, кроме процедуры таможенного хранения, если не были оплачены ни НДС, ни (если это применимо) акцизные сборы.
<a id="p109582"></a>Разъяснение: Данный код должен использоваться в контексте торговли, указанной в [Статье 1(3)](https://bukva.ai/docs/reglament-9522013/statya-1#p100107) Кодекса, а также торговли между Союзом и странами, с которыми он образовал таможенный союз, если не были оплачены ни НДС, ни акцизные сборы.
<a id="p109583"></a>Пример: Сигареты с Канарских островов привезены в Бельгию и хранятся на налоговом складе; выплата НДС и акцизных сборов приостановлена.
<a id="p109584"></a>96 - Помещение товаров Союза на другую процедуру хранения, кроме процедуры таможенного хранения, если либо НДС, либо, если это применимо, акцизные сборы были оплачены, а оплата другого налога приостановлена.
<a id="p109585"></a>Разъяснение: Данный код должен использоваться в контексте торговли, указанной в [Статье 1(3)](https://bukva.ai/docs/reglament-9522013/statya-1#p100107) Кодекса, а также торговли между Союзом и странами, с которыми он образовал таможенный союз, если либо НДС, либо акцизные сборы были оплачены, а выплата другого налога приостановлена.
<a id="p109586"></a>Пример: Сигареты с Канарских островов привезены во Францию и хранятся на налоговом складе; НДС был оплачен, а выплата акцизных сборов приостановлена.

<a id="p109587"></a>Коды процедуры в контексте таможенных деклараций


| <a id="p109588"></a>Колонки (Заголовок таблицы в Приложении D к Делегированному Регламенту (ЕС) 2015/2446 | <a id="p109589"></a>Декларации | <a id="p109590"></a>Коды процедуры Союза, для соответствующих случаев |
| --- | --- | --- |
| <a id="p109591"></a>H1 | <a id="p109592"></a>Декларация на выпуск в свободное обращение и специальную процедуру - специальное использование - декларация конечного использования | <a id="p109593"></a>[01](https://bukva.ai/docs/reglament-20152447/statya-350#p109514), [07](https://bukva.ai/docs/reglament-20152447/statya-350#p109516), [40](https://bukva.ai/docs/reglament-20152447/statya-350#p109520), [42](https://bukva.ai/docs/reglament-20152447/statya-350#p109527), [43](https://bukva.ai/docs/reglament-20152447/statya-350#p109532), [44](https://bukva.ai/docs/reglament-20152447/statya-350#p109534), [45](https://bukva.ai/docs/reglament-20152447/statya-350#p109538), [46](https://bukva.ai/docs/reglament-20152447/statya-350#p109542), [48](https://bukva.ai/docs/reglament-20152447/statya-350#p109545), [61](https://bukva.ai/docs/reglament-20152447/statya-350#p109564), [63](https://bukva.ai/docs/reglament-20152447/statya-350#p109566), [68](https://bukva.ai/docs/reglament-20152447/statya-350#p109570) |
| <a id="p109594"></a>H2 | <a id="p109595"></a>Специальная процедура - хранение - декларация таможенного хранения | <a id="p109596"></a>[71](https://bukva.ai/docs/reglament-20152447/statya-350#p109573) |
| <a id="p109597"></a>H3 | <a id="p109598"></a>Специальная процедура - специальное использование - декларация временного допуска | <a id="p109599"></a>[53](https://bukva.ai/docs/reglament-20152447/statya-350#p109549) |
| <a id="p109600"></a>H4 | <a id="p109601"></a>Специальная процедура - переработка - декларация внутренней переработки | <a id="p109602"></a>[51](https://bukva.ai/docs/reglament-20152447/statya-350#p109547) |
| <a id="p109603"></a>H5 | <a id="p109604"></a>Декларация на ввоз товаров в контексте торговли с территориями, на которых установлены специальные фискальные режимы | <a id="p109605"></a>[40](https://bukva.ai/docs/reglament-20152447/statya-350#p109520), [42](https://bukva.ai/docs/reglament-20152447/statya-350#p109527), [61](https://bukva.ai/docs/reglament-20152447/statya-350#p109564), [63](https://bukva.ai/docs/reglament-20152447/statya-350#p109566), [95](https://bukva.ai/docs/reglament-20152447/statya-350#p109581), [96](https://bukva.ai/docs/reglament-20152447/statya-350#p109584) |
| <a id="p109606"></a>H6 | <a id="p109607"></a>Таможенная декларация в почтовом перемещении на выпуск в свободное обращение | <a id="p109608"></a>[01](https://bukva.ai/docs/reglament-20152447/statya-350#p109514), [07](https://bukva.ai/docs/reglament-20152447/statya-350#p109516), [40](https://bukva.ai/docs/reglament-20152447/statya-350#p109520) |
| <a id="p109609"></a>I1 | <a id="p109610"></a>Импортная упрощенная декларация | <a id="p109611"></a>[01](https://bukva.ai/docs/reglament-20152447/statya-350#p109514), [07](https://bukva.ai/docs/reglament-20152447/statya-350#p109516), [40](https://bukva.ai/docs/reglament-20152447/statya-350#p109520), [42](https://bukva.ai/docs/reglament-20152447/statya-350#p109527), [43](https://bukva.ai/docs/reglament-20152447/statya-350#p109532), [44](https://bukva.ai/docs/reglament-20152447/statya-350#p109534), [45](https://bukva.ai/docs/reglament-20152447/statya-350#p109538), [46](https://bukva.ai/docs/reglament-20152447/statya-350#p109542), [48](https://bukva.ai/docs/reglament-20152447/statya-350#p109545), [51](https://bukva.ai/docs/reglament-20152447/statya-350#p109547), [53](https://bukva.ai/docs/reglament-20152447/statya-350#p109549), [61](https://bukva.ai/docs/reglament-20152447/statya-350#p109564), [63](https://bukva.ai/docs/reglament-20152447/statya-350#p109566), [68](https://bukva.ai/docs/reglament-20152447/statya-350#p109570) |


<a id="p109612"></a>1/11. Дополнительная процедура
<a id="p109613"></a>Если этот элемент данных используется для определения процедуры Союза, то первый знак кода определяет категорию мер следующим образом:


| <a id="p109614"></a>Внутренняя переработка | <a id="p109615"></a>Axx |  |
| --- | --- | --- |
| <a id="p109616"></a>Внешняя переработка | <a id="p109617"></a>Bxx |  |
| <a id="p109618"></a>Освобождение | <a id="p109619"></a>Cxx |  |
| <a id="p109620"></a>Временный допуск | <a id="p109621"></a>Dxx |  |
| <a id="p109622"></a>Сельскохозяйственная продукция | <a id="p109623"></a>Exx |  |
| <a id="p109624"></a>Другие | <a id="p109625"></a>Fxx |  |


<a id="p109626"></a>Внутренняя переработка ([Статья 256](https://bukva.ai/docs/reglament-9522013/statya-256#p102086) Кодекса)


| <a id="p109627"></a>Код | <a id="p109628"></a>Процедура |
| --- | --- |
|  | <a id="p109629"></a>Импорт |
| <a id="p109630"></a>A04 | <a id="p109631"></a>Товары, которые помещены на процедуру внутренней переработки (только НДС) |
| <a id="p109632"></a>A10 | <a id="p109633"></a>Уничтожение товаров на внутренней переработке |


<a id="p109634"></a>Внешняя переработка ([Статья 259](https://bukva.ai/docs/reglament-9522013/statya-259#p102110) Кодекса)


| <a id="p109635"></a>Код | <a id="p109636"></a>Процедура |
| --- | --- |
|  | <a id="p109637"></a>Импорт |
| <a id="p109638"></a>B02 | <a id="p109639"></a>Переработанная продукция, возвращающаяся после ремонта по гарантии в соответствии со [Статьей 260](https://bukva.ai/docs/reglament-9522013/statya-260#p102119) Кодекса (товары, отремонтированные бесплатно) |
| <a id="p109640"></a>B03 | <a id="p109641"></a>Переработанная продукция, возвращающаяся после замены по гарантии в соответствии со [Статьей 261](https://bukva.ai/docs/reglament-9522013/statya-261#p102123) Кодекса (стандартная система обмена) |
| <a id="p109642"></a>B06 | <a id="p109643"></a>Переработанная продукция, возвращающаяся - только НДС |


<a id="p109644"></a>Освобождение от импортных пошлин ([Регламент](https://bukva.ai/docs/reglament-11862009/statya-1) (ЕС) 1186/2009 Совета ЕС [<*>](https://bukva.ai/docs/reglament-20152447/statya-350#p109829))


<table>
<colgroup><col width="8%"><col width="78%"><col width="14%"></colgroup>
<tr><td></td><td><a id="p109645"></a>Освобождение от импортных пошлин</td><td></td></tr>
<tr><td><a id="p109646"></a>Код</td><td><a id="p109647"></a>Описание</td><td><a id="p109648"></a>Статья N</td></tr>
<tr><td><a id="p109649"></a>C01</td><td><a id="p109650"></a>Личная собственность, принадлежащая физическим лицам, переезжающим на постоянное место жительства на таможенную территорию Союза</td><td><a id="p109651"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-3#p100049">3</a></td></tr>
<tr><td><a id="p109652"></a>C02</td><td><a id="p109653"></a>Приданое и домашние вещи, импортированные по случаю заключения брака</td><td><a id="p109654"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-12#p100085">12(1)</a></td></tr>
<tr><td><a id="p109655"></a>C03</td><td><a id="p109656"></a>Подарки, которые обычно дарят по случаю заключения брака</td><td><a id="p109657"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-12#p100086">12(2)</a></td></tr>
<tr><td><a id="p109658"></a>C04</td><td><a id="p109659"></a>Личное имущество, приобретенное по наследству физическим лицом, имеющим свое постоянное место жительства на таможенной территории Союза</td><td><a id="p109660"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-17#p100103">17</a></td></tr>
<tr><td><a id="p109661"></a>C06</td><td><a id="p109662"></a>Школьные принадлежности, школьные материалы и другие школьные домашние вещи</td><td><a id="p109663"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-21#p100122">21</a></td></tr>
<tr><td><a id="p109664"></a>C07</td><td><a id="p109665"></a>Грузы, имеющие ничтожную стоимость</td><td><a id="p109666"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-23#p100132">23</a></td></tr>
<tr><td><a id="p109667"></a>C08</td><td><a id="p109668"></a>Грузы, направленные от одного частного лица другому</td><td><a id="p109669"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-25#p100142">25</a></td></tr>
<tr><td><a id="p109670"></a>C09</td><td><a id="p109671"></a>Основные средства и другое оборудование, импортированные при переводе деятельности из третьей страны в Союз</td><td><a id="p109672"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-28#p100169">28</a></td></tr>
<tr><td><a id="p109673"></a>C10</td><td><a id="p109674"></a>Основные средства и другое оборудование, принадлежащие лицам, имеющим свободную профессию, и юридическим лицам, вовлеченным в деятельность, не связанную с получением прибыли</td><td><a id="p109675"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-34#p100192">34</a></td></tr>
<tr><td><a id="p109676"></a>C11</td><td><a id="p109677"></a>Образовательные, научные и культурные материалы; научные инструменты и аппаратура, указанные в <a href="https://bukva.ai/docs/reglament-11862009/statya-1#p100673">Приложении I</a> к Регламенту (ЕС) 1186/2009</td><td><a id="p109678"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-42#p100224">42</a></td></tr>
<tr><td><a id="p109679"></a>C12</td><td><a id="p109680"></a>Образовательные, научные и культурные материалы; инструменты и аппаратура, используемые для научных исследований, указанные в <a href="https://bukva.ai/docs/reglament-11862009/statya-1#p100720">Приложении II</a> к Регламенту (ЕС) 1186/2009</td><td><a id="p109681"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-43#p100226">43</a></td></tr>
<tr><td><a id="p109682"></a>C13</td><td><a id="p109683"></a>Образовательные, научные и культурные материалы; инструменты и аппаратура, используемые для научных исследований, импортированные исключительно для некоммерческих целей (в том числе запасные части, компоненты, приспособления и инструменты)</td><td><a id="p109684"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-44#p100230">44</a> - <a href="https://bukva.ai/docs/reglament-11862009/statya-45#p100235">45</a></td></tr>
<tr><td><a id="p109685"></a>C14</td><td><a id="p109686"></a>Оборудование, импортированное для некоммерческих целей научно-исследовательскими учреждениями или организациями, базирующимися за пределами Союза, или от их имени</td><td><a id="p109687"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-51#p100258">51</a></td></tr>
<tr><td><a id="p109688"></a>C15</td><td><a id="p109689"></a>Лабораторные животные, а также биологические или химические вещества, предназначенные для исследований</td><td><a id="p109690"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-53#p100275">53</a></td></tr>
<tr><td><a id="p109691"></a>C16</td><td><a id="p109692"></a>Терапевтические вещества человеческого происхождения и реагенты определения группы крови и совместимости тканей</td><td><a id="p109693"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-54#p100285">54</a></td></tr>
<tr><td><a id="p109694"></a>C17</td><td><a id="p109695"></a>Инструменты и аппаратура, используемые в медицинских исследованиях, устанавливающие медицинские диагнозы или осуществляющие медицинское лечение</td><td><a id="p109696"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-57#p100303">57</a></td></tr>
<tr><td><a id="p109697"></a>C18</td><td><a id="p109698"></a>Эталонные вещества для контроля качества медицинской продукции</td><td><a id="p109699"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-59#p100315">59</a></td></tr>
<tr><td><a id="p109700"></a>C19</td><td><a id="p109701"></a>Фармацевтическая продукция, используемая для международных спортивных мероприятий</td><td><a id="p109702"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-60#p100319">60</a></td></tr>
<tr><td><a id="p109703"></a>C20</td><td><a id="p109704"></a>Товары для благотворительных организаций или филантропов - предметы первой необходимости, импортированные государственными организациями или другими одобренными организациями</td><td><a id="p109705"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-61#p100326">61 (1) (a)</a></td></tr>
<tr><td><a id="p109706"></a>C21</td><td><a id="p109707"></a>Изделия, указанные в <a href="https://bukva.ai/docs/reglament-11862009/statya-1#p100781">Приложении III</a> к Регламенту (ЕС) 186/2009, предназначенные для слепых</td><td><a id="p109708"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-66#p100348">66</a></td></tr>
<tr><td><a id="p109709"></a>C22</td><td><a id="p109710"></a>Изделия, указанные в <a href="https://bukva.ai/docs/reglament-11862009/statya-1#p100798">Приложении IV</a> к Регламенту (ЕС) 1186/2009, предназначенные для слепых, импортированные самими слепыми для их собственного использования (в том числе запасные части, компоненты, приспособления и инструменты)</td><td><a id="p109711"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-67#p100352">67(1) (a)</a> и <a href="https://bukva.ai/docs/reglament-11862009/statya-67#p100354">67(2)</a></td></tr>
<tr><td><a id="p109712"></a>C23</td><td><a id="p109713"></a>Изделия, указанные в <a href="https://bukva.ai/docs/reglament-11862009/statya-1#p100798">Приложении IV</a> к Регламенту (ЕС) 1186/2009, предназначенные для слепых, импортированные определенными учреждениями или организациями (в том числе запасные части, компоненты, приспособления и инструменты)</td><td><a id="p109714"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-67#p100353">67(1) (b)</a> и <a href="https://bukva.ai/docs/reglament-11862009/statya-67#p100354">67(2)</a></td></tr>
<tr><td><a id="p109715"></a>C24</td><td><a id="p109716"></a>Изделия, предназначенные для других лиц с ограниченными возможностями (кроме слепых лиц), импортированные самими лицами с ограниченными возможностями для своего собственного использования (в том числе запасные части, компоненты, приспособления и инструменты)</td><td><a id="p109717"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-68#p100358">68(1) (a)</a> и <a href="https://bukva.ai/docs/reglament-11862009/statya-68#p100360">68(2)</a></td></tr>
<tr><td><a id="p109718"></a>C25</td><td><a id="p109719"></a>Изделия, предназначенные для других лиц с ограниченными возможностями (кроме слепых лиц), импортированные определенными учреждениями или организациями (в том числе запасные части, компоненты, приспособления и инструменты)</td><td><a id="p109720"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-68#p100359">68(1) (b)</a> и <a href="https://bukva.ai/docs/reglament-11862009/statya-68#p100360">68(2)</a></td></tr>
<tr><td><a id="p109721"></a>C26</td><td><a id="p109722"></a>Товары, импортированные для жертв катастроф</td><td><a id="p109723"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-74#p100380">74</a></td></tr>
<tr><td><a id="p109724"></a>C27</td><td><a id="p109725"></a>Награды, присваиваемые правительствами третьих стран лицам, чье постоянное место жительства находится на таможенной территории Союза</td><td><a id="p109726"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-81#p100408">81 (a)</a></td></tr>
<tr><td><a id="p109727"></a>C28</td><td><a id="p109728"></a>Товары, импортированные на таможенную территорию Союза лицами, которые прибыли с официальным визитом в третью страну или которые получили их в связи с этим как подарок от принимающих органов</td><td><a id="p109729"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-82#p100416">82 (a)</a></td></tr>
<tr><td><a id="p109730"></a>C29</td><td><a id="p109731"></a>Товары, которые должны быть использованы монархами или главами государств</td><td><a id="p109732"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-85#p100428">85</a></td></tr>
<tr><td><a id="p109733"></a>C30</td><td><a id="p109734"></a>Образцы товаров ничтожной стоимости, импортированные в целях продвижения торговли</td><td><a id="p109735"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-86#p100436">86</a></td></tr>
<tr><td><a id="p109736"></a>C31</td><td><a id="p109737"></a>Печатные рекламные материалы</td><td><a id="p109738"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-87#p100441">87</a></td></tr>
<tr><td><a id="p109739"></a>C32</td><td><a id="p109740"></a>Мелкие репрезентативные образцы товаров, произведенных за пределами таможенной территории Союза, предназначенные для торговых ярмарок или подобных мероприятий</td><td><a id="p109741"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-90#p100455">90 (a)</a></td></tr>
<tr><td><a id="p109742"></a>C33</td><td><a id="p109743"></a>Товары, импортированные для изучения, анализа или испытания</td><td><a id="p109744"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-95#p100489">95</a></td></tr>
<tr><td><a id="p109745"></a>C34</td><td><a id="p109746"></a>Грузы, направленные организациям, защищающим авторские права или промышленные или коммерческие патентные права</td><td><a id="p109747"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-102#p100510">102</a></td></tr>
<tr><td><a id="p109748"></a>C35</td><td><a id="p109749"></a>Информационная литература для туристов</td><td><a id="p109750"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-103#p100514">103</a></td></tr>
<tr><td><a id="p109751"></a>C36</td><td><a id="p109752"></a>Различные документы и статьи</td><td><a id="p109753"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-104#p100521">104</a></td></tr>
<tr><td><a id="p109754"></a>C37</td><td><a id="p109755"></a>Вспомогательные материалы для складирования и защиты товаров во время их перевозки</td><td><a id="p109756"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-105#p100542">105</a></td></tr>
<tr><td><a id="p109757"></a>C38</td><td><a id="p109758"></a>Подстилки, корм для скота и пища для животных во время их перевозки</td><td><a id="p109759"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-106#p100546">106</a></td></tr>
<tr><td><a id="p109760"></a>C39</td><td><a id="p109761"></a>Топлива и масла, представленные в наземных моторных транспортных средствах и специальных контейнерах</td><td><a id="p109762"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-107#p100550">107</a></td></tr>
<tr><td><a id="p109763"></a>C40</td><td><a id="p109764"></a>Материалы для строительства, обслуживания или украшения кладбищ и для мемориалов жертвам войны</td><td><a id="p109765"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-112#p100582">112</a></td></tr>
<tr><td><a id="p109766"></a>C41</td><td><a id="p109767"></a>Гробы, урны с прахом и похоронные принадлежности</td><td><a id="p109768"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-113#p100586">113</a></td></tr>
<tr><td><a id="p109769"></a>C42</td><td><a id="p109770"></a>Личная собственность, ввезенная для свободного обращения до того, как соответствующее лицо переедет на постоянное место жительства на таможенной территории Союза (освобождение от пошлины согласно обязательству)</td><td><a id="p109771"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-9#p100072">9(1)</a></td></tr>
<tr><td><a id="p109772"></a>C43</td><td><a id="p109773"></a>Личное имущество, ввезенное для свободного обращения, принадлежащее физическому лицу, имеющему намерение переехать на постоянное место жительства на таможенную территорию Союза (беспошлинный допуск согласно обязательству)</td><td><a id="p109774"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-10#p100074">10</a></td></tr>
<tr><td><a id="p109775"></a>C44</td><td><a id="p109776"></a>Личное имущество, приобретенное по наследству юридическими лицами, вовлеченными в деятельность, не связанную с получением прибыли, которые учреждены на таможенной территории Союза</td><td><a id="p109777"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-20#p100118">20</a></td></tr>
<tr><td><a id="p109778"></a>C45</td><td><a id="p109779"></a>Сельскохозяйственная, животноводческая, пчеловодческая, садоводческая и лесная продукция с объектов, расположенных в третьей стране, прилегающих к таможенной территории Союза</td><td><a id="p109780"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-35#p100196">35</a></td></tr>
<tr><td><a id="p109781"></a>C46</td><td><a id="p109782"></a>Продукция рыболовства или рыбоводства, осуществляемого на озерах или водных объектах, граничащих с государством-членом ЕС и третьей страной, рыбаками Союза, и продукция охотничьей деятельности, осуществляемой на таких озерах и водных объектах спортсменами Союза</td><td><a id="p109783"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-38#p100203">38</a></td></tr>
<tr><td><a id="p109784"></a>C47</td><td><a id="p109785"></a>Семена, удобрения и продукция для обработки почвы и культур, предназначенные для использования на объектах, расположенных на таможенной территории Союза, прилегающих к третьей стране</td><td><a id="p109786"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-39#p100207">39</a></td></tr>
<tr><td><a id="p109787"></a>C48</td><td><a id="p109788"></a>Товары, содержащиеся в личном багаже и освобожденные от НДС</td><td><a id="p109789"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-41#p100215">41</a></td></tr>
<tr><td><a id="p109790"></a>C49</td><td><a id="p109791"></a>Товары для благотворительных организаций или филантропов - товары каждого описания, которые были направлены бесплатно и которые должны использоваться для привлечения средств на случайных благотворительных мероприятиях для нуждающихся лиц</td><td><a id="p109792"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-61#p100327">61 (1) (b)</a></td></tr>
<tr><td><a id="p109793"></a>C50</td><td><a id="p109794"></a>Товары для благотворительных организаций или филантропов - оборудование и офисные материалы, направленные бесплатно</td><td><a id="p109795"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-61#p100328">61 (1) (c)</a></td></tr>
<tr><td><a id="p109796"></a>C51</td><td><a id="p109797"></a>Кубки, медали и подобные предметы, имеющие существенный символический характер, которыми были награждены в третьих странах лица, имеющие постоянное место жительства на таможенной территории Союза</td><td><a id="p109798"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-81#p100409">81 (b)</a></td></tr>
<tr><td><a id="p109799"></a>C52</td><td><a id="p109800"></a>Кубки, медали и подобные предметы, имеющие существенный символический характер, которые были вручены бесплатно органами или лицами, учрежденными в третьей стране для предоставления на таможенной территории Союза</td><td><a id="p109801"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-81#p100410">81 (c)</a></td></tr>
<tr><td><a id="p109802"></a>C53</td><td><a id="p109803"></a>Награды, трофеи и сувениры символического характера и ограниченной стоимости, предназначенные для бесплатного распространения лицам, имеющим постоянное место жительства в третьих странах на бизнес-конференциях или подобных международных мероприятиях</td><td><a id="p109804"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-81#p100411">81 (d)</a></td></tr>
<tr><td><a id="p109805"></a>C54</td><td><a id="p109806"></a>Товары, импортированные на таможенную территорию Союза лицами, приехавшими с официальным визитом на таможенную территорию Союза и которые намерены вручить их по этому случаю в качестве подарка принимающим органам</td><td><a id="p109807"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-82#p100417">82 (b)</a></td></tr>
<tr><td><a id="p109808"></a>C55</td><td><a id="p109809"></a>Товары, направленные в качестве подарков в знак дружбы или доброй воли официальным органом, публичным органом или группой, осуществляющими деятельность в общественных интересах, которые расположены в третьей стране, официальному органу, государственному органу или группе, осуществляющим деятельность в общественных интересах, которые расположены на таможенной территории Союза, и одобренные компетентными органами для получения этих изделий без оплаты пошлины</td><td><a id="p109810"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-82#p100418">82 (c)</a></td></tr>
<tr><td><a id="p109811"></a>C56</td><td><a id="p109812"></a>Изделия для рекламных целей, без внутренней коммерческой стоимости, направленные бесплатно поставщиками своим потребителям, которые, кроме своей рекламной функции, не могут быть использованы иным способом</td><td><a id="p109813"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-89#p100450">89</a></td></tr>
<tr><td><a id="p109814"></a>C57</td><td><a id="p109815"></a>Товары, импортированные исключительно для того, чтобы они были продемонстрированы, или для демонстрации машин и аппаратов, произведенных за пределами таможенной территории Союза, и показа на торговых ярмарках или подобных мероприятиях</td><td><a id="p109816"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-90#p100456">90(1) (b)</a></td></tr>
<tr><td><a id="p109817"></a>C58</td><td><a id="p109818"></a>Различные материалы небольшой стоимости, такие как краски, лаки, обои и т.п., используемые в строительстве, оснащении и отделке временных стендов, занятых представителями третьих стран на торговых ярмарках или подобных мероприятиях, которые разрушаются после использования</td><td><a id="p109819"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-90#p100457">90(1) (c)</a></td></tr>
<tr><td><a id="p109820"></a>C59</td><td><a id="p109821"></a>Печатные материалы, каталоги, проспекты, прайс-листы, рекламные постеры, календари, иллюстрированные или неиллюстрированные, фотографии без рамок и другие изделия, поставленные бесплатно для рекламы товаров, произведенных за пределами таможенной территории Союза и показанные на торговых ярмарках или подобных мероприятиях</td><td><a id="p109822"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-90#p100458">90(1) (d)</a></td></tr>
<tr><td><a id="p109823"></a>C60</td><td><a id="p109824"></a>Приданное и домашние вещи, импортированные по случаю заключения брака, ввозимые для свободного обращения в первые два месяца до свадьбы (освобождение от пошлины при подаче соответствующего обеспечения)</td><td><a id="p109825"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-12#p100085">12(1)</a>, <a href="https://bukva.ai/docs/reglament-11862009/statya-15#p100095">15(1)(a)</a></td></tr>
<tr><td><a id="p109826"></a>C61</td><td><a id="p109827"></a>Подарки, которые обычно дарят по случаю заключения брака, ввезенные для свободного обращения в первые два месяца до свадьбы (освобождение от пошлины при подаче соответствующего обеспечения)</td><td><a id="p109828"></a><a href="https://bukva.ai/docs/reglament-11862009/statya-12#p100086">12(2)</a>, <a href="https://bukva.ai/docs/reglament-11862009/statya-15#p100095">15(1)(a)</a></td></tr>
<tr><td colspan="3"><a id="p109829"></a>&lt;1&gt; <a href="https://bukva.ai/docs/reglament-11862009/statya-1">Регламент</a> (ЕС) 1186/2009 Совета ЕС от 16 ноября 2009 г., устанавливающий в Сообществе Систему освобождения от таможенных пошлин (ОЖ N L 324, 10.12.2009, стр. 23).</td></tr>
</table>


<a id="p109830"></a>Временный допуск


| <a id="p109831"></a>Код |  | <a id="p109832"></a>Статья N |
| --- | --- | --- |
| <a id="p109833"></a>D01 | <a id="p109834"></a>Паллеты (в том числе запасные части, принадлежности и оборудование паллет) | <a id="p109835"></a>208 и 209 |
| <a id="p109836"></a>D02 | <a id="p109837"></a>Контейнеры (в том числе запасные части, принадлежности и оборудование контейнеров) | <a id="p109838"></a>210 и 211 |
| <a id="p109839"></a>D03 | <a id="p109840"></a>Средства дорожного, железнодорожного, воздушного, морского и внутреннего водного транспорта | <a id="p109841"></a>212 |
| <a id="p109842"></a>D04 | <a id="p109843"></a>Личные предметы и товары для спортивных целей, импортируемые туристами | <a id="p109844"></a>219 |
| <a id="p109845"></a>D05 | <a id="p109846"></a>Бытовые вещи моряков | <a id="p109847"></a>220 |
| <a id="p109848"></a>D06 | <a id="p109849"></a>Материалы для помощи при катастрофах | <a id="p109850"></a>221 |
| <a id="p109851"></a>D07 | <a id="p109852"></a>Медицинское, хирургическое и лабораторное оборудование | <a id="p109853"></a>222 |
| <a id="p109854"></a>D08 | <a id="p109855"></a>Животные (12 месяцев или старше) | <a id="p109856"></a>223 |
| <a id="p109857"></a>D09 | <a id="p109858"></a>Товары для использования в приграничной зоне | <a id="p109859"></a>224 |
| <a id="p109860"></a>D10 | <a id="p109861"></a>Товары, несущие звуковую информацию, изображения или данные | <a id="p109862"></a>225 |
| <a id="p109863"></a>D11 | <a id="p109864"></a>Публичные материалы | <a id="p109865"></a>225 |
| <a id="p109866"></a>D12 | <a id="p109867"></a>Профессиональное оборудование | <a id="p109868"></a>226 |
| <a id="p109869"></a>D13 | <a id="p109870"></a>Педагогические материалы и научное оборудование | <a id="p109871"></a>227 |
| <a id="p109872"></a>D14 | <a id="p109873"></a>Упаковки, полные | <a id="p109874"></a>228 |
| <a id="p109875"></a>D15 | <a id="p109876"></a>Упаковки, пустые | <a id="p109877"></a>228 |
| <a id="p109878"></a>D16 | <a id="p109879"></a>Формы, штампы, блочные конструкции, чертежи, эскизы, измерительные, проверочные и испытательные инструменты и другие подобные изделия | <a id="p109880"></a>229 |
| <a id="p109881"></a>D17 | <a id="p109882"></a>Специальные приборы и инструменты | <a id="p109883"></a>230 |
| <a id="p109884"></a>D18 | <a id="p109885"></a>Товары, подлежащие испытаниям, экспериментам или демонстрации | <a id="p109886"></a>231(a) |
| <a id="p109887"></a>D19 | <a id="p109888"></a>Товары, импортированные согласно удовлетворительно принятым испытаниям в связи с договорами на продажу | <a id="p109889"></a>231(b) |
| <a id="p109890"></a>D20 | <a id="p109891"></a>Товары, используемые для выполнения испытаний, экспериментов или демонстраций без получения дохода (шесть месяцев) | <a id="p109892"></a>231(c) |
| <a id="p109893"></a>D21 | <a id="p109894"></a>Образцы | <a id="p109895"></a>232 |
| <a id="p109896"></a>D22 | <a id="p109897"></a>Средства замены производства (шесть месяцев) | <a id="p109898"></a>233 |
| <a id="p109899"></a>D23 | <a id="p109900"></a>Товары для мероприятий или для продажи | <a id="p109901"></a>234(1) |
| <a id="p109902"></a>D24 | <a id="p109903"></a>Товары для утверждения (шесть месяцев) | <a id="p109904"></a>234(2) |
| <a id="p109905"></a>D25 | <a id="p109906"></a>Произведения искусства, предметы коллекционеров и антиквариат | <a id="p109907"></a>234(3)(a) |
| <a id="p109908"></a>D26 | <a id="p109909"></a>Товары, кроме вновь произведенных, импортированные с целью их продажи на аукционе | <a id="p109910"></a>234(3)(b) |
| <a id="p109911"></a>D27 | <a id="p109912"></a>Запасные части, принадлежности и оборудование | <a id="p109913"></a>235 |
| <a id="p109914"></a>D28 | <a id="p109915"></a>Товары, импортированные в отдельных ситуациях, не имеющих экономического значения | <a id="p109916"></a>236(b) |
| <a id="p109917"></a>D29 | <a id="p109918"></a>Товары, импортированные на срок, не превышающий трех месяцев | <a id="p109919"></a>236(a) |
| <a id="p109920"></a>D30 | <a id="p109921"></a>Транспортные средства для лиц, учрежденных за пределами таможенной территории Союза, или для лиц, готовящихся к переезду на постоянное место жительства за пределами указанной территории | <a id="p109922"></a>216 |
| <a id="p109923"></a>D51 | <a id="p109924"></a>Временный допуск с частичным освобождением от импортных пошлин | <a id="p109925"></a>206 |


<a id="p109926"></a>Сельскохозяйственная продукция


<table>
<colgroup><col width="11%"><col width="89%"></colgroup>
<tr><td><a id="p109927"></a>Код</td><td><a id="p109928"></a>Описание</td></tr>
<tr><td></td><td><a id="p109929"></a>Импорт</td></tr>
<tr><td><a id="p109930"></a>E01</td><td><a id="p109931"></a>Использование цены за единицу для определения таможенной стоимости для отдельных скоропортящихся товаров <a href="https://bukva.ai/docs/reglament-9522013/statya-1#p100775">(Статья 74(2)(c)</a> Кодекса и <a href="#p101368">Статья 142(6))</a></td></tr>
<tr><td><a id="p109932"></a>E02</td><td><a id="p109933"></a>Стандартная стоимость импорта (например: Регламент (ЕС) 543/2011 &lt;*&gt; &lt;**&gt;)</td></tr>
<tr><td colspan="2"><a id="p109934"></a><a id="p109935"></a>&lt;*&gt; Имплементационный Регламент (ЕС) 543/2011 Европейской Комиссии от 7 июня 2011 г., устанавливающий подробные правила применения Регламента (ЕС) 1234/2007 Совета ЕС в отношении секторов фруктов и овощей, а также переработанных фруктов и овощей (ОЖ N L 157, 15.6.2011, стр. 1).<br>&lt;**&gt; Регламент (ЕС) 612/2009 Европейской Комиссии от 7 июля 2009 г. об установлении подробных правил применения системы возмещения экспорта сельскохозяйственной продукции (ОЖ N L 186, 17.7.2009, стр. 1).</td></tr>
</table>


<a id="p109936"></a>Прочее


<table>
<colgroup><col width="11%"><col width="89%"></colgroup>
<tr><td><a id="p109937"></a>Код</td><td><a id="p109938"></a>Описание</td></tr>
<tr><td></td><td><a id="p109939"></a>Импорт</td></tr>
<tr><td><a id="p109940"></a>F01</td><td><a id="p109941"></a>Освобождение от импортных пошлин для возвращенных товаров (<a href="https://bukva.ai/docs/reglament-9522013/statya-203#p101721">Статья 203</a> Кодекса)</td></tr>
<tr><td><a id="p109942"></a>F02</td><td><a id="p109943"></a>Освобождение от импортных пошлин для возвращенных товаров (Специальные обстоятельства, предусмотренные в Статье 159 Делегированного Регламента (ЕС) 2015/2446: сельскохозяйственные товары)</td></tr>
<tr><td><a id="p109944"></a>F03</td><td><a id="p109945"></a>Освобождение от импортных пошлин для возвращенных товаров (Специальные обстоятельства, предусмотренные в Статье 158(3) Делегированного Регламента (ЕС) 2015/2446: ремонт или реставрация)</td></tr>
<tr><td><a id="p109946"></a>F04</td><td><a id="p109947"></a>Переработанная продукция, которая возвращается в Европейский Союз после того, как она была ранее реэкспортирована после процедуры внутренней переработки (<a href="https://bukva.ai/docs/reglament-9522013/statya-1#p101736">Статья 205(1)</a> Кодекса)</td></tr>
<tr><td><a id="p109948"></a>F05</td><td><a id="p109949"></a>Освобождение от импортных пошлин и от НДС и/или акцизных сборов для возвращенных товаров (<a href="https://bukva.ai/docs/reglament-9522013/statya-203#p101721">Статья 203</a> Кодекса и <a href="https://bukva.ai/docs/direktiva-2006112es/statya-1#p100871">Статья 143(1)(e)</a> (Директивы 2006/112/ЕС)</td></tr>
<tr><td><a id="p109950"></a>F06</td><td><a id="p109951"></a>Перемещение акцизных товаров по соглашению о приостановке акцизной пошлины с места импорта в соответствии со <a href="https://bukva.ai/docs/direktiva-2008118es/statya-17#p100219">Статьей 17(1)(b)</a> Директивы 2008/11/ЕС</td></tr>
<tr><td><a id="p109952"></a>F07</td><td><a id="p109953"></a>Переработанная продукция, которая возвращается в Европейский Союз после того, как она была ранее реэкспортирована после процедуры внутренней переработки, если импортная пошлина определяется в соответствии со <a href="https://bukva.ai/docs/reglament-9522013/statya-1#p100873">Статьей 86(3)</a> Кодекса (<a href="https://bukva.ai/docs/reglament-9522013/statya-1#p101737">Статья 205(2)</a> Кодекса)</td></tr>
<tr><td><a id="p109954"></a>F15</td><td><a id="p109955"></a>Товары, ввезенные в контексте торговли со специальными фискальными территориями (<a href="https://bukva.ai/docs/reglament-9522013/statya-1#p100107">Статья 1(3)</a> Кодекса)</td></tr>
<tr><td><a id="p109956"></a>F16</td><td><a id="p109957"></a>Товары, ввезенные в контексте торговли между Союзом и странами, с которыми он образовал таможенный союз</td></tr>
<tr><td><a id="p109958"></a>F21</td><td><a id="p109959"></a>Освобождение от импортных пошлин продукции морского рыболовства и другой продукции, выловленной из территориального моря страны или территории за пределами таможенной территории Союза судами, зарегистрированными или записанными исключительно в государстве-члене ЕС и плавающими под флагом этого государства</td></tr>
<tr><td><a id="p109960"></a>F22</td><td><a id="p109961"></a>Освобождение от импортных пошлин продукции, полученной из продукции морского рыболовства и другой продукции, выловленной из территориального моря страны или территории за пределами таможенной территории Союза на борту плавучего рыбозавода, зарегистрированного или записанного в государстве-члене ЕС и плавающего под флагом государства</td></tr>
<tr><td><a id="p109962"></a>F44</td><td><a id="p109963"></a>Выпуск в свободное обращение переработанной продукции, если должна применяться <a href="https://bukva.ai/docs/reglament-9522013/statya-1#p100873">Статья 86(3)</a> Кодекса</td></tr>
<tr><td><a id="p109964"></a>F45</td><td><a id="p109965"></a>Освобождение от налога на добавленную стоимость при окончательном импорте отдельных товаров (Директива 2009/132/ЕС Совета ЕС <a href="#p109974">&lt;*&gt;</a>)</td></tr>
<tr><td><a id="p109966"></a>F46</td><td><a id="p109967"></a>Использование первоначальной тарифной классификации товаров в ситуациях, предусмотренных в <a href="https://bukva.ai/docs/reglament-9522013/statya-1#p100872">Статье 86(2)</a> Кодекса</td></tr>
<tr><td><a id="p109968"></a>F47</td><td><a id="p109969"></a>Упрощение составления таможенных деклараций для товаров, подпадающих под различные тарифные подзаголовки, предусмотренные в <a href="https://bukva.ai/docs/reglament-9522013/statya-177#p101548">Статье 177</a> Кодекса</td></tr>
<tr><td><a id="p109970"></a>F48</td><td><a id="p109971"></a>Импорт по специальной схеме для удаленной торговли товарами, импортированными из третьих стран или третьих территорий, установленных в <a href="https://bukva.ai/docs/direktiva-2006112es/statya-1#p102020">Титуле XII Главы 6 Раздела 4</a> Директивы 2006/112/ЕС</td></tr>
<tr><td><a id="p109972"></a>F49</td><td><a id="p109973"></a>Импорт согласно специальным соглашениям для декларирования и оплаты импорта с НДС, установленным в <a href="https://bukva.ai/docs/direktiva-2006112es/statya-1#p102107">Титуле XII Главы 7</a> Директивы 2006/112/ЕС</td></tr>
<tr><td colspan="2"><a id="p109974"></a>&lt;*&gt; Директива 2009/132/ЕС Совета ЕС от 19 октября 2009 г. об определении сферы действия <a href="https://bukva.ai/docs/direktiva-2006112es/statya-1#p100863">Статьи 143(b)</a> и <a href="https://bukva.ai/docs/direktiva-2006112es/statya-1#p100868">(c)</a> Директивы 2006/112/ЕС в отношении освобождения от налога на добавленную стоимость при окончательном импорте отдельных товаров (ОЖ N L 292, 10.11.2009, стр. 5).</td></tr>
</table>


<a id="p109975"></a>2/1. Упрощенная декларация/Предыдущий документ
<a id="p109976"></a>Указанный элемент данных состоит из буквенно-цифровых кодов.
<a id="p109977"></a>Каждый код имеет три компонента. [Первый компонент](https://bukva.ai/docs/reglament-20152447/statya-350#p109979) (an..3), который состоит из комбинации цифр и/или букв, служит для определения типа документа. [Второй компонент](https://bukva.ai/docs/reglament-20152447/statya-350#p110054) (an..35) представляет данные, необходимые для признания указанного документа, либо его идентификационный номер, либо другую узнаваемую ссылку. [Третий компонент](https://bukva.ai/docs/reglament-20152447/statya-350#p110130) (an..5) используется для определения того, на какой пункт предыдущего документа имеется ссылка.
<a id="p109978"></a>Если подается таможенная декларация на бумажной основе, то три компонента отделяются тире (-).

1. <a id="p109979"></a>Первый компонент (an..3)
<a id="p109980"></a>Выберите сокращение для документа из "списка сокращений документов" ниже.
<a id="p109981"></a>Список сокращений документов
<a id="p109982"></a>(цифровой код в соответствии с Руководством ООН для взаимного электронного обмена для управления, коммерции и транспорта 2014b: Список кодов для элемента данных 1001, Документ/название сообщения, кодировано).


| <a id="p109983"></a>Список контейнеров | <a id="p109984"></a>235 |
| --- | --- |
| <a id="p109985"></a>Товарная накладная | <a id="p109986"></a>270 |
| <a id="p109987"></a>Упаковочный список | <a id="p109988"></a>271 |
| <a id="p109989"></a>Счет проформа | <a id="p109990"></a>325 |
| <a id="p109991"></a>Декларация временного хранения | <a id="p109992"></a>337 |
| <a id="p109993"></a>Сводная ввозная декларация | <a id="p109994"></a>355 |
| <a id="p109995"></a>Коммерческий счет-инвойс | <a id="p109996"></a>380 |
| <a id="p109997"></a>Общая транспортная накладная | <a id="p109998"></a>703 |
| <a id="p109999"></a>Основной коносамент | <a id="p110000"></a>704 |
| <a id="p110001"></a>Коносамент | <a id="p110002"></a>705 |
| <a id="p110003"></a>Внутренний коносамент | <a id="p110004"></a>714 |
| <a id="p110005"></a>Железнодорожная товаротранспортная накладная | <a id="p110006"></a>720 |
| <a id="p110007"></a>Дорожная товаротранспортная накладная | <a id="p110008"></a>730 |
| <a id="p110009"></a>Авианакладная | <a id="p110010"></a>740 |
| <a id="p110011"></a>Основная авианакладная | <a id="p110012"></a>741 |
| <a id="p110013"></a>Почтовая накладная (почтовые посылки) | <a id="p110014"></a>750 |
| <a id="p110015"></a>Смешанный/комбинированный транспортный документ | <a id="p110016"></a>760 |
| <a id="p110017"></a>Манифест груза | <a id="p110018"></a>785 |
| <a id="p110019"></a>Бордеро | <a id="p110020"></a>787 |
| <a id="p110021"></a>Транзитная декларация Союза/ общая транзитная декларация - смешанные отгрузки (T) | <a id="p110022"></a>820 |
| <a id="p110023"></a>Внешняя транзитная декларация Союза/ общая транзитная декларация (T1) | <a id="p110024"></a>821 |
| <a id="p110025"></a>Внутренняя транзитная декларация Союза/ общая транзитная декларация (T2) | <a id="p110026"></a>822 |
| <a id="p110027"></a>Контрольный документ T5 | <a id="p110028"></a>823 |
| <a id="p110029"></a>Доказательство таможенного статуса товаров Союза T2L | <a id="p110030"></a>825 |
| <a id="p110031"></a>[Карнет](https://bukva.ai/docs/tamozhennaya-konventsiya-o-mezhdunarodnoy-2/statya-64#p100621) TIR | <a id="p110032"></a>952 |
| <a id="p110033"></a>[Карнет](https://bukva.ai/docs/tamozhennaya-konventsiya-o-karnete-ata-dlya-2/statya-28#p100156) ATA | <a id="p110034"></a>955 |
| <a id="p110035"></a>Ссылка/дата внесения в отчеты декларанта | <a id="p110036"></a>CLE |
| <a id="p110037"></a>Информационный [лист](https://bukva.ai/docs/reglament-20152447/statya-350#p112301) INF3 | <a id="p110038"></a>IF3 |
| <a id="p110039"></a>Манифест груза - упрощенная процедура | <a id="p110040"></a>MNS |
| <a id="p110041"></a>Декларация/уведомление MRN | <a id="p110042"></a>MRN |
| <a id="p110043"></a>Декларация внутреннего транзита Союза - [Статья 227](https://bukva.ai/docs/reglament-9522013/statya-227#p101892) Кодекса | <a id="p110044"></a>T2F |
| <a id="p110045"></a>Доказательство таможенного статуса товаров Союза T2G | <a id="p110046"></a>T2G |
| <a id="p110047"></a>Доказательство T2M | <a id="p110048"></a>T2M |
| <a id="p110049"></a>Упрощенная декларация | <a id="p110050"></a>SDE |
| <a id="p110051"></a>Прочее | <a id="p110052"></a>ZZZ |


<a id="p110053"></a>Код "CLE", включенный в настоящий список, означает "дату и номер внесения в отчеты декларанта". ([Статья 182(1)](https://bukva.ai/docs/reglament-9522013/statya-1#p101582) Кодекса). Дата кодирована следующим образом: ггггммдд.

2. <a id="p110054"></a>Второй компонент (an..35)
<a id="p110055"></a>Идентификационный номер или другой признанный номер документа вносится сюда.
<a id="p110056"></a>В случае если в качестве предварительного документа указан MRN, исходящий номер должен иметь следующую структуру:


| <a id="p110057"></a>Поле | <a id="p110058"></a>Содержание | <a id="p110059"></a>Формат | <a id="p110060"></a>Примеры |
| --- | --- | --- | --- |
| <a id="p110061"></a>1 | <a id="p110062"></a>Последние две цифры года официального принятия декларации (ГГ) | <a id="p110063"></a>n2 | <a id="p110064"></a>15 |
| <a id="p110065"></a>2 | <a id="p110066"></a>Идентификатор страны, в которой подана декларация/доказательство таможенного статуса товаров Союза/уведомление (буквенный 2-значный код страны) | <a id="p110067"></a>a2 | <a id="p110068"></a>RO |
| <a id="p110069"></a>3 | <a id="p110070"></a>Уникальный идентификатор для сообщения по году и по стране | <a id="p110071"></a>an12 | <a id="p110072"></a>9876AB889012 |
| <a id="p110073"></a>4 | <a id="p110074"></a>Идентификатор процедуры | <a id="p110075"></a>a1 | <a id="p110076"></a>B |
| <a id="p110077"></a>5 | <a id="p110078"></a>Проверочная цифра | <a id="p110079"></a>an1 | <a id="p110080"></a>5 |


<a id="p110081"></a>[Поле 1](https://bukva.ai/docs/reglament-20152447/statya-350#p110061) и [2](https://bukva.ai/docs/reglament-20152447/statya-350#p110065) - как разъяснено выше.
<a id="p110082"></a>В [поле 3](https://bukva.ai/docs/reglament-20152447/statya-350#p110069) вносится идентификатор соответствующего сообщения. Вопрос о том, каким образом используется это [поле](https://bukva.ai/docs/reglament-20152447/statya-350#p110069), входит в компетенцию национальных администраций, но каждое сообщение, обрабатываемое в течение года в данной стране, должно иметь уникальный номер в отношении рассматриваемой процедуры.
<a id="p110083"></a>Национальные администрации, которые хотят включить в MRN номер компетентного таможенного учреждения, могут использовать до 6 первых знаков для его представления.
<a id="p110084"></a>В [поле 4](https://bukva.ai/docs/reglament-20152447/statya-350#p110073) вносится идентификатор процедуры, определенный в [таблице](https://bukva.ai/docs/reglament-20152447/statya-350#p110087) ниже.
<a id="p110085"></a>В [поле 5](https://bukva.ai/docs/reglament-20152447/statya-350#p110077) вносится значение, которое является проверочной цифрой для всего MRN. Это [поле](https://bukva.ai/docs/reglament-20152447/statya-350#p110077) позволяет определить ошибку при вводе всего MRN.
<a id="p110086"></a>Коды, используемые в [поле 4](https://bukva.ai/docs/reglament-20152447/statya-350#p110073) - Идентификатор процедуры:


<table>
<colgroup><col width="9%"><col width="58%"><col width="33%"></colgroup>
<tr><td><a id="p110087"></a>Код</td><td><a id="p110088"></a>Процедура</td><td><a id="p110089"></a>Соответствующие колонки в таблице Титула I, Главы 2 Делегированного Регламента (ЕС) 2015/2446</td></tr>
<tr><td><a id="p110090"></a>A</td><td><a id="p110091"></a>Только экспорт</td><td><a id="p110092"></a>B1, B2, B3 или C1</td></tr>
<tr><td><a id="p110093"></a>B</td><td><a id="p110094"></a>Экспортная и сводная вывозная декларация</td><td><a id="p110095"></a>Комбинации A1 или A2 с B1, B2, B3 или C1</td></tr>
<tr><td><a id="p110096"></a>C</td><td><a id="p110097"></a>Только сводная вывозная декларация</td><td><a id="p110098"></a>A1 или A2</td></tr>
<tr><td><a id="p110099"></a>D</td><td><a id="p110100"></a>Реэкспортное уведомление</td><td><a id="p110101"></a>A3</td></tr>
<tr><td><a id="p110102"></a>E</td><td><a id="p110103"></a>Отправка товаров в отношении специальных фискальных территорий</td><td><a id="p110104"></a>B4</td></tr>
<tr><td><a id="p110105"></a>J</td><td><a id="p110106"></a>Только транзитная декларация</td><td><a id="p110107"></a>D1, D2 или D3</td></tr>
<tr><td><a id="p110108"></a>K</td><td><a id="p110109"></a>Транзитная декларация и сводная вывозная декларация</td><td><a id="p110110"></a>Комбинации D1, D2 или D3 с A1 или A2</td></tr>
<tr><td><a id="p110111"></a>L</td><td><a id="p110112"></a>Транзитная декларация и сводная ввозная декларация</td><td><a id="p110113"></a>Комбинации D1, D2 или D3 с F1a, F2a, F3a, F4a или F5</td></tr>
<tr><td><a id="p110114"></a>M</td><td><a id="p110115"></a>Доказательство таможенного статуса товаров Союза/ Манифест товаров Союза</td><td><a id="p110116"></a>E1, E2</td></tr>
<tr><td><a id="p110117"></a>R</td><td><a id="p110118"></a>Только импортная декларация</td><td><a id="p110119"></a>H1, H2, H3, H4, H6, H7 <a href="#p110129">&lt;*&gt;</a> или I1</td></tr>
<tr><td><a id="p110120"></a>S</td><td><a id="p110121"></a>Импортная декларация и сводная ввозная декларация</td><td><a id="p110122"></a>Комбинации H1, H2, H3, H4, H6, H7 <a href="#p110129">&lt;*&gt;</a> или I1 с F1a, F2a, F3a, F4a или F5</td></tr>
<tr><td><a id="p110123"></a>T</td><td><a id="p110124"></a>Только сводная ввозная декларация</td><td><a id="p110125"></a>F1a, F1b, F1c, F1d, F2a, F2b, F2c, F2d, F3a, F3b, F4a, F4b, F4c или F5</td></tr>
<tr><td><a id="p110126"></a>V</td><td><a id="p110127"></a>Ввоз товаров в отношении территорий со специальными фискальными режимами</td><td><a id="p110128"></a>H5</td></tr>
<tr><td colspan="3"><a id="p110129"></a>&lt;*&gt; H7, определенная в Приложении B Титула I Главы 3 Делегированного Регламента (ЕС) 2015/2446 Европейской Комиссии. Ограничена ситуациями, в которых импортная декларация относится к предыдущему документу в последующей декларации.</td></tr>
</table>


3. <a id="p110130"></a>Третий компонент (n..5)
<a id="p110131"></a>Номер пункта рассматриваемых товаров, предусмотренный в D.E. [1/6](https://bukva.ai/docs/reglament-20152447/statya-350#p108994). Номер пунктов товаров, сводной декларации или предыдущего документа.
<a id="p110132"></a>Примеры:
- <a id="p110133"></a>Рассматриваемым пунктом декларации был 5-й пункт транзитного документа T1 (предыдущий документ), которому учреждение места назначения присвоило номер "238 544". Поэтому кодом будет "821-238544-5". ("821" - для транзитной процедуры, "238544" - для регистрационного номера документа (или MRN для операций NCTS) и "5" - для номера пункта).
- <a id="p110134"></a>Товары были продекларированы через упрощенную декларацию. Был присвоен MRN "16DE987AB889012R1". В связи с этим в дополнительной декларации будет код "SDE-16DE9876AB889012R1". ("SDE" - для упрощенной декларации, "16DE987AB889012R1" - для MRN документа).
<a id="p110135"></a>Если вышеуказанный документ составлен с использованием таможенной декларации на бумажной основе (SAD), сокращение включит в себя коды, определенные для первого подразделения D.E. [1/1](https://bukva.ai/docs/reglament-20152447/statya-350#p108984) Вид декларации (IM, CO и EU).
<a id="p110136"></a>Если в случае транзитной декларации на бумажной основе должны быть введены несколько ссылок, и государства-члены ЕС предусматривают, что должна использоваться кодированная информация, то применяется код 00200, определенный в D.E. [2/2](https://bukva.ai/docs/reglament-20152447/statya-350#p109021) Дополнительная информация.

<a id="p110137"></a>2/2. Дополнительная информация
<a id="p110138"></a>Пятизначный код используется для кодирования дополнительной информации таможенного характера. Данный код следует за дополнительной информацией, если законодательство Союза не предусматривает использования кода вместо текста.
<a id="p110139"></a>Пример: Если декларант и грузоотправитель являются одним и тем же лицом, вводится код 00300.
<a id="p110140"></a>Законодательство Союза предусматривает введение определенной дополнительной информации в другие элементы данных, кроме D.E. [2/2](https://bukva.ai/docs/reglament-20152447/statya-350#p109021) Дополнительная информация. Но эта дополнительная информация должна быть кодирована согласно тем же правилам, что и информация, специально вводимая в D.E. [2/2](https://bukva.ai/docs/reglament-20152447/statya-350#p109021) Дополнительная информация.

<a id="p110141"></a>Дополнительная информация - код XXXXX
<a id="p110142"></a>Общая категория - Код 0xxxx


| <a id="p110143"></a>Правовое основание | <a id="p110144"></a>Предмет | <a id="p110145"></a>Дополнительная информация | <a id="p110146"></a>Код |
| --- | --- | --- | --- |
| <a id="p110147"></a>Статья 163 Делегированного Регламента (ЕС) 2015/2446 | <a id="p110148"></a>Заявление на разрешение использования специальной процедуры, кроме транзита, основанное на таможенной декларации | <a id="p110149"></a>"Упрощенное разрешение" | <a id="p110150"></a>00100 |
| <a id="p110151"></a>Титул II Приложения D к Делегированному Регламенту (ЕС) 2015/2446 | <a id="p110152"></a>Несколько вхождений документов или сторон | <a id="p110153"></a>"Различные" | <a id="p110154"></a>00200 |
| <a id="p110155"></a>Титул II Приложения D к Делегированному Регламенту (ЕС) 2015/2446 | <a id="p110156"></a>Идентичность между декларантом и грузоотправителем | <a id="p110157"></a>"Грузоотправитель" | <a id="p110158"></a>00300 |
| <a id="p110159"></a>Титул II Приложения D к Делегированному Регламенту (ЕС) 2015/2446 | <a id="p110160"></a>Идентичность между декларантом и экспортером | <a id="p110161"></a>"Экспортер" | <a id="p110162"></a>00400 |
| <a id="p110163"></a>Титул II Приложения D к Делегированному Регламенту (ЕС) 2015/2446 | <a id="p110164"></a>Идентичность между декларантом и импортером | <a id="p110165"></a>"Грузополучатель" | <a id="p110166"></a>00500 |
| <a id="p110167"></a>Статья 176(1)(c) и Статья 241(1) первый подпараграф Делегированного Регламента (ЕС) 2015/2446 | <a id="p110168"></a>Завершение внутренней переработки | <a id="p110169"></a>"IP" и соответствующий "номер разрешения или номер INF | <a id="p110170"></a>00700 |
| <a id="p110171"></a>Статья 241(1) второй подпараграф Делегированного Регламента (ЕС) 2015/2446 | <a id="p110172"></a>Завершение внутренней переработки (меры специальной коммерческой политики) | <a id="p110173"></a>"IP CPM" | <a id="p110174"></a>00800 |
| <a id="p110175"></a>Статья 238 Делегированного Регламента (ЕС) 2015/2446 | <a id="p110176"></a>Завершение временного допуска | <a id="p110177"></a>"TA" и соответствующий номер разрешения | <a id="p110178"></a>00900 |


<a id="p110179"></a>По импорту: код 1xxxx


| <a id="p110180"></a>Правовое основание | <a id="p110181"></a>Предмет | <a id="p110182"></a>Дополнительная информация | <a id="p110183"></a>Код |
| --- | --- | --- | --- |
| <a id="p110184"></a>Титул II Приложения D к Делегированному Регламенту (ЕС) 2015/2446 | <a id="p110185"></a>Ситуации, когда рассматриваются оборотные коносаменты "заказать заполненный бланк", в случае сводных ввозных деклараций, если сведения о грузополучателе неизвестны. | <a id="p110186"></a>"Грузополучатель неизвестен" | <a id="p110187"></a>10600 |


<a id="p110188"></a>Прочее: код 4xxxx


| <a id="p110189"></a>Правовое основание | <a id="p110190"></a>Предмет | <a id="p110191"></a>Дополнительная информация | <a id="p110192"></a>Код |
| --- | --- | --- | --- |
| <a id="p110193"></a>Статья 123 Делегированного Регламента (ЕС) 2015/2446 | <a id="p110194"></a>Запрос по продлению срока действия доказательства таможенного статуса товаров Союза | <a id="p110195"></a>"Продление периода срока действия доказательства таможенного статуса товаров Союза" | <a id="p110196"></a>40100 |


<a id="p110197"></a>2/3. Документы, составленные, сертификаты и разрешения, дополнительные ссылки
<a id="p110198"></a>(a) Документы Союза или международные документы, сертификаты и разрешения, составленные в подтверждение декларации, и дополнительные ссылки должны быть внесены в форму посредством кода, определенного в [Титуле I](https://bukva.ai/docs/reglament-20152447/statya-350#p108976), после которого следует или идентификационный номер, или другая признанная ссылка. Список документов, сертификатов и разрешений, а также дополнительные ссылки и их соответствующие коды можно найти в базе данных TARIC.
<a id="p110199"></a>(b) Национальные документы, сертификаты и разрешения, составленные для подтверждения декларации, и дополнительные ссылки должны быть внесены в форму посредством кода, определенного в [Титуле I](https://bukva.ai/docs/reglament-20152447/statya-350#p108976) (Ex: 2123, 34d5), после которого может следовать либо идентификационный номер, либо другая признанная ссылка. Четыре знака представляют коды, основанные на собственной номенклатуре государства-члена ЕС.

<a id="p110200"></a>2/7. Идентификация склада
<a id="p110201"></a>Коды, которые должны быть внесены, имеют следующую структуру из двух частей:
- <a id="p110202"></a>Знак, идентифицирующий тип склада:
<a id="p110203"></a>R - Государственный таможенный склад вида I;
<a id="p110204"></a>S - Государственный таможенный склад вида II;
<a id="p110205"></a>T - Государственный таможенный склад вида III;
<a id="p110206"></a>U - Частный таможенный склад;
<a id="p110207"></a>V - Склад хранения для временного хранения товаров;
<a id="p110208"></a>Y - Нетаможенный склад;
<a id="p110209"></a>Z - Свободная зона.
- <a id="p110210"></a>Идентификационный номер, присвоенный государством-членом ЕС при выдаче разрешения в случаях, когда такое разрешение выдается.

<a id="p110211"></a>3/1. Экспортер
<a id="p110212"></a>В случае групповых партий, если используются таможенные декларации на бумажной основе, а государство-член ЕС предусматривает использование кодированной информации, то применяется код 00200, определенный в D.E. [2/2](https://bukva.ai/docs/reglament-20152447/statya-350#p109021) Дополнительная информация.

<a id="p110213"></a>3/2. Идентификационный номер экспортера
<a id="p110214"></a>Номер EORI структурируется следующим образом:


| <a id="p110215"></a>Поле | <a id="p110216"></a>Содержание | <a id="p110217"></a>Формат |
| --- | --- | --- |
| <a id="p110218"></a>1 | <a id="p110219"></a>Идентификатор государства-члена ЕС (код страны) | <a id="p110220"></a>a2 |
| <a id="p110221"></a>2 | <a id="p110222"></a>Уникальный идентификатор в государстве-члене ЕС | <a id="p110223"></a>an..15 |


<a id="p110224"></a>Код страны: Используется код страны, определенный в Титуле I в отношении кода страны D.E. [3/1](https://bukva.ai/docs/reglament-20152447/statya-350#p109057) Экспортер.
<a id="p110225"></a>Структура уникального идентификационного номера третьей страны, который был представлен Союзу, является следующей:


| <a id="p110226"></a>Поле | <a id="p110227"></a>Содержание | <a id="p110228"></a>Формат |
| --- | --- | --- |
| <a id="p110229"></a>1 | <a id="p110230"></a>Код страны | <a id="p110231"></a>a2 |
| <a id="p110232"></a>2 | <a id="p110233"></a>Уникальный идентификационный номер в третьей стране | <a id="p110234"></a>an..15 |


<a id="p110235"></a>3/21. Код статуса представителя
<a id="p110236"></a>Вставьте один из следующих кодов (n1) перед полным наименованием/именем и адресом для определения статуса представителя:
<a id="p110237"></a>2 - Представитель (прямое представительство в значении [Статьи 18(1)](https://bukva.ai/docs/reglament-9522013/statya-1#p100306) Кодекса);
<a id="p110238"></a>3 - Представитель (косвенное представительство в значении [Статьи 18(1)](https://bukva.ai/docs/reglament-9522013/statya-1#p100306) Кодекса).
<a id="p110239"></a>Если указанный элемент данных напечатан на бумажном документе, он должен быть в квадратных скобках (Напр., [2] или [3]).

<a id="p110240"></a>3/37. Идентификационный номер дополнительного(ых) участника(ов) системы поставки
<a id="p110241"></a>Этот элемент данных состоит из двух компонентов:

1. <a id="p110242"></a>Код роли
<a id="p110243"></a>Могут быть продекларированы следующие лица:


| <a id="p110244"></a>Код роли | <a id="p110245"></a>Лицо | <a id="p110246"></a>Описание |
| --- | --- | --- |
| <a id="p110247"></a>CS | <a id="p110248"></a>Посредник | <a id="p110249"></a>Экспедитор, объединяющий индивидуальные мелкие грузы в одну более крупную партию (в процессе консолидации), которая направляется другому лицу, которое зеркально отражает деятельность посредника и разделяет объединенную партию на первоначальные грузы |
| <a id="p110250"></a>FW | <a id="p110251"></a>Экспедитор | <a id="p110252"></a>Лицо, осуществляющее отправление товаров |
| <a id="p110253"></a>MF | <a id="p110254"></a>Производитель | <a id="p110255"></a>Лицо, которое производит товары |
| <a id="p110256"></a>WH | <a id="p110257"></a>Владелец склада | <a id="p110258"></a>Лицо, принимающее ответственность за товары, поступившие на склад |


2. <a id="p110259"></a>Идентификационный номер лица
<a id="p110260"></a>Структура этого номера соответствует структуре, определенной для D.E. [3/2](https://bukva.ai/docs/reglament-20152447/statya-350#p109064) Идентификационный номер экспортера.

<a id="p110261"></a>3/40. Идентификационный номер дополнительных фискальных ссылок
<a id="p110262"></a>Этот элемент данных состоит из двух компонентов:

1. <a id="p110263"></a>Код роли
<a id="p110264"></a>Могут быть продекларированы следующие лица:


| <a id="p110265"></a>Код роли | <a id="p110266"></a>Лицо | <a id="p110267"></a>Описание |
| --- | --- | --- |
| <a id="p110268"></a>FR1 | <a id="p110269"></a>Импортер | <a id="p110270"></a>Лицо или лица, назначенные или признанные ответственными за оплату налога на добавленную стоимость государством-членом ЕС импорта в соответствии со [Статьей 201](https://bukva.ai/docs/direktiva-2006112es/statya-201#p101262) Директивы 2006/112/ЕС |
| <a id="p110271"></a>FR2 | <a id="p110272"></a>Потребитель | <a id="p110273"></a>Лицо, ответственное за оплату налога на добавленную стоимость при внутрисоюзном приобретении товаров в соответствии со [Статьей 200](https://bukva.ai/docs/direktiva-2006112es/statya-200#p101260) Директивы 2006/112/ЕС |
| <a id="p110274"></a>FR3 | <a id="p110275"></a>Налоговый представитель | <a id="p110276"></a>Налоговый представитель, ответственный за оплату налога на добавленную стоимость в государстве-члене ЕС импорта, назначенный импортером |
| <a id="p110277"></a>FR4 | <a id="p110278"></a>Владелец разрешения на отсроченный платеж | <a id="p110279"></a>Лицо, имеющее статус налогоплательщика, или лицо, ответственное за оплату, или другое лицо, которое получило отсрочку платежа в соответствии со [Статьей 211](https://bukva.ai/docs/direktiva-2006112es/statya-211#p101290) Директивы 2006/112/ЕС |
| <a id="p110280"></a>FR5 | <a id="p110281"></a>Поставщик (IOSS) | <a id="p110282"></a>Лицо, облагаемое налогом, использующее специальную схему удаленной торговли товарами, импортированными из третьих стран или третьих территорий, установленных в [Титуле XII Главе 6 Разделе 4](https://bukva.ai/docs/direktiva-2006112es/statya-1#p102020) Директивы 2006/112/ЕС и владелец идентификационного номера плательщика НДС, указанный в [Статье 369q](https://bukva.ai/docs/direktiva-2006112es/statya-1#p102066) Директивы |
| <a id="p110283"></a>FR7 | <a id="p110284"></a>Налогоплательщик или лицо, обязанное платить НДС | <a id="p110285"></a>Идентификационный номер плательщика НДС или лица, обязанного платить НДС, если оплата НДС отсрочена в соответствии со [Статьей 211, вторым подпараграфом](https://bukva.ai/docs/direktiva-2006112es/statya-1#p101292) Директивы 2006/112/ЕС. |


2. <a id="p110286"></a>Идентификационный номер налога на добавленную стоимость структурируется следующим образом:


| <a id="p110287"></a>Поле | <a id="p110288"></a>Содержание | <a id="p110289"></a>Формат |
| --- | --- | --- |
| <a id="p110290"></a>1 | <a id="p110291"></a>Идентификатор государства-члена ЕС выдачи (код ISO 3166 - alpha 2-; Греция может использовать EL) | <a id="p110292"></a>a2 |
| <a id="p110293"></a>2 | <a id="p110294"></a>Индивидуальный номер, присвоенный государством-членом ЕС для идентификации налогоплательщика, указанный в [Статье 214](https://bukva.ai/docs/direktiva-2006112es/statya-214#p101301) Директивы 2006/112/ЕС | <a id="p110295"></a>an..15 |


<a id="p110296"></a>4/1. Условия поставки
<a id="p110297"></a>Вносимые при необходимости коды и заявления в первые два подраздела являются следующими:


<table>
<colgroup><col width="33%"><col width="36%"><col width="31%"></colgroup>
<tr><td><a id="p110298"></a>Первый подраздел</td><td><a id="p110299"></a>Значение</td><td><a id="p110300"></a>Второй подраздел</td></tr>
<tr><td><a id="p110301"></a>Код Инкотермс</td><td><a id="p110302"></a>Инкотермс - ICC/ECE</td><td><a id="p110303"></a>Место, которое должно быть определено</td></tr>
<tr><td colspan="3"><a id="p110304"></a>Коды, применяемые для всех видов транспорта</td></tr>
<tr><td><a id="p110305"></a>EXW (Инкотермс 2010<br>или Инкотермс 2020)</td><td><a id="p110306"></a>Франко завод</td><td><a id="p110307"></a>Названное место поставки</td></tr>
<tr><td><a id="p110308"></a>FCA (Инкотермс 2010<br>или Инкотермс 2020)</td><td><a id="p110309"></a>Франко перевозчик</td><td><a id="p110310"></a>Названное место поставки</td></tr>
<tr><td><a id="p110311"></a>CPT (Инкотермс 2010<br>или Инкотермс 2020)</td><td><a id="p110312"></a>Перевозка оплачена до</td><td><a id="p110313"></a>Названное место назначения</td></tr>
<tr><td><a id="p110314"></a>CIP (Инкотермс 2010<br>или Инкотермс 2020)</td><td><a id="p110315"></a>Перевозка и страхование оплачены до</td><td><a id="p110316"></a>Названное место назначения</td></tr>
<tr><td><a id="p110317"></a>DAT (Инкотермс 2010)</td><td><a id="p110318"></a>Поставка на терминале</td><td><a id="p110319"></a>Названные терминал в порту или в месте назначения</td></tr>
<tr><td><a id="p110320"></a>DPU (Инкотермс 2020)</td><td><a id="p110321"></a>Поставка в место разгрузки</td><td><a id="p110322"></a>Названное место назначения</td></tr>
<tr><td><a id="p110323"></a>DAP (Инкотермс 2010<br>или Инкотермс 2020)</td><td><a id="p110324"></a>Поставка в месте</td><td><a id="p110325"></a>Названное место назначения</td></tr>
<tr><td><a id="p110326"></a>DDP (Инкотермс 2010<br>или Инкотермс 2020)</td><td><a id="p110327"></a>Поставка с оплатой пошлин</td><td><a id="p110328"></a>Названное место назначения</td></tr>
<tr><td colspan="3"><a id="p110329"></a>Коды, применяемые для морского и внутреннего водного транспорта</td></tr>
<tr><td><a id="p110330"></a>FAS (Инкотермс 2010<br>или Инкотермс 2020)</td><td><a id="p110331"></a>Свободно вдоль борта судна</td><td><a id="p110332"></a>Названный порт отгрузки</td></tr>
<tr><td><a id="p110333"></a>FOB (Инкотермс 2010<br>или Инкотермс 2020)</td><td><a id="p110334"></a>Свободно на борту</td><td><a id="p110335"></a>Названный порт отгрузки</td></tr>
<tr><td><a id="p110336"></a>CFR (Инкотермс 20120)</td><td><a id="p110337"></a>Стоимость и фрахт</td><td><a id="p110338"></a>Названный порт назначения</td></tr>
<tr><td><a id="p110339"></a>CIF (Инкотермс 2010<br>или Инкотермс 2020)</td><td><a id="p110340"></a>Стоимость, страхование и фрахт</td><td><a id="p110341"></a>Названный порт назначения</td></tr>
<tr><td><a id="p110342"></a>XXX</td><td><a id="p110343"></a>Другие условия поставки, кроме условий, указанных выше</td><td><a id="p110344"></a>Описание условий поставки, данное в договоре</td></tr>
</table>


<a id="p110345"></a>4/3. Расчет налогов - вид налога
<a id="p110346"></a>Применяемые коды даны ниже:


| <a id="p110347"></a>A00 | <a id="p110348"></a>Импортная пошлина |
| --- | --- |
| <a id="p110349"></a>A30 | <a id="p110350"></a>Окончательные антидемпинговые пошлины |
| <a id="p110351"></a>A35 | <a id="p110352"></a>Предварительные антидемпинговые пошлины |
| <a id="p110353"></a>A40 | <a id="p110354"></a>Окончательные компенсационные пошлины |
| <a id="p110355"></a>A45 | <a id="p110356"></a>Предварительные компенсационные пошлины |
| <a id="p110357"></a>B00 | <a id="p110358"></a>НДС |
| <a id="p110359"></a>C00 | <a id="p110360"></a>Экспортная пошлина |
| <a id="p110361"></a>E00 | <a id="p110362"></a>Пошлины, собранные от имени других стран |


<a id="p110363"></a>4/8. Расчет налогов - Способ оплаты
<a id="p110364"></a>Следующие коды могут использоваться государствами-членами ЕС:
<a id="p110365"></a>A - Оплата наличными
<a id="p110366"></a>B - Оплата кредитной картой
<a id="p110367"></a>C - Оплата чеком
<a id="p110368"></a>D - Другой (например, прямой дебет денежного счета агента)
<a id="p110369"></a>E - Отсроченный или отложенный платеж
<a id="p110370"></a>G - Отложенный платеж - система НДС ([Статья 211](https://bukva.ai/docs/direktiva-2006112es/statya-211#p101290) Директивы 2006/112/ЕС)
<a id="p110371"></a>H - Электронный перевод средств
<a id="p110372"></a>J - Оплата через почтовое отделение (почтовые товары) или другой государственный сектор или правительственный департамент
<a id="p110373"></a>K - Акцизный кредит или скидка
<a id="p110374"></a>P - С кассового счета агента
<a id="p110375"></a>R - Гарантия оплачиваемой суммы
<a id="p110376"></a>S - Индивидуальный гарантийный счет
<a id="p110377"></a>T - С гарантийного счета агента
<a id="p110378"></a>U - Из гарантии агента - постоянный орган
<a id="p110379"></a>V - Из гарантии агента - индивидуальный орган
<a id="p110380"></a>O - Гарантия, поданная Агентством по оказанию помощи

<a id="p110381"></a>4/9. Надбавки и вычеты
<a id="p110382"></a>Надбавки (Определенные согласно [Статьям 70](https://bukva.ai/docs/reglament-9522013/statya-70#p100720) и [71](https://bukva.ai/docs/reglament-9522013/statya-71#p100732) Кодекса):
<a id="p110383"></a>AB: Комиссионные и брокерская комиссия, кроме комиссионных за покупку
<a id="p110384"></a>AD: Контейнеры и упаковка
<a id="p110385"></a>AE: Материалы, компоненты, части и подобные предметы, включенные в импортированные товары
<a id="p110386"></a>AF: Инструменты, штампы, формы и подобные предметы, использованные в производстве импортированных товаров
<a id="p110387"></a>AG: Материалы, потребленные в производстве импортированных товаров
<a id="p110388"></a>AH: Инженерно-конструкторские работы, разработки, художественные работы, проектные работы, а также планы и наброски, выполненные в других местах, кроме Европейского Союза, и необходимые для производства импортированных товаров
<a id="p110389"></a>AI: Роялти и сборы за лицензию
<a id="p110390"></a>AJ: Доходы от последующей перепродажи, распоряжения или использования, причитающиеся продавцу
<a id="p110391"></a>AK: Транспортные расходы, сборы на погрузку и обработку и затраты на страхование до места ввоза в Европейский Союз
<a id="p110392"></a>AL: Косвенные платежи и другие выплаты ([Статья 70](https://bukva.ai/docs/reglament-9522013/statya-70#p100720) Кодекса)
<a id="p110393"></a>AN: Надбавки на основании решения, выданного в соответствии со Статьей 71 Делегированного Регламента (ЕС) 2015/2446
<a id="p110394"></a>Вычеты (Определенные согласно [Статье 72](https://bukva.ai/docs/reglament-9522013/statya-72#p100751) Кодекса):
<a id="p110395"></a>BA: Затраты на перевозку после прибытия в место ввоза
<a id="p110396"></a>BB: Затраты на строительство, сборку, монтаж, техническое обслуживание или техническую помощь, выполненные после импорта
<a id="p110397"></a>BC: Импортные пошлины или другие сборы, выплачиваемые в Союзе по причине импорта или продажи товаров
<a id="p110398"></a>BD: Проценты
<a id="p110399"></a>BE: Сборы за право воспроизводить импортированные товары в Европейском Союзе
<a id="p110400"></a>BF: Комиссионные за покупку
<a id="p110401"></a>BG: Вычеты на основании решения, выданного в соответствии со Статьей 71 Делегированного Регламента (ЕС) 2015/2446

<a id="p110402"></a>4/13 Показатели оценки
<a id="p110403"></a>Код состоит из четырех знаков, каждый из которых либо "0", либо "1".
<a id="p110404"></a>Каждая цифра "1" или "0" отражает, является ли индикатор оценки релевантным для оценки соответствующих товаров или нет.
<a id="p110405"></a>1-й знак: Отношение сторон, влияет ли цена или нет.
<a id="p110406"></a>2-й знак: Ограничения распоряжения или использования товаров покупателем в соответствии со [Статьей 70(3)(a)](https://bukva.ai/docs/reglament-9522013/statya-1#p100725) Кодекса
<a id="p110407"></a>3-й знак: Продажа или цена зависят от условий или от рассмотрения в соответствии со [Статьей 70(3)(b)](https://bukva.ai/docs/reglament-9522013/statya-1#p100729) Кодекса
<a id="p110408"></a>4-й знак: Продажа определяется соглашением, согласно которому часть доходов от последующей перепродажи, распоряжения или использования причитается прямо или косвенно продавцу
<a id="p110409"></a>Пример:
<a id="p110410"></a>Для товаров, зависящих от отношения сторон, но не относящихся ни одной из ситуаций, определенных под 2-м, 3-м и 4-м знаком, можно использовать комбинацию кода "1000".

<a id="p110411"></a>4/16. Способ оценки
<a id="p110412"></a>Положения, используемые для определения таможенной стоимости импортированных товаров, должны быть кодированы следующим образом:


| <a id="p110413"></a>Код | <a id="p110414"></a>Соответствующая Статья [Кодекса](https://bukva.ai/docs/reglament-9522013/statya-1) | <a id="p110415"></a>Способ |
| --- | --- | --- |
| <a id="p110416"></a>1 | <a id="p110417"></a>[70](https://bukva.ai/docs/reglament-9522013/statya-70#p100720) | <a id="p110418"></a>Стоимость сделки с импортированными товарами |
| <a id="p110419"></a>2 | <a id="p110420"></a>[74(2)a)](https://bukva.ai/docs/reglament-9522013/statya-1#p100773) | <a id="p110421"></a>Стоимость сделки с идентичными товарами |
| <a id="p110422"></a>3 | <a id="p110423"></a>[74(2)b)](https://bukva.ai/docs/reglament-9522013/statya-1#p100774) | <a id="p110424"></a>Стоимость сделки с подобными товарами |
| <a id="p110425"></a>4 | <a id="p110426"></a>[74(2)c)](https://bukva.ai/docs/reglament-9522013/statya-1#p100775) | <a id="p110427"></a>Метод вычитания стоимости |
| <a id="p110428"></a>5 | <a id="p110429"></a>[74(2)d)](https://bukva.ai/docs/reglament-9522013/statya-1#p100776) | <a id="p110430"></a>Способ расчетного значения |
| <a id="p110431"></a>6 | <a id="p110432"></a>[74(3)](https://bukva.ai/docs/reglament-9522013/statya-1#p100780) | <a id="p110433"></a>Стоимость на основании имеющихся данных ("резервный" метод) |


<a id="p110434"></a>4/17. Преференция
<a id="p110435"></a>Данная информация включает в себя трехзначные коды, состоящие из однозначного компонента из [пункта 1](https://bukva.ai/docs/reglament-20152447/statya-350#p110437)) и двузначного компонента из [пункта 2](https://bukva.ai/docs/reglament-20152447/statya-350#p110442)).
<a id="p110436"></a>Соответствующие коды даны ниже:
<a id="p110437"></a>(1). Первый знак кода:
<a id="p110438"></a>1 - Тарифное соглашение erga omnes
<a id="p110439"></a>2 - Генеральная система преференций (GSP)
<a id="p110440"></a>3 - Другие тарифные преференции, кроме тех, которые указаны под [кодом 2](https://bukva.ai/docs/reglament-20152447/statya-350#p110419)
<a id="p110441"></a>4 - Таможенные пошлины согласно положениям соглашений таможенного союза, заключенных Европейским Союзом
<a id="p110442"></a>(2) Следующие два знака кода
<a id="p110443"></a>00 - Ничего из следующего
<a id="p110444"></a>10 - Приостановка тарифов
<a id="p110445"></a>18 - Приостановка тарифов с сертификатом, подтверждающим специальный характер продукции
<a id="p110446"></a>19 - Временная приостановка для продукции, импортированной с сертификатом летной пригодности формы 1 или эквивалентным сертификатом
<a id="p110447"></a>20 - Тарифная квота <*>

<a id="p110448"></a>

---

<a id="p110449"></a><*> Если запрошенная тарифная квота исчерпана, то государства-члены ЕС могут разрешить запрос действия для другой существующей преференции.

<a id="p110450"></a>25 - Тарифная квота с сертификатом, подтверждающим специальный характер продукции <*>
<a id="p110451"></a>28 - Тарифная квота после внешней переработки <*>
<a id="p110452"></a>50 - Сертификат, подтверждающий специальный характер продукции

<a id="p110453"></a>5/23. Местонахождение товаров
<a id="p110454"></a>Используйте ISO 2-букв. коды, использованные в поле 1 D.E. [3/1](https://bukva.ai/docs/reglament-20152447/statya-350#p109057) Экспортер
<a id="p110455"></a>Для видов местонахождения используйте коды, определенные ниже:
<a id="p110456"></a>A - Назначенное место
<a id="p110457"></a>B - Разрешенное место
<a id="p110458"></a>C - Одобренное место
<a id="p110459"></a>D - Прочее

<a id="p110460"></a>Для идентификации места используйте один из идентификаторов, указанных ниже:


| <a id="p110461"></a>Определитель | <a id="p110462"></a>Идентификатор | <a id="p110463"></a>Описание |
| --- | --- | --- |
| <a id="p110464"></a>T | <a id="p110465"></a>Почтовый индекс | <a id="p110466"></a>Используйте почтовый индекс с номером дома или без него для рассматриваемого места |
| <a id="p110467"></a>U | <a id="p110468"></a>UN/LOCODE | <a id="p110469"></a>Используйте коды UN/LOCODE, указанные во [вводной части 13 номер 4](https://bukva.ai/docs/reglament-20152447/statya-350#p104392) |
| <a id="p110470"></a>V | <a id="p110471"></a>Идентификатор таможенного учреждения | <a id="p110472"></a>Используйте коды, определенные для D.E. [1701000000](https://bukva.ai/docs/reglament-20152447/statya-350#p108726) Таможенное учреждение вывоза |
| <a id="p110473"></a>W | <a id="p110474"></a>Координаты GNSS | <a id="p110475"></a>Десятичные градусы с отрицательными значениями для юга и запада.<br>Примеры: 44.424896°/8.774792° или 50.838068°/4.381508° |
| <a id="p110476"></a>X | <a id="p110477"></a>Номер EORI | <a id="p110478"></a>Используйте идентификационный номер, определенный в описании для D.E. [3/2](https://bukva.ai/docs/reglament-20152447/statya-350#p109064) Идентификационный номер экспортера. Если субъект экономической деятельности имеет несколько предприятий, номер EORI должен быть заполнен идентификатором, уникальным для этого места. |
| <a id="p110479"></a>Y | <a id="p110480"></a>Номер разрешения | <a id="p110481"></a>Введите номер разрешения рассматриваемого места, т.е. склад, в котором товары могут быть досмотрены. Если разрешение касается нескольких предприятий номер разрешения должен быть заполнен идентификатором, уникальным для этого места. |
| <a id="p110482"></a>Z | <a id="p110483"></a>Адрес | <a id="p110484"></a>Введите адрес рассматриваемого места. |


<a id="p110485"></a>Если код "X" (номер EORI) или "Y" (номер разрешения) используется для идентификации места, и существует несколько мест, связанных с номером EORI или с номером разрешения, может использоваться дополнительный идентификатор, позволяющий точно определить место.

<a id="p110486"></a>7/2. Контейнер
<a id="p110487"></a>Соответствующие коды даны ниже:


| <a id="p110488"></a>0 | <a id="p110489"></a>Товары не перевозятся в контейнерах |
| --- | --- |
| <a id="p110490"></a>1 | <a id="p110491"></a>Товары перевозятся в контейнерах |


<a id="p110492"></a>7/4. Вид транспорта на границе
<a id="p110493"></a>Применяемые коды даны ниже:


| <a id="p110494"></a>Код | <a id="p110495"></a>Описание |
| --- | --- |
| <a id="p110496"></a>1 | <a id="p110497"></a>Морской транспорт |
| <a id="p110498"></a>2 | <a id="p110499"></a>Железнодорожный транспорт |
| <a id="p110500"></a>3 | <a id="p110501"></a>Дорожный транспорт |
| <a id="p110502"></a>4 | <a id="p110503"></a>Воздушный транспорт |
| <a id="p110504"></a>5 | <a id="p110505"></a>Почта (Активный вид транспорта не известен) |
| <a id="p110506"></a>7 | <a id="p110507"></a>Смешанные транспортные установки |
| <a id="p110508"></a>8 | <a id="p110509"></a>Внутренний водный транспорт |
| <a id="p110510"></a>9 | <a id="p110511"></a>Вид неизвестен (т.е. собственная двигательная установка) |


<a id="p110512"></a>8/2. Вид гарантии
<a id="p110513"></a>Коды гарантии
<a id="p110514"></a>Применяемые коды даны ниже:


<table>
<colgroup><col width="11%"><col width="89%"></colgroup>
<tr><td><a id="p110515"></a>Код</td><td><a id="p110516"></a>Описание</td></tr>
<tr><td><a id="p110517"></a>0</td><td><a id="p110518"></a>Для отказа от гарантии (<a href="https://bukva.ai/docs/reglament-9522013/statya-1#p100949">Статья 95(2)</a> Кодекса)</td></tr>
<tr><td><a id="p110519"></a>1</td><td><a id="p110520"></a>Для полной гарантии (<a href="https://bukva.ai/docs/reglament-9522013/statya-1#p100906">Статья 89(5)</a> Кодекса)</td></tr>
<tr><td><a id="p110521"></a>2</td><td><a id="p110522"></a>Для индивидуальной гарантии в форме обязательства гаранта (<a href="https://bukva.ai/docs/reglament-9522013/statya-1#p100929">Статья 92(1)(b)</a> Кодекса</td></tr>
<tr><td><a id="p110523"></a>3</td><td><a id="p110524"></a>Для индивидуальной гарантии наличными или другим средством платежа, признанным таможенными органами в качестве эквивалентного вкладу наличными, выполненному в евро или в валюте государства-члена ЕС, в котором требуется гарантия (<a href="https://bukva.ai/docs/reglament-9522013/statya-1#p100928">Статья 92(1)(a)</a> Кодекса)</td></tr>
<tr><td><a id="p110525"></a>4</td><td><a id="p110526"></a>Для индивидуальной гарантии в форме расписок (<a href="https://bukva.ai/docs/reglament-9522013/statya-1#p100929">Статья 92(1)(b)</a> Кодекса и <a href="#p101484">Статья 160</a>)</td></tr>
<tr><td><a id="p110527"></a>5</td><td><a id="p110528"></a>Для отказа от гарантии, если сумма импортной или экспортной пошлины, которая должна быть обеспечена, не превышает предела статистической стоимости для деклараций, указанных в соответствии со Статьей 3(4) Регламента (ЕС) 471/2009 Европейского Парламента и Совета ЕС <a href="#p110547">&lt;*&gt;</a> (<a href="https://bukva.ai/docs/reglament-9522013/statya-1#p100914">Статья 89(9)</a> Кодекса)</td></tr>
<tr><td><a id="p110529"></a>I</td><td><a id="p110530"></a>Для индивидуальной гарантии в другой форме, которая предусматривает эквивалентное обеспечение того, что сумма импортной или экспортной пошлины, соответствующая таможенному долгу и другим сборам, будет выплачена (<a href="https://bukva.ai/docs/reglament-9522013/statya-1#p100930">Статья 92(1)(c)</a> Кодекса)</td></tr>
<tr><td><a id="p110531"></a>8</td><td><a id="p110532"></a>Для гарантии, не требуемой для отдельных государственных органов (<a href="https://bukva.ai/docs/reglament-9522013/statya-1#p100908">Статья 89(7)</a> Кодекса)</td></tr>
<tr><td><a id="p110533"></a>B</td><td><a id="p110534"></a>Для гарантии, предоставленной для товаров, отправленных согласно процедуре TIR</td></tr>
<tr><td><a id="p110535"></a>C</td><td><a id="p110536"></a>Для гарантии, не требующейся для товаров, перевозимых на стационарных транспортных установках (<a href="https://bukva.ai/docs/reglament-9522013/statya-1#p100911">Статья 89(8)(b)</a> Кодекса)</td></tr>
<tr><td><a id="p110537"></a>D</td><td><a id="p110538"></a>Для гарантии, не требующейся для товаров, помещенных на процедуру временного допуска в соответствии со Статьей 81(a) Делегированного Регламента (ЕС) 2015/2446 (<a href="https://bukva.ai/docs/reglament-9522013/statya-1#p100912">Статья 89(8)(c)</a> Кодекса)</td></tr>
<tr><td><a id="p110539"></a>E</td><td><a id="p110540"></a>Для гарантии, не требующейся для товаров, помещенных на процедуру временного допуска в соответствии со Статьей 81(b) Делегированного Регламента (ЕС) 2015/2446 (<a href="https://bukva.ai/docs/reglament-9522013/statya-1#p100912">Статья 89(8)(c)</a> Кодекса)</td></tr>
<tr><td><a id="p110541"></a>F</td><td><a id="p110542"></a>Для гарантии, не требующейся для товаров, помещенных на процедуру временного допуска в соответствии со Статьей 81(c) Делегированного Регламента (ЕС) 2015/2446 (<a href="https://bukva.ai/docs/reglament-9522013/statya-1#p100912">Статья 89(8)(c)</a> Кодекса)</td></tr>
<tr><td><a id="p110543"></a>G</td><td><a id="p110544"></a>Для гарантии, не требующейся для товаров, помещенных на процедуру временного допуска в соответствии со Статьей 81(d) Делегированного Регламента (ЕС) 2015/2446 (<a href="https://bukva.ai/docs/reglament-9522013/statya-1#p100912">Статья 89(8)(c)</a> Кодекса)</td></tr>
<tr><td><a id="p110545"></a>H</td><td><a id="p110546"></a>Для гарантии, не требующейся для товаров, помещенных на транзитную процедуру Союза в соответствии со <a href="https://bukva.ai/docs/reglament-9522013/statya-1#p100913">Статьей 89(8)(d)</a> Кодекса</td></tr>
<tr><td colspan="2"><a id="p110547"></a>&lt;*&gt; Регламент (ЕС) 471/2009 Европейского Парламента и Совета ЕС от 6 мая 2009 г. о статистике Сообщества в отношении внешней торговли с третьими странами и об отмене Регламента (ЕС) 1172/95 Совета ЕС (ОЖ N L 152, 16.6.2009, стр. 23).</td></tr>
</table>


<a id="p110548"></a>**ТИТУЛ III. ЛИНГВИСТИЧЕСКИЕ ССЫЛКИ И ИХ КОДЫ**

<a id="p110549"></a>Таблица лингвистических ссылок и их кодов


| <a id="p110550"></a>Лингвистическая ссылка | <a id="p110551"></a>Коды |
| --- | --- |
| <a id="p110552"></a>- BG Ограничена валидност<br>- CS Omezená platnost<br>- DA Begrænset gyldighed<br>- DE Beschränkte Geltung<br>- EE Piiratud kehtivus<br>- EL $\iota\sigma\chi\text{ύ}\varsigma$ $\Pi\epsilon\rho\iota o\rho\iota\sigma\mu\text{έ}\nu\eta$<br>- ES Validez limitada<br>- FR limitée Validité<br>- HR Ogranièena valjanost<br>- IT Validità limitata<br>- LV derîgums Ierobežots<br>- LT Galiojimas apribotas<br>- HU érvényû Korlátozott<br>- MT Validità limitata<br>- NL Beperkte geldigheid<br>- PL Ograniczona $wa¿noœæ$<br>- PT Validade limitada<br>- RO Validitate limitatã<br>- SL Omejena veljavnost<br>- SK Obmedzená platnost'<br>- FI Voimassa rajoitetusti<br>- SV Begränsad giltighet<br>- EN Limited validity | <a id="p110553"></a>Ограниченное действие - 99200 |
| <a id="p110554"></a>- BG Освободено<br>- CS Osvobození<br>- DA Fritaget<br>- DE Befreiung<br>- EE Loobutud<br>- EL $\text{Α}\pi\alpha\lambda\lambda\alpha\gamma\text{ή}$<br>- ES Dispensa<br>- FR Dispense<br>- HR Osloboðeno<br>- IT Dispensa<br>- LV Derîgs bez zîmoga<br>- LT Leista neplombuoti<br>- HU Mentesség<br>- MT Tne - h - hija<br>- NL Vrijstelling<br>- PL Zwolnienie<br>- PT Dispensa<br>- RO Dispensã<br>- SL Opustitev<br>- SK Upustenie<br>- FI Vapautettu<br>- SV Befrielse<br>- EN Waiver | <a id="p110555"></a>Отказ - 99201 |
| <a id="p110556"></a>- BG Алтернативно доказателство<br>- CS dùkaz Alternativní<br>- DA Alternativt bevis<br>- DE Alternativnachweis<br>- EE Alternatiivsed tõendid<br>- EL $\alpha\pi\text{ό}\delta\epsilon\iota\xi\eta$ $\text{Ε}\nu\alpha\lambda\lambda\alpha\kappa\tau\iota\kappa\text{ή}$<br>- ES Prueba alternative<br>- FR Preuve alternative<br>- HR Alternativni dokaz<br>- IT Prova alternativa<br>- LV pierâdîjums Alternatîvs<br>- LT Alternatyvusis árodymas<br>- HU igazolás Alternatív<br>- MT Prova alternattiva<br>- NL Alternatief bewijs<br>- PL Alternatywny dowód<br>- PT Prova alternativa<br>- RO alternativã Probã<br>- SL Alternativno dokazilo<br>- SK dôkaz Alternatívny<br>- FI Vaihtoehtoinen todiste<br>- SV Alternativt bevis<br>- EN Alternative proof | <a id="p110557"></a>Альтернативное доказательство - 99202 |
| <a id="p110558"></a>- BG Различия: митническо учреждение, където са представени стоките...... (наименование и държава)<br>- CS Nesrovnalosti: ъøad , kterému bylo zboží pøedloženo ...... ( název a zemì )<br>- DA Forskelle: det sted, hvor varerne blev frembudt...... (navn og land)<br>- DE Unstimmigkeiten: Stelle, bei der die Gestellung erfolgte...... (Name und Land)<br>- EE Erinevused: asutus, kuhu kaup esitati....... (nimi ja riik)<br>- EL $\Delta\iota\alpha\phi o\rho\text{έ}\varsigma$ : $\epsilon\mu\pi o\rho\epsilon\text{ύ}\mu\alpha\tau\alpha$ $\pi\rho o\sigma\kappa o\mu\iota\sigma\theta\text{έ}\nu\tau\alpha$ $\sigma\tau o$ $\tau\epsilon\lambda\omega\nu\epsilon\text{ί}o$ ...... ( $Ό\nu o\mu\alpha$ $\kappa\alpha\iota$ $\chi\text{ώ}\rho\alpha$ )<br>- ES Diferencias: mercancías presentadas en la oficina...... (nombre y país )<br>- FR Différences : marchandises présentées au bureau...... (nom et pays)<br>- HR Razlike: carinarnica kojoj je roba podnesena... (naziv i zemlja)<br>- IT Differenze: ufficio al quale sono state presentate le merci...... (nome e paese)<br>- LV Atšíirîbas : muitas iestâde , kurâ preces tika uzrâdîtas ...... (nosaukums un valsts)<br>- LT Skirtumai: ástaiga , kuriai pateiktos prekës ...... (pavadinimas ir valstybë )<br>- HU Eltérések : hivatal, ahol az áruk bemutatása megtörtént ...... ( név és ország )<br>- MT Differenzi: $uffi\dot{c}\dot{c}ju$ fejn $l - o\dot{g}\dot{g}etti$ kienu $ppre¿entati$ ...... (isem u $pajji¿$ )<br>- NL Verschillen: kantoor waar de goederen zijn aangebracht...... (naam en land)<br>- PL Niezgodnoœci : urz¹d , w którym przedstawiono towar...... (nazwa i kraj)<br>- PT Diferenças : mercadorias apresentadas na estãncia ...... (nome e país )<br>- RO Diferenþe : mãrfuri prezentate la biroul vamal...... (nume ºi þara )<br>- SL Razlike: urad, pri katerem je bilo blago predloženo ...... (naziv in država )<br>- SK Rozdiely: úrad , ktorému bol tovar predložený ...... ( názov a krajina).<br>- FI Muutos: toimipaikka, jossa tavarat esitetty...... (nimi ja maa)<br>- SV Avvikelse: tullkontor där varorna anmäldes ...... (namn och land)<br>- EN Differences: office where goods were presented...... (name and country) | <a id="p110559"></a>Различия: учреждение, в котором товары были представлены... (название и страна) - 99203 |
| <a id="p110560"></a>- BG Извеждането от ............... подлежи на ограничения или такси съгласно Регламент/Директива/Решение N...,<br>- CS Výstup ze ............... podléhá omezením nebo dávkám podle naøízení / smìrnice / rozhodnutí ![формула](https://i.bukva.ai/sakP7uTQ/img_4.png) ...<br>- DA Udpassage fra............... undergivet restriktioner eller afgifter i henhold til forordning/direktiv/ afgørelse nr....<br>- DE Ausgang aus...............- gemäß Verordnung/Richtlinie/ Beschluss Nr.... Beschränkungen oder Abgaben unterworfen.<br>- EE... territooriumilt väljumise suhtes kohaldatakse piiranguid ja makse vastavalt määrusele /direktiivile/otsusele nr...<br>- EL H $\text{έ}\xi o\delta o\varsigma$ $\alpha\pi\text{ό}$ ............... $\upsilon\pi o\beta\text{ά}\lambda\lambda\epsilon\tau\alpha\iota$ $\sigma\epsilon$ $\pi\epsilon\rho\iota o\rho\iota\sigma\mu o\text{ύ}\varsigma$ $\text{ή}$ $\sigma\epsilon$ $\epsilon\pi\iota\beta\alpha\rho\text{ύ}\nu\sigma\epsilon\iota\varsigma$ $\alpha\pi\text{ό}$ $\tau o\nu$ $\text{Κ}\alpha\nu o\nu\iota\sigma\mu\text{ό}$ / $\tau\eta\nu$ $\text{Ο}\delta\eta\gamma\text{ί}\alpha$ / $\tau\eta\nu$ $\text{Α}\pi\text{ό}\phi\alpha\sigma\eta$ $\alpha\rho\iota\theta.$ ....<br>- ES Salida de............... sometida a restricciones o imposiciones en virtud del (de la) Reglamento/Directiva/ Decisión no...<br>- FR Sortie de............... soumise $\text{а}$ des restrictions ou $\text{а}$ des impositions par le règlement ou la directive/ décision no...<br>- HR Izlaz iz... podliježe ogranièenjima ili pristojbama na temelju Uredbe/Direktive/Odluke br....<br>- IT Uscita dalla...............soggetta a restrizioni o ad imposizioni a norma del(la) regolamento/direttiva/ decisione n....<br>- LV Izvešana no............... piemçrojot ierobežojumus vai maksâjumus saskaòâ ar Regulu/ Direktîvu / Lçmumu Nr....,<br>- LT Išvežimui iš ............... taikomi apribojimai arba mokesèiai , nustatytiReglamentu/ Direktyva/Sprendimu Nr....,<br>- HU A kilépés ............... területérõl a... rendelet/ irányelv / határozat szerinti korlátozás vagy teher megfizetésének kötelezettsége alá esik<br>- MT ![_Hrug&](https://i.bukva.ai/sakP7uTQ/img_5.png) mill-............... $su\dot{g}\dot{g}ett$ g - hall - restrizzjonijiet jew - hlasijiet tah - t Regola/ Direttiva/ $De\dot{c}i¿joni$ Nru...<br>- NL Bij uitgang uit de..................zijn de beperkingen of heffingen van Verordening/ Richtlijn/Besluit nr.... van toepassing.<br>- PL Wyprowadzenie z............... podlega ograniczeniom lub op³atom zgodnie z rozporz¹dzeniem / dyrektyw¹ / decyzj¹ nr...<br>- PT Saída da............... sujeita a restrições ou a imposições pelo(a) Regulamento/ Directiva/ Decisão n.o...<br>- RO Ieºire din............... supusã restricþiilor sau impozitelor prin Regulamentul/ Directiva/Decizia nr... - SL Iznos iz............... zavezan omejitvam ali obveznim dajatvam na podlagi Uredbe/Direktive/ Odloèbe št ....<br>- SK Výstup z...............podlieha obmedzeniam alebo platbám podl'a nariadenia/ smernice/rozhodnutia ![формула](https://i.bukva.ai/sakP7uTQ/img_6.png) ....<br>- FI............... vientiin sovelletaan asetuksen/direktiivin/ päätöksen N:o... mukaisia rajoituksia tai maksuja<br>- EN Exit from............... subject to restrictions or charges under Regulation/Directive/Decision No... | <a id="p110561"></a>Вывоз из.... согласно ограничениям или сборам в соответствии с Регламентом/Директивой/Решением... - 99204 |
| <a id="p110562"></a>- BG Одобрен изпращач<br>- CS odesílatel Schválený<br>- DA Godkendt afsender<br>- DE Zugelassener Versender<br>- EE Volitatud kaubasaatja<br>- EL $\alpha\pi o\sigma\tau o\lambda\text{έ}\alpha\varsigma$ $\text{Ε}\gamma\kappa\epsilon\kappa\rho\iota\mu\text{έ}\nu o\varsigma$<br>- ES Expedidor autorizado<br>- FR agréé Expéditeur<br>- HR pošiljatelj Ovlašteni<br>- IT Speditore autorizzato<br>- LV nosûtîtâjs Atzîtais<br>- LT gavëjas Ágaliotasis<br>- HU feladó Engedélyezett<br>- MT Awtorizzat li jibg - hat<br>- NL Toegelaten afzender<br>- PL $Upowa¿niony$ nadawca<br>- PT Expedidor autorizado<br>- RO Expeditor agreat<br>- SL pošiljatelj Pooblašèeni<br>- SK Schválený odosielatel'<br>- FI Valtuutettu lähettäjä<br>- SV avsändare Godkänd<br>- EN Authorised consignor | <a id="p110563"></a>Авторизованный грузоотправитель - 99206 |
| <a id="p110564"></a>- BG Освободен от подпис<br>- CS Podpis se nevyžaduje<br>- DA Fritaget for underskrift<br>- DE Freistellung von der Unterschriftsleistung<br>- EE Allkirjanõudest loobutud<br>- EL $\upsilon\pi o\gamma\rho\alpha\phi\text{ή}$ $\alpha\pi\alpha\iota\tau\epsilon\text{ί}\tau\alpha\iota$ $\Delta\epsilon\nu$<br>- ES Dispensa de firma<br>- FR Dispense de signature<br>- HR Osloboðeno potpisa<br>- IT Dispensa dalla firma<br>- LV Derîgs bez paraksta<br>- LT Leista nepasirašyti<br>- HU mentesítve alól Aláírás<br>- MT Firma mhux $meh - tie\dot{g}a$<br>- NL Van ondertekening vrijgesteld<br>- PL Zwolniony ze sk³adania podpisu<br>- PT Dispensada a assinatura<br>- RO Dispensã de semnãturã<br>- SL Opustitev podpisa<br>- SK Upustenie od podpisu<br>- FI Vapautettu allekirjoituksesta<br>- SV Befrielse från underskrift<br>- EN Signature waived | <a id="p110565"></a>Подпись отменена - 99207 |
| <a id="p110566"></a>- BG ЗАБРАНЕНО ОБЩО ОБЕЗПЕЧЕНИЕ<br>- CS ZÁKAZ SOUBORNÉ JISTOTY<br>- DA FORBUD MOD SAMLET SIKKERHEDSSTILLELSE<br>- DE GESAMTBÜRGSCHAFT UNTERSAGT<br>- EE ÜLDTAGATISE KASUTAMINE KEELATUD<br>- EL H АПАГОРЕYЕТАI $\text{Ε}\Gamma\Gamma\text{ΥΗ}\Sigma\text{Η}$ $\Sigma\text{ΥΝΟ}\Lambda\text{ΙΚΗ}$<br>- ES GARANTÍA GLOBAL PROHIBIDA<br>- FR GARANTIE GLOBALE INTERDITE<br>- HR ZABRANJENO ZAJEDNIÈKO JAMSTVO<br>- IT GARANZIA GLOBALE VIETATA<br>- LV VISPÂRÇJS GALVOJUMS AIZLIEGTS<br>- LT NAUDOTI UŽDRAUSTA $GARANTIJ¥$ $BENDR¥J¥$<br>- HU ÖSSZKEZESSÉG TILOS<br>- MT MHUX PERMESSA GARANZIJA KOMPRENSIVA<br>- NL DOORLOPENDE ZEKERHEID VERBODEN<br>- PL ZAKAZ KORZYSTANIA Z ZABEZPIECZENIA GENERALNEGO<br>- PT GARANTIA GLOBAL PROIBIDA<br>- RO INTERZISÃ GLOBALÃ GARANÞIA<br>- SL PREPOVEDANO SKUPNO ZAVAROVANJE<br>- SK ZÁKAZ CELKOVEJ ZÁRUKY<br>- FI YLEISVAKUUDEN KÄYTTÖ KIELLETTY<br>- SV SAMLAD FÖRBJUDEN SÄKERHET<br>- EN COMPREHENSIVE GUARANTEE PROHIBITED | <a id="p110567"></a>ПОЛНАЯ ГАРАНТИЯ ЗАПРЕЩЕНА - 99208 |
| <a id="p110568"></a>- BG ИЗПОЛЗВАНЕ БЕЗ ОГРАНИЧЕНИЯ<br>- CS POUŽITÍ NEOMEZENÉ<br>- DA UBEGRÆNSET ANVENDELSE<br>- DE UNBESCHRÄNKTE VERWENDUNG<br>- EE PIIRAMATU KASUTAMINE<br>- EL $\text{ΧΡΗ}\Sigma\text{Η}$ $\text{Α}\Pi\text{ΕΡΙΟΡΙ}\Sigma\text{ΤΗ}$<br>- ES UTILIZACIÓN NO LIMITADA<br>- FR UTILISATION NON LIMITÉE<br>- HR NEOGRANIÈENA UPORABA<br>- IT UTILIZZAZIONE NON LIMITATA<br>- LV NEIEROBEŽOTS IZMANTOJUMS<br>- LT NEAPRIBOTAS NAUDOJIMAS<br>- HU KORLÁTOZÁS ALÁ NEM HASZNÁLAT ESÕ<br>- MT $U¯U$ MHUX RISTRETT<br>- NL GEBRUIK ONBEPERKT<br>- PL NIEOGRANICZONE KORZYSTANIE<br>- PT UTILIZAÇÃO ILIMITADA<br>- RO UTILIZARE NELIMITATÃ<br>- SL NEOMEJENA UPORABA<br>- SK POUŽITIE NEOBMEDZENÉ<br>- FI KÄYTTÖÄ EI RAJOITETTU<br>- SV ANVÄNDNING OBEGRÄNSAD<br>- EN UNRESTRICTED USE | <a id="p110569"></a>НЕОГРАНИЧЕННОЕ ИСПОЛЬЗОВАНИЕ - 99209 |
| <a id="p110570"></a>- BG Разни<br>- CS Rùzní<br>- DA Diverse<br>- DE Verschiedene<br>- EE Erinevad<br>- EL $\Delta\iota\text{ά}\phi o\rho\alpha$<br>- ES Varios<br>- FR Divers<br>- HR Razni<br>- IT Vari<br>- LV Dažâdi<br>- LT Ávairûs<br>- HU Többféle<br>- MT Diversi<br>- NL Diverse<br>- PL $Ró¿ne$<br>- PT Diversos<br>- RO Diverºi<br>- SL Razno<br>- SK Rôzne<br>- FI Useita<br>- SV Flera<br>- EN Various | <a id="p110571"></a>Разное - 99211 |
| <a id="p110572"></a>- BG Насипно<br>- CS loženo Volnì<br>- DA Bulk<br>- DE Lose<br>- EE Pakendamata<br>- EL $\text{Χύ}\mu\alpha$<br>- ES A granel<br>- FR Vrac<br>- HR Rasuto<br>- IT Alla rinfusa<br>- LV Berams (lejams)<br>- LT Nesupakuota<br>- HU Ömlesztett<br>- MT Bil - kwantità<br>- NL Los gestort<br>- PL Luzem<br>- PT A granel<br>- RO Vrac<br>- SL Razsuto<br>- SK Vol'ne ložené<br>- FI Irtotavaraa<br>- SV Bulk<br>- EN Bulk | <a id="p110573"></a>Навалом - 99212 |
| <a id="p110574"></a>- BG Изпращач<br>- CS Odesílatel<br>- DA Afsender<br>- DE Versender<br>- EE Saatja<br>- EL $\text{Α}\pi o\sigma\tau o\lambda\text{έ}\alpha\varsigma$<br>- ES Expedidor<br>- FR Expéditeur<br>- HR Pošiljatelj<br>- IT Speditore<br>- LV Nosûtîtâjs<br>- LT Siuntëjas<br>- HU Feladó<br>- MT Min jikkonsenja<br>- NL Afzender<br>- PL Nadawca<br>- PT Expedidor<br>- RO Expeditor<br>- SL Pošiljatelj<br>- SK Odosielatel'<br>- FI Lähettäjä<br>- SV Avsändare<br>- EN Consignor | <a id="p110575"></a>Грузоотправитель - 99213 |


<a id="p110576"></a>Приложение 12-01

<a id="p110577"></a>**ФОРМЫ И КОДЫ В ОТНОШЕНИИ ТРЕБОВАНИЙ**
**К ОБЩИМ ДАННЫМ РЕГИСТРАЦИИ СУБЪЕКТОВ ЭКОНОМИЧЕСКОЙ**
**ДЕЯТЕЛЬНОСТИ И ДРУГИХ ЛИЦ**

<a id="p110578"></a>**ВВЕДЕНИЕ**

1. <a id="p110579"></a>Формы и коды, включенные в настоящее Приложение, применяются в отношении требований к общим данным для регистрации субъектов экономической деятельности и других лиц.
2. <a id="p110580"></a>[Титул I](https://bukva.ai/docs/reglament-20152447/statya-350#p110596) включает в себя формы элементов данных.
3. <a id="p110581"></a>Когда информация для регистрации субъектов экономической деятельности и других лиц, связанных с Приложением 12-01 к Делегированному Регламенту (ЕС) 2015/2446, принимает форму кодов, применяется список кодов, предусмотренный в [Титуле II](https://bukva.ai/docs/reglament-20152447/statya-350#p110681).
4. <a id="p110582"></a>Термин "тип/длина" в разъяснении элемента указывает на требование для типа данных и длины данных. Коды для типов данных следующие:
<a id="p110583"></a>a - буквенный;
<a id="p110584"></a>n - цифровой;
<a id="p110585"></a>an - буквенно-цифровой.
<a id="p110586"></a>Число, следующее за кодом, указывает на допустимую длину данных. Применяется следующее.
<a id="p110587"></a>Дополнительные две точки перед индикатором длины означают, что данные не имеют фиксированной длины, но они могут иметь длину до количества знаков, определенных индикатором длины. Запятая в длине данных означает, что элемент может содержать десятые доли, знаки до запятой указывают общую длину элемента, знаки после запятой указывают максимальное количество знаков после десятичного знака.
<a id="p110588"></a>Примеры длины и формы поля:
<a id="p110589"></a>a1 - 1 буквенный знак, фиксированная длина;
<a id="p110590"></a>n2 - 2 цифровых знака, фиксированная длина;
<a id="p110591"></a>an3 - 3 буквенно-цифровых знака, фиксированная длина;
<a id="p110592"></a>a..4 - до 4 буквенных знаков;
<a id="p110593"></a>n..5 - до 5 цифровых знаков;
<a id="p110594"></a>an..6 - до 6 буквенно-цифровых знаков;
<a id="p110595"></a>n..7,2 - до 7 цифровых знаков, в том числе максимально 2 десятичных знака, ограничителю разрешено "плавать".

<a id="p110596"></a>**ТИТУЛ I. ФОРМАТЫ И КОЛИЧЕСТВО ЭЛЕМЕНТОВ ТРЕБОВАНИЙ**
**ДЛЯ РЕГИСТРАЦИИ СУБЪЕКТОВ ЭКОНОМИЧЕСКОЙ ДЕЯТЕЛЬНОСТИ**
**И ДРУГИХ ЛИЦ**


| <a id="p110597"></a>Номер D.E. | <a id="p110598"></a>Название D.E. | <a id="p110599"></a>Формат D.E.<br>(Тип/длина) | <a id="p110600"></a>Список кодов в [Титуле II](https://bukva.ai/docs/reglament-20152447/statya-350#p110681) (Y(да)/N(нет)) | <a id="p110601"></a>Количество элементов | <a id="p110602"></a>Примечания |
| --- | --- | --- | --- | --- | --- |
| <a id="p110603"></a>1 | <a id="p110604"></a>Номер EORI | <a id="p110605"></a>an..17 | <a id="p110606"></a>N | <a id="p110607"></a>1x | <a id="p110608"></a>Структура номера EORI определена в [Титуле II](https://bukva.ai/docs/reglament-20152447/statya-350#p110681) |
| <a id="p110609"></a>2 | <a id="p110610"></a>Полное имя/наименование лица | <a id="p110611"></a>an..512 | <a id="p110612"></a>N | <a id="p110613"></a>1x |  |
| <a id="p110614"></a>3 | <a id="p110615"></a>Адрес учреждения/адрес места жительства | <a id="p110616"></a>Улица и номер: an..70<br>Почтовый индекс: an..9<br>Город: an..35<br>Код страны: a2 | <a id="p110617"></a>N | <a id="p110618"></a>1x | <a id="p110619"></a>Используется код страны, определенный в [Титуле II](https://bukva.ai/docs/reglament-20152447/statya-350#p110681) в отношении кода страны D.E. [1](https://bukva.ai/docs/reglament-20152447/statya-350#p110686) Номер EORI |
| <a id="p110620"></a>4 | <a id="p110621"></a>Учреждение на таможенной территории Союза | <a id="p110622"></a>n1 | <a id="p110623"></a>Y | <a id="p110624"></a>1x |  |
| <a id="p110625"></a>5 | <a id="p110626"></a>Идентификационный(ые) номер(а) плательщика НДС | <a id="p110627"></a>Код страны: a2<br>Идентификационный номер плательщика НДС: an..15 | <a id="p110628"></a>N | <a id="p110629"></a>99x | <a id="p110630"></a>Формат идентификационного номера плательщика НДС определен в [Статье 215](https://bukva.ai/docs/direktiva-2006112es/statya-215#p101309) Директивы 2006/112/ЕС об общей системе налога на добавленную стоимость. |
| <a id="p110631"></a>6 | <a id="p110632"></a>Правовой статус | <a id="p110633"></a>an..50 | <a id="p110634"></a>N | <a id="p110635"></a>1x |  |
| <a id="p110636"></a>7 | <a id="p110637"></a>Информация для контакта | <a id="p110638"></a>Имя лица для контакта: an..70<br>Улица и номер: an..70<br>Почтовый индекс: an..9<br>Город: an..35<br>Номер телефона: an..50<br>Номер факса: an..50<br>Адрес электронной почты: an..50 | <a id="p110639"></a>N | <a id="p110640"></a>9x |  |
| <a id="p110641"></a>8 | <a id="p110642"></a>Уникальный идентификационный номер третьей страны | <a id="p110643"></a>an..17 | <a id="p110644"></a>N | <a id="p110645"></a>99x |  |
| <a id="p110646"></a>9 | <a id="p110647"></a>Согласие на раскрытие персональных данных, указанных в [пунктах 1](https://bukva.ai/docs/reglament-20152447/statya-350#p110603), [2](https://bukva.ai/docs/reglament-20152447/statya-350#p110609) и [3](https://bukva.ai/docs/reglament-20152447/statya-350#p110614) | <a id="p110648"></a>n1 | <a id="p110649"></a>Y | <a id="p110650"></a>1x |  |
| <a id="p110651"></a>10 | <a id="p110652"></a>Сокращенное наименование | <a id="p110653"></a>an..70 | <a id="p110654"></a>N | <a id="p110655"></a>1x |  |
| <a id="p110656"></a>11 | <a id="p110657"></a>Дата учреждения | <a id="p110658"></a>n8 (ггггммдд) | <a id="p110659"></a>N | <a id="p110660"></a>1x |  |
| <a id="p110661"></a>12 | <a id="p110662"></a>Вид лица | <a id="p110663"></a>n1 | <a id="p110664"></a>Y | <a id="p110665"></a>1x |  |
| <a id="p110666"></a>13 | <a id="p110667"></a>Основная экономическая деятельность | <a id="p110668"></a>an4 | <a id="p110669"></a>Y | <a id="p110670"></a>1x |  |
| <a id="p110671"></a>14 | <a id="p110672"></a>Дата начала номера EORI | <a id="p110673"></a>n8 (ггггммдд) | <a id="p110674"></a>N | <a id="p110675"></a>1x |  |
| <a id="p110676"></a>15 | <a id="p110677"></a>Дата окончания EORI | <a id="p110678"></a>n8 (ггггммдд) | <a id="p110679"></a>N | <a id="p110680"></a>1x |  |


<a id="p110681"></a>**ТИТУЛ II. КОДЫ В ОТНОШЕНИИ ТРЕБОВАНИЙ К ОБЩИМ ДАННЫМ**
**РЕГИСТРАЦИИ СУБЪЕКТОВ ЭКОНОМИЧЕСКОЙ ДЕЯТЕЛЬНОСТИ**
**И ДРУГИХ ЛИЦ**

<a id="p110682"></a>**КОДЫ**

<a id="p110683"></a>**1. ВВЕДЕНИЕ**

<a id="p110684"></a>Настоящий Титул содержит коды, используемые для регистрации субъектов экономической деятельности и других лиц.

<a id="p110685"></a>**2. КОДЫ**

<a id="p110686"></a>1 Номер EORI
<a id="p110687"></a>Номер EORI структурируется следующим образом:


| <a id="p110688"></a>Поле | <a id="p110689"></a>Содержание | <a id="p110690"></a>Формат |
| --- | --- | --- |
| <a id="p110691"></a>1 | <a id="p110692"></a>Идентификатор государства-члена ЕС (код страны) | <a id="p110693"></a>a2 |
| <a id="p110694"></a>2 | <a id="p110695"></a>Уникальный идентификатор в государстве-члене ЕС | <a id="p110696"></a>an..15 |


<a id="p110697"></a>Код страны: буквенные коды Союза для стран и территорий основаны на текущих 2 alpha кодах ISO (a2) настолько, насколько они совместимы с требованиями Регламента (ЕС) 1106/2012 Европейской Комиссии. Европейская Комиссия регулярно публикует Регламенты, обновляющие список кодов стран.

<a id="p110698"></a>4 Учреждение на таможенной территории Союза
<a id="p110699"></a>0 - Не учреждено на таможенной территории Союза
<a id="p110700"></a>1 - Учреждено на таможенной территории Союза

<a id="p110701"></a>9 Согласие на раскрытие персональных данных, указанных в [пунктах 1](https://bukva.ai/docs/reglament-20152447/statya-350#p110603), [2](https://bukva.ai/docs/reglament-20152447/statya-350#p110609) и [3](https://bukva.ai/docs/reglament-20152447/statya-350#p110614)
<a id="p110702"></a>0 - Не публикуется
<a id="p110703"></a>1 - Публикуется

<a id="p110704"></a>12 Вид лица
<a id="p110705"></a>Используются следующие коды:
<a id="p110706"></a>1 - Физическое лицо
<a id="p110707"></a>2 - Юридическое лицо
<a id="p110708"></a>3 - Ассоциация лиц, которая не является юридическим лицом, но которая признана согласно законодательству Союза или национальному законодательству имеющей полномочия на выполнение правовых актов.

<a id="p110709"></a>13 Основная экономическая деятельность
<a id="p110710"></a>Код основной экономической деятельности на четырехзначном уровне в соответствии со статистической классификацией экономической деятельности в Европейской Сообществе (NACE; Регламент (ЕС) 1893/2006), указанный в бизнес регистре государств-членов ЕС.


<a id="p110711"></a>Приложение 12-02

<a id="p110712"></a>**РЕШЕНИЯ ОБ ОБЯЗАТЕЛЬНОЙ ИНФОРМАЦИИ О ПРОИСХОЖДЕНИИ**


<table>
<colgroup><col width="2%"><col width="2%"><col width="2%"><col width="3%"><col width="3%"><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="4%"><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="2%"></colgroup>
<tr><td colspan="42"><a id="p110713"></a>ЕВРОПЕЙСКИЙ СОЮЗ - РЕШЕНИЕ ОБ ОБЯЗАТЕЛЬНОЙ ИНФОРМАЦИИ О ПРОИСХОЖДЕНИИ BOI</td></tr>
<tr><td colspan="20" rowspan="3"><a id="p110714"></a>1. Таможенный орган, принимающий решение</td><td colspan="22"><a id="p110715"></a>2. Исходящий номер решения BOI</td></tr>
<tr><td></td><td></td><td></td><td colspan="2"></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td colspan="2"></td></tr>
<tr><td colspan="22"><a id="p110716"></a>Национальный исходящий номер (если есть):</td></tr>
<tr><td colspan="20" rowspan="2"><a id="p110717"></a>3. Владелец (полное название/имя и сведения) (конфиденциально)</td><td colspan="22"><a id="p110718"></a>4. Срок действия</td></tr>
<tr><td colspan="22"><a id="p110719"></a>год месяц день</td></tr>
<tr><td colspan="20" rowspan="2"><a id="p110720"></a>N EORI</td><td colspan="9"><a id="p110721"></a>Дата начала решения:</td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td colspan="3"></td></tr>
<tr><td colspan="9"></td><td colspan="13"></td></tr>
<tr><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td colspan="9" rowspan="2"><a id="p110722"></a>Окончание продленного использования:</td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td colspan="3"></td></tr>
<tr><td colspan="20"></td><td colspan="13"></td></tr>
<tr><td colspan="20" rowspan="4"><a id="p110723"></a>Общие замечания<br>Без ущерба действию положений <a href="https://bukva.ai/docs/reglament-9522013/statya-1#p100435">Статьи 34(4)</a> и <a href="https://bukva.ai/docs/reglament-9522013/statya-1#p100436">(5)</a> Регламента (ЕС) 952/2013 Европейского Парламента и Совета ЕС данная BOI действует 3 года с даты решения.</td><td colspan="22"><a id="p110724"></a>5. Дата и регистрационный номер заявления</td></tr>
<tr><td colspan="22"><a id="p110725"></a>год месяц день</td></tr>
<tr><td colspan="9"><a id="p110726"></a>Дата:</td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td colspan="3"></td></tr>
<tr><td colspan="22" rowspan="2"></td></tr>
<tr><td colspan="20" rowspan="7"><a id="p110727"></a>Владелец BOI должен иметь возможность доказать, что эти товары и обстоятельства, определяющие приобретение ими статуса происхождения, соответствуют во всех отношениях товарам и обстоятельствам, описанным в решении.</td></tr>
<tr><td colspan="22"><a id="p110728"></a>Регистрационный номер</td></tr>
<tr><td colspan="4"><a id="p110729"></a>(если есть):</td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td></tr>
<tr><td colspan="22"></td></tr>
<tr><td colspan="22"><a id="p110730"></a>6. Код товара</td></tr>
<tr><td colspan="22"></td></tr>
<tr><td colspan="22"><a id="p110731"></a>(Эта классификация имеет всего лишь указательный характер и необязательна для администрирования, за исключением BTI, указанной в <a href="#p110771">графе 17</a>)</td></tr>
<tr><td colspan="42"><a id="p110732"></a>7. Описание товаров</td></tr>
<tr><td colspan="42"></td></tr>
<tr><td colspan="42"><a id="p110733"></a>и (если требуется) их состав и способы, используемые для<br>их досмотра; коммерческая стоимость (конфиденциально)</td></tr>
<tr><td colspan="42"><a id="p110734"></a>8. Страна происхождения и правовые рамки (непреференциальные/преференциальные; ссылка на соглашение, конвенцию, решение, регламент; вид сделки; "не имеющие происхождения", если преференциальное происхождение не может быть определено; другие)</td></tr>
<tr><td colspan="42"></td></tr>
<tr><td colspan="5"><a id="p110735"></a>Вид сделки:</td><td colspan="8"><a id="p110736"></a>ИМПОРТ</td><td colspan="2"><a id="p110737"></a><img src="https://i.bukva.ai/sakP7uTQ/img_7.png" alt="формула"></td><td colspan="6"><a id="p110738"></a>или ЭКСПОРТ</td><td colspan="2"><a id="p110739"></a><img src="https://i.bukva.ai/sakP7uTQ/img_8.png" alt="формула"></td><td colspan="19"></td></tr>
<tr><td colspan="42"><a id="p110740"></a>9. Обоснование оценки происхождения таможенным органом (товары полностью получены, последнее значительное преобразование, существенная обработка или переработка, накопление происхождения, др.)</td></tr>
<tr><td colspan="42"></td></tr>
<tr><td colspan="42"><a id="p110741"></a>Место</td></tr>
<tr><td colspan="42"></td></tr>
<tr><td colspan="4"><a id="p110742"></a>Дата</td><td colspan="7"><a id="p110743"></a>Подпись</td><td colspan="31"><a id="p110744"></a>Печать</td></tr>
<tr><td colspan="42"></td></tr>
<tr><td></td><td colspan="6"><a id="p110745"></a>Год</td><td colspan="6"><a id="p110746"></a>Месяц</td><td colspan="29"><a id="p110747"></a>День</td></tr>
<tr><td></td><td></td><td></td><td></td><td></td><td colspan="4"></td><td></td><td></td><td colspan="6"></td><td></td><td></td><td colspan="23"></td></tr>
<tr><td colspan="42"></td></tr>
</table>


<table>
<colgroup><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="7%"><col width="2%"><col width="2%"><col width="2%"><col width="7%"><col width="2%"><col width="3%"><col width="10%"><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="3%"><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="5%"></colgroup>
<tr><td colspan="33"><a id="p110748"></a>ЕВРОПЕЙСКИЙ СОЮЗ - РЕШЕНИЕ ОБ ОБЯЗАТЕЛЬНОЙ ИНФОРМАЦИИ О ПРОИСХОЖДЕНИИ BOI</td></tr>
<tr><td colspan="13"><a id="p110749"></a>10. Цена на условиях франко завод (если требуется) (конфиденциально)</td><td colspan="20"><a id="p110750"></a>2. Исходящий номер решение BOI</td></tr>
<tr><td colspan="13"></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td></tr>
<tr><td colspan="13"></td><td colspan="20" rowspan="2"></td></tr>
<tr><td colspan="13"></td></tr>
<tr><td colspan="6"><a id="p110751"></a>12. Основные используемые материалы</td><td colspan="6" rowspan="2"><a id="p110752"></a>Страна происхождения</td><td colspan="5" rowspan="2"><a id="p110753"></a>Заголовок HS/ Код CN</td><td colspan="10" rowspan="2"><a id="p110754"></a>Стоимость</td><td colspan="6" rowspan="2"><a id="p110755"></a>(конфиденциально)</td></tr>
<tr><td colspan="6"><a id="p110756"></a>(если требуется)</td></tr>
<tr><td colspan="33"><a id="p110757"></a>Место</td></tr>
<tr><td colspan="33"></td></tr>
<tr><td colspan="4"><a id="p110758"></a>Дата</td><td colspan="3"><a id="p110759"></a>Подпись</td><td colspan="26"><a id="p110760"></a>Печать</td></tr>
<tr><td colspan="33"></td></tr>
<tr><td></td><td colspan="4"><a id="p110761"></a>Год</td><td colspan="4"><a id="p110762"></a>Месяц</td><td colspan="24"><a id="p110763"></a>День</td></tr>
<tr><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td><td colspan="2"></td><td></td><td></td><td colspan="21"></td></tr>
<tr><td colspan="33"></td></tr>
</table>


<table>
<colgroup><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="4%"><col width="2%"><col width="2%"><col width="2%"><col width="3%"><col width="3%"><col width="3%"><col width="2%"><col width="2%"><col width="3%"><col width="4%"><col width="2%"><col width="1%"><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="1%"><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="1%"><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="2%"><col width="6%"></colgroup>
<tr><td colspan="41"><a id="p110764"></a>ЕВРОПЕЙСКИЙ СОЮЗ - РЕШЕНИЕ ОБ ОБЯЗАТЕЛЬНОЙ ИНФОРМАЦИИ О ПРОИСХОЖДЕНИИ BOI</td></tr>
<tr><td colspan="18"></td><td colspan="23"><a id="p110765"></a>13. Исходящий номер решение BOI</td></tr>
<tr><td colspan="18"></td><td></td><td colspan="2"></td><td></td><td></td><td></td><td colspan="2"></td><td></td><td></td><td></td><td></td><td></td><td></td><td colspan="2"></td><td></td><td></td><td></td><td></td><td></td><td></td><td></td></tr>
<tr><td colspan="18"></td><td colspan="23" rowspan="2"></td></tr>
<tr><td colspan="18"></td></tr>
<tr><td colspan="41"><a id="p110766"></a>14. Описание переработки, необходимой для получения (конфиденциально) происхождения (если требуется)</td></tr>
<tr><td colspan="41"></td></tr>
<tr><td colspan="41"><a id="p110767"></a>15. Язык</td></tr>
<tr><td colspan="41"><a id="p110768"></a>BG CS DA DE EL EN ES ET FI FR HR HU IT LT LV</td></tr>
<tr><td colspan="41"><a id="p110769"></a>MT NL PL PT RO SK SL SV</td></tr>
<tr><td colspan="18"><a id="p110770"></a>16. Ссылка на существующую BOI или заявление</td><td colspan="23"><a id="p110771"></a>17. Ссылка на существующую BTI или заявление</td></tr>
<tr><td colspan="18"></td><td colspan="23"></td></tr>
<tr><td colspan="18"><a id="p110772"></a>18. Ключевые слова:</td><td colspan="23"><a id="p110773"></a>(&lt;*&gt; конфиденциально)</td></tr>
<tr><td colspan="18"></td><td colspan="23"></td></tr>
<tr><td colspan="2"></td><td colspan="15"></td><td><a id="p110774"></a>&lt;*&gt;</td><td colspan="2"></td><td colspan="20"></td><td><a id="p110775"></a>&lt;*&gt;</td></tr>
<tr><td colspan="2"></td><td colspan="15"></td><td></td><td colspan="2"></td><td colspan="20"></td><td></td></tr>
<tr><td colspan="2"></td><td colspan="15"></td><td><a id="p110776"></a>&lt;*&gt;</td><td colspan="2"></td><td colspan="20"></td><td><a id="p110777"></a>&lt;*&gt;</td></tr>
<tr><td colspan="2"></td><td colspan="15"></td><td></td><td colspan="2"></td><td colspan="20"></td><td></td></tr>
<tr><td colspan="2"></td><td colspan="15"></td><td><a id="p110778"></a>&lt;*&gt;</td><td colspan="2"></td><td colspan="20"></td><td><a id="p110779"></a>&lt;*&gt;</td></tr>
<tr><td colspan="2"></td><td colspan="15"></td><td></td><td colspan="2"></td><td colspan="20"></td><td></td></tr>
<tr><td colspan="2"></td><td colspan="15"></td><td><a id="p110780"></a>&lt;*&gt;</td><td colspan="2"></td><td colspan="20"></td><td><a id="p110781"></a>&lt;*&gt;</td></tr>
<tr><td colspan="2"></td><td colspan="15"></td><td></td><td colspan="2"></td><td colspan="20"></td><td></td></tr>
<tr><td colspan="41"><a id="p110782"></a>19. Настоящее решение BOI было выдано на основании следующих элементов, представленных заявителем</td></tr>
<tr><td colspan="7"><a id="p110783"></a>Описание <img src="https://i.bukva.ai/sakP7uTQ/img_9.png" alt="формула"></td><td colspan="5"><a id="p110784"></a>Брошюры <img src="https://i.bukva.ai/sakP7uTQ/img_10.png" alt="формула"></td><td colspan="5"><a id="p110785"></a>Фотографии <img src="https://i.bukva.ai/sakP7uTQ/img_11.png" alt="формула"></td><td colspan="8"><a id="p110786"></a>Образцы <img src="https://i.bukva.ai/sakP7uTQ/img_12.png" alt="формула"></td><td colspan="8"><a id="p110787"></a>Другое <img src="https://i.bukva.ai/sakP7uTQ/img_13.png" alt="формула"></td><td colspan="8"></td></tr>
<tr><td colspan="5"><a id="p110788"></a>Место</td><td colspan="4"><a id="p110789"></a>Дата</td><td colspan="4"><a id="p110790"></a>Подпись</td><td colspan="28"><a id="p110791"></a>Печать</td></tr>
<tr><td colspan="41"></td></tr>
<tr><td></td><td colspan="5"><a id="p110792"></a>Год</td><td colspan="5"><a id="p110793"></a>Месяц</td><td colspan="30"><a id="p110794"></a>День</td></tr>
<tr><td></td><td></td><td></td><td></td><td></td><td colspan="3"></td><td></td><td></td><td colspan="4"></td><td></td><td></td><td colspan="25"></td></tr>
<tr><td colspan="41"></td></tr>
</table>


<a id="p110795"></a>Приложение 12-03

<a id="p110796"></a>**БИРКА, КОТОРАЯ КРЕПИТСЯ НА СДАВАЕМЫЙ В АЭРОПОРТУ СОЮЗА БАГАЖ**
**(СТАТЬЯ 44)**

1. <a id="p110797"></a>Характеристики

<a id="p110798"></a>Бирка, указанная в [Статье 44](https://bukva.ai/docs/reglament-20152447/statya-44#p100459), должна быть разработана таким образом, чтобы нельзя было использовать ее повторно.

> <a id="p110799"></a>*(a) Бирка должна иметь зеленую полосу не менее 5 мм шириной по всей длине по обоим краям разделов маршрута и идентификации. Более того, эти зеленые полоски могут распространяться также на другие части багажной бирки, за исключением всех частей, показывающих номер штрихкода, который должен быть напечатан на чистом белом фоне. (См. образцы в [п. 2(a))](https://bukva.ai/docs/reglament-20152447/statya-350#p110802)*

<a id="p110800"></a>(b) Для "срочного багажа" бирка должна иметь зеленые полосы вместо красных по краям. (См. образец в [п. 2(b))](https://bukva.ai/docs/reglament-20152447/statya-350#p110804)

2. <a id="p110801"></a>Образцы

<a id="p110802"></a>(a)

<a id="p110803"></a> ![рис. 15](https://i.bukva.ai/sakP7uTQ/img_14.png) 


<a id="p110804"></a>(b)

<a id="p110805"></a> ![рис. 16](https://i.bukva.ai/sakP7uTQ/img_15.png) 


<a id="p110806"></a>Приложение 21-01

<a id="p110807"></a>СПИСОК ЭЛЕМЕНТОВ ДАННЫХ НАДЗОРА, УКАЗАННЫЙ В [СТАТЬЕ 55(1)](https://bukva.ai/docs/reglament-20152447/statya-55#p100533)


<table>
<colgroup><col width="11%"><col width="31%"><col width="20%"><col width="19%"><col width="19%"></colgroup>
<tr><td rowspan="2"><a id="p110808"></a>Порядковый номер D.E.</td><td rowspan="2"><a id="p110809"></a>Название D.E.</td><td rowspan="2"><a id="p110810"></a>Формат (определенный в <a href="#p104348">Приложении B</a>)</td><td colspan="2"><a id="p110811"></a>Количество элементов</td></tr>
<tr><td><a id="p110812"></a>На уровне заголовка</td><td><a id="p110813"></a>На уровне пункта</td></tr>
<tr><td><a id="p110814"></a>1/1</td><td><a id="p110815"></a>Вид декларации</td><td colspan="3"><a id="p110816"></a>То же, что и для элемента данных под порядковым номером 1/1</td></tr>
<tr><td><a id="p110817"></a>1/2</td><td><a id="p110818"></a>Вид дополнительной декларации</td><td colspan="3"><a id="p110819"></a>То же, что и для элемента данных под порядковым номером 1/2</td></tr>
<tr><td><a id="p110820"></a>1/6</td><td><a id="p110821"></a>Номер пунктов товаров</td><td colspan="3"><a id="p110822"></a>То же, что и для элемента данных под порядковым номером 1/6</td></tr>
<tr><td><a id="p110823"></a>1/10</td><td><a id="p110824"></a>Процедура</td><td colspan="3"><a id="p110825"></a>То же, что и для элемента данных под порядковым номером 1/10</td></tr>
<tr><td><a id="p110826"></a>1/11</td><td><a id="p110827"></a>Дополнительная процедура</td><td colspan="3"><a id="p110828"></a>То же, что и для элемента данных под порядковым номером 1/11</td></tr>
<tr><td><a id="p110829"></a>2/3</td><td><a id="p110830"></a>Представленные документы, сертификаты и разрешения, дополнительные ссылки</td><td colspan="3"><a id="p110831"></a>То же, что и для элемента данных под порядковым номером 2/3</td></tr>
<tr><td><a id="p110832"></a>3/2</td><td><a id="p110833"></a>Идентификационный номер экспортера</td><td colspan="3"><a id="p110834"></a>То же, что и для элемента данных под порядковым номером 3/2</td></tr>
<tr><td><a id="p110835"></a>3/10</td><td><a id="p110836"></a>Идентификационный номер грузополучателя</td><td colspan="3"><a id="p110837"></a>То же, что и для элемента данных под порядковым номером 3/10</td></tr>
<tr><td><a id="p110838"></a>3/16</td><td><a id="p110839"></a>Идентификационный номер импортера</td><td colspan="3"><a id="p110840"></a>То же, что и для элемента данных под порядковым номером 3/16</td></tr>
<tr><td><a id="p110841"></a>3/18</td><td><a id="p110842"></a>Идентификационный номер декларанта</td><td colspan="3"><a id="p110843"></a>То же, что и для элемента данных под порядковым номером 3/18</td></tr>
<tr><td><a id="p110844"></a>3/39</td><td><a id="p110845"></a>Идентификационный номер владельца разрешения</td><td colspan="3"><a id="p110846"></a>То же, что и для элемента данных под порядковым номером 3/39</td></tr>
<tr><td><a id="p110847"></a>3/40</td><td><a id="p110848"></a>Идентификационный номер дополнительных фискальных ссылок</td><td colspan="3"><a id="p110849"></a>То же, что и для элемента данных под порядковым номером 3/40</td></tr>
<tr><td><a id="p110850"></a>4/3</td><td><a id="p110851"></a>Расчет налогов - вид налога</td><td colspan="3"><a id="p110852"></a>То же, что и для элемента данных под порядковым номером 4/3</td></tr>
<tr><td><a id="p110853"></a>4/4</td><td><a id="p110854"></a>Расчет налогов - налоговая база</td><td colspan="3"><a id="p110855"></a>То же, что и для элемента данных под порядковым номером 4/4</td></tr>
<tr><td><a id="p110856"></a>4/5</td><td><a id="p110857"></a>Расчет налогов - ставка налога</td><td colspan="3"><a id="p110858"></a>То же, что и для элемента данных под порядковым номером 4/5</td></tr>
<tr><td><a id="p110859"></a>4/6</td><td><a id="p110860"></a>Расчет налогов - сумма выплачиваемого налога</td><td colspan="3"><a id="p110861"></a>То же, что и для элемента данных под порядковым номером 4/6</td></tr>
<tr><td><a id="p110862"></a>4/8</td><td><a id="p110863"></a>Расчет налогов - способ оплаты</td><td colspan="3"><a id="p110864"></a>То же, что и для элемента данных под порядковым номером 4/8</td></tr>
<tr><td><a id="p110865"></a>4/16</td><td><a id="p110866"></a>Способ оценки</td><td colspan="3"><a id="p110867"></a>То же, что и для элемента данных под порядковым номером 4/16</td></tr>
<tr><td><a id="p110868"></a>4/17</td><td><a id="p110869"></a>Преференция</td><td colspan="3"><a id="p110870"></a>То же, что и для элемента данных под порядковым номером 4/17</td></tr>
<tr><td><a id="p110871"></a>5/8</td><td><a id="p110872"></a>Код страны места назначения</td><td colspan="3"><a id="p110873"></a>То же, что и для элемента данных под порядковым номером 5/8</td></tr>
<tr><td><a id="p110874"></a>5/14</td><td><a id="p110875"></a>Код страны отправления/экспорта</td><td colspan="3"><a id="p110876"></a>То же, что и для элемента данных под порядковым номером 5/14</td></tr>
<tr><td><a id="p110877"></a>5/15</td><td><a id="p110878"></a>Код страны происхождения</td><td colspan="3"><a id="p110879"></a>То же, что и для элемента данных под порядковым номером 5/15</td></tr>
<tr><td><a id="p110880"></a>5/16</td><td><a id="p110881"></a>Код страны преференциального происхождения</td><td colspan="3"><a id="p110882"></a>То же, что и для элемента данных под порядковым номером 5/16</td></tr>
<tr><td><a id="p110883"></a>6/1</td><td><a id="p110884"></a>Масса нетто (кг)</td><td colspan="3"><a id="p110885"></a>То же, что и для элемента данных под порядковым номером 6/1</td></tr>
<tr><td><a id="p110886"></a>6/2</td><td><a id="p110887"></a>Дополнительные единицы</td><td colspan="3"><a id="p110888"></a>То же, что и для элемента данных под порядковым номером 6/2</td></tr>
<tr><td><a id="p110889"></a>6/5</td><td><a id="p110890"></a>Масса брутто (кг)</td><td colspan="3"><a id="p110891"></a>То же, что и для элемента данных под порядковым номером 6/5</td></tr>
<tr><td><a id="p110892"></a>6/8</td><td><a id="p110893"></a>Описание товаров</td><td colspan="3"><a id="p110894"></a>То же, что и для элемента данных под порядковым номером 6/8</td></tr>
<tr><td><a id="p110895"></a>6/10</td><td><a id="p110896"></a>Количество упаковок</td><td colspan="3"><a id="p110897"></a>То же, что и для элемента данных под порядковым номером 6/10</td></tr>
<tr><td><a id="p110898"></a>6/14</td><td><a id="p110899"></a>Код товара - код Комбинированной номенклатуры</td><td colspan="3"><a id="p110900"></a>То же, что и для элемента данных под порядковым номером 6/14</td></tr>
<tr><td><a id="p110901"></a>6/15</td><td><a id="p110902"></a>Код товара - код TARIC</td><td colspan="3"><a id="p110903"></a>То же, что и для элемента данных под порядковым номером 6/15</td></tr>
<tr><td><a id="p110904"></a>6/16</td><td><a id="p110905"></a>Код товара - дополнительный(ые) код(ы) TARIC</td><td colspan="3"><a id="p110906"></a>То же, что и для элемента данных под порядковым номером 6/16</td></tr>
<tr><td><a id="p110907"></a>6/17</td><td><a id="p110908"></a>Код товара - Национальный(ые) дополнительный(ые) код(ы)</td><td colspan="3"><a id="p110909"></a>То же, что и для элемента данных под порядковым номером 6/17</td></tr>
<tr><td><a id="p110910"></a>7/2</td><td><a id="p110911"></a>Контейнер</td><td colspan="3"><a id="p110912"></a>То же, что и для элемента данных под порядковым номером 7/2</td></tr>
<tr><td><a id="p110913"></a>7/4</td><td><a id="p110914"></a>Вид транспорта на границе</td><td colspan="3"><a id="p110915"></a>То же, что и для элемента данных под порядковым номером 7/4</td></tr>
<tr><td><a id="p110916"></a>7/5</td><td><a id="p110917"></a>Внутренний вид транспорта</td><td colspan="3"><a id="p110918"></a>То же, что и для элемента данных под порядковым номером 7/5</td></tr>
<tr><td><a id="p110919"></a>7/10</td><td><a id="p110920"></a>Идентификационный номер контейнера</td><td colspan="3"><a id="p110921"></a>То же, что и для элемента данных под порядковым номером 7/10</td></tr>
<tr><td><a id="p110922"></a>8/1</td><td><a id="p110923"></a>Порядковый номер квоты</td><td colspan="3"><a id="p110924"></a>То же, что и для элемента данных под порядковым номером 8/1</td></tr>
<tr><td><a id="p110925"></a>8/6</td><td><a id="p110926"></a>Статистическое значение</td><td colspan="3"><a id="p110927"></a>То же, что и для элемента данных под порядковым номером 8/6</td></tr>
<tr><td><a id="p110928"></a>- -</td><td><a id="p110929"></a>Дата принятия декларации</td><td><a id="p110930"></a>В соответствии с форматом элемента данных под порядковым номером 5/4</td><td><a id="p110931"></a>1x</td><td></td></tr>
<tr><td><a id="p110932"></a>- -</td><td><a id="p110933"></a>Номер декларации (уникальный номер)</td><td><a id="p110934"></a>В соответствии с форматом MRN, определенным в элементе данных под порядковым номером 2/1</td><td><a id="p110935"></a>1x</td><td></td></tr>
<tr><td><a id="p110936"></a>- -</td><td><a id="p110937"></a>Выдавшее лицо</td><td><a id="p110938"></a>В соответствии с форматом элемента данных под порядковым номером 5/8</td><td><a id="p110939"></a>1x</td><td></td></tr>
</table>


<a id="p110940"></a>Приложение 21-02

<a id="p110941"></a>**СПИСОК**
ЭЛЕМЕНТОВ ДАННЫХ НАДЗОРА, УКАЗАННЫЙ В [СТАТЬЕ 55(6)](https://bukva.ai/docs/reglament-20152447/statya-55#p100543)
**И СООТВЕТСТВИЕ ГРАФЕ ДЕКЛАРАЦИИ И/ИЛИ ФОРМАТУ**


<table>
<colgroup><col width="16%"><col width="26%"><col width="18%"><col width="13%"><col width="11%"><col width="17%"></colgroup>
<tr><td rowspan="2"><a id="p110942"></a>Порядковый номер D.E.</td><td rowspan="2"><a id="p110943"></a>Название D.E.</td><td rowspan="2"><a id="p110944"></a>Формат (определенный в <a href="#p104348">Приложении B</a>)</td><td colspan="2"><a id="p110945"></a>Количество элементов</td><td rowspan="2"><a id="p110946"></a>Соответствие графе декларации и/или формату</td></tr>
<tr><td><a id="p110947"></a>На уровне заголовка</td><td><a id="p110948"></a>На уровне пункта</td></tr>
<tr><td><a id="p110949"></a>1/10</td><td><a id="p110950"></a>Процедура</td><td colspan="3"><a id="p110951"></a>То же, что и для элемента данных под порядковым номером 1/10</td><td><a id="p110952"></a>37(1) - n2</td></tr>
<tr><td><a id="p110953"></a>3/40</td><td><a id="p110954"></a>Идентификационный номер дополнительных фискальных ссылок</td><td colspan="3"><a id="p110955"></a>То же, что и для элемента данных под порядковым номером 3/40</td><td><a id="p110956"></a>44 - an..40</td></tr>
<tr><td><a id="p110957"></a>4/4</td><td><a id="p110958"></a>Расчет налогов - налоговая база <a href="#p111016">&lt;1&gt;</a></td><td colspan="3"><a id="p110959"></a>То же, что и для элемента данных под порядковым номером 4/4</td><td><a id="p110960"></a>47 - an..6 + n..16,6</td></tr>
<tr><td><a id="p110961"></a>4/17</td><td><a id="p110962"></a>Преференция</td><td colspan="3"><a id="p110963"></a>То же, что и для элемента данных под порядковым номером 4/17</td><td><a id="p110964"></a>36 - n3</td></tr>
<tr><td><a id="p110965"></a>5/8</td><td><a id="p110966"></a>Код страны места назначения</td><td colspan="3"><a id="p110967"></a>То же, что и для элемента данных под порядковым номером 5/8</td><td><a id="p110968"></a>17a - a2</td></tr>
<tr><td><a id="p110969"></a>5/15</td><td><a id="p110970"></a>Код страны происхождения</td><td colspan="3"><a id="p110971"></a>То же, что и для элемента данных под порядковым номером 5/15</td><td><a id="p110972"></a>34a - a2</td></tr>
<tr><td><a id="p110973"></a>6/1</td><td><a id="p110974"></a>Масса нетто (кг)</td><td colspan="3"><a id="p110975"></a>То же, что и для элемента данных под порядковым номером 6/1</td><td><a id="p110976"></a>38 - an..15</td></tr>
<tr><td><a id="p110977"></a>6/2</td><td><a id="p110978"></a>Дополнительные единицы</td><td colspan="3"><a id="p110979"></a>То же, что и для элемента данных под порядковым номером 6/2</td><td><a id="p110980"></a>41 - an..15</td></tr>
<tr><td><a id="p110981"></a>6/14</td><td><a id="p110982"></a>Код товара - код Комбинированной номенклатуры</td><td colspan="3"><a id="p110983"></a>То же, что и для элемента данных под порядковым номером 6/14</td><td><a id="p110984"></a>33 - n8</td></tr>
<tr><td><a id="p110985"></a>6/15</td><td><a id="p110986"></a>Код товара - код TARIC</td><td colspan="3"><a id="p110987"></a>То же, что и для элемента данных под порядковым номером 6/15</td><td><a id="p110988"></a>33 - n2</td></tr>
<tr><td><a id="p110989"></a>6/16</td><td><a id="p110990"></a>Код товара - дополнительный(ые) код(ы) TARIC</td><td colspan="3"><a id="p110991"></a>То же, что и для элемента данных под порядковым номером 6/16</td><td><a id="p110992"></a>33 - an8</td></tr>
<tr><td><a id="p110993"></a>8/1</td><td><a id="p110994"></a>Порядковый номер квоты</td><td colspan="3"><a id="p110995"></a>То же, что и для элемента данных под порядковым номером 8/1</td><td><a id="p110996"></a>39 - n6</td></tr>
<tr><td><a id="p110997"></a>8/6</td><td><a id="p110998"></a>Статистическое значение</td><td colspan="3"><a id="p110999"></a>То же, что и для элемента данных под порядковым номером 8/6</td><td><a id="p111000"></a>46 - an..18</td></tr>
<tr><td><a id="p111001"></a>- -</td><td><a id="p111002"></a>Дата принятия декларации</td><td><a id="p111003"></a>В соответствии с форматом элемента данных под порядковым номером 5/4</td><td><a id="p111004"></a>1x</td><td></td><td><a id="p111005"></a>дата</td></tr>
<tr><td><a id="p111006"></a>- -</td><td><a id="p111007"></a>Номер декларации (уникальный номер)</td><td><a id="p111008"></a>В соответствии с форматом MRN, определенным в элементе данных под порядковым номером 2/1</td><td><a id="p111009"></a>1x</td><td></td><td><a id="p111010"></a>an..40</td></tr>
<tr><td><a id="p111011"></a>- -</td><td><a id="p111012"></a>Выдавшее лицо</td><td><a id="p111013"></a>В соответствии с форматом элемента данных под порядковым номером 5/8</td><td><a id="p111014"></a>1x</td><td></td><td><a id="p111015"></a>Выдающее государство-член ЕС - a2</td></tr>
<tr><td colspan="6"><a id="p111016"></a>&lt;1&gt; Когда код Союза, внесенный для (Расчет налогов - Вид налога) - B00.</td></tr>
</table>


<a id="p111017"></a>Приложение 21-03

<a id="p111018"></a>СПИСОК ЭЛЕМЕНТОВ ДАННЫХ НАДЗОРА, УКАЗАННЫЙ В [СТАТЬЕ 55(1)](https://bukva.ai/docs/reglament-20152447/statya-55#p100533)


<table>
<colgroup><col width="24%"><col width="29%"><col width="31%"><col width="16%"></colgroup>
<tr><td><a id="p111019"></a>D.E. N <a href="#p111172">&lt;1&gt;</a></td><td><a id="p111020"></a>Название элемента/класса данных <a href="#p111173">&lt;2&gt;</a></td><td><a id="p111021"></a>Название подэлемента/подкласса данных</td><td><a id="p111022"></a>Название подэлемента данных</td></tr>
<tr><td><a id="p111023"></a>11 01 000 000</td><td><a id="p111024"></a>Вид декларации</td><td></td><td></td></tr>
<tr><td><a id="p111025"></a>11 02 000 000</td><td><a id="p111026"></a>Вид дополнительной декларации</td><td></td><td></td></tr>
<tr><td><a id="p111027"></a>11 03 000 000</td><td><a id="p111028"></a>Номер пункта товаров</td><td></td><td></td></tr>
<tr><td><a id="p111029"></a>11 09 001 000</td><td><a id="p111030"></a>Процедура</td><td><a id="p111031"></a>Запрошенная процедура</td><td></td></tr>
<tr><td><a id="p111032"></a>11 09 002 000</td><td><a id="p111033"></a>Процедура</td><td><a id="p111034"></a>Предыдущая процедура</td><td></td></tr>
<tr><td><a id="p111035"></a>11 10 000 000</td><td><a id="p111036"></a>Дополнительная процедура</td><td></td><td></td></tr>
<tr><td><a id="p111037"></a>12 03 001 000</td><td><a id="p111038"></a>Подтверждающий документ</td><td><a id="p111039"></a>Исходящий номер</td><td></td></tr>
<tr><td><a id="p111040"></a>12 03 002 000</td><td><a id="p111041"></a>Подтверждающий документ</td><td><a id="p111042"></a>Вид</td><td></td></tr>
<tr><td><a id="p111043"></a>12 03 010 000</td><td><a id="p111044"></a>Подтверждающий документ</td><td><a id="p111045"></a>Название выдающего органа</td><td></td></tr>
<tr><td><a id="p111046"></a>12 04 001 000</td><td><a id="p111047"></a>Дополнительная ссылка</td><td><a id="p111048"></a>Исходящий номер</td><td></td></tr>
<tr><td><a id="p111049"></a>12 04 002 000</td><td><a id="p111050"></a>Дополнительная ссылка</td><td><a id="p111051"></a>Вид</td><td></td></tr>
<tr><td><a id="p111052"></a>12 05 001 000</td><td><a id="p111053"></a>Транспортный документ</td><td><a id="p111054"></a>Исходящий номер</td><td></td></tr>
<tr><td><a id="p111055"></a>12 05 002 000</td><td><a id="p111056"></a>Транспортный документ</td><td><a id="p111057"></a>Вид</td><td></td></tr>
<tr><td><a id="p111058"></a>12 12 001 000</td><td><a id="p111059"></a>Разрешение</td><td><a id="p111060"></a>Исходящий номер</td><td></td></tr>
<tr><td><a id="p111061"></a>12 12 002 000</td><td><a id="p111062"></a>Разрешение</td><td><a id="p111063"></a>Вид</td><td></td></tr>
<tr><td><a id="p111064"></a>12 12 080 000</td><td><a id="p111065"></a>Разрешение</td><td><a id="p111066"></a>Владелец разрешения</td><td></td></tr>
<tr><td><a id="p111067"></a>13 01 017 000</td><td><a id="p111068"></a>Экспортера</td><td><a id="p111069"></a>Идентификационный номер</td><td></td></tr>
<tr><td><a id="p111070"></a>13 01 018 020</td><td><a id="p111071"></a>Экспортер</td><td></td><td><a id="p111072"></a>Страна</td></tr>
<tr><td><a id="p111073"></a>13 03 017 000</td><td><a id="p111074"></a>Грузополучатель</td><td><a id="p111075"></a>Идентификационный номер</td><td></td></tr>
<tr><td><a id="p111076"></a>13 04 017 000</td><td><a id="p111077"></a>Импортер</td><td><a id="p111078"></a>Идентификационный номер</td><td></td></tr>
<tr><td><a id="p111079"></a>13 04 018 020</td><td><a id="p111080"></a>Импортер</td><td></td><td><a id="p111081"></a>Страна</td></tr>
<tr><td><a id="p111082"></a>13 05 017 000</td><td><a id="p111083"></a>Декларант</td><td><a id="p111084"></a>Идентификационный номер</td><td></td></tr>
<tr><td><a id="p111085"></a>13 16 031 000</td><td><a id="p111086"></a>Дополнительные фискальные ссылки</td><td><a id="p111087"></a>Роль</td><td></td></tr>
<tr><td><a id="p111088"></a>13 16 034 000</td><td><a id="p111089"></a>Дополнительные фискальные ссылки</td><td><a id="p111090"></a>Идентификационный номер плательщика НДС</td><td></td></tr>
<tr><td><a id="p111091"></a>14 03 039 000</td><td><a id="p111092"></a>Пошлины и налоги</td><td><a id="p111093"></a>Вид налога</td><td></td></tr>
<tr><td><a id="p111094"></a>14 03 038 000</td><td><a id="p111095"></a>Пошлины и налоги</td><td><a id="p111096"></a>Способ оплаты</td><td></td></tr>
<tr><td><a id="p111097"></a>14 03 042 000</td><td><a id="p111098"></a>Пошлины и налоги</td><td><a id="p111099"></a>Сумма оплачиваемого налога</td><td></td></tr>
<tr><td><a id="p111100"></a>14 03 040 000</td><td><a id="p111101"></a>Пошлины и налоги</td><td><a id="p111102"></a>Налоговая база</td><td></td></tr>
<tr><td><a id="p111103"></a>14 03 040 041</td><td><a id="p111104"></a>Пошлины и налоги</td><td><a id="p111105"></a>Налоговая ставка</td><td></td></tr>
<tr><td><a id="p111106"></a>14 03 040 005</td><td><a id="p111107"></a>Пошлины и налоги</td><td><a id="p111108"></a>Единица измерения и определитель</td><td></td></tr>
<tr><td><a id="p111109"></a>14 03 040 006</td><td><a id="p111110"></a>Пошлины и налоги</td><td><a id="p111111"></a>Количество</td><td></td></tr>
<tr><td><a id="p111112"></a>14 03 040 014</td><td><a id="p111113"></a>Пошлины и налоги</td><td><a id="p111114"></a>Сумма</td><td></td></tr>
<tr><td><a id="p111115"></a>14 10 000 000</td><td><a id="p111116"></a>Способ оценки</td><td></td><td></td></tr>
<tr><td><a id="p111117"></a>14 11 000 000</td><td><a id="p111118"></a>Преференции</td><td></td><td></td></tr>
<tr><td><a id="p111119"></a>16 03 000 000</td><td><a id="p111120"></a>Страна места назначения</td><td></td><td></td></tr>
<tr><td><a id="p111121"></a>16 06 000 000</td><td><a id="p111122"></a>Страна места отправки</td><td></td><td></td></tr>
<tr><td><a id="p111123"></a>16 08 000 000</td><td><a id="p111124"></a>Страна происхождения</td><td></td><td></td></tr>
<tr><td><a id="p111125"></a>16 09 000 000</td><td><a id="p111126"></a>Страна преференциального происхождения</td><td></td><td></td></tr>
<tr><td><a id="p111127"></a>18 01 000 000</td><td><a id="p111128"></a>Масса нетто</td><td></td><td></td></tr>
<tr><td><a id="p111129"></a>18 02 000 000</td><td><a id="p111130"></a>Дополнительные единицы</td><td></td><td></td></tr>
<tr><td><a id="p111131"></a>18 04 000 000</td><td><a id="p111132"></a>Масса брутто</td><td></td><td></td></tr>
<tr><td><a id="p111133"></a>18 05 000 000</td><td><a id="p111134"></a>Описание товаров</td><td></td><td></td></tr>
<tr><td><a id="p111135"></a>18 06 004 000</td><td><a id="p111136"></a>Упаковка</td><td><a id="p111137"></a>Количество упаковок</td><td></td></tr>
<tr><td><a id="p111138"></a>18 09 056 000</td><td><a id="p111139"></a>Код товара</td><td><a id="p111140"></a>Код подзаголовка гармонизированной системы</td><td></td></tr>
<tr><td><a id="p111141"></a>18 09 057 000</td><td><a id="p111142"></a>Код товара</td><td><a id="p111143"></a>Код Объединенной номенклатуры</td><td></td></tr>
<tr><td><a id="p111144"></a>18 09 058 000</td><td><a id="p111145"></a>Код товара</td><td><a id="p111146"></a>Код TARIC</td><td></td></tr>
<tr><td><a id="p111147"></a>18 09 059 000</td><td><a id="p111148"></a>Код товара</td><td><a id="p111149"></a>Дополнительной код TARIC</td><td></td></tr>
<tr><td><a id="p111150"></a>18 09 060 000</td><td><a id="p111151"></a>Код товара</td><td><a id="p111152"></a>Национальный дополнительный код</td><td></td></tr>
<tr><td><a id="p111153"></a>9 01 000 000</td><td><a id="p111154"></a>Индикатор контейнера</td><td></td><td></td></tr>
<tr><td><a id="p111155"></a>19 03 000 000</td><td><a id="p111156"></a>Вид транспортного средства на границе</td><td></td><td></td></tr>
<tr><td><a id="p111157"></a>19 04 000 000 Inland mode of transport</td><td><a id="p111158"></a>Вид внутреннего транспорта</td><td></td><td></td></tr>
<tr><td><a id="p111159"></a>19 07 063 000</td><td><a id="p111160"></a>Транспортное оборудование</td><td><a id="p111161"></a>Идентификационный номер контейнера</td><td></td></tr>
<tr><td><a id="p111162"></a>99 01 000 000</td><td><a id="p111163"></a>Порядковый номер квоты</td><td></td><td></td></tr>
<tr><td><a id="p111164"></a>99 06 000 000</td><td><a id="p111165"></a>Статистическое значение</td><td></td><td></td></tr>
<tr><td><a id="p111166"></a>- -</td><td><a id="p111167"></a>Дата принятия декларации <a href="#p111174">&lt;3&gt;</a></td><td></td><td></td></tr>
<tr><td><a id="p111168"></a>--</td><td><a id="p111169"></a>Номер декларации (уникальная ссылка) <a href="#p111175">&lt;4&gt;</a></td><td></td><td></td></tr>
<tr><td><a id="p111170"></a>- -</td><td><a id="p111171"></a>Выдавшее лицо <a href="#p111176">&lt;5&gt;</a></td><td></td><td></td></tr>
<tr><td colspan="4"><a id="p111172"></a><a id="p111173"></a><a id="p111174"></a><a id="p111175"></a><a id="p111176"></a>&lt;1&gt; Форматы и количества элементов требований к данным из колонки "D.E. N" такие же, что указаны в <a href="#p104348">Приложении B</a>.<br>&lt;2&gt; Для класса данных, напечатанных курсивом, только указанные атрибуты подлежат надзору.<br>&lt;3&gt; Формат данной информации должен быть "ггггммдд". Количество элементов данной информации должно быть "1x" на уровне декларации.<br>&lt;4&gt; Формат данной информации должен быть предусмотрен в соответствии с форматом MRN, определенным в номере подэлемента данных <a href="#p108269">12 01 001 000</a>. Количество элементов данной информации должно быть "1x" на уровне декларации.<br>&lt;5&gt; Формат данной информации должен быть предусмотрен в соответствии с форматом номера элемента данных 16 03 000 000. Необходимо использовать код GEONOM, указанный во <a href="#p104388">вводной части 13, номер 3</a>, Приложения B. Количество элементов данной информации должно быть "1x" на уровне декларации.</td></tr>
</table>


<a id="p111177"></a>Приложение 22-02

<a id="p111178"></a>**ИНФОРМАЦИОННЫЙ СЕРТИФИКАТ INF4 И ЗАЯВЛЕНИЕ**
**НА ИНФОРМАЦИОННЫЙ СЕРТИФИКАТ INF4**

<a id="p111179"></a>Инструкции для печати:
1. <a id="p111180"></a>Форма, на которой выдается информационный [сертификат INF4](https://bukva.ai/docs/reglament-20152447/statya-350#p111187), распечатывается на белой бумаге, без древесной массы, предназначенной для письма и весом 40 - 65 г на квадратный метр.
2. <a id="p111181"></a>[Форма](https://bukva.ai/docs/reglament-20152447/statya-350#p111187) имеет размер 210 x 297 мм.
3. <a id="p111182"></a>Печать форм является обязанностью государств-членов ЕС; формы должны иметь серийный номер, по которому их можно идентифицировать. Форма печатается на одном из официальных языков Европейского Союза.
4. <a id="p111183"></a>Старые версии форм могут также использоваться до того, как закончатся их существующие запасы или до 1 мая 2019 г., в зависимости от того, что наступит раньше.

<a id="p111184"></a>**ЕВРОПЕЙСКИЙ СОЮЗ**
1. <a id="p111185"></a>Поставщик (имя/название, полный адрес, страна)
<a id="p111186"></a>**INF 4**
N 000.000
<a id="p111187"></a>**ИНФОРМАЦИОННЫЙ СЕРТИФИКАТ**
Для содействия установлению преференциального происхождения товаров в Союзе
2. <a id="p111188"></a>Грузополучатель (имя/название, полный адрес, страна)
3. <a id="p111189"></a>Инвойс(ы) [<1>](https://bukva.ai/docs/reglament-20152447/statya-350#p111197) [<2>](https://bukva.ai/docs/reglament-20152447/statya-350#p111198)
<a id="p111190"></a>См. [примечания](https://bukva.ai/docs/reglament-20152447/statya-350#p111201) на обратной стороне перед заполнением формы
4. <a id="p111191"></a>Замечания
5. <a id="p111192"></a>Номер - Маркировки и номера - Номер и вид упаковок - Описание товаров [<3>](https://bukva.ai/docs/reglament-20152447/statya-350#p111199)
6. <a id="p111193"></a>Масса брутто (кг) или другие единицы измерения (л, м3 и т.п.)
<a id="p111194"></a>**7. ЗАПОЛНЯЕТСЯ ТАМОЖНЕЙ**
Декларация удостоверена правильно
Неправильно
Выдающая страна: .............................
Место ................., дата ...................
(Подпись) (Печать)
<a id="p111195"></a>**8. ДЕКЛАРАЦИЯ ПОСТАВЩИКА**
Я, нижеподписавшийся, заявляю, что декларация(и) о статусе происхождения товаров, описанных в [графе (5)](https://bukva.ai/docs/reglament-20152447/statya-350#p111192) и [<4>](https://bukva.ai/docs/reglament-20152447/statya-350#p111200)

| в [графе 3](https://bukva.ai/docs/reglament-20152447/statya-350#p111189) и прилагаемом(ых) |
| --- |


| от .................... (дата) |
| --- |


Место ....................., дата ................
(Подпись)


<a id="p111196"></a>

---

<a id="p111197"></a><1> Термин "инвойс" также включает в себя товарные накладные или другие коммерческие документы, относящиеся к партии или партиям, внесенным в декларацию(и).
<a id="p111198"></a><2> Данную [графу](https://bukva.ai/docs/reglament-20152447/statya-350#p111189) не нужно заполнять в случае долгосрочных деклараций.
<a id="p111199"></a><3> Описать товары, внесенные в [графу 5](https://bukva.ai/docs/reglament-20152447/statya-350#p111192), в соответствии с коммерческой практикой и достаточно подробно для их идентификации.
<a id="p111200"></a><4> Поставить крестик в соответствующую графу.

<a id="p111201"></a>Примечания

1. <a id="p111202"></a>Сертификаты не должны содержать стираний или исправлений. Все изменения должны быть сделаны посредством зачеркивания неправильных сведений и добавлением всех необходимых исправлений. Все изменения должны быть завизированы лицом, которое заполнило сертификат, и подписаны таможенными органами выдающей страны или территории.
2. <a id="p111203"></a>Между пунктами, внесенными в сертификат, не должно оставаться места, и перед каждым пунктом должен быть номер пункта. Горизонтальная линия должна быть проведена сразу же после последнего пункта. Все неиспользованное место должно быть перечеркнуто таким образом, чтобы было невозможно впоследствии внести туда запись.
3. <a id="p111204"></a>Товары должны быть описаны в соответствии с коммерческой практикой и достаточно подробно, чтобы их можно было идентифицировать.
4. <a id="p111205"></a>Форма заполняется на одном из официальных языков Союза. Таможенные органы государства-члена ЕС, которые должны представить информацию или которые требуют ее, могут попросить перевод информации, установленной в документах, представленных им на официальном языке или официальных языках указанного государства-члена ЕС.

<a id="p111206"></a>**ЕВРОПЕЙСКИЙ СОЮЗ**
1. <a id="p111207"></a>Поставщик (имя/название, полный адрес, страна)
<a id="p111208"></a>**INF 4**
N 000.000
<a id="p111209"></a>**ЗАЯВЛЕНИЕ НА ИНФОРМАЦИОННЫЙ СЕРТИФИКАТ**
Для содействия установлению преференциального происхождения товаров в Союзе
2. <a id="p111210"></a>Грузополучатель (имя/название, полный адрес, страна)
3. <a id="p111211"></a>Инвойс(ы) [<1>](https://bukva.ai/docs/reglament-20152447/statya-350#p111218) [<2>](https://bukva.ai/docs/reglament-20152447/statya-350#p111219)
<a id="p111212"></a>См. [примечания](https://bukva.ai/docs/reglament-20152447/statya-350#p111201) на обратной стороне перед заполнением формы
4. <a id="p111213"></a>Замечания
5. <a id="p111214"></a>Номер - Маркировки и номера - Номер и вид упаковок - Описание товаров [<3>](https://bukva.ai/docs/reglament-20152447/statya-350#p111220)
6. <a id="p111215"></a>Масса брутто (кг) или другие единицы измерения (л, м3 и т.п.)

<a id="p111216"></a>**8. ДЕКЛАРАЦИЯ ПОСТАВЩИКА**
Я, нижеподписавшийся, заявляю, что декларация(и) о статусе происхождения товаров, описанных в [графе (5)](https://bukva.ai/docs/reglament-20152447/statya-350#p111214) и [<4>](https://bukva.ai/docs/reglament-20152447/statya-350#p111221)

| в [графе 3](https://bukva.ai/docs/reglament-20152447/statya-350#p111211) и прилагаемом(ых) |
| --- |


| от .................... (дата) |
| --- |


Место ....................., дата ................
(Подпись)


<a id="p111217"></a>

---

<a id="p111218"></a><1> Термин "инвойс" также включает в себя товарные накладные или другие коммерческие документы, относящиеся к партии или партиям, внесенным в декларацию(и).
<a id="p111219"></a><2> Данную [графу](https://bukva.ai/docs/reglament-20152447/statya-350#p111211) не нужно заполнять в случае долгосрочных деклараций.
<a id="p111220"></a><3> Описать товары, внесенные в [графу 5](https://bukva.ai/docs/reglament-20152447/statya-350#p111214), в соответствии с коммерческой практикой и достаточно подробно для их идентификации.
<a id="p111221"></a><4> Поставить крестик в соответствующую графу.


<a id="p111222"></a>**ДЕКЛАРАЦИЯ ПОСТАВЩИКА**

<a id="p111223"></a>Я, нижеподписавшийся, поставщик товаров, описанных с обратной стороны,
<a id="p111224"></a>ЗАЯВЛЯЮ, что товары соответствуют условиям, необходимым для выдачи прилагаемого сертификата;
<a id="p111225"></a>ОПРЕДЕЛЯЮ следующие обстоятельства, которые дают право для того, чтобы эти товары соответствовали вышеуказанным условиям:
<a id="p111226"></a>ПРЕДСТАВЛЯЮ следующие подтверждающие документы [<1>](https://bukva.ai/docs/reglament-20152447/statya-350#p111232):
<a id="p111227"></a>ПРИНИМАЮ ОБЯЗАТЕЛЬСТВО представить по запросу соответствующих органов все подтверждающие доказательства, которые эти органы могут потребовать в целях выдачи прилагаемого сертификата, а также принимаю обязательство, если потребуется, согласиться на все проверки моих бухгалтерских записей или проверки процесса производства вышеназванных товаров, выполняемые вышеназванными органами;
<a id="p111228"></a>ПРОШУ выдать прилагающийся сертификат на эти товары.

<a id="p111229"></a>(Место и дата)

<a id="p111230"></a>(Подпись)

<a id="p111231"></a>

---

<a id="p111232"></a><1> Например, документы на импорт, сертификаты перемещения, инвойсы, декларации производителей и т.п., касающиеся переработанной продукции или товаров, реэкспортированных в неизмененном состоянии.


<a id="p111233"></a>Приложение 22-06

<a id="p111234"></a>**ЗАЯВЛЕНИЕ НА СТАТУС ЗАРЕГИСТРИРОВАННОГО ЭКСПОРТЕРА**
в целях схем генеральных тарифных преференций Европейского
Союза, Норвегии, Швейцарии и Турции [<1>](https://bukva.ai/docs/reglament-20152447/statya-350#p111247)


| <a id="p111235"></a>1. Имя/название экспортера, полный адрес и страна, сведения для контакта, TIN |
| --- |
| <a id="p111236"></a>2. Дополнительные сведения для контакта, в том числе номер телефона и факса, а также электронный адрес, если имеется (необязательно). |
| <a id="p111237"></a>3. Определить, является ли основная деятельность производством или торговлей. |
| <a id="p111238"></a>4. Показательное описание товаров, которые претендуют на преференциальный режим, в том числе показательный список заголовков Гармонизированной системы (или глав, под которые подпадают продаваемые товары в рамках более двадцати заголовков Гармонизированной системы). |
| <a id="p111239"></a>5. Обязательства, которые принимает экспортер |
| <a id="p111240"></a>Нижеподписавшийся настоящим:<br>- заявляет, что вышеуказанные сведения являются правильными;<br>- удостоверяет, что предыдущие регистрации не были отозваны; напротив, удостоверяет, что ситуация, которая привела к такому отзыву, была исправлена;<br>- обязуется делать заявления о происхождении только для товаров, которые претендуют на преференциальный режим и соответствуют правилам происхождения, определенным для этих товаров в Общей системе преференций;<br>- обязуется вести соответствующие коммерческие бухгалтерские отчеты по производству/поставке товаров, претендующих на преференциальный режим, и хранить их не менее трех лет после окончания календарного года, в котором было составлено заявление о происхождении;<br>- обязуется незамедлительно уведомлять компетентный орган о возникающих изменениях его регистрационных данных после приобретения номера зарегистрированного экспортера;<br>- обязуется сотрудничать с компетентным органом;<br>- обязуется принять все проверки точности его заявлений о происхождении, в том числе проверки бухгалтерских отчетов, и визиты на его предприятия органов Европейской Комиссии или государств-членов ЕС, а также органов Норвегии, Швейцарии и Турции;<br>- обязуется просить об отзыве его регистрации в системе, если он больше не соответствует условиям, необходимым для экспорта каких-либо товаров по схеме;<br>- обязуется попросить об отзыве его регистрации в системе, если он больше не намерен экспортировать такие товары по схеме.<br>--------------------------------<br>Место, дата, подпись уполномоченного лица, имя и должность [<2>](https://bukva.ai/docs/reglament-20152447/statya-350#p111248) |
| <a id="p111241"></a>6. Предварительное определенное и информированное согласие экспортера на публикацию его данных на публичных веб-сайтах |
| <a id="p111242"></a>Нижеподписавшийся настоящим проинформирован, что информация, представленная в настоящей декларации, может быть раскрыта публично через публичный веб-сайт. Нижеподписавшийся принимает публикацию данной информации через публичный веб-сайт. Нижеподписавшийся может отозвать свое согласие на публикацию данной информации через публичный веб-сайт посредством направления запроса в компетентные органы, отвечающие за регистрацию.<br>--------------------------------<br>Место, дата, подпись уполномоченного лица, имя и должность [<2>](https://bukva.ai/docs/reglament-20152447/statya-350#p111248) |
| <a id="p111243"></a>7. Графа для официального использования компетентным органом<br>Заявитель зарегистрирован под следующим номером:<br>Регистрационный номер: _____________________________<br>Дата регистрации ___________________________________<br>Дата, с которой действует регистрация ________________<br>Подпись и печать [<2>](https://bukva.ai/docs/reglament-20152447/statya-350#p111248) _________________________________ |


| <a id="p111244"></a>Информационное уведомление,<br>касающееся защиты и обработки персональных данных, включенных в систему |
| --- |
| <a id="p111245"></a>1. Если Европейская Комиссия обрабатывает персональные данные, содержащиеся в настоящем заявлении о том, чтобы стать зарегистрированным экспортером, применяется [Регламент](https://bukva.ai/docs/reglament-452001/statya-1) (ЕС) 45/2001 Европейского Парламента и Совета ЕС о защите физических лиц при обработке персональных данных, осуществляемой учреждениями и органами Союза, и о свободном обращении таких данных. Если компетентные органы страны-бенефициара или третьей страны, имплементирующие [Директиву](https://bukva.ai/docs/direktiva-9546es/statya-1) 95/46/ЕС Европейского Парламента и Совета ЕС о защите физических лиц при обработке персональных данных и о свободном обращении таких данных, обрабатывают персональные данные, содержащиеся в настоящем заявлении о том, чтобы стать зарегистрированным экспортером, то применяются соответствующие национальные положения вышеназванной [Директивы](https://bukva.ai/docs/direktiva-9546es/statya-1).<br>2. Персональные данные в отношении заявления о том, чтобы стать зарегистрированным экспортером, обрабатываются в целях Союза, правил Генеральной схемы преференций ЕС о происхождении, определенных в соответствующем законодательстве ЕС. Вышеназванное законодательство, предоставляя правила Генеральной схемы преференций ЕС о происхождении, составляет правовую основу для обработки персональных данных в отношении заявления о том, чтобы стать зарегистрированным экспортером.<br>3. Компетентный орган в стране, в которой было подано заявление, является контролирующим органом в отношении обработки данных в системе REX.<br>Список компетентных органов публикуется на веб-сайте Европейской Комиссии.<br>4. Доступ ко всем данным настоящего заявления через ID/пароль пользователя предоставляется пользователям в Европейской Комиссии, компетентных органах стран-бенефициаров и таможенных органах в государствах-членах ЕС, Норвегии, Швейцарии и Турции.<br>5. Данные отозванной регистрации хранятся компетентными органами страны-бенефициара в системе REX десять календарных лет. Этот срок начинается после завершения года, в котором отзыв регистрации имел место.<br>6. Субъект данных имеет право доступа к данным, относящимся к нему, которые будут обрабатываться через систему REX и при необходимости право исправлять, удалять или блокировать данные в соответствии с [Регламентом](https://bukva.ai/docs/reglament-452001/statya-1) (ЕС) 45/2001 или национальным законодательством, имплементирующим [Директиву](https://bukva.ai/docs/direktiva-9546es/statya-1) 95/46/ЕС. Любой запрос о праве доступа, исправления, удаления или блокирования подается соответственно компетентным органам стран-бенефициаров, ответственным за регистрации, и обрабатывается ими. Если зарегистрированный экспортер подал запрос об осуществлении этого права Европейской Комиссии, Европейская Комиссия направляет такие запросы заинтересованным компетентным органам страны-бенефициара. Если зарегистрированный экспортер не может получить свое право от органа, контролирующего данные, то зарегистрированный экспортер подает такой запрос Европейской Комиссии, действующей в качестве контролирующего органа. Европейская Комиссия имеет право исправлять, удалять или блокировать данные.<br>7. Жалобы могут направляться соответствующему национальному органу по защите данных. Сведения для контакта национальных органов по защите данных имеются на веб-сайте Европейской Комиссии, Генерального директората по вопросам юстиции: (http://ec.europa.eu/justice/data-protection/bodies/authorities/eu/index_en.htm#h2-1).<br>Если жалоба касается обработки данных Европейской Комиссией, она направляется Европейскому инспектору по защите данных (EDPS)/htpp://www.edps.europa.eu/EDPSWEB/). |


<a id="p111246"></a>

---

<a id="p111247"></a><1> Настоящая форма заявления является общей для Генеральной схемы преференций четырех субъектов: Союз (ЕС), Норвегия, Швейцария и Турция ("субъекты"). Следует обратить внимание, что соответствующие Генеральные схемы преференций этих субъектов могут отличаться в части страны и продукции. Следовательно, данная регистрация будет действительна только в целях экспорта согласно Генеральной(ым) схеме(ам) преференций, которая(ые) считает(ют) вашу страну страной-бенефициаром.
<a id="p111248"></a><2> Если заявление о том, чтобы стать зарегистрированным экспортером, или другой обмен информацией между зарегистрированными экспортерами и компетентными органами в странах-бенефициарах или таможенными органами в государствах-членах ЕС, были сделаны с использованием электронных технологий обработки данных, то подпись и печать, указанные в [графах 5](https://bukva.ai/docs/reglament-20152447/statya-350#p111239), [6](https://bukva.ai/docs/reglament-20152447/statya-350#p111241) и [7](https://bukva.ai/docs/reglament-20152447/statya-350#p111243), заменяются электронной аутентификацией.


<a id="p111249"></a>Приложение 22-06A

<a id="p111250"></a>**ЗАЯВЛЕНИЕ НА СТАТУС ЗАРЕГИСТРИРОВАННОГО ЭКСПОРТЕРА**
в целях регистрации экспортеров Государств-членов ЕС


| <a id="p111251"></a>1. Имя/название экспортера, полный адрес и страна, сведения для контакта, EORI или TIN |
| --- |
| <a id="p111252"></a>2. Дополнительные сведения для контакта, в том числе номер телефона и факса, а также электронный адрес, если имеется (необязательно). |
| <a id="p111253"></a>3. Определить, является ли основная деятельность производством или торговлей. |
| <a id="p111254"></a>4. Показательное описание товаров, которые претендуют на преференциальный режим, в том числе показательный список заголовков Гармонизированной системы (или глав, под которые подпадают продаваемые товары в рамках более двадцати заголовков Гармонизированной системы). |
| <a id="p111255"></a>5. Обязательства, которые принимает экспортер |
| <a id="p111256"></a>Нижеподписавшийся настоящим:<br>- заявляет, что вышеуказанные сведения являются правильными;<br>- удостоверяет, что предыдущие регистрации не были отозваны; напротив, удостоверяет, что ситуация, которая привела к такому отзыву, была исправлена;<br>- обязуется делать заявления о происхождении и другие документы о происхождении только для товаров, которые претендуют на преференциальный режим и соответствуют правилам происхождения, определенным для этих товаров в соглашениях о преференциях;<br>- обязуется вести соответствующие коммерческие бухгалтерские отчеты по производству/поставке товаров, претендующих на преференциальный режим, и хранить их столько, сколько требуется согласно преференциальному соглашению, но не менее трех лет после окончания календарного года, в котором было составлено заявление о происхождении или другой документ о происхождении;<br>- обязуется незамедлительно уведомлять таможенные органы о возникающих изменениях его регистрационных данных после приобретения номера зарегистрированного экспортера;<br>- обязуется сотрудничать с таможенными органами;<br>- обязуется принять все проверки точности его заявлений о происхождении или других документов о происхождении, в том числе проверки бухгалтерских отчетов, и визиты на его предприятия органов Европейской Комиссии или государств-членов ЕС;<br>- обязуется просить об отзыве его регистрации в системе, если он больше не соответствует условиям, необходимым для применения системы зарегистрированных экспортеров;<br>- обязуется попросить об отзыве его регистрации в системе, если он больше не намерен использовать систему зарегистрированных экспортеров.<br>--------------------------------<br>Место, дата, подпись уполномоченного лица, имя и должность [<1>](https://bukva.ai/docs/reglament-20152447/statya-350#p111263) |
| <a id="p111257"></a>6. Предварительное определенное и информированное согласие экспортера на публикацию его данных на публичных веб-сайтах |
| <a id="p111258"></a>Нижеподписавшийся настоящим проинформирован, что информация, представленная в настоящей декларации, может быть раскрыта для всеобщего ознакомления через публичный веб-сайт. Нижеподписавшийся принимает публикацию данной информации через публичный веб-сайт. Нижеподписавшийся может отозвать свое согласие на публикацию данной информации через публичный веб-сайт посредством направления запроса в компетентные органы, отвечающие за регистрацию.<br>--------------------------------<br>Место, дата, подпись уполномоченного лица, имя и должность [<1>](https://bukva.ai/docs/reglament-20152447/statya-350#p111263) |
| <a id="p111259"></a>7. Графа для официального использования таможенными органами<br>Заявитель зарегистрирован под следующим номером:<br>Регистрационный номер: _____________________________<br>Дата регистрации ___________________________________<br>Дата, с которой действует регистрация ________________<br>Подпись и печать [<1>](https://bukva.ai/docs/reglament-20152447/statya-350#p111263) _________________________________ |


| <a id="p111260"></a>Информационное уведомление,<br>касающееся защиты и обработки персональных данных, включенных в систему |
| --- |
| <a id="p111261"></a>1. Если Европейская Комиссия обрабатывает персональные данные, содержащиеся в настоящем заявлении, о том, чтобы стать зарегистрированным экспортером, применяется [Регламент](https://bukva.ai/docs/reglament-452001/statya-1) (ЕС) 45/2001 Европейского Парламента и Совета ЕС о защите физических лиц при обработке персональных данных, осуществляемой учреждениями и органами Союза, и о свободном обращении таких данных.<br>2. Персональные данные в отношении заявления о том, чтобы стать зарегистрированным экспортером, обрабатываются в целях правил о происхождении соответствующих соглашений о преференциальной торговле Союза. Правила происхождения, указанные в Имплементационном Регламенте (ЕС) 2015/2447 Европейской Комиссии, составляют правовую основу для обработки персональных данных в отношении заявления о том, чтобы стать зарегистрированным экспортером.<br>3. Компетентный орган в стране, в которой было подано заявление, является контролирующим органом в отношении обработки данных в системе REX.<br>Список таможенных департаментов публикуется на веб-сайте Европейской Комиссии.<br>4. Доступ ко всем данным настоящего заявления через ID/пароль пользователя предоставляется пользователям в Европейской Комиссии и таможенных органах в государствах-членах ЕС, Норвегии, Швейцарии и Турции.<br>5. Данные отозванной регистрации хранятся таможенными органами государств-членов ЕС в системе REX десять календарных лет. Этот срок начинается после завершения года, в котором отзыв регистрации имел место.<br>6. Субъект данных имеет право доступа к данным, относящимся к нему, которые будут обрабатываться через систему REX и при необходимости право исправлять, удалять или блокировать данные в соответствии с [Регламентом](https://bukva.ai/docs/reglament-452001/statya-1) (ЕС) 45/2001 или национальным законодательством, имплементирующим [Директиву](https://bukva.ai/docs/direktiva-9546es/statya-1) 95/46/ЕС Европейского Парламента и Совета ЕС о защите физических лиц при обработке персональных данных и о свободном обращении таких данных. Любой запрос о праве доступа, исправления, удаления или блокирования подается соответственно таможенным органам государств-членов ЕС, ответственным за регистрации, и обрабатывается ими. Если зарегистрированный экспортер подал запрос об осуществлении этого права Европейской Комиссии, Европейская Комиссия направляет такие запросы таможенным органам государств-членов ЕС соответственно. Если зарегистрированный экспортер не может получить свое право от органа, контролирующего данные, то зарегистрированный экспортер подает такой запрос Европейской Комиссии, действующей в качестве контролирующего органа. Европейская Комиссия имеет право исправлять, удалять или блокировать данные.<br>7. Жалобы могут направляться соответствующему национальному органу по защите данных. Сведения для контакта национальных органов по защите данных имеются на веб-сайте Европейской Комиссии, Генерального директората по вопросам юстиции: (http://ec.europa.eu/justice/data-protection/bodies/authorities/eu/index_en.htm#h2-1).<br>Если жалоба касается обработки данных Европейской Комиссией, она направляется Европейскому инспектору по защите данных (EDPS)/htpp://www.edps.europa.eu/EDPSWEB/). |


<a id="p111262"></a>

---

<a id="p111263"></a><1> Если заявление о том, чтобы стать зарегистрированным экспортером, или другой обмен информацией между зарегистрированными экспортерами и компетентными органами в странах-бенефициарах или таможенными органами в государствах-членах ЕС, были сделаны с использованием электронных технологий обработки данных, то подпись и печать, указанные в [графах 5](https://bukva.ai/docs/reglament-20152447/statya-350#p111255), [6](https://bukva.ai/docs/reglament-20152447/statya-350#p111257) и [7](https://bukva.ai/docs/reglament-20152447/statya-350#p111259), заменяются электронной аутентификацией.


<a id="p111264"></a>Приложение 22-07

<a id="p111265"></a>Заявление о происхождении

<a id="p111266"></a>Составляется в любом коммерческом документе, указывающем имя/наименование и полный адрес экспортера и грузополучателя, а также описание продукции и дату выдачи [<1>](https://bukva.ai/docs/reglament-20152447/statya-350#p111275)
<a id="p111267"></a>French version (версия на французском языке)
<a id="p111268"></a>L'exportateur... (Numero d'exportateur enregistre [<2>](https://bukva.ai/docs/reglament-20152447/statya-350#p111276) [<3>](https://bukva.ai/docs/reglament-20152447/statya-350#p111277) [<4>](https://bukva.ai/docs/reglament-20152447/statya-350#p111278)) des produits couverts par le present document declare que, sauf indication claire du contraire, ces produits ont l'origine preferentielle... [<5>](https://bukva.ai/docs/reglament-20152447/statya-350#p111279) au sens des regles d'origine du Systeme des preferences tarifaires generalisees de l'Union europeenne et que le critere d'origine satisfait est...... [<6>](https://bukva.ai/docs/reglament-20152447/statya-350#p111280).
<a id="p111269"></a>English version (версия на английском языке)
<a id="p111270"></a>The exporter... (Number of Registered Exporter [<2>](https://bukva.ai/docs/reglament-20152447/statya-350#p111276) [<3>](https://bukva.ai/docs/reglament-20152447/statya-350#p111277) [<4>](https://bukva.ai/docs/reglament-20152447/statya-350#p111278)) of the products covered by this document declares that, except where otherwise clearly indicated, these products are of... preferential origin [<5>](https://bukva.ai/docs/reglament-20152447/statya-350#p111279) according to rules of origin of the Generalised System of Preferences of the European Union and that the origin criterion met is...... [<6>](https://bukva.ai/docs/reglament-20152447/statya-350#p111280).
<a id="p111271"></a>Spanish version (версия на испанском языке)
<a id="p111272"></a>El exportador... (Numero de exportador registrado [<2>](https://bukva.ai/docs/reglament-20152447/statya-350#p111276) [<3>](https://bukva.ai/docs/reglament-20152447/statya-350#p111277) [<4>](https://bukva.ai/docs/reglament-20152447/statya-350#p111278)) de los productos incluidos en el presente documento declara que, salvo indicacion en sentido contrario, estos productos gozan de un origen preferencial... [<5>](https://bukva.ai/docs/reglament-20152447/statya-350#p111279) en el sentido de las normas de origen del Sistema de preferencias generalizado de la Union europea y que el criterio de origen satisfecho es ...... [<6>](https://bukva.ai/docs/reglament-20152447/statya-350#p111280)
<a id="p111273"></a>(Экспортер ... (Номер зарегистрированного экспортера [<2>](https://bukva.ai/docs/reglament-20152447/statya-350#p111276) [<3>](https://bukva.ai/docs/reglament-20152447/statya-350#p111277) [<4>](https://bukva.ai/docs/reglament-20152447/statya-350#p111278)) продукции, на которую распространяется настоящий документ, заявляет, что, кроме ясно указанного в других местах, настоящая продукция имеет преференциальное происхождение ... [<5>](https://bukva.ai/docs/reglament-20152447/statya-350#p111279) согласно правилам происхождения Генеральной системы преференций Европейского Союза, и что выполненный критерий происхождения ...... [<6>](https://bukva.ai/docs/reglament-20152447/statya-350#p111280).)

<a id="p111274"></a>

---

<a id="p111275"></a><1> Если заявление о происхождении заменяет другое заявление в соответствии с [параграфами (2)](https://bukva.ai/docs/reglament-20152447/statya-101#p100989) и [(3) Статьи 101](https://bukva.ai/docs/reglament-20152447/statya-101#p100991) Имплементационного Регламента (ЕС) 2015/2447, то заменяющее заявление о происхождении должно содержать указание "Replacement statement" или "Attestation de remplacement" или "Comunicacion de sustitucion" ("Заменяющее заявление"). При замене также указывается дата выдачи первоначального заявления и все другие необходимые данные в соответствии со [вторым подпараграфом Статьи 101](https://bukva.ai/docs/reglament-20152447/statya-101#p100990) Имплементационного Регламента (ЕС) 2015/2447.
<a id="p111276"></a><2> Если заявление о происхождении заменяет другое заявление в соответствии с [подпараграфом 1 Статьи 101(2)](https://bukva.ai/docs/reglament-20152447/statya-101#p100989) и [параграфом (3) Статьи 101](https://bukva.ai/docs/reglament-20152447/statya-101#p100991) Имплементационного Регламента (ЕС) 2015/2447, то грузоотправитель, перенаправляющий товары, составляющий такое заявление, указывает свое имя/название и полный адрес, за которыми следует номер зарегистрированного экспортера.
<a id="p111277"></a><3> Если заявление о происхождении заменяет другое заявление в соответствии с [подпараграфом 2 Статьи 101(2)](https://bukva.ai/docs/reglament-20152447/statya-101#p100990) Имплементационного Регламента (ЕС) 2015/2447, то грузоотправитель, перенаправляющий товары, составляющий такое заявление, указывает свое имя/название и полный адрес, за которыми следует указание (French version (версия на французском языке)) "agissant sur la base de l'attestation d'origine etablie par [nom et adresse complete de l'exportateur dans le pays beneficiaire] enregistre sous le numero suivant [Numero d'exportateur enregistre dans le pays beneficiaire]", (English version (версия на английском языке)) "acting on the basis of the statement on origin made out by [name and complete address of the exporter in the beneficiary country], registered under the following number [Number of Registered Exporter of the exporter in the beneficiary country]", (Spanish version (версия на французском языке)) "actuando sobre la base de la comunicacion extendida por [nombre y direccion completa del exportador en el pais beneficiario], registrado con el numero siguiente [Numero de exportador registrado del exportador en el pais beneficiario]." (действуя на основании заявления о происхождении, составленного [имя/название и полный адрес экспортера в стране-бенефициаре], зарегистрированным под следующим номером [номер зарегистрированного экспортера в стране-бенефициаре]).
<a id="p111278"></a><4> Если заявление о происхождении заменяет другое заявление в соответствии со [Статьей 101(2)](https://bukva.ai/docs/reglament-20152447/statya-101#p100989) Имплементационного Регламента (ЕС) 2015/2447, то грузоотправитель, перенаправляющий товары, указывает номер зарегистрированного экспортера, только если стоимость продукции, имеющей происхождение, в первоначальном коносаменте превышает 6000 евро.
<a id="p111279"></a><5> Должна быть указана страна происхождения продукции. Если заявление о происхождении относится к продукции, имеющей происхождение в Союзе, то экспортер должен указать происхождение посредством символа "EU". Если заявление о происхождении относится в целом или в части к продукции, имеющей происхождение в Сеуте или Мелилье в пределах значения [Статьи 112](https://bukva.ai/docs/reglament-20152447/statya-112#p101079) Имплементационного Регламента (ЕС) 2015/2447, то экспортер должен ясно указать происхождение посредством символа "CM".
<a id="p111280"></a><6> Продукция полностью получена: внесите букву "P"; Продукция в значительной степени обработана или переработана: внесите букву "W", после которой вносится заголовок Гармонизированной системы (например, "W" 9618).
<a id="p111281"></a>При необходимости вышеуказанное заменяется одним из следующих указаний:
<a id="p111282"></a>(a) В случае двустороннего накопления: "EU cumulation", "Cumul UE" или "Acumulacion UE" ("Накопление ЕС").
<a id="p111283"></a>(b) В случае накопления с Норвегией, Швейцарией или Турцией: "Norway cumulation", "Switzerland cumulation", "Turkey cumulation", "Cumul Norvege" "Cumul Suisse", "Cumul Turquie" или "Acumulacion Noruega", "Acumulacion Suiza", или "Acumulacion Turquia". ("Накопление с Норвегией", "Накопление со Швейцарией", "Накопление с Турцией")
<a id="p111284"></a>(c) В случае регионального накопления: "regional cumulation", "cumul regional" или "Acumulacion regional". ("Региональное накопление")
<a id="p111285"></a>(d) В случае расширенного накопления: "extended cumulation with country x", "cumul etendu avec le pays x" или "Acumulacion ampliada con el pais x". ("расширенное накопление со страной x")


<a id="p111286"></a>Приложение 22-08

<a id="p111287"></a>**СЕРТИФИКАТ**
**ПРОИСХОЖДЕНИЯ ФОРМЫ A <*>**


<a id="p111288"></a>

---

<a id="p111289"></a><*> Сертификат происхождения [формы A](https://bukva.ai/docs/reglament-20152447/statya-350#p111297) приведен в Регламенте на двух языках: английском и французском - прим. перев.

1. <a id="p111290"></a>Сертификат происхождения [формы A](https://bukva.ai/docs/reglament-20152447/statya-350#p111297) должен соответствовать [образцу](https://bukva.ai/docs/reglament-20152447/statya-350#p111297), указанному в настоящем Приложении. Использование английского или французского языка для [примечаний](https://bukva.ai/docs/reglament-20152447/statya-350#p111311) на обороте сертификата необязательно. Сертификаты составляются на английском или французском языке. Если сертификат заполняется вручную, записи вносятся чернилами и печатными буквами.
2. <a id="p111291"></a>Каждый сертификат должен иметь размеры 210 x 297 мм, допускается отклонение до - 5 мм или + 8 мм в длину и в ширину. Используемая бумага должна быть белой писчей бумагой, отсортированной, без древесной массы, имеющей плотность не менее 25 г/м2. Она должна иметь фон в виде напечатанного зеленым цветом орнамента, что позволит на глаз определить подделку механическими или химическими средствами.
<a id="p111292"></a>Если сертификаты имеют несколько копий, только на верхней копии, которая является оригиналом, печатается зеленым цветом орнамент.
3. <a id="p111293"></a>Каждый сертификат должен иметь серийный номер, напечатанный или нанесенный другим способом, по которому его можно идентифицировать.
4. <a id="p111294"></a>Сертификаты, имеющие более старые версии примечаний на обратной стороне формы, могут также использоваться до тех пор, пока не иссякнут их существующие запасы.


<table>
<colgroup><col width="13%"><col width="16%"><col width="18%"><col width="9%"><col width="19%"><col width="14%"><col width="11%"></colgroup>
<tr><td colspan="3" rowspan="2"><a id="p111295"></a>1. Товары отгружены из (бизнес-наименование экспортера, адрес, страна)</td><td colspan="4"><a id="p111296"></a>N</td></tr>
<tr><td colspan="4" rowspan="2"><a id="p111297"></a>ГЕНЕРАЛЬНАЯ СИСТЕМА ПРЕФЕРЕНЦИЙ<br>СЕРТИФИКАТ ПРОИСХОЖДЕНИЯ<br>(Объединенная декларация и сертификат)<br>ФОРМЫ A<br>выданный в ........................................<br>(страна)</td></tr>
<tr><td colspan="3" rowspan="2"><a id="p111298"></a>2. Товары отгружены (наименование грузополучателя, адрес, страна)</td></tr>
<tr><td colspan="4"><a id="p111299"></a>См. <a href="#p111311">примечания</a> на обороте</td></tr>
<tr><td colspan="3"><a id="p111300"></a>3. Транспортные средства и маршрут (насколько известно)</td><td colspan="4"><a id="p111301"></a>4. Для официального использования</td></tr>
<tr><td><a id="p111302"></a>5. Номер пункта</td><td><a id="p111303"></a>6. Маркировка и количество упаковок</td><td colspan="2"><a id="p111304"></a>7. Количество и вид упаковок, описание товаров</td><td><a id="p111305"></a>8. Критерии происхождения (см. <a href="#p111311">Примечания</a> на обороте)</td><td><a id="p111306"></a>9. Вес брутто или другое количество</td><td><a id="p111307"></a>10. Номер и дата инвойса</td></tr>
<tr><td colspan="3"><a id="p111308"></a>11. Удостоверение<br>Настоящим удостоверяю, на основании выполненного контроля, что декларация экспортера является достоверной</td><td colspan="4" rowspan="7"><a id="p111309"></a>12. Декларация экспортера<br>Нижеподписавшийся настоящим заявляет, что вышеназванные сведения и заявления являются достоверными; что товары были произведены в<br>...................................................<br>(страна)<br>и что они соответствуют требованиям происхождения, определенным для этих товаров в Генеральной системе преференций для товаров, экспортированных в<br>........................................................<br>(импортирующая страна)<br>..................................................................<br>Место и дата, подпись и печать разрешающего органа</td></tr>
<tr><td colspan="3"></td></tr>
<tr><td colspan="3"><a id="p111310"></a>..................................................<br>Место и дата, подпись и печать сертифицирующего органа</td></tr>
</table>


<a id="p111311"></a>*Примечания* (2013)

<a id="p111312"></a>I. Страны, которые принимают [Форму A](https://bukva.ai/docs/reglament-20152447/statya-350#p111297) в целях Генеральной системы преференций (GSP)


| <a id="p111313"></a>Австралия [<1>](https://bukva.ai/docs/reglament-20152447/statya-350#p111369) | <a id="p111314"></a>Европейский Союз: | <a id="p111315"></a>Франция | <a id="p111316"></a>Нидерланды |
| --- | --- | --- | --- |
| <a id="p111317"></a>Белоруссия | <a id="p111318"></a>Австрия | <a id="p111319"></a>Германия | <a id="p111320"></a>Польша |
| <a id="p111321"></a>Канада | <a id="p111322"></a>Бельгия | <a id="p111323"></a>Греция | <a id="p111324"></a>Португалия |
| <a id="p111325"></a>Исландия | <a id="p111326"></a>Болгария | <a id="p111327"></a>Венгрия | <a id="p111328"></a>Румыния |
| <a id="p111329"></a>Япония | <a id="p111330"></a>Хорватия | <a id="p111331"></a>Ирландия | <a id="p111332"></a>Словакия |
| <a id="p111333"></a>Новая Зеландия [<2>](https://bukva.ai/docs/reglament-20152447/statya-350#p111370) | <a id="p111334"></a>Кипр | <a id="p111335"></a>Италия | <a id="p111336"></a>Словения |
| <a id="p111337"></a>Норвегия | <a id="p111338"></a>Чешская Республика | <a id="p111339"></a>Латвия | <a id="p111340"></a>Испания |
| <a id="p111341"></a>Российская Федерация | <a id="p111342"></a>Дания | <a id="p111343"></a>Литва | <a id="p111344"></a>Швеция |
| <a id="p111345"></a>Швейцария, включая Лихтенштейн [<3>](https://bukva.ai/docs/reglament-20152447/statya-350#p111371) | <a id="p111346"></a>Эстония | <a id="p111347"></a>Люксембург | <a id="p111348"></a>Соединенное Королевство |
| <a id="p111349"></a>Турция | <a id="p111350"></a>Финляндия | <a id="p111351"></a>Мальта |  |
| <a id="p111352"></a>Соединенные Штаты Америки [<4>](https://bukva.ai/docs/reglament-20152447/statya-350#p111372) |  |  |  |


<a id="p111353"></a>Все подробности условий, разрешающих допуск к GSP в этих странах, можно получить в назначенных органах стран, экспортирующих и получающих преференцию или в таможенных органах стран, дающих преференцию, перечисленных выше. Информационное примечание также можно получить в секретариате UNCTAD.
<a id="p111354"></a>II. Общие условия
<a id="p111355"></a>Для получения преференции продукция должна:
<a id="p111356"></a>(a) подпадать под описание продукции, имеющей право на преференцию в стране назначения. Описание, вносимое в [форму](https://bukva.ai/docs/reglament-20152447/statya-350#p111297), должно быть достаточно подробным для того, чтобы продукция могла быть идентифицирована таможенным должностным лицом, досматривающим ее;
<a id="p111357"></a>(b) соответствовать правилам происхождения страны назначения. Каждое изделие в партии должно отдельно соответствовать своему собственному праву; и
<a id="p111358"></a>(c) соответствовать условиям коносамента, определенным страной назначения. В общем, продукция должна быть отгружена напрямую из страны экспорта в страну назначения, но большинство стран, дающих преференции, принимают прохождение через промежуточные страны согласно определенным условиям (для Австралии прямая отгрузка необязательна).
<a id="p111359"></a>III. Записи в [графе 8](https://bukva.ai/docs/reglament-20152447/statya-350#p111305)
<a id="p111360"></a>Продукция, пользующаяся преференциями, должна быть либо полностью получена в соответствии с правилами страны назначения или существенно переработана или обработана для выполнения требований правил происхождения этой страны.
<a id="p111361"></a>(a) Продукция, которая полностью получена: для экспорта во все страны, указанные в [Разделе I](https://bukva.ai/docs/reglament-20152447/statya-350#p111312), укажите букву "P" в [графе 8](https://bukva.ai/docs/reglament-20152447/statya-350#p111305) (для Австралии и Новой Зеландии [графа 8](https://bukva.ai/docs/reglament-20152447/statya-350#p111305) может остаться пустой).
<a id="p111362"></a>(b) Продукция, существенно переработанная или обработанная: для экспорта в страны, определенные ниже, запись в [графе 8](https://bukva.ai/docs/reglament-20152447/statya-350#p111305) должна быть следующей:
<a id="p111363"></a>(1) Соединенные Штаты Америки: для отгрузок одной страны укажите букву "Y" в [графе 8](https://bukva.ai/docs/reglament-20152447/statya-350#p111305), для отгрузок из признанных объединений стран укажите букву "Z", после чего укажите сумму затрат или стоимость внутренних материалов и прямые затраты на переработку, выраженные в процентном отношении к цене на условиях самовывоза экспортируемой продукции; (пример, "Y" 35% или "Z" 35%).
<a id="p111364"></a>(2) Канада: для продукции, соответствующей критериям происхождения от переработки или обработки в нескольких наименее развитых странах, имеющих право, укажите букву "G" в [графе 8](https://bukva.ai/docs/reglament-20152447/statya-350#p111305); в противном случае - "F".
<a id="p111365"></a>(3) Исландия, Европейский Союз, Япония, Норвегия, Швейцария, в том числе Лихтенштейн, и Турция: укажите букву "W" в [графе 8](https://bukva.ai/docs/reglament-20152447/statya-350#p111305), после нее укажите Гармонизированное описание товара и заголовок четырехзначного уровня кодовой системы (Гармонизированной системы) экспортируемой продукции (пример, "W" 96.18).
<a id="p111366"></a>(4) Российская Федерация: для продукции, которая включает добавленную стоимость в экспортирующей получающей преференцию стране, укажите букву "Y" в [графе 8](https://bukva.ai/docs/reglament-20152447/statya-350#p111305), за ней укажите стоимость импортированных материалов и компонентов, выраженную в процентном отношении от цены на условиях fob экспортируемой продукции (пример, "Y" 45%); для продукции, полученной в получающей преференцию стране и обработанной или переработанной в одной или нескольких других таких странах, укажите "Pk".
<a id="p111367"></a>(5) Австралия и Новая Зеландия: заполнение [графы 8](https://bukva.ai/docs/reglament-20152447/statya-350#p111305) не требуется. Достаточно, чтобы декларация была заполнена должным образом в [графе 12](https://bukva.ai/docs/reglament-20152447/statya-350#p111309).

<a id="p111368"></a>

---

<a id="p111369"></a><1> Для Австралии основное требование - декларация экспортера в обычном коммерческом инвойсе. [Форма A](https://bukva.ai/docs/reglament-20152447/statya-350#p111297), сопровождаемая обычным коммерческим инвойсом, является приемлемой альтернативой, но официальная сертификация не требуется.
<a id="p111370"></a><2> Официальная сертификация не требуется.
<a id="p111371"></a><3> Княжество Лихтенштейн образует согласно Договору от 29 марта 1923 г. таможенный союз со Швейцарией.
<a id="p111372"></a><4> Соединенные Штаты не требуют GSP [Формы A](https://bukva.ai/docs/reglament-20152447/statya-350#p111297). Считается, что декларации, устанавливающей всю соответствующую подробную информацию о производстве или изготовлении товаров, достаточно, только если об этом запрашивает районный таможенный сборщик.


<a id="p111373"></a>Приложение 22-09

<a id="p111374"></a>Декларация инвойса

<a id="p111375"></a>Декларация инвойса, текст которой дан ниже, должна составляться в соответствии со сносками. Но воспроизводить сноски не нужно.
<a id="p111376"></a>French version (версия на французском языке)
<a id="p111377"></a>L'exportateur des produits couverts par le present document [autorisation douaniere no [<1>](https://bukva.ai/docs/reglament-20152447/statya-350#p111386)] declare que, sauf indication claire du contraire, ces produits ont l'origine preferentielle... [<2>](https://bukva.ai/docs/reglament-20152447/statya-350#p111387) au sens des regles d'origine du Systeme des preferences tarifaires generalisees de l'Union europeenne... [<3>](https://bukva.ai/docs/reglament-20152447/statya-350#p111388) et [<4>](https://bukva.ai/docs/reglament-20152447/statya-350#p111389).
<a id="p111378"></a>English version (версия на английском языке)
<a id="p111379"></a>The exporter of the products covered by this document (customs authorization No... [<1>](https://bukva.ai/docs/reglament-20152447/statya-350#p111386)) declares that, except where otherwise clearly indicated, these products are of... preferential origin [<2>](https://bukva.ai/docs/reglament-20152447/statya-350#p111387) according to rules of origin of the Generalized System of Preferences of the European Union [<3>](https://bukva.ai/docs/reglament-20152447/statya-350#p111388) and [<4>](https://bukva.ai/docs/reglament-20152447/statya-350#p111389).
<a id="p111380"></a>Spanish version (версия на испанском языке)
<a id="p111381"></a>El exportador de los productos incluidos en el presente docemento (autorizacion aduanera n°... [<1>](https://bukva.ai/docs/reglament-20152447/statya-350#p111386) declara que, salvo indicacion en sentido contrario, estos productos gozan de un origen preferencial... [<2>](https://bukva.ai/docs/reglament-20152447/statya-350#p111387)) en el sentido de las normas de origen del Sistema de preferencias generalizado de la Union europea [<3>](https://bukva.ai/docs/reglament-20152447/statya-350#p111388) y [<4>](https://bukva.ai/docs/reglament-20152447/statya-350#p111389).
<a id="p111382"></a>(Экспортер продукции, на которую распространяется настоящий документ, (таможенное разрешение N...... [<1>](https://bukva.ai/docs/reglament-20152447/statya-350#p111386)), заявляет, что если иное явно не установлено, эта продукция ......................... имеет преференциальное происхождение [<2>](https://bukva.ai/docs/reglament-20152447/statya-350#p111387) согласно правилам происхождения Генеральной системы преференций Европейского Союза [<3>](https://bukva.ai/docs/reglament-20152447/statya-350#p111388) и [<4>](https://bukva.ai/docs/reglament-20152447/statya-350#p111389).)
<a id="p111383"></a>(место и дата) [<5>](https://bukva.ai/docs/reglament-20152447/statya-350#p111390)
<a id="p111384"></a>(Подпись экспортера; дополнительно ФИО лица, подписавшего декларацию, должно быть указано разборчивым почерком) [<6>](https://bukva.ai/docs/reglament-20152447/statya-350#p111391)

<a id="p111385"></a>

---

<a id="p111386"></a><1> Если декларация инвойса составлена утвержденным экспортером Европейского Союза в пределах значения [Статьи 77(4)](https://bukva.ai/docs/reglament-20152447/statya-77#p100759) Имплементационного Регламента (ЕС) 2015/2447, номер разрешения утвержденного экспортера должен быть указан в этом месте. Если (это всегда будет случай с декларациями инвойса, составленными в странах-бенефициарах) декларация инвойса составляется неутвержденным экспортером, слова в скобках должны быть опущены, или оставьте пустое место.
<a id="p111387"></a><2> Указывается страна происхождения продукции. Если декларация инвойса относится полностью или в части к продукции, происходящей из Сеуты и Мелильи в пределах значения [Статьи 112](https://bukva.ai/docs/reglament-20152447/statya-112#p101079) Имплементационного Регламента (ЕС) 2015/2447, экспортер должен ясно указать их в документе, в котором составляется декларация посредством символа "СМ".
<a id="p111388"></a><3> При необходимости внесите одно из следующих указаний: "EU cumulation", "Norway cumulation", "Switzerland cumulation", "Turkey cumulation", "regional cumulation", "extended cumulation with country x" или "Cumul UE", "Cumul Norvege", "Cumul Suisse", "Cumul Turquie", "cumul regional", "cumul etendu avec le pays x" или "Acumulacion UE", "Acumulacion Noruega", "Acumulacion Suiza", "Acumulacion Turquia", "Acumulacion regional", "Acumulacion ampliada con en pais x". ("Накопление ЕС", "Накопление с Норвегией", "Накопление со Швейцарией", "Накопление с Турцией", "региональное накопление", "расширенное накопление со страной x").
<a id="p111389"></a><4> Если декларация инвойса составляется в контексте другого соглашения о преференциальной торговле, ссылка на Генеральную систему преференций заменяется ссылкой на другое указанное соглашение о преференциальной торговле.
<a id="p111390"></a><5> Эти указания могут быть опущены, если информация содержится в самом документе.
<a id="p111391"></a><6> См. [Статью 77(7)](https://bukva.ai/docs/reglament-20152447/statya-77#p100768) Имплементационного Регламента (ЕС) 2015/2447 (касается только утвержденных экспортеров Европейского Союза). В тех случаях, когда от экспортера не требуется подпись, исключение подписи также предполагает исключение имени подписывающего лица.


<a id="p111392"></a>Приложение 22-10

<a id="p111393"></a>**СЕРТИФИКАТ**
**ПЕРЕДВИЖЕНИЯ EUR.1 И СООТВЕТСТВУЮЩИЕ ЗАЯВЛЕНИЯ**

1. <a id="p111394"></a>Сертификат передвижения EUR.1 составляется по [форме](https://bukva.ai/docs/reglament-20152447/statya-350#p111397), указанной в образце в настоящем Приложении. Эта [форма](https://bukva.ai/docs/reglament-20152447/statya-350#p111397) печатается на одном из официальных языков Союза. Сертификаты составляются на одном из этих языков и в соответствии с положениями внутреннего законодательства экспортирующего государства или территории. Если сертификат составлен от руки, он должен быть заполнен чернилами и печатными буквами.
2. <a id="p111395"></a>Каждый сертификат должен иметь размеры 210 x 297 мм, допускается отклонение до - 5 мм или + 8 мм в длину. Используемая бумага должна быть белой, отсортированной для письма, без древесной массы, имеющей плотность не менее 25 г/м <2>. Она должна иметь фон в виде напечатанного зеленым цветом орнамента, что позволит на глаз определить подделку механическими или химическими средствами.
3. <a id="p111396"></a>Компетентные органы экспортирующего государства или территории могут сохранить право печатать сами бланки сертификатов или могут печатать их в утвержденной печатной организации. В последнем случае каждый сертификат должен включать в себя наименование и адрес печатной организации или знак, по которому ее можно идентифицировать. Он также должен иметь серийный номер, напечатанный или нет, по которому его можно идентифицировать.

<a id="p111397"></a>**СЕРТИФИКАТ ПЕРЕВОЗКИ**


<table>
<colgroup><col width="43%"><col width="9%"><col width="15%"><col width="5%"><col width="9%"><col width="19%"></colgroup>
<tr><td rowspan="3"><a id="p111398"></a>1. Экспортер (имя/наименование, полный адрес, страна)</td><td colspan="5"><a id="p111399"></a>EUR. 1 N A 000.000</td></tr>
<tr><td colspan="5"><a id="p111400"></a>См. <a href="#p111426">примечания</a> на обороте этой формы</td></tr>
<tr><td colspan="5" rowspan="2"><a id="p111401"></a>2. Сертификат, используемый в преференциальной торговле между<br>......................................................<br>и<br>.......................................................<br>(укажите соответствующие страны, группы стран или территории)</td></tr>
<tr><td rowspan="2"><a id="p111402"></a>3. Грузополучатель (имя/ наименование, полный адрес, страна) (необязательно)</td></tr>
<tr><td colspan="3"><a id="p111403"></a>4. Страна, группа стран или территория, в которой продукция, как считается, имеет происхождение</td><td colspan="2"><a id="p111404"></a>5. Страна, группа стран или территория назначения</td></tr>
<tr><td><a id="p111405"></a>6. Сведения о перевозке (необязательно)</td><td colspan="5"><a id="p111406"></a>7. Примечания</td></tr>
<tr><td colspan="3"><a id="p111407"></a>8. Номер пункта; Маркировки и номера; Количество и вид упаковки <a href="#p111413">&lt;1&gt;</a>; Описание товаров</td><td colspan="2"><a id="p111408"></a>9. Масса брутто (кг) или др. единицы измерения (литры, м3 и т.п.)</td><td><a id="p111409"></a>10. Инвойс (необязательно)</td></tr>
<tr><td colspan="2"><a id="p111410"></a>11. ТАМОЖЕННОЕ УДОСТОВЕРЕНИЕ<br>Декларация удостоверена<br>Экспортный документ <a href="#p111414">&lt;2&gt;</a><br>Форма ............. N ............................<br>От ..................................................<br>Таможенное учреждение ........................<br>Выдающая страна или территория ............<br>......................................................<br>.....................................................<br>(Место и дата)<br>...................................................<br>(подпись)</td><td><a id="p111411"></a>Печать</td><td colspan="3"><a id="p111412"></a>12. ДЕКЛАРАЦИЯ ЭКСПОРТЕРА<br>Я, нижеподписавшийся, заявляю, что товары, описанные выше, соответствуют условиям, необходимым для выдачи этого сертификата<br>....................................<br>(Место и дата)<br>....................................<br>(подпись)</td></tr>
<tr><td colspan="6"><a id="p111413"></a><a id="p111414"></a>&lt;1&gt; Если товары не упакованы, укажите количество изделий или укажите "навалом".<br>&lt;2&gt; Заполнить, только если этого требуют регламенты экспортирующей страны или территории.</td></tr>
</table>


<table>
<colgroup><col width="50%"><col width="50%"></colgroup>
<tr><td><a id="p111415"></a>13. ЗАПРОС О ПРОВЕРКЕ:</td><td><a id="p111416"></a>14. РЕЗУЛЬТАТ ПРОВЕРКИ</td></tr>
<tr><td></td><td rowspan="4"><a id="p111417"></a>Выполненная проверка показывает, что настоящий сертификат <a href="#p111425">&lt;1&gt;</a><br><img src="https://i.bukva.ai/sakP7uTQ/img_16.png" alt="формула"> был выдан указанным таможенным учреждением, и что информация, указанная в нем, достоверная.<br><img src="https://i.bukva.ai/sakP7uTQ/img_17.png" alt="формула"> не соответствует требованиям достоверности и точности (см. <a href="#p111426">примечания</a>)</td></tr>
<tr><td></td></tr>
<tr><td></td></tr>
<tr><td><a id="p111418"></a>Проверка достоверности и точности настоящего сертификата запрошена</td></tr>
<tr><td><a id="p111419"></a>.......................................................<br>(Место и дата)</td><td><a id="p111420"></a>....................................................<br>(Место и дата)</td></tr>
<tr><td><a id="p111421"></a>Печать</td><td><a id="p111422"></a>Печать</td></tr>
<tr><td rowspan="2"><a id="p111423"></a>.......................................<br>(Подпись)</td><td><a id="p111424"></a>..........................................<br>(Подпись)</td></tr>
<tr><td><a id="p111425"></a>--------------------------------<br>&lt;1&gt; Укажите X в соответствующей графе</td></tr>
</table>


<a id="p111426"></a>Примечания

1. <a id="p111427"></a>Сертификаты не должны содержать исправлений или написания одного слова поверх другого. Все исправления должны быть выполнены посредством зачеркивания неверных сведений и добавлением необходимых исправленных сведений. Все исправления должны быть подписаны лицом, заполнившим сертификат, и удостоверены таможенными органами выдающей страны или территории.
2. <a id="p111428"></a>Не должно оставаться место между пунктами сертификата, и каждый пункт должен иметь порядковый номер. Горизонтальная линия должна быть проведена непосредственно ниже последнего пункта. Все неиспользованное место должно быть перечеркнуто таким образом, чтобы невозможно было ничего добавить.
3. <a id="p111429"></a>Товары должны быть описаны в соответствии с коммерческой практикой и должно иметься достаточно сведений, чтобы идентифицировать товары.

<a id="p111430"></a>**ЗАЯВЛЕНИЕ О СЕРТИФИКАТЕ ПЕРЕМЕЩЕНИЯ**


<table>
<colgroup><col width="48%"><col width="22%"><col width="4%"><col width="11%"><col width="15%"></colgroup>
<tr><td rowspan="3"><a id="p111431"></a>1. Экспортер (Имя/наименование, полный адрес, страна)</td><td colspan="4"><a id="p111432"></a>EUR.1 N A 000.000</td></tr>
<tr><td colspan="4"><a id="p111433"></a>См. примечания на обороте перед заполнением этой формы</td></tr>
<tr><td colspan="4" rowspan="2"><a id="p111434"></a>2. Заявление о выдаче сертификата, используемого в преференциальной торговле между<br>.........................................................<br>и<br>.......................................................<br>(укажите соответствующие страны, группы стран или территории)</td></tr>
<tr><td rowspan="2"><a id="p111435"></a>3. Грузополучатель (Имя/наименование, полный адрес, страна) (необязательно)</td></tr>
<tr><td colspan="2"><a id="p111436"></a>4. Страна, группа стран или территория, в которой, как считается, продукция имеет происхождение</td><td colspan="2"><a id="p111437"></a>5. Страна, группа стран или территория назначения</td></tr>
<tr><td><a id="p111438"></a>6. Сведения о перевозке (необязательно)</td><td colspan="4"><a id="p111439"></a>7. Примечания</td></tr>
<tr><td colspan="2"><a id="p111440"></a>8. Номер пункта; Маркировки и номера; Количество и вид упаковки <a href="#p111443">&lt;1&gt;</a>; Описание товаров</td><td colspan="2"><a id="p111441"></a>9. Масса брутто (кг) или др. единицы измерения (литры, м3 и т.п.)</td><td><a id="p111442"></a>10. Инвойс (необязательно)</td></tr>
<tr><td colspan="5"><a id="p111443"></a>&lt;1&gt; Если товары не упакованы, укажите количество изделий или укажите "навалом".</td></tr>
</table>


<a id="p111444"></a>**ДЕКЛАРАЦИЯ ЭКСПОРТЕРА**

<a id="p111445"></a>Я, нижеподписавшийся, экспортер товаров, описанных на обороте,


<table>
<colgroup><col width="24%"><col width="36%"><col width="39%"></colgroup>
<tr><td><a id="p111446"></a>ЗАЯВЛЯЮ,</td><td colspan="2"><a id="p111447"></a>что товары соответствуют условиям, необходимым для выдачи прилагаемого сертификата</td></tr>
<tr><td><a id="p111448"></a>ОПРЕДЕЛЯЮ</td><td colspan="2"><a id="p111449"></a>следующие обстоятельства, которые позволяют этим товарам соответствовать вышеназванным условиям:<br>........................................................................................<br>.........................................................................................<br>.........................................................................................<br>.........................................................................................</td></tr>
<tr><td><a id="p111450"></a>ПРЕДОСТАВЛЯЮ</td><td colspan="2"><a id="p111451"></a>следующие подтверждающие документы <a href="#p111458">&lt;1&gt;</a>:<br>........................................................................................<br>.........................................................................................<br>.........................................................................................<br>.........................................................................................</td></tr>
<tr><td><a id="p111452"></a>ПРИНИМАЮ ОБЯЗАТЕЛЬСТВО</td><td colspan="2"><a id="p111453"></a>предоставить по запросу соответствующих органов все подтверждающие доказательства, которые эти органы могут потребовать в целях выдачи прилагаемого сертификата, и принимаю обязательство, если потребуется, согласиться на все проверки моих бухгалтерских записей и на проверки процессов производства вышеназванных товаров, выполняемых вышеназванными органами</td></tr>
<tr><td><a id="p111454"></a>ПРОШУ</td><td colspan="2"><a id="p111455"></a>Выдать прилагающийся сертификат на эти товары</td></tr>
<tr><td colspan="2"><a id="p111456"></a>...........................<br>(место и дата)<br>........................<br>(подпись)</td><td></td></tr>
</table>


<a id="p111457"></a>

---

<a id="p111458"></a><1> Например, документы об импорте, сертификаты передвижения, инвойсы, декларации производителя и т.п., относящиеся к продукции, используемой в производстве, или к товарам, реэкспортируемым в том же состоянии.


<a id="p111459"></a>Приложение 22-13 - IA

<a id="p111460"></a>Декларация инвойса

<a id="p111461"></a>Декларация инвойса, текст которой дан ниже, должна быть составлена в соответствии с примечаниями. Но воспроизводить примечания не нужно.
<a id="p111462"></a>Экспортер продукции, на которую распространяется настоящий документ (таможенное разрешение N... [<1>](https://bukva.ai/docs/reglament-20152447/statya-350#p111514)), заявляет, что если иное явно не установлено, эта продукция имеет ......................... [<2>](https://bukva.ai/docs/reglament-20152447/statya-350#p111515) преференциальное происхождение.

<a id="p111463"></a>Bulgarian version (Версия на болгарском языке)

<a id="p111464"></a>Износителят на продуктите, обхванати от този документ (митническо разрешение N ... [<1>](https://bukva.ai/docs/reglament-20152447/statya-350#p111514)), декларира, че освен където е отбелязано друго, тези продукти са с ... преференциален произход [<2>](https://bukva.ai/docs/reglament-20152447/statya-350#p111515).

<a id="p111465"></a>Spanish version (Версия на испанском языке)

<a id="p111466"></a>El exportador de los productos incluidos en el presente documento ( autorización aduanera n o... [<1>](https://bukva.ai/docs/reglament-20152447/statya-350#p111514)) declara que, salvo indicación en sentido contrario, estos productos gozan de un origen preferencial... [<2>](https://bukva.ai/docs/reglament-20152447/statya-350#p111515).

<a id="p111467"></a>Czech version (Версия на чешском языке)

<a id="p111468"></a> Vývozce výrobkù uvedených v tomto dokumentu ( èíslo povolení ... [<1>](https://bukva.ai/docs/reglament-20152447/statya-350#p111514)) prohlašuje , že kromì zøetelnì oznaèených mají tyto výrobky preferenèní pùvod v... [<2>](https://bukva.ai/docs/reglament-20152447/statya-350#p111515)).

<a id="p111469"></a>Danish version (Версия на датском языке)

<a id="p111470"></a> Eksportøren af varer, der er omfattet af nærværende dokument, (toldmyndighedernes tilladelse nr.... [<1>](https://bukva.ai/docs/reglament-20152447/statya-350#p111514)), erklærer , at varerne, medmindre andet tydeligt er angivet, har præferenceoprindelse i... [<2>](https://bukva.ai/docs/reglament-20152447/statya-350#p111515).

<a id="p111471"></a>German version (Версия на немецком языке)

<a id="p111472"></a>Der Ausführer ( Ermächtigter Ausführer ; Bewilligungs-Nr.... [<1>](https://bukva.ai/docs/reglament-20152447/statya-350#p111514)) der Waren, auf die sich dieses Handelspapier bezieht, erklärt , dass diese Waren, soweit nicht anders angegeben, präferenzbegünstigte ... [<2>](https://bukva.ai/docs/reglament-20152447/statya-350#p111515) Ursprungswaren sind.

<a id="p111473"></a>Estonian version (Версия на эстонском языке)

<a id="p111474"></a> Käesoleva dokumendiga hõlmatud toodete eksportija (tolli loa nr.... [<1>](https://bukva.ai/docs/reglament-20152447/statya-350#p111514)) deklareerib, et need tooted on... [<2>](https://bukva.ai/docs/reglament-20152447/statya-350#p111515) sooduspäritoluga , välja arvatud juhul, kui on selgelt näidatud teisiti.

<a id="p111475"></a>Greek version (Версия на греческом языке)

<a id="p111476"></a>O $\epsilon\xi\alpha\gamma\omega\gamma\text{έ}\alpha\varsigma$ $\tau\omega\nu$ $\pi\rho o\text{ϊό}\nu\tau\omega\nu$ $\pi o\upsilon$ $\kappa\alpha\lambda\text{ύ}\pi\tau o\nu\tau\alpha\iota$ $\alpha\pi\text{ό}$ $\tau o$ $\pi\alpha\rho\text{ό}\nu$ $\text{έ}\gamma\gamma\rho\alpha\phi o$ [ $\text{ά}\delta\epsilon\iota\alpha$ $\tau\epsilon\lambda\omega\nu\epsilon\text{ί}o\upsilon$ $\upsilon\pi’$ $\alpha\rho\iota\theta.$ .... [<1>](https://bukva.ai/docs/reglament-20152447/statya-350#p111514)] $\delta\eta\lambda\text{ώ}\nu\epsilon\iota$ $\text{ό}\tau\iota$ , $\epsilon\kappa\tau\text{ό}\varsigma$ $\epsilon\text{ά}\nu$ $\delta\eta\lambda\text{ώ}\nu\epsilon\tau\alpha\iota$ $\sigma\alpha\phi\text{ώ}\varsigma$ $\text{ά}\lambda\lambda\omega\varsigma$ , $\tau\alpha$ $\pi\rho o\text{ϊό}\nu\tau\alpha$ $\alpha\upsilon\tau\text{ά}$ $\epsilon\text{ί}\nu\alpha\iota$ $\pi\rho o\tau\iota\mu\eta\sigma\iota\alpha\kappa\text{ή}\varsigma$ $\kappa\alpha\tau\alpha\gamma\omega\gamma\text{ή}\varsigma$ ... [<2>](https://bukva.ai/docs/reglament-20152447/statya-350#p111515).

<a id="p111477"></a>English version (Версия на английском языке)

<a id="p111478"></a>The exporter of the products covered by this document (customs authorisation No... [<1>](https://bukva.ai/docs/reglament-20152447/statya-350#p111514) declares that, except where otherwise clearly indicated, these products are of... [<2>](https://bukva.ai/docs/reglament-20152447/statya-350#p111515) preferential origin.

<a id="p111479"></a>French version (Версия на французском языке)

<a id="p111480"></a>L'exportateur des produits couverts par le présent document [autorisation douanière n o... [<1>](https://bukva.ai/docs/reglament-20152447/statya-350#p111514)] déclare que, sauf indication claire du contraire, ces produits ont l'origine préférentielle ... [<2>](https://bukva.ai/docs/reglament-20152447/statya-350#p111515).

<a id="p111481"></a>Croatian version (Версия на хорватском языке)

<a id="p111482"></a>Izvoznik proizvoda obuhvaæenih ovom ispravom (carinsko ovlaštenje br.... [<1>](https://bukva.ai/docs/reglament-20152447/statya-350#p111514)) izjavljuje da su, osim ako je drukèije izrièito navedeno, ovi proizvodi... [<2>](https://bukva.ai/docs/reglament-20152447/statya-350#p111515) preferencijalnog podrijetla.

<a id="p111483"></a>Italian version (Версия на итальянском языке)

<a id="p111484"></a>L'esportatore delle merci contemplate nel presente documento [autorizzazione doganale n.... [<1>](https://bukva.ai/docs/reglament-20152447/statya-350#p111514)] dichiarache, salvo indicazione contraria, le merci sono di origine preferenziale... [<2>](https://bukva.ai/docs/reglament-20152447/statya-350#p111515).

<a id="p111485"></a>Latvian version (Версия на латвийском языке)

<a id="p111486"></a> Eksportçtâjs produktiem, kuri ietverti šajâ dokumentâ (muitas pilnvara Nr.... [<1>](https://bukva.ai/docs/reglament-20152447/statya-350#p111514)), deklarç , ka, izòemot tur, kur ir citâdi skaidri noteikts, šiem produktiem ir priekšrocîbu izcelsme no... [<2>](https://bukva.ai/docs/reglament-20152447/statya-350#p111515).

<a id="p111487"></a>Lithuanian version (Версия на литовском языке)

<a id="p111488"></a> Šiame dokumente išvardintø prekiø eksportuotojas ( muitinës liudijimo Nr... [<1>](https://bukva.ai/docs/reglament-20152447/statya-350#p111514)) deklaruoja, kad, jeigu kitaip nenurodyta, tai yra... [<2>](https://bukva.ai/docs/reglament-20152447/statya-350#p111515) preferencinës kilmës prekës .

<a id="p111489"></a>Hungarian version (Версия на венгерском языке)

<a id="p111490"></a>A jelen okmányban szereplõ áruk exportõre ( vámfelhatalmazási szám :... [<1>](https://bukva.ai/docs/reglament-20152447/statya-350#p111514)) kijelentem, hogy eltérõ egyértelmû jelzés hiányában az áruk preferenciális ... [<2>](https://bukva.ai/docs/reglament-20152447/statya-350#p111515) származásúak .

<a id="p111491"></a>Maltese version (Версия на мальтийском языке)

<a id="p111492"></a>L-esportatur tal-prodotti koperti b'dan id-dokument (awtorizzazzjoni tad-dwana nru.... [<1>](https://bukva.ai/docs/reglament-20152447/statya-350#p111514)) jiddikjara li, h - lief fejn indikat b'mod $\dot{c}ar$ li mhux hekk, dawn il- prodotti huma ta' $ori\dot{g}ini$ preferenzjali... [<2>](https://bukva.ai/docs/reglament-20152447/statya-350#p111515).

<a id="p111493"></a>Dutch version (Версия на голландском языке)

<a id="p111494"></a>De exporteur van de goederen waarop dit document van toepassing is (douanevergunning nr.... [<1>](https://bukva.ai/docs/reglament-20152447/statya-350#p111514)), verklaart dat, behoudens uitdrukkelijke andersluidende vermelding, deze goederen van preferentiële ... oorsprong zijn [<2>](https://bukva.ai/docs/reglament-20152447/statya-350#p111515).

<a id="p111495"></a>Polish version (Версия на польском языке)

<a id="p111496"></a>Eksporter produktów objêtych tym dokumentem ( $upowa\dot{z}nienie$ w³adz celnych nr... [<1>](https://bukva.ai/docs/reglament-20152447/statya-350#p111514)) deklaruje, $¿e$ z wyj¹tkiem gdzie jest to wyraŸnie okreœlone , produkty te maj¹ ... [<2>](https://bukva.ai/docs/reglament-20152447/statya-350#p111515) preferencyjne pochodzenie.

<a id="p111497"></a>Portuguese version (Версия на португальском языке)

<a id="p111498"></a>O exportador dos produtos cobertos pelo presente documento [ autorização aduaneira n. o... [<1>](https://bukva.ai/docs/reglament-20152447/statya-350#p111514)], declara que, salvo expressamente indicado em contrário , estes produtos são de origem preferencial... [<2>](https://bukva.ai/docs/reglament-20152447/statya-350#p111515).

<a id="p111499"></a>Romanian version (Версия на румынском языке)

<a id="p111500"></a>Exportatorul produselor ce fac obiectul acestui document [ autorizaþia vamalã nr.... [<1>](https://bukva.ai/docs/reglament-20152447/statya-350#p111514)] declarã cã , exceptând cazul în care în mod expres este indicat altfel, aceste produse sunt de origine preferenþialã ... [<2>](https://bukva.ai/docs/reglament-20152447/statya-350#p111515).

<a id="p111501"></a>Slovenian version (Версия на словенском языке)

<a id="p111502"></a>Izvoznik blaga, zajetega s tem dokumentom (pooblastilo carinskih organov št. .... [<1>](https://bukva.ai/docs/reglament-20152447/statya-350#p111514)) izjavlja, da, razen èe ni drugaèe jasno navedeno, ima to blago preferencialno... [<2>](https://bukva.ai/docs/reglament-20152447/statya-350#p111515) poreklo.

<a id="p111503"></a>Slovak version (Версия на словацком языке)

<a id="p111504"></a> Vývozca výrobkov uvedených v tomto dokumente [ èíslo povolenia... [<1>](https://bukva.ai/docs/reglament-20152447/statya-350#p111514)] vyhlasuje, že okrem zretel'ne oznaèených , majú tieto výrobky preferenèný pôvod v... [<2>](https://bukva.ai/docs/reglament-20152447/statya-350#p111515).

<a id="p111505"></a>Finnish version (Версия на финском языке)

<a id="p111506"></a> Tässä asiakirjassa mainittujen tuotteiden viejä (tullin lupa nro... [<1>](https://bukva.ai/docs/reglament-20152447/statya-350#p111514)) ilmoittaa, että nämä tuotteet ovat, ellei toisin ole selvästi merkitty, etuuskohteluun oikeutettuja... [<2>](https://bukva.ai/docs/reglament-20152447/statya-350#p111515) alkuperätuotteita .

<a id="p111507"></a>Swedish version (Версия на шведском языке)

<a id="p111508"></a> Exportören av de varor som omfattas av detta dokument (tullmyndighetens tillstånd nr... [<1>](https://bukva.ai/docs/reglament-20152447/statya-350#p111514)) försäkrar att dessa varor, om inte annat tydligt markerats, har förmånsberättigande ... ursprung [<2>](https://bukva.ai/docs/reglament-20152447/statya-350#p111515).

<a id="p111509"></a>................................................................................................... [<3>](https://bukva.ai/docs/reglament-20152447/statya-350#p111516)

<a id="p111510"></a>(Место и дата)

<a id="p111511"></a>.................................................................................................. [<4>](https://bukva.ai/docs/reglament-20152447/statya-350#p111517)

<a id="p111512"></a>(Подпись экспортера; кроме этого, имя лица, подписывающего
декларацию, должно быть указано ясным почерком)


<a id="p111513"></a>

---

<a id="p111514"></a><1> Если декларация инвойса составлена одобренным экспортером, то номер разрешения утвержденного экспортера должен быть указан в этом месте. Если декларация инвойса составляется неодобренным экспортером, то слова в скобках должны быть опущены, или оставьте пустое место.
<a id="p111515"></a><2> Указывается страна происхождения продукции. Если декларация инвойса относится полностью или в части к продукции, происходящей из Сеуты и Мелильи, то экспортер должен ясно указать их в документе, в котором составляется декларация посредством символа "СМ".
<a id="p111516"></a><3> Эти указания могут быть опущены, если информация содержится в самом документе.
<a id="p111517"></a><4> См. [Статью 119(5)](https://bukva.ai/docs/reglament-20152447/statya-119#p101184). В тех случаях, когда от экспортера не требуется подпись, исключение подписи также предполагает исключение имени подписывающего лица.


<a id="p111518"></a>Приложение 22-14

<a id="p111519"></a>Сертификат
происхождения для отдельной продукции, подлежащей
специальным непреференциальным соглашениям по импорту

<a id="p111520"></a>Введение:
1. <a id="p111521"></a>Срок действия сертификата происхождения составляет 12 месяцев с даты выдачи выдающими органами.
2. <a id="p111522"></a>Сертификаты происхождения состоят только из одного листа, идентифицированного словом "оригинал" после заголовка документа. Если необходимы дополнительные копии, они должны иметь обозначение "копия" после заголовка документа. Таможенные органы в Союзе принимают в качестве действующего только оригинал сертификата происхождения.
3. <a id="p111523"></a>Сертификаты происхождения должны иметь размеры 210 x 297 мм, допускается отклонение до + 8 мм или - 5 мм в длину. Используемая бумага должна быть белой, без древесной массы, и имеющей плотность не менее 40 г/м2. Лицевая сторона оригинала должна иметь фон в виде напечатанного желтым цветом орнамента, что позволит определить подделку механическими или химическими средствами.
4. <a id="p111524"></a>Сертификаты происхождения печатаются и заполняются машинописным способом на одном из официальных языков Союза. Записи не должны содержать исправлений или написания одного слова поверх другого. Все исправления должны быть выполнены посредством зачеркивания неверных записей и добавлением необходимых исправленных сведений. Все исправления должны быть подписаны лицом, заполнившим сертификат, и удостоверены выдающими органами.
<a id="p111525"></a>Все дополнительные сведения, необходимые для имплементации законодательства Союза, регулирующего специальные соглашения по импорту, вносятся в [графу 5](https://bukva.ai/docs/reglament-20152447/statya-350#p111561) сертификата происхождения.
<a id="p111526"></a>Незаполненное пространство в [графах 5](https://bukva.ai/docs/reglament-20152447/statya-350#p111561), [6](https://bukva.ai/docs/reglament-20152447/statya-350#p111562) и [7](https://bukva.ai/docs/reglament-20152447/statya-350#p111563) должно быть перечеркнуто таким образом, чтобы ничего нельзя было дополнить на более позднем этапе.
5. <a id="p111527"></a>Каждый сертификат происхождения должен иметь серийный номер, напечатанный или нет, по которому он может быть идентифицирован, и должен иметь печать выдающего органа и должен быть подписан лицом или лицами, имеющими полномочия на это.
6. <a id="p111528"></a>Сертификаты происхождения, выданные ретроспективно, должны иметь в [графе 5](https://bukva.ai/docs/reglament-20152447/statya-350#p111561) следующее указание на одном из официальных языков Европейского Союза:
- <a id="p111529"></a>Выдан ретроспективно;
- <a id="p111530"></a>Expedido a posteriori;
- <a id="p111531"></a>Udstedt efterfølgende ;
- <a id="p111532"></a>Nachträglich ausgestellt;
- <a id="p111533"></a>$\text{Ε}\kappa\delta o\theta\text{έ}\nu$ $\epsilon\kappa$ $\tau\omega\nu$ $\upsilon\sigma\tau\text{έ}\rho\omega\nu$ ;
- <a id="p111534"></a>Issued retrospectively;
- <a id="p111535"></a>Délivré a posteriori;
- <a id="p111536"></a>Rilasciato a posteriori;
- <a id="p111537"></a>Afgegeven a posteriori;
- <a id="p111538"></a>Emitido a posteriori;
- <a id="p111539"></a>Annettu jälkikäteen / utfärdat i efterhand;
- <a id="p111540"></a>Utfärdat i efterhand;
- <a id="p111541"></a>Vystaveno dodateènì ;
- <a id="p111542"></a>Välja antud tagasiulatuvalt;
- <a id="p111543"></a>Izsniegts retrospektîvi ;
- <a id="p111544"></a>Retrospektyvusis išdavimas ;
- <a id="p111545"></a>Kiadva visszamenõleges hatállyal ;
- <a id="p111546"></a>$Mah - ru\dot{g}$ retrospettivament;
- <a id="p111547"></a>Wystawione retrospektywnie;
- <a id="p111548"></a>Vyhotovené dodatoène ;
- <a id="p111549"></a>издаден впоследствие;
- <a id="p111550"></a>Eliberat ulterior;
- <a id="p111551"></a>Izdano naknadno.
7. <a id="p111552"></a>Сертификаты, имеющие в верхней правой [графе](https://bukva.ai/docs/reglament-20152447/statya-350#p111554) старой версии "СЕРТИФИКАТ ПРОИСХОЖДЕНИЯ импорта сельскохозяйственной продукции в Европейское Экономическое Сообщество" и в [графе](https://bukva.ai/docs/reglament-20152447/statya-350#p111561) "Примечания" текст старой версии, могут также использоваться до тех пор, пока не иссякнут их запасы, или до 1 мая 2019 г., в зависимости от того, что наступит раньше.


<table>
<colgroup><col width="30%"><col width="20%"><col width="7%"><col width="12%"><col width="6%"><col width="25%"></colgroup>
<tr><td colspan="2" rowspan="2"><a id="p111553"></a>1. Грузоотправитель</td><td colspan="4"><a id="p111554"></a>СЕРТИФИКАТ ПРОИСХОЖДЕНИЯ<br>для импорта отдельной продукции, подлежащей специальным непреференциальным соглашениям по импорту в Европейский Союз</td></tr>
<tr><td colspan="2"><a id="p111555"></a>N</td><td colspan="2"><a id="p111556"></a>ОРИГИНАЛ</td></tr>
<tr><td colspan="2" rowspan="2"><a id="p111557"></a>2. Грузополучатель (необязательно)</td><td colspan="4"><a id="p111558"></a>3. ВЫДАЮЩИЙ ОРГАН</td></tr>
<tr><td colspan="4"><a id="p111559"></a>4. Страна происхождения</td></tr>
<tr><td colspan="2"><a id="p111560"></a>ПРИМЕЧАНИЯ<br>A. Сертификат должен быть заполнен машинописным способом или посредством системы механической обработки данных или посредством подобной процедуры.<br>B. Оригинал сертификата должен быть подан вместе с декларацией на выпуск в свободное обращение в соответствующее таможенное учреждение в Европейском Союзе.</td><td colspan="4"><a id="p111561"></a>5. Примечания</td></tr>
<tr><td colspan="5"><a id="p111562"></a>6. Номер пункта - Маркировки и номера - Количество и вид упаковки - ОПИСАНИЕ ТОВАРОВ</td><td><a id="p111563"></a>7. Масса брутто и нетто (кг)</td></tr>
<tr><td colspan="6"><a id="p111564"></a>8. НАСТОЯЩИМ УДОСТОВЕРЯЮ, ЧТО ВЫШЕНАЗВАННАЯ ПРОДУКЦИЯ ИМЕЕТ ПРОИСХОЖДЕНИЕ В СТРАНЕ, УКАЗАННОЙ В <a href="#p111559">ГРАФЕ 4</a>, И ЧТО СВЕДЕНИЯ В <a href="#p111561">ГРАФЕ 5</a> ЯВЛЯЮТСЯ ПРАВИЛЬНЫМИ.</td></tr>
<tr><td><a id="p111565"></a>Место и дата выдачи</td><td colspan="2"><a id="p111566"></a>Подпись</td><td colspan="3"><a id="p111567"></a>Печать выдающего органа</td></tr>
<tr><td colspan="6"><a id="p111568"></a>9. ДЛЯ ТАМОЖЕННЫХ ОРГАНОВ В ЕВРОПЕЙСКОМ СОЮЗЕ</td></tr>
</table>


<a id="p111569"></a>Приложение 22-15

<a id="p111570"></a>**ДЕКЛАРАЦИЯ**
**ПОСТАВЩИКА ДЛЯ ПРОДУКЦИИ, ИМЕЮЩЕЙ СТАТУС**
**ПРЕФЕРЕНЦИАЛЬНОГО ПРОИСХОЖДЕНИЯ**

<a id="p111571"></a>[Декларация](https://bukva.ai/docs/reglament-20152447/statya-350#p111572) поставщика, текст которой дан ниже, должна быть составлена в соответствии с примечаниями. Но воспроизводить примечания не нужно.

<a id="p111572"></a>**ДЕКЛАРАЦИЯ**

<a id="p111573"></a>Я, нижеподписавшийся, заявляю, что товары, указанные в настоящем документе .......... [<1>](https://bukva.ai/docs/reglament-20152447/statya-350#p111582), имеют происхождение в ........................ [<2>](https://bukva.ai/docs/reglament-20152447/statya-350#p111584) и соответствуют правилам происхождения, регулирующим преференциальную торговлю с ................. [<3>](https://bukva.ai/docs/reglament-20152447/statya-350#p111585):
<a id="p111574"></a>Я заявляю, что [<4>](https://bukva.ai/docs/reglament-20152447/statya-350#p111587):
<a id="p111575"></a> ![формула](https://i.bukva.ai/sakP7uTQ/img_18.png) Накопление применялось с .......... (название страны/стран)
<a id="p111576"></a> ![формула](https://i.bukva.ai/sakP7uTQ/img_19.png) Накопление не применялось
<a id="p111577"></a>Я обязуюсь представлять таможенным органам все дополнительные подтверждающие документы, которые они потребуют:
<a id="p111578"></a>........................................ [<5>](https://bukva.ai/docs/reglament-20152447/statya-350#p111588)
<a id="p111579"></a>......................................... [<6>](https://bukva.ai/docs/reglament-20152447/statya-350#p111589)
<a id="p111580"></a>......................................... [<7>](https://bukva.ai/docs/reglament-20152447/statya-350#p111590)

<a id="p111581"></a>

---

<a id="p111582"></a><1> Если это касается только некоторых товаров, указанных в документе, они должны быть ясно указаны или маркированы, и эта маркировка вносится в декларацию следующим образом:
<a id="p111583"></a>............... указанные в документе и маркированные ........... имеющие происхождение в ........................
<a id="p111584"></a><2> В Европейском Союзе, стране, группе стран или территории, в которых товары имеют происхождение.
<a id="p111585"></a><3> Страна, группа стран или территория. Если преференциальное происхождение продукции из страны, группы стран или территории может приобретаться в соответствии с несколькими правилами происхождения, поставщики должны определить правовые рамки, используемые для определения происхождения товаров (а именно Конвенция PEM и/или переходные правила происхождения).
<a id="p111586"></a>Если страна, группа стран или территория являются стороной Конвенции PEM и если правовые рамки не определены, по умолчанию декларация поставщика считается заявлением о том, что Конвенция PEM была использована для определения происхождения товаров.
<a id="p111587"></a><4> Заполняется при необходимости только для товаров, имеющих статус преференциального происхождения в контексте отношений преференциальной торговли с одной из стран, с которыми применяется европейско-средиземноморское накопление происхождения.
<a id="p111588"></a><5> Место и дата.
<a id="p111589"></a><6> Имя и должность в компании.
<a id="p111590"></a><7> Подпись.


<a id="p111591"></a>Приложение 22-16

<a id="p111592"></a>**ДОЛГОСРОЧНАЯ ДЕКЛАРАЦИЯ**
**ПОСТАВЩИКА ДЛЯ ПРОДУКЦИИ, ИМЕЮЩЕЙ СТАТУС**
**ПРЕФЕРЕНЦИАЛЬНОГО ПРОИСХОЖДЕНИЯ**

<a id="p111593"></a>[Декларация](https://bukva.ai/docs/reglament-20152447/statya-350#p111594) поставщика, текст которой дан ниже, должна быть составлена в соответствии с примечаниями. Но воспроизводить примечания не нужно.

<a id="p111594"></a>**ДЕКЛАРАЦИЯ**

<a id="p111595"></a>Я, нижеподписавшийся, заявляю, что товары, описанные ниже:
<a id="p111596"></a>................................................................................... [<1>](https://bukva.ai/docs/reglament-20152447/statya-350#p111608)
<a id="p111597"></a>................................................................................... [<2>](https://bukva.ai/docs/reglament-20152447/statya-350#p111609)
<a id="p111598"></a>которые регулярно поставляются ................... [<3>](https://bukva.ai/docs/reglament-20152447/statya-350#p111610), имеют происхождение в ........................ [<4>](https://bukva.ai/docs/reglament-20152447/statya-350#p111611) и соответствуют правилам происхождения, регулирующим преференциальную торговлю с ................. [<5>](https://bukva.ai/docs/reglament-20152447/statya-350#p111612):
<a id="p111599"></a>Я заявляю, что [<6>](https://bukva.ai/docs/reglament-20152447/statya-350#p111614):
<a id="p111600"></a> ![формула](https://i.bukva.ai/sakP7uTQ/img_20.png) Накопление применялось с .......... (название страны/стран)
<a id="p111601"></a> ![формула](https://i.bukva.ai/sakP7uTQ/img_21.png) Накопление не применялось
<a id="p111602"></a>Данная декларация действует для всех отгрузок данной продукции, отправляемой с ............................ по ................................ [<7>](https://bukva.ai/docs/reglament-20152447/statya-350#p111615).
<a id="p111603"></a>Я обязуюсь представлять таможенным органам все дополнительные подтверждающие документы, которые они потребуют:
<a id="p111604"></a>......................................... [<8>](https://bukva.ai/docs/reglament-20152447/statya-350#p111616)
<a id="p111605"></a>......................................... [<9>](https://bukva.ai/docs/reglament-20152447/statya-350#p111617)
<a id="p111606"></a>......................................... [<10>](https://bukva.ai/docs/reglament-20152447/statya-350#p111618)

<a id="p111607"></a>

---

<a id="p111608"></a><1> Описание.
<a id="p111609"></a><2> Коммерческое обозначение, используемое в инвойсах, например образец N.
<a id="p111610"></a><3> Название компании, в которую поставляются товары.
<a id="p111611"></a><4> В Европейском Союзе, стране, группе стран или территории, в которых товары имеют происхождение.
<a id="p111612"></a><5> Страна, группа стран или территория. Если преференциальное происхождение продукции из страны, группы стран или территории может приобретаться в соответствии с несколькими правилами происхождения, поставщики должны определить правовые рамки, используемые для определения происхождения товаров (а именно Конвенция PEM и/или переходные правила происхождения).
<a id="p111613"></a>Если страна, группа стран или территория являются стороной Конвенции PEM и если правовые рамки не определены, по умолчанию декларация поставщика считается заявлением о том, что Конвенция PEM была использована для определения происхождения товаров.
<a id="p111614"></a><6> Заполняется при необходимости только для товаров, имеющих статус преференциального происхождения в контексте отношений преференциальной торговли с одной из стран, с которыми применяется европейско-средиземноморское накопление происхождения.
<a id="p111615"></a><7> Указать начальную и конечную даты. Срок не должен превышать 24 месяца.
<a id="p111616"></a><8> Место и дата выдачи.
<a id="p111617"></a><9> Имя и должность в компании.
<a id="p111618"></a><10> Подпись.


<a id="p111619"></a>Приложение 22-17

<a id="p111620"></a>**ДЕКЛАРАЦИЯ**
**ПОСТАВЩИКА ДЛЯ ПРОДУКЦИИ, НЕ ИМЕЮЩЕЙ СТАТУС**
**ПРЕФЕРЕНЦИАЛЬНОГО ПРОИСХОЖДЕНИЯ**

<a id="p111621"></a>[Декларация](https://bukva.ai/docs/reglament-20152447/statya-350#p111622) поставщика, текст которой дан ниже, должна быть составлена в соответствии с примечаниями. Но воспроизводить примечания не нужно.

<a id="p111622"></a>**ДЕКЛАРАЦИЯ**

<a id="p111623"></a>Я, нижеподписавшийся, поставщик товаров, на который распространяется прилагающийся документ, заявляю, что:
1. <a id="p111624"></a>Следующие материалы, которые не имеют преференциального статуса происхождения, были использованы в Европейском Союзе для производства этих товаров:


| <a id="p111625"></a>Описание поставленных товаров [<1>](https://bukva.ai/docs/reglament-20152447/statya-350#p111639) | <a id="p111626"></a>Описание использованных материалов, не имеющих происхождения | <a id="p111627"></a>Заголовок HS использованных материалов, не имеющих происхождения [<2>](https://bukva.ai/docs/reglament-20152447/statya-350#p111642) | <a id="p111628"></a>Стоимость использованных материалов, не имеющих происхождения [<3>](https://bukva.ai/docs/reglament-20152447/statya-350#p111646) |
| --- | --- | --- | --- |
|  |  |  |  |
|  |  |  |  |
|  |  |  | <a id="p111629"></a>Итого: |


2. <a id="p111630"></a>Все материалы, использованные в Европейском Союзе для производства данных товаров, имеют происхождение в ........................ [<4>](https://bukva.ai/docs/reglament-20152447/statya-350#p111648) и соответствуют правилам происхождения, регулирующим преференциальную торговлю с ................. [<5>](https://bukva.ai/docs/reglament-20152447/statya-350#p111649), и
<a id="p111631"></a>Я заявляю, что [<6>](https://bukva.ai/docs/reglament-20152447/statya-350#p111651):
<a id="p111632"></a> ![формула](https://i.bukva.ai/sakP7uTQ/img_22.png) Накопление применялось с .......... (название страны/стран)
<a id="p111633"></a> ![формула](https://i.bukva.ai/sakP7uTQ/img_23.png) Накопление не применялось
<a id="p111634"></a>Я обязуюсь представлять таможенным органам все дополнительные подтверждающие документы, которые они потребуют:
<a id="p111635"></a>......................................... [<7>](https://bukva.ai/docs/reglament-20152447/statya-350#p111652)
<a id="p111636"></a>......................................... [<8>](https://bukva.ai/docs/reglament-20152447/statya-350#p111653)
<a id="p111637"></a>......................................... [<9>](https://bukva.ai/docs/reglament-20152447/statya-350#p111654)

<a id="p111638"></a>

---

<a id="p111639"></a><1> Если инвойс, накладная или другой коммерческий документ, к которому настоящая декларация прилагается, относится к множеству товаров или к товарам, не включающим одинаковую часть материалов, не имеющих происхождения, то поставщик должен ясно дифференцировать их.
<a id="p111640"></a>Пример:
<a id="p111641"></a>Документ распространяется на различные модели электрических двигателей под заголовком 8501, используемых в производстве стиральных машин под заголовком 8450. Характер и стоимость материалов, не имеющих происхождения, использованных в производстве двигателей, отличаются от одной модели к другой. Модели должны быть указаны отдельно в [колонке 1](https://bukva.ai/docs/reglament-20152447/statya-350#p111625), а информация в других колонках должна быть дана для каждой модели, с тем чтобы производители стиральных машин могли правильно оценить статус происхождения каждого вида своей продукции в зависимости от вида двигателя, который они включают в себя.
<a id="p111642"></a><2> Заполняется только при необходимости.
<a id="p111643"></a>Пример:
<a id="p111644"></a>Правила для одежды ex Главы 62 разрешают использовать пряжу, не имеющую происхождения. Таким образом, если французский производитель одежды использует ткань в Португалии из пряжи, не имеющей происхождения, то португальский поставщик должен внести только "пряжу" в качестве материала, не имеющего происхождения, в [колонку 2](https://bukva.ai/docs/reglament-20152447/statya-350#p111626) его декларации - заголовок HS и стоимость пряжи несущественны.
<a id="p111645"></a>Фирма, производящая проволоку под заголовком HS 7217 из железного прутка, не имеющего происхождения, вносит "железный пруток" в [колонку 2](https://bukva.ai/docs/reglament-20152447/statya-350#p111626), если проволока должна быть включена в машину, для которой правило происхождения устанавливает ограничение в процентах на стоимость использованных материалов, не имеющих происхождения, то стоимость прутка должна быть внесена в [колонку 4](https://bukva.ai/docs/reglament-20152447/statya-350#p111628).
<a id="p111646"></a><3> "Стоимость" - таможенная стоимость материалов во время импорта или, если она не известна или ее нельзя установить, первая установленная цена, выплаченная за материалы в Европейском Союзе.
<a id="p111647"></a>Для каждого вида использованных материалов, не имеющих происхождения, определите точную стоимость на единицу товаров, показанных в [колонке 1](https://bukva.ai/docs/reglament-20152447/statya-350#p111625).
<a id="p111648"></a><4> Заполняется только при необходимости. Европейский Союз, страна, группа стран или территория, в которых материалы имеют происхождение.
<a id="p111649"></a><5> Заполняется только при необходимости. Страна, группа стран или территория. Если преференциальное происхождение продукции из страны, группы стран или территории может быть приобретено в соответствии с несколькими правилами происхождения, поставщики должны определить правовые рамки, используемые для определения происхождения товаров (а именно Конвенцию PEM и/или переходные правила происхождения).
<a id="p111650"></a>Если страна, группа стран или территория являются стороной Конвенции PEM и если правовые рамки не определены, то по умолчанию декларация поставщика считается относящейся к тому, что Конвенция PEM была использована для определения происхождения товаров.
<a id="p111651"></a><6> Заполняется при необходимости только для товаров, имеющих статус преференциального происхождения в контексте отношений преференциальной торговли с одной из стран, с которыми применяется европейско-средиземноморское накопление происхождения.
<a id="p111652"></a><7> Место и дата.
<a id="p111653"></a><8> Имя и должность в компании.
<a id="p111654"></a><9> Подпись.


<a id="p111655"></a>Приложение 22-18

<a id="p111656"></a>**ДОЛГОСРОЧНАЯ ДЕКЛАРАЦИЯ**
**ПОСТАВЩИКА ДЛЯ ПРОДУКЦИИ, НЕ ИМЕЮЩЕЙ СТАТУС**
**ПРЕФЕРЕНЦИАЛЬНОГО ПРОИСХОЖДЕНИЯ**

<a id="p111657"></a>[Декларация](https://bukva.ai/docs/reglament-20152447/statya-350#p111658) поставщика, текст которой дан ниже, должна быть составлена в соответствии с примечаниями. Но воспроизводить примечания не нужно.

<a id="p111658"></a>**ДЕКЛАРАЦИЯ**

<a id="p111659"></a>Я, нижеподписавшийся, поставщик товаров, на который распространяется прилагающийся документ, которые регулярно направляются ....................... [<1>](https://bukva.ai/docs/reglament-20152447/statya-350#p111676), заявляю, что:
1. <a id="p111660"></a>Следующие материалы, которые не имеют преференциального статуса происхождения, были использованы в Европейском Союзе для производства этих товаров:


| <a id="p111661"></a>Описание поставленных товаров [<2>](https://bukva.ai/docs/reglament-20152447/statya-350#p111677) | <a id="p111662"></a>Описание использованных материалов, не имеющих происхождения | <a id="p111663"></a>Заголовок HS использованных материалов, не имеющих происхождения [<3>](https://bukva.ai/docs/reglament-20152447/statya-350#p111680) | <a id="p111664"></a>Стоимость использованных материалов, не имеющих происхождения [<4>](https://bukva.ai/docs/reglament-20152447/statya-350#p111684) |
| --- | --- | --- | --- |
|  |  |  |  |
|  |  |  |  |
|  |  |  | <a id="p111665"></a>Итого: |


2. <a id="p111666"></a>Все материалы, использованные в Европейском Союзе для производства данных товаров, имеют происхождение в ........................ [<5>](https://bukva.ai/docs/reglament-20152447/statya-350#p111686) и соответствуют правилам происхождения, регулирующим преференциальную торговлю с ................. [<6>](https://bukva.ai/docs/reglament-20152447/statya-350#p111687), и
<a id="p111667"></a>Я заявляю, что [<7>](https://bukva.ai/docs/reglament-20152447/statya-350#p111689):
<a id="p111668"></a> ![формула](https://i.bukva.ai/sakP7uTQ/img_24.png) Накопление применялось с .......... (название страны/стран)
<a id="p111669"></a> ![формула](https://i.bukva.ai/sakP7uTQ/img_25.png) Накопление не применялось
<a id="p111670"></a>Данная декларация действует для всех отгрузок данной продукции, отправляемой с ............................ по ................................ [<8>](https://bukva.ai/docs/reglament-20152447/statya-350#p111690).
<a id="p111671"></a>Я обязуюсь представлять таможенным органам все дополнительные подтверждающие документы, которые они потребуют:
<a id="p111672"></a>......................................... [<9>](https://bukva.ai/docs/reglament-20152447/statya-350#p111691)
<a id="p111673"></a>......................................... [<10>](https://bukva.ai/docs/reglament-20152447/statya-350#p111692)
<a id="p111674"></a>......................................... [<11>](https://bukva.ai/docs/reglament-20152447/statya-350#p111693)

<a id="p111675"></a>

---

<a id="p111676"></a><1> Имя/наименование потребителя.
<a id="p111677"></a><2> Если инвойс, накладная или другой коммерческий документ, к которому настоящая декларация прилагается, относится к множеству товаров или к товарам, не включающим одинаковую часть материалов, не имеющих происхождение, то поставщик должен ясно дифференцировать их.
<a id="p111678"></a>Пример:
<a id="p111679"></a>Документ распространяется на различные модели электрических двигателей под заголовком 8501, используемых в производстве стиральных машин под заголовком 8450. Характер и стоимость материалов, не имеющих происхождения, использованных в производстве двигателей, отличаются от одной модели к другой. Модели должны быть указаны отдельно в [колонке 1](https://bukva.ai/docs/reglament-20152447/statya-350#p111661), а информация в других колонках должна быть дана для каждой модели, с тем чтобы производители стиральных машин могли правильно оценить статус происхождения каждого вида своей продукции в зависимости от вида двигателя, который они включают в себя.
<a id="p111680"></a><3> Заполняется только при необходимости.
<a id="p111681"></a>Пример:
<a id="p111682"></a>Правила для одежды ex Главы 62 разрешают использовать пряжу, не имеющую происхождения. Таким образом, если французский производитель одежды использует ткань в Португалии из пряжи, не имеющей происхождения, то португальский поставщик должен внести только "пряжу" в качестве материала, не имеющего происхождения, в [колонку 2](https://bukva.ai/docs/reglament-20152447/statya-350#p111662) его декларации - заголовок HS и стоимость пряжи несущественны.
<a id="p111683"></a>Фирма, производящая проволоку под заголовком HS 7217 из железного прутка, не имеющего происхождения, вносит "железный пруток" в [колонку 2](https://bukva.ai/docs/reglament-20152447/statya-350#p111662), если проволока должна быть включена в машину, для которой правило происхождения устанавливает ограничение в процентах на стоимость использованных материалов, не имеющих происхождения, то стоимость прутка должна быть внесена в [колонку 4](https://bukva.ai/docs/reglament-20152447/statya-350#p111664).
<a id="p111684"></a><4> "Стоимость" - таможенная стоимость материалов во время импорта или, если она не известна или ее нельзя установить, первая установленная цена, выплаченная за материалы в Европейском Союзе.
<a id="p111685"></a>Для каждого вида использованных материалов, не имеющих происхождения, определите точную стоимость на единицу товаров, показанных в [колонке 1](https://bukva.ai/docs/reglament-20152447/statya-350#p111661).
<a id="p111686"></a><5> Заполняется только при необходимости. Союз, страна, группа стран или территория, в которых материалы имеют происхождение.
<a id="p111687"></a><6> Заполняется только при необходимости. Страна, группа стран или территория. Если преференциальное происхождение продукции из страны, группы стран или территории может быть приобретено в соответствии с несколькими правилами происхождения, поставщики должны определить правовые рамки, используемые для определения происхождения товаров (а именно Конвенцию PEM и/или переходные правила происхождения).
<a id="p111688"></a>Если страна, группа стран или территория являются стороной Конвенции PEM и если правовые рамки не определены, то по умолчанию декларация поставщика считается относящейся к тому, что Конвенция PEM была использована для определения происхождения товаров.
<a id="p111689"></a><7> Заполняется при необходимости только для товаров, имеющих статус преференциального происхождения в контексте отношений преференциальной торговли с одной из стран, с которыми применяется европейско-средиземноморское накопление происхождения.
<a id="p111690"></a><8> Указать даты начала и окончания. Срок не должен превышать 24 месяцев.
<a id="p111691"></a><9> Место и дата.
<a id="p111692"></a><10> Имя и должность в компании.
<a id="p111693"></a><11> Подпись.


<a id="p111694"></a>Приложение 22-19

<a id="p111695"></a>**ТРЕБОВАНИЯ**
**ДЛЯ СОСТАВЛЕНИЯ ЗАМЕНЯЮЩИХ СЕРТИФИКАТОВ ПРОИСХОЖДЕНИЯ**
**ФОРМЫ A**

1. <a id="p111696"></a>Верхняя правая [графа](https://bukva.ai/docs/reglament-20152447/statya-350#p111297) заменяющего сертификата происхождения ФОРМЫ A (заменяющий сертификат) указывает название посреднической страны, в которой он выдан.
2. <a id="p111697"></a>[Графа 4](https://bukva.ai/docs/reglament-20152447/statya-350#p111301) заменяющего сертификата содержит слова "Заменяющий сертификат" ("Replacement certificate" или "Certificat de remplacement"), а также дату выдачи первоначального доказательства происхождения и его серийный номер.
3. <a id="p111698"></a>Имя/наименование реэкспортера указывается в [графе 1](https://bukva.ai/docs/reglament-20152447/statya-350#p111295) заменяющего сертификата.
4. <a id="p111699"></a>Имя/наименование окончательного грузополучателя может быть дано в [графе 2](https://bukva.ai/docs/reglament-20152447/statya-350#p111298) заменяющего сертификата.
5. <a id="p111700"></a>Все сведения о реэкспортированной продукции, указанные в первоначальном доказательстве происхождения, переводятся в [графы 3](https://bukva.ai/docs/reglament-20152447/statya-350#p111300) - [9](https://bukva.ai/docs/reglament-20152447/statya-350#p111306) заменяющего сертификата, а ссылки на инвойс реэкспортера могут быть даны в [графе 10](https://bukva.ai/docs/reglament-20152447/statya-350#p111307) заменяющего сертификата.
6. <a id="p111701"></a>Удостоверение, выполненное таможенным учреждением, выдающим заменяющий сертификат, размещается в [графе 11](https://bukva.ai/docs/reglament-20152447/statya-350#p111308) заменяющего сертификата.
7. <a id="p111702"></a>Сведения в [графе 12](https://bukva.ai/docs/reglament-20152447/statya-350#p111309) заменяющего сертификата, касающиеся страны происхождения, должны быть идентичны тем сведениям, которые указаны в первоначальном доказательстве происхождения. Данная [графа](https://bukva.ai/docs/reglament-20152447/statya-350#p111309) должна быть подписана реэкспортером.


<a id="p111703"></a>Приложение 22-20

<a id="p111704"></a>**ТРЕБОВАНИЯ**
**ДЛЯ СОСТАВЛЕНИЯ ЗАМЕНЯЮЩИХ ЗАЯВЛЕНИЙ О ПРОИСХОЖДЕНИЯ**

1. <a id="p111705"></a>Если заменяется [заявление](https://bukva.ai/docs/reglament-20152447/statya-350#p111265) о происхождении, грузоотправитель, перенаправляющий товары, указывает следующее в первоначальном заявлении о происхождении:
<a id="p111706"></a>(a) сведения заменяющего(их) заявления(й);
<a id="p111707"></a>(b) свое имя/название и адрес;
<a id="p111708"></a>(c) грузополучатель или грузополучатели в Союзе или, если применяется, в Норвегии или Швейцарии.
2. <a id="p111709"></a>На первоначальном [заявлении](https://bukva.ai/docs/reglament-20152447/statya-350#p111265) о происхождении должна быть отметка "Заменено" ("Replaced", "Remplacee" или "Sustituida").
3. <a id="p111710"></a>Грузоотправитель, перенаправляющий товары, указывает следующее в заменяющем заявлении о происхождении:
<a id="p111711"></a>(a) все сведения о перенаправленной продукции, взятые из первоначального доказательства;
<a id="p111712"></a>(b) дата, на которую было составлено первоначальное [заявление](https://bukva.ai/docs/reglament-20152447/statya-350#p111265) о происхождении;
<a id="p111713"></a>(c) сведения первоначального заявления о происхождении, установленные в [Приложении 22-07](https://bukva.ai/docs/reglament-20152447/statya-350#p111265), в том числе при необходимости информация о применяемом накоплении;
<a id="p111714"></a>(d) свое имя/название и адрес и, если применяется, свой номер зарегистрированного экспортера;
<a id="p111715"></a>(e) имя/название и адрес грузополучателя или грузополучателей в Союзе или, если применяется, в Норвегии или Швейцарии;
<a id="p111716"></a>(f) дата и место замены.
4. <a id="p111717"></a>На заменяющем заявлении о происхождении должна быть отметка "Заменяющее заявление" ("Replacement statement", "Attestation de remplacement" или " Comunicación de sustitución ").


<a id="p111718"></a>Приложение 23-01

<a id="p111719"></a>**ВОЗДУШНЫЕ ТРАНСПОРТНЫЕ ЗАТРАТЫ,**
**ВКЛЮЧАЕМЫЕ В ТАМОЖЕННУЮ СТОИМОСТЬ**

1. <a id="p111720"></a>Следующая [таблица](https://bukva.ai/docs/reglament-20152447/statya-350#p111729) показывает:
<a id="p111721"></a>(a) третьи страны, показанные по континентам и зонам [(колонка 1)](https://bukva.ai/docs/reglament-20152447/statya-350#p111729);
<a id="p111722"></a>(b) проценты, которые представляют часть воздушных транспортных затрат, включаемых в таможенную стоимость [(колонка 2)](https://bukva.ai/docs/reglament-20152447/statya-350#p111730).
2. <a id="p111723"></a>Если товары отгружаются из других стран или аэропортов, не включенных в следующую таблицу, кроме аэропортов, указанных в [параграфе 3](https://bukva.ai/docs/reglament-20152447/statya-350#p111724), берутся проценты, данные для ближайшего аэропорта к месту отправления.
3. <a id="p111724"></a>Что касается французских заморских департаментов, которые являются частью таможенной территории Союза, применяются следующие правила:
<a id="p111725"></a>(a) для товаров, отгруженных непосредственно из третьей страны в эти департаменты, все воздушные транспортные затраты полностью включаются в таможенную стоимость;
<a id="p111726"></a>(b) для товаров, отгруженных из третьих стран в европейскую часть Союза после перегрузки или разгрузки в одном из этих департаментов, в таможенную стоимость включается только те воздушные транспортные затраты, которые могли быть понесены, если товары были направлены в эти департаменты;
<a id="p111727"></a>(c) для товаров, отгруженных из третьих стран в эти департаменты после перегрузки или разгрузки в аэропорту в европейской части Союза, в таможенную стоимость включаются воздушные транспортные расходы, полученные в результате применения процентов, данных в следующей [таблице](https://bukva.ai/docs/reglament-20152447/statya-350#p111729) с учетом рейса из аэропорта отправления в аэропорт перегрузки или разгрузки.
<a id="p111728"></a>Перегрузка или разгрузка удостоверяется соответствующей надписью таможенных органов на воздушной накладной или на другом воздушном транспортном документе. Если такого удостоверения нет, применяется [Статья 137](https://bukva.ai/docs/reglament-20152447/statya-137#p101321).


| <a id="p111729"></a>1 | <a id="p111730"></a>2 |
| --- | --- |
| <a id="p111731"></a>Страна отправления | <a id="p111732"></a>Проценты общих затрат воздушной перевозки, включаемые в таможенную стоимость |
| <a id="p111733"></a>Америка |  |
| <a id="p111734"></a>Зона A<br>Канада: Гандер, Галифакс, Монктон, Монреаль, Оттава, Квебек, Торонто<br>Соединенные Штаты Америки: Акрон, Олбани, Атланта, Балтимор, Бостон, Буффало, Чарльстон, Чикаго, Цинциннати, Коламбус, Детройт, Индианаполис, Джэксонвилл, Канзас-Сити, Лексингтон, Луисвилл, Мемфис, Милуоки, Миннеаполис, Нэшвилл, Новый Орлеан, Нью-Йорк, Филадельфия, Питтсбург, Сент-Луис, Вашингтон округ Колумбия | <a id="p111735"></a>70 |
| <a id="p111736"></a>Зона B<br>Канада: Эдмонтон, Ванкувер, Виннипег<br>Соединенные Штаты Америки: Альбукерк, Остин, Биллингс, Даллас, Денвер, Хьюстон, Лас-Вегас, Лос-Анджелес, Майами, Оклахома, Финикс, Портленд, Пуэрто-Рико, Солт-Лейк-Сити, Сан-Франциско, Сиэтл<br>Центральная Америка: все страны<br>Южная Америка: все страны | <a id="p111737"></a>78 |
| <a id="p111738"></a>Зона C<br>Соединенные Штаты Америки: Анкоридж, Фербенкс, Гонолулу, Джуно | <a id="p111739"></a>89 |
| <a id="p111740"></a>Африка |  |
| <a id="p111741"></a>Зона D<br>Алжир, Египет, Ливия, Марокко, Тунис | <a id="p111742"></a>33 |
| <a id="p111743"></a>Зона E<br>Бенин, Буркина Фасо, Камерун, Кабо-Верде, Центральная Африканская Республика, Чад, Кот-д'Ивуар, Джибути, Эфиопия, Гамбия, Гана, Гвинея, Гвинея-Биссау, Либерия, Мали, Мавритания, Нигер, Нигерия, Сенегал, Сьерра Леоне, Судан, Того | <a id="p111744"></a>50 |
| <a id="p111745"></a>Зона F<br>Бурунди, Демократическая Республика Конго, Конго, Экваториальная Гвинея, Габон, Кения, Руанда, Сан Томе и Принсипи, Сейшелы, Сомали, Св. Елена, Танзания, Уганда | <a id="p111746"></a>61 |
| <a id="p111747"></a>Зона G<br>Ангола, Ботсвана, Коморские острова, Лесото, Мадагаскар, Малави, Маврикий, Мозамбик, Намибия, Южно-Африканская Республика, Свазиленд, Замбия, Зимбабве | <a id="p111748"></a>74 |
| <a id="p111749"></a>Азия |  |
| <a id="p111750"></a>Зона H<br>Армения, Азербайджан, Грузия, Иран, Ирак, Израиль, Иордания, Кувейт, Ливан, Сирия | <a id="p111751"></a>27 |
| <a id="p111752"></a>Зона I<br>Бахрейн, Маскат и Оман, Катар, Саудовская Аравия, Объединенные Арабские Эмираты, Йемен | <a id="p111753"></a>43 |
| <a id="p111754"></a>Зона J<br>Афганистан, Бангладеш, Бутан, Индия, Непал, Пакистан | <a id="p111755"></a>46 |
| <a id="p111756"></a>Зона K<br>Россия: Новосибирск, Омск, Пермь, Свердловск<br>Казахстан, Киргизстан, Таджикистан, Туркменистан, Узбекистан | <a id="p111757"></a>57 |
| <a id="p111758"></a>Зона L<br>Россия: Иркутск, Киренск, Красноярск<br>Бруней, Китай, Индонезия, Гонконг, Кампучия, Лаос, Макао, Малайзия, Мальдивы, Монголия, Мьянма, Филиппины, Сингапур, Шри-Ланка, Тайвань, Таиланд, Вьетнам | <a id="p111759"></a>70 |
| <a id="p111760"></a>Зона M<br>Россия: Хабаровск, Владивосток<br>Япония, Корея (Северная), Корея (Южная) | <a id="p111761"></a>83 |
| <a id="p111762"></a>Австралия и Океания |  |
| <a id="p111763"></a>Зона N<br>Австралия и Океания: все страны | <a id="p111764"></a>79 |
| <a id="p111765"></a>Европа |  |
| <a id="p111766"></a>Зона O<br>Россия: Горький, Самара, Москва, Орел, Ростов, Волгоград, Воронеж<br>Исландия, Украина | <a id="p111767"></a>30 |
| <a id="p111768"></a>Зона P<br>Албания, Белоруссия, Босния и Герцеговина, Фарерские Острова, Косово, Молдова, Черногория, Северная Македония, Норвегия, Сербия, Турция | <a id="p111769"></a>15 |
| <a id="p111770"></a>Зона Q<br>Швейцария, Соединенное Королевство, за исключением Северной Ирландии | <a id="p111771"></a>5 |


<a id="p111772"></a>Приложение 23-02

<a id="p111773"></a>**СПИСОК**
**ТОВАРОВ, УКАЗАННЫХ В СТАТЬЕ 142(6)**

<a id="p111774"></a>Оценка отдельных скоропортящихся товаров, импортированных
по коносаменту в соответствии со [Статьей 74(2)(c)](https://bukva.ai/docs/reglament-9522013/statya-1#p100775) Кодекса

1. <a id="p111775"></a>Следующая [таблица](https://bukva.ai/docs/reglament-20152447/statya-350#p111791) показывает список продукции и соответствующие сроки, для которых Европейская Комиссия обнародует цену за единицу продукции, используемую в качестве основания для определения таможенной стоимости только целых фруктов и овощей одного вида, импортированных по коносаменту. В таком случае таможенная декларация является окончательной, насколько это касается определения таможенной стоимости.
2. <a id="p111776"></a>В целях определения таможенной стоимости продукции, указанной в настоящем приложении, и импортированной по коносаменту, цена за единицу на 100 кг нетто устанавливается для каждого вида продукции. Такая цена считается репрезентативной в отношении импорта такой продукции в Союз.
3. <a id="p111777"></a>Цены за единицу продукции используются для определения таможенной стоимости импортированных товаров на срок 14 дней, каждый период начинается с пятницы. Исходным периодом для определения цен за единицу является предыдущий срок 14 дней, заканчивающийся в четверг предыдущей недели, в течение которой должны быть установлены новые цены за единицу. При особых обстоятельствах Европейская Комиссия может принять решение о продлении срока на срок действия дополнительно 14 дней. Государства-члены ЕС срочно информируются о таких решениях.
4. <a id="p111778"></a>Цены за единицу продукции, которые государства-члены ЕС предоставляют Европейской Комиссии, должны рассчитываться на основании валовых поступлений от продаж, указанных на первом коммерческом уровне после импорта, и вычета следующих элементов из этих данных:
- <a id="p111779"></a>маркетинговая маржа для маркетинговых центров;
- <a id="p111780"></a>затраты на перевозку, страхование и связанные с ними затраты в пределах таможенной территории;
- <a id="p111781"></a>импортные пошлины и другие сборы, которые не включаются в таможенную стоимость.
<a id="p111782"></a>Цены за единицу продукции сообщается в евро. Если применяется, то используется курс валют, определенный в [Статье 146](https://bukva.ai/docs/reglament-20152447/statya-146#p101396).
5. <a id="p111783"></a>Государства-члены ЕС могут установить стандартные суммы для вычета в отношении транспортных затрат, затрат на страхование и затрат, связанных в ними, в соответствии с [пунктом 4](https://bukva.ai/docs/reglament-20152447/statya-350#p111778). Эти стандартные суммы и методы их расчета должны быть представлены Европейской Комиссии.
6. <a id="p111784"></a>Цены сообщаются Европейской Комиссии (DG TAXUD) не позднее 12 часов по полудню в понедельник той недели, в которой обнародуются цены за единицу продукции Если этот день является нерабочим, то сообщение выполняется в рабочий день, предшествующий этому дню. Сообщение Европейской Комиссии включает в себя также указание примерного количества продукции, для которой были рассчитаны цены за единицу.
7. <a id="p111785"></a>После получения Европейской Комиссией цен за единицу эти данные пересматриваются и впоследствии распространяются через TARIC. Цены за единицу продукции применяются, только если они распространены Европейской Комиссией.
8. <a id="p111786"></a>Европейская Комиссия может принять решение не принимать и впоследствии не распространять цены за единицу продукции для одного или нескольких видов продукции, если указанные цены могут существенно отличаться от цен, ранее опубликованных, с учетом, в частности, таких факторов, как количество и сезонность. При необходимости Европейская Комиссия делает запросы в соответствующие таможенные органы для разрешения этих случаев.
9. <a id="p111787"></a>Для содействия этому процессу государства-члены ЕС предоставляют ежегодную статистику по импорту для продукции, указанной в следующей [таблице](https://bukva.ai/docs/reglament-20152447/statya-350#p111791), до 30 сентября текущего года со ссылкой на предыдущий год. Эта статистика должна касаться общего импортированного количества каждого вида продукции, а также указывает распределение импортированной продукции по партиям.
10. <a id="p111788"></a>Основываясь на этой статистике, Европейская Комиссия устанавливает, какие государства-члены ЕС отвечают за уведомление о ценах за единицу по каждому виду продукции на следующий год, информируя их не позднее 30 ноября.

<a id="p111789"></a>**СПИСОК ТОВАРОВ, УКАЗАННЫХ В СТАТЬЕ 142(6)**

<a id="p111790"></a>Описание товаров в настоящей [таблице](https://bukva.ai/docs/reglament-20152447/statya-350#p111791) имеет исключительно показательное значение и действует без ущерба правилам интерпретации Объединенной номенклатуры. В целях настоящего Приложения сфера соглашений, указанных в [Статье 142(6)](https://bukva.ai/docs/reglament-20152447/statya-142#p101368), должна быть определена сферой кодов ОН, существовавших во время принятия настоящего Регламента.


| <a id="p111791"></a>Код CN (TARIC) | <a id="p111792"></a>Описание товаров | <a id="p111793"></a>Срок действия |
| --- | --- | --- |
| <a id="p111794"></a>0701 90 50 | <a id="p111795"></a>Молодой картофель | <a id="p111796"></a>1.1. - 30.6. |
| <a id="p111797"></a>0703 10 19 | <a id="p111798"></a>Лук (кроме сеток) | <a id="p111799"></a>1.1. - 31.12. |
| <a id="p111800"></a>0703 20 00 | <a id="p111801"></a>Чеснок | <a id="p111802"></a>1.1. - 31.12 |
| <a id="p111803"></a>0708 20 00 | <a id="p111804"></a>Бобы (Vigna spp., Phaseolus spp.) | <a id="p111805"></a>1.1. - 31.12 |
| <a id="p111806"></a>0709 20 00 10 | <a id="p111807"></a>Спаржа:<br>- зеленая | <a id="p111808"></a>1.1. - 31.12 |
| <a id="p111809"></a>0709 20 00 90 | <a id="p111810"></a>Спаржа:<br>- другая | <a id="p111811"></a>1.1. - 31.12 |
| <a id="p111812"></a>0709 60 10 | <a id="p111813"></a>Сладкий перец | <a id="p111814"></a>1.1. - 31.12 |
| <a id="p111815"></a>0714 20 10 | <a id="p111816"></a>Сладкий картофель, свежий, целый, предназначенный для употребления в пищу | <a id="p111817"></a>1.1. - 31.12 |
| <a id="p111818"></a>0804 30 00 90 | <a id="p111819"></a>Ананасы<br>- кроме сушеных | <a id="p111820"></a>1.1. - 31.12 |
| <a id="p111821"></a>0804 40 00 10 | <a id="p111822"></a>Авокадо<br>- свежие | <a id="p111823"></a>1.1. - 31.12 |
| <a id="p111824"></a>0805 10 22<br>0805 10 24<br>0805 10 28 | <a id="p111825"></a>Сладкие апельсины, свежие | <a id="p111826"></a>1.6. - 30.11 |
| <a id="p111827"></a>0805 21 10 10<br>0805 21 90 11<br>0805 21 90 91 | <a id="p111828"></a>Мандарины (в том числе танжерины сатсумы), свежие | <a id="p111829"></a>1.3. - 31.10 |
| <a id="p111830"></a>0805 22 00 11 | <a id="p111831"></a>Монреаль, свежий | <a id="p111832"></a>1.3. - 31.10. |
| <a id="p111833"></a>0805 22 00 20 | <a id="p111834"></a>Клементины (кроме монреали), свежие | <a id="p111835"></a>1.3. - 31.10. |
| <a id="p111836"></a>0805 29 00 11<br>0805 29 00 21<br>0805 29 00 91 | <a id="p111837"></a>Вилкинги и подобные цитрусовые гибриды, свежие | <a id="p111838"></a>1.3. - 31.10. |
| <a id="p111839"></a>0805 40 00 11<br>0805 40 00 31 | <a id="p111840"></a>Грейпфрут, в том числе помело, свежие, белые | <a id="p111841"></a>1.1. - 31.12 |
| <a id="p111842"></a>0805 40 00 19<br>0805 40 00 39 | <a id="p111843"></a>Грейпфрут, в том числе помело, свежие, розовые | <a id="p111844"></a>1.1. - 31.12 |
| <a id="p111845"></a>0805 50 90 11 | <a id="p111846"></a>Лаймы (Cirtus aurantifolia, Citrus latifolia)<br>- свежие | <a id="p111847"></a>1.1. - 31.12 |
| <a id="p111848"></a>0806 10 10 | <a id="p111849"></a>Столовый виноград | <a id="p111850"></a>21.11. - 20.07 |
| <a id="p111851"></a>0807 11 00 | <a id="p111852"></a>Арбузы | <a id="p111853"></a>1.1. - 31.12 |
| <a id="p111854"></a>0807 19 00 50 | <a id="p111855"></a>Дыни amarillo, cuper, honey dew (включая Cantalene), Onteniente, Piel de Sapo, (включая Verde Liso), Rochet, Tendral, Futuro | <a id="p111856"></a>1.1. - 31.12 |
| <a id="p111857"></a>0807 19 00 90 | <a id="p111858"></a>Другие дыни | <a id="p111859"></a>1.1. - 31.12 |
| <a id="p111860"></a>0808 30 90 10 | <a id="p111861"></a>Груши сорт Nashi (Pyrus pyrifolia), Ya (Pyrus bretscheideri) | <a id="p111862"></a>1.5. - 30.6. |
| <a id="p111863"></a>0808 30 90 90 | <a id="p111864"></a>Груши, другие | <a id="p111865"></a>1.5. - 30.6. |
| <a id="p111866"></a>0809 10 00 | <a id="p111867"></a>Абрикосы | <a id="p111868"></a>1.1. - 31.5<br>1.8. - 31.12 |
| <a id="p111869"></a>0809 30 10 | <a id="p111870"></a>Нектарины | <a id="p111871"></a>1.1. - 10.6.<br>1.10. - 31.12. |
| <a id="p111872"></a>0809 30 90 | <a id="p111873"></a>Персики | <a id="p111874"></a>1.1. - 10.6.<br>1.10. - 31.12. |
| <a id="p111875"></a>0809 40 05 | <a id="p111876"></a>Сливы | <a id="p111877"></a>1.10. - 10.06. |
| <a id="p111878"></a>0810 10 00 | <a id="p111879"></a>Клубника | <a id="p111880"></a>1.1. - 31.12. |
| <a id="p111881"></a>0810 20 10 | <a id="p111882"></a>Малина | <a id="p111883"></a>1.1. - 31.12. |
| <a id="p111884"></a>0810 50 00 | <a id="p111885"></a>Киви | <a id="p111886"></a>1.1. - 31.12. |


<a id="p111887"></a>Приложение 32-01

<a id="p111888"></a>**ОБЯЗАТЕЛЬСТВО ПОРУЧИТЕЛЯ - ИНДИВИДУАЛЬНАЯ ГАРАНТИЯ**

<a id="p111889"></a>I. Обязательство поручителя

1. <a id="p111890"></a>Нижеподписавшийся [<1>](https://bukva.ai/docs/reglament-20152447/statya-350#p111919)...................................................................................
<a id="p111891"></a>проживающий [<2>](https://bukva.ai/docs/reglament-20152447/statya-350#p111920) в .............................................................................................
<a id="p111892"></a>настоящим совместно и в отдельности гарантирует таможенному органу гарантии ..................
<a id="p111893"></a>до максимальной суммы ....................................................................................
<a id="p111894"></a>в пользу Европейского Союза (состоящего из Королевства Бельгия, Республики Болгария, Чешской Республики, Королевства Дания, Федеративной Республики Германия, Республики Эстония, Греческой Республики, Республики Хорватия, Королевства Испания, Французской Республики, Ирландии, Итальянской Республики, Республики Кипр, Республики Латвия, Республики Литва, Великого Герцогства Люксембург, Венгрии, Республики Мальта, Королевства Нидерландов, Республики Австрия, Республики Польша, Португальской Республики, Румынии, Республики Словения, Словацкой Республики, Республики Финляндия, Королевства Швеция), Республики Исландия, Республики Северная Македония, Королевства Норвегия, Республики Сербия, Швейцарской Конфедерации, Республики Турция, Украины, Соединенного Королевства Великобритании и Северной Ирландии [<3>](https://bukva.ai/docs/reglament-20152447/statya-350#p111921) [<4>](https://bukva.ai/docs/reglament-20152447/statya-350#p111922), Княжества Андорра и Республики Сан-Марино [<5>](https://bukva.ai/docs/reglament-20152447/statya-350#p111923), уплату любой суммы, которую лицо, предоставляющее настоящую гарантию [<6>](https://bukva.ai/docs/reglament-20152447/statya-350#p111924),
<a id="p111895"></a>.................................................................................................
<a id="p111896"></a>может быть должно или уже должно вышеуказанным странам за долги в форме пошлины или других сборов [<6a>](https://bukva.ai/docs/reglament-20152447/statya-350#p111925), в отношении товаров, описанных ниже, на которые распространяется следующая таможенная операция [<7>](https://bukva.ai/docs/reglament-20152447/statya-350#p111926):.....................................................................
<a id="p111897"></a>Описание товаров:....................................................................
2. <a id="p111898"></a>Нижеподписавшийся принимает на себя обязательство оплатить по первому требованию компетентных органов стран, указанных в [параграфе 1](https://bukva.ai/docs/reglament-20152447/statya-350#p111890), в письменной форме и без отсрочки на срок свыше 30 дней с даты требования, запрошенную сумму, если он или она или другое заинтересованное лицо не установят до истечения этого срока к удовлетворению таможенных органов, что специальная процедура, кроме конечного использования или временного хранения, была завершена, таможенный надзор за конечным использованием товаров или временное хранение были завершены правильно или в случае другой операции, кроме специальной процедуры и временного хранения, что ситуация с товарами была урегулирована.
<a id="p111899"></a>По запросу нижеподписавшегося и по причинам, признанным уважительными, компетентные органы могут отсрочить оплату на период, превышающий тридцатидневный срок с даты требования оплаты, в течение которого он или она обязаны оплатить требуемую сумму. Затраты, понесенные в результате продления срока, в частности, проценты, должны быть рассчитаны таким образом, чтобы сумма была равна той, которая была бы выплачена при подобных обстоятельствах на денежном рынке или финансовом рынке в этой стране.
3. <a id="p111900"></a>Обязательство действует с даты его принятия таможенным органом гарантии. Нижеподписавшийся остается ответственным за оплату долга, возникшего во время таможенной операции, на которую распространяется настоящее обязательство, и начавшейся до даты, на которую начал действовать отзыв или отмена гарантии, даже если требование оплаты предъявлено после указанной даты.
4. <a id="p111901"></a>В целях настоящего обязательства нижеподписавшийся дает свой адрес для оказания услуг в каждой из других стран, указанных в [параграфе 1](https://bukva.ai/docs/reglament-20152447/statya-350#p111890) [<8>](https://bukva.ai/docs/reglament-20152447/statya-350#p111939):


| <a id="p111902"></a>Страна | <a id="p111903"></a>ФИО или наименование фирмы и полный адрес |
| --- | --- |
| <a id="p111904"></a>....................................<br>....................................<br>....................................<br>....................................<br>.................................... | <a id="p111905"></a>..............................................................................<br>..............................................................................<br>..............................................................................<br>..............................................................................<br>.............................................................................. |


<a id="p111906"></a>Нижеподписавшийся подтверждает, что вся переписка и уведомления и все формальности или процедуры, относящиеся к данному обязательству, направленные или выполненные в письменной форме по его адресу, принимаются как доставленные ему или ей должным образом.
<a id="p111907"></a>Нижеподписавшийся подтверждает юрисдикцию судов в тех местах, где он или она имеет адрес для оказания услуг.
<a id="p111908"></a>Нижеподписавшийся принимает на себя обязательство не менять свой адрес для оказания услуг, или, если он или она меняет один или несколько адресов, проинформировать таможенный орган гарантии об этом заранее.
<a id="p111909"></a>Совершено в ...........................................................................................
<a id="p111910"></a>дата .........................................................................................................
<a id="p111911"></a>.................................................................................................................

<a id="p111912"></a>(Подпись) [<9>](https://bukva.ai/docs/reglament-20152447/statya-350#p111940)

<a id="p111913"></a>II. Принятие таможенным органом гарантии

<a id="p111914"></a>Таможенный орган гарантии .......................................................................................
<a id="p111915"></a>Обязательство поручителя принято (дата) ......................................................... для покрытия таможенной операции, выполненной по таможенной декларации/декларации временного хранения N ............................................................................. [<10>](https://bukva.ai/docs/reglament-20152447/statya-350#p111941)
<a id="p111916"></a>.................................................
<a id="p111917"></a>(Печать и подпись)

<a id="p111918"></a>

---

<a id="p111919"></a><1> ФИО или наименование фирмы.
<a id="p111920"></a><2> Полный адрес.
<a id="p111921"></a><3> Зачеркнуть название/названия государства/государств, на территории которого(ых) не может использоваться.
<a id="p111922"></a><4> Согласно Протоколу по Ирландии/Северной Ирландии Соглашения о выходе Соединенного Королевства и Северной Ирландии из Европейского Союза и Европейского Сообщества по атомной энергии Северная Ирландия должна считаться частью Европейского Союза в целях настоящей гарантии. В этой связи гарант, учрежденный на таможенной территории Европейского Союза, должен указать адрес для обслуживания или назначить агента в Северной Ирландии, если гарантия может использоваться в ней. Но если гарантия в контексте общего транзита действует в Европейском Союзе и в Соединенном Королевстве, единый адрес для обслуживания или назначенный агент в Соединенном Королевстве могут распространяться на все части Соединенного Королевства, включая Северную Ирландию.
<a id="p111923"></a><5> Ссылки на Княжество Андорра и Республику Сан-Марино применяются исключительно к транзитным операциям Союза.
<a id="p111924"></a><6> ФИО или наименование фирмы и полный адрес лица, предоставляющего гарантию.
<a id="p111925"></a><6a> Применяется в отношении других сборов, взимаемых в связи с импортом или экспортом товаров, если гарантия используется для помещения товаров на транзитную процедуру Союза/общую процедуру транзита или может использоваться в нескольких государствах-членах ЕС.
<a id="p111926"></a><7> Внести одну из следующих таможенных операций:
<a id="p111927"></a>(a) временное хранение;
<a id="p111928"></a>(b) процедура транзита Союза/процедура общего транзита;
<a id="p111929"></a>(c) процедура таможенного склада;
<a id="p111930"></a>(d) процедура временного допуска с общим освобождением от импортной пошлины;
<a id="p111931"></a>(e) процедура внутренней переработки;
<a id="p111932"></a>(f) процедура конечного использования;
<a id="p111933"></a>(g) выпуск в свободное обращение по обычной таможенной декларации без отсроченного платежа;
<a id="p111934"></a>(h) выпуск в свободное обращение по обычной таможенной декларации с отсроченным платежом;
<a id="p111935"></a>(i) выпуск в свободное обращение по таможенной декларации, поданной в соответствии со [Статьей 166](https://bukva.ai/docs/reglament-9522013/statya-166#p101473) Регламента (ЕС) 952/2013 Европейского Парламента и Совета ЕС от 9 октября 2013 г. об установлении Таможенного кодекса Союза;
<a id="p111936"></a>(j) выпуск в свободное обращение по таможенной декларации, поданной в соответствии со [Статьей 182](https://bukva.ai/docs/reglament-9522013/statya-182#p101580) Регламента (ЕС) 952/2013 Европейского Парламента и Совета ЕС от 9 октября 2013 г. об установлении Таможенного кодекса Союза;
<a id="p111937"></a>(k) процедура временного допуска с частичным освобождением от импортной пошлины;
<a id="p111938"></a>(l) если другое - указать другой вид импортной пошлины.
<a id="p111939"></a><8> Если по законодательству страны нет положения о назначении поручителем адреса для оказания услуг в этой стране, необходимо назначить агента для получения адресованной ему корреспонденции и уведомления во [втором подпараграфе](https://bukva.ai/docs/reglament-20152447/statya-350#p111906) и обязательства в [четвертом подпараграфе параграфа 4](https://bukva.ai/docs/reglament-20152447/statya-350#p111908). Суды в том месте, в котором находится адрес поручителя для оказания услуг или его агент, имеют юрисдикцию для рассмотрения споров в отношении этой гарантии.
<a id="p111940"></a><9> Лицо, подписывающее документ, должно сделать перед своей подписью следующую запись от руки: "Гарантия на сумму ..................................................................." (сумма пишется прописью).
<a id="p111941"></a><10> Заполняется органом, в котором товары были помещены на процедуру или были на временном хранении.


<a id="p111942"></a>Приложение 32-02

<a id="p111943"></a>**ОБЯЗАТЕЛЬСТВО ПОРУЧИТЕЛЯ - ИНДИВИДУАЛЬНАЯ ГАРАНТИЯ**
**В ФОРМЕ РАСПИСОК**
**ОБЩАЯ ПРОЦЕДУРА ТРАНЗИТА/ПРОЦЕДУРА ТРАНЗИТА СОЮЗА**

<a id="p111944"></a>I. Обязательство поручителя

1. <a id="p111945"></a>Нижеподписавшийся [<1>](https://bukva.ai/docs/reglament-20152447/statya-350#p111970)...................................................................
<a id="p111946"></a>проживающий в [<2>](https://bukva.ai/docs/reglament-20152447/statya-350#p111971)................................................................................
<a id="p111947"></a>настоящим совместно и в отдельности гарантирует таможенному органу гарантии ..................
<a id="p111948"></a>в пользу Европейского Союза (состоящего из Королевства Бельгия, Республики Болгария, Чешской Республики, Королевства Дания, Федеративной Республики Германия, Республики Эстония, Греческой Республики, Республики Хорватия, Королевства Испания, Французской Республики, Ирландии, Итальянской Республики, Республики Кипр, Республики Латвия, Республики Литва, Великого Герцогства Люксембург, Венгрии, Республики Мальта, Королевства Нидерландов, Республики Австрия, Республики Польша, Португальской Республики, Румынии, Республики Словения, Словацкой Республики, Республики Финляндия, Королевства Швеция) и Республики Исландия, Республики Северная Македония, Королевства Норвегия, Республики Сербия, Швейцарской Конфедерации, Республики Турция, Украины, Соединенного Королевства Великобритании и Северной Ирландии [<3>](https://bukva.ai/docs/reglament-20152447/statya-350#p111972), Княжества Андорра и Республики Сан-Марино [<4>](https://bukva.ai/docs/reglament-20152447/statya-350#p111973), уплату любой суммы, которую владелец процедуры может быть должен или уже должен вышеназванным странам за долги в форме пошлины или других сборов, выплачиваемых в связи с импортом или экспортом товаров, помещенных транзитную процедуру Союза или на общую транзитную процедуру, в отношении которых нижеподписавшийся обязан выдать индивидуальную гарантию в форме расписок максимально до 10 000 евро на расписку.
2. <a id="p111949"></a>Нижеподписавшийся принимает на себя обязательство оплатить по первому требованию компетентных органов стран, указанных в [пункте 1](https://bukva.ai/docs/reglament-20152447/statya-350#p111945), в письменной форме и без отсрочки на срок свыше 30 дней с даты требования, запрошенную сумму до 10 000 евро на индивидуальную гарантию в форме расписки, если он или она или другое заинтересованное лицо не установят до истечения этого срока к удовлетворению компетентных органов, что операция была завершена.
<a id="p111950"></a>По запросу нижеподписавшегося и по причинам, признанным уважительными, компетентные органы могут отсрочить за пределы тридцатидневного срока с даты требования оплаты срок, в течение которого он или она обязаны оплатить требуемую сумму. Затраты, понесенные в результате продления срока, в частности, проценты, должны быть рассчитаны таким образом, чтобы сумма была равна той, которая была бы выплачена при подобных обстоятельствах на денежном рынке или финансовом рынке в указанной стране.
3. <a id="p111951"></a>Обязательство действует с даты его принятия таможенным органом гарантии. Нижеподписавшийся остается ответственным за оплату долга, возникающего во время транзитной операции Союза или общей транзитной операции, на которые распространяется настоящее обязательство, и начавшихся до даты, на которую начал действовать отзыв или отмена гарантии, даже если требование оплаты предъявлено после этой даты.
4. <a id="p111952"></a>В целях настоящего обязательства нижеподписавшийся дает свой адрес для оказания услуг [<5>](https://bukva.ai/docs/reglament-20152447/statya-350#p111974) в каждой из других стран, указанных в [параграфе 1](https://bukva.ai/docs/reglament-20152447/statya-350#p111945):


| <a id="p111953"></a>Страна | <a id="p111954"></a>ФИО или наименование фирмы и полный адрес |
| --- | --- |
| <a id="p111955"></a>....................................<br>....................................<br>....................................<br>....................................<br>.................................... | <a id="p111956"></a>..............................................................................<br>..............................................................................<br>..............................................................................<br>..............................................................................<br>.............................................................................. |


<a id="p111957"></a>Нижеподписавшийся подтверждает, что вся переписка и уведомления и все формальности или процедуры, относящиеся к данному обязательству, направленные или выполненные в письменной форме по одному из его или ее адресов, принимаются как доставленные ему или ей должным образом.
<a id="p111958"></a>Нижеподписавшийся подтверждает юрисдикцию судов в тех местах, где он или она имеет адрес для оказания услуг.
<a id="p111959"></a>Нижеподписавшийся принимает на себя обязательство не менять свой адрес для оказания услуг, или, если он или она меняет один или несколько адресов, проинформировать таможенный орган гарантии об этом заранее.

<a id="p111960"></a>Совершено в ........................................................................................
<a id="p111961"></a>дата .......................................................................................................
<a id="p111962"></a>..............................................................................................................

<a id="p111963"></a>(Подпись) [<6>](https://bukva.ai/docs/reglament-20152447/statya-350#p111975)

<a id="p111964"></a>II. Принятие таможенным органом гарантии

<a id="p111965"></a>Таможенный орган гарантии .................................................................
<a id="p111966"></a>Обязательство поручителя принято .......................................................

<a id="p111967"></a>.................................................
<a id="p111968"></a>(Печать и подпись)

<a id="p111969"></a>

---

<a id="p111970"></a><1> ФИО или наименование фирмы.
<a id="p111971"></a><2> Полный адрес.
<a id="p111972"></a><3> Согласно Протоколу по Ирландии/Северной Ирландии Соглашения о выходе Соединенного Королевства и Северной Ирландии из Европейского Союза и Европейского Сообщества по атомной энергии Северная Ирландия должна считаться частью Европейского Союза в целях настоящей гарантии. В этой связи гарант, учрежденный на таможенной территории Европейского Союза, должен указать адрес для обслуживания или назначить агента в Северной Ирландии, если гарантия может использоваться в ней. Но если гарантия в контексте общего транзита действует в Европейском Союзе и в Соединенном Королевстве, единый адрес для обслуживания или назначенный агент в Соединенном Королевстве могут распространяться на все части Соединенного Королевства, включая Северную Ирландию.
<a id="p111973"></a><4> Ссылки на Княжество Андорра и Республику Сан-Марино применяются исключительно к транзитным операциям Союза.
<a id="p111974"></a><5> Если по законодательству страны нет положения о назначении поручителем адреса для оказания услуг в этой стране, необходимо назначить агента для получения адресованной ему корреспонденции и уведомления во [втором подпараграфе](https://bukva.ai/docs/reglament-20152447/statya-350#p111957) и обязательства в [четвертом подпараграфе параграфа 4](https://bukva.ai/docs/reglament-20152447/statya-350#p111959). Суды, в том месте, в котором находится адрес поручителя для оказания услуг или его агент, имеют юрисдикцию для рассмотрения споров в отношении этой гарантии.
<a id="p111975"></a><6> Подписи должна предшествовать следующая собственноручная запись подписывающего лица: "Действует как гарантия в форме расписки".


<a id="p111976"></a>Приложение 32-03

<a id="p111977"></a>**ОБЯЗАТЕЛЬСТВО ПОРУЧИТЕЛЯ - ПОЛНАЯ ГАРАНТИЯ**

<a id="p111978"></a>I. Обязательство поручителя

1. <a id="p111979"></a>Нижеподписавшийся [<1>](https://bukva.ai/docs/reglament-20152447/statya-350#p112029)...............................................................................
<a id="p111980"></a>проживающий в [<2>](https://bukva.ai/docs/reglament-20152447/statya-350#p112030).........................................................................................
<a id="p111981"></a>настоящим совместно и в отдельности гарантирует таможенному органу гарантии ..................
<a id="p111982"></a>до максимальной суммы ...................................................................................
<a id="p111983"></a>в пользу Европейского Союза (состоящего из Королевства Бельгия, Республики Болгария, Чешской Республики, Королевства Дания, Федеративной Республики Германия, Республики Эстония, Ирландии, Греческой Республики, Королевства Испания, Французской Республики, Республики Хорватия, Итальянской Республики, Республики Кипр, Республики Латвия, Республики Литва, Великого Герцогства Люксембург, Венгрии, Республики Мальта, Королевства Нидерландов, Республики Австрия, Республики Польша, Португальской Республики, Румынии, Республики Словения, Словацкой Республики, Республики Финляндия, Королевства Швеция) и Республики Исландия, Республики Северная Македония, Королевства Норвегия, Республики Сербия, Швейцарской Конфедерации, Республики Турция, Украины, Соединенного Королевства Великобритании и Северной Ирландии [<3>](https://bukva.ai/docs/reglament-20152447/statya-350#p112031) [<4>](https://bukva.ai/docs/reglament-20152447/statya-350#p112032), Княжества Андорра и Республики Сан-Марино [<5>](https://bukva.ai/docs/reglament-20152447/statya-350#p112033),
<a id="p111984"></a>уплату любой суммы, которую лицо, предоставляющее гарантию [<6>](https://bukva.ai/docs/reglament-20152447/statya-350#p112034), может быть должно или уже должно вышеназванным странам за долги в форме пошлины или других сборов [<7>](https://bukva.ai/docs/reglament-20152447/statya-350#p112035), которые могут быть понесены или были понесены в отношении товаров, подпадающих под таможенные операции, указанные в [пункте 1a](https://bukva.ai/docs/reglament-20152447/statya-350#p111991) и/или [пункте 1b](https://bukva.ai/docs/reglament-20152447/statya-350#p111999).
<a id="p111985"></a>Максимальная сумма гарантии состоит из суммы:
<a id="p111986"></a>...........................................................................................................
<a id="p111987"></a>(a) являющейся 100/50/30% [<8>](https://bukva.ai/docs/reglament-20152447/statya-350#p112036) части исходной суммы, относящейся к сумме таможенного долга и других сборов, которые могут быть понесены, равной сумме сумм, указанных в [пункте 1a](https://bukva.ai/docs/reglament-20152447/statya-350#p111991),
<a id="p111988"></a>и
<a id="p111989"></a>...........................................................................................................
<a id="p111990"></a>(b) являющейся 100/30% [<9>](https://bukva.ai/docs/reglament-20152447/statya-350#p112037) части исходной суммы, относящейся к сумме таможенного долга и других сборов, которые были понесены, равной сумме сумм, указанных в [пункте 1b](https://bukva.ai/docs/reglament-20152447/statya-350#p111999),
<a id="p111991"></a>1a. Суммы, образующие часть исходной суммы, относящейся к сумме таможенного долга и, если применяется, других сборов, которые могут быть понесены, являются следующими для каждой из целей, указанных ниже [<10>](https://bukva.ai/docs/reglament-20152447/statya-350#p112038):
<a id="p111992"></a>(a) временное хранение -...;
<a id="p111993"></a>(b) процедура транзита Союза/общая транзитная процедура -...;
<a id="p111994"></a>(c) процедура таможенного склада -...;
<a id="p111995"></a>(d) процедура временного доступа с общим освобождением от импортной пошлины -...;
<a id="p111996"></a>(e) процедура внутренней переработки -...;
<a id="p111997"></a>(f) процедура конечного использования -...;
<a id="p111998"></a>(g) если другое - укажите другой вид операции -...
<a id="p111999"></a>1b. Суммы, образующие часть исходной суммы, относящейся к сумме таможенного долга и, если применяется, других сборов, которые были понесены, являются следующими для каждой из целей, указанных ниже [<11>](https://bukva.ai/docs/reglament-20152447/statya-350#p112039):
<a id="p112000"></a>(a) выпуск в свободное обращение по обычной таможенной декларации без отсроченного платежа -...;
<a id="p112001"></a>(b) выпуск в свободное обращение по обычной таможенной декларации с отсроченным платежом -...;
<a id="p112002"></a>(c) выпуск в свободное обращение по обычной таможенной декларации, поданной в соответствии со [Статьей 166](https://bukva.ai/docs/reglament-9522013/statya-166#p101473) Регламента (ЕС) 952/2013 Европейского Парламента и Совета ЕС от 9 октября 2013 г., устанавливающего Таможенный кодекс Союза -...;
<a id="p112003"></a>(d) выпуск в свободное обращение по обычной таможенной декларации, поданной в соответствии со [Статьей 182](https://bukva.ai/docs/reglament-9522013/statya-182#p101580) Регламента (ЕС) 952/2013 Европейского Парламента и Совета ЕС от 9 октября 2013 г., устанавливающего Таможенный кодекс Союза -...;
<a id="p112004"></a>(e) процедура временного допуска с частичным освобождением от импортной пошлины -...;
<a id="p112005"></a>(f) процедура конечного использования -... [<12>](https://bukva.ai/docs/reglament-20152447/statya-350#p112040)
<a id="p112006"></a>(g) если другое - укажите другой вид операции -...
2. <a id="p112007"></a>Нижеподписавшийся принимает на себя обязательство оплатить по первому требованию компетентных органов стран, указанных в [параграфе 1](https://bukva.ai/docs/reglament-20152447/statya-350#p111979), в письменной форме и без отсрочки платежа на срок свыше 30 дней с даты требования, запрошенную сумму до лимита вышеназванной максимальной суммы, если он или она или другое заинтересованное лицо не установит, что операция до истечения этого срока в соответствии с требованиями компетентных органов была завершена, таможенный надзор за конечным использованием товаров или временное хранение были завершены правильно или в случае других операций, кроме специальных процедур, что ситуация с товарами была урегулирована.
<a id="p112008"></a>По запросу нижеподписавшегося и по причинам, признанным уважительными, компетентные органы могут отсрочить оплату на период, превышающий тридцатидневный срок с даты требования оплаты, в течение которого он или она обязаны оплатить требуемую сумму. Затраты, понесенные в результате продления срока, в частности, проценты, должны быть рассчитаны таким образом, чтобы сумма была равна той, которая была бы выплачена при подобных обстоятельствах на денежном рынке или финансовом рынке в этой стране.
<a id="p112009"></a>Сумма не может быть уменьшена на сумму, уже выплаченную по условиям этих обязательств, если от нижеподписавшегося не требуется оплатить долг, возникший во время таможенной операции, начавшейся до того, как было получено предшествующее требование или в течение 30 дней после него.
3. <a id="p112010"></a>Обязательство действует с даты его принятия таможенным органом гарантии. Нижеподписавшийся остается ответственным за оплату долга, возникающего во время таможенной операции, на которую распространяется настоящее обязательство, и начавшейся до даты, на которую начал действовать отзыв или отмена гарантии, даже если требование оплаты предъявлено после этой даты.
4. <a id="p112011"></a>В целях настоящего обязательства нижеподписавшийся дает свой адрес для оказания услуг [<13>](https://bukva.ai/docs/reglament-20152447/statya-350#p112041) в каждой из других стран, указанных в [параграфе 1](https://bukva.ai/docs/reglament-20152447/statya-350#p111979):


| <a id="p112012"></a>Страна | <a id="p112013"></a>ФИО или наименование фирмы и полный адрес |
| --- | --- |
| <a id="p112014"></a>...........................<br>...........................<br>...........................<br>...........................<br>........................... | <a id="p112015"></a>...........................................................................<br>...........................................................................<br>...........................................................................<br>...........................................................................<br>........................................................................... |


<a id="p112016"></a>Нижеподписавшийся подтверждает, что вся переписка и уведомления и все формальности или процедуры, относящиеся к этому обязательству, направленные или выполненные в письменной форме по одному из его или ее адресов, принимаются как доставленные ему или ей должным образом.
<a id="p112017"></a>Нижеподписавшийся подтверждает юрисдикцию судов в тех местах, где он или она имеет адрес для оказания услуг.
<a id="p112018"></a>Нижеподписавшийся принимает на себя обязательство не менять свой адрес для оказания услуг, или, если он или она меняет один или несколько адресов, проинформировать таможенный орган гарантии об этом заранее.
<a id="p112019"></a>Совершено в .................................
<a id="p112020"></a>дата ......................
<a id="p112021"></a>...................................................
<a id="p112022"></a>(Подпись) [<14>](https://bukva.ai/docs/reglament-20152447/statya-350#p112042)

<a id="p112023"></a>II. Принятие таможенным органом гарантии

<a id="p112024"></a>Таможенный орган гарантии ..............................................................................
<a id="p112025"></a>Обязательство поручителя принято .........................................................

<a id="p112026"></a>...........................................................

<a id="p112027"></a>(Печать и подпись)

<a id="p112028"></a>

---

<a id="p112029"></a><1> ФИО или наименование фирмы.
<a id="p112030"></a><2> Полный адрес.
<a id="p112031"></a><3> Зачеркнуть название/названия государства/государств, на территории которого(ых) не может использоваться.
<a id="p112032"></a><4> Согласно Протоколу по Ирландии/Северной Ирландии Соглашения о выходе Соединенного Королевства и Северной Ирландии из Европейского Союза и Европейского Сообщества по атомной энергии Северная Ирландия должна считаться частью Европейского Союза в целях настоящей гарантии. В этой связи гарант, учрежденный на таможенной территории Европейского Союза, должен указать адрес для обслуживания или назначить агента в Северной Ирландии, если гарантия может использоваться в ней. Но если гарантия в контексте общего транзита действует в Европейском Союзе и в Соединенном Королевстве, единый адрес для обслуживания или назначенный агент в Соединенном Королевстве могут распространяться на все части Соединенного Королевства, включая Северную Ирландию.
<a id="p112033"></a><5> Ссылки на Княжество Андорра и Республику Сан-Марино применяются исключительно к транзитным операциям Сообщества.
<a id="p112034"></a><6> ФИО или наименование фирмы и полный адрес лица, предоставляющего гарантию.
<a id="p112035"></a><7> Применяется в отношении других сборов, причитающихся в связи с импортом или экспортом товаров, если гарантия используется для помещения товаров на процедуру транзита Союза/общую процедуру транзита или может использоваться в нескольких государствах-членах ЕС или одной договаривающейся стороной.
<a id="p112036"></a><8> Зачеркнуть то, что не применяется.
<a id="p112037"></a><9> Зачеркнуть то, что не применяется.
<a id="p112038"></a><10> Другие процедуры, кроме общего транзита, применяются исключительно в Европейском Союзе.
<a id="p112039"></a><11> Другие процедуры, кроме общего транзита, применяются исключительно в Европейском Союзе.
<a id="p112040"></a><12> Для сумм, заявленных в таможенной декларации для процедуры конечного использования.
<a id="p112041"></a><13> Если по законодательству страны нет положения о назначении поручителем адреса для оказания услуг в этой стране, необходимо назначить агента для получения адресованной ему корреспонденции и уведомления во [втором подпараграфе](https://bukva.ai/docs/reglament-20152447/statya-350#p112016) и обязательства в [четвертом подпараграфе параграфа 4](https://bukva.ai/docs/reglament-20152447/statya-350#p112018). Суды в том месте, в котором находится адрес поручителя для оказания услуг или его агент, имеют юрисдикцию для рассмотрения споров в отношении этой гарантии.
<a id="p112042"></a><14> Лицо, подписывающее документ, должно сделать перед своей подписью следующую запись от руки: "Гарантия на сумму ..................................................................." (сумма пишется прописью).


<a id="p112043"></a>Приложение 32-06

<a id="p112044"></a>Лицевая сторона


<table>
<colgroup><col width="50%"><col width="50%"></colgroup>
<tr><td colspan="2"><a id="p112045"></a>TC 32 - ИНДИВИДУАЛЬНАЯ ГАРАНТИЯ В ФОРМЕ РАСПИСКИ A 000 000</td></tr>
<tr><td colspan="2"><a id="p112046"></a>Выдана: .................................................................................................................................<br>................................................................................................................................................<br>(наименование и адрес частного лица или фирмы)<br>(обязательство поручителя принято (дата) ........................................................................<br>таможенным учреждением гарантии .................................................................................</td></tr>
<tr><td colspan="2"><a id="p112047"></a>Настоящая расписка, выданная (дата) .................... действует на сумму до 10 000 евро для транзитной операции Союза/общей транзитной операции, начавшейся не позднее, чем ...............................................<br>и в отношении которой владельцем процедуры является ...............................................<br>................................................................................................................................................<br>(Наименование и адрес частного лица или фирмы)</td></tr>
<tr><td><a id="p112048"></a>.....................................................................<br>(Подпись владельца процедуры &lt;*&gt;)</td><td><a id="p112049"></a>...................................................................<br>(Подпись и печать поручителя)</td></tr>
<tr><td colspan="2"><a id="p112050"></a>--------------------------------<br>&lt;*&gt; Подпись необязательна</td></tr>
</table>


<a id="p112051"></a>Оборотная сторона


<table>
<colgroup><col width="51%"><col width="49%"></colgroup>
<tr><td colspan="2"><a id="p112052"></a>Заполняется таможенным учреждением отправления<br>Транзитная операция выполняется по документу T1, T2, T2F <a href="#p112055">&lt;*&gt;</a>,<br>Зарегистрированным (дата) ............................. под N ......................................................<br>таможенным учреждением .................................................................................................</td></tr>
<tr><td><a id="p112053"></a>.....................................................................<br>(Официальная печать)</td><td><a id="p112054"></a>...................................................................<br>(Подпись)</td></tr>
<tr><td colspan="2"><a id="p112055"></a>--------------------------------<br>&lt;*&gt; Зачеркнуть ненужное</td></tr>
</table>


<a id="p112056"></a>Технические требования для расписки.
<a id="p112057"></a>Расписка распечатывается на бумаге без древесной массы, подходящей для печати и имеющей плотность не менее 55 г/м2. Она должна иметь фон в виде напечатанного красным цветом орнамента, что позволит определить подделку механическими или химическими средствами. Бумага должна быть белой.
<a id="p112058"></a>Формат бумаг должен быть 148 на 105 мм.
<a id="p112059"></a>Расписка должна иметь указание названия и адреса печатающей организации или отметку, по которой она может быть идентифицирована, и идентификационный номер.


<a id="p112060"></a>Приложение 33-03

<a id="p112061"></a>**МОДЕЛЬ ИНФОРМАЦИОННОЙ ПАМЯТКИ**
**О ТРЕБОВАНИИ ОПЛАТЫ ГАРАНТИРУЮЩЕЙ АССОЦИАЦИИ ДОЛГА**
**В ТРАНЗИТНОЙ ПРОЦЕДУРЕ ПО КАРНЕТУ ATA/E-ATA**

<a id="p112062"></a>Заголовок координирующего учреждения, начинающего спор.
<a id="p112063"></a>Адресат: координирующее учреждение, включающее учреждения временного импорта, или другое координирующее учреждение

<a id="p112064"></a>ПРЕДМЕТ: Карнет ATA - ПОДАЧА ПРЕТЕНЗИИ

<a id="p112065"></a>Информирую, что претензия об уплате пошлин и налогов по [конвенции](https://bukva.ai/docs/tamozhennaya-konventsiya-o-karnete-ata-dlya-2/statya-1) ATA/Стамбульской [конвенции](https://bukva.ai/docs/konventsiya-o-vremennom-vvoze-2/statya-1) [<1>](https://bukva.ai/docs/reglament-20152447/statya-350#p112080) была направлена (дата)............. [<2>](https://bukva.ai/docs/reglament-20152447/statya-350#p112081) в гарантирующее учреждение в отношении:
1. <a id="p112066"></a>[Карнета](https://bukva.ai/docs/tamozhennaya-konventsiya-o-karnete-ata-dlya-2/statya-28#p100156) ATA N:
2. <a id="p112067"></a>Выданного Торгово-промышленной палатой:
<a id="p112068"></a>Город:
<a id="p112069"></a>Страна:
3. <a id="p112070"></a>От имени:
<a id="p112071"></a>Владелец:
<a id="p112072"></a>Адрес:
4. <a id="p112073"></a>Дата истечения карнета:
5. <a id="p112074"></a>Дата, установленная для реэкспорта [<3>](https://bukva.ai/docs/reglament-20152447/statya-350#p112082):
6. <a id="p112075"></a>Номер транзитной/импортной расписки [<4>](https://bukva.ai/docs/reglament-20152447/statya-350#p112083):
7. <a id="p112076"></a>Дата удостоверения квитанции:
<a id="p112077"></a>Подпись и печать выдающего координирующего учреждения.
<a id="p112078"></a>.....................................................................................................

<a id="p112079"></a>

---

<a id="p112080"></a><1> [Статья 7](https://bukva.ai/docs/tamozhennaya-konventsiya-o-karnete-ata-dlya-2/statya-7#p100044) Конвенции ATA, Брюссель, 6 декабря 1961 г./[Статья 9](https://bukva.ai/docs/konventsiya-o-vremennom-vvoze-2/statya-9-2#p100261) Приложения A к Стамбульской конвенции, 26 июня 1990 г.
<a id="p112081"></a><2> Укажите дату отправления.
<a id="p112082"></a><3> Сведения можно получить из незавершенной транзитной расписки или расписки о временном допуске, или, если нет расписки, из информации, имеющейся в выдающем координирующем учреждении.
<a id="p112083"></a><4> Зачеркнуть ту, которая не применяется.


<a id="p112084"></a>Приложение 33-04

<a id="p112085"></a>Форма налогообложения для расчета пошлин и налогов,
полученных в результате требования оплаты гарантирующей
ассоциации долга в транзитной процедуре
по карнету ATA/e-ATA

<a id="p112086"></a>                           ФОРМА НАЛОГООБЛОЖЕНИЯ

от ............... N .................
Следующие сведения должны быть даны в указанном порядке:
1. N [карнета](https://bukva.ai/docs/tamozhennaya-konventsiya-o-karnete-ata-dlya-2/statya-28#p100156) ATA: .........................................................
2. Количество транзитных/импортных расписок [<1>](https://bukva.ai/docs/reglament-20152447/statya-350#p112088) ...........................
...........................................................................
3. Дата удостоверения расписки: ...........................................
4. Владелец и адрес: ......................................................
...........................................................................
5. Торгово-промышленная палата: ...........................................
6. Страна происхождения: ..................................................
7. Дата истечения срока действия карнета: .................................
8. Дата, установленная для реэкспорта товаров: ............................
9. Таможенное учреждение ввоза: ...........................................
10. Таможенное учреждение временного допуска: .............................
11. Торговое описание товаров: ............................................
...........................................................................
12. Код CN: ...............................................................
13. Количество штук: ......................................................
14. Вес или объем: ........................................................
15. Стоимость: ............................................................
16. Разбивка пошлин и налогов: ............................................
Тип Сумма налогообложения Ставка Общая сумма Курс валют
Итого:


(Итого словами: ..........................................................)
17. Таможенное учреждение: ................................................
Место и дата: .............................................................
                   Подпись                           Печать


<a id="p112087"></a>

---

<a id="p112088"></a><1> Зачеркнуть ту, которая не применяется


<a id="p112089"></a>Приложение 33-05

<a id="p112090"></a>Модель завершения, указывающая, что процедура требования
была начата в отношении гарантирующей ассоциации
в государстве-члене ЕС, в котором таможенный долг возник
в транзитной процедуре по карнету ATA/e-ATA

<a id="p112091"></a>Заголовок письма координирующего учреждения второго государства-члена ЕС, предоставляющего требование.
<a id="p112092"></a>Адресат: координирующее учреждение первого государства-члена ЕС, представляющего оригинальное требование.

<a id="p112093"></a>**ПРЕДМЕТ: КАРНЕТ ATA - ЗАВЕРШЕНИЕ**

<a id="p112094"></a>Информирую, что требование оплатить пошлины и налоги по [конвенции](https://bukva.ai/docs/tamozhennaya-konventsiya-o-karnete-ata-dlya-2/statya-1) ATA/Стамбульской [конвенции](https://bukva.ai/docs/konventsiya-o-vremennom-vvoze-2/statya-1) [<1>](https://bukva.ai/docs/reglament-20152447/statya-350#p112109) было направлено ......... [<2>](https://bukva.ai/docs/reglament-20152447/statya-350#p112110) в гарантирующее учреждение в отношении:
1. <a id="p112095"></a>[Карнета](https://bukva.ai/docs/tamozhennaya-konventsiya-o-karnete-ata-dlya-2/statya-28#p100156) ATA N:
2. <a id="p112096"></a>Выданного Торгово-промышленной палатой:
<a id="p112097"></a>Город:
<a id="p112098"></a>Страна:
3. <a id="p112099"></a>От имени:
<a id="p112100"></a>Получатель:
<a id="p112101"></a>Адрес:
4. <a id="p112102"></a>Срок истечения карнета:
5. <a id="p112103"></a>Дата, установленная для реэкспорта [<3>](https://bukva.ai/docs/reglament-20152447/statya-350#p112111):
6. <a id="p112104"></a>Количество транзитных/импортных расписок [<4>](https://bukva.ai/docs/reglament-20152447/statya-350#p112112):
7. <a id="p112105"></a>Дата удостоверения расписки:
<a id="p112106"></a>Настоящим сообщением прекращаются ваши обязательства по этому делу.
<a id="p112107"></a>Подпись и печать выдающего координирующего учреждения.

<a id="p112108"></a>

---

<a id="p112109"></a><1> [Статья 7](https://bukva.ai/docs/tamozhennaya-konventsiya-o-karnete-ata-dlya-2/statya-7#p100044) Конвенции ATA, Брюссель, 6 декабря 1961 г./[Статья 9](https://bukva.ai/docs/konventsiya-o-vremennom-vvoze-2/statya-9-2#p100261) Приложения A к Стамбульской конвенции, 26 июня 1990 г.
<a id="p112110"></a><2> Укажите дату отправления.
<a id="p112111"></a><3> Сведения можно получить из незавершенной транзитной расписки или расписки о временном допуске, или, если нет расписки, из информации, имеющейся в выдающем координирующем учреждении.
<a id="p112112"></a><4> Зачеркнуть ту, которая не применяется.


<a id="p112113"></a>Приложение 33-06

<a id="p112114"></a>**ЗАПРОС**
**ДОПОЛНИТЕЛЬНОЙ ИНФОРМАЦИИ, ЕСЛИ ТОВАРЫ РАСПОЛОЖЕНЫ**
**В ДРУГОМ ГОСУДАРСТВЕ-ЧЛЕНЕ ЕС**


<table>
<colgroup><col width="5%"><col width="45%"><col width="50%"></colgroup>
<tr><td colspan="2"><a id="p112115"></a>ЕВРОПЕЙСКАЯ КОМИССИЯ</td><td><a id="p112116"></a>ЗАПРОС НА ДОСМОТР</td></tr>
<tr><td><a id="p112117"></a>1</td><td rowspan="2"><a id="p112118"></a>1. Наименование и адрес таможенного органа, принимающего решение</td><td><a id="p112119"></a>2. Возмещение/зачет пошлин</td></tr>
<tr><td rowspan="4"><a id="p112120"></a>Оригинал</td><td><a id="p112121"></a>Ссылка на дело таможенного органа, принимающего решение</td></tr>
<tr><td><a id="p112122"></a>3. Наименование и адрес таможенного учреждения государства-члена ЕС, в котором находятся товары</td><td><a id="p112123"></a>4. Применение <a href="#p101566">Статьи 175</a></td></tr>
<tr><td rowspan="3"><a id="p112124"></a>5. Местонахождение товаров <a href="#p112161">&lt;1&gt;</a></td><td><a id="p112125"></a>6. Наименование и полный адрес лица, от которого требуемая информация может быть получена или которое может помочь таможенному учреждению государства-члена ЕС, в котором находятся товары</td></tr>
<tr><td rowspan="2"><a id="p112126"></a>7. Список прилагаемых документов</td></tr>
<tr><td><a id="p112127"></a>1</td></tr>
<tr><td></td><td colspan="2"><a id="p112128"></a>8. Цель запроса<br>- должно быть получено следующее:<br>- следующий досмотр должен быть выполнен:</td></tr>
<tr><td></td><td colspan="2"><a id="p112129"></a>9. Таможенный орган, принимающий решение<br>Место и дата:<br>Подпись:</td></tr>
<tr><td></td><td></td><td><a id="p112130"></a>Печать</td></tr>
</table>


| <a id="p112131"></a>ОТВЕТ НАДЗОРНОГО ТАМОЖЕННОГО ОРГАНА [<2>](https://bukva.ai/docs/reglament-20152447/statya-350#p112162) | <a id="p112132"></a>УВЕДОМЛЕНИЕ О ПОЛУЧЕНИИ [<2>](https://bukva.ai/docs/reglament-20152447/statya-350#p112162) |
| --- | --- |
|  |  |


<table>
<colgroup><col width="50%"><col width="50%"></colgroup>
<tr><td colspan="2"><a id="p112133"></a>10. Информация, полученная</td></tr>
<tr><td colspan="2"></td></tr>
<tr><td colspan="2"><a id="p112134"></a>11. Результаты выполненного досмотра</td></tr>
<tr><td colspan="2"></td></tr>
<tr><td><a id="p112135"></a>12. Место и дата:</td><td rowspan="6"><a id="p112136"></a>13. Подпись и официальная печать:</td></tr>
<tr><td></td></tr>
<tr><td></td></tr>
<tr><td></td></tr>
<tr><td></td></tr>
<tr><td></td></tr>
</table>


<table>
<colgroup><col width="7%"><col width="44%"><col width="49%"></colgroup>
<tr><td colspan="2"><a id="p112137"></a>ЕВРОПЕЙСКАЯ КОМИССИЯ</td><td><a id="p112138"></a>ЗАПРОС НА ДОСМОТР</td></tr>
<tr><td><a id="p112139"></a>1</td><td rowspan="3"><a id="p112140"></a>1. Наименование и адрес таможенного органа, принимающего решение</td><td rowspan="2"><a id="p112141"></a>2. Возмещение/зачет пошлин</td></tr>
<tr><td rowspan="5"><a id="p112142"></a>Копия</td></tr>
<tr><td><a id="p112143"></a>Ссылка на дело таможенного органа, принимающего решение</td></tr>
<tr><td><a id="p112144"></a>3. Наименование и адрес таможенного учреждения государства-члена ЕС, в котором находятся товары</td><td><a id="p112145"></a>4. Применение <a href="#p101566">Статьи 175</a></td></tr>
<tr><td rowspan="3"><a id="p112146"></a>5. Местонахождение товаров <a href="#p112161">&lt;1&gt;</a></td><td><a id="p112147"></a>6. Наименование и полный адрес лица, от которого требуемая информация может быть получена или которое может помочь таможенному учреждению государства-члена ЕС, в котором находятся товары</td></tr>
<tr><td rowspan="2"><a id="p112148"></a>7. Список прилагаемых документов</td></tr>
<tr><td><a id="p112149"></a>1</td></tr>
<tr><td></td><td colspan="2"><a id="p112150"></a>8. Цель запроса<br>- должно быть получено следующее:<br>- следующий досмотр должен быть выполнен:</td></tr>
<tr><td></td><td><a id="p112151"></a>9. Таможенный орган, принимающий<br>Место и дата:<br>Подпись:</td><td><a id="p112152"></a>решение</td></tr>
<tr><td></td><td></td><td><a id="p112153"></a>Печать</td></tr>
</table>


| <a id="p112154"></a>ОТВЕТ НАДЗОРНОГО ТАМОЖЕННОГО ОРГАНА [<2>](https://bukva.ai/docs/reglament-20152447/statya-350#p112162) | <a id="p112155"></a>УВЕДОМЛЕНИЕ О ПОЛУЧЕНИИ [<2>](https://bukva.ai/docs/reglament-20152447/statya-350#p112162) |
| --- | --- |
|  |  |


<table>
<colgroup><col width="50%"><col width="50%"></colgroup>
<tr><td colspan="2"><a id="p112156"></a>10. Информация, полученная</td></tr>
<tr><td colspan="2"><a id="p112157"></a>11. Результаты выполненного досмотра</td></tr>
<tr><td><a id="p112158"></a>12. Место и дата:</td><td><a id="p112159"></a>13. Подпись и официальная печать:</td></tr>
</table>


<a id="p112160"></a>

---

<a id="p112161"></a><1> Заполняется при необходимости.
<a id="p112162"></a><2> Удалить при необходимости. Надзорный таможенный орган выдает уведомление о получении, только если он не может принять к исполнению запрос в течение 30 дней с даты его получения. Уведомление о получении выполняется на копии этого документа.


<a id="p112163"></a>**ПРИЛОЖЕНИЕ 33-07**

<a id="p112164"></a>**ВОЗМЕЩЕНИЕ ИЛИ ЗАЧЕТ ПОШЛИНЫ**


<table>
<colgroup><col width="52%"><col width="12%"><col width="17%"><col width="19%"></colgroup>
<tr><td colspan="4"><a id="p112165"></a>ЕВРОПЕЙСКИЙ СОЮЗ</td></tr>
<tr><td><a id="p112166"></a>1. Наименование и адрес заинтересованного лица</td><td colspan="3"><a id="p112167"></a>2. Применение Статьи 96 <a href="https://bukva.ai/docs/reglament-9522013/statya-1">Делегированного Регламента (ЕС) 2015/2446, дополняющего [Регламент</a> (ЕС) 952/2013] и 176</td></tr>
<tr><td><a id="p112168"></a>3. Наименование и адрес таможенного учреждения, которое предоставило возмещение/зачет</td><td colspan="3"><a id="p112169"></a>4. Ссылка на решение, дающее разрешение на возмещение/зачет</td></tr>
<tr><td colspan="4"><a id="p112170"></a>5. Наименование и адрес надзорного таможенного учреждения</td></tr>
<tr><td colspan="2" rowspan="2"><a id="p112171"></a>6. Описание товаров, количество и тип</td><td colspan="2"><a id="p112172"></a>7. Код CN товаров</td></tr>
<tr><td><a id="p112173"></a>8. Количество или масса нетто товаров</td><td><a id="p112174"></a>9. Таможенная стоимость товаров</td></tr>
<tr><td colspan="4"><a id="p112175"></a>10. Надзорное таможенное учреждение</td></tr>
<tr><td colspan="4"><a id="p112176"></a>Удостоверение выдачи разрешения на возмещение или зачет пошлин</td></tr>
<tr><td colspan="4"><a id="p112177"></a>Настоящим удостоверяется, что в соответствии с решением, указанным в <a href="#p112169">графе 4</a>, товары, описанные выше, были:</td></tr>
<tr><td colspan="4"><a id="p112178"></a>На ..................................................... (дата) (дд/мм/гггг)</td></tr>
<tr><td><a id="p112179"></a><img src="https://i.bukva.ai/sakP7uTQ/img_26.png" alt="формула"> экспортированы из Союза</td><td colspan="3"><a id="p112180"></a><img src="https://i.bukva.ai/sakP7uTQ/img_27.png" alt="формула"> уничтожены под таможенным надзором</td></tr>
<tr><td><a id="p112181"></a><img src="https://i.bukva.ai/sakP7uTQ/img_28.png" alt="формула"> размещены на таможенном складе</td><td colspan="3"><a id="p112182"></a><img src="https://i.bukva.ai/sakP7uTQ/img_29.png" alt="формула"> размещены в свободной зоне или на свободном складе</td></tr>
<tr><td><a id="p112183"></a><img src="https://i.bukva.ai/sakP7uTQ/img_30.png" alt="формула"> поставлены бесплатно благотворительно, как определено в решении</td><td colspan="3"><a id="p112184"></a><img src="https://i.bukva.ai/sakP7uTQ/img_31.png" alt="формула"> начата таможенная процедура, определенная в решении</td></tr>
<tr><td colspan="4"><a id="p112185"></a>Ссылки на таможенную декларацию, если есть ................................................<br>На настоящую дату товары соответствуют условиям, изложенным для возмещения или зачета пошлин</td></tr>
<tr><td><a id="p112186"></a>11. Место и дата</td><td colspan="3" rowspan="2"><a id="p112187"></a>Печать</td></tr>
<tr><td><a id="p112188"></a>Подпись:</td></tr>
</table>


<a id="p112189"></a>

---

<a id="p112190"></a><1> Если надзорное таможенное учреждение обнаруживает, что товары больше не удовлетворяют этим условиям, оно удаляет это предложение и записывает это на обратной стороне листа в [графе](https://bukva.ai/docs/reglament-20152447/statya-350#p112191) "Замечания".

<a id="p112191"></a>Замечания


|  |
| --- |
|  |
|  |
|  |
|  |
|  |
|  |
|  |
|  |
|  |
|  |
|  |
|  |
|  |


<a id="p112192"></a>Приложение 51-01

<a id="p112193"></a>**ДОКУМЕНТ РЕГИСТРАЦИИ СТАТУСА**


<table>
<colgroup><col width="18%"><col width="36%"><col width="6%"><col width="6%"><col width="4%"><col width="8%"><col width="8%"><col width="16%"></colgroup>
<tr><td colspan="2"></td><td colspan="4" rowspan="3"><a id="p112194"></a>1. КОД СТАТУСА</td><td colspan="2" rowspan="6"><a id="p112195"></a>A MRN</td></tr>
<tr><td rowspan="6"></td><td><a id="p112196"></a>ЕВРОПЕЙСКИЙ СОЮЗ</td></tr>
<tr><td rowspan="4"><a id="p112197"></a>2. Заявитель N<br><img src="https://i.bukva.ai/sakP7uTQ/img_32.png" alt="формула"></td></tr>
<tr><td colspan="4"><a id="p112198"></a>3. Формы</td></tr>
<tr><td colspan="2"></td><td colspan="2"></td></tr>
<tr><td colspan="4"><a id="p112199"></a>5. Пункты</td></tr>
<tr><td><a id="p112200"></a>14. Представитель N</td><td colspan="6"><a id="p112201"></a>ДОКУМЕНТ РЕГИСТРАЦИИ СТАТУСА</td></tr>
<tr><td rowspan="4"><a id="p112202"></a>31. Упаковка и описание товаров</td><td colspan="4" rowspan="4"><a id="p112203"></a>Маркировки и номера - Контейнеры (N) - количество и вид</td><td colspan="2"><a id="p112204"></a>32. Пункт</td><td rowspan="2"><a id="p112205"></a>33. Код товара</td></tr>
<tr><td></td><td></td></tr>
<tr><td></td><td></td><td><a id="p112206"></a>35. Масса брутто (кг)</td></tr>
<tr><td></td><td></td><td><a id="p112207"></a>38. Масса нетто (кг)</td></tr>
<tr><td><a id="p112208"></a>44. Дополнительная информация/представленные документы/<br>Сертификаты и разрешения</td><td colspan="7"></td></tr>
<tr><td rowspan="4"><a id="p112209"></a>31. Упаковка и описание товаров</td><td colspan="4" rowspan="4"><a id="p112210"></a>Маркировки и номера - Контейнеры (N) - количество и вид</td><td colspan="2"><a id="p112211"></a>32. Пункт</td><td rowspan="2"><a id="p112212"></a>33. Код товара</td></tr>
<tr><td></td><td></td></tr>
<tr><td></td><td></td><td><a id="p112213"></a>35. Масса брутто (кг)</td></tr>
<tr><td></td><td></td><td><a id="p112214"></a>38. Масса нетто (кг)</td></tr>
<tr><td><a id="p112215"></a>44. Дополнительная информация/представленные документы/<br>Сертификаты и разрешения</td><td colspan="7"></td></tr>
<tr><td rowspan="4"><a id="p112216"></a>31. Упаковка и описание товаров</td><td colspan="4" rowspan="4"><a id="p112217"></a>Маркировки и номера - Контейнеры (N) - количество и вид</td><td colspan="2"><a id="p112218"></a>32. Пункт</td><td rowspan="2"><a id="p112219"></a>33. Код товара</td></tr>
<tr><td></td><td></td></tr>
<tr><td></td><td></td><td><a id="p112220"></a>35. Масса брутто (кг)</td></tr>
<tr><td></td><td></td><td><a id="p112221"></a>38. Масса нетто (кг)</td></tr>
<tr><td><a id="p112222"></a>44. Дополнительная информация/представленные документы/<br>Сертификаты и разрешения</td><td colspan="7"></td></tr>
<tr><td></td><td colspan="2"></td><td colspan="5"><a id="p112223"></a>54. Место и дата:<br>Подпись и имя заявителя/представителя:</td></tr>
</table>


<a id="p112224"></a>Приложение 61-02

<a id="p112225"></a>Сертификат взвешивания бананов - образец


<table>
<colgroup><col width="3%"><col width="29%"><col width="5%"><col width="12%"><col width="17%"><col width="3%"><col width="3%"><col width="7%"><col width="21%"></colgroup>
<tr><td colspan="4" rowspan="2"><a id="p112226"></a>1. Наименование авторизированного весовщика<br><img src="https://i.bukva.ai/sakP7uTQ/img_33.png" alt="формула"></td><td colspan="5"><a id="p112227"></a>2. Дата и номер выдачи сертификата взвешивания</td></tr>
<tr><td colspan="5"><a id="p112228"></a>3. Ссылка на трейдера</td></tr>
<tr><td colspan="4"><a id="p112229"></a>4. Обозначение транспортного средства по прибытии</td><td colspan="5"><a id="p112230"></a>5. Страна происхождения</td></tr>
<tr><td colspan="4"><a id="p112231"></a>6. Количество и тип упаковки</td><td colspan="5"><a id="p112232"></a>7. Общий установленный вес нетто</td></tr>
<tr><td colspan="9"><a id="p112233"></a>8. Марка(и)</td></tr>
<tr><td colspan="9"><a id="p112234"></a>9. Проверенные единицы упакованных бананов (Укажите вес брутто для каждой взвешенной единицы)</td></tr>
<tr><td><a id="p112235"></a>1</td><td></td><td><a id="p112236"></a>8</td><td colspan="2"></td><td colspan="2"><a id="p112237"></a>15</td><td colspan="2"></td></tr>
<tr><td><a id="p112238"></a>2</td><td></td><td><a id="p112239"></a>9</td><td colspan="2"></td><td colspan="2"><a id="p112240"></a>16</td><td colspan="2"></td></tr>
<tr><td><a id="p112241"></a>3</td><td></td><td><a id="p112242"></a>10</td><td colspan="2"></td><td colspan="2"><a id="p112243"></a>17</td><td colspan="2"></td></tr>
<tr><td><a id="p112244"></a>4</td><td></td><td><a id="p112245"></a>11</td><td colspan="2"></td><td colspan="2"><a id="p112246"></a>18</td><td colspan="2"></td></tr>
<tr><td><a id="p112247"></a>5</td><td></td><td><a id="p112248"></a>12</td><td colspan="2"></td><td colspan="2"><a id="p112249"></a>19</td><td colspan="2"></td></tr>
<tr><td><a id="p112250"></a>6</td><td></td><td><a id="p112251"></a>13</td><td colspan="2"></td><td colspan="2"><a id="p112252"></a>20</td><td colspan="2"></td></tr>
<tr><td><a id="p112253"></a>7</td><td></td><td><a id="p112254"></a>14</td><td colspan="2"></td><td colspan="2"><a id="p112255"></a>21</td><td colspan="2"></td></tr>
<tr><td colspan="9"><a id="p112256"></a>10. Общий вес брутто проверенных единиц упакованных бананов:</td></tr>
<tr><td colspan="6"><a id="p112257"></a>11. Количество проверенных единиц упакованных бананов:</td><td colspan="3"></td></tr>
<tr><td colspan="9"><a id="p112258"></a>12. Средний вес брутто:</td></tr>
<tr><td colspan="8"><a id="p112259"></a>13. Тара:</td><td></td></tr>
<tr><td colspan="8"><a id="p112260"></a>14. Средний вес нетто на единицу упакованных бананов:</td><td></td></tr>
<tr><td colspan="9"><a id="p112261"></a>15. Подпись и печать авторизированного весовщика:<br>16. Место и дата:</td></tr>
</table>


<a id="p112262"></a>Приложение 61-03

<a id="p112263"></a>**СЕРТИФИКАТ**
**ВЗВЕШИВАНИЯ БАНАНОВ - ПРОЦЕДУРА**

<a id="p112264"></a>В целях [Статьи 252](https://bukva.ai/docs/reglament-20152447/statya-252#p102161) вес нетто каждой партии свежих бананов определяется авторизированными весовщиками в любом месте разгрузки в соответствии со следующей процедурой, изложенной ниже.
<a id="p112265"></a>В целях настоящего Приложения и [Статьи 252](https://bukva.ai/docs/reglament-20152447/statya-252#p102161) применяются следующие определения:
<a id="p112266"></a>(a) "вес нетто свежих бананов" - вес самих бананов без материалов упаковки и контейнеров упаковки любого вида;
<a id="p112267"></a>(b) "партия свежих бананов" - партия, состоящая из общего количества свежих бананов, погруженная на одно транспортное средство и отгруженная одним экспортером одному или нескольким грузополучателям;
<a id="p112268"></a>(c) "место разгрузки" - любое место, где партия свежих бананов может быть разгружена или удалена по таможенной процедуре, или в случае перевозки в контейнерах, если контейнер выгружен с судна или с воздушного судна или другого основного транспортного средства или если контейнер не упакован.
1. <a id="p112269"></a>Пробы количества упакованных бананов отбираются для каждого типа упаковки и для каждой страны происхождения. Взвешиваемый образец количества упакованных бананов представляет собой представительный образец партии свежих бананов. Он состоит из количества не менее чем указано ниже:


| <a id="p112270"></a>Количество единиц упакованных бананов (по типу упаковки и происхождению) | <a id="p112271"></a>Количество досматриваемых единиц упакованных бананов |
| --- | --- |
| <a id="p112272"></a>- до 400 | <a id="p112273"></a>3 |
| <a id="p112274"></a>- 401 - 700 | <a id="p112275"></a>4 |
| <a id="p112276"></a>- 701 - 1100 | <a id="p112277"></a>6 |
| <a id="p112278"></a>- 1101 - 2200 | <a id="p112279"></a>8 |
| <a id="p112280"></a>- 2201 - 4400 | <a id="p112281"></a>10 |
| <a id="p112282"></a>- 4401 - 6600 | <a id="p112283"></a>12 |
| <a id="p112284"></a>- более 6600 | <a id="p112285"></a>14 |


2. <a id="p112286"></a>Вес нетто определяется следующим образом:
<a id="p112287"></a>(a) посредством взвешивания каждой досматриваемой единицы упакованных бананов (вес брутто);
<a id="p112288"></a>(b) посредством открытия не менее одной единицы упакованных бананов, затем расчета веса упаковки;
<a id="p112289"></a>(c) вес этой упаковки принимается для всей упаковки такого типа и происхождения и вычитается из веса всех единиц взвешенных упакованных бананов;
<a id="p112290"></a>(d) средний вес нетто на единицу упакованных бананов, установленный таким образом для каждого типа и происхождения, основанный на весе выбранных образцов, принимается за основу для определения веса нетто партии свежих бананов;
3. <a id="p112291"></a>Если таможенный орган не проверяет сертификаты взвешивания бананов одновременно, чистый вес, продекларированный по этим сертификатам, принимается таможенными органами при условии, что разница составляет не более 1% между продекларированным весом нетто и средним весом нетто, установленным таможенными органами;
4. <a id="p112292"></a>[Сертификат](https://bukva.ai/docs/reglament-20152447/statya-350#p112225) взвешивания бананов представляется в таможенное учреждение, в которое представляется декларация на выпуск в свободное обращение. Таможенные органы применяют результаты отбора, указанные в [сертификате](https://bukva.ai/docs/reglament-20152447/statya-350#p112225) взвешивания бананов, ко всей партии свежих бананов, к которой относится данный [сертификат](https://bukva.ai/docs/reglament-20152447/statya-350#p112225).


<a id="p112293"></a>Приложение 62-02

<a id="p112294"></a>INF 3 - Информационный лист возвращенных товаров


<table>
<colgroup><col width="24%"><col width="4%"><col width="20%"><col width="9%"><col width="7%"><col width="3%"><col width="5%"><col width="3%"><col width="8%"><col width="16%"></colgroup>
<tr><td colspan="10"><a id="p112295"></a>ЕВРОПЕЙСКИЙ СОЮЗ</td></tr>
<tr><td colspan="3" rowspan="2"><a id="p112296"></a>1. Экспортер</td><td colspan="7"><a id="p112297"></a>INF3 N</td></tr>
<tr><td colspan="7"><a id="p112298"></a>Оригинал</td></tr>
<tr><td colspan="3" rowspan="2"><a id="p112299"></a>2. Грузополучатель во время экспорта</td><td colspan="7"><a id="p112300"></a>ВОЗВРАЩЕННЫЕ ТОВАРЫ</td></tr>
<tr><td colspan="7"><a id="p112301"></a>ИНФОРМАЦИОННЫЙ ЛИСТ</td></tr>
<tr><td colspan="8"><a id="p112302"></a>ВАЖНО</td><td colspan="2" rowspan="2"><a id="p112303"></a>3. Страна, в которую товары направлялись во время экспорта</td></tr>
<tr><td colspan="8"><a id="p112304"></a>1. До заполнения данной формы заинтересованное лицо должно изучить положения, относящиеся к возвращенным товарам, а также примечания с обратной стороны формы.</td></tr>
<tr><td colspan="10"><a id="p112305"></a>2. Заинтересованное лицо должно заполнить на печатной машинке или вручную печатными буквами <a href="#p112296">графы 1</a> - <a href="#p112333">11</a> настоящей формы.</td></tr>
<tr><td colspan="10"><a id="p112306"></a>3. Если этот информационный лист заполнен для товаров, экспорт которых был осуществлен в рамках общей сельскохозяйственной политики, по экспортной лицензии или предварительному фиксированному сертификату или для товаров, в отношении которых причитается возмещение или другие суммы, предусмотренные для экспорта, он является действительным, только если <a href="#p112317">графа B</a> и, если необходимо, <a href="#p112316">графа A</a> заверены компетентным органом.</td></tr>
<tr><td colspan="10"><a id="p112307"></a>4. Данный информационный лист должен быть представлен таможенному органу, через который осуществляется реимпорт.</td></tr>
<tr><td colspan="6"><a id="p112308"></a>4. Количество, вид, маркировки и номера упаковок и описание экспортированных товаров</td><td colspan="3"><a id="p112309"></a>5. Вес брутто</td><td></td></tr>
<tr><td colspan="10"></td></tr>
<tr><td colspan="3"></td><td colspan="2"><a id="p112310"></a>6. Вес нетто</td><td colspan="5"><a id="p112311"></a>7. Статистическая стоимость</td></tr>
<tr><td colspan="7"><a id="p112312"></a>8. Количество, для которого требуется информационный лист</td><td colspan="3" rowspan="2"><a id="p112313"></a>9. Код CN</td></tr>
<tr><td colspan="2"><a id="p112314"></a>(a) цифрами:</td><td colspan="5"><a id="p112315"></a>(b) прописью</td></tr>
<tr><td rowspan="8"><a id="p112316"></a>A. ЗАВЕРЕНИЕ КОМПЕТЕНТНЫМИ ОРГАНАМИ ДЛЯ ЭКСПОРТНЫХ ЛИЦЕНЗИЙ ИЛИ ПРЕДВАРИТЕЛЬНЫХ ФИКСИРОВАННЫХ СЕРТИФИКАТОВ<br>- Регламенты или лицензии или сертификаты</td><td colspan="4" rowspan="3"><a id="p112317"></a>B. ЗАВЕРЕНИЕ КОМПЕТЕНТНЫМИ ОРГАНАМИ ДЛЯ ПОЛУЧЕНИЯ ВОЗМЕЩЕНИЯ ИЛИ ДРУГИХ СУММ, ПРЕДУСМОТРЕННЫХ ДЛЯ ЭКСПОРТА</td><td colspan="5"><a id="p112318"></a>10. Дополнительная информация, относящаяся к товарам</td></tr>
<tr><td colspan="5"><a id="p112319"></a>(a) Тип экспортного документа</td></tr>
<tr><td colspan="5"><a id="p112320"></a>Тип</td></tr>
<tr><td colspan="4" rowspan="2"><a id="p112321"></a>- Нет возмещения или других сумм, получаемых по экспорту <a href="#p112341">&lt;1&gt;</a></td><td colspan="5"><a id="p112322"></a>N</td></tr>
<tr><td colspan="5"><a id="p112323"></a>Дата</td></tr>
<tr><td colspan="4" rowspan="3"><a id="p112324"></a>- Возмещение или другие суммы, выплачиваемые ................... (количество) <a href="#p112341">&lt;1&gt;</a><br>- Причитается к выплате возмещения или другие суммы по экспорту, отмененные для ..................... (количество) <a href="#p112341">&lt;1&gt;</a></td><td colspan="5"><a id="p112325"></a>(b) товары экспортированы для завершения операции внутренней переработки <a href="#p112341">&lt;1&gt;</a></td></tr>
<tr><td colspan="5"><a id="p112326"></a>(c) товары, которые были выпущены в свободное обращение для специального использования <a href="#p112341">&lt;1&gt;</a></td></tr>
<tr><td colspan="5" rowspan="3"><a id="p112327"></a>(d) товары, имеющие происхождение в государствах-членах ЕС или товары третьей страны, находящиеся в свободном обращении <a href="#p112341">&lt;1&gt;</a></td></tr>
<tr><td><a id="p112328"></a>В ........, дата ..........</td><td colspan="4"><a id="p112329"></a>В .............., дата .................</td></tr>
<tr><td><a id="p112330"></a>(подпись) (печать)</td><td colspan="4"><a id="p112331"></a>(подпись) (печать)</td></tr>
<tr><td colspan="4"><a id="p112332"></a>C. ЗАВЕРЕНИЕ ОРГАНИЗАЦИИ, ЗАВЕРШИВШЕЙ ТАМОЖЕННОЕ ОФОРМЛЕНИЕ ЭКСПОРТА</td><td colspan="6" rowspan="4"><a id="p112333"></a>11. ЗАПРОС ЭКСПОРТЕРА<br>Нижеподписавшийся, являющийся экспортером <a href="#p112341">&lt;1&gt;</a><br>от имени экспортера <a href="#p112341">&lt;1&gt;</a>,<br>просит выдать данный информационный лист в целях реимпорта товаров, описанных в нем</td></tr>
<tr><td colspan="4"><a id="p112334"></a>Информация, данная в <a href="#p112296">графах 1</a> - <a href="#p112318">10</a>, является достоверной</td></tr>
<tr><td colspan="4"><a id="p112335"></a>Принятые меры по идентификации</td></tr>
<tr><td colspan="4" rowspan="2"><a id="p112336"></a>В ............................, дата .............................</td></tr>
<tr><td colspan="6" rowspan="2"><a id="p112337"></a>В ............... дата ................</td></tr>
<tr><td colspan="4" rowspan="2"><a id="p112338"></a>(подпись) (печать)</td></tr>
<tr><td colspan="6"><a id="p112339"></a>(подпись)</td></tr>
</table>


<a id="p112340"></a>

---

<a id="p112341"></a><1> Зачеркнуть, где необходимо.


| <a id="p112342"></a>ПОЛНОЕ НАЗВАНИЕ И АДРЕС ТАМОЖЕННОГО УЧРЕЖДЕНИЯ ЭКСПОРТА |
| --- |


| <a id="p112343"></a>ПРИМЕЧАНИЯ |
| --- |
| <a id="p112344"></a>[Графа 1](https://bukva.ai/docs/reglament-20152447/statya-350#p112296): Укажите название или торговое название и полный адрес, включая государство-член ЕС |
| <a id="p112345"></a>[Графа 4](https://bukva.ai/docs/reglament-20152447/statya-350#p112308): Укажите точные сведения о товарах согласно их обычному коммерческому описанию или согласно их тарифному описанию. Описание должно соответствовать тому, которое используется в экспортном документе. |
| <a id="p112346"></a>[Графы 5](https://bukva.ai/docs/reglament-20152447/statya-350#p112309) и [6](https://bukva.ai/docs/reglament-20152447/statya-350#p112310): Укажите количество, указанное в экспортном документе. |
| <a id="p112347"></a>[Графа 7](https://bukva.ai/docs/reglament-20152447/statya-350#p112311): Укажите статистическую стоимость во время экспорта в валюте государства-члена ЕС экспорта. |
| <a id="p112348"></a>[Графа 8](https://bukva.ai/docs/reglament-20152447/statya-350#p112312): Укажите сведения о весе нетто, объеме и т.п., которое заинтересованное лицо желает реимпортировать. |
| <a id="p112349"></a>[Графа 10(c)](https://bukva.ai/docs/reglament-20152447/statya-350#p112326): Этот пункт относится к товарам, которые были выпущены в свободное обращение в Сообществе, освобожденным полностью или частично от уплаты импортных пошлин по причине их использования для специальных целей. |
| <a id="p112350"></a>[Графа 10(d)](https://bukva.ai/docs/reglament-20152447/statya-350#p112327): Этот пункт относится к ситуации с товарами во время их экспорта. |
|  |
| <a id="p112351"></a>ЗАПРОС УЧРЕЖДЕНИЯ РЕИМПОРТА |
| <a id="p112352"></a>Учреждение реимпорта, указанное ниже, запрашивает: |
| <a id="p112353"></a>- проверку подлинности данного информационного листа и достоверности информации в нем <1>: |
| <a id="p112354"></a>- предоставление следующей информации <1>: |
| <a id="p112355"></a><1> Зачеркнуть необходимое |


| <a id="p112356"></a>Полное название и адрес учреждения реимпорта | <a id="p112357"></a>В .......................... дата ........................... |
| --- | --- |
|  | <a id="p112358"></a>(подпись) |


| <a id="p112359"></a>ОТВЕТ КОМПЕТЕНТНЫХ ОРГАНОВ<br>Данный информационный лист является подлинным, и сведения, содержащиеся в нем, - достоверными <1>.<br>Данный информационный лист вызывает следующие комментарии <1>:<br>Другая запрошенная информация <1>: |
| --- |
| <a id="p112360"></a><1> Зачеркнуть необходимое |


| <a id="p112361"></a>Полное название и адрес учреждения реимпорта | <a id="p112362"></a>В .......................... дата ........................... |
| --- | --- |
|  | <a id="p112363"></a>(подпись) |


| <a id="p112364"></a>РЕИМПОРТ |
| --- |


<table>
<colgroup><col width="50%"><col width="50%"></colgroup>
<tr><td rowspan="2"><a id="p112365"></a>Реимпортированное количество</td><td><a id="p112366"></a>Исходящий номер, дата и тип документа о реимпорте</td></tr>
<tr><td><a id="p112367"></a>Подпись и печать учреждения реимпорта</td></tr>
<tr><td></td><td></td></tr>
</table>


<table>
<colgroup><col width="24%"><col width="4%"><col width="20%"><col width="9%"><col width="7%"><col width="3%"><col width="5%"><col width="3%"><col width="8%"><col width="16%"></colgroup>
<tr><td colspan="10"><a id="p112368"></a>ЕВРОПЕЙСКИЙ СОЮЗ</td></tr>
<tr><td colspan="3" rowspan="2"><a id="p112369"></a>1. Экспортер</td><td colspan="7"><a id="p112370"></a>INF3 N</td></tr>
<tr><td colspan="7"><a id="p112371"></a>Копия</td></tr>
<tr><td colspan="3" rowspan="2"><a id="p112372"></a>2. Грузополучатель во время экспорта</td><td colspan="7"><a id="p112373"></a>ВОЗВРАЩЕННЫЕ ТОВАРЫ</td></tr>
<tr><td colspan="7"><a id="p112374"></a>ИНФОРМАЦИОННЫЙ ЛИСТ</td></tr>
<tr><td colspan="8"><a id="p112375"></a>ВАЖНО</td><td colspan="2" rowspan="2"><a id="p112376"></a>3. Страна, в которую товары направлялись во время экспорта</td></tr>
<tr><td colspan="8"><a id="p112377"></a>1. До заполнения данной формы заинтересованное лицо должно изучить положения, относящиеся к возвращенным товарам, а также примечания с обратной стороны формы.</td></tr>
<tr><td colspan="10"><a id="p112378"></a>2. Заинтересованное лицо должно заполнить на печатной машинке или вручную печатными буквами <a href="#p112369">графы 1</a> - <a href="#p112405">11</a> настоящей формы.</td></tr>
<tr><td colspan="10"><a id="p112379"></a>3. Если этот информационный лист заполнен для товаров, экспорт которых был осуществлен в рамках общей сельскохозяйственной политики, по экспортной лицензии или предварительному фиксированному сертификату или для товаров, в отношении которых причитается возмещение или другие суммы, предусмотренные для экспорта, он является действительным, только если <a href="#p112390">графа B</a> и, если необходимо, <a href="#p112389">графа A</a> заверены компетентным органом.</td></tr>
<tr><td colspan="10"><a id="p112380"></a>4. Данный информационный лист должен быть представлен таможенному органу, через который осуществляется реимпорт.</td></tr>
<tr><td colspan="6"><a id="p112381"></a>4. Количество, вид, маркировки и номера упаковок и описание экспортированных товаров</td><td colspan="3"><a id="p112382"></a>5. Вес брутто</td><td></td></tr>
<tr><td colspan="10"></td></tr>
<tr><td colspan="3"></td><td colspan="2"><a id="p112383"></a>6. Вес нетто</td><td colspan="5"><a id="p112384"></a>7. Статистическая стоимость</td></tr>
<tr><td colspan="7"><a id="p112385"></a>8. Количество, для которого требуется информационный лист</td><td colspan="3" rowspan="2"><a id="p112386"></a>9. Код CN</td></tr>
<tr><td colspan="2"><a id="p112387"></a>(a) цифрами:</td><td colspan="5"><a id="p112388"></a>(b) прописью</td></tr>
<tr><td rowspan="8"><a id="p112389"></a>A. ЗАВЕРЕНИЕ КОМПЕТЕНТНЫМИ ОРГАНАМИ ДЛЯ ЭКСПОРТНЫХ ЛИЦЕНЗИЙ ИЛИ ПРЕДВАРИТЕЛЬНЫХ ФИКСИРОВАННЫХ СЕРТИФИКАТОВ<br>- Регламенты, или лицензии, или сертификаты</td><td colspan="4" rowspan="3"><a id="p112390"></a>B. ЗАВЕРЕНИЕ КОМПЕТЕНТНЫМИ ОРГАНАМИ ДЛЯ ПОЛУЧЕНИЯ ВОЗМЕЩЕНИЯ ИЛИ ДРУГИХ СУММ, ПРЕДУСМОТРЕННЫХ ДЛЯ ЭКСПОРТА</td><td colspan="5"><a id="p112391"></a>10. Дополнительная информация, относящаяся к товарам</td></tr>
<tr><td colspan="5"><a id="p112392"></a>(a) Тип экспортного документа</td></tr>
<tr><td colspan="5" rowspan="2"><a id="p112393"></a>N</td></tr>
<tr><td colspan="4" rowspan="3"><a id="p112394"></a>- Нет возмещения или других сумм, получаемых по экспорту <a href="#p112416">&lt;1&gt;</a></td></tr>
<tr><td colspan="5"><a id="p112395"></a>Дата</td></tr>
<tr><td colspan="5" rowspan="2"><a id="p112396"></a>(b) товары экспортированы для завершения операции внутренней переработки <a href="#p112416">&lt;1&gt;</a></td></tr>
<tr><td colspan="4" rowspan="4"><a id="p112397"></a>- Возмещение или другие суммы, выплачиваемые ................... (количество) <a href="#p112416">&lt;1&gt;</a><br>- Причитается к выплате возмещения или другие суммы по экспорту, отмененные для..................... (количество) <a href="#p112416">&lt;1&gt;</a></td></tr>
<tr><td colspan="5" rowspan="2"><a id="p112398"></a>(c) товары, которые были выпущены в свободное обращение для специального использования <a href="#p112416">&lt;1&gt;</a></td></tr>
<tr><td rowspan="2"></td></tr>
<tr><td colspan="5" rowspan="3"><a id="p112399"></a>(d) товары, имеющие происхождение в государствах-членах ЕС или товары третьей страны, находящиеся в свободном обращении <a href="#p112416">&lt;1&gt;</a></td></tr>
<tr><td><a id="p112400"></a>В ........, дата ..........</td><td colspan="4"><a id="p112401"></a>В .............., дата .................</td></tr>
<tr><td><a id="p112402"></a>(подпись) (печать)</td><td colspan="4"><a id="p112403"></a>(подпись) (печать)</td></tr>
<tr><td colspan="4" rowspan="2"><a id="p112404"></a>C. ЗАВЕРЕНИЕ ОРГАНИЗАЦИИ, ЗАВЕРШИВШЕЙ ТАМОЖЕННОЕ</td><td colspan="6"><a id="p112405"></a>11. ЗАПРОС ЭКСПОРТЕРА</td></tr>
<tr><td colspan="6" rowspan="2"><a id="p112406"></a>Нижеподписавшийся, являющийся экспортером <a href="#p112416">&lt;1&gt;</a></td></tr>
<tr><td colspan="4" rowspan="3"><a id="p112407"></a>ОФОРМЛЕНИЕ ЭКСПОРТА<br>Информация, данная в <a href="#p112369">графах 1</a> - <a href="#p112391">10</a>, является достоверной</td></tr>
<tr><td colspan="6"><a id="p112408"></a>от имени экспортера <a href="#p112416">&lt;1&gt;</a>,</td></tr>
<tr><td colspan="6" rowspan="2"><a id="p112409"></a>просит выдать данный информационный лист в целях реимпорта товаров, описанных в нем</td></tr>
<tr><td colspan="4"><a id="p112410"></a>Принятые меры по идентификации</td></tr>
<tr><td colspan="4"><a id="p112411"></a>В ............................, дата .............................</td><td colspan="6"><a id="p112412"></a>В ......... дата ................</td></tr>
<tr><td colspan="4"><a id="p112413"></a>(подпись) (печать)</td><td colspan="6"><a id="p112414"></a>(подпись)</td></tr>
</table>


<a id="p112415"></a>

---

<a id="p112416"></a><1> Зачеркнуть, где необходимо.


| <a id="p112417"></a>ПОЛНОЕ НАЗВАНИЕ И АДРЕС ТАМОЖЕННОГО УЧРЕЖДЕНИЯ ЭКСПОРТА |
| --- |


| <a id="p112418"></a>ПРИМЕЧАНИЯ |
| --- |
| <a id="p112419"></a>[Графа 1](https://bukva.ai/docs/reglament-20152447/statya-350#p112369): Укажите название или торговое название и полный адрес, включая государство-член ЕС |
| <a id="p112420"></a>[Графа 4](https://bukva.ai/docs/reglament-20152447/statya-350#p112381): Укажите точные сведения о товарах согласно их обычному коммерческому описанию или согласно их тарифному описанию. Описание должно соответствовать тому, которое используется в экспортном документе. |
| <a id="p112421"></a>[Графы 5](https://bukva.ai/docs/reglament-20152447/statya-350#p112382) и [6](https://bukva.ai/docs/reglament-20152447/statya-350#p112383): Укажите количество, указанное в экспортном документе. |
| <a id="p112422"></a>[Графа 7](https://bukva.ai/docs/reglament-20152447/statya-350#p112384): Укажите статистическую стоимость во время экспорта в валюте государства-члена ЕС экспорта. |
| <a id="p112423"></a>[Графа 8](https://bukva.ai/docs/reglament-20152447/statya-350#p112385): Укажите сведения о весе нетто, объеме и т.п., которое заинтересованное лицо желает реимпортировать. |
| <a id="p112424"></a>[Графа 10(c)](https://bukva.ai/docs/reglament-20152447/statya-350#p112398): Этот пункт относится к товарам, которые были выпущены в свободное обращение в Сообществе, освобожденным полностью или частично от уплаты импортных пошлин по причине их использования для специальных целей. |
| <a id="p112425"></a>[Графа 10(d)](https://bukva.ai/docs/reglament-20152447/statya-350#p112399): Этот пункт относится к ситуации с товарами во время их экспорта. |
|  |
| <a id="p112426"></a>ЗАПРОС УЧРЕЖДЕНИЯ РЕИМПОРТА |
| <a id="p112427"></a>Учреждение реимпорта, указанное ниже, запрашивает: |
| <a id="p112428"></a>- проверку подлинности данного информационного листа и достоверности информации в нем <1>: |
| <a id="p112429"></a>- предоставление следующей информации <1>: |
| <a id="p112430"></a><1> Зачеркнуть необходимое. |


| <a id="p112431"></a>Полное название и адрес учреждения реимпорта | <a id="p112432"></a>В ........................ дата .......................... |
| --- | --- |
|  | <a id="p112433"></a>(подпись) |


| <a id="p112434"></a>ОТВЕТ КОМПЕТЕНТНЫХ ОРГАНОВ<br>Данный информационный лист является подлинным, и сведения, содержащиеся в нем, - достоверными <1>.<br>Данный информационный лист вызывает следующие комментарии <1>:<br>Другая запрошенная информация <1>: |
| --- |
| <a id="p112435"></a><1> Зачеркнуть необходимое |


<table>
<colgroup><col width="50%"><col width="50%"></colgroup>
<tr><td rowspan="2"><a id="p112436"></a>Полное название и адрес учреждения реимпорта</td><td><a id="p112437"></a>В .......................... дата ...........................</td></tr>
<tr><td><a id="p112438"></a>(подпись)</td></tr>
</table>


<table>
<colgroup><col width="50%"><col width="50%"></colgroup>
<tr><td colspan="2"><a id="p112439"></a>РЕИМПОРТ</td></tr>
<tr><td rowspan="2"><a id="p112440"></a>Реимпортированное количество</td><td><a id="p112441"></a>Исходящий номер, дата и тип документа о реимпорте</td></tr>
<tr><td><a id="p112442"></a>Подпись и печать учреждения реимпорта</td></tr>
<tr><td></td><td></td></tr>
</table>


<a id="p112443"></a>Примечание, касающееся информационного листа INF 3

1. <a id="p112444"></a>Формы печатаются на белой бумаге, без механических вкраплений, предназначенной для целей написания, и должны иметь вес не менее 40 г/м2.
2. <a id="p112445"></a>Размер форм должен быть 210 x 297 мм, допускаются максимальные отклонения в длину от - 5 до 8 мм; должен строго соблюдаться вид форм, кроме размера [граф 6](https://bukva.ai/docs/reglament-20152447/statya-350#p112310) и [7](https://bukva.ai/docs/reglament-20152447/statya-350#p112311).
3. <a id="p112446"></a>Государства-члены ЕС отвечают за принятие необходимых мер для печати форм. Каждая форма должна иметь индивидуальный серийный номер, который может быть предварительно напечатан.
4. <a id="p112447"></a>Формы должны печататься на одном из официальных языков Союза, принятом компетентными органами государства-члена ЕС экспорта. Они должны заполняться на том же языке, на котором напечатана форма. При необходимости компетентные органы таможенного учреждения реимпорта, в котором требуется предоставление информационного [листа](https://bukva.ai/docs/reglament-20152447/statya-350#p112301) INF3, могут запросить его перевод на его официальный язык или один из его официальных языков.


<a id="p112448"></a>Приложение 72-01

<a id="p112449"></a>**ЖЕЛТЫЙ ЯРЛЫК**


<a id="p112450"></a>

<table>
<colgroup><col width="69%"><col width="10%"><col width="20%"></colgroup>
<tr><td>Товары, не выполняющие условия, изложенные в <a href="https://bukva.ai/docs/dogovor-o-funktsionirovanii-evropeyskogo-soyuza/statya-28#p100219">Статьях 28</a> и <a href="https://bukva.ai/docs/dogovor-o-funktsionirovanii-evropeyskogo-soyuza/statya-29#p100222">29</a> Договора о функционировании Европейского Союза</td><td rowspan="2">23</td><td>мм</td></tr>
</table>


<a id="p112451"></a>Цвет: черные буквы на желтом фоне


<a id="p112452"></a>Приложение 72-02

<a id="p112453"></a>**ЖЕЛТЫЙ ЯРЛЫК**

<a id="p112454"></a>                <──────────── 49 мм ────────────>

| Товары Союза, отгруженные из части таможенной территории Европейского Союза или в эту часть, если не применяются положения [Директивы](https://bukva.ai/docs/direktiva-2006112es/statya-1) 2006/112/ЕС Совета ЕС или [Директивы](https://bukva.ai/docs/direktiva-2008118es/statya-1) 2008/118/ЕС Совета ЕС | 23 | мм |
| --- | --- | --- |


<a id="p112455"></a>Цвет: черные буквы на желтом фоне


<a id="p112456"></a>Приложение 72-03


<table>
<colgroup><col width="4%"><col width="26%"><col width="4%"><col width="67%"></colgroup>
<tr><td colspan="4"><a id="p112457"></a>TC11 - РАСПИСКА</td></tr>
<tr><td colspan="4"></td></tr>
<tr><td colspan="4"><a id="p112458"></a>Таможенное учреждение назначения в .............. (место, название и исходящий номер)<br>настоящим удостоверяет, что транзитная декларация T1, T2, T2F &lt;1&gt;<br>зарегистрированная ................... (дд/мм/гггг) под N .............. (MRN) &lt;2&gt;<br>таможенным учреждением назначения в ............... (место, название и исходящий номер)<br>была подана.</td></tr>
<tr><td colspan="3"></td><td rowspan="3"><a id="p112459"></a>В ........................ дата ........................... (дд/мм/гггг).<br>...............................................................<br>(Подпись)</td></tr>
<tr><td></td><td><a id="p112460"></a>Официальная печать</td><td></td></tr>
<tr><td colspan="3"></td></tr>
<tr><td colspan="4"><a id="p112461"></a>--------------------------------<br>&lt;1&gt; Зачеркнуть при необходимости<br>&lt;2&gt; В случае временного сбоя электронной транзитной системы введите номер, используемый в BCP.</td></tr>
</table>


<a id="p112462"></a>Приложение 72-04

<a id="p112463"></a>**ПРОЦЕДУРА**
**НЕПРЕРЫВНОСТИ ДЕЯТЕЛЬНОСТИ ДЛЯ ТРАНЗИТА СОЮЗА**

<a id="p112464"></a>**ЧАСТЬ I**

<a id="p112465"></a>Глава I

<a id="p112466"></a>**ОБЩИЕ ПОЛОЖЕНИЯ**

1. <a id="p112467"></a>Настоящее положение устанавливает специальные положения для использования процедуры непрерывности деятельности согласно [Статье 291](https://bukva.ai/docs/reglament-20152447/statya-291#p102483) настоящего Регламента для владельцев процедуры, включая авторизованных грузоотправителей в случае временного сбоя:
- <a id="p112468"></a>электронной системы транзита;
- <a id="p112469"></a>компьютеризированной системы, используемой владельцами процедуры для подачи транзитной декларации Союза посредством электронных технологий обработки данных; или
- <a id="p112470"></a>электронной связи между компьютеризированной системой, используемой владельцами процедуры для подачи транзитной декларации Союза посредством электронных технологий обработки данных и электронной системы транзита.
2. <a id="p112471"></a>Транзитные декларации
<a id="p112472"></a>2.1. Транзитная декларация, используемая в процедуре непрерывности деятельности, должна быть признаваемой всеми сторонами, участвующими в транзитной операции, во избежание проблем в таможенном учреждении транзита, в таможенном учреждении назначения и по прибытии авторизованному грузополучателю. По этой причине используются только следующие документы:
- <a id="p112473"></a>Единый административный документ (SAD); или
- <a id="p112474"></a>SAD, напечатанный на простой бумаге компьютеризированной системой субъекта экономической деятельности, как предусмотрено в Приложении B-01 к Делегированному Регламенту (ЕС) 2015/2446; или
- <a id="p112475"></a>сопроводительный документ транзита (TAD)/сопроводительный документ транзита/безопасности (TSAD), дополненный при необходимости Списком пунктов (LoI) или Списком пунктов транзита/безопасности (TSLoI).
<a id="p112476"></a>2.2. Транзитная декларация может быть дополнена одним или несколькими листами-продолжениями с использованием формы, установленной в Приложении B-01 к Делегированному Регламенту (ЕС) 2015/2446. Формы должны являться неотъемлемой частью декларации. Списки погрузки, соответствующие [Части II, Главы IV](https://bukva.ai/docs/reglament-20152447/statya-350#p112615) настоящего Приложения и составленные с использованием формы, установленной в [Части II, Главе III](https://bukva.ai/docs/reglament-20152447/statya-350#p112607) настоящего Приложения, могут использоваться вместо листов-продолжений в качестве описательной части написанной транзитной декларации, неотъемлемой частью которой они являются.
<a id="p112477"></a>2.3. Для имплементации [пункта 2.1](https://bukva.ai/docs/reglament-20152447/statya-350#p112472). настоящего Приложения транзитная декларация заполняется в соответствии с Приложениями B к Делегированному Регламенту (ЕС) 2015/2446 и B к настоящему Регламенту.

<a id="p112478"></a>Глава II

<a id="p112479"></a>**ИМПЛЕМЕНТАЦИОННЫЕ ПРАВИЛА**

3. <a id="p112480"></a>Отсутствие электронной системы транзита.


- <a id="p112482"></a>транзитная декларация заполняется и подается в таможенное учреждение места отправления в копиях 1, 4 и 5 SAD в соответствии с Приложением B-01 к Делегированному Регламенту (ЕС) 2015/2446 или в двух копиях TAD/TSAD, дополненных при необходимости LoI или TSLoI в соответствии с Приложениями B-02, B-03, B-04 и B-05;
- <a id="p112483"></a>транзитная декларация регистрируется в графе C с использованием системы нумерации, отличающейся от системы, используемой в электронной системе транзита;
- <a id="p112484"></a>процедура непрерывности деятельности указывается на копиях транзитной декларации одним из штампов с использованием форм, установленных в [Части II, Главе I](https://bukva.ai/docs/reglament-20152447/statya-350#p112584) настоящего Приложения, в графе A SAD или вместо MRN и штрихкод в TAD/TSAD;
- <a id="p112485"></a>авторизованный грузоотправитель должен выполнить все обязательства и условия в отношении внесения записей в декларацию и использования специального штампа, указанного в [пунктах 22](https://bukva.ai/docs/reglament-20152447/statya-350#p112561) - [25](https://bukva.ai/docs/reglament-20152447/statya-350#p112576) настоящего Приложения, используя соответственно графы C и D;
- <a id="p112486"></a>на транзитной декларации ставится печать либо таможенного учреждения отправления в случае стандартной процедуры, либо авторизованного грузоотправителя, если применяется [Статья 233(4)(a)](https://bukva.ai/docs/reglament-9522013/statya-1#p101931).
<a id="p112487"></a>3.2. Если принято решение о применении процедуры непрерывности деятельности, все данные по транзиту с LRN или MRN, относящиеся к операции транзита, должны быть отозваны из электронной системы транзита на основании информации, представленной лицом, которое подало эти данные по транзиту в электронную систему транзита.
<a id="p112488"></a>3.3. Таможенный орган осуществляет мониторинг использования процедуры непрерывности деятельности во избежание ее неправильного использования.
4. <a id="p112489"></a>При отсутствии компьютеризированной системы, используемой владельцами процедуры для подачи данных транзитной декларации Союза посредством технологий электронной обработки данных или электронной связи между этой компьютеризированной системой и электронной системы транзита:
- <a id="p112490"></a>применяются положения, установленные в [пункте 3](https://bukva.ai/docs/reglament-20152447/statya-350#p112480) настоящего Приложения;
- <a id="p112491"></a>владелец процедуры информирует таможенный орган, если его компьютеризированная система или электронная связь между этой компьютеризированной системой и электронной системой транзита снова появилась.
5. <a id="p112492"></a>Отсутствие компьютеризированной системы авторизованного грузоотправителя или электронной связи между указанной компьютеризированной системой и электронной системой транзита.
<a id="p112493"></a>Если компьютеризированная система авторизованного грузоотправителя или связь между указанной компьютеризированной системой и электронной системой транзита отсутствуют, применяется следующая процедура:
- <a id="p112494"></a>применяются положения, установленные в [пункте 4](https://bukva.ai/docs/reglament-20152447/statya-350#p112489) настоящего Приложения;
- <a id="p112495"></a>если авторизованный грузоотправитель составляет более 2% своих деклараций в год по процедуре непрерывности деятельности, то разрешение пересматривается для оценки того, продолжают ли выполняться его условия.
6. <a id="p112496"></a>Сбор данных таможенным органом.
<a id="p112497"></a>Но в случаях, указанных в [пунктах 4](https://bukva.ai/docs/reglament-20152447/statya-350#p112489) и [5](https://bukva.ai/docs/reglament-20152447/statya-350#p112492) настоящего Приложения, таможенный орган может разрешить владельцу процедуры предоставлять транзитную декларацию в одной копии (используя SAD или TAD/TSAD) таможенному учреждению отправления для того, чтобы она была обработана электронной системой транзита.

<a id="p112498"></a>Глава III

<a id="p112499"></a>**ДЕЙСТВИЕ ПРОЦЕДУРЫ**

7. <a id="p112500"></a>Предоставление индивидуальной гарантии поручителем.
<a id="p112501"></a>Если таможенное учреждение гарантии не является таможенным учреждением отправления для транзитной операции, то оно должно хранить копию обязательства поручителя. Владелец процедуры представляет оригинал таможенному учреждению места отправления, где он должен храниться. При необходимости таможенное учреждение места отправления может запросить перевод на официальный язык или на один из официальных языков страны.
8. <a id="p112502"></a>Подписание транзитной декларации и обязательство владельца процедуры.
<a id="p112503"></a>Подписывая транзитную декларацию, владелец процедуры принимает ответственность за:
- <a id="p112504"></a>достоверность информации, данной в декларации;
- <a id="p112505"></a>подлинность представленных документов;
- <a id="p112506"></a>выполнение всех обязательств, относящихся к ввозу товаров по транзитной процедуре.
9. <a id="p112507"></a>Идентификационные меры.
<a id="p112508"></a>Если применяется [Статья 302](https://bukva.ai/docs/reglament-20152447/statya-302#p102568) настоящего Регламента, то таможенное учреждение места отправления вносит следующую фразу напротив заголовка "установленные пломбы" в графе "D. Контроль учреждения отправления" транзитной декларации.
- <a id="p112509"></a>Отмена - 99201.
10. <a id="p112510"></a>Записи в транзитной декларации и выпуск товаров.
- <a id="p112511"></a>Таможенное учреждение записывает результаты проверки в каждую копию транзитной декларации.
- <a id="p112512"></a>Если выводы проверки соответствуют декларации, то таможенное учреждение отправления выпускает товары и записывает дату в копиях транзитной декларации.
11. <a id="p112513"></a>Товары, помещенные на процедуру транзита, перевозятся по копиям 4 и 5 SAD или по одной копии TAD/TSAD, выданным владельцу процедуры таможенным учреждением места отправления. Копия 1 SAD и копия TAD/TSAD остаются в таможенном учреждении отправления.
12. <a id="p112514"></a>Таможенное учреждение транзита.
<a id="p112515"></a>12.1. Перевозчик предоставляет транзитное уведомление, составленное по форме, установленной в [Части II, Главы V](https://bukva.ai/docs/reglament-20152447/statya-350#p112660) настоящего Приложения, в каждое таможенное учреждение транзита, которое хранит его. Вместо транзитного уведомления может быть представлена фотокопия копии 4 SAD или фотокопия копии TAD/TSAD, которая хранится у таможенного учреждения транзита.
<a id="p112516"></a>12.2. Если товары перевозятся через другое таможенное учреждение транзита, кроме того, которое заявлено, то таможенное учреждение фактического транзита информирует таможенное учреждение места отправления.
13. <a id="p112517"></a>Представление в таможенное учреждение места назначения.
<a id="p112518"></a>13.1. Таможенное учреждение места назначения регистрирует копии транзитной декларации, записывает на них дату прибытия и вносит сведения о контроле, выполненным им.
<a id="p112519"></a>13.2. Транзитная операция может закончиться в другом учреждении, кроме таможенного учреждения, заявленного в транзитной декларации. Это учреждение затем становится таможенным учреждением фактического места назначения.
<a id="p112520"></a>Если таможенное учреждение фактического места назначения подпадает под юрисдикцию другого государства-члена ЕС, кроме того, которое имеет юрисдикцию над заявленным таможенным учреждением, то фактическое таможенное учреждение вносит в графу "I. Контроль учреждения места назначения" транзитной декларации следующую запись в дополнение к обычным замечаниям, которые должны быть сделаны:
- <a id="p112521"></a>Различия: таможенное учреждение, в которое были представлены товары ..... (номер таможенного учреждения) - 99203.
<a id="p112522"></a>13.3. Если применяется [второй параграф пункта 13.2](https://bukva.ai/docs/reglament-20152447/statya-350#p112520). настоящего Приложения и если транзитная декларация имеет следующее заявление, то таможенное учреждение фактического места назначения хранит товары под своим контролем и не разрешает их уничтожение другим, кроме государств-членов ЕС, имеющих юрисдикцию над таможенным учреждением места отправления, если последним не разрешено специально:
- <a id="p112523"></a>Вывоз из Союза согласно ограничениям или сборам по Регламенту/Директиве/Решению N ..... - 99204.
14. <a id="p112524"></a>Расписка.
<a id="p112525"></a>Расписка может быть составлена на обратной стороне копии 5 SAD в месте, предусмотренном или в форме, установленной в [Приложении 72-03](https://bukva.ai/docs/reglament-20152447/statya-350#p112457).
15. <a id="p112526"></a>Возврат копии 5 SAD или копии TAD/TSAD.
<a id="p112527"></a>Компетентный таможенный орган государства-члена ЕС места назначения возвращает копию 5 SAD таможенному органу в государстве-члене ЕС места отправления без промедления и самое позднее в течение 8 дней после завершения операции. Если используется TAD/TSAD, то на тех же условиях, что и копия 5, возвращается копия представленного TAD/TSAD.
16. <a id="p112528"></a>Информирование владельца процедуры и альтернативное доказательство завершения процедуры.
<a id="p112529"></a>Если копии, указанные в [пункте 15](https://bukva.ai/docs/reglament-20152447/statya-350#p112526) настоящего Приложения, не возвращены в таможенный орган государства-члена ЕС места отправления в течение 30 дней после срока представления товаров в таможенное учреждение места назначения, то этот орган информирует владельца процедуры и просит его представить доказательство того, что процедура была завершена правильно.
17. <a id="p112530"></a>Процедура запроса.
<a id="p112531"></a>17.1. Если таможенное учреждение места отправления не получило в течение 60 дней после срока предоставления товаров в таможенное учреждение места назначения доказательства того, что процедура была завершена правильно, то таможенное учреждение государства-члена ЕС места отправления незамедлительно запрашивает информацию, необходимую для завершения процедуры. Если во время этапов процедуры запроса установлено, что процедура транзита Союза не может быть завершена, то таможенный орган государства члена ЕС отправления устанавливает, возник ли таможенный долг.
<a id="p112532"></a>Если таможенный долг возник, то таможенное учреждение государства-члена ЕС места отправления принимает следующие меры:
- <a id="p112533"></a>определяет должника;
- <a id="p112534"></a>определяет таможенные органы, ответственные за уведомление о таможенном долге в соответствии со [Статьей 102(1)](https://bukva.ai/docs/reglament-9522013/statya-1#p100998) Кодекса.
<a id="p112535"></a>17.2. Если до истечения указанного срока таможенный орган государства-члена ЕС отправления получает информацию о том, что процедура транзита Союза не была завершена правильно, или у него есть подозрения в отношении этого, оно незамедлительно направляет запрос.
<a id="p112536"></a>17.3. Процедура запроса таким же образом должна быть инициирована, если выявлено впоследствии, что доказательство завершения транзитной процедуры было сфальсифицировано и что процедура запроса необходима для выполнения целей [пункта 17.1](https://bukva.ai/docs/reglament-20152447/statya-350#p112531) настоящего Приложения.
18. <a id="p112537"></a>Гарантия - базовая сумма.
<a id="p112538"></a>18.1. Для применения [Статьи 156](https://bukva.ai/docs/reglament-20152447/statya-156#p101463) владелец процедуры обеспечивает, чтобы поставленная сумма не превышала базовой суммы с учетом также всех операций, для которых процедура еще не завершена.
<a id="p112539"></a>18.2. Владелец процедуры информирует таможенное учреждение гарантии, если базовая сумма падает ниже уровня, достаточного для покрытия его транзитной операции.
19. <a id="p112540"></a>Сертификаты полной гарантии, сертификаты отказа от гарантии и расписки индивидуальной гарантии.


- <a id="p112542"></a>сертификат полной гарантии в [форме](https://bukva.ai/docs/reglament-20152447/statya-350#p112677), установленной в Главе VI;
- <a id="p112543"></a>сертификаты отказа от гарантии в [форме](https://bukva.ai/docs/reglament-20152447/statya-350#p112711), установленной в Главе VII;
- <a id="p112544"></a>расписка индивидуальной гарантии в [форме](https://bukva.ai/docs/reglament-20152447/statya-350#p112045), установленной в Приложении 32-06.
<a id="p112545"></a>19.2. Сведения сертификатов и расписки должны быть внесены в транзитные декларации.
<a id="p112546"></a>19.3. Срок действия сертификата полной гарантии или сертификат отказа от гарантии не должен превышать пяти лет. Но срок может быть продлен таможенным учреждением гарантии еще один раз не более чем на срок пять лет.
<a id="p112547"></a>Если в период срока действия сертификата таможенное учреждение гарантии информируется о том, что сертификат в результате многочисленных изменений не является достаточно читаемым и может быть отклонен таможенным упреждением места отправления, то таможенное упреждение гарантии должно признать сертификат недействительным и выдать при необходимости новый.
<a id="p112548"></a>Сертификаты со сроком действия два года продолжают действовать. Их срок действия может быть продлен таможенным учреждением гарантии на второй срок не выше пяти лет.
<a id="p112549"></a>19.4. С даты вступления в силу отзыва разрешения на использование полной гарантии или отзыва и отмены обязательства, предусмотренного в случае полной гарантии, любой выданный сертификат не может использоваться для помещения на процедуру транзита Союза и должен быть возвращен незамедлительно владельцем процедуры в таможенное учреждение гарантии.
<a id="p112550"></a>Каждое государство-член ЕС предоставляет Европейской Комиссии информацию о средствах, посредством которых сертификаты, которые остаются действующими и еще не были возвращены или которые были объявлены украденными, утраченными или сфальсифицированы, могут быть идентифицированы. Европейская Комиссия информирует другие государства-члены ЕС соответствующим образом.
20. <a id="p112551"></a>Специальные погрузочные списки.
<a id="p112552"></a>20.1. Таможенный орган может принять транзитную декларацию, дополненную погрузочными списками, которые не соответствуют всем требованиям, установленным в [Части II Главы III](https://bukva.ai/docs/reglament-20152447/statya-350#p112607) настоящего Приложения.
<a id="p112553"></a>Такие списки могут использоваться, только если:
- <a id="p112554"></a>они составлены компаниями с использованием электронной системы обработки данных для хранения своих отчетов;
- <a id="p112555"></a>они разработаны и составлены таким образом, что их без труда может использовать таможенный орган;
- <a id="p112556"></a>они включают в себя по каждому пункту информацию, требуемую согласно [Части II Главы IV](https://bukva.ai/docs/reglament-20152447/statya-350#p112615) настоящего Приложения.
<a id="p112557"></a>20.2. Описательные списки, составленные в целях выполнения оформления отправки/экспорта, могут быть также разрешены для использования в качестве погрузочных списков согласно [пункту 20.1](https://bukva.ai/docs/reglament-20152447/statya-350#p112552). настоящего Приложения, даже если такие списки составлены компаниями, не использующими электронную систему обработки данных для хранения своих отчетов.
<a id="p112558"></a>20.3. Владелец процедуры, который использует электронную систему обработки данных для хранения своих отчетов и уже использует специальные погрузочные списки, может также использовать их для операций транзита Союза, в которых участвует только один вид товаров, если эти мощности необходимы для системы владельца процедуры.
21. <a id="p112559"></a>Использование пломб специального вида.
<a id="p112560"></a>Владелец процедуры вносит в заголовок "пломбы установленные" в графе "D. Контроль учреждения отправления" транзитной декларации номер и индивидуальный идентификатор пломбы установленных пломб.
22. <a id="p112561"></a>Авторизованный грузоотправитель - предварительное удостоверение и формальности при отправлении.
<a id="p112562"></a>22.1. Для применения [пунктов 3](https://bukva.ai/docs/reglament-20152447/statya-350#p112480) и [5](https://bukva.ai/docs/reglament-20152447/statya-350#p112492) настоящего Приложения разрешение устанавливает, что графа "C. Учреждение отправления" транзитной декларации:
- <a id="p112563"></a>должна быть проштампована заранее печатью таможенного учреждения места отправления и подписана официальным лицом указанного учреждения; или
- <a id="p112564"></a>должна быть проштампована авторизованным грузоотправителем специальной печатью, одобренной компетентным органом, и с использованием формы, установленной в [Части II Главы II](https://bukva.ai/docs/reglament-20152447/statya-350#p112592) настоящего Приложения. Печать может быть предварительно напечатана на форме, если используется печатающая организация, одобренная для этих целей.
<a id="p112565"></a>Авторизованный грузоотправитель заполняет графу, внося дату, на которую товары отгружены, и присваивает номер транзитной декларации в соответствии с правилами, изложенными в разрешении.
<a id="p112566"></a>22.2. Таможенный орган может предписать использование форм, имеющих отличительный знак в качестве средства идентификации.
23. <a id="p112567"></a>Авторизованный грузоотправитель - меры безопасности для печати.
<a id="p112568"></a>Авторизованный грузоотправитель принимает все необходимые меры для обеспечения безопасного хранения специальных печатей или форм, имеющих печать таможенного учреждения отправления или специальную печать.
<a id="p112569"></a>Он информирует таможенный орган о мерах безопасности, которые он принимает для применения в соответствии с [первым подпараграфом](https://bukva.ai/docs/reglament-20152447/statya-350#p112567).
<a id="p112570"></a>23.1. В случае неправильного использования любым лицом форм, проштампованных таможенным учреждением места отправления или специальным штампом, авторизованный грузоотправитель обязан, без ущерба каким-либо уголовным процедурам, оплатить пошлины и другие сборы, оплачиваемые в отдельной стране в отношении товаров, перевозимых согласно таким формам, если он не может доказать к удовлетворению таможенного органа, которым он был авторизован, что он принял меры, необходимые от него согласно [пункту 23](https://bukva.ai/docs/reglament-20152447/statya-350#p112567).
24. <a id="p112571"></a>Авторизованный грузоотправитель - информация, вносимая в декларацию.
<a id="p112572"></a>24.1. Не позднее отгрузки товаров авторизованный грузоотправитель заполняет транзитную декларацию и при необходимости вносит в графу 44 маршрут, предписанный в соответствии со [Статьей 298](https://bukva.ai/docs/reglament-20152447/statya-298#p102527) настоящего Регламента, и в графу "D. Контроль учреждения отправления" срок, предписанный в соответствии со [Статьей 297](https://bukva.ai/docs/reglament-20152447/statya-297#p102519) настоящего Регламента, в течение которого товары должны быть представлены в таможенное учреждение места назначения, а также применяемые идентификационные меры и следующую запись:
- <a id="p112573"></a>Авторизованный грузоотправитель - 99206
<a id="p112574"></a>24.2. Если компетентный орган государства-члена ЕС места отправления проверяет груз до его отправления, то он записывает этот факт в декларации, в графе "D. Контроль учреждения отправления".
<a id="p112575"></a>24.3. После отгрузки копия 1 SAD или копия TAD/TSAD поставляется без промедления в таможенное учреждение отправления согласно правилам, изложенным в разрешении. Другие копии сопровождают товары в соответствии с [пунктом 11](https://bukva.ai/docs/reglament-20152447/statya-350#p112513) настоящего Приложения.
25. <a id="p112576"></a>Авторизованный грузоотправитель - Отмена подписи.
<a id="p112577"></a>25.1. Авторизованному грузоотправителю может быть разрешено таможенным органом не подписывать транзитную декларацию, имеющую специальную печать, указанную в [Главе II Части II](https://bukva.ai/docs/reglament-20152447/statya-350#p112592) настоящего Приложения, которая составлена электронной системой обработки данных. Эта отмена разрешается, при условии что авторизованный грузоотправитель предварительно дал таможенному органу письменное обязательство, подтверждающее, что он является владельцем процедуры для всех транзитных операций, выполняемых согласно таможенным декларациям, имеющим специальную печать.
<a id="p112578"></a>25.2. Транзитная декларация, составленная в соответствии с [пунктом 25.1](https://bukva.ai/docs/reglament-20152447/statya-350#p112577). настоящего Приложения, должна содержать в графах, оставленных для подписи владельца процедуры, следующую фразу:
- <a id="p112579"></a>Подпись отменена - 99207.
26. <a id="p112580"></a>Авторизованный грузополучатель - Обязательства.
<a id="p112581"></a>26.1. Если товары прибывают в место, определенное в разрешении, то авторизованный грузополучатель без промедления информирует таможенное учреждение места назначения об этом прибытии. Он указывает дату прибытия, состояние всех установленных пломб и все нарушения в копиях 4 и 5 SAD или в копии TAD/TSAD, которые сопровождают товары, и доставляет их в таможенное учреждение места назначения согласно правилам, изложенным в разрешении.
<a id="p112582"></a>26.2. Таможенное учреждение места назначения вносит записи, предусмотренные в [пункте 13](https://bukva.ai/docs/reglament-20152447/statya-350#p112517) настоящего Приложения, в копии 4 и 5 SAD или в копии TAD/TSAD.

<a id="p112583"></a>**ЧАСТЬ II**

<a id="p112584"></a>Глава I

<a id="p112585"></a>**ОБРАЗЦЫ ПЕЧАТЕЙ, ИСПОЛЬЗУЕМЫХ ДЛЯ ПРОЦЕДУРЫ**
**НЕПРЕРЫВНОСТИ ДЕЯТЕЛЬНОСТИ**

1. <a id="p112586"></a>Штамп N 1


|  | <a id="p112587"></a>ЗАПАСНАЯ ПРОЦЕДУРА NCTS<br>ТРАНЗИТ СОЮЗА/ОБЩИЙ ТРАНЗИТ<br>ДАННЫХ В СИСТЕМЕ НЕ ИМЕЕТСЯ<br>НАЧАТО ________________________<br>(Дата/час) |
| --- | --- |
|  | <a id="p112588"></a>(размеры: 26 x 59 мм) |


2. <a id="p112589"></a>Штамп N 2


|  | <a id="p112590"></a>ПРОЦЕДУРА НЕПРЕРЫВНОСТИ ДЕЯТЕЛЬНОСТИ<br>ТРАНЗИТ СОЮЗА/ОБЩИЙ ТРАНЗИТ<br>ДАННЫХ В СИСТЕМЕ НЕ ИМЕЕТСЯ<br>НАЧАТО ________________________<br>(Дата/час) |
| --- | --- |
|  | <a id="p112591"></a>(размеры: 26 x 59 мм) |


<a id="p112592"></a>Приложение II

<a id="p112593"></a>**ОБРАЗЕЦ СПЕЦИАЛЬНОЙ ПЕЧАТИ, ИСПОЛЬЗУЕМОЙ АВТОРИЗОВАННЫМ**
**ГРУЗООТПРАВИТЕЛЕМ/АВТОРИЗОВАННЫМ ЛИЦОМ, ВЫДАВШИМ ЕЕ**


<table>
<colgroup><col width="20%"><col width="47%"><col width="8%"><col width="25%"></colgroup>
<tr><td><a id="p112594"></a>1</td><td colspan="3"><a id="p112595"></a>2</td></tr>
<tr><td colspan="3"><a id="p112596"></a>3</td><td><a id="p112597"></a>4</td></tr>
<tr><td colspan="2"><a id="p112598"></a>5</td><td colspan="2"><a id="p112599"></a>6</td></tr>
</table>


<a id="p112600"></a>(размеры: 55 x 25 мм)

1. <a id="p112601"></a>Герб или какие-либо другие знаки или буквы, характеризующие страну
2. <a id="p112602"></a>Исходящий номер таможенного учреждения отправления
3. <a id="p112603"></a>Номер декларации
4. <a id="p112604"></a>Дата
5. <a id="p112605"></a>Авторизованный грузоотправитель/авторизованное лицо, выдавшее печать
6. <a id="p112606"></a>Номер разрешения

<a id="p112607"></a>Глава III

<a id="p112608"></a>**ПОГРУЗОЧНЫЙ СПИСОК**


<table>
<colgroup><col width="8%"><col width="38%"><col width="14%"><col width="4%"><col width="14%"><col width="8%"><col width="13%"></colgroup>
<tr><td colspan="3" rowspan="4"></td><td colspan="3"></td><td rowspan="4"></td></tr>
<tr><td colspan="3"></td></tr>
<tr><td><a id="p112609"></a>N</td><td><a id="p112610"></a>Маркировки, номера и вид упаковки, описание товаров</td><td colspan="2"><a id="p112611"></a>Страна отправления/экспорта</td><td><a id="p112612"></a>Масса брутто (кг)</td><td colspan="2"><a id="p112613"></a>Для официального использования</td></tr>
<tr><td rowspan="9"></td><td rowspan="9"></td><td colspan="2" rowspan="9"></td><td></td><td colspan="2" rowspan="9"></td></tr>
<tr><td></td></tr>
<tr><td></td></tr>
<tr><td></td></tr>
<tr><td></td></tr>
<tr><td></td></tr>
<tr><td></td></tr>
<tr><td></td></tr>
<tr><td></td></tr>
<tr><td colspan="7"><a id="p112614"></a>(подпись)</td></tr>
</table>


<a id="p112615"></a>Глава IV

<a id="p112616"></a>**ПОЯСНЕНИЯ ПО ПОГРУЗОЧНОМУ СПИСКУ**

<a id="p112617"></a>Раздел 1

1. <a id="p112618"></a>Определение
<a id="p112619"></a>1.1. Погрузочный список - документ, имеющий характеристики, описанные в настоящем Приложении.
<a id="p112620"></a>1.2. Он может использоваться с транзитной декларацией в рамках применения [пункта 2.2](https://bukva.ai/docs/reglament-20152447/statya-350#p112476). настоящего Приложения.
2. <a id="p112621"></a>Форма погрузочного списка
<a id="p112622"></a>2.1. Только лицевая часть формы может использоваться в качестве погрузочного списка.


<a id="p112624"></a>(a) заголовок "Погрузочный список";
<a id="p112625"></a>(b) графа 70 x 55 мм, разделенная на верхнюю часть 70 на 15 мм и нижнюю часть 70 на 40 мм;
<a id="p112626"></a>(c) колонки со следующими заголовками в следующем порядке:
- <a id="p112627"></a>серийный номер;
- <a id="p112628"></a>маркировки, номера, количество и вид упаковок, описание товаров;
- <a id="p112629"></a>страна отправления/экспорта;
- <a id="p112630"></a>масса брутто (кг);
- <a id="p112631"></a>для администрации.
<a id="p112632"></a>Пользователи могут корректировать ширину колонок по своим потребностям. Но колонка "для администрации" должна всегда быть шириной не менее 30 мм. Пользователи могут также сами принимать решение, как использовать другие места, указанные в [пунктах (a)](https://bukva.ai/docs/reglament-20152447/statya-350#p112624), [(b)](https://bukva.ai/docs/reglament-20152447/statya-350#p112625) и [(c)](https://bukva.ai/docs/reglament-20152447/statya-350#p112626).
<a id="p112633"></a>2.3. Горизонтальная линия должна быть проведена сразу же после последней записи, а все неиспользованное пространство должно быть перечеркнуто во избежание более позднего дополнения.

<a id="p112634"></a>Часть 2

<a id="p112635"></a>Сведения, вносимые в графы под различными заголовками

1. <a id="p112636"></a>Графа


<a id="p112638"></a>Если погрузочный лист сопровождает транзитную декларацию, то владелец процедуры вносит "T1", "T2" или "T2F" в верхнюю часть графы.
2. <a id="p112639"></a>Нижняя часть
<a id="p112640"></a>Сведения, указанные в [параграфе 4 Раздела III](https://bukva.ai/docs/reglament-20152447/statya-350#p112656) ниже, должны быть внесены в данную часть графы.
2. <a id="p112641"></a>Колонки


<a id="p112643"></a>Каждому пункту, показанному в погрузочном списке, должен предшествовать серийный номер.


<a id="p112645"></a>Необходимые сведения должны быть даны в соответствии с Приложением B к Делегированному Регламенту (ЕС) 2015/2446.
<a id="p112646"></a>Если погрузочный список сопровождает транзитную декларацию, то список должен включать в себя информацию, внесенную в графы 31 (Упаковки и описание товаров), 40 (Сводная декларация/предыдущий документ), 44 (Дополнительная информация, представленные документы, сертификаты и разрешения) и при необходимости 33 (Код товара) и 38 (Масса нетто (кг)) транзитной декларации.


<a id="p112648"></a>Внесите название государства-члена ЕС, из которого товары были отгружены или экспортированы.


<a id="p112650"></a>Внесите сведения, внесенные в графу 35 SAD (см. Приложение B к Делегированному Регламенту (ЕС) 2015/2446).

<a id="p112651"></a>Раздел 3

<a id="p112652"></a>Использование погрузочных списков

1. <a id="p112653"></a>Транзитная декларация не может иметь и погрузочный список, и один или несколько листов продолжений, приложенных к ней.
2. <a id="p112654"></a>Если используется погрузочный список, графы 15 (Страна отправления/экспорта), 32 (Номер пункта), 33 (Код товара), 35 (Масса брутто (кг)), 38 (Масса нетто (кг)), 40 (Сводная декларация/предыдущий документ) и при необходимости 44 (Дополнительная информация, представленные документы, сертификаты и разрешения) формы транзитной декларации должны быть перечеркнуты, а графа 31 (Упаковка и описание товаров) не может использоваться для внесения маркировок, номеров, количества и вида упаковок или описания товаров. Ссылка на серийный номер и символ различных погрузочных списков должны быть внесены в графу 31 (Упаковки и описание товаров) транзитной декларации.
3. <a id="p112655"></a>Погрузочный список должен быть составлен в количестве копий, равном количеству копий транзитной декларации, к которой он относится.
4. <a id="p112656"></a>Если транзитная декларация зарегистрирована, то погрузочный список должен быть дан под тем же самым регистрационным номером, что и копии транзитной декларации, к которой он относится. Этот номер должен быть внесен с использованием печати, которая включает в себя название таможенного учреждения отправления или вручную. Если вносится вручную, то он должен быть написан на официальной печати таможенного учреждения отправления.
<a id="p112657"></a>Подписывать формы официальному лицу таможенного учреждения отправления необязательно.
5. <a id="p112658"></a>Если несколько погрузочных списков приложены к одной транзитной декларации, то списки должны иметь серийный номер, присвоенный владельцем процедуры, и количество приложенных погрузочных списков должно быть внесено в графу 4 (Погрузочные списки).
6. <a id="p112659"></a>Формы погрузочного списка должны быть напечатаны на бумаге, подходящей для целей письма, имеющей плотность не менее 40 г/м2 и достаточно прочной для предотвращения легкого разрыва или смятия при обычном использовании. Решение по цвету может быть принято заинтересованными лицами. Формат форм должен составлять 210 на 297 мм с максимальным отступлением минус 5 мм и плюс 8 мм по длине.

<a id="p112660"></a>Глава V

<a id="p112661"></a>**УВЕДОМЛЕНИЕ ОБ ОТПРАВКЕ ГРУЗА ТРАНЗИТОМ**


<table>
<colgroup><col width="32%"><col width="33%"><col width="36%"></colgroup>
<tr><td colspan="3"><a id="p112662"></a>TC 10 - УВЕДОМЛЕНИЕ ОБ ОТПРАВКЕ ГРУЗА ТРАНЗИТОМ</td></tr>
<tr><td colspan="3"><a id="p112663"></a>Идентификация транспортного средства: ...........................................</td></tr>
<tr><td colspan="2"><a id="p112664"></a>ТРАНЗИТНАЯ ДЕКЛАРАЦИЯ</td><td rowspan="2"><a id="p112665"></a>ИСХОДЯЩИЙ НОМЕР ПРЕДПОЛАГАЕМОГО УЧРЕЖДЕНИЯ ТРАНЗИТА</td></tr>
<tr><td><a id="p112666"></a>Тип (T1, T2 или T2F) и номер</td><td><a id="p112667"></a>Исходящий номер таможенного учреждения отправления</td></tr>
<tr><td rowspan="12"></td><td rowspan="12"></td><td></td></tr>
<tr><td></td></tr>
<tr><td></td></tr>
<tr><td><a id="p112668"></a>ДЛЯ ОФИЦИАЛЬНОГО ИСПОЛЬЗОВАНИЯ</td></tr>
<tr><td><a id="p112669"></a>Дата транзита:</td></tr>
<tr><td><a id="p112670"></a>.......................................</td></tr>
<tr><td><a id="p112671"></a>.......................................</td></tr>
<tr><td><a id="p112672"></a>(Подпись)</td></tr>
<tr><td></td></tr>
<tr><td><a id="p112673"></a>Официальная</td></tr>
<tr><td><a id="p112674"></a>печать</td></tr>
<tr><td></td></tr>
</table>


<a id="p112675"></a>Глава VI

<a id="p112676"></a>**СЕРТИФИКАТ ПОЛНОЙ ГАРАНТИИ**

<a id="p112677"></a>**TC 31 - СЕРТИФИКАТ ПОЛНОЙ ГАРАНТИИ**

<a id="p112678"></a>Лицевая сторона


<table>
<colgroup><col width="35%"><col width="11%"><col width="4%"><col width="4%"><col width="4%"><col width="12%"><col width="29%"></colgroup>
<tr><td><a id="p112679"></a>1. Действует до</td><td><a id="p112680"></a>День</td><td colspan="3"><a id="p112681"></a>Месяц</td><td><a id="p112682"></a>Год</td><td><a id="p112683"></a>2. Номер</td></tr>
<tr><td></td><td></td><td colspan="3"></td><td></td><td></td></tr>
<tr><td><a id="p112684"></a>3. Владелец процедуры (ФИО или наименование компании, полный адрес и страна)</td><td colspan="6"></td></tr>
<tr><td><a id="p112685"></a>4. Поручитель (ФИО или наименование компании, полный адрес и страна)</td><td colspan="6"></td></tr>
<tr><td><a id="p112686"></a>5. Таможенное учреждение гарантии (Исходящий номер)</td><td colspan="6"></td></tr>
<tr><td><a id="p112687"></a>6. Базовая сумма</td><td colspan="3"><a id="p112688"></a>цифрами:</td><td colspan="3"><a id="p112689"></a>прописью:</td></tr>
<tr><td><a id="p112690"></a>Код валюты</td><td colspan="3"></td><td colspan="3"></td></tr>
<tr><td colspan="7"><a id="p112691"></a>7. Таможенное учреждение гарантии удостоверяет, что владелец процедуры, названный выше, представляет полную гарантию, которая действует для транзитной операции Союза/общей транзитной операции на таможенных территориях, указанных ниже, наименования которых не были зачеркнуты:</td></tr>
<tr><td colspan="7"><a id="p112692"></a>Европейский Союз - Исландия - Северная Македония - Норвегия - Сербия - Швейцария - Турция - Украина - Соединенное Королевство <a href="#p112700">&lt;**&gt;</a> - Андорра <a href="#p112699">&lt;*&gt;</a> - Сан-Марино <a href="#p112699">&lt;*&gt;</a></td></tr>
<tr><td colspan="7"></td></tr>
<tr><td colspan="3"><a id="p112693"></a>8. Специальные замечания</td><td colspan="4"></td></tr>
<tr><td colspan="3"><a id="p112694"></a>9. Срок действия продлен до<br>дд/мм/гг включительно<br>Составлено в ......., ........<br>(место)   (дата)</td><td colspan="4"><a id="p112695"></a>Составлено в ......, .......<br>(место)   (дата)</td></tr>
<tr><td colspan="3"><a id="p112696"></a>(Подпись и печать учреждения гарантии)</td><td colspan="4"><a id="p112697"></a>(Подпись и печать учреждения гарантии)</td></tr>
</table>


<a id="p112698"></a>

---

<a id="p112699"></a><*> Только для транзитных операций Союза
<a id="p112700"></a><**> Согласно Протоколу по Ирландии/Северной Ирландии Соглашения о выходе Соединенного Королевства Великобритании и Северной Ирландии из Европейского Союза и Европейского Сообщества по атомной энергии Северная Ирландия должна считаться частью Европейского Союза в целях настоящей гарантии.

<a id="p112701"></a>Обратная сторона

10. <a id="p112702"></a>Лица, имеющие право подписи транзитной декларации Союза/общей транзитной декларации от имени владельца процедуры


| <a id="p112703"></a>11. ФИО и образец подписи лица, имеющего право подписи | <a id="p112704"></a>12. Подпись владельца процедуры [<*>](https://bukva.ai/docs/reglament-20152447/statya-350#p112708) | <a id="p112705"></a>11. ФИО и образец подписи лица, имеющего право подписи | <a id="p112706"></a>12. Подпись владельца процедуры [<*>](https://bukva.ai/docs/reglament-20152447/statya-350#p112708) |
| --- | --- | --- | --- |
|  |  |  |  |
|  |  |  |  |
|  |  |  |  |
|  |  |  |  |
|  |  |  |  |
|  |  |  |  |
|  |  |  |  |


<a id="p112707"></a>

---

<a id="p112708"></a><*> Если владелец процедуры является юридическим лицом, лицо, чья подпись указана в [графе 12](https://bukva.ai/docs/reglament-20152447/statya-350#p112704), должно добавить к своей подписи свои ФИО и должность.

<a id="p112709"></a>Глава VII

<a id="p112710"></a>**СЕРТИФИКАТ ОТМЕНЫ ГАРАНТИИ**

<a id="p112711"></a>**TC 31 - СЕРТИФИКАТ ОТМЕНЫ ГАРАНТИИ**

<a id="p112712"></a>Лицевая сторона


<table>
<colgroup><col width="33%"><col width="17%"><col width="3%"><col width="14%"><col width="17%"><col width="16%"></colgroup>
<tr><td><a id="p112713"></a>1. Действует до</td><td><a id="p112714"></a>День</td><td colspan="2"><a id="p112715"></a>Месяц</td><td><a id="p112716"></a>Год</td><td><a id="p112717"></a>2. Номер</td></tr>
<tr><td></td><td></td><td colspan="2"></td><td></td><td></td></tr>
<tr><td><a id="p112718"></a>3. Владелец процедуры (ФИО или наименование компании, полный адрес и страна)</td><td colspan="5"></td></tr>
<tr><td><a id="p112719"></a>4. Таможенное учреждение гарантии (Исходящий номер)</td><td colspan="5"></td></tr>
<tr><td><a id="p112720"></a>5. Базовая сумма</td><td colspan="2" rowspan="2"><a id="p112721"></a>цифрами:</td><td colspan="3" rowspan="2"><a id="p112722"></a>прописью:</td></tr>
<tr><td><a id="p112723"></a>Код валюты</td></tr>
<tr><td colspan="6"><a id="p112724"></a>6. Таможенное учреждение гарантии удостоверяет, что владельцу процедуры, названному выше, разрешена отмена гарантии в отношении транзитной операции Союза/общей транзитной операции на таможенных территориях, указанных ниже, наименования которых не были зачеркнуты:</td></tr>
<tr><td colspan="6"><a id="p112725"></a>Европейский Союз - Исландия - Северная Македония - Норвегия - Сербия - Швейцария - Турция, - Украина - Соединенное Королевство <a href="#p112737">&lt;**&gt;</a> - Андорра <a href="#p112736">&lt;*&gt;</a> Сан-Марино <a href="#p112736">&lt;*&gt;</a></td></tr>
<tr><td colspan="6"></td></tr>
<tr><td colspan="2"><a id="p112726"></a>7. Специальные замечания</td><td colspan="4"></td></tr>
<tr><td colspan="2"><a id="p112727"></a>8. Срок действия продлен до</td><td colspan="4"><a id="p112728"></a>Составлено в ......................,.................</td></tr>
<tr><td colspan="2"><a id="p112729"></a>дд/мм/гг включительно</td><td colspan="4" rowspan="3"><a id="p112730"></a>(место) (дата)</td></tr>
<tr><td colspan="2"><a id="p112731"></a>Составлено в ......................,.................</td></tr>
<tr><td colspan="2"><a id="p112732"></a>(место) (дата)</td></tr>
<tr><td colspan="2"><a id="p112733"></a>(Подпись и печать учреждения гарантии)</td><td colspan="4"><a id="p112734"></a>(Подпись и печать учреждения гарантии)</td></tr>
<tr><td colspan="2"></td><td colspan="4"></td></tr>
</table>


<a id="p112735"></a>

---

<a id="p112736"></a><*> Только для транзитных операций Союза
<a id="p112737"></a><**> Согласно Протоколу по Ирландии/Северной Ирландии Соглашения о выходе Соединенного Королевства Великобритании и Северной Ирландии из Европейского Союза и Европейского Сообщества по атомной энергии Северная Ирландия должна считаться частью Европейского Союза в целях настоящей гарантии.

<a id="p112738"></a>Обратная сторона

9. <a id="p112739"></a>Лица, имеющие право подписи транзитной декларации Союза/общей транзитной декларации от имени владельца процедуры


| <a id="p112740"></a>10. ФИО и образец подписи лица, имеющего право подписи | <a id="p112741"></a>11. Подпись владельца процедуры [<*>](https://bukva.ai/docs/reglament-20152447/statya-350#p112745) | <a id="p112742"></a>10. ФИО и образец подписи лица, имеющего право подписи | <a id="p112743"></a>11. Подпись владельца процедуры [<*>](https://bukva.ai/docs/reglament-20152447/statya-350#p112745) |
| --- | --- | --- | --- |
|  |  |  |  |
|  |  |  |  |
|  |  |  |  |
|  |  |  |  |
|  |  |  |  |
|  |  |  |  |
|  |  |  |  |


<a id="p112744"></a>

---

<a id="p112745"></a><*> Если владелец процедуры является юридическим лицом, лицо, чья подпись указана в [графе 11](https://bukva.ai/docs/reglament-20152447/statya-350#p112741), должно добавить к своей подписи свои ФИО и должность.

<a id="p112746"></a>Глава VIII

<a id="p112747"></a>**ПОЯСНЕНИЯ К СЕРТИФИКАТАМ ПОЛНОЙ ГАРАНТИИ**
**И СЕРТИФИКАТАМ ОТМЕНЫ ГАРАНТИИ**

1. <a id="p112748"></a>Сведения, вносимые в лицевую страницу сертификата

<a id="p112749"></a>После того, как он выдан, не должно быть изменений, дополнений или исключений в [графах 1](https://bukva.ai/docs/reglament-20152447/statya-350#p112679) - [8](https://bukva.ai/docs/reglament-20152447/statya-350#p112693) сертификата полной гарантии или в [графах 1](https://bukva.ai/docs/reglament-20152447/statya-350#p112713) - [7](https://bukva.ai/docs/reglament-20152447/statya-350#p112726) сертификата отмены гарантии.


<a id="p112751"></a>Государства-члены ЕС вносят в [графу 6](https://bukva.ai/docs/reglament-20152447/statya-350#p112687) сертификата полной гарантии и [графу 5](https://bukva.ai/docs/reglament-20152447/statya-350#p112720) сертификата отмены гарантии код используемой валюты ISO ALPHA 3 (ISO 4217).


<a id="p112753"></a>Если владелец процедуры принял обязательство подавать все свои транзитные декларации в определенное таможенное учреждение места отправления, то наименование учреждения должно быть внесено заглавными буквами в [графу 8](https://bukva.ai/docs/reglament-20152447/statya-350#p112693) сертификата полной гарантии или в [графу 7](https://bukva.ai/docs/reglament-20152447/statya-350#p112726) сертификата отмены гарантии.


<a id="p112755"></a>Если срок действия сертификата продлен, то таможенное учреждение гарантии должно внести запись в [графу 8](https://bukva.ai/docs/reglament-20152447/statya-350#p112693) сертификата полной гарантии или в [графу 7](https://bukva.ai/docs/reglament-20152447/statya-350#p112726) сертификата отмены гарантии.

2. <a id="p112756"></a>Сведения, вносимые в оборотную сторону сертификата -
лица, имеющие право подписи транзитной декларации

<a id="p112757"></a>2.1. Когда сертификат выдан или в любое время во время его срока действия, владелец процедуры должен внести с оборотной стороны наименования (имена) лиц, которым он дал разрешение на подпись транзитных деклараций. Каждая из этих записей должна содержать ФИО авторизированного лица и образец его подписи, и каждая запись должна быть завизирована владельцем процедуры. Владелец процедуры может по выбору зачеркнуть все графы, которые он не желает использовать.
<a id="p112758"></a>2.2. Владелец процедуры может аннулировать это разрешение в любое время.
<a id="p112759"></a>2.3. Любое лицо, чье имя внесено в обратную сторону сертификата этого вида, который представлен в таможенное учреждение отправления, является авторизированным представителем владельца процедуры.

3. <a id="p112760"></a>Технические требования

<a id="p112761"></a>3.1. Формы сертификатов полной гарантии и сертификатов отмены гарантии должны быть напечатаны на белой бумаге, без древесной массы, имеющей плотность не менее 100 г/м2. Обе стороны должны иметь напечатанный фон в виде напечатанного орнамента с тем, чтобы предотвратить фальсификацию механическими или химическими средствами. Печатать необходимо:
- <a id="p112762"></a>зеленым цветом для сертификатов полной гарантии;
- <a id="p112763"></a>бледно-голубым цветом для сертификатов отмены гарантии.


<a id="p112765"></a>3.3. Государства-члены ЕС отвечают за печать форм или обеспечивают печать форм. Каждый сертификат должен иметь серийный идентификационный номер.
<a id="p112766"></a>3.4. Недопустимо делать исправления или изменения. Изменения выполняются посредством зачеркивания неправильных сведений и при необходимости добавления требуемых сведений. Все такие изменения подписываются лицом, вносящим изменения, и удостоверяются таможенным органом.


<a id="p112767"></a>COMMISSION IMPLEMENTING REGULATION (EU) No. 2015/2447
**LAYING DOWN DETAILED RULES FOR IMPLEMENTING**
**CERTAIN PROVISIONS OF REGULATION (EU) NO 952/2013**
**OF THE EUROPEAN PARLIAMENT AND OF THE COUNCIL**
**LAYING DOWN THE UNION CUSTOMS CODE <*>**

<a id="p112768"></a>(Brussels, 24 November 2015)

<a id="p112769"></a>(Amended by:
Commission Implementing Regulation (EU) 2017/989 of 8 June
2017, Commission Implementing Regulation (EU) 2018/604 of 18
April 2018, Commission Implementing Regulation (EU)
2019/1394 of 10 September 2019, Commission Implementing
Regulation (EU) 2020/893 of 29 June 2020, Commission
Implementing Regulation (EU) 2020/1727 of 18 November 2020,
Commission Implementing Regulation (EU) 2020/2038 of 10
December 2020, Commission Implementing Regulation (EU)
2021/235 of 8 February 2021, Commission Implementing
Regulation (EU) 2022/2334 of 29 November 2022, Commission
Implementing Regulation (EU) 2023/403 of 8 February 2023)

<a id="p112770"></a>(Corrected by:
(Corrigendum, OJ L 87, 2.4.2016, p. 35 (2015/2447))


<a id="p112771"></a>

---

<a id="p112772"></a><*> This text is meant purely as a documentation tool and has no legal effect. The Union's institutions do not assume any liability for its contents. The authentic versions of the relevant acts, including their preambles, are those published in the Official Journal of the European Union and available in EUR-Lex. Those official texts are directly accessible through the links embedded in this document

<a id="p112773"></a>**TITLE I. GENERAL PROVISIONS**

<a id="p112774"></a>**CHAPTER 1**

<a id="p112775"></a>**SCOPE OF THE CUSTOMS LEGISLATION,**
**MISSION OF CUSTOMS AND DEFINITIONS**

<a id="p112776"></a>Article 1

<a id="p112777"></a>Definitions

<a id="p112778"></a>(1) For the purposes of this Regulation, Article 1 of Commission Delegated Regulation (EU) 2015/2446 <*> shall apply.

<a id="p112779"></a>

---

<a id="p112780"></a><*> Commission Delegated Regulation (EU) 2015/2446 of 28 July 2015 supplementing Regulation (EU) No 952/2013 of the European Parliament and of the Council with regard to detailed rules of specifying some of the provisions of the Union Customs Code (see page 1 of this Official Journal).

<a id="p112781"></a>(2) For the purposes of this Regulation, the following definitions shall apply:
<a id="p112782"></a>(1) "cabin baggage" means, in the case of air travel, the baggage that the natural person takes with him into and out of the aircraft cabin;
<a id="p112783"></a>(2) "customs office of presentation" means the customs office competent for the place where the goods are presented;
<a id="p112784"></a>(3) "hold baggage", in the case of air travel, means the baggage that has been checked in at the airport of departure and is not accessible to the natural person during the flight nor, where relevant, during any stopovers;
<a id="p112785"></a>(4) "identical goods" means, in the context of customs valuation, goods produced in the same country which are the same in all respects, including physical characteristics, quality and reputation. Minor differences in appearance shall not preclude goods otherwise conforming to the definition from being regarded as identical;
<a id="p112786"></a>(5) "international Union airport" means any Union airport which, having been so authorised by the customs authority, is approved for air traffic with territories outside of the customs territory of the Union;
<a id="p112787"></a>(6) "intra-Union flight" means the movement of an aircraft between two Union airports, without any stopover, which does not start from or end at a non-Union airport;
<a id="p112788"></a>(7) "main processed products" means the processed products for which the authorisation for inward processing has been granted;
<a id="p112789"></a>(8) "marketing activities" means, in the context of customs valuation, all activities relating to advertising or marketing and promoting the sale of the goods in question and all activities relating to warranties or guarantees in respect of them;
<a id="p112790"></a>(9) "secondary processed products" means processed products which are a necessary by-product of the processing operation other than the main processed products;
<a id="p112791"></a>(10) "business or tourist aircraft" means private aircraft intended for journeys whose itinerary depends on the wishes of the user;
<a id="p112792"></a>(11) "public customs warehouse type III" means a customs warehouse which is operated by the customs authorities;
<a id="p112793"></a>(12) "fixed transport installation" means technical means used for continuous transport of goods such as electricity, gas and oil;
<a id="p112794"></a>(13) "customs office of transit" means either of the following:
<a id="p112795"></a>(a) the customs office competent for the point of exit from the customs territory of the Union when the goods are leaving that territory in the course of a transit operation via a frontier with a territory outside the customs territory of the Union other than a common transit country;
<a id="p112796"></a>(b) the customs office competent for the point of entry into the customs territory of the Union when the goods have crossed a territory outside the customs territory of the Union in the course of a transit operation;
<a id="p112797"></a>(14) "similar goods", in the context of customs valuation, means goods produced in the same country, which, although not alike in all respects, have like characteristics and like component materials which enable them to perform the same functions and to be commercially interchangeable; the quality of the goods, their reputation and the existence of a trademark are among the factors to be considered in determining whether goods are similar.

<a id="p112798"></a>**CHAPTER 2**

<a id="p112799"></a>**RIGHTS AND OBLIGATIONS OF PERSONS WITH REGARD**
**TO THE CUSTOMS LEGISLATION**

<a id="p112800"></a>Section 1. PROVISION OF INFORMATION

<a id="p112801"></a>Subsection 1

<a id="p112802"></a>**FORMATS AND CODES OF COMMON DATA REQUIREMENTS,**
**DATA - EXCHANGE AND STORAGE**

<a id="p112803"></a>Article 2

<a id="p112804"></a>Formats and codes for common data requirements
(Article 6(2) of the Code)

1. <a id="p112805"></a>The formats and codes for the common data requirements referred to in Article 2(1) of Delegated Regulation (EU) 2015/2446 for the exchange and storage of information required for applications and decisions are set out in Annex A to this Regulation.
2. <a id="p112806"></a>The formats and codes for the common data requirements referred to in Article 2(2) of Delegated Regulation (EU) 2015/2446 for the exchange and storage of information required for declarations, notifications and proof of customs status are set out in Annex B to this Regulation.
4. <a id="p112807"></a>The formats and codes for the common data requirements referred to in Article 2(4) of Delegated Regulation (EU) 2015/2446 for the exchange and storage of information required for declarations, notifications and proof of customs status are set out in Annex 9 to Commission Delegated Regulation (EU) 2016/341 <*>.

<a id="p112808"></a>

---

<a id="p112809"></a><*> Commission Delegated Regulation (EU) 2016/341 of 17 December 2015 supplementing Regulation (EU) No 952/2013 of the European Parliament and of the Council as regards transitional rules for certain provisions of the Union Customs Code where the relevant electronic systems are not yet operational and amending Delegated Regulation (EU) 2015/2446 (OJ L 69, 15.3.2016, p. 1).

<a id="p112810"></a>4a. The formats and codes for the common data requirements referred to in Article 2(4a) of Delegated Regulation (EU) 2015/2446 for the exchange and storage of information required for declarations, notifications and proof of customs status are set out in Annex C to this Regulation.
5. <a id="p112811"></a>Until the date of deployment of the UCC Customs Decisions system referred to in the Annex to Implementing Decision (EU) 2016/578, customs authorities may decide that formats and codes other than those laid down in Annex A to this Regulation are to apply in respect of the following applications and authorisations:
<a id="p112812"></a>(a) applications and authorisations relating to the simplification for the determination of amounts being part of the customs value of the goods;
<a id="p112813"></a>(b) applications and authorisations relating to comprehensive guarantees;
<a id="p112814"></a>(c) applications and authorisations for deferred payment;
<a id="p112815"></a>(d) applications and authorisations for the operation of temporary storage facilities as referred to in Article 148 of the Code;
<a id="p112816"></a>(e) applications and authorisations for regular shipping services;
<a id="p112817"></a>(f) applications and authorisations for authorised issuer;
<a id="p112818"></a>(g) applications and authorisations for the status of authorised weigher of bananas;
<a id="p112819"></a>(h) applications and authorisations for self-assessment;
<a id="p112820"></a>(i) applications and authorisations for the status of authorised consignee for TIR operations;
<a id="p112821"></a>(j) applications and authorisations for the status of authorised consignor for Union transit;
<a id="p112822"></a>(k) applications and authorisations for the status of authorised consignee for Union transit;
<a id="p112823"></a>(l) applications and authorisations for the use of seals of a special type;
<a id="p112824"></a>(m) applications and authorisations for the use of a transit declaration with reduced dataset;
<a id="p112825"></a>(n) applications and authorisations for the use of an electronic transport document as customs declaration.
6. <a id="p112826"></a>Until the date of deployment of the UCC Customs Decisions system, customs authorities may allow the formats and codes of the data requirements for applications and authorisations set out in Annex 12 to Delegated Regulation (EU) 2016/341 to be used instead of the data requirements laid down in Annex A to this Regulation for the following applications and authorisations:
<a id="p112827"></a>(a) applications and authorisations for the use of simplified declaration;
<a id="p112828"></a>(b) applications and authorisations for centralised clearance;
<a id="p112829"></a>(c) applications and authorisations for entry of data in the declarant's records;
<a id="p112830"></a>(d) applications and authorisations for the use of inward processing;
<a id="p112831"></a>(e) applications and authorisations for the use of outward processing;
<a id="p112832"></a>(f) applications and authorisations for the use of end use;
<a id="p112833"></a>(g) applications and authorisations for the use of temporary admission;
<a id="p112834"></a>(h) applications and authorisations for the operation of storage facilities for customs warehousing.
7. <a id="p112835"></a>Notwithstanding paragraph 6, until the dates of deployment of the UCC Automated Export System (AES) or of the upgrading of the National Import Systems referred to in the Annex to Implementing Decision (EU) 2016/578, where an application for an authorisation is based on a customs declaration in accordance with Article 163(1) of Delegated Regulation (EU) 2015/2446, the formats and codes set out in Annex 12 to Delegated Regulation (EU) 2016/341 shall apply in respect of the additional data elements required for that application.

<a id="p112836"></a>Article 3

<a id="p112837"></a>Security of electronic systems
(Article 16(1) of the Code)

1. <a id="p112838"></a>When developing, maintaining and employing electronic systems referred to in Article 16(1) of the Code the Member States shall establish and maintain adequate security arrangements for the effective, reliable and secure operation of the various systems. They shall also ensure that measures are in place for checking the source of data and for protecting data against the risk of unauthorised access, loss, alteration or destruction.
2. <a id="p112839"></a>Each input, modification and deletion of data shall be recorded together with information giving the reason for, and exact time of, such processing and identifying the person who carried it out.
3. <a id="p112840"></a>The Member States shall inform each other, the Commission and, where appropriate, the economic operator concerned of all actual or suspected breaches of security of the electronic systems.

<a id="p112841"></a>Article 4

<a id="p112842"></a>Storage of data
(Article 16(1) of the Code)

<a id="p112843"></a>All data validated by the relevant electronic system shall be kept for at least 3 years from the end of the year in which such data was validated, unless otherwise specified.

<a id="p112844"></a>Article 5

<a id="p112845"></a>Availability of electronic systems
(Article 16(1) of the Code)

1. <a id="p112846"></a>The Commission and the Member States shall conclude operational agreements laying down the practical requirements for the availability and performance of the electronic systems as well as for business continuity.
2. <a id="p112847"></a>Operational agreements referred to in paragraph 1 shall in particular lay down appropriate response time for the exchange and processing of information in the relevant electronic systems.
3. <a id="p112848"></a>The electronic systems shall be kept permanently available. However, that obligation shall not apply:
<a id="p112849"></a>(a) in specific cases related to the use of the electronic systems laid down in the agreements referred to in paragraph 1 or, at national level, in the absence of those agreements;
<a id="p112850"></a>(b) in the case of force majeure.

<a id="p112851"></a>Subsection 2

<a id="p112852"></a>**REGISTRATION OF PERSONS**

<a id="p112853"></a>Article 6

<a id="p112854"></a>Competent customs authority
(Article 9 of the Code)

<a id="p112855"></a>The customs authorities responsible for registration shall be those designated by the Member States. The Member States shall communicate the name and address of those authorities to the Commission. The Commission shall publish that information on the Internet.

<a id="p112856"></a>Article 7

<a id="p112857"></a>Electronic system relating to EORI number
(Article 16 of the Code)

1. <a id="p112858"></a>For the exchange and storage of information pertaining to EORI, an electronic system set up for those purposes pursuant to Article 16(1) of the Code ("EORI system") shall be used.
<a id="p112859"></a>Information shall be made available through that system by the competent customs authority whenever new EORI numbers are assigned or there are changes to data stored in respect of registrations already issued.
2. <a id="p112860"></a>Only one EORI number shall be assigned in respect of each person.
3. <a id="p112861"></a>The format and codes of the data stored in the EORI system are laid down in Annex 12-01.
4. <a id="p112862"></a>By way of derogation from paragraph 1 of this Article, until the date of the upgrading of the central EORI system, the formats and codes set out in Annex 12-01 shall not apply.
<a id="p112863"></a>Until the date of the upgrading of the central EORI system, the codes of the common data requirements for the registration of economic operators and other persons are set out in Annex 9 to Delegated Regulation (EU) 2016/341.
5. <a id="p112864"></a>Where Member States collect data listed in point 4 of Annex 12-01 they shall ensure that the formats and codes as set out in Annex 12-01 are used.

<a id="p112865"></a>Section 2. DECISIONS RELATING TO THE APPLICATION OF CUSTOMS
**LEGISLATION**

<a id="p112866"></a>Subsection 1

<a id="p112867"></a>**DECISIONS TAKEN BY THE CUSTOMS AUTHORITIES**

<a id="p112868"></a>Article 8

<a id="p112869"></a>General procedure for the right to be heard
(Article 22(6) of the Code)

1. <a id="p112870"></a>The communication referred to in the first subparagraph of Article 22(6) of the Code shall:
<a id="p112871"></a>(a) include a reference to the documents and information on which the customs authorities intend to base their decision;
<a id="p112872"></a>(b) indicate the period within which the person concerned shall express his point of view from the date on which he receives that communication or is deemed to have received it;
<a id="p112873"></a>(c) include a reference to the right of the person concerned to have access to the documents and information referred to in point (a) in accordance with the applicable provisions.
2. <a id="p112874"></a>Where the person concerned gives his point of view before the expiry of the period referred to in paragraph 1(b) the customs authorities may proceed with taking the decision unless the person concerned simultaneously expresses his intention to further express his point of view within the period prescribed.

<a id="p112875"></a>Article 9

<a id="p112876"></a>Specific procedure for the right to be heard
(Article 22(6) of the Code)

1. <a id="p112877"></a>The customs authorities may make the communication referred to in the first subparagraph of Article 22(6) of the Code as part of the process of verification or control where they intend to take a decision on the basis of any of the following:
<a id="p112878"></a>(a) the results of a verification following presentation of the goods;
<a id="p112879"></a>(b) the results of a verification of the customs declaration as referred to in Article 191 of the Code;
<a id="p112880"></a>(c) the results of post-release control as referred to in Article 48 of the Code, where the goods are still under customs supervision;
<a id="p112881"></a>(d) the results of a verification of proof of the customs status of Union goods or, where applicable, the results of verification of the application for the registration of such proof or for the endorsement of such proof;
<a id="p112882"></a>(e) the issuing of a proof of origin by the customs authorities;
<a id="p112883"></a>(f) the results of control of goods for which no summary declaration, temporary storage declaration, re-export declaration or customs declaration was lodged.
2. <a id="p112884"></a>Where a communication is made in accordance with paragraph 1 the person concerned may:
<a id="p112885"></a>(a) immediately express his point of view by the same means as those used for the communication in accordance with Article 9 of Delegated Regulation (EU) 2015/2446; or
<a id="p112886"></a>(b) demand a communication in accordance with Article 8 except in the cases referred to in paragraph 1(f).
<a id="p112887"></a>The person concerned shall be informed by the customs authorities of those two options.
3. <a id="p112888"></a>Where the customs authorities take a decision adversely affecting the person concerned, they shall record whether that person has expressed his point of view in accordance with paragraph 2(a).

<a id="p112889"></a>Subsection 2

<a id="p112890"></a>**DECISIONS TAKEN UPON APPLICATION**

<a id="p112891"></a>Article 10

<a id="p112892"></a>Electronic systems relating to decisions
(Article 16(1) of the Code)

1. <a id="p112893"></a>For the exchange and storage of information pertaining to applications and decisions which may have an impact in more than one Member State and to any subsequent event which may affect the original application or decision, an electronic system set up for those purposes pursuant to Article 16(1) of the Code shall be used.
<a id="p112894"></a>Information shall be made available through that system by the competent customs authority without delay and at the latest within 7 days of the authority gaining knowledge of the information.
2. <a id="p112895"></a>An EU harmonised trader interface designed by the Commission and the Member States in agreement with each other shall be used for the exchange of information pertaining to applications and decisions which may have an impact in more than one Member State.
3. <a id="p112896"></a>Paragraphs 1 and 2 of this Article shall be applicable from the date of deployment of the UCC Customs Decisions system as referred to in the Annex to Implementing Decision 2014/255/EU.

<a id="p112897"></a>Article 11

<a id="p112898"></a>Customs authority designated to receive applications
(Third subparagraph of Article 22(1) of the Code)

<a id="p112899"></a>Member States shall communicate to the Commission a list of the customs authorities referred to in the third subparagraph of Article 22(1) of the Code designated to receive applications. Member States shall also communicate to the Commission any subsequent changes to that list.

<a id="p112900"></a>Article 12

<a id="p112901"></a>Acceptance of the application
(Article 22(2) of the Code)

1. <a id="p112902"></a>Where the customs authority accepts an application pursuant to Article 11(1) of Delegated Regulation (EU) 2015/2446, the date of acceptance of that application shall be the date on which all the information required in accordance with the second subparagraph of Article 22(2) of the Code was received by the customs authority.
2. <a id="p112903"></a>Where the customs authority establishes that the application does not contain all the information required, it shall ask the applicant to provide the relevant information within a reasonable time limit which shall not exceed 30 days.
<a id="p112904"></a>Where the applicant does not provide the information requested by the customs authorities within the period set by them for that purpose, the application shall not be accepted and the applicant shall be notified accordingly.
3. <a id="p112905"></a>In the absence of any communication to the applicant in relation to whether the application has been accepted or not, that application shall be deemed to be accepted. The date of the acceptance shall be the date of submission of the application or, in those cases where additional information has been provided by the applicant following a request of the customs authority as referred to in paragraph 2, the date when the last piece of information has been provided.

<a id="p112906"></a>Article 13

<a id="p112907"></a>Storage of information relating to decisions
(Article 23(5) of the Code)

<a id="p112908"></a>The customs authority competent to take a decision shall retain all data and supporting information which was relied upon when taking the decision for at least 3 years after the end date of its validity.

<a id="p112909"></a>Article 14

<a id="p112910"></a>Consultation between the customs authorities
(Article 22 of the Code)

1. <a id="p112911"></a>Where a customs authority competent to take a decision needs to consult a customs authority of another Member State concerned about the fulfilment of the necessary conditions and criteria for taking a favourable decision, that consultation shall take place within the period prescribed for the decision concerned. The customs authority competent to take a decision shall establish a time-limit for the consultation that starts from the date of communication by that customs authority of the conditions and criteria which need to be examined by the consulted customs authority.
<a id="p112912"></a>Where, following the examination referred to in the first subparagraph, the consulted customs authority establishes that the applicant does not fulfil one or more of the conditions and criteria for taking a favourable decision, the results, duly documented and justified, shall be transmitted to the customs authority competent to take the decision.
2. <a id="p112913"></a>The time-limit established for the consultation in accordance with paragraph 1 may be extended by the customs authority competent to take the decision in any of the following cases:
<a id="p112914"></a>(a) where due to the nature of the examinations to be performed the consulted authority requests more time;
<a id="p112915"></a>(b) where the applicant carries out adjustments in order to ensure the fulfilment of the conditions and criteria referred to in paragraph 1 and communicates them to the customs authority competent to take the decision, which shall inform the consulted customs authority accordingly.
3. <a id="p112916"></a>Where the consulted customs authority does not respond within the time-limit established for the consultation in accordance with paragraphs 1 and 2, the conditions and criteria for which the consultation took place are deemed to be fulfilled.
4. <a id="p112917"></a>The consultation procedure laid down in paragraphs 1 and 2 may also be applied for the purposes of re-assessment and monitoring of a decision.

<a id="p112918"></a>Article 15

<a id="p112919"></a>Revocation of a favourable decision
(Article 28 of the Code)

<a id="p112920"></a>A decision suspended in accordance with Article 16(1) of Delegated Regulation (EU) 2015/2446 shall be revoked by the customs authority competent to take a decision in cases referred to in Article 16(1)(b) and (c) of that Regulation, where the holder of the decision fails to take, within the prescribed period of time, the necessary measures to fulfil the conditions laid down for the decision or to comply with the obligations imposed under that decision.

<a id="p112921"></a>Subsection 3

<a id="p112922"></a>**DECISIONS RELATING TO BINDING INFORMATION**

<a id="p112923"></a>Article 16

<a id="p112924"></a>Application for a decision relating to binding information
(Article 22(1) of the Code)

1. <a id="p112925"></a>Where an application for a decision relating to binding information is submitted pursuant to Article 19(1) of Delegated Regulation (EU) 2015/2446 in another Member State than the one in which the applicant is established the customs authority to which the application was submitted shall notify the customs authority of the Member State where the applicant is established within 7 days from the acceptance of the application.
<a id="p112926"></a>Where the customs authority that receives the notification holds any information that it considers relevant for the processing of the application, it shall transmit such information to the customs authority to which the application was submitted as soon as possible and at the latest within 30 days from the date of the notification.
2. <a id="p112927"></a>An application for a binding tariff information (BTI) decision shall relate only to goods which have similar characteristics and between which the differences are irrelevant for the purposes of their tariff classification.
3. <a id="p112928"></a>An application for a binding origin information (BOI) decision shall relate to only one type of goods and one set of circumstances for the determination of origin.
4. <a id="p112929"></a>For the purposes of ensuring compliance with the requirement set out in point (a) of the second subparagraph of Article 33(1) of the Code in relation to an application for a BTI decision, the customs authority referred to in Article 19(1) of Delegated Regulation (EU) 2015/2446 shall consult the electronic system referred to in Article 21 of this Regulation and keep a record of such consultations.

<a id="p112930"></a>Article 17

<a id="p112931"></a>Consistency with existing BTI decisions
(Article 22(3) of the Code)

<a id="p112932"></a>The customs authority competent to take a decision shall, for the purposes of ensuring that a BTI decision which it intends to issue is consistent with BTI decisions that have already been issued, consult the electronic system referred to in Article 21 and keep a record of such consultations.

<a id="p112933"></a>Article 18

<a id="p112934"></a>Notification of BOI decisions
(Article 6(3) of the Code)

1. <a id="p112935"></a>Where, the customs authority competent to take the decision notifies the applicant of the BOI decision using means other than electronic data-processing techniques, it shall do so using the form set out in Annex 12-02.
2. <a id="p112936"></a>Where the customs authority competent to take the decision notifies the applicant of the BOI decision using electronic data-processing techniques, that decision shall be printable in accordance with the format set out in Annex 12-02.

<a id="p112937"></a>Article 19

<a id="p112938"></a>Exchange of data relating to BOI decisions
(Article 23(5) of the Code)

1. <a id="p112939"></a>The customs authorities shall transmit to the Commission the relevant details of the BOI decisions on a quarterly basis.
2. <a id="p112940"></a>The Commission shall make the details obtained in accordance with paragraph 1 available to the customs authorities of all Member States.

<a id="p112941"></a>Article 20

<a id="p112942"></a>Monitoring of decisions relating to binding information
(Article 23(5) of the Code)

<a id="p112943"></a>When customs formalities are being fulfilled by or on behalf of the holder of a decision relating to binding information in respect of goods covered by that decision, this shall be indicated in the customs declaration by stating the decision reference number.

<a id="p112944"></a>Article 21

<a id="p112945"></a>Electronic system relating to BTI
(Articles 16(1) and 23(5) of the Code)

1. <a id="p112946"></a>For the exchange and storage of information pertaining to applications and decisions related to BTI or to any subsequent event which may affect the original application or decision, an electronic system set up for those purposes pursuant to Article 16(1) of the Code shall be used.
<a id="p112947"></a>Information shall be made available through that system by the competent customs authority without delay and at the latest within 7 days of the authority gaining knowledge of the information.
2. <a id="p112948"></a>In addition to the information referred to in paragraph 1:
<a id="p112949"></a>(a) the surveillance referred to in Article 55 of this Regulation shall include data that are relevant for monitoring the usage of BTI decisions;
<a id="p112950"></a>(b) the customs authority that has received the application and has taken the BTI decision shall notify through the system referred to in paragraph 1 if a period of extended use of the BTI decision is granted, indicating the end date of the period of extended use and the quantities of the goods covered by this period.
3. <a id="p112951"></a>The Commission shall communicate the results of the monitoring referred to in point (a) of paragraph 2 to the Member States on a regular basis in order to support the monitoring by the customs authorities of the compliance with the obligations resulting from the BTI.
4. <a id="p112952"></a>An EU harmonised trader interface designed by the Commission and the Member States in agreement with each other shall be used for the exchange of information pertaining to applications and decisions related to BTI.
5. <a id="p112953"></a>When processing an application for a BTI decision, the customs authorities shall indicate the status of the application in the system referred to in paragraph 1.
6. <a id="p112954"></a>By derogation from paragraph 1 of this Article, until the date of the upgrading of the system referred to therein in accordance with the Annex to Implementing Decision 2014/255/EU, Member States shall use the central database of the Commission set up by Article 8(3) of Commission Regulation (EEC) No 2454/93 <*>.

<a id="p112955"></a>

---

<a id="p112956"></a><*> Commission Regulation (EEC) No 2454/93 of 2 July 1993 laying down provisions for the implementation of Council Regulation (EEC) No 2913/92 establishing the Community Customs Code (OJ L 253, 11.10.1993, p. 1).

7. <a id="p112957"></a>Until the date of deployment of the first phase of the upgrading of the system referred to in paragraph 1 of this Article and the system referred to in Article 56 of this Regulation, the customs authorities shall carry out the monitoring of the usage of BTI decisions when conducting customs controls or post-release controls in accordance with Articles 46 and 48 of the Code. By derogation from paragraph 3 of this Article, until that date of deployment, the Commission shall not be obliged to communicate results of the monitoring referred to in point (a) of paragraph 2 of this Article to the Member States.

<a id="p112958"></a>Article 22

<a id="p112959"></a>Extended use of decisions relating to binding information
(Article 34(9) of the Code)

1. <a id="p112960"></a>Where the customs authorities decide to grant a period of extended use in accordance with the third subparagraph of Article 34(9) of the Code, they shall specify the date on which the period of extended use of the decision concerned expires.
2. <a id="p112961"></a>Where the customs authorities decide to grant a period of extended use of a BTI decision in accordance with the third subparagraph of Article 34(9) of the Code, they shall specify, in addition to the date referred to in paragraph 1, the quantities of the goods that may be cleared during the period of extended use.
<a id="p112962"></a>The use of a decision for which a period of extended use has been granted shall cease as soon as those quantities are reached.
<a id="p112963"></a>On the basis of the surveillance referred to in Article 55, the Commission shall inform the Member States as soon as those quantities have been reached.

<a id="p112964"></a>Article 23

<a id="p112965"></a>Actions to ensure the correct and uniform tariff
classification or determination of origin
(Article 34(10) of the Code)

1. <a id="p112966"></a>The Commission shall, without delay, notify the customs authorities of the suspension of the taking of BTI and BOI decisions in accordance with Article 34(10)(a) of the Code where:
<a id="p112967"></a>(a) the Commission has identified incorrect or non-uniform decisions;
<a id="p112968"></a>(b) the customs authorities have submitted to the Commission cases where they failed to resolve, within a maximum period of 90 days, their differences of opinion with regard to the correct and uniform classification or determination of origin.
<a id="p112969"></a>No decision related to binding information shall be issued for goods subject to point (a) or (b) from the date when the Commission has notified the customs authorities of the suspension until the correct and uniform classification or determination of origin is ensured.
2. <a id="p112970"></a>The correct and uniform classification or determination of origin shall be subject to consultation at Union level at the earliest opportunity and at the latest within 120 days of the Commission notification referred to in paragraph 1.
3. <a id="p112971"></a>The Commission shall notify the customs authorities immediately once the suspension is withdrawn.
4. <a id="p112972"></a>For the purposes of applying paragraphs 1 to 3, BOI decisions shall be deemed to be non-uniform where they confer different origin on goods which:
<a id="p112973"></a>(a) fall under the same tariff heading and whose origin was determined in accordance with the same origin rules; and
<a id="p112974"></a>(b) have been obtained under identical conditions using the same manufacturing process and equivalent materials as regards notably their originating or non-originating status.

<a id="p112975"></a>Section 3. AUTHORISED ECONOMIC OPERATOR

<a id="p112976"></a>Article 24

<a id="p112977"></a>Compliance
(Article 39(a) of the Code)

1. <a id="p112978"></a>The criterion laid down in Article 39(a) of the Code shall be considered to be fulfilled if,
<a id="p112979"></a>(a) there is no decision taken by an administrative or judicial authority concluding that one of the persons described in point (b) has committed, over the last three years, a serious or repeated infringements of customs legislation or taxation rules in relation to his-her economic activity; and
<a id="p112980"></a>(b) none of the following persons has a record of serious criminal offence in relation to his/her economic activity including the applicant's economic activity, where applicable:
<a id="p112981"></a>(i) the applicant,
<a id="p112982"></a>(ii) the employee(s) in charge of the applicant's customs matters, and
<a id="p112983"></a>(iii) the person(s) in charge of the applicant or exercising control over its management.
2. <a id="p112984"></a>However, the criterion referred to in Article 39(a) of the Code may be considered to be fulfilled where the customs authority competent to take the decision considers an infringement to be of minor importance, in relation to the number or size of the related operations, and the customs authority has no doubt as to the good faith of the applicant.
3. <a id="p112985"></a>Where the person referred to in paragraph 1(b) (iii), other than the applicant is established or has his/her residence in a third country, the customs authority competent to take the decision shall assess the fulfilment of the criterion referred to in Article 39(a) of the Code on the basis of the records and information that are available to it.
4. <a id="p112986"></a>Where the applicant has been established for less than 3 years, the customs authority competent to take the decision shall assess the fulfilment of the criterion referred to in Article 39(a) of the Code on the basis of the records and information that are available to it.

<a id="p112987"></a>Article 25

<a id="p112988"></a>Satisfactory system of managing commercial and transport records
(Article 39(b) of the Code)

1. <a id="p112989"></a>The criterion laid down in Article 39(b) of the Code shall be considered to be fulfilled if the following conditions are met:
<a id="p112990"></a>(a) the applicant maintains an accounting system which is consistent with the generally accepted accounting principles applied in the Member State where the accounts are held, allows audit-based customs control and maintains a historical record of data that provides an audit trail from the moment the data enters the file;
<a id="p112991"></a>(b) records kept by the applicant for customs purposes are integrated in the accounting system of the applicant or allow cross checks of information with the accounting system to be made;
<a id="p112992"></a>(c) the applicant allows the customs authority physical access to its accounting systems and, where applicable, to its commercial and transport records;
<a id="p112993"></a>(d) the applicant allows the customs authority electronic access to its accounting systems and, where applicable, to its commercial and transport records where those systems or records are kept electronically;
<a id="p112994"></a>(e) the applicant has a logistical system which identifies goods as Union or non-Union goods and indicates, where appropriate, their location;
<a id="p112995"></a>(f) the applicant has an administrative organisation which corresponds to the type and size of business and which is suitable for the management of the flow of goods, and has internal controls capable of preventing, detecting and correcting errors and of preventing and detecting illegal or irregular transactions;
<a id="p112996"></a>(g) where applicable, the applicant has satisfactory procedures in place for the handling of licences and authorisations granted in accordance with commercial policy measures or relating to trade in agricultural products;
<a id="p112997"></a>(h) the applicant has satisfactory procedures in place for the archiving of its records and information and for protection against the loss of information;
<a id="p112998"></a>(i) the applicant ensures that relevant employees are instructed to inform the customs authorities whenever compliance difficulties are discovered and establishes procedures for informing the customs authorities of such difficulties;
<a id="p112999"></a>(j) the applicant has appropriate security measures in place to protect the applicant's computer system from unauthorised intrusion and to secure the applicant's documentation;
<a id="p113000"></a>(k) where applicable, the applicant has satisfactory procedures in place for the handling of import and export licences connected to prohibitions and restrictions, including measures to distinguish goods subject to the prohibitions or restrictions from other goods and measures to ensure compliance with those prohibitions and restrictions.
2. <a id="p113001"></a>Where the applicant applies only for an authorisation as an economic operator authorised for security and safety as referred to in Article 38(2)(b) of the Code (AEOS), the requirement laid down in paragraph 1(e) shall not apply.

<a id="p113002"></a>Article 26

<a id="p113003"></a>Financial solvency
(Article 39(c) of the Code)

1. <a id="p113004"></a>The criterion laid down in Article 39(c) of the Code shall be considered to be fulfilled where the applicant complies with the following:
<a id="p113005"></a>(a) the applicant is not subject to bankruptcy proceedings;
<a id="p113006"></a>(b) during the last 3 years preceding the submission of the application, the applicant has fulfilled his financial obligations regarding payments of customs duties and all other duties, taxes or charges which are collected on or in connection with the import or export of goods;
<a id="p113007"></a>(c) the applicant demonstrates on the basis of the records and information available for the last 3 years preceding the submission of the application that he has sufficient financial standing to meet his obligations and fulfil his commitments having regard to the type and volume of the business activity, including having no negative net assets, unless where they can be covered.
2. <a id="p113008"></a>If the applicant has been established for less than 3 years, his financial solvency as referred to in Article 39(c) of the Code shall be checked on the basis of records and information that are available.

<a id="p113009"></a>Article 27

<a id="p113010"></a>Practical standards of competence
or professional qualifications
(Article 39(d) of the Code)

1. <a id="p113011"></a>The criterion laid down in Article 39(d) of the Code shall be considered to be fulfilled if any of the following conditions are met:
<a id="p113012"></a>(a) the applicant or the person in charge of the applicant's customs matters complies with one of the following practical standards of competence:
<a id="p113013"></a>(i) a proven practical experience of a minimum of 3 years in customs matters;
<a id="p113014"></a>(ii) a quality standard concerning customs matters adopted by a European Standardisation body;
<a id="p113015"></a>(b) the applicant or the person in charge of the applicant's customs matters has successfully completed training covering customs legislation consistent with and relevant to the extent of his involvement in customs related activities, provided by any of the following:
<a id="p113016"></a>(i) a customs authority of a Member State;
<a id="p113017"></a>(ii) an educational establishment recognised, for the purposes of providing such qualification, by the customs authorities or a body of a Member State responsible for professional training;
<a id="p113018"></a>(iii) a professional or trade association recognised by the customs authorities of a Member State or accredited in the Union, for the purposes of providing such qualification.
2. <a id="p113019"></a>Where the person in charge of the applicant's customs matters is a contracted person, the criterion laid down in Article 39(d) of the Code shall be considered to be fulfilled if the contracted person is an economic operator authorised for customs simplifications as referred to in Article 38(2)(a) of the Code (AEOC).

<a id="p113020"></a>Article 28

<a id="p113021"></a>Security and safety standards
(Article 39(e) of the Code)

1. <a id="p113022"></a>The criterion laid down in Article 39(e) of the Code shall be considered to be fulfilled if the following conditions are met:
<a id="p113023"></a>(a) buildings to be used in connection with the operations relating to the AEOS authorisation provide protection against unlawful intrusion and are constructed of materials which resist unlawful entry;
<a id="p113024"></a>(b) appropriate measures are in place to prevent unauthorised access to offices, shipping areas, loading docks, cargo areas and other relevant places;
<a id="p113025"></a>(c) measures for the handling of goods have been taken which include protection against the unauthorised introduction or exchange, the mishandling of goods and against tampering with cargo units;
<a id="p113026"></a>(d) the applicant has taken measures allowing to clearly identify his business partners and to ensure, through implementation of appropriate contractual arrangements or other appropriate measures in accordance with the applicant's business model, that those business partners ensure the security of their part of the international supply chain;
<a id="p113027"></a>(e) the applicant conducts in so far as national law permits, security screening on prospective employees working in security sensitive positions and carries out background checks of current employees in such positions periodically and where warranted by circumstances;
<a id="p113028"></a>(f) the applicant has appropriate security procedures in place for any external service providers contracted;
<a id="p113029"></a>(g) the applicant ensures that its staff having responsibilities relevant for security issues regularly participate in programmes to raise their awareness of those security issues;
<a id="p113030"></a>(h) the applicant has appointed a contact person competent for safety and security related questions.
2. <a id="p113031"></a>Where the applicant is a holder of a security and safety certificate issued on the basis of an international convention or of an International Standard of the International Organisation for Standardisation, or of a European Standard of a European standardisation body, these certificates shall be taken into account when checking compliance with the criteria laid down in Article 39(e) of the Code.
<a id="p113032"></a>The criteria shall be deemed to be met to the extent that it is established that the criteria for issuing that certificate are identical or equivalent to those laid down in Article 39(e) of the Code.
<a id="p113033"></a>The criteria shall be deemed to be met where the applicant is the holder of a security and safety certificate issued by a third country with which the Union has concluded an agreement which provides for the recognition of that certificate.
3. <a id="p113034"></a>Where the applicant is a regulated agent or a known consignor as defined in Article 3 of Regulation (EC) No 300/2008 of the European Parliament and of the Council <*> and fulfils the requirements laid down in Commission Regulation (EU) No 185/2010 <**>, the criteria laid down in paragraph 1 shall be deemed to be met in relation to the sites and the operations for which the applicant obtained the status of regulated agent or known consignor to the extent that the criteria for issuing the regulated agent or known consignor status are identical or equivalent to those laid down in Article 39(e) of the Code.

<a id="p113035"></a>

---

<a id="p113036"></a><*> Regulation (EC) No 300/2008 of the European Parliament and of the Council of 11 March 2008 on common rules in the field of civil aviation security and repealing Regulation (EC) No 2320/2002 (OJ L 97, 9.4.2008, p. 72).
<a id="p113037"></a><**> Commission Regulation (EU) No 185/2010 of 4 March 2010 laying down detailed measures for the implementation of the common basic standards on aviation security (OJ L 55, 5.3.2010, p. 1).

<a id="p113038"></a>Article 29

<a id="p113039"></a>Examination of the criteria
(Article 22 of the Code)

1. <a id="p113040"></a>For the purposes of examining the criteria laid down in Article 39(b) and (e) of the Code, the customs authority competent to take the decision shall ensure that on-the-spot verifications are carried out at all the premises that are relevant to the customs related activities of the applicant.
<a id="p113041"></a>Where the applicant has a large number of premises, and the applicable time-limit for taking the decision does not allow for examination of all those premises the customs authority may decide to examine only a representative proportion of those premises if it is satisfied that the applicant applies the same security and safety standards at all of its premises and apply the same common standards and procedures for maintaining its records at all of its premises.
2. <a id="p113042"></a>The customs authorities competent to take a decision may take into consideration the results of assessments or audits carried out in accordance with Union legislation to the extent they are relevant for the examination of the criteria referred to in Article 39 of the Code.
3. <a id="p113043"></a>For the purposes of examining whether the criteria laid down in Article 39(b), (c) and (e) of the Code are fulfilled, the customs authorities may take into account expert conclusions provided by the applicant, where the expert having drawn up the conclusions is not related to the applicant within the meaning of Article 127 of this Regulation.
4. <a id="p113044"></a>The customs authorities shall take due account of the specific characteristics of economic operators, in particular of small and medium-sized enterprises, when examining the fulfilment of criteria laid down in Article 39 of the Code.
5. <a id="p113045"></a>The examination of the criteria laid down in Article 39 of the Code as well as its results shall be documented by the customs authority competent to take the decision.

<a id="p113046"></a>Article 30

<a id="p113047"></a>Electronic system relating to the AEO status
(Article 16(1) of the Code)

1. <a id="p113048"></a>For the exchange and storage of information pertaining to applications for an authorisation as an authorised economic operator (AEO) and AEO authorisations granted and any further event or act which may subsequently affect the original decision, including annulment, suspension, revocation or amendment or the results of any monitoring or re-assessment, an electronic system set up for those purposes pursuant to Article 16(1) of the Code shall be used. The competent customs authority shall make information available through this system without delay and at the latest within 7 days.
<a id="p113049"></a>An EU harmonised trader interface designed by the Commission and the Member States in agreement with each other shall be used for the exchange of information pertaining to applications and decisions related to AEO authorisations.
2. <a id="p113050"></a>Where applicable, in particular when AEO status is a basis for the grant of approval, authorisations or facilitations under other Union legislation, the competent customs authority may grant access to the electronic system referred to in paragraph 1 to the appropriate national authority responsible for civil aviation security. The access shall be related to the following information:
<a id="p113051"></a>(a) the AEOS authorisations, including the name of the holder of the authorisation and, where applicable, their amendment or revocation or the suspension of the status of authorised economic operator and the reasons therefor;
<a id="p113052"></a>(b) any re-assessments of AEOS authorisations and the results thereof.
<a id="p113053"></a>The national authorities responsible for civil aviation security handling the information concerned shall use it only for the purposes of the relevant programmes for regulated agent or known consignor and shall implement appropriate technical and organisational measures to ensure the security of this information.
3. <a id="p113054"></a>By derogation from paragraph 1 of this Article, until the date of the upgrading of the AEO System referred to in the Annex to Implementing Decision 2014/255/EU, Member States shall use that system set up by Article 14x of Commission Regulation (EEC) No 2454/93.

<a id="p113055"></a>Article 31

<a id="p113056"></a>Consultation procedure and exchange
of information between customs authorities
(Article 22 of the Code)

1. <a id="p113057"></a>The customs authority competent to take the decision may consult customs authorities of other Member States which are competent for the place where necessary information is held or where checks have to be carried out for the purpose of examining one or more criteria laid down in Article 39 of the Code.
2. <a id="p113058"></a>The consultation referred to in paragraph 1 shall be mandatory, where:
<a id="p113059"></a>(a) the application for the status of AEO is submitted in accordance with Article 12(1) of Delegated Regulation (EU) 2015/2446, to the customs authority - of the place where the applicant's main accounts for customs purposes are held or are accessible;
<a id="p113060"></a>(b) the application for the status of AEO is submitted in accordance with Article 27 of Delegated Regulation (EU) 2015/2446, to the customs authorities of the Member State where the applicant has a permanent business establishment and where the information about its general logistical management activities in the Union is kept or is accessible;
<a id="p113061"></a>(c) a part of the records and documentation of relevance for the application for the status of AEO is kept in a Member State other than the one of the customs authority competent to take a decision;
<a id="p113062"></a>(d) the applicant for the status of AEO maintains a storage facility or has other customs-related activities in a Member State other than the one of the competent customs authority.
3. <a id="p113063"></a>By way of derogation from the time-limit laid down in the second sentence of the first subparagraph of Article 14(1) of this Regulation, the customs authorities shall complete the consultation process within 80 days from the date on which the customs authority competent to take the decision communicates the necessary conditions and criteria which have to be examined by the consulted customs authority.
4. <a id="p113064"></a>Where the customs authority of another Member State has information of relevance for the granting of AEO status, it shall communicate that information to the customs authority competent to take a decision within 30 days starting from the date of the communication of the application through the electronic system referred to in Article 30 of this Regulation.

<a id="p113065"></a>Article 32

<a id="p113066"></a>Rejection of an application
(Article 22 of the Code)

<a id="p113067"></a>The rejection of an AEO application shall not affect existing favourable decisions taken with regard to the applicant in accordance with the customs legislation, unless the granting of those favourable decisions is based on the fulfilment of any of the AEO criteria that have been proven not to be met during the examination of the AEO application.

<a id="p113068"></a>Article 33

<a id="p113069"></a>Combination of both types of authorisations
(Article 38(3) of the Code)

<a id="p113070"></a>Where an applicant is entitled to be granted both an AEOC and an AEOS authorisation, the customs authority competent to take the decision shall issue one combined authorisation.

<a id="p113071"></a>Article 34

<a id="p113072"></a>Revocation of an authorisation
(Article 28 of the Code)

1. <a id="p113073"></a>The revocation of an AEO authorisation shall not affect any favourable decision which has been taken with regard to the same person unless AEO status was a condition for that favourable decision, or that decision was based on a criterion listed in Article 39 of the Code which is no longer met.
2. <a id="p113074"></a>The revocation or amendment of a favourable decision which has been taken with regard to the holder of the authorisation shall not automatically affect the AEO authorisation of that person.
3. <a id="p113075"></a>Where the same person is both an AEOC and an AEOS, and Article 28 of the Code or Article 15 of this Regulation is applicable owing to the non-fulfilment of the conditions laid down in Article 39(d) of the Code, the AEOC authorisation shall be revoked and AEOS authorisation shall remain valid.
<a id="p113076"></a>Where the same person is both an AEOS and an AEOC, and Article 28 of the Code or Article 15 of this Regulation is applicable owing to the non-fulfilment of the conditions laid down in Article 39(e) of the Code, the AEOS authorisation shall be revoked and AEOC authorisation shall remain valid.

<a id="p113077"></a>Article 35

<a id="p113078"></a>Monitoring
(Article 23(5) of the Code)

1. <a id="p113079"></a>The customs authorities of the Member States shall inform the competent customs authority without delay of any factors arising after the grant of the status of AEO which may influence its continuation or content.
2. <a id="p113080"></a>The competent customs authority shall make available all relevant information at its disposal to the customs authorities of the other Member States where the AEO carries out customs-related activities.
3. <a id="p113081"></a>Where a customs authority revokes a favourable decision which has been taken on the basis of the status of AEO, it shall notify the customs authority which granted the status.
4. <a id="p113082"></a>Where the AEOS is a regulated agent or a known consignor as defined in Article 3 of Regulation (EC) No 300/2008 and fulfils the requirements laid down in Regulation (EU) No 185/2010, the competent customs authority shall immediately make available to the appropriate national authority responsible for civil aviation security the following minimum information related to the AEO status which it has at its disposal:
<a id="p113083"></a>(a) the AEOS authorisation, including the name of the holder of the authorisation and, where applicable, its amendment or revocation or the suspension of the status of authorised economic operator and the reasons therefor;
<a id="p113084"></a>(b) information about whether the specific site concerned has been visited by customs authorities, the date of the last visit, and whether the visit took place with a view to the authorisation process, re-assessment or monitoring;
<a id="p113085"></a>(c) any re-assessments of the AEOS authorisation and the results thereof.
<a id="p113086"></a>The national customs authorities shall, in agreement with the appropriate national authority responsible for civil aviation security, establish detailed modalities for the exchange of any information which is not covered by the electronic system referred to in Article 30 of this Regulation.
<a id="p113087"></a>The national authorities responsible for civil aviation security handling the information concerned shall use it only for the purposes of the relevant programmes for regulated agent or known consignor and shall implement appropriate technical and organisational measures to ensure the security of the information.

<a id="p113088"></a>Section 4. CONTROL OF GOODS

<a id="p113089"></a>Subsection 1

<a id="p113090"></a>**CUSTOMS CONTROLS AND RISK MANAGEMENT**

<a id="p113091"></a>Article 36

<a id="p113092"></a>Electronic system relating
to risk management and customs controls
(Article 16(1) of the Code)

1. <a id="p113093"></a>For the exchange and storage of information pertaining to the communication among the customs authorities of the Member States and the Commission of any risk-related information, an electronic system set up for those purposes pursuant to Article 16(1) of the Code ("customs risk management system") shall be used.
2. <a id="p113094"></a>The system mentioned in paragraph 1 shall also be used for communication between customs authorities and between customs authorities and the Commission in the implementation of common risk criteria and standards, common priority control areas, customs crisis management, the exchange of risk-related information and risk analysis results as referred to in Article 46(5) of the Code as well as the results of customs controls.
3. <a id="p113095"></a>By way of derogation from paragraphs 1 and 2 of this Article, the system referred to in Article 182(1) shall also be used for the exchange, processing and storage of specific risk information related to entry summary declarations.

<a id="p113096"></a>Subsection 2

<a id="p113097"></a>**CABIN AND HOLD BAGGAGE TRANSPORTED BY AIR**

<a id="p113098"></a>Article 37

<a id="p113099"></a>Transit flights
(Article 49 of the Code)

1. <a id="p113100"></a>Customs controls and formalities applicable to the cabin and hold baggage of persons taking a flight from a non-Union airport in an aircraft which, after a stopover at a Union airport, continues to another Union airport shall be carried out at the last international Union airport.
<a id="p113101"></a>The cabin and hold baggage shall be subject to the rules applicable to the baggage of persons coming from a third country unless the person carrying such baggage proves the status of the goods contained therein as Union goods.
2. <a id="p113102"></a>Customs controls and formalities applicable to the cabin and hold baggage of persons taking a flight from a Union airport in an aircraft which stops over at another Union airport before continuing to a non-Union airport, shall be carried out at the first international Union airport.
<a id="p113103"></a>The cabin baggage may be subject to control at the last international Union airport where the aircraft stops over in order to ascertain their customs status of Union goods.

<a id="p113104"></a>Article 38

<a id="p113105"></a>Transit flights in business and tourist aircraft
(Article 49 of the Code)

<a id="p113106"></a>Customs controls and formalities applicable to the baggage of persons on board business or tourist aircraft shall be carried out at the following airports:
<a id="p113107"></a>(a) for flights coming from a non-Union airport and where the aircraft, after a stopover at a Union airport, continues to another Union airport, at the first international Union airport;
<a id="p113108"></a>(b) for flights coming from a Union airport and where the aircraft, after a stopover at a Union airport, continues to a non-Union airport, at the last international Union airport.

<a id="p113109"></a>Article 39

<a id="p113110"></a>Inbound transfer flights
(Article 49 of the Code)

1. <a id="p113111"></a>Where baggage arriving at a Union airport on board an aircraft coming from a non-Union airport is transferred, at that Union airport, to another aircraft proceeding on an intra-Union flight, paragraphs 2 and 3 shall apply.
2. <a id="p113112"></a>Customs controls and formalities applicable to hold baggage shall be carried out at the last international Union airport of arrival of the intra-Union flight. However, customs controls and formalities applicable to hold baggage coming from a non-Union airport and transferred at an international Union airport to an aircraft bound for another international Union airport in the territory of the same Member State may be carried out at the international Union airport where the transfer of hold baggage takes place.
<a id="p113113"></a>Customs controls and formalities applicable to hold baggage may, in exceptional cases and in addition to the controls and formalities referred to in the first subparagraph, be carried out at the first international Union airport where they prove necessary following controls on cabin baggage.
3. <a id="p113114"></a>Customs controls and formalities applicable to cabin baggage shall be carried out at the first international Union airport.
<a id="p113115"></a>Additional customs controls and formalities applicable to cabin baggage may be carried out at the airport of arrival of an intra-Union flight only in exceptional cases where they prove necessary following controls on hold baggage.

<a id="p113116"></a>Article 40

<a id="p113117"></a>Outbound transfer flights
(Article 49 of the Code)

1. <a id="p113118"></a>Where baggage is loaded at a Union airport onto an aircraft proceeding on an intra-Union flight and subsequently transferred, at another Union airport, onto another aircraft whose destination is a non-Union airport, paragraphs 2 and 3 shall apply.
2. <a id="p113119"></a>Customs controls and formalities applicable to hold baggage shall be carried out at the first international Union airport of departure. However, customs controls and formalities applicable to hold baggage having been loaded on an aircraft at an international Union airport and transferred at another international Union airport in the territory of the same Member State to an aircraft bound for a non-Union airport may be carried out at the international Union airport where the transfer of hold baggage takes place.
<a id="p113120"></a>Customs controls and formalities applicable to hold baggage may, in exceptional cases and in addition to the controls and formalities referred to in the first subparagraph, be carried out at the last international Union airport where they prove necessary following controls on cabin baggage.
3. <a id="p113121"></a>Customs controls and formalities applicable to cabin baggage shall be carried out at the last international Union airport.
<a id="p113122"></a>Additional customs controls and formalities applicable to cabin baggage may be carried out at the airport of departure of an intra-Union flight only in exceptional cases where they prove necessary following controls on hold baggage.

<a id="p113123"></a>Article 41

<a id="p113124"></a>Transfer to a tourist or business aircraft
(Article 49 of the Code)

1. <a id="p113125"></a>Customs controls and formalities applicable to baggage arriving at a Union airport on board a scheduled or charter flight from a non-Union airport and transferred, at that Union airport, to a tourist or business aircraft proceeding on an intra-Union flight shall be carried out at the airport of arrival of the scheduled or charter flight.
2. <a id="p113126"></a>Customs controls and formalities applicable to baggage loaded at a Union airport onto a tourist or business aircraft proceeding on an intra-Union flight for transfer, at another Union airport, to a scheduled or charter flight whose destination is a non-Union airport, shall be carried out at the airport of departure of the scheduled or charter flight.

<a id="p113127"></a>Article 42

<a id="p113128"></a>Transfers between airports
on the territory of the same Member State
(Article 49 of the Code)

<a id="p113129"></a>The customs authorities may carry out controls, at the international Union airport where the transfer of hold baggage takes place, on the following:
<a id="p113130"></a>(a) baggage coming from a non-Union airport and transferred in an international Union airport to an aircraft bound for an international Union airport in the same national territory;
<a id="p113131"></a>(b) baggage having been loaded on an aircraft in an international Union airport for transfer in another international Union airport in the same national territory to an aircraft bound for a non-Union airport.

<a id="p113132"></a>Article 43

<a id="p113133"></a>Measures to prevent illegal transfer
(Article 49 of the Code)

<a id="p113134"></a>The Member States shall ensure that:
<a id="p113135"></a>(a) on arrival at an international Union airport where customs controls are to be carried out, any transfer of goods contained in cabin baggage before those controls have been carried out on that baggage is monitored;
<a id="p113136"></a>(b) on departure from an international Union airport where customs controls are to be carried out, any transfer of goods contained in cabin baggage after those controls have been carried out on that baggage is monitored;
<a id="p113137"></a>(c) on arrival at an international Union airport where customs controls are to be carried out, the appropriate arrangements have been made to prevent any transfer of goods contained in hold baggage before those controls have been carried out on that baggage;
<a id="p113138"></a>(d) on departure from an international Union airport where customs controls are to be carried out, the appropriate arrangements have been made to prevent any transfer of goods contained in hold baggage after those controls have been carried out on the hold baggage.

<a id="p113139"></a>Article 44

<a id="p113140"></a>Baggage tag
(Article 49 of the Code)

<a id="p113141"></a>Hold baggage registered at a Union airport shall be identified by a tag affixed on the baggage. A specimen and the technical characteristics of the tag are set out in Annex 12-03.

<a id="p113142"></a>Article 45

<a id="p113143"></a>List of international Union airports
(Article 49 of the Code)

<a id="p113144"></a>Each Member State shall provide the Commission with a list of its international Union airports and shall inform the Commission of any changes to that list.

<a id="p113145"></a>Subsection 3

<a id="p113146"></a>**BAGGAGE TRANSPORTED BY SEA**

<a id="p113147"></a>Article 46

<a id="p113148"></a>Pleasure crafts
(Article 49 of the Code)

<a id="p113149"></a>Customs controls and formalities applicable to the baggage of persons on board pleasure craft shall be carried out at all ports of call in the Union, whatever the origin or destination of the craft. Pleasure craft is a recreational craft as defined in Directive 94/25/CE of the European Parliament and of the Council <*>.

<a id="p113150"></a>

---

<a id="p113151"></a><*> Directive 94/25/EC of the European Parliament and of the Council of 16 June 1994 on the approximation of the laws, regulations and administrative provisions of the Member States relating to recreational craft (OJ L 164, 30.6.1994, p. 15).

<a id="p113152"></a>Article 47

<a id="p113153"></a>Transfer crossings
(Article 49 of the Code)

<a id="p113154"></a>Customs controls and formalities applicable to the baggage of persons using a maritime service provided by the same vessel and comprising successive legs departing from, calling at or terminating in a non-Union port shall be carried out at any Union port at which the baggage is loaded or unloaded.

<a id="p113155"></a>**CHAPTER 3**

<a id="p113156"></a>**CURRENCY CONVERSION**

<a id="p113157"></a>Article 48

<a id="p113158"></a>Provisions on tariff exchange rate
(Article 53 of the Code)

1. <a id="p113159"></a>The value of the euro, where required in accordance with Article 53(1)(b) of the Code, shall be fixed once a month.
<a id="p113160"></a>The exchange rate to be used shall be the most recent rate set by the European Central Bank prior to the penultimate day of the month and shall apply throughout the following month.
<a id="p113161"></a>However, where the rate applicable at the start of the month differs by more than 5% from the rate set by the European Central Bank prior to the 15th of that same month, the latter rate shall apply from the 15th until the end of the month in question.
2. <a id="p113162"></a>Where the conversion of currency is necessary for any of the reasons referred to in Article 53(2) of the Code, the value of the euro in national currencies to be applied shall be the rate set by the European Central Bank on the first working day of October; this rate shall apply with effect from 1 January of the following year.
3. <a id="p113163"></a>Member States may maintain unchanged the value in national currency of the amount determined in euro if, at the time of the annual adjustment, the conversion of that amount, leads to an alteration of less than 5% in the value expressed in national currency.
<a id="p113164"></a>Member States may round upwards or downwards to the nearest decimal point the sum arrived at after conversion.

<a id="p113165"></a>**TITLE II. FACTORS ON THE BASIS OF WHICH IMPORT OR EXPORT**
**DUTY AND OTHER MEASURES IN RESPECT OF TRADE IN GOODS ARE**
**APPLIED**

<a id="p113166"></a>**CHAPTER 1**

<a id="p113167"></a>**COMMON CUSTOMS TARIFF AND TARIFF CLASSIFICATION OF GOODS**

<a id="p113168"></a>Section 1. MANAGEMENT OF TARIFF QUOTAS

<a id="p113169"></a>Article 49

<a id="p113170"></a>General rules on the uniform management of tariff quotas
(Article 56(4) of the Code)

1. <a id="p113171"></a>Tariff quotas opened in accordance with Union legislation referring to the method of administration in this article and in Articles 50 to 54 of this Regulation shall be managed in accordance with the chronological order of dates of acceptance of customs declarations for release for free circulation.
2. <a id="p113172"></a>Each tariff quota is identified in the Union legislation by an order number that facilitates its management.
3. <a id="p113173"></a>For the purposes of this Section, declarations for release for free circulation accepted by the customs authorities on 1, 2 or 3 January shall be regarded as being accepted on 3 January of the same year. However, where one of those days falls on a Saturday or a Sunday, such acceptance shall be regarded as having taken place on 4 January of that year.
4. <a id="p113174"></a>For the purposes of this Section, working days shall mean days which are not public holidays for the Union institutions in Brussels.

<a id="p113175"></a>Article 50

<a id="p113176"></a>Responsibilities of the customs authorities of the Member
States for the uniform management of tariff quotas
(Article 56(4) of the Code)

1. <a id="p113177"></a>The customs authorities shall examine whether a request to benefit from a tariff quota made by the declarant in a customs declaration for release for free circulation is valid in accordance with the Union legislation opening the tariff quota.
2. <a id="p113178"></a>Where a customs declaration for release for free circulation containing a valid request by the declarant to benefit from a tariff quota is accepted and all the supporting documents required for the granting of the tariff quota have been provided to the customs authorities, the customs authorities shall transmit that request to the Commission without delay specifying the date of acceptance of the customs declaration and the exact amount for which the request is made.

<a id="p113179"></a>Article 51

<a id="p113180"></a>Allocation of quantities under tariff quotas
(Article 56(4) of the Code)

1. <a id="p113181"></a>The Commission shall make allocations on working days. However, the Commission may decide not to allocate quantities on a given working day provided that the competent authorities of the Member States have been informed in advance.
2. <a id="p113182"></a>Quantities under tariff quotas may not be allocated earlier than on the second working day after the date of acceptance of the customs declaration in which the declarant made the request to benefit from the tariff quota.
<a id="p113183"></a>Any allocation by the Commission shall take into account all unanswered requests to benefit from tariff quotas based on customs declarations accepted up to and including the second previous working day to the day of the allocation, and which the customs authorities have transmitted to the system referred to in Article 54 of this Regulation.
3. <a id="p113184"></a>For each tariff quota, the Commission shall allocate quantities on the basis of requests to benefit from that tariff quota received by it following the chronological order of the dates of acceptance of the relevant customs declarations, and to the extent that the remaining balance of the tariff quota so permits.
4. <a id="p113185"></a>Where on an allocation day, the sum of quantities of all requests to benefit from a tariff quota which relate to declarations accepted on the same date are greater than the remaining balance of the tariff quota, the Commission shall allocate quantities in respect of those requests on a pro rata basis with respect to the requested quantities.
5. <a id="p113186"></a>Where a new tariff quota is opened, the Commission shall not allocate quantities under that tariff quota before the 11th working day following the date of publication of the Union act opening that tariff quota.

<a id="p113187"></a>Article 52

<a id="p113188"></a>Cancellation of requests and returns of unused
allocated quantities under tariff quotas
(Article 56(4) of the Code)

1. <a id="p113189"></a>Customs authorities shall immediately return to the electronic system referred to in Article 54 of this Regulation any quantity that has been erroneously allocated. However the obligation to return shall not apply where an erroneous allocation representing a customs debt of less than EUR 10 is discovered after the first month following the end of the period of validity of the tariff quota concerned.
2. <a id="p113190"></a>Where the customs authorities invalidate a customs declaration in respect of goods which are the subject of a request to benefit from a tariff quota before the Commission has allocated the requested quantity, the customs authorities shall cancel the entire request to benefit from the tariff quota.
<a id="p113191"></a>Where the Commission has already allocated the requested quantity on the basis of an invalidated customs declaration, the customs authority shall immediately return the allocated quantity to the electronic system referred to in Article 54 of this Regulation.

<a id="p113192"></a>Article 53

<a id="p113193"></a>Critical status of tariff quotas
(Article 56(4) of the Code)

1. <a id="p113194"></a>For the purposes of Article 153 of Delegated Regulation (EU) 2015/2446, a tariff quota shall be considered critical as soon as 90% of the complete volume of the tariff quota has been used.
2. <a id="p113195"></a>By way of derogation from paragraph 1, a tariff quota shall be considered critical from the date of its opening in any of the following cases:
<a id="p113196"></a>(a) the tariff quota is opened for less than 3 months;
<a id="p113197"></a>(b) tariff quotas having the same product coverage and origin and an equivalent quota period as the tariff quota in question ("equivalent tariff quotas") have not been opened in the previous 2 years;
<a id="p113198"></a>(c) an equivalent tariff quota opened in the previous 2 years had been exhausted on or before the last day of the third month of its quota period or had a higher initial volume than the tariff quota in question.
3. <a id="p113199"></a>A tariff quota whose sole purpose is the application of either a safeguard measure or a measure resulting from a suspension of concessions as provided for in Regulation (EU) No 654/2014 of the European Parliament and of the Council <*> shall be considered as critical as soon as 90% of the complete volume has been used irrespective of whether or not equivalent tariff quotas were opened in the previous 2 years.

<a id="p113200"></a>

---

<a id="p113201"></a><*> Regulation (EU) No 654/2014 of the European Parliament and of the Council of 15 May 2014 concerning the exercise of the Union's rights for the application and the enforcement of international trade rules and amending Council Regulation (EC) No 3286/94 (OJ L 189, 27.6.2014, p. 50).

<a id="p113202"></a>Article 54

<a id="p113203"></a>Electronic system relating
to the management of tariff quotas
(Articles 16(1) and 56(4) of the Code)

1. <a id="p113204"></a>For the management of tariff quotas, an electronic system set up for those purposes pursuant to Article 16(1) of the Code shall be used for:
<a id="p113205"></a>(a) the exchange of information between the customs authorities and the Commission pertaining to requests to benefit from and returns on tariff quotas and to the status of tariff quotas and the storage of that information;
<a id="p113206"></a>(b) the management by the Commission of the requests to benefit from and returns on tariff quotas;
<a id="p113207"></a>(c) the exchange of information between the customs authorities and the Commission relating to the allocation of quantities under tariff quotas and the storage of that information;
<a id="p113208"></a>(d) the recording of any further event or act which may affect the original drawings or returns on tariff quotas or their allocation.
2. <a id="p113209"></a>The Commission shall make available the information related to the allocation results through that system.

<a id="p113210"></a>Section 2. SURVEILLANCE OF THE RELEASE FOR FREE CIRCULATION
**OR THE EXPORT OF GOODS**

<a id="p113211"></a>Article 55

<a id="p113212"></a>General rules on surveillance of the release for free
circulation or the export of goods
(Article 56(5) of the Code)

1. <a id="p113213"></a>Where the Commission lays down a requirement that certain goods shall be subject to surveillance at release for free circulation or at export, it shall inform the customs authorities of the CN codes of those goods and of the data necessary for the purposes of the surveillance, in due time before the surveillance requirement becomes applicable.
<a id="p113214"></a>From the date set out in the fourth subparagraph of Article 4(1) of Directive (EU) 2017/2455, the list of data which may be required by the Commission is laid down in Annex 21-03 to this Regulation.
2. <a id="p113215"></a>Where goods have been made subject to surveillance at release for free circulation or at export, the customs authorities shall provide the Commission with data on customs declarations for the relevant procedure at least once a week.
<a id="p113216"></a>Where the goods are released in accordance with Article 194(1) of the Code, the customs authorities shall provide the Commission with the data without delay.
3. <a id="p113217"></a>The Commission shall only disclose the data referred in paragraph 1 provided by the customs authorities in aggregated form.
<a id="p113218"></a>3a. The Commission shall grant users authorised in accordance with Article 56(2) access to the non-aggregated data provided by the customs authorities of the Member State that requested their access and to data aggregated at Union level.
<a id="p113219"></a>3b. By derogation from paragraph 3a, the Commission shall grant access to the competent authorities of the Member States to the non-aggregated data where an act of the Union provides for such an access.
4. <a id="p113220"></a>Where goods are placed under a customs procedure on the basis of a simplified declaration as referred to in Article 166 of the Code or by entry in the declarant's records as referred to in Article 182 of the Code, and the data required by the Commission were not available at the time when the goods were released in accordance with Article 194(1) of the Code, the customs authorities shall provide the Commission with that information without delay after receiving the supplementary declaration lodged in accordance with Article 167 of the Code.
5. <a id="p113221"></a>Where the obligation to lodge a supplementary declaration is waived in accordance with Article 167(3) of the Code or the supplementary declaration is lodged or made available in accordance with Article 225 of this Regulation, the authorisation holder shall send to the customs authorities at least once a month the data required by the Commission or the customs authorities shall collect that data from the system of the declarant.
<a id="p113222"></a>The customs authorities shall enter the data in the electronic system referred to in Article 56 of this Regulation without delay.
6. <a id="p113223"></a>By way of derogation from paragraph 1, the Commission may require the following lists of data for purpose of surveillance at release for free circulation:
<a id="p113224"></a>(a) the list of data laid down in Annex 21-02 to this Regulation, until the date of deployment of the upgrading of the national import systems referred to in the Annex to Commission Implementing Decision (EU) 2019/2151 <*>;

<a id="p113225"></a>

---

<a id="p113226"></a><*> Commission Implementing Decision (EU) 2019/2151 of 13 December 2019 establishing the work programme relating to the development and deployment of the electronic systems provided for in the Union Customs Code (OJ L 325, 16.12.2019, p. 168).

<a id="p113227"></a>(b) the list of data laid down in Annex 21-01 to this Regulation, until the last date of the deployment window of the first phase of UCC Centralised Clearance for Import, referred to in the Annex to Implementing Decision (EU) 2019/2151.
<a id="p113228"></a>By way of derogation from paragraph 1, the Commission may require the list of data laid down in Annex 21-01 or Annex 21-02 to this Regulation for purpose of surveillance at export, until the last date of the deployment window of the automated export system referred to in the Annex to Implementing Decision (EU) 2019/2151.

<a id="p113229"></a>Article 56

<a id="p113230"></a>Electronic system relating to surveillance of the release
for free circulation or the export of goods
(Articles 16(1) and 56(5) of the Code)

1. <a id="p113231"></a>For the surveillance of the release for free circulation or the export of goods, an electronic system set up pursuant to Article 16(1) of the Code shall be used for the transmission and storage of the following information:
<a id="p113232"></a>(a) surveillance data on the release for free circulation or the export of goods;
<a id="p113233"></a>(b) information which may update the surveillance data introduced and stored in the electronic system on the release for free circulation or the export of goods.
2. <a id="p113234"></a>The Commission may authorise users to access the electronic system referred to in paragraph 1 based on requests of the Member States.
3. <a id="p113235"></a>By derogation from paragraph 1 of this Article, until the date of the deployment of the first phase of the upgrading of the system referred to in the Annex to Implementing Decision 2014/255/EU, the Commission's Surveillance 2 system shall be used for the transmission and storage of the data referred to in points (a) and (b) of that paragraph.

<a id="p113236"></a>**CHAPTER 2**

<a id="p113237"></a>**ORIGIN OF GOODS**

<a id="p113238"></a>Section 1. PROOF OF NON-PREFERENTIA ORIGIN

<a id="p113239"></a>Article 57

<a id="p113240"></a>Certificate of origin for products subject
to special non-preferential import arrangements
(Article 61(1) and (2) of the Code)

1. <a id="p113241"></a>A certificate of origin relating to products having their origin in a third country for which special non-preferential import arrangements are established shall, where those arrangements refer to this Article, be issued using the form set out in Annex 22-14 in compliance with the technical specifications laid down therein.
<a id="p113242"></a>References in special non-preferential import arrangements to certificates of origin issued in accordance with Articles 55 to 65 of Regulation (EEC) No 2454/93 shall be considered references to the certificates of origin referred to in this Article.
2. <a id="p113243"></a>Certificates of origin shall be issued by the competent authorities of the third country where the products to which the special non-preferential import arrangements apply originate, or by a reliable agency duly authorised by those authorities for that purpose (issuing authorities), provided that the origin of the products has been determined in accordance with Article 60 of the Code.
<a id="p113244"></a>The issuing authorities shall keep a copy of each certificate of origin issued.
3. <a id="p113245"></a>Certificates of origin shall be issued before the products to which they relate are declared for export in the third country of origin.
4. <a id="p113246"></a>By way of derogation from paragraph 3, certificates of origin may exceptionally be issued after the export of the products to which they relate where the failure to issue them at the time of export was the result of an error, an involuntary omission or special circumstances.
<a id="p113247"></a>The issuing authorities may not issue retrospectively a certificate of origin provided for in paragraph 1 unless they are satisfied that the particulars in the exporter's application correspond to those in the relevant export file.

<a id="p113248"></a>Article 58

<a id="p113249"></a>Provision of information concerning
administrative cooperation relating to special
non-preferential import arrangements
(Article 61 of the Code)

1. <a id="p113250"></a>Where the special non-preferential import arrangements for certain products provide for the use of the certificate of origin laid down in Article 57 of this Regulation, the use of such arrangements shall be subject to the condition that an administrative cooperation procedure has been set up unless otherwise specified in the arrangements concerned.
<a id="p113251"></a>For the purpose of setting up that administrative cooperation procedure, the third countries concerned shall send to the Commission:
<a id="p113252"></a>(a) the names and addresses of the issuing authorities together with specimens of the stamps used by those authorities;
<a id="p113253"></a>(b) the names and addresses of the governmental authorities to which requests for the subsequent verification of certificates of origin provided for in Article 59 of this Regulation are to be sent.
<a id="p113254"></a>The Commission shall transmit the above information to the competent authorities of the Member States.
2. <a id="p113255"></a>Where a third country fails to send the information specified in paragraph 1 to the Commission, the competent authorities in the Union shall refuse use of the special non-preferential import arrangement.

<a id="p113256"></a>Article 59

<a id="p113257"></a>Subsequent verification of the certificates
of origin for products subject to special
non-preferential import arrangements
(Article 61 of the Code)

1. <a id="p113258"></a>Verification of the certificates of origin referred to in Article 57 of this Regulation shall be carried out in accordance with this Article after the acceptance of the customs declaration (subsequent verification).
2. <a id="p113259"></a>Where the customs authorities have reasonable doubts as to the authenticity of a certificate of origin or the accuracy of the information it contains and where they carry out random subsequent verifications, they shall request the authority referred to in Article 58(1)(b) of this Regulation to verify whether that certificate of origin is authentic or the declared origin was established correctly and in accordance with Article 60 of the Code or both.
<a id="p113260"></a>For those purposes, the customs authorities shall return the certificate of origin or a copy thereof to the authority referred to in Article 58(1)(b) of this Regulation. If an invoice has accompanied the declaration, the original invoice or a copy thereof shall be attached to the returned certificate of origin.
<a id="p113261"></a>The customs authorities shall give, where appropriate, the reasons for the subsequent verification and provide any information in their possession suggesting that the particulars given on the certificate of origin are inaccurate or that the certificate of origin is not authentic.
3. <a id="p113262"></a>The authority referred to in Article 58(1)(b) of this Regulation shall communicate the results of the verifications to the customs authorities as soon as possible.
<a id="p113263"></a>Where there is no reply within 6 months after sending a request in accordance with paragraph 2, the customs authorities shall refuse use of the special non-preferential import arrangement for the products in question.

<a id="p113264"></a>Section 2. PREFERENTIAL ORIGIN

<a id="p113265"></a>Article 60

<a id="p113266"></a>For the purposes of this Section, the definitions laid down in Article 37 of Delegated Regulation (EU) 2015/2446 shall apply.

<a id="p113267"></a>Subsection 1

<a id="p113268"></a>**PROCEDURES TO FACILITATE THE ISSUE**
**OR MAKING OUT OF PROOFS OF ORIGIN**

<a id="p113269"></a>Article 61

<a id="p113270"></a>Supplier's declarations and their use
(Article 64(1) of the Code)

1. <a id="p113271"></a>Where a supplier provides the exporter or the trader with the information necessary to determine the originating status of goods for the purposes of the provisions governing preferential trade between the Union and certain countries or territories (preferential originating status), the supplier shall do so by means of a supplier's declaration.
<a id="p113272"></a>A separate supplier's declaration shall be established for each consignment of goods, except in the cases provided for in Article 62 of this Regulation.
<a id="p113273"></a>1a. In trade between the Contracting Parties to the Regional Convention on pan-Euro-Mediterranean preferential rules of origin <*> ("PEM Convention"), where two or more sets of rules of origin apply, the preferential origin of goods may be determined according to one or more sets of rules of origin.

<a id="p113274"></a>

---

<a id="p113275"></a><*> OJ L 54, 26.2.2013, p. 1.

<a id="p113276"></a>Suppliers shall specify the legal framework used to determine the origin of the goods. Where such a legal framework is not specified, by default, the supplier's declaration shall be considered as stating that the PEM Convention has been used to determine the origin of the goods.
<a id="p113277"></a>1b. For the purpose of trade between the Contracting Parties to the PEM Convention, the exporter may use the supplier's declarations as supporting documents to apply for the issue of a movement certificate or to make out an origin declaration in accordance with the transitional rules of origin <*> applicable in parallel with the PEM Convention rules of origin, when:

<a id="p113278"></a>

---

<a id="p113279"></a><*> The transitional rules of origin are the revised rules of the PEM Convention (OJ L 339, 30.12.2019, p. 1) applicable in parallel with the current rules of the PEM Convention on a transitional basis pending the adoption of the revised rules of the PEM Convention.

<a id="p113280"></a>(a) the supplier's declarations state the originating status in accordance with the PEM Convention rules of origin for products classified under Chapters 1, 3 and 16 (for processed fishery products) and 25 to 97 of the Harmonised System; and
<a id="p113281"></a>(b) there is no application of cumulation with Contracting Parties to the PEM Convention who are applying only the PEM Convention.
<a id="p113282"></a>The exporter shall take all necessary steps to ensure that the conditions for issuing or making out a proof of origin according to a specific set of rules of origin are fulfilled.
2. <a id="p113283"></a>The supplier shall include the declaration on the commercial invoice relating to that consignment, on a delivery note or on any other commercial document which describes the goods concerned in sufficient detail to enable them to be identified.
3. <a id="p113284"></a>The supplier may provide the declaration at any time, even after the goods have been delivered.

<a id="p113285"></a>Article 62

<a id="p113286"></a>Long-term supplier's declaration
(Article 64(1) of the Code)

1. <a id="p113287"></a>Where a supplier regularly supplies an exporter or trader with consignments of goods, and all of those goods are expected to have the same originating status, the supplier may provide a single declaration covering multiple consignments of those goods (a long-term supplier's declaration).
<a id="p113288"></a>1a. In trade between the Contracting Parties to the PEM Convention, where two or more sets of rules of origin apply, the preferential origin of goods may be determined according to one or more sets of rules of origin.
<a id="p113289"></a>Suppliers shall specify, the legal framework used to determine the origin of the goods. Where such a legal framework is not specified, by default, the supplier's declaration shall be considered as stating that the PEM Convention have been used to determine the origin of the goods.
<a id="p113290"></a>1b. For the purpose of trade between the Contracting Parties to the PEM Convention, the exporter may use the supplier's declarations as supporting documents to apply for the issue of a movement certificate or to make out an origin declaration in accordance with the transitional rules of origin applicable in parallel with the PEM Convention, when:
<a id="p113291"></a>(a) the supplier's declarations state the originating status in accordance with the PEM Convention rules of origin for products classified under Chapters 1, 3 and 16 (for processed fishery products) and 25 to 97 of the Harmonised System; and
<a id="p113292"></a>(b) there is no application of cumulation with Contracting Parties to the PEM Convention who are applying only the PEM Convention.
<a id="p113293"></a>The exporter shall take all necessary steps to ensure that the conditions for issuing or making out a proof of origin according to a specific set of rules of origin are fulfilled.
2. <a id="p113294"></a>A long-term supplier's declaration shall be made out for consignments dispatched during a period of time and shall state three dates:
<a id="p113295"></a>(a) the date on which the declaration is made out (date of issue);
<a id="p113296"></a>(b) the date of commencement of the period (start date), which may not be more than 12 months before or more than 6 months after the date of issue;
<a id="p113297"></a>(c) the date of end of the period (end date), which may not be more than 24 months after the start date.
3. <a id="p113298"></a>The supplier shall inform the exporter or trader concerned immediately where the long-term supplier's declaration is not valid in relation to some or all consignments of goods supplied and to be supplied.

<a id="p113299"></a>Article 63

<a id="p113300"></a>Making-out of supplier's declarations
(Article 64(1) of the Code)

1. <a id="p113301"></a>For products having obtained preferential originating status, the supplier's declarations shall be made out as laid down in Annex 22-15. However, long-term suppliers' declarations for those products shall be made out as laid down in Annex 22-16.
2. <a id="p113302"></a>For products which have undergone working or processing in the Union without having obtained preferential originating status, the supplier's declarations shall be made out as laid down in Annex 22-17. However, for long-term supplier's declarations, the supplier's declarations shall be made out as laid down in Annex 22-18.
3. <a id="p113303"></a>The supplier's declaration shall bear a handwritten signature of the supplier. However, where both the supplier's declaration and the invoice are drawn up by electronic means, these can be electronically authenticated or the supplier can give the exporter or trader a written undertaking accepting complete responsibility for every supplier's declaration which identifies him as if it had been signed with his handwritten signature.

<a id="p113304"></a>Article 64

<a id="p113305"></a>Issuing of Information Certificates INF 4
(Article 64(1) of the Code)

1. <a id="p113306"></a>The customs authorities may request the exporter or trader to obtain from the supplier an Information Certificate INF 4 certifying the accuracy and authenticity of the supplier's declaration.
2. <a id="p113307"></a>On application from the supplier, the Information Certificate INF 4 shall be issued by the customs authorities of the Member State in which the supplier's declaration has been made out using the form set out in Annex 22-02 in compliance with the technical specifications laid down therein. The authorities may require any evidence and may carry out inspections of the supplier's accounts or other checks that they consider appropriate.
3. <a id="p113308"></a>The customs authorities shall issue the Information Certificate INF 4 to the supplier within 90 days of receipt of his application, indicating whether the supplier's declaration is accurate and authentic.
4. <a id="p113309"></a>A customs authority to which an application for the issue of an information certificate INF 4 has been made shall keep the application form for at least 3 years or for a longer period of time if necessary in order to ensure compliance with the provisions governing preferential trade between the Union and certain countries or territories.

<a id="p113310"></a>Article 65

<a id="p113311"></a>Administrative cooperation between the Member States
(Article 64(1) of the Code)

<a id="p113312"></a>The customs authorities shall assist each other in checking the accuracy of the information given in suppliers' declarations.

<a id="p113313"></a>Article 66

<a id="p113314"></a>Checking suppliers' declarations
(Article 64(1) of the Code)

1. <a id="p113315"></a>Where an exporter is unable to present an Information Certificate INF 4 within 120 days of the request of the customs authorities, the customs authorities of the Member State of export may ask the customs authorities of the Member State in which the supplier's declaration has been made out to confirm the origin of the products concerned for the purposes of the provisions governing preferential trade between the Union and certain countries.
2. <a id="p113316"></a>For the purposes of paragraph 1, the customs authorities of the Member State of export shall send the customs authorities of the Member State in which the supplier's declaration has been made out all available information and documents and give the reasons for their enquiry.
3. <a id="p113317"></a>For the purposes of paragraph 1 the customs authorities of the Member State in which the supplier's declaration has been made out may request evidence from the supplier or carry out appropriate verifications of that declaration.
4. <a id="p113318"></a>The customs authorities requesting the verification shall be informed of the results as soon as possible by means of an Information Certificate INF 4.
5. <a id="p113319"></a>Where there is no reply within 150 days of the date of the verification request or where the reply does not contain sufficient information to determine the origin of the products concerned, the customs authorities of the country of export shall declare invalid the proof of origin established on the basis of the supplier's declaration.

<a id="p113320"></a>Article 67

<a id="p113321"></a>Approved exporter authorisation
(Article 64(1) of the Code)

1. <a id="p113322"></a>Where the Union has a preferential arrangement with a third country which provides that a proof of origin is to take the form of an invoice declaration or an origin declaration made out by an approved exporter, exporters and re-consignors established in the customs territory of the Union may apply for an authorisation as an approved exporter for the purposes of making out and replacing those declarations.
2. <a id="p113323"></a>Articles 11(1)(d), 16, 17 and 18 of Delegated Regulation (EU) 2015/2446 concerning the conditions for accepting applications and the suspension of decisions and Articles 10 and 15 of this Regulation concerning the use of electronic means for exchanging and storing information and the revocation of favourable decisions pertaining to applications and decisions shall not apply to decisions relating to approved exporter authorisations.
3. <a id="p113324"></a>Approved exporter authorisations shall be granted solely to persons who fulfil the conditions set out in the origin provisions either of agreements which the Union has concluded with certain countries or territories outside the customs territory of the Union or of measures adopted unilaterally by the Union in respect of such countries or territories.
4. <a id="p113325"></a>The customs authorities shall grant to the approved exporter a customs authorisation number which shall appear on the proofs of preferential origin. The customs authorisation number shall begin with the ISO 3166-1-alpha-2 country code of the Member State issuing the authorisation.
5. <a id="p113326"></a>The Commission shall provide the third countries concerned with the addresses of the customs authorities responsible for the control of the proofs of preferential origin made out by approved exporters.
6. <a id="p113327"></a>Where the applicable preferential arrangement does not specify the form that invoice declarations or origin declarations shall take, those declarations shall be drawn up in accordance with the form set out in Annex 22-13.
7. <a id="p113328"></a>Where the applicable preferential arrangement does not specify the value threshold up to which an exporter who is not an approved exporter may make out an invoice declaration or an origin declaration, the value threshold shall be EUR 6 000 for each consignment.

<a id="p113329"></a>Article 68

<a id="p113330"></a>Registration of exporters outside
the framework of the GSP scheme of the Union
(Article 64(1) of the Code)

1. <a id="p113331"></a>Where the Union has a preferential arrangement which requires an exporter to complete a document on origin in accordance with the relevant Union legislation, such a document may be completed only by an exporter who is registered for that purpose by the customs authorities of a Member State. The identity of such exporters shall be recorded in the Registered Exporter System (REX) referred to in the Annex to Implementing Decision (EU) 2016/578. Articles 80, 82, 83, 84, 86, 87, 89 and 91 of this Regulation shall apply mutatis mutandis.
2. <a id="p113332"></a>For the purposes of this Article, Articles 11(1)(d), 16, 17 and 18 of Delegated Regulation (EU) 2015/2446 concerning the conditions for accepting applications and the suspension of decisions and Articles 10(1) and 15 of this Regulation shall not apply. Applications and decisions related to this Article shall not be exchanged and stored in an electronic information and communication system as laid down in Article 10 of this Regulation.
4. <a id="p113333"></a>Notwithstanding paragraph 1, where the applicable preferential arrangement does not specify the value threshold up to which an exporter who is not a registered exporter may complete a document on origin, the value threshold shall be EUR 6 000 for each consignment.
6. <a id="p113334"></a>Where a preferential arrangement allows the Union to exempt originating products from the requirement to provide a document on origin, that exemption shall apply under the conditions laid down in Article 103, insofar as those conditions are not provided for in the preferential arrangement concerned.
7. <a id="p113335"></a>Where a preferential arrangement allows the Union to waive the requirement for a document on origin to be signed by the exporter, no such signature shall be required.

<a id="p113336"></a>Article 69

<a id="p113337"></a>Replacement of documents on corigin issued or made out
outside the framework of the GSP scheme of the Union
(Article 64(1) of the Code)

1. <a id="p113338"></a>Where originating products covered by a document on origin issued or made out previously for the purposes of a preferential tariff measure as referred to in Article 56(2)(d) or (e) of the Code other than the GSP scheme of the Union have not yet been released for free circulation and are placed under the control of a customs office in the Union, the initial document on origin may be replaced by one or more replacement documents on origin for the purposes of sending all or some of those products elsewhere within the Union.
2. <a id="p113339"></a>The replacement document on origin referred to in paragraph 1 may be issued for, or made out by, any of the following, in the same form as the initial document on origin or in the form of a replacement statement on origin, drawn up mutatis mutandis in accordance with Article 101 and Annex 22-20:
<a id="p113340"></a>(a) an exporter approved or registered in the Union and re-consigning the goods;
<a id="p113341"></a>(b) a re-consignor of the goods in the Union where the total value of originating products in the initial consignment to be split does not exceed the applicable value threshold;
<a id="p113342"></a>(c) a re-consignor of the goods in the Union where the total value of originating products in the initial consignment to be split exceeds the applicable value threshold, and the re-consignor attaches a copy of the initial document on origin to the replacement document on origin.
<a id="p113343"></a>Where the replacement of the initial document on origin is not possible in accordance with the first subparagraph, the replacement document on origin referred to in paragraph 1 may be issued in the form of a movement certificate EUR.1 by the customs office under whose control the goods are placed.
3. <a id="p113344"></a>Where the replacement document on origin is a movement certificate EUR.1, the endorsement made by the customs office issuing the replacement movement certificate EUR.1 shall be placed in box 11 of the certificate. The particulars in box 4 of the certificate concerning the country of origin shall be identical to those particulars in the initial document on origin. Box 12 shall be signed by the re-consignor. A re-consignor who signs box 12 in good faith shall not be responsible for the accuracy of the particulars entered on the initial document on origin.
<a id="p113345"></a>The customs office which is requested to issue the replacement movement certificate EUR.1 shall note on the initial document on origin or on an attachment thereto the weights, numbers, nature of the products forwarded and their country of destination, and indicate thereon the serial numbers of the corresponding replacement certificate or certificates. It shall keep the initial document on origin for at least 3 years.

<a id="p113346"></a>Article 69a

<a id="p113347"></a>Preferential origin of processed products obtained from
goods having preferential originating status
(Article 64(1) of the Code)

1. <a id="p113348"></a>Where non-Union goods having preferential originating status in the framework of a preferential arrangement between the Union and third countries, are placed under the inward processing procedure, processed products obtained therefrom shall, when released for free circulation, be deemed to have the same preferential originating status as those goods.
2. <a id="p113349"></a>Paragraph 1 shall not apply in any of the following cases:
<a id="p113350"></a>(a) the processing operation also involves non-Union goods other than those referred to in paragraph 1, including goods having preferential originating status under a different preferential arrangement;
<a id="p113351"></a>(b) the processed products are obtained from equivalent goods referred to in Article 223 of the Code;
<a id="p113352"></a>(c) the customs authorities have authorised temporary re-export of the goods for further processing in accordance with Article 258 of the Code.
3. <a id="p113353"></a>Where paragraph 1 applies, a document on origin issued or made out for the goods placed under the inward processing procedure shall be deemed to be a document on origin issued or made out for the processed products.

<a id="p113354"></a>Subsection 2

<a id="p113355"></a>**OBLIGATIONS OF BENEFICIARY COUNTRIES WITHIN THE FRAMEWORK**
**OF THE GSP SCHEME OF THE UNION**

<a id="p113356"></a>Article 70

<a id="p113357"></a>Obligation to provide administrative cooperation
within the framework of the REX system
(Article 64(1) of the Code)

1. <a id="p113358"></a>In order to ensure the proper application of the GSP scheme beneficiary countries shall undertake:
<a id="p113359"></a>(a) to put in place and to maintain the necessary administrative structures and systems required for the implementation and management in that country of the rules and procedures laid down in this Subsection and Subsections 3 to 9 of this Section and Subsections 2 and 3 of Title II Chapter 1 Section 2 of Delegated Regulation (EU) 2015/2446, including where appropriate the arrangements necessary for the application of cumulation;
<a id="p113360"></a>(b) that their competent authorities will cooperate with the Commission and the customs authorities of the Member States.
2. <a id="p113361"></a>The cooperation referred to in point (b) of paragraph 1 shall consist of:
<a id="p113362"></a>(a) providing all necessary support in the event of a request by the Commission for the monitoring by it of the proper management of the GSP scheme in the country concerned, including verification visits on the spot by the Commission or the customs authorities of the Member States;
<a id="p113363"></a>(b) without prejudice to Articles 108 and 109 of this Regulation, verifying the originating status of products and the compliance with the other conditions laid down in this Subsection, Subsections 3 to 9 of this Section and Subsections 2 and 3 of Title II Chapter 1 Section 2 of Delegated Regulation (EU) 2015/2446, including visits on the spot, where requested by the Commission or the customs authorities of the Member States in the context of origin investigations.
3. <a id="p113364"></a>To be entitled to apply the registered exporters system, the beneficiary countries shall submit the undertaking referred to in paragraph 1 to the Commission at least 3 months before the date on which they intend to start the registration of exporters.
4. <a id="p113365"></a>Where a country or territory has been removed from Annex II to Regulation (EU) No 978/2012 of the European Parliament and of the Council <*>, the rules and procedures laid down in Article 55 of Delegated Regulation (EU) 2015/2446 and the obligations laid down in Articles 72, 80 and 108 of this Regulation shall continue to apply to that country or territory for a period of 3 years from the date of its removal from that Annex.

<a id="p113366"></a>

---

<a id="p113367"></a><*> Regulation (EU) No 978/2012 of the European Parliament and of the Council of 25 October 2012 applying a scheme of generalised tariff preferences and repealing Council Regulation (EC) No 732/2008 (OJ L 303, 31.10.2012, p. 1).


<a id="p113368"></a>Article 71

<a id="p113369"></a>Procedures and methods of administrative cooperation
applicable with regard to exports using certificates
of origin Form A and invoice declarations
(Article 64(1) of the Code)

1. <a id="p113370"></a>Every beneficiary country shall comply or ensure compliance with:
<a id="p113371"></a>(a) the rules on the origin of the products being exported, laid down in Subsection 2 of Title II Chapter 1 Section 2 of Delegated Regulation (EU) 2015/2446;
<a id="p113372"></a>(b) the rules for completion and issue of certificates of origin Form A;
<a id="p113373"></a>(c) the provisions for the use of invoice declarations, to be drawn up in accordance with the requirements set out in Annex 22-09;
<a id="p113374"></a>(d) the provisions concerning the obligations of notifications referred to in Article 73 of this Regulation;
<a id="p113375"></a>(e) the provisions concerning granting of derogations referred to in Article 64(6) of the Code.
2. <a id="p113376"></a>The competent authorities of the beneficiary countries shall cooperate with the Commission or the Member States by, in particular:
<a id="p113377"></a>(a) providing all necessary support in the event of a request by the Commission for the monitoring by it of the proper management of the GSP scheme in the country concerned, including verification visits on the spot by the Commission or the customs authorities of the Member States;
<a id="p113378"></a>(b) without prejudice to Articles 73 and 110 of this Regulation, verifying the originating status of products and the compliance with the other conditions laid down in this Subsection, Subsections 3 to 9 of this Section and Subsections 2 and 3 of Title II Chapter 1 Section 2 of Delegated Regulation (EU) 2015/2446, including visits on the spot, where requested by the Commission or the customs authorities of the Member States in the context of origin investigations.
3. <a id="p113379"></a>Where, in a beneficiary country, a competent authority for issuing certificates of origin Form A is designated, documentary proofs of origin are verified, and certificates of origin Form A for exports to the Union are issued, that beneficiary country shall be considered to have accepted the conditions laid down in paragraph 1.
4. <a id="p113380"></a>When a country is admitted or readmitted as a beneficiary country in respect of products referred to in Regulation (EU) No 978/2012, goods originating in that country shall benefit from the generalised system of preferences on condition that they were exported from the beneficiary country on or after the date referred to in Article 73(2) of this Regulation.
5. <a id="p113381"></a>Where a country or territory has been removed from Annex II to Regulation (EU) No 978/2012, the obligation to provide administrative cooperation laid down in Article 55 of Delegated Regulation (EU) 2015/2446 and Articles 110 and 111 of this Regulation shall continue to apply to that country or territory for a period of 3 years from the date of its removal from that annex.
6. <a id="p113382"></a>The obligations referred to in paragraph 5 shall apply to Singapore for a period of 3 years starting from 1 January 2014.

<a id="p113383"></a>Article 72

<a id="p113384"></a>Notification obligations applicable after the date of
application of the registered exporter (REX) system
(Article 64(1) of the Code)

1. <a id="p113385"></a>Beneficiary countries shall notify the Commission of the names and addresses and contact details of the authorities situated in their territory which are:
<a id="p113386"></a>(a) part of the governmental authorities of the country concerned, or act under the authority of the government thereof, and competent to register exporters in the REX system, modify and update registration data and revoke registrations;
<a id="p113387"></a>(b) part of the governmental authorities of the country concerned and responsible for ensuring the administrative cooperation with the Commission and the customs authorities of the Member States as provided for in this Subsection, Subsections 3 to 9 of this Section and Subsections 2 and 3 of Title II Chapter 1 Section 2 of Delegated Regulation (EU) 2015/2446.
2. <a id="p113388"></a>The notification shall be sent to the Commission at the latest 3 months before the date on which the beneficiary countries intend to start the registration of exporters.
3. <a id="p113389"></a>Beneficiary countries shall inform the Commission immediately of any changes to the information notified under the first paragraph.

<a id="p113390"></a>Article 73

<a id="p113391"></a>Notification obligations applicable until the date of
application of the registered exporter (REX) system
(Article 64(1) of the Code)

1. <a id="p113392"></a>The beneficiary countries shall inform the Commission of the names and addresses of the governmental authorities situated in their territory which are empowered to issue certificates of origin Form A, together with specimen impressions of the stamps used by those authorities, and the names and addresses of the relevant governmental authorities responsible for the control of the certificates of origin Form A and the invoice declarations.
<a id="p113393"></a>The Commission will forward this information to the customs authorities of the Member States. When this information is communicated within the framework of an amendment of previous communications, the Commission will indicate the date of entry into use of those new stamps according to the instructions given by the competent governmental authorities of the beneficiary countries. This information is for official use; however, when goods are to be released for free circulation, the customs authorities in question may allow the importer to consult the specimen impressions of the stamps.
<a id="p113394"></a>Beneficiary countries which have already provided the information required under the first sub-paragraph shall not be obliged to provide it again, unless there has been a change.
2. <a id="p113395"></a>For the purpose of Article 71(4) of this Regulation, the Commission will publish, on its website, the date on which a country admitted or readmitted as a beneficiary country in respect of products referred to in Regulation (EU) No 978/2012 met the obligations set out in paragraph 1 of this Article.
3. <a id="p113396"></a>Upon request of a beneficiary country, the Commission shall send to that beneficiary country specimen impressions of the stamps used by the customs authorities of the Member States for the issue of movement certificates EUR.1.

<a id="p113397"></a>Subsection 3

<a id="p113398"></a>**PROCEDURES AT EXPORT IN BENEFICIARY COUNTRIES AND IN THE**
**UNION APPLICABLE WITHIN THE FRAMEWORK OF THE GSP SCHEME OF**
**THE UNION UNTIL THE APPLICATION OF THE REGISTERED EXPORTER**
**SYSTEM**

<a id="p113399"></a>Article 74

<a id="p113400"></a>Procedure for the issue of a certificate of origin Form A
(Article 64(1) of the Code)

1. <a id="p113401"></a>Certificates of origin Form A shall be issued on written application from the exporter or its representative, together with any other appropriate supporting documents proving that the products to be exported qualify for the issue of a certificate of origin Form A. Certificates of origin Form A shall be issued using the form set out in Annex 22-08.
2. <a id="p113402"></a>The competent authorities of beneficiary countries shall make available the certificate of origin Form A to the exporter as soon as the exportation has taken place or is ensured. However, the competent authorities of beneficiary countries may also issue a certificate of origin Form A after exportation of the products to which it relates, if:
<a id="p113403"></a>(a) it was not issued at the time of exportation because of errors or involuntary omissions or special circumstances; or
<a id="p113404"></a>(b) it is demonstrated to the satisfaction of the competent authorities that a certificate of origin Form A was issued but was not accepted at importation for technical reasons; or
<a id="p113405"></a>(c) the final destination of the products concerned was determined during their transportation or storage and after possible splitting of a consignment, in accordance with Article 43 of Delegated Regulation (EU) 2015/2446.
3. <a id="p113406"></a>The competent authorities of beneficiary countries may issue a certificate retrospectively only after verifying that the information supplied in the exporter's application for a certificate of origin Form A issued retrospectively is in accordance with that in the corresponding export file and that a certificate of origin Form A was not issued when the products in question were exported, except when the certificate of origin Form A was not accepted for technical reasons. The words "Issued retrospectively", " Délivré a posteriori" or "emitido a posteriori" shall be indicated in box 4 of the certificate of origin Form A issued retrospectively.
4. <a id="p113407"></a>In the event of theft, loss or destruction of a certificate of origin Form A, the exporter may apply to the competent authorities which issued it for a duplicate to be made out on the basis of the export documents in their possession. The words "Duplicate", "Duplicata" or "Duplicado", the date of issue and the serial number of the original certificate shall be indicated in box 4 of the duplicate certificate of origin Form A. The duplicate takes effect from the date of the original.
5. <a id="p113408"></a>For the purposes of verifying whether the product for which a certificate of origin Form A is requested complies with the relevant rules of origin, the competent governmental authorities shall be entitled to call for any documentary evidence or to carry out any check which they consider appropriate.
6. <a id="p113409"></a>Completion of boxes 2 and 10 of the certificate of origin Form A shall be optional. Box 12 shall bear the mention "Union" or the name of one of the Member States. The date of issue of the certificate of origin Form A shall be indicated in box 11. The signature to be entered in that box, which is reserved for the competent governmental authorities issuing the certificate, as well as the signature of the exporter's authorised signatory to be entered in box 12, shall be handwritten.

<a id="p113410"></a>Article 75

<a id="p113411"></a>Conditions for making out an invoice declaration
(Article 64(1) of the Code)

1. <a id="p113412"></a>The invoice declaration may be made out by any exporter operating in a beneficiary country for any consignment consisting of one or more packages containing originating products whose total value does not exceed EUR 6 000, and provided that the administrative cooperation referred to in Article 71(2) applies to this procedure.
2. <a id="p113413"></a>The exporter making out an invoice declaration shall be prepared to submit at any time, at the request of the customs or other competent governmental authorities of the exporting country, all appropriate documents proving the originating status of the products concerned.
3. <a id="p113414"></a>An invoice declaration shall be made out by the exporter in either French, English or Spanish by typing, stamping or printing on the invoice, the delivery note or any other commercial document, the declaration, the text of which appears in Annex 22-09. If the declaration is handwritten, it shall be written in ink in printed characters. Invoice declarations shall bear the original handwritten signature of the exporter.
4. <a id="p113415"></a>The use of an invoice declaration shall be subject to the following conditions:
<a id="p113416"></a>(a) one invoice declaration shall be made out for each consignment;
<a id="p113417"></a>(b) if the goods contained in the consignment have already been subject to verification in the exporting country by reference to the definition of "originating products", the exporter may refer to that verification in the invoice declaration.

<a id="p113418"></a>Article 76

<a id="p113419"></a>Conditions for issuing a certificate of origin
Form A in case of cumulation
(Article 64(1) of the Code)

<a id="p113420"></a>When cumulation under Articles 53, 54, 55 or 56 of Delegated Regulation (EU) 2015/2446 applies, the competent governmental authorities of the beneficiary country called on to issue a certificate of origin Form A for products in the manufacture of which materials originating in a party with which cumulation is permitted are used shall rely on the following:
<a id="p113421"></a>(a) in the case of bilateral cumulation, on the proof of origin provided by the exporter's supplier and issued in accordance with the provisions of Article 77 of this Regulation;
<a id="p113422"></a>(b) in the case of cumulation with Norway, Switzerland or Turkey, on the proof of origin provided by the exporter's supplier and issued in accordance with the relevant rules of origin of Norway, Switzerland or Turkey, as the case may be;
<a id="p113423"></a>(c) in the case of regional cumulation, on the proof of origin provided by the exporter's supplier, namely a certificate of origin Form A, issued using the form set out in Annex 22-08 or, as the case may be, an invoice declaration, the text of which appears in Annex 22-09;
<a id="p113424"></a>(d) in the case of extended cumulation, on the proof of origin provided by the exporter's supplier and issued in accordance with the provisions of the relevant free-trade agreement between the Union and the country concerned.
<a id="p113425"></a>In the cases referred to in points (a), (b), (c) and (d) of the first subparagraph, Box 4 of certificate of origin Form A shall, as the case may be, contain the indication:
- <a id="p113426"></a>"EU cumulation", "Norway cumulation", "Switzerland cumulation", "Turkey cumulation", "regional cumulation", "extended cumulation with country x", or
- <a id="p113427"></a>"Cumul UE", "Cumul Norvège ", "Cumul Suisse", "Cumul Turquie", "cumul r gional", "cumul étendu avec le pays x", or
- <a id="p113428"></a>" Acumulación UE", " Acumulación Noruega", " Acumulación Suiza", " Acumulación Turquía ", " Acumulación regional", " Acumulación ampliada con el país x".

<a id="p113429"></a>Article 77

<a id="p113430"></a>Proof of Union's originating status for the purpose of
bilateral cumulation and approved exporter
(Article 64(1) of the Code)

1. <a id="p113431"></a>Evidence of the originating status of Union products shall be furnished by either of the following:
<a id="p113432"></a>(a) the production of a movement certificate EUR.1, issued using the form set out in Annex 22-10; or
<a id="p113433"></a>(b) the production of an invoice declaration, the text of which is set out in Annex 22-09. An invoice declaration may be made out by any exporter for consignments containing originating products whose total value does not exceed EUR 6 000 or by an approved Union exporter.
2. <a id="p113434"></a>The exporter or its representative shall enter "GSP beneficiary countries" and "EU", or "Pays bénéficiaires du SPG" and "UE", in box 2 of the movement certificate EUR.1.
3. <a id="p113435"></a>The provisions of this Subsection, Subsections 3 to 9 of this Section and Subsections 2 and 3 of Title II Chapter 1 Section 2 of Delegated Regulation (EU) 2015/2446 concerning the issue, use and subsequent verification of certificates of origin Form A shall apply mutatis mutandis to EUR.1 movement certificates and, with the exception of the provisions concerning their issue, to invoice declarations.
4. <a id="p113436"></a>The customs authorities of the Member States may authorise any exporter established in the customs territory of the Union, hereinafter referred to as an "approved exporter", who makes frequent shipments of products originating in the Union within the framework of bilateral cumulation to make out invoice declarations, irrespective of the value of the products concerned, where that exporter offers, to the satisfaction of the customs authorities, all guarantees necessary to verify the following:
<a id="p113437"></a>(a) the originating status of the products;
<a id="p113438"></a>(b) the fulfilment of other requirements applicable in that Member State.
5. <a id="p113439"></a>The customs authorities may grant the status of approved exporter subject to any conditions which they consider appropriate. The customs authorities shall grant to the approved exporter a customs authorisation number which shall appear on the invoice declaration.
6. <a id="p113440"></a>The customs authorities shall monitor the use of the authorisation by the approved exporter. The customs authorities may withdraw the authorisation at any time.
<a id="p113441"></a>They shall withdraw the authorisation in each of the following cases:
<a id="p113442"></a>(a) the approved exporter no longer offers the guarantees referred to in paragraph 4;
<a id="p113443"></a>(b) the approved exporter does not fulfil the conditions referred to in paragraph 5;
<a id="p113444"></a>(c) the approved exporter otherwise makes improper use of the authorisation.
7. <a id="p113445"></a>An approved exporter shall not be required to sign invoice declarations provided that the approved exporter gives the customs authorities a written undertaking accepting full responsibility for any invoice declaration which identifies the approved exporter as if the approved exporter had signed it with his handwritten signature.

<a id="p113446"></a>Subsection 4

<a id="p113447"></a>**PROCEDURES AT EXPORT IN BENEFICIARY COUNTRIES AND IN THE**
**UNION APPLICABLE WITHIN THE FRAMEWORK OF THE GSP SCHEME OF**
**THE UNION FROM THE DATE OF THE APPLICATION OF THE REGISTERED**
**EXPORTER SYSTEM**

<a id="p113448"></a>Article 78

<a id="p113449"></a>Obligation for exporters to be registered and waiver thereof
(Article 64(1) of the Code)

1. <a id="p113450"></a>The GSP scheme shall apply in the following cases:
<a id="p113451"></a>(a) in cases of goods satisfying the requirements of this Subsection, Subsections 3 to 9 of this Section and Subsections 2 and 3 of Title II Chapter 1 Section 2 of Delegated Regulation (EU) 2015/2446 exported by a registered exporter;
<a id="p113452"></a>(b) in cases of any consignment of one or more packages containing originating products exported by any exporter, where the total value of the originating products consigned does not exceed EUR 6 000.
2. <a id="p113453"></a>The value of originating products in a consignment is the value of all originating products within one consignment covered by a statement on origin made out in the country of exportation.

<a id="p113454"></a>Article 79

<a id="p113455"></a>Registration procedure in the beneficiary countries and
procedures at export applicable during the transition period
to the application of the registered exporter system
(Article 64(1) of the Code)

1. <a id="p113456"></a>Beneficiary countries shall start the registration of exporters on 1 January 2017.
<a id="p113457"></a>However, where the beneficiary country is not in a position to start registration on that date, it shall notify the Commission in writing by 1 July 2016 that it postpones the registration of exporters until 1 January 2018 or 1 January 2019.
2. <a id="p113458"></a>During a period of 12 months following the date on which the beneficiary country starts the registration of exporters, the competent authorities of that beneficiary country shall continue to issue certificates of origin Form A at the request of exporters who are not yet registered at the time of requesting the certificate.
<a id="p113459"></a>Without prejudice to Article 94(2) of this Regulation, certificates of origin Form A issued in accordance with the first sub-paragraph of this paragraph shall be admissible in the Union as proof of origin if they are issued before the date of registration of the exporter concerned.
<a id="p113460"></a>The competent authorities of a beneficiary country experiencing difficulties in completing the registration process within the above 12month period may request its extension to the Commission. Such extensions shall not exceed 6 months.
3. <a id="p113461"></a>Exporters in a beneficiary country, registered or not, shall make out statements on origin for originating products consigned, where the total value thereof does not exceed EUR 6 000, as of the date from which the beneficiary country intends to start the registration of exporters.
<a id="p113462"></a>Exporters, once registered, shall make out statements on origin for originating products consigned, where the total value thereof exceeds EUR 6 000, as of the date from which their registration is valid in accordance with Article 86(4) of this Regulation.
4. <a id="p113463"></a>All beneficiary countries shall apply the registered exporter system as of 30 June 2020 at the latest.
<a id="p113464"></a>Subsection 5

<a id="p113465"></a>Article 80

<a id="p113466"></a>Registered exporter database: obligations of the authorities
(Article 64(1) of the Code)

1. <a id="p113467"></a>The Commission shall set up a system for registering exporters authorised to certify the origin of goods (the REX system) and make it available by 1 January 2017.
2. <a id="p113468"></a>The competent authorities of beneficiary countries shall upon receipt of the complete application form referred to in Annex 22-06 assign without delay the number of registered exporter to the exporter and enter into the REX system the number of registered exporter, the registration data and the date from which the registration is valid in accordance with Article 86(4).
<a id="p113469"></a>The customs authorities of Member States shall upon receipt of the complete application form referred to in Annex 22-06A assign without delay the number of registered exporter to the exporter or, where appropriate, the re-consignor of goods and enter into the REX system the number of registered exporter, the registration data and the date from which the registration is valid in accordance with Article 86(4).
<a id="p113470"></a>The competent authorities of a beneficiary country or the customs authorities of a Member State shall inform the exporter or, where appropriate, the re-consignor of goods of the number of registered exporter assigned to that exporter or re-consignor of goods and of the date from which the registration is valid.
3. <a id="p113471"></a>Where the competent authorities consider that the information provided in the application is incomplete, they shall inform the exporter thereof without delay.
4. <a id="p113472"></a>The competent authorities of beneficiary countries and the customs authorities of Member States shall keep the data registered by them up-to-date. They shall modify those data immediately after having been informed by the registered exporter in accordance with Article 89 of this Regulation. The competent authorities of a beneficiary country or the customs authorities of a Member State shall inform the registered exporter of the modification of his registration data.

<a id="p113473"></a>Article 81

<a id="p113474"></a>Date of application of certain provisions
(Article 64(1) of the Code)

1. <a id="p113475"></a>Articles 70, 72, 78 to 80, 82 to 93, 99 to 107, 108, 109 and 112 of this Regulation shall apply in respect of export of goods by exporters registered under the REX system in a beneficiary country from the date on which that beneficiary country starts registering exporters under that system. In so far as exporters in the Union are concerned, these Articles shall apply from 1 January 2017.
2. <a id="p113476"></a>Articles 71, 73, 74 to 77, 94 to 98 and 110 to 112 of this Regulation shall apply in respect of export of goods by exporters who are not registered under the REX system in a beneficiary country. In so far as exporters in the Union are concerned, these Articles shall apply until 31 December 2017.

<a id="p113477"></a>Article 82

<a id="p113478"></a>Registered exporter database: access rights to the database
(Article 64(1) of the Code)

1. <a id="p113479"></a>The Commission shall ensure that access to the REX system is given in accordance with this Article.
2. <a id="p113480"></a>The Commission shall have access to consult all the data.
3. <a id="p113481"></a>The competent authorities of a beneficiary country shall have access to consult the data concerning exporters registered by them.
4. <a id="p113482"></a>The customs authorities of the Member States shall have access to consult the data registered by them, by the customs authorities of other Member States and by the competent authorities of beneficiary countries as well as by Norway, Switzerland or Turkey. This access to the data shall take place for the purpose of carrying out verifications of customs declarations under Article 188 of the Code or post-release control under Article 48 of the Code.
5. <a id="p113483"></a>The Commission shall provide secure access to the REX system to the competent authorities of beneficiary countries.
6. <a id="p113484"></a>Where a country or territory has been removed from Annex II to Regulation (EU) No 978/2012, its competent authorities shall keep the access to the REX system as long as required in order to enable them to comply with their obligations under Article 70 of this Regulation.
7. <a id="p113485"></a>The Commission shall make the following data available to the public on condition that consent has been given by the exporter by signing box 6 of the form set out in Annex 22-06 or Annex 22-06A, as applicable:
<a id="p113486"></a>(a) name of the registered exporter as specified in box 1 of the form set out in Annex 22-06 or Annex 22-06A, as appropriate;
<a id="p113487"></a>(b) address of the place where the registered exporter is established as specified in box 1 of the form set out in Annex 22-06 or Annex 22-06A, as appropriate;
<a id="p113488"></a>(c) contact details as specified in box 1 and box 2 of the form set out in Annex 22-06 or Annex 22-06A, as appropriate;
<a id="p113489"></a>(d) indicative description of the goods which qualify for preferential treatment, including indicative list of Harmonised System headings or chapters, as specified in box 4 of the form set out in Annex 22-06 or Annex 22-06A, as appropriate;
<a id="p113490"></a>(e) EORI number of the registered exporter as specified in box 1 of the form set out in Annex 22-06A, or the trader identification number (TIN) of the registered exporter as specified in box 1 of the form set out in Annex 22-06;
<a id="p113491"></a>(f) whether the registered exporter is a trader or a producer as specified in box 3 of the form set out in Annex 22-06 or Annex 22-06A, as appropriate.
<a id="p113492"></a>The refusal to sign box 6 shall not constitute a ground for refusing to register the exporter.
8. <a id="p113493"></a>The Commission shall always make the following data available to the public
<a id="p113494"></a>(a) the number of registered exporter;
<a id="p113495"></a>(b) the date of registration of the registered exporter;
<a id="p113496"></a>(c) the date from which the registration is valid;
<a id="p113497"></a>(d) the date of the revocation of the registration where applicable;
<a id="p113498"></a>(e) information whether the registration applies also to exports to Norway, Switzerland or Turkey;
<a id="p113499"></a>(f) the date of the last synchronisation between the REX system and the public website.

<a id="p113500"></a>Article 83

<a id="p113501"></a>Registered exporter database: data protection
(Article 64(1) of the Code)

1. <a id="p113502"></a>The data registered in the REX system shall be processed solely for the purpose of the application of the GSP scheme as set out in this Subsection.
2. <a id="p113503"></a>Registered exporters shall be provided with the information laid down in Article 11(1)(a) to (e) of Regulation (EC) No 45/2001 of the European Parliament and of the Council <*> or Article 10 of Directive 95/46/EC of the European Parliament and of the Council <**>. In addition, they shall also be provided with the following information:

<a id="p113504"></a>

---

<a id="p113505"></a><*> Regulation (EC) No 45/2001 of the European Parliament and of the Council of 18 December 2000 on the protection of individuals with regard to the processing of personal data by the Community institutions and bodies and on the free movement of such data (OJ L 8, 12.1.2001, p. 1).
<a id="p113506"></a><**> Directive 95/46/EC of the European Parliament and of the Council of 24 October 1995 on the protection of individuals with regard to the processing of personal data and on the free movement of such data (OJ L 281, 23.11.1995, p. 31).

<a id="p113507"></a>(a) information concerning the legal basis of the processing operations for which the data is intended;
<a id="p113508"></a>(b) the data retention period.
<a id="p113509"></a>Registered exporters shall be provided with that information via a notice attached to the application to become a registered exporter as set out in Annex 22-06 or in Annex 22-06A, as appropriate.
3. <a id="p113510"></a>Each competent authority in a beneficiary country and each customs authority in a Member State that has introduced data into the REX system shall be considered the controller with respect to the processing of those data.
<a id="p113511"></a>The Commission shall be considered as a joint controller with respect to the processing of all data to guarantee that the registered exporter will obtain his rights.
4. <a id="p113512"></a>The rights of registered exporters with regard to the processing of data which is stored in the REX system listed in Annex 22-06 or in Annex 22-06A, as appropriate and processed in national systems shall be exercised in accordance with the data protection legislation implementing Directive 95/46/EC of the Member State which is storing their data.
5. <a id="p113513"></a>Member States who replicate in their national systems the data of the REX system they have access to shall keep the replicated data-up-to date.
6. <a id="p113514"></a>The rights of registered exporters with regard to the processing of their registration data by the Commission shall be exercised in accordance with Regulation (EC) No 45/2001.
7. <a id="p113515"></a>Any request by a registered exporter to exercise the right of access, rectification, erasure or blocking of data in accordance with Regulation (EC) No 45/2001 shall be submitted to and processed by the controller of data.
<a id="p113516"></a>Where a registered exporter has submitted such a request to the Commission without having tried to obtain his rights from the controller of data, the Commission shall forward that request to the controller of data of the registered exporter.
<a id="p113517"></a>If the registered exporter fails to obtain his rights from the controller of data, the registered exporter shall submit such request to the Commission acting as controller. The Commission shall have the right to rectify, erase or block the data.
8. <a id="p113518"></a>The national supervisory data protection authorities and the European Data Protection Supervisor, each acting within the scope of their respective competence, shall cooperate and ensure coordinated supervision of the registration data.
<a id="p113519"></a>They shall, each acting within the scope of their respective competences, exchange relevant information, assist each other in carrying out audits and inspections, examine difficulties of interpretation or application of this Regulation, study problems with the exercise of independent supervision or in the exercise of the rights of data subjects, draw up harmonised proposals for joint solutions to any problems and promote awareness of data protection rights, as necessary.

<a id="p113520"></a>Article 84

<a id="p113521"></a>Notification obligations applicable to Member States for the
implementation of the registered exporter (REX) system
(Article 64(1) of the Code)

<a id="p113522"></a>Member States shall notify the Commission of the names, addresses and contact details of their customs authorities which are:
<a id="p113523"></a>(a) competent to register exporters and re-consignors of goods in the REX system, modify and update registration data and revoke registration;
<a id="p113524"></a>(b) responsible for ensuring the administrative cooperation with the competent authorities of the beneficiary countries as provided for in this Subsection, Subsections 3 to 9 of this Section and Subsections 2 and 3 of Title II Chapter 1 Section 2 of Delegated Regulation (EU) 2015/2446.
<a id="p113525"></a>The notification shall be sent to the Commission by 30 September 2016.
<a id="p113526"></a>Member States shall inform the Commission immediately of any changes to the information notified under the first sub-paragraph.

<a id="p113527"></a>Article 85

<a id="p113528"></a>Registration procedure in the Member States and procedures
at export applicable during the transition period to the
application of the registered exporter system
(Article 64(1) of the Code)

1. <a id="p113529"></a>On 1 January 2017, the customs authorities of Member States shall start the registration of exporters established in their territories.
2. <a id="p113530"></a>As of 1 January 2018, the customs authorities in all Member States shall cease to issue movement certificates EUR.1 and approved exporters shall cease to make out invoice declarations for the purpose of cumulation under Article 53 of Delegated Regulation (EU) 2015/2446.
3. <a id="p113531"></a>Until 31 December 2017, the customs authorities of Member States shall issue movement certificates EUR.1 or replacement certificates of origin Form A at the request of exporters or re-consignors of goods who are not yet registered. This shall also apply if the originating products sent to the Union are accompanied by statements on origin made out by a registered exporter in a beneficiary country.
<a id="p113532"></a>Until 31 December 2017, approved exporters in Member States who are not yet registered may make out invoice declarations for the purpose of cumulation under Article 53 of Delegated Regulation (EU) 2015/2446.
4. <a id="p113533"></a>Exporters in the Union, registered or not, shall make out statements on origin for originating products consigned, where the total value thereof does not exceed EUR 6 000, as from 1 January 2017.
<a id="p113534"></a>Exporters, once registered, shall make out statements on origin for originating products consigned, where the total value thereof exceeds EUR 6 000, as of the date on which their registration is valid in accordance with Article 86(4) of this Regulation.
5. <a id="p113535"></a>Re-consignors of goods who are registered may make out replacement statements on origin from the date from which their registration is valid in accordance with Article 86(4) of this Regulation. This shall apply regardless of whether the goods are accompanied by a certificate of origin Form A issued in the beneficiary country or an invoice declaration or a statement on origin made out by the exporter.

<a id="p113536"></a>Article 86

<a id="p113537"></a>Application to become a registered exporter
(Article 64(1) of the Code)

1. <a id="p113538"></a>To become a registered exporter, an exporter shall lodge an application with the competent authorities of the beneficiary country where he has his headquarters or where he is permanently established.
<a id="p113539"></a>The application shall be made using the form set out in Annex 22-06.
2. <a id="p113540"></a>To become a registered exporter, an exporter or a re-consignor of goods established in the customs territory of the Union shall lodge an application with the customs authorities of that Member States. The application shall be made using the form set out in Annex 22-06A.
3. <a id="p113541"></a>For the purposes of exports under the GSP schemes of the Union, of Norway or of Switzerland, exporters shall only be required to be registered once.
<a id="p113542"></a>A registered exporter number shall be assigned to the exporter by the competent authorities of the beneficiary country with a view to exporting under the GSP schemes of the Union, Norway and Switzerland, to the extent that those countries have recognised the country where the registration has taken place as a beneficiary country.
<a id="p113543"></a>The first and second subparagraphs shall apply mutatis mutandis for the purpose of exports under the GSP scheme of Turkey once that country starts applying the REX system. The Commission shall publish in the Official Journal of the European Union (C series) the date on which Turkey starts applying that system.
4. <a id="p113544"></a>The registration shall be valid as of the date on which the competent authorities of a beneficiary country or the customs authorities of a Member State receive a complete application for registration, in accordance with paragraphs 1 and 2.
5. <a id="p113545"></a>Where the exporter is represented for the purpose of carrying out export formalities and the representative of the exporter is also a registered exporter, this representative shall not use his own registered exporter number.

<a id="p113546"></a>Article 87

<a id="p113547"></a>Registered exporter system: Publication requirement
(Article 64(1) of the Code)

<a id="p113548"></a>The Commission shall publish on its website the date on which beneficiary countries start applying the REX system. The Commission shall keep the information up-to-date.

<a id="p113549"></a>Article 88

<a id="p113550"></a>Automatic registration of exporters for a country becoming
a beneficiary country of the GSP scheme of the Union
(Article 64(1) of the Code)

<a id="p113551"></a>Where a country is added to the list of beneficiary countries in Annex II to Regulation (EU) No 978/2012, the Commission shall automatically activate for its GSP scheme the registrations of all exporters registered in that country provided that the registration data of the exporters are available in the REX system and are valid for at least the GSP scheme of Norway, Switzerland or Turkey.
<a id="p113552"></a>In this case, an exporter who is already registered for at least the GSP scheme of either, Norway, Switzerland or Turkey, need not lodge an application with his competent authorities to be registered for the GSP scheme of the Union.

<a id="p113553"></a>Article 89

<a id="p113554"></a>Revocation of registration
(Article 64(1) of the Code)

1. <a id="p113555"></a>Registered exporters shall immediately inform the competent authorities of the beneficiary country or the customs authorities of the Member State of changes to the information which they have provided for the purposes of their registration.
2. <a id="p113556"></a>Registered exporters who no longer meet the conditions for exporting goods under the GSP scheme, or no longer intend to export goods under the GSP scheme shall inform the competent authorities in the beneficiary country or the customs authorities in the Member State accordingly.
3. <a id="p113557"></a>The competent authorities in a beneficiary country or the customs authorities in a Member State shall revoke the registration if the registered exporter:
<a id="p113558"></a>(a) no longer exists;
<a id="p113559"></a>(b) no longer meets the conditions for exporting goods under the GSP scheme;
<a id="p113560"></a>(c) has informed the competent authority of the beneficiary country or the customs authorities of the Member State that he no longer intends to export goods under the GSP scheme;
<a id="p113561"></a>(d) intentionally or negligently draws up, or causes to be drawn up, a statement on origin which contains incorrect information and leads to wrongfully obtaining the benefit of preferential tariff treatment.
4. <a id="p113562"></a>The competent authority of a beneficiary country or the customs authorities of a Member State may revoke the registration if the registered exporter fails to keep the data concerning his registration up-to-date.
5. <a id="p113563"></a>Revocation of registrations shall take effect for the future, i.e. in respect of statements on origin made out after the date of revocation. Revocation of registration shall have no effect on the validity of statements on origin made out before the registered exporter is informed of the revocation.
6. <a id="p113564"></a>The competent authority of a beneficiary country or the customs authorities of a Member State shall inform the registered exporter about the revocation of his registration and of the date from which the revocation will take effect.
7. <a id="p113565"></a>Judicial remedy shall be available to the exporter or the re-consignor of goods in the event of revocation of his registration.
8. <a id="p113566"></a>The revocation of a registered exporter shall be cancelled in case of an incorrect revocation. The exporter or the re-consignor of goods shall be entitled to use the registered exporter number assigned to him at the time of the registration.
9. <a id="p113567"></a>Exporters or re-consignors of goods whose registration has been revoked may make a new application to become a registered exporter in accordance with Article 86 of this Regulation. Exporters or re-consignors of goods whose registration has been revoked in accordance with paragraphs 3(d) and 4 may only be registered again if they prove to the competent authorities of the beneficiary country or to the customs authorities of the Member State which had registered them that they have remedied the situation which led to the revocation of their registration.
10. <a id="p113568"></a>The data relating to a revoked registration shall be kept in the REX system by the competent authority of the beneficiary country or by the customs authorities of the Member State, which introduced them into that system, for a maximum of 10 calendar years after the calendar year in which the revocation took place. After those 10 calendar years, the competent authority of a beneficiary country or the customs authorities of the Member State shall delete the data.

<a id="p113569"></a>Article 90

<a id="p113570"></a>Automatic revocation of registrations when a country
is withdrawn from the list of beneficiary countries
(Article 64(1) of the Code)

1. <a id="p113571"></a>The Commission shall revoke all registrations of exporters registered in a beneficiary country if the beneficiary country is removed from the list of beneficiary countries in Annex II to Regulation (EU) No 978/2012 or if the tariff preferences granted to the beneficiary country have been temporarily withdrawn in accordance with Regulation (EU) No 978/2012.
2. <a id="p113572"></a>Where that country is reintroduced in that list or where the temporary withdrawal of the tariff preferences granted to the beneficiary country is terminated, the Commission shall re-activate the registrations of all exporters registered in that country provided that the registration data of the exporters are available in the system and have remained valid for at least the GSP scheme of Norway or Switzerland, or Turkey. Otherwise, exporters shall be registered again in accordance with Article 86 of this Regulation.
3. <a id="p113573"></a>In the event of revocation of the registrations of all registered exporters in a beneficiary country in accordance with the first paragraph, the data of the revoked registrations will be kept in the REX system for at least 10 calendar years after the calendar year in which the revocation took place. After that 10-year period, and when the beneficiary country has not been a beneficiary country of the GSP scheme of Norway, Switzerland, nor Turkey for more than 10 years, the Commission will delete the data of the revoked registrations from the REX system.

<a id="p113574"></a>Article 91

<a id="p113575"></a>Obligations of exporters
(Article 64(1) of the Code)

1. <a id="p113576"></a>Exporters and registered exporters shall comply with the following obligations:
<a id="p113577"></a>(a) they shall maintain appropriate commercial accounting records concerning the production and supply of goods qualifying for preferential treatment;
<a id="p113578"></a>(b) they shall keep available all evidence relating to the materials used in the manufacture;
<a id="p113579"></a>(c) they shall keep all customs documentation relating to the materials used in the manufacture;
<a id="p113580"></a>(d) they shall keep for at least 3 years from the end of the calendar year in which the statement on origin was made out, or longer if required by national law, records of:
<a id="p113581"></a>(i) the statements on origin they made out;
<a id="p113582"></a>(ii) their originating and non-originating materials, production and stock accounts.
<a id="p113583"></a>Those records and those statements on origin may be kept in an electronic format but shall allow the materials used in the manufacture of the exported products to be traced and their originating status to be confirmed.
2. <a id="p113584"></a>The obligations provided for in paragraph 1 shall also apply to suppliers who provide exporters with suppliers' declarations certifying the originating status of the goods they supply.
3. <a id="p113585"></a>The re-consignors of goods, whether registered or not, who make out replacement statements on origin shall keep the initial statements on origin they replaced for at least 3 years from the end of the calendar year in which the replacement statement on origin was made out, or longer if required by national law.

<a id="p113586"></a>Article 92

<a id="p113587"></a>General provisions on the statement on origin
(Article 64(1) of the Code)

1. <a id="p113588"></a>A statement on origin may be made out at the time of exportation to the Union or when the exportation to the Union is ensured.
<a id="p113589"></a>Where the products concerned are considered as originating in the beneficiary country of export or another beneficiary country in accordance with the second sub-paragraph of Article 55(4) of Delegated Regulation (EU) 2015/2446 or with the second sub-paragraph of Article 55(6) of that Regulation, the statement on origin shall be made out by the exporter in the beneficiary country of export.
2. <a id="p113590"></a>A statement on origin may also be made out after exportation ("retrospective statement") of the products concerned. Such a retrospective statement on origin shall be admissible if presented to the customs authorities in the Member State of lodging of the customs declaration for release for free circulation at the latest 2 years after the importation.
<a id="p113591"></a>Where the splitting of a consignment takes place in accordance with Article 43 of Delegated Regulation (EU) 2015/2446 and provided that the 2-year deadline referred to in the first sub-paragraph is respected, the statement on origin may be made out retrospectively by the exporter of the country of exportation of the products. This applies mutatis mutandis if the splitting of a consignment takes place in another beneficiary country or in Norway, Switzerland or Turkey.
3. <a id="p113592"></a>The statement on origin shall be provided by the exporter to its customer in the Union and shall contain the particulars specified in Annex 22-07 of. It shall be made out in English, French or Spanish.
<a id="p113593"></a>It may be made out on any commercial document allowing identification of the exporter concerned and the goods involved.
<a id="p113594"></a>The exporter shall not be required to sign the statement on origin.
4. <a id="p113595"></a>Paragraphs 1, 2 and 3 shall apply mutatis mutandis to the following:
<a id="p113596"></a>(a) statements on origin made out in the Union for the purpose of bilateral cumulation as referred to in Article 53 of Delegated Regulation (EU) 2015/2446;
<a id="p113597"></a>(b) statements on origin of goods exported to a beneficiary country of the GSP schemes of Norway, Switzerland or Turkey for the purpose of cumulation with materials originating in the Union.

<a id="p113598"></a>Article 93

<a id="p113599"></a>Statement on origin in the case of cumulation
(Article 64(1) of the Code)

1. <a id="p113600"></a>For the purpose of establishing the origin of materials used under bilateral or regional cumulation, the exporter of a product manufactured using materials originating in a country with which cumulation is permitted shall rely on the statement on origin provided by the supplier of those materials. In these cases, the statement on origin made out by the exporter shall, as the case may be, contain the indication "EU cumulation", "regional cumulation", "Cumul UE", "Cumul regional" or " Acumulación UE", " Acumulación regional".
2. <a id="p113601"></a>For the purpose of establishing the origin of materials used within the framework of cumulation under Article 54 of Delegated Regulation (EU) 2015/2446, the exporter of a product manufactured using materials originating in Norway, Switzerland or Turkey shall rely on the proof of origin provided by the supplier of those materials on condition that that proof has been issued in accordance with the provisions of the GSP rules of origin of Norway, Switzerland or Turkey, as the case may be. In this case, the statement on origin made out by the exporter shall contain the indication "Norway cumulation", "Switzerland cumulation", "Turkey cumulation", "Cumul Norvège ", "Cumul Suisse", "Cumul Turquie" or " Acumulación Noruega", " Acumulación Suiza", " Acumulación Turquía ".
3. <a id="p113602"></a>For the purpose of establishing the origin of materials used within the framework of extended cumulation under Article 56 of Delegated Regulation (EU) 2015/2446, the exporter of a product manufactured using materials originating in a party with which extended cumulation is permitted shall rely on the proof of origin provided by the supplier of those materials on condition that that proof has been issued in accordance with the provisions of the relevant free-trade agreement between the Union and the party concerned.
<a id="p113603"></a>In this case, the statement on origin made out by the exporter shall contain the indication "extended cumulation with country x", "cumul étendu avec le pays x" or " Acumulación ampliada con el país ".

<a id="p113604"></a>Subsection 6

<a id="p113605"></a>**PROCEDURES AT RELEASE FOR FREE CIRCULATION IN THE UNION**
**APPLICABLE WITHIN THE FRAMEWORK OF THE GSP SCHEME OF THE**
**UNION UNTIL THE DATE OF THE APPLICATION OF THE REGISTERED**
**EXPORTER SYSTEM**

<a id="p113606"></a>Article 94

<a id="p113607"></a>Submission and validity of certificates of origin Form A or
invoice declarations and belated presentation thereof
(Article 64(1) of the Code)

1. <a id="p113608"></a>Certificates of origin Form A or invoice declarations shall be submitted to the customs authorities of the Member States of importation in accordance with the procedures concerning the customs declaration.
2. <a id="p113609"></a>A proof of origin shall be valid for 10 months from the date of issue in the exporting country and shall be submitted within the said period to the customs authorities of the importing country.
<a id="p113610"></a>Proofs of origin submitted to the customs authorities of the importing country after the lapsing of their period of validity may be accepted for the purpose of applying the tariff preferences, where failure to submit these documents by the final date set is due to exceptional circumstances.
<a id="p113611"></a>In other cases of belated presentation, the customs authorities of the importing country may accept the proofs of origin where the products have been presented to customs before the said final date.

<a id="p113612"></a>Article 95

<a id="p113613"></a>Replacement of certificates of origin
Form A and invoice declarations
(Article 64(1) of the Code)

1. <a id="p113614"></a>Where originating products not yet released for free circulation are placed under the control of a customs office of a Member State, that customs office shall, on written request from the re-consignor, replace the initial certificate of origin Form A or invoice declaration by one or more certificates of origin Form A (replacement certificate) for the purposes of sending all or some of these products elsewhere within the Union or to Norway or Switzerland. The re-consignor shall indicate in his request whether a photocopy of the initial proof of origin is to be annexed to the replacement certificate.
2. <a id="p113615"></a>The replacement certificate shall be drawn up in accordance with Annex 22-19.
<a id="p113616"></a>The customs office shall verify that the replacement certificate is in conformity with the initial proof of origin.
3. <a id="p113617"></a>Where the request for a replacement certificate is made by a re-consignor acting in good faith, he shall not be responsible for the accuracy of the particulars entered on the initial proof of origin.
4. <a id="p113618"></a>The customs office which is requested to issue the replacement certificate shall note on the initial proof of origin or on an attachment thereto the weights, numbers, nature of the products forwarded and their country of destination and indicate thereon the serial numbers of the corresponding replacement certificate or certificates. It shall keep the initial proof of origin for at least 3 years.
5. <a id="p113619"></a>In the case of products which benefit from the tariff preferences under a derogation granted in accordance with Article 64(6) of the Code, the procedure laid down in this Article shall apply only when such products are intended for the Union.

<a id="p113620"></a>Article 96

<a id="p113621"></a>Importation by instalments using certificates
of origin Form A or invoice declarations
(Article 64(1) of the Code)

1. <a id="p113622"></a>Where, at the request of the importer and on the conditions laid down by the customs authorities of the importing Member State, unassembled or disassembled products within the meaning of general interpretative rule 2(a) of the Harmonised System and falling within Section XVI or XVII or heading 7308 or 9406 of the Harmonised System are imported by instalments, a single proof of origin for such products may be submitted to the customs authorities on importation of the first instalment.
2. <a id="p113623"></a>At the request of the importer and having regard to the conditions laid down by the customs authorities of the importing Member State, a single proof of origin may be submitted to the customs authorities at the importation of the first consignment when the goods:
<a id="p113624"></a>(a) are imported within the framework of frequent and continuous trade flows of a significant commercial value;
<a id="p113625"></a>(b) are the subject of the same contract of sale, the parties of this contract established in the exporting country or in the Member State(s);
<a id="p113626"></a>(c) are classified in the same code (eight digits) of the Combined Nomenclature;
<a id="p113627"></a>(d) come exclusively from the same exporter, are destined for the same importer, and are made the subject of entry formalities at the same customs office of the same Member State.
<a id="p113628"></a>This procedure shall be applicable for a period determined by the competent customs authorities.

<a id="p113629"></a>Article 97

<a id="p113630"></a>Exemptions from the obligation to provide a certificate
of origin Form A or an invoice declaration
(Article 64(1) of the Code)

1. <a id="p113631"></a>Products sent as small packages from private persons to private persons or forming part of travellers' personal luggage shall be admitted as originating products benefiting from GSP tariff preferences without requiring the presentation of a certificate of origin Form A or an invoice declaration, provided that:
<a id="p113632"></a>(a) such products:
<a id="p113633"></a>(i) are not imported by way of trade;
<a id="p113634"></a>(ii) have been declared as meeting the conditions required for benefiting from the GSP scheme;
<a id="p113635"></a>(b) there is no doubt as to the veracity of the declaration referred to in point (a)(ii).
2. <a id="p113636"></a>Imports shall not be considered as imports by way of trade if all the following conditions are met:
<a id="p113637"></a>(a) the imports are occasional;
<a id="p113638"></a>(b) the imports consist solely of products for the personal use of the recipients or travellers or their families;
<a id="p113639"></a>(c) it is evident from the nature and quantity of the products that no commercial purpose is in view.
3. <a id="p113640"></a>The total value of the products referred to in paragraph 2 shall not exceed EUR 500 in the case of small packages or EUR 1 200 in the case of products forming part of travellers' personal luggage.

<a id="p113641"></a>Article 98

<a id="p113642"></a>Discrepancies and formal errors in certificates
of origin Form A or invoice declarations
(Article 64(1) of the Code)

1. <a id="p113643"></a>The discovery of slight discrepancies between the statements made in the certificate of origin Form A or in an invoice declaration, and those made in the documents submitted to the customs office for the purpose of carrying out the formalities for importing the products shall not ipso facto render the certificate or declaration null and void if it is duly established that that document does correspond to the products submitted.
2. <a id="p113644"></a>Obvious formal errors on a certificate of origin Form A, a movement certificate EUR.1 or an invoice declaration shall not cause this document to be rejected if these errors are not such as to create doubts concerning the correctness of the statements made in that document.

<a id="p113645"></a>Subsection 7

<a id="p113646"></a>**PROCEDURES AT RELEASE FOR FREE CIRCULATION IN THE UNION**
**APPLICABLE WITHIN THE FRAMEWORK OF THE GSP SCHEME OF THE**
**UNION FROM THE DATE OF THE APPLICATION OF THE REGISTERED**
**EXPORTER SYSTEM**

<a id="p113647"></a>Article 99

<a id="p113648"></a>Validity of statement on origin
(Article 64(1) of the Code)

1. <a id="p113649"></a>A statement on origin shall be made out for each consignment.
2. <a id="p113650"></a>A statement on origin shall be valid for 12 months from the date on which it is made out.
3. <a id="p113651"></a>A single statement on origin may cover several consignments if the goods meet the following conditions:
<a id="p113652"></a>(a) they are presented unassembled or disassembled within the meaning of General Interpretative rule 2(a) of the Harmonised System;
<a id="p113653"></a>(b) they are falling within Sections XVI or XVII or headings 7308 or 9406 of the Harmonised System; and
<a id="p113654"></a>(c) they are intended to be imported by instalments.

<a id="p113655"></a>Article 100

<a id="p113656"></a>Admissibility of a statement on origin
(Article 64(1) of the Code)

<a id="p113657"></a>In order for importers to be entitled to claim benefit from the GSP scheme upon declaration of a statement on origin, the goods shall have been exported on or after the date on which the beneficiary country from which the goods are exported started the registration of exporters in accordance with Article 79 of this Regulation.
<a id="p113658"></a>When a country is admitted or readmitted as a beneficiary country in respect of products referred to in Regulation (EU) No 978/2012, goods originating in that country shall benefit from the generalised scheme of preferences on condition that they were exported from the beneficiary country on or after the date on which this beneficiary country started applying the registered exporters system referred to in Article 70(3) of this Regulation.

<a id="p113659"></a>Article 101

<a id="p113660"></a>Replacement of statements on origin
(Article 64(1) of the Code)

1. <a id="p113661"></a>Where originating products not yet released for free circulation are placed under the control of a customs office of a Member State, the re-consignor may replace the initial statement on origin by one or more replacement statements on origin (replacement statements), for the purposes of sending all or some of the products elsewhere within the customs territory of the Union or to Norway or Switzerland.
<a id="p113662"></a>The replacement statement shall be drawn up in accordance with the requirements in Annex 22-20.
<a id="p113663"></a>Replacement statements on origin may only be made out if the initial statement on origin was made out in accordance with Articles 92, 93, 99 and 100 of this Regulation and Annex 22-07.
2. <a id="p113664"></a>Re-consignors shall be registered for the purposes of making out replacement statements on origin as regards originating products to be sent elsewhere within the territory of the Union where the total value of the originating products of the initial consignment to be split exceeds EUR 6 000.
<a id="p113665"></a>However, re-consignors who are not registered may make out replacement statements on origin where the total value of the originating products of the initial consignment to be split exceeds EUR 6 000 if they attach a copy of the initial statement on origin made out in the beneficiary country.
3. <a id="p113666"></a>Only re-consignors registered in the REX system may make out replacement statements on origin as regards products to be sent to Norway or Switzerland.
4. <a id="p113667"></a>A replacement statement on origin shall be valid for 12 months from the date of making out the initial statement on origin.
5. <a id="p113668"></a>Paragraphs 1 to 4 shall also apply to statements replacing replacement statements on origin.
6. <a id="p113669"></a>Where products benefit from tariff preferences under a derogation granted in accordance with Article 64(6) of the Code, the replacement provided for in this Article may only be made if such products are intended for the Union.

<a id="p113670"></a>Article 102

<a id="p113671"></a>General principles and precautions
to be taken by the declarant
(Article 64(1) of the Code)

1. <a id="p113672"></a>Where a declarant requests preferential treatment under the GSP scheme, he shall make reference to the statement on origin in the customs declaration for release for free circulation. The reference to the statement on origin will be its date of issue with the format yyyymmdd, where yyyy is the year, mm is the month and dd is the day. Where the total value of the originating products consigned exceeds EUR 6 000, the declarant shall also indicate the number of the registered exporter.
2. <a id="p113673"></a>Where the declarant has requested application of the GSP scheme in accordance with paragraph 1, without being in possession of a statement on origin at the time of the acceptance of the customs declaration for release for free circulation, that declaration shall be considered as being simplified within the meaning of Article 166 of the Code and treated accordingly.
3. <a id="p113674"></a>Before declaring goods for release for free circulation, the declarant shall take due care to ensure that the goods comply with the rules in this Subsection, Subsections 3 to 9 of this Section and Subsections 2 and 3 of Title II Chapter 1 Section 2 of Delegated Regulation (EU) 2015/2446, in particular, by checking:
<a id="p113675"></a>(a) on the public website that the exporter is registered in the REX system, where the total value of the originating products consigned exceeds EUR 6 000; and
<a id="p113676"></a>(b) that the statement on origin is made out in accordance with Annex 22-07.

<a id="p113677"></a>Article 103

<a id="p113678"></a>Exemptions from the obligation
to provide a statement on origin
(Article 64(1) of the Code)

1. <a id="p113679"></a>The following products shall be exempted from the obligation to make out and produce a statement on origin:
<a id="p113680"></a>(a) products sent as small packages from private persons to private persons, the total value of which does not exceed EUR 500;
<a id="p113681"></a>(b) products forming part of travellers' personal luggage, the total value of which does not exceed EUR 1 200.
2. <a id="p113682"></a>The products referred to in paragraph 1 shall meet the following conditions:
<a id="p113683"></a>(a) they are not imported by way of trade;
<a id="p113684"></a>(b) they have been declared as meeting the conditions for benefiting from the GSP scheme;
<a id="p113685"></a>(c) there is no doubt as to the veracity of the declaration referred to in point (b).
3. <a id="p113686"></a>For the purposes of point (a) of paragraph 2, imports shall not be considered as imports by way of trade if all the following conditions are met:
<a id="p113687"></a>(a) the imports are occasional;
<a id="p113688"></a>(b) the imports consist solely of products for the personal use of the recipients or travellers or their families;
<a id="p113689"></a>(c) it is evident from the nature and quantity of the products that no commercial purpose is in view.

<a id="p113690"></a>Article 104

<a id="p113691"></a>Discrepancies and formal errors in statements on origin;
Belated presentation of statements on origin
(Article 64(1) of the Code)

1. <a id="p113692"></a>The discovery of slight discrepancies between the particulars included in a statement on origin and those mentioned in the documents submitted to the customs authorities for the purpose of carrying out the formalities for importing the products shall not ipso facto render the statement on origin null and void if it is duly established that the document does correspond to the products concerned.
2. <a id="p113693"></a>Obvious formal errors such as typing errors on a statement on origin shall not cause this document to be rejected if these errors are not such as to create doubts concerning the correctness of the statements made in that document.
3. <a id="p113694"></a>Statements on origin which are submitted to the customs authorities of the importing country after the period of validity mentioned in Article 99 of this Regulation may be accepted for the purpose of applying the tariff preferences, where failure to submit these documents by the final date set is due to exceptional circumstances. In other cases of belated presentation, the customs authorities of the importing country may accept the statements on origin where the products have been presented to customs before the said final date.

<a id="p113695"></a>Article 105

<a id="p113696"></a>Importation by instalments using statements on origin
(Article 64(1) of the Code)

1. <a id="p113697"></a>The procedure referred to in Article 99(3) of this Regulation shall apply for a period determined by the customs authorities of the Member States.
2. <a id="p113698"></a>The customs authorities of the Member States of importation supervising the successive releases for free circulation shall verify that the successive consignments are part of the unassembled or disassembled products for which the statement on origin has been made out.

<a id="p113699"></a>Article 106

<a id="p113700"></a>Suspension of the application of the preference
(Article 64(1) of the Code)

1. <a id="p113701"></a>The customs authorities may, where they have doubts with regard to the originating status of the products request the declarant to produce, within a reasonable time period which they shall specify, any available evidence for the purpose of verifying the accuracy of the indication on origin of the declaration or the compliance with the conditions under Article 43 of Delegated Regulation (EU) 2015/2446.
2. <a id="p113702"></a>The customs authorities may suspend the application of the preferential tariff measure for the duration of the verification procedure laid down in Article 109 of this Regulation where:
<a id="p113703"></a>(a) the information provided by the declarant is not sufficient to confirm the originating status of the products or the compliance with the conditions laid down in Article 42 of Delegated Regulation (EU) 2015/2446 or Article 43 of that Regulation;
<a id="p113704"></a>(b) the declarant does not reply within the time period allowed for provision of the information referred to in paragraph 1.
3. <a id="p113705"></a>While awaiting either the information requested from the declarant, referred to in paragraph 1, or the results of the verification procedure, referred to in paragraph 2, release of the products shall be offered to the importer subject to any precautionary measures judged necessary.

<a id="p113706"></a>Article 107

<a id="p113707"></a>Refusal to grant tariff preference
(Article 64(1) of the Code)

1. <a id="p113708"></a>The customs authorities of the Member State of importation shall refuse to grant tariff preferences, without being obliged to request any additional evidence or send a request for verification to the beneficiary country where:
<a id="p113709"></a>(a) the goods are not the same as those mentioned in the statement on origin;
<a id="p113710"></a>(b) the declarant fails to submit a statement on origin for the products concerned, where such a statement is required;
<a id="p113711"></a>(c) without prejudice to Article 78(1)(b) and to Article 79(3) of this Regulation, the statement on origin in possession of the declarant has not been made out by an exporter registered in the beneficiary country;
<a id="p113712"></a>(d) the statement on origin is not made out in accordance with Annex 22-07;
<a id="p113713"></a>(e) the conditions of Article 43 of Delegated Regulation (EU) 2015/2446 are not met.
2. <a id="p113714"></a>The customs authorities of the Member State of importation shall refuse to grant tariff preferences, following a request for verification within the meaning of Article 109 addressed to the competent authorities of the beneficiary country, where the customs authorities of the Member State of importation:
<a id="p113715"></a>(a) have received a reply according to which the exporter was not entitled to make out the statement on origin;
<a id="p113716"></a>(b) have received a reply according to which the products concerned are not originating in a beneficiary country or the conditions of Article 42 of Delegated Regulation (EU) 2015/2446 were not met;
<a id="p113717"></a>(c) had reasonable doubt as to the validity of the statement on origin or the accuracy of the information provided by the declarant regarding the true origin of the products in question when they made the request for verification, and either of the following conditions are met:
<a id="p113718"></a>(i) they have received no reply within the time period permitted in accordance with Article 109 of this Regulation; or
<a id="p113719"></a>(ii) they have received a reply not providing adequate answers to the questions raised in the request.

<a id="p113720"></a>Subsection 8

<a id="p113721"></a>**CONTROL OF ORIGIN WITHIN THE FRAMEWORK OF THE GSP**
**SCHEME OF THE UNION**

<a id="p113722"></a>Article 108

<a id="p113723"></a>Obligations of the competent authorities relating to the
control of origin after the date of application of the
registered exporter system
(Article 64(1) of the Code)

1. <a id="p113724"></a>For the purpose of ensuring compliance with the rules concerning the originating status of products, the competent authorities of the beneficiary country shall carry out:
<a id="p113725"></a>(a) verifications of the originating status of products at the request of the customs authorities of the Member States;
<a id="p113726"></a>(b) regular controls on exporters on their own initiative.
<a id="p113727"></a>The first sub-paragraph shall apply mutatis mutandis to requests sent to the authorities of Norway and Switzerland for the verification of replacement statements on origin made out on their territory, with a view to requesting these authorities to further liaise with the competent authorities in the beneficiary country.
<a id="p113728"></a>Extended cumulation shall only be permitted under Article 56 of Delegated Regulation (EU) 2015/2446, if a country with which the Union has a free-trade agreement in force has agreed to provide the beneficiary country with its support in matters of administrative cooperation in the same way as it would provide such support to the customs authorities of the Member States in accordance with the relevant provisions of the free-trade agreement concerned.
2. <a id="p113729"></a>The controls referred to in point (b) of paragraph 1 shall ensure the continued compliance of exporters with their obligations. They shall be carried out at intervals determined on the basis of appropriate risk analysis criteria. For that purpose, the competent authorities of the beneficiary countries shall require exporters to provide copies or a list of the statements on origin they have made out.
3. <a id="p113730"></a>The competent authorities of the beneficiary countries shall have the right to call for any evidence and to carry out any inspection of the exporter's accounts and, where appropriate, those of producers supplying him, including at the premises, or to carry out any other check considered appropriate.

<a id="p113731"></a>Article 109

<a id="p113732"></a>Subsequent verification of statements on origin
and replacement statements on origin
(Article 64(1) of the Code)

1. <a id="p113733"></a>Subsequent verifications of statements on origin or replacement statements on origin shall be carried out at random or whenever the customs authorities of the Member States have reasonable doubts as to their authenticity, the originating status of the products concerned or the fulfilment of other requirements of this Subsection, Subsections 3 to 9 of this Section and Subsections 2 and 3 of Title II Chapter 1 Section 2 of Delegated Regulation (EU) 2015/2446.
<a id="p113734"></a>Where the customs authorities of a Member State request the cooperation of the competent authorities of a beneficiary country to carry out a verification of the validity of statements on origin, the originating status of products, or of both, it shall, where appropriate, indicate on its request the reasons why it has reasonable doubts on the validity of the statement on origin or the originating status of the products.
<a id="p113735"></a>A copy of the statement on origin or the replacement statement on origin and any additional information or documents suggesting that the information given on that statement or that replacement statement is incorrect may be forwarded in support of the request for verification.
<a id="p113736"></a>The requesting Member State shall set a 6-month initial deadline to communicate the results of the verification, starting from the date of the verification request, with the exception of requests sent to Norway or Switzerland for the purpose of verifying replacement statements on origin made out in their territories on the basis of a statement on origin made out in a beneficiary country, for which this deadline shall be extended to 8 months.
2. <a id="p113737"></a>If in cases of reasonable doubt there is no reply within the period specified in paragraph 1 or if the reply does not contain sufficient information to determine the real origin of the products, a second communication shall be sent to the competent authorities. This communication shall set a further deadline of not more than 6 months. If after the second communication the results of the verification are not communicated to the requesting authorities within 6 months from the date on which the second communication was sent, or if this result do not allow the authenticity of the document in question or the real origin of the products to be determined, the requesting authorities shall refuse entitlement to the tariff preferences.
3. <a id="p113738"></a>Where the verification provided for in paragraph 1 or any other available information appears to indicate that the rules of origin are being contravened, the exporting beneficiary country shall on its own initiative or at the request of the customs authorities of the Member States or the Commission carry out appropriate inquiries or arrange for such inquiries to be carried out with due urgency to identify and prevent such contraventions. For this purpose, the Commission or the customs authorities of the Member States may participate in those inquiries.

<a id="p113739"></a>Article 110

<a id="p113740"></a>Subsequent verification of certificates of origin
Form A and invoice declarations
(Article 64(1) of the Code)

1. <a id="p113741"></a>Subsequent verifications of certificates of origin Form A and invoice declarations shall be carried out at random or whenever the customs authorities of the Member States have reasonable doubts as to the authenticity of such documents, the originating status of the products concerned or the fulfilment of the other requirements of this Subsection, Subsections 3 to 9 of this Section and Subsections 2 and 3 of Title II Chapter 1 Section 2 of Delegated Regulation (EU) 2015/2446.
2. <a id="p113742"></a>When they make a request for subsequent verification, the customs authorities of the Member States shall return the certificate of origin Form A and the invoice, if it has been submitted, the invoice declaration, or a copy of these documents, to the competent governmental authorities in the exporting beneficiary country giving, where appropriate, the reasons for the enquiry. Any documents and information obtained suggesting that the information given on the proof of origin is incorrect shall be forwarded in support of the request for verification.
<a id="p113743"></a>If the customs authorities of the Member States decide to suspend the granting of the tariff preferences while awaiting the results of the verification, release of the products shall be offered to the importer subject to any precautionary measures judged necessary.
3. <a id="p113744"></a>When a request for subsequent verification has been made, such verification shall be carried out and its results communicated to the customs authorities of the Member States within a maximum of 6 months or, in the case of requests sent to Norway or Switzerland for the purpose of verifying replacement proofs of origin made out in their territories on the basis of a certificate of origin Form A or an invoice declaration made out in a beneficiary country, within a maximum of 8 months from the date on which the request was sent. The results shall be such as to establish whether the proof of origin in question applies to the products actually exported and whether these products can be considered as products originating in the beneficiary country.
4. <a id="p113745"></a>In the case of certificates of origin Form A issued following bilateral cumulation, the reply shall include a copy (copies) of the movement certificate(s) EUR.1 or, where necessary, of the corresponding invoice declaration(s).
5. <a id="p113746"></a>If, in cases of reasonable doubt, there is no reply within the 6 months specified in paragraph 3 or if the reply does not contain sufficient information to determine the authenticity of the document in question or the real origin of the products, a second communication shall be sent to the competent authorities. If after the second communication the results of the verification are not communicated to the requesting authorities within 4 months from the date on which the second communication was sent, or if these results do not allow the authenticity of the document in question or the real origin of the products to be determined, the requesting authorities shall, except in exceptional circumstances, refuse entitlement to the tariff preferences.
6. <a id="p113747"></a>Where the verification procedure or any other available information appears to indicate that the rules of origin are being contravened, the exporting beneficiary country shall, on its own initiative or at the request of the customs authorities of the Member States, carry out appropriate inquiries or arrange for such inquiries to be carried out with due urgency to identify and prevent such contraventions. For this purpose, the Commission or the customs authorities of the Member States may participate in the inquiries.
7. <a id="p113748"></a>For the purposes of the subsequent verification of certificates of origin Form A, the exporters shall keep all appropriate documents proving the originating status of the products concerned and the competent governmental authorities of the exporting beneficiary country shall keep copies of the certificates, as well as any export documents referring to them. These documents shall be kept for at least 3 years from the end of the year in which the certificate of origin Form A was issued.

<a id="p113749"></a>Article 111

<a id="p113750"></a>Subsequent verification of proofs of origin relating to
products having acquired origin through cumulation
(Article 64(1) of the Code)

<a id="p113751"></a>Articles 73 and 110 of this Regulation shall also apply between the countries of the same regional group for the purposes of provision of information to the Commission or to the customs authorities of the Member States and of the subsequent verification of certificates of origin Form A or invoice declarations issued in accordance with the rules on regional cumulation of origin.

<a id="p113752"></a>Subsection 9

<a id="p113753"></a>**OTHER PROVISIONS APPLICABLE WITHIN THE FRAMEWORK OF THE GSP**
**SCHEME OF THE UNION**

<a id="p113754"></a>Article 112

<a id="p113755"></a>Ceuta and Melilla
(Article 64(1) of the Code)

1. <a id="p113756"></a>Articles 41 to 58 of Delegated Regulation (EU) 2015/2446 shall apply in determining whether products may be regarded as originating in a beneficiary country when exported to Ceuta or Melilla or as originating in Ceuta and Melilla when exported to a beneficiary country for the purposes of bilateral cumulation.
2. <a id="p113757"></a>Articles 74 to 79 and Articles 84 to 93 of this Regulation shall apply to products exported from a beneficiary country to Ceuta or Melilla and to products exported from Ceuta and Melilla to a beneficiary country for the purposes of bilateral cumulation.
3. <a id="p113758"></a>For the purposes mentioned in paragraphs 1 and 2, Ceuta and Melilla shall be regarded as a single territory.

<a id="p113759"></a>Subsection 10

<a id="p113760"></a>**PROOFS OF ORIGIN APPLICABLE WITHIN THE FRAMEWORK OF THE**
**RULES OF ORIGIN FOR THE PURPOSES OF PREFERENTIAL TARIFF**
**MEASURES ADOPTED UNILATERALLY BY THE UNION FOR CERTAIN**
**COUNTRIES OR TERRITORIES**

<a id="p113761"></a>Article 113

<a id="p113762"></a>General requirements
(Article 64(1) of the Code)

<a id="p113763"></a>Products originating in one of the beneficiary countries or territories shall benefit from the tariff preferences referred to in Article 59 of Delegated Regulation (EU) 2015/2446, on submission of either of the following:
<a id="p113764"></a>(a) a movement certificate EUR.1, issued using the form set out in Annex 22-10; or
<a id="p113765"></a>(b) in the cases specified in Article 119(1), a declaration, the text of which appears in Annex 22-13, given by the exporter on an invoice, a delivery note or any other commercial document which describes the products concerned in sufficient detail to enable them to be identified (hereinafter referred to as the "invoice declaration").
<a id="p113766"></a>Box 7 of movement certificates EUR.1 or invoice declarations shall contain the indication "Autonomous trade measures" or "Mesures commerciales autonomes".

<a id="p113767"></a>Article 114

<a id="p113768"></a>Procedure for the issue of a movement certificate EUR.1
(Article 64(1) of the Code)

1. <a id="p113769"></a>Originating products within the meaning of Title II, Chapter 1, Section 2, Subsection 4 of Delegated Regulation (EU) 2015/2446 shall be eligible, on importation into the Union, to benefit from the tariff preferences referred to in Article 59 of Delegated Regulation (EU) 2015/2446, provided that they have been transported direct to the Union within the meaning of Article 69 of Delegated Regulation (EU) 2015/2446, on submission of an EUR.1 movement certificate issued by the customs or other competent governmental authorities of a beneficiary country or territory, on condition that the beneficiary country or territory:
<a id="p113770"></a>(a) has communicated to the Commission the information required by Article 124 of this Regulation; and
<a id="p113771"></a>(b) assists the Union by allowing the customs authorities of Member States to verify the authenticity of the document or the accuracy of the information regarding the true origin of the products in question.
2. <a id="p113772"></a>A movement certificate EUR.1 may be issued only where it can serve as the documentary evidence required for the purposes of the tariff preferences referred to in Article 59 of Delegated Regulation (EU) 2015/2446.
3. <a id="p113773"></a>A movement certificate EUR.1 shall be issued only on written application from the exporter or his representative. Such application shall be lodged using the form set out in Annex 22-10 and shall be completed in accordance with the provisions of this Article and Articles 113, 115, 116, 117, 118, 121 and 123 of this Regulation.
<a id="p113774"></a>Applications for movement certificates EUR.1 shall be kept by the competent authorities of the exporting beneficiary country or territory or Member State for at least 3 years from the end of the year in which the movement certificate was issued.
4. <a id="p113775"></a>The exporter or his representative shall submit with his application any appropriate supporting documents proving that the products to be exported qualify for the issue of a movement certificate EUR.1.
<a id="p113776"></a>The exporter shall undertake to submit, at the request of the competent authorities, any supplementary evidence they may require for the purpose of establishing the correctness of the originating status of the products eligible for preferential treatment and shall undertake to agree to any inspection of their accounts and to any check by the said authorities on the circumstances in which the products were obtained.
5. <a id="p113777"></a>The movement certificate EUR.1 shall be issued by the competent governmental authorities of the beneficiary country or territory or by the customs authorities of the exporting Member State, if the products to be exported can be considered as originating products within the meaning of Title II, Chapter 1, Section 2, Subsection 4 of Delegated Regulation (EU) 2015/2446.
6. <a id="p113778"></a>Since the movement certificate EUR.1 constitutes the documentary evidence for the application of the preferential arrangements set out in Article 59 of Delegated Regulation (EU) 2015/2446, it shall be the responsibility of the competent governmental authorities of the beneficiary country or territory or of the customs authorities of the exporting Member State to take any steps necessary to verify the origin of the products and to check the other statements on the certificate.
7. <a id="p113779"></a>For the purpose of verifying whether the conditions set out in paragraph 5 have been met, the competent governmental authorities of the beneficiary country or the customs authorities of the exporting Member State shall have the right to call for any documentary evidence or to carry out any check which they consider appropriate.
8. <a id="p113780"></a>It shall be the responsibility of the competent governmental authorities of the beneficiary country or territory or of the customs authorities of the exporting Member State to ensure that the forms referred to in paragraph 1 are duly completed.
9. <a id="p113781"></a>The date of issue of the movement certificate EUR.1 shall be indicated in that part of the certificate reserved for the customs authorities.
10. <a id="p113782"></a>A movement certificate EUR.1 shall be issued by the competent authorities of the beneficiary country or territory or by the customs authorities of the exporting Member State when the products to which it relates are exported. It shall be made available to the exporter as soon as the export has taken place or is ensured.

<a id="p113783"></a>Article 115

<a id="p113784"></a>Importation by instalments
(Article 64(1) of the Code)

<a id="p113785"></a>Where, at the request of the importer and on the conditions laid down by the customs authorities of the importing country, unassembled or disassembled products within the meaning of general interpretative rule 2(a) of the Harmonised System and falling within Sections XVI or XVII or headings 7308 or 9406 of the Harmonised System are imported by instalments, a single proof of origin for such products shall be submitted to the customs authorities on importation of the first instalment.

<a id="p113786"></a>Article 116

<a id="p113787"></a>Submission of proof of origin (Article 64(1) of the Code)

<a id="p113788"></a>Proofs of origin shall be submitted to the customs authorities of the Member State of importation in accordance with the procedures laid down in Article 163 of the Code. The said authorities may require a translation of a proof of origin and may also require the import declaration to be accompanied by a statement from the importer to the effect that the products meet the conditions required for the application of this Subsection.

<a id="p113789"></a>Article 117

<a id="p113790"></a>Movement certificates EUR.1 issued retrospectively
(Article 64(1) of the Code)

1. <a id="p113791"></a>By way of derogation from Article 114(10), a movement certificate EUR.1 may exceptionally be issued after exportation of the products to which it relates if either of the following conditions are fulfilled:
<a id="p113792"></a>(a) it was not issued at the time of exportation because of errors or involuntary omissions or special circumstances; or
<a id="p113793"></a>(b) it is demonstrated to the satisfaction of the competent authorities that a movement certificate EUR.1 was issued but was not accepted at importation for technical reasons.
2. <a id="p113794"></a>The competent authorities may issue a movement certificate EUR.1 retrospectively only after verifying that the information supplied in the exporter's application agrees with that in the corresponding export file and that a movement certificate EUR.1 satisfying the provisions of this Subsection was not issued when the products in question were exported.
3. <a id="p113795"></a>Movement certificates EUR.1 issued retrospectively shall be endorsed with one of the following phrases:
<a id="p113796"></a>**BG: "ИЗДАДЕН ВПОСЛЕДСТВИЕ"**
<a id="p113797"></a>**ES: "EXPEDIDO A POSTERIORI"**
<a id="p113798"></a>**HR: "IZDANO NAKNADNO"**
<a id="p113799"></a>**CS: "VYSTAVENO DODATEÈNÌ "**
<a id="p113800"></a>**DA: "UDSTEDT EFTERFØLGENDE "**
<a id="p113801"></a>**DE: " NACHTRÄGLICH AUSGESTELLT"**
<a id="p113802"></a>**ET: " VÄLJA ANTUD TAGASIULATUVALT"**
<a id="p113803"></a>EL: " $EK\Delta O\Theta EN$ EK $T\Omega N$ $Y\Sigma TEP\Omega N$ "
<a id="p113804"></a>**EN: "ISSUED RETROSPECTIVELY"**
<a id="p113805"></a>FR: " DÉLIVRÉ $\text{А}$ POSTERIORI"
<a id="p113806"></a>**IT: "RILASCIATO A POSTERIORI"**
<a id="p113807"></a>**LV: "IZSNIEGTS RETROSPEKTÎVI "**
<a id="p113808"></a>**LT: "RETROSPEKTYVUSIS IŠDAVIMAS "**
<a id="p113809"></a>**HU: "KIADVA VISSZAMENÕLEGES HATÁLLYAL "**
<a id="p113810"></a>MT: " ![формула](https://i.bukva.ai/sakP7uTQ/img_34.png) RETROSPETTIVAMENT"
<a id="p113811"></a>**NL: "AFGEGEVEN A POSTERIORI"**
<a id="p113812"></a>**PL: "WYSTAWIONE RETROSPEKTYWNIE"**
<a id="p113813"></a>**PT: "EMITIDO A POSTERIORI"**
<a id="p113814"></a>**RO: "ELIBERAT ULTERIOR"**
<a id="p113815"></a>**SL: "IZDANO NAKNADNO"**
<a id="p113816"></a>**SK: " VYDANÉ DODATOÈNE "**
<a id="p113817"></a>**FI: "ANNETTU JÄLKIKÄTEEN "**
<a id="p113818"></a>**SV: " UTFÄRDAT I EFTERHAND"**
4. <a id="p113819"></a>The endorsement referred to in paragraph 3 shall be inserted in the "Remarks" box of the movement certificate EUR.1.

<a id="p113820"></a>Article 118

<a id="p113821"></a>Issue of a duplicate movement certificate EUR.1
(Article 64(1) of the Code)

1. <a id="p113822"></a>In the event of theft, loss or destruction of a movement certificate EUR.1, the exporter may apply to the competent authorities which issued it, for a duplicate to be made out on the basis of the export documents in their possession.
2. <a id="p113823"></a>The duplicate issued in this way shall be endorsed with one of the following words:
<a id="p113824"></a>**BG: "ДУБЛИКАТ"**
<a id="p113825"></a>**ES: "DUPLICADO"**
<a id="p113826"></a>**HR: "DUPLIKAT"**
<a id="p113827"></a>**CS: " DUPLIKÁT "**
<a id="p113828"></a>**DA: " DUPLIKÁT "**
<a id="p113829"></a>**DE: "DUPLIKAT"**
<a id="p113830"></a>**ET: "DUPLIKAAT"**
<a id="p113831"></a>**EL: "ANTIГРАФО"**
<a id="p113832"></a>**EN: "DUPLICATE"**
<a id="p113833"></a>**FR: "DUPLICATA"**
<a id="p113834"></a>**IT: "DUPLICATO"**
<a id="p113835"></a>**LV: " DUBLIKÂTS "**
<a id="p113836"></a>**LT: "DUBLIKATAS"**
<a id="p113837"></a>**HU: " MÁSODLAT "**
<a id="p113838"></a>**MT: "DUPLIKAT"**
<a id="p113839"></a>**NL: "DUPLICAAT"**
<a id="p113840"></a>**PL: "DUPLIKAT"**
<a id="p113841"></a>**PT: "SEGUNDA VIA"**
<a id="p113842"></a>**RO: "DUPLICAT"**
<a id="p113843"></a>**SL: "DVOJNIK"**
<a id="p113844"></a>**SK: " DUPLIKÁT "**
<a id="p113845"></a>**FI: "KAKSOISKAPPALE"**
<a id="p113846"></a>**SV: "DUPLIKAT"**
3. <a id="p113847"></a>The endorsement referred to in paragraph 2 shall be inserted in the "Remarks" box of the movement certificate EUR.1.
4. <a id="p113848"></a>The duplicate, which shall bear the date of issue of the original movement certificate EUR.1, shall take effect as from that date.

<a id="p113849"></a>Article 119

<a id="p113850"></a>Conditions for making out an invoice declaration
(Article 64(1) of the Code)

1. <a id="p113851"></a>The invoice declaration may be made out by either of the following:
<a id="p113852"></a>(a) an approved Union exporter within the meaning of Article 120 of this Regulation;
<a id="p113853"></a>(b) any exporter for any consignment consisting of one or more packages containing originating products whose total value does not exceed EUR 6 000, and on condition that the assistance referred to in Article 114(1) of this Regulation shall apply to this procedure.
2. <a id="p113854"></a>An invoice declaration may be made out if the products concerned can be considered as originating in the Union or in a beneficiary country or territory and fulfil the other requirements of Title II, Chapter 1, Section 2, Subsections 4 and 5 of Delegated Regulation (EU) 2015/2446.
3. <a id="p113855"></a>The exporter making out an invoice declaration shall be prepared to submit at any time, at the request of the customs or other competent governmental authorities of the exporting country or territory, all appropriate documents proving the originating status of the products concerned as well as the fulfilment of the other requirements of Title II, Chapter 1, Section 2, Subsections 4 and 5 of Delegated Regulation (EU) 2015/2446.
4. <a id="p113856"></a>An invoice declaration shall be made out by the exporter by typing, stamping or printing on the invoice, the delivery note or any other commercial document, the declaration, the text of which appears in Annex 22-13, using one of the linguistic versions set out in that Annex and in accordance with the provisions of the domestic law of the exporting country. If the declaration is handwritten, it shall be written in ink, in printed characters.
5. <a id="p113857"></a>Invoice declarations shall bear the original handwritten signature of the exporter. However, an approved exporter within the meaning of Article 120 of this Regulation shall not be required to sign such declarations provided that he gives the customs authorities a written undertaking that he accepts full responsibility for any invoice declaration which identifies him as if it had been signed with his handwritten signature.
6. <a id="p113858"></a>In the cases referred to in paragraph 1(b), the use of an invoice declaration shall be subject to the following special conditions:
<a id="p113859"></a>(a) an invoice declaration shall be made out for each consignment;
<a id="p113860"></a>(b) if the goods contained in the consignment have already been subject to verification in the exporting country by reference to the definition of "originating products", the exporter may refer to this check in the invoice declaration.
<a id="p113861"></a>The provisions of the first subparagraph shall not exempt exporters from complying with any other formalities required under customs or postal regulations.

<a id="p113862"></a>Article 120

<a id="p113863"></a>Approved exporter
(Article 64(1) of the Code)

1. <a id="p113864"></a>The customs authorities in the Union may authorise any exporter established in the customs territory of the Union, hereinafter referred to as an "approved exporter", who makes frequent shipments of products originating in the Union within the meaning of Article 59(2) of Delegated Regulation (EU) 2015/2446, and who offers, to the satisfaction of the customs authorities, all guarantees necessary to verify the originating status of the products as well as the fulfilment of the other requirements of Title II, Chapter 1, Section 2, Subsections 4 and 5 of Delegated Regulation (EU) 2015/2446, to make out invoice declarations, irrespective of the value of the products concerned.
2. <a id="p113865"></a>The customs authorities may grant the status of approved exporter subject to any conditions which they consider appropriate.
3. <a id="p113866"></a>The customs authorities shall assign the approved exporter a customs authorisation number which shall appear on the invoice declaration.
4. <a id="p113867"></a>The customs authorities shall monitor the use of the authorisation by the approved exporter.
5. <a id="p113868"></a>The customs authorities may withdraw the authorisation at any time. They shall do so where the approved exporter no longer offers the guarantees referred to in paragraph 1, does not fulfil the conditions referred to in paragraph 2, or otherwise makes improper use of the authorisation.

<a id="p113869"></a>Article 121

<a id="p113870"></a>Validity of proof of origin
(Article 64(1) of the Code)

1. <a id="p113871"></a>A proof of origin shall be valid for 4 months from the date of issue in the exporting country, and shall be submitted within the said period to the customs authorities of the importing country.
2. <a id="p113872"></a>Proofs of origin which are submitted to the customs authorities of the importing country after the final date for presentation specified in paragraph 1 may be accepted for the purpose of applying the tariff preferences referred to in Article 59 of Delegated Regulation (EU) 2015/2446, where the failure to submit these documents by the final date set is due to exceptional circumstances.
3. <a id="p113873"></a>In other cases of belated presentation, the customs authorities of the importing country may accept the proofs of origin where the products have been submitted before the said final date.
4. <a id="p113874"></a>At the request of the importer and having regard to the conditions laid down by the customs authorities of the importing Member State, a single proof of origin may be submitted to the customs authorities at the importation of the first consignment when the goods fulfil the following conditions:
<a id="p113875"></a>(a) they are imported within the framework of frequent and continuous trade flows of a significant commercial value;
<a id="p113876"></a>(b) they are the subject of the same contract of sale, the parties of this contract established in the exporting country or in the Union;
<a id="p113877"></a>(c) they are classified in the same code (eight digits) of the Combined Nomenclature;
<a id="p113878"></a>(d) they come exclusively from the same exporter, are destined for the same importer, and are made the subject of entry formalities at the same customs office in the Union.
<a id="p113879"></a>This procedure shall be applicable for the quantities and a period determined by the competent customs authorities. This period cannot, in any circumstances, exceed 3 months.
5. <a id="p113880"></a>The procedure described in the preceding paragraph shall also apply where a single proof of origin is submitted to the customs authorities for importations by instalments in accordance with Article 115 of this Regulation. However, in this case, the competent customs authorities may grant a period of application exceeding 3 months.

<a id="p113881"></a>Article 122

<a id="p113882"></a>Exemptions from proof of origin
(Article 64(1) of the Code)

1. <a id="p113883"></a>Products sent as small packages from private person to private persons or forming part of travellers' personal luggage shall be admitted as originating products benefiting from the tariff preferences referred to in Article 59 of Delegated Regulation (EU) 2015/2446 without requiring the submission of a movement certificate EUR.1 or an invoice declaration, provided that such products are not imported by way of trade and have been declared as meeting the conditions required for the application of Title II, Chapter 1, Section 2, Subsections 4 and 5 of Delegated Regulation (EU) 2015/2446, and where there is no doubt as to the veracity of such a declaration.
2. <a id="p113884"></a>Imports which are occasional and consist solely of products for the personal use of the recipients or travellers or their families shall not be considered as imports by way of trade if it is evident from the nature and quantity of the products that no commercial purpose is in view.
<a id="p113885"></a>Furthermore, the total value of the products shall not exceed EUR 500 in the case of small packages or EUR 1 200 in the case of products forming part of traveller's personal luggage.

<a id="p113886"></a>Article 123

<a id="p113887"></a>Discrepancies and formal errors
(Article 64(1) of the Code)

<a id="p113888"></a>The discovery of slight discrepancies between the statements made in the proof of origin and those made in the documents submitted to the customs office for the purpose of carrying out the formalities for importing the products shall not ipso facto render the proof of origin null and void if it is duly established that the document does correspond to the products submitted.
<a id="p113889"></a>Obvious formal errors such as typing errors on a proof of origin should not cause this document to be rejected if these errors are not such as to create doubts concerning the correctness of the statements made in that document.

<a id="p113890"></a>Subsection 11

<a id="p113891"></a>**METHODS OF ADMINISTRATIVE COOPERATION FOR THE PURPOSE OF**
**ORIGIN VERIFICATION WITHIN THE FRAMEWORK OF PREFERENTIAL**
**TARIFF MEASURES ADOPTED UNILATERALLY BY THE UNION FOR**
**CERTAIN COUNTRIES OR TERRITORIES**

<a id="p113892"></a>Article 124

<a id="p113893"></a>Administrative cooperation
(Article 64(1) of the Code)

1. <a id="p113894"></a>The beneficiary countries or territories shall inform the Commission of the names and addresses of the governmental authorities situated in their territory which are empowered to issue movement certificates EUR.1, together with specimen impressions of the stamps used by those authorities, and the names and addresses of the relevant governmental authorities responsible for the control of the movement certificates EUR.1 and the invoice declarations. The stamps shall be valid as from the date of receipt by the Commission of the specimens. The Commission shall forward this information to the customs authorities of the Member States. When these communications are made within the framework of an amendment of previous communications, the Commission shall indicate the date of entry into use of those new stamps according to the instructions given by the competent governmental authorities of the beneficiary countries or territories. This information is for official use; however, when goods are to be released for free circulation, the customs authorities in question may allow the importer to consult the specimen impressions of stamps mentioned in this paragraph.
2. <a id="p113895"></a>The Commission shall send, to the beneficiary countries or territories, the specimen impressions of the stamps used by the customs authorities of the Member States for the issue of movement certificates EUR.1.

<a id="p113896"></a>Article 125

<a id="p113897"></a>Verification of proofs of origin
(Article 64(1) of the Code)

1. <a id="p113898"></a>Subsequent verifications of movement certificates EUR.1 and of invoice declarations shall be carried out at random or whenever the customs authorities in the importing Member State or the competent governmental authorities of the beneficiary countries or territories have reasonable doubts as to the authenticity of such documents, the originating status of the products within the meaning of Title II, Chapter 1, Section 2, Subsections 4 of Delegated Regulation (EU) 2015/2446 concerned or the fulfilment of the other requirements of Title II, Chapter 1, Section 2, Subsection 5 of Delegated Regulation (EU) 2015/2446.
2. <a id="p113899"></a>For the purposes of implementing the provisions of paragraph 1, the competent authorities in the importing Member State or beneficiary country or territory shall return the EUR.1 movement certificate and the invoice, if it has been submitted, the invoice declaration, or a copy of these documents, to the competent authorities in the exporting beneficiary country or territory or Member State, giving, where appropriate, the reasons for the enquiry. Any documents and information obtained suggesting that the information given on the proof of origin is incorrect shall be forwarded in support of the request for verification.
<a id="p113900"></a>If the customs authorities in the importing Member State decide to suspend the granting of the tariff preferences referred to in Article 59 of Delegated Regulation (EU) 2015/2446 while awaiting the results of the verification, release of the products shall be offered to the importer subject to any precautionary measures judged necessary.
3. <a id="p113901"></a>When an application for subsequent verification has been made in accordance with paragraph 1, such verification shall be carried out and its results communicated to the customs authorities of the importing Member States or to the competent governmental authorities of the importing beneficiary country or territory within a maximum of 6 months. The results shall be such as to establish whether the proof of origin in question applies to the products actually exported and whether these products can be considered as originating in the beneficiary country or territory or in the Union.
4. <a id="p113902"></a>If in cases of reasonable doubt there is no reply within the 6 months specified in paragraph 3 or if the reply does not contain sufficient information to determine the authenticity of the document in question or the real origin of the products, a second communication shall be sent to the competent authorities. If after the second communication the results of the verification are not communicated to the requesting authorities within 4 months, or if these results do not allow the authenticity of the document in question or the real origin of the products to be determined, the requesting authorities shall, except in exceptional circumstances, refuse entitlement to the tariff preferences.
5. <a id="p113903"></a>Where the verification procedure or any other available information appears to indicate that the provisions of Title II, Chapter 1, Section 2, Subsections 4 and 5 of Delegated Regulation (EU) 2015/2446 are being contravened, the exporting beneficiary country or territory shall, on its own initiative or at the request of the Union, carry out appropriate inquiries or arrange for such inquiries to be carried out with due urgency to identify and prevent such contraventions. For this purpose, the Union may participate in the inquiries.
6. <a id="p113904"></a>For the purposes of the subsequent verification of movement certificates EUR.1, copies of the certificates as well as any export documents referring to them shall be kept by the competent governmental authorities of the exporting beneficiary country or territory or by the customs authorities of the exporting Member State for at least 3 years from the end of the year in which the movement certificates were issued.

<a id="p113905"></a>Subsection 12

<a id="p113906"></a>**OTHER PROVISIONS APPLICABLE WITHIN THE FRAMEWORK OF THE**
**RULES OF ORIGIN FOR THE PURPOSES OF PREFERENTIAL TARIFF**
**MEASURES ADOPTED UNILATERALLY BY THE UNION FOR CERTAIN**
**COUNTRIES OR TERRITORIES**

<a id="p113907"></a>Article 126

<a id="p113908"></a>Ceuta and Melilla
(Article 64(1) of the Code)

1. <a id="p113909"></a>Subsections 10 and 11 shall apply mutatis mutandis in determining whether products may be regarded as originating in the exporting beneficiary countries or territories benefiting from the preferences when imported into Ceuta and Melilla or as originating in Ceuta and Melilla.
2. <a id="p113910"></a>Ceuta and Melilla shall be regarded as a single territory.
3. <a id="p113911"></a>The provisions of Subsections 10 and 11 concerning the issue, use and subsequent verification of movement certificates EUR.1 shall apply mutatis mutandis to products originating in Ceuta and Melilla.
4. <a id="p113912"></a>The Spanish customs authorities shall be responsible for the application of this Subsection in Ceuta and Melilla.

<a id="p113913"></a>**CHAPTER 3**

<a id="p113914"></a>**VALUE OF GOODS FOR CUSTOMS PURPOSES**

<a id="p113915"></a>Article 127

<a id="p113916"></a>General provisions
(Article 70(3)(d) of the Code)

1. <a id="p113917"></a>For the purposes of this Chapter, two persons shall be deemed to be related if one of the following conditions is fulfilled:
<a id="p113918"></a>(a) they are officers or directors of the other person's business;
<a id="p113919"></a>(b) they are legally recognised partners in business;
<a id="p113920"></a>(c) they are employer and employee;
<a id="p113921"></a>(d) a third party directly or indirectly owns or controls or holds 5% or more of the outstanding voting stock or shares of both of them;
<a id="p113922"></a>(e) one of them directly or indirectly controls the other;
<a id="p113923"></a>(f) both of them are directly or indirectly controlled by a third person;
<a id="p113924"></a>(g) together they control a third person directly or indirectly;
<a id="p113925"></a>(h) they are members of the same family.
2. <a id="p113926"></a>Persons who are associated in business with one another in that one is the sole agent, sole distributor or sole concessionaire, however described, of the other shall be deemed to be related only if they fall within the criteria referred to in paragraph 1.
3. <a id="p113927"></a>For the purposes of paragraph 1(e), (f) and (g) one person is deemed to control another when the former is legally or operationally in a position to exercise direction over the latter.

<a id="p113928"></a>Article 128

<a id="p113929"></a>Transaction value
(Article 70(1) of the Code)

1. <a id="p113930"></a>The transaction value of the goods sold for export to the customs territory of the Union shall be determined at the time of acceptance of the customs declaration on the basis of the sale occurring immediately before the goods were brought into that customs territory.
2. <a id="p113931"></a>Where the goods are sold for export to the customs territory of the Union not before they were brought into that customs territory but while in temporary storage or while placed under a special procedure other than internal transit, end-use or outward processing, the transaction value will be determined on the basis of that sale.

<a id="p113932"></a>Article 129

<a id="p113933"></a>Price actually paid or payable
(Article 70(1) and (2) of the Code)

1. <a id="p113934"></a>The price actually paid or payable within the meaning of Article 70(1) and (2) of the Code shall include all payments made or to be made as a condition of sale of the imported goods by the buyer to any of the following persons:
<a id="p113935"></a>(a) the seller;
<a id="p113936"></a>(b) a third party for the benefit of the seller;
<a id="p113937"></a>(c) a third party related to the seller;
<a id="p113938"></a>(d) a third party where the payment to that party is made in order to satisfy an obligation of the seller.
<a id="p113939"></a>Payments may be made by way of letters of credit or negotiable instruments, and payments may be made directly or indirectly.
2. <a id="p113940"></a>Activities, including marketing activities, undertaken by the buyer or an undertaking related to the buyer on his or its own account, other than those for which an adjustment is provided in Article 71 of the Code, shall not be considered an indirect payment to the seller.

<a id="p113941"></a>Article 130

<a id="p113942"></a>Discounts
(Article 70(1) and (2) of the Code)

1. <a id="p113943"></a>For the purposes of determining the customs value under Article 70(1) of the Code, discounts shall be taken into account if, at the time of acceptance of the customs declaration, the sales contract provides for their application and their amount.
2. <a id="p113944"></a>Discounts for early payment shall be taken into account with regard to goods for which the price has not actually been paid at the time of acceptance of the customs declaration.
3. <a id="p113945"></a>Discounts arising from amendments to the contract subsequent to the time of acceptance of the customs declaration shall not be taken into account.

<a id="p113946"></a>Article 131

<a id="p113947"></a>Partial delivery
(Article 70(1) of the Code)

1. <a id="p113948"></a>Where goods declared for a customs procedure are part of a larger quantity of the same goods purchased in one transaction, the price actually paid or payable shall, for the purposes of Article 70(1) of the Code, be calculated pro rata on the basis of the price for the total quantity purchased.
2. <a id="p113949"></a>Apportioning the price actually paid or payable shall also apply in the case of the loss of part of a consignment or when the goods have been damaged before the goods are released for free circulation.

<a id="p113950"></a>Article 132

<a id="p113951"></a>Price adjustments for defective goods
(Article 70(1) of the Code)

<a id="p113952"></a>An adjustment made by the seller, to the benefit of the buyer, of the price actually paid or payable for the goods may be taken into consideration for the determination of the customs value in accordance with Article 70(1) of the Code, if the following conditions are fulfilled:
<a id="p113953"></a>(a) the goods were defective at the time of acceptance of the customs declaration for release for free circulation;
<a id="p113954"></a>(b) the seller made the adjustment to compensate for the defect in order to fulfil either of the following:
<a id="p113955"></a>(i) a contractual obligation entered into before the acceptance of the customs declaration;
<a id="p113956"></a>(ii) a statutory obligation applicable to the goods.


<a id="p113957"></a>Article 133

<a id="p113958"></a>Valuation of conditions and considerations
(Article 70(3)(b) of the Code)

<a id="p113959"></a>Where the sale or price of imported goods is subject to a condition or consideration the value of which can be determined with respect to the goods being valued, such value shall be regarded as part of the price actually paid or payable, unless those conditions or considerations relate to either of the following:
<a id="p113960"></a>(a) an activity to which Article 129(2) of this Regulation applies;
<a id="p113961"></a>(b) an element of the customs value under Article 71 of the Code.

<a id="p113962"></a>Article 134

<a id="p113963"></a>Transactions between related persons
(Article 70(3)(d) of the Code)

1. <a id="p113964"></a>Where the buyer and the seller are related, and in order to determine whether such relationship did not influence the price, the circumstances surrounding the sale shall be examined as may be necessary, and the declarant shall be given an opportunity to supply further detailed information as may be necessary about those circumstances.
2. <a id="p113965"></a>However, the goods shall be valued in accordance with Article 70(1) of the Code where the declarant demonstrates that the declared transaction value closely approximates to one of the following test values, determined at or about the same time:
<a id="p113966"></a>(a) the transaction value in sales, between buyers and sellers who are not related in any particular case, of identical or similar goods for export to the customs territory of the Union;
<a id="p113967"></a>(b) the customs value of identical or similar goods, determined in accordance with Article 74(2)(c) of the Code;
<a id="p113968"></a>(c) the customs value of identical or similar goods, determined in accordance with Article 74(2)(d) of the Code.
3. <a id="p113969"></a>When establishing the value of identical or similar goods referred to in paragraph 2, account shall be taken of the following elements:
<a id="p113970"></a>(a) demonstrated differences in commercial levels;
<a id="p113971"></a>(b) quantity levels;
<a id="p113972"></a>(c) the elements listed in Article 71(1) of the Code;
<a id="p113973"></a>(d) costs incurred by the seller in sales in which he and the buyer are not related, where such costs are not incurred by the seller in sales between related persons.
4. <a id="p113974"></a>The test values listed in paragraph 2 are to be used at the request of the declarant. They shall not substitute for the declared transaction value.

<a id="p113975"></a>Article 135

<a id="p113976"></a>Goods and services used
for the production of the imported goods
(Article 71(1)(b) of the Code)

1. <a id="p113977"></a>Where a buyer supplies any of the goods or services listed in Article 71(1)(b) of the Code to the seller, the value of those goods and services shall be deemed to be equal to their purchasing price. The purchasing price shall include all the payments which the buyer of the goods or services listed in Article 71(1)(b) is required to make to acquire the goods or services.
<a id="p113978"></a>Where those goods or services were produced by the buyer or a person related to him, their value shall be the cost of producing them.
2. <a id="p113979"></a>Where the value of the goods and services listed in Article 71(1)(b) of the Code cannot be determined in accordance with paragraph 1, it shall be determined on the basis of other objective and quantifiable data.
3. <a id="p113980"></a>Where the goods listed in Article 71(1)(b) of the Code have been used by the buyer before they were supplied, their value shall be adjusted to take account of any depreciation.
4. <a id="p113981"></a>The value of the services referred to in Article 71(1)(b) of the Code, shall include the costs of unsuccessful development activities insofar as those were incurred in respect of projects or orders relating to the imported goods.
5. <a id="p113982"></a>For the purposes of Article 71(1)(b)(iv) of the Code, the costs of research and preliminary design sketches shall not be included in the customs value.
6. <a id="p113983"></a>The value of the goods and services supplied, as established in accordance with paragraphs 1 to 5 shall be apportioned pro rata over the imported goods.

<a id="p113984"></a>Article 136

<a id="p113985"></a>Royalties and licence fees
(Article 71(1)(c) of the Code)

1. <a id="p113986"></a>Royalties and licence fees are related to the imported goods where in particular, the rights transferred under the licence or royalties agreement are embodied in the goods. The method of calculation of the amount of the royalty or licence fee is not the decisive factor.
2. <a id="p113987"></a>Where the method of calculation of the amount of royalties or licence fees derives from the price of the imported goods, it shall in the absence of evidence to the contrary be assumed that the payment of those royalties or licence fees is related to the goods to be valued.
3. <a id="p113988"></a>If royalties or licence fees relate partly to the goods being valued and partly to other ingredients or component parts added to the goods after their importation, or to post-importation activities or services, an appropriate adjustment shall be made.
4. <a id="p113989"></a>Royalties and licence fees are considered to be paid as a condition of sale for the imported goods when any of the following conditions is met:
<a id="p113990"></a>(a) the seller or a person related to the seller requires the buyer to make this payment;
<a id="p113991"></a>(b) the payment by the buyer is made to satisfy an obligation of the seller, in accordance with contractual obligations;
<a id="p113992"></a>(c) the goods cannot be sold to, or purchased by, the buyer without payment of the royalties or license fees to a licensor.
5. <a id="p113993"></a>The country in which the recipient of the royalties or licence fees payment is established is not a material consideration.

<a id="p113994"></a>Article 137

<a id="p113995"></a>Place where goods are brought
into the customs territory of the Union
(Article 71(1)(e) of the Code)

1. <a id="p113996"></a>For the purposes of Article 71(1)(e) of the Code, the place where goods are brought into the customs territory of the Union shall be:
<a id="p113997"></a>(a) for goods carried by sea, the port where the goods arrive first in the customs territory of the Union;
<a id="p113998"></a>(b) for goods carried by sea into one of the French overseas departments which are part of the customs territory of the Union, and carried directly to another part of the customs territory of the Union, or vice versa, the port where the goods arrive first in the customs territory of the Union, provided that they were unloaded or transhipped there;
<a id="p113999"></a>(c) for goods carried by sea and then, without transhipment, by inland waterway, the first port where unloading can take place;
<a id="p114000"></a>(d) for goods carried by rail, inland waterway, or road, the place where the customs office of entry is situated;
<a id="p114001"></a>(e) for goods carried by other modes of transport, the place where the frontier of the customs territory of the Union is crossed.
2. <a id="p114002"></a>For the purposes of Article 71(1)(e) of the Code, where the goods are brought into the customs territory of the Union and then carried to a destination in another part of that territory through territories outside of the customs territory of the Union, the place where the goods are brought into the customs territory of the Union shall be the place where goods were first brought into that customs territory, provided that the goods are carried directly through those territories by a usual route to the place of destination.
3. <a id="p114003"></a>Paragraph 2 shall also apply where the goods have been unloaded, transhipped or temporarily immobilised in territories outside of the customs territory of the Union for reasons relating solely to their transport.
4. <a id="p114004"></a>Where the conditions laid down in paragraphs 1(b), 2 and 3 are not fulfilled, the place where goods are brought into the customs territory of the Union shall be the following:
<a id="p114005"></a>(a) for goods carried by sea, the port of unloading;
<a id="p114006"></a>(b) for goods carried by other modes of transport the place specified in points (c), (d) or (e) of paragraph 1 situated in that part of the customs territory of the Union to which the goods are consigned.

<a id="p114007"></a>Article 138

<a id="p114008"></a>Transport costs
(Article 71(1)(e) of the Code)

1. <a id="p114009"></a>Where goods are carried by the same mode of transport to a point beyond the place where they are brought into the customs territory of the Union, transport costs shall be assessed in proportion to the distance to the place where the goods are brought into the customs territory of the Union in accordance with Article 137 of this Regulation, unless evidence is produced to the customs authorities to show the costs that would have been incurred under a standard schedule of freight rates for the carriage of the goods to the place where goods are brought into the customs territory of the Union.
2. <a id="p114010"></a>Air transport costs, including air express delivery costs, to be included in the customs value of goods shall be determined in accordance with Annex 23-01.
3. <a id="p114011"></a>Where transport is free of charge or provided by the buyer, the transport costs to be included in the customs value of the goods shall be calculated in accordance with the schedule of freight rates normally applied for the same modes of transport.

<a id="p114012"></a>Article 139

<a id="p114013"></a>Charges levied on postal consignments
(Article 70(1) of the Code)

<a id="p114014"></a>Postal charges levied up to the place of destination in respect of goods sent by post shall be included in the customs value of these goods, with the exception of any supplementary postal charge levied in the customs territory of the Union.

<a id="p114015"></a>Article 140

<a id="p114016"></a>Non-acceptance of declared transaction values
(Article 70(1) of the Code)

1. <a id="p114017"></a>Where the customs authorities have reasonable doubts that the declared transaction value represents the total amount paid or payable as referred to in Article 70(1) of the Code, they may ask the declarant to supply additional information.
2. <a id="p114018"></a>If their doubts are not dispelled, the customs authorities may decide that the value of the goods cannot be determined in accordance with Article 70(1) of the Code.

<a id="p114019"></a>Article 141

<a id="p114020"></a>Customs value of identical or similar goods
(Article 74(2)(a) and (b) of the Code)

1. <a id="p114021"></a>When determining the customs value of imported goods in accordance with Article 74(2)(a) or (b) of the Code, the transaction value of identical or similar goods in a sale at the same commercial level and in substantially the same quantities as the goods being valued shall be used.
<a id="p114022"></a>Where no such sale is found, the customs value shall be determined having regard to the transaction value of identical or similar goods sold at a different commercial level or in different quantities. This transaction value should be adjusted to take account of differences attributable to commercial level and/or quantity.
2. <a id="p114023"></a>An adjustment shall be made to take account of significant differences in costs and charges between the imported goods and the identical or similar goods in question due to differences in distances and modes of transport.
3. <a id="p114024"></a>Where more than one transaction value of identical or similar goods is found, the lowest of those values shall be used to determine the customs value of the imported goods.
4. <a id="p114025"></a>"Identical goods" and "similar goods", as the case may be, do not include goods which incorporate or reflect engineering, development, artwork, design work, plans or sketches for which no adjustment has been made under Article 71(1)(b)(iv) of the Code because such work was undertaken in the Union.
5. <a id="p114026"></a>A transaction value for goods produced by a different person is to be taken into account only when no transaction value can be found for identical or similar goods produced by the person who produced the goods being valued.

<a id="p114027"></a>Article 142

<a id="p114028"></a>Deductive method
(Article 74(2)(c) of the Code)

1. <a id="p114029"></a>The unit price used to determine the customs value under Article 74(2)(c) of the Code shall be the price at which the imported goods or imported identical or similar goods are sold in the Union, in the condition as imported, at or about the time of importation of the goods being valued.
2. <a id="p114030"></a>In the absence of a unit price as referred to in paragraph 1, the unit price used shall be the price at which the imported goods or imported identical or similar goods are sold in the conditions as imported in the customs territory of the Union at the earliest time after the importation of the goods to be valued and in any case within 90 days of that importation.
3. <a id="p114031"></a>In the absence of a unit price as referred either to paragraphs 1 and 2, at the request of the declarant the unit price at which the imported goods are sold in the customs territory of the Union after further working or processing shall be used, due allowance being made for the value added by such working or processing.
4. <a id="p114032"></a>The following sales shall not be taken into account for the purposes of determining the customs value under Article 74(2)(c) of the Code:
<a id="p114033"></a>(a) sales of goods at a commercial level other than the first after importation;
<a id="p114034"></a>(b) sales to related persons;
<a id="p114035"></a>(c) sales to persons who directly or indirectly supply, free of charge or at reduced cost, the goods or services listed in Article 71(1)(b) of the Code for use in connection with the production and sale for export of the imported goods;
<a id="p114036"></a>(d) sales in quantities which are not sufficient to allow the unit price to be determined.
5. <a id="p114037"></a>When determining the customs value, the following shall be deducted from the unit price determined in accordance with paragraphs 1 to 4:
<a id="p114038"></a>(a) either the commissions usually paid or agreed to be paid or the additions usually made for profit and general expenses (including the direct and indirect costs of marketing the goods in question) in connection with sales in the customs territory of the Union of imported goods of the same class or kind which are goods that fall within a group or range of goods produced by a particular industrial sector;
<a id="p114039"></a>(b) usual costs of transport and insurance and associated costs incurred within the customs territory of the Union;
<a id="p114040"></a>(c) import duties and other charges payable in the customs territory of the Union by reason of the import or sale of the goods.
6. <a id="p114041"></a>The customs value of certain perishable goods as referred to in Annex 23-02 imported on consignment may be directly determined in accordance with Article 74(2)(c) of the Code. For this purpose the unit prices shall be notified to the Commission by the Member States and disseminated by the Commission via TARIC in accordance with Article 6 of Council Regulation (EEC) No 2658/87 <*>.

<a id="p114042"></a>

---

<a id="p114043"></a><*> Council Regulation (EEC) No 2658/87 of 23 July 1987 on the tariff and statistical nomenclature and on the Common Customs Tariff (OJ L 256, 7.9.1987, p. 1).

<a id="p114044"></a>Such unit prices may be used to determine the customs value of the imported goods for periods of 14 days. Each period shall start on a Friday.
<a id="p114045"></a>The unit prices shall be calculated and notified as follows:
<a id="p114046"></a>(a) after the deductions provided for in paragraph 5 unit price per 100 kg net for each category of goods shall be notified by the Member States to the Commission. Member States may fix standard amounts for the costs referred to point (b) of paragraph 5, which shall be made known to the Commission;
<a id="p114047"></a>(b) the reference period for determining unit prices shall be the preceding period of 14 days which ends on the Thursday preceding the week during which new unit prices are to be established;
<a id="p114048"></a>(c) Member States shall notify the unit prices in euro to the Commission not later than 12.00 on the Monday of the week in which they are to be disseminated by the Commission. Where that day is not a working day, notification shall be made on the working day immediately preceding that day. Unit prices shall only apply if this notification is disseminated by the Commission.

<a id="p114049"></a>Article 143

<a id="p114050"></a>Computed Value method
(Article 74(2)(d) of the Code)

1. <a id="p114051"></a>In applying Article 74(2)(d) of the Code, the customs authorities may not require or compel any person not established in the customs territory of the Union to produce for examination, or to allow access to, any account or other record for the purposes of determining the customs value.
2. <a id="p114052"></a>The cost or value of materials and fabrication referred to in Article 74(2)(d)(i) of the Code shall include the cost of elements specified in Article 71(1)(a) (ii) and (iii) of the Code. It shall also include the apportioned value of any product or service specified in Article 71(1)(b) of the Code which has been supplied directly or indirectly by the buyer for use in connection with the production of the goods being valued. The value of elements specified in Article 71(1)(b)(iv) of the Code which are undertaken in the Union shall be included only to the extent that those elements are charged to the producer.
3. <a id="p114053"></a>The cost of production includes all expenditure incurred in creating, adding to or substantially enhancing economic goods. It also includes the costs specified in Article 71(1)(b)(ii) and (iii) of the Code.
4. <a id="p114054"></a>The general expenses referred to in Article 74(2)(d)(ii) of the Code, cover the direct and indirect costs of producing and selling the goods for export which are not included under Article 74(2)(d)(i) of the Code.

<a id="p114055"></a>Article 144

<a id="p114056"></a>Fall-back method
(Article 74(3) of the Code)

1. <a id="p114057"></a>When determining the customs value under Article 74(3) of the Code, reasonable flexibility may be used in the application of the methods provided for in Articles 70 and 74(2) of the Code. The value so determined shall, to the greatest extent possible, be based on previously determined customs values.
2. <a id="p114058"></a>Where no customs value can be determined under paragraph 1, other appropriate methods shall be used. In this case the customs value shall not be determined on the basis of any of the following:
<a id="p114059"></a>(a) the selling price within the customs territory of the Union of goods produced in the customs territory of the Union;
<a id="p114060"></a>(b) a system whereby the higher of two alternative values is used for customs valuation;
<a id="p114061"></a>(c) the price of goods on the domestic market of the country of exportation;
<a id="p114062"></a>(d) the cost of production, other than computed values which have been determined for identical or similar goods under Article 74(2)(d) of the Code;
<a id="p114063"></a>(e) prices for export to a third country;
<a id="p114064"></a>(f) minimum customs values;
<a id="p114065"></a>(g) arbitrary or fictitious values.

<a id="p114066"></a>Article 145

<a id="p114067"></a>Supporting documents regarding customs value
(Article 163(1) of the Code)

<a id="p114068"></a>The invoice which relates to the declared transaction value is required as a supporting document.

<a id="p114069"></a>Article 146

<a id="p114070"></a>Currency conversion for customs valuation purposes
(Article 53(1)(a) of the Code)

1. <a id="p114071"></a>In accordance with Article 53(1)(a) of the Code, the following rates of exchange shall be used for currency conversion for customs valuation purposes:
<a id="p114072"></a>(a) the rate of exchange published by the European Central Bank, for the Member States whose currency is the euro;
<a id="p114073"></a>(b) the rate of exchange published by the competent national authority or, where the national authority has designated a private bank for the purposes of publishing the rate of exchange, the rate published by that private bank, for the Member States whose currency is not the euro.
2. <a id="p114074"></a>The rate of exchange to be used in accordance with paragraph 1 shall be the rate of exchange published on the second last Wednesday of each month.
<a id="p114075"></a>Where no rate of exchange has been published on that day, the most recently published rate shall apply.
3. <a id="p114076"></a>The rate of exchange shall apply for a month, beginning on the first day of the following month.
4. <a id="p114077"></a>Where a rate of exchange has not been published as referred to in paragraphs 1 and 2, the rate to be used for the application of Article 53(1)(a) of the Code shall be determined by the Member State concerned. This rate must reflect the value of the currency of the Member State concerned as closely as possible.

<a id="p114078"></a>**TITLE III. CUSTOMS DEBT AND GUARANTEES**

<a id="p114079"></a>**CHAPTER 1**

<a id="p114080"></a>**GUARANTEE FOR A POTENTIAL OR EXISTING CUSTOMS DEBT**

<a id="p114081"></a>Section 1. GENERAL PROVISIONS

<a id="p114082"></a>Article 147

<a id="p114083"></a>Electronic systems relating to guarantees
(Article 16 of the Code)

<a id="p114084"></a>For the exchange and storage of information pertaining to guarantees which may be used in more than one Member State, an electronic system set up for those purposes pursuant to Article 16(1) of the Code shall be used.
<a id="p114085"></a>The first paragraph of this Article shall be applicable from the date of deployment of the UCC GUM system referred to in the Annex to Implementing Decision 2014/255/EU.

<a id="p114086"></a>Article 148

<a id="p114087"></a>Individual guarantee for a potential customs debt
(Article 90(1) subparagraph 2 of the Code)

1. <a id="p114088"></a>Where it is compulsory for a guarantee to be provided, a guarantee covering a single operation (individual guarantee) for a potential customs debt shall cover the amount of import or export duty corresponding to the customs debt which may be incurred, calculated on the basis of the highest rates of duty applicable to goods of the same type.
2. <a id="p114089"></a>Where the other charges due in connection with the import or export of goods are to be covered by the individual guarantee, their calculation shall be based on the highest rates applicable to goods of the same type in the Member State where the goods concerned are placed under the customs procedure or are in temporary storage.

<a id="p114090"></a>Article 149

<a id="p114091"></a>Optional guarantee
(Article 91 of the Code)

<a id="p114092"></a>Where the customs authorities decide to require a guarantee which is optional, Articles 150 to 158 of this Regulation shall apply.

<a id="p114093"></a>Article 150

<a id="p114094"></a>Guarantee in the form of cash deposit
(Article 92(1)(a) of the Code)

<a id="p114095"></a>Where a guarantee is required for special procedures or temporary storage and is provided as an individual guarantee in the form of a cash deposit, that guarantee shall be provided to the customs authorities of the Member State where the goods are placed under the procedure or are in temporary storage.
<a id="p114096"></a>Where a special procedure other than the end-use procedure has been discharged or the supervision of end-use goods or the temporary storage has ended correctly, the guarantee shall be repaid by the customs authority of the Member State where it was provided.

<a id="p114097"></a>Article 151

<a id="p114098"></a>Guarantee in the form of an undertaking by a guarantor
(Articles 92(1)(b) and 94 of the Code)

1. <a id="p114099"></a>The undertaking given by a guarantor shall be approved by the customs office where the guarantee is provided (customs office of guarantee) which shall notify the approval to the person required to provide the guarantee.
2. <a id="p114100"></a>The customs office of guarantee may revoke the approval of the undertaking by a guarantor at any time. The customs office of guarantee shall notify the revocation to the guarantor and the person required to provide the guarantee.
3. <a id="p114101"></a>A guarantor may cancel his undertaking at any time. The guarantor shall notify the cancellation to the customs office of guarantee.
4. <a id="p114102"></a>The cancellation of the undertaking of the guarantor shall not affect goods which, at the moment where the cancellation takes effect, have already been placed and still are under a customs procedure or in temporary storage by virtue of the cancelled undertaking.
5. <a id="p114103"></a>An individual guarantee provided in the form of an undertaking shall be given using the form set out in Annex 32-01.
6. <a id="p114104"></a>A comprehensive guarantee provided in the form of an undertaking shall be given using the form set out in Annex 32-03.
7. <a id="p114105"></a>Notwithstanding paragraphs 5 and 6 and Article 160, each Member State may, in accordance with national law, allow an undertaking given by a guarantor to take a form different from the ones set out in Annexes 32-01, 32-02 and 32-03 provided it has the same legal effect.

<a id="p114106"></a>Article 152

<a id="p114107"></a>Individual guarantee provided
in the form of an undertaking by a guarantor
(Articles 89 and 92(1)(b) of the Code)

1. <a id="p114108"></a>Where an individual guarantee is provided in the form of an undertaking by a guarantor, the proof of that undertaking shall be kept by the customs office of guarantee for the period of validity of the guarantee.
2. <a id="p114109"></a>Where an individual guarantee is provided in the form of an undertaking by a guarantor, the holder of the procedure shall not modify the access code associated with the guarantee reference number.

<a id="p114110"></a>Article 153

<a id="p114111"></a>Mutual assistance between customs authorities
(Article 92(1)(c) of the Code)

<a id="p114112"></a>Where a customs debt is incurred in a Member State other than the Member State which has accepted a guarantee in one of the forms referred to in Article 83(1) of Delegated Regulation (EU) 2015/2446, which may be used in more than one Member State, the Member State which has accepted the guarantee shall transfer to the Member State where the customs debt is incurred, on a request made by the latter after the expiry of the time-limit for payment, the amount of import or export duty within the limits of the accepted guarantee and of the unpaid duty.
<a id="p114113"></a>That transfer shall be made within 1 month of reception of the request.

<a id="p114114"></a>Article 154

<a id="p114115"></a>Guarantee reference number and access code
(Article 89(2) of the Code)

1. <a id="p114116"></a>Where an individual guarantee may be used in more than one Member State, the customs office of guarantee shall communicate to the person who has provided the guarantee or, in case of a guarantee in the form of vouchers, to the guarantor the following information:
<a id="p114117"></a>(a) a guarantee reference number;
<a id="p114118"></a>(b) an access code associated with the guarantee reference number.
2. <a id="p114119"></a>Where a comprehensive guarantee may be used in more than one Member State, the customs office of guarantee shall communicate to the person who has provided the guarantee the following information:
<a id="p114120"></a>(a) a guarantee reference number for each part of the reference amount to be monitored in accordance with Article 157 of this Regulation;
<a id="p114121"></a>(b) an access code associated with the guarantee reference number.
<a id="p114122"></a>Upon request of the person who has provided the guarantee, the customs office of guarantee shall assign one or more additional access codes to this guarantee to be used by that person or his representatives.
3. <a id="p114123"></a>A customs authority shall verify the existence and the validity of the guarantee each time a person communicates to it a guarantee reference number.

<a id="p114124"></a>Section 2

<a id="p114125"></a>**COMPREHENSIVE GUARANTEE**

<a id="p114126"></a>Article 155

<a id="p114127"></a>Reference amount
(Article 90 of the Code)

1. <a id="p114128"></a>Unless otherwise provided for in Article 158 of this Regulation, the amount of the comprehensive guarantee shall be equal to a reference amount established by the customs office of guarantee in accordance with Article 90 of the Code.
2. <a id="p114129"></a>Where a comprehensive guarantee is to be provided for import or export duty and other charges the amount of which can be established with certainty at the time when the guarantee is required, the part of the reference amount covering those duties and charges shall correspond to the amount of the import or export duty and of the other charges payable.
3. <a id="p114130"></a>Where a comprehensive guarantee is to be provided for import or export duty and other charges, the amount of which cannot be established with certainty at the time when the guarantee is required or which vary in amount over time, the part of the reference amount covering those duties and charges shall be fixed as follows:
<a id="p114131"></a>(a) for the part that is to cover import or export duty and other charges which have been incurred, the reference amount shall correspond to the amount of the import or export duty and of the other charges payable;
<a id="p114132"></a>(b) for the part that is to cover import or export duty and other charges which may be incurred, the reference amount shall correspond to the amount of the import or export duty and of the other charges which may become payable in connection with each customs declaration or temporary storage declaration in respect of which the guarantee is provided, in the period between the placing of the goods under the relevant customs procedure or in temporary storage and the moment when that procedure is discharged or the supervision of end-use goods or temporary storage is ended.
<a id="p114133"></a>For the purposes of point (b), account shall be taken of the highest rates of import or export duty applicable to goods of the same type and of the highest rates of other charges due in connection with the import or export of goods of the same type in the Member State of the customs office of guarantee.
<a id="p114134"></a>Where the information necessary to determine the part of the reference amount pursuant to the first subparagraph is not available to the customs office of guarantee, that amount shall be fixed at EUR 10 000 for each declaration.
4. <a id="p114135"></a>The customs office of guarantee shall establish the reference amount in cooperation with the person required to provide the guarantee. When fixing the part of the reference amount in accordance with paragraph 3, the custom office of guarantee shall establish that amount on the basis of the information on goods placed under the relevant customs procedures or in temporary storage in the preceding 12 months and on an estimate of the volume of intended operations as shown, inter alia, by the commercial documentation and accounts of the person required to provide the guarantee.
5. <a id="p114136"></a>The customs office of guarantee shall review the reference amount on its own initiative or following a request from the person required to provide the guarantee, and shall adjust it to comply with the provisions of this Article and Article 90 of the Code.

<a id="p114137"></a>Article 156

<a id="p114138"></a>Monitoring of the reference amount
by the person required to provide a guarantee
(Article 89 of the Code)

<a id="p114139"></a>The person required to provide a guarantee shall ensure that the amount of import or export duty, and of other charges due in connection with the import or export of goods where they are to be covered by the guarantee, which is payable or may become payable does not exceed the reference amount.
<a id="p114140"></a>That person shall inform the customs office of guarantee when the reference amount is no longer at a level sufficient to cover his operations.

<a id="p114141"></a>Article 157

<a id="p114142"></a>Monitoring of the reference
amount by the customs authorities
(Article 89(6) of the Code)

1. <a id="p114143"></a>The monitoring of the part of the reference amount that covers the amount of import or export duty, and of other charges due in connection with the import or export of goods, which will become payable with respect to goods placed under release for free circulation shall be ensured for each customs declaration at the time of placing of goods under the procedure. Where customs declarations for release for free circulation are lodged in accordance with an authorisation referred to in Articles 166(2) or 182 of the Code, the monitoring of the relevant part of the reference amount shall be ensured on the basis of the supplementary declarations or, where applicable, on the basis of the particulars entered in the records.
2. <a id="p114144"></a>The monitoring of the part of the reference amount that covers the amount of import or export duty, and other charges due in connection with the import or export of goods, which may become payable with respect to goods placed under the Union transit procedure shall be ensured, by means of the electronic system referred to in Article 273(1) of this Regulation, for each customs declaration at the time of placing of goods under the procedure. That monitoring shall not apply to goods placed under the Union transit procedure using the simplification referred to in Article 233(4)(e) of the Code where the customs declaration is not processed by the electronic system referred to in Article 273(1) of this Regulation.
3. <a id="p114145"></a>The monitoring of the part of the reference amount that covers the amount of import or export duty, and other charges due in connection with the import or export of goods where they are to be covered by the guarantee, which will be incurred or may be incurred in cases other than those referred to in paragraphs 1 and 2 shall be ensured by regular and appropriate audit.

<a id="p114146"></a>Article 158

<a id="p114147"></a>Level of comprehensive guarantee
(Article 95(2) and (3) of the Code)

1. <a id="p114148"></a>Under the conditions laid down in Article 84 of Delegated Regulation (EU) 2015/2446, the amount of the comprehensive guarantee referred to in Article 95(2) of the Code shall be reduced to 50%, 30% or 0% of the part of the reference amount determined in accordance with Article 155(3)(b) of this Regulation.
2. <a id="p114149"></a>The amount of the comprehensive guarantee referred to in Article 95(3) of the Code shall be reduced to 30% of the parts of the reference amount determined in accordance with Article 155(2) and Article 155(3)(a) of this Regulation.

<a id="p114150"></a>Section 3. PROVISIONS FOR THE UNION TRANSIT PROCEDURE AND
**THE PROCEDURE UNDER THE TIR AND THE ATA CONVENTIONS**

<a id="p114151"></a>Subsection 1

<a id="p114152"></a>**UNION TRANSIT**

<a id="p114153"></a>Article 159

<a id="p114154"></a>Calculation for the purpose of common transit
(Article 89(2) of the Code)

<a id="p114155"></a>For the purpose of the calculation referred to in Article 148 and in the second subparagraph of Article 155(3)(b) of this Regulation, Union goods carried in accordance with the Convention on a common transit procedure <*> shall be treated as non-Union goods.

<a id="p114156"></a>

---

<a id="p114157"></a><*> OJ L 226, 13.8.1987, p. 2.

<a id="p114158"></a>Article 160

<a id="p114159"></a>Individual guarantee in the form of vouchers
(Article 92(1)(b) of the Code)

1. <a id="p114160"></a>In the context of Union transit procedure, an individual guarantee in the form of an undertaking by a guarantor may also be provided by the guarantor by issuing vouchers to persons who intend to be the holders of the procedure.
<a id="p114161"></a>The proof of that undertaking shall be made out using the form set out in Annex 32-02 and the vouchers shall be made out using with the form set out in Annex 32-06.
<a id="p114162"></a>Each voucher shall cover an amount of EUR 10 000 for which the guarantor shall be liable.
<a id="p114163"></a>The period of validity of a voucher shall be 1 year from the date of issue.
2. <a id="p114164"></a>The guarantor shall provide the customs office of guarantee with any required details about the individual guarantee vouchers that he has issued.
3. <a id="p114165"></a>For each voucher, the guarantor shall communicate to the person who intends to be the holder of the procedure the following information:
<a id="p114166"></a>(a) a guarantee reference number;
<a id="p114167"></a>(b) an access code associated with the guarantee reference number.
<a id="p114168"></a>The person who intends to be the holder of the procedure shall not modify the access code.
4. <a id="p114169"></a>The person who intends to be the holder of the procedure shall submit at the customs office of departure a number of vouchers corresponding to the multiple of EUR 10 000 required to cover the sum of the amounts referred to in Article 148 of this Regulation.

<a id="p114170"></a>Article 161

<a id="p114171"></a>Revocation and cancellation of an undertaking provided in
case of an individual guarantee in the form of vouchers
(Articles 92(1)(b) and 94 of the Code)

<a id="p114172"></a>The customs authority responsible for the relevant customs office of guarantee shall introduce into the electronic system referred to in Article 273(1) of this Regulation information of any revocation or cancellation of an undertaking provided in case of an individual guarantee in the form of vouchers and the date when it becomes effective.
<a id="p114173"></a>From the day on which the revocation or cancellation becomes effective, no individual guarantee vouchers issued earlier may be used for placing goods under the Union transit procedure.

<a id="p114174"></a>Article 162

<a id="p114175"></a>Comprehensive guarantee
(Articles 89(5) and 95 of the Code)

1. <a id="p114176"></a>In the context of Union transit procedure, the comprehensive guarantee may only be provided in the form of an undertaking by a guarantor.
2. <a id="p114177"></a>The proof of that undertaking shall be kept by the customs office of guarantee for the period of validity of the guarantee.
3. <a id="p114178"></a>The holder of the procedure shall not modify the access code associated with the guarantee reference number.

<a id="p114179"></a>Subsection 2

<a id="p114180"></a>**PROCEDURES UNDER THE TIR AND THE ATA CONVENTIONS**

<a id="p114181"></a>Article 163

<a id="p114182"></a>Liability of guaranteeing associations for TIR operations (Articles 226(3)(b) and 227(2)(b) of the Code)

<a id="p114183"></a>For the purposes of paragraphs 3 and 4 of Article 8 of the Customs Convention on the International Transport of Goods under cover of TIR carnets, including any subsequent amendments thereof (TIR Convention), where a TIR operation is carried out in the customs territory of the Union, any guaranteeing association established in the customs territory of the Union may become liable for the payment of the secured amount relating to the goods concerned in the TIR operation up to a limit, per TIR carnet, of EUR 100 000 or the national currency equivalent thereof.

<a id="p114184"></a>Article 164

<a id="p114185"></a>Notification of non-discharge
of a procedure to guaranteeing associations
(Articles 226(3)(b) and (c) and 227(2)(b)
and (c) of the Code)

<a id="p114186"></a>A valid notification of non-discharge of a procedure in accordance with the TIR Convention or with the ATA Convention or with the Istanbul Convention, made by the customs authorities of one Member State to a guaranteeing association, shall constitute a notification to any other guaranteeing association of another Member State identified as liable for payment of an amount of import or export duty or other charges.

<a id="p114187"></a>**CHAPTER 2**

<a id="p114188"></a>**RECOVERY, PAYMENT, REPAYMENT AND REMISSION OF THE AMOUNT**
**OF IMPORT OR EXPORT DUTY**

<a id="p114189"></a>Section 1. DETERMINATION OF THE AMOUNT OF IMPORT OR EXPORT
**DUTY, NOTIFICATION OF THE CUSTOMS DEBT AND ENTRY IN THE**
**ACCOUNTS**

<a id="p114190"></a>Subsection 1

<a id="p114191"></a>Article 165

<a id="p114192"></a>Mutual assistance between customs authorities
(Articles 101(1) and 102(1) of the Code)

1. <a id="p114193"></a>Where a customs debt is incurred, the customs authorities competent for the recovery of the amount of import or export duty corresponding to the customs debt shall inform the other customs authorities involved of the following:
<a id="p114194"></a>(a) the fact that a customs debt was incurred;
<a id="p114195"></a>(b) the action taken against the debtor to recover the sums concerned.
2. <a id="p114196"></a>The Member States shall assist each other in the recovery of the amount of import or export duty corresponding to the customs debt.
3. <a id="p114197"></a>Without prejudice to Article 87(4) of the Code, where the customs authority of the Member State in which the goods were placed under a special procedure other than transit, or were in temporary storage, obtains, before the expiry of the time-limit referred to in Article 80 of Delegated Regulation (EU) 2015/2446, evidence that the events from which the customs debt arises or is deemed to arise have occurred in another
<a id="p114198"></a>Member State, that customs authority shall immediately and in any event within that time-limit send all the information available to the customs authority responsible for that place. The latter customs authority shall acknowledge receipt of the communication and indicate whether it is responsible for the recovery. If no response is received within 90 days, the sending customs authority shall immediately proceed with the recovery.
4. <a id="p114199"></a>Without prejudice to Article 87(4) of the Code, where the customs authority of the Member State in which it has been found that the customs debt has been incurred with respect to goods which were neither placed under a customs procedure nor under temporary storage, obtains, before the notification of the customs debt, evidence that the events from which the customs debt arises or is deemed to arise have occurred in another Member State, that customs authority shall immediately and in any event before that notification, send all the information available to the customs authority responsible for that place. The latter customs authority shall acknowledge receipt of the communication and indicate whether it is responsible for the recovery. If no response is received within 90 days, the sending customs authority shall immediately proceed with the recovery.

<a id="p114200"></a>Article 166

<a id="p114201"></a>Customs office of coordination
relating to ATA carnets or CPD carnets
(Article 226(3)(c) of the Code)

1. <a id="p114202"></a>The customs authorities shall designate a customs office of coordination responsible for any action concerning customs debts which are incurred through non-compliance with obligations or conditions relating to ATA carnets or CPD carnets under Article 79 of the Code.
2. <a id="p114203"></a>Each Member State shall communicate to the Commission the customs office of coordination together with its reference number. The Commission shall make this information available on its website.

<a id="p114204"></a>Article 167

<a id="p114205"></a>Recovery of other charges under the Union transit procedure
and transit in accordance with the TIR Convention
(Article 226(3)(a) and (b) of the Code)

1. <a id="p114206"></a>Where the customs authorities who notified the customs debt and the obligation to pay other charges due in connection with the import or export of goods placed under the Union transit procedure or under the transit procedure in accordance with the TIR Convention obtain evidence regarding the place where the events giving rise to the customs debt and the obligation to pay other charges occurred, those customs authorities shall suspend the recovery procedure and immediately send all the necessary documents, including an authenticated copy of the evidence, to the authorities responsible for that place. The sending authorities shall simultaneously request confirmation of the responsibility of the receiving authorities for recovery of the other charges.
2. <a id="p114207"></a>The receiving authorities shall acknowledge receipt of the communication and shall indicate whether they are competent for recovery of the other charges. If no response is received within 28 days, the sending authorities shall immediately resume the recovery proceedings they initiated.
3. <a id="p114208"></a>Any pending proceedings for recovery of other charges initiated by the sending authorities shall be suspended as soon as the receiving authorities have acknowledged receipt of communication and indicated that they are competent of recovering the other charges.
<a id="p114209"></a>As soon as the receiving authorities provide proof that they have recovered the sums in question, the sending authorities shall repay any other charges already recovered or cancel the recovery proceedings.

<a id="p114210"></a>Article 168

<a id="p114211"></a>Notification of recovery of duties
and other charges under the Union transit procedure
and transit in accordance with the TIR Convention
(Article 226(3)(a) and (b) of the Code)

<a id="p114212"></a>Where a customs debt is incurred with respect to goods placed under the Union transit procedure or under the transit procedure in accordance with the TIR Convention, the customs authorities competent for recovery shall inform the customs office of departure of the recovery of duties and other charges.

<a id="p114213"></a>Articles 169

<a id="p114214"></a>Recovery of other charges for goods
placed under transit in accordance with the ATA
Convention or the Istanbul Convention
(Article 226(3)(c) of the Code)

1. <a id="p114215"></a>Where the customs authorities who notified the customs debt and the obligation to pay other charges for goods placed under transit in accordance with the ATA Convention/ or the Istanbul Convention obtain evidence regarding the place where the events giving rise to the customs debt and the obligation to pay other charges occurred, those customs authorities shall immediately send all the necessary documents, including an authenticated copy of the evidence, to the authorities competent for that place. The sending authorities shall simultaneously request confirmation of the responsibility of the receiving authorities for recovery of the other charges.
2. <a id="p114216"></a>The receiving authorities shall acknowledge receipt of the communication and shall indicate whether they are competent for recovery of the other charges. For those purposes, the receiving authorities shall use the model of discharge set out in Annex 33-05 indicating that claim proceedings have been initiated with respect to the guaranteeing association in the receiving Member State. If no response is received within 90 days, the sending authorities shall immediately resume the recovery proceedings they initiated.
3. <a id="p114217"></a>Where the receiving authorities are competent, they shall initiate new proceedings for recovery of other charges, where appropriate after the period referred to in paragraph 2, and they shall inform the sending authorities immediately.
<a id="p114218"></a>The receiving authorities shall where necessary collect from the guaranteeing association with which they are connected the amount of duties and other charges due at the rates applicable in the Member State where those authorities are located.
4. <a id="p114219"></a>As soon as the receiving authorities indicate that they are competent for recovery of other charges, the sending authorities shall refund to the guaranteeing association with which they are connected any sums which that association may have deposited or provisionally paid.
5. <a id="p114220"></a>The proceedings shall be transferred within a period of 1 year from the date of expiry of the validity of the carnet unless that payment has become definitive pursuant to Article 7(2) or (3) of the ATA Convention or Article 9(1)(b) and (c) of Annex A to the Istanbul Convention.

<a id="p114221"></a>Article 170

<a id="p114222"></a>Recovery of other charges for goods placed
under temporary admission in accordance with the ATA
Convention or the Istanbul Convention
(Article 226(3)(c) of the Code)

<a id="p114223"></a>In case of recovery of other charges for goods placed under temporary admission in accordance with the ATA Convention or the Istanbul Convention, Article 169 shall apply mutatis mutandis.

<a id="p114224"></a>Subsection 2

<a id="p114225"></a>**NOTIFICATION OF THE CUSTOMS DEBT AND CLAIM FOR PAYMENT FROM**
**GUARANTEEING ASSOCIATION**

<a id="p114226"></a>Article 171

<a id="p114227"></a>Claim for payment from a guaranteeing association under the
procedure of the ATA Convention and the Istanbul Convention
(Article 98 of the Code)

1. <a id="p114228"></a>Where the customs authorities establish that the customs debt has been incurred for goods covered by an ATA carnet, they shall make a claim against the guaranteeing association without delay. The coordinating customs office making the claim referred to in Article 86 of Delegated Regulation (EU) 2015/2446 shall at the same time send to the coordinating customs office in the jurisdiction of which the customs office of placement under temporary admission is situated, an information memo on the claim for payment sent to the guaranteeing association. It shall use the form set out in Annex 33-03.
2. <a id="p114229"></a>The information memo shall be accompanied by a copy of the non-discharged voucher, if the coordinating customs office has it in its possession. The information memo may be used whenever this is deemed necessary.
3. <a id="p114230"></a>The taxation form as referred to in Article 86 of Delegated Regulation (EU) 2015/2446 may be sent later than the claim to the guaranteeing association is made, though not more than 3 months from the claim and in any event not more than 6 months from the date on which the customs authorities initiate the recovery proceedings. The taxation form is set out in Annex 33-04.

<a id="p114231"></a>Section 2. REPAYMENT AND REMISSION

<a id="p114232"></a>Article 172

<a id="p114233"></a>Application for repayment or remission
(Article 22(1) of the Code)

<a id="p114234"></a>Applications for repayment or remission shall be submitted by the person who has paid or is liable to pay the amount of import or export duty, or by any person who has succeeded him in his rights and obligations.

<a id="p114235"></a>Article 173

<a id="p114236"></a>Presentation of goods
as a condition for repayment or remission
(Article 116(1) of the Code)

<a id="p114237"></a>Repayment or remission shall be subject to the presentation of the goods. Where the goods cannot be presented to the customs authorities, the customs authority competent to take the decision shall grant repayment or remission only where it has evidence showing that the goods in question are the goods in respect of which repayment or remission has been requested.

<a id="p114238"></a>Article 174

<a id="p114239"></a>Restriction on the transfer of goods
(Article 116(1) of the Code)

<a id="p114240"></a>Without prejudice to Article 176(4) of this Regulation and until a decision has been taken on an application for repayment or remission, the goods in respect of which repayment or remission has been requested shall not be transferred to a location other than that specified in the application unless the applicant notifies in advance the customs authority referred to in Article 92(1) of Delegated Regulation (EU) 2015/2446, which shall inform the customs authority competent to take the decision.

<a id="p114241"></a>Article 175

<a id="p114242"></a>Mutual assistance between the customs authorities
(Articles 22 and 116(1) of the Code)

1. <a id="p114243"></a>Where for the purposes of repayment or remission supplementary information must be obtained from the customs authority of a Member State other than that in which the customs debt has been notified or where the goods must be examined by that authority in order to ensure that the conditions for repayment or remission are fulfilled, the customs authority competent to take the decision shall request the assistance of the customs authority of the Member State where the goods are located, specifying the nature of the information to be obtained or the checks to be carried out.
<a id="p114244"></a>The request for information shall be accompanied by the particulars of the application and all documents necessary to enable the customs authority of the Member State where the goods are located to obtain the information or carry out the checks requested.
2. <a id="p114245"></a>Where the customs authority competent to take the decision sends the request referred to in paragraph 1 by means other than electronic data-processing techniques in accordance with Article 93 of Delegated Regulation (EU) 2015/2446, it shall send to the customs authority of the Member State where the goods are located two copies of the request made out in writing using the form set out in Annex 33-06.
3. <a id="p114246"></a>The customs authority of the Member State where the goods are located shall comply promptly with the request referred to in paragraph 1.
<a id="p114247"></a>The customs authority of the Member State where the goods are located shall obtain the information or carry out the checks requested by the customs authority competent to take the decision, within 30 days of the date of receipt of the request. It shall enter the results obtained in the relevant part of the original of the request referred to in paragraph 1 and shall return that document to the customs authority competent to take the decision together with all the documents referred to in the second subparagraph of paragraph 1.
<a id="p114248"></a>Where the customs authority of the Member State where the goods are located is unable to obtain the information or carry out the checks requested within the period laid down in the second subparagraph, it shall return the request, duly annotated, within 30 days of the date of receipt of the request.

<a id="p114249"></a>Article 176

<a id="p114250"></a>Completion of customs formalities
(Article 116(1) of the Code)

1. <a id="p114251"></a>Where repayment or remission is subject to the completion of customs formalities, the holder of the decision for repayment or remission shall inform the monitoring customs office that he has completed those formalities. Where the decision specifies that the goods may be exported or placed under a special procedure, and the debtor avails himself of that opportunity, the monitoring customs office shall be the customs office where the goods are placed under that procedure.
2. <a id="p114252"></a>The monitoring customs office shall notify the customs authority competent to take the decision of the completion of the customs formalities to which the repayment or remission is subject by means of a reply referred to in Article 95 of Delegated Regulation (EU) 2015/2446 using the form set out in Annex 33-07 of this Regulation.
3. <a id="p114253"></a>Where the customs authority competent to take the decision has decided that repayment or remission is justified, the amount of duty shall be repaid or remitted only after that customs authority has received the information referred to in paragraph 2.
4. <a id="p114254"></a>The customs authority competent to take the decision may authorise completion of the customs formalities to which any repayment or remission may be subject, before it takes a decision. Such authorisation shall be without prejudice to that decision. In these cases, paragraphs 1 to 3 shall be applicable mutatis mutandis.
5. <a id="p114255"></a>For the purposes of this article, monitoring customs office shall mean the customs office which ensures, where appropriate, that the formalities or requirements to which repayment or remission of the amount of import and export duty is subject, are fulfilled.

<a id="p114256"></a>Article 177

<a id="p114257"></a>Formalities related
to the decision on repayment or remission
(Article 116(2) of the Code)

1. <a id="p114258"></a>When taking a decision on repayment or remission of the import or export duties subject to the prior completion of certain customs formalities, the customs authority shall set a time-limit, which shall not exceed 60 days from the date of the notification of that decision, for completion of those customs formalities.
2. <a id="p114259"></a>Failure to observe the time-limit referred to in paragraph 1 shall result in loss of entitlement to repayment or remission except where person concerned proves that he was prevented from meeting that time-limit due to unforeseeable circumstances or force majeure.

<a id="p114260"></a>Article 178

<a id="p114261"></a>Parts or components of a single article
(Article 116(1) of the Code)

<a id="p114262"></a>Where repayment or remission is subject to destruction, abandonment to the State or placement under a special procedure or the export procedure of goods, but the corresponding formalities are completed only for one or more parts or components of those goods, the amount to be repaid or remitted shall be the difference between the amount of import or export duty on the goods and the amount of import or export duty which would have been applicable on the remainder of the goods if they had been placed in an unaltered state under a customs procedure involving the incurrence of a customs debt, on the date on which the goods were so placed.

<a id="p114263"></a>Article 179

<a id="p114264"></a>Waste and scrap
(Article 116(1) of the Code)

<a id="p114265"></a>Where destruction of goods authorised by the customs authority competent to take the decision produces waste or scrap, such waste or scrap shall be deemed to be non-Union goods once a decision granting repayment or remission has been taken.

<a id="p114266"></a>Article 180

<a id="p114267"></a>Export or destruction without customs supervision
(Article 116(1) of the Code)

1. <a id="p114268"></a>In cases covered by the second subparagraph of Article 116(1), Article 118 or in Article 120 of the Code, where export or destruction took place without customs supervision, repayment or remission on the basis of Article 120 of the Code shall be conditional on the following:
<a id="p114269"></a>(a) the applicant submitting to the customs authority competent to take the decision evidence needed to establish whether the goods in respect of which repayment or remission is requested fulfil one of the following conditions:
<a id="p114270"></a>(a) the goods have been exported from the customs territory of the Union;
<a id="p114271"></a>(b) the goods have been destroyed under the supervision of authorities or persons authorised by those authorities to certify such destruction;
<a id="p114272"></a>(b) the applicant returning to the customs authority competent to take the decision any document certifying or containing information confirming the customs status of Union goods of the goods in question, under cover of which the said goods may have left the customs territory of the Union, or the presentation of whatever evidence the said authority considers necessary to satisfy itself that the document in question cannot be used subsequently in connection with goods brought into the customs territory of the Union.
2. <a id="p114273"></a>The evidence establishing that the goods in respect of which repayment or remission is requested have been exported from the customs territory of the Union shall consist of the following documents:
<a id="p114274"></a>(a) the certification of exit referred to in Article 334 of this Regulation;
<a id="p114275"></a>(b) the original or a certified copy of the customs declaration for the procedure involving the incurrence of the customs debt;
<a id="p114276"></a>(c) where necessary, commercial or administrative documents containing a full description of the goods which were presented with the customs declaration for the said procedure or with the customs declaration for export from the customs territory of the Union or with the customs declaration made for the goods in the third country of destination.
3. <a id="p114277"></a>The evidence establishing that the goods in respect of which repayment or remission is requested have been destroyed under the supervision of authorities or persons authorised to certify officially such destruction shall consist of either of the following documents:
<a id="p114278"></a>(a) a report or declaration of destruction drawn up by the authorities under whose supervision the goods were destroyed, or a certified copy thereof;
<a id="p114279"></a>(b) a certificate drawn up by the person authorised to certify destruction, accompanied by evidence of his authority.
<a id="p114280"></a>Those documents shall contain a full description of the destroyed goods to establish, by means of comparison with the particulars given in the customs declaration for a customs procedure involving the incurrence of the customs debt and the supporting documents, that the destroyed goods are those which had been placed under the said procedure.
4. <a id="p114281"></a>Where the evidence referred to in paragraphs 2 and 3 is insufficient for the customs authority to take a decision on the case submitted to it, or where certain evidence is not available, such evidence may be supplemented or replaced by any other documents considered necessary by the said authority.

<a id="p114282"></a>Article 181

<a id="p114283"></a>Information to be provided to the Commission
(Article 121(4) of the Code)

1. <a id="p114284"></a>Each Member State shall communicate to the Commission a list of the cases where repayment or remission has been granted on the basis of Article 119 or Article 120 of the Code and where the amount repaid or remitted to a certain debtor with respect to one or more import or export operations but as a result of a single error or special situation is more than EUR 50 000, except cases referred to in Article 116(3) of the Code.
2. <a id="p114285"></a>The communication shall be made during the first and third quarters of each year for all cases in which it was decided to repay or remit duties during the preceding half-year.
3. <a id="p114286"></a>Where a Member State has not taken any decision on cases referred to in paragraph 1 during the half-year in question, it shall send the Commission a communication with the entry "Not applicable".
4. <a id="p114287"></a>Each Member State shall hold at the disposal of the Commission a list of the cases where repayment or remission has been granted on the basis of Article 119 or Article 120 of the Code and where the amount repaid or remitted is equal to or less than EUR 50 000.
5. <a id="p114288"></a>For each of the cases referred to in this Article, the following information shall be provided:
<a id="p114289"></a>(a) the reference number of the customs declaration or of the document notifying the debt;
<a id="p114290"></a>(b) the date of the customs declaration or of the document notifying the debt;
<a id="p114291"></a>(c) the type of the decision;
<a id="p114292"></a>(d) the legal basis for the decision;
<a id="p114293"></a>(e) the amount and currency;
<a id="p114294"></a>(f) the case particulars (including a brief explanation as to why the customs authorities consider the conditions for remission/repayment of the relevant legal basis fulfilled).

<a id="p114295"></a>**TITLE IV. GOODS BROUGHT INTO**
**THE CUSTOMS TERRITORY OF THE UNION**

<a id="p114296"></a>**CHAPTER 1**

<a id="p114297"></a>**ENTRY SUMMARY DECLARATION**

<a id="p114298"></a>Article 182

<a id="p114299"></a>Electronic system relating to entry summary declarations
(Article 16 of the Code)

1. <a id="p114300"></a>An electronic system set up pursuant to Article 16(1) of the Code shall be used for:
<a id="p114301"></a>(a) submitting, processing and storing the particulars of the entry summary declarations and other information relating to those declarations, relating to customs risk analysis for security and safety purposes, including the support of aviation security, and relating to the measures that must be taken based on the results of that analysis;
<a id="p114302"></a>(b) exchanging information concerning the particulars of the entry summary declaration and results of risk analysis of entry summary declarations, concerning other information necessary to perform that risk analysis, and concerning measures undertaken on the basis of risk analysis, including recommendations on places of control and the results of those controls;
<a id="p114303"></a>(c) exchanging information for monitoring and evaluating the implementation of the common safety and security risk criteria and standards and of the control measures and priority control areas referred to in Article 46(3) of the Code.
<a id="p114304"></a>The development and release dates of the sequenced deployment of the system are set out in the project UCC Import Control System 2 (ICS2) in the Annex to Commission Implementing Decision (EU) 2019/2151 <*>.

<a id="p114305"></a>

---

<a id="p114306"></a><*> Commission Implementing Decision (EU) 2019/2151 of 13 December 2019 establishing the work programme relating to the development and deployment of the electronic systems provided for in the Union Customs Code (OJ L 325, 16.12.2019, p. 168).

<a id="p114307"></a>1a. Economic operators shall use an EU harmonised trader interface, designed by the Commission and the Member States in agreement with each other, for submissions, requests for amendments, requests for invalidations, processing and storage of the particulars of entry summary declarations and for the exchange of related information with the customs authorities.
2. <a id="p114308"></a>By way of derogation from paragraph 1 of this Article, until the dates of the deployment of the electronic system referred to therein in accordance with the Annex to Implementing Decision (EU) 2019/2151, the electronic system for the lodging and exchange of information relating to entry summary declarations laid down in Regulation (EEC) No 2454/93 shall be used in accordance with Articles 185(1), 187 and 188(3) of this Regulation.

<a id="p114309"></a>Article 183

<a id="p114310"></a>Lodging of an entry summary declaration
(Article 127(4), (5) and (6) of the Code)

1. <a id="p114311"></a>Where none of the waivers from the obligation to lodge an entry summary declaration in Article 104 of Delegated Regulation (EU) 2015/2446 applies, the particulars of the entry summary declaration shall be provided as follows for goods transported by air:
<a id="p114312"></a>(a) air carriers shall lodge a full entry summary declaration through the electronic system referred to in Article 182(2) until the date set out in accordance with the Annex to Implementing Decision (EU) 2019/2151 for the release 2 of the electronic system referred to in Article 182(1) of this Regulation;
<a id="p114313"></a>(b) express carriers shall lodge the following:
- <a id="p114314"></a>where the intrinsic value of the consignment exceeds EUR 22, a full entry summary declaration through the electronic system referred to in Article 182(2) until the date set out in the Annex to Implementing Decision (EU) 2019/2151 as start date of the deployment window of release 2 of the electronic system referred to in Article 182(1) of this Regulation;
- <a id="p114315"></a>for all consignments, the minimum dataset referred to in Article 106(2) of Delegated Regulation (EU) 2015/2446 through the electronic system referred to in Article 182(1) of this Regulation from the date set out in accordance with the Annex to Implementing Decision (EU) 2019/2151 for the release 1 of that system;
<a id="p114316"></a>(c) postal operators shall lodge the minimum dataset referred to in Article 106(2) of Delegated Regulation (EU) 2015/2446 for consignments having a Member State as final destination, through the electronic system referred to in Article 182(1) of this Regulation, from the date set out in accordance with the Annex to Implementing Decision (EU) 2019/2151 for the release 1 of that system;
<a id="p114317"></a>(d) by the submission of one or more dataset through the electronic system referred to in Article 182(1) of this Regulation, from the date set out in accordance with the Annex to Implementing Decision (EU) 2019/2151 for the deployment of release 2 of that system;
<a id="p114318"></a>1a. Where none of the waivers from the obligation to lodge an entry summary declaration in Article 104 of Delegated Regulation (EU) 2015/2446 applies, for goods transported by sea, inland waterways, road or rail, the particulars of the entry summary declaration shall be provided as follows:
<a id="p114319"></a>(a) by lodging the full entry summary declaration through the electronic system referred to in Article 182(2), until the date set out in accordance with the Annex to Implementing Decision (EU) 2019/2151 for the deployment of release 3 of the electronic system referred to in Article 182(1) of this Regulation;
<a id="p114320"></a>(b) by the submission of one or more dataset through the electronic system referred to in Article 182(1) of this Regulation, from the date set out in accordance with the Annex to Implementing Decision (EU) 2019/2151 for the deployment of release 3 of that system.
2. <a id="p114321"></a>Where the entry summary declaration is lodged by the submission of more than one dataset, or by the submission of the minimum dataset referred to in Article 106(2) and (2a) of Delegated Regulation (EU) 2015/2446, the person submitting the partial or minimum dataset shall do so to the customs office that, according to his/her knowledge, should be the customs office of first entry. If that person does not know the place in the customs territory of the Union at which the means of transport carrying the goods is expected to first arrive, the customs office of first entry may be determined based on the place to which the goods are consigned.

<a id="p114322"></a>Article 184

<a id="p114323"></a>Obligations to inform relating to the provision
of particulars of the entry summary declaration
by persons other than the carrier
(Article 127(6) of the Code)

1. <a id="p114324"></a>From the date set out in accordance with the Annex to Implementing Decision (EU) 2019/2151 for deployment of release 3 of the electronic system referred to in Article 182(1) of this Regulation, in the cases referred to in Article 112(1) of Delegated Regulation (EU) 2015/2446, the carrier and any of the persons issuing a bill of lading shall provide, in the particulars of the entry summary declaration, the identity of any person that has concluded a transport contract with them and has not provided them with the particulars required for the entry summary declaration.
<a id="p114325"></a>Where the consignee indicated in the bill of lading as not having underlying bills of lading does not make the required particulars available to the person issuing the bill of lading, that person shall provide the identity of the consignee in the particulars of the entry summary declaration.
2. <a id="p114326"></a>From the date set out in accordance with the Annex to Implementing Decision (EU) 2019/2151 for deployment of release 3 of the electronic system referred to in Article 182(1) of this Regulation, in the cases referred to in Article 112(1) of Delegated Regulation (EU) 2015/2446, the person issuing the bill of lading shall inform the person that concluded a transport contract with him about the issuance of that bill of lading.
<a id="p114327"></a>In the case of a goods co-loading arrangement, the person issuing the bill of lading shall inform the person with whom he entered into that arrangement of the issuance of that bill of lading.
3. <a id="p114328"></a>From the date set out in accordance with the Annex to Implementing Decision (EU) 2019/2151 for deployment of release 2 of the system referred to in Article 182(1) of this Regulation, in the cases referred to in Article 113(1) of Delegated Regulation (EU) 2015/2446, the carrier and any of the persons issuing an air waybill shall provide, in the particulars of the entry summary declaration, the identity of any person that has concluded a transport contract with them, or issued an air waybill in respect of the same goods, and did not make the particulars required for the entry summary declaration available to them.
4. <a id="p114329"></a>From the date set out in accordance with the Annex to Implementing Decision (EU) 2019/2151 for deployment of release 2 of the electronic system referred to in Article 182(1) of this Regulation, in the cases referred to in Article 113(1) of Delegated Regulation (EU) 2015/2446, the person issuing an air waybill shall inform the person who concluded a transport contract with him of the issuance of that air waybill.
<a id="p114330"></a>In the case of a goods co-loading arrangement, the person issuing the airway bill shall inform the person with whom he entered into that arrangement of the issuance of that airway bill.
5. <a id="p114331"></a>From the date set out in accordance with the Annex to Implementing Decision (EU) 2019/2151 for the deployment of release 2 of the electronic system referred to in Article 182(1) of this Regulation, in the cases referred to in Article 113a(2) and (3) of Delegated Regulation (EU) 2015/2446, the carrier shall provide, in the particulars of the entry summary declaration, the identity of the postal operator, third country postal operator or express carrier who does not make the particulars required for the entry summary declaration available to him or her.
6. <a id="p114332"></a>From the date set out in accordance with the Annex to Implementing Decision (EU) 2019/2151 for the deployment of release 3 of the electronic system referred to in Article 182(1) of this Regulation, in the cases referred to in Article 112a(1) of Delegated Regulation (EU) 2015/2446, the carrier and any of the persons issuing a consignment note shall provide in the particulars of the entry summary declaration, the identity of any person that has concluded a transport contract with them with the particulars required for the entry summary declaration.
7. <a id="p114333"></a>From the date set out in accordance with the Annex to Implementing Decision (EU) 2019/2151 for the deployment of release 3 of the electronic system referred to in Article 182(1) of this Regulation, in the cases referred to in Article 112a(1) of Delegated Regulation (EU) 2015/2446, the person issuing the consignment note shall inform the person that concluded a transport contract with him or her about the issuance of that consignment note.
<a id="p114334"></a>In the case of a goods co-loading arrangement, the person issuing the consignment note shall inform the person with whom he or she entered into that arrangement of the issuance of that consignment note.

<a id="p114335"></a>Article 185

<a id="p114336"></a>Registration of the entry summary declaration
(Article 127(1) of the Code)

1. <a id="p114337"></a>The customs authorities shall register the entry summary declaration upon its receipt and shall immediately notify the declarant or his/her representative of its registration and shall communicate a MRN of the entry summary declaration and the date of registration to that person.
2. <a id="p114338"></a>From the date set out in the Annex to Implementing Decision (EU) 2019/2151 as start date of the deployment window of release 1 of the electronic system referred to Article 182(1) of this Regulation, where the particulars of the entry summary declaration are provided by the submission of at least the minimum dataset referred to in Article 106(2) and (2a) of Delegated Regulation (EU) 2015/2446 or by the submission of more than one dataset, the customs authorities shall:
<a id="p114339"></a>(a) register each of those submissions of particulars of the entry summary declaration upon receipt;
<a id="p114340"></a>(b) immediately notify the person that submitted the dataset about the registration;
<a id="p114341"></a>(c) communicate the MRN of each submission and the date of registration of each submission to that person.
3. <a id="p114342"></a>The customs authorities shall immediately notify the carrier of the registration, provided that the carrier has requested to be notified and has access to the electronic systems referred to in Article 182 of this Regulation, in any of the following cases:
<a id="p114343"></a>(a) where the entry summary declaration is lodged by a person referred to in the second subparagraph of Article 127(4) of the Code;
<a id="p114344"></a>(b) where particulars of the entry summary declaration are provided in accordance with Article 127(6) of the Code.
4. <a id="p114345"></a>The obligation to inform the carrier in the cases referred to in point (b) of paragraph 3 shall apply from the date set out in the Annex to Implementing Decision (EU) 2019/2151 as start date of the deployment window of release 2 of the electronic system referred to in Article 182(1) of this Regulation, provided that the carrier has access to that system.

<a id="p114346"></a>Article 186

<a id="p114347"></a>Risk analysis and controls
relating to the entry summary declarations
(Articles 46(3) and (5), 47(2) and 128 of the Code)

1. <a id="p114348"></a>Risk analysis shall be completed before the arrival of the goods at the customs office of first entry, provided that the entry summary declaration has been lodged within the time limits laid down in Articles 105 to 109 of Delegated Regulation (EU) 2015/2446, unless a risk is identified or an additional risk analysis needs to be carried out.
<a id="p114349"></a>Without prejudice to the first subparagraph, a first risk analysis on goods to be brought into the customs territory of the Union by air shall be carried out as soon as possible upon receipt of the minimum dataset of the entry summary declaration referred to in Article 106(2) and (2a) of Delegated Regulation (EU) 2015/2446.
2. <a id="p114350"></a>The customs office of first entry shall complete the risk analysis primarily for security and safety purposes after the following exchange of information through the system referred to in Article 182(1):
<a id="p114351"></a>(a) Immediately after registration, the customs office of first entry shall make the particulars of the entry summary declaration available to the customs authorities of the Member States indicated in those particulars and to the customs authorities of the other Member States that have recorded in the system information relating to security and safety risks that matches particulars of that entry summary declaration.
<a id="p114352"></a>(b) Within the time-limits laid down in Articles 105 to 109 of Delegated Regulation (EU) 2015/2446, the customs authorities of the Member States referred to in point (a) of this paragraph shall perform a risk analysis primarily for security and safety purposes and, if they identify a risk, they shall make the results available to the customs office of first entry.
<a id="p114353"></a>(c) The customs office of first entry shall take into account the information on risk analysis results provided by the customs authorities of Member States referred in point (a) to complete the risk analysis.
<a id="p114354"></a>(d) The customs office of first entry shall make the results of the completed risk analysis available to the customs authorities of the Member States that contributed to the risk analysis and to those that are potentially concerned by the movement of the goods.
<a id="p114355"></a>(e) The customs office of first entry shall notify the completion of the risk analysis to the following persons, provided that they have requested to be notified and have access to the electronic system referred to in Article 182(1):
<a id="p114356"></a>(i) the declarant or his/her representative;
<a id="p114357"></a>(ii) the carrier, if different from the declarant and his/her representative.
3. <a id="p114358"></a>Where the customs office of first entry requires further information on the particulars of the entry summary declaration for the completion of the risk analysis, that analysis shall be completed after that information has been provided.
<a id="p114359"></a>For those purposes, the customs office of first entry shall request that information from the person that lodged the entry summary declaration or, where applicable, the person that submitted the particulars of the entry summary declaration. Where that person is different from the carrier, the customs office of first entry shall inform the carrier, provided that the carrier has requested to be notified and has access to the electronic system referred to in Article 182(1).
4. <a id="p114360"></a>Where the customs office of first entry has reasonable grounds to suspect that goods brought by air could pose a serious aviation security threat, it shall require that the consignment, before being loaded on an aircraft bound for the customs territory of the Union, be screened as High Risk Cargo and Mail in accordance with point 6.7 of the Annex to Commission Implementing Regulation (EU) 2015/1998 <*> and point 6.7.3 of the Annex to Commission Implementing Decision C(2015)8005 final of 16 November 2015 laying down detailed measures for the implementation of the common basic standards on aviation security containing information, as referred to in point (a) of Article 18 of Regulation (EC) No 300/2008.

<a id="p114361"></a>

---

<a id="p114362"></a><*> Commission Implementing Regulation (EU) 2015/1998 of 5 November 2015 laying down detailed measures for the implementation of the common basic standards on aviation security (OJ L 299 14.11.2015, p. 1).

<a id="p114363"></a>The customs office of first entry shall notify the following persons, provided that they have access to the electronic system referred to in Article 182(1) of this Regulation:
<a id="p114364"></a>(a) the declarant or his/her representative;
<a id="p114365"></a>(b) the carrier, if different from the declarant and his/her representative.
<a id="p114366"></a>Following that notification, the person who lodged the entry summary declaration, or where applicable, the person that submitted the particulars of the entry summary declaration shall provide the customs office of first entry with the results of that screening and with all other related relevant information. The risk analysis shall only be completed after that information has been provided.
5. <a id="p114367"></a>Where the customs office of first entry has reasonable grounds to consider that goods brought by air or containerised cargo brought by sea, as referred to in Article 105(a) of Delegated Regulation (EU) 2015/2446, would pose such a serious threat to security and safety that immediate action is required, it shall direct that the goods not be loaded on the relevant means of transport.
<a id="p114368"></a>The customs office of first entry shall notify the following persons, provided that they have access to the electronic system referred to in Article 182(1) of this Regulation:
<a id="p114369"></a>(a) the declarant or his/her representative;
<a id="p114370"></a>(b) the carrier, if different from the declarant and his/her representative.
<a id="p114371"></a>That notification shall be made immediately after the detection of the relevant risk and, in the case of containerised cargo brought by sea as referred to in Article 105(a) of Delegated Regulation (EU) 2015/2446, at the latest within 24 hours of the receipt of the entry summary declaration or, where applicable, of the particulars of the entry summary declaration by the carrier.
<a id="p114372"></a>The customs office of first entry shall also immediately inform the customs authorities of all Member States of that notification and make the relevant particulars of the entry summary declaration available to them.
6. <a id="p114373"></a>Where a consignment has been identified as posing a threat of such nature that immediate action is required upon arrival of the means of transport, the customs office of first entry shall take that action upon arrival of the goods.
7. <a id="p114374"></a>After completing the risk analysis, the customs office of first entry may recommend, through the electronic system referred to in Article 182(1), the most appropriate place and measures to carry out a control.
<a id="p114375"></a>The customs office competent for the place that has been recommended as the most appropriate for control shall decide on the control and shall make through the electronic system referred to in Article 182(1) the results of that decision available to all the customs offices potentially concerned by the movement of goods, at the latest at the moment of presentation of the goods at the customs office of first entry.
<a id="p114376"></a>7a. In the cases referred to in Article 46(5) and Article 47(2) of the Code, the customs offices shall make the results of their customs controls available to other customs authorities of the Member States through the electronic system referred to in Article 182(1) of this Regulation, and shall exchange risk relevant information through the system referred in Article 36 of this Regulation.
8. <a id="p114377"></a>Where goods for which the obligation to lodge an entry summary declaration is waived in accordance with points (c) to (k), (m) and (n) of Article 104(1) and Article 104(2) to (4) of Delegated Regulation (EU) 2015/2446 are brought into the customs territory of the Union, the risk analysis shall be carried out upon the presentation of the goods.
9. <a id="p114378"></a>Goods presented to customs may be released for a customs procedure or re-exported as soon as the risk analysis has been carried out, and the results of the risk analysis and, where required, the measures taken, allow such a release.
10. <a id="p114379"></a>Risk analysis shall also be carried out if the particulars of the entry summary declaration are amended in accordance with Article 129 of the Code. In that case, without prejudice to the time-limit laid down in the third subparagraph of paragraph 5 of this Article for containerised cargo brought by sea, the risk analysis shall be completed immediately upon receipt of the particulars unless a risk is identified or an additional risk analysis needs to be carried out.

<a id="p114380"></a>Article 187

<a id="p114381"></a>Transitional rules for risk analysis
(Article 128 of the Code)

1. <a id="p114382"></a>By way of derogation from Article 186 of this Regulation, until the dates set out in accordance with the Annex to Implementing Decision (EU) 2019/2151 for deployment of the electronic system referred to in Article 182(1) of this Regulation, the risk analysis shall be based on the information in the entry summary declarations lodged and exchanged in the electronic system referred in Article 182(2) of this Regulation, in accordance with the rules in this Article.
2. <a id="p114383"></a>Risk analysis shall be carried out before the arrival of the goods at the customs office of first entry provided that the entry summary declaration has been lodged within the time-limits laid down in Articles 105 to 109 of Delegated Regulation (EU) 2015/2446 unless a risk is identified.
3. <a id="p114384"></a>In case of containerised cargo brought into the customs territory of the Union by sea as referred to in Article 105(a) of Delegated Regulation (EU) 2015/2446, the customs authorities shall complete the risk analysis within 24 hours of the receipt of the entry summary declaration. Where that analysis provides reasonable grounds for the customs authorities to consider that the entry of the goods into the customs territory of the Union would pose such a serious threat to security and safety that immediate action is required, the customs authorities shall notify the person who lodged the entry summary declaration, and, where that person is different from the carrier, inform the carrier provided that the carrier has access to the electronic system referred to in Article 182 of this Regulation, that the goods are not to be loaded. That notification shall be made and that information shall be provided immediately after the detection of the relevant risk and within 24 hours of receipt of the entry summary declaration.
4. <a id="p114385"></a>Where a vessel or aircraft is to call at more than one port or airport in the customs territory of the Union, provided that it moves between those ports without calling at any port or airport outside the customs territory of the Union the following applies:
<a id="p114386"></a>(a) for all the goods carried by the vessel or aircraft concerned, an entry summary declaration shall be lodged at the first Union port or airport. The customs authorities at that port or airport shall carry out the risk analysis for security and safety purposes for all the goods carried by the vessel or aircraft concerned. Additional risk analyses may be carried out for those goods at the port or airport at which they are discharged;
<a id="p114387"></a>(b) in the case of consignments identified as posing a threat of such a serious nature that immediate intervention is required, the customs office of the first port or airport of entry in the Union shall take prohibitive action, and, in any case, pass on the results of the risk analysis to the subsequent ports or airports; and
<a id="p114388"></a>(c) at subsequent ports or airports in the customs territory of the Union, Article 145 of the Code shall apply for goods presented to customs at that port or airport.
5. <a id="p114389"></a>Where goods for which the obligation to lodge an entry summary declaration is waived in accordance with points (c) to (k), (m) and (n) of Article 104(1) and Article 104(2) to (4) of Delegated Regulation (EU) 2015/2446 are brought into the customs territory of the Union, the risk analysis shall be carried out upon presentation of the goods, where available, on the basis of the temporary storage declaration or the customs declaration covering those goods.
6. <a id="p114390"></a>Goods presented to customs may be released for a customs procedure or re-exported as soon as the risk analysis has been carried out and the results of the risk analysis and, where required, the measures taken, allow such a release.
7. <a id="p114391"></a>Risk analysis shall also be carried out if the particulars of the entry summary declaration are amended in accordance with Article 129 of the Code. In that case, without prejudice to the time-limit laid down in paragraph 3 of this Article for containerised cargo brought by sea, the risk analysis shall be completed immediately upon receipt of the particulars unless a risk is identified or an additional risk analysis needs to be carried out.

<a id="p114392"></a>Article 188

<a id="p114393"></a>Amendment and invalidation of an entry summary declaration
(Article 129(1) of the Code)

1. <a id="p114394"></a>The electronic system referred to in Article 182(1) shall be used for lodging a request for amendment or invalidation of an entry summary declaration or of the particulars therein.
<a id="p114395"></a>Where different persons request an amendment or an invalidation of the particulars of the entry summary declaration, each of those persons shall only be permitted to request the amendment or invalidation of the particulars that he/she submitted.
2. <a id="p114396"></a>The customs authorities shall immediately notify the person who lodged the request for amendment or invalidation of their decision to register it or reject it.
<a id="p114397"></a>Where the amendments to or invalidation of the particulars of the entry summary declaration are lodged by a person different from the carrier, the customs authorities shall also notify the carrier, provided that the carrier has requested to be notified and has access to the electronic system referred to in Article 182(1).
3. <a id="p114398"></a>By way of derogation from paragraph 1 of this Article, Member States may allow that requests for amending or invalidating the particulars of an entry summary declaration that has been lodged using the electronic system referred to in Article 182(2) are made using means other than the electronic data-processing techniques referred to in Article 6(1) of the Code.

<a id="p114399"></a>**CHAPTER 2**

<a id="p114400"></a>**ARRIVAL OF GOODS**

<a id="p114401"></a>Section 1. ENTRY OF GOODS INTO THE CUSTOMS
**TERRITORY OF THE UNION**

<a id="p114402"></a>Article 189

<a id="p114403"></a>Diversion of a sea-going vessel or aircraft entering the custom territory of the Union
(Article 133 of the Code)

1. <a id="p114404"></a>Where, after having lodged the entry summary declaration through the electronic system referred to in Article 182(2), a sea-going vessel or an aircraft is diverted and is expected to arrive in the first place at a customs office located in a Member State that was not indicated as a country of routing in the entry summary declaration, the operator of that means of transport shall inform the customs office indicated as the customs office of first entry in the entry summary declaration of that diversion and shall lodge the arrival notification to the actual customs office of first entry.
<a id="p114405"></a>The first subparagraph of this Article shall not apply where goods have been brought into the customs territory of the Union under a transit procedure in accordance with Article 141 of the Code.
2. <a id="p114406"></a>The customs office indicated in the entry summary declaration as the customs office of first entry shall immediately after being informed in accordance with paragraph 1 notify the customs office which according to that information is the customs office of first entry of the diversion. It shall ensure the availability of the relevant particulars of the entry summary declaration and of the results of the risk analysis to the customs office of first entry.
3. <a id="p114407"></a>From the date set out in the Annex to Implementing Decision (EU) 2019/2151 as start date of the deployment window of release 2 of the electronic system referred to in Article 182(1) of this Regulation, where an aircraft is diverted and has arrived in the first place at a customs office located in a Member State that was not indicated as a country of routing in the entry summary declaration, the actual customs office of first entry shall, through that system, retrieve the particulars of the entry summary declaration, the risk-analysis results and the control recommendations made by the expected customs office of first entry.
4. <a id="p114408"></a>From the date set out in the Annex to Implementing Decision (EU) 2019/2151 as start date of the deployment window of release 3 of the electronic system referred to in Article 182(1) of this Regulation, where a sea-going vessel is diverted and has arrived in the first place at a customs office located in a Member State that was not indicated as a country of routing in the entry summary declaration, the actual customs office of first entry shall, through that system, retrieve the particulars of the entry summary declaration, the risk-analysis results and the control recommendations made by the expected customs office of first entry.

<a id="p114409"></a>Section 2. PRESENTATION, UNLOADING AND EXAMINATION OF GOODS

<a id="p114410"></a>Article 190

<a id="p114411"></a>Presentation of goods to customs
(Article 139 of the Code)

<a id="p114412"></a>Customs authorities may accept use of port or airport systems or other available methods of information for the presentation of goods to customs.

<a id="p114413"></a>Section 3. TEMPORARY STORAGE OF GOODS

<a id="p114414"></a>Article 191

<a id="p114415"></a>Consultation procedure between customs authorities prior to
authorising temporary storage facilities
(Article 22 of the Code)

1. <a id="p114416"></a>The consultation procedure referred to in Article 14 of this Regulation shall be followed in accordance with paragraphs 2 and 3 of this Article before a decision is taken to authorise the operation of temporary storage facilities involving more than one Member State unless the customs authority competent to take the decision is of the opinion that the conditions for granting such an authorisation are not fulfilled.
<a id="p114417"></a>Before issuing an authorisation the customs authority competent to take the decision shall obtain the agreement of the consulted customs authorities.
2. <a id="p114418"></a>The customs authority competent to take the decision shall communicate the application and the draft authorisation to the consulted customs authorities at the latest 30 days after the date of acceptance of the application.
3. <a id="p114419"></a>The consulted customs authorities shall communicate their objections or agreement within 30 days after the date on which the draft authorisation was communicated to them. Objections shall be duly justified.
<a id="p114420"></a>Where objections are communicated within that period and no agreement is reached among the consulted and consulting authorities within 60 days after the date on which the draft authorisation was communicated, the authorisation shall only be granted for the part of the application that has not given rise to objections.
<a id="p114421"></a>If the consulted customs authorities do not communicate any objections within the time-limit, their agreement shall be deemed to be given.

<a id="p114422"></a>Article 192

<a id="p114423"></a>Temporary storage declaration
(Article 145 of the Code)

<a id="p114424"></a>Where a customs declaration is lodged prior to the expected presentation of the goods to customs in accordance with Article 171 of the Code, the customs authorities may consider that declaration as a temporary storage declaration.

<a id="p114425"></a>Article 193

<a id="p114426"></a>Movement of goods in temporary storage
(Article 148(5) of the Code)

1. <a id="p114427"></a>Where the movement takes place between temporary storage facilities under the responsibility of different customs authorities the holder of the authorisation for the operation of the temporary storage facilities from which the goods are moved shall inform:
<a id="p114428"></a>(a) the customs authority responsible for supervising the temporary storage facility from which the goods are moved of the intended movement in the manner stipulated in the authorisation and, upon arrival of the goods at the temporary storage facilities of destination, about the completion of the movement in the manner stipulated in the authorisation;
<a id="p114429"></a>(b) the holder of the authorisation for the facilities to which the goods are moved that the goods have been dispatched.
2. <a id="p114430"></a>Where the movement takes place between temporary storage facilities under the responsibility of different customs authorities, the holder of the authorisation for the facilities to which the goods are moved shall:
<a id="p114431"></a>(a) notify the customs authorities responsible for those facilities of the arrival of the goods; and
<a id="p114432"></a>(b) upon arrival of the goods at the temporary storage facilities of destination, inform the holder of the authorisation of the temporary storage facilities of departure.
3. <a id="p114433"></a>The information referred to in paragraph 1 and 2 shall include a reference to the relevant temporary storage declaration and to the end date of temporary storage.
4. <a id="p114434"></a>Where a movement of goods in temporary storage takes place, the goods shall remain under the responsibility of the holder of the authorisation for the operation of temporary storage facilities from which the goods are moved until the goods are entered in the records of the holder of the authorisation for the temporary storage facilities to which the goods are moved unless otherwise provided in the authorisation.

<a id="p114435"></a>**TITLE V. GENERAL RULES ON CUSTOMS STATUS, PLACING GOODS**
**UNDER A CUSTOMS PROCEDURE, VERIFICATION, RELEASE AND**
**DISPOSAL OF GOODS**

<a id="p114436"></a>**CHAPTER 1**

<a id="p114437"></a>**CUSTOMS STATUS OF GOODS**

<a id="p114438"></a>Article 194

<a id="p114439"></a>Electronic system relating to the proof
of the customs status of Union goods
(Article 16(1) of the Code)

<a id="p114440"></a>For the exchange and storage of information relating to the proof of the customs status of Union goods, provided for in Article 199(1)(b) and (c) of this Regulation, an electronic system set up pursuant to Article 16(1) of the Code shall be used. An EU harmonised trader interface designed by the Commission and the Member States in agreement with each other shall be used for the exchange of information relating to the proof of the customs status of Union goods.
<a id="p114441"></a>The first paragraph of this Article shall be applicable from the date of deployment of the UCC Proof of Union Status system referred to in the Annex to Implementing Decision 2014/255/EU.

<a id="p114442"></a>Section 1. REGULAR SHIPPING SERVICE

<a id="p114443"></a>Article 195

<a id="p114444"></a>Consultation of the Member States concerned
by the regular shipping service
(Article 22 of the Code)

<a id="p114445"></a>Before granting an authorisation referred to in Article 120 of Delegated Regulation (EU) 2015/2446, after having examined whether the conditions laid down in Article 120(2) of that Delegated Regulation for the authorisation are met, the customs authority competent to take the decision shall consult the customs authorities of the Member States concerned by the regular shipping service for the purpose of Article 119(2)(b) of that Delegated Regulation as well as the customs authorities of any other Member States for which the applicant declares to have plans for future regular shipping services, on the fulfilment of the condition of Article 120(2)(b) of that Delegated Regulation.
<a id="p114446"></a>The time-limit for the consultation shall be 15 days from the date of communication by the customs authority competent to take the decision of the conditions and criteria which need to be examined by the consulted customs authorities.

<a id="p114447"></a>Article 196

<a id="p114448"></a>Registration of vessels and ports
(Article 22 of the Code)

<a id="p114449"></a>By way of derogation from the time-limit laid down in the first paragraph of Article 10 of this Regulation, a customs authority shall make the information communicated to it in accordance with Article 121(1) of Delegated Regulation (EU) 2015/2446 available through the system referred to in Article 10 within 1 working day of the communication of that information.
<a id="p114450"></a>Until the date of deployment of the UCC Customs Decision system referred to in the Annex to the Implementing Decision 2014/255/EU, the information referred to in the first paragraph is to be made available through the electronic regular shipping services information and communication system.
<a id="p114451"></a>That information shall be accessible to the customs authorities concerned by the authorised regular shipping service.

<a id="p114452"></a>Article 197

<a id="p114453"></a>Unforeseen circumstances during
the transport by regular shipping services
(Article 155(2) of the Code)

<a id="p114454"></a>Where a vessel registered to a regular shipping service, as a result of unforeseen circumstances, tranships goods at sea, calls at or loads or unloads goods in a port outside the customs territory of the Union, in a port that is not part of the regular shipping service or in a free zone of a Union port, the shipping company shall inform the customs authorities of the subsequent Union ports of call, including those along the scheduled route of that vessel, without delay.
<a id="p114455"></a>The date the vessel resumes its operation in the regular shipping service shall be communicated to those customs authorities in advance.

<a id="p114456"></a>Article 198

<a id="p114457"></a>Verification of conditions for regular shipping services
(Article 153 of the Code)

1. <a id="p114458"></a>The customs authorities of the Member States may require evidence from the shipping company that the provisions of Articles 120(2)(c) and (d) and (3) and 121(1) and (3) of Delegated Regulation (EU) 2015/2446 and of Article 197 of this Regulation have been observed.
2. <a id="p114459"></a>Where a customs authority establishes that the provisions referred to in paragraph 1 have not been observed by the shipping company, the authority shall immediately inform the customs authorities of the other
<a id="p114460"></a>Member States in which the regular shipping service is operated, using the system referred to in Article 10 of this Regulation. Those authorities shall take the measures required.
<a id="p114461"></a>Until the UCC Customs Decision system referred to in the Annex to the Implementing Decision 2014/255/EU is deployed, the electronic regular shipping services information and communication system shall be used instead of the system referred to in Article 10 of this Regulation.

<a id="p114462"></a>Section 2. PROOF OF CUSTOMS STATUS OF UNION GOODS

<a id="p114463"></a>Subsection 1

<a id="p114464"></a>**GENERAL PROVISIONS**

<a id="p114465"></a>Article 199

<a id="p114466"></a>Means of proof of the customs status of Union goods
(Article 153(2) of the Code)

1. <a id="p114467"></a>Any of the following means, as applicable, shall be used to prove that the goods have the customs status of Union goods:
<a id="p114468"></a>(a) the transit declaration data of goods placed under internal transit. In that case Article 119(3) of Delegated Regulation (EU) 2015/2446 does not apply;
<a id="p114469"></a>(b) T2L or T2LF data referred to in Article 205 of this Regulation;
<a id="p114470"></a>(c) the customs goods manifest referred to in Article 206 of this Regulation;
<a id="p114471"></a>(d) the invoice or transport document referred to in Article 211 of this Regulation;
<a id="p114472"></a>(e) the fishing logbook, landing declaration, transhipment declaration and vessel monitoring system data, as appropriate, referred to in Article 213 of this Regulation;
<a id="p114473"></a>(f) a means of proof referred to in Articles 207 to 210 of this Regulation;
<a id="p114474"></a>(g) the excise declaration data referred to in Articles 21, 26 and 34 of Council Directive 2008/118/EC <*>;

<a id="p114475"></a>

---

<a id="p114476"></a><*> Council Directive 2008/118/EC of 16 December 2008 concerning the general arrangements for excise duty and repealing Directive 92/12/EEC (OJ L 9, 14.1.2009, p. 12).

<a id="p114477"></a>(h) the label referred to in Article 290 of this Regulation.
2. <a id="p114478"></a>By derogation from paragraph 1 of this Article, until the date of deployment of the UCC Proof of Union Status system referred to in the Annex to the Implementing Decision 2014/255/EU, the proof of the customs status of Union goods may be provided in the form of the shipping company's manifest relating to those goods.
3. <a id="p114479"></a>By derogation from paragraph 1(d) of this Article, until the date of deployment of the UCC Proof of Union Status system referred to in the Annex to the Implementing Decision 2014/255/EU, the proof of the customs status of Union goods may be provided in the form of an invoice or transport document relating to goods the value of which exceeds EUR 15 000.
4. <a id="p114480"></a>Where the means of proof referred to in paragraph 1 is used for goods with the customs status of Union goods with a packaging not having the customs status of Union goods, that means of proof shall include the following indication:
<a id="p114481"></a>"N packaging - [code 98200]"
5. <a id="p114482"></a>Where the means of proof referred to in paragraph 1(b), (c) and (d) is issued retrospectively, it shall include the following indication:
<a id="p114483"></a>"Issued retrospectively - [code 98201]"
6. <a id="p114484"></a>The means of proof referred to in paragraph 1 shall not be used in respect of goods for which the export formalities have been completed or which have been placed under the outward processing procedure.

<a id="p114485"></a>Article 200

<a id="p114486"></a>Endorsement, registration and use of certain means of proof
of the customs status of Union goods
(Article 153(2) of the Code)

1. <a id="p114487"></a>The competent customs office shall endorse and register the means of proof of the customs status of Union goods referred to in Article 199(1)(b) and (c) of this Regulation, except for cases referred to in Article 128(1) of Delegated Regulation (EU) 2015/2446, and communicate the MRN of those means of proof to the person concerned.
2. <a id="p114488"></a>A document confirming the registration of the means of proof referred to in paragraph 1 shall be made available at the request of the person concerned by the competent customs office. It shall be provided using the form set out in Annex 51-01.
3. <a id="p114489"></a>The means of proof referred to in paragraph 1 shall be presented to the competent customs office where the goods are presented after reentering the customs territory of the Union, by indicating its MRN.
4. <a id="p114490"></a>That competent customs office shall monitor the use of the means of proof referred to in paragraph 1 with a view to ensure in particular that the means of proof is not used for goods other than those for which it is issued.

<a id="p114491"></a>Article 201

<a id="p114492"></a>Endorsement of an invoice
(Article 153(2) of the Code)

<a id="p114493"></a>Until the date of deployment of the UCC Proof of Union Status system referred to in the Annex to Implementing Decision 2014/255/EU, where the total value of the Union goods exceeds EUR 15 000 the invoice or transport document referred to in Article 199(3) of this Regulation, duly completed and signed by the person concerned, shall be endorsed by the competent customs office.

<a id="p114494"></a>Article 202

<a id="p114495"></a>Endorsement of T2L or T2LF documents
(Article 153(2) of the Code)

<a id="p114496"></a>Until the date of deployment of the UCC Proof of Union Status system referred to in the Annex to Implementing Decision 2014/255/EU, where Member States have provided that means other than electronic data processing techniques may be used, the competent customs office shall endorse the T2L or T2LF documents and, where necessary, any continuation sheets or loading lists used.

<a id="p114497"></a>Article 203

<a id="p114498"></a>Endorsement of the shipping company's manifest
(Article 153(2) of the Code)

<a id="p114499"></a>Until the date of deployment of the UCC Proof of Union Status system referred to in the Annex to Implementing Decision 2014/255/EU, at the request of the shipping company, the manifest it has duly completed and signed shall be endorsed by the competent customs office.

<a id="p114500"></a>Article 204

<a id="p114501"></a>Authorisation "day-after" manifest
(Article 153(2) of the Code)

<a id="p114502"></a>Until the date of deployment of the UCC Proof of Union Status system referred to in the Annex to Implementing Decision 2014/255/EU, the customs authorities may authorise the manifest referred to in Article 199(2) serving to demonstrate the customs status of Union goods to be drawn up the day after the departure of the vessel, at the latest. However, the manifest shall always be drawn up before the arrival of the vessel at the port of destination.

<a id="p114503"></a>Article 205

<a id="p114504"></a>Proof of the customs status
of Union goods in the form of T2L or T2LF data
(Article 153(2) of the Code)

1. <a id="p114505"></a>Where the MRN is indicated to prove the customs status as Union goods, the T2L or T2LF data serving as the basis for the MRN may only be used for the first presentation of the goods.
<a id="p114506"></a>Where the T2L or T2LF is used only for a part of the goods upon their first presentation, a new proof shall be established for the remaining part of the goods in accordance with Article 200 of this Regulation and Article 123 of Delegated Regulation (EU) 2015/2446.
2. <a id="p114507"></a>Travellers, other than economic operators, shall lodge their requests for endorsement of a T2L or T2LF using the form set out in Annex 51-01.

<a id="p114508"></a>Article 206

<a id="p114509"></a>Proof of the customs status of Union
goods in the form of a customs goods manifest
(Article 153(2) of the Code)

1. <a id="p114510"></a>Each customs goods manifest shall be attributed one MRN.
<a id="p114511"></a>Such a manifest may only be attributed a MRN where it coversgoods having the customs status of Union goods loaded on the vessel in a Union port.
2. <a id="p114512"></a>Customs authorities may accept that commercial, port or transport information systems are used for submission of the request for endorsement and registration of the customs goods manifest and for its presentation at the competent customs office, provided that such systems contain all the information required for such manifest.

<a id="p114513"></a>Article 207

<a id="p114514"></a>Proof of the customs status of Union
goods in TIR or ATA carnets or forms 302
(Article 6(3) and 153(2) of the Code)

1. <a id="p114515"></a>In accordance with Article 127 of Delegated Regulation (EU) 2015/2446, Union goods shall be identified in the TIR or ATA carnet or in the NATO form 302 or in the EU form 302 by the code "T2L" or "T2LF". The holder of the procedure may include one of those codes, as appropriate, accompanied by his signature in the relevant documents in the space reserved for the description of goods before presenting it to the customs office of departure for authentication. The appropriate code "T2L" or "T2LF" shall be authenticated with the stamp of the customs office of departure accompanied by the signature of the competent official.
<a id="p114516"></a>In case of an electronic NATO form 302 or an electronic EU form 302, the holder of the procedure may also include one of these codes in the form 302 data. In that case, the authentication by the office of departure shall be done in electronic form.
2. <a id="p114517"></a>When the TIR carnet, the ATA carnet, the NATO form 302 or the EU form 302 covers both Union goods and non-Union goods, they shall be listed separately and the code "T2L" or "T2LF", as appropriate, shall be entered in such a way that it clearly relates only to Union goods.

<a id="p114518"></a>Article 208

<a id="p114519"></a>Proof of the customs status
of Union goods for motorised road vehicles
(Article 153(2) of the Code)

1. <a id="p114520"></a>In case of motorised road vehicles registered in a Member State which have temporarily left and re-entered the customs territory of the Union the customs status of Union goods shall be considered proven where they are accompanied by their registration plates and registration documents and the registration particulars shown on those plates and documents unambiguously indicate that registration.
2. <a id="p114521"></a>Where the customs status of Union goods cannot be considered proven in accordance with paragraph 1, the proof of the customs status of Union goods shall be provided by one of the other means listed in Article 199 of this Regulation.

<a id="p114522"></a>Article 209

<a id="p114523"></a>Proof of the customs status of Union goods for packaging
(Article 153(2) of the Code)

1. <a id="p114524"></a>In case of packaging, pallets and other similar equipment, excluding containers, belonging to a person established in the customs territory of the Union which are used for the transport of goods that have temporarily left and re-entered the customs territory of the Union, the customs status of Union goods shall be considered proven where the packaging, pallets and other similar equipment can be identified as belonging to that person, they are declared as having the customs status of Union goods and there is no doubt as to the veracity of the declaration.
2. <a id="p114525"></a>Where the customs status of Union goods cannot be considered proven in accordance with paragraph 1, the proof of the customs status of Union goods shall be provided by one of the other means listed in Article 199 of this Regulation.

<a id="p114526"></a>Article 210

<a id="p114527"></a>Proof of the customs status of Union goods
for goods in baggage carried by a passenger
(Article 153(2) of the Code)

<a id="p114528"></a>In case of goods in baggage carried by a passenger which are not intended for commercial use and have temporarily left and re-entered the customs territory of the Union the customs status of Union goods shall be considered to be proven where the passenger declares that they have the customs status of Union goods and there is no doubt as to the veracity of the declaration.

<a id="p114529"></a>Article 211

<a id="p114530"></a>Proof of the customs status of Union goods for goods the
value of which does not exceed EUR 15 000
(Article 153(2) of the Code)

<a id="p114531"></a>In case of goods having the customs status of Union goods the value of which does not exceed EUR 15 000, the customs status of Union goods may be proven by the production of the invoice or transport document relating to those goods provided that it relates only to goods having the customs status of Union goods.

<a id="p114532"></a>Article 212

<a id="p114533"></a>Verification of means of proof and administrative assistance
(Article 153(2) of the Code)

<a id="p114534"></a>The customs authorities of the Member States shall assist one another in checking the authenticity and accuracy of the means of proof referred to in Article 199 of this Regulation and in verifying that the information and documents provided in accordance with the provisions of this Title and Articles 123 to 133 of Delegated Regulation (EU) 2015/2446 are correct and that the procedures used to prove the customs status of Union goods have been correctly applied.

<a id="p114535"></a>Subsection 2

<a id="p114536"></a>**SPECIFIC PROVISIONS CONCERNING PRODUCTS OF SEA-FISHING AND**
**GOODS OBTAINED FROM SUCH PRODUCTS**

<a id="p114537"></a>Article 213

<a id="p114538"></a>Proof of the customs status of Union goods for products
of sea-fishing and goods obtained from such products
(Article 153(2) of the Code)

<a id="p114539"></a>Where products and goods referred to in Article 119(1)(d) and (e) of Delegated Regulation (EU) 2015/2446 are brought into the customs territory of the Union in accordance with Article 129 of that Delegated Regulation, the customs status of Union goods shall be proven by the production of a fishing logbook, a landing declaration, transhipment declaration and vessel monitoring system data, as appropriate, as required in accordance with Council Regulation (EC) No 1224/2009 <*>.

<a id="p114540"></a>

---

<a id="p114541"></a><*> Council Regulation (EC) No 1224/2009 of 20 November 2009 establishing a Community control system for ensuring compliance with the rules of the common fisheries policy, amending Regulations (EC) No 847/96, (EC) No 2371/2002, (EC) No 811/2004, (EC) No 768/2005, (EC) No 2115/2005, (EC) No 2166/2005, (EC) No 388/2006, (EC) No 509/2007, (EC) No 676/2007, (EC) No 1098/2007, (EC) No 1300/2008, (EC) No 1342/2008 and repealing Regulations (EEC) No 2847/93, (EC) No 1627/94 and (EC) No 1966/2006 (OJ L 343, 22.12.2009, p. 1).

<a id="p114542"></a>However, the customs authority which is responsible for the Union port of unloading to which those products and goods are directly transported by the Union fishing vessel which caught the products and, where applicable, processed them, may consider the customs status of Union goods to be proven in either of the following cases:
<a id="p114543"></a>(a) there is no doubt about the status of those products and/or goods;
<a id="p114544"></a>(b) the fishing vessel has an overall length of less than 10 metres.


<a id="p114545"></a>Article 214

<a id="p114546"></a>Products of sea-fishing
and goods obtained from such products transhipped
and transported through a country or territory which
is not part of the customs territory of the Union
(Article 153(2) of the Code)

1. <a id="p114547"></a>Where, before arriving to the customs territory of the Union, the products or goods referred to in points (d) and (e) of Article 119(1) of Delegated Regulation (EU) 2015/2446 have been transhipped and transported through a country or territory which is not part of the customs territory of the Union, a certification by the customs authority of that country or territory that the products or goods were under customs supervision while in that country or territory and have undergone no handling other than that necessary for their preservation shall be presented for those products and goods on their entry into the customs territory of the Union.
2. <a id="p114548"></a>The certification required in accordance with paragraph 1 shall be made out on a printout of the fishing logbook referred to in Article 133 of Delegated Regulation (EU) 2015/2446, accompanied by a printout of the transhipment declaration, as appropriate.
3. <a id="p114549"></a>The certification required in accordance with paragraph 1 may be provided by any relevant forms or documents other than on a printout of a fishing logbook including a reference to that fishing logbook.

<a id="p114550"></a>Article 215

<a id="p114551"></a>Proof of the customs status
of Union goods for products of sea-fishing and other
products taken or caught by vessels flying the flag of a
third country within the customs territory of the Union
(Article 153(2) of the Code)

<a id="p114552"></a>The proof of the customs status of Union goods for products of sea-fishing and other products taken or caught by vessels flying the flag of a third country within the customs territory of the Union shall be provided by means of the fishing logbook or any other means referred to in Article 199 of this Regulation.

<a id="p114553"></a>**CHAPTER 2**

<a id="p114554"></a>**PLACING GOODS UNDER A CUSTOMS PROCEDURE**

<a id="p114555"></a>Section 1. GENERAL PROVISIONS

<a id="p114556"></a>Article 216

<a id="p114557"></a>Electronic system relating
to placing goods under a customs procedure
(Article 16(1) of the Code)

<a id="p114558"></a>For the processing and exchange of information relating to the placing of goods under a customs procedure, electronic systems set up pursuant to Article 16(1) of the Code shall be used.
<a id="p114559"></a>The first paragraph of this Article shall be applicable from the respective dates of the upgrading of the national import Systems, the deployment of the UCC Special Procedures and UCC AES referred to in the Annex to Implementing Decision 2014/255/EU.

<a id="p114560"></a>Article 217

<a id="p114561"></a>Issuing of receipt for oral declarations
(Article 158(2) of the Code)

<a id="p114562"></a>Where a customs declaration is made orally in accordance with Articles 135 or 137 of Delegated Regulation (EU) 2015/2446 for goods which are subject to import or export duty or other charges, the customs authorities shall issue a receipt to the person concerned against payment of the amount due for that duty or those charges.
<a id="p114563"></a>The receipt shall include at least the following information:
<a id="p114564"></a>(a) a description of the goods which is sufficiently precise to enable the goods to be identified;
<a id="p114565"></a>(b) the invoice value or, where it is not available, the quantity of the goods;
<a id="p114566"></a>(c) the amounts of duty and other charges collected;
<a id="p114567"></a>(d) the date on which it was issued;
<a id="p114568"></a>(e) the name of the authority which issued it.

<a id="p114569"></a>Article 218

<a id="p114570"></a>Customs formalities deemed to have been carried
out by an act referred to in Article 141(1), (2), (4), (4a),
(5) and (6) to (8) of Delegated Regulation (EU) 2015/2446
(Articles 6(3)(a), 139, 158(2), 172, 194 and 267 of the Code)

<a id="p114571"></a>For the purposes of Articles 138, 139 and 140 of Delegated Regulation (EU) 2015/2446, the following customs formalities, as applicable, shall be deemed to have been carried out by an act referred to in Article 141(1), (2), (4), (4a), (5), and (6) to (8) of that Delegated Regulation:
<a id="p114572"></a>(a) the conveying of the goods in accordance with Article 135 of the Code and the presenting of the goods to customs in accordance with Article 139 of the Code;
<a id="p114573"></a>(b) the presenting of the goods to customs in accordance with Article 267 of the Code;
<a id="p114574"></a>(c) the acceptance of the customs declaration by the customs authorities in accordance with Article 172 of the Code;
<a id="p114575"></a>(d) the release of the goods by the customs authorities in accordance with Article 194 of the Code.

<a id="p114576"></a>Article 219

<a id="p114577"></a>Cases where a customs declaration is not considered
to have been lodged by an act referred to in Article 141
of Delegated Regulation (EU) 2015/2446
(Articles 6(3)(a) and 158(2) of the Code)

<a id="p114578"></a>Where a check reveals that an act referred to in Article 141 of Delegated Regulation (EU) 2015/2446 has been carried out but the goods brought into or taken out are not goods as referred to in Articles 138, 139 and 140 of that Delegated Regulation, the customs declaration for those goods shall be considered not to have been lodged.

<a id="p114579"></a>Article 220

<a id="p114580"></a>Transitional rules for goods in postal consignments
(Articles 158(2), 172 and 194 of the Code)

1. <a id="p114581"></a>For the purposes of Article 138 of Delegated Regulation (EU) 2015/2446, the customs declaration for goods referred to in Article 141(3) of that Delegated Regulation shall be considered to have been accepted and the goods released when the goods are delivered to the consignee.
2. <a id="p114582"></a>Where it has not been possible to deliver the goods to the consignee, the customs declaration shall be deemed not to have been lodged.
<a id="p114583"></a>The goods which have not been delivered to the consignee shall be deemed to be in temporary storage until they are destroyed, re-exported or otherwise disposed in accordance with Article 198 of the Code.

<a id="p114584"></a>Article 220a

<a id="p114585"></a>Procedural rules applying to the use of NATO
form 302 for customs procedures other than transit
(Articles 6(3) and 158(2) of the Code)

1. <a id="p114586"></a>The customs office designated by the Member State where the military activity on the customs territory of the Union starts shall supply the NATO forces stationed in its territory with NATO forms 302 which:
<a id="p114587"></a>(a) are pre-authenticated with the stamp and signature of an official of that office;
<a id="p114588"></a>(b) are serially numbered;
<a id="p114589"></a>(c) bear the full address of that designated customs office for the return copy of the NATO form 302.
2. <a id="p114590"></a>At the time of dispatch of the goods, the NATO forces shall do either of the following:
<a id="p114591"></a>(a) lodge the NATO form 302 data electronically at the designated customs office;
<a id="p114592"></a>(b) complete the NATO form 302 with a statement that the goods are being moved under their control and authenticate this statement by their signature, stamp and date.
3. <a id="p114593"></a>Where the NATO forces proceed in accordance with point (b) of paragraph 2, they shall, without delay, provide a copy of the NATO form 302 to the customs office designated as responsible for the customs formalities and controls pertaining to the NATO forces dispatching the goods or on whose behalf the goods are being dispatched.
<a id="p114594"></a>The other copies of the NATO form 302 shall accompany the consignment to the NATO forces of destination, which shall stamp and sign them upon arrival of the goods.
<a id="p114595"></a>At the time of arrival of the goods, two copies of the form shall be given to the customs office designated as responsible for the customs formalities and controls pertaining to the NATO forces of destination.
<a id="p114596"></a>That designated customs office shall retain one copy and shall return the second copy to the customs office responsible for customs formalities and controls pertaining to the NATO forces dispatching the goods or on whose behalf the goods are being dispatched.

<a id="p114597"></a>Article 220b

<a id="p114598"></a>Procedural rules applying to the use of EU form 302
for customs procedures other than transit
(Articles 6(3) and 158(2) of the Code)

1. <a id="p114599"></a>The customs office designated by the Member State where the military activity on the customs territory of the Union starts shall supply the military forces of a Member State stationed in its territory with EU forms 302 which:
<a id="p114600"></a>(a) are pre-authenticated with the stamp and signature of an official of that office;
<a id="p114601"></a>(b) are serially numbered;
<a id="p114602"></a>(c) bear the full address of that designated customs office for the return copy of the EU form 302.
2. <a id="p114603"></a>At the time of dispatch of the goods, the military forces of the Member State shall do either of the following:
<a id="p114604"></a>(a) lodge the EU form 302 data electronically at the designated customs office;
<a id="p114605"></a>(b) complete the EU form 302 with a statement that the goods are being moved under their control and authenticate this statement by their signature, stamp and date.
3. <a id="p114606"></a>Where the military forces of the Member State proceed in accordance with point (b) of paragraph 2, they shall provide, without delay, a copy of the EU form 302, to the customs office designated as responsible for the customs formalities and controls pertaining to the military forces of the Member State dispatching the goods or on whose behalf the goods are being dispatched.
<a id="p114607"></a>The other copies of the EU form 302 shall accompany the consignment to the military forces of the Member State of destination, which shall stamp and sign them upon arrival of the goods.
<a id="p114608"></a>At the time of arrival of the goods, two copies of the form shall be given to the customs office designated as responsible for customs formalities and controls pertaining to the military forces of the Member State of destination.
<a id="p114609"></a>That designated customs office shall retain one copy and shall return the second copy to the customs office responsible for customs formalities and controls pertaining to the military forces of the Member State dispatching the goods or on whose behalf the goods are being dispatched.

<a id="p114610"></a>Article 221

<a id="p114611"></a>Competent customs office
for placing goods under a customs procedure
(Article 159 of the Code)

1. <a id="p114612"></a>For the purposes of the waiver of the obligation for goods to be presented in accordance with Article 182(3) of the Code, the supervising customs office referred to in the second subparagraph of Article 182(3)(c) of the Code shall be the competent customs office for placing goods under a customs procedure referred to in Article 159(3) of the Code.
2. <a id="p114613"></a>The following customs offices shall be competent for placing the goods under the export procedure:
<a id="p114614"></a>(a) the customs office responsible for the place where the exporter is established;
<a id="p114615"></a>(b) the customs office competent for the place where the goods are packed or loaded for export shipment;
<a id="p114616"></a>(c) a different customs office in the Member State concerned which is competent for administrative reasons for the operation in question.
<a id="p114617"></a>Where the goods do not exceed EUR 3 000 in value per consignment and per declarant and are not subject to prohibitions or restrictions, the customs office competent for the place of exit of the goods from the Union customs territory shall also be competent for placing the goods under the export procedure in addition to the customs offices identified in the first subparagraph.
<a id="p114618"></a>Where sub-contracting is involved, the customs office responsible for the place where the sub-contractor is established shall also be competent for placing the goods under the export procedure in addition to the customs offices identified in the first and second subparagraphs.
<a id="p114619"></a>Where justified by the circumstances of an individual case, another customs office better placed for the presentation of the goods to customs shall also be competent for placing the goods under the export procedure.
3. <a id="p114620"></a>Oral customs declarations for export and re-export shall be made at the customs office competent for the place of exit of the goods.
4. <a id="p114621"></a>From the date referred to in the fourth subparagraph of Article 4(1) of Directive (EU) 2017/2455, the customs office competent for the release for free circulation of goods in a consignment benefiting from relief from import duty under Article 23(1) or Article 25(1) of Regulation (EC) No 1186/2009, under a VAT scheme other than the special scheme for distance sales of goods imported from third territories or third countries referred to in Title XII, Chapter 6, Section 4, of Directive 2006/112/EC, shall be a customs office situated in the Member State where the dispatch or the transport of the goods ends.
5. <a id="p114622"></a>The customs authority in each Member State in whose territory NATO forces eligible to use NATO form 302 are stationed shall designate the customs office or offices responsible for customs formalities and controls concerning goods to be moved or used in the context of military activities.
6. <a id="p114623"></a>The customs authority in each Member State shall designate the customs office or offices responsible for customs formalities and controls concerning goods to be moved or used in the context of military activities carried out under cover of the EU form 302.

<a id="p114624"></a>Article 222

<a id="p114625"></a>Items of goods
(Article 162 of the Code)

1. <a id="p114626"></a>Where a customs declaration covers two or more items of goods, the particulars stated in that declaration relating to each item shall be regarded as constituting a separate customs declaration.
2. <a id="p114627"></a>Except where specific goods contained in a consignment are subject to different measures, goods contained in a consignment shall be regarded as constituting a single item for the purposes of paragraph 1 where either of the following conditions is fulfilled:
<a id="p114628"></a>(a) they are to be classified under a single tariff subheading;
<a id="p114629"></a>(b) they are the subject of an application for simplification in accordance with Article 177 of the Code.

<a id="p114630"></a>Section 2. SIMPLIFIED CUSTOMS DECLARATIONS

<a id="p114631"></a>Article 223

<a id="p114632"></a>Management of tariff
quota in simplified customs declarations
(Article 166 of the Code)

1. <a id="p114633"></a>Where a simplified declaration is lodged for release for free circulation of goods subject to a tariff quota managed in accordance with the chronological order of dates of acceptance of customs declarations, the declarant may request the granting of the tariff quota only when the necessary particulars are available either in the simplified declaration or in a supplementary declaration.
2. <a id="p114634"></a>Where the request for the granting of a tariff quota managed in accordance with the chronological order of dates of acceptance of customs declarations is made in a supplementary declaration, the request may not be processed until the supplementary declaration has been lodged.
3. <a id="p114635"></a>For the purposes of allocating the tariff quota the date of acceptance of the simplified declaration shall be taken into account.

<a id="p114636"></a>Article 224

<a id="p114637"></a>Supporting documents for simplified declarations
(Article 166 of the Code)

<a id="p114638"></a>Where goods have been placed under a customs procedure on the basis of a simplified declaration, the supporting documents referred to in Article 163(2) of the Code shall be provided to the customs authorities before release of the goods.

<a id="p114639"></a>Article 225

<a id="p114640"></a>Supplementary declaration
(Article 167(4) of the Code)

<a id="p114641"></a>In the case of entry in the declarant's records pursuant to Article 182 of the Code, where the supplementary declaration is of a general, periodic or recapitulative nature and the economic operator is authorised under self-assessment to calculate the amount of import and export duty payable, that authorisation holder shall either lodge the supplementary declaration or the customs authorities may allow the supplementary declarations to be available through direct electronic access in the authorisation holder's system.

<a id="p114642"></a>Section 3. PROVISIONS APPLYING TO ALL CUSTOMS DECLARATIONS

<a id="p114643"></a>Article 226

<a id="p114644"></a>Master Reference Number
(Article 172 of the Code)

<a id="p114645"></a>Except for the cases where customs declaration is lodged orally or by an act deemed to be a customs declaration, or where the customs declaration takes the form of an entry in the declarant's records in accordance with Article 182 of the Code, the customs authorities, shall notify the declarant of the acceptance of the customs declaration and shall provide him with a MRN for that declaration and the date of its acceptance.
<a id="p114646"></a>This article shall not apply until the respective dates of deployment of the AES, NCTS and the upgrading of the national import systems referred to in the Annex to Implementing Decision 2014/255/EU are operational.

<a id="p114647"></a>Article 227

<a id="p114648"></a>Customs declaration lodged prior
to the presentation of the goods

<a id="p114649"></a>Where the customs declaration is lodged in accordance with Article 171 of the Code, customs authorities shall process the particulars provided before the presentation of the goods in particular for the purposes of risk analysis.

<a id="p114650"></a>Section 4. OTHER SIMPLIFICATIONS

<a id="p114651"></a>Subsection 1

<a id="p114652"></a>**GOODS FALLING UNDER DIFFERENT TARIFF SUB-HEADINGS**

<a id="p114653"></a>Article 228

<a id="p114654"></a>Goods falling under different tariff subheadings
declared under a single subheading
(Article 177(1) of the Code)

1. <a id="p114655"></a>For the purposes of Article 177 of the Code, where the goods in a consignment fall within tariff subheadings subject to a specific duty expressed by reference to the same unit of measure, the duty to be charged on the whole consignment shall be based on the tariff subheading subject to the highest specific duty.
2. <a id="p114656"></a>For the purposes of Article 177 of the Code, where the goods in a consignment fall within tariff subheadings subject to a specific duty expressed by reference to different units of measure, the highest specific duty for each unit of measure shall be applied to all of the goods in the consignment for which the specific duty is expressed by reference to that unit, and converted into an ad valorem duty for each type of those goods.
<a id="p114657"></a>The duty to be charged on the whole consignment shall be based on the tariff subheading subject to the highest rate of the ad valorem duty resulting from the conversion pursuant to the first subparagraph.
3. <a id="p114658"></a>For the purposes of Article 177 of the Code, where the goods in a consignment fall within tariff subheadings subject to an ad valorem duty and a specific duty, the highest specific duty as determined in accordance with paragraphs 1 or 2 shall be converted into an ad valorem duty for each type of goods for which the specific duty is expressed by reference to the same unit.
<a id="p114659"></a>The duty to be charged on the whole consignment shall be based on the tariff subheading subject to the highest rate of ad valorem duty, including the ad valorem duty resulting from the conversion pursuant to the first subparagraph.

<a id="p114660"></a>Subsection 2

<a id="p114661"></a>**CENTRALISED CLEARANCE**

<a id="p114662"></a>Article 229

<a id="p114663"></a>Consultation procedure between customs authorities in the
case of authorisations for centralised clearance
(Article 22 of the Code)

1. <a id="p114664"></a>The consultation procedure referred to in Article 14 shall be followed where a customs authority receives an application for an authorisation for centralised clearance referred to in Article 179 of the Code involving more than one customs authority, unless the customs authority competent to take a decision is of the opinion that the conditions for granting such an authorisation are not fulfilled.
2. <a id="p114665"></a>At the latest 45 days after the date of acceptance of the application, the customs authority competent to take a decision shall communicate the following to the other customs authorities involved:
<a id="p114666"></a>(a) the application and the draft authorisation, including the time-limits referred to in Article 231(5) and (6) of this Regulation;
<a id="p114667"></a>(b) where appropriate, a control plan, elaborating the specific controls to be carried out by the different customs authorities involved once the authorisation is granted;
<a id="p114668"></a>(c) other relevant information considered necessary by the customs authorities involved.
3. <a id="p114669"></a>The consulted customs authorities shall communicate their agreement or objections as well as any changes to the draft authorisation or to the proposed control plan within 45 days of the date on which the draft authorisation was communicated. Objections shall be duly justified.
<a id="p114670"></a>Where objections are communicated, and no agreement is reached within 90 days of the date on which the draft authorisation was communicated, the authorisation shall not be granted for the parts on which objections were raised. Where the consulted customs authorities do not communicate objections within the prescribed time-limit, their agreement shall be deemed to be given.
4. <a id="p114671"></a>Until the respective dates of deployment of the CCI and the AES referred to in the Annex to Implementing Decision 2014/255/EU, by derogation from paragraphs 2 and the first subparagraph of paragraph 3 of this Article, the periods referred to therein may be extended by 15 days by the customs authority competent to take this decision.
<a id="p114672"></a>By derogation from the second subparagraph of paragraph 3 of this Article, the period referred to therein may be extended by 30 days by the customs authority competent to take this decision.
5. <a id="p114673"></a>Until the date of deployment of the UCC Customs Decisions system referred to in the Annex to Implementing Decision 2014/255/EU, by derogation from point b of paragraph 2 of this Article, the control plan referred to therein shall always be communicated.

<a id="p114674"></a>Article 230

<a id="p114675"></a>Monitoring of the authorisation
(Article 23(5) of the Code)

1. <a id="p114676"></a>The customs authorities of the Member States shall inform the customs authority competent to take a decision without delay of any factors arising after the granting of the authorisation for centralised clearance which may influence its continuation or content.
2. <a id="p114677"></a>The customs authority competent to take a decision shall make available all relevant information at its disposal to the customs authorities of the other Member States regarding the customs-related activities of the holder of the authorisation for centralised clearance.

<a id="p114678"></a>Article 231

<a id="p114679"></a>Customs formalities and controls
in respect of centralised clearance
(Article 179(4) of the Code)

1. <a id="p114680"></a>The holder of the authorisation for centralised clearance shall have the goods presented at a competent customs office as set out in that authorisation by lodging at the supervising customs office any of the following:
<a id="p114681"></a>(a) a standard customs declaration as referred to in Article 162 of the Code;
<a id="p114682"></a>(b) a simplified customs declaration as referred to in Article 166 of the Code;
<a id="p114683"></a>(c) a notification of presentation as referred to in Article 234(1)(a) of this Regulation.
2. <a id="p114684"></a>Where the customs declaration takes the form of an entry in the declarant's records, Articles 234, 235 and 236 of this Regulation shall apply.
3. <a id="p114685"></a>The presentation waiver granted in accordance with Article 182(3) of the Code shall apply to centralised clearance provided that the holder of the authorisation to lodge a customs declaration in the form of an entry in the declarant's records has fulfilled the obligation laid down in Article 234(1)(f) of this Regulation.
4. <a id="p114686"></a>Where the supervising customs office has accepted the customs declaration or received the notification referred to in paragraph 1(c), it shall:
<a id="p114687"></a>(a) carry out the appropriate controls for the verification of the customs declaration or notification of presentation;
<a id="p114688"></a>(b) transmit immediately to the customs office of presentation the customs declaration or the notification and the results of the related risk analysis;
<a id="p114689"></a>(c) inform the customs office of presentation of either of the following:
<a id="p114690"></a>(i) that the goods may be released for the customs procedure concerned;
<a id="p114691"></a>(ii) that customs controls are required in accordance with Article 179(3)(c) of the Code.
5. <a id="p114692"></a>Where the supervising customs office informs the customs office of presentation that the goods may be released for the customs procedure concerned, the customs office of presentation shall, within the time-limit laid down in the authorisation for centralised clearance, inform the supervising customs office whether or not its own controls of those goods, including controls related to national prohibitions and restrictions, affect such release.
6. <a id="p114693"></a>Where the supervising customs office informs the customs office of presentation that customs controls are required in accordance with Article 179(3)(c) of the Code, the customs office of presentation shall, within the time-limit laid down in the authorisation for centralised clearance, acknowledge receipt of the request of the supervising customs office to carry out the required controls and, where appropriate, inform the supervising customs office of its own controls of the goods, including controls related to national prohibitions and restrictions.
7. <a id="p114694"></a>The supervising customs office shall inform the customs office of presentation of the release of the goods.
8. <a id="p114695"></a>At export, the supervising customs office shall, upon release of the goods, make the particulars of the export declaration, supplemented as appropriate in accordance with Article 330 of this Regulation, available to the declared customs office of exit. The customs office of exit shall inform the supervising customs office of the exit of the goods in accordance with Article 333 of this Regulation. The supervising customs office shall certify the exit to the declarant in accordance with Article 334 of this Regulation.
9. <a id="p114696"></a>By way of derogation from paragraph 1 of this Article, until the respective dates of deployment of the CCI and the AES referred to in the Annex to Implementing Decision 2014/255/EU, for goods covered by an authorisation for centralised clearance, the authorisation holder or the declarant shall:
<a id="p114697"></a>(a) present the goods at the places set out in the authorisation and designated or approved by the customs authorities in accordance with Article 139 of the Code, except where the obligation for the goods to be presented is waived in accordance with Article 182(3) of the Code; and
<a id="p114698"></a>(b) lodge a customs declaration or enter the goods in its records at the customs office specified in the authorisation.
10. <a id="p114699"></a>Until the respective dates of deployment of the CCI and the AES referred to in the Annex to Implementing Decision 2014/255/EU, the competent customs authorities shall apply the control plan which shall specify a minimum level of controls.
11. <a id="p114700"></a>Until the respective dates of deployment of the AES and of the UCC Centralised Clearance for Import (CCI) referred to in the Annex to Implementing Decision (EU) 2016/578, paragraphs 5 and 6 of this Article shall not apply.

<a id="p114701"></a>Article 232

<a id="p114702"></a>Centralised clearance
involving more than one customs authority
(Article 179 of the Code)

1. <a id="p114703"></a>The supervising customs office shall transmit the following to the customs office of presentation:
<a id="p114704"></a>(a) any amendment to or invalidation of the standard customs declaration that has occurred after the release of the goods;
<a id="p114705"></a>(b) where a supplementary declaration has been lodged, that declaration and any amendment or invalidation thereof.
2. <a id="p114706"></a>Where the supplementary declaration is accessible to customs in the trader's IT System in accordance with Article 225 of this Regulation, the supervising customs office shall transmit the particulars no later than 10 days from the end of the period of time covered by the supplementary declaration, and any amendment or invalidation of that extracted supplementary declaration.

<a id="p114707"></a>Subsection 3

<a id="p114708"></a>**ENTRY IN THE DECLARANT'S RECORDS**

<a id="p114709"></a>Article 233

<a id="p114710"></a>Control plan
(Article 23(5) of the Code)

1. <a id="p114711"></a>The customs authorities shall set up a control plan specific to the economic operator when granting an authorisation to lodge a customs declaration in the form of an entry in the declarant's records in accordance with Article 182(1) of the Code, providing for the supervision of the customs procedures operated under the authorisation, defining the frequency of the customs controls and ensuring, inter alia, that effective customs controls can be carried out at all stages of the entry in the declarant's records procedure.
2. <a id="p114712"></a>Where applicable the control plan shall take into account the limitation period for notification of the customs debt referred to in Article 103(1) of the Code.
3. <a id="p114713"></a>The control plan shall provide for the control to be carried out in the event that a presentation waiver is granted in accordance with Article 182(3) of the Code.
4. <a id="p114714"></a>In case of centralised clearance, the control plan, specifying the sharing of tasks between the supervising customs office and the customs office of presentation, shall take into account the prohibitions and restrictions applicable at the place where the customs office of presentation is located.

<a id="p114715"></a>Article 234

<a id="p114716"></a>Obligations of the holder
of the authorisation to lodge a customs declaration in the
form of an entry in the declarant's records
(Article 182(1) of the Code)

1. <a id="p114717"></a>The holder of the authorisation to lodge a customs declaration in the form of an entry in the declarant's records shall:
<a id="p114718"></a>(a) present the goods to customs, except where Article 182(3) of the Code applies, and enter the date of the notification of presentation in the records;
<a id="p114719"></a>(b) enter at least the particulars of a simplified customs declaration and any supporting documents in the records;
<a id="p114720"></a>(c) on request of the supervising customs office, make available the particulars of the customs declaration entered in the records and any supporting document, except where the customs authorities allow that the declarant provides a direct computerised access to that information in its records;
<a id="p114721"></a>(d) make available to the supervising customs office information on goods that are subject to restrictions and prohibitions;
<a id="p114722"></a>(e) provide the supervising customs office with supporting documents as referred to in Article 163(2) of the Code before the goods declared can be released;
<a id="p114723"></a>(f) where the waiver referred to in Article 182(3) of the Code applies, ensure that the holder of the authorisation for the operation of temporary storage facilities has the information necessary to prove the end of temporary storage;
<a id="p114724"></a>(g) except where the obligation to lodge a supplementary declaration is waived in accordance with Article 167(2) of the Code, lodge the supplementary declaration to the supervising customs office in the manner and within the time-limit laid down in the authorisation.
2. <a id="p114725"></a>The authorisation to lodge a customs declaration in the form of an entry in the declarant's records shall not apply to the following declarations:
<a id="p114726"></a>(a) customs declarations which constitute an application for an authorisation for a special procedure in accordance with Article 163 of Delegated Regulation (EU) 2015/2446;
<a id="p114727"></a>(b) customs declarations lodged instead of an entry summary declaration in accordance with Article 130(1) of the Code.
3. <a id="p114728"></a>Where the supervising customs office has requested, in accordance with the third sub-paragraph of Article 182(3) of the Code, that goods be presented to customs because the customs authorities have identified a new serious financial risk or another specific situation in relation to an authorisation to lodge a customs declaration in the form of an entry in the declarant's records with waiver of the obligation to present the goods, the supervising customs office shall indicate to the holder of such authorisation:
<a id="p114729"></a>(a) the specific period of time during which to present to customs the goods covered by those situations,
<a id="p114730"></a>(b) the obligation to enter the date of notification of presentation in the records, and
<a id="p114731"></a>(c) the obligation to comply with points (b) to (e) and (g) of paragraph 1.
<a id="p114732"></a>In these situations, the release of the goods shall take place in accordance with Article 194 of the Code.

<a id="p114733"></a>Article 235

<a id="p114734"></a>Release of the goods where a customs declaration is lodged
in the form of an entry in the declarant's records
(Article 182 of the Code)

1. <a id="p114735"></a>Where the authorisation to lodge a customs declaration in the form of an entry in the declarant's records lays down a time limit for informing the holder of that authorisation of any controls to be performed, the goods shall be deemed to have been released at the expiry of that time-limit, unless the supervising customs office has indicated within that time-limit its intention to perform a control.
2. <a id="p114736"></a>Where the authorisation does not lay down a time-limit as referred to in paragraph 1, the supervising customs office shall release the goods in accordance with Article 194 of the Code.

<a id="p114737"></a>Article 236

<a id="p114738"></a>Tariff quota
(Article 182 of the Code)

1. <a id="p114739"></a>Where a customs declaration is lodged in the form of an entry in the declarant's records for release for free circulation of goods subject to a tariff quota managed in accordance with the chronological order of dates of acceptance of customs declarations, the holder of the authorisation to lodge a customs declaration in that form shall request the granting of the tariff quota in a supplementary declaration.
2. <a id="p114740"></a>Where the request for the granting of a tariff quota managed in accordance with the chronological order of dates of acceptance of customs declarations is made in a supplementary declaration, the request can only be processed after the lodging of that declaration. However, the date on which the goods are entered in the declarant's records shall be taken into account for the purposes of allocating the tariff quota.
3. <a id="p114741"></a>By derogation from paragraph 1 of this Article, until the dates of the upgrading of the national import declaration systems referred to in the Annex to Implementing Decision 2014/255/EU, Member States may provide that the request to benefit from a tariff quota managed in accordance with the provisions of Articles 49 to 54 of this Regulation is made in a form other than that referred to in paragraph 1 of this Article, provided that all the necessary particulars are available for Member States to judge on the validity of the request.

<a id="p114742"></a>Subsection 4

<a id="p114743"></a>**SELF-ASSESSMENT**

<a id="p114744"></a>Article 237

<a id="p114745"></a>Determination of the amount
of import and export duty payable
(Article 185(1) of the Code)

1. <a id="p114746"></a>Where an economic operator is authorised to determine the amount of import and export duty payable in accordance with Article 185(1) of the Code, that operator shall, at the end of the period fixed by the customs authorities in the authorisation, determine the amount of import and export duty payable for that period in accordance with the rules laid down in the authorisation.
2. <a id="p114747"></a>Within 10 days of the end of the period fixed by the customs authorities in the authorisation, the holder of that authorisation shall submit to the supervising customs office details of the amount determined in accordance with paragraph 1. The customs debt shall be deemed to be notified at the time of that submission.
3. <a id="p114748"></a>The holder of the authorisation shall pay the amount referred to in paragraph 2 within the period prescribed in the authorisation and at the latest within the deadline laid down in Article 108(1) of the Code.

<a id="p114749"></a>**CHAPTER 3**

<a id="p114750"></a>**VERIFICATION AND RELEASE OF GOODS**

<a id="p114751"></a>Section 1. VERIFICATION

<a id="p114752"></a>Article 238

<a id="p114753"></a>Place and time of examination of the goods
(Article 189 of the Code)

<a id="p114754"></a>Where the competent customs office has decided to examine the goods in accordance with Article 188(c) of the Code or take samples in accordance with Article 188(d) of the Code, it shall designate the time and place for that purpose and shall inform the declarant thereof.
<a id="p114755"></a>At the request of the declarant, the competent customs office may designate a place other than the customs premises or a time outside the official opening hours of that customs office.

<a id="p114756"></a>Article 239

<a id="p114757"></a>Examination of the goods
(Articles 189 and 190 of the Code)

1. <a id="p114758"></a>Where the customs office decides to examine only part of the goods, it shall inform the declarant of the items which they wish to examine.
2. <a id="p114759"></a>Where the declarant refuses to be present at the examination of the goods or fails to provide the necessary assistance as required by the customs authorities, they shall set a time-limit for his presence or assistance.
<a id="p114760"></a>Where the declarant has not complied with the requirements of the customs authorities on expiry of the time-limit, the customs authorities shall proceed with the examination of the goods, at the declarant's risk and expense. Where necessary, the customs authorities may call on the services of an expert designated in accordance with the law of the Member State concerned in so far as no provisions exist in Union law.

<a id="p114761"></a>Article 240

<a id="p114762"></a>Taking of samples
(Articles 189 and 190 of the Code)

1. <a id="p114763"></a>Where the customs office decides to take samples of the goods, it shall inform the declarant thereof.
2. <a id="p114764"></a>Where the declarant refuses to be present when the samples are taken or fails to provide the necessary assistance as required by the customs authorities, they shall set a time-limit for his presence or assistance.
<a id="p114765"></a>Where the declarant has not complied with the requirements of the customs authorities on expiry of the time-limit, the customs authorities shall proceed with the taking of samples, at the declarant's risk and expense.
3. <a id="p114766"></a>Samples shall be taken by the customs authorities themselves. However, they may require samples to be taken by the declarant or call on an expert to take the samples, under their supervision. The expert shall be designated in accordance with the law of the Member State concerned in so far as no provisions exist in Union law.
4. <a id="p114767"></a>The quantities taken as samples shall not exceed what is needed for analysis or more detailed examination, including possible subsequent analysis.
5. <a id="p114768"></a>The quantities taken as samples shall not be deducted from the quantity declared.
6. <a id="p114769"></a>Where an export or outward processing declaration is concerned, the declarant may replace the quantities of goods taken as samples by identical goods, in order to make up the consignment.

<a id="p114770"></a>Article 241

<a id="p114771"></a>Examination of samples
(Articles 189 and 190 of the Code)

1. <a id="p114772"></a>Where the examination of samples of the same goods leads to different results requiring different customs treatment, further samples shall be taken, where possible.
2. <a id="p114773"></a>Where the results of the examination of the further samples confirm the different results, the goods shall be deemed to consist of different goods in quantities corresponding to the results of the examination. The same shall apply where it is not possible to take further samples.

<a id="p114774"></a>Article 242

<a id="p114775"></a>Return or disposal of samples taken
(Articles 189 and 190 of the Code)

1. <a id="p114776"></a>The samples taken shall be returned to the declarant at his request, except in the following cases:
<a id="p114777"></a>(a) where the samples have been destroyed by the analysis or the examination;
<a id="p114778"></a>(b) where the samples need to be kept by the customs authorities for the purposes of either of the following:
<a id="p114779"></a>(i) further examination;
<a id="p114780"></a>(ii) appeal or court proceedings.
2. <a id="p114781"></a>Where the declarant does not make a request for the samples to be returned, the customs authorities may require the declarant to remove any samples that remain or dispose of them in accordance with Article 198(1)(c) of the Code.

<a id="p114782"></a>Article 243

<a id="p114783"></a>Results of the verification of the customs declaration
and of the examination of the goods
(Article 191 of the Code)

1. <a id="p114784"></a>Where the customs authorities verify the accuracy of the particulars contained in a customs declaration, they shall record the fact that a verification has been carried out and the results of that verification.
<a id="p114785"></a>Where only part of the goods has been examined, the goods examined shall be recorded.
<a id="p114786"></a>Where the declarant was absent, his absence shall be recorded.
2. <a id="p114787"></a>The customs authorities shall inform the declarant of the results of the verification.
3. <a id="p114788"></a>Where the results of the verification of the customs declaration are not in accordance with the particulars given in the declaration, the customs authorities shall establish and record which particulars are to be taken into account for the purposes of the following:
<a id="p114789"></a>(a) calculating the amount of import or export duty and other charges on the goods;
<a id="p114790"></a>(b) calculating any refunds or other amounts or financial advantages provided for on export under the common agricultural policy;
<a id="p114791"></a>(c) applying any other provisions governing the customs procedure under which the goods are placed.
4. <a id="p114792"></a>Where the declared non-preferential origin is found to be incorrect, the origin to be taken into account for the purpose of paragraph 3(a) shall be established on the basis of the evidence presented by the declarant or, where this is not sufficient or satisfactory, on the basis of any available information.

<a id="p114793"></a>Article 244

<a id="p114794"></a>Provision of a guarantee
(Article 191 of the Code)

<a id="p114795"></a>Where the customs authorities consider that the verification of the customs declaration may result in a higher amount of import or export duty or other charges to become payable than that resulting from the particulars of the customs declaration, the release of the goods shall be conditional upon the provision of a guarantee sufficient to cover the difference between the amount according to the particulars of the customs declaration and the amount which may finally be payable.
<a id="p114796"></a>However, the declarant may request the immediate notification of the customs debt to which the goods may ultimately be liable instead of lodging this guarantee.

<a id="p114797"></a>Article 245

<a id="p114798"></a>Release of the goods after verification
(Articles 191 and 194(1) of the Code)

1. <a id="p114799"></a>Where, on the basis of the verification of the customs declaration, the customs authorities determine an amount of import or export duty different from the amount which results from the particulars in the declaration, Article 195(1) of the Code shall apply as regards the amount thus assessed.
2. <a id="p114800"></a>Where the customs authorities have doubts about whether or not a prohibition or restriction applies and this cannot be resolved until the results of the checks carried out by the customs authorities are available, the goods in question shall not be released.

<a id="p114801"></a>Section 2. RELEASE

<a id="p114802"></a>Article 246

<a id="p114803"></a>Recording and notification of the release of goods
(Article 22(3) of the Code)

<a id="p114804"></a>The customs authorities shall notify the release of the goods to the declarant and record the release of the goods for the customs procedure concerned indicating at least the reference of the customs declaration or notification and the date of release of the goods.

<a id="p114805"></a>Article 247

<a id="p114806"></a>Unreleased goods
(Article 22(3) of the Code)

1. <a id="p114807"></a>Where, for any of the reasons listed in Article 198(1)(b) of the Code, the goods cannot be released or where, after their release, the goods are found not to have fulfilled the conditions for that release the customs authorities shall give the declarant a reasonable time-limit to remedy the situation of the goods.
2. <a id="p114808"></a>The customs authorities may, at the risk and expense of the declarant, transfer the goods referred to in paragraph 1 to special premises under the customs authorities' supervision.

<a id="p114809"></a>**CHAPTER 4**

<a id="p114810"></a>**DISPOSAL OF GOODS**

<a id="p114811"></a>Article 248

<a id="p114812"></a>Destruction of goods
(Article 197 of the Code)

<a id="p114813"></a>The customs authorities shall establish the type and quantity of any waste or scrap resulting from the destruction of goods in order to determine any customs duty and other charges applicable to that waste or scrap when placed under a customs procedure or re-exported.

<a id="p114814"></a>Article 249

<a id="p114815"></a>Abandonment of goods
(Article 199 of the Code)

1. <a id="p114816"></a>The customs authorities may reject a request for a permission to abandon goods to the State in accordance with Article 199 of the Code where any of the following conditions is fulfilled:
<a id="p114817"></a>(a) the goods cannot be sold within the customs territory of the Union or the cost of that sale would be disproportionate to the value of the goods;
<a id="p114818"></a>(b) the goods are to be destroyed.
2. <a id="p114819"></a>A request for the abandonment to the State shall be deemed to have been made in accordance with Article 199 of the Code where the customs authorities have made a public appeal for the owner of the goods to come forward and 90 days have passed without the owner doing so.

<a id="p114820"></a>Article 250

<a id="p114821"></a>Sale of goods and other
measures taken by the customs authorities
(Article 198(1) of the Code)

1. <a id="p114822"></a>Customs authorities may sell goods abandoned to the State or confiscated only on the condition that the buyer immediately carries out the formalities to place the goods under a customs procedure or to re-export them.
2. <a id="p114823"></a>Where the goods are sold at a price inclusive of the amount of import duty and other charges, the goods shall be considered to have been released for free circulation. The customs authorities shall calculate the amount of duty and enter it in the accounts. That sale shall be conducted according to the procedures applicable in the Member State concerned.

<a id="p114824"></a>**TITLE VI. RELEASE FOR FREE CIRCULATION AND RELIEF FROM**
**IMPORT DUTY**

<a id="p114825"></a>**CHAPTER 1**

<a id="p114826"></a>**RELEASE FOR FREE CIRCULATION**

<a id="p114827"></a>Article 251

<a id="p114828"></a>Banana weighing certificates
(Article 163(1) of the Code)

1. <a id="p114829"></a>The economic operator authorised to draw up certificates in accordance with Article 155 of Delegated Regulation (EU) 2015/2446 (banana weighing certificates) shall give the customs authorities advance notice of the weighing of a consignment of fresh bananas for the purpose of drawing up a that certificate, giving details of the type of packaging, the origin and the time and place of weighing.
2. <a id="p114830"></a>The banana weighing certificate shall be in the declarant's possession and at the disposal of the customs authorities at the time of lodging of a declaration for release for free circulation of fresh bananas falling within CN code 0803 90 10 subject to import duty.
3. <a id="p114831"></a>By way of derogation from paragraph 2, at the declarant's request for an authorisation as set out in Article 166 of the Code, the customs authorities may decide to release consignments of fresh bananas into free circulation on the basis of a provisional declaration of the weight on the following conditions:
<a id="p114832"></a>(a) The authorisation shall oblige the importer to transport bananas in their unaltered state from the same shipment to designated authorised weighs mentioned in the simplified declaration where the correct weight and value will be determined;
<a id="p114833"></a>(b) The declarant is responsible for submitting the weighing certificate to the customs office of free circulation within 10 calendar days after the simplified declaration has been accepted;
<a id="p114834"></a>(c) The declarant shall lodge a guarantee as set out in Article 195(1) of the Code.
<a id="p114835"></a>The provisional weight may be derived from a previous weighing certificate for bananas from the same type and origin.
4. <a id="p114836"></a>The banana weighing certificate shall be drawn up using the form set out in Annex 61-02.

<a id="p114837"></a>Article 252

<a id="p114838"></a>Control of the weighing of fresh bananas
(Article 188 of the Code)

<a id="p114839"></a>Customs offices shall control at least 5% of the total number of banana weighing certificates presented each year, either by being present at the weighing of the representative samples of the bananas by the economic operator authorised to draw up banana weighing certificates or by weighing those samples themselves, in accordance with the procedure laid down in points 1, 2 and 3 of Annex 61-03.

<a id="p114840"></a>**CHAPTER 2**

<a id="p114841"></a>**RELIEF FROM IMPORT DUTY**

<a id="p114842"></a>Section 1. RETURNED GOODS

<a id="p114843"></a>Article 253

<a id="p114844"></a>Information required
(Article 203(6) of the Code)

1. <a id="p114845"></a>The declarant shall make the information establishing that the conditions for relief from import duty have been fulfilled available to the customs office where the customs declaration for release for free circulation is lodged.
2. <a id="p114846"></a>The information referred to in paragraph 1 may be provided by any of the following means:
<a id="p114847"></a>(a) access to the relevant particulars of the customs or re-export declaration on the basis of which the returned goods were originally exported or re-exported from the customs territory of the Union;
<a id="p114848"></a>(b) a print out, authenticated by the competent customs office, of the customs or re-export declaration on the basis of which the returned goods were originally exported or re-exported from the customs territory of the Union;
<a id="p114849"></a>(c) a document issued by the competent customs office, with the relevant particulars of that customs declaration or re-export declaration;
<a id="p114850"></a>(d) a document issued by the customs authorities certifying that the conditions for the relief from import duty have been fulfilled (information sheet INF3).
3. <a id="p114851"></a>Where information available to the competent customs authorities establishes that the goods declared for release for free circulation were originally exported from the customs territory of the Union and at that time fulfilled the conditions for being granted relief from import duty as returned goods, the information referred to in paragraph 2 shall not be required.
4. <a id="p114852"></a>Paragraph 2 shall not apply where goods may be declared for release for free circulation orally or by any other act. Nor shall it apply to the international movement of packing materials, means of transport or certain goods admitted under specific customs arrangements unless where provided otherwise.

<a id="p114853"></a>Article 254

<a id="p114854"></a>Goods which on export benefited from measures laid down
under the common agricultural policy
(Article 203(6) of the Code)

<a id="p114855"></a>A declaration for release for free circulation relating to returned goods whose export may have given rise to the completion of formalities with a view to obtaining refunds or other amounts provided for under the common agricultural policy, shall be supported by the documents referred to in Article 253 of this Regulation and by a certificate issued by the authorities responsible for the granting of such refunds or amounts in the Member State of export.
<a id="p114856"></a>Where the customs authorities at the customs office where the goods are declared for release for free circulation have information establishing that no refund or other amount provided for on export under the common agricultural policy has been granted, and cannot subsequently be granted, the certificate shall not be required.

<a id="p114857"></a>Article 255

<a id="p114858"></a>Issuing information sheet INF 3
(Articles 6(3)(a) and 203(6) of the Code)

1. <a id="p114859"></a>The exporter may request an information sheet INF 3 from the customs office of export.
2. <a id="p114860"></a>Where the exporter requests the information sheet INF 3 at the time of export, the information sheet INF 3 shall be issued by the customs office of export at the time of completion of the export formalities for the goods.
<a id="p114861"></a>Where it is possible that the exported goods will be returned to the customs territory of the Union through several customs offices, the exporter may request several information sheets INF 3 each covering a part of the total quantity of the goods exported.
3. <a id="p114862"></a>Where the exporter requests an information sheet INF 3 after the completion of the export formalities for the goods, the information sheet INF 3 may be issued by the customs office of export if the information about the goods stated in the exporter's request corresponds to the information about the exported goods at the disposal of the customs office of export and no refund or other amount provided for on export under the common agricultural policy has been granted, and cannot subsequently be granted, in respect of the goods.
4. <a id="p114863"></a>Where an information sheet INF 3 has been issued, the exporter may request that the customs office of export replace it by several information sheets INF 3 each covering a part of the total quantity of goods included in the information sheet INF 3 initially issued.
5. <a id="p114864"></a>The exporter may ask for an information sheet INF 3 to be issued only in respect of a part of the exported goods.
6. <a id="p114865"></a>Where an information sheet INF 3 is issued on paper, a copy shall be kept by the customs office of export which issued it.
7. <a id="p114866"></a>Where the original information sheet INF 3 was issued on paper and has been stolen, lost or destroyed the customs office of export which issued it may issue a duplicate at the request of an exporter.
<a id="p114867"></a>The customs office of export shall record on the copy of information sheet INF 3 in its possession that a duplicate has been issued.
8. <a id="p114868"></a>Where information sheet INF 3 is issued on paper, it shall be drawn up using the form laid down in Annex 62-02.

<a id="p114869"></a>Article 256

<a id="p114870"></a>Communication between authorities
(Article 203(6) of the Code)

<a id="p114871"></a>At the request of the customs office where the returned goods are declared for release for free circulation, the customs office of export shall communicate any information at its disposal establishing that the conditions for the relief from import duty have been fulfilled in respect of those goods.

<a id="p114872"></a>Section 2. PRODUCTS OF SEA-FISHING AND OTHER PRODUCTS TAKEN
**FROM THE SEA**

<a id="p114873"></a>Article 257

<a id="p114874"></a>Relief from import duty
(Article 208(2) of the Code)

<a id="p114875"></a>Evidence that the conditions laid down in Article 208(1) of the Code are fulfilled may be provided in accordance with the provisions of Articles 213, 214 and 215 of this Regulation and Articles 130, 131, 132 and 133 of Delegated Regulation (EU) 2015/2446, as appropriate.

<a id="p114876"></a>**TITLE VII. SPECIAL PROCEDURES**

<a id="p114877"></a>**CHAPTER 1**

<a id="p114878"></a>**GENERAL PROVISIONS**

<a id="p114879"></a>Section 1. APPLICATION FOR AN AUTHORISATION

<a id="p114880"></a>Article 258

<a id="p114881"></a>Supporting document for an oral customs
declaration for temporary admission
(Article 22(2) of the Code)

<a id="p114882"></a>Where an application for an authorisation for temporary admission is based on an oral customs declaration, the declarant shall present the supporting document referred to in Article 165 of Delegated Regulation (EU) 2015/2446 in duplicate, and one copy shall be endorsed by the customs authorities and given to the holder of the authorisation.

<a id="p114883"></a>Section 2. TAKING A DECISION ON THE APPLICATION

<a id="p114884"></a>Article 259

<a id="p114885"></a>Examination of the economic conditions
(Articles 28(1)(a) and 211(6) of the Code)

1. <a id="p114886"></a>Where following an application for an authorisation as referred to in Article 211(1)(a) of the Code an examination of the economic conditions is required in accordance with Article 211(6) of the Code, the customs administration of the customs authority competent for taking a decision on the application shall transmit the file to the Commission without delay requesting such examination.
2. <a id="p114887"></a>Where, after the issuing of an authorisation for the use of a processing procedure, evidence becomes available to a customs administration of a Member State that the essential interests of Union producers are likely to be adversely affected by the use of that authorisation, that customs administration shall transmit the file to the Commission requesting an examination of the economic conditions.
3. <a id="p114888"></a>An examination of the economic conditions at Union level may also take place at the initiative of the Commission where it has evidence that the essential interests of Union producers are likely to be adversely affected by the use of an authorisation.
4. <a id="p114889"></a>The Commission shall establish an expert group, composed of the representatives of the Member States, which shall advise the Commission on whether the economic conditions are fulfilled or not.
5. <a id="p114890"></a>The conclusion reached on the economic conditions shall be taken into account by the customs authority concerned and by any other customs authority dealing with similar applications or authorisations.
<a id="p114891"></a>It may be specified in the conclusions reached on the economic conditions that the case under examination is unique and therefore cannot serve as a precedent for other applications or authorisations.
6. <a id="p114892"></a>Where it has been concluded that the economic conditions are no longer fulfilled, the competent customs authority shall revoke the relevant authorisation. The revocation shall take effect no later than 1 year after the day following the date on which the decision on the revocation is received by the holder of the authorisation.

<a id="p114893"></a>Article 260

<a id="p114894"></a>Consultation procedure between customs authorities
(Article 22 of the Code)

1. <a id="p114895"></a>Where an application has been submitted for an authorisation referred to in Article 211(1) of the Code and involving more than one Member State, Articles 10 and 14 of this Regulation and paragraphs 2 to 5 of this Article shall apply, unless the customs authority competent to take the decision is of the opinion that the conditions for granting such an authorisation are not fulfilled.
2. <a id="p114896"></a>The customs authority competent to take the decision shall communicate to the other customs authorities concerned the application and the draft authorisation at the latest 30 days after the date of acceptance of the application.
3. <a id="p114897"></a>No authorisation involving more than one Member State shall be issued without the prior agreement of the customs authorities concerned on the draft authorisation.
4. <a id="p114898"></a>The other customs authorities concerned shall communicate objections, if any, or their agreement within 30 days after the date on which the draft authorisation was communicated. Objections shall be duly justified.
<a id="p114899"></a>Where objections are communicated within that time-limit and no agreement is reached within 60 days after the date on which the draft authorisation was communicated, the authorisation shall not be granted to the extent to which objections were raised.
5. <a id="p114900"></a>If the other customs authorities concerned have not communicated objections within 30 days after the date on which the draft authorisation was communicated, their agreement shall be deemed to be given.

<a id="p114901"></a>Article 261

<a id="p114902"></a>Cases in which the consultation procedure is not required
(Article 22 of the Code)

1. <a id="p114903"></a>The competent customs authority shall take a decision on an application without consultation of the other customs authorities concerned as laid down in Article 260 of this Regulation in any of the following cases:
<a id="p114904"></a>(a) an authorisation involving more than one Member State is:
<a id="p114905"></a>(i) renewed;
<a id="p114906"></a>(ii) subject to minor amendments;
<a id="p114907"></a>(iii) annulled;
<a id="p114908"></a>(iv) suspended;
<a id="p114909"></a>(v) revoked;
<a id="p114910"></a>(b) two or more of the Member States involved have agreed thereto;
<a id="p114911"></a>(c) the only activity involving different Member States is an operation where the customs office of placement and the customs office of discharge are not the same;
<a id="p114912"></a>(d) an application for an authorisation for temporary admission which involves more than one Member State is made based on a customs declaration in the standard form.
<a id="p114913"></a>In such cases, the customs authority having taken the decision shall make available to the other customs authorities concerned the particulars of the authorisation.
2. <a id="p114914"></a>The competent customs authority shall take a decision on an application without consultation of the other customs authorities concerned as laid down in Article 260 of this Regulation and without making available the particulars of the authorisation to the other customs authorities concerned in accordance with paragraph 1, in any of the following cases:
<a id="p114915"></a>(a) where ATA or CPD carnets are used;
<a id="p114916"></a>(b) where an authorisation for temporary admission is granted by release of goods for the relevant customs procedure in accordance with Article 262 of this Regulation;
<a id="p114917"></a>(c) where two or more of the Member States involved have agreed thereto;
<a id="p114918"></a>(d) where the only activity involving different Member States consists in the movement of goods.

<a id="p114919"></a>Article 262

<a id="p114920"></a>Authorisation in the form of release of goods
(Article 22(1) of the Code)

<a id="p114921"></a>Where an application for an authorisation has been made based on a customs declaration in accordance with Article 163(1) or (5) of Delegated Regulation (EU) 2015/2446, the authorisation shall be granted by release of goods for the relevant customs procedure.

<a id="p114922"></a>Section 3. OTHER PROCEDURAL RULES

<a id="p114923"></a>Article 263

<a id="p114924"></a>Customs declaration lodged at another customs office
(Article 159(3) of the Code)

<a id="p114925"></a>The competent customs authority may allow in exceptional cases that the customs declaration be lodged at a customs office that is not specified in the authorisation. In that case, the competent customs authority shall inform the supervising customs office without delay.

<a id="p114926"></a>Article 264

<a id="p114927"></a>Discharge of a special procedure
(Article 215 of the Code)

1. <a id="p114928"></a>Where goods have been placed under a special procedure using two or more customs declarations by virtue of one authorisation, the placing of such goods or of the products obtained therefrom under a subsequent customs procedure, or their assignment to their prescribed end-use, shall be considered to discharge the procedure for the goods in question placed under the earliest of the customs declarations.
2. <a id="p114929"></a>Where goods have been placed under a special procedure using two or more customs declarations by virtue of one authorisation and the special procedure is discharged by taking the goods out of the customs territory of the Union or by destruction of the goods with no waste remaining, the taking out of the goods or the destruction with no waste remaining shall be considered to discharge the procedure for the goods in question placed under the earliest of the customs declarations.
3. <a id="p114930"></a>By derogation from paragraphs 1 and 2, the holder of the authorisation or the holder of the procedure may request the discharge to be made in relation to specific goods placed under the procedure.
4. <a id="p114931"></a>The application of paragraphs 1 and 2 shall not lead to unjustified import duty advantages.
5. <a id="p114932"></a>Where the goods under the special procedure are placed together with other goods, and there is total destruction or irretrievable loss, the customs authorities may accept evidence produced by the holder of the procedure indicating the actual quantity of goods under the procedure which was destroyed or lost.
<a id="p114933"></a>Where the holder of the procedure cannot produce evidence acceptable to the customs authorities, the amount of goods which has been destroyed or lost shall be established by reference to the proportion of goods of the same type under the procedure at the time when the destruction or loss occurred.

<a id="p114934"></a>Article 265

<a id="p114935"></a>Bill of discharge
(Article 215 of the Code)

1. <a id="p114936"></a>Without prejudice to Articles 46 and 48 of the Code, the supervising customs office shall control the bill of discharge as referred to in Article 175(1) of Delegated Regulation (EU) 2015/2446 without delay.
<a id="p114937"></a>The supervising customs office may accept the amount of import duty payable as determined by the holder of the authorisation.
2. <a id="p114938"></a>The amount of import duty payable shall be entered in the accounts as referred to in Article 104 of the Code within 14 days from the date on which the bill of discharge was communicated to the supervising customs office.

<a id="p114939"></a>Article 266

<a id="p114940"></a>Transfer of rights and obligations
(Article 218 of the Code)

<a id="p114941"></a>The competent customs authority shall decide whether a transfer of rights and obligations as referred to in Article 218 of the Code may take place or not. If such transfer may take place, the competent customs authority shall establish the conditions under which the transfer is allowed.

<a id="p114942"></a>Article 267

<a id="p114943"></a>Movement of goods under a special procedure
(Article 219 of the Code)

1. <a id="p114944"></a>Movement of goods to the customs office of exit with a view to discharging a special procedure other than end-use and outward processing by taking goods out of the customs territory of the Union shall be carried out under cover of the re-export declaration.
2. <a id="p114945"></a>Where goods are moved under outward processing from the customs office of placement to the customs office of exit, the goods shall be subject to the provisions that would have been applicable had the goods been placed under the export procedure.
3. <a id="p114946"></a>Where goods are moved under end-use to the customs office of exit, the goods shall be subject to the provisions that would have been applicable had the goods been placed under the export procedure.
4. <a id="p114947"></a>Customs formalities other than keeping of records as referred to in Article 214 of the Code are not required for any movement which is not covered by paragraphs 1 to 3.
5. <a id="p114948"></a>Where movement of goods takes place in accordance with paragraphs 1 or 3, the goods shall remain under the special procedure until they have been taken out of the customs territory of the Union.

<a id="p114949"></a>Article 268

<a id="p114950"></a>Formalities for the use of equivalent goods
(Article 223 of the Code)

1. <a id="p114951"></a>The use of equivalent goods shall not be subject to the formalities for placing goods under a special procedure.
2. <a id="p114952"></a>Equivalent goods may be stored together with other Union goods or non-Union goods. In such cases, the customs authorities may establish specific methods of identifying the equivalent goods with a view to distinguishing them from the other Union goods or non-Union goods.
<a id="p114953"></a>Where it is impossible or would only be possible at disproportionate cost to identify at all times each type of goods, accounting segregation shall be carried out with regard to each type of goods, customs status and, where appropriate, origin of the goods.
3. <a id="p114954"></a>In the case of end-use, the goods which are replaced by equivalent goods shall no longer be under customs supervision in any of the following cases:
<a id="p114955"></a>(a) the equivalent goods have been used for the purposes laid down for the application of the duty exemption or reduced rate of duty;
<a id="p114956"></a>(b) the equivalent goods are exported, destroyed or abandoned to the State;
<a id="p114957"></a>(c) the equivalent goods have been used for purposes other than those laid down for the application of the duty exemption or reduced duty rate and the applicable import duty has been paid.

<a id="p114958"></a>Article 269

<a id="p114959"></a>Status of equivalent goods
(Article 223 of the Code)

1. <a id="p114960"></a>In case of customs warehousing and temporary admission, the equivalent goods shall become non-Union goods and the goods which they are replacing shall become Union goods at the time of their release for the subsequent customs procedure discharging the procedure or at the time when the equivalent goods have left the customs territory of the Union.
2. <a id="p114961"></a>In case of inward processing, the equivalent goods and the processed products obtained therefrom shall become non-Union goods and the goods which they are replacing shall become Union goods at the time of their release for the subsequent customs procedure discharging the procedure or at the time when the processed products have left the customs territory of the Union.
<a id="p114962"></a>However, where the goods placed under the inward processing procedure are put on the market before the procedure is discharged, their status shall change at the time when they are put on the market. In exceptional cases, where the equivalent goods are expected not to be available at the time when the goods are put on the market, the customs authorities may allow, at the request of the holder of the procedure, the equivalent goods to be available at a later time within a reasonable period to be determined by them.
3. <a id="p114963"></a>In case of prior export of processed products under inward processing, the equivalent goods and the processed products obtained therefrom shall become non-Union goods with retroactive effect at the time of their release for the export procedure if the goods to be imported are placed under that procedure.
<a id="p114964"></a>Where the goods to be imported are placed under inward processing, they shall at the same time become Union goods.

<a id="p114965"></a>Article 270

<a id="p114966"></a>Electronic system relating to eATA carnets
(Article 16(1) of the Code)

<a id="p114967"></a>An electronic information and communication system (eATA Carnet System) set up pursuant to Article 16(1) of the Code shall be used for the processing, exchange and storage of information pertaining to eATA carnets issued based on Article 21a of the Istanbul Convention. Information shall be made available through this system by the competent customs authorities without delay.

<a id="p114968"></a>Article 271

<a id="p114969"></a>Electronic system relating
to Standardised exchange of information
(Article 16(1) of the Code)

1. <a id="p114970"></a>An electronic information and communication system set up pursuant to Article 16(1) of the Code shall be used for the standardised exchange of information (INF) pertaining to any of the following procedures:
<a id="p114971"></a>(a) inward processing EX/IM or outward processing EX/IM;
<a id="p114972"></a>(b) inward processing IM/EX or outward processing IM/EX, where more than one Member State is involved;
<a id="p114973"></a>(c) inward processing IM/EX where one Member State is involved and the responsible customs authority as referred to in Article 101(1) of the Code has requested an INF.
<a id="p114974"></a>Such system shall also be used for the processing and storage of the relevant information. Where an INF is required, the information shall be made available through this system by the supervising customs office without delay. Where a customs declaration, re-export declaration or re-export notification refers to an INF, the competent customs authorities shall update the INF without delay.
<a id="p114975"></a>In addition, the electronic information and communication system shall be used for the standardised exchange of information pertaining to commercial policy measures.
<a id="p114976"></a>1a. Economic operators shall use an EU harmonised trader interface designed by the Commission and the Member States in agreement with each other for the standardised exchange of information (INF) pertaining to the procedures referred to in paragraph 1.
2. <a id="p114977"></a>Paragraphs 1 and 1a of this Article shall apply from the date of deployment of the UCC Information Sheets (INF) for Special Procedures set out in the Annex to Implementing Decision (EU) 2019/2151.

<a id="p114978"></a>**CHAPTER 2**

<a id="p114979"></a>**TRANSIT**

<a id="p114980"></a>Section 1. EXTERNAL AND INTERNAL TRANSIT PROCEDURE

<a id="p114981"></a>Subsection 1

<a id="p114982"></a>**GENERAL PROVISIONS**

<a id="p114983"></a>Article 272

<a id="p114984"></a>Controls and formalities for goods leaving
and re-entering the customs territory of the Union
(Articles 226(3)(b), (c), (e), (f) and 227(2)(b),
(c), (e), (f) of the Code)

<a id="p114985"></a>Where, in the course of movement of goods from one point to another within the customs territory of the Union, goods leave and re-enter the customs territory of the Union, the customs controls and formalities applicable in accordance with the TIR Convention, the ATA Convention, the Istanbul Convention, the Agreement between the Parties to the North Atlantic Treaty regarding the Status of their Forces, signed in London on 19 June 1951 or in accordance with the acts of the Universal Postal Union shall be carried out at the points where the goods temporarily leave the customs territory of the Union and where they re-enter that territory.

<a id="p114986"></a>Article 273

<a id="p114987"></a>Electronic system relating to transit
(Article 16(1) of the Code)

1. <a id="p114988"></a>For the exchange of TIR carnet data for TIR operations and for the completion of the customs formalities of Union transit procedures, an electronic system set up pursuant to Article 16(1) of the Code (electronic transit system) shall be used.
2. <a id="p114989"></a>In case of discrepancies between the particulars in the TIR carnet and the particulars in the electronic transit system, the TIR carnet shall prevail.
3. <a id="p114990"></a>By derogation from paragraph 1 of this Article, until the date of the upgrading of the system referred to therein in accordance with the Annex to Implementing Decision 2014/255/EU, Member States shall use the New Computerised Transit System set up by Commission Regulation (EC) No 1192/2008 <*>.

<a id="p114991"></a>

---

<a id="p114992"></a><*> Commission Regulation (EC) No 1192/2008 of 17 November 2008 amending Regulation (EEC) No 2454/93 laying down provisions for the implementation of Council Regulation (EEC) No 2913/92 establishing the Community Customs Code (OJ L 329, 6.12.2008, p. 1).

<a id="p114993"></a>Subsection 2

<a id="p114994"></a>**MOVEMENT OF GOODS UNDER THE TIR OPERATIONS**

<a id="p114995"></a>Article 274

<a id="p114996"></a>TIR operation in particular circumstances
(Articles 6(3)(b), 226(3)(b) and 227(2)(b) of the Code)

<a id="p114997"></a>The customs authority shall accept a TIR carnet without exchange of TIR carnet data for the TIR operation in the event of a temporary failure of:
<a id="p114998"></a>(a) the electronic transit system;
<a id="p114999"></a>(b) the computerised system used by the TIR carnet holders for lodging the TIR carnet data by means of electronic data-processing techniques;
<a id="p115000"></a>(c) the electronic connection between the computerised system used by the TIR carnet holders for lodging the TIR carnet data by means of electronic data-processing techniques and the electronic transit system.
<a id="p115001"></a>The acceptance of TIR carnets without exchange of TIR carnet data in the event of a temporary failure as referred to in points (b) or (c) shall be subject to the approval of the customs authorities.

<a id="p115002"></a>Article 275

<a id="p115003"></a>Itinerary for movements of goods under a TIR operation
(Articles 226(3)(b) and 227(2)(b) of the Code)

1. <a id="p115004"></a>Goods moved under a TIR operation shall be transported to the customs office of destination or exit along an economically justified itinerary.
2. <a id="p115005"></a>Where the customs office of departure or entry considers it necessary, it shall prescribe an itinerary for the TIR operation taking into account any relevant information communicated by the TIR carnet holder.
<a id="p115006"></a>When prescribing an itinerary, the customs office shall enter in the electronic transit system and on the TIR carnet at least the indication of the Member States through which the TIR operation is to take place.

<a id="p115007"></a>Article 276

<a id="p115008"></a>Formalities to be completed
at the customs office of departure or entry
for movements of goods under a TIR operation
(Articles 226(3)(b) and 227(2)(b) of the Code)

1. <a id="p115009"></a>The TIR carnet holder shall submit the TIR carnet data for the TIR operation at the customs office of departure or entry.
2. <a id="p115010"></a>The customs office to which the TIR carnet data has been submitted shall set a time-limit within which the goods shall be presented at the customs office of destination or exit, taking into account the following:
<a id="p115011"></a>(a) the itinerary;
<a id="p115012"></a>(b) the means of transport;
<a id="p115013"></a>(c) transport legislation or other legislation which might have an impact on setting a time-limit;
<a id="p115014"></a>(d) any relevant information communicated by the TIR carnet holder.
3. <a id="p115015"></a>Where the time-limit is set by the customs office of departure or entry, it shall be binding on the customs authorities of the Member States the territory of which the goods enter during the TIR operation, and that time-limit shall not be altered by those authorities.
4. <a id="p115016"></a>Where the goods are released for the TIR operation, the customs office of departure or entry shall record the MRN of the TIR operation in the TIR carnet. The customs office releasing those goods shall notify the TIR carnet holder of the release of the goods for the TIR operation.
<a id="p115017"></a>At the request of the TIR carnet holder the customs office of departure or entry shall provide a transit accompanying document or, where appropriate, a transit/security accompanying document to the TIR carnet holder.
<a id="p115018"></a>The transit accompanying document shall be provided using the form set out in Annex B-02 to Delegated Regulation (EU) 2015/2446 and, if necessary, supplemented by the List of items in the form set out in Annex B-03 to the same Delegated Regulation. The transit/security accompanying document shall be provided using the form set out in Annex B-04 to the same Delegated Regulation and supplemented by the Transit/Security list of items in the form set out in Annex B-05 to the same Delegated Regulation.
5. <a id="p115019"></a>The customs office of departure or entry shall transmit the particulars of the TIR operation to the declared customs office of destination or exit.

<a id="p115020"></a>Article 277

<a id="p115021"></a>Incidents during movement of goods under a TIR operation
(Articles 226(3)(b) and 227(2)(b) of the Code)

1. <a id="p115022"></a>The carrier shall present without undue delay after the incident the goods together with the road vehicle, the combination of vehicles or the container, the TIR carnet and the MRN of the TIR operation to the nearest customs authority of the Member State in whose territory the means of transport is located where:
<a id="p115023"></a>(a) the carrier is obliged to deviate from the itinerary prescribed in accordance with Article 275 due to circumstances beyond his control;
<a id="p115024"></a>(b) there is an incident or accident within the meaning of Article 25 of the TIR Convention.
2. <a id="p115025"></a>Where the customs authority in whose territory the means of transport is located considers that the TIR operation concerned may continue, it shall take any steps that it considers necessary.
<a id="p115026"></a>Relevant information concerning the incidents referred to in paragraph 1 shall be recorded in the electronic transit system by that customs authority.
3. <a id="p115027"></a>Until the dates of deployment of the upgrading of the NCTS referred to in the Annex to Implementing Decision 2014/255/EU, relevant information concerning the incidents referred to in paragraph 1 shall be recorded in the electronic transit system by the customs office of destination or exit.
4. <a id="p115028"></a>Until the dates of deployment of the upgrading of the NCTS referred to in the Annex to Implementing Decision 2014/255/EU, the second subparagraph of paragraph 2 of this Article shall not apply.

<a id="p115029"></a>Article 278

<a id="p115030"></a>Presentation of goods moved under a TIR operation
at the customs office of destination or exit
(Articles 226(3)(b) and 227(2)(b) of the Code)

1. <a id="p115031"></a>Where goods moved under a TIR operation arrive at the customs office of destination or exit, the following shall be presented at that customs office:
<a id="p115032"></a>(a) the goods together with the road vehicle, the combination of vehicles or the container;
<a id="p115033"></a>(b) the TIR carnet;
<a id="p115034"></a>(c) the MRN of the TIR operation;
<a id="p115035"></a>(d) any information required by the customs office of destination or exit.
<a id="p115036"></a>The presentation shall take place during the official opening hours. However, the customs office of destination or exit may, at the request of the person concerned, allow the presentation to take place outside the official opening hours or at another place.
2. <a id="p115037"></a>Where the presentation has taken place at the customs office of destination or exit after expiry of the time-limit set by the customs office of departure or entry in accordance with Article 276(2) of this Regulation, the TIR carnet holder shall be deemed to have complied with the time-limit where he or the carrier proves to the satisfaction of the customs office of destination or exit that the delay is not attributable to him.
3. <a id="p115038"></a>A TIR operation may be terminated at a customs office other than that declared in the transit declaration. That customs office shall then be considered to be the customs office of destination or exit.

<a id="p115039"></a>Article 279

<a id="p115040"></a>Formalities at the customs office of destination
or exit for goods moved under a TIR operation
(Articles 226(3)(b) and 227(2)(b) of the Code)

1. <a id="p115041"></a>The customs office of destination or exit shall notify the customs office of departure or entry of the arrival of the goods on the day the goods together with the road vehicle, the combination of vehicles or the container, the TIR carnet, the MRN of the TIR operation are presented in accordance with Article 278(1) of this Regulation.
2. <a id="p115042"></a>Where the TIR operation is terminated at a customs office other than that declared in the transit declaration, the customs office considered to be the customs office of destination or exit in accordance with Article 278(3) of this Regulation shall notify the arrival to the customs office of departure or entry on the day the goods are presented in accordance with Article 278(1) of this Regulation.
<a id="p115043"></a>The customs office of departure or entry shall notify the arrival to the customs office of destination or exit declared in the transit declaration.
3. <a id="p115044"></a>The customs office of destination or exit shall notify the control results to the customs office of departure or entry at the latest on the third day following the day the goods are presented at the customs office of destination or exit or at another place in accordance with Article 278(1) of this Regulation. In exceptional cases that time-limit may be extended up to 6 days.
<a id="p115045"></a>However, where goods are received by an authorised consignee referred to in Article 230 of the Code, the customs office of departure or entry shall be notified at the latest on the sixth day following the day the goods were delivered to the authorised consignee.
4. <a id="p115046"></a>The customs office of destination or exit shall terminate the TIR operation in accordance with Articles 1(d) and 28(1) of the TIR Convention. It shall complete counterfoil No 2 of the TIR carnet and retain Voucher No 2 of the TIR carnet. The TIR carnet shall be returned to the TIR carnet holder or to the person acting on his behalf.
5. <a id="p115047"></a>Where Article 274 of this Regulation applies, the customs authorities of the Member State of destination or exit shall return the appropriate part of Voucher No 2 of the TIR carnet to the customs office of departure or entry without delay and at the latest within 8 days from the date when the TIR operation was terminated.

<a id="p115048"></a>Article 280

<a id="p115049"></a>Enquiry procedure
for movements of goods under a TIR operation
(Articles 226(3)(b) and 227(2)(b) of the Code)

1. <a id="p115050"></a>Where the customs office of departure or entry has not received the control results within 6 days after receiving the notification of arrival of the goods, that customs office shall immediately request the control results from the customs office of destination or exit which sent the notification of arrival of the goods.
<a id="p115051"></a>The customs office of destination or exit shall send the control results immediately after receiving the request from the customs office of departure or entry.
2. <a id="p115052"></a>Where the customs authority of the Member State of departure or entry has not yet received information that allows for the discharge of the TIR operation or for the recovery of the customs debt, it shall request the relevant information from the TIR carnet holder or, where sufficient particulars are available at the place of destination or exit, from the customs office of destination or exit, in the following cases:
<a id="p115053"></a>(a) the customs office of departure or entry has not received the notification of arrival of the goods by the expiry of the time-limit for the presentation of the goods set in accordance with Article 276(2) of this Regulation;
<a id="p115054"></a>(b) the customs office of departure or entry has not received the control results requested in accordance with paragraph 1;
<a id="p115055"></a>(c) the customs office of departure or entry becomes aware that the notification of arrival of the goods or the control results were sent in error.
3. <a id="p115056"></a>The customs authority of the Member State of departure or entry shall send requests for information in accordance with paragraph 2(a) within a period of 7 days after the expiry of the time-limit referred to therein and requests for information in accordance with paragraph 2(b) within a period of 7 days after the expiry of the applicable time-limit referred to in paragraph 1.
<a id="p115057"></a>However, if, before the expiry of those time-limits, the customs authority of the Member State of departure or entry receives information that the TIR operation has not been terminated correctly, or suspects that to be the case, it shall send the request without delay.
4. <a id="p115058"></a>Replies to requests made in accordance with paragraph 2 shall be sent within 28 days from the date on which the request was sent.
5. <a id="p115059"></a>Where, following a request in accordance with paragraph 2, the customs office of destination or exit has not provided sufficient information for the TIR operation to be discharged, the customs authority of the Member State of departure or entry shall request the TIR carnet holder to provide that information, at the latest 35 days after the initiating the enquiry procedure.
<a id="p115060"></a>However, until the dates of deployment of the upgrading of the NCTS referred to in Annex to Implementing Decision 2014/255/EU, that customs authority shall request the TIR carnet holder to provide that information, at the latest 28 days after the initiating the enquiry procedure.
<a id="p115061"></a>The TIR carnet holder shall reply to that request within 28 days from the date on which it was sent. At the request of the TIR carnet holder this period may be extended for further 28 days.
6. <a id="p115062"></a>Where a TIR carnet has been accepted without exchange of TIR carnet data for the TIR operation in accordance with Article 274, the customs authority of the Member State of departure or entry shall initiate an enquiry procedure in order to obtain the information needed to discharge the TIR operation if, after 2 months from the date of the acceptance of the TIR carnet, it has not received proof that the TIR operation has been terminated. This authority sends the request for the relevant information to the customs authority of the Member State of destination or exit. That customs authority shall reply to that request within 28 days from the date on which it was sent.
<a id="p115063"></a>However, if, before the expiry of that period, the customs authority of the Member State of departure or entry receives information that the TIR operation has not been terminated correctly, or suspects that to be the case, it shall initiate the enquiry procedure without delay.
<a id="p115064"></a>The enquiry procedure shall also be initiated by the customs authority of the Member State of departure or entry if information becomes available that proof of the termination of the TIR operation was falsified and the enquiry procedure is necessary to achieve the objectives of the paragraph 9.
7. <a id="p115065"></a>The customs authority of the Member State of departure or entry shall inform the guaranteeing association concerned that it has not been possible to discharge the TIR operation, and invite it to provide proof that the TIR operation has been terminated. That information shall not be considered a notification within the meaning of Article 11(1) of the TIR Convention.
8. <a id="p115066"></a>Where during the steps of an enquiry procedure set out in paragraphs 1 to 7 it is established that the TIR operation was terminated correctly, the customs authority of the Member State of departure or entry shall discharge the TIR operation and shall immediately inform the guaranteeing association and the TIR carnet holder and, where appropriate, any customs authority that may have initiated a recovery procedure.
9. <a id="p115067"></a>Where during the steps of an enquiry procedure set out in paragraphs 1 to 7 it is established that the TIR operation cannot be discharged, the customs authority of the Member State of departure or entry shall establish whether a customs debt has been incurred.
<a id="p115068"></a>If a customs debt has been incurred, the customs authority of the Member State of departure or entry shall take the following measures:
<a id="p115069"></a>(a) identify the debtor;
<a id="p115070"></a>(b) determine the customs authority responsible for the notification of the customs debt in accordance with Article 102(1) of the Code.

<a id="p115071"></a>Article 281

<a id="p115072"></a>Alternative proof of termination of a TIR operation
(Articles 226(3)(b) and 227(2)(b) of the Code)

1. <a id="p115073"></a>The TIR operation shall be considered as having been terminated correctly within the time-limit set in accordance with Article 276(2) of this Regulation where the TIR carnet holder or the guaranteeing association presents, to the satisfaction of the customs authority of a Member State of departure or entry, one of the following documents identifying the goods:
<a id="p115074"></a>(a) a document certified by the customs authority of the Member State of destination or exit which identifies the goods and establishes that the goods have been presented at the customs office of destination or exit, or been delivered to an authorised consignee as referred to in Article 230 of the Code;
<a id="p115075"></a>(b) a document or a customs record, certified by the customs authority of a Member State, which establishes that the goods have physically left the customs territory of the Union;
<a id="p115076"></a>(c) a customs document issued in a third country where the goods are placed under a customs procedure;
<a id="p115077"></a>(d) a document issued in a third country, stamped or otherwise certified by the customs authority of that country and establishing that the goods are considered to be in free circulation in that country.
2. <a id="p115078"></a>Instead of the documents referred to in paragraph 1, copies thereof certified as being true copies by the body which certified the original documents, by the authority of the third country concerned or by an authority of a Member State may be provided as proof.
3. <a id="p115079"></a>The notification of arrival of the goods referred to in Article 279(1) and (2) of this Regulation shall not be considered to be proof that the TIR operation has been terminated correctly.

<a id="p115080"></a>Article 282

<a id="p115081"></a>Formalities for goods moved under
the TIR operation received by an authorised consignee
(Articles 226(3)(b) and 227(2)(b) of the Code)

1. <a id="p115082"></a>When the goods arrive at a place specified in the authorisation referred to in Article 230 of the Code, the authorised consignee shall:
<a id="p115083"></a>(a) immediately notify the customs office of destination of arrival of the goods and inform it of any irregularities or incidents that occurred during transport;
<a id="p115084"></a>(b) unload the goods only after obtaining the permission from the customs office of destination;
<a id="p115085"></a>(c) after unloading, enter the results of the inspection and any other relevant information relating to the unloading into his records without delay;
<a id="p115086"></a>(d) notify the customs office of destination of the results of the inspection of the goods and inform it of any irregularities on the third day following the day on which he has received the permission to unload the goods, at the latest.
2. <a id="p115087"></a>When the customs office of destination has received notification of arrival of the goods at the premises of the authorised consignee, it shall notify the customs office of departure or entry of the arrival of the goods.
3. <a id="p115088"></a>When the customs office of destination has received the results of the inspection of the goods referred to in paragraph 1(d) it shall send the control results to the customs office of departure or entry on the sixth day following the day the goods were delivered to the authorised consignee, at the latest.
4. <a id="p115089"></a>At the request of the TIR carnet holder, the authorised consignee shall issue a receipt which certifies the arrival of the goods at a place specified in the authorisation referred to in Article 230 of the Code and contains a reference to the MRN of the TIR operation and to the TIR carnet. The receipt shall not be considered to be proof that the TIR operation has been terminated within the meaning of Article 279(4) of this Regulation.
5. <a id="p115090"></a>The authorised consignee shall ensure that the TIR carnet together with the MRN of the TIR operation are presented within the time-limit laid down in the authorisation, at the customs office of destination for the purposes of terminating the TIR operation in accordance with Article 279(4) of this Regulation.
6. <a id="p115091"></a>The TIR carnet holder shall be considered to have fulfilled his obligations under Article 1(o) of the TIR Convention where the TIR carnet together with the road vehicle, the combination of vehicles or the container and the goods have been presented intact to the authorised consignee at a place specified in the authorisation.

<a id="p115092"></a>Subsection 3

<a id="p115093"></a>**MOVEMENT OF GOODS IN ACCORDANCE WITH THE ATA CONVENTION AND**
**THE ISTANBUL CONVENTION**

<a id="p115094"></a>Article 283

<a id="p115095"></a>Notification of offences and irregularities
(Articles 226(3)(c) and 227(2)(c) of the Code)

<a id="p115096"></a>The customs office of coordination, referred to in Article 166, of the Member State where an offence or irregularity has been committed in the course of or in connection with an ATA transit movement shall notify the ATA carnet holder and the guaranteeing association of the offence or irregularity within a year of the date of expiry of the validity of the carnet.

<a id="p115097"></a>Article 284

<a id="p115098"></a>Alternative proof
of termination of the ATA transit operation
(Articles 226(3)(c) and 227(2)(c) of the Code)

1. <a id="p115099"></a>The ATA transit operation shall be considered as having been terminated correctly where the ATA carnet holder presents, within the time-limits prescribed in Article 7(1) and (2) of the ATA Convention where the carnet is issued under the ATA Convention or in Article 9(1)(a) and (b) of Annex A to the Istanbul Convention where the carnet is issued under the Istanbul Convention and to the satisfaction of the customs authority, one of the following documents identifying the goods:
<a id="p115100"></a>(a) the documents referred to in Article 8 of the ATA Convention where the carnet is issued under the ATA Convention or in Article 10 of Annex A to the Istanbul Convention where the carnet is issued under the Istanbul Convention;
<a id="p115101"></a>(b) a document certified by the customs authority establishing that the goods have been presented at the customs office of destination or exit;
<a id="p115102"></a>(c) a document issued by the customs authorities in a third country where the goods are placed under a customs procedure.
2. <a id="p115103"></a>Instead of the documents referred to in paragraph 1, copies thereof certified as being true copies by the body which certified the original documents may be provided as proof.

<a id="p115104"></a>Subsection 4

<a id="p115105"></a>**MOVEMENT OF GOODS UNDER COVER**
**OF NATO FORM 302 OR EU FORM 302**

<a id="p115106"></a>Article 286

<a id="p115107"></a>Supply of NATO forms 302 to NATO forces
(Articles 226(3)(e) and 227(2)(e) of the Code)

<a id="p115108"></a>The designated customs office of the Member State of departure shall supply the NATO forces stationed in its territory with NATO forms 302 which:
<a id="p115109"></a>(a) are pre-authenticated with the stamp and signature of an official of that office;
<a id="p115110"></a>(b) are serially numbered;
<a id="p115111"></a>(c) bear the full address of that designated customs office for the return copy of the NATO form 302.

<a id="p115112"></a>Article 286a

<a id="p115113"></a>Supply of EU forms 302
to military forces of the Member States
(Articles 226(3)(a) and 227(2)(a) of the Code)

<a id="p115114"></a>The designated customs office of the Member State of departure shall supply the military forces of a Member State stationed in its territory with EU forms 302 which:
<a id="p115115"></a>(a) are pre-authenticated with the stamp and signature of an official of that office;
<a id="p115116"></a>(b) are serially numbered;
<a id="p115117"></a>(c) bear the full address of that designated customs office for the return copy of the EU form 302.

<a id="p115118"></a>Article 287

<a id="p115119"></a>Procedural rules applying to the use of NATO form 302
(Articles 226(3)(e) and 227(2)(e) of the Code)

1. <a id="p115120"></a>At the time of dispatch of the goods, the NATO forces shall do either of the following:
<a id="p115121"></a>(a) lodge the NATO form 302 data electronically at the customs office of departure or entry;
<a id="p115122"></a>(b) complete NATO form 302 with a statement that the goods are being moved under their control and authenticate this statement by their signature, stamp and date;
2. <a id="p115123"></a>Where the NATO forces lodge the NATO form 302 data electronically in accordance with point (a) of paragraph 1 of this Article, Articles 294, 296, 304, 306 and 314 to 316 of this Regulation shall apply mutatis mutandis.
3. <a id="p115124"></a>Where the NATO forces proceed in accordance with point (b) of paragraph 1, they shall, without delay, give a copy of the NATO form 302 to the designated customs office responsible for customs formalities and controls pertaining to the NATO forces dispatching the goods or on whose behalf the goods are being dispatched.
<a id="p115125"></a>The other copies of the NATO form 302 shall accompany the consignment to the NATO forces of destination, which shall stamp and sign them upon arrival of the goods.
<a id="p115126"></a>At the time of arrival of the goods, two copies of the NATO 302 form shall be given to the customs office designated as responsible for customs formalities and controls pertaining to the NATO forces of destination.
<a id="p115127"></a>That designated customs office shall retain one copy of the NATO 302 form and shall return the second copy to the customs office responsible for customs formalities and controls pertaining to the NATO forces dispatching the goods or on whose behalf the goods are being dispatched.

<a id="p115128"></a>Article 287a

<a id="p115129"></a>Procedural rules applying to the use of EU form 302
(Articles 226(3)(a) and 227(2)(a) of the Code)

1. <a id="p115130"></a>At the time of dispatch of the goods, the military forces of the Member State shall do either of the following:
<a id="p115131"></a>(a) lodge the EU form 302 data electronically at the customs office of departure or entry;
<a id="p115132"></a>(b) complete the EU form 302 with a statement that the goods are being moved under their control and authenticate this statement by their signature, stamp and date.
2. <a id="p115133"></a>Where the military forces of the Member State lodge the EU form 302 data electronically in accordance with point (a) of paragraph 1 of this Article, Articles 294, 296, 304, 306 and 314 to 316 shall apply mutatis mutandis.
3. <a id="p115134"></a>Where the military forces of the Member State proceed in accordance with point (b) of paragraph 1, they shall, without delay, give a copy of the EU form 302 to the designated customs office responsible for customs formalities and controls pertaining to the military forces of the Member State dispatching the goods or on whose behalf the goods are being dispatched.
<a id="p115135"></a>The other copies of the EU form 302 shall accompany the consignment to the military forces of the Member State of destination, which shall stamp and sign them upon arrival of the goods.
<a id="p115136"></a>At the time of arrival of the goods, two copies of the EU form 302 shall be given to the customs office designated as responsible for customs formalities and controls pertaining to the military forces of the Member State of destination.
<a id="p115137"></a>That designated customs office shall retain one copy of the EU form 302 and shall return the second copy to the customs office responsible for customs formalities and controls pertaining to the military forces of the Member State dispatching the goods or on whose behalf the goods are being dispatched.

<a id="p115138"></a>Subsection 5

<a id="p115139"></a>**TRANSIT OF GOODS TRANSPORTED UNDER THE POSTAL SYSTEM**

<a id="p115140"></a>Article 288

<a id="p115141"></a>Movement of non-Union goods in postal consignments under the external transit procedure
(Article 226(3)(f) of the Code)

<a id="p115142"></a>Where non-Union goods are moved under the external transit procedure in accordance with Article 226(3)(f) of the Code, the postal consignment and any accompanying documents shall bear a label set out in Annex 72-01.

<a id="p115143"></a>Article 289

<a id="p115144"></a>Movement of postal consignments
containing both Union and non-Union goods
(Articles 226(3)(f) and 227(2)(f) of the Code)

1. <a id="p115145"></a>Where a postal consignment contains both Union goods and non-Union goods that consignment and any accompanying documents shall bear a label set out in Annex 72-01.
2. <a id="p115146"></a>For the Union goods contained in a consignment as referred to in paragraph 1, proof of the customs status of Union goods or a reference to the MRN of that means of proof shall be sent separately to the postal operator of destination or be enclosed in the consignment.
<a id="p115147"></a>Where the proof of the customs status of Union goods is sent separately to the postal operator of destination, that postal operator shall present the proof of the customs status of Union goods to the customs office of destination together with the consignment.
<a id="p115148"></a>Where the proof of customs status of Union goods or its MRN is enclosed in the consignment, that shall be clearly indicated on the exterior of the package.

<a id="p115149"></a>Article 290

<a id="p115150"></a>Movement of postal consignments under the internal
transit procedure in special situations
(Article 227(2)(f) of the Code)

1. <a id="p115151"></a>Where Union goods are moved to, from or between special fiscal territories under the internal transit procedure in accordance with Article 227(2)(f) of the Code, the postal consignment and any accompanying documents shall bear a label set out in Annex 72-02.
2. <a id="p115152"></a>Where Union goods are moved under the internal transit procedure in accordance with Article 227(2)(f) of the Code from the customs territory of the Union to a common transit country for onward transmission to the customs territory of the Union, those goods shall be accompanied by proof of the customs status of Union goods established by one of the means listed in Article 199 of this Regulation.
<a id="p115153"></a>The proof of the customs status of Unions goods shall be presented to a customs office on re-entry in the customs territory of the Union.

<a id="p115154"></a>Section 2. EXTERNAL AND INTERNAL UNION TRANSIT PROCEDURE

<a id="p115155"></a>Subsection 1

<a id="p115156"></a>**GENERAL PROVISIONS**

<a id="p115157"></a>Article 291

<a id="p115158"></a>Transit operation in particular circumstances
(Articles 6(3)(b), 226(3)(a) and 227(2)(a) of the Code)

1. <a id="p115159"></a>The customs authority shall accept a paper-based transit declaration in the event of a temporary failure of:
<a id="p115160"></a>(a) the electronic transit system;
<a id="p115161"></a>(b) the computerised system used by the holders of the procedure for lodging the Union transit declaration by means of electronic data-processing techniques;
<a id="p115162"></a>(c) the electronic connection between the computerised system used by the holders of the procedure for lodging the Union transit declaration by means of electronic data-processing techniques and the electronic transit system.
<a id="p115163"></a>The rules on the use of a paper-based transit declaration shall be laid down in Annex 72-04.
2. <a id="p115164"></a>The acceptance of a paper-based transit declaration in the event of a temporary failure as referred to in points (b) or (c) shall be subject to the approval of the customs authorities.

<a id="p115165"></a>Article 292

<a id="p115166"></a>Verification and administrative assistance
(Article 48 of the Code)

1. <a id="p115167"></a>The competent customs authority may carry out post-release controls of the information supplied and of any documents, forms, authorisations or data relating to the transit operation in order to check that the entries, the information exchanged and the stamps are authentic. Such controls shall be made where doubts arise as to the accuracy and authenticity of the information provided or where fraud is suspected. It may also be made on the basis of risk analysis or by random selection.
2. <a id="p115168"></a>A competent customs authority receiving a request to make a post-release control shall respond without delay.
3. <a id="p115169"></a>Where the competent customs authority of the Member State of departure makes a request to the competent customs authority for a post-release control of information related to the Union transit operation, the conditions laid down in Article 215(2) of the Code for discharging the transit procedure shall be deemed not to have been fulfilled until the authenticity and accuracy of the data have been confirmed.

<a id="p115170"></a>Article 293

<a id="p115171"></a>The Convention on a common transit procedure
(Articles 226(3)(a) and 227(2)(a) of the Code)

1. <a id="p115172"></a>Where the holder of the goods uses the common transit procedure, paragraph 2 of this Article and Article 189 of Delegated Regulation (EU) 2015/2446 shall apply. However, goods circulating within the customs territory of the Union shall be deemed to be placed under the Union transit procedure in accordance with Article 1(2) of the Convention on a common transit procedure.
2. <a id="p115173"></a>Where the provisions of the Convention on a common transit procedure apply and Union goods pass through one or more common transit countries, the goods shall be placed under the internal Union transit procedure as referred to in Article 227(2)(a) of the Code, except for Union goods which are carried entirely by sea or air.

<a id="p115174"></a>Article 294

<a id="p115175"></a>Mixed consignments
(Articles 226(3)(a) and 227(2)(a) of the Code)

<a id="p115176"></a>A consignment may comprise both goods which are to be placed under the external Union transit procedure in accordance with Article 226 of the Code and goods which are to be placed under the internal Union transit procedure in accordance with Article 227 of the Code, provided that each item of the goods is marked accordingly in the transit declaration.

<a id="p115177"></a>Article 295

<a id="p115178"></a>Scope
(Article 226(3)(a) of the Code)

<a id="p115179"></a>The Union transit procedure shall be compulsory in the following cases:
<a id="p115180"></a>(a) where non-Union goods carried by air are loaded or reloaded at an Union airport;
<a id="p115181"></a>(b) where non-Union goods carried by sea are carried by a regular shipping service authorised in accordance with Article 120 of Delegated Regulation (EU) 2015/2446.

<a id="p115182"></a>Subsection 2

<a id="p115183"></a>**FORMALITIES AT THE CUSTOMS OFFICE OF DEPARTURE**

<a id="p115184"></a>Article 296

<a id="p115185"></a>Transit declaration and means of transport
(Articles 226(3)(a) and 227(2)(a) of the Code)

1. <a id="p115186"></a>Each transit declaration shall include only goods placed under the Union transit procedure that are moved or are to be moved from one customs office of departure to one customs office of destination on a single means of transport, in a container or in a package.
<a id="p115187"></a>However, one transit declaration may include goods moved or to be moved from one customs office of departure to one customs office of destination in more than one container or in more than one package where the containers or packages are loaded on a single means of transport.
2. <a id="p115188"></a>For the purposes of this Article, any of the following shall also be regarded as constituting a single means of transport, provided that the goods carried are dispatched together:
<a id="p115189"></a>(a) a road vehicle accompanied by its trailer(s) or semi-trailer(s);
<a id="p115190"></a>(b) a set of coupled railway carriages or wagons;
<a id="p115191"></a>(c) boats constituting a single chain.
3. <a id="p115192"></a>Where for the purpose of the Union transit procedure a single means of transport is used for loading goods at more than one customs office of departure and for unloading at more than one customs office of destination, separate transit declarations shall be lodged for each of the consignments.

<a id="p115193"></a>Article 297

<a id="p115194"></a>Time-limit for the presentation of goods
(Articles 226(3)(a) and 227(2)(a) of the Code)

1. <a id="p115195"></a>The customs office of departure shall set a time-limit within which the goods shall be presented at the customs office of destination, taking into account the following:
<a id="p115196"></a>(a) the itinerary;
<a id="p115197"></a>(b) the means of transport;
<a id="p115198"></a>(c) transport legislation or other legislation which might have an impact on setting a time-limit;
<a id="p115199"></a>(d) any relevant information communicated by the holder of the procedure.
2. <a id="p115200"></a>Where the time-limit is set by the customs office of departure, it shall be binding on the customs authorities of the Member States the territory of which the goods enter during a Union transit operation, and that time-limit shall not be altered by those authorities.

<a id="p115201"></a>Article 298

<a id="p115202"></a>Itinerary for movements
of goods under the Union transit procedure
(Articles 226(3)(a) and 227(2)(a) of the Code)

1. <a id="p115203"></a>Goods placed under the Union transit procedure shall be moved to the customs office of destination along an economically justified itinerary.
2. <a id="p115204"></a>Where the customs office of departure or the holder of the procedure considers it necessary, that customs office shall prescribe an itinerary for the movements of goods during the Union transit procedure taking into account any relevant information communicated by the holder of the procedure.
<a id="p115205"></a>When prescribing an itinerary, the customs office shall enter in the electronic transit system at least the indication of the Member States through which the transit is to take place.

<a id="p115206"></a>Article 299

<a id="p115207"></a>Sealing as an identification measure
(Articles 192, 226(3)(a) and 227(2)(a) of the Code)

1. <a id="p115208"></a>Where goods are to be placed under the Union transit procedure, the customs office of departure shall seal the following:
<a id="p115209"></a>(a) the space containing the goods, where the means of transport or container has been recognised by the customs office of departure as suitable for sealing;
<a id="p115210"></a>(b) each individual package, in other cases.
2. <a id="p115211"></a>The customs office of departure shall record the number of the seals and the individual seal identifiers, in the electronic transit system.

<a id="p115212"></a>Article 300

<a id="p115213"></a>Suitability for sealing
(Articles 226(3)(a) and 227(2)(a) of the Code)

1. <a id="p115214"></a>The customs office of departure shall consider means of transport or containers to be suitable for sealing on the following conditions:
<a id="p115215"></a>(a) seals can be simply and effectively affixed to the means of transport or container;
<a id="p115216"></a>(b) the means of transport or container is so constructed that when goods are removed or introduced, the removal or introduction leaves visible traces, the seals are broken or show signs of tampering, or an electronic monitoring system registers the removal or introduction;
<a id="p115217"></a>(c) the means of transport or container contains no concealed spaces where goods may be hidden;
<a id="p115218"></a>(d) the spaces reserved for the goods are readily accessible for inspection by the customs authority.
2. <a id="p115219"></a>Road vehicles, trailers, semi-trailers and containers approved for the carriage of goods under customs seal in accordance with an international agreement to which the Union is a contracting party shall also be regarded as suitable for sealing.

<a id="p115220"></a>Article 301

<a id="p115221"></a>Characteristics of customs seals
(Articles 226(3)(a) and 227(2)(a) of the Code)

1. <a id="p115222"></a>Customs seals shall have at least the following essential characteristics and comply with the following technical specifications:
<a id="p115223"></a>(a) essential characteristics of the seals:
<a id="p115224"></a>(i) remaining intact and securely fastened in normal use;
<a id="p115225"></a>(ii) being easily checkable and recognisable;
<a id="p115226"></a>(iii) being so manufactured that any breakage, tampering or removal leaves traces visible to the naked eye;
<a id="p115227"></a>(iv) being designed for single use or, if intended for multiple use, being so designed that they can be given a clear, individual identification mark each time they are re-used;
<a id="p115228"></a>(v) bearing of individual seal identifiers which are permanent, readily legible and uniquely numbered;
<a id="p115229"></a>(b) technical specifications:
<a id="p115230"></a>(i) the form and dimensions of seals may vary with the sealing method used but the dimensions shall be such as to ensure that identification marks are easy to read;
<a id="p115231"></a>(ii) the identification marks of seals shall be impossible to falsify and difficult to reproduce;
<a id="p115232"></a>(iii) the material used shall be resistant to accidental breakage and such as to prevent undetectable falsification or reuse.
2. <a id="p115233"></a>Where seals have been certified by a competent body in accordance with ISO International Standard No 17712:2013 "Freight containers - Mechanical Seals", those seals shall be deemed to fulfil the requirements laid down in paragraph 1.
<a id="p115234"></a>For containerised transports, seals with high-security features shall be used to the widest possible extent.
3. <a id="p115235"></a>The customs seal shall bear the following indications:
<a id="p115236"></a>(a) the word "Customs" in one of the official languages of the Union or a corresponding abbreviation;
<a id="p115237"></a>(b) a country code, in the form of the ISO-alpha-2 country code, identifying the Member State in which the seal is affixed;
<a id="p115238"></a>(c) Member States may add the symbol of the European flag.
<a id="p115239"></a>Member States may in agreement with each other decide to use common security features and technology.
4. <a id="p115240"></a>Each Member State shall notify the Commission about its customs seal types in use. The Commission shall make this information available to all Member States.
5. <a id="p115241"></a>Whenever a seal needs to be removed to allow customs inspection, the customs authority shall endeavour to reseal as necessary, with a custom seal of at least equivalent security features and note the particulars of the action, including the new seal number, on the cargo documentation.

<a id="p115242"></a>Article 302

<a id="p115243"></a>Alternative identification measures to sealing
(Articles 192, 226(3)(a) and 227(2)(a) of the Code)

1. <a id="p115244"></a>By way of derogation from Article 299 of this Regulation, the customs office of departure may decide not to seal the goods placed under the Union transit procedure and instead rely on the description of the goods in the transit declaration or in the supplementary documents provided that the description is sufficiently precise to permit easy identification of the goods and states their quantity and nature and any special features such as serial numbers of the goods.
2. <a id="p115245"></a>By way of derogation from Article 299 of this Regulation, unless the customs office of departure decides otherwise, neither the means of transport nor the individual packages containing the goods shall be sealed where:
<a id="p115246"></a>(a) the goods are carried by air, and either labels are affixed to each consignment bearing the number of the accompanying airway bill, or the consignment constitutes a load unit on which the number of the accompanying airway bill is indicated;
<a id="p115247"></a>(b) the goods are carried by rail, and identification measures are applied by the railway companies;
<a id="p115248"></a>(c) the goods are carried by sea and a reference to the accompanying bill of lading is mentioned in an electronic transport document used as customs declaration to place goods under the Union transit procedure, as referred to in Article 233(4)(e) of the Code.

<a id="p115249"></a>Article 303

<a id="p115250"></a>Release of goods for the Union transit procedure
(Articles 226(3)(a) and 227(2)(a) of the Code)

1. <a id="p115251"></a>Only goods which have been sealed in accordance with Article 299 of this Regulation or in respect of which alternative identification measures have been taken in accordance with Article 302 of this Regulation shall be released for the Union transit procedure.
2. <a id="p115252"></a>On release of the goods, the customs office of departure shall transmit the particulars of the Union transit operation:
<a id="p115253"></a>(a) to the declared customs office of destination;
<a id="p115254"></a>(b) to each declared customs office of transit.
<a id="p115255"></a>Those particulars shall be based on data derived from the transit declaration, as amended where appropriate.
3. <a id="p115256"></a>The customs office of departure shall notify the holder of the procedure of the release of the goods for the Union transit procedure.
4. <a id="p115257"></a>At the request of the holder of the procedure, the customs office of departure shall provide a transit accompanying document or, where appropriate, a transit/security accompanying document to the holder of the procedure.
<a id="p115258"></a>The transit accompanying document shall be provided using the form set out in Annex B-02 to of Delegated Regulation (EU) 2015/2446 and, if necessary, supplemented by the List of items in the form set out in Annex B-03 to the same Delegated Regulation. The transit/security accompanying document shall be provided using the form set out in Annex B-04 to the same Delegated Regulation and supplemented by the Transit/Security list of items in the form set out in Annex B-05 to the same Delegated Regulation.

<a id="p115259"></a>Subsection 3

<a id="p115260"></a>**FORMALITIES DURING THE UNION TRANSIT PROCEDURE**

<a id="p115261"></a>Article 304

<a id="p115262"></a>Presentation of goods moved under the Union
transit procedure at the customs office of transit
(Articles 226(3)(a) and 227(2)(a) of the Code)

1. <a id="p115263"></a>The goods together with the MRN of the transit declaration shall be presented at each customs office of transit.
2. <a id="p115264"></a>With respect to the presentation of the MRN of the transit declaration at each customs office of transit, the second paragraph of Article 184 of Delegated Regulation (EU) 2015/2446 shall apply.
3. <a id="p115265"></a>The customs offices of transit shall record the border passage of the goods on the basis of the particulars of the Union transit operation received from the customs office of departure. That passage shall be notified by the customs offices of transit to the customs office of departure.
4. <a id="p115266"></a>Where goods are carried via a customs office of transit other than that declared, the actual customs office of transit shall request the particulars of the Union transit operation from the customs office of departure and notify the border passage of the goods to the customs office of departure.
5. <a id="p115267"></a>The customs offices of transit may inspect the goods. Any inspection of the goods shall be carried out mainly on the basis of the particulars of the Union transit operation received from the customs office of departure.
6. <a id="p115268"></a>Paragraphs 1 to 4 shall not apply to the transport of goods by rail provided that the customs office of transit can verify the border passage of the goods by other means. Such verification shall take place only in case of need. The verification may take place retrospectively.

<a id="p115269"></a>Article 305

<a id="p115270"></a>Incidents during movement
of goods under a Union transit operation
(Articles 226(3)(a) and 227(2)(a) of the Code)

1. <a id="p115271"></a>The carrier shall present without undue delay after the incident the goods together with the MRN of the transit declaration to the nearest customs authority of the Member State in whose territory the means of transport is located where:
<a id="p115272"></a>(a) the carrier is obliged to deviate from the itinerary prescribed in accordance with Article 298 of this Regulation due to circumstances beyond his control;
<a id="p115273"></a>(b) seals are broken or tampered with in the course of a transport operation for reasons beyond the carrier's control;
<a id="p115274"></a>(c) under the supervision of the customs authority, goods are transferred from one means of transport to another means of transport;
<a id="p115275"></a>(d) imminent danger necessitates immediate partial or total unloading of the sealed means of transport;
<a id="p115276"></a>(e) there is an incident which may affect the ability of the holder of the procedure or the carrier to comply with his obligations;
<a id="p115277"></a>(f) any of the elements constituting a single means of transport as referred to in Article 296(2) of this Regulation is changed.
2. <a id="p115278"></a>Where the customs authority in whose territory the means of transport is located considers that the Union transit operation concerned may continue, it shall take any steps that it considers necessary.
<a id="p115279"></a>Relevant information concerning the incidents referred to in paragraph 1 shall be recorded in the electronic transit system by that customs authority.
3. <a id="p115280"></a>In case of an incident as referred to in paragraph 1(c), the customs authorities shall not require presentation of the goods together with the MRN of the transit declaration if all of the following conditions are fulfilled:
<a id="p115281"></a>(a) the goods are transferred from a means of transport that is not sealed;
<a id="p115282"></a>(b) the holder of the procedure or the carrier on behalf of the holder of the procedure provides relevant information concerning the transfer to the customs authority of the Member State in whose territory the means of transport is located;
<a id="p115283"></a>(c) the relevant information is recorded in the electronic transit system by that authority.
4. <a id="p115284"></a>In the case of an incident as referred to in paragraph 1(f), the carrier may continue the Union transit operation when one or more carriages or wagons are withdrawn from a set of coupled railway carriages or wagons due to technical problems.
5. <a id="p115285"></a>In the case of an incident as referred to in paragraph 1(f), where the tractor unit of a road vehicle is changed without its trailers or semi-trailers being changed, the customs authority shall not require presentation of the goods together with the MRN of the transit declaration if all of the following conditions are fulfilled:
<a id="p115286"></a>(a) the holder of the procedure or the carrier on behalf of the holder of the procedure provides relevant information concerning the composition of the road vehicle to the customs authority of the Member State in whose territory that road vehicle is located;
<a id="p115287"></a>(b) the relevant information is recorded in the electronic transit system by that authority.
6. <a id="p115288"></a>Until the dates of deployment of the upgrading of the NCTS referred to in Annex to Implementing Decision 2014/255/EU, in the cases referred to in paragraph 1, the carrier shall make the necessary entries in the transit accompanying document or in the transit/security accompanying document and present without undue delay after the incident the goods together with the transit accompanying document or the transit/security accompanying document to the nearest customs authority of the Member State in whose territory the means of transport is located.
<a id="p115289"></a>In the cases referred to in paragraphs 3(a) and (b), 4 and 5(a) the carrier is waived from the presentation of the goods and of the MRN of the transit declaration to this customs authority.
<a id="p115290"></a>Relevant information concerning incidents during transit operation shall be recorded in the electronic transit system by the customs office of transit or by the customs office of destination.
7. <a id="p115291"></a>Until the dates of deployment of the upgrading of the NCTS referred to in Annex to Implementing Decision 2014/255/EU, the second subparagraph of paragraph 2 of this Article shall not apply.

<a id="p115292"></a>Subsection 4

<a id="p115293"></a>**FORMALITIES AT THE CUSTOMS OFFICE OF DESTINATION**

<a id="p115294"></a>Article 306

<a id="p115295"></a>Presentation of goods placed under the Union transit
procedure at the customs office of destination
(Articles 226(3)(a) and 227(2)(a) of the Code)

1. <a id="p115296"></a>Where goods placed under a Union transit procedure arrive at the customs office of destination, the following shall be presented at that customs office:
<a id="p115297"></a>(a) the goods;
<a id="p115298"></a>(b) the MRN of the transit declaration;
<a id="p115299"></a>(c) any information required by the customs office of destination.
<a id="p115300"></a>The presentation shall take place during the official opening hours. However, the customs office of destination may, at the request of the person concerned, allow the presentation to take place outside the official opening hours or at any other place.
2. <a id="p115301"></a>With respect to the presentation of the MRN of the transit declaration at the customs office of destination, the second paragraph of Article 184 of Delegated Regulation (EU) 2015/2446 shall apply.
3. <a id="p115302"></a>Where the presentation has taken place after expiry of the time-limit set by the customs office of departure in accordance with Article 297(1) of this Regulation, the holder of the procedure shall be deemed to have complied with the time-limit where he or the carrier proves to the satisfaction of the customs office of destination that the delay is not attributable to him.
4. <a id="p115303"></a>The Union transit procedure may be ended at a customs office other than that declared in the transit declaration. That customs office shall then be considered to be the customs office of destination.
5. <a id="p115304"></a>At the request of the person presenting the goods at the customs office of destination, that customs office shall endorse a receipt which certifies the presentation of the goods at that customs office and contains a reference to the MRN of the transit declaration.
<a id="p115305"></a>The receipt shall be provided using the form set out in Annex 72-03 and be completed in advance by the person concerned.
<a id="p115306"></a>The receipt shall not be used as alternative proof of the Union transit procedure having ended within the meaning of Article 312 of this Regulation.

<a id="p115307"></a>Article 307

<a id="p115308"></a>Notification of arrival
of goods under the Union transit procedure
(Articles 226(3)(a) and 227(2)(a) of the Code)

1. <a id="p115309"></a>The customs office of destination shall notify the customs office of departure of arrival of the goods on the day the goods and the MRN of the transit declaration are presented in accordance with Article 306(1) of this Regulation.
2. <a id="p115310"></a>Where the Union transit procedure is ended at a customs office other than that declared in the transit declaration, the customs office considered to be the customs office of destination in accordance with Article 306(4) of this Regulation shall notify the arrival to the customs office of departure on the day the goods and the MRN of the transit declaration are presented in accordance with Article 306(1) of this Regulation.
<a id="p115311"></a>The customs office of departure shall notify the arrival to the customs office of destination declared in the transit declaration.

<a id="p115312"></a>Article 308

<a id="p115313"></a>Controls and issuing of alternative proof
(Articles 226(3)(a) and 227(2)(a) of the Code)

1. <a id="p115314"></a>Where the Union transit procedure is ended, the customs office of destination shall carry out customs controls on the basis of the particulars of the Union transit operation received from the customs office of departure.
2. <a id="p115315"></a>Where the Union transit procedure is ended, no irregularity has been detected by the customs office of destination, and the holder of the procedure presents the transit accompanying document or the transit/security accompanying document, that customs office shall endorse that document at the request of the holder of the procedure for the purposes of providing alternative proof in accordance with Article 312. The endorsement shall consist of the stamp of that customs office, the official's signature, the date and the following mention:
<a id="p115316"></a>"Alternative proof - 99202".

<a id="p115317"></a>Article 309

<a id="p115318"></a>Sending the control results
(Articles 226(3)(a) and 227(2)(a) of the Code)

1. <a id="p115319"></a>The customs office of destination shall notify the control results to the customs office of departure at the latest on the third day following the day the goods are presented at the customs office of destination or at another place in accordance with Article 306(1) of this Regulation. In exceptional cases, that time-limit may be extended up to 6 days.
2. <a id="p115320"></a>By derogation from paragraph 1, where goods are received by an authorised consignee as referred to in Article 233(4)(b) of the Code, the customs office of departure shall be notified at the latest on the sixth day following the day the goods were delivered to the authorised consignee.
<a id="p115321"></a>Where goods are carried by rail and one or more carriages or wagons are withdrawn from a set of coupled railway carriages or wagons due to technical problems, as referred to in Article 305(4) of this Regulation, the customs office of departure shall be notified at the latest on the 12th day following the day the first part of goods has been presented.
3. <a id="p115322"></a>Until the dates of deployment of the upgrading of the NCTS referred to in the Annex to Implementing Decision 2014/255/EU, the second subparagraph of paragraph 2 of this Article shall not apply.

<a id="p115323"></a>Subsection 5

<a id="p115324"></a>**ENQUIRY PROCEDURE AND RECOVERY OF THE CUSTOMS DEBT**

<a id="p115325"></a>Article 310

<a id="p115326"></a>Enquiry procedure
for goods moved under the Union transit procedure
(Articles 226(3)(a) and 227(2)(a) of the Code)

1. <a id="p115327"></a>Where the customs office of departure has not received the control results within 6 days in accordance with Article 309(1) of this Regulation or the first subparagraph of Article 309(2) of this Regulation or within 12 days in accordance with the second subparagraph of Article 309(2) of this Regulation after receiving the notification of arrival of the goods, that customs office shall immediately request the control results from the customs office of destination which sent the notification of arrival of the goods.
<a id="p115328"></a>The customs office of destination shall send the control results immediately after receiving the request from the customs office of departure.
2. <a id="p115329"></a>Where the customs authority of the Member State of departure has not yet received information that allows for the discharge of the Union transit procedure or for the recovery of the customs debt, it shall request the relevant information from the holder of the procedure or, where sufficient particulars are available at the place of destination, from the customs office of destination, in the following cases:
<a id="p115330"></a>(a) the customs office of departure has not received the notification of arrival of the goods by the expiry of the time-limit for the presentation of the goods set in accordance with Article 297 of this Regulation;
<a id="p115331"></a>(b) the customs office of departure has not received the control results requested in accordance with paragraph 1;
<a id="p115332"></a>(c) the customs office of departure becomes aware that the notification of arrival of the goods or the control results were sent in error.
3. <a id="p115333"></a>The customs authority of the Member State of departure shall send requests for information in accordance with paragraph 2(a) within a period of 7 days after the expiry of the time-limit referred to therein and requests for information in accordance with paragraph 2(b) within a period of 7 days after the expiry of the applicable time-limit referred to in paragraph 1.
<a id="p115334"></a>However, if, before the expiry of those time-limits, the customs authority of the Member State of departure receives information that the Union transit procedure has not been ended correctly, or suspects that to be the case, it shall send the request without delay.
4. <a id="p115335"></a>Replies to requests made in accordance with paragraph 2 shall be sent within 28 days from the date on which the request was sent.
5. <a id="p115336"></a>Where, following a request in accordance with paragraph 2, the customs office of destination has not provided sufficient information for the Union transit procedure to be discharged, the customs authority of the Member State of departure shall request the holder of the procedure to provide that information, at the latest 35 days after initiating the enquiry procedure.
<a id="p115337"></a>However, until the dates of deployment of the upgrading of the NCTS referred to in Annex to Implementing Decision 2014/255/EU, that customs authority shall request the holder of the procedure to provide that information, at the latest 28 days after the initiating the enquiry procedure.
<a id="p115338"></a>The holder of the procedure shall reply to that request within 28 days from the date on which it was sent.
6. <a id="p115339"></a>If the information provided in a reply from the holder of the procedure in accordance with paragraph 5 is not sufficient to discharge the Union transit procedure, but the customs authority of the Member State of departure considers it sufficient in order to continue the enquiry procedure, that authority shall immediately send a request for supplementary information to the customs office involved.
<a id="p115340"></a>That customs office shall reply to the request within 40 days from the date on which it was sent.
7. <a id="p115341"></a>Where during the steps of an enquiry procedure set out in paragraphs 1 to 6 it is established that the Union transit procedure was ended correctly, the customs authority of the Member State of departure shall discharge the Union transit procedure and shall immediately inform the holder of the procedure and, where appropriate, any customs authority that may have initiated a recovery procedure.
8. <a id="p115342"></a>Where during the steps of an enquiry procedure set out in paragraphs 1 to 6 it is established that the Union transit procedure cannot be discharged, the customs authority of the Member State of departure shall establish whether a customs debt has been incurred.
<a id="p115343"></a>If a customs debt has been incurred, the customs authority of the Member State of departure shall take the following measures:
<a id="p115344"></a>(a) identify the debtor;
<a id="p115345"></a>(b) determine the customs authority responsible for the notification of the customs debt in accordance with Article 102(1) of the Code.

<a id="p115346"></a>Article 311

<a id="p115347"></a>Request to transfer recovery of the customs debt
(Articles 226(3)(a) and 227(2)(a) of the Code)

1. <a id="p115348"></a>Where the customs authority of the Member State of departure, during the enquiry procedure, and before the time-limit referred to in Article 77(a) of Delegated Regulation (EU) 2015/2446 expires, obtains evidence that the place where the events from which the customs debt arises occurred is in another Member State, that authority shall immediately and in any event within that time-limit send all the information available to the competent customs authority at that place.
2. <a id="p115349"></a>The competent customs authority at that place shall acknowledge receipt of the information and inform the customs authority of the Member State of departure whether it is responsible for the recovery. If the customs authority of the Member State of departure has not received that information within 28 days, it shall immediately resume the enquiry procedure or start the recovery.
3. <a id="p115350"></a>Where the customs authority of a Member State involved in a transit operation obtains evidence, before the time-limit referred to in Article 77(a) of Delegated Regulation (EU) 2015/2446 expires, that the place where the events from which the customs debt arises occurred is in its territory, that authority shall immediately and in any event within that time-limit send a duly justified request to the customs authority of the Member State of departure to transfer the responsibility to start the recovery to the requesting customs authority.
4. <a id="p115351"></a>The customs authority of the Member State of departure shall acknowledge the receipt of the request made in accordance with paragraph 3 and shall inform the requesting customs authority, within 28 days from the date on which the request was sent, whether it agrees to satisfy the request and to transfer to the requesting authority the responsibility to start the recovery.

<a id="p115352"></a>Article 312

<a id="p115353"></a>Alternative proof of ending the Union transit procedure
(Articles 226(3)(a) and 227(2)(a) of the Code)

1. <a id="p115354"></a>The Union transit procedure shall be considered as having been ended correctly where the holder of the procedure presents, to the satisfaction of the customs authority of the Member State of departure, one of the following documents identifying the goods:
<a id="p115355"></a>(a) a document certified by the customs authority of the Member State of destination which identifies the goods and establishes that the goods have been presented at the customs office of destination, or have been delivered to an authorised consignee as referred to in Article 233(4)(b) of the Code;
<a id="p115356"></a>(b) a document or a customs record, certified by the customs authority of a Member State which establishes that the goods have physically left the customs territory of the Union;
<a id="p115357"></a>(c) a customs document issued in a third country where the goods are placed under a customs procedure;
<a id="p115358"></a>(d) a document issued in a third country, stamped or otherwise certified by the customs authority of that country and establishing that the goods are considered to be in free circulation in that country.
2. <a id="p115359"></a>Instead of the documents referred to in paragraph 1, copies thereof certified as being true copies by the body which certified the original documents, by the authority of the third country concerned or by an authority of a Member State may be provided as proof.
3. <a id="p115360"></a>The notification of arrival of the goods referred to in Article 307 shall not be considered to be proof that the Union transit procedure has been ended correctly.

<a id="p115361"></a>Subsection 6

<a id="p115362"></a>**SIMPLIFICATIONS USED FOR THE UNION TRANSIT PROCEDURE**

<a id="p115363"></a>Article 313

<a id="p115364"></a>Territorial scope of simplifications
(Article 233(4)(a), (b), (c) and (e) of the Code)

1. <a id="p115365"></a>The simplifications referred to in Article 233(4)(a) and (c) of the Code shall apply only to Union transit operations beginning in the Member State where the authorisation of the simplifications is granted.
2. <a id="p115366"></a>The simplification referred to in Article 233(4)(b) of the Code shall apply only to Union transit operations ending in the Member State where the authorisation of the simplification is granted.
3. <a id="p115367"></a>The simplification referred to in Article 233(4)(e) of the Code shall apply in the Member States specified in the authorisation of the simplification.

<a id="p115368"></a>Article 314

<a id="p115369"></a>Placing of goods under the Union
transit procedure by an authorised consignor
(Article 233(4)(a) of the Code)

1. <a id="p115370"></a>Where an authorised consignor intends to place goods under the Union transit procedure, he shall lodge a transit declaration at the customs office of departure. The authorised consignor cannot start the Union transit procedure until the expiry of the time-limit specified in the authorisation referred to in Article 233(4)(a) of the Code.
2. <a id="p115371"></a>The authorised consignor shall enter the following information into the electronic transit system:
<a id="p115372"></a>(a) the itinerary where an itinerary has been prescribed in accordance with Article 298;
<a id="p115373"></a>(b) the time-limit set in accordance with Article 297 of this Regulation within which the goods shall be presented at the customs office of destination;
<a id="p115374"></a>(c) the number and the individual seal identifiers of the seals, where appropriate.
3. <a id="p115375"></a>The authorised consignor may print a transit accompanying document or transit/security accompanying document only after receipt of the notification of the release of the goods for the Union transit procedure from the customs office of departure. However, until the dates of deployment of the upgrading of the NCTS referred to in Annex to Implementing Decision 2014/255/EU, the authorised consignor shall print those documents.

<a id="p115376"></a>Article 315

<a id="p115377"></a>Formalities for goods moved under the Union transit
procedure received by an authorised consignee
(Article 233(4)(b) of the Code)

1. <a id="p115378"></a>When the goods arrive at a place specified in the authorisation referred to in Article 233(4)(b) of the Code, the authorised consignee shall:
<a id="p115379"></a>(a) immediately notify the customs office of destination of arrival of the goods and inform it of any irregularities or incidents that occurred during transport;
<a id="p115380"></a>(b) unload the goods only after obtaining the permission from the customs office of destination;
<a id="p115381"></a>(c) after unloading, enter the results of the inspection and any other relevant information relating to the unloading into his records without delay;
<a id="p115382"></a>(d) notify the customs office of destination of the results of the inspection of the goods and inform it of any irregularities on the third day following the day on which he has received the permission to unload the goods, at the latest.
2. <a id="p115383"></a>When the customs office of destination has received notification of arrival of the goods at the premises of the authorised consignee, it shall notify the customs office of departure of the arrival of the goods.
3. <a id="p115384"></a>When the customs office of destination has received the results of the inspection of the goods referred to in paragraph 1(d), it shall send the control results to the customs office of departure on the sixth day following the day the goods were delivered to the authorised consignee, at the latest.

<a id="p115385"></a>Article 316

<a id="p115386"></a>End of the Union transit procedure
for goods received by an authorised consignee
(Article 233(4)(b) of the Code)

1. <a id="p115387"></a>The holder of the procedure shall be considered to have fulfilled his obligations and the transit procedure shall be deemed to end in accordance with Article 233(2) of the Code, when the goods have been presented intact to the authorised consignee as provided for in Article 233(4)(b) of the Code at the place specified in the authorisation within the time-limit set in accordance with Article 297(1) of this Regulation.
2. <a id="p115388"></a>At the carrier's request the authorised consignee shall issue the receipt which certifies the arrival of the goods at a place specified in the authorisation referred to in Article 233(4)(b) of the Code and contains a reference to the MRN of the Union transit operation. The receipt shall be provided using the form set out in Annex 72-03.

<a id="p115389"></a>Article 317

<a id="p115390"></a>Formalities for the use of seals of a special type
(Article 233(4)(c) of the Code)

1. <a id="p115391"></a>Seals of a special type shall fulfil the requirements laid down in Article 301(1) of this Regulation.
<a id="p115392"></a>Where seals have been certified by a competent body in accordance with ISO International Standard No 17712:2013 "Freight containers - Mechanical Seals", those seals shall be deemed to fulfil those requirements.
<a id="p115393"></a>For containerised transports, seals with high-security features shall be used to the widest possible extent.
2. <a id="p115394"></a>The seal of a special type shall bear either of the following indications:
<a id="p115395"></a>(a) the name of the person authorised in accordance with Article 233(4)(c) of the Code to use it;
<a id="p115396"></a>(b) a corresponding abbreviation or code on the basis of which the customs authority of the Member State of departure can identify the person concerned.
3. <a id="p115397"></a>The holder of the procedure shall enter the number and the individual seal identifiers of the seals of a special type in the transit declaration and shall affix seals no later than when goods are released for the Union transit procedure.

<a id="p115398"></a>Article 318

<a id="p115399"></a>Customs supervision for the use of seals of a special type
(Article 233(4)(c) of the Code)

<a id="p115400"></a>The customs authority shall do the following:
<a id="p115401"></a>(a) notify the Commission and the customs authorities of the other Member States of seals of a special type in use and of seals of a special type which it has decided not to approve for reasons of irregularities or technical deficiencies;
<a id="p115402"></a>(b) review the seals of a special type approved by it and in use, when it receives information that another authority has decided not to approve a particular seal of a special type;
<a id="p115403"></a>(c) conduct a mutual consultation in order to reach a common assessment;
<a id="p115404"></a>(d) monitor the use of the seals of a special type by persons authorised in accordance with Article 197 of Delegated Regulation (EU) 2015/2446.
<a id="p115405"></a>Where necessary, the Commission and the Member States in agreement with each other may establish a common numbering system, define use of common security features and technology.

<a id="p115406"></a>Article 319

<a id="p115407"></a>Consultation prior to authorisations to use an electronic
transport document as a transit declaration for air
transport or maritime transport
(Article 22 of the Code)

<a id="p115408"></a>After having examined whether the conditions laid down in Article 191 of Delegated Regulation (EU) 2015/2446 and the conditions laid down in Article 199 of that Delegated Regulation for air transport or in Article 200 of that Delegated Regulation for maritime transport, respectively, for the authorisation are met, the customs authority competent to take a decision shall consult the customs authority at the airports of departure and destination in the event of air transport or the customs authority at the ports of departure and destination in the event of maritime transport.
<a id="p115409"></a>The time-limit for the consultation shall be fixed at 45 days from the communication referred to in Article 14 from the customs authority competent to take a decision of the conditions and criteria which need to be examined by the consulted customs authority.

<a id="p115410"></a>Article 320

<a id="p115411"></a>Formalities for the use of an electronic
transport document as a transit declaration
for air transport or maritime transport
(Article 233(4)(e) of the Code)

1. <a id="p115412"></a>The goods shall be released for the Union transit procedure when the particulars of the electronic transport document have been made available to the customs office of departure at the airport in the event of air transport or to the customs office of departure at the port in the event of maritime transport in accordance with the means defined in the authorisation.
2. <a id="p115413"></a>Where the goods are to be placed under the Union transit procedure, the holder of the procedure shall enter the appropriate codes next to all items in the electronic transport document.
3. <a id="p115414"></a>The Union transit procedure shall end when the goods are presented at the customs office of destination at the airport in the event of air transport or at the customs office of destination at the port in the event of maritime transport, and the particulars of the electronic transport document have been made available to that customs office in accordance with the means defined in the authorisation.
4. <a id="p115415"></a>The holder of the procedure shall notify the customs offices of departure and destination immediately of all offences and irregularities.
5. <a id="p115416"></a>The Union transit procedure is deemed to be discharged unless the customs authorities have received information or have established that the procedure has not ended correctly.

<a id="p115417"></a>Subsection 7

<a id="p115418"></a>**GOODS TRANSPORTED BY FIXED TRANSPORT INSTALLATION**

<a id="p115419"></a>Article 321

<a id="p115420"></a>Transport by fixed transport installation
and operation of the Union transit procedure
(Articles 226(3)(a) and 227(2)(a) of the Code)

1. <a id="p115421"></a>Where the goods transported by a fixed transport installation enter the customs territory of the Union through that installation, those goods shall be deemed to be placed under the Union transit procedure when entering that territory.
2. <a id="p115422"></a>Where the goods are already in the customs territory of the Union and is transported by a fixed transport installation, those goods shall be deemed to be placed under the Union transit procedure when placed into the fixed transport installation.
3. <a id="p115423"></a>For the purposes of the Union transit procedure where goods are transported by fixed transport installations, the holder of the procedure shall be the operator of the fixed transport installation established in the Member State through the territory of which the goods enter the customs territory of the Union in the case referred to in paragraph 1 or the operator of the fixed transport installation in the Member State in which the movement starts in the case referred to in paragraph 2.
<a id="p115424"></a>The holder of the procedure and the customs authority shall agree on the methods of customs supervision over the goods transported.
4. <a id="p115425"></a>For the purposes of Article 233(3) of the Code, the operator of a fixed transport installation established in a Member State through the territory of which the goods are transported by fixed transport installation shall be regarded as the carrier.
5. <a id="p115426"></a>The Union transit procedure shall be deemed to have ended when:
<a id="p115427"></a>(a) the appropriate entry is made in the commercial records of the consignee, or
<a id="p115428"></a>(b) the operator of the fixed transport installation certified that the goods transported by fixed transport installation:
<a id="p115429"></a>(i) have arrived at the consignee's plant;
<a id="p115430"></a>(ii) are accepted into the distribution network of the consignee; or
<a id="p115431"></a>(iii) have left the customs territory of the Union.
6. <a id="p115432"></a>Non-Union goods shall be deemed to be in temporary storage from the moment the Union transit procedure has ended in accordance with point (a) or points (b)(i) or (ii) of paragraph 5.

<a id="p115433"></a>**CHAPTER 4**

<a id="p115434"></a>**SPECIFIC USE**

<a id="p115435"></a>Section 1. TEMPORARY ADMISSION

<a id="p115436"></a>Article 322

<a id="p115437"></a>Discharge of the temporary admission procedure in cases
concerning means of rail transport, pallets and containers
(Article 215 of the Code)

1. <a id="p115438"></a>For means of rail transport used jointly under an agreement between Union and non-Union carriers providing transport services by rail, the temporary admission procedure maybe discharged when means of rail transport of the same type or of the same value as those which were put at the disposal of a person established in the customs territory of the Union are exported or re-exported.
2. <a id="p115439"></a>For pallets, the temporary admission procedure maybe discharged when pallets of the same type or of the same value as those which were placed under the procedure are exported or re-exported.
3. <a id="p115440"></a>For containers, in accordance with the Convention on Customs Treatment of Pool Containers used in International Transport <*>, the temporary admission procedure shall be discharged when containers of the same type or of the same value as those which were placed under the procedure are exported or re-exported.

<a id="p115441"></a>

---

<a id="p115442"></a><*> OJ L 91, 22.4.1995, p. 46.

<a id="p115443"></a>Article 323

<a id="p115444"></a>Special discharge for goods for events or for sale
(Article 215 of the Code)

<a id="p115445"></a>For the purposes of discharging the temporary admission procedure in respect of goods referred to in Article 234(1) of Delegated Regulation (EU) 2015/2446 with the exception of goods referred to in Article 1(1) of Directive 2008/118/EC, their consumption, destruction or distribution free of charge to the public at the event shall be considered as re-export provided that their quantity corresponds to the nature of the event, the number of visitors and the extent of the participation of the holder of the procedure therein.

<a id="p115446"></a>Article 323a

<a id="p115447"></a>Special discharge for goods to be moved or used
in the context of military activities
(Article 215 of the Code)

<a id="p115448"></a>For the purposes of discharging the temporary admission procedure in respect of goods referred to in Article 235a of Delegated Regulation (EU) 2015/2446, their consumption or destruction shall be considered as re-export provided that the consumed or destroyed quantity corresponds to the nature of the military activity.

<a id="p115449"></a>**CHAPTER 5**

<a id="p115450"></a>**PROCESSING**

<a id="p115451"></a>Inward processing

<a id="p115452"></a>Article 324

<a id="p115453"></a>Special cases of discharge
of the inward processing IM/EX procedure
(Article 215 of the Code)

1. <a id="p115454"></a>For the purposes of discharging the inward processing IM/EX procedure, the following shall be regarded as re-export:
<a id="p115455"></a>(a) the processed products are delivered to persons who are eligible for relief from import duty pursuant to the Vienna Convention of 18 April 1961 on Diplomatic Relations, or to the Vienna Convention of 24 April 1963 on Consular Relations, or the New York Convention of 16 December 1969 on Special Missions as referred to in Article 128(1)(a) of Council Regulation (EC) No 1186/2009 <*>;

<a id="p115456"></a>

---

<a id="p115457"></a><*> Council Regulation (EC) No 1186/2009 of 16 November 2009 setting up a Community system of reliefs from customs duty (OJ L 324, 10.12.2009, p. 23).

<a id="p115458"></a>(b) the processed products are delivered to the armed forces of other countries stationed in the territory of a Member State, where that Member State grants special relief from import duty in accordance with Article 131(1) of Regulation (EC) No 1186/2009;
<a id="p115459"></a>(c) the delivery of aircraft;
<a id="p115460"></a>(d) the delivery of spacecraft and related equipment;
<a id="p115461"></a>(e) the delivery of main processed products for which the erga omnes import duty rate is "free" or for which an authorised release certificate EASA Form 1 or an equivalent certificate as referred to in Article 2 of Council Regulation (EU) 2018/581 <*> has been issued;

<a id="p115462"></a>

---

<a id="p115463"></a><*> Council Regulation (EU) 2018/581 of 16 April 2018 temporarily suspending the autonomous Common Customs Tariff duties on certain goods of a kind to be incorporated in or used for aircraft, and repealing Regulation (EC) No 1147/2002 (OJ L 98, 18.4.2018, p.1).

<a id="p115464"></a>(f) disposal, in accordance with the relevant provisions, of secondary processed products whose destruction under customs supervision is prohibited on environmental grounds.
2. <a id="p115465"></a>Paragraph 1 shall not apply:
<a id="p115466"></a>(a) where non-Union goods placed under the inward processing IM/EX procedure would be subject to an agricultural or commercial policy measure, a provisional or definitive anti-dumping duty, a countervailing duty, a safeguard measure or an additional duty resulting from a suspension of concessions if they were declared for release for free circulation.
<a id="p115467"></a>However, paragraph 1 shall apply in cases where non-Union goods placed under the inward processing IM/EX procedure would be subject to prior Union surveillance, if they were declared for release for free circulation, subject to the condition that the holder of the authorisation for inward processing IM/EX provides the data elements in accordance with the relevant surveillance measure;
<a id="p115468"></a>(b) where a customs debt would be incurred in accordance with Article 78(1) of the Code for non-originating goods placed under the inward processing IM/EX procedure if the holder of the authorisation intends to re-export the processed products.
3. <a id="p115469"></a>In the case of paragraph 1(c), the supervising customs office shall allow the inward processing IM/EX procedure to be discharged once the goods placed under the procedure have been used for the first time for the manufacture, repair including maintenance, modification or conversion of aircraft or parts thereof, on condition that the records of the holder of the procedure are such as to make it possible to verify that the procedure is being correctly applied and operated.
4. <a id="p115470"></a>In the case of paragraph 1(d), the supervising customs office shall allow the inward processing IM/EX procedure to be discharged once the goods placed under the procedure have been used for the first time for the manufacture, repair including maintenance, modification or conversion of satellites, their launch vehicles and ground station equipment and parts thereof that are an integral part of the systems, on condition that the records of the holder of the procedure are such as to make it possible to verify that the procedure is being correctly applied and operated.
5. <a id="p115471"></a>In the case of paragraph 1(e), the supervising customs office shall allow the inward processing IM/EX procedure to be discharged once the goods placed under the procedure have been used for the first time in the processing operations related to the delivered processed products or to parts thereof, on condition that the records of the holder of the procedure are such as to make it possible to verify that the procedure is being correctly applied and operated.
6. <a id="p115472"></a>In the case of paragraph 1(f), the holder of the inward processing procedure shall prove that discharge of the inward processing IM/EX procedure in accordance with the normal rules is either impossible or uneconomic.

<a id="p115473"></a>Article 325

<a id="p115474"></a>Processed products or goods deemed to
have been released for free circulation
(Article 215 of the Code)

1. <a id="p115475"></a>Where the authorisation for inward processing IM/EX has specified that processed products or goods placed under the procedure are deemed to have been released for free circulation if they have not been placed under a subsequent customs procedure or re-exported on expiry of the period for discharge, the customs declaration for release for free circulation shall be deemed to have been lodged and accepted and release granted on the date of expiry of the period for discharge.
2. <a id="p115476"></a>In the cases referred to in paragraph 1, the products or the goods placed under the inward processing IM/EX procedure shall become Union goods when they are put on the market.

<a id="p115477"></a>**TITLE VIII**
**GOODS TAKEN OUT OF THE CUSTOMS TERRITORY OF THE UNION**

<a id="p115478"></a>**CHAPTER 1**

<a id="p115479"></a>**FORMALITIES PRIOR TO THE EXIT OF GOODS**

<a id="p115480"></a>Article 326

<a id="p115481"></a>Electronic system relating to exit
(Article 16(1) of the Code)

<a id="p115482"></a>For the processing and exchange of information relating to the exit of goods out of the customs territory of the Union, an electronic system set up for those purposes pursuant to Article 16(1) of the Code shall be used.
<a id="p115483"></a>The first paragraph of this Article shall be applicable from the dates of deployment of the UCC AES referred to in the Annex to Implementing Decision 2014/255/EU.

<a id="p115484"></a>Article 327

<a id="p115485"></a>Goods not covered by a pre-departure declaration
(Article 267 of the Code)

<a id="p115486"></a>Where it is found that goods intended to be taken out of the customs territory of the Union are not covered by a pre-departure declaration, and except where the obligation to lodge such a declaration is waived, the exit of the goods shall be subject to the lodgement of such a declaration.

<a id="p115487"></a>Article 328

<a id="p115488"></a>Risk analysis
(Article 264 of the Code)

1. <a id="p115489"></a>Risk analysis shall be carried out prior to the release of the goods within a time-limit which corresponds to the period between the end of the time-limit for the lodgement of the pre-departure declaration as laid down in Article 244 of Delegated Regulation (EU) 2015/2446 and the loading or the departure of the goods, as appropriate.
2. <a id="p115490"></a>Where a waiver from the obligation to lodge a pre-departure declaration pursuant to Article 245 of Delegated Regulation (EU) 2015/2446 applies, risk analysis shall be carried out upon presentation of the goods on the basis of the customs declaration or re-export declaration covering those goods or, where not available, on the basis of any other available information about the goods.

<a id="p115491"></a>**CHAPTER 2**

<a id="p115492"></a>**FORMALITIES ON EXIT OF GOODS**

<a id="p115493"></a>Article 329

<a id="p115494"></a>Determination of the customs office of exit
(Article 159(3) of the Code)

1. <a id="p115495"></a>Except where paragraphs 2 to 7 apply, the customs office of exit shall be the customs office competent for the place from where the goods leave the customs territory of the Union for a destination outside that territory.
2. <a id="p115496"></a>In the case of goods leaving the customs territory of the Union by fixed transport installation, the customs office of exit shall be the customs office of export.
3. <a id="p115497"></a>Where the goods are loaded in a seaport onto a vessel that is not assigned to a regular shipping service as referred to in Article 120 of Delegated Regulation (EU) 2015/2446 for carriage to a destination outside the customs territory of the Union, the customs office of exit shall be the customs office competent for the place where the goods are loaded onto such vessel.
4. <a id="p115498"></a>Where paragraph 3 does not apply and the goods are loaded onto a vessel or onto an aircraft without any subsequent transhipment for carriage to a destination outside the customs territory of the Union by sea or air, the customs office of exit shall be the customs office competent for the place where the goods are loaded onto such vessel or aircraft.
5. <a id="p115499"></a>Where, after having been released for export, goods are placed under an external transit procedure, the customs office of exit shall be the customs office of departure of the transit operation.
6. <a id="p115500"></a>Where, after having been released for export, goods are placed under a transit procedure other than the external transit procedure, the customs office of exit shall be the customs office of departure of the transit operation provided that either of the following conditions is fulfilled:
<a id="p115501"></a>(a) the customs office of destination of the transit operation is situated in a common transit country;
<a id="p115502"></a>(b) the customs office of destination of the transit operation is situated at the border of the customs territory of the Union and the goods are taken out of that customs territory, after having passed through a country or territory outside the customs territory of Union.
7. <a id="p115503"></a>On request the customs office of exit shall be the customs office competent for the place where the goods are taken over under a single transport contract for transport of the goods out of the customs territory of the Union by the railway companies, the postal operators, the airlines or the shipping companies provided that the goods are to leave the customs territory of the Union by rail, post, air or sea.
<a id="p115504"></a>7a. From the date of deployment of the Automated Export System (AES) referred to in the Annex to Implementing Decision (EU) 2016/578 at the latest, paragraphs 6 and 7 shall not apply in cases where Union goods falling within a category listed in Article 1(1) of Directive 2008/118/EC are exported.
<a id="p115505"></a>From the date of deployment of the Automated Export System (AES) referred to in the Annex to Implementing Decision (EU) 2016/578 at the latest, paragraph 7 shall not apply in cases where non-Union goods are re-exported.
9. <a id="p115506"></a>Where a re-export notification is to be lodged in accordance with Article 274(1) of the Code, the customs office of exit shall be the customs office competent for the place where the goods are in the free zone or in temporary storage.

<a id="p115507"></a>Article 330

<a id="p115508"></a>Communication between the customs offices of export and exit
(Article 267(1) of the Code)

<a id="p115509"></a>Except where the customs declaration takes the form of an entry in the declarant's records in accordance with Article 182 of the Code, on release of the goods, the customs office of export shall, transmit the particulars of the export declaration to the declared customs office of exit. Those particulars shall be based on data derived from the export declaration, as amended where appropriate.

<a id="p115510"></a>Article 331

<a id="p115511"></a>Presentation of goods at the customs office of exit
(Article 267 of the Code)

1. <a id="p115512"></a>The person presenting goods on exit shall at the moment of presentation of the goods at the customs office of exit:
<a id="p115513"></a>(a) indicate the MRN of the export or re-export declaration;
<a id="p115514"></a>(b) indicate any discrepancies between the goods declared and released for export and those presented, including cases where goods have been repackaged or containerised before their presentation at the customs office of exit;
<a id="p115515"></a>(c) where only part of the goods covered by an export or re-export declaration is presented, the person presenting the goods shall also indicate the quantity of the goods actually presented.
<a id="p115516"></a>However, where those goods are presented in packages or containerised, he shall notify the number of packages and, if containerised, the container identification numbers.
2. <a id="p115517"></a>Goods declared for export or re-export may be presented at a customs office of exit other than that declared in the export or re-export declaration. Where the actual customs office of exit is located in another Member State than that originally declared, that customs office shall request the particulars of the export or re-export declaration from the customs office of export.
3. <a id="p115518"></a>Where goods transported by a fixed transport installation are taken out of the customs territory of the Union through that installation, those goods shall be deemed to be presented to customs when placed into the fixed transport installation.

<a id="p115519"></a>Article 332

<a id="p115520"></a>Formalities on exit of goods
(Article 267 of the Code)

1. <a id="p115521"></a>Where goods to be taken out of the customs territory of the Union are subject to customs controls, the customs office of exit shall examine the goods on the basis of the information received from the customs office of export.
2. <a id="p115522"></a>Where the person presenting the goods indicates, or the customs office of exit discovers, that some of the goods declared for export, re-export or outward processing are missing when presented to the customs office of exit, that customs office shall inform the customs office of export about the missing goods.
3. <a id="p115523"></a>Where the person presenting the goods indicates, or the customs office of exit discovers, that some of the goods presented to the customs office of exit are in excess of those declared for export, re-export or outward processing, that customs office shall refuse the exit of the goods in excess until an export or re-export declaration has been lodged for those goods. That export or re-export declaration may be lodged at the customs office of exit.
4. <a id="p115524"></a>Where the person presenting the goods indicates, or the customs office of exit discovers, that there is a discrepancy in the nature of the goods declared for export, re-export or outward processing compared to those presented to the customs office of exit, the customs office of exit shall refuse the exit of those goods until an export or re-export declaration has been lodged for them and shall inform the customs office of export. That export or re-export declaration may be lodged at the customs office of exit.
5. <a id="p115525"></a>The carrier shall notify the exit of the goods to the customs office of exit by providing all of the following information:
<a id="p115526"></a>(a) the unique consignment reference number or the transport document reference number;
<a id="p115527"></a>(b) where the goods are presented in packages or containerised the number of packages and, if containerised, the container identification numbers;
<a id="p115528"></a>(c) the MRN of the export or re-export declaration where applicable.
<a id="p115529"></a>The obligation laid down in the first subparagraph shall not apply insofar as that information is available to the customs authorities through existing commercial, port or transport information systems, or in the situation covered by Article 329(7).
6. <a id="p115530"></a>For the purposes of paragraph 5, the person handing over the goods to the carrier shall provide him with the particulars referred to in that paragraph.
<a id="p115531"></a>The carrier may load the goods for carriage out of the customs territory of the Union where the information referred to in paragraph 5 is available to him.

<a id="p115532"></a>Article 333

<a id="p115533"></a>Supervision of goods released for exit and exchange of
information between customs offices
(Article 267 of the Code)

1. <a id="p115534"></a>Once goods have been released for exit, the customs office of exit shall supervise them until they are taken out of the customs territory of the Union.
2. <a id="p115535"></a>Where the customs offices of exit and export are different, the customs office of exit shall inform the customs office of export of the exit of the goods at the latest on the working day following the day on which the goods have left the customs territory of the Union.
<a id="p115536"></a>However, in the cases referred to in paragraphs 3 to 7 of Article 329 of this Regulation, the time-limit for the customs office of exit to inform the customs office of export of the exit of the goods shall be the following:
<a id="p115537"></a>(a) in the cases referred to in Article 329(3) and (4), at the latest on the working day following the day on which the vessel or aircraft on which the goods have been loaded has left the port or airport of loading;
<a id="p115538"></a>(b) in the cases referred to in Article 329(5), at the latest on the working day following the day on which the goods have been placed under the external transit procedure;
<a id="p115539"></a>(c) in the cases referred to in Article 329(6), at the latest on the working day following the day on which the transit procedure has been discharged;
<a id="p115540"></a>(d) in the cases referred to in Article 329(7), at the latest on the working day following the day on which the goods have been taken over under cover of a single transport contract.
3. <a id="p115541"></a>Where the customs offices of exit and export are different and the exit of the goods is refused, the customs office of exit shall inform the customs office of export at the latest on the working day following the day on which the exit of the goods has been refused.
4. <a id="p115542"></a>Where goods covered by one export or re-export declaration are moved to a customs office of exit and subsequently leave the customs territory of the Union as more than one consignment due to unforeseen circumstances, the customs office of exit shall inform the customs office of export of the exit of the goods only once all the goods have left the customs territory of the Union.
5. <a id="p115543"></a>In unforeseen circumstances, where goods covered by one export or re-export declaration are moved to a customs office of exit and subsequently leave the customs territory of the Union through more than one customs office of exit, any of the persons referred to in Article 267(2) of the Code may request the customs office of exit where the goods were first presented to inform the other customs office(s) of exit from where part of the goods will leave the customs territory of the Union. Each customs office of exit shall supervise the physical exit of the goods which leave the customs territory of the Union from that office. The subsequent customs office(s) of exit shall inform the first customs office of exit about those goods which have left the customs territory of Union from those offices. The first customs office of exit and the subsequent customs office(s) of exit shall exchange that information in agreement with each other, and outside the Automated Export System referred to in the Annex to Implementing Decision (EU) 2016/578. The first customs office of exit shall inform the customs office of export when all the goods have left the customs territory of the Union.
6. <a id="p115544"></a>Where goods are to leave the customs territory of the Union in the case referred to in Article 329(7) of this Regulation, the carrier shall upon the request by the competent customs authorities at the point of exit provide information on those goods. That information shall consist in one of the following:
<a id="p115545"></a>(a) the MRN of the export declaration;
<a id="p115546"></a>(b) a copy of the single transport contract for the goods concerned;
<a id="p115547"></a>(c) the unique consignment reference number or the transport document reference number and where the goods are presented in packages or containerised, the number of packages and, if containerised, the container identification number.
7. <a id="p115548"></a>By derogation from points (b) and (c) of the second subparagraph of paragraph 2 of this Article, until the dates of deployment of the Automated Export System referred to in the Annex to Implementing Decision (EU) 2016/578, in the cases referred to in Article 329(5) and 329(6) of this Regulation, the time-limit for the customs office of exit to inform the customs office of export of the exit of the goods shall be the first working day following the day on which the goods are placed under that transit procedure or the goods leave the customs territory of the union or the transit procedure is discharged.

<a id="p115549"></a>Article 334

<a id="p115550"></a>Certification of exit of goods
(Article 267 of the Code)

1. <a id="p115551"></a>The customs office of export shall certify the exit of the goods to the declarant or the exporter in the following cases:
<a id="p115552"></a>(a) where that office has been informed of the exit of the goods by the customs office of exit;
<a id="p115553"></a>(b) where that office is the same as the customs office of exit and the goods have exited;
<a id="p115554"></a>(c) where that office considers that the evidence provided in accordance with Article 335(4) of this Regulation is sufficient.
2. <a id="p115555"></a>Where the customs office of export has certified the exit of the goods in accordance with paragraph 1(c), it shall inform the customs office of exit thereof.

<a id="p115556"></a>Article 335

<a id="p115557"></a>Enquiry procedure
(Article 267 of the Code)

1. <a id="p115558"></a>Where, after 90 days from the release of goods for export, the customs office of export has not been informed of the exit of the goods, it may request the declarant to inform it of the date on which and the customs office of exit from which the goods left the customs territory of the Union.
2. <a id="p115559"></a>The declarant may, on his own initiative, inform the customs office of export of the dates on which and the customs offices of exit from which the goods left the customs territory of the Union.
3. <a id="p115560"></a>Where the declarant provides information to the customs office of export in accordance with paragraph 1 or 2, he may request the customs office of export to certify the exit. For that purpose, the customs office of export shall request information on the exit of the goods from the customs office of exit, which shall respond within 10 days.
<a id="p115561"></a>Where the customs office of exit does not respond within that timelimit, the customs office of export shall inform the declarant thereof.
4. <a id="p115562"></a>Where the customs office of export informs the declarant that the customs office of exit has not responded within the time-limit referred to in paragraph 3, the declarant may provide to the customs office of export evidence that the goods have left the customs territory of the Union.
<a id="p115563"></a>That evidence may be provided, in particular, by one of the following means or a combination thereof:
<a id="p115564"></a>(a) a copy of the delivery note signed or authenticated by the consignee outside the customs territory of the Union;
<a id="p115565"></a>(b) the proof of payment;
<a id="p115566"></a>(c) the invoice;
<a id="p115567"></a>(d) the delivery note;
<a id="p115568"></a>(e) a document signed or authenticated by the economic operator which has taken the goods out of the customs territory of the Union;
<a id="p115569"></a>(f) a document processed by the customs authority of a Member State or a third country in line with the rules and procedures applicable in that State or country;
<a id="p115570"></a>(g) economic operators' records of goods supplied to ships, aircraft or offshore installations.

<a id="p115571"></a>**CHAPTER 3**

<a id="p115572"></a>**EXPORT AND RE-EXPORT**

<a id="p115573"></a>Article 336

<a id="p115574"></a>Export or re-export declaration
for goods in several consignments
(Article 162 of the Code)

<a id="p115575"></a>Where goods are intended to be taken out of the customs territory of the Union as more than one consignment each individual consignment shall be covered by a separate export or re-export declaration.

<a id="p115576"></a>Article 337

<a id="p115577"></a>Retrospective lodgement
of an export or re-export declaration
(Articles 162 and 267 of the Code)

1. <a id="p115578"></a>Where an export or re-export declaration was required but the goods have been brought out of the customs territory of the Union without such declaration, the exporter shall lodge a retrospective export or re-export declaration. That declaration shall be lodged at the customs office competent for the place where the exporter is established. That customs office shall certify the exit of the goods to the exporter provided that the release would have been granted if the declaration had been lodged before the exit of the goods from the customs territory of the Union and it has the evidence at its disposal that the goods have left the customs territory of the Union.
2. <a id="p115579"></a>Where Union goods which were intended for re-import have left the customs territory of the Union but are no longer intended to be re-imported, and a different type of customs declaration would have been used if there was no intention of re-importation, the exporter may lodge a retrospective export declaration, replacing the original declaration, at the customs office of export. That customs office shall certify the exit of the goods to the exporter.
<a id="p115580"></a>However, where the Union goods have left the customs territory of the Union under cover of an ATA and CPD carnet, the customs office of export shall certify the exit of the goods to the exporter provided that the re-importation voucher and counterfoil of the ATA and CPD carnet are invalidated.

<a id="p115581"></a>Article 338

<a id="p115582"></a>Lodgement of a re-export declaration
for goods covered by an ATA and CPD carnet
(Article 159(3) of the Code)

<a id="p115583"></a>The competent customs office for the re-export of goods covered by an ATA and CPD carnet shall, in addition to the customs offices referred to in Article 221(2) of this Regulation, be the customs office of exit.

<a id="p115584"></a>Article 339

<a id="p115585"></a>Use of an ATA and CPD carnet as an export declaration
(Article 162 of the Code)

1. <a id="p115586"></a>An ATA and CPD carnet shall be considered an export declaration where the carnet has been issued in a Member State contracting party to the ATA Convention or Istanbul Convention and endorsed and guaranteed by an association established in the Union and forming part of a guaranteeing chain as defined in Article 1(d) of Annex A to the Istanbul Convention.
2. <a id="p115587"></a>The ATA and CPD carnet shall not be used as an export declaration in relation to Union goods where:
<a id="p115588"></a>(a) those goods are subject to export formalities with a view to refunds being granted on export under the common agricultural policy;
<a id="p115589"></a>(b) those goods that have been part of intervention stocks, are subject to measures of control as to use or destination, and have undergone customs formalities on export to territories outside the customs territory of the Union under the common agricultural policy;
<a id="p115590"></a>(c) those goods are eligible for the repayment or remission of import duty on the condition that they are exported from the customs territory of the Union;
<a id="p115591"></a>(d) those goods are moved under a duty suspension arrangement within the territory of the Union pursuant to Directive 2008/118/EC, except where the provisions of Article 30 of that Directive apply.
3. <a id="p115592"></a>Where an ATA carnet is used as an export declaration, the customs office of export shall carry out the following formalities:
<a id="p115593"></a>(a) verify the information given in boxes A to G of the exportation voucher against the goods under cover of the carnet;
<a id="p115594"></a>(b) complete, where appropriate, the box on the cover page of the carnet headed "Certificate by customs authorities";
<a id="p115595"></a>(c) complete the counterfoil and box H of the exportation voucher;
<a id="p115596"></a>(d) identify the customs office of export in box H(b) of the re-importation voucher;
<a id="p115597"></a>(e) retain the exportation voucher.
4. <a id="p115598"></a>Where the customs office of export is not the customs office of exit, the customs office of export shall carry out the formalities referred to in paragraph 3, but it shall not complete box 7 of the counterfoil, which shall be completed by the customs office of exit.
5. <a id="p115599"></a>The time-limits for re-importing the goods set by the customs office of export in box H(b) of the exportation voucher may not exceed the validity of the carnet.

<a id="p115600"></a>Article 340

<a id="p115601"></a>Goods released for export or re-export that do not
leave the customs territory of the Union
(Article 267 of the Code)

1. <a id="p115602"></a>Where goods released for the export or re-export are no longer intended to be taken out of the customs territory of the Union, the declarant shall immediately inform the customs office of export.
2. <a id="p115603"></a>Without prejudice to paragraph 1, where the goods have already been presented to the customs office of exit, the person who removes the goods from the customs office of exit for carriage to a place within the customs territory of the Union shall inform the customs office of exit that the goods will not be taken out of the customs territory of the Union and specify the MRN of the export or re-export declaration.
3. <a id="p115604"></a>Where, in the cases referred to in Article 329(5), (6) and (7), a modification in the transport contract has the effect of terminating inside the customs territory of the Union a transport operation which should have terminated outside, the companies or authorities in question shall inform the customs office of exit of that modification and may only carry out the modified contract with the prior agreement of that customs office.
<a id="p115605"></a>3a. From the date of deployment of the Automated Export System (AES) referred to in the Annex to Implementing Decision (EU) 2016/578 at the latest, in the cases referred to in paragraphs 2 and 3, the customs office of exit shall inform the customs office of export that the goods were not taken out of the customs territory of the Union.
4. <a id="p115606"></a>In the case of an invalidation of the export or re-export declaration in accordance with Article 248 of Delegated Regulation (EU) 2015/2446, the customs office of export shall inform the declarant and the declared customs office of exit of that invalidation.

<a id="p115607"></a>**CHAPTER 4**

<a id="p115608"></a>**EXIT SUMMARY DECLARATION**

<a id="p115609"></a>Article 341

<a id="p115610"></a>Measures to be taken
upon receipt of an exit summary declaration
(Article 271 of the Code)

<a id="p115611"></a>The customs office where the exit summary declaration is lodged in accordance with Article 271(1) of the Code shall:
<a id="p115612"></a>(a) register the exit summary declaration immediately upon its receipt;
<a id="p115613"></a>(b) provide a MRN to the declarant;
<a id="p115614"></a>(c) where appropriate, release the goods for exit from the customs territory of the Union.

<a id="p115615"></a>Article 342

<a id="p115616"></a>Goods for which an exit summary declaration has been lodged
that do not leave the customs territory of the Union
(Article 174 of the Code)

<a id="p115617"></a>Where goods for which an exit summary declaration has been lodged are no longer intended to be taken out of the customs territory of the Union, the person who removes the goods from the customs office of exit for carriage to a place within that territory shall inform the customs office of exit that the goods will not be taken out of the customs territory of the Union and specify the MRN of the exit summary declaration.

<a id="p115618"></a>**CHAPTER 5**

<a id="p115619"></a>**RE-EXPORT NOTIFICATION**

<a id="p115620"></a>Article 343

<a id="p115621"></a>Measures to be taken
upon receipt of a re-export notification
(Article 274 of the Code)

<a id="p115622"></a>The customs office of exit shall:
<a id="p115623"></a>(a) register the re-export notification immediately upon its receipt;
<a id="p115624"></a>(b) provide a MRN to the declarant;
<a id="p115625"></a>(c) where appropriate, release the goods for exit from the customs territory of the Union.

<a id="p115626"></a>Article 344

<a id="p115627"></a>Goods for which a re-export notification has been lodged
that do not leave the customs territory of the Union
(Article 174 of the Code)

<a id="p115628"></a>Where goods for which a re-export notification has been lodged are no longer intended to be taken out of the customs territory of the Union, the person who removes the goods from the customs office of exit for carriage to a place within that territory shall inform the customs office of exit that the goods will not be taken out of the customs territory of the Union and specify the MRN of the re-export notification.

<a id="p115629"></a>**TITLE IX. FINAL PROVISIONS**

<a id="p115630"></a>Article 345

<a id="p115631"></a>Procedural rules for the reassessment of authorisations
already in force on 1 May 2016

1. <a id="p115632"></a>Decisions following a reassessment of an authorisation in accordance with Article 250(1) of Delegated Regulation (EU) 2015/2446 shall be taken before 1 May 2019.
<a id="p115633"></a>Those decisions shall revoke the reassessed authorisations and, where appropriate, grant new authorisations. The decisions shall be notified to the holders of the authorisation without delay.
2. <a id="p115634"></a>In the cases referred to in Article 253(b) of Delegated Regulation (EU) 2015/2446, if a new authorisation to use a comprehensive guarantee is granted as a result of the reassessment of an authorisation to use a comprehensive guarantee linked to a decision granting deferment of payment using one of the procedures referred to in Article 226(b) or (c) of Council Regulation (EEC) No 2913/92 <*>, a new deferment of payment authorisation shall be issued automatically at the same time in accordance with Article 110 of the Code.

<a id="p115635"></a>

---

<a id="p115636"></a><*> Council Regulation (EEC) No 2913/92 of 12 October 1992 establishing the Community Customs Code (OJ L 302, 19.10.1992, p. 1).

3. <a id="p115637"></a>Where the authorisations referred to in Article 251 of Delegated Regulation (EU) 2015/2446 contains references to Regulation (EEC) No 2913/92 or Regulation (EEC) No 2454/93, those references shall be read in accordance with the table of correspondence set out in Annex 90 of Delegated Regulation (EU) 2015/2446.
4. <a id="p115638"></a>By derogation from paragraph 1, Single Authorisations for Simplified Procedures (SASP) issued in accordance with Regulation (EEC) No 2454/93 and still valid on 1 May 2016 shall remain valid until the respective dates of deployment of the CCI and AES referred to in the Annex to Implementing Decision 2016/578/EU.

<a id="p115639"></a>Article 346

<a id="p115640"></a>Transitional provisions concerning applications for
authorisations submitted before 1 May 2016

<a id="p115641"></a>Customs authorities may accept applications for the granting of authorisations in accordance with the Code and this Regulation submitted before 1 May 2016. The customs authority competent to take the decision may grant authorisations in accordance with the Code and this Regulation before 1 May 2016. However, those authorisations shall not be valid before 1 May 2016.

<a id="p115642"></a>Article 347

<a id="p115643"></a>Transitional provision on transaction value

1. <a id="p115644"></a>The transaction value of the goods may be determined on the basis of a sale occurring before the sale referred to in Article 128(1) of this Regulation where the person on whose behalf the declaration is lodged is bound by a contract concluded prior to 18 January 2016.
2. <a id="p115645"></a>This Article shall apply until 31 December 2017.

<a id="p115646"></a>Article 348

<a id="p115647"></a>Transitional provisions concerning the release of goods

<a id="p115648"></a>Where goods have been declared for release for free circulation, customs warehousing, inward processing, processing under customs control, temporary admission, end-use, transit, export or outward processing in accordance with Regulation (EEC) No 2913/92 before 1 May 2016 and have not been released by that date, they shall be released for the procedure stated in the declaration in accordance with the relevant provisions of the Code, Delegated Regulation (EU) 2015/2446 and this Regulation.

<a id="p115649"></a>Article 349

<a id="p115650"></a>Transitional provisions for goods placed under certain
customs procedures which have not been discharged
before 1 May 2016

1. <a id="p115651"></a>Where goods were placed under the following customs procedures before 1 May 2016, and the procedure has not been discharged before that date, the procedure shall be discharged in accordance with the relevant provisions of the Code, Delegated Regulation (EU) 2015/2446 and this Regulation:
<a id="p115652"></a>(a) release of goods for free circulation with a favourable tariff treatment or at a reduced or zero rate of duty on account of their end-use;
<a id="p115653"></a>(b) customs warehousing of types A, B, C, E and F;
<a id="p115654"></a>(c) inward processing in the form of the suspension system;
<a id="p115655"></a>(d) processing under customs control.
2. <a id="p115656"></a>Where goods were placed under the following customs procedures before 1 May 2016, and the procedure has not been discharged before that date, the procedure shall be discharged in accordance with relevant provisions of Regulation (EEC) No 2913/92 and Regulation (EEC) No 2454/93:
<a id="p115657"></a>(a) customs warehousing of type D;
<a id="p115658"></a>(b) temporary importation;
<a id="p115659"></a>(c) inward processing in the form of the drawback system;
<a id="p115660"></a>(d) outward processing.
<a id="p115661"></a>However, as from 1 January 2019 the procedure for customs warehousing of Type D shall be discharged in accordance with the relevant provisions of the Code, Delegated Regulation (EU) 2015/2446 and this Regulation.
3. <a id="p115662"></a>Goods placed in a free zone of control type II as referred to in Article 799 of Regulation (EEC) No 2454/93 or in a free warehouse which have not been assigned to a customs approved treatment or use in accordance with Regulation (EEC) No 2913/92 shall, from 1 May 2016, be considered to be placed under a customs warehousing procedure in accordance with the relevant provisions of the Code, Delegated Regulation (EU) 2015/2446 and this Regulation.
4. <a id="p115663"></a>Where goods have been released for a transit operation before 1 May 2016 and that operation has not been discharged by that date, it shall be discharged in accordance with the relevant provisions of Regulation (EEC) No 2913/92 and Regulation (EEC) No 2454/93.

<a id="p115664"></a>Article 350

<a id="p115665"></a>This Regulation shall enter into force on the twentieth day following that of its publication in the Official Journal of the European Union.
<a id="p115666"></a>It shall apply from 1 May 2016.
<a id="p115667"></a>This Regulation shall be binding in its entirety and directly applicable in all Member States.


<a id="p115668"></a>Annex A

<a id="p115669"></a>**FORMATS AND CODES OF THE COMMON DATA REQUIREMENTS FOR**
**APPLICATIONS AND DECISIONS**

<a id="p115670"></a>**GENERAL PROVISIONS**

1. <a id="p115671"></a>The provisions included in these notes are applicable to all Titles of this Annex.
2. <a id="p115672"></a>The formats, codes and if applicable, the structure of the data requirements included in this Annex are applicable in relation with the data requirements for applications and decisions as provided for in Annex A to Delegated Regulation (EU) 2015/2446.
3. <a id="p115673"></a>The formats and the codes defined in this Annex shall apply to applications and decisions made by using an electronic data processing technique as well as to paper-based applications and decisions.
4. <a id="p115674"></a>Title I includes the formats of the data elements.
5. <a id="p115675"></a>Whenever the information in an application or decision dealt with in Annex A to Delegated Regulation (EU) 2015/2446 takes the form of codes, the code-list provided for in Title II shall be applied.
6. <a id="p115676"></a>The size of a data element shall not prevent the applicant to provide sufficient information. Where the details necessary cannot fit within a given data element format, attachments shall be used.
7. <a id="p115677"></a>The term "type/length" in the explanation of an attribute indicates the requirements for the data type and the data length. The codes for the data types are as follows:


| <a id="p115678"></a>a | <a id="p115679"></a>alphabetic |
| --- | --- |
| <a id="p115680"></a>n | <a id="p115681"></a>numeric |
| <a id="p115682"></a>an | <a id="p115683"></a>alphanumeric |


<a id="p115684"></a>The number following the code indicates the admissible data length. The following applies:
<a id="p115685"></a>The optional two dots before the length indicator mean that the data has no fixed length, but it can have up to a number of digits, as specified by the length indicator. A comma in the data length means that the attribute can hold decimals, the digit before the comma indicates the total length of the attribute, the digit after the comma indicates the maximum number of digits after the decimal point.
<a id="p115686"></a>Examples of field lengths and formats:


| <a id="p115687"></a>a1 | <a id="p115688"></a>1 alphabetic character, fixed length |
| --- | --- |
| <a id="p115689"></a>n2 | <a id="p115690"></a>2 numeric characters, fixed length |
| <a id="p115691"></a>an3 | <a id="p115692"></a>3 alphanumeric characters, fixed length |
| <a id="p115693"></a>a..4 | <a id="p115694"></a>up to 4 alphabetic characters |
| <a id="p115695"></a>n..5 | <a id="p115696"></a>up to 5 numeric characters |
| <a id="p115697"></a>an..6 | <a id="p115698"></a>up to 6 alphanumeric characters |
| <a id="p115699"></a>n..7,2 | <a id="p115700"></a>up to 7 numeric characters including maximum 2 decimals, a delimiter being allowed to float. |


8. <a id="p115701"></a>The abbreviations and acronyms used in the Annex shall be interpreted the following way:


| <a id="p115702"></a>Abbreviation/acronym | <a id="p115703"></a>Meaning |
| --- | --- |
| <a id="p115704"></a>D.E. | <a id="p115705"></a>Data element |
| <a id="p115706"></a>n.a. | <a id="p115707"></a>Not applicable |


9. <a id="p115708"></a>The cardinality refers to the maximum possible number of recurrences of a given data element within the application or decision concerned.

<a id="p115709"></a>**TITLE I. FORMATS OF THE COMMON DATA REQUIREMENTS**
**FOR APPLICATIONS AND DECISIONS**


| <a id="p115710"></a>Reference to the Title in Annex A to Delegated<br>Regulation (EU) 2015/2446 | <a id="p115711"></a>D.E. order number | <a id="p115712"></a>D.E. name | <a id="p115713"></a>D.E. format<br>(Type/length) | <a id="p115714"></a>Cardinality | <a id="p115715"></a>Code-list in<br>Title II (Y/N) | <a id="p115716"></a>Notes |
| --- | --- | --- | --- | --- | --- | --- |
| <a id="p115717"></a>Title I | <a id="p115718"></a>1/1 | <a id="p115719"></a>Application/Decision code type | <a id="p115720"></a>an..4 | <a id="p115721"></a>1x | <a id="p115722"></a>Y |  |
| <a id="p115723"></a>Title I | <a id="p115724"></a>1/2 | <a id="p115725"></a>Signature/authentication | <a id="p115726"></a>an..256 | <a id="p115727"></a>1x | <a id="p115728"></a>N |  |
| <a id="p115729"></a>Title I | <a id="p115730"></a>1/3 | <a id="p115731"></a>Type of application | <a id="p115732"></a>Code: n1 + (if applicable) Decision reference number:<br>- country code: a2 +<br>- decision code type: an..4 +<br>- reference number: an..29 | <a id="p115733"></a>1x | <a id="p115734"></a>Y |  |
| <a id="p115735"></a>Title I | <a id="p115736"></a>1/4 | <a id="p115737"></a>Geographical validity - Union | <a id="p115738"></a>Code: n1 + (if applicable)<br>Country code: a2 | <a id="p115739"></a>Validity code: 1x<br>Country code: 99x | <a id="p115740"></a>Y | <a id="p115741"></a>As for the country code, the code defined in Commission Regulation (EU) No 1106/2012 <*> shall be used. |
| <a id="p115742"></a>Title I | <a id="p115743"></a>1/5 | <a id="p115744"></a>Geographical validity -<br>Common transit countries | <a id="p115745"></a>Country code: a2 | <a id="p115746"></a>99x | <a id="p115747"></a>N | <a id="p115748"></a>As for the country code, the ISO 3166 alpha-2 codes shall be used. |
| <a id="p115749"></a>Title I | <a id="p115750"></a>1/6 | <a id="p115751"></a>Decision reference number | <a id="p115752"></a>Country code: a2 +<br>Decision code type: an..4 +<br>Reference number: an..29 | <a id="p115753"></a>1x | <a id="p115754"></a>Y | <a id="p115755"></a>The structure is defined in Title II. |
| <a id="p115756"></a>Title I | <a id="p115757"></a>1/7 | <a id="p115758"></a>Decision taking customs authority | <a id="p115759"></a>Coded: an8<br>OR<br>Name: an..70 +<br>Street and number: an..70 +<br>Country: a2 +<br>Postcode: an..9 +<br>City: an..35 | <a id="p115760"></a>1x | <a id="p115761"></a>N | <a id="p115762"></a>The structure of the codes is defined in Title II. |
| <a id="p115763"></a>Title I | <a id="p115764"></a>2/1 | <a id="p115765"></a>Other applications and decisions relating to binding information held | <a id="p115766"></a>Tick-box: n1 +<br>Country of application: a2 +<br>Place of application: an..35 +<br>Date of application: n8<br>(yyyymmdd) +<br>Decision reference number: a2 (country code) + an..4 (decision code type) + an..29 (reference number) +<br>Start date of the decision:<br>n8 (yyyymmdd) +<br>Commodity code: an..22 | <a id="p115767"></a>Tick-box: 1x<br>Otherwise: 99x | <a id="p115768"></a>N |  |
| <a id="p115769"></a>Title I | <a id="p115770"></a>2/2 | <a id="p115771"></a>Decisions relating to binding information issued to other Holders | <a id="p115772"></a>Tick-box: n1 +<br>Decision reference number: a2 (country code) + an..4 (decision code type) + an..29 (reference number) +<br>Start date of the decision: n8 (yyyymmdd) +<br>Commodity code: an..22 | <a id="p115773"></a>Tick-box: 1x<br>Otherwise: 99x | <a id="p115774"></a>N |  |
| <a id="p115775"></a>Title I | <a id="p115776"></a>2/3 | <a id="p115777"></a>Legal or administrative procedures pending or handed down | <a id="p115778"></a>Country code: a2 +<br>Name of the court: an..70 +<br>Address of the court:<br>Street and number: an..70 +<br>Country: a2 +<br>Postcode: an..9 +<br>City: an..35 +<br>Reference to legal and/or administrative procedures: an..512 | <a id="p115779"></a>99x | <a id="p115780"></a>N |  |
| <a id="p115781"></a>Title I | <a id="p115782"></a>2/4 | <a id="p115783"></a>Attached documents | <a id="p115784"></a>Total number of documents: n..3 + Document type: an..70 +<br>Document identifier: an..35 +<br>Document date: n8 (yyyymmdd) | <a id="p115785"></a>1x<br>999x |  |  |
| <a id="p115786"></a>Title I | <a id="p115787"></a>2/5 | <a id="p115788"></a>Identification number of the storage facility | <a id="p115789"></a>an..35 | <a id="p115790"></a>999x | <a id="p115791"></a>N |  |
| <a id="p115792"></a>Title I | <a id="p115793"></a>3/1 | <a id="p115794"></a>Applicant/Holder of the authorisation or decision | <a id="p115795"></a>Name: an..70 +<br>Street and number: an..70 +<br>Country: a2 +<br>Postcode: an..9 +<br>City: an..35 | <a id="p115796"></a>1x | <a id="p115797"></a>N |  |
| <a id="p115798"></a>Title I | <a id="p115799"></a>3/2 | <a id="p115800"></a>Applicant/Holder of the authorisation or decision identification | <a id="p115801"></a>an..17 | <a id="p115802"></a>1x | <a id="p115803"></a>N |  |
| <a id="p115804"></a>Title I | <a id="p115805"></a>3/3 | <a id="p115806"></a>Representative | <a id="p115807"></a>Name: an..70 +<br>Street and number: an..70 +<br>Country: a2 +<br>Postcode: an..9 +<br>City: an..35 | <a id="p115808"></a>1x | <a id="p115809"></a>N |  |
| <a id="p115810"></a>Title I | <a id="p115811"></a>3/4 | <a id="p115812"></a>Representative identification | <a id="p115813"></a>an..17 | <a id="p115814"></a>1x | <a id="p115815"></a>N |  |
| <a id="p115816"></a>Title I | <a id="p115817"></a>3/5 | <a id="p115818"></a>Name and contact details of the person responsible for customs matters | <a id="p115819"></a>Name: an..70 +<br>Telephone number: an..50 +<br>Fax number: an..50 +<br>E-mail address: an..50 | <a id="p115820"></a>1x | <a id="p115821"></a>N |  |
| <a id="p115822"></a>Title I | <a id="p115823"></a>3/6 | <a id="p115824"></a>Contact person responsible for the application | <a id="p115825"></a>Name: an..70 +<br>Telephone number: an..50 +<br>Fax number: an..50 +<br>E-mail address: an..50 | <a id="p115826"></a>1x | <a id="p115827"></a>N |  |
| <a id="p115828"></a>Title I | <a id="p115829"></a>3/7 | <a id="p115830"></a>Person in charge of the applicant company or exercising control over its management | <a id="p115831"></a>Name: an..70 +<br>Street and number: an..70 +<br>Country: a2 +<br>Postcode: an..9 +<br>City: an..35 +<br>National identification number: an..35 +<br>Date of birth: n8 (yyyymmdd) | <a id="p115832"></a>99x | <a id="p115833"></a>N |  |
| <a id="p115834"></a>Title I | <a id="p115835"></a>3/8 | <a id="p115836"></a>Owner of the goods | <a id="p115837"></a>Name: an..70 +<br>Street and number: an..70 +<br>Country: a2 +<br>Postcode: an..9 +<br>City: an..35 | <a id="p115838"></a>99x | <a id="p115839"></a>N |  |
| <a id="p115840"></a>Title I | <a id="p115841"></a>4/1 | <a id="p115842"></a>Place | <a id="p115843"></a>n.a. |  | <a id="p115844"></a>N | <a id="p115845"></a>Data element used only for paper-based applications and decisions. |
| <a id="p115846"></a>Title I | <a id="p115847"></a>4/2 | <a id="p115848"></a>Date | <a id="p115849"></a>n8 (yyyymmdd) | <a id="p115850"></a>1x | <a id="p115851"></a>N |  |
| <a id="p115852"></a>Title I | <a id="p115853"></a>4/3 | <a id="p115854"></a>Place where main accounts for customs purposes are held or accessible | <a id="p115855"></a>Street and number: an..70 +<br>Country: a2 +<br>Postcode: an..9 +<br>City: an..35<br>OR<br>UN/LOCODE: an..17 | <a id="p115856"></a>1x | <a id="p115857"></a>N | <a id="p115858"></a>If the UN/LOCODE is used to define the location concerned, the structure shall follow the description provided for in UN-ECE Recommendation 16 on UN/LOCODE - Code for ports and other locations. |
| <a id="p115859"></a>Title I | <a id="p115860"></a>4/4 | <a id="p115861"></a>Place where records are kept | <a id="p115862"></a>Street and number: an..70 +<br>Country: a2 +<br>Postcode: an..9 +<br>City: an..35<br>OR<br>UN/LOCODE: an..17 | <a id="p115863"></a>99x | <a id="p115864"></a>N | <a id="p115865"></a>If the UN/LOCODE is used to define the location concerned, the structure shall follow the description provided for in UN-ECE Recommendation 16 on UN/LOCODE - Code for ports and other locations. |
| <a id="p115866"></a>Title I | <a id="p115867"></a>4/5 | <a id="p115868"></a>First place of use or processing | <a id="p115869"></a>Country: a2 +<br>Type of location code: a1 +<br>Qualifier of the identification: a1 +<br>Coded:<br>Identification of location: an..35 +<br>Additional identifier: n..3<br>OR<br>Free text description:<br>Street and number: an..70 +<br>Postcode: an..9 +<br>City: an..35 | <a id="p115870"></a>1x | <a id="p115871"></a>N | <a id="p115872"></a>The structure and the codes defined in Annex B for D.E. 5/23 Location of goods shall be used for the indication of the location. |
| <a id="p115873"></a>Title I | <a id="p115874"></a>4/6 | <a id="p115875"></a>[Requested] Start date of the decision | <a id="p115876"></a>n8 (yyyymmdd)<br>OR<br>Free text: an..512 | <a id="p115877"></a>1x | <a id="p115878"></a>N |  |
| <a id="p115879"></a>Title I | <a id="p115880"></a>4/7 | <a id="p115881"></a>Date of expiry of the decision | <a id="p115882"></a>n8 (yyyymmdd) | <a id="p115883"></a>1x | <a id="p115884"></a>N |  |
| <a id="p115885"></a>Title I | <a id="p115886"></a>4/8 | <a id="p115887"></a>Location of goods | <a id="p115888"></a>Country: a2 +<br>Type of location code: a1 +<br>Qualifier of the identification: a1 +<br>Coded:<br>Identification of location: an..35 +<br>Additional identifier: n..3<br>OR<br>Free text description:<br>Name: an..70 +<br>Street and number: an..70 +<br>Postcode: an..9 +<br>City: an..35 | <a id="p115889"></a>9999x | <a id="p115890"></a>N | <a id="p115891"></a>The structure and the codes defined in Annex B for D.E. 5/23 Location of goods shall be used for the indication of the location. |
| <a id="p115892"></a>Title I | <a id="p115893"></a>4/9 | <a id="p115894"></a>Place(s) of processing or use | <a id="p115895"></a>Country: a2 +<br>Type of location code: a1 +<br>Qualifier of the identification: a1 +<br>Coded:<br>Identification of location: an..35 +<br>Additional identifier: n..3<br>OR<br>Free text description:<br>Name: an..70 +<br>Street and number: an..70 +<br>Postcode: an..9 +<br>City: an..35 | <a id="p115896"></a>999x | <a id="p115897"></a>N | <a id="p115898"></a>The structure and the codes defined in Annex B for D.E. 5/23 Location of goods shall be used for the indication of the location. |
| <a id="p115899"></a>Title I | <a id="p115900"></a>4/10 | <a id="p115901"></a>Customs office(s) of placement | <a id="p115902"></a>an8 | <a id="p115903"></a>999x | <a id="p115904"></a>N | <a id="p115905"></a>The structure of the codes is defined in<br>Title II for D.E. 1/7 Decision taking customs authority. |
| <a id="p115906"></a>Title I | <a id="p115907"></a>4/11 | <a id="p115908"></a>Customs office(s) of discharge | <a id="p115909"></a>an8 | <a id="p115910"></a>999x | <a id="p115911"></a>N | <a id="p115912"></a>The structure of the codes is defined in<br>Title II for D.E. 1/7 Decision taking customs authority. |
| <a id="p115913"></a>Title I | <a id="p115914"></a>4/12 | <a id="p115915"></a>Customs office of guarantee | <a id="p115916"></a>an8 | <a id="p115917"></a>1x | <a id="p115918"></a>N | <a id="p115919"></a>The structure of the codes is defined in<br>Title II for D.E. 1/7 Decision taking customs authority. |
| <a id="p115920"></a>Title I | <a id="p115921"></a>4/13 | <a id="p115922"></a>Supervising customs office | <a id="p115923"></a>an8 | <a id="p115924"></a>1x | <a id="p115925"></a>N | <a id="p115926"></a>The structure of the codes is defined in<br>Title II for D.E. 1/7 Decision taking customs authority. |
| <a id="p115927"></a>Title I | <a id="p115928"></a>4/14 | <a id="p115929"></a>Customs office(s) of destination | <a id="p115930"></a>an8 | <a id="p115931"></a>999x | <a id="p115932"></a>N | <a id="p115933"></a>The structure of the codes is defined in<br>Title II for D.E. 1/7 Decision taking customs authority. |
| <a id="p115934"></a>Title I | <a id="p115935"></a>4/15 | <a id="p115936"></a>Customs office(s) of departure | <a id="p115937"></a>an8 | <a id="p115938"></a>999x | <a id="p115939"></a>N | <a id="p115940"></a>The structure of the codes is defined in Title II for D.E. 1/7 Decision taking customs authority. |
| <a id="p115941"></a>Title I | <a id="p115942"></a>4/16 | <a id="p115943"></a>Time-limit | <a id="p115944"></a>n..4 | <a id="p115945"></a>1x | <a id="p115946"></a>N |  |
| <a id="p115947"></a>Title I | <a id="p115948"></a>4/17 | <a id="p115949"></a>Period for discharge | <a id="p115950"></a>Period: n..2 +<br>Tick-box: n1 +<br>Free text: an..512 | <a id="p115951"></a>1x | <a id="p115952"></a>N |  |
| <a id="p115953"></a>Title I | <a id="p115954"></a>4/18 | <a id="p115955"></a>Bill of discharge | <a id="p115956"></a>Tick-box: n1 +<br>Deadline: n2 +<br>Free text: an..512 | <a id="p115957"></a>1x | <a id="p115958"></a>N |  |
| <a id="p115959"></a>Title I | <a id="p115960"></a>5/1 | <a id="p115961"></a>Commodity code | <a id="p115962"></a>1st subdivision (Combined Nomenclature code): an..8 +<br>2nd subdivision (TARIC subheading): an2 +<br>3rd subdivision (TARIC additional code(s)): an4 +<br>4th subdivision (national additional code(s)):<br>an..4 | <a id="p115963"></a>999x<br>As regards decisions relating to binding information:<br>1x | <a id="p115964"></a>N |  |
| <a id="p115965"></a>Title I | <a id="p115966"></a>5/2 | <a id="p115967"></a>Description of goods | <a id="p115968"></a>Free text: an..512<br>As regards the application for and the decision relating to Binding Tariff Information, the format should be an..2560 | <a id="p115969"></a>999x<br>As regards decisions relating to binding information:<br>1x | <a id="p115970"></a>N |  |
| <a id="p115971"></a>Title I | <a id="p115972"></a>5/3 | <a id="p115973"></a>Goods quantity | <a id="p115974"></a>Measurement unit: an..4 +<br>Quantity: n..16,6 | <a id="p115975"></a>999x<br>As regards decisions relating to binding information: 1x | <a id="p115976"></a>N |  |
| <a id="p115977"></a>Title I | <a id="p115978"></a>5/4 | <a id="p115979"></a>Goods value | <a id="p115980"></a>Currency: a3 +<br>Amount: n..16,2 | <a id="p115981"></a>999x | <a id="p115982"></a>N | <a id="p115983"></a>The ISO-alpha-3 currency codes (ISO 4217) shall be used for the currency. |
| <a id="p115984"></a>Title I | <a id="p115985"></a>5/5 | <a id="p115986"></a>Rate of yield | <a id="p115987"></a>Free text: an..512 | <a id="p115988"></a>999x | <a id="p115989"></a>N |  |
| <a id="p115990"></a>Title I | <a id="p115991"></a>5/6 | <a id="p115992"></a>Equivalent goods | <a id="p115993"></a>Commodity code: an8 +<br>Tick-box: n1 +<br>Code: n1 +<br>Commercial quality and technical characteristics of goods: an..512 | <a id="p115994"></a>999x | <a id="p115995"></a>N | <a id="p115996"></a>The codes provided for D.E. 5/8 Identification of goods in Title II may be used. |
| <a id="p115997"></a>Title I | <a id="p115998"></a>5/7 | <a id="p115999"></a>Processed products | <a id="p116000"></a>Commodity code: an8 + Description of goods: an..512 | <a id="p116001"></a>999x | <a id="p116002"></a>N |  |
| <a id="p116003"></a>Title I | <a id="p116004"></a>5/8 | <a id="p116005"></a>Identification of goods | <a id="p116006"></a>Code: n1 +<br>Free text: an..512 | <a id="p116007"></a>999x | <a id="p116008"></a>Y |  |
| <a id="p116009"></a>Title I | <a id="p116010"></a>5/9 | <a id="p116011"></a>Excluded categories or movement of goods | <a id="p116012"></a>an6 | <a id="p116013"></a>999x | <a id="p116014"></a>N |  |
| <a id="p116015"></a>Title I | <a id="p116016"></a>6/1 | <a id="p116017"></a>Prohibitions and restrictions | <a id="p116018"></a>Free text: an..512 | <a id="p116019"></a>1x | <a id="p116020"></a>N |  |
| <a id="p116021"></a>Title I | <a id="p116022"></a>6/2 | <a id="p116023"></a>Economic conditions | <a id="p116024"></a>n..2 +<br>Free text: an..512 | <a id="p116025"></a>999x | <a id="p116026"></a>Y |  |
| <a id="p116027"></a>Title I | <a id="p116028"></a>6/3 | <a id="p116029"></a>General remarks | <a id="p116030"></a>Free text: an..512 | <a id="p116031"></a>1x | <a id="p116032"></a>N |  |
| <a id="p116033"></a>Title I | <a id="p116034"></a>7/1 | <a id="p116035"></a>Type of transaction | <a id="p116036"></a>Tick-box: n1 +<br>Type of special procedure: a..70 | <a id="p116037"></a>99x | <a id="p116038"></a>N |  |
| <a id="p116039"></a>Title I | <a id="p116040"></a>7/2 | <a id="p116041"></a>Type of customs procedures | <a id="p116042"></a>Procedure code: an2 +<br>Decision reference number (Country code: a2 + decision code type: an..4 + Reference number: an..29) | <a id="p116043"></a>99x | <a id="p116044"></a>N | <a id="p116045"></a>The codes provided for in Annex B concerning D.E. 1/10 Procedure shall be used for the indication of the type of customs procedure. Where the authorisation is intended to be used in the context of transit procedure, code "80" shall be used.<br>Where the authorisation is intended to be used for the operation of a temporary storage facility, code "XX" shall be used.<br>Where the authorisation is intended to be used for the operation of customs warehouses, the following codes shall be used:<br>- code "XR" for a public customs warehouse type I,<br>- code "XS" for a public customs warehouse type II,<br>- code "XU" for a private customs warehouse. |
| <a id="p116046"></a>Title I | <a id="p116047"></a>7/3 | <a id="p116048"></a>Type of declaration | <a id="p116049"></a>Type of declaration: n1 +<br>Decision reference number (Country code: a2 + decision code type: an..4 + Reference number: an..29) | <a id="p116050"></a>9x | <a id="p116051"></a>Y |  |
| <a id="p116052"></a>Title I | <a id="p116053"></a>7/4 | <a id="p116054"></a>Number of operations | <a id="p116055"></a>n..7 | <a id="p116056"></a>1x | <a id="p116057"></a>N |  |
| <a id="p116058"></a>Title I | <a id="p116059"></a>7/5 | <a id="p116060"></a>Details of planned activities | <a id="p116061"></a>Free text: an..512 | <a id="p116062"></a>1x | <a id="p116063"></a>N |  |
| <a id="p116064"></a>Title I | <a id="p116065"></a>8/1 | <a id="p116066"></a>Type of main accounts for customs purposes | <a id="p116067"></a>Free text: an..512 | <a id="p116068"></a>1x | <a id="p116069"></a>N |  |
| <a id="p116070"></a>Title I | <a id="p116071"></a>8/2 | <a id="p116072"></a>Type of records | <a id="p116073"></a>Free text: an..512 | <a id="p116074"></a>99x | <a id="p116075"></a>N |  |
| <a id="p116076"></a>Title I | <a id="p116077"></a>8/3 | <a id="p116078"></a>Access to data | <a id="p116079"></a>Free text: an..512 | <a id="p116080"></a>1x | <a id="p116081"></a>N |  |
| <a id="p116082"></a>Title I | <a id="p116083"></a>8/4 | <a id="p116084"></a>Samples etc. | <a id="p116085"></a>Tick-box: n1 | <a id="p116086"></a>1x | <a id="p116087"></a>N |  |
| <a id="p116088"></a>Title I | <a id="p116089"></a>8/5 | <a id="p116090"></a>Additional information | <a id="p116091"></a>Free text: an..512 | <a id="p116092"></a>1x | <a id="p116093"></a>N |  |
| <a id="p116094"></a>Title I | <a id="p116095"></a>8/6 | <a id="p116096"></a>Guarantee | <a id="p116097"></a>Tick-box: n1 +<br>GRN: an..24 | <a id="p116098"></a>1x | <a id="p116099"></a>Y |  |
| <a id="p116100"></a>Title I | <a id="p116101"></a>8/7 | <a id="p116102"></a>Guarantee amount | <a id="p116103"></a>Currency: a3 +<br>Amount: n..16,2 | <a id="p116104"></a>1x | <a id="p116105"></a>N | <a id="p116106"></a>The ISO-alpha-3 currency codes (ISO 4217) shall be used for the currency. |
| <a id="p116107"></a>Title I | <a id="p116108"></a>8/8 | <a id="p116109"></a>Transfer of rights and obligations | <a id="p116110"></a>Tick-box: n1 +<br>Free text: an..512 | <a id="p116111"></a>1x | <a id="p116112"></a>N |  |
| <a id="p116113"></a>Title I | <a id="p116114"></a>8/9 | <a id="p116115"></a>Keywords | <a id="p116116"></a>Free text: an..70 | <a id="p116117"></a>99x | <a id="p116118"></a>N |  |
| <a id="p116119"></a>Title I | <a id="p116120"></a>8/10 | <a id="p116121"></a>Details about the storage facilities | <a id="p116122"></a>Free text: an..512 | <a id="p116123"></a>999x | <a id="p116124"></a>N |  |
| <a id="p116125"></a>Title I | <a id="p116126"></a>8/11 | <a id="p116127"></a>Storage of Union goods | <a id="p116128"></a>Tick-box: n1 +<br>Free text: an..512 | <a id="p116129"></a>1x | <a id="p116130"></a>N |  |
| <a id="p116131"></a>Title I | <a id="p116132"></a>8/12 | <a id="p116133"></a>Consent for publication in the list of authorisation holders | <a id="p116134"></a>Tick-box: n1 | <a id="p116135"></a>1x | <a id="p116136"></a>N |  |
| <a id="p116137"></a>Title I | <a id="p116138"></a>8/13 | <a id="p116139"></a>Calculation of the amount of the import duty in accordance with Article 86(3) of the Code | <a id="p116140"></a>Tick-box: n1 | <a id="p116141"></a>1x | <a id="p116142"></a>N |  |
| <a id="p116143"></a>Title II | <a id="p116144"></a>II/1 | <a id="p116145"></a>Reissue of a BTI decision | <a id="p116146"></a>Tick-box: n1 +<br>BTI Decision reference number: a2 (country code) + an..4 (decision code type) + an..29 (reference number) +<br>BTI Decision validity: n8 (yyyymmdd) +<br>Commodity code: an..22 | <a id="p116147"></a>1x | <a id="p116148"></a>N |  |
| <a id="p116149"></a>Title II | <a id="p116150"></a>II/2 | <a id="p116151"></a>Customs nomenclature | <a id="p116152"></a>Tick-box: n1 +<br>an..70 | <a id="p116153"></a>1x | <a id="p116154"></a>N |  |
| <a id="p116155"></a>Title II | <a id="p116156"></a>II/3 | <a id="p116157"></a>Commercial denomination and additional information | <a id="p116158"></a>Free text: an..2560 | <a id="p116159"></a>1x | <a id="p116160"></a>N |  |
| <a id="p116161"></a>Title II | <a id="p116162"></a>II/4 | <a id="p116163"></a>Justification of the classification of the goods | <a id="p116164"></a>Free text: an..2560 | <a id="p116165"></a>1x | <a id="p116166"></a>N |  |
| <a id="p116167"></a>Title II | <a id="p116168"></a>II/5 | <a id="p116169"></a>Material provided by the applicant on the basis of which the BTI decision has been issued | <a id="p116170"></a>Tick-box: n1 | <a id="p116171"></a>99x | <a id="p116172"></a>N |  |
| <a id="p116173"></a>Title II | <a id="p116174"></a>II/6 | <a id="p116175"></a>Images | <a id="p116176"></a>Tick-box: n1 | <a id="p116177"></a>1x | <a id="p116178"></a>N |  |
| <a id="p116179"></a>Title II | <a id="p116180"></a>II/7 | <a id="p116181"></a>Date of application | <a id="p116182"></a>n8 (yyyymmdd) | <a id="p116183"></a>1x | <a id="p116184"></a>N |  |
| <a id="p116185"></a>Title II | <a id="p116186"></a>II/8 | <a id="p116187"></a>End date of extended use | <a id="p116188"></a>n8 (yyyymmdd) | <a id="p116189"></a>1x | <a id="p116190"></a>N |  |
| <a id="p116191"></a>Title II | <a id="p116192"></a>II/9 | <a id="p116193"></a>Invalidation reason | <a id="p116194"></a>n2 | <a id="p116195"></a>1x | <a id="p116196"></a>Y |  |
| <a id="p116197"></a>Title II | <a id="p116198"></a>II/10 | <a id="p116199"></a>Registration number of the application | <a id="p116200"></a>Country code: a2 +<br>Decision code type: an..4 +<br>Reference number: an..29 |  | <a id="p116201"></a>N | <a id="p116202"></a>The structure defined in Title II for D.E. 1/6 Decision reference number shall be used. |
| <a id="p116203"></a>Title III | <a id="p116204"></a>III/1 | <a id="p116205"></a>Legal basis | <a id="p116206"></a>n.a. |  | <a id="p116207"></a>N |  |
| <a id="p116208"></a>Title III | <a id="p116209"></a>III/2 | <a id="p116210"></a>Composition of the goods | <a id="p116211"></a>n.a. |  | <a id="p116212"></a>N |  |
| <a id="p116213"></a>Title III | <a id="p116214"></a>III/3 | <a id="p116215"></a>Information enabling the determination of origin | <a id="p116216"></a>n.a. |  | <a id="p116217"></a>N |  |
| <a id="p116218"></a>Title III | <a id="p116219"></a>III/4 | <a id="p116220"></a>Indicate which data should be treated as confidential | <a id="p116221"></a>n.a. |  | <a id="p116222"></a>N |  |
| <a id="p116223"></a>Title III | <a id="p116224"></a>III/5 | <a id="p116225"></a>Country of origin and legal framework | <a id="p116226"></a>n.a. |  | <a id="p116227"></a>N |  |
| <a id="p116228"></a>Title III | <a id="p116229"></a>III/6 | <a id="p116230"></a>Justification of the assessment of the origin | <a id="p116231"></a>n.a. |  | <a id="p116232"></a>N |  |
| <a id="p116233"></a>Title III | <a id="p116234"></a>III/7 | <a id="p116235"></a>Ex-works price | <a id="p116236"></a>n.a. |  | <a id="p116237"></a>N |  |
| <a id="p116238"></a>Title III | <a id="p116239"></a>III/8 | <a id="p116240"></a>Materials used, country of origin, Combined Nomenclature code and value | <a id="p116241"></a>n.a. |  | <a id="p116242"></a>N |  |
| <a id="p116243"></a>Title III | <a id="p116244"></a>III/9 | <a id="p116245"></a>Description of the processing required in order to obtain origin | <a id="p116246"></a>n.a. |  | <a id="p116247"></a>N |  |
| <a id="p116248"></a>Title III | <a id="p116249"></a>III/10 | <a id="p116250"></a>Language | <a id="p116251"></a>a2 |  | <a id="p116252"></a>N | <a id="p116253"></a>ISO alpha 2 codes as specified in ISO - 639-1 of 2002 shall be used for the language. |
| <a id="p116254"></a>Title IV | <a id="p116255"></a>IV/1 | <a id="p116256"></a>Legal status of applicant | <a id="p116257"></a>an..50 | <a id="p116258"></a>1x | <a id="p116259"></a>N |  |
| <a id="p116260"></a>Title IV | <a id="p116261"></a>IV/2 | <a id="p116262"></a>Date of establishment | <a id="p116263"></a>n8 (yyyymmdd) | <a id="p116264"></a>1x | <a id="p116265"></a>N |  |
| <a id="p116266"></a>Title IV | <a id="p116267"></a>IV/3 | <a id="p116268"></a>Role(s) of the applicant in the international supply chain | <a id="p116269"></a>an..3 | <a id="p116270"></a>99x | <a id="p116271"></a>Y |  |
| <a id="p116272"></a>Title IV | <a id="p116273"></a>IV/4 | <a id="p116274"></a>Member States where customs related activities are carried out | <a id="p116275"></a>Country: a2 +<br>Street and number: an..70 +<br>Postcode: an..9 +<br>City: an..35 +<br>Type of facility: an..70 (free text) | <a id="p116276"></a>99x | <a id="p116277"></a>N |  |
| <a id="p116278"></a>Title IV | <a id="p116279"></a>IV/5 | <a id="p116280"></a>Border crossing information | <a id="p116281"></a>an8 | <a id="p116282"></a>99x | <a id="p116283"></a>N | <a id="p116284"></a>The structure of the codes is defined in Title II for D.E. 1/7 Decision taking customs authority. |
| <a id="p116285"></a>Title IV | <a id="p116286"></a>IV/6 | <a id="p116287"></a>Simplifications and facilitations already granted, security and safety certificates issued on the basis of international conventions, of an International Standard of the International Organisation for Standardisation, or of a European Standard of a<br>European Standardisation body or certificates granting a status equivalent to that of an AEO issued in third countries and recognised in an agreement | <a id="p116288"></a>Type of simplification/facilitation an..70 +<br>Certificate identification number: an..35 +<br>Country code: a2 +<br>Customs procedure code: an2 | <a id="p116289"></a>99x | <a id="p116290"></a>N | <a id="p116291"></a>The codes provided for in Annex B concerning D.E. 1/10 Procedure shall be used for the indication of the type of customs procedure. |
| <a id="p116292"></a>Title IV | <a id="p116293"></a>IV/7 | <a id="p116294"></a>Consent for the exchange of the information in the AEO authorisation in order to ensure the proper functioning of systems set out in international agreements/arrangements with third countries related to mutual recognition of the status of authorised economic operator and measures related to security | <a id="p116295"></a>Tick-box: n1 +<br>Transliterated name: an..70 +<br>Transliterated street and number: an..70 +<br>Transliterated postcode: an..9 +<br>Transliterated city: an..35 | <a id="p116296"></a>1x | <a id="p116297"></a>N |  |
| <a id="p116298"></a>Title IV | <a id="p116299"></a>IV/8 | <a id="p116300"></a>Permanent Business Establishment (PBE) | <a id="p116301"></a>Name an..70 +<br>Street and number: an..70 +<br>Country: a2 +<br>Postcode: an..9 +<br>City: an..35 +<br>VAT number: an..17 | <a id="p116302"></a>99x | <a id="p116303"></a>N |  |
| <a id="p116304"></a>Title IV | <a id="p116305"></a>IV/9 | <a id="p116306"></a>Office(s) where customs documentation is kept and accessible | <a id="p116307"></a>Name an..70 +<br>Street and number: an..70 +<br>Country: a2 +<br>Postcode: an..9 +<br>City: an..35 | <a id="p116308"></a>99x | <a id="p116309"></a>N |  |
| <a id="p116310"></a>Title IV | <a id="p116311"></a>IV/10 | <a id="p116312"></a>Place where general logistical activities are conducted | <a id="p116313"></a>Name an..70 +<br>Street and number: an..70 +<br>Country: a2 +<br>Postcode: an..9 +<br>City: an..35 | <a id="p116314"></a>1x | <a id="p116315"></a>N |  |
| <a id="p116316"></a>Title IV | <a id="p116317"></a>IV/11 | <a id="p116318"></a>Business activities | <a id="p116319"></a>an..4 | <a id="p116320"></a>99x | <a id="p116321"></a>N | <a id="p116322"></a>The codes provided for in Regulation (EC) No 1893/2006 of the European Parliament and of the Council <**> shall be used. |
| <a id="p116323"></a>Title V | <a id="p116324"></a>V/1 | <a id="p116325"></a>Subject and nature of the simplification | <a id="p116326"></a>Free text: an..512 | <a id="p116327"></a>1x | <a id="p116328"></a>N |  |
| <a id="p116329"></a>Title VI | <a id="p116330"></a>VI/1 | <a id="p116331"></a>Amount of duty and other charges | <a id="p116332"></a>Currency: a3 +<br>Amount: n..16,2 | <a id="p116333"></a>99x | <a id="p116334"></a>N | <a id="p116335"></a>The ISO-alpha-3 currency codes (ISO 4217) shall be used for the currency. |
| <a id="p116336"></a>Title VI | <a id="p116337"></a>VI/2 | <a id="p116338"></a>Average period between the placing of goods under the procedure and the discharge of the procedure | <a id="p116339"></a>Free text: an..35 | <a id="p116340"></a>99x | <a id="p116341"></a>N |  |
| <a id="p116342"></a>Title VI | <a id="p116343"></a>VI/3 | <a id="p116344"></a>Level of guarantee | <a id="p116345"></a>Level of guarantee code: a2<br>Free text: an..512 | <a id="p116346"></a>99x | <a id="p116347"></a>Y |  |
| <a id="p116348"></a>Title VI | <a id="p116349"></a>VI/4 | <a id="p116350"></a>Form of the guarantee | <a id="p116351"></a>Guarantee form: n..2 +<br>Name an..70 +<br>Street and number: an..70 +<br>Country: a2 +<br>Postcode: an..9 +<br>City: an..35 +<br>Free text: an..512 | <a id="p116352"></a>1x | <a id="p116353"></a>Y |  |
| <a id="p116354"></a>Title VI | <a id="p116355"></a>VI/5 | <a id="p116356"></a>Reference amount | <a id="p116357"></a>Currency: a3 +<br>Amount: n..16,2<br>Free text: an..512 | <a id="p116358"></a>1x | <a id="p116359"></a>N | <a id="p116360"></a>The ISO-alpha-3 currency codes (ISO 4217) shall be used for the currency. |
| <a id="p116361"></a>Title VI | <a id="p116362"></a>VI/6 | <a id="p116363"></a>Time-limit for payment | <a id="p116364"></a>n1 | <a id="p116365"></a>1x | <a id="p116366"></a>Y |  |
| <a id="p116367"></a>Title VII | <a id="p116368"></a>VII/1 | <a id="p116369"></a>Type of deferment of payment | <a id="p116370"></a>n1 | <a id="p116371"></a>1x | <a id="p116372"></a>Y |  |
| <a id="p116373"></a>Title VIII | <a id="p116374"></a>VIII/1 | <a id="p116375"></a>Title for recovery | <a id="p116376"></a>an..35 | <a id="p116377"></a>999x | <a id="p116378"></a>N |  |
| <a id="p116379"></a>Title VIII | <a id="p116380"></a>VIII/2 | <a id="p116381"></a>Customs office where the customs debt was notified | <a id="p116382"></a>an8 | <a id="p116383"></a>1x | <a id="p116384"></a>N | <a id="p116385"></a>The structure of the codes is defined in Title II for D.E. 1/7 Decision taking customs authority. |
| <a id="p116386"></a>Title VIII | <a id="p116387"></a>VIII/3 | <a id="p116388"></a>Customs office responsible for the place where the goods are located | <a id="p116389"></a>an8 | <a id="p116390"></a>1x | <a id="p116391"></a>N | <a id="p116392"></a>The structure of the codes is defined in Title II for D.E. 1/7 Decision taking customs authority. |
| <a id="p116393"></a>Title VIII | <a id="p116394"></a>VIII/4 | <a id="p116395"></a>Comments of the customs office responsible for the place where the goods are located | <a id="p116396"></a>Free text: an..512 | <a id="p116397"></a>1x | <a id="p116398"></a>N |  |
| <a id="p116399"></a>Title VIII | <a id="p116400"></a>VIII/5 | <a id="p116401"></a>Customs procedure (request for prior completion of formalities) | <a id="p116402"></a>Procedure code: an2 +<br>Tick-box: n1 +<br>Decision reference number (Country code: a2 + decision code type: an..4 + Reference number: an..29) | <a id="p116403"></a>1x | <a id="p116404"></a>N | <a id="p116405"></a>The codes provided for in Annex B concerning D.E. 1/10 Procedure shall be used. |
| <a id="p116406"></a>Title VIII | <a id="p116407"></a>VIII/6 | <a id="p116408"></a>Customs value | <a id="p116409"></a>Currency: a3 +<br>Amount: n..16,2 | <a id="p116410"></a>1x | <a id="p116411"></a>N | <a id="p116412"></a>The ISO-alpha-3 currency codes (ISO 4217) shall be used for the currency. |
| <a id="p116413"></a>Title VIII | <a id="p116414"></a>VIII/7 | <a id="p116415"></a>Amount of import or export duty to be repaid or remitted of | <a id="p116416"></a>Currency: a3 +<br>Amount: n..16,2 | <a id="p116417"></a>1x | <a id="p116418"></a>N | <a id="p116419"></a>The ISO-alpha-3 currency codes (ISO 4217) shall be used for the currency. |
| <a id="p116420"></a>Title VIII | <a id="p116421"></a>VIII/8 | <a id="p116422"></a>Type of import or export duty | <a id="p116423"></a>Union codes: a1+n2<br>National codes: n1+an2 | <a id="p116424"></a>99x | <a id="p116425"></a>N | <a id="p116426"></a>The codes provided for in Annex B concerning D.E. 4/3 Calculation of taxes - tax type shall be used. |
| <a id="p116427"></a>Title VIII | <a id="p116428"></a>VIII/9 | <a id="p116429"></a>Legal basis | <a id="p116430"></a>a1 | <a id="p116431"></a>1x | <a id="p116432"></a>Y |  |
| <a id="p116433"></a>Title VIII | <a id="p116434"></a>VIII/10 | <a id="p116435"></a>Use or destination of goods | <a id="p116436"></a>Free text: an..512 | <a id="p116437"></a>1x | <a id="p116438"></a>N |  |
| <a id="p116439"></a>Title VIII | <a id="p116440"></a>VIII/11 | <a id="p116441"></a>Time-limit for completion of formalities | <a id="p116442"></a>n..3 | <a id="p116443"></a>1x | <a id="p116444"></a>N |  |
| <a id="p116445"></a>Title VIII | <a id="p116446"></a>VIII/12 | <a id="p116447"></a>Statement of the decision-taking customs authority | <a id="p116448"></a>Free text: an..512 | <a id="p116449"></a>1x | <a id="p116450"></a>N |  |
| <a id="p116451"></a>Title VIII | <a id="p116452"></a>VIII/13 | <a id="p116453"></a>Description of the grounds for repayment or remission | <a id="p116454"></a>Free text: an..512 | <a id="p116455"></a>1x | <a id="p116456"></a>N |  |
| <a id="p116457"></a>Title VIII | <a id="p116458"></a>VIII/14 | <a id="p116459"></a>Bank and account details | <a id="p116460"></a>Free text: an..512 | <a id="p116461"></a>1x | <a id="p116462"></a>N |  |
| <a id="p116463"></a>Title IX | <a id="p116464"></a>IX/1 | <a id="p116465"></a>Movement of goods | <a id="p116466"></a>Legal base code: an1 +<br>EORI number: an..17 +<br>Country: a2 +<br>Type of location code: a1 +<br>Qualifier of the identification: a1 +<br>Coded:<br>Identification of location: an..35 +<br>Additional identifier: n..3<br>OR<br>Free text description:<br>Name: an..70 +<br>Street and number: an..70 +<br>Country: a2 +<br>Postcode: an..9 +<br>City: an..35 | <a id="p116467"></a>999x | <a id="p116468"></a>Y | <a id="p116469"></a>The structure and the codes defined in Annex B for D.E. 5/23 Location of goods shall be used for the indication of the address of the temporary storage facility. |
| <a id="p116470"></a>Title X | <a id="p116471"></a>X/1 | <a id="p116472"></a>Member State(s) concerned by the regular shipping service | <a id="p116473"></a>Qualifier: n1 +<br>Country code: a2 | <a id="p116474"></a>99x | <a id="p116475"></a>Y | <a id="p116476"></a>The country codes provided for in Commission Regulation (EU) No 1106/2012 <***> shall be used. |
| <a id="p116477"></a>Title X | <a id="p116478"></a>X/2 | <a id="p116479"></a>Name of vessels | <a id="p116480"></a>Name of vessel an..35 +<br>IMO number of vessel: IMO + n7 | <a id="p116481"></a>99x | <a id="p116482"></a>N |  |
| <a id="p116483"></a>Title X | <a id="p116484"></a>X/3 | <a id="p116485"></a>Ports of call | <a id="p116486"></a>an8 | <a id="p116487"></a>99x | <a id="p116488"></a>N | <a id="p116489"></a>The structure of the codes is defined in Title II for D.E. 1/7 Decision taking customs authority. |
| <a id="p116490"></a>Title X | <a id="p116491"></a>X/4 | <a id="p116492"></a>Undertaking | <a id="p116493"></a>Tick-box: n1 | <a id="p116494"></a>1x | <a id="p116495"></a>N |  |
| <a id="p116496"></a>Title XI | <a id="p116497"></a>XI/1 | <a id="p116498"></a>Customs office(s) responsible for the registration of the proof of the customs status of Union goods | <a id="p116499"></a>an8 | <a id="p116500"></a>999x | <a id="p116501"></a>N | <a id="p116502"></a>The structure of the codes is defined in Title II for D.E. 1/7 Decision taking customs authority. |
| <a id="p116503"></a>Title XII | <a id="p116504"></a>XII/1 | <a id="p116505"></a>Time-limit for the submission of a supplementary declaration | <a id="p116506"></a>n..2 | <a id="p116507"></a>1x | <a id="p116508"></a>N |  |
| <a id="p116509"></a>Title XII | <a id="p116510"></a>XII/2 | <a id="p116511"></a>Subcontractor | <a id="p116512"></a>Name: an..70 +<br>Street and number: an..70 +<br>Country: a2 +<br>Postcode: an..9 +<br>City: an..35 | <a id="p116513"></a>1x | <a id="p116514"></a>N |  |
| <a id="p116515"></a>Title XII | <a id="p116516"></a>XII/3 | <a id="p116517"></a>Subcontractor identification | <a id="p116518"></a>an..17 | <a id="p116519"></a>1x | <a id="p116520"></a>N |  |
| <a id="p116521"></a>Title XIII | <a id="p116522"></a>XIII/1 | <a id="p116523"></a>Companies involved in the authorisation in other Member States | <a id="p116524"></a>Name an..70 +<br>Street and number: an..70 +<br>Country: a2 +<br>Postcode: an..9 +<br>City: an..35 | <a id="p116525"></a>999x | <a id="p116526"></a>N |  |
| <a id="p116527"></a>Title XIII | <a id="p116528"></a>XIII/2 | <a id="p116529"></a>Companies involved in the authorisation in other Member States identification | <a id="p116530"></a>an..17 | <a id="p116531"></a>999x | <a id="p116532"></a>N |  |
| <a id="p116533"></a>Title XIII | <a id="p116534"></a>XIII/3 | <a id="p116535"></a>Customs office(s) of presentation | <a id="p116536"></a>an8 | <a id="p116537"></a>999x | <a id="p116538"></a>N | <a id="p116539"></a>The structure of the codes is defined in Title II for D.E. 1/7 Decision taking customs authority. |
| <a id="p116540"></a>Title XIII | <a id="p116541"></a>XIII/4 | <a id="p116542"></a>Identification of the VAT, excise and statistical authorities | <a id="p116543"></a>Name an..70 +<br>Street and number: an..70 +<br>Country: a2 +<br>Postcode: an..9 +<br>City: an..35 | <a id="p116544"></a>999x | <a id="p116545"></a>N |  |
| <a id="p116546"></a>Title XIII | <a id="p116547"></a>XIII/5 | <a id="p116548"></a>Method of VAT payment | <a id="p116549"></a>a1 | <a id="p116550"></a>1x | <a id="p116551"></a>N | <a id="p116552"></a>The codes provided for in Annex B concerning D.E. 4/8 Calculation of taxes - Method of payment shall be used. |
| <a id="p116553"></a>Title XIII | <a id="p116554"></a>XIII/6 | <a id="p116555"></a>Tax representative | <a id="p116556"></a>Name an..70 +<br>Street and number: an..70 +<br>Country: a2 +<br>Postcode: an..9 +<br>City: an..35 | <a id="p116557"></a>99x | <a id="p116558"></a>N |  |
| <a id="p116559"></a>Title XIII | <a id="p116560"></a>XIII/7 | <a id="p116561"></a>Tax representative identification | <a id="p116562"></a>an..17 | <a id="p116563"></a>99x | <a id="p116564"></a>N | <a id="p116565"></a>The VAT number shall be used |
| <a id="p116566"></a>Title XIII | <a id="p116567"></a>XIII/8 | <a id="p116568"></a>Tax representative status code | <a id="p116569"></a>n1 | <a id="p116570"></a>1x (per representative) | <a id="p116571"></a>Y |  |
| <a id="p116572"></a>Title XIII | <a id="p116573"></a>XIII/9 | <a id="p116574"></a>Person responsible for excise formalities | <a id="p116575"></a>Name an..70 +<br>Street and number: an..70 +<br>Country: a2 +<br>Postcode: an..9 +<br>City: an..35 | <a id="p116576"></a>99x | <a id="p116577"></a>N |  |
| <a id="p116578"></a>Title XIII | <a id="p116579"></a>XIII/10 | <a id="p116580"></a>Person responsible for excise formalities identification | <a id="p116581"></a>an..17 | <a id="p116582"></a>99x | <a id="p116583"></a>N |  |
| <a id="p116584"></a>Title XIV | <a id="p116585"></a>XIV/1 | <a id="p116586"></a>Waiver of the presentation notification | <a id="p116587"></a>Tick box: n1 +<br>Free text: an..512 | <a id="p116588"></a>1x | <a id="p116589"></a>N |  |
| <a id="p116590"></a>Title XIV | <a id="p116591"></a>XIV/2 | <a id="p116592"></a>Waiver of pre-departure declaration | <a id="p116593"></a>Free text: an..512 | <a id="p116594"></a>1x | <a id="p116595"></a>N |  |
| <a id="p116596"></a>Title XIV | <a id="p116597"></a>XIV/3 | <a id="p116598"></a>Customs office responsible for the place where the goods are available for controls | <a id="p116599"></a>an8 | <a id="p116600"></a>1x | <a id="p116601"></a>N | <a id="p116602"></a>The structure of the codes is defined in Title II for D.E. 1/7 Decision taking customs authority. |
| <a id="p116603"></a>Title XIV | <a id="p116604"></a>XIV/4 | <a id="p116605"></a>Deadline for submitting the supplementary declaration | <a id="p116606"></a>n..2 | <a id="p116607"></a>1x | <a id="p116608"></a>N |  |
| <a id="p116609"></a>Title XV | <a id="p116610"></a>XV/1 | <a id="p116611"></a>Identification of formalities and controls to be delegated to the economic operator | <a id="p116612"></a>Free text: an..512 | <a id="p116613"></a>1x | <a id="p116614"></a>N |  |
| <a id="p116615"></a>Title XVI | <a id="p116616"></a>XVI/1 | <a id="p116617"></a>Economic activity | <a id="p116618"></a>n1 | <a id="p116619"></a>1x | <a id="p116620"></a>Y |  |
| <a id="p116621"></a>Title XVI | <a id="p116622"></a>XVI/2 | <a id="p116623"></a>Weighing equipment | <a id="p116624"></a>Free text: an..512 | <a id="p116625"></a>1x | <a id="p116626"></a>N |  |
| <a id="p116627"></a>Title XVI | <a id="p116628"></a>XVI/3 | <a id="p116629"></a>Additional guarantees | <a id="p116630"></a>Free text: an..512 | <a id="p116631"></a>1x | <a id="p116632"></a>N |  |
| <a id="p116633"></a>Title XVI | <a id="p116634"></a>XVI/4 | <a id="p116635"></a>Advanced notification to customs authorities | <a id="p116636"></a>Free text: an..512 | <a id="p116637"></a>1x | <a id="p116638"></a>N |  |
| <a id="p116639"></a>Title XVII | <a id="p116640"></a>XVII/1 | <a id="p116641"></a>Prior exportation (IP EX/IM) | <a id="p116642"></a>Tick-box: n1 +<br>Time limit: n..2 | <a id="p116643"></a>1x | <a id="p116644"></a>N |  |
| <a id="p116645"></a>Title XVII | <a id="p116646"></a>XVII/2 | <a id="p116647"></a>Release for free circulation by use of bill of discharge | <a id="p116648"></a>Tick-box: n1 | <a id="p116649"></a>1x | <a id="p116650"></a>N |  |
| <a id="p116651"></a>Title XVIII | <a id="p116652"></a>XVIII/1 | <a id="p116653"></a>Standard exchange system | <a id="p116654"></a>Tick-box: n1 +<br>Type of standard exchange system: n1 +<br>Free text: an..512 | <a id="p116655"></a>1x | <a id="p116656"></a>Y |  |
| <a id="p116657"></a>Title XVIII | <a id="p116658"></a>XVIII/2 | <a id="p116659"></a>Replacement products | <a id="p116660"></a>Commodity code: an..8 +<br>Description: an..512 +<br>Code: n1 | <a id="p116661"></a>999x | <a id="p116662"></a>Y |  |
| <a id="p116663"></a>Title XVIII | <a id="p116664"></a>XVIII/3 | <a id="p116665"></a>Prior import of replacement products | <a id="p116666"></a>Tick-box: n1 +<br>Time limit: n..2 | <a id="p116667"></a>1x | <a id="p116668"></a>N |  |
| <a id="p116669"></a>Title XVIII | <a id="p116670"></a>XVIII/4 | <a id="p116671"></a>Prior import of processed products (OP IM/EX) | <a id="p116672"></a>Tick-box: n1 +<br>Time limit: n..2 | <a id="p116673"></a>1x | <a id="p116674"></a>N |  |
| <a id="p116675"></a>Title XIX | <a id="p116676"></a>XIX/1 | <a id="p116677"></a>Temporary removal | <a id="p116678"></a>Tick-box: n1 +<br>Free text: an..512 | <a id="p116679"></a>1x | <a id="p116680"></a>N |  |
| <a id="p116681"></a>Title XIX | <a id="p116682"></a>XIX/2 | <a id="p116683"></a>Loss rate | <a id="p116684"></a>Free text: an..512 | <a id="p116685"></a>1x | <a id="p116686"></a>N |  |
| <a id="p116687"></a>Title XX | <a id="p116688"></a>XX/1 | <a id="p116689"></a>Identification measures | <a id="p116690"></a>Free text: an..512<br>Decision reference number (Country code: a2 +<br>Decision code type: an..4 +<br>Reference number: an..29) | <a id="p116691"></a>1x | <a id="p116692"></a>N | <a id="p116693"></a>The structure of the authorisations for the use of special seals shall follow the structure defined in Title II in relation with D.E. 1/6 Decision reference number. |
| <a id="p116694"></a>Title XX | <a id="p116695"></a>XX/2 | <a id="p116696"></a>Comprehensive guarantee | <a id="p116697"></a>Tick box: n1 +<br>Decision reference number (Country code: a2 +<br>Decision code type: an..4 +<br>Reference number: an..29) | <a id="p116698"></a>1x | <a id="p116699"></a>N | <a id="p116700"></a>The structure of the authorisations for the provision of a comprehensive guarantee or guarantee waiver shall follow the structure defined in Title II in relation with D.E. 1/6 Decision reference number. |
| <a id="p116701"></a>Title XXI | <a id="p116702"></a>XXI/1 | <a id="p116703"></a>Type of seal | <a id="p116704"></a>Free text: an..512 | <a id="p116705"></a>1x | <a id="p116706"></a>N |  |


<a id="p116707"></a>

---

<a id="p116708"></a><*> Commission Regulation (EU) No 1106/2012 of 27 November 2012 implementing Regulation (EC) No 471/2009 of the European Parliament and of the Council on Community statistics relating to external trade with non-member countries, as regards the update of the nomenclature of countries and territories Text with EEA relevance (OJ L 328, 28.11.2012, p. 7).
<a id="p116709"></a><**> Regulation (EC) No 1893/2006 of the European Parliament and of the Council of 20 December 2006 establishing the statistical classification of economic activities NACE Revision 2 and amending Council Regulation (EEC) No 3037/90 as well as certain EC Regulations on specific statistical domains (OJ L 393, 30.12.2006, p. 1).
<a id="p116710"></a><***> Commission Regulation (EU) No 1106/2012 of 27 November 2012 implementing Regulation (EC) No 471/2009 of the European Parliament and of the Council on Community statistics relating to external trade with non-member countries, as regards the update of the nomenclature of countries and territories Text with EEA relevance (OJ L 328, 28.11.2012, p. 7).

<a id="p116711"></a>**TITLE II. CODES IN RELATION WITH THE COMMON DATA**
**REQUIREMENTS FOR APPLICATIONS AND DECISIONS**

<a id="p116712"></a>**1. INTRODUCTION**

<a id="p116713"></a>This Title contains the codes to be used on applications and decisions.

<a id="p116714"></a>**2. CODES**

<a id="p116715"></a>1/1. Application/Decision code type
<a id="p116716"></a>The following codes shall be used:


| <a id="p116717"></a>Code | <a id="p116718"></a>Application/Decision type | <a id="p116719"></a>Table column heading in Annex A to Delegated Regulation (EU) 2015/2446 |
| --- | --- | --- |
| <a id="p116720"></a>BTI | <a id="p116721"></a>Application or decision relating to Binding Tariff Information | <a id="p116722"></a>1a |
| <a id="p116723"></a>BOI | <a id="p116724"></a>Application or decision relating to Binding Origin Information | <a id="p116725"></a>1b |
| <a id="p116726"></a>AEOC | <a id="p116727"></a>Application or authorisation for the status of Authorised Economic Operator - Customs simplifications | <a id="p116728"></a>2 |
| <a id="p116729"></a>AEOS | <a id="p116730"></a>Application or authorisation for the status of Authorised Economic Operator - Security and safety | <a id="p116731"></a>2 |
| <a id="p116732"></a>AEOF | <a id="p116733"></a>Application or authorisation for the status of Authorised Economic Operator - Customs simplifications/Security and safety | <a id="p116734"></a>2 |
| <a id="p116735"></a>CVA | <a id="p116736"></a>Application or authorisation for the simplification of the determination of amounts being part of the customs value of goods | <a id="p116737"></a>3 |
| <a id="p116738"></a>CGU | <a id="p116739"></a>Application or authorisation for the provision of a comprehensive guarantee, including possible reduction or waiver | <a id="p116740"></a>4a |
| <a id="p116741"></a>DPO | <a id="p116742"></a>Application or authorisation for the deferment of payment | <a id="p116743"></a>4b |
| <a id="p116744"></a>REP | <a id="p116745"></a>Application or decision for the repayment of the amounts of import or export duty | <a id="p116746"></a>4c |
| <a id="p116747"></a>REM | <a id="p116748"></a>Application or decision for the remission of the amounts of import or export duty | <a id="p116749"></a>4c |
| <a id="p116750"></a>TST | <a id="p116751"></a>Application or authorisation for the operation of storage facilities for the temporary storage of goods | <a id="p116752"></a>5 |
| <a id="p116753"></a>RSS | <a id="p116754"></a>Application or authorisation to establish regular shipping services | <a id="p116755"></a>6a |
| <a id="p116756"></a>ACP | <a id="p116757"></a>Application or authorisation for the status of authorised issuer to establish the proof of the customs status of Union goods | <a id="p116758"></a>6b |
| <a id="p116759"></a>SDE | <a id="p116760"></a>Application or authorisation to use simplified declaration | <a id="p116761"></a>7a |
| <a id="p116762"></a>CCL | <a id="p116763"></a>Application or authorisation for centralised clearance | <a id="p116764"></a>7b |
| <a id="p116765"></a>EIR | <a id="p116766"></a>Application or authorisation for making a customs declaration through an entry of data in the declarant's records, including for the export procedure | <a id="p116767"></a>7c |
| <a id="p116768"></a>SAS | <a id="p116769"></a>Application or authorisation for self-assessment | <a id="p116770"></a>7d |
| <a id="p116771"></a>AWB | <a id="p116772"></a>Application or authorisation for the status of authorised weigher of bananas | <a id="p116773"></a>7e |
| <a id="p116774"></a>IPO | <a id="p116775"></a>Application or authorisation for the use of inward processing procedure | <a id="p116776"></a>8a |
| <a id="p116777"></a>OPO | <a id="p116778"></a>Application or authorisation for the use of outward processing procedure | <a id="p116779"></a>8b |
| <a id="p116780"></a>EUS | <a id="p116781"></a>Application or authorisation for the use of end use | <a id="p116782"></a>8c |
| <a id="p116783"></a>TEA | <a id="p116784"></a>Application or authorisation for the use of temporary admission | <a id="p116785"></a>8d |
| <a id="p116786"></a>CWP | <a id="p116787"></a>Application or authorisation for the operation of storage facilities for the customs warehousing of goods in a private customs warehouse | <a id="p116788"></a>8e |
| <a id="p116789"></a>CW1 | <a id="p116790"></a>Application or authorisation for the operation of storage facilities for the customs warehousing of goods in a public customs warehouse type I | <a id="p116791"></a>8e |
| <a id="p116792"></a>CW2 | <a id="p116793"></a>Application or authorisation for the operation of storage facilities for the customs warehousing of goods in a public customs warehouse type II | <a id="p116794"></a>8e |
| <a id="p116795"></a>ACT | <a id="p116796"></a>Application or authorisation for the status of authorised consignee for TIR procedure | <a id="p116797"></a>9a |
| <a id="p116798"></a>ACR | <a id="p116799"></a>Application or authorisation for the status of authorised consignor for Union transit | <a id="p116800"></a>9b |
| <a id="p116801"></a>ACE | <a id="p116802"></a>Application or authorisation for the status of authorised consignee for Union transit | <a id="p116803"></a>9c |
| <a id="p116804"></a>SSE | <a id="p116805"></a>Application or authorisation for the use of seals of a special type | <a id="p116806"></a>9d |
| <a id="p116807"></a>TRD | <a id="p116808"></a>Application or authorisation to use transit declaration with a reduced dataset | <a id="p116809"></a>9e |
| <a id="p116810"></a>ETD | <a id="p116811"></a>Authorisation for the use of an electronic transport document as customs declaration | <a id="p116812"></a>9f |


<a id="p116813"></a>1/3. Type of application
<a id="p116814"></a>The following codes shall be used:
<a id="p116815"></a>1 first application
<a id="p116816"></a>2 application for amendment of the decision
<a id="p116817"></a>3 application for renewal of the authorisation
<a id="p116818"></a>4 application for revocation of the decision

<a id="p116819"></a>1/4 Geographical validity - Union
<a id="p116820"></a>The following codes shall be used:
<a id="p116821"></a>1 application or authorisation valid in all Member States
<a id="p116822"></a>2 application or authorisation limited to certain Member States
<a id="p116823"></a>3 application or authorisation limited to one Member State

<a id="p116824"></a>1/6. Decision reference number
<a id="p116825"></a>The decision reference number is structured as follows:


| <a id="p116826"></a>Field | <a id="p116827"></a>Content | <a id="p116828"></a>Format | <a id="p116829"></a>Examples |
| --- | --- | --- | --- |
| <a id="p116830"></a>1 | <a id="p116831"></a>Identifier of the Member State where the decision is taken (alpha 2 country code) | <a id="p116832"></a>a2 | <a id="p116833"></a>PT |
| <a id="p116834"></a>2 | <a id="p116835"></a>Decision code type | <a id="p116836"></a>an..4 | <a id="p116837"></a>SSE |
| <a id="p116838"></a>3 | <a id="p116839"></a>Unique identifier for the decision per country | <a id="p116840"></a>an..29 | <a id="p116841"></a>1234XYZ123456789098765432-10AB |


<a id="p116842"></a>Field 1 as explained above.
<a id="p116843"></a>Field 2 shall be filled in with the code of the decision as defined for D.E. 1/1 Decision code type in this Title.
<a id="p116844"></a>Field 3 shall be filled in with an identifier for the decision concerned. The way that field is used is under the responsibility of national administrations but each decision taken within the given country must have a unique number in relation to the decision type concerned.

<a id="p116845"></a>1/7. Decision taking customs authority
<a id="p116846"></a>The structure of the codes is the following:
- <a id="p116847"></a>the first two characters (a2) serve to identify the country by means of the country code as defined in Commission Regulation (EU) No 1106/2012,
- <a id="p116848"></a>the next six characters (an6) stand for the office concerned in that country. It is suggested that the following structure be adopted:
<a id="p116849"></a>The first three characters (an3) would be taken up by the UN/LOCODE <*> location name and the last three by a national alphanumeric subdivision (an3). If this subdivision is not used, the characters "000" should be inserted.

<a id="p116850"></a>

---

<a id="p116851"></a><*> Recommendation 16 on UN/LOCODE - CODE FOR PORTS AND OTHER LOCATIONS.

<a id="p116852"></a>Example: BEBRU000: BE = ISO 3166 for Belgium, BRU = UN/LOCODE location name for the city of Brussels, 000 for the unused subdivision.

<a id="p116853"></a>5/8. Identification of goods
<a id="p116854"></a>Codes to be used for the identification of goods are the following:
<a id="p116855"></a>1 serial or manufacturer's number
<a id="p116856"></a>2 affixing of plumbs, seals, clip-marks or other distinctive marks
<a id="p116857"></a>4 taking of samples, illustrations or technical descriptions
<a id="p116858"></a>5 carrying out of analyses
<a id="p116859"></a>6 information document to facilitate the temporary exportation of goods sent from one country for manufacture, processing or repair in another (only suitable for outward processing)
<a id="p116860"></a>7 other means of identification (provide an explanation on the means of identification to be used)
<a id="p116861"></a>8 without identification measures according to Article 250(2)(b) of the Code (only suitable for temporary admission)

<a id="p116862"></a>6/2. Economic conditions
<a id="p116863"></a>Codes to be used for the cases in which the economic conditions are deemed to be fulfilled for inward processing:
<a id="p116864"></a>Code 1 the processing of goods not listed in Annex 71-02 to Delegated Regulation (EU) 2015/2446,
<a id="p116865"></a>Code 2 repair,
<a id="p116866"></a>Code 3 processing of goods directly or indirectly put at the disposal of the holder of the authorisation, carried out according to specifications on behalf of a person established outside of the customs territory of the Union, generally against payment of processing costs alone,
<a id="p116867"></a>Code 4 the processing of durum wheat into pasta,
<a id="p116868"></a>Code 5 the placing of goods under inward processing within the limits of the quantity determined on the basis of a balance in accordance with Article 18 of <*>,

<a id="p116869"></a>

---

<a id="p116870"></a><*> Regulation (EU) No 510/2014 of the European Parliament and of the Council of 16 April 2014 laying down the trade arrangements applicable to certain goods resulting from the processing of agricultural products and repealing Council Regulations (EC) No 1216/2009 and (EC) No 614/2009 (OJ L 150, 20.5.2014, p. 1).

<a id="p116871"></a>Code 6 the processing of goods which are listed in Annex 71-02 to Delegated Regulation (EU) 2015/2446, in case of unavailability of goods produced in the Union sharing the same 8-digit Combined Nomenclature code, the same commercial quality and technical characteristics as the goods intended to be imported for the processing operations envisaged,
<a id="p116872"></a>Code 7 the processing of goods which are listed in Annex 71-02 to Delegated Regulation (EU) 2015/2446, provided there are differences in price between goods produced in the Union and those intended to be imported, where comparable goods cannot be used because their price would not make the proposed commercial operation economically viable,
<a id="p116873"></a>Code 8 the processing of goods which are listed in Annex 71-02 to Delegated Regulation (EU) 2015/2446, provided there are contractual obligations, where comparable goods do not conform to the contractual requirements of the third-country purchaser of the processed products, or where, in accordance with the contract, the processed products must be obtained from the goods intended to be placed under inward processing in order to comply with provisions concerning the protection of industrial or commercial property rights,
<a id="p116874"></a>Code 9 the processing of goods which are listed in Annex 71-02 to Delegated Regulation (EU) 2015/2446, provided the aggregate value of the goods to be placed under the inward processing procedure per applicant and calendar year for each eight-digit Combined Nomenclature code does not exceed EUR 150 000,
<a id="p116875"></a>Code 10 the processing of goods to ensure their compliance with technical requirements for their release for free circulation,
<a id="p116876"></a>Code 11 the processing of goods of a non-commercial nature,
<a id="p116877"></a>Code 12 the processing of goods obtained under a previous authorisation, the issuing of which was subject to an examination of the economic conditions,
<a id="p116878"></a>Code 13 the processing of solid and fluid fractions of palm oil, coconut oil, fluid fractions of coconut oil, palm kernel oil, fluid fractions of palm kernel oil, babassu oil or castor oil into products which are not destined for the food sector,
<a id="p116879"></a>Code 14 the processing into products to be incorporated in or used for aircraft for which an authorised release certificate EASA Form 1 or an equivalent certificate has been issued,
<a id="p116880"></a>Code 15 the processing into products benefitting from the autonomous suspension of import duty on certain weapons and military equipment in accordance with Council Regulation (EC) No 150/2003 <*>,

<a id="p116881"></a>

---

<a id="p116882"></a><*> Council Regulation (EC) No 150/2003 of 21 January 2003 suspending import duties on certain weapons and military equipment (OJ L 25, 30.1.2003, p. 1).

<a id="p116883"></a>Code 16 the processing of goods into samples,
<a id="p116884"></a>Code 17 the processing of any electronic type of components, parts, assemblies or any other materials into information technology products,
<a id="p116885"></a>Code 18 the processing of goods falling within Combined Nomenclature codes 2707 or 2710 into products falling within Combined Nomenclature codes 2707, 2710 or 2902,
<a id="p116886"></a>Code 19 the reduction to waste and scrap, destruction, recovery of parts or components,
<a id="p116887"></a>Code 20 denaturing,
<a id="p116888"></a>Code 21 usual forms of handling referred to in Article 220 of the Code,
<a id="p116889"></a>Code 22 the aggregate value of goods to be placed under the inward processing procedure per applicant and calendar year for each eight-digit Combined Nomenclature code does not exceed EUR 150 000 with regard to goods which are covered by Annex 71-02 to Delegated Regulation (EU) 2015/2446 and EUR 300 000 for other goods, except where the goods intended to be placed under the inward-processing procedure would be subject to a provisional or definitive anti-dumping duty, a countervailing duty, a safeguard measure or an additional duty resulting from a suspension of concessions if they were declared for release for free circulation.

<a id="p116890"></a>7/3. Type of declaration
<a id="p116891"></a>The following codes shall be used for the declaration types:
<a id="p116892"></a>1 Standard declaration (in accordance with Article 162 of the Code)
<a id="p116893"></a>2 Simplified declaration (in accordance with Article 166 of the Code)
<a id="p116894"></a>3 Entry in the declarant's records (in accordance with Article 182 of the Code)

<a id="p116895"></a>8/6. Guarantee
<a id="p116896"></a>The following codes shall be used:
<a id="p116897"></a>0 Guarantee not required
<a id="p116898"></a>1 Guarantee required

<a id="p116899"></a>II/9. Invalidation reason
<a id="p116900"></a>Enter one of the following codes:
<a id="p116901"></a>55 Annulled
<a id="p116902"></a>61 Invalidated due to customs nomenclature code changes
<a id="p116903"></a>62 Invalidated due to a Union measure
<a id="p116904"></a>63 Invalidated due to national legal measure
<a id="p116905"></a>64 Revocation due to incorrect classification
<a id="p116906"></a>65 Revocation for reasons other than classification
<a id="p116907"></a>66 Invalidated due to limited validity of nomenclature code at the time of issue

<a id="p116908"></a>IV/3. Role(s) of the applicant in the international supply chain
<a id="p116909"></a>The following codes shall be used:


| <a id="p116910"></a>Code | <a id="p116911"></a>Role | <a id="p116912"></a>Description |
| --- | --- | --- |
| <a id="p116913"></a>MF | <a id="p116914"></a>Manufacturer of goods | <a id="p116915"></a>Party who manufactures goods.<br>This code should be used only if the economic operator manufacturers the goods. It does not cover cases where the economic operator is only involved in trading with the goods (e.g. exporting, importing). |
| <a id="p116916"></a>IM | <a id="p116917"></a>Importer | <a id="p116918"></a>Party who makes, or on whose behalf a Customs clearing agent or other authorised person makes an import declaration. This may include a person who has possession of the goods or to whom the goods are consigned. |
| <a id="p116919"></a>EX | <a id="p116920"></a>Exporter | <a id="p116921"></a>Party who makes, or on whose behalf the export declaration is made, and who is the owner of the goods or has similar rights of disposal over them at the time when the declaration is accepted. |
| <a id="p116922"></a>CB | <a id="p116923"></a>Customs broker | <a id="p116924"></a>Agent or representative or a professional Customs clearing agent who deals directly with Customs on behalf of the importer or exporter.<br>The code can be used also for economic operators who acts as agents/representatives also for other purposes (e.g. carrier's agent). |
| <a id="p116925"></a>CA | <a id="p116926"></a>Carrier | <a id="p116927"></a>Party undertaking or arranging transport of goods between named points. |
| <a id="p116928"></a>FW | <a id="p116929"></a>Freight forwarder | <a id="p116930"></a>Party arranging forwarding of goods. |
| <a id="p116931"></a>CS | <a id="p116932"></a>Consolidator | <a id="p116933"></a>Party consolidating various consignments, payments etc. |
| <a id="p116934"></a>TR | <a id="p116935"></a>Terminal operator | <a id="p116936"></a>A party which handles the loading and unloading of marine vessels. |
| <a id="p116937"></a>WH | <a id="p116938"></a>Warehouse keeper | <a id="p116939"></a>Party taking responsibility for goods entered into a warehouse.<br>This code should be used also by economic operators who operate other type of storage facilities (e.g. temporary storage, free zone, etc.). |
| <a id="p116940"></a>CF | <a id="p116941"></a>Container operator | <a id="p116942"></a>Party to whom the possession of specified property (e.g. container) has been conveyed for a period of time in return for rental payments. |
| <a id="p116943"></a>DEP | <a id="p116944"></a>Stevedore | <a id="p116945"></a>A party which handles the loading and unloading of marine vessels from several terminals. |
| <a id="p116946"></a>HR | <a id="p116947"></a>Shipping line service | <a id="p116948"></a>Identifies the shipping line service organisation. |
| <a id="p116949"></a>999 | <a id="p116950"></a>Others |  |


<a id="p116951"></a>VI/3. Level of guarantee
<a id="p116952"></a>The following codes shall be used for the level of the guarantee:
<a id="p116953"></a>To cover existing customs debts and, where applicable, other charges:
<a id="p116954"></a>AA 100% of the relevant part of the reference amount
<a id="p116955"></a>AB 30% of the relevant part of the reference amount
<a id="p116956"></a>To cover potential customs debts and, where applicable, other charges:
<a id="p116957"></a>BA 100% of the relevant part of the reference amount
<a id="p116958"></a>BB 50% of the relevant part of the reference amount
<a id="p116959"></a>BC 30% of the relevant part of the reference amount
<a id="p116960"></a>BD 0% of the relevant part of the reference amount

<a id="p116961"></a>VI/4. Form of the guarantee
<a id="p116962"></a>The following codes shall be used for the form of the guarantee:
<a id="p116963"></a>1 Cash deposit
<a id="p116964"></a>2 Undertaking given by a guarantor
<a id="p116965"></a>3* Other forms as specified in Article 83 of Delegated Regulation (EU) 2015/2446
<a id="p116966"></a>31 the creation of a mortgage, a charge on land, an antichresis or other right deemed equivalent to a right pertaining to immovable property;
<a id="p116967"></a>32 the cession of a claim, the pledging, with or without surrendering possession, of goods, securities or claims or a savings bank book or entry in the national debt register;
<a id="p116968"></a>33 the assumption of joint contractual liability for the full amount of the debt by a third party approved for that purpose by the customs authorities or the lodging of a bill of exchange the payment of which is guaranteed by such third party;
<a id="p116969"></a>34 a cash deposit or means of payment deemed equivalent thereto other than in euro or the currency of the Member State in which the guarantee is required;
<a id="p116970"></a>35 participation, subject to payment of a contribution, in a general guarantee scheme administered by the customs authorities.

<a id="p116971"></a>VI/6. Time-limit for payment
<a id="p116972"></a>The following codes shall be used for the time limit:
<a id="p116973"></a>1 Normal period before payment, i.e. maximum 10 days following the notification to the debtor of the customs debt in accordance with Article 108 of the Code
<a id="p116974"></a>2 Deferred payment (Article 110 of the Code)

<a id="p116975"></a>VII/1. Type of deferment of payment
<a id="p116976"></a>The following codes shall be used for the deferment of payment:
<a id="p116977"></a>1 Article 110(b) of the Code, i.e. globally in respect of each amount of import or export duty entered in the accounts in accordance with the first subparagraph of Article 105(1) during a fixed period that does not exceed 31 days
<a id="p116978"></a>2 Article 110(c) of the Code, i.e. globally in respect of all amounts of import or export duty forming a single entry in accordance with the second subparagraph of Article 105(1)

<a id="p116979"></a>VIII/9. Legal basis
<a id="p116980"></a>The following codes shall be used as legal basis:


| <a id="p116981"></a>Code | <a id="p116982"></a>Description | <a id="p116983"></a>Legal basis |
| --- | --- | --- |
| <a id="p116984"></a>A | <a id="p116985"></a>Overcharged amounts of import or export duty | <a id="p116986"></a>Article 117 of the Code |
| <a id="p116987"></a>B | <a id="p116988"></a>Defective goods or goods not complying with the terms of the contract | <a id="p116989"></a>Article 118 of the Code |
| <a id="p116990"></a>C | <a id="p116991"></a>Error by the competent authorities | <a id="p116992"></a>Article 119 of the Code |
| <a id="p116993"></a>D | <a id="p116994"></a>Equity | <a id="p116995"></a>Article 120 of the Code |
| <a id="p116996"></a>E | <a id="p116997"></a>Amount of import or export duty paid in relation with a customs declaration invalidated in accordance with Article 174 of the Code | <a id="p116998"></a>Article 116(1) of the Code |


<a id="p116999"></a>IX/1. Movement of goods
<a id="p117000"></a>The following codes shall be used for the legal basis of the movement:
<a id="p117001"></a>For goods under temporary storage:
<a id="p117002"></a>A Article 148(5)(a) of the Code
<a id="p117003"></a>B Article 148(5)(b) of the Code
<a id="p117004"></a>C Article 148(5)(c) of the Code

<a id="p117005"></a>X/1. Member State(s) concerned by the regular shipping service
<a id="p117006"></a>The following codes shall be used as qualifier:
<a id="p117007"></a>0 involved Member States;
<a id="p117008"></a>1 potentially involved Member States.

<a id="p117009"></a>XIII/8. Tax representative status code
<a id="p117010"></a>The following codes shall be used:
<a id="p117011"></a>1 the applicant is acting in his own name and on his own behalf;
<a id="p117012"></a>2 a tax representative is acting on behalf of the applicant.

<a id="p117013"></a>XVI/1. Economic activity
<a id="p117014"></a>The following codes shall be used for the activity:
<a id="p117015"></a>1 Importation
<a id="p117016"></a>2 Carriage
<a id="p117017"></a>3 Storage
<a id="p117018"></a>4 Handling

<a id="p117019"></a>XVIII/1. Standard exchange system
<a id="p117020"></a>The following codes shall be used:
<a id="p117021"></a>1 Standard exchange system without prior importation of replacement products
<a id="p117022"></a>2 Standard exchange system with prior importation of replacement products

<a id="p117023"></a>XVIII/2. Replacement products
<a id="p117024"></a>The following codes shall be used:
<a id="p117025"></a>4 Taking of samples, illustrations or technical descriptions
<a id="p117026"></a>5 Carrying out of analyses
<a id="p117027"></a>7 Other means of identification


<a id="p117028"></a>Annex B

<a id="p117029"></a>**FORMATS AND CODES OF THE COMMON DATA REQUIREMENTS FOR**
**DECLARATIONS, NOTIFICATIONS AND PROOF OF THE CUSTOMS STATUS**
**OF UNION GOODS (ARTICLE 2(2))**

<a id="p117030"></a>**INTRODUCTORY NOTES**

<a id="p117031"></a>(1) The formats, codes and, if applicable, the structure of the data elements included in this Annex are applicable in relation with the data requirements for declarations, notifications and proof of the customs status of Union goods as provided for in Annex B to Delegated Regulation (EU) 2015/2446.
<a id="p117032"></a>(2) The formats, codes and, if applicable, the structure of the data elements defined in this Annex shall apply to declarations, notifications and proof of the customs status of Union goods made by using an electronic data processing technique.
<a id="p117033"></a>(3) The cardinality at the level of the declaration header (D) included in the table in Title I of this Annex indicates how many times the data element may be used at the level of the declaration header within a declaration, notification or proof of the customs status of Union goods.
<a id="p117034"></a>(4) The cardinality at Master Consignment level (MC) included in the table in Title I of this Annex indicates how many times the data element may be used at the Master Consignment level.
<a id="p117035"></a>(5) The cardinality at Master Consignment Goods Item level (MI) included in the table in Title I of this Annex indicates how many times the data element may be used at the Master Consignment Goods Item level.
<a id="p117036"></a>(6) The cardinality at House Consignment level (HC) included in the table in Title I of this Annex indicates how many times the data element may be used at the House Consignment level.
<a id="p117037"></a>(7) The cardinality at House Consignment Goods Item level (HI) included in the table in Title I of this Annex indicates how many times the data element may be used at House Consignment Goods Item level.
<a id="p117038"></a>(8) The cardinality at Goods Shipment level (GS) included in the table in Title I of this Annex indicates how many times the data element may be used at Goods Shipment level.
<a id="p117039"></a>(9) The cardinality at Government Agency Goods Item level (SI) included in the table in Title I of this Annex indicates how many times the data element may be used at Government Agency Item level.
<a id="p117040"></a>(10) Whenever the information in a declaration, notification or proof of the customs status of Union goods dealt with in Annex B to Delegated Regulation (EU) 2015/2446 takes the form of codes, the code-list provided for in Title II or national codes, where foreseen, shall be applied.
<a id="p117041"></a>(11) National codes can be used by Member States for data elements 11 10 000 000 Additional procedure, 12 01 000 000 Previous document (sub-element 12 01 005 000 Measurement unit and qualifier), 12 02 000 000 Additional information (sub-element 12 02 008 000 Code), 12 03 000 000 Supporting document (sub-elements 12 03 002 000 Type and 12 03 005 000), 12 04 000 000 Additional reference (sub-element 12 04 002 000 Type), 14 03 000 000 Duties and taxes (sub-element 14 03 039 000 Tax type and sub-element 14 03 040 005 Measurement unit and qualifier), 18 09 000 000 Commodity code (sub-element 18 09 060 000 National additional code), 16 04 000 000 Region of destination and 16 10 000 000 Region of dispatch. Member States shall notify the Commission of the list of national codes used for these data elements. The Commission shall publish the list of those codes.
<a id="p117042"></a>(12) The term "type/length" in the explanation of an attribute indicates the requirements for the data type and the data length. The codes for the data types are as follows:


| <a id="p117043"></a>a | <a id="p117044"></a>alphabetic |
| --- | --- |
| <a id="p117045"></a>n | <a id="p117046"></a>numeric |
| <a id="p117047"></a>an | <a id="p117048"></a>alphanumeric |


<a id="p117049"></a>The number following the code indicates the admissible data length.
<a id="p117050"></a>The following applies:
<a id="p117051"></a>The optional two dots before the length indicator mean that the data has no fixed length, but it can have up to a number of digits, as specified by the length indicator. A comma in the data length means that the attribute can hold decimals, the digit before the comma indicates the total length of the attribute, the digit after the comma indicates the maximum number of digits after the decimal point.
<a id="p117052"></a>Examples of field lengths and formats:

| <a id="p117053"></a>a1 | <a id="p117054"></a>1 alphabetic character, fixed length |
| --- | --- |
| <a id="p117055"></a>n2 | <a id="p117056"></a>2 numeric characters, fixed length |
| <a id="p117057"></a>an3 | <a id="p117058"></a>3 alphanumeric, fixed length |
| <a id="p117059"></a>a..4 | <a id="p117060"></a>up to 4 alphabetic characters |
| <a id="p117061"></a>n..5 | <a id="p117062"></a>up to 5 numeric characters |
| <a id="p117063"></a>an..6 | <a id="p117064"></a>up to 6 alphanumeric characters |
| <a id="p117065"></a>n..7,2 | <a id="p117066"></a>up to 7 numeric characters including maximum 2 decimals, a delimiter being allowed to float |


<a id="p117067"></a>(13) The following references to codelists defined in international standards or in EU-legal acts are used:


|  | <a id="p117068"></a>Short name | <a id="p117069"></a>Source | <a id="p117070"></a>Definition |
| --- | --- | --- | --- |
| <a id="p117071"></a>1. | <a id="p117072"></a>Package Type Code | <a id="p117073"></a>UN/ECE Recommendation 21 | <a id="p117074"></a>Package Type Code as defined in the latest version of Annex IV to UN/ECE Recommendation 21 |
| <a id="p117075"></a>2. | <a id="p117076"></a>Currency Code | <a id="p117077"></a>ISO 4217 | <a id="p117078"></a>Three-letter alphabetic code defined by International Standard ISO 4217 |
| <a id="p117079"></a>3. | <a id="p117080"></a>GEONOM Code | <a id="p117081"></a>Commission Regulation (EU) No | <a id="p117082"></a>The Union's alphabetic codes for countries and territories are based on the current ISO alpha 2 codes (a2) in so far as they are compatible with the requirements of Commission Implementing Regulation (EU) 2020/1470 of 12 October 2020 on the nomenclature of countries and territories for the European statistics on international trade in goods and on the geographical breakdown for other business statistics (OJ L 334, 13.10.2020, p. 2 - 21).<br>In the context of transit operations, the ISO 3166- alpha-2 country code shall be used and the code "XI" shall be used for Northern Ireland. |
| <a id="p117083"></a>4. | <a id="p117084"></a>UN/LOCODE | <a id="p117085"></a>UNECE Recommendation No. 16 | <a id="p117086"></a>UN/LOCODE as defined in UNECE Recommendation No. 16 |
| <a id="p117087"></a>5. | <a id="p117088"></a>UN Number | <a id="p117089"></a>ADR agreement | <a id="p117090"></a>UN Number as set out in Annex A, Part 3, Table A (Dangerous Goods List) to the European Agreement Concerning the International Carriage of Dangerous Goods by Road |
| <a id="p117091"></a>6. | <a id="p117092"></a>Code for Types of Means of Transport | <a id="p117093"></a>UNECE Recommendation No. 28 | <a id="p117094"></a>Code for types of means of transport as defined in UNECE Recommendation No. 28 |
| <a id="p117095"></a>7. | <a id="p117096"></a>Code for nature of transaction | <a id="p117097"></a>Commission Regulation (EU) No. 113/2010 | <a id="p117098"></a>Code for nature of transaction as defined in Annex II to Commission Regulation (EU) No. 113/2010 |
| <a id="p117099"></a>8. | <a id="p117100"></a>UPU item nature indication codes | <a id="p117101"></a>UPU code-list 136 | <a id="p117102"></a>UPU (Universal Postal Union) item nature indication codes as specified in UPU code list 136 |
| <a id="p117103"></a>9. | <a id="p117104"></a>CUS codes | <a id="p117105"></a>ECICS (European Customs Inventory of Chemical Substances) | <a id="p117106"></a>Customs Union and Statistics (CUS) number assigned within the European Customs Inventory of Chemical Substances (ECICS) to mainly chemical substances and preparations. |


<a id="p117107"></a>**TITLE I. FORMATS AND CARDINALITY OF THE COMMON DATA**
**REQUIREMENTS FOR DECLARATIONS AND NOTIFICATIONS**

<a id="p117108"></a>**CHAPTER 1**

<a id="p117109"></a>**FORMATS**


<table>
<colgroup><col width="13%"><col width="14%"><col width="14%"><col width="11%"><col width="10%"><col width="13%"><col width="24%"></colgroup>
<tr><td><a id="p117110"></a>Data element/class Data sub-element/sub-class Data sub-element number</td><td><a id="p117111"></a>Data element/class name</td><td><a id="p117112"></a>Data sub-element/sub-class name</td><td><a id="p117113"></a>Data subelement name</td><td><a id="p117114"></a>Format</td><td><a id="p117115"></a>Code-list in Title II (Y/N)</td><td><a id="p117116"></a>Notes</td></tr>
<tr><td><a id="p117117"></a>11 01 000 000</td><td><a id="p117118"></a>Declaration type</td><td></td><td></td><td><a id="p117119"></a>an..5</td><td><a id="p117120"></a>Y</td><td></td></tr>
<tr><td><a id="p117121"></a>11 02 000 000</td><td><a id="p117122"></a>Additional declaration type</td><td></td><td></td><td><a id="p117123"></a>a1</td><td><a id="p117124"></a>Y</td><td></td></tr>
<tr><td><a id="p117125"></a>11 03 000 000</td><td><a id="p117126"></a>Goods item number</td><td></td><td></td><td><a id="p117127"></a>n..5</td><td><a id="p117128"></a>N</td><td></td></tr>
<tr><td><a id="p117129"></a>11 04 00 0000</td><td><a id="p117130"></a>Specific circumstance indicator</td><td></td><td></td><td><a id="p117131"></a>an3</td><td><a id="p117132"></a>Y</td><td></td></tr>
<tr><td><a id="p117133"></a>11 05 000 000</td><td><a id="p117134"></a>Re-entry indicator</td><td></td><td></td><td><a id="p117135"></a>n1</td><td><a id="p117136"></a>Y</td><td></td></tr>
<tr><td><a id="p117137"></a>11 06 000 000</td><td><a id="p117138"></a>Split Consignment</td><td></td><td></td><td></td><td><a id="p117139"></a>N</td><td></td></tr>
<tr><td><a id="p117140"></a>11 06 001 000</td><td></td><td><a id="p117141"></a>Split consignment indicator</td><td></td><td><a id="p117142"></a>n1</td><td><a id="p117143"></a>Y</td><td></td></tr>
<tr><td><a id="p117144"></a>11 06 002 000</td><td></td><td><a id="p117145"></a>Previous MRN</td><td></td><td><a id="p117146"></a>an18</td><td><a id="p117147"></a>N</td><td></td></tr>
<tr><td><a id="p117148"></a>11 07 000 000</td><td><a id="p117149"></a>Security</td><td></td><td></td><td><a id="p117150"></a>n1</td><td><a id="p117151"></a>Y</td><td></td></tr>
<tr><td><a id="p117152"></a>11 08 000 000</td><td><a id="p117153"></a>Reduced dataset indicator</td><td></td><td></td><td><a id="p117154"></a>n1</td><td><a id="p117155"></a>Y</td><td></td></tr>
<tr><td><a id="p117156"></a>11 09 000 000</td><td><a id="p117157"></a>Procedure</td><td></td><td></td><td></td><td><a id="p117158"></a>N</td><td></td></tr>
<tr><td><a id="p117159"></a>11 09 001 000</td><td></td><td><a id="p117160"></a>Requested procedure</td><td></td><td><a id="p117161"></a>an2</td><td><a id="p117162"></a>Y</td><td></td></tr>
<tr><td><a id="p117163"></a>11 09 002 000</td><td></td><td><a id="p117164"></a>Previous procedure</td><td></td><td><a id="p117165"></a>an2</td><td><a id="p117166"></a>Y</td><td></td></tr>
<tr><td><a id="p117167"></a>11 10 000 000</td><td><a id="p117168"></a>Additional procedure</td><td></td><td></td><td><a id="p117169"></a>an3</td><td><a id="p117170"></a>Y</td><td><a id="p117171"></a>The Union codes are further specified in Title II.<br>Member States may define national codes. National codes must have the format n1an2.</td></tr>
<tr><td><a id="p117172"></a>12 01 000 000</td><td><a id="p117173"></a>Previous document</td><td></td><td></td><td></td><td><a id="p117174"></a>N</td><td></td></tr>
<tr><td><a id="p117175"></a>12 01 001 000</td><td></td><td><a id="p117176"></a>Reference number</td><td></td><td><a id="p117177"></a>an..70</td><td><a id="p117178"></a>N</td><td></td></tr>
<tr><td><a id="p117179"></a>12 01 002 000</td><td></td><td><a id="p117180"></a>Type</td><td></td><td><a id="p117181"></a>an4</td><td><a id="p117182"></a>N</td><td><a id="p117183"></a>The codes can be found in the TARIC database.</td></tr>
<tr><td><a id="p117184"></a>12 01 003 000</td><td></td><td><a id="p117185"></a>Type of packages</td><td></td><td><a id="p117186"></a>an..2</td><td><a id="p117187"></a>N</td><td><a id="p117188"></a>Package type code as referred to in introductory note 13 number 1.</td></tr>
<tr><td><a id="p117189"></a>12 01 004 000</td><td></td><td><a id="p117190"></a>Number of packages</td><td></td><td><a id="p117191"></a>n..8</td><td><a id="p117192"></a>N</td><td></td></tr>
<tr><td><a id="p117193"></a>12 01 005 000</td><td></td><td><a id="p117194"></a>Measurement unit and qualifier</td><td></td><td><a id="p117195"></a>an..4</td><td><a id="p117196"></a>N</td><td><a id="p117197"></a>The measurement units and qualifiers defined in TARIC shall be used. In such case, the format of the measurement units and qualifiers shall be an..4, but shall never be n..4 formats, reserved for national measurement units and qualifiers.<br>If no such measurement units and qualifiers are available in TARIC, national measurement units and qualifiers may be used. Their format shall be n..4.</td></tr>
<tr><td><a id="p117198"></a>12 01 006 000</td><td></td><td><a id="p117199"></a>Quantity</td><td></td><td><a id="p117200"></a>n..16,6</td><td><a id="p117201"></a>N</td><td></td></tr>
<tr><td><a id="p117202"></a>12 01 079 000</td><td></td><td><a id="p117203"></a>Complement of information</td><td></td><td><a id="p117204"></a>an..35</td><td><a id="p117205"></a>N</td><td></td></tr>
<tr><td><a id="p117206"></a>12 01 007 000</td><td></td><td><a id="p117207"></a>Goods item identifier</td><td></td><td><a id="p117208"></a>n..5</td><td><a id="p117209"></a>N</td><td></td></tr>
<tr><td><a id="p117210"></a>12 02 000 000</td><td><a id="p117211"></a>Additional information</td><td></td><td></td><td></td><td><a id="p117212"></a>N</td><td></td></tr>
<tr><td><a id="p117213"></a>12 02 008 000</td><td></td><td><a id="p117214"></a>Code</td><td></td><td><a id="p117215"></a>an5</td><td><a id="p117216"></a>Y</td><td><a id="p117217"></a>The Union codes are further specified in Title II.<br>Member States may define national codes. National codes must have the format a1an4.</td></tr>
<tr><td><a id="p117218"></a>12 02 009 000</td><td></td><td><a id="p117219"></a>Text</td><td></td><td><a id="p117220"></a>an..512</td><td><a id="p117221"></a>N</td><td></td></tr>
<tr><td><a id="p117222"></a>12 03 000 000</td><td><a id="p117223"></a>Supporting document</td><td></td><td></td><td></td><td><a id="p117224"></a>N</td><td></td></tr>
<tr><td><a id="p117225"></a>12 03 001 000</td><td></td><td><a id="p117226"></a>Reference number</td><td></td><td><a id="p117227"></a>an..70</td><td><a id="p117228"></a>N</td><td></td></tr>
<tr><td><a id="p117229"></a>12 03 002 000</td><td></td><td><a id="p117230"></a>Type</td><td></td><td><a id="p117231"></a>an4</td><td><a id="p117232"></a>N</td><td><a id="p117233"></a>The codes for Union or international documents,<br>certificates and authorisations can be found in the TARIC database. Their format is a1an3.<br>For national documents,<br>certificates and authorisations, Member States may define national codes. National codes must have the format n1an3.</td></tr>
<tr><td><a id="p117234"></a>12 03 010 000</td><td></td><td><a id="p117235"></a>Issuing Authority name</td><td></td><td><a id="p117236"></a>an..70</td><td><a id="p117237"></a>N</td><td></td></tr>
<tr><td><a id="p117238"></a>12 03 005 000</td><td></td><td><a id="p117239"></a>Measurement unit and qualifier</td><td><a id="p117240"></a>-</td><td><a id="p117241"></a>an..4</td><td><a id="p117242"></a>N</td><td><a id="p117243"></a>The measurement units and qualifiers defined in TARIC shall be used. In such case, the format of the measurement units and qualifiers shall be an..4, but shall never be n..4 formats, reserved for national measurement units and qualifiers. If no such measurement units and qualifiers are available in TARIC, national measurement units and qualifiers may be used. Their format shall be n..4.</td></tr>
<tr><td><a id="p117244"></a>12 03 006 000</td><td></td><td><a id="p117245"></a>Quantity</td><td><a id="p117246"></a>-</td><td><a id="p117247"></a>n..16,6</td><td><a id="p117248"></a>N</td><td></td></tr>
<tr><td><a id="p117249"></a>12 03 011 000</td><td></td><td><a id="p117250"></a>Date of validity</td><td></td><td><a id="p117251"></a>an..19</td><td><a id="p117252"></a>N</td><td></td></tr>
<tr><td><a id="p117253"></a>12 03 012 000</td><td></td><td><a id="p117254"></a>Currency</td><td></td><td><a id="p117255"></a>a3</td><td><a id="p117256"></a>N</td><td><a id="p117257"></a>Currency code as referred to in introductory note 13 number 2.</td></tr>
<tr><td><a id="p117258"></a>12 03 013 000</td><td></td><td><a id="p117259"></a>Document Line<br>Item Number</td><td></td><td><a id="p117260"></a>n..5</td><td><a id="p117261"></a>N</td><td></td></tr>
<tr><td><a id="p117262"></a>12 03 014 000</td><td></td><td><a id="p117263"></a>Amount</td><td></td><td><a id="p117264"></a>n..16,2</td><td><a id="p117265"></a>N</td><td></td></tr>
<tr><td><a id="p117266"></a>12 03 079 000</td><td></td><td><a id="p117267"></a>Complement of information</td><td></td><td><a id="p117268"></a>an..35</td><td><a id="p117269"></a>N</td><td></td></tr>
<tr><td><a id="p117270"></a>12 04 000 000</td><td><a id="p117271"></a>Additional reference</td><td></td><td></td><td></td><td><a id="p117272"></a>N</td><td></td></tr>
<tr><td><a id="p117273"></a>12 04 001 000</td><td></td><td><a id="p117274"></a>Reference number</td><td></td><td><a id="p117275"></a>an..70</td><td><a id="p117276"></a>N</td><td></td></tr>
<tr><td><a id="p117277"></a>12 04 002 000</td><td></td><td><a id="p117278"></a>Type</td><td></td><td><a id="p117279"></a>an4</td><td><a id="p117280"></a>N</td><td><a id="p117281"></a>Union codes can be found in the TARIC database. Their format is a1an3.<br>Member States may define national codes. National codes must have the format n1an3.</td></tr>
<tr><td><a id="p117282"></a>12 05 000 000</td><td><a id="p117283"></a>Transport document</td><td></td><td></td><td></td><td><a id="p117284"></a>N</td><td></td></tr>
<tr><td><a id="p117285"></a>12 05 001 000</td><td></td><td><a id="p117286"></a>Reference number</td><td></td><td><a id="p117287"></a>an..70</td><td><a id="p117288"></a>N</td><td></td></tr>
<tr><td><a id="p117289"></a>12 05 002 000</td><td></td><td><a id="p117290"></a>Type</td><td></td><td><a id="p117291"></a>an4</td><td><a id="p117292"></a>N</td><td><a id="p117293"></a>The codes can be found in the<br>TARIC database.</td></tr>
<tr><td><a id="p117294"></a>12 06 000 000</td><td><a id="p117295"></a>TIR Carnet number</td><td></td><td></td><td><a id="p117296"></a>an..12</td><td><a id="p117297"></a>N</td><td></td></tr>
<tr><td><a id="p117298"></a>12 07 000 000</td><td><a id="p117299"></a>Referral request reference</td><td></td><td></td><td><a id="p117300"></a>an..17</td><td><a id="p117301"></a>N</td><td></td></tr>
<tr><td><a id="p117302"></a>12 08 000 000</td><td><a id="p117303"></a>Reference number/UCR</td><td></td><td></td><td><a id="p117304"></a>an..35</td><td><a id="p117305"></a>N</td><td></td></tr>
<tr><td><a id="p117306"></a>12 09 000 000</td><td><a id="p117307"></a>LRN</td><td></td><td></td><td><a id="p117308"></a>an..22</td><td><a id="p117309"></a>N</td><td></td></tr>
<tr><td><a id="p117310"></a>12 10 000 000</td><td><a id="p117311"></a>Deferred payment</td><td></td><td></td><td><a id="p117312"></a>an..35</td><td><a id="p117313"></a>N</td><td></td></tr>
<tr><td><a id="p117314"></a>12 11 000 000</td><td><a id="p117315"></a>Warehouse</td><td></td><td></td><td></td><td><a id="p117316"></a>N</td><td></td></tr>
<tr><td><a id="p117317"></a>12 11 002 000</td><td></td><td><a id="p117318"></a>Type</td><td></td><td><a id="p117319"></a>al</td><td><a id="p117320"></a>Y</td><td></td></tr>
<tr><td><a id="p117321"></a>12 11 015 000</td><td></td><td><a id="p117322"></a>Identifier</td><td></td><td><a id="p117323"></a>an..35</td><td><a id="p117324"></a>N</td><td></td></tr>
<tr><td><a id="p117325"></a>12 12 000 000</td><td><a id="p117326"></a>Authorisation</td><td></td><td></td><td></td><td><a id="p117327"></a>N</td><td></td></tr>
<tr><td><a id="p117328"></a>12 12 002 000</td><td></td><td><a id="p117329"></a>Type</td><td></td><td><a id="p117330"></a>an..4</td><td><a id="p117331"></a>N</td><td><a id="p117332"></a>The codes can be found in the TARIC database.</td></tr>
<tr><td><a id="p117333"></a>12 12 001 000</td><td></td><td><a id="p117334"></a>Reference Number</td><td></td><td><a id="p117335"></a>an..35</td><td><a id="p117336"></a>N</td><td></td></tr>
<tr><td><a id="p117337"></a>12 12 080 000</td><td></td><td><a id="p117338"></a>Holder of authorisation</td><td></td><td><a id="p117339"></a>an..17</td><td><a id="p117340"></a>N</td><td><a id="p117341"></a>The structure of the EORI number is defined in Title II of Annex 12-01.</td></tr>
<tr><td><a id="p117342"></a>13 01 000 000</td><td><a id="p117343"></a>Exporter</td><td></td><td></td><td></td><td><a id="p117344"></a>N</td><td></td></tr>
<tr><td><a id="p117345"></a>13 01 016 000</td><td></td><td><a id="p117346"></a>Name</td><td></td><td><a id="p117347"></a>an..70</td><td><a id="p117348"></a>N</td><td></td></tr>
<tr><td><a id="p117349"></a>13 01 017 000</td><td></td><td><a id="p117350"></a>Identification number</td><td></td><td><a id="p117351"></a>an..17</td><td><a id="p117352"></a>N</td><td><a id="p117353"></a>The structure of the EORI number is defined in Title II of Annex 12-01.<br>The structure of a third country unique identification number recognised by the Union is defined in Title II.</td></tr>
<tr><td><a id="p117354"></a>13 01 018 000</td><td></td><td><a id="p117355"></a>Address</td><td></td><td></td><td><a id="p117356"></a>N</td><td></td></tr>
<tr><td><a id="p117357"></a>13 01 018 019</td><td></td><td></td><td><a id="p117358"></a>Street and number</td><td><a id="p117359"></a>an..70</td><td><a id="p117360"></a>N</td><td></td></tr>
<tr><td><a id="p117361"></a>13 01 018 020</td><td></td><td></td><td><a id="p117362"></a>Country</td><td><a id="p117363"></a>a2</td><td><a id="p117364"></a>N</td><td><a id="p117365"></a>GEONOM code as referred to in introductory note 13 number 3.</td></tr>
<tr><td><a id="p117366"></a>13 01 018 021</td><td></td><td></td><td><a id="p117367"></a>Postcode</td><td><a id="p117368"></a>an..17</td><td><a id="p117369"></a>N</td><td></td></tr>
<tr><td><a id="p117370"></a>13 01 018 022</td><td></td><td></td><td><a id="p117371"></a>City</td><td><a id="p117372"></a>an..35</td><td><a id="p117373"></a>N</td><td></td></tr>
<tr><td><a id="p117374"></a>13 02 000 000</td><td><a id="p117375"></a>Consignor</td><td></td><td></td><td></td><td><a id="p117376"></a>N</td><td></td></tr>
<tr><td><a id="p117377"></a>13 02 016 000</td><td></td><td><a id="p117378"></a>Name</td><td></td><td><a id="p117379"></a>an..70</td><td><a id="p117380"></a>N</td><td></td></tr>
<tr><td><a id="p117381"></a>13 02 017 000</td><td></td><td><a id="p117382"></a>Identification number</td><td></td><td><a id="p117383"></a>an..17</td><td><a id="p117384"></a>N</td><td><a id="p117385"></a>The structure of the EORI number is defined in Title II of Annex 12-01.<br>The structure of a third country unique identification number recognised by the Union is defined in Title II for D.E. 1 301 017 000 Identification number.</td></tr>
<tr><td><a id="p117386"></a>13 02 028 000</td><td></td><td><a id="p117387"></a>Type of person</td><td></td><td><a id="p117388"></a>n1</td><td><a id="p117389"></a>Y</td><td></td></tr>
<tr><td><a id="p117390"></a>13 02 018 000</td><td></td><td><a id="p117391"></a>Address</td><td></td><td></td><td><a id="p117392"></a>N</td><td></td></tr>
<tr><td><a id="p117393"></a>13 02 018 019</td><td></td><td></td><td><a id="p117394"></a>Street and number</td><td><a id="p117395"></a>an..70</td><td><a id="p117396"></a>N</td><td></td></tr>
<tr><td><a id="p117397"></a>13 02 018 023</td><td></td><td></td><td><a id="p117398"></a>Street</td><td><a id="p117399"></a>an..70</td><td><a id="p117400"></a>N</td><td></td></tr>
<tr><td><a id="p117401"></a>13 02 018 024</td><td></td><td></td><td><a id="p117402"></a>Street additional line</td><td><a id="p117403"></a>an..70</td><td><a id="p117404"></a>N</td><td></td></tr>
<tr><td><a id="p117405"></a>13 02 018 025</td><td></td><td></td><td><a id="p117406"></a>Number</td><td><a id="p117407"></a>an..35</td><td><a id="p117408"></a>N</td><td></td></tr>
<tr><td><a id="p117409"></a>13 02 018 026</td><td></td><td></td><td><a id="p117410"></a>P.O. box</td><td><a id="p117411"></a>an..70</td><td><a id="p117412"></a>N</td><td></td></tr>
<tr><td><a id="p117413"></a>13 02 018 027</td><td></td><td></td><td><a id="p117414"></a>Subdivision</td><td><a id="p117415"></a>an..35</td><td><a id="p117416"></a>N</td><td></td></tr>
<tr><td><a id="p117417"></a>13 02 018 020</td><td></td><td></td><td><a id="p117418"></a>Country</td><td><a id="p117419"></a>a2</td><td><a id="p117420"></a>N</td><td><a id="p117421"></a>GEONOM code as referred to in introductory note 13 number 3.</td></tr>
<tr><td><a id="p117422"></a>13 02 018 021</td><td></td><td></td><td><a id="p117423"></a>Postcode</td><td><a id="p117424"></a>an..17</td><td><a id="p117425"></a>N</td><td></td></tr>
<tr><td><a id="p117426"></a>13 02 018 022</td><td></td><td></td><td><a id="p117427"></a>City</td><td><a id="p117428"></a>an..35</td><td><a id="p117429"></a>N</td><td></td></tr>
<tr><td><a id="p117430"></a>13 02 029 000</td><td></td><td><a id="p117431"></a>Communication</td><td></td><td></td><td><a id="p117432"></a>N</td><td></td></tr>
<tr><td><a id="p117433"></a>13 02 029 015</td><td></td><td></td><td><a id="p117434"></a>Identifier</td><td><a id="p117435"></a>an..512</td><td><a id="p117436"></a>N</td><td></td></tr>
<tr><td><a id="p117437"></a>13 02 029 002</td><td></td><td></td><td><a id="p117438"></a>Type</td><td><a id="p117439"></a>an..3</td><td><a id="p117440"></a>Y</td><td></td></tr>
<tr><td><a id="p117441"></a>13 02 074 000</td><td></td><td><a id="p117442"></a>Contact person</td><td></td><td></td><td></td><td></td></tr>
<tr><td><a id="p117443"></a>13 02 074 016</td><td></td><td></td><td><a id="p117444"></a>Name</td><td><a id="p117445"></a>an..70</td><td><a id="p117446"></a>N</td><td></td></tr>
<tr><td><a id="p117447"></a>13 02 074 075</td><td></td><td></td><td><a id="p117448"></a>Phone number</td><td><a id="p117449"></a>an..35</td><td><a id="p117450"></a>N</td><td></td></tr>
<tr><td><a id="p117451"></a>13 02 074 076</td><td></td><td></td><td><a id="p117452"></a>E-mail address</td><td><a id="p117453"></a>an..256</td><td><a id="p117454"></a>N</td><td></td></tr>
<tr><td><a id="p117455"></a>13 03 000 000</td><td><a id="p117456"></a>Consignee</td><td></td><td></td><td></td><td><a id="p117457"></a>N</td><td></td></tr>
<tr><td><a id="p117458"></a>13 03 016 000</td><td></td><td><a id="p117459"></a>Name</td><td></td><td><a id="p117460"></a>an..70</td><td><a id="p117461"></a>N</td><td></td></tr>
<tr><td><a id="p117462"></a>13 03 017 000</td><td></td><td><a id="p117463"></a>Identification number</td><td></td><td><a id="p117464"></a>an..17</td><td><a id="p117465"></a>N</td><td><a id="p117466"></a>The structure of the EORI number is defined in Title II of Annex 12-01.<br>The structure of a third country unique identification number recognised by the Union is defined in Title II for D.E. 1 301 017 000 Identification number.</td></tr>
<tr><td><a id="p117467"></a>13 03 028 000</td><td></td><td><a id="p117468"></a>Type of person</td><td></td><td><a id="p117469"></a>n1</td><td><a id="p117470"></a>Y</td><td><a id="p117471"></a>The Type of person code as defined in Title II for D.E.<br>13 02 028 000 (Consignor Type of Person) shall be used.</td></tr>
<tr><td><a id="p117472"></a>13 03 018 000</td><td></td><td><a id="p117473"></a>Address</td><td></td><td></td><td><a id="p117474"></a>N</td><td></td></tr>
<tr><td><a id="p117475"></a>13 03 018 019</td><td></td><td></td><td><a id="p117476"></a>Street and number</td><td><a id="p117477"></a>an..70</td><td><a id="p117478"></a>N</td><td></td></tr>
<tr><td><a id="p117479"></a>13 03 018 023</td><td></td><td></td><td><a id="p117480"></a>Street</td><td><a id="p117481"></a>an..70</td><td><a id="p117482"></a>N</td><td></td></tr>
<tr><td><a id="p117483"></a>13 03 018 024</td><td></td><td></td><td><a id="p117484"></a>Street additional line</td><td><a id="p117485"></a>an..70</td><td><a id="p117486"></a>N</td><td></td></tr>
<tr><td><a id="p117487"></a>13 03 018 025</td><td></td><td></td><td><a id="p117488"></a>Number</td><td><a id="p117489"></a>an..35</td><td><a id="p117490"></a>N</td><td></td></tr>
<tr><td><a id="p117491"></a>13 03 018 026</td><td></td><td></td><td><a id="p117492"></a>P.O. box</td><td><a id="p117493"></a>an..70</td><td><a id="p117494"></a>N</td><td></td></tr>
<tr><td><a id="p117495"></a>13 03 018 027</td><td></td><td></td><td><a id="p117496"></a>Subdivision</td><td><a id="p117497"></a>an..35</td><td><a id="p117498"></a>N</td><td></td></tr>
<tr><td><a id="p117499"></a>13 03 018 020</td><td></td><td></td><td><a id="p117500"></a>Country</td><td><a id="p117501"></a>a2</td><td><a id="p117502"></a>N</td><td><a id="p117503"></a>GEONOM code as referred to in introductory note 13 number 3.</td></tr>
<tr><td><a id="p117504"></a>13 03 018 021</td><td></td><td></td><td><a id="p117505"></a>Postcode</td><td><a id="p117506"></a>an..17</td><td><a id="p117507"></a>N</td><td></td></tr>
<tr><td><a id="p117508"></a>13 03 018 022</td><td></td><td></td><td><a id="p117509"></a>City</td><td><a id="p117510"></a>an..35</td><td><a id="p117511"></a>N</td><td></td></tr>
<tr><td><a id="p117512"></a>13 03 029 000</td><td></td><td><a id="p117513"></a>Communication</td><td></td><td></td><td><a id="p117514"></a>N</td><td></td></tr>
<tr><td><a id="p117515"></a>13 03 029 015</td><td></td><td></td><td><a id="p117516"></a>Identifier</td><td><a id="p117517"></a>an..512</td><td><a id="p117518"></a>N</td><td></td></tr>
<tr><td><a id="p117519"></a>13 03 029 002</td><td></td><td></td><td><a id="p117520"></a>Type</td><td><a id="p117521"></a>an..3</td><td><a id="p117522"></a>Y</td><td><a id="p117523"></a>The Communication Type code as defined in Title II for D.E.<br>13 02 029 002 (Consignor-Communication-Type) shall be used.</td></tr>
<tr><td><a id="p117524"></a>13 04 000 000</td><td><a id="p117525"></a>Importer</td><td></td><td></td><td></td><td><a id="p117526"></a>N</td><td></td></tr>
<tr><td><a id="p117527"></a>13 04 016 000</td><td></td><td><a id="p117528"></a>Name</td><td></td><td><a id="p117529"></a>an..70</td><td><a id="p117530"></a>N</td><td></td></tr>
<tr><td><a id="p117531"></a>13 04 017 000</td><td></td><td><a id="p117532"></a>Identification number</td><td></td><td><a id="p117533"></a>an..17</td><td><a id="p117534"></a>N</td><td><a id="p117535"></a>The structure of the EORI number is defined in Title II of Annex 12-01.</td></tr>
<tr><td><a id="p117536"></a>13 04 018 000</td><td></td><td><a id="p117537"></a>Address</td><td></td><td></td><td><a id="p117538"></a>N</td><td></td></tr>
<tr><td><a id="p117539"></a>13 04 018 019</td><td></td><td></td><td><a id="p117540"></a>Street and number</td><td><a id="p117541"></a>an..70</td><td><a id="p117542"></a>N</td><td></td></tr>
<tr><td><a id="p117543"></a>13 04 018 029</td><td></td><td></td><td><a id="p117544"></a>Country</td><td><a id="p117545"></a>a2</td><td><a id="p117546"></a>N</td><td><a id="p117547"></a>GEONOM code as referred to in introductory note 13 number 3.</td></tr>
<tr><td><a id="p117548"></a>13 04 018 021</td><td></td><td></td><td><a id="p117549"></a>Postcode</td><td><a id="p117550"></a>an..17</td><td><a id="p117551"></a>N</td><td></td></tr>
<tr><td><a id="p117552"></a>13 04 018 022</td><td></td><td></td><td><a id="p117553"></a>City</td><td><a id="p117554"></a>an..35</td><td><a id="p117555"></a>N</td><td></td></tr>
<tr><td><a id="p117556"></a>13 05 000 000</td><td><a id="p117557"></a>Declarant</td><td></td><td></td><td></td><td><a id="p117558"></a>N</td><td></td></tr>
<tr><td><a id="p117559"></a>13 05 016 000</td><td></td><td><a id="p117560"></a>Name</td><td></td><td><a id="p117561"></a>an..70</td><td><a id="p117562"></a>N</td><td></td></tr>
<tr><td><a id="p117563"></a>13 05 017 000</td><td></td><td><a id="p117564"></a>Identification number</td><td></td><td><a id="p117565"></a>an..17</td><td><a id="p117566"></a>N</td><td><a id="p117567"></a>The structure of the EORI number is defined in Title II of Annex 12-01.</td></tr>
<tr><td><a id="p117568"></a>13 05 018 000</td><td></td><td><a id="p117569"></a>Address</td><td></td><td></td><td><a id="p117570"></a>N</td><td></td></tr>
<tr><td><a id="p117571"></a>13 05 018 019</td><td></td><td></td><td><a id="p117572"></a>Street and number</td><td><a id="p117573"></a>an..70</td><td><a id="p117574"></a>N</td><td></td></tr>
<tr><td><a id="p117575"></a>13 05 018 023</td><td></td><td></td><td><a id="p117576"></a>Street</td><td><a id="p117577"></a>an..70</td><td><a id="p117578"></a>N</td><td></td></tr>
<tr><td><a id="p117579"></a>13 05 018 024</td><td></td><td></td><td><a id="p117580"></a>Street additional line</td><td><a id="p117581"></a>an..70</td><td><a id="p117582"></a>N</td><td></td></tr>
<tr><td><a id="p117583"></a>13 05 018 025</td><td></td><td></td><td><a id="p117584"></a>Number</td><td><a id="p117585"></a>an..35</td><td><a id="p117586"></a>N</td><td></td></tr>
<tr><td><a id="p117587"></a>13 05 018 026</td><td></td><td></td><td><a id="p117588"></a>P.O. box</td><td><a id="p117589"></a>an..70</td><td><a id="p117590"></a>N</td><td></td></tr>
<tr><td><a id="p117591"></a>13 05 018 027</td><td></td><td></td><td><a id="p117592"></a>Subdivision</td><td><a id="p117593"></a>an..35</td><td><a id="p117594"></a>N</td><td></td></tr>
<tr><td><a id="p117595"></a>13 05 018 020</td><td></td><td></td><td><a id="p117596"></a>Country</td><td><a id="p117597"></a>a2</td><td><a id="p117598"></a>N</td><td><a id="p117599"></a>GEONOM code as referred to in introductory note 13 number 3.</td></tr>
<tr><td><a id="p117600"></a>13 05 018 021</td><td></td><td></td><td><a id="p117601"></a>Postcode</td><td><a id="p117602"></a>an..17</td><td><a id="p117603"></a>N</td><td></td></tr>
<tr><td><a id="p117604"></a>13 05 018 022</td><td></td><td></td><td><a id="p117605"></a>City</td><td><a id="p117606"></a>an..35</td><td><a id="p117607"></a>N</td><td></td></tr>
<tr><td><a id="p117608"></a>13 05 029 000</td><td></td><td><a id="p117609"></a>Communication</td><td></td><td></td><td><a id="p117610"></a>N</td><td></td></tr>
<tr><td><a id="p117611"></a>13 05 029 015</td><td></td><td></td><td><a id="p117612"></a>Identifier</td><td><a id="p117613"></a>an..512</td><td><a id="p117614"></a>N</td><td></td></tr>
<tr><td><a id="p117615"></a>13 05 029 002</td><td></td><td></td><td><a id="p117616"></a>Type</td><td><a id="p117617"></a>an..3</td><td><a id="p117618"></a>Y</td><td><a id="p117619"></a>The Communication Type code as defined in Title II for D.E.<br>13 02 029 002 (Consignor-Communication-Type) shall be used.</td></tr>
<tr><td><a id="p117620"></a>13 05 074 000</td><td></td><td><a id="p117621"></a>Contact person</td><td></td><td></td><td><a id="p117622"></a>N</td><td></td></tr>
<tr><td><a id="p117623"></a>13 05 074 016</td><td></td><td></td><td><a id="p117624"></a>Name</td><td><a id="p117625"></a>an..70</td><td><a id="p117626"></a>N</td><td></td></tr>
<tr><td><a id="p117627"></a>13 05 074 075</td><td></td><td></td><td><a id="p117628"></a>Phone number</td><td><a id="p117629"></a>an..35</td><td><a id="p117630"></a>N</td><td></td></tr>
<tr><td><a id="p117631"></a>13 05 074 076</td><td></td><td></td><td><a id="p117632"></a>E-mail address</td><td><a id="p117633"></a>an..256</td><td><a id="p117634"></a>N</td><td></td></tr>
<tr><td><a id="p117635"></a>13 06 000 000</td><td><a id="p117636"></a>Representative</td><td></td><td></td><td></td><td><a id="p117637"></a>N</td><td></td></tr>
<tr><td><a id="p117638"></a>13 06 016 000</td><td></td><td><a id="p117639"></a>Name</td><td></td><td><a id="p117640"></a>an..70</td><td><a id="p117641"></a>N</td><td></td></tr>
<tr><td><a id="p117642"></a>13 06 017 000</td><td></td><td><a id="p117643"></a>Identification number</td><td></td><td><a id="p117644"></a>an..17</td><td><a id="p117645"></a>N</td><td><a id="p117646"></a>The structure of the EORI number is defined in Title II of Annex 12-01.<br>The structure of a third country unique identification number recognised by the Union is defined in Title II for D.E. 1 301 017 000 Identification number</td></tr>
<tr><td><a id="p117647"></a>13 06 030 000</td><td></td><td><a id="p117648"></a>Status</td><td></td><td><a id="p117649"></a>n1</td><td><a id="p117650"></a>Y</td><td></td></tr>
<tr><td><a id="p117651"></a>13 06 018 000</td><td></td><td><a id="p117652"></a>Address</td><td></td><td></td><td><a id="p117653"></a>N</td><td></td></tr>
<tr><td></td><td></td><td></td><td></td><td></td><td></td><td></td></tr>
<tr><td><a id="p117654"></a>13 06 018 023</td><td></td><td></td><td><a id="p117655"></a>Street</td><td><a id="p117656"></a>an..70</td><td><a id="p117657"></a>N</td><td></td></tr>
<tr><td><a id="p117658"></a>13 06 018 024</td><td></td><td></td><td><a id="p117659"></a>Street additional line</td><td><a id="p117660"></a>an..70</td><td><a id="p117661"></a>N</td><td></td></tr>
<tr><td><a id="p117662"></a>13 06 018 025</td><td></td><td></td><td><a id="p117663"></a>Number</td><td><a id="p117664"></a>an..35</td><td><a id="p117665"></a>N</td><td></td></tr>
<tr><td><a id="p117666"></a>13 06 018 026</td><td></td><td></td><td><a id="p117667"></a>P.O. box</td><td><a id="p117668"></a>an..70</td><td><a id="p117669"></a>N</td><td></td></tr>
<tr><td><a id="p117670"></a>13 06 018 027</td><td></td><td></td><td><a id="p117671"></a>Subdivision</td><td><a id="p117672"></a>an..35</td><td><a id="p117673"></a>N</td><td></td></tr>
<tr><td><a id="p117674"></a>13 06 018 020</td><td></td><td></td><td><a id="p117675"></a>Country</td><td><a id="p117676"></a>a2</td><td><a id="p117677"></a>N</td><td><a id="p117678"></a>GEONOM code as referred to in introductory note 13 number 3.</td></tr>
<tr><td><a id="p117679"></a>13 06 018 021</td><td></td><td></td><td><a id="p117680"></a>Postcode</td><td><a id="p117681"></a>an..17</td><td><a id="p117682"></a>N</td><td></td></tr>
<tr><td><a id="p117683"></a>13 06 018 022</td><td></td><td></td><td><a id="p117684"></a>City</td><td><a id="p117685"></a>an..35</td><td><a id="p117686"></a>N</td><td></td></tr>
<tr><td><a id="p117687"></a>13 06 029028</td><td></td><td><a id="p117688"></a>Communication</td><td></td><td></td><td><a id="p117689"></a>N</td><td></td></tr>
<tr><td><a id="p117690"></a>13 06 029 015</td><td></td><td></td><td><a id="p117691"></a>Identifier</td><td><a id="p117692"></a>an..512</td><td><a id="p117693"></a>N</td><td></td></tr>
<tr><td><a id="p117694"></a>13 06 029 002</td><td></td><td></td><td><a id="p117695"></a>Type</td><td><a id="p117696"></a>an..3</td><td><a id="p117697"></a>Y</td><td><a id="p117698"></a>The Communication Type code as defined in Title II for D.E.<br>13 02 029 002 (Consignor-Communication-Type) shall be used.</td></tr>
<tr><td><a id="p117699"></a>13 06 074 000</td><td></td><td><a id="p117700"></a>Contact person</td><td></td><td></td><td><a id="p117701"></a>N</td><td></td></tr>
<tr><td><a id="p117702"></a>13 06 074 016</td><td></td><td></td><td><a id="p117703"></a>Name</td><td><a id="p117704"></a>an..70</td><td><a id="p117705"></a>N</td><td></td></tr>
<tr><td><a id="p117706"></a>13 06 074 075</td><td></td><td></td><td><a id="p117707"></a>Phone number</td><td><a id="p117708"></a>an..35</td><td><a id="p117709"></a>N</td><td></td></tr>
<tr><td><a id="p117710"></a>13 06 074 076</td><td></td><td></td><td><a id="p117711"></a>E-mail address</td><td><a id="p117712"></a>an..256</td><td><a id="p117713"></a>N</td><td></td></tr>
<tr><td><a id="p117714"></a>13 07 000 000</td><td><a id="p117715"></a>Holder of the transit procedure</td><td></td><td></td><td></td><td><a id="p117716"></a>N</td><td></td></tr>
<tr><td><a id="p117717"></a>13 07 016 000</td><td></td><td><a id="p117718"></a>Name</td><td></td><td><a id="p117719"></a>an..70</td><td><a id="p117720"></a>N</td><td></td></tr>
<tr><td><a id="p117721"></a>13 07 017 000</td><td></td><td><a id="p117722"></a>Identification number</td><td></td><td><a id="p117723"></a>an..17</td><td><a id="p117724"></a>N</td><td><a id="p117725"></a>The structure of the EORI number is defined in Title II of Annex 12-01.</td></tr>
<tr><td><a id="p117726"></a>13 07 078 000</td><td></td><td><a id="p117727"></a>TIR Holder identification number</td><td></td><td><a id="p117728"></a>an..17</td><td><a id="p117729"></a>N</td><td><a id="p117730"></a>The structure of the EORI number is defined in Title II of Annex 12-01.</td></tr>
<tr><td><a id="p117731"></a>13 07 018 000</td><td></td><td><a id="p117732"></a>Address</td><td></td><td></td><td><a id="p117733"></a>N</td><td></td></tr>
<tr><td><a id="p117734"></a>13 07 019 019</td><td></td><td></td><td><a id="p117735"></a>Street and number</td><td><a id="p117736"></a>an..70</td><td><a id="p117737"></a>N</td><td></td></tr>
<tr><td><a id="p117738"></a>13 07 020 020</td><td></td><td></td><td><a id="p117739"></a>Country</td><td><a id="p117740"></a>a2</td><td><a id="p117741"></a>N</td><td><a id="p117742"></a>GEONOM code as referred to in introductory note 13 number 3.</td></tr>
<tr><td><a id="p117743"></a>13 07 021 021</td><td></td><td></td><td><a id="p117744"></a>Postcode</td><td><a id="p117745"></a>an..17</td><td><a id="p117746"></a>N</td><td></td></tr>
<tr><td><a id="p117747"></a>13 07 022 022</td><td></td><td></td><td><a id="p117748"></a>City</td><td><a id="p117749"></a>an..35</td><td><a id="p117750"></a>N</td><td></td></tr>
<tr><td><a id="p117751"></a>13 07 074 000</td><td></td><td><a id="p117752"></a>Contact person</td><td></td><td></td><td><a id="p117753"></a>N</td><td></td></tr>
<tr><td><a id="p117754"></a>13 07 074 016</td><td></td><td></td><td><a id="p117755"></a>Name</td><td><a id="p117756"></a>an..70</td><td><a id="p117757"></a>N</td><td></td></tr>
<tr><td><a id="p117758"></a>13 07 074 075</td><td></td><td></td><td><a id="p117759"></a>Phone number</td><td><a id="p117760"></a>an..35</td><td><a id="p117761"></a>N</td><td></td></tr>
<tr><td><a id="p117762"></a>13 07 074 076</td><td></td><td></td><td><a id="p117763"></a>E-mail address</td><td><a id="p117764"></a>an..256</td><td><a id="p117765"></a>N</td><td></td></tr>
<tr><td><a id="p117766"></a>13 08 000 000</td><td><a id="p117767"></a>Seller</td><td></td><td></td><td></td><td><a id="p117768"></a>N</td><td></td></tr>
<tr><td><a id="p117769"></a>13 08 016 000</td><td></td><td><a id="p117770"></a>Name</td><td></td><td><a id="p117771"></a>an..70</td><td><a id="p117772"></a>N</td><td></td></tr>
<tr><td><a id="p117773"></a>13 08 017 000</td><td></td><td><a id="p117774"></a>Identification number</td><td></td><td><a id="p117775"></a>an..17</td><td><a id="p117776"></a>N</td><td><a id="p117777"></a>The structure of the EORI number is defined in Title II of Annex 12-01.</td></tr>
<tr><td></td><td></td><td></td><td></td><td></td><td></td><td><a id="p117778"></a>The structure of a third country unique identification number recognised by the Union is defined in Title II for D.E.<br>13 01 017 000 Identification number.</td></tr>
<tr><td><a id="p117779"></a>13 08 028 000</td><td></td><td><a id="p117780"></a>Type of person</td><td></td><td><a id="p117781"></a>n1</td><td><a id="p117782"></a>Y</td><td><a id="p117783"></a>The Type of person code as defined in Title II for D.E.<br>13 02 028 000 (Consignor-Type of Person) shall be used.</td></tr>
<tr><td><a id="p117784"></a>13 08 018 000</td><td></td><td><a id="p117785"></a>Address</td><td></td><td></td><td><a id="p117786"></a>N</td><td></td></tr>
<tr><td><a id="p117787"></a>13 08 018 019</td><td></td><td></td><td><a id="p117788"></a>Street and number</td><td><a id="p117789"></a>an..70</td><td><a id="p117790"></a>N</td><td></td></tr>
<tr><td><a id="p117791"></a>13 08 018 023</td><td></td><td></td><td><a id="p117792"></a>Street</td><td><a id="p117793"></a>an..70</td><td><a id="p117794"></a>N</td><td></td></tr>
<tr><td><a id="p117795"></a>13 08 018 024</td><td></td><td></td><td><a id="p117796"></a>Street additional line</td><td><a id="p117797"></a>an..70</td><td><a id="p117798"></a>N</td><td></td></tr>
<tr><td><a id="p117799"></a>13 08 018 025</td><td></td><td></td><td><a id="p117800"></a>Number</td><td><a id="p117801"></a>an..35</td><td><a id="p117802"></a>N</td><td></td></tr>
<tr><td><a id="p117803"></a>13 08 018 026</td><td></td><td></td><td><a id="p117804"></a>P.O. box</td><td><a id="p117805"></a>an..70</td><td><a id="p117806"></a>N</td><td></td></tr>
<tr><td><a id="p117807"></a>13 08 018 027</td><td></td><td></td><td><a id="p117808"></a>Subdivision</td><td><a id="p117809"></a>an..35</td><td><a id="p117810"></a>N</td><td></td></tr>
<tr><td><a id="p117811"></a>13 08 018 020</td><td></td><td></td><td><a id="p117812"></a>Country</td><td><a id="p117813"></a>a2</td><td><a id="p117814"></a>N</td><td><a id="p117815"></a>GEONOM code as referred to in introductory note 13 number 3.</td></tr>
<tr><td><a id="p117816"></a>13 08 018 021</td><td></td><td></td><td><a id="p117817"></a>Postcode</td><td><a id="p117818"></a>an..17</td><td><a id="p117819"></a>N</td><td></td></tr>
<tr><td><a id="p117820"></a>13 08 018 022</td><td></td><td></td><td><a id="p117821"></a>City</td><td><a id="p117822"></a>an..35</td><td><a id="p117823"></a>N</td><td></td></tr>
<tr><td><a id="p117824"></a>13 08 029 000</td><td></td><td><a id="p117825"></a>Communication</td><td></td><td></td><td><a id="p117826"></a>N</td><td></td></tr>
<tr><td><a id="p117827"></a>13 08 029 015</td><td></td><td></td><td><a id="p117828"></a>Identifier</td><td><a id="p117829"></a>an..512</td><td><a id="p117830"></a>N</td><td></td></tr>
<tr><td><a id="p117831"></a>13 08 029 002</td><td></td><td></td><td><a id="p117832"></a>Type</td><td><a id="p117833"></a>an..3</td><td><a id="p117834"></a>Y</td><td><a id="p117835"></a>The Communication Type code as defined in Title II for D.E.<br>13 02 029 002 (Consignor-Communication-Type) shall be used.</td></tr>
<tr><td><a id="p117836"></a>13 09 000 000</td><td><a id="p117837"></a>Buyer</td><td></td><td></td><td></td><td><a id="p117838"></a>N</td><td></td></tr>
<tr><td><a id="p117839"></a>13 09 016 000</td><td></td><td><a id="p117840"></a>Name</td><td></td><td><a id="p117841"></a>an..70</td><td><a id="p117842"></a>N</td><td></td></tr>
<tr><td rowspan="2"><a id="p117843"></a>13 09 017 000</td><td rowspan="2"></td><td rowspan="2"><a id="p117844"></a>Identification number</td><td rowspan="2"></td><td rowspan="2"><a id="p117845"></a>an..17</td><td rowspan="2"><a id="p117846"></a>N</td><td><a id="p117847"></a>The structure of the EORI number is defined in Title II of Annex 12-01.</td></tr>
<tr><td><a id="p117848"></a>The structure of a third country unique identification number recognised by the Union is defined in Title II for D.E.<br>13 01 017 000 Identification number.</td></tr>
<tr><td><a id="p117849"></a>13 09 028 000</td><td></td><td><a id="p117850"></a>Type of person</td><td></td><td><a id="p117851"></a>n1</td><td><a id="p117852"></a>Y</td><td><a id="p117853"></a>The Type of person code as defined in Title II for D.E.<br>13 02 028 000 (Consignor-Type of Person) shall be used.</td></tr>
<tr><td><a id="p117854"></a>13 09 018 000</td><td></td><td><a id="p117855"></a>Address</td><td></td><td></td><td><a id="p117856"></a>N</td><td></td></tr>
<tr><td><a id="p117857"></a>13 09 018 019</td><td></td><td></td><td><a id="p117858"></a>Street and number</td><td><a id="p117859"></a>an..70</td><td><a id="p117860"></a>N</td><td></td></tr>
<tr><td><a id="p117861"></a>13 09 018 023</td><td></td><td></td><td><a id="p117862"></a>Street</td><td><a id="p117863"></a>an..70</td><td><a id="p117864"></a>N</td><td></td></tr>
<tr><td><a id="p117865"></a>13 09 018 024</td><td></td><td></td><td><a id="p117866"></a>Street additional line</td><td><a id="p117867"></a>an..70</td><td><a id="p117868"></a>N</td><td></td></tr>
<tr><td><a id="p117869"></a>13 09 018 025</td><td></td><td></td><td><a id="p117870"></a>Number</td><td><a id="p117871"></a>an..35</td><td><a id="p117872"></a>N</td><td></td></tr>
<tr><td><a id="p117873"></a>13 09 018 026</td><td></td><td></td><td><a id="p117874"></a>P.O. box</td><td><a id="p117875"></a>an..70</td><td><a id="p117876"></a>N</td><td></td></tr>
<tr><td><a id="p117877"></a>13 09 018 027</td><td></td><td></td><td><a id="p117878"></a>Subdivision</td><td><a id="p117879"></a>an..35</td><td><a id="p117880"></a>N</td><td></td></tr>
<tr><td><a id="p117881"></a>13 09 018 020</td><td></td><td></td><td><a id="p117882"></a>Country</td><td><a id="p117883"></a>a2</td><td><a id="p117884"></a>N</td><td><a id="p117885"></a>GEONOM code as referred to in introductory note 13 number 3.</td></tr>
<tr><td><a id="p117886"></a>13 09 018 021</td><td></td><td></td><td><a id="p117887"></a>Postcode</td><td><a id="p117888"></a>an..17</td><td><a id="p117889"></a>N</td><td></td></tr>
<tr><td><a id="p117890"></a>13 09 018 022</td><td></td><td></td><td><a id="p117891"></a>City</td><td><a id="p117892"></a>an..35</td><td><a id="p117893"></a>N</td><td></td></tr>
<tr><td><a id="p117894"></a>13 09 029 000</td><td></td><td><a id="p117895"></a>Communication</td><td></td><td></td><td><a id="p117896"></a>N</td><td></td></tr>
<tr><td><a id="p117897"></a>13 09 029 015</td><td></td><td></td><td><a id="p117898"></a>Identifier</td><td><a id="p117899"></a>an..512</td><td><a id="p117900"></a>N</td><td></td></tr>
<tr><td><a id="p117901"></a>13 09 029 002</td><td></td><td></td><td><a id="p117902"></a>Type</td><td><a id="p117903"></a>an..3</td><td><a id="p117904"></a>Y</td><td><a id="p117905"></a>The Communication Type code as defined in Title II for D.E.<br>13 02 029 002 (Consignor-Communication-Type) shall be used.</td></tr>
<tr><td><a id="p117906"></a>13 10 000 000</td><td><a id="p117907"></a>Person notifying the arrival</td><td></td><td></td><td></td><td><a id="p117908"></a>N</td><td></td></tr>
<tr><td><a id="p117909"></a>13 10 017 000</td><td></td><td><a id="p117910"></a>Identification number</td><td></td><td><a id="p117911"></a>an..17</td><td><a id="p117912"></a>N</td><td><a id="p117913"></a>The structure of the EORI number is defined in Title II of Annex 12-01.</td></tr>
<tr><td><a id="p117914"></a>13 10 029 000</td><td></td><td><a id="p117915"></a>Communication</td><td></td><td></td><td><a id="p117916"></a>N</td><td></td></tr>
<tr><td><a id="p117917"></a>13 10 029 015</td><td></td><td></td><td><a id="p117918"></a>Identifier</td><td><a id="p117919"></a>an..512</td><td><a id="p117920"></a>N</td><td></td></tr>
<tr><td><a id="p117921"></a>13 10 029 002</td><td></td><td></td><td><a id="p117922"></a>Type</td><td><a id="p117923"></a>an..3</td><td><a id="p117924"></a>Y</td><td><a id="p117925"></a>The Communication Type code as defined in Title II for D.E.<br>13 02 029 002 (Consignor-Communication- Type) shall<br>be used.</td></tr>
<tr><td><a id="p117926"></a>13 11 000 000</td><td><a id="p117927"></a>Person presenting the goods</td><td></td><td></td><td></td><td><a id="p117928"></a>N</td><td></td></tr>
<tr><td><a id="p117929"></a>13 11 017 000</td><td></td><td><a id="p117930"></a>Identification number</td><td></td><td><a id="p117931"></a>an..17</td><td><a id="p117932"></a>N</td><td><a id="p117933"></a>The structure of the EORI number is defined in Title II of Annex 12-01.</td></tr>
<tr><td><a id="p117934"></a>13 12 000 000</td><td><a id="p117935"></a>Carrier</td><td></td><td></td><td></td><td><a id="p117936"></a>N</td><td></td></tr>
<tr><td><a id="p117937"></a>13 12 016 000</td><td></td><td><a id="p117938"></a>Name</td><td></td><td><a id="p117939"></a>an..70</td><td><a id="p117940"></a>N</td><td></td></tr>
<tr><td><a id="p117941"></a>13 12 017 000</td><td></td><td><a id="p117942"></a>Identification number</td><td></td><td><a id="p117943"></a>an..17</td><td><a id="p117944"></a>N</td><td><a id="p117945"></a>The structure of the EORI number is defined in Title II of Annex 12-01.<br>The structure of a third country unique identification number recognised by the Union is defined in Title II for D.E.<br>13 01 017 000 Identification number.</td></tr>
<tr><td><a id="p117946"></a>13 12 018 000</td><td></td><td><a id="p117947"></a>Address</td><td></td><td></td><td><a id="p117948"></a>N</td><td></td></tr>
<tr><td><a id="p117949"></a>13 12 018 023</td><td></td><td></td><td><a id="p117950"></a>Street</td><td><a id="p117951"></a>an..70</td><td><a id="p117952"></a>N</td><td></td></tr>
<tr><td><a id="p117953"></a>13 12 018 024</td><td></td><td></td><td><a id="p117954"></a>Street additional line</td><td><a id="p117955"></a>an..70</td><td><a id="p117956"></a>N</td><td></td></tr>
<tr><td><a id="p117957"></a>13 12 018 025</td><td></td><td></td><td><a id="p117958"></a>Number</td><td><a id="p117959"></a>an..35</td><td><a id="p117960"></a>N</td><td></td></tr>
<tr><td><a id="p117961"></a>13 12 018 026</td><td></td><td></td><td><a id="p117962"></a>P.O. box</td><td><a id="p117963"></a>an..70</td><td><a id="p117964"></a>N</td><td></td></tr>
<tr><td><a id="p117965"></a>13 12 018 027</td><td></td><td></td><td><a id="p117966"></a>Subdivision</td><td><a id="p117967"></a>an..35</td><td><a id="p117968"></a>N</td><td></td></tr>
<tr><td><a id="p117969"></a>13 12 018 020</td><td></td><td></td><td><a id="p117970"></a>Country</td><td><a id="p117971"></a>a2</td><td><a id="p117972"></a>N</td><td><a id="p117973"></a>GEONOM code as referred to in introductory note 13 number 3.</td></tr>
<tr><td><a id="p117974"></a>13 12 018 021</td><td></td><td></td><td><a id="p117975"></a>Postcode</td><td><a id="p117976"></a>an..17</td><td><a id="p117977"></a>N</td><td></td></tr>
<tr><td><a id="p117978"></a>13 12 018 022</td><td></td><td></td><td><a id="p117979"></a>City</td><td><a id="p117980"></a>an..35</td><td><a id="p117981"></a>N</td><td></td></tr>
<tr><td><a id="p117982"></a>13 12 029 000</td><td></td><td><a id="p117983"></a>Communication</td><td></td><td></td><td><a id="p117984"></a>N</td><td></td></tr>
<tr><td><a id="p117985"></a>13 12 029 015</td><td></td><td></td><td><a id="p117986"></a>Identifier</td><td><a id="p117987"></a>an..512</td><td><a id="p117988"></a>N</td><td></td></tr>
<tr><td><a id="p117989"></a>13 12 029 002</td><td></td><td></td><td><a id="p117990"></a>Type</td><td><a id="p117991"></a>an..3</td><td><a id="p117992"></a>Y</td><td><a id="p117993"></a>The Communication Type code as defined in Title II for D.E.<br>13 02 029 002 (Consignor-Communication-Type) shall be used.</td></tr>
<tr><td><a id="p117994"></a>13 12 074 000</td><td></td><td><a id="p117995"></a>Contact person</td><td></td><td></td><td><a id="p117996"></a>N</td><td></td></tr>
<tr><td><a id="p117997"></a>13 12 074 016</td><td></td><td></td><td><a id="p117998"></a>Name</td><td><a id="p117999"></a>an..70</td><td><a id="p118000"></a>N</td><td></td></tr>
<tr><td><a id="p118001"></a>13 12 074 075</td><td></td><td></td><td><a id="p118002"></a>Phone number</td><td><a id="p118003"></a>an..35</td><td><a id="p118004"></a>N</td><td></td></tr>
<tr><td><a id="p118005"></a>13 12 074 076</td><td></td><td></td><td><a id="p118006"></a>E-mail address</td><td><a id="p118007"></a>an..256</td><td><a id="p118008"></a>N</td><td></td></tr>
<tr><td><a id="p118009"></a>13 13 000 000</td><td><a id="p118010"></a>Notify party</td><td></td><td></td><td></td><td><a id="p118011"></a>N</td><td></td></tr>
<tr><td><a id="p118012"></a>13 13 016 000</td><td></td><td><a id="p118013"></a>Name</td><td></td><td><a id="p118014"></a>an..70</td><td><a id="p118015"></a>N</td><td></td></tr>
<tr><td><a id="p118016"></a>13 13 017 000</td><td></td><td><a id="p118017"></a>Identification number</td><td></td><td><a id="p118018"></a>an..17</td><td><a id="p118019"></a>N</td><td><a id="p118020"></a>The structure of the EORI number is defined in Title II of Annex 12-01.<br>The structure of a third country unique identification number recognised by the Union is defined in Title II for D.E. 1 301 017 000 Identification number.</td></tr>
<tr><td><a id="p118021"></a>13 13 028 000</td><td></td><td><a id="p118022"></a>Type of person</td><td></td><td><a id="p118023"></a>n1</td><td><a id="p118024"></a>Y</td><td><a id="p118025"></a>The Type of person code as defined in Title II for D.E.<br>13 02 028 000 (Consignor - Type of Person) shall be used.</td></tr>
<tr><td><a id="p118026"></a>13 13 018 000</td><td></td><td><a id="p118027"></a>Address</td><td></td><td></td><td><a id="p118028"></a>N</td><td></td></tr>
<tr><td><a id="p118029"></a>13 13 018 023</td><td></td><td></td><td><a id="p118030"></a>Street</td><td><a id="p118031"></a>an..70</td><td><a id="p118032"></a>N</td><td></td></tr>
<tr><td><a id="p118033"></a>13 13 018 024</td><td></td><td></td><td><a id="p118034"></a>Street additional line</td><td><a id="p118035"></a>an..70</td><td><a id="p118036"></a>N</td><td></td></tr>
<tr><td><a id="p118037"></a>13 13 018 025</td><td></td><td></td><td><a id="p118038"></a>Number</td><td><a id="p118039"></a>an..35</td><td><a id="p118040"></a>N</td><td></td></tr>
<tr><td><a id="p118041"></a>13 13 018 026</td><td></td><td></td><td><a id="p118042"></a>P.O. box</td><td><a id="p118043"></a>an..70</td><td><a id="p118044"></a>N</td><td></td></tr>
<tr><td><a id="p118045"></a>13 13 018 027</td><td></td><td></td><td><a id="p118046"></a>Subdivision</td><td><a id="p118047"></a>an..35</td><td><a id="p118048"></a>N</td><td></td></tr>
<tr><td><a id="p118049"></a>13 13 018 020</td><td></td><td></td><td><a id="p118050"></a>Country</td><td><a id="p118051"></a>a2</td><td><a id="p118052"></a>N</td><td><a id="p118053"></a>GEONOM code as referred to in introductory note 13 number 3.</td></tr>
<tr><td><a id="p118054"></a>13 13 018 021</td><td></td><td></td><td><a id="p118055"></a>Postcode</td><td><a id="p118056"></a>an..17</td><td><a id="p118057"></a>N</td><td></td></tr>
<tr><td><a id="p118058"></a>13 13 018 022</td><td></td><td></td><td><a id="p118059"></a>City</td><td><a id="p118060"></a>an..35</td><td><a id="p118061"></a>N</td><td></td></tr>
<tr><td><a id="p118062"></a>13 13 029 000</td><td></td><td><a id="p118063"></a>Communication</td><td></td><td></td><td><a id="p118064"></a>N</td><td></td></tr>
<tr><td><a id="p118065"></a>13 13 029 015</td><td></td><td></td><td><a id="p118066"></a>Identifier</td><td><a id="p118067"></a>an..512</td><td><a id="p118068"></a>N</td><td></td></tr>
<tr><td><a id="p118069"></a>13 13 029 002</td><td></td><td></td><td><a id="p118070"></a>Type</td><td><a id="p118071"></a>an..3</td><td><a id="p118072"></a>N</td><td></td></tr>
<tr><td><a id="p118073"></a>13 14 000 000</td><td><a id="p118074"></a>Additional supply chain actor</td><td></td><td></td><td></td><td><a id="p118075"></a>N</td><td></td></tr>
<tr><td><a id="p118076"></a>13 14 031 000</td><td></td><td><a id="p118077"></a>Role</td><td></td><td><a id="p118078"></a>a..3</td><td><a id="p118079"></a>Y</td><td></td></tr>
<tr><td><a id="p118080"></a>13 14 017 000</td><td></td><td><a id="p118081"></a>Identification number</td><td></td><td><a id="p118082"></a>an..17</td><td><a id="p118083"></a>N</td><td><a id="p118084"></a>The structure of the EORI number is defined in Title II of Annex 12-01.<br>The structure of a third country unique identification number recognised by the Union is defined in Title II for D.E.<br>13 01 017 000 Identification number.</td></tr>
<tr><td><a id="p118085"></a>13 15 000 000</td><td><a id="p118086"></a>Supplementary declarant</td><td></td><td></td><td></td><td><a id="p118087"></a>N</td><td></td></tr>
<tr><td><a id="p118088"></a>13 15 017 000</td><td></td><td><a id="p118089"></a>Identification number</td><td></td><td><a id="p118090"></a>an..17</td><td><a id="p118091"></a>N</td><td><a id="p118092"></a>The structure of the EORI number is defined in Title II of Annex 12-01.</td></tr>
<tr><td><a id="p118093"></a>13 15 032 000</td><td></td><td><a id="p118094"></a>Supplementary filing type</td><td></td><td><a id="p118095"></a>an..3</td><td><a id="p118096"></a>Y</td><td></td></tr>
<tr><td><a id="p118097"></a>13 16 000 000</td><td><a id="p118098"></a>Additional fiscal reference</td><td></td><td></td><td></td><td><a id="p118099"></a>N</td><td></td></tr>
<tr><td><a id="p118100"></a>13 16 031 000</td><td></td><td><a id="p118101"></a>Role</td><td></td><td><a id="p118102"></a>an3</td><td><a id="p118103"></a>Y</td><td></td></tr>
<tr><td><a id="p118104"></a>13 16 034 000</td><td></td><td><a id="p118105"></a>VAT identification number</td><td></td><td><a id="p118106"></a>an..17</td><td><a id="p118107"></a>N</td><td></td></tr>
<tr><td><a id="p118108"></a>13 17 000 000</td><td><a id="p118109"></a>Person lodging the customs goods manifest</td><td></td><td></td><td></td><td><a id="p118110"></a>N</td><td></td></tr>
<tr><td><a id="p118111"></a>13 17 017 000</td><td></td><td><a id="p118112"></a>Identification number</td><td></td><td><a id="p118113"></a>an..17</td><td><a id="p118114"></a>N</td><td><a id="p118115"></a>The structure of the EORI number is defined in Title II of Annex 12-01</td></tr>
<tr><td><a id="p118116"></a>13 18 000 000</td><td><a id="p118117"></a>Person requesting a proof of the customs status of Union goods</td><td></td><td></td><td></td><td><a id="p118118"></a>N</td><td></td></tr>
<tr><td><a id="p118119"></a>13 18 017 000</td><td></td><td><a id="p118120"></a>Identification number</td><td></td><td><a id="p118121"></a>an..17</td><td><a id="p118122"></a>N</td><td><a id="p118123"></a>The structure of the EORI number is defined in Title II of Annex 12-01</td></tr>
<tr><td><a id="p118124"></a>13 19 000 000</td><td><a id="p118125"></a>Person notifying the arrival of goods following movement under temporary storage</td><td></td><td></td><td></td><td><a id="p118126"></a>N</td><td></td></tr>
<tr><td><a id="p118127"></a>13 19 017 000</td><td></td><td><a id="p118128"></a>Identification number</td><td></td><td><a id="p118129"></a>an..17</td><td><a id="p118130"></a>N</td><td><a id="p118131"></a>The structure of the EORI number is defined in Title II of Annex 12-01</td></tr>
<tr><td><a id="p118132"></a>13 20 000 000</td><td><a id="p118133"></a>Person providing a guarantee</td><td></td><td></td><td></td><td><a id="p118134"></a>N</td><td></td></tr>
<tr><td><a id="p118135"></a>13 20 017 000</td><td></td><td><a id="p118136"></a>Identification number</td><td></td><td><a id="p118137"></a>an..17</td><td></td><td><a id="p118138"></a>The structure of the EORI number is defined in Title II of Annex 12-01</td></tr>
<tr><td><a id="p118139"></a>13 21 000 000</td><td><a id="p118140"></a>Person paying the customs duty</td><td></td><td></td><td></td><td><a id="p118141"></a>N</td><td></td></tr>
<tr><td><a id="p118142"></a>13 21 017 000</td><td></td><td><a id="p118143"></a>Identification number</td><td></td><td><a id="p118144"></a>an..17</td><td></td><td><a id="p118145"></a>The structure of the EORI number is defined in Title II of Annex 12-01</td></tr>
<tr><td><a id="p118146"></a>14 01 000 000</td><td><a id="p118147"></a>Delivery terms</td><td></td><td></td><td></td><td><a id="p118148"></a>N</td><td></td></tr>
<tr><td><a id="p118149"></a>14 01 035 000</td><td></td><td><a id="p118150"></a>INCOTERM code</td><td></td><td><a id="p118151"></a>a3</td><td><a id="p118152"></a>Y</td><td><a id="p118153"></a>The codes and headings describing the commercial contract are defined in Title II.</td></tr>
<tr><td><a id="p118154"></a>14 01 036 000</td><td></td><td><a id="p118155"></a>UN/LOCODE</td><td></td><td><a id="p118156"></a>an..17</td><td><a id="p118157"></a>N</td><td><a id="p118158"></a>UN/LOCODE as referred to in introductory note 13 number 4.</td></tr>
<tr><td><a id="p118159"></a>14 01 020 000</td><td></td><td><a id="p118160"></a>Country</td><td></td><td><a id="p118161"></a>a2</td><td><a id="p118162"></a>N</td><td><a id="p118163"></a>GEONOM code as referred to in introductory note 13 number 3.</td></tr>
<tr><td><a id="p118164"></a>14 01 037 000</td><td></td><td><a id="p118165"></a>Location</td><td></td><td><a id="p118166"></a>an..35</td><td><a id="p118167"></a>N</td><td></td></tr>
<tr><td><a id="p118168"></a>14 02 000 000</td><td><a id="p118169"></a>Transport charges</td><td></td><td></td><td></td><td><a id="p118170"></a>N</td><td></td></tr>
<tr><td><a id="p118171"></a>14 02 038 000</td><td></td><td><a id="p118172"></a>Method of payment</td><td></td><td><a id="p118173"></a>a1</td><td><a id="p118174"></a>Y</td><td></td></tr>
<tr><td><a id="p118175"></a>14 03 000 000</td><td><a id="p118176"></a>Duties and taxes</td><td></td><td></td><td></td><td><a id="p118177"></a>N</td><td></td></tr>
<tr><td><a id="p118178"></a>14 03 039 000</td><td></td><td><a id="p118179"></a>Tax type</td><td></td><td><a id="p118180"></a>an3</td><td><a id="p118181"></a>Y</td><td><a id="p118182"></a>The Union codes are further specified in Title II<br>Member States may define national codes. National codes must have the format n1an2.</td></tr>
<tr><td><a id="p118183"></a>14 03 038 000</td><td></td><td><a id="p118184"></a>Method of payment</td><td></td><td><a id="p118185"></a>a1</td><td><a id="p118186"></a>Y</td><td></td></tr>
<tr><td><a id="p118187"></a>14 03 042 000</td><td></td><td><a id="p118188"></a>Payable tax amount</td><td></td><td><a id="p118189"></a>n..16,2</td><td><a id="p118190"></a>N</td><td></td></tr>
<tr><td><a id="p118191"></a>14 03 040 000</td><td></td><td><a id="p118192"></a>Tax base</td><td></td><td></td><td><a id="p118193"></a>N</td><td></td></tr>
<tr><td><a id="p118194"></a>14 03 040 041</td><td></td><td></td><td><a id="p118195"></a>Tax rate</td><td><a id="p118196"></a>n..17,3</td><td><a id="p118197"></a>N</td><td></td></tr>
<tr><td><a id="p118198"></a>14 03 040 005</td><td></td><td></td><td><a id="p118199"></a>Measurement unit and qualifier</td><td><a id="p118200"></a>an..4</td><td><a id="p118201"></a>N</td><td><a id="p118202"></a>The measurement units and qualifiers defined in TARIC shall be used. In such case, the format of the measurement units and qualifiers shall be an..4, but shall never be n..4 formats, reserved for national measurement units and qualifiers. If no such measurement units and qualifiers are available in TARIC, national measurement units and qualifiers may be used. Their format shall be n..4.</td></tr>
<tr><td><a id="p118203"></a>14 03 040 006</td><td></td><td></td><td><a id="p118204"></a>Quantity</td><td><a id="p118205"></a>n..16,6</td><td><a id="p118206"></a>N</td><td></td></tr>
<tr><td><a id="p118207"></a>14 03 040 014</td><td></td><td></td><td><a id="p118208"></a>Amount</td><td><a id="p118209"></a>n..16,2</td><td><a id="p118210"></a>N</td><td></td></tr>
<tr><td><a id="p118211"></a>14 03 040 043</td><td></td><td></td><td><a id="p118212"></a>Tax amount</td><td><a id="p118213"></a>n..16,6</td><td><a id="p118214"></a>N</td><td></td></tr>
<tr><td><a id="p118215"></a>14 16 000 000</td><td><a id="p118216"></a>Total duties and taxes amount</td><td></td><td></td><td><a id="p118217"></a>n..16,2</td><td><a id="p118218"></a>N</td><td></td></tr>
<tr><td><a id="p118219"></a>14 17 000 000</td><td><a id="p118220"></a>Internal currency unit</td><td></td><td></td><td><a id="p118221"></a>a3</td><td><a id="p118222"></a>N</td><td><a id="p118223"></a>Currency code as referred to in introductory note 13 number 2.</td></tr>
<tr><td><a id="p118224"></a>14 04 000 000</td><td><a id="p118225"></a>Additions and deductions</td><td></td><td></td><td></td><td><a id="p118226"></a>N</td><td></td></tr>
<tr><td><a id="p118227"></a>14 04 008 000</td><td></td><td><a id="p118228"></a>Code</td><td></td><td><a id="p118229"></a>a2</td><td><a id="p118230"></a>Y</td><td></td></tr>
<tr><td><a id="p118231"></a>14 04 014 000</td><td></td><td><a id="p118232"></a>Amount</td><td></td><td><a id="p118233"></a>n..16,2</td><td><a id="p118234"></a>N</td><td></td></tr>
<tr><td><a id="p118235"></a>14 05 000 000</td><td><a id="p118236"></a>Invoice currency</td><td></td><td></td><td><a id="p118237"></a>a3</td><td><a id="p118238"></a>N</td><td><a id="p118239"></a>Currency code as referred to in introductory note 13 number 2.</td></tr>
<tr><td><a id="p118240"></a>14 06 000 000</td><td><a id="p118241"></a>Total amount invoiced</td><td></td><td></td><td><a id="p118242"></a>n..16,2</td><td><a id="p118243"></a>N</td><td></td></tr>
<tr><td><a id="p118244"></a>14 07 000 000</td><td><a id="p118245"></a>Valuation indicators</td><td></td><td></td><td><a id="p118246"></a>an4</td><td><a id="p118247"></a>Y</td><td></td></tr>
<tr><td><a id="p118248"></a>14 08 000 000</td><td><a id="p118249"></a>Item amount invoiced</td><td></td><td></td><td><a id="p118250"></a>n..16,2</td><td><a id="p118251"></a>N</td><td></td></tr>
<tr><td><a id="p118252"></a>14 09 000 000</td><td><a id="p118253"></a>Exchange rate</td><td></td><td></td><td><a id="p118254"></a>n..12,5</td><td><a id="p118255"></a>N</td><td></td></tr>
<tr><td><a id="p118256"></a>14 10 000 000</td><td><a id="p118257"></a>Valuation method</td><td></td><td></td><td><a id="p118258"></a>n1</td><td><a id="p118259"></a>Y</td><td></td></tr>
<tr><td><a id="p118260"></a>14 11 000 000</td><td><a id="p118261"></a>Preference</td><td></td><td></td><td><a id="p118262"></a>n3</td><td><a id="p118263"></a>Y</td><td></td></tr>
<tr><td><a id="p118264"></a>14 12 000 000</td><td><a id="p118265"></a>Postal value</td><td></td><td></td><td></td><td><a id="p118266"></a>N</td><td></td></tr>
<tr><td><a id="p118267"></a>14 12 012 000</td><td></td><td><a id="p118268"></a>Currency code</td><td></td><td><a id="p118269"></a>a3</td><td><a id="p118270"></a>N</td><td><a id="p118271"></a>Currency code as referred to in introductory note 13 number 2.</td></tr>
<tr><td><a id="p118272"></a>14 12 0140 00</td><td></td><td><a id="p118273"></a>Amount</td><td></td><td><a id="p118274"></a>n..16,2</td><td><a id="p118275"></a>N</td><td></td></tr>
<tr><td><a id="p118276"></a>14 13 000 000</td><td><a id="p118277"></a>Postal charges</td><td></td><td></td><td></td><td><a id="p118278"></a>N</td><td></td></tr>
<tr><td><a id="p118279"></a>14 13 012 000</td><td></td><td><a id="p118280"></a>Currency code</td><td></td><td><a id="p118281"></a>a3</td><td><a id="p118282"></a>N</td><td><a id="p118283"></a>Currency code as referred to in introductory note 13 number 2.</td></tr>
<tr><td><a id="p118284"></a>14 13 014 000</td><td></td><td><a id="p118285"></a>Amount</td><td></td><td><a id="p118286"></a>n..16,2</td><td><a id="p118287"></a>N</td><td></td></tr>
<tr><td><a id="p118288"></a>14 14 000 000</td><td><a id="p118289"></a>Intrinsic value</td><td></td><td></td><td></td><td><a id="p118290"></a>N</td><td></td></tr>
<tr><td><a id="p118291"></a>14 14 012 000</td><td></td><td><a id="p118292"></a>Currency code</td><td></td><td><a id="p118293"></a>a3</td><td><a id="p118294"></a>N</td><td><a id="p118295"></a>Currency code as referred to in introductory note 13 number 2.</td></tr>
<tr><td><a id="p118296"></a>14 14 014 000</td><td></td><td><a id="p118297"></a>Amount</td><td></td><td><a id="p118298"></a>n..16,2</td><td><a id="p118299"></a>N</td><td></td></tr>
<tr><td><a id="p118300"></a>14 15 000 000</td><td><a id="p118301"></a>Transport and insurance costs to the destination</td><td></td><td></td><td></td><td><a id="p118302"></a>N</td><td></td></tr>
<tr><td><a id="p118303"></a>14 15 012 000</td><td></td><td><a id="p118304"></a>Currency code</td><td></td><td><a id="p118305"></a>a3</td><td><a id="p118306"></a>N</td><td><a id="p118307"></a>Currency code as referred to in introductory note 13 number 2.</td></tr>
<tr><td><a id="p118308"></a>14 15 014 000</td><td></td><td><a id="p118309"></a>Amount</td><td></td><td><a id="p118310"></a>n..16,2</td><td><a id="p118311"></a>N</td><td></td></tr>
<tr><td><a id="p118312"></a>15 01 000 000</td><td><a id="p118313"></a>Estimated date and time of departure</td><td></td><td></td><td><a id="p118314"></a>an..19</td><td><a id="p118315"></a>N</td><td></td></tr>
<tr><td><a id="p118316"></a>15 02 000 000</td><td><a id="p118317"></a>Actual date and time of departure</td><td></td><td></td><td><a id="p118318"></a>an..19</td><td><a id="p118319"></a>N</td><td></td></tr>
<tr><td><a id="p118320"></a>15 03 000 000</td><td><a id="p118321"></a>Estimated date and time of arrival</td><td></td><td></td><td><a id="p118322"></a>an..19</td><td><a id="p118323"></a>N</td><td></td></tr>
<tr><td><a id="p118324"></a>15 04 000 000</td><td><a id="p118325"></a>Estimated date and time of arrival at the port of unloading</td><td></td><td></td><td><a id="p118326"></a>an..19</td><td><a id="p118327"></a>N</td><td></td></tr>
<tr><td><a id="p118328"></a>15 05 000 000</td><td><a id="p118329"></a>Actual date and time of arrival</td><td></td><td></td><td><a id="p118330"></a>an..19</td><td><a id="p118331"></a>N</td><td></td></tr>
<tr><td><a id="p118332"></a>15 06 000 000</td><td><a id="p118333"></a>Declaration date</td><td></td><td></td><td><a id="p118334"></a>an..19</td><td><a id="p118335"></a>N</td><td></td></tr>
<tr><td><a id="p118336"></a>15 07 000 000</td><td><a id="p118337"></a>Requested validity of the proof</td><td></td><td></td><td><a id="p118338"></a>n..3</td><td><a id="p118339"></a>N</td><td></td></tr>
<tr><td><a id="p118340"></a>15 08 000 000</td><td><a id="p118341"></a>Date and time of presentation of the goods</td><td></td><td></td><td><a id="p118342"></a>an..19</td><td><a id="p118343"></a>N</td><td></td></tr>
<tr><td><a id="p118344"></a>15 09 000 000</td><td><a id="p118345"></a>Date of acceptance</td><td></td><td></td><td><a id="p118346"></a>an..19</td><td><a id="p118347"></a>N</td><td></td></tr>
<tr><td><a id="p118348"></a>16 02 000 000</td><td><a id="p118349"></a>Addressed Member State</td><td></td><td></td><td></td><td><a id="p118350"></a>N</td><td></td></tr>
<tr><td><a id="p118351"></a>16 02 020 000</td><td></td><td><a id="p118352"></a>Country</td><td></td><td><a id="p118353"></a>a2</td><td><a id="p118354"></a>N</td><td><a id="p118355"></a>GEONOM code as referred to in introductory note 13 number 3.</td></tr>
<tr><td><a id="p118356"></a>16 03 000 000</td><td><a id="p118357"></a>Country of destination</td><td></td><td></td><td><a id="p118358"></a>a2</td><td><a id="p118359"></a>N</td><td><a id="p118360"></a>GEONOM code as referred to in introductory note 13 number 3.<br>In the context of transit operations, The ISO 3166- alpha-2 country code shall be used</td></tr>
<tr><td><a id="p118361"></a>16 04 000 000</td><td><a id="p118362"></a>Region of destination</td><td></td><td></td><td><a id="p118363"></a>an..35</td><td><a id="p118364"></a>N</td><td><a id="p118365"></a>Codes are defined by the Member State concerned.</td></tr>
<tr><td><a id="p118366"></a>16 05 000 000</td><td><a id="p118367"></a>Place of delivery</td><td></td><td></td><td></td><td><a id="p118368"></a>N</td><td></td></tr>
<tr><td><a id="p118369"></a>16 05 036 000</td><td></td><td><a id="p118370"></a>UN/LOCODE</td><td></td><td><a id="p118371"></a>an..17</td><td><a id="p118372"></a>N</td><td><a id="p118373"></a>UN/LOCODE as referred to in introductory note 13 number 4.</td></tr>
<tr><td><a id="p118374"></a>16 05 020 000</td><td></td><td><a id="p118375"></a>Country</td><td></td><td><a id="p118376"></a>a2</td><td><a id="p118377"></a>N</td><td><a id="p118378"></a>GEONOM code as referred to in introductory note 13 number 3.</td></tr>
<tr><td><a id="p118379"></a>16 05 037 000</td><td></td><td><a id="p118380"></a>Location</td><td></td><td><a id="p118381"></a>an..35</td><td><a id="p118382"></a>N</td><td></td></tr>
<tr><td><a id="p118383"></a>16 06 000 000</td><td><a id="p118384"></a>Country of dispatch</td><td></td><td></td><td><a id="p118385"></a>a2</td><td><a id="p118386"></a>N</td><td><a id="p118387"></a>GEONOM code as referred to in introductory note 13 number 3.</td></tr>
<tr><td><a id="p118388"></a>16 07 000 000</td><td><a id="p118389"></a>Country of export</td><td></td><td></td><td><a id="p118390"></a>a2</td><td><a id="p118391"></a>N</td><td><a id="p118392"></a>GEONOM code as referred to in introductory note 13 number 3.</td></tr>
<tr><td><a id="p118393"></a>16 08 000 000</td><td><a id="p118394"></a>Country of origin</td><td></td><td></td><td><a id="p118395"></a>a2</td><td><a id="p118396"></a>N</td><td><a id="p118397"></a>GEONOM code as referred to in introductory note 13 number 3.</td></tr>
<tr><td><a id="p118398"></a>16 09 000 000</td><td><a id="p118399"></a>Country of preferential origin</td><td></td><td></td><td><a id="p118400"></a>an..4</td><td><a id="p118401"></a>N</td><td><a id="p118402"></a>GEONOM code as referred to in introductory note 13 number 3.<br>Where the proof of origin refers to a region/group of countries, use the numeric identifier codes specified in the integrated tariff established in accordance with Article 2 of Council (EEC) Regulation No 2658/87.</td></tr>
<tr><td><a id="p118403"></a>16 10 000 000</td><td><a id="p118404"></a>Region of dispatch</td><td></td><td></td><td><a id="p118405"></a>an..9</td><td><a id="p118406"></a>N</td><td><a id="p118407"></a>Codes are defined by the Member State concerned.</td></tr>
<tr><td><a id="p118408"></a>16 11 000 000</td><td><a id="p118409"></a>Countries of routing of means of transport</td><td></td><td></td><td></td><td><a id="p118410"></a>N</td><td></td></tr>
<tr><td><a id="p118411"></a>16 11 020 000</td><td></td><td><a id="p118412"></a>Country</td><td></td><td><a id="p118413"></a>a2</td><td><a id="p118414"></a>N</td><td><a id="p118415"></a>GEONOM code as referred to in introductory note 13 number 3.</td></tr>
<tr><td><a id="p118416"></a>16 12 000 000</td><td><a id="p118417"></a>Country of routing of consignment</td><td></td><td></td><td></td><td><a id="p118418"></a>N</td><td></td></tr>
<tr><td><a id="p118419"></a>16 12 020 000</td><td></td><td><a id="p118420"></a>Country</td><td></td><td><a id="p118421"></a>a2</td><td><a id="p118422"></a>N</td><td><a id="p118423"></a>GEONOM code as referred to in introductory note 13 number 3.</td></tr>
<tr><td><a id="p118424"></a>16 13 000 000</td><td><a id="p118425"></a>Place of loading</td><td></td><td></td><td></td><td><a id="p118426"></a>N</td><td></td></tr>
<tr><td><a id="p118427"></a>16 13 036 000</td><td></td><td><a id="p118428"></a>UN/LOCODE</td><td></td><td><a id="p118429"></a>an..17</td><td><a id="p118430"></a>N</td><td><a id="p118431"></a>UN/LOCODE as referred to in introductory note 13 number 4.</td></tr>
<tr><td><a id="p118432"></a>16 13 020 000</td><td></td><td><a id="p118433"></a>Country</td><td></td><td><a id="p118434"></a>a2</td><td><a id="p118435"></a>N</td><td><a id="p118436"></a>Where the place of loading is not coded according to the UN/LOCODE, the country where the place of loading is located is identified by the GEONOM code as referred to in introductory note 13 number 3.</td></tr>
<tr><td><a id="p118437"></a>16 13 037 000</td><td></td><td><a id="p118438"></a>Location</td><td></td><td><a id="p118439"></a>an..35</td><td><a id="p118440"></a>N</td><td></td></tr>
<tr><td><a id="p118441"></a>16 14 000 000</td><td><a id="p118442"></a>Place of unloading</td><td></td><td></td><td></td><td><a id="p118443"></a>N</td><td></td></tr>
<tr><td><a id="p118444"></a>16 14 036 000</td><td></td><td><a id="p118445"></a>UN/LOCODE</td><td></td><td><a id="p118446"></a>an..17</td><td><a id="p118447"></a>N</td><td><a id="p118448"></a>UN/LOCODE as referred to in introductory note 13 number 4.</td></tr>
<tr><td><a id="p118449"></a>16 14 020 000</td><td></td><td><a id="p118450"></a>Country</td><td></td><td><a id="p118451"></a>a2</td><td><a id="p118452"></a>N</td><td><a id="p118453"></a>Where the place of unloading is not coded according to the UN/LOCODE, the country where the place of unloading is located is identified by the GEONOM code as referred to in introductory note 13 number 3.</td></tr>
<tr><td><a id="p118454"></a>16 14 037 000</td><td></td><td><a id="p118455"></a>Location</td><td></td><td><a id="p118456"></a>an..35</td><td><a id="p118457"></a>N</td><td></td></tr>
<tr><td><a id="p118458"></a>16 15 000 000</td><td><a id="p118459"></a>Location of goods</td><td></td><td></td><td></td><td><a id="p118460"></a>N</td><td><a id="p118461"></a>Only one type for location of goods can be used.</td></tr>
<tr><td><a id="p118462"></a>16 15 045 000</td><td></td><td><a id="p118463"></a>Type of location</td><td></td><td><a id="p118464"></a>a1</td><td><a id="p118465"></a>Y</td><td></td></tr>
<tr><td><a id="p118466"></a>16 15 046 000</td><td></td><td><a id="p118467"></a>Qualifier of identification</td><td></td><td><a id="p118468"></a>a1</td><td><a id="p118469"></a>Y</td><td></td></tr>
<tr><td><a id="p118470"></a>16 15 036 000</td><td></td><td><a id="p118471"></a>UN/LOCODE</td><td></td><td><a id="p118472"></a>an..17</td><td><a id="p118473"></a>N</td><td><a id="p118474"></a>UN/LOCODE as referred to in introductory note 13 number 4.</td></tr>
<tr><td><a id="p118475"></a>16 15 047 000</td><td></td><td><a id="p118476"></a>Customs office</td><td></td><td></td><td><a id="p118477"></a>N</td><td></td></tr>
<tr><td><a id="p118478"></a>16 15 047 001</td><td></td><td></td><td><a id="p118479"></a>Reference number</td><td><a id="p118480"></a>an8</td><td><a id="p118481"></a>N</td><td><a id="p118482"></a>The identifier of the customs office shall follow the structure defined for D.E.<br>17 01 001 000 Reference number</td></tr>
<tr><td><a id="p118483"></a>16 15 048 000</td><td></td><td><a id="p118484"></a>GNSS</td><td></td><td></td><td><a id="p118485"></a>N</td><td></td></tr>
<tr><td><a id="p118486"></a>16 15 048 049</td><td></td><td></td><td><a id="p118487"></a>Latitude</td><td><a id="p118488"></a>an..17</td><td><a id="p118489"></a>N</td><td></td></tr>
<tr><td><a id="p118490"></a>16 15 048 050</td><td></td><td></td><td><a id="p118491"></a>Longitude</td><td><a id="p118492"></a>an..17</td><td><a id="p118493"></a>N</td><td></td></tr>
<tr><td><a id="p118494"></a>16 15 051 000</td><td></td><td><a id="p118495"></a>Economic operator</td><td></td><td></td><td><a id="p118496"></a>N</td><td></td></tr>
<tr><td><a id="p118497"></a>16 15 051 017</td><td></td><td></td><td><a id="p118498"></a>Identification number</td><td><a id="p118499"></a>an..17</td><td><a id="p118500"></a>N</td><td><a id="p118501"></a>The structure of the EORI number is defined in Title II of Annex 12-01.</td></tr>
<tr><td><a id="p118502"></a>16 15 052 000</td><td></td><td><a id="p118503"></a>Authorisation number</td><td></td><td><a id="p118504"></a>an..35</td><td><a id="p118505"></a>N</td><td></td></tr>
<tr><td><a id="p118506"></a>16 15 053 000</td><td></td><td><a id="p118507"></a>Additional identifier</td><td></td><td><a id="p118508"></a>an..4</td><td><a id="p118509"></a>N</td><td></td></tr>
<tr><td><a id="p118510"></a>16 15 018 000</td><td></td><td><a id="p118511"></a>Address</td><td></td><td></td><td><a id="p118512"></a>N</td><td></td></tr>
<tr><td><a id="p118513"></a>16 15 018 019</td><td></td><td></td><td><a id="p118514"></a>Street and number</td><td><a id="p118515"></a>an..70</td><td><a id="p118516"></a>N</td><td></td></tr>
<tr><td><a id="p118517"></a>16 15 018 021</td><td></td><td></td><td><a id="p118518"></a>Postcode</td><td><a id="p118519"></a>an..17</td><td><a id="p118520"></a>N</td><td></td></tr>
<tr><td><a id="p118521"></a>16 15 018 022</td><td></td><td></td><td><a id="p118522"></a>City</td><td><a id="p118523"></a>an..35</td><td><a id="p118524"></a>N</td><td><a id="p118525"></a>GEONOM code as referred to in introductory note 13 number 3.</td></tr>
<tr><td><a id="p118526"></a>16 15 018 020</td><td></td><td></td><td><a id="p118527"></a>Country</td><td><a id="p118528"></a>a2</td><td><a id="p118529"></a>N</td><td></td></tr>
<tr><td><a id="p118530"></a>16 15 081 000</td><td></td><td><a id="p118531"></a>Postcode Address</td><td></td><td></td><td></td><td></td></tr>
<tr><td><a id="p118532"></a>16 15 081 021</td><td></td><td></td><td><a id="p118533"></a>Postcode</td><td><a id="p118534"></a>an..17</td><td><a id="p118535"></a>N</td><td></td></tr>
<tr><td><a id="p118536"></a>16 15 081 025</td><td></td><td></td><td><a id="p118537"></a>House Number</td><td><a id="p118538"></a>an..35</td><td><a id="p118539"></a>N</td><td></td></tr>
<tr><td><a id="p118540"></a>16 15 081 020</td><td></td><td></td><td><a id="p118541"></a>Country</td><td><a id="p118542"></a>a2</td><td><a id="p118543"></a>N</td><td></td></tr>
<tr><td><a id="p118544"></a>16 15 074 000</td><td></td><td><a id="p118545"></a>Contact person</td><td></td><td></td><td><a id="p118546"></a>N</td><td></td></tr>
<tr><td><a id="p118547"></a>16 15 074 016</td><td></td><td></td><td><a id="p118548"></a>Name</td><td><a id="p118549"></a>an..70</td><td><a id="p118550"></a>N</td><td></td></tr>
<tr><td><a id="p118551"></a>16 15 074 075</td><td></td><td></td><td><a id="p118552"></a>Phone number</td><td><a id="p118553"></a>an..35</td><td><a id="p118554"></a>N</td><td></td></tr>
<tr><td><a id="p118555"></a>16 15 074 076</td><td></td><td></td><td><a id="p118556"></a>E-mail address</td><td><a id="p118557"></a>an..256</td><td><a id="p118558"></a>N</td><td></td></tr>
<tr><td><a id="p118559"></a>16 16 000 000</td><td><a id="p118560"></a>Place of acceptance</td><td></td><td></td><td></td><td><a id="p118561"></a>N</td><td></td></tr>
<tr><td><a id="p118562"></a>16 16 036 000</td><td></td><td><a id="p118563"></a>UN/LOCODE</td><td></td><td><a id="p118564"></a>an..17</td><td><a id="p118565"></a>N</td><td><a id="p118566"></a>UN/LOCODE as referred to in introductory note 13 number 4.</td></tr>
<tr><td><a id="p118567"></a>16 16 020 000</td><td></td><td><a id="p118568"></a>Country</td><td></td><td><a id="p118569"></a>a2</td><td><a id="p118570"></a>N</td><td><a id="p118571"></a>Where the place of acceptance is not coded according to the UN/LOCODE, the country where the place of acceptance is located is identified by the GEONOM code as referred to in introductory note 13 number 3.</td></tr>
<tr><td><a id="p118572"></a>16 16 037 000</td><td></td><td><a id="p118573"></a>Location</td><td></td><td><a id="p118574"></a>an..35</td><td><a id="p118575"></a>N</td><td></td></tr>
<tr><td><a id="p118576"></a>16 17 000 000</td><td><a id="p118577"></a>Binding itinerary</td><td></td><td></td><td><a id="p118578"></a>n1</td><td><a id="p118579"></a>Y</td><td></td></tr>
<tr><td><a id="p118580"></a>17 01 000 000</td><td><a id="p118581"></a>Customs office of exit</td><td></td><td></td><td></td><td><a id="p118582"></a>N</td><td></td></tr>
<tr><td><a id="p118583"></a>17 01 001 000</td><td></td><td><a id="p118584"></a>Reference number</td><td></td><td><a id="p118585"></a>an8</td><td><a id="p118586"></a>N</td><td><a id="p118587"></a>The structure of the customs office identifier is defined in Title II.</td></tr>
<tr><td><a id="p118588"></a>17 02 000 000</td><td><a id="p118589"></a>Customs office of export</td><td></td><td></td><td></td><td><a id="p118590"></a>N</td><td></td></tr>
<tr><td><a id="p118591"></a>17 02 001 000</td><td></td><td><a id="p118592"></a>Reference number</td><td></td><td><a id="p118593"></a>an8</td><td><a id="p118594"></a>N</td><td><a id="p118595"></a>The identifier of the customs office shall follow the structure defined for D.E.<br>17 01 001 000 Reference number</td></tr>
<tr><td><a id="p118596"></a>17 03 000 000</td><td><a id="p118597"></a>Customs office of departure</td><td></td><td></td><td></td><td><a id="p118598"></a>N</td><td></td></tr>
<tr><td><a id="p118599"></a>17 03 001 000</td><td></td><td><a id="p118600"></a>Reference number</td><td></td><td><a id="p118601"></a>an8</td><td><a id="p118602"></a>N</td><td><a id="p118603"></a>The identifier of the customs office shall follow the structure defined for D.E.<br>17 01 001 000 Reference number</td></tr>
<tr><td><a id="p118604"></a>17 04 000 000</td><td><a id="p118605"></a>Customs office of transit</td><td></td><td></td><td></td><td><a id="p118606"></a>N</td><td></td></tr>
<tr><td><a id="p118607"></a>17 04 001 000</td><td></td><td><a id="p118608"></a>Reference number</td><td></td><td><a id="p118609"></a>an8</td><td><a id="p118610"></a>N</td><td><a id="p118611"></a>The identifier of the customs office shall follow the structure defined for D.E.<br>17 01 001 000 Reference number</td></tr>
<tr><td><a id="p118612"></a>17 05 000 000</td><td><a id="p118613"></a>Customs office of destination</td><td></td><td></td><td></td><td><a id="p118614"></a>N</td><td></td></tr>
<tr><td><a id="p118615"></a>17 05 001 000</td><td></td><td><a id="p118616"></a>Reference number</td><td></td><td><a id="p118617"></a>an8</td><td><a id="p118618"></a>N</td><td><a id="p118619"></a>The identifier of the customs office shall follow the structure defined for D.E.<br>17 01 001 000 Reference number</td></tr>
<tr><td><a id="p118620"></a>17 06 000 000</td><td><a id="p118621"></a>Customs office of exit for transit</td><td></td><td></td><td></td><td><a id="p118622"></a>N</td><td></td></tr>
<tr><td><a id="p118623"></a>17 06 001 000</td><td></td><td><a id="p118624"></a>Reference number</td><td></td><td><a id="p118625"></a>an8</td><td><a id="p118626"></a>N</td><td><a id="p118627"></a>The identifier of the customs office shall follow the structure defined for D.E.<br>17 01 001 000 Reference number</td></tr>
<tr><td><a id="p118628"></a>17 07 000 000</td><td><a id="p118629"></a>Customs office of first entry</td><td></td><td></td><td></td><td><a id="p118630"></a>N</td><td></td></tr>
<tr><td><a id="p118631"></a>17 07 001 000</td><td></td><td><a id="p118632"></a>Reference number</td><td></td><td><a id="p118633"></a>an8</td><td><a id="p118634"></a>N</td><td><a id="p118635"></a>The identifier of the customs office shall follow the structure defined for D.E.<br>17 01 001 000 Reference number</td></tr>
<tr><td><a id="p118636"></a>17 08 000 000</td><td><a id="p118637"></a>Actual Customs office of first entry</td><td></td><td></td><td></td><td><a id="p118638"></a>N</td><td></td></tr>
<tr><td><a id="p118639"></a>17 08 001 000</td><td></td><td><a id="p118640"></a>Reference number</td><td></td><td><a id="p118641"></a>an8</td><td><a id="p118642"></a>N</td><td><a id="p118643"></a>The identifier of the customs office shall follow the structure defined for D.E.<br>17 01 001 000 Reference number</td></tr>
<tr><td><a id="p118644"></a>17 09 000 000</td><td><a id="p118645"></a>Customs office of presentation</td><td></td><td></td><td></td><td><a id="p118646"></a>N</td><td></td></tr>
<tr><td><a id="p118647"></a>17 09 001 000</td><td></td><td><a id="p118648"></a>Reference number</td><td></td><td><a id="p118649"></a>an8</td><td><a id="p118650"></a>N</td><td><a id="p118651"></a>The identifier of the customs office shall follow the structure defined for D.E.<br>17 01 001 000 Reference<br>number</td></tr>
<tr><td><a id="p118652"></a>17 10 000 000</td><td><a id="p118653"></a>Supervising customs office</td><td></td><td></td><td></td><td><a id="p118654"></a>N</td><td></td></tr>
<tr><td><a id="p118655"></a>17 10 001 000</td><td></td><td><a id="p118656"></a>Reference number</td><td></td><td><a id="p118657"></a>an8</td><td><a id="p118658"></a>N</td><td><a id="p118659"></a>The identifier of the customs office shall follow the structure defined for D.E.<br>17 01 001 000 Reference<br>number</td></tr>
<tr><td><a id="p118660"></a>18 01 000 000</td><td><a id="p118661"></a>Net mass</td><td></td><td></td><td><a id="p118662"></a>n..16,6</td><td><a id="p118663"></a>N</td><td></td></tr>
<tr><td><a id="p118664"></a>18 02 000 000</td><td><a id="p118665"></a>Supplementary units</td><td></td><td></td><td><a id="p118666"></a>n..16,6</td><td><a id="p118667"></a>N</td><td></td></tr>
<tr><td><a id="p118668"></a>18 03 000 000</td><td><a id="p118669"></a>Total gross mass</td><td></td><td></td><td><a id="p118670"></a>n..16,6</td><td><a id="p118671"></a>N</td><td></td></tr>
<tr><td><a id="p118672"></a>18 04 000 000</td><td><a id="p118673"></a>Gross mass</td><td></td><td></td><td><a id="p118674"></a>n..16,6</td><td><a id="p118675"></a>N</td><td></td></tr>
<tr><td><a id="p118676"></a>18 05 000 000</td><td><a id="p118677"></a>Description of goods</td><td></td><td></td><td><a id="p118678"></a>an..512</td><td><a id="p118679"></a>N</td><td></td></tr>
<tr><td><a id="p118680"></a>18 06 000 000</td><td><a id="p118681"></a>Packaging</td><td></td><td></td><td></td><td><a id="p118682"></a>N</td><td></td></tr>
<tr><td><a id="p118683"></a>18 06 003 000</td><td></td><td><a id="p118684"></a>Type of packages</td><td></td><td><a id="p118685"></a>an2</td><td><a id="p118686"></a>N</td><td><a id="p118687"></a>Package type code as referred to in introductory note 13 number 1.</td></tr>
<tr><td><a id="p118688"></a>18 06 004 000</td><td></td><td><a id="p118689"></a>Number of packages</td><td></td><td><a id="p118690"></a>n..8</td><td><a id="p118691"></a>N</td><td></td></tr>
<tr><td><a id="p118692"></a>18 06 054 000</td><td></td><td><a id="p118693"></a>Shipping marks</td><td></td><td><a id="p118694"></a>an..512</td><td><a id="p118695"></a>N</td><td></td></tr>
<tr><td><a id="p118696"></a>18 07 000 000</td><td><a id="p118697"></a>Dangerous goods</td><td></td><td></td><td></td><td><a id="p118698"></a>N</td><td></td></tr>
<tr><td><a id="p118699"></a>18 07 055 000</td><td></td><td><a id="p118700"></a>UN number</td><td></td><td><a id="p118701"></a>an4</td><td><a id="p118702"></a>N</td><td><a id="p118703"></a>UN number as referred to in introductory note 13 number 5.</td></tr>
<tr><td><a id="p118704"></a>18 08 000 000</td><td><a id="p118705"></a>CUS code</td><td></td><td></td><td><a id="p118706"></a>an9</td><td><a id="p118707"></a>N</td><td><a id="p118708"></a>CUS Code as referred to in introductory note 13 number 9</td></tr>
<tr><td><a id="p118709"></a>18 09 000 000</td><td><a id="p118710"></a>Commodity code</td><td></td><td></td><td></td><td><a id="p118711"></a>N</td><td></td></tr>
<tr><td><a id="p118712"></a>18 09 056 000</td><td></td><td><a id="p118713"></a>Harmonized<br>System subheading code</td><td></td><td><a id="p118714"></a>an6</td><td><a id="p118715"></a>N</td><td></td></tr>
<tr><td><a id="p118716"></a>18 09 057 000</td><td></td><td><a id="p118717"></a>Combined nomenclature code</td><td></td><td><a id="p118718"></a>an2</td><td><a id="p118719"></a>N</td><td></td></tr>
<tr><td><a id="p118720"></a>18 09 058 000</td><td></td><td><a id="p118721"></a>TARIC code</td><td></td><td><a id="p118722"></a>an2</td><td><a id="p118723"></a>N</td><td><a id="p118724"></a>To be completed in accordance with the TARIC code (two characters for the application of specific Union measures in respect of formalities to be completed at destination)</td></tr>
<tr><td><a id="p118725"></a>18 09 059 000</td><td></td><td><a id="p118726"></a>TARIC additional code</td><td></td><td><a id="p118727"></a>an4</td><td><a id="p118728"></a>N</td><td><a id="p118729"></a>To be completed in accordance with the TARIC codes (additional codes).</td></tr>
<tr><td><a id="p118730"></a>18 09 060 000</td><td></td><td><a id="p118731"></a>National additional code</td><td></td><td><a id="p118732"></a>an..4</td><td><a id="p118733"></a>N</td><td><a id="p118734"></a>Codes to be adopted by the Member States concerned</td></tr>
<tr><td><a id="p118735"></a>18 10 000 000</td><td><a id="p118736"></a>Type of goods</td><td></td><td></td><td><a id="p118737"></a>a..3</td><td><a id="p118738"></a>N</td><td><a id="p118739"></a>UPU Item nature indication codes as referred to in introductory note 13 number 8</td></tr>
<tr><td><a id="p118740"></a>19 01 000 000</td><td><a id="p118741"></a>Container indicator</td><td></td><td></td><td><a id="p118742"></a>n1</td><td><a id="p118743"></a>Y</td><td></td></tr>
<tr><td><a id="p118744"></a>19 02 000 000</td><td><a id="p118745"></a>Conveyance reference number</td><td></td><td></td><td><a id="p118746"></a>an..17</td><td><a id="p118747"></a>N</td><td></td></tr>
<tr><td><a id="p118748"></a>19 03 000 000</td><td><a id="p118749"></a>Mode of transport at the border</td><td></td><td></td><td><a id="p118750"></a>n1</td><td><a id="p118751"></a>Y</td><td></td></tr>
<tr><td><a id="p118752"></a>19 04 000 000</td><td><a id="p118753"></a>Inland mode of transport</td><td></td><td></td><td><a id="p118754"></a>n1</td><td><a id="p118755"></a>Y</td><td><a id="p118756"></a>The codes provided for in Title II as regards D.E.19 03 000 000 Mode of transport at the border shall be used.</td></tr>
<tr><td><a id="p118757"></a>19 05 000 000</td><td><a id="p118758"></a>Departure transport means</td><td></td><td></td><td></td><td><a id="p118759"></a>N</td><td></td></tr>
<tr><td><a id="p118760"></a>19 05 061 000</td><td></td><td><a id="p118761"></a>Type of identification</td><td></td><td><a id="p118762"></a>n2</td><td><a id="p118763"></a>Y</td><td></td></tr>
<tr><td><a id="p118764"></a>19 05 017 000</td><td></td><td><a id="p118765"></a>Identification number</td><td></td><td><a id="p118766"></a>an..35</td><td><a id="p118767"></a>N</td><td></td></tr>
<tr><td><a id="p118768"></a>19 05 062 000</td><td></td><td><a id="p118769"></a>Nationality</td><td></td><td><a id="p118770"></a>a2</td><td><a id="p118771"></a>N</td><td><a id="p118772"></a>GEONOM code as referred to in introductory note 13 number 3.</td></tr>
<tr><td><a id="p118773"></a>19 06 000 000</td><td><a id="p118774"></a>Arrival transport means</td><td></td><td></td><td></td><td><a id="p118775"></a>-</td><td></td></tr>
<tr><td><a id="p118776"></a>19 06 061 000</td><td></td><td><a id="p118777"></a>Type of identification</td><td></td><td><a id="p118778"></a>n2</td><td><a id="p118779"></a>Y</td><td><a id="p118780"></a>The codes defined in Title II for D.E. 19 05 061 000 Type of identification shall be used for the type of identification.</td></tr>
<tr><td><a id="p118781"></a>19 06 017 000</td><td></td><td><a id="p118782"></a>Identification number</td><td></td><td><a id="p118783"></a>an..35</td><td><a id="p118784"></a>N</td><td></td></tr>
<tr><td><a id="p118785"></a>19 07 000 000</td><td><a id="p118786"></a>Transport<br>Equipment</td><td></td><td></td><td></td><td><a id="p118787"></a>N</td><td></td></tr>
<tr><td><a id="p118788"></a>19 07 063 000</td><td></td><td><a id="p118789"></a>Container identification number</td><td></td><td><a id="p118790"></a>an..17</td><td><a id="p118791"></a>N</td><td></td></tr>
<tr><td><a id="p118792"></a>19 07 044 000</td><td></td><td><a id="p118793"></a>Goods reference</td><td></td><td><a id="p118794"></a>n..5</td><td><a id="p118795"></a>N</td><td></td></tr>
<tr><td><a id="p118796"></a>19 07 064 000</td><td></td><td><a id="p118797"></a>Container size and type identification</td><td></td><td><a id="p118798"></a>an..10</td><td><a id="p118799"></a>Y</td><td></td></tr>
<tr><td><a id="p118800"></a>19 07 065 000</td><td></td><td><a id="p118801"></a>Container packed status</td><td></td><td><a id="p118802"></a>an..3</td><td><a id="p118803"></a>Y</td><td></td></tr>
<tr><td><a id="p118804"></a>19 07 066 000</td><td></td><td><a id="p118805"></a>Container supplier type code</td><td></td><td><a id="p118806"></a>an..3</td><td><a id="p118807"></a>Y</td><td></td></tr>
<tr><td><a id="p118808"></a>19 08 000 000</td><td><a id="p118809"></a>Active border transport means</td><td></td><td></td><td></td><td><a id="p118810"></a>N</td><td></td></tr>
<tr><td><a id="p118811"></a>19 08 061 000</td><td></td><td><a id="p118812"></a>Type of identification</td><td></td><td><a id="p118813"></a>n2</td><td><a id="p118814"></a>Y</td><td><a id="p118815"></a>The codes defined in Title II for D.E. 19 05 061 000 Type of identification shall be used for the type of identification.</td></tr>
<tr><td><a id="p118816"></a>19 08 017 000</td><td></td><td><a id="p118817"></a>Identification number</td><td></td><td><a id="p118818"></a>an..35</td><td><a id="p118819"></a>N</td><td></td></tr>
<tr><td><a id="p118820"></a>19 08 062 000</td><td></td><td><a id="p118821"></a>Nationality</td><td></td><td><a id="p118822"></a>a2</td><td><a id="p118823"></a>N</td><td><a id="p118824"></a>GEONOM code as referred to in introductory note 13 number 3.</td></tr>
<tr><td><a id="p118825"></a>19 08 067 000</td><td></td><td><a id="p118826"></a>Type of means of transport</td><td></td><td><a id="p118827"></a>an..4</td><td><a id="p118828"></a>N</td><td><a id="p118829"></a>Code for type of means of transport as referred to in introductory note 13 number 6.</td></tr>
<tr><td><a id="p118830"></a>19 09 000 000</td><td><a id="p118831"></a>Passive border transport means</td><td></td><td></td><td></td><td><a id="p118832"></a>N</td><td></td></tr>
<tr><td><a id="p118833"></a>19 09 061 000</td><td></td><td><a id="p118834"></a>Type of identification</td><td></td><td><a id="p118835"></a>n2</td><td><a id="p118836"></a>Y</td><td><a id="p118837"></a>The codes defined in Title II for D.E. 1 905 061 000 Type of identification shall be used for the type of identification</td></tr>
<tr><td><a id="p118838"></a>19 09 017 000</td><td></td><td><a id="p118839"></a>Identification number</td><td></td><td><a id="p118840"></a>an..35</td><td><a id="p118841"></a>N</td><td></td></tr>
<tr><td><a id="p118842"></a>19 09 062 000</td><td></td><td><a id="p118843"></a>Nationality</td><td></td><td><a id="p118844"></a>a2</td><td><a id="p118845"></a>N</td><td><a id="p118846"></a>GEONOM code as referred to in introductory note 13 number 3.</td></tr>
<tr><td><a id="p118847"></a>19 09 067 000</td><td></td><td><a id="p118848"></a>Type of means of transport</td><td></td><td><a id="p118849"></a>an..4</td><td><a id="p118850"></a>N</td><td><a id="p118851"></a>Code for type of means of transport as referred to in introductory note 13 number 6.</td></tr>
<tr><td><a id="p118852"></a>19 10 000 000</td><td><a id="p118853"></a>Seal</td><td></td><td></td><td></td><td><a id="p118854"></a>N</td><td></td></tr>
<tr><td><a id="p118855"></a>19 10 068 000</td><td></td><td><a id="p118856"></a>Number of seals</td><td></td><td><a id="p118857"></a>n..4</td><td><a id="p118858"></a>N</td><td></td></tr>
<tr><td><a id="p118859"></a>19 10 015 000</td><td></td><td><a id="p118860"></a>Identifier</td><td></td><td><a id="p118861"></a>an..20</td><td><a id="p118862"></a>N</td><td></td></tr>
<tr><td><a id="p118863"></a>19 11 000 000</td><td><a id="p118864"></a>Receptacle identification number</td><td></td><td></td><td><a id="p118865"></a>an..35</td><td><a id="p118866"></a>N</td><td></td></tr>
<tr><td><a id="p118867"></a>99 01 000 000</td><td><a id="p118868"></a>Quota order number</td><td></td><td></td><td><a id="p118869"></a>an6</td><td><a id="p118870"></a>N</td><td></td></tr>
<tr><td><a id="p118871"></a>99 02 000 000</td><td><a id="p118872"></a>Guarantee type</td><td></td><td></td><td><a id="p118873"></a>an1</td><td><a id="p118874"></a>Y</td><td></td></tr>
<tr><td><a id="p118875"></a>99 03 000 000</td><td><a id="p118876"></a>Guarantee reference</td><td></td><td></td><td></td><td><a id="p118877"></a>N</td><td></td></tr>
<tr><td><a id="p118878"></a>99 03 069 000</td><td></td><td><a id="p118879"></a>GRN</td><td></td><td><a id="p118880"></a>an..24</td><td><a id="p118881"></a>N</td><td></td></tr>
<tr><td><a id="p118882"></a>99 03 070 000</td><td></td><td><a id="p118883"></a>Access code</td><td></td><td><a id="p118884"></a>an..4</td><td><a id="p118885"></a>N</td><td></td></tr>
<tr><td><a id="p118886"></a>99 03 012 000</td><td></td><td><a id="p118887"></a>Currency</td><td></td><td><a id="p118888"></a>a3</td><td><a id="p118889"></a>N</td><td><a id="p118890"></a>Currency code as referred to in introductory note 13 number 2.</td></tr>
<tr><td><a id="p118891"></a>99 03 071 000</td><td></td><td><a id="p118892"></a>Amount to be covered</td><td></td><td><a id="p118893"></a>n..16,2</td><td><a id="p118894"></a>N</td><td></td></tr>
<tr><td><a id="p118895"></a>99 03 072 000</td><td></td><td><a id="p118896"></a>Customs office of guarantee</td><td></td><td><a id="p118897"></a>an8</td><td><a id="p118898"></a>N</td><td><a id="p118899"></a>The identifier of the customs office shall follow the structure defined for D.E.<br>17 01 001 000 Reference number</td></tr>
<tr><td><a id="p118900"></a>99 03 073 000</td><td></td><td><a id="p118901"></a>Other guarantee reference</td><td></td><td><a id="p118902"></a>an..35</td><td><a id="p118903"></a>N</td><td></td></tr>
<tr><td><a id="p118904"></a>99 04 000 000</td><td><a id="p118905"></a>Guarantee not valid in</td><td></td><td></td><td><a id="p118906"></a>a2</td><td><a id="p118907"></a>N</td><td><a id="p118908"></a>GEONOM code as referred to in introductory note 13 number 3.</td></tr>
<tr><td><a id="p118909"></a>99 05 000 000</td><td><a id="p118910"></a>Nature of transaction</td><td></td><td></td><td><a id="p118911"></a>n..2</td><td><a id="p118912"></a>N</td><td><a id="p118913"></a>Code for nature of transaction as referred to in introductory note 13 number 7.</td></tr>
<tr><td><a id="p118914"></a>99 06 000 000</td><td><a id="p118915"></a>Statistical value</td><td></td><td></td><td><a id="p118916"></a>n..16,2</td><td><a id="p118917"></a>N</td><td></td></tr>
</table>


<a id="p118918"></a>**CHAPTER 2**

<a id="p118919"></a>**CARDINALITIES**

<a id="p118920"></a>Cardinalities for Declaration levels


| <a id="p118921"></a>MC | <a id="p118922"></a>1x (per declaration) |
| --- | --- |
| <a id="p118923"></a>MI | <a id="p118924"></a>9,999x (per MC) |
| <a id="p118925"></a>HC | <a id="p118926"></a>99,999x (per MC for entry) |
| <a id="p118927"></a>HC | <a id="p118928"></a>999x (per MC for transit) |
| <a id="p118929"></a>HI | <a id="p118930"></a>9,999x (per HC) |
| <a id="p118931"></a>GS | <a id="p118932"></a>1x (per declaration in export and import) |
| <a id="p118933"></a>GS | <a id="p118934"></a>9,999x (per recapitulative supplementary declaration) |
| <a id="p118935"></a>GS | <a id="p118936"></a>1x (per HC) |
| <a id="p118937"></a>SI | <a id="p118938"></a>9,999x (per GS) |


<a id="p118939"></a>Cardinalities for data classes


| <a id="p118940"></a>Data element/class<br>Data sub-element/sub-class | <a id="p118941"></a>Data element/class name | <a id="p118942"></a>Data sub-element/sub-class name | <a id="p118943"></a>Cardinality<br>Declaration | <a id="p118944"></a>Cardinality MC | <a id="p118945"></a>Cardinality MI | <a id="p118946"></a>Cardinality HC | <a id="p118947"></a>Cardinality HI | <a id="p118948"></a>Cardinality GS | <a id="p118949"></a>Cardinality SI |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| <a id="p118950"></a>11 01 000 000 | <a id="p118951"></a>Declaration type |  | <a id="p118952"></a>1x |  |  |  | <a id="p118953"></a>1x |  |  |
| <a id="p118954"></a>11 02 000 000 | <a id="p118955"></a>Additional declaration type |  | <a id="p118956"></a>1x |  |  |  |  |  |  |
| <a id="p118957"></a>11 03 000 000 | <a id="p118958"></a>Goods item number |  |  |  | <a id="p118959"></a>1x |  | <a id="p118960"></a>1x |  | <a id="p118961"></a>1x |
| <a id="p118962"></a>11 04 000 000 | <a id="p118963"></a>Specific circumstance indicator |  | <a id="p118964"></a>1x |  |  |  |  |  |  |
| <a id="p118965"></a>11 05 000 000 | <a id="p118966"></a>Re-entry indicator |  | <a id="p118967"></a>1x |  |  |  |  |  |  |
| <a id="p118968"></a>11 06 000 000 | <a id="p118969"></a>Split Consignment |  | <a id="p118970"></a>1x |  |  |  |  |  |  |
| <a id="p118971"></a>11 06 001 000 |  | <a id="p118972"></a>Split consignment indicator | <a id="p118973"></a>1x |  |  |  |  |  |  |
| <a id="p118974"></a>11 06 002 000 |  | <a id="p118975"></a>Previous MRN | <a id="p118976"></a>1x |  |  |  |  |  |  |
| <a id="p118977"></a>11 07 000 000 | <a id="p118978"></a>Security |  | <a id="p118979"></a>1x |  |  |  |  |  |  |
| <a id="p118980"></a>11 08 000 000 | <a id="p118981"></a>Reduced dataset indicator |  | <a id="p118982"></a>1x |  |  |  |  |  |  |
| <a id="p118983"></a>11 09 000 000 | <a id="p118984"></a>Procedure |  |  |  |  |  |  |  | <a id="p118985"></a>1x |
| <a id="p118986"></a>11 09 001 000 |  | <a id="p118987"></a>Requested procedure |  |  |  |  |  |  | <a id="p118988"></a>1x |
| <a id="p118989"></a>11 09 002 000 |  | <a id="p118990"></a>Previous procedure |  |  |  |  |  |  | <a id="p118991"></a>1x |
| <a id="p118992"></a>11 10 000 000 | <a id="p118993"></a>Additional procedure |  |  |  |  |  |  |  | <a id="p118994"></a>99x |
| <a id="p118995"></a>12 01 000 000 | <a id="p118996"></a>Previous document |  | <a id="p118997"></a>9,999x | <a id="p118998"></a>9,999x | <a id="p118999"></a>99x | <a id="p119000"></a>99x | <a id="p119001"></a>99x | <a id="p119002"></a>99x | <a id="p119003"></a>99x |
| <a id="p119004"></a>12 01 001 000 |  | <a id="p119005"></a>Reference number | <a id="p119006"></a>1x | <a id="p119007"></a>1x | <a id="p119008"></a>1x | <a id="p119009"></a>1x | <a id="p119010"></a>1x | <a id="p119011"></a>1x | <a id="p119012"></a>1x |
| <a id="p119013"></a>12 01 002 000 |  | <a id="p119014"></a>Type | <a id="p119015"></a>1x | <a id="p119016"></a>1x | <a id="p119017"></a>1x | <a id="p119018"></a>1x | <a id="p119019"></a>1x | <a id="p119020"></a>1x | <a id="p119021"></a>1x |
| <a id="p119022"></a>12 01 003 000 |  | <a id="p119023"></a>Type of packages |  |  | <a id="p119024"></a>1x |  | <a id="p119025"></a>1x |  | <a id="p119026"></a>1x |
| <a id="p119027"></a>12 01 004 000 |  | <a id="p119028"></a>Number of packages |  |  | <a id="p119029"></a>1x |  | <a id="p119030"></a>1x |  | <a id="p119031"></a>1x |
| <a id="p119032"></a>12 01 005 000 |  | <a id="p119033"></a>Measurement unit and qualifier |  |  | <a id="p119034"></a>1x |  | <a id="p119035"></a>1x |  | <a id="p119036"></a>1x |
| <a id="p119037"></a>12 01 006 000 |  | <a id="p119038"></a>Quantity |  |  | <a id="p119039"></a>1x |  | <a id="p119040"></a>1x |  | <a id="p119041"></a>1x |
| <a id="p119042"></a>12 01 079 000 |  | <a id="p119043"></a>Complement of information |  | <a id="p119044"></a>1x |  | <a id="p119045"></a>1x | <a id="p119046"></a>1x |  |  |
| <a id="p119047"></a>12 01 007 000 |  | <a id="p119048"></a>Goods item identifier |  | <a id="p119049"></a>1x | <a id="p119050"></a>1x | <a id="p119051"></a>1x | <a id="p119052"></a>1x |  | <a id="p119053"></a>1x |
| <a id="p119054"></a>12 02 000 000 | <a id="p119055"></a>Additional information |  |  | <a id="p119056"></a>99x | <a id="p119057"></a>99x | <a id="p119058"></a>99x | <a id="p119059"></a>99x | <a id="p119060"></a>99x | <a id="p119061"></a>99x |
| <a id="p119062"></a>12 02 008 000 |  | <a id="p119063"></a>Code |  | <a id="p119064"></a>1x | <a id="p119065"></a>1x | <a id="p119066"></a>1x | <a id="p119067"></a>1x | <a id="p119068"></a>1x | <a id="p119069"></a>1x |
| <a id="p119070"></a>12 02 009 000 |  | <a id="p119071"></a>Text |  | <a id="p119072"></a>1x | <a id="p119073"></a>1x | <a id="p119074"></a>1x | <a id="p119075"></a>1x | <a id="p119076"></a>1x | <a id="p119077"></a>1x |
| <a id="p119078"></a>12 03 000 000 | <a id="p119079"></a>Supporting document |  |  | <a id="p119080"></a>99x | <a id="p119081"></a>99x | <a id="p119082"></a>99x | <a id="p119083"></a>99x | <a id="p119084"></a>99x | <a id="p119085"></a>99x |
| <a id="p119086"></a>12 03 001 000 |  | <a id="p119087"></a>Reference number |  | <a id="p119088"></a>1x | <a id="p119089"></a>1x | <a id="p119090"></a>1x | <a id="p119091"></a>1x | <a id="p119092"></a>1x | <a id="p119093"></a>1x |
| <a id="p119094"></a>12 03 002 000 |  | <a id="p119095"></a>Type |  | <a id="p119096"></a>1x | <a id="p119097"></a>1x | <a id="p119098"></a>1x | <a id="p119099"></a>1x | <a id="p119100"></a>1x | <a id="p119101"></a>1x |
| <a id="p119102"></a>12 03 010 000 |  | <a id="p119103"></a>Issuing Authority name |  |  |  |  |  | <a id="p119104"></a>1x | <a id="p119105"></a>1x |
| <a id="p119106"></a>12 03 005 000 |  | <a id="p119107"></a>Measurement unit and qualifier |  |  |  |  |  |  | <a id="p119108"></a>1x |
| <a id="p119109"></a>12 03 006 000 |  | <a id="p119110"></a>Quantity |  |  |  |  |  |  | <a id="p119111"></a>1x |
| <a id="p119112"></a>12 03 011 000 |  | <a id="p119113"></a>Date of validity |  |  |  |  |  | <a id="p119114"></a>1x | <a id="p119115"></a>1x |
| <a id="p119116"></a>12 03 012 000 |  | <a id="p119117"></a>Currency |  |  |  |  |  |  | <a id="p119118"></a>1x |
| <a id="p119119"></a>12 03 013 000 |  | <a id="p119120"></a>Document Line<br>Item Number |  | <a id="p119121"></a>1x |  |  | <a id="p119122"></a>1x | <a id="p119123"></a>1x | <a id="p119124"></a>1x |
| <a id="p119125"></a>12 03 014 000 |  | <a id="p119126"></a>Amount |  |  |  |  |  |  | <a id="p119127"></a>1x |
| <a id="p119128"></a>12 03 079 000 |  | <a id="p119129"></a>Complement of information |  | <a id="p119130"></a>1x |  |  | <a id="p119131"></a>1x |  |  |
| <a id="p119132"></a>12 04 000 000 | <a id="p119133"></a>Additional reference |  |  | <a id="p119134"></a>99x | <a id="p119135"></a>99x | <a id="p119136"></a>99x | <a id="p119137"></a>99x | <a id="p119138"></a>99x | <a id="p119139"></a>99x |
| <a id="p119140"></a>12 04 001 000 |  | <a id="p119141"></a>Reference number |  | <a id="p119142"></a>1x |  | <a id="p119143"></a>1x | <a id="p119144"></a>1x | <a id="p119145"></a>1x | <a id="p119146"></a>1x |
| <a id="p119147"></a>12 04 002 000 |  | <a id="p119148"></a>Type |  | <a id="p119149"></a>1x | <a id="p119150"></a>1x | <a id="p119151"></a>1x | <a id="p119152"></a>1x | <a id="p119153"></a>1x | <a id="p119154"></a>1x |
| <a id="p119155"></a>12 05 000 000 | <a id="p119156"></a>Transport document |  | <a id="p119157"></a>9,999x | <a id="p119158"></a>99x |  | <a id="p119159"></a>99x |  | <a id="p119160"></a>99x | <a id="p119161"></a>99x |
| <a id="p119162"></a>12 05 001 000 |  | <a id="p119163"></a>Reference number | <a id="p119164"></a>1x | <a id="p119165"></a>1x |  | <a id="p119166"></a>1x |  | <a id="p119167"></a>1x | <a id="p119168"></a>1x |
| <a id="p119169"></a>12 05 002 000 |  | <a id="p119170"></a>Type | <a id="p119171"></a>1x | <a id="p119172"></a>1x |  | <a id="p119173"></a>1x |  | <a id="p119174"></a>1x | <a id="p119175"></a>1x |
| <a id="p119176"></a>12 06 000 000 | <a id="p119177"></a>TIR Carnet number |  | <a id="p119178"></a>1x |  |  |  |  |  |  |
| <a id="p119179"></a>12 07 000 000 | <a id="p119180"></a>Referral request reference |  | <a id="p119181"></a>1x |  |  |  |  |  |  |
| <a id="p119182"></a>12 08 000 000 | <a id="p119183"></a>Reference number/UCR |  |  | <a id="p119184"></a>1x | <a id="p119185"></a>1x | <a id="p119186"></a>1x | <a id="p119187"></a>1x | <a id="p119188"></a>1x | <a id="p119189"></a>1x |
| <a id="p119190"></a>12 09 000 000 | <a id="p119191"></a>LRN |  | <a id="p119192"></a>1x |  |  |  |  |  |  |
| <a id="p119193"></a>12 10 000 000 | <a id="p119194"></a>Deferred payment |  | <a id="p119195"></a>9x |  |  |  |  |  |  |
| <a id="p119196"></a>12 11 000 000 | <a id="p119197"></a>Warehouse |  |  | <a id="p119198"></a>1x |  |  |  | <a id="p119199"></a>lx |  |
| <a id="p119200"></a>12 11 002 000 |  | <a id="p119201"></a>Type |  | <a id="p119202"></a>1x |  |  |  | <a id="p119203"></a>lx |  |
| <a id="p119204"></a>12 11 015 000 |  | <a id="p119205"></a>Identifier |  | <a id="p119206"></a>1x |  |  |  | <a id="p119207"></a>1 |  |
| <a id="p119208"></a>12 12 000 000 | <a id="p119209"></a>Authorisation |  | <a id="p119210"></a>99x |  |  |  |  |  | <a id="p119211"></a>99x |
| <a id="p119212"></a>12 12 002 000 |  | <a id="p119213"></a>Type | <a id="p119214"></a>1x |  |  |  |  |  | <a id="p119215"></a>1x |
| <a id="p119216"></a>12 12 001 000 |  | <a id="p119217"></a>Reference Number | <a id="p119218"></a>1x |  |  |  |  |  | <a id="p119219"></a>1x |
| <a id="p119220"></a>12 12 080 000 |  | <a id="p119221"></a>Holder of authorisation | <a id="p119222"></a>1x |  |  |  |  |  | <a id="p119223"></a>1x |
| <a id="p119224"></a>13 01 000 000 | <a id="p119225"></a>Exporter |  | <a id="p119226"></a>1x |  |  |  |  | <a id="p119227"></a>1x | <a id="p119228"></a>1x |
| <a id="p119229"></a>13 01 016 000 |  | <a id="p119230"></a>Name | <a id="p119231"></a>1x |  |  |  |  | <a id="p119232"></a>1x | <a id="p119233"></a>1x |
| <a id="p119234"></a>13 01 017 000 |  | <a id="p119235"></a>Identification number | <a id="p119236"></a>1x |  |  |  |  | <a id="p119237"></a>1x | <a id="p119238"></a>1x |
| <a id="p119239"></a>13 01 018 000 |  | <a id="p119240"></a>Address | <a id="p119241"></a>1x |  |  |  |  | <a id="p119242"></a>1x | <a id="p119243"></a>1x |
| <a id="p119244"></a>13 02 000 000 | <a id="p119245"></a>Consignor |  |  | <a id="p119246"></a>1x | <a id="p119247"></a>1x | <a id="p119248"></a>1x |  | <a id="p119249"></a>1x | <a id="p119250"></a>1x |
| <a id="p119251"></a>13 02 016 000 |  | <a id="p119252"></a>Name |  | <a id="p119253"></a>1x | <a id="p119254"></a>1x | <a id="p119255"></a>1x |  | <a id="p119256"></a>1x | <a id="p119257"></a>1x |
| <a id="p119258"></a>13 02 017 000 |  | <a id="p119259"></a>Identification number |  | <a id="p119260"></a>1x | <a id="p119261"></a>1x | <a id="p119262"></a>1x |  | <a id="p119263"></a>1x | <a id="p119264"></a>1x |
| <a id="p119265"></a>13 02 028 000 |  | <a id="p119266"></a>Type of person |  | <a id="p119267"></a>1x | <a id="p119268"></a>1x | <a id="p119269"></a>1x |  | <a id="p119270"></a>1x | <a id="p119271"></a>1x |
| <a id="p119272"></a>13 02 018 000 |  | <a id="p119273"></a>Address |  | <a id="p119274"></a>1x | <a id="p119275"></a>1x | <a id="p119276"></a>1x |  | <a id="p119277"></a>1x | <a id="p119278"></a>1x |
| <a id="p119279"></a>13 02 029 000 |  | <a id="p119280"></a>Communication |  | <a id="p119281"></a>9x |  | <a id="p119282"></a>9x |  |  |  |
| <a id="p119283"></a>13 02 074 000 |  | <a id="p119284"></a>Contact person |  | <a id="p119285"></a>9x |  | <a id="p119286"></a>9x | <a id="p119287"></a>9x |  |  |
| <a id="p119288"></a>13 03 000 000 | <a id="p119289"></a>Consignee |  | <a id="p119290"></a>1x | <a id="p119291"></a>1x | <a id="p119292"></a>1x | <a id="p119293"></a>1x | <a id="p119294"></a>1x | <a id="p119295"></a>1x | <a id="p119296"></a>1x |
| <a id="p119297"></a>13 03 016 000 |  | <a id="p119298"></a>Name | <a id="p119299"></a>1x | <a id="p119300"></a>1x | <a id="p119301"></a>1x | <a id="p119302"></a>1x | <a id="p119303"></a>1x | <a id="p119304"></a>1x | <a id="p119305"></a>1x |
| <a id="p119306"></a>13 03 017 000 |  | <a id="p119307"></a>Identification number | <a id="p119308"></a>1x | <a id="p119309"></a>1x | <a id="p119310"></a>1x | <a id="p119311"></a>1x | <a id="p119312"></a>1x | <a id="p119313"></a>1x | <a id="p119314"></a>1x |
| <a id="p119315"></a>13 03 028 000 |  | <a id="p119316"></a>Type of person |  | <a id="p119317"></a>1x |  | <a id="p119318"></a>1x |  |  |  |
| <a id="p119319"></a>13 03 018 000 |  | <a id="p119320"></a>Address | <a id="p119321"></a>1x | <a id="p119322"></a>1x | <a id="p119323"></a>1x | <a id="p119324"></a>1x | <a id="p119325"></a>1x | <a id="p119326"></a>1x | <a id="p119327"></a>1x |
| <a id="p119328"></a>13 03 029 000 |  | <a id="p119329"></a>Communication |  | <a id="p119330"></a>9x |  | <a id="p119331"></a>9x |  |  |  |
| <a id="p119332"></a>13 04 000 000 | <a id="p119333"></a>Importer |  | <a id="p119334"></a>1x |  |  |  |  |  |  |
| <a id="p119335"></a>13 04 016 000 |  | <a id="p119336"></a>Name | <a id="p119337"></a>1x |  |  |  |  |  |  |
| <a id="p119338"></a>13 04 017 000 |  | <a id="p119339"></a>Identification number | <a id="p119340"></a>1x |  |  |  |  |  |  |
| <a id="p119341"></a>13 04 018 000 |  | <a id="p119342"></a>Address | <a id="p119343"></a>1x |  |  |  |  |  |  |
| <a id="p119344"></a>13 05 000 000 | <a id="p119345"></a>Declarant |  | <a id="p119346"></a>1x |  |  |  |  |  |  |
| <a id="p119347"></a>13 05 016 000 |  | <a id="p119348"></a>Name | <a id="p119349"></a>1x |  |  |  |  |  |  |
| <a id="p119350"></a>13 05 017 000 |  | <a id="p119351"></a>Identification number | <a id="p119352"></a>1x |  |  |  |  |  |  |
| <a id="p119353"></a>13 05 018 000 |  | <a id="p119354"></a>Address | <a id="p119355"></a>1x |  |  |  |  |  |  |
| <a id="p119356"></a>13 05 029 000 |  | <a id="p119357"></a>Communication | <a id="p119358"></a>9x |  |  |  |  |  |  |
| <a id="p119359"></a>13 05 074 000 |  | <a id="p119360"></a>Contact person | <a id="p119361"></a>9x |  |  |  |  |  |  |
| <a id="p119362"></a>13 06 000 000 | <a id="p119363"></a>Representative |  | <a id="p119364"></a>1x |  |  |  |  |  |  |
| <a id="p119365"></a>13 06 016 000 |  | <a id="p119366"></a>Name | <a id="p119367"></a>1x |  |  |  |  |  |  |
| <a id="p119368"></a>13 06 017 000 |  | <a id="p119369"></a>Identification number | <a id="p119370"></a>1x |  |  |  |  |  |  |
| <a id="p119371"></a>13 06 030 000 |  | <a id="p119372"></a>Status | <a id="p119373"></a>1x |  |  |  |  |  |  |
| <a id="p119374"></a>13 06 018 000 |  | <a id="p119375"></a>Address | <a id="p119376"></a>1x |  |  |  |  |  |  |
| <a id="p119377"></a>13 06 029 028 |  | <a id="p119378"></a>Communication | <a id="p119379"></a>9x |  |  |  |  |  |  |
| <a id="p119380"></a>13 06 074 000 |  | <a id="p119381"></a>Contact person | <a id="p119382"></a>9x |  |  |  |  |  |  |
| <a id="p119383"></a>13 07 000 000 | <a id="p119384"></a>Holder of the transit procedure |  | <a id="p119385"></a>1x |  |  |  |  |  |  |
| <a id="p119386"></a>13 07 016 000 |  | <a id="p119387"></a>Name | <a id="p119388"></a>1x |  |  |  |  |  |  |
| <a id="p119389"></a>13 07 017 000 |  | <a id="p119390"></a>Identification number | <a id="p119391"></a>1x |  |  |  |  |  |  |
| <a id="p119392"></a>13 07 078 000 |  | <a id="p119393"></a>TIR Holder identification number | <a id="p119394"></a>1x |  |  |  |  |  |  |
| <a id="p119395"></a>13 07 018 000 |  | <a id="p119396"></a>Address | <a id="p119397"></a>1x |  |  |  |  |  |  |
| <a id="p119398"></a>13 07 074 000 |  | <a id="p119399"></a>Contact person | <a id="p119400"></a>1x |  |  |  |  |  |  |
| <a id="p119401"></a>13 08 000 000 | <a id="p119402"></a>Seller |  |  |  |  |  |  | <a id="p119403"></a>1x | <a id="p119404"></a>1x |
| <a id="p119405"></a>13 08 016 000 |  | <a id="p119406"></a>Name |  |  |  |  |  | <a id="p119407"></a>1x | <a id="p119408"></a>1x |
| <a id="p119409"></a>13 08 017 000 |  | <a id="p119410"></a>Identification number |  |  |  |  |  | <a id="p119411"></a>1x | <a id="p119412"></a>1x |
| <a id="p119413"></a>13 08 028 000 |  | <a id="p119414"></a>Type of person |  |  |  |  |  | <a id="p119415"></a>1x | <a id="p119416"></a>1x |
| <a id="p119417"></a>13 08 018 000 |  | <a id="p119418"></a>Address |  |  |  |  |  | <a id="p119419"></a>1x | <a id="p119420"></a>1x |
| <a id="p119421"></a>13 08 029 000 |  | <a id="p119422"></a>Communication |  |  |  |  |  | <a id="p119423"></a>9x |  |
| <a id="p119424"></a>13 09 000 000 | <a id="p119425"></a>Buyer |  |  |  |  |  |  | <a id="p119426"></a>1x | <a id="p119427"></a>1x |
| <a id="p119428"></a>13 09 016 000 |  | <a id="p119429"></a>Name |  |  |  |  |  | <a id="p119430"></a>1x | <a id="p119431"></a>1x |
| <a id="p119432"></a>13 09 017 000 |  | <a id="p119433"></a>Identification number |  |  |  |  |  | <a id="p119434"></a>1x | <a id="p119435"></a>1x |
| <a id="p119436"></a>13 09 028 000 |  | <a id="p119437"></a>Type of person |  |  |  |  |  | <a id="p119438"></a>1x | <a id="p119439"></a>1x |
| <a id="p119440"></a>13 09 018 000 |  | <a id="p119441"></a>Address |  |  |  |  |  | <a id="p119442"></a>1x | <a id="p119443"></a>1x |
| <a id="p119444"></a>13 09 029 000 |  | <a id="p119445"></a>Communication |  |  |  |  |  | <a id="p119446"></a>9x |  |
| <a id="p119447"></a>13 10 000 000 | <a id="p119448"></a>Person notifying the arrival |  | <a id="p119449"></a>1x |  |  |  |  |  |  |
| <a id="p119450"></a>13 10 017 000 |  | <a id="p119451"></a>Identification number | <a id="p119452"></a>1x |  |  |  |  |  |  |
| <a id="p119453"></a>13 10 029 000 |  | <a id="p119454"></a>Communication | <a id="p119455"></a>9x |  |  |  |  |  |  |
| <a id="p119456"></a>13 11 000 000 | <a id="p119457"></a>Person presenting the goods |  | <a id="p119458"></a>1x |  |  |  |  |  |  |
| <a id="p119459"></a>13 11 017 000 |  | <a id="p119460"></a>Identification number | <a id="p119461"></a>1x |  |  |  |  |  |  |
| <a id="p119462"></a>13 12 000 000 | <a id="p119463"></a>Carrier |  |  | <a id="p119464"></a>1x |  | <a id="p119465"></a>1x |  |  |  |
| <a id="p119466"></a>13 12 016 000 |  | <a id="p119467"></a>Name |  | <a id="p119468"></a>1x |  |  |  |  |  |
| <a id="p119469"></a>13 12 017 000 |  | <a id="p119470"></a>Identification number |  | <a id="p119471"></a>1x |  | <a id="p119472"></a>1x |  |  |  |
| <a id="p119473"></a>13 12 018 000 |  | <a id="p119474"></a>Address |  | <a id="p119475"></a>1x |  |  |  |  |  |
| <a id="p119476"></a>13 12 029 000 |  | <a id="p119477"></a>Communication |  | <a id="p119478"></a>9x |  |  |  |  |  |
| <a id="p119479"></a>13 12 074 000 |  | <a id="p119480"></a>Contact person |  | <a id="p119481"></a>9x |  |  |  |  |  |
| <a id="p119482"></a>13 13 000 000 | <a id="p119483"></a>Notify party |  |  | <a id="p119484"></a>1x |  | <a id="p119485"></a>1x |  |  |  |
| <a id="p119486"></a>13 13 016 000 |  | <a id="p119487"></a>Name |  | <a id="p119488"></a>1x |  | <a id="p119489"></a>1x |  |  |  |
| <a id="p119490"></a>13 13 017 000 |  | <a id="p119491"></a>Identification number |  | <a id="p119492"></a>1x |  | <a id="p119493"></a>1x |  |  |  |
| <a id="p119494"></a>13 13 028 000 |  | <a id="p119495"></a>Type of person |  | <a id="p119496"></a>1x |  | <a id="p119497"></a>1x |  |  |  |
| <a id="p119498"></a>13 13 018 000 |  | <a id="p119499"></a>Address |  | <a id="p119500"></a>1x |  | <a id="p119501"></a>1x |  |  |  |
| <a id="p119502"></a>13 13 029 000 |  | <a id="p119503"></a>Communication |  | <a id="p119504"></a>9x |  | <a id="p119505"></a>9x |  |  |  |
| <a id="p119506"></a>13 14 000 000 | <a id="p119507"></a>Additional supply chain actor |  |  | <a id="p119508"></a>99x | <a id="p119509"></a>99x | <a id="p119510"></a>99x | <a id="p119511"></a>99x | <a id="p119512"></a>99x | <a id="p119513"></a>99x |
| <a id="p119514"></a>13 14 031 000 |  | <a id="p119515"></a>Role |  | <a id="p119516"></a>1x | <a id="p119517"></a>1x | <a id="p119518"></a>1x | <a id="p119519"></a>1x | <a id="p119520"></a>1x | <a id="p119521"></a>1x |
| <a id="p119522"></a>13 14 017 000 |  | <a id="p119523"></a>Identification number |  | <a id="p119524"></a>1x | <a id="p119525"></a>1x | <a id="p119526"></a>1x | <a id="p119527"></a>1x | <a id="p119528"></a>1x | <a id="p119529"></a>1x |
| <a id="p119530"></a>13 15 000 000 | <a id="p119531"></a>Supplementary declarant |  |  | <a id="p119532"></a>1x |  | <a id="p119533"></a>1x |  |  |  |
| <a id="p119534"></a>13 15 017 000 |  | <a id="p119535"></a>Identification number |  | <a id="p119536"></a>1x |  | <a id="p119537"></a>1x |  |  |  |
| <a id="p119538"></a>13 15 032 000 |  | <a id="p119539"></a>Supplementary filing type |  | <a id="p119540"></a>1x |  | <a id="p119541"></a>1x |  |  |  |
| <a id="p119542"></a>13 16 000 000 | <a id="p119543"></a>Additional fiscal reference |  |  |  |  |  |  | <a id="p119544"></a>99x | <a id="p119545"></a>99x |
| <a id="p119546"></a>13 16 031 000 |  | <a id="p119547"></a>Role |  |  |  |  |  | <a id="p119548"></a>1x | <a id="p119549"></a>1x |
| <a id="p119550"></a>13 16 034 000 |  | <a id="p119551"></a>VAT identification number |  |  |  |  |  | <a id="p119552"></a>1x | <a id="p119553"></a>1x |
| <a id="p119554"></a>13 17 000 000 | <a id="p119555"></a>Person lodging the customs goods manifest |  | <a id="p119556"></a>1x |  |  |  |  |  |  |
| <a id="p119557"></a>13 17 017 000 |  | <a id="p119558"></a>Identification number | <a id="p119559"></a>1x |  |  |  |  |  |  |
| <a id="p119560"></a>13 18 000 000 | <a id="p119561"></a>Person requesting a proof of the customs status of Union goods |  | <a id="p119562"></a>1x |  |  |  |  |  |  |
| <a id="p119563"></a>13 18 017 000 |  | <a id="p119564"></a>Identification number | <a id="p119565"></a>1x |  |  |  |  |  |  |
| <a id="p119566"></a>13 19 000 000 | <a id="p119567"></a>Person notifyng the arrival of goods following movement under temporary storage |  | <a id="p119568"></a>1x |  |  |  |  |  |  |
| <a id="p119569"></a>13 19 017 000 |  | <a id="p119570"></a>Identification number | <a id="p119571"></a>1x |  |  |  |  |  |  |
| <a id="p119572"></a>13 20 000 000 | <a id="p119573"></a>Person providing a guarantee |  | <a id="p119574"></a>1x |  |  |  |  |  |  |
| <a id="p119575"></a>13 20 017 000 |  | <a id="p119576"></a>Identification number | <a id="p119577"></a>1x |  |  |  |  |  |  |
| <a id="p119578"></a>13 21 000 000 | <a id="p119579"></a>Person paying the customs duty |  | <a id="p119580"></a>1x |  |  |  |  |  |  |
| <a id="p119581"></a>13 21 017 000 |  | <a id="p119582"></a>Identification number | <a id="p119583"></a>1x |  |  |  |  |  |  |
| <a id="p119584"></a>14 01 000 000 | <a id="p119585"></a>Delivery terms |  |  |  |  |  |  | <a id="p119586"></a>1x |  |
| <a id="p119587"></a>14 01 035 000 |  | <a id="p119588"></a>INCOTERM code |  |  |  |  |  | <a id="p119589"></a>1x |  |
| <a id="p119590"></a>14 01 036 000 |  | <a id="p119591"></a>UN/LOCODE |  |  |  |  |  | <a id="p119592"></a>1x |  |
| <a id="p119593"></a>14 01 020 000 |  | <a id="p119594"></a>Country |  |  |  |  |  | <a id="p119595"></a>1x |  |
| <a id="p119596"></a>14 01 037 000 |  | <a id="p119597"></a>Location |  |  |  |  |  | <a id="p119598"></a>1x |  |
| <a id="p119599"></a>14 02 000 000 | <a id="p119600"></a>Transport charges |  |  | <a id="p119601"></a>1x | <a id="p119602"></a>1x | <a id="p119603"></a>1x |  |  |  |
| <a id="p119604"></a>14 02 038 000 |  | <a id="p119605"></a>Method of payment |  | <a id="p119606"></a>1x | <a id="p119607"></a>1x | <a id="p119608"></a>1x |  |  |  |
| <a id="p119609"></a>14 03 000 000 | <a id="p119610"></a>Duties and taxes |  |  |  |  |  |  |  | <a id="p119611"></a>99x |
| <a id="p119612"></a>14 03 039 000 |  | <a id="p119613"></a>Tax type |  |  |  |  |  |  | <a id="p119614"></a>1x |
| <a id="p119615"></a>14 03 038 000 |  | <a id="p119616"></a>Method of payment |  |  |  |  |  |  | <a id="p119617"></a>99x |
| <a id="p119618"></a>14 03 042 000 |  | <a id="p119619"></a>Payable tax amount |  |  |  |  |  |  | <a id="p119620"></a>1x |
| <a id="p119621"></a>14 03 040 000 |  | <a id="p119622"></a>Tax base |  |  |  |  |  |  | <a id="p119623"></a>99x |
| <a id="p119624"></a>14 16 000 000 |  | <a id="p119625"></a>Total duties and taxes amount |  |  |  |  |  |  | <a id="p119626"></a>1x |
| <a id="p119627"></a>14 17 000 000 | <a id="p119628"></a>Internal currency unit |  | <a id="p119629"></a>1x |  |  |  |  |  |  |
| <a id="p119630"></a>14 04 000 000 | <a id="p119631"></a>Additions and deductions |  |  |  |  |  |  | <a id="p119632"></a>99x | <a id="p119633"></a>99x |
| <a id="p119634"></a>14 04 008 000 |  | <a id="p119635"></a>Code |  |  |  |  |  | <a id="p119636"></a>1x | <a id="p119637"></a>1x |
| <a id="p119638"></a>14 04 014 000 |  | <a id="p119639"></a>Amount |  |  |  |  |  | <a id="p119640"></a>1x | <a id="p119641"></a>1x |
| <a id="p119642"></a>14 05 000 000 | <a id="p119643"></a>Invoice currency |  | <a id="p119644"></a>1x |  |  |  |  | <a id="p119645"></a>1x |  |
| <a id="p119646"></a>14 06 000 000 | <a id="p119647"></a>Total amount invoiced |  | <a id="p119648"></a>1x |  |  |  |  | <a id="p119649"></a>1x |  |
| <a id="p119650"></a>14 07 000 000 | <a id="p119651"></a>Valuation indicators |  |  |  |  |  |  |  | <a id="p119652"></a>1x |
| <a id="p119653"></a>14 08 000 000 | <a id="p119654"></a>Item amount invoiced |  |  |  |  |  |  |  | <a id="p119655"></a>1x |
| <a id="p119656"></a>14 09 000 000 | <a id="p119657"></a>Exchange rate |  | <a id="p119658"></a>1x |  |  |  |  |  |  |
| <a id="p119659"></a>14 10 000 000 | <a id="p119660"></a>Valuation method |  |  |  |  |  |  |  | <a id="p119661"></a>1x |
| <a id="p119662"></a>14 11 000 000 | <a id="p119663"></a>Preference |  |  |  |  |  |  |  | <a id="p119664"></a>1x |
| <a id="p119665"></a>14 12 000 000 | <a id="p119666"></a>Postal value |  |  |  |  |  | <a id="p119667"></a>1x |  | <a id="p119668"></a>1x |
| <a id="p119669"></a>14 12 012 000 |  | <a id="p119670"></a>Currency code |  |  |  |  | <a id="p119671"></a>1x |  | <a id="p119672"></a>1x |
| <a id="p119673"></a>14 12 014 000 |  | <a id="p119674"></a>Amount |  |  |  |  | <a id="p119675"></a>1x |  | <a id="p119676"></a>1x |
| <a id="p119677"></a>14 13 000 000 | <a id="p119678"></a>Postal charges |  | <a id="p119679"></a>1x |  |  | <a id="p119680"></a>1x |  |  |  |
| <a id="p119681"></a>14 13 012 000 |  | <a id="p119682"></a>Currency code | <a id="p119683"></a>1x |  |  | <a id="p119684"></a>1x |  |  |  |
| <a id="p119685"></a>14 13 014 000 |  | <a id="p119686"></a>Amount | <a id="p119687"></a>1x |  |  | <a id="p119688"></a>1x |  |  |  |
| <a id="p119689"></a>14 14 000 000 | <a id="p119690"></a>Intrinsic value |  |  |  |  |  |  |  | <a id="p119691"></a>1x |
| <a id="p119692"></a>14 14 012 000 |  | <a id="p119693"></a>Currency code |  |  |  |  |  |  | <a id="p119694"></a>1x |
| <a id="p119695"></a>14 14 014 000 |  | <a id="p119696"></a>Amount |  |  |  |  |  |  | <a id="p119697"></a>1x |
| <a id="p119698"></a>14 15 000 000 | <a id="p119699"></a>Transport and insurance costs to the destination |  |  |  |  |  |  | <a id="p119700"></a>1x | <a id="p119701"></a>1x |
| <a id="p119702"></a>14 15 012 000 |  | <a id="p119703"></a>Currency code |  |  |  |  |  | <a id="p119704"></a>1x | <a id="p119705"></a>1x |
| <a id="p119706"></a>14 15 014 000 |  | <a id="p119707"></a>Amount |  |  |  |  |  | <a id="p119708"></a>1x | <a id="p119709"></a>1x |
| <a id="p119710"></a>15 01 000 000 | <a id="p119711"></a>Estimated date and time of departure |  | <a id="p119712"></a>1x |  |  |  |  |  |  |
| <a id="p119713"></a>15 02 000 000 | <a id="p119714"></a>Actual date and time of departure |  | <a id="p119715"></a>1x |  |  |  |  |  |  |
| <a id="p119716"></a>15 03 000 000 | <a id="p119717"></a>Estimated date and time of arrival |  | <a id="p119718"></a>1x |  |  |  |  |  |  |
| <a id="p119719"></a>15 04 000 000 | <a id="p119720"></a>Estimated date and time of arrival at the port of unloading |  | <a id="p119721"></a>1x | <a id="p119722"></a>1x |  |  |  |  |  |
| <a id="p119723"></a>15 05 000 000 | <a id="p119724"></a>Actual date and time of arrival |  | <a id="p119725"></a>1x |  |  |  |  |  |  |
| <a id="p119726"></a>15 06 000 000 | <a id="p119727"></a>Declaration date |  | <a id="p119728"></a>1x |  |  |  |  |  |  |
| <a id="p119729"></a>15 07 000 000 | <a id="p119730"></a>Requested validity of the proof |  | <a id="p119731"></a>1x |  |  |  |  |  |  |
| <a id="p119732"></a>15 08 000 000 | <a id="p119733"></a>Date and time of presentation of the goods |  | <a id="p119734"></a>1x |  |  |  |  |  |  |
| <a id="p119735"></a>15 09 000 000 | <a id="p119736"></a>Date of acceptance |  |  |  |  |  |  | <a id="p119737"></a>1x | <a id="p119738"></a>1x |
| <a id="p119739"></a>16 02 000 000 | <a id="p119740"></a>Addressed Member State |  | <a id="p119741"></a>1x |  |  |  |  |  |  |
| <a id="p119742"></a>16 02 020 000 |  | <a id="p119743"></a>Country | <a id="p119744"></a>1x |  |  |  |  |  |  |
| <a id="p119745"></a>16 03 000 000 | <a id="p119746"></a>Country of destination |  |  | <a id="p119747"></a>1x |  |  | <a id="p119748"></a>1x | <a id="p119749"></a>1x | <a id="p119750"></a>1x |
| <a id="p119751"></a>16 04 000 000 | <a id="p119752"></a>Region of destination |  |  |  |  |  |  | <a id="p119753"></a>1x | <a id="p119754"></a>1x |
| <a id="p119755"></a>16 05 000 000 | <a id="p119756"></a>Place of delivery |  |  | <a id="p119757"></a>1x |  | <a id="p119758"></a>1x |  |  |  |
| <a id="p119759"></a>16 05 036 000 |  | <a id="p119760"></a>UN/LOCODE |  | <a id="p119761"></a>1x |  | <a id="p119762"></a>1x |  |  |  |
| <a id="p119763"></a>16 05 020 000 |  | <a id="p119764"></a>Country |  | <a id="p119765"></a>1x |  | <a id="p119766"></a>1x |  |  |  |
| <a id="p119767"></a>16 05 037 000 |  | <a id="p119768"></a>Location |  | <a id="p119769"></a>1x |  | <a id="p119770"></a>1x |  |  |  |
| <a id="p119771"></a>16 06 000 000 | <a id="p119772"></a>Country of dispatch |  |  | <a id="p119773"></a>1x |  | <a id="p119774"></a>1x | <a id="p119775"></a>1x | <a id="p119776"></a>1x | <a id="p119777"></a>1x |
| <a id="p119778"></a>16 07 000 000 | <a id="p119779"></a>Country of export |  |  |  |  |  |  | <a id="p119780"></a>1x | <a id="p119781"></a>1x |
| <a id="p119782"></a>16 08 000 000 | <a id="p119783"></a>Country of origin |  |  |  |  |  | <a id="p119784"></a>1x |  | <a id="p119785"></a>1x |
| <a id="p119786"></a>16 09 000 000 | <a id="p119787"></a>Country of preferential origin |  |  |  |  |  |  |  | <a id="p119788"></a>1x |
| <a id="p119789"></a>16 10 000 000 | <a id="p119790"></a>Region of dispatch |  |  |  |  |  |  |  | <a id="p119791"></a>1x |
| <a id="p119792"></a>16 11 000 000 | <a id="p119793"></a>Countries of routing of means of transport |  | <a id="p119794"></a>99x |  |  |  |  |  |  |
| <a id="p119795"></a>16 11 020 000 |  | <a id="p119796"></a>Country | <a id="p119797"></a>1x |  |  |  |  |  |  |
| <a id="p119798"></a>16 12 000 000 | <a id="p119799"></a>Country of routing of consignment |  |  | <a id="p119800"></a>99x |  | <a id="p119801"></a>99x |  |  |  |
| <a id="p119802"></a>16 12 020 000 |  | <a id="p119803"></a>Country |  | <a id="p119804"></a>1x |  | <a id="p119805"></a>1x |  |  |  |
| <a id="p119806"></a>16 13 000 000 | <a id="p119807"></a>Place of loading |  |  | <a id="p119808"></a>1x |  |  |  |  |  |
| <a id="p119809"></a>16 13 036 000 |  | <a id="p119810"></a>UN/LOCODE |  | <a id="p119811"></a>1x |  |  |  |  |  |
| <a id="p119812"></a>16 13 020 000 |  | <a id="p119813"></a>Country |  | <a id="p119814"></a>1x |  |  |  |  |  |
| <a id="p119815"></a>16 13 037 000 |  | <a id="p119816"></a>Location |  | <a id="p119817"></a>1x |  |  |  |  |  |
| <a id="p119818"></a>16 14 000 000 | <a id="p119819"></a>Place of unloading |  |  | <a id="p119820"></a>1x |  |  |  |  |  |
| <a id="p119821"></a>16 14 036 000 |  | <a id="p119822"></a>UN/LOCODE |  | <a id="p119823"></a>1x |  |  |  |  |  |
| <a id="p119824"></a>16 14 020 000 |  | <a id="p119825"></a>Country |  | <a id="p119826"></a>1x |  |  |  |  |  |
| <a id="p119827"></a>16 14 037 000 |  | <a id="p119828"></a>Location |  | <a id="p119829"></a>1x |  |  |  |  |  |
| <a id="p119830"></a>16 15 000 000 | <a id="p119831"></a>Location of goods |  |  | <a id="p119832"></a>1x |  |  |  | <a id="p119833"></a>lx |  |
| <a id="p119834"></a>16 15 045 000 |  | <a id="p119835"></a>Type of location |  | <a id="p119836"></a>1x |  |  |  | <a id="p119837"></a>lx |  |
| <a id="p119838"></a>16 15 046 000 |  | <a id="p119839"></a>Qualifier of identification |  | <a id="p119840"></a>1x |  |  |  | <a id="p119841"></a>1x |  |
| <a id="p119842"></a>16 15 036 000 |  | <a id="p119843"></a>UN/LOCODE |  | <a id="p119844"></a>1x |  |  |  |  |  |
| <a id="p119845"></a>16 15 047 000 |  | <a id="p119846"></a>Customs office |  | <a id="p119847"></a>1x |  |  |  |  |  |
| <a id="p119848"></a>16 15 048 000 |  | <a id="p119849"></a>GNSS |  | <a id="p119850"></a>1x |  |  |  | <a id="p119851"></a>1 |  |
| <a id="p119852"></a>16 15 051 000 |  | <a id="p119853"></a>Economic operator |  | <a id="p119854"></a>1x |  |  |  | <a id="p119855"></a>lx |  |
| <a id="p119856"></a>16 15 052 000 |  | <a id="p119857"></a>Authorisation number |  | <a id="p119858"></a>1x |  |  |  | <a id="p119859"></a>1x |  |
| <a id="p119860"></a>16 15 053 000 |  | <a id="p119861"></a>Additional identifier |  | <a id="p119862"></a>1x |  |  |  | <a id="p119863"></a>1x |  |
| <a id="p119864"></a>16 15 018 000 |  | <a id="p119865"></a>Address |  | <a id="p119866"></a>1x |  |  |  |  |  |
| <a id="p119867"></a>16 15 081 000 |  | <a id="p119868"></a>Postcode Address |  | <a id="p119869"></a>1x |  |  |  |  |  |
| <a id="p119870"></a>16 15 074 000 |  | <a id="p119871"></a>Contact person |  | <a id="p119872"></a>Xx |  |  |  | <a id="p119873"></a>Xx |  |
| <a id="p119874"></a>16 16 000 000 | <a id="p119875"></a>Place of acceptance |  |  | <a id="p119876"></a>1x |  | <a id="p119877"></a>1x |  |  |  |
| <a id="p119878"></a>16 16 036 000 |  | <a id="p119879"></a>UN/LOCODE |  | <a id="p119880"></a>1x |  | <a id="p119881"></a>1x |  |  |  |
| <a id="p119882"></a>16 16 020 000 |  | <a id="p119883"></a>Country |  | <a id="p119884"></a>1x |  | <a id="p119885"></a>1x |  |  |  |
| <a id="p119886"></a>16 16 037 000 |  | <a id="p119887"></a>Location |  | <a id="p119888"></a>1x |  | <a id="p119889"></a>1x |  |  |  |
| <a id="p119890"></a>16 17 000 000 | <a id="p119891"></a>Binding itinerary |  | <a id="p119892"></a>1x |  |  |  |  |  |  |
| <a id="p119893"></a>17 01 000 000 | <a id="p119894"></a>Customs office of exit |  | <a id="p119895"></a>1x |  |  |  |  |  |  |
| <a id="p119896"></a>17 01 001 000 |  | <a id="p119897"></a>Reference number | <a id="p119898"></a>1x |  |  |  |  |  |  |
| <a id="p119899"></a>17 02 000 000 | <a id="p119900"></a>Customs office of export |  | <a id="p119901"></a>1x |  |  |  |  |  |  |
| <a id="p119902"></a>17 02 001 000 |  | <a id="p119903"></a>Reference number | <a id="p119904"></a>1x |  |  |  |  |  |  |
| <a id="p119905"></a>17 03 000 000 | <a id="p119906"></a>Customs office of departure |  | <a id="p119907"></a>1x |  |  |  |  |  |  |
| <a id="p119908"></a>17 03 001 000 |  | <a id="p119909"></a>Reference number | <a id="p119910"></a>1x |  |  |  |  |  |  |
| <a id="p119911"></a>17 04 000 000 | <a id="p119912"></a>Customs office of transit |  | <a id="p119913"></a>9x |  |  |  |  |  |  |
| <a id="p119914"></a>17 04 001 000 |  | <a id="p119915"></a>Reference number | <a id="p119916"></a>1x |  |  |  |  |  |  |
| <a id="p119917"></a>17 05 000 000 | <a id="p119918"></a>Customs office of destination |  | <a id="p119919"></a>1x |  |  |  |  |  |  |
| <a id="p119920"></a>17 05 001 000 |  | <a id="p119921"></a>Reference number | <a id="p119922"></a>1x |  |  |  |  |  |  |
| <a id="p119923"></a>17 06 000 000 | <a id="p119924"></a>Customs office of exit for transit |  | <a id="p119925"></a>9x |  |  |  |  |  |  |
| <a id="p119926"></a>17 06 001 000 |  | <a id="p119927"></a>Reference number | <a id="p119928"></a>1x |  |  |  |  |  |  |
| <a id="p119929"></a>17 07 000 000 | <a id="p119930"></a>Customs office of first entry |  | <a id="p119931"></a>1x |  |  |  |  |  |  |
| <a id="p119932"></a>17 07 001 000 |  | <a id="p119933"></a>Reference number | <a id="p119934"></a>1x |  |  |  |  |  |  |
| <a id="p119935"></a>17 08 000 000 | <a id="p119936"></a>Actual Customs office of first entry |  | <a id="p119937"></a>1x |  |  |  |  |  |  |
| <a id="p119938"></a>17 08 001 000 |  | <a id="p119939"></a>Reference number | <a id="p119940"></a>1x |  |  |  |  |  |  |
| <a id="p119941"></a>17 09 000 000 | <a id="p119942"></a>Customs office of presentation |  | <a id="p119943"></a>1x |  |  |  |  |  |  |
| <a id="p119944"></a>17 09 001 000 |  | <a id="p119945"></a>Reference number | <a id="p119946"></a>1x |  |  |  |  |  |  |
| <a id="p119947"></a>17 10 000 000 | <a id="p119948"></a>Supervising customs office |  | <a id="p119949"></a>1x |  |  |  |  |  |  |
| <a id="p119950"></a>17 10 001 000 |  | <a id="p119951"></a>Reference number | <a id="p119952"></a>1x |  |  |  |  |  |  |
| <a id="p119953"></a>18 01 000 000 | <a id="p119954"></a>Net mass |  |  |  |  |  | <a id="p119955"></a>1x |  | <a id="p119956"></a>1x |
| <a id="p119957"></a>18 02 000 000 | <a id="p119958"></a>Supplementary units |  |  |  |  |  |  |  | <a id="p119959"></a>1x |
| <a id="p119960"></a>18 03 000 000 | <a id="p119961"></a>Total gross mass |  | <a id="p119962"></a>1x | <a id="p119963"></a>1x |  | <a id="p119964"></a>1x |  |  |  |
| <a id="p119965"></a>18 04 000 000 | <a id="p119966"></a>Gross mass |  |  | <a id="p119967"></a>1x | <a id="p119968"></a>1x | <a id="p119969"></a>1x | <a id="p119970"></a>1x | <a id="p119971"></a>1x | <a id="p119972"></a>1x |
| <a id="p119973"></a>18 05 000 000 | <a id="p119974"></a>Description of goods |  |  |  | <a id="p119975"></a>1x |  | <a id="p119976"></a>1x |  | <a id="p119977"></a>1x |
| <a id="p119978"></a>18 06 000 000 | <a id="p119979"></a>Packaging |  |  |  | <a id="p119980"></a>99x |  | <a id="p119981"></a>99x |  | <a id="p119982"></a>99x |
| <a id="p119983"></a>18 06 003 000 |  | <a id="p119984"></a>Type of packages |  |  | <a id="p119985"></a>1x |  | <a id="p119986"></a>1x |  | <a id="p119987"></a>1x |
| <a id="p119988"></a>18 06 004 000 |  | <a id="p119989"></a>Number of packages |  |  | <a id="p119990"></a>1x |  | <a id="p119991"></a>1x |  | <a id="p119992"></a>1x |
| <a id="p119993"></a>18 06 054 000 |  | <a id="p119994"></a>Shipping marks |  |  | <a id="p119995"></a>1x |  | <a id="p119996"></a>1x |  | <a id="p119997"></a>1x |
| <a id="p119998"></a>18 07 000 000 | <a id="p119999"></a>Dangerous goods |  |  |  | <a id="p120000"></a>99x |  | <a id="p120001"></a>99x |  |  |
| <a id="p120002"></a>18 07 055 000 |  | <a id="p120003"></a>UN number |  |  | <a id="p120004"></a>1x |  | <a id="p120005"></a>1x |  |  |
| <a id="p120006"></a>18 08 000 000 | <a id="p120007"></a>CUS code |  |  |  | <a id="p120008"></a>1x |  | <a id="p120009"></a>1x |  | <a id="p120010"></a>1x |
| <a id="p120011"></a>18 09 000 000 | <a id="p120012"></a>Commodity code |  |  |  | <a id="p120013"></a>1x |  | <a id="p120014"></a>1x |  | <a id="p120015"></a>1x |
| <a id="p120016"></a>18 09 056 000 |  | <a id="p120017"></a>Harmonized<br>System subheading code |  |  | <a id="p120018"></a>1x |  | <a id="p120019"></a>1x |  | <a id="p120020"></a>1x |
| <a id="p120021"></a>18 09 057 000 |  | <a id="p120022"></a>Combined nomenclature code |  |  | <a id="p120023"></a>1x |  | <a id="p120024"></a>1x |  | <a id="p120025"></a>1x |
| <a id="p120026"></a>18 09 058 000 |  | <a id="p120027"></a>TARIC code |  |  |  |  |  |  | <a id="p120028"></a>1x |
| <a id="p120029"></a>18 09 059 000 |  | <a id="p120030"></a>TARIC additional code |  |  |  |  |  |  | <a id="p120031"></a>99x |
| <a id="p120032"></a>18 09 060 000 |  | <a id="p120033"></a>National additional code |  |  |  |  |  |  | <a id="p120034"></a>99x |
| <a id="p120035"></a>18 10 000 000 | <a id="p120036"></a>Type of goods |  |  |  |  |  | <a id="p120037"></a>1x |  | <a id="p120038"></a>1x |
| <a id="p120039"></a>19 01 000 000 | <a id="p120040"></a>Container indicator |  |  | <a id="p120041"></a>1x |  | <a id="p120042"></a>1x |  | <a id="p120043"></a>1x |  |
| <a id="p120044"></a>19 02 000 000 | <a id="p120045"></a>Conveyance reference number |  | <a id="p120046"></a>9x |  |  |  |  |  |  |
| <a id="p120047"></a>19 03 000 000 | <a id="p120048"></a>Mode of transport at the border |  | <a id="p120049"></a>1x | <a id="p120050"></a>1x |  |  |  | <a id="p120051"></a>1x |  |
| <a id="p120052"></a>19 04 000 000 | <a id="p120053"></a>Inland mode of transport |  |  | <a id="p120054"></a>1x |  |  |  | <a id="p120055"></a>1x |  |
| <a id="p120056"></a>19 05 000 000 | <a id="p120057"></a>Departure transport means |  |  | <a id="p120058"></a>999x |  | <a id="p120059"></a>999x |  | <a id="p120060"></a>999x |  |
| <a id="p120061"></a>19 05 061 000 |  | <a id="p120062"></a>Type of identification |  | <a id="p120063"></a>1x |  |  |  | <a id="p120064"></a>1x |  |
| <a id="p120065"></a>19 05 017 000 |  | <a id="p120066"></a>Identification number |  | <a id="p120067"></a>1x |  |  |  | <a id="p120068"></a>1x |  |
| <a id="p120069"></a>19 05 062 000 |  | <a id="p120070"></a>Nationality |  | <a id="p120071"></a>1x |  |  |  | <a id="p120072"></a>lx |  |
| <a id="p120073"></a>19 06 000 000 | <a id="p120074"></a>Arrival transport means |  |  | <a id="p120075"></a>1x |  |  |  | <a id="p120076"></a>1x |  |
| <a id="p120077"></a>19 06 061 000 |  | <a id="p120078"></a>Type of identification |  | <a id="p120079"></a>1x |  |  |  | <a id="p120080"></a>1x |  |
| <a id="p120081"></a>19 06 017 000 |  | <a id="p120082"></a>Identification number |  | <a id="p120083"></a>1x |  |  |  | <a id="p120084"></a>1x |  |
| <a id="p120085"></a>19 07 000 000 | <a id="p120086"></a>Transport Equipment |  |  | <a id="p120087"></a>9,999x | <a id="p120088"></a>9,999x | <a id="p120089"></a>9,999x | <a id="p120090"></a>9,999x | <a id="p120091"></a>9,999x |  |
| <a id="p120092"></a>19 07 063 000 |  | <a id="p120093"></a>Container identification number |  | <a id="p120094"></a>1x | <a id="p120095"></a>1x | <a id="p120096"></a>1x | <a id="p120097"></a>1x | <a id="p120098"></a>1x |  |
| <a id="p120099"></a>19 07 044 000 |  | <a id="p120100"></a>Goods reference |  | <a id="p120101"></a>9,999x |  |  |  | <a id="p120102"></a>9,999x |  |
| <a id="p120103"></a>19 07 064 000 |  | <a id="p120104"></a>Container size and type identification |  | <a id="p120105"></a>1x | <a id="p120106"></a>1x | <a id="p120107"></a>1x | <a id="p120108"></a>1x |  |  |
| <a id="p120109"></a>19 07 065 000 |  | <a id="p120110"></a>Container packed status |  | <a id="p120111"></a>1x | <a id="p120112"></a>1x | <a id="p120113"></a>1x | <a id="p120114"></a>1x |  |  |
| <a id="p120115"></a>19 07 066 000 |  | <a id="p120116"></a>Container supplier type code |  | <a id="p120117"></a>1x | <a id="p120118"></a>1x | <a id="p120119"></a>1x | <a id="p120120"></a>1x |  |  |
| <a id="p120121"></a>19 08 000 000 | <a id="p120122"></a>Active border transport means |  | <a id="p120123"></a>1x | <a id="p120124"></a>9x |  |  |  | <a id="p120125"></a>1x |  |
| <a id="p120126"></a>19 08 061 000 |  | <a id="p120127"></a>Type of identification | <a id="p120128"></a>1x | <a id="p120129"></a>1x |  |  |  | <a id="p120130"></a>1x |  |
| <a id="p120131"></a>19 08 017 000 |  | <a id="p120132"></a>Identification number | <a id="p120133"></a>1x | <a id="p120134"></a>1x |  |  |  | <a id="p120135"></a>1x |  |
| <a id="p120136"></a>19 08 062 000 |  | <a id="p120137"></a>Nationality | <a id="p120138"></a>1x | <a id="p120139"></a>1x |  |  |  | <a id="p120140"></a>lx |  |
| <a id="p120141"></a>19 08 067 000 |  | <a id="p120142"></a>Type of means of transport | <a id="p120143"></a>1x |  |  |  |  |  |  |
| <a id="p120144"></a>19 09 000 000 | <a id="p120145"></a>Passive border transport means |  |  | <a id="p120146"></a>999x |  | <a id="p120147"></a>999x | <a id="p120148"></a>999x |  |  |
| <a id="p120149"></a>19 09 061 000 |  | <a id="p120150"></a>Type of identification |  | <a id="p120151"></a>1x |  | <a id="p120152"></a>1x | <a id="p120153"></a>1x |  |  |
| <a id="p120154"></a>19 09 017 000 |  | <a id="p120155"></a>Identification number |  | <a id="p120156"></a>1x |  | <a id="p120157"></a>1x | <a id="p120158"></a>1x |  |  |
| <a id="p120159"></a>19 09 062 000 |  | <a id="p120160"></a>Nationality |  | <a id="p120161"></a>1x |  | <a id="p120162"></a>1x | <a id="p120163"></a>1x |  |  |
| <a id="p120164"></a>19 09 067 000 |  | <a id="p120165"></a>Type of means of transport |  | <a id="p120166"></a>1x |  | <a id="p120167"></a>1x | <a id="p120168"></a>1x |  |  |
| <a id="p120169"></a>19 10 000 000 | <a id="p120170"></a>Seal |  |  | <a id="p120171"></a>99x | <a id="p120172"></a>99x | <a id="p120173"></a>99x | <a id="p120174"></a>99x |  |  |
| <a id="p120175"></a>19 10 068 000 |  | <a id="p120176"></a>Number of seals |  | <a id="p120177"></a>1x <*> | <a id="p120178"></a>1x <*> | <a id="p120179"></a>1x <*> | <a id="p120180"></a>1x <*> |  |  |
| <a id="p120181"></a>19 10 015 000 |  | <a id="p120182"></a>Identifier |  | <a id="p120183"></a>1x | <a id="p120184"></a>1x | <a id="p120185"></a>1x | <a id="p120186"></a>1x |  |  |
| <a id="p120187"></a>19 11 000 000 | <a id="p120188"></a>Receptacle identification number |  |  | <a id="p120189"></a>9,999x |  | <a id="p120190"></a>9,999x |  |  |  |
| <a id="p120191"></a>99 01 000 000 | <a id="p120192"></a>Quota order number |  |  |  |  |  |  |  | <a id="p120193"></a>1x |
| <a id="p120194"></a>99 02 000 000 | <a id="p120195"></a>Guarantee type |  | <a id="p120196"></a>9x |  |  |  |  |  |  |
| <a id="p120197"></a>99 03 000 000 | <a id="p120198"></a>Guarantee reference |  | <a id="p120199"></a>99x |  |  |  |  |  |  |
| <a id="p120200"></a>99 03 069 000 |  | <a id="p120201"></a>GRN | <a id="p120202"></a>1x |  |  |  |  |  |  |
| <a id="p120203"></a>99 03 070 000 |  | <a id="p120204"></a>Access code | <a id="p120205"></a>1x |  |  |  |  |  |  |
| <a id="p120206"></a>99 03 012 000 |  | <a id="p120207"></a>Currency | <a id="p120208"></a>1x |  |  |  |  |  |  |
| <a id="p120209"></a>99 03 071 000 |  | <a id="p120210"></a>Amount to be covered | <a id="p120211"></a>1x |  |  |  |  |  |  |
| <a id="p120212"></a>99 03 072 000 |  | <a id="p120213"></a>Customs office of guarantee | <a id="p120214"></a>1x |  |  |  |  |  |  |
| <a id="p120215"></a>99 03 073 000 |  | <a id="p120216"></a>Other guarantee reference | <a id="p120217"></a>1x |  |  |  |  |  |  |
| <a id="p120218"></a>99 04 000 000 | <a id="p120219"></a>Guarantee not valid in |  | <a id="p120220"></a>99x |  |  |  |  |  |  |
| <a id="p120221"></a>99 05 000 000 | <a id="p120222"></a>Nature of transaction |  |  |  |  |  |  | <a id="p120223"></a>1x | <a id="p120224"></a>1x |
| <a id="p120225"></a>99 06 000 000 | <a id="p120226"></a>Statistical value |  |  |  |  |  |  |  | <a id="p120227"></a>1x |


<a id="p120228"></a>

---

<a id="p120229"></a><*> The cardinality for the Number of seals has to be understood in relation to the transport equipment, i.e. 1x per container.

<a id="p120230"></a>**TITLE II. CODES IN RELATION WITH THE COMMON DATA**
**REQUIREMENTS FOR DECLARATIONS AND NOTIFICATIONS**

<a id="p120231"></a>**(1) INTRODUCTION:**

<a id="p120232"></a>This Title contains the codes to be used on electronic declarations and notifications.

<a id="p120233"></a>**(2) CODES:**

<a id="p120234"></a>11 01 000 000 Declaration type


| <a id="p120235"></a>Code | <a id="p120236"></a>Description | <a id="p120237"></a>Dataset in the data requirements table in Title I of Annex B to Delegated Regulation (EU) 2015/2446 |
| --- | --- | --- |
| <a id="p120238"></a>C | <a id="p120239"></a>Union goods not placed under a transit procedure | <a id="p120240"></a>D3 |
| <a id="p120241"></a>CO | <a id="p120242"></a>Union goods subject to specific measures during the transitional period following the accession of new Member States.<br>Placing of Union goods under the customs warehousing procedure referred to in column B3 of the data requirements table in Title I of Annex B to Delegated Regulation (EU) 2015/2446 in order to obtain payment of special export refunds prior to exportation or manufacturing under customs supervision and under customs control prior to exportation and payment of export refunds.<br>Union goods in the context of trade between parts of the customs territory of the Union to which the provisions of Council Directive 2006/112/EC <*> or Council Directive 2008/118/EC <**> are applicable and parts of that territory to which those provisions do not apply, or in the context of trade between parts of that territory where those provisions do not apply as referred to in columns B4 and H5 of the data requirements table in Title I of Annex B to Delegated Regulation (EU) 2015/2446. | <a id="p120243"></a>B3, B4, H1, H5, I1 |
| <a id="p120244"></a>EX | <a id="p120245"></a>For trade with countries and territories situated outside of the customs territory of the Union.<br>For placing goods under a customs procedure referred to in columns B1, B2 and C1 and for re-export referred to in column B1 of the data requirements table in Title I of Annex B to Delegated Regulation (EU) 2015/2446. | <a id="p120246"></a>B1, B2, C1 |
| <a id="p120247"></a>IM | <a id="p120248"></a>For trade with countries and territories situated outside of the customs territory of the Union.<br>For placing goods under a customs procedure referred to in columns H1 to H4, H6 and I1 of the data requirements table in Title I of Annex B to Delegated Regulation (EU) 2015/2446.<br>For placing non-Union goods under a customs procedure in the context of trade between Member States. | <a id="p120249"></a>H1, H2, H3, H4, H5, H6, H7, I1 |
| <a id="p120250"></a>T | <a id="p120251"></a>Mixed consignments comprising both goods which are to be placed under the external Union transit procedure and goods which are to be placed under the internal Union transit procedure, covered by Article 294 of this Regulation | <a id="p120252"></a>D1, D2, D3 |
| <a id="p120253"></a>T1 | <a id="p120254"></a>Goods placed under the external Union transit procedure | <a id="p120255"></a>D1, D2, D3 |
| <a id="p120256"></a>T2 | <a id="p120257"></a>Goods placed under the internal Union transit procedure in accordance with Article 227 of the Code, unless Article 293(2) applies | <a id="p120258"></a>D1, D2, D3 |
| <a id="p120259"></a>T2F | <a id="p120260"></a>Goods placed under the internal Union transit procedure, in accordance with Article 188 of Delegated Regulation (EU) 2015/2446 | <a id="p120261"></a>D1, D2, D3 |
| <a id="p120262"></a>T2L | <a id="p120263"></a>Proof establishing the customs status of Union goods | <a id="p120264"></a>E1, E2 |
| <a id="p120265"></a>T2LF | <a id="p120266"></a>Proof establishing the customs status of Union goods consigned to, from or between special fiscal territories | <a id="p120267"></a>E1, E2 |
| <a id="p120268"></a>T2LSM | <a id="p120269"></a>Proof establishing the status of goods destined for San Marino in application of Article 2 of Decision 4/92 of the EEC-San Marino Cooperation Committee of 22 December 1992 | <a id="p120270"></a>E1 |
| <a id="p120271"></a>T2SM | <a id="p120272"></a>Goods placed under the internal Union transit procedure, in application of Article 2 of Decision 4/92 of the EEC-San Marino Co-operation Committee of 22 December 1992 | <a id="p120273"></a>D1, D2 |
| <a id="p120274"></a>TD | <a id="p120275"></a>Goods already placed under a transit procedure, or carried under the inward processing, customs warehouse or temporary admission procedure in the context of the application of Article 233(4) of the Code | <a id="p120276"></a>D3 |
| <a id="p120277"></a>TIR | <a id="p120278"></a>Goods placed under the TIR (Transport Internationaux Routiers) procedure | <a id="p120279"></a>D1, D2 |
| <a id="p120280"></a>X | <a id="p120281"></a>Union goods to be exported, not placed under a transit procedure in the context of the application of Article 233(4)(e) of the Code | <a id="p120282"></a>D3 |


<a id="p120283"></a>

---

<a id="p120284"></a><*> Council Directive 2006/112/EC of 28 November 2006 on the common system of value added tax (OJ L 347, 11.12.2006, p. 1).
<a id="p120285"></a><**> Council Directive 2008/118/EC of 16 December 2008 concerning the general arrangements for excise duty and repealing Directive 92/12/EEC (OJ L 9, 14.1.2009, p. 12).

<a id="p120286"></a>11 02 000 000 Additional declaration type
<a id="p120287"></a>A for a standard customs declaration (under Article 162 of the Code)
<a id="p120288"></a>B for a simplified declaration on occasional basis (under Article 166(1) of the Code
<a id="p120289"></a>C for a simplified customs declaration with regular use (under Article 166(2) of the Code)
<a id="p120290"></a>D for lodging a standard customs declaration (such as referred to under code A) in accordance with Article 171 of the Code
<a id="p120291"></a>E for lodging a simplified declaration (such as referred to under code B) in accordance with Article 171 of the Code
<a id="p120292"></a>F for lodging a simplified declaration (such as referred to under code C) in accordance with Article 171 of the Code
<a id="p120293"></a>R Retrospective lodgement of an export or re-export declaration in accordance with Article 249 of Delegated Regulation (EU) 2015/2446 and Article 337 of Implementing Regulation (EU) 2015/2447)
<a id="p120294"></a>X for a supplementary declaration of simplified declarations covered by B and E
<a id="p120295"></a>Y for a supplementary declaration of general or periodic nature of simplified declarations covered by C and F
<a id="p120296"></a>Z for a supplementary declaration of general or periodic nature under the procedure covered under Article 182 of the Code
<a id="p120297"></a>U for a supplementary recapitulative declaration of simplified declarations covered by C and F
<a id="p120298"></a>V for a supplementary recapitulative declaration under the procedure covered under Article 182 of the Code

<a id="p120299"></a>11 04 000 000 Specific circumstance indicator
<a id="p120300"></a>The following codes shall be used:


| <a id="p120301"></a>Codes | <a id="p120302"></a>Description |
| --- | --- |
| <a id="p120303"></a>A20 | <a id="p120304"></a>Exit summary declaration - Express consignments |
| <a id="p120305"></a>F10 | <a id="p120306"></a>Sea and inland waterways - Complete dataset - Straight bill of lading containing the necessary information from consignee |
| <a id="p120307"></a>F11 | <a id="p120308"></a>Sea and inland waterways - Complete dataset - Master bill of lading with underlying house bill(s) of lading containing the necessary information from consignee at the level of the lowest house bill of lading |
| <a id="p120309"></a>F12 | <a id="p120310"></a>Sea and inland waterways - Partial dataset - Master bill of lading only |
| <a id="p120311"></a>F13 | <a id="p120312"></a>Sea and inland waterways - Partial dataset - Straight bill of lading only |
| <a id="p120313"></a>F14 | <a id="p120314"></a>Sea and inland waterways - Partial dataset - House bill of lading only |
| <a id="p120315"></a>F15 | <a id="p120316"></a>Sea and inland waterways - Partial dataset - House bill of lading with the necessary information from consignee |
| <a id="p120317"></a>F16 | <a id="p120318"></a>Sea and inland waterways - Partial dataset - Necessary information required to be provided by consignee at the lowest level of transport contract (Lowest house bill of lading where the master bill of lading is no straight bill of lading) |
| <a id="p120319"></a>F20 | <a id="p120320"></a>Air cargo (general) - Complete dataset lodged pre-loading |
| <a id="p120321"></a>F21 | <a id="p120322"></a>Air cargo (general) - Partial dataset - Master air waybill lodged pre-arrival |
| <a id="p120323"></a>F22 | <a id="p120324"></a>Air cargo (general) - Partial dataset - House air waybill lodged pre-arrival - Partial dataset provided by a person pursuant to Article 127(6) of the Code and in accordance with Article 113(1) of Delegated Regulation (EU) 2015/2446 |
| <a id="p120325"></a>F23 | <a id="p120326"></a>Air cargo (general) - Partial dataset - Minimum dataset lodged pre-loading in accordance with Article 106(1) second subparagraph of Delegated Regulation (EU) 2015/2446 without master air waybill reference number |
| <a id="p120327"></a>F24 | <a id="p120328"></a>Air cargo (general) - Partial dataset - Minimum dataset lodged pre-loading in accordance with Article 106(1) second subparagraph of Delegated Regulation (EU) 2015/2446 with master air waybill reference number |
| <a id="p120329"></a>F25 | <a id="p120330"></a>Air cargo (general) - Partial dataset - Master air waybill reference number lodged pre-loading in accordance with Article 106(1) second subparagraph of Delegated Regulation (EU) 2015/2446 |
| <a id="p120331"></a>F26 | <a id="p120332"></a>Air cargo (general) - Partial dataset - Minimum dataset lodged pre-loading in accordance with Article 106(1) second subparagraph of Delegated Regulation (EU) 2015/2446 and containing additional house air waybill information |
| <a id="p120333"></a>F27 | <a id="p120334"></a>Air cargo (general) - Complete dataset lodged pre-arrival |
| <a id="p120335"></a>F28 | <a id="p120336"></a>Air cargo (general) - Complete dataset lodged pre-loading - Direct air waybill |
| <a id="p120337"></a>F29 | <a id="p120338"></a>Air cargo (general) - Complete dataset lodged pre-arrival - Direct air waybill |
| <a id="p120339"></a>F30 | <a id="p120340"></a>Express consignments - Complete dataset lodged pre-arrival |
| <a id="p120341"></a>F31 | <a id="p120342"></a>Express consignments on air cargo general - Complete dataset lodged pre-arrival by the express operator |
| <a id="p120343"></a>F32 | <a id="p120344"></a>Entry summary declaration - Express consignments - Minimum dataset to be lodged pre-loading in relation with situations defined in Article 106(1) second subparagraph |
| <a id="p120345"></a>F33 | <a id="p120346"></a>Express consignment on air cargo general - Partial dataset - House air waybill lodged pre-arrival - Partial dataset provided by a person pursuant to Article 127(6) of the Code and in accordance with Article 113(1) of Delegated Regulation (EU) 2015/2446 |
| <a id="p120347"></a>F40 | <a id="p120348"></a>Postal consignments - Partial dataset - Road master transport document information |
| <a id="p120349"></a>F41 | <a id="p120350"></a>Postal consignments - Partial dataset - Rail master transport document information |
| <a id="p120351"></a>F42 | <a id="p120352"></a>Postal consignments - Partial dataset - Master air waybill containing necessary postal air waybill information lodged in accordance with the time-limits applicable for the mode of transport concerned |
| <a id="p120353"></a>F43 | <a id="p120354"></a>Postal consignments - Partial dataset - Minimum dataset lodged pre-loading in accordance with Article 106(1) second subparagraph and in accordance with Article 113(2) of Delegated Regulation (EU) 2015/2446 |
| <a id="p120355"></a>F44 | <a id="p120356"></a>Postal consignment - Partial dataset - Receptacle identification number lodged preloading in accordance with Article 106(1) second subparagraph and in accordance with Article 113(2) of Delegated Regulation (EU) 2015/2446 |
| <a id="p120357"></a>F45 | <a id="p120358"></a>Postal consignment - Partial dataset - Master bill of lading only |
| <a id="p120359"></a>F50 | <a id="p120360"></a>Road mode of transport |
| <a id="p120361"></a>F51 | <a id="p120362"></a>Rail mode of transport |
| <a id="p120363"></a>G4 | <a id="p120364"></a>Temporary storage declaration |
| <a id="p120365"></a>G5 | <a id="p120366"></a>Arrival notification in case of movement of goods under temporary storage |


<a id="p120367"></a>11 05 000 000 Re-entry indicator
<a id="p120368"></a>The relevant codes are given below:
<a id="p120369"></a>0 No (Entry summary declaration lodged for goods which enter into the customs territory of the Union for the first time)
<a id="p120370"></a>1 Yes (Entry summary declaration lodged for goods which re-enter into the customs territory of the Union after having exited it)

<a id="p120371"></a>11 06 001 000 Split consignment indicator
<a id="p120372"></a>The relevant codes are given below:
<a id="p120373"></a>0 No (Entry summary declaration lodged for full Master consignment)
<a id="p120374"></a>1 Yes (Entry summary declaration lodged for split Master consignment)

<a id="p120375"></a>11 07 000 000 Security
<a id="p120376"></a>The relevant codes are given below:


| <a id="p120377"></a>Code | <a id="p120378"></a>Description | <a id="p120379"></a>Explanation |
| --- | --- | --- |
| <a id="p120380"></a>0 | <a id="p120381"></a>No | <a id="p120382"></a>Declaration is not combined with Exit summary declaration or Entry summary declaration |
| <a id="p120383"></a>1 | <a id="p120384"></a>ENS | <a id="p120385"></a>Declaration is combined with Entry summary declaration |
| <a id="p120386"></a>2 | <a id="p120387"></a>EXS | <a id="p120388"></a>Declaration is combined with Exit summary declaration |
| <a id="p120389"></a>3 | <a id="p120390"></a>ENS and EXS | <a id="p120391"></a>Declaration is combined with Exit summary declaration and Entry summary declaration |


<a id="p120392"></a>11 08 000 000 Reduced dataset indicator
<a id="p120393"></a>The relevant codes are given below:
<a id="p120394"></a>0 No (Goods are not declared using a reduced data set)
<a id="p120395"></a>1 Yes (Goods are declared using a reduced data set)

<a id="p120396"></a>11 09 000 000 Procedure
<a id="p120397"></a>The codes to be entered in this subdivision are four-digit codes, composed of a two-digit code representing the procedure requested, followed by a second two-digit code representing the previous procedure. The list of two-digit codes is given below.
<a id="p120398"></a>"Previous procedure" means the procedure under which the goods were placed before being placed under the procedure requested.
<a id="p120399"></a>It should be noted that where the previous procedure is customs warehousing or temporary admission, or where the goods have come from a free zone, the relevant code should be used only where the goods have not been placed under inward or outward processing or end-use.
<a id="p120400"></a>For example: re-export of goods imported under inward processing and subsequently placed under customs warehousing = 3151 (not 3171). (First operation = 5100; second operation = 7151; third operation re-export = 3151).
<a id="p120401"></a>Similarly, where goods previously temporarily exported are re-imported and released for free circulation after having been placed under customs warehousing, temporary admission or in a free zone this is regarded as simple re-importation after temporary export.
<a id="p120402"></a>For example: entry for home use with simultaneous entry for free circulation of goods exported under outward processing and placed under customs warehousing upon re-importation = 6121 (not 6171). (First operation: temporary export under outward processing = 2100; second operation: storage in a customs warehouse = 7121; third operation: entry for home use + entry for free circulation = 6121).
<a id="p120403"></a>The codes marked in the list below with the letter (a) cannot be used as the first two digits of the procedure code, but only to indicate the previous procedure.
<a id="p120404"></a>For example: 4054 = entry for free circulation and home use of goods previously placed under inward processing in another Member State.

<a id="p120405"></a>List of procedures for coding purposes
<a id="p120406"></a>Two of these basic elements must be combined to produce a four-digit code.
<a id="p120407"></a>00 This code is used to indicate that there is no previous procedure (a)
<a id="p120408"></a>01 Release for free circulation of goods simultaneously redispatched in the context of trade between parts of the customs territory of the Union in which the provisions of Directive 2006/112/EC or Directive 2008/118/EC are applicable and parts of that territory in which those provisions do not apply, or in the context of trade between the parts of that territory where those provisions do not apply
<a id="p120409"></a>Example: Non-Union goods arriving from a third country released for free circulation in Germany and sent on to the Canary Islands.
<a id="p120410"></a>07 Release of goods for free circulation simultaneously placed under a warehousing procedure other than a customs warehousing procedure where neither VAT nor, when applicable, excise duties have been paid.
<a id="p120411"></a>Explanation: This code is to be used where the goods are released for free circulation but where VAT and excise duties have not been paid.
<a id="p120412"></a>Examples: Imported raw sugar is released for free circulation but VAT has not been paid. While the goods are placed in a warehouse or approved area other than customs warehouse, payment of the VAT is suspended.
<a id="p120413"></a>Imported mineral oils are released for free circulation and no VAT has been paid. While the goods are stored in a tax warehouse, payment of VAT and excise duties is suspended.
<a id="p120414"></a>10 Permanent export.
<a id="p120415"></a>Example: Export of Union goods to a third country, but also dispatch of Union goods to parts of the customs territory of the Union to which the provisions of Directive 2006/112/EC or Directive 2008/118/EC do not apply.
<a id="p120416"></a>11 Export of processed products obtained from equivalent goods under inward processing before placing non-Union goods under inward processing.
<a id="p120417"></a>Explanation: Prior export (EX-IM) in accordance with Art. 223(2)(c) of the Code.
<a id="p120418"></a>Example: Export of cigarettes manufactured from Union tobacco leaves before placing of non-Union tobacco leaves under inward processing.
<a id="p120419"></a>21 Temporary export under the outward processing procedure, if not covered by code 22.
<a id="p120420"></a>Example: Outward processing procedure under Articles 259 to 262 of the Code. The simultaneous application to textile products of the outward processing procedure and the economic outward processing procedure (Council Regulation (EC) No 3036/94) is not covered by this code.
<a id="p120421"></a>22 Temporary export other than that referred to under code 21 and 23.
<a id="p120422"></a>This code covers the following situations:
- <a id="p120423"></a>The simultaneous application to textile products of the outward processing procedure and the economic outward processing procedure (Council Regulation (EC) No 3036/94 <*>).

<a id="p120424"></a>

---

<a id="p120425"></a><*> Council Regulation (EC) No 3036/94 of 8 December 1994 establishing economic outward processing arrangements applicable to certain textiles and clothing products reimported into the Community after working or processing in certain third countries (OJ L 322, 15.12.1994, p. 1).

- <a id="p120426"></a>Temporary export of goods from the Union for repair, processing, adaptation, making up or re-working where no customs duties will be due at re-importation.
<a id="p120427"></a>23 Temporary export for return in the unaltered state.
<a id="p120428"></a>Example: Temporary export for exhibitions of articles such as samples, professional equipment, etc.
<a id="p120429"></a>31 Re-export.
<a id="p120430"></a>Explanation: Re-export of non-Union goods following a special procedure.
<a id="p120431"></a>Example: Goods are placed under customs warehousing and subsequently declared for re-export.
<a id="p120432"></a>40 Simultaneous release for free circulation and home use of goods.
<a id="p120433"></a>Entry for home use of goods in the context of trade between the Union and the countries with which it has formed a customs union.
<a id="p120434"></a>Entry for home use of goods in the context of trade referred to in Article 1(3) of the code.
<a id="p120435"></a>Examples:
- <a id="p120436"></a>Goods coming from Japan with payment of customs duty, VAT and when applicable excise duties.
- <a id="p120437"></a>Goods coming from Andorra and entered for home use in Germany.
- <a id="p120438"></a>Goods arriving from Martinique and entered for home use in Belgium.
<a id="p120439"></a>42 Simultaneous release for free circulation and home use of goods which are the subject of a VAT-exempt supply to another Member State and, when applicable, an excise-duty suspension.
<a id="p120440"></a>Entry for home use of Union goods, in the context of trade between parts of the customs territory of the Union in which the provisions of Directive 2006/112/EC and Directive 2008/118/EC are not applicable and parts of that territory in which those provisions are applicable, which are the subject of a VAT-exempt supply to another Member State and, when applicable, an excise duty suspension.
<a id="p120441"></a>Explanation: Exemption from payment of VAT and, where applicable, the excise duty suspension, is granted because the import is followed by intra-Union supply or transfer of the goods to another Member State. In that case the VAT and, where applicable, the excise duty will be due in the Member State of final destination. In order to use this procedure, the persons must meet other conditions listed in in Article 143(2) of Directive 2006/112/EC and, where applicable, the conditions listed in Article 17(1)(b) of Directive 2008/118/EC. The information required by Article 143 (2) of Directive 2006/112/EC shall be entered in D.E.13 16 034 000 VAT identification number.
<a id="p120442"></a>Examples: Non-Union goods are released for free circulation in one Member State and are the subject of a VAT-exempt supply to another Member State. The VAT formalities are dealt with by a customs agent who is a tax representative using the intra-Union VAT system.
<a id="p120443"></a>Non-Union goods subject to excise duties imported from a third country, which are released for free circulation and are the subject of a VAT-exempt supply to another Member State. The release for free circulation is immediately followed by a movement under excise duty suspension from the place of importation initiated by a registered consignor in accordance with Article 17(1)(b) of Directive 2008/118/EC.
<a id="p120444"></a>43 Simultaneous release for free circulation and home use of goods subject to specific measures connected with the collection of an amount during the transitional period following the accession of new Member States.
<a id="p120445"></a>Example: Release for free circulation of agricultural products subject, during a special transitional period following the accession of new Member States, to a special customs procedure or special measures between the new Member States and the rest of the Union.
<a id="p120446"></a>44 End-use
<a id="p120447"></a>Release for free circulation and home use under a duty exemption or at a reduced rate of duty on account of their specific use.
<a id="p120448"></a>Example: Release for free circulation of non-Union engines for integration into a civil aircraft built in the European Union.
<a id="p120449"></a>Non-union goods for integration in certain categories of ships, boats and other vessels and for drilling or production platforms.
<a id="p120450"></a>45 Release of goods for free circulation and partial entry for home use for either VAT or excise duties and their placing in a warehouse other than customs warehouses.
<a id="p120451"></a>Explanation: This code is to be used for goods which are subjected to both VAT and excise duties and where only one of these categories of taxes are paid when the goods are released for free circulation.
<a id="p120452"></a>Examples: Non-Union cigarettes are released for free circulation and VAT has been paid. While the goods are in the tax warehouse, the payment of excise duties is suspended.
<a id="p120453"></a>Excise goods imported from a third country or from a third territory referred to in Article 5(3) of Directive 2008/118/EC are released for free circulation. The release for free circulation is immediately followed by a movement under excise duty suspension initiated by a registered consignor at the place of importation, in accordance with Article 17(1)(b) of Directive 2008/118/EC, to a tax warehouse in the same Member State.
<a id="p120454"></a>46 Import of processed products obtained from equivalent goods under the outward-processing procedure before exportation of goods they are replacing.
<a id="p120455"></a>Explanation: Prior import in accordance with Article 223(2)d) of the Code.
<a id="p120456"></a>Example: Import of tables manufactured from non-Union wood before placing Union wood under outward processing.
<a id="p120457"></a>48 Entry for home use with simultaneous release for free circulation of replacement products under outward processing prior to the export of the defective goods.
<a id="p120458"></a>Explanation: Standard exchange system (IM-EX), prior importation in accordance with Article 262(1) of the Code.
<a id="p120459"></a>51 Placing goods under inward processing procedure.
<a id="p120460"></a>Explanation: Inward processing in accordance with Article 256 of the Code.
<a id="p120461"></a>53 Placing of goods under temporary admission.
<a id="p120462"></a>Explanation: Placing of non-Union goods intended for re-export under the temporary admission procedure.
<a id="p120463"></a>May be used in the customs territory of the Union, with total or partial relief from import duties in accordance with article 250 of the Code.
<a id="p120464"></a>Example: Temporary admission, e.g. for an exhibition.
<a id="p120465"></a>54 Inward processing in another Member State (without their being released for free circulation in that Member State) (a).
<a id="p120466"></a>Explanation: This code is used to record the operation for the purposes of statistics on intra-Union trade.
<a id="p120467"></a>Example: Non-Union goods are placed under inward processing in Belgium (5100). After undergoing inward processing, they are dispatched to Germany for release for free circulation (4054) or further processing (5154).
<a id="p120468"></a>61 Re-importation with simultaneous release for free circulation and home use of goods.
<a id="p120469"></a>Explanation:
<a id="p120470"></a>Goods re-imported from a third country with payment of the customs duties and VAT.
<a id="p120471"></a>63 Re-importation with simultaneous release for free circulation and home use of goods which are the subject of a VAT-exempt supply to another Member State and, when applicable, an excise duty suspension.
<a id="p120472"></a>Explanation: Exemption from payment of VAT and, where applicable, the excise duty suspension, is granted because that the re-importation is followed by intra-Union supply or transfer of the goods to another Member State. In such a case the VAT and, where applicable, the excise duty, will be due in the Member State of final destination. In order to use this procedure, the persons must meet other conditions listed in in Article 143(2) of Directive 2006/112/EC and, where applicable, the conditions listed in Article 17(1)(b) of Directive 2008/118/EC. The information required by Article 143 (2) of Directive 2006/112/EC shall be entered in D.E. 13 16 034 000 VAT identification number.
<a id="p120473"></a>Examples: Re-importation after outward processing or temporary export, with any VAT debt being charged to a tax representative.
<a id="p120474"></a>Excise goods reimported after outward processing and released for free circulation, which are the subject of a VAT- exempt supply to another Member State. The release for free circulation is immediately followed by a movement under excise duty suspension from the place of re-importation initiated by a registered consignor in accordance with Article 17(1)(b) of Directive 2008/118/EC.
<a id="p120475"></a>68 Re-importation with partial entry for home use and simultaneous release for free circulation and placing of goods under warehousing other than customs warehousing procedure.
<a id="p120476"></a>Explanation: This code is to be used for goods which are subject to both VAT and excise duties and where only one of those categories of taxes is paid when the goods are released for free circulation.
<a id="p120477"></a>Example: Processed alcoholic beverages are re-imported and placed in a tax warehouse.
<a id="p120478"></a>71 Placing of goods under the customs warehousing procedure.
<a id="p120479"></a>76 Placing of Union goods under the customs warehousing procedure in accordance with Article 237(2) of the Code.
<a id="p120480"></a>Example: Boned meat of adult male bovine animals placed under customs warehousing prior to export (Article 4 of Commission Regulation (EC) No 1741/2006 (1) of 24 November 2006 laying down the conditions for granting the special export refund on boned meat of adult male bovine animals placed under the customs warehousing procedure prior to export (OJ L 329, 25.11.2006, p. 7)).
<a id="p120481"></a>Following the release for free circulation, application for repayment or remission of import duty based on the goods being defective or not complying with the terms of the contract (Art.118 of the Code).
<a id="p120482"></a>In accordance with Article 118 (4) of the Code the goods in question may be placed under the customs warehousing procedure instead of having to be taken out of the customs territory of Union in order for the repayment or remission to be granted.
<a id="p120483"></a>77 Manufacturing of Union goods under customs supervision by the customs authorities and under customs control (within the meaning of Art. 5(27) and (3) of Code) prior to exportation and payment of export refunds.
<a id="p120484"></a>Example: Preserved beef and veal products manufactured under supervision by the customs authorities and under customs control prior to export (Articles 2 and 3 of Commission Regulation (EC) No 1731/2006 of 23 November 2006 on special detailed rules for the application of export refunds in the case of certain preserved beef and veal products (OJ L 325, 24.11.2006, p. 12)).
<a id="p120485"></a>78 Placing of goods under free-zone. (a)
<a id="p120486"></a>95 Placing of Union Goods under a warehousing procedure other than a customs warehousing procedure where neither VAT nor, when applicable, excise duties have been paid.
<a id="p120487"></a>Explanation: This code is to be used in the context of trade referred to in Article 1 (3) of the Code as well as trade between the Union and the countries with which it has formed a customs union and where neither VAT nor excise duties have been paid.
<a id="p120488"></a>Example: Cigarettes from the Canary Islands are brought to Belgium and stored in a tax warehouse; payment of VAT and excise duties is suspended.
<a id="p120489"></a>96 Placing of Union Goods under a warehousing procedure other than a customs warehousing procedure where either VAT or, when applicable, excise duties have been paid and the payment of the other tax is suspended.
<a id="p120490"></a>Explanation: This code is to be used in the context of trade referred to in Article 1 (3) of the Code as well as trade between the Union and the countries with which it has formed a customs union and where either VAT or excise duties have been paid and the payment of the other tax is suspended.
<a id="p120491"></a>Example: Cigarettes from the Canary Islands are brought to France and stored in a tax warehouse; VAT has been paid and the payment of excise duties is suspended.

<a id="p120492"></a>Procedure codes used in the context of customs declarations


| <a id="p120493"></a>Columns (table heading in Annex B to Delegated Regulation (EU) 2015/2446) | <a id="p120494"></a>Declarations | <a id="p120495"></a>Union procedure codes, where appropriate |
| --- | --- | --- |
| <a id="p120496"></a>B1 | <a id="p120497"></a>Export declaration and re-export declaration | <a id="p120498"></a>10, 11, 23, 31 |
| <a id="p120499"></a>B2 | <a id="p120500"></a>Special procedure - processing - declaration for outward processing | <a id="p120501"></a>21, 22 |
| <a id="p120502"></a>B3 | <a id="p120503"></a>Declaration for Customs warehousing of Union goods | <a id="p120504"></a>76, 77 |
| <a id="p120505"></a>B4 | <a id="p120506"></a>Declaration for dispatch of goods in the context of trade with special fiscal territories | <a id="p120507"></a>10 |
| <a id="p120508"></a>C1 | <a id="p120509"></a>Export Simplified declaration | <a id="p120510"></a>10, 11, 23, 31 |
| <a id="p120511"></a>H1 | <a id="p120512"></a>Declaration for release for free circulation and special procedure - specific use - declaration for end-use | <a id="p120513"></a>01, 07, 40, 42, 43, 44, 45, 46, 48, 61, 63, 68 |
| <a id="p120514"></a>H2 | <a id="p120515"></a>Special procedure - storage - declaration for customs warehousing | <a id="p120516"></a>71 |
| <a id="p120517"></a>H3 | <a id="p120518"></a>Special procedure - specific use - declaration for temporary admission | <a id="p120519"></a>53 |
| <a id="p120520"></a>H4 | <a id="p120521"></a>Special procedure - processing - declaration for inward processing | <a id="p120522"></a>51 |
| <a id="p120523"></a>H5 | <a id="p120524"></a>Declaration for the introduction of goods in the context of trade with special fiscal territories | <a id="p120525"></a>40, 42, 61, 63, 95, 96 |
| <a id="p120526"></a>H6 | <a id="p120527"></a>Customs declaration in postal traffic for release for free circulation | <a id="p120528"></a>01, 07, 40 |
| <a id="p120529"></a>H7 | <a id="p120530"></a>Customs declaration for release for free circulation in respect of a consignment which benefits from a relief from import duty in accordance with Article 23(1) or Article 25(1) of Regulation (EC) No 1186/2009 | <a id="p120531"></a>4 000 |
| <a id="p120532"></a>I1 | <a id="p120533"></a>Import Simplified declaration | <a id="p120534"></a>01, 07, 40, 42, 43, 44, 45, 46, 48, 51, 53, 61, 63, 68 |


<a id="p120535"></a>11 10 000 000 Additional procedure
<a id="p120536"></a>Where this data element is used to specify a Union procedure, the first character of the code identifies a category of measures in the following manner:
<a id="p120537"></a>Axx Inward processing (Article 256 of the Code)
<a id="p120538"></a>Bxx Outward processing (Article 259 of the Code)
<a id="p120539"></a>Cxx Relief (Council Regulation (EC) No 1186/2009 <*>)

<a id="p120540"></a>

---

<a id="p120541"></a><*> Council Regulation (EC) No 1186/2009 of 16 November 2009 setting up a Community system of reliefs from customs duty (OJ L 324, 10.12.2009, p. 23).

<a id="p120542"></a>Dxx Temporary admission (Delegated Regulation (EU) 2015/2446)
<a id="p120543"></a>Exx Agricultural products
<a id="p120544"></a>Fxx Other

<a id="p120545"></a>Inward processing (Article 256 of the Code)


| <a id="p120546"></a>Code | <a id="p120547"></a>Description |
| --- | --- |
|  | <a id="p120548"></a>Import |
| <a id="p120549"></a>A04 | <a id="p120550"></a>Goods which are placed under an inward processing procedure (VAT only) |
| <a id="p120551"></a>A10 | <a id="p120552"></a>Destruction of goods under inward processing |


<a id="p120553"></a>Outward processing (Article 259 of the Code)


| <a id="p120554"></a>Code | <a id="p120555"></a>Description |
| --- | --- |
|  | <a id="p120556"></a>Import |
| <a id="p120557"></a>B02 | <a id="p120558"></a>Processed products returning after repair under guarantee in accordance with Article 260 of the Code (goods repaired free of charge). |
| <a id="p120559"></a>B03 | <a id="p120560"></a>Processed products returning after replacement under guarantee in accordance with Article 261 of the Code (standard exchange system) |
| <a id="p120561"></a>B06 | <a id="p120562"></a>Processed products returning - VAT only |
|  | <a id="p120563"></a>Export |
| <a id="p120564"></a>B51 | <a id="p120565"></a>Goods imported for IP exported for repair under OP |
| <a id="p120566"></a>B52 | <a id="p120567"></a>Goods imported for IP exported for replacement under guarantee |
| <a id="p120568"></a>B53 | <a id="p120569"></a>OP under agreements with third countries, possibly combined with VAT OP |
| <a id="p120570"></a>B54 | <a id="p120571"></a>VAT outward processing only |


<a id="p120572"></a>Relief from import duties
(Council Regulation (EC) No 1186/2009) <*>


<a id="p120573"></a>

---

<a id="p120574"></a><*> Council Regulation (EC) No 1186/2009 of 16 November 2009 setting up a Community system of reliefs from customs duty (OJ L 324, 10.12.2009, p. 23).


| <a id="p120575"></a>Code | <a id="p120576"></a>Description | <a id="p120577"></a>Article No |
| --- | --- | --- |
| <a id="p120578"></a>C01 | <a id="p120579"></a>Personal property imported by natural persons transferring their normal place of residence to the customs territory of the Union | <a id="p120580"></a>3 |
| <a id="p120581"></a>C02 | <a id="p120582"></a>Trousseaux and household effects imported on the occasion of a marriage | <a id="p120583"></a>12(1) |
| <a id="p120584"></a>C03 | <a id="p120585"></a>Presents customarily given on the occasion of a marriage | <a id="p120586"></a>12(2) |
| <a id="p120587"></a>C04 | <a id="p120588"></a>Personal property acquired by inheritance by a natural person having his normal place of residence in the customs territory of the Union | <a id="p120589"></a>17 |
| <a id="p120590"></a>C06 | <a id="p120591"></a>School outfits, educational materials and related household effects | <a id="p120592"></a>21 |
| <a id="p120593"></a>C07 | <a id="p120594"></a>Consignments of negligible value | <a id="p120595"></a>23 |
| <a id="p120596"></a>C08 | <a id="p120597"></a>Consignments sent from one private individual to another | <a id="p120598"></a>25 |
| <a id="p120599"></a>C09 | <a id="p120600"></a>Capital goods and other equipment imported on the transfer of activities from a third country into the Union | <a id="p120601"></a>28 |
| <a id="p120602"></a>C10 | <a id="p120603"></a>Capital goods and other equipment belonging to persons engaged in a liberal profession and to legal persons engaged in a non-profit making activity | <a id="p120604"></a>34 |
| <a id="p120605"></a>C11 | <a id="p120606"></a>Educational, scientific and cultural materials; scientific instruments and apparatus as listed in Annex I to Regulation (EC) No 1186/2009) | <a id="p120607"></a>42 |
| <a id="p120608"></a>C12 | <a id="p120609"></a>Educational, scientific and cultural materials; scientific instruments and apparatus as listed in Annex II to Regulation (EC) No 1186/2009 | <a id="p120610"></a>43 |
| <a id="p120611"></a>C13 | <a id="p120612"></a>Educational, scientific and cultural materials; scientific instruments and apparatus imported exclusively for non-commercial purposes (including spare parts, components, accessories and tools) | <a id="p120613"></a>44 - 45 |
| <a id="p120614"></a>C14 | <a id="p120615"></a>Equipment imported for non-commercial purposes by or on behalf of a scientific research establishment or organisation based outside the Union | <a id="p120616"></a>51 |
| <a id="p120617"></a>C15 | <a id="p120618"></a>Laboratory animals and biological or chemical substances intended for research | <a id="p120619"></a>53 |
| <a id="p120620"></a>C16 | <a id="p120621"></a>Therapeutic substances of human origin and blood-grouping and tissue-typing reagents | <a id="p120622"></a>54 |
| <a id="p120623"></a>C17 | <a id="p120624"></a>Instruments and apparatus used in medical research, establishing medical diagnoses or carrying out medical treatment | <a id="p120625"></a>57 |
| <a id="p120626"></a>C18 | <a id="p120627"></a>Reference substances for the quality control of medicinal products | <a id="p120628"></a>59 |
| <a id="p120629"></a>C19 | <a id="p120630"></a>Pharmaceutical products used at international sports events | <a id="p120631"></a>60 |
| <a id="p120632"></a>C20 | <a id="p120633"></a>Goods for charitable or philanthropic organisations - basic necessities imported by State organisations or other approved organisations | <a id="p120634"></a>61(1)(a) |
| <a id="p120635"></a>C21 | <a id="p120636"></a>Articles in Annex III to Regulation (EC) No 1186/2009 intended for the blind | <a id="p120637"></a>66 |
| <a id="p120638"></a>C22 | <a id="p120639"></a>Articles in Annex IV to Regulation (EC) No 1186/2009 intended for the blind imported by blind persons themselves for their own use (including spare parts, components, accessories and tools) | <a id="p120640"></a>67(1)(a) and 67(2) |
| <a id="p120641"></a>C23 | <a id="p120642"></a>Articles in Annex IV to Regulation (EC) No 1186/2009 intended for the blind imported by certain institutions or organisations (including spare parts, components, accessories and tools) | <a id="p120643"></a>67(1) (b) and 67(2) |
| <a id="p120644"></a>C24 | <a id="p120645"></a>Articles intended for other handicapped persons (other than blind persons) imported by handicapped persons themselves for their own use (including spare parts, components, accessories and tools) | <a id="p120646"></a>68(1)(a) and 68(2) |
| <a id="p120647"></a>C25 | <a id="p120648"></a>Articles intended for other handicapped persons (other than blind persons) imported by certain institutions or organisations (including spare parts, components, accessories and tools) | <a id="p120649"></a>68(1)(b) and 68(2) |
| <a id="p120650"></a>C26 | <a id="p120651"></a>Goods imported for the benefit of disaster victims | <a id="p120652"></a>74 |
| <a id="p120653"></a>C27 | <a id="p120654"></a>Decorations conferred by governments of third countries on persons whose normal place of residence is in the customs territory of the Union | <a id="p120655"></a>81(a) |
| <a id="p120656"></a>C28 | <a id="p120657"></a>Goods imported into the customs territory of the Union by persons who have paid an official visit to a third country and who have received them on this occasion as gifts from the host authorities | <a id="p120658"></a>82(a) |
| <a id="p120659"></a>C29 | <a id="p120660"></a>Goods to be used by monarchs or heads of state | <a id="p120661"></a>85 |
| <a id="p120662"></a>C30 | <a id="p120663"></a>Samples of goods of negligible value imported for trade promotion purposes | <a id="p120664"></a>86 |
| <a id="p120665"></a>C31 | <a id="p120666"></a>Printed advertising matter | <a id="p120667"></a>87 |
| <a id="p120668"></a>C32 | <a id="p120669"></a>Small representative samples of goods manufactured outside the customs territory of the Union intended for a trade fair or similar event | <a id="p120670"></a>90(a) |
| <a id="p120671"></a>C33 | <a id="p120672"></a>Goods imported for examination, analysis or test purposes | <a id="p120673"></a>95 |
| <a id="p120674"></a>C34 | <a id="p120675"></a>Consignments sent to organisations protecting copyrights or industrial and commercial patent rights | <a id="p120676"></a>102 |
| <a id="p120677"></a>C35 | <a id="p120678"></a>Tourist information literature | <a id="p120679"></a>103 |
| <a id="p120680"></a>C36 | <a id="p120681"></a>Miscellaneous documents and articles | <a id="p120682"></a>104 |
| <a id="p120683"></a>C37 | <a id="p120684"></a>Ancillary materials for the stowage and protection of goods during their transport | <a id="p120685"></a>105 |
| <a id="p120686"></a>C38 | <a id="p120687"></a>Litter, fodder and feeding stuffs for animals during their transport | <a id="p120688"></a>106 |
| <a id="p120689"></a>C39 | <a id="p120690"></a>Fuel and lubricants present in land motor vehicles and special containers | <a id="p120691"></a>107 |
| <a id="p120692"></a>C40 | <a id="p120693"></a>Materials for the construction, upkeep, or ornamentation of memorials to, or cemeteries for, war victims | <a id="p120694"></a>112 |
| <a id="p120695"></a>C41 | <a id="p120696"></a>Coffins, funerary urns and ornamental funerary articles | <a id="p120697"></a>113 |
| <a id="p120698"></a>C42 | <a id="p120699"></a>Personal property entered for free circulation before the person concerned establishes his normal place of residence in the customs territory of the Union (duty relief subject to an undertaking) | <a id="p120700"></a>9(1) |
| <a id="p120701"></a>C43 | <a id="p120702"></a>Personal property entered for free circulation by a natural person having intention to establish his normal place of residence in the customs territory of the Union (duty-free admission subject to an undertaking) | <a id="p120703"></a>10 |
| <a id="p120704"></a>C44 | <a id="p120705"></a>Personal property acquired by inheritance by legal persons engaged in a non-profit making activity who are established in the customs territory of the Union | <a id="p120706"></a>20 |
| <a id="p120707"></a>C45 | <a id="p120708"></a>Agricultural, stock-farming, bee-keeping, horticultural and forestry products from properties located in a third country adjoining the customs territory of the Union | <a id="p120709"></a>35 |
| <a id="p120710"></a>C46 | <a id="p120711"></a>Products of fishing or fish-farming activities carried out in the lakes or waterways bordering a Member State and a third country by Union fishermen and products of hunting activities carried out on such lakes or waterways by Union sportsmen | <a id="p120712"></a>38 |
| <a id="p120713"></a>C47 | <a id="p120714"></a>Seeds, fertilizers and products for treatment of soil and crops, intended for use on property located in the customs territory of the Union adjoining a third country | <a id="p120715"></a>39 |
| <a id="p120716"></a>C48 | <a id="p120717"></a>Goods contained in the personal luggage and exempted from VAT | <a id="p120718"></a>41 |
| <a id="p120719"></a>C49 | <a id="p120720"></a>Goods for charitable or philanthropic organisations - goods of every description sent free of charge and to be used for fundraising at occasional charity events for the benefit of needy persons | <a id="p120721"></a>61(1)(b) |
| <a id="p120722"></a>C50 | <a id="p120723"></a>Goods for charitable or philanthropic organisations - equipment and office materials sent free of charge | <a id="p120724"></a>61(1)(c) |
| <a id="p120725"></a>C51 | <a id="p120726"></a>Cups, medals and similar articles of an essentially symbolic nature which, having been awarded in a third country to persons having their normal place of residence in the customs territory of the Union | <a id="p120727"></a>81(b) |
| <a id="p120728"></a>C52 | <a id="p120729"></a>Cups, medals and similar articles of an essentially symbolic nature which are given free of charge by authorities or persons established in a third country to be presented in the customs territory of the Union | <a id="p120730"></a>81(c) |
| <a id="p120731"></a>C53 | <a id="p120732"></a>Awards, trophies and souvenirs of a symbolic nature and of limited value intended for distribution free of charge to persons normally resident in third countries at business conferences or similar international events | <a id="p120733"></a>81(d) |
| <a id="p120734"></a>C54 | <a id="p120735"></a>Goods imported into the customs territory of the Union by persons coming to pay an official visit in the customs territory of the Union and who intend to offer them on that occasion as gifts to the host authorities | <a id="p120736"></a>82(b) |
| <a id="p120737"></a>C55 | <a id="p120738"></a>Goods sent as gifts, in token of friendship or goodwill, by an official body, public authority or group, carrying on an activity in the public interest which is located in a third country, to an official body, public authority or group carrying on an activity in the public interest which is located in the customs territory of the Union and approved by the competent authorities to receive such articles free of duty | <a id="p120739"></a>82(c) |
| <a id="p120740"></a>C56 | <a id="p120741"></a>Articles for advertising purposes, of no intrinsic commercial value, sent free of charge by suppliers to their customers, which, apart from their advertising function, are not capable of being used otherwise | <a id="p120742"></a>89 |
| <a id="p120743"></a>C57 | <a id="p120744"></a>Goods imported solely in order to be demonstrated or in order to demonstrate machines and apparatus, manufactured outside the customs territory of the Union and displayed at a trade fair or similar event | <a id="p120745"></a>90(1)(b) |
| <a id="p120746"></a>C58 | <a id="p120747"></a>Various materials of little value such as paints, varnishes, wallpaper, etc., used in the building, fitting-out and decoration of temporary stands occupied by representatives of third countries at a trade fair or similar event, which are destroyed by being used | <a id="p120748"></a>90(1)(c) |
| <a id="p120749"></a>C59 | <a id="p120750"></a>Printed matter, catalogues, prospectuses, price lists, advertising posters, calendars, whether or not illustrated, unframed photographs and other articles supplied free of charge in order to advertise goods manufactured outside the customs territory of the Union and displayed at a trade fair or similar event | <a id="p120751"></a>90(1)(d) |
| <a id="p120752"></a>C60 | <a id="p120753"></a>Trousseaux and household effects imported on the occasion of a marriage entered for free circulation not earlier than two months before the wedding (duty relief subject to lodging of appropriate guarantee) | <a id="p120754"></a>12(1), 15(1)(a) |
| <a id="p120755"></a>C61 | <a id="p120756"></a>Presents customarily given on the occasion of a marriage entered for free circulation not earlier than two months before the wedding (duty relief subject to lodging of appropriate guarantee) | <a id="p120757"></a>12(2), 15(1)(a) |
|  | <a id="p120758"></a>Relief from export duties |  |
| <a id="p120759"></a>C71 | <a id="p120760"></a>Domesticated animals exported at the time of transfer of agricultural activities from the Union to a third country | <a id="p120761"></a>115 |
| <a id="p120762"></a>C72 | <a id="p120763"></a>Fodder and feeding stuffs accompanying animals during their exportation | <a id="p120764"></a>121 |
| <a id="p120765"></a>C73 | <a id="p120766"></a>Consignments of negligible value | <a id="p120767"></a>114 |
| <a id="p120768"></a>C74 | <a id="p120769"></a>Agricultural or stock-farming products obtained in the customs territory of the Union from properties adjacent to a third country, operated, in the capacity of owner or lessee, by persons having their principal undertaking in a third country adjoining the customs territory of the Union | <a id="p120770"></a>116 |
| <a id="p120771"></a>C75 | <a id="p120772"></a>Seeds for use on properties located in a third country adjacent to the customs territory of the Union and operated, in the capacity of owner or lessee, by persons having their principal undertaking in the said customs territory in the immediate proximity of the third country in question | <a id="p120773"></a>119 |


<a id="p120774"></a>Temporary admission


| <a id="p120775"></a>Code | <a id="p120776"></a>Description | <a id="p120777"></a>Article No |
| --- | --- | --- |
| <a id="p120778"></a>D01 | <a id="p120779"></a>Pallets (including pallet spare parts, accessories and equipment) | <a id="p120780"></a>208 and 209 |
| <a id="p120781"></a>D02 | <a id="p120782"></a>Containers (including container spare parts, accessories and equipment) | <a id="p120783"></a>210 and 211 |
| <a id="p120784"></a>D03 | <a id="p120785"></a>Means of road, rail, air, sea and inland waterway transport | <a id="p120786"></a>212 |
| <a id="p120787"></a>D04 | <a id="p120788"></a>Personal effects and goods for sports purposes imported by travelers | <a id="p120789"></a>219 |
| <a id="p120790"></a>D05 | <a id="p120791"></a>Welfare material for seafarers | <a id="p120792"></a>220 |
| <a id="p120793"></a>D06 | <a id="p120794"></a>Disaster relief material | <a id="p120795"></a>221 |
| <a id="p120796"></a>D07 | <a id="p120797"></a>Medical, surgical and laboratory equipment | <a id="p120798"></a>222 |
| <a id="p120799"></a>D08 | <a id="p120800"></a>Animals (twelve months or more) | <a id="p120801"></a>223 |
| <a id="p120802"></a>D09 | <a id="p120803"></a>Goods for use in frontier zone | <a id="p120804"></a>224 |
| <a id="p120805"></a>D10 | <a id="p120806"></a>Sound, image or data carrying media | <a id="p120807"></a>225 |
| <a id="p120808"></a>D11 | <a id="p120809"></a>Publicity material | <a id="p120810"></a>225 |
| <a id="p120811"></a>D12 | <a id="p120812"></a>Professional equipment | <a id="p120813"></a>226 |
| <a id="p120814"></a>D13 | <a id="p120815"></a>Pedagogic material and scientific equipment | <a id="p120816"></a>227 |
| <a id="p120817"></a>D14 | <a id="p120818"></a>Packings, full | <a id="p120819"></a>228 |
| <a id="p120820"></a>D15 | <a id="p120821"></a>Packings, empty | <a id="p120822"></a>228 |
| <a id="p120823"></a>D16 | <a id="p120824"></a>Moulds, dies, blocks, drawings, sketches, measuring, checking and testing instruments and other similar articles | <a id="p120825"></a>229 |
| <a id="p120826"></a>D17 | <a id="p120827"></a>Special tools and instruments | <a id="p120828"></a>230 |
| <a id="p120829"></a>D18 | <a id="p120830"></a>Goods subject to tests, experiments or demonstrations. | <a id="p120831"></a>231(a) |
| <a id="p120832"></a>D19 | <a id="p120833"></a>Goods, subject to satisfactory acceptance tests, provided for in a sales contract | <a id="p120834"></a>231(b) |
| <a id="p120835"></a>D20 | <a id="p120836"></a>Goods used to carry out tests, experiments or demonstrations without financial gain (six months). | <a id="p120837"></a>231(c) |
| <a id="p120838"></a>D21 | <a id="p120839"></a>Samples | <a id="p120840"></a>232 |
| <a id="p120841"></a>D22 | <a id="p120842"></a>Replacement means of production (six months) | <a id="p120843"></a>233 |
| <a id="p120844"></a>D23 | <a id="p120845"></a>Goods for events or for sale | <a id="p120846"></a>234(1) |
| <a id="p120847"></a>D24 | <a id="p120848"></a>Goods for approval (six months) | <a id="p120849"></a>234(2) |
| <a id="p120850"></a>D25 | <a id="p120851"></a>Works of art, collectors' items and antiques | <a id="p120852"></a>234(3)(a) |
| <a id="p120853"></a>D26 | <a id="p120854"></a>Goods other than newly manufactured ones imported with a view to their sale by auction | <a id="p120855"></a>234(3)(b) |
| <a id="p120856"></a>D27 | <a id="p120857"></a>Spare parts, accessories and equipment | <a id="p120858"></a>235 |
| <a id="p120859"></a>D28 | <a id="p120860"></a>Goods imported in particular situations having no economic effect | <a id="p120861"></a>236(b) |
| <a id="p120862"></a>D29 | <a id="p120863"></a>Goods imported for a period not exceeding three months | <a id="p120864"></a>236(a) |
| <a id="p120865"></a>D30 | <a id="p120866"></a>Means of transport for persons established outside the customs territory of the Union or for persons preparing the transfer of their normal place of residence outside that territory. | <a id="p120867"></a>216 |
| <a id="p120868"></a>D51 | <a id="p120869"></a>Temporary admission with partial relief from import duty | <a id="p120870"></a>206 |


<a id="p120871"></a>Agricultural products


| <a id="p120872"></a>Code | <a id="p120873"></a>Description |
| --- | --- |
|  | <a id="p120874"></a>Import |
| <a id="p120875"></a>E01 | <a id="p120876"></a>Use of the unit price for the determination of the customs value for certain perishable goods (Article 74(2)(c) of the Code and Article 142(6)) |
| <a id="p120877"></a>E02 | <a id="p120878"></a>Standard import values (for example: Regulation (EU) No 543/2011) <*> |
|  | <a id="p120879"></a>Export |
| <a id="p120880"></a>E51 | <a id="p120881"></a>Agricultural products listed in Annex I to the Treaty on the Functioning of the European Union for which a refund is requested, subject to an export certificate |
| <a id="p120882"></a>E52 | <a id="p120883"></a>Agricultural products listed in Annex I to the Treaty on the Functioning of the European Union for which a refund is requested, not requiring an export certificate |
| <a id="p120884"></a>E53 | <a id="p120885"></a>Agricultural products listed in Annex I to the Treaty on the Functioning of the European Union for which a refund is requested, exported in small quantities, not requiring an export certificate |
| <a id="p120886"></a>E61 | <a id="p120887"></a>Processed agricultural products not listed in Annex I to the Treaty on the Functioning of the European Union for which a refund is requested, subject to a refund certificate |
| <a id="p120888"></a>E62 | <a id="p120889"></a>Processed agricultural products not listed in Annex I to the Treaty on the Functioning of the European Union for which a refund is requested, not requiring a refund certificate |
| <a id="p120890"></a>E63 | <a id="p120891"></a>Processed agricultural products not listed in Annex I to the Treaty on the Functioning of the European Union for which a refund is requested, exported in small quantities, without a refund certificate |
| <a id="p120892"></a>E64 | <a id="p120893"></a>Victualing of goods eligible for refunds (Article 33 Regulation (EC) No 612/2009 <**> |
| <a id="p120894"></a>E65 | <a id="p120895"></a>Entry in victualing warehouse (Article 37 Regulation (EC) No 612/2009) |
| <a id="p120896"></a>E71 | <a id="p120897"></a>Agricultural products for which a refund is requested, exported in small quantities disregarded for the calculation of minimum rates of checks |


<a id="p120898"></a>

---

<a id="p120899"></a><*> Commission Implementing Regulation (EU) No 543/2011 of 7 June 2011 laying down detailed rules for the application of Council Regulation (EC) No 1234/2007 in respect of the fruit and vegetables and processed fruit and vegetables sectors (OJ L 157, 15.6.2011, p. 1).
<a id="p120900"></a><**> Commission Regulation (EC) No 612/2009 of 7 July 2009 on laying down common detailed rules for the application of the system of export refunds on agricultural products (OJ L 186, 17.7.2009, p. 1).

<a id="p120901"></a>Other


| <a id="p120902"></a>Code | <a id="p120903"></a>Description |
| --- | --- |
|  | <a id="p120904"></a>Import |
| <a id="p120905"></a>F01 | <a id="p120906"></a>Relief from import duties for returned goods (Article 203 of the Code) |
| <a id="p120907"></a>F02 | <a id="p120908"></a>Relief from import duties for returned goods (Special circumstances provided for in Article 159 of Delegated Regulation (EU) 2015/2446: agriculture goods) |
| <a id="p120909"></a>F03 | <a id="p120910"></a>Relief from import duties for returned goods (Special circumstances provided for in Article 158(3) of Delegated Regulation (EU) 2015/2446 repair or restoration) |
| <a id="p120911"></a>F04 | <a id="p120912"></a>Processed products which return to the European Union after having been previously re-exported subsequent to an inward processing procedure (Article 205(1) of the Code) |
| <a id="p120913"></a>F05 | <a id="p120914"></a>Relief from import duties and from VAT and/or excise duties for returned goods (Art. 203 of the Code and Art. 143(1)(e) (Directive 2006/112/EC) |
| <a id="p120915"></a>F06 | <a id="p120916"></a>A movement of excise goods under an excise duty suspension arrangement from the place of importation in accordance with Article 17(1)(b) of Directive 2008/118/EC |
| <a id="p120917"></a>F07 | <a id="p120918"></a>Processed products which return to the European Union after having been previously re-exported subsequent to an inward processing procedure where the import duty is determined in accordance with Article 86(3) of the Code (Article 205(2) of the Code) |
| <a id="p120919"></a>F15 | <a id="p120920"></a>Goods introduced in the context of trade with special fiscal territories (Article 1(3) of the Code) |
| <a id="p120921"></a>F16 | <a id="p120922"></a>Goods introduced in the context of trade between the Union and the countries with which it has formed a customs union |
| <a id="p120923"></a>F21 | <a id="p120924"></a>Exemption from import duties of products of sea-fishing and other products taken from the territorial sea of a country or territory outside the customs territory of the Union by vessels solely registered or recorded in a Member State and flying the flag of that state |
| <a id="p120925"></a>F22 | <a id="p120926"></a>Exemption from import duties of products obtained from products of sea-fishing and other products taken from the territorial sea of a country or territory outside the customs territory of the Union on board factory-ships registered or recorded in a Member State and flying the flag of the state |
| <a id="p120927"></a>F44 | <a id="p120928"></a>Release for free circulation of processed products when Article 86(3) of Code) is to be applied |
| <a id="p120929"></a>F45 | <a id="p120930"></a>Exemption from value added tax on the final importation of certain goods (Council Directive 2009/132/EC <*>) |
| <a id="p120931"></a>F46 | <a id="p120932"></a>Use of the original tariff classification of the goods in situations provided for in Article 86(2) of the Code |
| <a id="p120933"></a>F47 | <a id="p120934"></a>Simplification of the drawing-up of customs declarations for goods falling under different tariff subheadings provided for in Article 177 of the Code |
| <a id="p120935"></a>F48 | <a id="p120936"></a>Import under the special scheme for distance sales of goods imported from third countries or third territories set out in Title XII Chapter 6 Section 4 of Directive 2006/112/EC |
| <a id="p120937"></a>F49 | <a id="p120938"></a>Import under the special arrangements for declaration and payment of import VAT set out in Title XII Chapter 7 of Directive 2006/112/EC |
|  | <a id="p120939"></a>Export |
| <a id="p120940"></a>F61 | <a id="p120941"></a>Victualing and bunkering |
| <a id="p120942"></a>F65 | <a id="p120943"></a>Simplification of the drawing-up of customs declarations for goods falling under different tariff subheadings provided for in Article 177 of the Code |
| <a id="p120944"></a>F75 | <a id="p120945"></a>Goods dispatched in the context of trade with special fiscal territories (Article 1(3) of the Code) |


<a id="p120946"></a>

---

<a id="p120947"></a><*> Council Directive 2009/132/EC of 19 October 2009 determining the scope of Article 143(b) and (c) of Directive 2006/112/EC as regards exemption from value added tax on the final importation of certain goods (OJ L 292, 10.11.2009, p. 5).

<a id="p120948"></a>12 01 000 000 Previous document

<a id="p120949"></a>12 01 001 000 Reference number
<a id="p120950"></a>The identification number or another recognisable reference of the document is inserted here.
<a id="p120951"></a>In case the MRN is referred to as previous document, the reference number shall have the following structure:


| <a id="p120952"></a>Field | <a id="p120953"></a>Content | <a id="p120954"></a>Format | <a id="p120955"></a>Examples |
| --- | --- | --- | --- |
| <a id="p120956"></a>1 | <a id="p120957"></a>Last two digits of year of formal acceptance of the declaration (YY) | <a id="p120958"></a>n2 | <a id="p120959"></a>21 |
| <a id="p120960"></a>2 | <a id="p120961"></a>Identifier of the country where the declaration/proof of the customs status of Union goods/notification is lodged (alpha 2 country code) | <a id="p120962"></a>a2 | <a id="p120963"></a>RO |
| <a id="p120964"></a>3 | <a id="p120965"></a>Unique identifier for message per year and country | <a id="p120966"></a>an12 | <a id="p120967"></a>9876AB889012 |
| <a id="p120968"></a>4 | <a id="p120969"></a>Procedure identifier | <a id="p120970"></a>al | <a id="p120971"></a>B |
| <a id="p120972"></a>5 | <a id="p120973"></a>Check digit | <a id="p120974"></a>an1 | <a id="p120975"></a>1 |


<a id="p120976"></a>Fields 1 and 2 as explained above.
<a id="p120977"></a>Field 3 shall be filled in with an identifier for the message concerned. The way that field is used is under the responsibility of national administrations but each message handled during one year within the given country must have a unique number in relation to the procedure concerned.
<a id="p120978"></a>National administrations that want to have the reference number of the competent customs office included in the MRN, may use up to the first 6 characters to represent it.
<a id="p120979"></a>Field 4 shall be filled in with an identifier of the procedure as defined in the table below.
<a id="p120980"></a>Field 5 shall be filled with a value that is a check digit for the whole MRN. This field allows for detection of an error when capturing the whole MRN.
<a id="p120981"></a>Codes to be used in field 4 Procedure identifier:


| <a id="p120982"></a>Code | <a id="p120983"></a>Procedure |
| --- | --- |
| <a id="p120984"></a>A | <a id="p120985"></a>Export only |
| <a id="p120986"></a>B | <a id="p120987"></a>Export and exit summary declaration |
| <a id="p120988"></a>C | <a id="p120989"></a>Exit summary declaration only |
| <a id="p120990"></a>D | <a id="p120991"></a>Re-export notification |
| <a id="p120992"></a>E | <a id="p120993"></a>Dispatch of goods in relation with special fiscal territories |
| <a id="p120994"></a>J | <a id="p120995"></a>Transit declaration only |
| <a id="p120996"></a>K | <a id="p120997"></a>Transit declaration and exit summary declaration |
| <a id="p120998"></a>L | <a id="p120999"></a>Transit declaration and entry summary declaration |
| <a id="p121000"></a>M | <a id="p121001"></a>Transit declaration and exit summary declaration and entry summary declaration |
| <a id="p121002"></a>P | <a id="p121003"></a>Proof of the customs status of Union goods/Customs goods manifest |
| <a id="p121004"></a>R | <a id="p121005"></a>Import declaration only |
| <a id="p121006"></a>S | <a id="p121007"></a>Import declaration and entry summary declaration |
| <a id="p121008"></a>T | <a id="p121009"></a>Entry summary declaration only |
| <a id="p121010"></a>U | <a id="p121011"></a>Temporary storage declaration |
| <a id="p121012"></a>V | <a id="p121013"></a>Introduction of goods in relation with special fiscal territories |
| <a id="p121014"></a>W | <a id="p121015"></a>Temporary storage declaration and entry summary declaration |
| <a id="p121016"></a>Z | <a id="p121017"></a>Arrival notification |


<a id="p121018"></a>12 01 002 000 Type
<a id="p121019"></a>Previous documents must be entered in the form of a code defined in Title I. The list of documents and their respective codes can be found in the TARIC database.

<a id="p121020"></a>12 02 000 000 Additional information

<a id="p121021"></a>12 02 008 000 Code
<a id="p121022"></a>A five-digit code is used to encode additional information of a customs nature:
<a id="p121023"></a>Code Oxxxx - General category
<a id="p121024"></a>Code 1xxxx - On import
<a id="p121025"></a>Code 2xxxx - On transit
<a id="p121026"></a>Code 3xxxx - On Export
<a id="p121027"></a>Code 4xxxx - Other


| <a id="p121028"></a>Code | <a id="p121029"></a>Legal basis | <a id="p121030"></a>Subject | <a id="p121031"></a>Additional information |
| --- | --- | --- | --- |
| <a id="p121032"></a>00100 | <a id="p121033"></a>Article 163 of Delegated Regulation (EU) 2015/2446 | <a id="p121034"></a>Application for the authorisation of the use of a special procedure other than transit based on the customs declaration | <a id="p121035"></a>"Simplified authorisation"" |
| <a id="p121036"></a>00700 | <a id="p121037"></a>Article 176(1)(c) and Article 241(1) first subparagraph of Delegated Regulation (EU) 2015/2446 | <a id="p121038"></a>Discharge of inward processing | <a id="p121039"></a>"IP" and the relevant authorisation number or INF number |
| <a id="p121040"></a>00800 | <a id="p121041"></a>Article 241(1) second subparagraph of Delegated Regulation (EU) 2015/2446 | <a id="p121042"></a>Discharge of inward processing (specific commercial policy measures) | <a id="p121043"></a>"IP CPM" |
| <a id="p121044"></a>00900 | <a id="p121045"></a>Article 238 of Delegated Regulation (EU) 2015/2446 | <a id="p121046"></a>Discharge of temporary admission | <a id="p121047"></a>"TA" and the relevant authorisation number |
| <a id="p121048"></a>01000 | <a id="p121049"></a>Article 36(2) of the Vienna Convention on Diplomatic Relations of 1961 | <a id="p121050"></a>The personal baggage of a diplomatic agent shall be exempt from inspection | <a id="p121051"></a>"Diplomatic Goods - Exempt from inspection" |
| <a id="p121052"></a>10600 | <a id="p121053"></a>Title II of Annex B to Delegated Regulation (EU) 2015/2446 | <a id="p121054"></a>Situations where negotiable bills of lading that are "to order blank endorsed" are concerned, in the case of entry summary declarations, where the consignee details are unknown | <a id="p121055"></a>"Consignee unknown" |
| <a id="p121056"></a>20100 | <a id="p121057"></a>Article 18 of the "common transit procedure" <*> | <a id="p121058"></a>Export from one common transit country subject to restriction or export from the Union subject to restriction |  |
| <a id="p121059"></a>20200 | <a id="p121060"></a>Article 18 of the "common transit procedure" <*> | <a id="p121061"></a>Export from one common transit country subject to duties or export from the Union subject to duties |  |
| <a id="p121062"></a>20300 | <a id="p121063"></a>Article 18 of the "common transit procedure" | <a id="p121064"></a>Export | <a id="p121065"></a>"Export" |
| <a id="p121066"></a>30300 | <a id="p121067"></a>Article 254(4)(b) of the Code | <a id="p121068"></a>Export of goods subject to end-use | <a id="p121069"></a>"E-U" |
| <a id="p121070"></a>30500 | <a id="p121071"></a>Article 329(7) | <a id="p121072"></a>Request for the customs office competent for the place where the goods are taken over under a single transport contract for transport of the goods out of the customs territory of the Union to be the customs office of exit | <a id="p121073"></a>Customs office of exit |
| <a id="p121074"></a>30600 | <a id="p121075"></a>Title II of Annex B to Delegated Regulation (EU) 2015/2446 | <a id="p121076"></a>Situations where negotiable bills of lading that are "to order blank endorsed" are concerned, in the case of exit summary declarations, where the consignee details are unknown | <a id="p121077"></a>"Consignee unknown" |
| <a id="p121078"></a>30700 | <a id="p121079"></a>Article 160 Delegated Regulation (EU) 2015/2446 | <a id="p121080"></a>The request to have an information sheet INF3 | <a id="p121081"></a>"INF3" |
| <a id="p121082"></a>40100 | <a id="p121083"></a>Article 123 of Delegated Regulation (EU) 2015/2446 | <a id="p121084"></a>Request for a longer period of validity of the proof of the customs status of Union goods | <a id="p121085"></a>"Longer period of validity of the proof of the customs status of Union goods" |


<a id="p121086"></a>

---

<a id="p121087"></a><*> Convention on a common transit procedure of 20 May 1987 (OJ L 226, 13.8.1987, p. 2).

<a id="p121088"></a>12 03 000 000 Supporting document

<a id="p121089"></a>12 03 002 000 Type
<a id="p121090"></a>(a) Union or international documents, certificates and authorisations produced in support of the declaration, must be entered in the form of a code defined in Title I, followed either by an identification number or another recognisable reference. The list of documents, certificates and authorisations, and their respective codes can be found in the TARIC database.
<a id="p121091"></a>(b) National documents, certificates and authorisations produced in support of the declaration, must be entered in the form of a code as defined in Title I (Ex: 2123, 34d5), possibly followed either by an identification number or another recognisable reference. The four characters represent codes based on that Member State's own nomenclature.

<a id="p121092"></a>12 04 000 000 Additional reference

<a id="p121093"></a>12 04 002 000 Type
<a id="p121094"></a>(a) Additional references must be entered in the form of a code defined in Title I. The list of additional references and their respective codes can be found in the TARIC database.
<a id="p121095"></a>(b) Additional references must be entered in the form of a code as defined in Title I, possibly followed either by an identification number or another recognisable reference. The four characters represent codes based on that Member State's own nomenclature.

<a id="p121096"></a>12 05 000 000 Transport document

<a id="p121097"></a>12 05 002 000 Type
<a id="p121098"></a>Transport documents must be entered in the form of a code defined in Title I. The list of transport documents and their respective codes can be found in the TARIC database.

<a id="p121099"></a>12 11 000 000 Warehouse

<a id="p121100"></a>12 11 002 000 Type
<a id="p121101"></a>The character identifying the type of warehouse:
<a id="p121102"></a>R Public customs warehouse type I
<a id="p121103"></a>S Public customs warehouse type II
<a id="p121104"></a>T Public customs warehouse type III
<a id="p121105"></a>U Private customs warehouse
<a id="p121106"></a>V Storage facilities for the temporary storage of goods
<a id="p121107"></a>Y Non-customs warehouse
<a id="p121108"></a>Z Free zone

<a id="p121109"></a>13 01 000 000 Exporter

<a id="p121110"></a>13 01 017 000 Identification number
<a id="p121111"></a>The structure of a third country unique identification number which has been made available to the Union is as follows:


| <a id="p121112"></a>Field | <a id="p121113"></a>Content | <a id="p121114"></a>Format |
| --- | --- | --- |
| <a id="p121115"></a>1 | <a id="p121116"></a>Country code | <a id="p121117"></a>a2 |
| <a id="p121118"></a>2 | <a id="p121119"></a>Unique identification number in a third country | <a id="p121120"></a>an..15 |


<a id="p121121"></a>Country code: The country code as defined in Title I for D.E. 1 301 018 020 (Exporter Address Country) shall be used.

<a id="p121122"></a>13 02 000 000 Consignor

<a id="p121123"></a>13 02 028 000 Type of person
<a id="p121124"></a>The following codes shall be used:
<a id="p121125"></a>1 Natural person
<a id="p121126"></a>2 Legal person
<a id="p121127"></a>3 Association of persons which is not a legal person but which is recognised under Union or national law as having the capacity to perform legal acts.

<a id="p121128"></a>13 02 029 000 Communication

<a id="p121129"></a>13 02 029 002 Type
<a id="p121130"></a>The following codes shall be used:
<a id="p121131"></a>EM Electronic mail
<a id="p121132"></a>TE Telephone

<a id="p121133"></a>13 06 000 000 Representative

<a id="p121134"></a>13 06 030 000 Status
<a id="p121135"></a>Insert one of the following codes before the full name and address to designate the status of the representative:
<a id="p121136"></a>2 Representative (direct representation within the meaning of Article 18(1) of the Code)
<a id="p121137"></a>3 Representative (indirect representation within the meaning of Article 18(1) of the Code).

<a id="p121138"></a>13 14 000 000 Additional supply chain actor

<a id="p121139"></a>13 14 031 000 Role
<a id="p121140"></a>The following parties can be declared:


| <a id="p121141"></a>Role<br>Code | <a id="p121142"></a>Party | <a id="p121143"></a>Description |
| --- | --- | --- |
| <a id="p121144"></a>CS | <a id="p121145"></a>Consolidator | <a id="p121146"></a>Freight forwarder combining individual smaller consignments into a single larger consignment (in a consolidation process) that is sent to a counterpart who mirrors the consolidator's activity by dividing the consolidated consignment into its original components |
| <a id="p121147"></a>FW | <a id="p121148"></a>Freight<br>Forwarder | <a id="p121149"></a>Party undertaking forwarding of goods |
| <a id="p121150"></a>MF | <a id="p121151"></a>Manufacturer | <a id="p121152"></a>Party which manufactures goods |
| <a id="p121153"></a>WH | <a id="p121154"></a>Warehouse<br>Keeper | <a id="p121155"></a>Party taking responsibility for goods entered into a warehouse |


<a id="p121156"></a>13 15 000 000 Supplementary declarant

<a id="p121157"></a>13 15 032 000 Supplementary filing type
<a id="p121158"></a>The following filing types can be used:


| <a id="p121159"></a>Type | <a id="p121160"></a>Description |
| --- | --- |
| <a id="p121161"></a>1 | <a id="p121162"></a>House level filing |
| <a id="p121163"></a>2 | <a id="p121164"></a>Sub-house level filing |


<a id="p121165"></a>13 16 000 000 Additional fiscal reference

<a id="p121166"></a>13 16 031 000 Role
<a id="p121167"></a>The following parties can be declared:


| <a id="p121168"></a>Role<br>Code | <a id="p121169"></a>Party | <a id="p121170"></a>Description |
| --- | --- | --- |
| <a id="p121171"></a>FR1 | <a id="p121172"></a>Importer | <a id="p121173"></a>Person or persons designated or recognised as liable for the payment of value added tax by the Member State of importation in accordance with Article 201 of Directive 2006/112/EC |
| <a id="p121174"></a>FR2 | <a id="p121175"></a>Customer | <a id="p121176"></a>Person liable for the payment of Value Added Tax on the intra-Union acquisition of goods in accordance with Article 200 of Directive 2006/112/EC |
| <a id="p121177"></a>FR3 | <a id="p121178"></a>Tax representative | <a id="p121179"></a>Tax representative liable for the payment of value added tax in the Member State of importation appointed by the importer |
| <a id="p121180"></a>FR4 | <a id="p121181"></a>Holder of the deferred payment authorisation | <a id="p121182"></a>The taxable person or the person liable for payment or another person that has received deferment of payment in accordance with Article 211 of Directive 2006/112/EC |
| <a id="p121183"></a>FR5 | <a id="p121184"></a>Vendor (IOSS) | <a id="p121185"></a>Taxable person making use of the special scheme for distance sales of goods imported from third countries or third territories set out in Title XII Chapter 6 Section 4 of Directive 2006/112/EC and holder of the VAT identification number referred to in Article 369q therein |
| <a id="p121186"></a>FR7 | <a id="p121187"></a>Taxable person or of the person liable for payment of VAT | <a id="p121188"></a>VAT identification number of the taxable person or of the person liable for payment of VAT where the payment of VAT is postponed in accordance with Article 211 second subparagraph of Directive 2006/112/EC |


<a id="p121189"></a>13 16 034 000 VAT identification number
<a id="p121190"></a>The value added tax identification number is structured as follows:


| <a id="p121191"></a>Field | <a id="p121192"></a>Content | <a id="p121193"></a>Format |
| --- | --- | --- |
| <a id="p121194"></a>1 | <a id="p121195"></a>Identifier of the Member State of issue (ISO code 3166 - alpha 2; Greece may use EL) | <a id="p121196"></a>a2 |
| <a id="p121197"></a>2 | <a id="p121198"></a>Individual number attributed by Member States for the identification of taxable persons referred to in Article 214 of Directive 2006/112/EC | <a id="p121199"></a>an..15 |


<a id="p121200"></a>When the goods are declared for release for free circulation under the special scheme for distance sales of goods imported from third countries or third territories set out in Title XII Chapter 6 Section 4 of Directive 2006/112/EC the special VAT number attributed for the use of this scheme shall be provided.

<a id="p121201"></a>14 01 000 000 Delivery terms

<a id="p121202"></a>14 01 035 000 INCOTERM code
<a id="p121203"></a>The codes and statements to be entered are as follows:


<table>
<colgroup><col width="21%"><col width="41%"><col width="38%"></colgroup>
<tr><td><a id="p121204"></a>Incoterms code</td><td><a id="p121205"></a>Incoterms - ICC/ECE Meaning</td><td><a id="p121206"></a>Place to be specified</td></tr>
<tr><td colspan="2"><a id="p121207"></a>Codes applicable for all modes of transport</td><td></td></tr>
<tr><td><a id="p121208"></a>EXW (Incoterms 2020)</td><td><a id="p121209"></a>Ex works</td><td><a id="p121210"></a>Named place of delivery</td></tr>
<tr><td><a id="p121211"></a>FCA (Incoterms 2020)</td><td><a id="p121212"></a>Free carrier</td><td><a id="p121213"></a>Named place of delivery</td></tr>
<tr><td><a id="p121214"></a>CPT (Incoterms 2020)</td><td><a id="p121215"></a>Carriage paid to</td><td><a id="p121216"></a>Named place of destination</td></tr>
<tr><td><a id="p121217"></a>CIP (Incoterms 2020)</td><td><a id="p121218"></a>Carriage and insurance paid to</td><td><a id="p121219"></a>Named place of destination</td></tr>
<tr><td><a id="p121220"></a>DPU (Incoterms 2020)</td><td><a id="p121221"></a>Delivered at place unloaded</td><td><a id="p121222"></a>Named place of destination</td></tr>
<tr><td><a id="p121223"></a>DAP (Incoterms 2020)</td><td><a id="p121224"></a>Delivered at place</td><td><a id="p121225"></a>Named place of destination</td></tr>
<tr><td><a id="p121226"></a>DDP (Incoterms 2020)</td><td><a id="p121227"></a>Delivered duty paid</td><td><a id="p121228"></a>Named place of destination</td></tr>
<tr><td><a id="p121229"></a>DAT (Incoterms 2010)</td><td><a id="p121230"></a>Delivered at terminal</td><td><a id="p121231"></a>Named terminal at port or place of destination</td></tr>
<tr><td colspan="3"><a id="p121232"></a>Codes applicable for sea and inland waterway transport</td></tr>
<tr><td><a id="p121233"></a>FAS (Incoterms 2020)</td><td><a id="p121234"></a>Free along ship</td><td><a id="p121235"></a>Named port of shipment</td></tr>
<tr><td><a id="p121236"></a>FOB (Incoterms 2020)</td><td><a id="p121237"></a>Free on board</td><td><a id="p121238"></a>Named port of shipment</td></tr>
<tr><td><a id="p121239"></a>CFR (Incoterms 2020)</td><td><a id="p121240"></a>Cost and freight</td><td><a id="p121241"></a>Named port of destination</td></tr>
<tr><td><a id="p121242"></a>CIF (Incoterms 2020)</td><td><a id="p121243"></a>Cost, insurance and freight</td><td><a id="p121244"></a>Named port of destination</td></tr>
<tr><td><a id="p121245"></a>XXX</td><td><a id="p121246"></a>Delivery terms other than those listed above</td><td><a id="p121247"></a>Narrative description of delivery terms given in the contract</td></tr>
</table>


<a id="p121248"></a>14 02 000 000 Transport charges

<a id="p121249"></a>14 02 038 000 Method of payment
<a id="p121250"></a>The following codes shall be used:
<a id="p121251"></a>A Payment in cash
<a id="p121252"></a>B Payment by credit card
<a id="p121253"></a>C Payment by cheque
<a id="p121254"></a>D Other (e.g. direct debit to cash account)
<a id="p121255"></a>H Electronic funds transfer
<a id="p121256"></a>Y Account holder with carrier
<a id="p121257"></a>Z Not pre-paid

<a id="p121258"></a>14 03 000 000 Duties and taxes

<a id="p121259"></a>14 03 039 000 Tax type
<a id="p121260"></a>The codes applicable are given below:
<a id="p121261"></a>A00 Import duty
<a id="p121262"></a>A30 Definitive antidumping duties
<a id="p121263"></a>A35 Provisional antidumping duties
<a id="p121264"></a>A40 Definitive countervailing duties
<a id="p121265"></a>A45 Provisional countervailing duties
<a id="p121266"></a>**B00 VAT**
<a id="p121267"></a>C00 Export duty
<a id="p121268"></a>E00 Duties collected on behalf of other countries

<a id="p121269"></a>14 03 038 000 Method of payment
<a id="p121270"></a>The following codes may be used by the Member States:
<a id="p121271"></a>A Payment in cash
<a id="p121272"></a>B Payment by credit card
<a id="p121273"></a>C Payment by cheque
<a id="p121274"></a>D Other (e.g. direct debit to agent's cash account)
<a id="p121275"></a>E Deferred or postponed payment
<a id="p121276"></a>G Postponed payment - VAT system (Article 211 of Directive 2006/112/EC)
<a id="p121277"></a>H Electronic credit transfer
<a id="p121278"></a>J Payment through post office administration (postal consignments) or other public sector or government department
<a id="p121279"></a>K Excise credit or rebate
<a id="p121280"></a>O Guarantee lodged with Intervention Agency
<a id="p121281"></a>P From agent's cash account
<a id="p121282"></a>R Guarantee of the amount payable
<a id="p121283"></a>S Individual guarantee account
<a id="p121284"></a>T From agent's guarantee account
<a id="p121285"></a>U From agent's guarantee - standing authority
<a id="p121286"></a>V From agent's guarantee - individual authority

<a id="p121287"></a>14 04 000 000 Additions and deductions

<a id="p121288"></a>14 04 008 000 Code
<a id="p121289"></a>Additions (As defined under Articles 70 and 71 of the Code)
<a id="p121290"></a>AB Commissions and brokerage, except buying commissions
<a id="p121291"></a>AD Containers and packing
<a id="p121292"></a>AE Materials, components, parts and similar items incorporated in the imported goods
<a id="p121293"></a>AF Tools, dies, moulds and similar items used in the production of the imported goods
<a id="p121294"></a>AG Materials consumed in the production of the imported goods
<a id="p121295"></a>AH Engineering, development, artwork, design work and plans and sketches undertaken elsewhere than in the European Union and necessary for the production of the imported goods
<a id="p121296"></a>AI Royalties and license fees
<a id="p121297"></a>AJ Proceeds of any subsequent resale, disposal or use accruing to the seller
<a id="p121298"></a>AK Transport costs, loading and handling charges and insurance costs up to
<a id="p121299"></a>the place of introduction in the European Union
<a id="p121300"></a>AL Indirect payments and other payments (Article 70 of the code)
<a id="p121301"></a>AN Additions based on a decision granted in accordance with Article 71 of Delegated Regulation (EU) 2015/2446
<a id="p121302"></a>Deductions (As defined under Articles 72 of the Code)
<a id="p121303"></a>BA Costs of transport after arrival at the place of introduction
<a id="p121304"></a>BB Charges for construction, erection, assembly, maintenance or technical assistance undertaken after importation
<a id="p121305"></a>BC Import duties or other charges payable in the Union for reason of the import or sale of goods
<a id="p121306"></a>BD Interest charges
<a id="p121307"></a>BE Charges for the right to reproduce the imported goods in the European Union
<a id="p121308"></a>BF Buying commissions
<a id="p121309"></a>BG Deductions based on a decision granted in accordance with Article 71 of Delegated Regulation (EU) 2015/2446

<a id="p121310"></a>14 07 000 000 Valuation indicators
<a id="p121311"></a>The code comprises four digits, each of which being either a "0" or a "1".
<a id="p121312"></a>Each "1" or "0" digit reflects whether or not a valuation indicator is relevant to the valuation of the goods concerned.
<a id="p121313"></a>1st digit: Party relationship, whether there is price influence or not
<a id="p121314"></a>2nd digit: Restrictions as to the disposal or use of the goods by the buyer in accordance with Article 70(3)(a) of the Code
<a id="p121315"></a>3rd digit: Sale or price is subject to some condition or consideration in accordance with Article 70(3)(b) of the Code
<a id="p121316"></a>4th digit: The sale is subject to an arrangement under which part of the proceeds of any subsequent resale, disposal or use accrues directly or indirectly to the seller
<a id="p121317"></a>Example: Goods subject to party relationship, but not to any of the other situations defined under 2nd, 3rd and 4th digits would entail the use of code combination "1 000."

<a id="p121318"></a>14 10 000 000 Valuation method
<a id="p121319"></a>The provisions used to determine the customs value of imported goods are to be coded as follows:


| <a id="p121320"></a>Code | <a id="p121321"></a>Relevant Article of the Code | <a id="p121322"></a>Method |
| --- | --- | --- |
| <a id="p121323"></a>1 | <a id="p121324"></a>70 | <a id="p121325"></a>Transaction value of the imported goods |
| <a id="p121326"></a>2 | <a id="p121327"></a>74(2)(a) | <a id="p121328"></a>Transaction value of identical goods |
| <a id="p121329"></a>3 | <a id="p121330"></a>74(2)(b) | <a id="p121331"></a>Transaction value of similar goods |
| <a id="p121332"></a>4 | <a id="p121333"></a>74(2)(c) | <a id="p121334"></a>Deductive value method |
| <a id="p121335"></a>5 | <a id="p121336"></a>74(2)(d) | <a id="p121337"></a>Computed value method |
| <a id="p121338"></a>6 | <a id="p121339"></a>74(3) | <a id="p121340"></a>Value based on the data available ("fall-back"method) |


<a id="p121341"></a>14 11 000 000 Preference
<a id="p121342"></a>This information includes three-digit codes comprising a single-digit component from 1) and a two-digit component from 2).
<a id="p121343"></a>The relevant codes are given below:
<a id="p121344"></a>(1) First digit of the code
<a id="p121345"></a>1 Tariff arrangement erga omnes
<a id="p121346"></a>2 Generalised System of Preferences (GSP)
<a id="p121347"></a>3 Tariff preferences other than those mentioned under code 2
<a id="p121348"></a>4 Customs duties under the provisions of customs union agreements concluded by the European Union
<a id="p121349"></a>(2) Next two digits of the code
<a id="p121350"></a>00 None of the following
<a id="p121351"></a>10 Tariff suspension
<a id="p121352"></a>18 Tariff suspension with certificate confirming the special nature of the product
<a id="p121353"></a>19 Temporary suspension for products imported with an authorised release certificate EASA Form 1 or an equivalent certificate
<a id="p121354"></a>20 Tariff quota <*>

<a id="p121355"></a>

---

<a id="p121356"></a><*> Where the requested tariff quota is exhausted, Member States may allow the request to be valid for any other preference.

<a id="p121357"></a>25 Tariff quota with certificate confirming the special nature of the product <*>

<a id="p121358"></a>

---

<a id="p121359"></a><*> Where the requested tariff quota is exhausted, Member States may allow the request to be valid for any other preference.

<a id="p121360"></a>28 Tariff quota following outward processing <*>

<a id="p121361"></a>

---

<a id="p121362"></a><*> Where the requested tariff quota is exhausted, Member States may allow the request to be valid for any other preference.

<a id="p121363"></a>50 Certificate confirming the special nature of the product

<a id="p121364"></a>16 15 000 000 Location of goods
<a id="p121365"></a>Use the GEONOM code as referred to in introductory note 13 number 3.

<a id="p121366"></a>16 15 045 000 Type of Location
<a id="p121367"></a>For the type of location, use the codes specified below:
<a id="p121368"></a>A Designated location
<a id="p121369"></a>B Authorised place
<a id="p121370"></a>C Approved place
<a id="p121371"></a>D Other

<a id="p121372"></a>16 15 046 000 Qualifier of identification
<a id="p121373"></a>For the identification of the location use one of the identifiers below:


| <a id="p121374"></a>Qualifier | <a id="p121375"></a>Identifier | <a id="p121376"></a>Description |
| --- | --- | --- |
| <a id="p121377"></a>T | <a id="p121378"></a>Postcode address | <a id="p121379"></a>Use the postal code with or without house number for the location concerned. |
| <a id="p121380"></a>U | <a id="p121381"></a>UN/LOCODE | <a id="p121382"></a>UN/LOCODE as referred to in introductory note 13 number 4. |
| <a id="p121383"></a>V | <a id="p121384"></a>Customs office identifier | <a id="p121385"></a>Use the codes specified under D.E. 1 701 000 000 Customs office of exit. |
| <a id="p121386"></a>W | <a id="p121387"></a>GNSS coordinates | <a id="p121388"></a>Decimal degrees with negative numbers for South and West.<br>Examples: 44.424896°/8.774792° or 50.838068°/4.381508° |
| <a id="p121389"></a>X | <a id="p121390"></a>EORI number | <a id="p121391"></a>Use the identification number as specified in the description for D.E. 13 01 017 000 Exporter identification n°. In case the economic operator has more than one premises, the EORI number shall be completed by an identifier unique for the location concerned. |
| <a id="p121392"></a>Y | <a id="p121393"></a>Authorisation number | <a id="p121394"></a>Enter the authorisation number of the location concerned, i.e. of the warehouse where the goods can be examined. In case the authorisation concerns more than one premises, the authorisation number shall be completed by an identifier unique for the location concerned. |
| <a id="p121395"></a>Z | <a id="p121396"></a>Address | <a id="p121397"></a>Enter the address of the location concerned. |


<a id="p121398"></a>In case code "X" (EORI number) or "Y"(authorisation number) is used for the identification of the location, and there are several locations associated with the EORI number or the authorisation number concerned, an additional identifier can be used to enable the unambiguous identification of the location.

<a id="p121399"></a>16 17 000 000 Binding itinerary
<a id="p121400"></a>The relevant codes are given below:
<a id="p121401"></a>0 Goods are not moved from the Customs Office of Departure to the Customs Office of Destination along an economically justified itinerary
<a id="p121402"></a>1 Goods shall be moved from the Customs Office of Departure to the Customs
<a id="p121403"></a>Office of Destination along an economically justified itinerary

<a id="p121404"></a>17 01 000 000 Customs office of exit

<a id="p121405"></a>17 01 001 000 Reference number
<a id="p121406"></a>Use (an8) codes structured as follows:
- <a id="p121407"></a>the first two characters (a2) serve to identify the country by means of the GEONOM code as referred to in introductory note 13 number 3,
- <a id="p121408"></a>the next six characters (an6) stand for the office concerned in that country. It is suggested that the following structure be adopted:
<a id="p121409"></a>The first three characters (an3) would be taken up by the UN/LOCODE location name and the last three by a national alphanumericsubdivision (an3). If this subdivision is not used, the characters "000" should be inserted.

<a id="p121410"></a>19 01 000 000 Container indicator
<a id="p121411"></a>The relevant codes are given below:


| <a id="p121412"></a>0 | <a id="p121413"></a>Goods not transported in containers |
| --- | --- |
| <a id="p121414"></a>1 | <a id="p121415"></a>Goods transported in containers |


<a id="p121416"></a>19 03 000 000 Mode of transport at the border
<a id="p121417"></a>The codes applicable are given below:


| <a id="p121418"></a>Code | <a id="p121419"></a>Description |
| --- | --- |
| <a id="p121420"></a>1 | <a id="p121421"></a>Maritime transport |
| <a id="p121422"></a>2 | <a id="p121423"></a>Rail transport |
| <a id="p121424"></a>3 | <a id="p121425"></a>Road transport |
| <a id="p121426"></a>4 | <a id="p121427"></a>Air transport |
| <a id="p121428"></a>5 | <a id="p121429"></a>Mail (Active mode of transport unknown) |
| <a id="p121430"></a>7 | <a id="p121431"></a>Fixed transport installations |
| <a id="p121432"></a>8 | <a id="p121433"></a>Inland waterway transport |
| <a id="p121434"></a>9 | <a id="p121435"></a>Other mode of transport (i.e. own propulsion) |


<a id="p121436"></a>19 05 000 000 Departure transport means

<a id="p121437"></a>19 05 061 000 Type of identification
<a id="p121438"></a>The codes applicable are given below:


| <a id="p121439"></a>Code | <a id="p121440"></a>Description |
| --- | --- |
| <a id="p121441"></a>10 | <a id="p121442"></a>IMO ship identification number |
| <a id="p121443"></a>11 | <a id="p121444"></a>Name of the sea-going vessel |
| <a id="p121445"></a>20 | <a id="p121446"></a>Wagon number |
| <a id="p121447"></a>21 | <a id="p121448"></a>Train number |
| <a id="p121449"></a>30 | <a id="p121450"></a>Registration number of the road vehicle |
| <a id="p121451"></a>31 | <a id="p121452"></a>Registration number of the road trailer |
| <a id="p121453"></a>40 | <a id="p121454"></a>IATA flight number |
| <a id="p121455"></a>41 | <a id="p121456"></a>Registration number of the aircraft |
| <a id="p121457"></a>80 | <a id="p121458"></a>European Vessel Identification Number (ENI code) |
| <a id="p121459"></a>81 | <a id="p121460"></a>Name of the inland waterways vessel |


<a id="p121461"></a>19 07 000 000 Transport Equipment

<a id="p121462"></a>19 07 064 000 Container size and type identification
<a id="p121463"></a>The following codes shall be used:


| <a id="p121464"></a>Code | <a id="p121465"></a>Description |
| --- | --- |
| <a id="p121466"></a>1 | <a id="p121467"></a>Dime coated tank |
| <a id="p121468"></a>2 | <a id="p121469"></a>Epoxy coated tank |
| <a id="p121470"></a>6 | <a id="p121471"></a>Pressurised tank |
| <a id="p121472"></a>7 | <a id="p121473"></a>Refrigerated tank |
| <a id="p121474"></a>9 | <a id="p121475"></a>Stainless steel tank |
| <a id="p121476"></a>10 | <a id="p121477"></a>Non-working reefer container 40 feet |
| <a id="p121478"></a>12 | <a id="p121479"></a>Europallet - 80 x 120 cm |
| <a id="p121480"></a>13 | <a id="p121481"></a>Scandinavian pallet - 100 x 120 cm |
| <a id="p121482"></a>14 | <a id="p121483"></a>Trailer |
| <a id="p121484"></a>15 | <a id="p121485"></a>Non-working reefer container 20 feet |
| <a id="p121486"></a>16 | <a id="p121487"></a>Exchangeable pallet |
| <a id="p121488"></a>17 | <a id="p121489"></a>Semi-trailer |
| <a id="p121490"></a>18 | <a id="p121491"></a>Tank container 20 feet |
| <a id="p121492"></a>19 | <a id="p121493"></a>Tank container 30 feet |
| <a id="p121494"></a>20 | <a id="p121495"></a>Tank container 40 feet |
| <a id="p121496"></a>21 | <a id="p121497"></a>Container IC 20 feet, owned by InterContainer, a European railway subsidiary |
| <a id="p121498"></a>22 | <a id="p121499"></a>Container IC 30 feet, owned by InterContainer, a European railway subsidiary |
| <a id="p121500"></a>23 | <a id="p121501"></a>Container IC 40 feet, owned by InterContainer, a European railway subsidiary |
| <a id="p121502"></a>24 | <a id="p121503"></a>Refrigerated tank 20 feet |
| <a id="p121504"></a>25 | <a id="p121505"></a>Refrigerated tank 30 feet |
| <a id="p121506"></a>26 | <a id="p121507"></a>Refrigerated tank 40 feet |
| <a id="p121508"></a>27 | <a id="p121509"></a>Tank container IC 20 feet, owned by InterContainer, a European railway subsidiary |
| <a id="p121510"></a>28 | <a id="p121511"></a>Tank container IC 30 feet, owned by InterContainer, a European railway subsidiary |
| <a id="p121512"></a>29 | <a id="p121513"></a>Tank container IC 40 feet, owned by InterContainer, a European railway subsidiary |
| <a id="p121514"></a>30 | <a id="p121515"></a>Refrigerated tank IC 20 feet, owned by InterContainer, a European railway subsidiary |
| <a id="p121516"></a>31 | <a id="p121517"></a>Temperature controlled container 30 feet |
| <a id="p121518"></a>32 | <a id="p121519"></a>Refrigerated tank IC 40 feet, owned by InterContainer, a European railway subsidiary |
| <a id="p121520"></a>33 | <a id="p121521"></a>A movable case with a length less than 6,15 metres |
| <a id="p121522"></a>34 | <a id="p121523"></a>A movable case with a length between 6,15 metres and 7,82 metres |
| <a id="p121524"></a>35 | <a id="p121525"></a>A movable case with a length between 7,82 metres and 9,15 metres |
| <a id="p121526"></a>36 | <a id="p121527"></a>A movable case with a length between 9,15 metres and 10,90 metres |
| <a id="p121528"></a>37 | <a id="p121529"></a>A movable case with a length between 10,90 metres and 13,75 metres |
| <a id="p121530"></a>38 | <a id="p121531"></a>Totebin |
| <a id="p121532"></a>39 | <a id="p121533"></a>Temperature controlled container 20 feet |
| <a id="p121534"></a>40 | <a id="p121535"></a>Temperature controlled container 40 feet |
| <a id="p121536"></a>41 | <a id="p121537"></a>Non-working refrigerated (reefer) container 30 feet |
| <a id="p121538"></a>42 | <a id="p121539"></a>Dual trailers |
| <a id="p121540"></a>43 | <a id="p121541"></a>20 feet IL container (open top) |
| <a id="p121542"></a>44 | <a id="p121543"></a>20 feet IL container (closed top) |
| <a id="p121544"></a>45 | <a id="p121545"></a>40 feet IL container (closed top) |


<a id="p121546"></a>19 07 065 000 Container packed status
<a id="p121547"></a>The following codes shall be used:


| <a id="p121548"></a>Code | <a id="p121549"></a>Description | <a id="p121550"></a>Meaning |
| --- | --- | --- |
| <a id="p121551"></a>A | <a id="p121552"></a>Empty | <a id="p121553"></a>Indicates that the container is empty. |
| <a id="p121554"></a>B | <a id="p121555"></a>Not empty | <a id="p121556"></a>Indicates that the container is not empty. |


<a id="p121557"></a>19 07 066 000 Container supplier type code
<a id="p121558"></a>The following codes shall be used:


| <a id="p121559"></a>Code | <a id="p121560"></a>Description |
| --- | --- |
| <a id="p121561"></a>1 | <a id="p121562"></a>Shipper supplied |
| <a id="p121563"></a>2 | <a id="p121564"></a>Carrier supplied |


<a id="p121565"></a>99 02 000 000 Guarantee type
<a id="p121566"></a>The codes applicable are given below:


| <a id="p121567"></a>Code | <a id="p121568"></a>Description |
| --- | --- |
| <a id="p121569"></a>0 | <a id="p121570"></a>For guarantee waiver (Article 95(2) of the Code) |
| <a id="p121571"></a>1 | <a id="p121572"></a>For comprehensive guarantee (Article 89(5) of the Code) |
| <a id="p121573"></a>2 | <a id="p121574"></a>For individual guarantee in the form of an undertaking by a guarantor (Article 92(1)(b) of the Code) |
| <a id="p121575"></a>3 | <a id="p121576"></a>For individual guarantee in cash or other means of payment recognised by the customs authorities as being equivalent to a cash deposit, made in euro or in the currency of the Member State in which the guarantee is required (Article 92(1)(a) of the Code) |
| <a id="p121577"></a>4 | <a id="p121578"></a>For individual guarantee in the form of vouchers (Article 92(1)(b) of the Code and Article 160) |
| <a id="p121579"></a>5 | <a id="p121580"></a>For guarantee waiver where the amount of import or export duty to be secured does not exceed the statistical value threshold for declarations laid down in accordance with Article 3(4) of Regulation (EC) No 471/2009 of the European Parliament and of the Council <*> (Article 89(9) of the Code) |
| <a id="p121581"></a>8 | <a id="p121582"></a>For guarantee not required for certain public bodies (Article 89(7) of the Code) |
| <a id="p121583"></a>B | <a id="p121584"></a>For guarantee furnished for goods dispatched under TIR procedure |
| <a id="p121585"></a>R | <a id="p121586"></a>For guarantee not required for goods carried on the Rhine, the Rhine waterways, the Danube or the Danube waterways (Article 89(8)(a) of the Code) |
| <a id="p121587"></a>C | <a id="p121588"></a>For guarantee not required for goods carried by fix transport installations (Article 89(8)(b) of the Code) |
| <a id="p121589"></a>D | <a id="p121590"></a>For guarantee not required for goods placed under the temporary admission procedure in accordance with Article 81(a) of Delegated Regulation (EU) 2015/2446 (Article 89(8)(c) of the Code) |
| <a id="p121591"></a>E | <a id="p121592"></a>For guarantee not required for goods placed under the temporary admission procedure in accordance with Article 81(b) of Delegated Regulation (EU) 2015/2446 (Article 89(8)(c) of the Code) |
| <a id="p121593"></a>F | <a id="p121594"></a>For guarantee not required for goods placed under the temporary admission procedure in accordance with Article81(c) of Delegated Regulation (EU) 2015/2446 (Article 89(8)(c) of the Code) |
| <a id="p121595"></a>G | <a id="p121596"></a>For guarantee not required for goods placed under the temporary admission procedure in accordance with Article 81(d) of Delegated Regulation (EU) 2015/2446 (Article 89(8)(c) of the Code) |
| <a id="p121597"></a>H | <a id="p121598"></a>For guarantee not required for goods placed under the Union transit procedure in accordance with Article 89(8)(d) of the Code |
| <a id="p121599"></a>I | <a id="p121600"></a>For individual guarantee in another form which provides equivalent assurance that the amount of import or export duty corresponding to the customs debt and other charges will be paid (Article 92(1)(c) of the Code) |
| <a id="p121601"></a>J | <a id="p121602"></a>Guarantee not required for the journey between customs office of departure and customs office of transit - Article 10(2)(b) of the Convention of 20 May 1987 on a common transit procedure |


<a id="p121603"></a>

---

<a id="p121604"></a><*> Regulation (EC) No 471/2009 of the European Parliament and of the Council of 6 May 2009 on Community statistics relating to external trade with non-member countries and repealing Council Regulation (EC) No 1172/95 (OJ L 152, 16.6.2009, p. 23).

<a id="p121605"></a>**TITLE III. LINGUISTIC REFERENCES AND THEIR CODES**


<table>
<colgroup><col width="68%"><col width="32%"></colgroup>
<tr><td><a id="p121606"></a>Linguistic references</td><td><a id="p121607"></a>Codes</td></tr>
<tr><td><a id="p121608"></a>- BG Ограничена валидност</td><td><a id="p121609"></a>Limited validity</td></tr>
<tr><td><a id="p121610"></a>- CS Omezená platnost</td><td><a id="p121611"></a>- 99200</td></tr>
<tr><td><a id="p121612"></a>- DA Begrænset gyldighed</td><td></td></tr>
<tr><td><a id="p121613"></a>- DE Beschränkte Geltung</td><td></td></tr>
<tr><td><a id="p121614"></a>- EE Piiratud kehtivus</td><td></td></tr>
<tr><td><a id="p121615"></a>- EL $\iota\sigma\chi\text{ύ}\varsigma$ $\Pi\epsilon\rho\iota o\rho\iota\sigma\mu\text{έ}\nu\eta$</td><td></td></tr>
<tr><td><a id="p121616"></a>- ES Validez limitada</td><td></td></tr>
<tr><td><a id="p121617"></a>- FR limitée Validité</td><td></td></tr>
<tr><td><a id="p121618"></a>- HR Ogranièena valjanost</td><td></td></tr>
<tr><td><a id="p121619"></a>- IT Validità limitata</td><td></td></tr>
<tr><td><a id="p121620"></a>- LV derîgums Ierobežots</td><td></td></tr>
<tr><td><a id="p121621"></a>- LT Galiojimas apribotas</td><td></td></tr>
<tr><td><a id="p121622"></a>- HU érvényû Korlátozott</td><td></td></tr>
<tr><td><a id="p121623"></a>- MT Validità limitata</td><td></td></tr>
<tr><td><a id="p121624"></a>- NL Beperkte geldigheid</td><td></td></tr>
<tr><td><a id="p121625"></a>- PL Ograniczona $wa¿noœæ$</td><td></td></tr>
<tr><td><a id="p121626"></a>- PT Validade limitada</td><td></td></tr>
<tr><td><a id="p121627"></a>- RO Validitate limitatã</td><td></td></tr>
<tr><td><a id="p121628"></a>- SL Omejena veljavnost</td><td></td></tr>
<tr><td><a id="p121629"></a>- SK Obmedzená platnost'</td><td></td></tr>
<tr><td><a id="p121630"></a>- FI Voimassa rajoitetusti</td><td></td></tr>
<tr><td><a id="p121631"></a>- SV Begränsad giltighet</td><td></td></tr>
<tr><td><a id="p121632"></a>- EN Limited validity</td><td></td></tr>
<tr><td><a id="p121633"></a>- BG Освободено</td><td><a id="p121634"></a>Waiver - 99201</td></tr>
<tr><td><a id="p121635"></a>- CS Osvobození</td><td></td></tr>
<tr><td><a id="p121636"></a>- DA Fritaget</td><td></td></tr>
<tr><td><a id="p121637"></a>- DE Befreiung</td><td></td></tr>
<tr><td><a id="p121638"></a>- EE Loobutud</td><td></td></tr>
<tr><td><a id="p121639"></a>- EL $\text{Α}\pi\alpha\lambda\lambda\alpha\gamma\text{ή}$</td><td></td></tr>
<tr><td><a id="p121640"></a>- ES Dispensa</td><td></td></tr>
<tr><td><a id="p121641"></a>- FR Dispense</td><td></td></tr>
<tr><td><a id="p121642"></a>- HR Osloboðeno</td><td></td></tr>
<tr><td><a id="p121643"></a>- IT Dispensa</td><td></td></tr>
<tr><td><a id="p121644"></a>- LV Derîgs bez zîmoga</td><td></td></tr>
<tr><td><a id="p121645"></a>- LT Leista neplombuoti</td><td></td></tr>
<tr><td><a id="p121646"></a>- HU Mentesség</td><td></td></tr>
<tr><td><a id="p121647"></a>- MT $Tne©¤©ija¤$</td><td></td></tr>
<tr><td><a id="p121648"></a>- NL Vrijstelling</td><td></td></tr>
<tr><td><a id="p121649"></a>- PL Zwolnienie</td><td></td></tr>
<tr><td><a id="p121650"></a>- PT Dispensa</td><td></td></tr>
<tr><td><a id="p121651"></a>- RO Dispensã</td><td></td></tr>
<tr><td><a id="p121652"></a>- SL Opustitev</td><td></td></tr>
<tr><td><a id="p121653"></a>- SK Upustenie</td><td></td></tr>
<tr><td><a id="p121654"></a>- FI Vapautettu</td><td></td></tr>
<tr><td><a id="p121655"></a>- SV Befrielse</td><td></td></tr>
<tr><td><a id="p121656"></a>- EN Waiver</td><td></td></tr>
<tr><td><a id="p121657"></a>- BG Алтернативно доказателство</td><td rowspan="18"><a id="p121658"></a>Alternative proof<br>- 99202</td></tr>
<tr><td><a id="p121659"></a>- CS dùkaz Alternativní</td></tr>
<tr><td><a id="p121660"></a>- DA Alternativt bevis</td></tr>
<tr><td><a id="p121661"></a>- DE Alternativnachweis</td></tr>
<tr><td><a id="p121662"></a>- EE Alternatiivsed tõendid</td></tr>
<tr><td><a id="p121663"></a>- EL $\alpha\pi\text{ό}\delta\epsilon\iota\xi\eta$ $\text{Ε}\nu\alpha\lambda\lambda\alpha\kappa\tau\iota\kappa\text{ή}$</td></tr>
<tr><td><a id="p121664"></a>- ES Prueba alternativa</td></tr>
<tr><td><a id="p121665"></a>- FR Preuve alternative</td></tr>
<tr><td><a id="p121666"></a>- HR Alternativni dokaz</td></tr>
<tr><td><a id="p121667"></a>- IT Prova alternativa</td></tr>
<tr><td><a id="p121668"></a>- LV pierâdîjums Alternatîvs</td></tr>
<tr><td><a id="p121669"></a>- LT Alternatyvusis árodvmas</td></tr>
<tr><td><a id="p121670"></a>- HU igazolás Alternatív</td></tr>
<tr><td><a id="p121671"></a>- MT Prova alternattiva</td></tr>
<tr><td><a id="p121672"></a>- NL Alternatief bewijs</td></tr>
<tr><td><a id="p121673"></a>- PL Alternatywny dowód</td></tr>
<tr><td><a id="p121674"></a>- PT Prova alternativa</td></tr>
<tr><td><a id="p121675"></a>- RO alternativã Probã</td></tr>
<tr><td><a id="p121676"></a>- SL Alternativno dokazilo</td><td rowspan="5"></td></tr>
<tr><td><a id="p121677"></a>- SK Alternat vny dôkaz</td></tr>
<tr><td><a id="p121678"></a>- FI Vaihtoehtoinen todiste</td></tr>
<tr><td><a id="p121679"></a>- SV Alternativt bevis</td></tr>
<tr><td><a id="p121680"></a>- EN Alternative proof</td></tr>
<tr><td><a id="p121681"></a>- BG Различия: митническо учреждение, където са представени стоките ...... (наименование и държава)</td><td rowspan="23"><a id="p121682"></a>Differences: office where goods were presented ...... (name and country) - 99203</td></tr>
<tr><td><a id="p121683"></a>- CS Nesrovnalosti: ъøad , kterému bylo zboží pøedloženo ...... ( název a zemì )</td></tr>
<tr><td><a id="p121684"></a>- DA Forskelle: det sted, hvor varerne blev frembudt ...... (navn og land)</td></tr>
<tr><td><a id="p121685"></a>- DE Unstimmigkeiten: Stelle, bei der die Gestellung erfolgte ...... (Name und Land)</td></tr>
<tr><td><a id="p121686"></a>- EE Erinevused: asutus, kuhu kaup esitati ...... (nimi ja riik)</td></tr>
<tr><td><a id="p121687"></a>- EL $\Delta\iota\alpha\phi o\rho\text{έ}\varsigma:$ $\epsilon\mu\pi o\rho\epsilon\text{ύ}\mu\alpha\tau\alpha$ $\pi\rho o\sigma\kappa o\mu\iota\sigma\theta\text{έ}\nu\tau\alpha$ $\sigma\tau o$ $\tau\epsilon\lambda\omega\nu\epsilon\text{ί}o$ ...... ( $Ό\nu o\mu\alpha$ $\kappa\alpha\iota$ $\chi\text{ώ}\rho\alpha$ )</td></tr>
<tr><td><a id="p121688"></a>- ES Diferencias: mercancías presentadas en la oficina ...... (nombre y pa s)</td></tr>
<tr><td><a id="p121689"></a>- FR $Différences:$ marchandises présentées au bureau ...... (nom et pays) ...... (nom et pays)</td></tr>
<tr><td><a id="p121690"></a>- HR Razlike: carinarnica kojoj je roba podnesena ... (naziv i zemlja)</td></tr>
<tr><td><a id="p121691"></a>- IT Differenze: ufficio al quale sono state presentate le merci ...... (nome e paese)</td></tr>
<tr><td><a id="p121692"></a>- LV $Atšíirîbas:$ muitas iestâde , kurâ preces tika uzrâdîtas ...... (nosaukums un valsts)</td></tr>
<tr><td><a id="p121693"></a>- LT Skirtumai: ástaiga , kuriai pateiktos prekës ...... (pavadinimas ir valstybë )</td></tr>
<tr><td><a id="p121694"></a>- HU $Eltérések:$ hivatal, ahol az áruk bemutatása megtörtént ... ( név és ország )</td></tr>
<tr><td><a id="p121695"></a>- MT Differenzi: <img src="https://i.bukva.ai/sakP7uTQ/img_35.png" alt="..ufficc ju"> fejn <img src="https://i.bukva.ai/sakP7uTQ/img_36.png" alt="..l-ogg etti"> kienu $ppre¿entati$ ...... (isem u $pajji¿$ )</td></tr>
<tr><td><a id="p121696"></a>- NL Verschillen: kantoor waar de goederen zijn aange bracht ...... (naam en land)</td></tr>
<tr><td><a id="p121697"></a>- PL $Niezgodnoœci:$ urz¹d , w którym przedstawiono towar ...... (nazwa i kraj)</td></tr>
<tr><td><a id="p121698"></a>- PT $Diferenças:$ mercadorias apresentadas na estãncia ...... (nome e país )</td></tr>
<tr><td><a id="p121699"></a>- RO $Diferenþe:$ mãrfuri prezentate la biroul vamal ...... (nume ºi þara )</td></tr>
<tr><td><a id="p121700"></a>- SL Razlike: urad, pri katerem je bilo blago predloženo ...... (naziv in država )</td></tr>
<tr><td><a id="p121701"></a>- SK Rozdiely: úrad , ktorému bol tovar predložený ...... ( názov a krajina)</td></tr>
<tr><td><a id="p121702"></a>- FI Muutos: toimipaikka, jossa tavarat esitetty ...... (nimi ja maa)</td></tr>
<tr><td><a id="p121703"></a>- SV Avvikelse: tullkontor där varorna anmäldes ...... (namn och land)</td></tr>
<tr><td><a id="p121704"></a>- EN Differences: office where goods were presented ...... (name and country)</td></tr>
<tr><td><a id="p121705"></a>- BG Извеждането от ......... подлежи на ограничения<br>или такси съгласно Регламент/Директива/Решение N ...</td><td rowspan="23"><a id="p121706"></a>Exit from ........ subject to restrictions or charges under Regulation/Directive/Decision No ... - 99 204</td></tr>
<tr><td><a id="p121707"></a>- CS Výstup ze ............... podléhá omezením nebo dávkám podle naøízení / smìrnice / rozhodnutí <img src="https://i.bukva.ai/sakP7uTQ/img_37.png" alt="формула"> ...</td></tr>
<tr><td><a id="p121708"></a>- DA Udpassage lra undergivet restriktioner eller afgifter i henhold til forordning/direktiv/ afgørelse nr. ...</td></tr>
<tr><td><a id="p121709"></a>- DE Ausgang aus ............... - gemäß Verordnung/Richtlinie/Beschluss Nr. .... Beschränkungen oder Abgaben unterworfen</td></tr>
<tr><td><a id="p121710"></a>- EE ... territooriumilt väljumise suhtes kohaldatakse piiranguid ja makse vastavalt määrusele /direktiivile/otsusele nr...</td></tr>
<tr><td><a id="p121711"></a>- EL H $\text{έ}\xi o\delta o\varsigma$ $\alpha\pi\text{ό}$ ...... $\upsilon\pi o\beta\text{ά}\lambda\lambda\epsilon\tau\alpha\iota$ $\sigma\epsilon$ $\pi\epsilon\rho\iota o\rho\iota\sigma\mu o\text{ύ}\varsigma$ $\text{ή}$ $\sigma\epsilon$ $\epsilon\pi\iota\beta\alpha\rho\text{ύ}\nu\sigma\epsilon\iota\varsigma$ $\alpha\pi\text{ό}$ $\tau o\nu$ $\kappa\alpha\nu o\nu\iota\sigma\mu\text{ό}$ / $\tau\eta\nu$ $o\delta\eta\gamma\text{ί}\alpha$ / $\tau\eta\nu$ $\alpha\pi\text{ό}\phi\alpha\sigma\eta$ $\alpha\rho\iota\theta$ . ...</td></tr>
<tr><td><a id="p121712"></a>- ES Salida de ...... sometida a restricciones o imposiciones en virtud del (de la) Reglamento/Directiva/ Decisión no ...</td></tr>
<tr><td><a id="p121713"></a>- FR Sortie de ...... soumise $\text{а}$ des restrictions ou $\text{а}$ des impositions par le Règlement ou la directive/ décision no ...</td></tr>
<tr><td><a id="p121714"></a>- HR Izlaz iz ... podliježe ogranièenjima ili pristojbama na temelju Uredbe/Direktive/Odluke br. ...</td></tr>
<tr><td><a id="p121715"></a>- IT Uscita dalla ...............soggetta a restrizioni o ad imposizioni a norma del(la) regolamento/direttiva/decisione n. ...</td></tr>
<tr><td><a id="p121716"></a>- LV Izvešana no ............... piemçrojot ierobežojumus vai maksâjumus saskaòâ ar Regulu/ Direktîvu / Lçmumu Nr. ...</td></tr>
<tr><td><a id="p121717"></a>- LT Išvežimui iš ............... taikomi apribojimai arba mokesèiai , nustatyti Reglamentu/Direktyva/Sprendimu Nr ...</td></tr>
<tr><td><a id="p121718"></a>- HU A kilépés ............... területérõl a ... rendelet/ irányelv / határozat szerinti korlátozás vagy teher megfize - ésénekkötelezettsége alá esik</td></tr>
<tr><td><a id="p121719"></a>- MT <img src="https://i.bukva.ai/sakP7uTQ/img_38.png" alt="формула"> mill- ........ <img src="https://i.bukva.ai/sakP7uTQ/img_39.png" alt="..sug g ett"> $g©all¤$ -restrizzjonijiet jew $©lasij¤iet$ $ta©t¤$ Regola/Direttiva/ <img src="https://i.bukva.ai/sakP7uTQ/img_40.png" alt=".Dec i¿joni"> Nru ...</td></tr>
<tr><td><a id="p121720"></a>- NL Bij uitgang uit de ..................zijn de beperkingen of heffingen van Verordening/Richtlijn/Besluit nr. ... van toepassing</td></tr>
<tr><td><a id="p121721"></a>- PL Wyprowadzenie z ............... podlega ograniczeniom lub op atom zgodnie z rozporz¹dzeniem / dyrektyw¹ / decyzj¹ nr ...</td></tr>
<tr><td><a id="p121722"></a>- PT Saída da ............... sujeita a restrições ou a imposições pelo(a) Regulamento/Directiva/ Decisão n.o...</td></tr>
<tr><td><a id="p121723"></a>- RO Ieºire din ............... supusã restricþiilor sau impozitelor prin Regulamentul/Directiva/Decizia nr ...</td></tr>
<tr><td><a id="p121724"></a>- SL Iznos iz ............... zavezan omejitvam ali obveznim dajatvam na podlagi Uredbe/Direktive/ Odloèbe št. ...</td></tr>
<tr><td><a id="p121725"></a>- SK Výstup z ...............podlieha obmedzeniam alebo platbám pod a nariadenia/smernice/rozhodnutia <img src="https://i.bukva.ai/sakP7uTQ/img_41.png" alt="формула"> ....</td></tr>
<tr><td><a id="p121726"></a>- FI ............... vientiin sovelletaan asetuksen/direktiivin/ päätöksen N: o ... mukaisia rajoituksia tai maksuja</td></tr>
<tr><td><a id="p121727"></a>- SV Utförsel från ............... underkastad restriktioner eller avgifter i enlighet med förordning /direktiv/beslut nr ...</td></tr>
<tr><td><a id="p121728"></a>- EN Exit from ............... subject to restrictions or charges under Regulation/Directive/Decision No ...</td></tr>
<tr><td></td><td></td></tr>
<tr><td><a id="p121729"></a>- BG Одобрен изпращач</td><td rowspan="23"><a id="p121730"></a>Authorised consignor - 99206</td></tr>
<tr><td><a id="p121731"></a>- CS odesílatel Schválený</td></tr>
<tr><td><a id="p121732"></a>- DA Godkendt afsender</td></tr>
<tr><td><a id="p121733"></a>- DE Zugelassener Versender</td></tr>
<tr><td><a id="p121734"></a>- EE Volitatud kaubasaatja</td></tr>
<tr><td><a id="p121735"></a>- EL $\alpha\pi o\sigma\tau o\lambda\text{έ}\alpha\varsigma$ $\text{Ε}\gamma\kappa\epsilon\kappa\rho\iota\mu\text{έ}\nu o\varsigma$</td></tr>
<tr><td><a id="p121736"></a>- ES Expedidor autorizado</td></tr>
<tr><td><a id="p121737"></a>- FR agréé Expéditeur</td></tr>
<tr><td><a id="p121738"></a>- HR pošiljatelj Ovlašteni</td></tr>
<tr><td><a id="p121739"></a>- IT Speditore autorizzato</td></tr>
<tr><td><a id="p121740"></a>- LV nosûtîtâjs Atzîtais</td></tr>
<tr><td><a id="p121741"></a>- LT siuntëjas Ágaliotasis</td></tr>
<tr><td><a id="p121742"></a>- HU feladó Engedélyezett</td></tr>
<tr><td><a id="p121743"></a>- MT Awtorizzat li $jibg©at¤$</td></tr>
<tr><td><a id="p121744"></a>- NL Toegelaten afzender</td></tr>
<tr><td><a id="p121745"></a>- PL Upowa niony nadawca</td></tr>
<tr><td><a id="p121746"></a>- PT Expedidor autorizado</td></tr>
<tr><td><a id="p121747"></a>- RO Expeditor agreat</td></tr>
<tr><td><a id="p121748"></a>- SL pošiljatelj Pooblašèeni</td></tr>
<tr><td><a id="p121749"></a>- SK Schválený odosielatel'</td></tr>
<tr><td><a id="p121750"></a>- FI Valtuutettu lähettäjä</td></tr>
<tr><td><a id="p121751"></a>- SV avsändare Godkänd</td></tr>
<tr><td><a id="p121752"></a>- EN Authorised consignor</td></tr>
<tr><td><a id="p121753"></a>- BG Освободен от подпис</td><td rowspan="23"><a id="p121754"></a>Signature waived - 99207</td></tr>
<tr><td><a id="p121755"></a>- CS Podpis se nevyžaduje</td></tr>
<tr><td><a id="p121756"></a>- DA Fritaget for underskrift</td></tr>
<tr><td><a id="p121757"></a>- DE Freistellung von der Unterschriftsleistung</td></tr>
<tr><td><a id="p121758"></a>- EE Allkirjanõudest loobutud</td></tr>
<tr><td><a id="p121759"></a>- EL $\upsilon\pi o\gamma\rho\alpha\phi\text{ή}$ $\alpha\pi\alpha\iota\tau\epsilon\text{ί}\tau\alpha\iota$ $\Delta\epsilon\nu$</td></tr>
<tr><td><a id="p121760"></a>- ES Dispensa de firma</td></tr>
<tr><td><a id="p121761"></a>- FR Dispense de signature</td></tr>
<tr><td><a id="p121762"></a>- HR Osloboðeno potpisa</td></tr>
<tr><td><a id="p121763"></a>- IT Dispensa dalla firma</td></tr>
<tr><td><a id="p121764"></a>- LV Derîgs bez paraksta</td></tr>
<tr><td><a id="p121765"></a>- LT Leista nepasirašyti</td></tr>
<tr><td><a id="p121766"></a>- HU mentesítve alól Aláírás</td></tr>
<tr><td><a id="p121767"></a>- MT Firma mhux <img src="https://i.bukva.ai/sakP7uTQ/img_42.png" alt=".metieg a©¤"></td></tr>
<tr><td><a id="p121768"></a>- NL Van ondertekening vrijgesteld</td></tr>
<tr><td><a id="p121769"></a>- PL Zwolniony ze sk³adania podpisu</td></tr>
<tr><td><a id="p121770"></a>- PT Dispensada a assinatura</td></tr>
<tr><td><a id="p121771"></a>- RO Dispensã de semnãturã</td></tr>
<tr><td><a id="p121772"></a>- SL Opustitev podpisa</td></tr>
<tr><td><a id="p121773"></a>- SK Upustenie od podpisu</td></tr>
<tr><td><a id="p121774"></a>- FI Vapautettu allekirjoituksesta</td></tr>
<tr><td><a id="p121775"></a>- SV Befrielse från underskrift</td></tr>
<tr><td><a id="p121776"></a>- EN Signature waived</td></tr>
<tr><td><a id="p121777"></a>- BG ЗАБРАНЕНО ОБЩО ОБЕЗПЕЧЕНИЕ</td><td rowspan="23"><a id="p121778"></a>COMPREHENSIVE GUARANTEE PROHIBITED - 99208</td></tr>
<tr><td><a id="p121779"></a>- CS ZÁKAZ SOUBORNÉ JISTOTY</td></tr>
<tr><td><a id="p121780"></a>- DA FORBUD MOD SAMLET SIKKERHEDSSTILLELSE</td></tr>
<tr><td><a id="p121781"></a>- DE GESAMTBÜRGSCHAFT UNTERSAGT</td></tr>
<tr><td><a id="p121782"></a>- EE ÜLDTAGATISE KASUTAMINE KEELATUD</td></tr>
<tr><td><a id="p121783"></a>- EL $\text{Α}\Pi\text{Α}\Gamma\text{ΟΡΕΥΕΤΑΙ}$ H $\text{Ε}\Gamma\Gamma\text{ΥΗ}\Sigma\text{Η}$ $\Sigma\text{ΥΝΟ}\Lambda\text{ΙΚΗ}$</td></tr>
<tr><td><a id="p121784"></a>- ES GARANTÍA GLOBAL PROHIBIDA</td></tr>
<tr><td><a id="p121785"></a>- FR GARANTIE GLOBALE INTERDITE</td></tr>
<tr><td><a id="p121786"></a>- HR ZABRANJENO ZAJEDNIÈKO JAMSTVO</td></tr>
<tr><td><a id="p121787"></a>- IT GARANZIA GLOBALE VIETATA</td></tr>
<tr><td><a id="p121788"></a>- LV VISPÂRÇJS GALVOJUMS AIZLIEGTS</td></tr>
<tr><td><a id="p121789"></a>- LT NAUDOTI UŽDRAUSTA $GARANTIJ¥$ $BENDR¥J¥$</td></tr>
<tr><td><a id="p121790"></a>- HU ÖSSZKEZESSÉG TILOS</td></tr>
<tr><td><a id="p121791"></a>- MT MHUX PERMESSA GARANZIJA KOMPRENSIVA</td></tr>
<tr><td><a id="p121792"></a>- NL DOORLOPENDE ZEKERHEID VERBODEN</td></tr>
<tr><td><a id="p121793"></a>- PL ZAKAZ KORZYSTANIA Z ZABEZPIECZENIA GENERALNEGO</td></tr>
<tr><td><a id="p121794"></a>- PT GARANTIA GLOBAL PROIBIDA</td></tr>
<tr><td><a id="p121795"></a>- RO INTERZISÃ GLOBALÃ GARANÞIA</td></tr>
<tr><td><a id="p121796"></a>- SL PREPOVEDANO SKUPNO ZAVAROVANJE</td></tr>
<tr><td><a id="p121797"></a>- SK ZÁKAZ CELKOVEJ ZÁRUKY</td></tr>
<tr><td><a id="p121798"></a>- FI YLEISVAKUUDEN KÄYTTÖ KIELLETTY</td></tr>
<tr><td><a id="p121799"></a>- SV SAMLAD FÖRBJUDEN SÄKERHET</td></tr>
<tr><td><a id="p121800"></a>- EN COMPREHENSIVE GUARANTEE PROHIBITED</td></tr>
<tr><td><a id="p121801"></a>- BG ИЗПОЛЗВАНЕ БЕЗ ОГРАНИЧЕНИЯ</td><td rowspan="23"><a id="p121802"></a>UNRESTRICTED USE - 99209</td></tr>
<tr><td><a id="p121803"></a>- CS POUŽITÍ NEOMEZENÉ</td></tr>
<tr><td><a id="p121804"></a>- DA UBEGRÆNSET ANVENDELSE</td></tr>
<tr><td><a id="p121805"></a>- DE UNBESCHRÄNKTE VERWENDUNG</td></tr>
<tr><td><a id="p121806"></a>- EE PIIRAMATU KASUTAMINE</td></tr>
<tr><td><a id="p121807"></a>- EL $\text{ΧΡΗ}\Sigma\text{Η}$ $\text{Α}\Pi\text{ΕΡΙΟΡΙ}\Sigma\text{ΤΗ}$</td></tr>
<tr><td><a id="p121808"></a>- ES UTILIZACIÓN NO LIMITADA</td></tr>
<tr><td><a id="p121809"></a>- FR UTILISATION NON LIMITÉE</td></tr>
<tr><td><a id="p121810"></a>- HR NEOGRANIÈENA UPORABA</td></tr>
<tr><td><a id="p121811"></a>- IT UTILIZZAZIONE NON LIMITATA</td></tr>
<tr><td><a id="p121812"></a>- LV NEIEROBEŽOTS IZMANTOJUMS</td></tr>
<tr><td><a id="p121813"></a>- LT NEAPRIBOTAS NAUDOJIMAS</td></tr>
<tr><td><a id="p121814"></a>- HU KORLÁTOZÁS ALÁ NEM HASZNÁLAT ESÕ</td></tr>
<tr><td><a id="p121815"></a>- MT $U¯U$ MHUX RISTRETT</td></tr>
<tr><td><a id="p121816"></a>- NL GEBRUIK ONBEPERKT</td></tr>
<tr><td><a id="p121817"></a>- PL NIEOGRANICZONE KORZYSTANIE</td></tr>
<tr><td><a id="p121818"></a>- PT UTILIZAÇÃO ILIMITADA</td></tr>
<tr><td><a id="p121819"></a>- RO UTILIZARE NELIMITATÃ</td></tr>
<tr><td><a id="p121820"></a>- SL NEOMEJENA UPORABA</td></tr>
<tr><td><a id="p121821"></a>- SK POUŽITIE NEOBMEDZENÉ</td></tr>
<tr><td><a id="p121822"></a>- FI KÄYTTÖÄ EI RAJOITETTU</td></tr>
<tr><td><a id="p121823"></a>- SV ANVÄNDNING OBEGRÄNSAD</td></tr>
<tr><td><a id="p121824"></a>- EN UNRESTRICTED USE</td></tr>
<tr><td><a id="p121825"></a>- BG Разни</td><td rowspan="23"><a id="p121826"></a>Various - 99211</td></tr>
<tr><td><a id="p121827"></a>- CS Rùzní</td></tr>
<tr><td><a id="p121828"></a>- DA Diverse</td></tr>
<tr><td><a id="p121829"></a>- DE Verschiedene</td></tr>
<tr><td><a id="p121830"></a>- EE Erinevad</td></tr>
<tr><td><a id="p121831"></a>- EL $\Delta\iota\text{ά}\phi o\rho\alpha$</td></tr>
<tr><td><a id="p121832"></a>- ES Varios</td></tr>
<tr><td><a id="p121833"></a>- FR Divers</td></tr>
<tr><td><a id="p121834"></a>- HR Razni</td></tr>
<tr><td><a id="p121835"></a>- IT Vari</td></tr>
<tr><td><a id="p121836"></a>- LV Dažâdi</td></tr>
<tr><td><a id="p121837"></a>- LT Ávairûs</td></tr>
<tr><td><a id="p121838"></a>- HU Többféle</td></tr>
<tr><td><a id="p121839"></a>- MT Diversi</td></tr>
<tr><td><a id="p121840"></a>- NL Diverse</td></tr>
<tr><td><a id="p121841"></a>- PL $Ró¿ne$</td></tr>
<tr><td><a id="p121842"></a>- PT Diversos</td></tr>
<tr><td><a id="p121843"></a>- RO Diverºi</td></tr>
<tr><td><a id="p121844"></a>- SL Razno</td></tr>
<tr><td><a id="p121845"></a>- SK Rôzne</td></tr>
<tr><td><a id="p121846"></a>- FI Useita</td></tr>
<tr><td><a id="p121847"></a>- SV Flera</td></tr>
<tr><td><a id="p121848"></a>- EN Various</td></tr>
<tr><td><a id="p121849"></a>- BG Насипно</td><td rowspan="23"><a id="p121850"></a>Bulk - 99212</td></tr>
<tr><td><a id="p121851"></a>- CS loženo Volnì</td></tr>
<tr><td><a id="p121852"></a>- DA Bulk</td></tr>
<tr><td><a id="p121853"></a>- DE Lose</td></tr>
<tr><td><a id="p121854"></a>- EE Pakendamata</td></tr>
<tr><td><a id="p121855"></a>- EL $\text{Χύ}\mu\alpha$</td></tr>
<tr><td><a id="p121856"></a>- ES A granel</td></tr>
<tr><td><a id="p121857"></a>- FR Vrac</td></tr>
<tr><td><a id="p121858"></a>- HR Rasuto</td></tr>
<tr><td><a id="p121859"></a>- IT Alla rinfusa</td></tr>
<tr><td><a id="p121860"></a>- LV Berams (lejams)</td></tr>
<tr><td><a id="p121861"></a>- LT Nesupakuota</td></tr>
<tr><td><a id="p121862"></a>- HU Ömlesztett</td></tr>
<tr><td><a id="p121863"></a>- MT Bil - kwantità</td></tr>
<tr><td><a id="p121864"></a>- NL Los gestort</td></tr>
<tr><td><a id="p121865"></a>- PL Luzem</td></tr>
<tr><td><a id="p121866"></a>- PT A granel</td></tr>
<tr><td><a id="p121867"></a>- RO Vrac</td></tr>
<tr><td><a id="p121868"></a>- SL Razsuto</td></tr>
<tr><td><a id="p121869"></a>- SK Vol'ne ložené</td></tr>
<tr><td><a id="p121870"></a>- FI Irtotavaraa</td></tr>
<tr><td><a id="p121871"></a>- SV Bulk</td></tr>
<tr><td><a id="p121872"></a>- EN Bulk</td></tr>
<tr><td><a id="p121873"></a>- BG Изпращач</td><td rowspan="23"><a id="p121874"></a>Consignor - 99213</td></tr>
<tr><td><a id="p121875"></a>- CS Odesílatel</td></tr>
<tr><td><a id="p121876"></a>- DA Afsender</td></tr>
<tr><td><a id="p121877"></a>- DE Versender</td></tr>
<tr><td><a id="p121878"></a>- EE Saatja</td></tr>
<tr><td><a id="p121879"></a>- EL $\text{Α}\pi o\sigma\tau o\lambda\text{έ}\alpha\varsigma$</td></tr>
<tr><td><a id="p121880"></a>- ES Expedidor</td></tr>
<tr><td><a id="p121881"></a>- FR Expéditeur</td></tr>
<tr><td><a id="p121882"></a>- HR Pošiljatelj</td></tr>
<tr><td><a id="p121883"></a>- IT Speditore</td></tr>
<tr><td><a id="p121884"></a>- LV Nosûtîtâjs</td></tr>
<tr><td><a id="p121885"></a>- LT Siuntëjas</td></tr>
<tr><td><a id="p121886"></a>- HU Feladó</td></tr>
<tr><td><a id="p121887"></a>- MT Min jikkonsenja</td></tr>
<tr><td><a id="p121888"></a>- NL Afzender</td></tr>
<tr><td><a id="p121889"></a>- PL Nadawca</td></tr>
<tr><td><a id="p121890"></a>- PT Expedidor</td></tr>
<tr><td><a id="p121891"></a>- RO Expeditor</td></tr>
<tr><td><a id="p121892"></a>- SL Pošiljatelj</td></tr>
<tr><td><a id="p121893"></a>- SK Odosielatel'</td></tr>
<tr><td><a id="p121894"></a>- FI Lähettäjä</td></tr>
<tr><td><a id="p121895"></a>- SV Avsändare</td></tr>
<tr><td><a id="p121896"></a>- EN Consignor</td></tr>
</table>


<a id="p121897"></a>Annex C

<a id="p121898"></a>**FORMATS AND CODES OF THE COMMON DATA REQUIREMENTS FOR**
**DECLARATIONS, NOTIFICATIONS AND PROOF OF THE CUSTOMS STATUS**
OF UNION GOODS (ARTICLE 2(4a))

<a id="p121899"></a>**INTRODUCTORY NOTES**

1. <a id="p121900"></a>The formats, codes and, if applicable, the structure of the data elements included in this Annex are applicable in relation with the data requirements for declarations notifications and proof of the customs status of Union goods as provided for in Annex D to Delegated Regulation (EU) 2015/2446.
2. <a id="p121901"></a>The formats, codes and, if applicable, the structure of the data elements defined in this Annex shall apply to declarations, notifications and proof of the customs status of Union goods made by using an electronic data processing technique as well as to paper-based declarations, notifications and proof of the customs status of Union goods.
3. <a id="p121902"></a>Title I includes the formats of the data elements.
4. <a id="p121903"></a>Whenever the information in a declaration, notification or proof of the customs status of Union goods dealt with in Annex D to Delegated Regulation (EU) 2015/2446 takes the form of codes, the code-list provided for in Title II shall be applied.
5. <a id="p121904"></a>The term "type/length" in the explanation of an attribute indicates the requirements for the data type and the data length. The codes for the data types are as follows:


| <a id="p121905"></a>a | <a id="p121906"></a>alphabetic |
| --- | --- |
| <a id="p121907"></a>n | <a id="p121908"></a>numeric |
| <a id="p121909"></a>an | <a id="p121910"></a>alphanumeric |


<a id="p121911"></a>The number following the code indicates the admissible data length. The following applies.
<a id="p121912"></a>The optional two dots before the length indicator mean that the data has no fixed length, but it can have up to a number of digits, as specified by the length indicator. A comma in the data length means that the attribute can hold decimals, the digit before the comma indicates the total length of the attribute, the digit after the comma indicates the maximum number of digits after the decimal point.
<a id="p121913"></a>Examples of field lengths and formats:


| <a id="p121914"></a>a1 | <a id="p121915"></a>1 alphabetic character, fixed length |
| --- | --- |
| <a id="p121916"></a>n2 | <a id="p121917"></a>2 numeric characters, fixed length |
| <a id="p121918"></a>an3 | <a id="p121919"></a>3 alphanumeric, fixed length |
| <a id="p121920"></a>a..4 | <a id="p121921"></a>up to 4 alphabetic characters |
| <a id="p121922"></a>n..5 | <a id="p121923"></a>up to 5 numeric characters |
| <a id="p121924"></a>an..6 | <a id="p121925"></a>up to 6 alphanumeric characters |
| <a id="p121926"></a>n..7,2 | <a id="p121927"></a>up to 7 numeric characters including maximum 2 decimals, a delimiter being allowed to float |


6. <a id="p121928"></a>The cardinality at header level included in the table in Title I of this Annex indicates how many times the data element may be used at header level within a declaration, notification or proof of the customs status of Union goods.
7. <a id="p121929"></a>The cardinality at item level included in the table in Title I of this Annex indicates how many times the data element may be repeated in relation with the declaration item concerned.
8. <a id="p121930"></a>National codes can be used by Member States for data elements 1/11 Additional procedure, 2/2 Additional information, 2/3 Documents produced, certificates and authorisations, additional references, 4/3 Calculation of taxes (Tax type), 4/4 Calculation of taxes (Tax base) and 6/17 Commodity code (national additional codes). Member States shall notify the Commission of the list of national codes used for these data elements. The Commission shall publish the list of those codes.

<a id="p121931"></a>**TITLE I. FORMATS AND CARDINALITY OF THE COMMON DATA**
**REQUIREMENTS FOR DECLARATIONS AND NOTIFICATIONS**


<table>
<colgroup><col width="7%"><col width="13%"><col width="21%"><col width="10%"><col width="10%"><col width="9%"><col width="30%"></colgroup>
<tr><td><a id="p121932"></a>D.E. order number</td><td><a id="p121933"></a>D.E. name</td><td><a id="p121934"></a>D.E. format (Type/length)</td><td><a id="p121935"></a>Code-list in Title II<br>(Y/N)</td><td><a id="p121936"></a>Header level cardinality</td><td><a id="p121937"></a>Item level cardinality</td><td><a id="p121938"></a>Notes</td></tr>
<tr><td><a id="p121939"></a>1/1</td><td><a id="p121940"></a>Declaration type</td><td><a id="p121941"></a>a2</td><td><a id="p121942"></a>Y</td><td><a id="p121943"></a>1x</td><td></td><td></td></tr>
<tr><td><a id="p121944"></a>1/2</td><td><a id="p121945"></a>Additional declaration type</td><td><a id="p121946"></a>a1</td><td><a id="p121947"></a>Y</td><td><a id="p121948"></a>1x</td><td></td><td></td></tr>
<tr><td><a id="p121949"></a>1/6</td><td><a id="p121950"></a>Goods item number</td><td><a id="p121951"></a>n..5</td><td><a id="p121952"></a>N</td><td></td><td><a id="p121953"></a>1x</td><td></td></tr>
<tr><td><a id="p121954"></a>1/8</td><td><a id="p121955"></a>Signature/authentication</td><td><a id="p121956"></a>an..35</td><td><a id="p121957"></a>N</td><td><a id="p121958"></a>1x</td><td></td><td></td></tr>
<tr><td><a id="p121959"></a>1/10</td><td><a id="p121960"></a>Procedure</td><td><a id="p121961"></a>Requested procedure code: an2 +<br>Previous procedure code: an2</td><td><a id="p121962"></a>Y</td><td></td><td><a id="p121963"></a>1x</td><td></td></tr>
<tr><td><a id="p121964"></a>1/11</td><td><a id="p121965"></a>Additional procedure</td><td><a id="p121966"></a>Union codes: a1 + an2<br>OR<br>National codes: n1 + an2</td><td><a id="p121967"></a>Y</td><td></td><td><a id="p121968"></a>99x</td><td><a id="p121969"></a>The Union codes are further specified in Title II</td></tr>
<tr><td><a id="p121970"></a>2/1</td><td><a id="p121971"></a>Simplified declaration/Previous documents</td><td><a id="p121972"></a>Previous document type: an..3 +<br>Previous document reference: an..35 +<br>Goods item identifier: n..5 +<br>Type of packages: an..2<br>Number of packages: n..8 Measurement unit and qualifier, if applicable: an..4 +<br>Quantity: n..16,6</td><td><a id="p121973"></a>Y</td><td><a id="p121974"></a>9,999<br>x</td><td><a id="p121975"></a>99x</td><td><a id="p121976"></a>The measurement units and qualifiers defined in TARIC shall be used. In such case, the format of the measurement units and qualifiers shall be an..4, but shall never be n..4 formats, reserved for national measurement units and qualifiers.<br>If no such measurement units and qualifiers are available in TARIC, national measurement units and qualifiers may be used. Their format shall be n..4.</td></tr>
<tr><td><a id="p121977"></a>2/2</td><td><a id="p121978"></a>Additional information</td><td><a id="p121979"></a>Coded version<br>(Union codes): n1 + an4<br>OR<br>(national codes): a1 +an4 OR<br>Free text description:<br>an..512</td><td><a id="p121980"></a>Y</td><td><a id="p121981"></a>99x</td><td><a id="p121982"></a>99x</td><td><a id="p121983"></a>The Union codes are further specified in Title II</td></tr>
<tr><td><a id="p121984"></a>2/3</td><td><a id="p121985"></a>Documents produced, certificates and authorisations, additional references</td><td><a id="p121986"></a>Document type (Union codes): a1 + an3 + (if applicable)<br>Document identifier: an..35 OR<br>Document type (national codes): n1 + an3 + (if applicable)<br>Document identifier: an..35 + (if applicable)<br>Issuing authority name: an..70 +<br>Date of validity: n8 (yyyymmdd) +<br>Measurement unit and qualifier, if applicable: an..4 +<br>Quantity: n..16,6 +<br>Currency code: a3 +<br>Amount: n..16,2</td><td><a id="p121987"></a>Y</td><td><a id="p121988"></a>99x</td><td><a id="p121989"></a>99x</td><td><a id="p121990"></a>The measurement units and qualifiers defined in TARIC shall be used. In such case, the format of the measurement units and qualifiers shall be an..4, but shall never be n..4 formats, reserved for national measurement units and qualifiers.<br>If no such measurement units and qualifiers are available in TARIC, national measurement units and qualifiers may be used. Their format shall be n..4.<br>The ISO-alpha-3 currency codes (ISO 4217) shall be used for the currency.</td></tr>
<tr><td><a id="p121991"></a>2/4</td><td><a id="p121992"></a>Reference number/<br>UCR</td><td><a id="p121993"></a>an..35</td><td><a id="p121994"></a>N</td><td><a id="p121995"></a>1x</td><td><a id="p121996"></a>1x</td><td><a id="p121997"></a>This data element may take the form of WCO (ISO 15459) codes or equivalent.</td></tr>
<tr><td><a id="p121998"></a>2/5</td><td><a id="p121999"></a>LRN</td><td><a id="p122000"></a>an..22</td><td><a id="p122001"></a>N</td><td><a id="p122002"></a>1x</td><td></td><td></td></tr>
<tr><td><a id="p122003"></a>2/6</td><td><a id="p122004"></a>Deferred payment</td><td><a id="p122005"></a>an..35</td><td><a id="p122006"></a>N</td><td><a id="p122007"></a>1x</td><td></td><td></td></tr>
<tr><td><a id="p122008"></a>2/7</td><td><a id="p122009"></a>Identification of warehouse</td><td><a id="p122010"></a>Warehouse type: a1 +<br>Warehouse identifier:<br>an..35</td><td><a id="p122011"></a>Y</td><td><a id="p122012"></a>1x</td><td></td><td></td></tr>
<tr><td><a id="p122013"></a>3/1</td><td><a id="p122014"></a>Exporter</td><td><a id="p122015"></a>Name: an..70 +<br>Street and number: an..70 +<br>Country: a2 +<br>Postcode: an..9 +<br>City: an..35</td><td><a id="p122016"></a>N</td><td><a id="p122017"></a>1x</td><td><a id="p122018"></a>1x</td><td><a id="p122019"></a>Country code:<br>The Union's alphabetic codes for countries and territories are based on the current ISO alpha 2 codes (a2) in so far as they are compatible with the requirements of Commission Implementing Regulation (EU) No 2020/1470 of 12 October 2020 on the nomenclature of countries and territories &lt;*&gt; for the European statistics on international trade in goods and on the geographical breakdown for other business statistics (OJ L 334, 13.10.2020, p. 2 - 21). The Commission regularly publishes regulations<br>updating the list of country codes.<br>In case of groupage consignments, where paper-based declarations are used, code "00200" may be used together with a list of exporters in accordance with the notes described for D.E. 3/1 Exporter in Title II of Annex D to Delegated Regulation (EU) 2015/2446.</td></tr>
<tr><td><a id="p122020"></a>3/2</td><td><a id="p122021"></a>Exporter identification no</td><td><a id="p122022"></a>an..17</td><td><a id="p122023"></a>N</td><td><a id="p122024"></a>1x</td><td><a id="p122025"></a>1x</td><td><a id="p122026"></a>The structure of the EORI number is defined in Title II.<br>The structure of a third country unique identification number recognised by the Union is defined in Title II.</td></tr>
<tr><td><a id="p122027"></a>3/15</td><td><a id="p122028"></a>Importer</td><td><a id="p122029"></a>Name: an..70 +<br>Street and number: an..70 +<br>Country: a2 +<br>Postcode: an..9 +<br>City: an..35</td><td><a id="p122030"></a>N</td><td><a id="p122031"></a>1x</td><td></td><td><a id="p122032"></a>The country code as defined for D.E. 3/1 Exporter shall be used.</td></tr>
<tr><td><a id="p122033"></a>3/16</td><td><a id="p122034"></a>Importer identification no</td><td><a id="p122035"></a>an..17</td><td><a id="p122036"></a>N</td><td><a id="p122037"></a>1x</td><td></td><td><a id="p122038"></a>The EORI number shall follow the structure defined in Title II for D.E. 3/2 Exporter identification no.</td></tr>
<tr><td><a id="p122039"></a>3/17</td><td><a id="p122040"></a>Declarant</td><td><a id="p122041"></a>Name: an..70 +<br>Street and number: an..70 +<br>Country: a2 +<br>Postcode: an..9 +<br>City: an..35</td><td><a id="p122042"></a>N</td><td><a id="p122043"></a>1x</td><td></td><td><a id="p122044"></a>The country code as defined for D.E. 3/1 Exporter shall be used.</td></tr>
<tr><td><a id="p122045"></a>3/18</td><td><a id="p122046"></a>Declarant identification no</td><td><a id="p122047"></a>an..17</td><td><a id="p122048"></a>N</td><td><a id="p122049"></a>1x</td><td></td><td><a id="p122050"></a>The EORI number shall follow the structure defined in Title II for D.E. 3/2 Exporter identification no</td></tr>
<tr><td><a id="p122051"></a>3/19</td><td><a id="p122052"></a>Representative</td><td><a id="p122053"></a>Name: an..70 +<br>Street and number: an..70 +<br>Country: a2 +<br>Postcode: an..9 +<br>City: an..35 +</td><td><a id="p122054"></a>N</td><td><a id="p122055"></a>1x</td><td></td><td><a id="p122056"></a>The country code as defined for D.E. 3/1 Exporter shall be used.</td></tr>
<tr><td><a id="p122057"></a>3/20</td><td><a id="p122058"></a>Representative identification no</td><td><a id="p122059"></a>an..17</td><td><a id="p122060"></a>N</td><td><a id="p122061"></a>1x</td><td></td><td><a id="p122062"></a>The EORI number shall follow the structure defined in Title II for D.E. 3/2 Exporter identification no.</td></tr>
<tr><td><a id="p122063"></a>3/21</td><td><a id="p122064"></a>Representative<br>status code</td><td><a id="p122065"></a>n1</td><td><a id="p122066"></a>Y</td><td><a id="p122067"></a>1x</td><td></td><td></td></tr>
<tr><td><a id="p122068"></a>3/24</td><td><a id="p122069"></a>Seller</td><td><a id="p122070"></a>Name: an..70 +<br>Street and number: an..70 +<br>Country: a2 +<br>Postcode: an..9 +<br>City: an..35 +<br>Phone number: an..50</td><td><a id="p122071"></a>N</td><td><a id="p122072"></a>1x</td><td><a id="p122073"></a>1x</td><td><a id="p122074"></a>The country code as defined for D.E. 3/1 Exporter shall be used.</td></tr>
<tr><td><a id="p122075"></a>3/25</td><td><a id="p122076"></a>Seller identification no</td><td><a id="p122077"></a>an..17</td><td><a id="p122078"></a>N</td><td><a id="p122079"></a>1x</td><td><a id="p122080"></a>1x</td><td><a id="p122081"></a>The EORI number shall follow the structure defined in Title II for D.E. 3/2 Exporter identification no.<br>The structure of a third country unique identification number shall follow the structure defined in Title II for D.E. 3/2 Exporter identification no.</td></tr>
<tr><td><a id="p122082"></a>3/26</td><td><a id="p122083"></a>Buyer</td><td><a id="p122084"></a>Name: an..70 +<br>Street and number: an..70 +<br>Country: a2 +<br>Postcode: an..9 +<br>City: an..35 +<br>Phone number: an..50</td><td><a id="p122085"></a>N</td><td><a id="p122086"></a>1x</td><td><a id="p122087"></a>1x</td><td><a id="p122088"></a>The country code as defined for D.E. 3/1 Exporter shall be used.</td></tr>
<tr><td><a id="p122089"></a>3/27</td><td><a id="p122090"></a>Buyer identifi<br>cation no</td><td><a id="p122091"></a>an..17</td><td><a id="p122092"></a>N</td><td><a id="p122093"></a>1x</td><td><a id="p122094"></a>1x</td><td><a id="p122095"></a>The EORI number shall follow the structure defined in Title II for D.E. 3/2 Exporter identification no.<br>The structure of a third country unique identification number shall follow the structure defined in Title II for D.E. 3/2 Exporter identification no.</td></tr>
<tr><td><a id="p122096"></a>3/37</td><td><a id="p122097"></a>Additional supply chain actor(s) identification no</td><td><a id="p122098"></a>Role code: a..3 +<br>Identifier: an..17</td><td><a id="p122099"></a>Y</td><td><a id="p122100"></a>99x</td><td><a id="p122101"></a>99x</td><td><a id="p122102"></a>The role codes for the additional supply chain actors are defined in Title II.<br>The EORI number shall follow the structure defined in Title II for D.E. 3/2 Exporter identification no.<br>The structure of a third country unique identification number shall follow the structure defined in Title II for D.E. 3/2 Exporter identification no.</td></tr>
<tr><td rowspan="2"><a id="p122103"></a>3/39</td><td rowspan="2"><a id="p122104"></a>Holder of the authorisation identification no</td><td rowspan="2"><a id="p122105"></a>Authorisation type code: an..4 +<br>Identifier: an..17</td><td rowspan="2"><a id="p122106"></a>N</td><td rowspan="2"><a id="p122107"></a>99x</td><td rowspan="2"></td><td><a id="p122108"></a>The codes defined in Annex A for D.E. 1/1 Application/Decision code type shall be used for the authorisation type code.</td></tr>
<tr><td><a id="p122109"></a>The EORI number shall follow the structure defined in Title II for D.E. 3/2 Exporter identification no.</td></tr>
<tr><td><a id="p122110"></a>3/40</td><td><a id="p122111"></a>Additional fiscal references identification no</td><td><a id="p122112"></a>Role code: an3 +<br>VAT identification number: an..17</td><td><a id="p122113"></a>Y</td><td><a id="p122114"></a>99x</td><td><a id="p122115"></a>99x</td><td><a id="p122116"></a>The role codes for the additional fiscal references are defined in Title II.</td></tr>
<tr><td><a id="p122117"></a>3/41</td><td><a id="p122118"></a>Person presenting the goods to customs in case of entry in the declarant's records or pre-lodged customs declarations identification no</td><td><a id="p122119"></a>an..17</td><td><a id="p122120"></a>N</td><td><a id="p122121"></a>1x</td><td></td><td><a id="p122122"></a>The EORI number shall follow the structure defined in Title II for D.E. 3/2 Exporter identification no.</td></tr>
<tr><td><a id="p122123"></a>3/45</td><td><a id="p122124"></a>Person providing a guarantee identification no</td><td><a id="p122125"></a>an..17</td><td><a id="p122126"></a>N</td><td><a id="p122127"></a>1x</td><td></td><td><a id="p122128"></a>The EORI number shall follow the structure defined in Title II for D.E. 3/2 Exporter identification no.</td></tr>
<tr><td><a id="p122129"></a>3/46</td><td><a id="p122130"></a>Person paying the customs duty identification no</td><td><a id="p122131"></a>an..17</td><td><a id="p122132"></a>N</td><td><a id="p122133"></a>1x</td><td></td><td><a id="p122134"></a>The EORI number shall follow the structure defined in Title II for D.E. 3/2 Exporter identification no.</td></tr>
<tr><td><a id="p122135"></a>4/1</td><td><a id="p122136"></a>Delivery terms</td><td><a id="p122137"></a>Coded version: INCOTERM code: a3 + UN/LOCODE: an..17<br>OR<br>Free text description:<br>INCOTERM code: a3 + Country code: a2 +<br>Location name: an..35</td><td><a id="p122138"></a>Y</td><td><a id="p122139"></a>1x</td><td></td><td><a id="p122140"></a>The codes and headings describing the commercial contract are defined in Title II. The code provided for the description of the location shall adhere to the pattern of UN/LOCODE. If no UN/LOCODE is available for the location, use the country code as provided for D.E. 3/1 Exporter followed by the name of the location.</td></tr>
<tr><td><a id="p122141"></a>4/3</td><td><a id="p122142"></a>Calculation of taxes - Tax type</td><td><a id="p122143"></a>Union codes: a1 + n2<br>OR<br>National codes: n1 + an2</td><td><a id="p122144"></a>Y</td><td></td><td><a id="p122145"></a>99x</td><td><a id="p122146"></a>The Union codes are further specified in Title II</td></tr>
<tr><td><a id="p122147"></a>4/4</td><td><a id="p122148"></a>Calculation of taxes - Tax base</td><td><a id="p122149"></a>Measurement unit and qualifier, if applicable: an..6 +<br>Quantity: n..16,6<br>OR<br>Amount: n..16,2</td><td><a id="p122150"></a>N</td><td></td><td><a id="p122151"></a>99x</td><td><a id="p122152"></a>The measurement units and qualifiers defined in TARIC should be used. In such case, the format of the measurement units and<br>qualifiers will be an..6, but will never have n..6<br>formats, reserved for<br>national measurement units and qualifiers.<br>If no such measurement units and qualifiers are available in TARIC, national<br>measurement units and qualifiers can be used. Their format will be n..6.</td></tr>
<tr><td><a id="p122153"></a>4/5</td><td><a id="p122154"></a>Calculation of taxes - Tax rate</td><td><a id="p122155"></a>n..17,3</td><td><a id="p122156"></a>N</td><td></td><td><a id="p122157"></a>99x</td><td></td></tr>
<tr><td><a id="p122158"></a>4/6</td><td><a id="p122159"></a>Calculation of taxes - Payable tax amount</td><td><a id="p122160"></a>n..16,2</td><td><a id="p122161"></a>N</td><td></td><td><a id="p122162"></a>99x</td><td></td></tr>
<tr><td><a id="p122163"></a>4/7</td><td><a id="p122164"></a>Calculation of taxes - Total</td><td><a id="p122165"></a>n..16,2</td><td><a id="p122166"></a>N</td><td></td><td><a id="p122167"></a>1x</td><td></td></tr>
<tr><td><a id="p122168"></a>4/8</td><td><a id="p122169"></a>Calculation of taxes - Method of payment</td><td><a id="p122170"></a>a1</td><td><a id="p122171"></a>Y</td><td></td><td><a id="p122172"></a>99x</td><td></td></tr>
<tr><td><a id="p122173"></a>4/9</td><td><a id="p122174"></a>Additions and deductions</td><td><a id="p122175"></a>Code: a2 +<br>Amount: n..16,2</td><td><a id="p122176"></a>Y</td><td><a id="p122177"></a>99x</td><td><a id="p122178"></a>99x</td><td></td></tr>
<tr><td><a id="p122179"></a>4/10</td><td><a id="p122180"></a>Invoice currency</td><td><a id="p122181"></a>a3</td><td><a id="p122182"></a>N</td><td><a id="p122183"></a>1x</td><td></td><td><a id="p122184"></a>The ISO-alpha-3 currency codes (ISO 4217) shall be used for the currency.</td></tr>
<tr><td><a id="p122185"></a>4/11</td><td><a id="p122186"></a>Total amount invoiced</td><td><a id="p122187"></a>n..16,2</td><td><a id="p122188"></a>N</td><td><a id="p122189"></a>1x</td><td></td><td></td></tr>
<tr><td><a id="p122190"></a>4/12</td><td><a id="p122191"></a>Internal currency unit</td><td><a id="p122192"></a>a3</td><td><a id="p122193"></a>N</td><td><a id="p122194"></a>1x</td><td></td><td><a id="p122195"></a>The ISO-alpha-3 currency codes (ISO 4217) shall be used for the currency.</td></tr>
<tr><td><a id="p122196"></a>4/13</td><td><a id="p122197"></a>Valuation indicators</td><td><a id="p122198"></a>an4</td><td><a id="p122199"></a>Y</td><td></td><td><a id="p122200"></a>1x</td><td></td></tr>
<tr><td><a id="p122201"></a>4/14</td><td><a id="p122202"></a>Item price/amount</td><td><a id="p122203"></a>n..16,2</td><td><a id="p122204"></a>N</td><td></td><td><a id="p122205"></a>1x</td><td></td></tr>
<tr><td><a id="p122206"></a>4/15</td><td><a id="p122207"></a>Exchange rate</td><td><a id="p122208"></a>n..12,5</td><td><a id="p122209"></a>N</td><td><a id="p122210"></a>1x</td><td></td><td></td></tr>
<tr><td><a id="p122211"></a>4/16</td><td><a id="p122212"></a>Valuation method</td><td><a id="p122213"></a>n1</td><td><a id="p122214"></a>Y</td><td></td><td><a id="p122215"></a>1x</td><td></td></tr>
<tr><td><a id="p122216"></a>4/17</td><td><a id="p122217"></a>Preference</td><td><a id="p122218"></a>n3 (n1 + n2)</td><td><a id="p122219"></a>Y</td><td></td><td><a id="p122220"></a>1x</td><td><a id="p122221"></a>The Commission will publish at regular intervals the list of the combinations of codes usable together with examples and notes.</td></tr>
<tr><td><a id="p122222"></a>4/18</td><td><a id="p122223"></a>Value</td><td><a id="p122224"></a>Currency code: a3 +<br>Value: n..16,2</td><td><a id="p122225"></a>N</td><td></td><td><a id="p122226"></a>1x</td><td><a id="p122227"></a>The ISO-alpha-3 currency codes (ISO 4217) shall be used for the currency.</td></tr>
<tr><td><a id="p122228"></a>4/19</td><td><a id="p122229"></a>Transport costs to the final destination</td><td><a id="p122230"></a>Currency code: a3 +<br>Amount: n..16,2</td><td><a id="p122231"></a>N</td><td><a id="p122232"></a>1x</td><td></td><td><a id="p122233"></a>The ISO-alpha-3 currency codes (ISO 4217) shall be used for the currency.</td></tr>
<tr><td><a id="p122234"></a>5/8</td><td><a id="p122235"></a>Country of destination code</td><td><a id="p122236"></a>a2</td><td><a id="p122237"></a>N</td><td><a id="p122238"></a>1x</td><td><a id="p122239"></a>1x</td><td><a id="p122240"></a>The country code as defined for D.E. 3/1 Exporter shall be used.<br>In the context of transit operations, the ISO 3166 alpha-2 country code shall be used.</td></tr>
<tr><td><a id="p122241"></a>5/9</td><td><a id="p122242"></a>Region of destination code</td><td><a id="p122243"></a>an..9</td><td><a id="p122244"></a>N</td><td><a id="p122245"></a>1x</td><td><a id="p122246"></a>1x</td><td><a id="p122247"></a>Codes are defined by the Member State concerned.</td></tr>
<tr><td><a id="p122248"></a>5/14</td><td><a id="p122249"></a>Country of dispatch/export code</td><td><a id="p122250"></a>a2</td><td><a id="p122251"></a>N</td><td><a id="p122252"></a>1x</td><td><a id="p122253"></a>1x</td><td><a id="p122254"></a>The country code as defined for D.E. 3/1 Exporter shall be used.</td></tr>
<tr><td><a id="p122255"></a>5/15</td><td><a id="p122256"></a>Country of origin code</td><td><a id="p122257"></a>a2</td><td><a id="p122258"></a>N</td><td></td><td><a id="p122259"></a>1x</td><td><a id="p122260"></a>The country code as defined for D.E. 3/1 Exporter shall be used.</td></tr>
<tr><td><a id="p122261"></a>5/16</td><td><a id="p122262"></a>Country of preferential origin code</td><td><a id="p122263"></a>an..4</td><td><a id="p122264"></a>N</td><td></td><td><a id="p122265"></a>1x</td><td><a id="p122266"></a>The country code as for D.E. 3/1 Exporter shall be used.<br>Where the proof of origin refers to a group of countries use the numeric identifier codes specified in the integrated tariff established in accordance with Article 2 of Council (EEC) Regulation No 2658/87.</td></tr>
<tr><td><a id="p122267"></a>5/23</td><td><a id="p122268"></a>Location of goods</td><td><a id="p122269"></a>Country: a2 +<br>Type of location: a1 +<br>Qualifier of the identification: a1 +<br>Coded<br>Identification of location: an..35 +<br>Additional identifier: n..3 OR<br>Free text description<br>Street and number:<br>an..70 +<br>Postcode: an..9 +<br>City: an..35</td><td><a id="p122270"></a>Y</td><td><a id="p122271"></a>1x</td><td></td><td><a id="p122272"></a>The structure of the code is defined in Title II.</td></tr>
<tr><td><a id="p122273"></a>5/26</td><td><a id="p122274"></a>Customs office of presentation</td><td><a id="p122275"></a>an8</td><td><a id="p122276"></a>N</td><td><a id="p122277"></a>1x</td><td></td><td><a id="p122278"></a>The identifier of the customs office shall follow the structure defined for D.E. 5/6 Office of destination (and country).</td></tr>
<tr><td><a id="p122279"></a>5/27</td><td><a id="p122280"></a>Supervising customs office</td><td><a id="p122281"></a>an8</td><td><a id="p122282"></a>N</td><td><a id="p122283"></a>1x</td><td></td><td><a id="p122284"></a>The identifier of the customs office shall follow the structure defined for D.E. 5/6 Office of destination (and country).</td></tr>
<tr><td><a id="p122285"></a>5/31</td><td><a id="p122286"></a>Date of acceptance</td><td><a id="p122287"></a>n8 (yyyymmdd)</td><td><a id="p122288"></a>N</td><td><a id="p122289"></a>1x</td><td><a id="p122290"></a>1x</td><td></td></tr>
<tr><td><a id="p122291"></a>6/1</td><td><a id="p122292"></a>Net mass (kg)</td><td><a id="p122293"></a>n..16,6</td><td><a id="p122294"></a>N</td><td></td><td><a id="p122295"></a>1x</td><td></td></tr>
<tr><td><a id="p122296"></a>6/2</td><td><a id="p122297"></a>Supplementary units</td><td><a id="p122298"></a>n..16,6</td><td><a id="p122299"></a>N</td><td></td><td><a id="p122300"></a>1x</td><td></td></tr>
<tr><td><a id="p122301"></a>6/5</td><td><a id="p122302"></a>Gross mass (kg)</td><td><a id="p122303"></a>n..16,6</td><td><a id="p122304"></a>N</td><td><a id="p122305"></a>1x</td><td><a id="p122306"></a>1x</td><td></td></tr>
<tr><td><a id="p122307"></a>6/8</td><td><a id="p122308"></a>Description of goods</td><td><a id="p122309"></a>an..512</td><td><a id="p122310"></a>N</td><td></td><td><a id="p122311"></a>1x</td><td></td></tr>
<tr><td><a id="p122312"></a>6/9</td><td><a id="p122313"></a>Type of packages</td><td><a id="p122314"></a>an..2</td><td><a id="p122315"></a>N</td><td></td><td><a id="p122316"></a>99x</td><td><a id="p122317"></a>The code-list corresponds to the latest version of UN/ECE Recommendation 21.</td></tr>
<tr><td><a id="p122318"></a>6/10</td><td><a id="p122319"></a>Number of packages</td><td><a id="p122320"></a>n..8</td><td><a id="p122321"></a>N</td><td></td><td><a id="p122322"></a>99x</td><td></td></tr>
<tr><td><a id="p122323"></a>6/11</td><td><a id="p122324"></a>Shipping marks</td><td><a id="p122325"></a>an..512</td><td><a id="p122326"></a>N</td><td></td><td><a id="p122327"></a>99x</td><td></td></tr>
<tr><td><a id="p122328"></a>6/13</td><td><a id="p122329"></a>CUS code</td><td><a id="p122330"></a>an8</td><td><a id="p122331"></a>N</td><td></td><td><a id="p122332"></a>1x</td><td><a id="p122333"></a>Code assigned within the European Customs Inventory of Chemical Substances (ECICS).</td></tr>
<tr><td><a id="p122334"></a>6/14</td><td><a id="p122335"></a>Commodity code<br>- Combined nomenclature code</td><td><a id="p122336"></a>an..8</td><td><a id="p122337"></a>N</td><td></td><td><a id="p122338"></a>1x</td><td></td></tr>
<tr><td><a id="p122339"></a>6/15</td><td><a id="p122340"></a>Commodity code<br>- TARIC code</td><td><a id="p122341"></a>an2</td><td><a id="p122342"></a>N</td><td></td><td><a id="p122343"></a>1x</td><td><a id="p122344"></a>To be completed in accordance with the TARIC code (two characters for the application of specific Union measures in respect of formalities to be completed at destination).</td></tr>
<tr><td><a id="p122345"></a>6/16</td><td><a id="p122346"></a>Commodity code<br>- TARIC additional code(s)</td><td><a id="p122347"></a>an4</td><td><a id="p122348"></a>N</td><td></td><td><a id="p122349"></a>99x</td><td><a id="p122350"></a>To be completed in accordance with the TARIC codes (additional codes).</td></tr>
<tr><td><a id="p122351"></a>6/17</td><td><a id="p122352"></a>Commodity code<br>- National additional code(s)</td><td><a id="p122353"></a>an..4</td><td><a id="p122354"></a>N</td><td></td><td><a id="p122355"></a>99x</td><td><a id="p122356"></a>Codes to be adopted by the Member States concerned.</td></tr>
<tr><td><a id="p122357"></a>6/18</td><td><a id="p122358"></a>Total packages</td><td><a id="p122359"></a>n..8</td><td><a id="p122360"></a>N</td><td><a id="p122361"></a>1x</td><td></td><td></td></tr>
<tr><td><a id="p122362"></a>6/19</td><td><a id="p122363"></a>Type of goods</td><td><a id="p122364"></a>an..3</td><td><a id="p122365"></a>N</td><td></td><td><a id="p122366"></a>1x</td><td><a id="p122367"></a>UPU code-list 136 shall be used.</td></tr>
<tr><td><a id="p122368"></a>7/2</td><td><a id="p122369"></a>Container</td><td><a id="p122370"></a>n1</td><td><a id="p122371"></a>Y</td><td><a id="p122372"></a>1x</td><td></td><td></td></tr>
<tr><td><a id="p122373"></a>7/4</td><td><a id="p122374"></a>Mode of transport at the border</td><td><a id="p122375"></a>n1</td><td><a id="p122376"></a>Y</td><td><a id="p122377"></a>1x</td><td></td><td></td></tr>
<tr><td><a id="p122378"></a>7/5</td><td><a id="p122379"></a>Inland mode of transport</td><td><a id="p122380"></a>n1</td><td><a id="p122381"></a>N</td><td><a id="p122382"></a>1x</td><td></td><td><a id="p122383"></a>The codes provided for in Title II as regards D.E. 7/4 Mode of transport at the border shall be used.</td></tr>
<tr><td><a id="p122384"></a>7/9</td><td><a id="p122385"></a>Identity of means of transport on arrival</td><td><a id="p122386"></a>Type of identification: n2 +<br>Identification number:<br>an..35</td><td><a id="p122387"></a>N</td><td><a id="p122388"></a>1x</td><td></td><td><a id="p122389"></a>The codes defined in Title II for D.E. 7/7 Identity of means of transport at departure shall be used for the type of identification.</td></tr>
<tr><td><a id="p122390"></a>7/10</td><td><a id="p122391"></a>Container identification number</td><td><a id="p122392"></a>an..17</td><td><a id="p122393"></a>N</td><td><a id="p122394"></a>9,999<br>x</td><td><a id="p122395"></a>9,999<br>x</td><td></td></tr>
<tr><td><a id="p122396"></a>7/15</td><td><a id="p122397"></a>Nationality of active means of transport crossing the border</td><td><a id="p122398"></a>a2</td><td><a id="p122399"></a>N</td><td><a id="p122400"></a>1x</td><td><a id="p122401"></a>1x</td><td><a id="p122402"></a>The country code as defined for D.E. 3/1 Exporter shall be used.</td></tr>
<tr><td><a id="p122403"></a>8/1</td><td><a id="p122404"></a>Quota order number</td><td><a id="p122405"></a>an6</td><td><a id="p122406"></a>N</td><td></td><td><a id="p122407"></a>1x</td><td></td></tr>
<tr><td><a id="p122408"></a>8/2</td><td><a id="p122409"></a>Guarantee type</td><td><a id="p122410"></a>Guarantee type: an 1</td><td><a id="p122411"></a>Y</td><td><a id="p122412"></a>9x</td><td></td><td></td></tr>
<tr><td><a id="p122413"></a>8/3</td><td><a id="p122414"></a>Guarantee reference</td><td><a id="p122415"></a>GRN: an..24 +<br>Access code: an..4 +<br>Currency code: a3 +<br>Amount of import or export duty and, where first subparagraph of Article 89(2) of the Code applies, other charges: n..16,2 +<br>Customs office of guarantee: an8<br>OR<br>Other guarantee reference: an..35+<br>Access code: an..4 +<br>Currency code: a3 +<br>Amount of import or export duty and, where first subparagraph of Article 89(2) of the Code applies, other charges: n..16,2 +<br>Customs office of guarantee: an8</td><td><a id="p122416"></a>N</td><td><a id="p122417"></a>99x</td><td></td><td><a id="p122418"></a>The ISO-alpha-3 currency codes (ISO 4217) shall be used for the currency.<br>The identifier of the customs office shall follow the structure defined for D.E. 5/6 Office of destination (and country).</td></tr>
<tr><td><a id="p122419"></a>8/5</td><td><a id="p122420"></a>Nature of transaction</td><td><a id="p122421"></a>n..2</td><td><a id="p122422"></a>N</td><td><a id="p122423"></a>1x</td><td><a id="p122424"></a>1x</td><td><a id="p122425"></a>The single digit codes listed in column A of the table provided for under<br>Article 10(2) of Commission Regulation (EC) No 113/2010 &lt;**&gt; shall be used. Where paper-based customs declarations are used, this digit will be entered in the left-hand side of box 24.<br>Member States may also provide for a second digit from the list in column B of that table to be collected. Where paper-based customs declarations are used, the second digit must be entered in the right-hand side of box 24.</td></tr>
<tr><td><a id="p122426"></a>8/6</td><td><a id="p122427"></a>Statistical value</td><td><a id="p122428"></a>n..16,2</td><td><a id="p122429"></a>N</td><td></td><td><a id="p122430"></a>1x</td><td></td></tr>
</table>


<a id="p122431"></a>

---

<a id="p122432"></a><*> OJ L 328, 28.11.2012, p. 7 - 15.
<a id="p122433"></a><**> Commission Regulation (EU) No 113/2010 of 9 February 2010 implementing Regulation (EC) No 471/2009 of the European Parliament and of the Council on Community statistics relating to external trade with non-member countries, as regards trade coverage, definition of the data, compilation of statistics on trade by business characteristics and by invoicing currency, and specific goods or movements (OJ L 37, 10.2.2010, p. 1).

<a id="p122434"></a>**TITLE II. CODES IN RELATION WITH THE COMMON DATA**
**REQUIREMENTS FOR DECLARATIONS AND NOTIFICATIONS CODES**

<a id="p122435"></a>**1. INTRODUCTION**

<a id="p122436"></a>This Title contains the codes to be used on standard electronic and paperbased declarations and notifications.

<a id="p122437"></a>**2. CODES**

<a id="p122438"></a>1/1. Declaration type
<a id="p122439"></a>IM: For trade with countries and territories situated outside of the customs territory of the Union.
<a id="p122440"></a>For placing goods under a customs procedure referred to in columns H1 to H4, H6 and I1 of the data requirements table in Title I of Annex D to Delegated Regulation (EU) 2015/2446.
<a id="p122441"></a>For placing non-Union goods under a customs procedure in the context of trade between Member States.
<a id="p122442"></a>CO: - Union goods subject to specific measures during the transitional period following the accession of new Member States.
- <a id="p122443"></a>Union goods in the context of trade between parts of the customs territory of the Union to which the provisions of Council Directive 2006/112/EC <*> or Council Directive 2008/118/EC <**> are applicable and parts of that territory to which those provisions do not apply, or in the context of trade between parts of that territory where those provisions do not apply as referred to in column H5 of the data requirements table in Title I of Annex D to Delegated Regulation (EU) 2015/2446.

<a id="p122444"></a>

---

<a id="p122445"></a><*> Council Directive 2006/112/EC of 28 November 2006 on the common system of value added tax (OJ L 347, 11.12.2006, p. 1).
<a id="p122446"></a><**> Council Directive 2008/118/EC of 16 December 2008 concerning the general arrangements for excise duty and repealing Directive 92/12/EEC (OJ L 9, 14.1.2009, p. 12).

<a id="p122447"></a>1/2. Additional Declaration type
<a id="p122448"></a>A for a standard customs declaration (under Article 162 of the Code)
<a id="p122449"></a>B for a simplified declaration on occasional basis (under Article 166(1) of the Code
<a id="p122450"></a>C for a simplified customs declaration with regular use (under Article 166(2) of the Code)
<a id="p122451"></a>D for lodging a standard customs declaration (such as referred to under code A) in accordance with Article 171 of the Code
<a id="p122452"></a>E for lodging a simplified declaration (such as referred to under code B) in accordance with Article 171 of the Code
<a id="p122453"></a>F for lodging a simplified declaration (such as referred to under code C) in accordance with Article 171 of the Code
<a id="p122454"></a>R Retrospective lodgement of an export or re-export declaration in accordance with Article 249 of Delegated Regulation (EU) 2015/2446 and Article 337 of Implementing Regulation (EU) 2015/2447)
<a id="p122455"></a>X for a supplementary declaration of simplified declarations covered by B and E
<a id="p122456"></a>Y for a supplementary declaration of simplified declarations covered by C and F
<a id="p122457"></a>Z for a supplementary declaration under the procedure covered under Article 182 of the Code

<a id="p122458"></a>1/10. Procedure
<a id="p122459"></a>The codes to be entered in this subdivision are four-digit codes, composed of a two-digit code representing the procedure requested, followed by a second two-digit code representing the previous procedure. The list of two-digit codes is given below.
<a id="p122460"></a>"Previous procedure" means the procedure under which the goods were placed before being placed under the procedure requested.
<a id="p122461"></a>It should be noted that where the previous procedure is customs warehousing or temporary admission, or where the goods have come from a free zone, the relevant code should be used only where the goods have not been placed under inward or outward processing or end-use.
<a id="p122462"></a>Similarly, where goods previously temporarily exported are re-imported and released for free circulation after having been placed under customs warehousing, temporary admission or in a free zone this is regarded as simple re-importation after temporary export.
<a id="p122463"></a>For example: entry for home use with simultaneous entry for free circulation of goods exported under outward processing and placed under customs warehousing upon re-importation = 6121 (not 6171). (First operation: temporary export under outward processing = 2100; second operation: storage in a customs warehouse = 7121; third operation: entry for home use + entry for free circulation = 6121).
<a id="p122464"></a>The codes marked in the list below with the letter (a) cannot be used as the first two digits of the procedure code, but only to indicate the previous procedure.
<a id="p122465"></a>For example: 4054 = entry for free circulation and home use of goods previously placed under inward processing in another Member State.
<a id="p122466"></a>List of procedures for coding purposes
<a id="p122467"></a>Two of these basic elements must be combined to produce a four-digit code.
<a id="p122468"></a>00 This code is used to indicate that there is no previous procedure (a).
<a id="p122469"></a>01 Release for free circulation of goods simultaneously redispatched in the context of trade between parts of the customs territory of the Union in which the provisions of Directive 2006/112/EC or Directive 2008/118/EC are applicable and parts of that territory in which those provisions do not apply, or in the context of trade between the parts of that territory where those provisions do not apply.
<a id="p122470"></a>Example: Non-Union goods arriving from a third country, released for free circulation in Germany and sent on to the Canary Islands.
<a id="p122471"></a>07 Release of goods for free circulation simultaneously placed under a warehousing procedure other than a customs warehousing procedure where neither VAT nor, when applicable, excise duties have been paid.
<a id="p122472"></a>Explanation: This code is to be used where the goods are released for free circulation but where VAT and excise duties have not been paid.
<a id="p122473"></a>Examples: Imported raw sugar is released for free circulation but
<a id="p122474"></a>VAT has not been paid. While the goods are placed in a warehouse or approved area other than customs warehouse, payment of the VAT is suspended.
<a id="p122475"></a>Imported mineral oils are released for free circulation and no VAT has been paid. While the goods are stored in a tax warehouse, payment of VAT and excise duties is suspended.
<a id="p122476"></a>40 Simultaneous release for free circulation and home use of goods.
<a id="p122477"></a>Entry for home use of goods in the context of trade between the Union and the countries with which it has formed a customs union.
<a id="p122478"></a>Entry for home use of goods in the context of trade referred to in Article 1(3) of the code.
<a id="p122479"></a>Examples:
- <a id="p122480"></a>Goods coming from Japan with payment of customs duty, VAT and when applicable excise duties.
- <a id="p122481"></a>Goods coming from Andorra and entered for home use in Germany.
- <a id="p122482"></a>Goods arriving from Martinique and entered for home use in Belgium.
<a id="p122483"></a>42 Simultaneous release for free circulation and home use of goods which are the subject of a VAT-exempt supply to another Member State and, when applicable, an excise-duty suspension.
<a id="p122484"></a>Entry for home use of Union goods, in the context of trade between parts of the customs territory of the Union in which the provisions of Directive 2006/112/EC and Directive 2008/118/EC are not applicable and parts of that territory in which those provisions are applicable, which are the subject of a VAT-exempt supply to another Member State and, when applicable, an excise duty suspension.
<a id="p122485"></a>Explanation: Exemption from payment of VAT and, where applicable, the excise duty suspension, is granted because the import is followed by intra-Union supply or transfer of the goods to another Member State. In that case the VAT and, where applicable, the excise duty will be due in the Member State of final destination. In order to use this procedure, the persons must meet other conditions listed in in Article 143(2) of Directive 2006/112/EC and, where applicable, the conditions listed in Article 17(1)(b) of Directive 2008/118/EC. The information required by Article 143 (2) of Directive 2006/112/EC shall be entered in D.E. 3/40 Additional fiscal references identification no.
<a id="p122486"></a>Examples: Non-Union goods are released for free circulation in one
<a id="p122487"></a>Member State and are the subject of a VAT-exempt supply to another Member State. The VAT formalities are dealt with by a customs agent who is a tax representative using the intra-Union VAT system.
<a id="p122488"></a>Non-Union goods subject to excise duties imported from a third country, which are released for free circulation and are the subject of a VAT-exempt supply to another Member State. The release for free circulation is immediately followed by a movement under excise duty suspension from the place of importation initiated by a registered consignor in accordance with Article 17(1)(b) of Directive 2008/118/EC.
<a id="p122489"></a>43 Simultaneous release for free circulation and home use of goods subject to specific measures connected with the collection of an amount during the transitional period following the accession of new Member States.
<a id="p122490"></a>Example: Release for free circulation of agricultural products subject, during a special transitional period following the accession of new Member States, to a special customs procedure or special measures between the new Member States and the rest of the Union.
<a id="p122491"></a>44 End-use
<a id="p122492"></a>Release for free circulation and home use under a duty exemption or at a reduced rate of duty on account of their specific use.
<a id="p122493"></a>Example: Release for free circulation of non-Union engines for integration into a civil aircraft built in the European Union.
<a id="p122494"></a>Non-union goods for integration in certain categories of ships, boats and other vessels and for drilling or production platforms.
<a id="p122495"></a>45 Release of goods for free circulation and partial entry for home use for either VAT or excise duties and their placing in a warehouse other than customs warehouses.
<a id="p122496"></a>Explanation: This code is to be used for goods which are subjected to both VAT and excise duties and where only one of these categories of taxes are paid when the goods are released for free circulation.
<a id="p122497"></a>Examples: Non-Union cigarettes are released for free circulation and VAT has been paid. While the goods are in the tax warehouse, the payment of excise duties is suspended.
<a id="p122498"></a>Excise goods imported from a third country or from a third territory referred to in Article 5(3) of Directive 2008/118/EC are released for free circulation. The release for free circulation is immediately followed by a movement under excise duty suspension initiated by a registered consignor at the place of importation, in accordance with Article 17(1)(b) of Directive 2008/118/EC, to a tax warehouse in the same Member State.
<a id="p122499"></a>Explanation:
<a id="p122500"></a>46 Import of processed products obtained from equivalent goods under the outward-processing procedure before exportation of goods they are replacing.
<a id="p122501"></a>Explanation: Prior import in accordance with Article 223(2)d) of the Code.
<a id="p122502"></a>Example: Import of tables manufactured from non-Union wood before placing Union wood under outward processing.
<a id="p122503"></a>48 Entry for home use with simultaneous release for free circulation of replacement products under outward processing prior to the export of the defective goods.
<a id="p122504"></a>Explanation: Standard exchange system (IM-EX), prior importation in accordance with Article 262(1) of the Code.
<a id="p122505"></a>51 Placing goods under inward processing procedure.
<a id="p122506"></a>Explanation: Inward processing in accordance with Article 256 of the Code.
<a id="p122507"></a>53 Placing of goods under temporary admission.
<a id="p122508"></a>Explanation: Placing of non-Union goods intended for re-export under the temporary admission procedure.
<a id="p122509"></a>May be used in the customs territory of the Union, with total or partial relief from import duties in accordance with article 250 of the Code.
<a id="p122510"></a>Example: Temporary admission, e.g. for an exhibition.
<a id="p122511"></a>54 Inward processing in another Member State (without their being released for free circulation in that Member State) (a).
<a id="p122512"></a>Explanation: This code is used to record the operation for the purposes of statistics on intra-Union trade.
<a id="p122513"></a>Example: Non-Union goods are placed under inward processing in Belgium (5100). After undergoing inward processing, they are dispatched to Germany for release for free circulation (4054) or further processing (5154).
<a id="p122514"></a>61 Re-importation with simultaneous release for free circulation and home use of goods.
<a id="p122515"></a>Explanation: Goods re-imported from a third country with payment of the customs duties and VAT.
<a id="p122516"></a>63 Re-importation with simultaneous release for free circulation and home use of goods which are the subject of a VAT-exempt supply to another Member State and, when applicable, an excise duty suspension.
<a id="p122517"></a>Explanation: Exemption from payment of VAT and, where applicable, the excise duty suspension, is granted because that the re-importation is followed by intra-Union supply or transfer of the goods to another Member State. In such a case the VAT and, where applicable, the excise duty, will be due in the Member State of final destination. In order to use this procedure, the persons must meet other conditions listed in in Article 143(2) of Directive 2006/112/EC and, where applicable, the conditions listed in Article 17(1)(b) of Directive 2008/118/EC. The information required by Article 143 (2) of Directive 2006/112/EC shall be entered in D.E. 3/40 Additional fiscal references identification no.
<a id="p122518"></a>Examples: Re-importation after outward processing or temporary export, with any VAT debt being charged to a tax representative.
<a id="p122519"></a>Excise goods reimported after outward processing and released for free circulation, which are the subject of a VAT- exempt supply to another Member State. The release for free circulation is immediately followed by a movement under excise duty suspension from the place of re-importation initiated by a registered consignor in accordance with Article 17(1)(b) of Directive 2008/118/EC.
<a id="p122520"></a>68 Re-importation with partial entry for home use and simultaneous release for free circulation and placing of goods under warehousing other than customs warehousing procedure.
<a id="p122521"></a>Explanation: This code is to be used for goods which are subject to both VAT and excise duties and where only one of those categories of taxes is paid when the goods are released for free circulation.
<a id="p122522"></a>Example: Processed alcoholic beverages are re-imported and placed in a tax warehouse.
<a id="p122523"></a>71 Placing of goods under the customs warehousing procedure.
<a id="p122524"></a>76 Placing of Union goods under the customs warehousing procedure in accordance with Article 237(2) of the Code.
<a id="p122525"></a>Example: Boned meat of adult male bovine animals placed under customs warehousing prior to export (Article 4 of Commission Regulation (EC) No 1741/2006 (1) of 24 November 2006 laying down the conditions for granting the special export refund on boned meat of adult male bovine animals placed under the customs warehousing procedure prior to export (OJ L 329, 25.11.2006, p. 7)).
<a id="p122526"></a>Following the release for free circulation, application for repayment or remission of import duty based on the goods being defective or not complying with the terms of the contract (Art.118 of the Code).
<a id="p122527"></a>In accordance with Article 118 (4) of the Code the goods in question may be placed under the customs warehousing procedure instead of having to be taken out of the customs territory of Union in order for the repayment or remission to be granted.
<a id="p122528"></a>77 Manufacturing of Union goods under customs supervision by the customs authorities and under customs control (within the meaning of Art. 5(27) and (3) of Code) prior to exportation and payment of export refunds.
<a id="p122529"></a>Example: Preserved beef and veal products manufactured under supervision by the customs authorities and under customs control prior to export (Articles 2 and 3 of Commission Regulation (EC) No 1731/2006 of 23 November 2006 on special detailed rules for the application of export refunds in the case of certain preserved beef and veal products (OJ L 325, 24.11.2006, p. 12)).
<a id="p122530"></a>78 Placing of goods under free-zone. (a)
<a id="p122531"></a>95 Placing of Union Goods under a warehousing procedure other than a customs warehousing procedure where neither VAT nor, when applicable, excise duties have been paid.
<a id="p122532"></a>Explanation: This code is to be used in the context of trade referred to in Article 1 (3) of the Code as well as trade between the Union and the countries with which it has formed a customs union and where neither VAT nor excise duties have been paid.
<a id="p122533"></a>Example: Cigarettes from the Canary Islands are brought to Belgium and stored in a tax warehouse; payment of VAT and excise duties is suspended.
<a id="p122534"></a>96 Placing of Union Goods under a warehousing procedure other than a customs warehousing procedure where either VAT or, when applicable, excise duties have been paid and the payment of the other tax is suspended.
<a id="p122535"></a>Explanation: This code is to be used in the context of trade referred to in Article 1 (3) of the Code as well as trade between the Union and the countries with which it has formed a customs union and where either VAT or excise duties have been paid and the payment of the other tax is suspended.
<a id="p122536"></a>Example: Cigarettes from the Canary Islands are brought to France and stored in a tax warehouse; VAT has been paid and the payment of excise duties is suspended.

<a id="p122537"></a>Procedure codes used in the context of customs declarations


| <a id="p122538"></a>Columns (table heading in Annex<br>D to Delegated Regulation (EU) 2015/2446) | <a id="p122539"></a>Declarations | <a id="p122540"></a>Union procedure codes, where appropriate |
| --- | --- | --- |
| <a id="p122541"></a>H1 | <a id="p122542"></a>Declaration for release for free circulation and special procedure - specific use - declaration for end-use | <a id="p122543"></a>01, 07, 40, 42, 43, 44, 45, 46, 48, 61, 63, 68 |
| <a id="p122544"></a>H2 | <a id="p122545"></a>Special procedure - storage - declaration for customs warehousing | <a id="p122546"></a>71 |
| <a id="p122547"></a>H3 | <a id="p122548"></a>Special procedure - specific use - declaration for temporary admission | <a id="p122549"></a>53 |
| <a id="p122550"></a>H4 | <a id="p122551"></a>Special procedure - processing<br>- declaration for inward processing | <a id="p122552"></a>51 |
| <a id="p122553"></a>H5 | <a id="p122554"></a>Declaration for the introduction of goods in the context of trade with special fiscal territories | <a id="p122555"></a>40, 42, 61, 63, 95, 96 |
| <a id="p122556"></a>H6 | <a id="p122557"></a>Customs declaration in postal traffic for release for free circulation | <a id="p122558"></a>01, 07, 40 |
| <a id="p122559"></a>I1 | <a id="p122560"></a>Import Simplified declaration | <a id="p122561"></a>01, 07, 40, 42, 43,<br>44, 45, 46, 48, 51,<br>53, 61, 63, 68 |


<a id="p122562"></a>1/11. Additional procedure
<a id="p122563"></a>Where this data element is used to specify a Union procedure, the first character of the code identifies a category of measures in the following manner:
<a id="p122564"></a>Inward processing Axx
<a id="p122565"></a>Outward processing Bxx
<a id="p122566"></a>Relief Cxx
<a id="p122567"></a>Temporary admission Dxx
<a id="p122568"></a>Agricultural products Exx
<a id="p122569"></a>Other Fxx

<a id="p122570"></a>Inward processing (Article 256 of the Code)


| <a id="p122571"></a>Code | <a id="p122572"></a>Description |
| --- | --- |
|  | <a id="p122573"></a>Import |
| <a id="p122574"></a>A04 | <a id="p122575"></a>Goods which are placed under an inward processing procedure (VAT only) |
| <a id="p122576"></a>A10 | <a id="p122577"></a>Destruction of goods under inward processing |


<a id="p122578"></a>Outward processing (Article 259 of the Code)


| <a id="p122579"></a>Code | <a id="p122580"></a>Description |
| --- | --- |
|  | <a id="p122581"></a>Import |
| <a id="p122582"></a>B02 | <a id="p122583"></a>Processed products returning after repair under guarantee in accordance with Article 260 of the Code (goods repaired free of charge) |
| <a id="p122584"></a>B03 | <a id="p122585"></a>Processed products returning after replacement under guarantee in accordance with Article 261 of the Code (standard exchange system) |
| <a id="p122586"></a>B06 | <a id="p122587"></a>Processed products returning - VAT only |


<a id="p122588"></a>Relief from import duties
(Council Regulation (EC) No 1186/2009) <*>


<a id="p122589"></a>

---

<a id="p122590"></a><*> Council Regulation (EC) No 1186/2009 of 16 November 2009 setting up a Community system of reliefs from customs duty (OJ L 324, 10.12.2009, p. 23).


| <a id="p122591"></a>Code | <a id="p122592"></a>Description | <a id="p122593"></a>Article No |
| --- | --- | --- |
| <a id="p122594"></a>C01 | <a id="p122595"></a>Personal property imported by natural persons transferring their normal place of residence to the customs territory of the Union | <a id="p122596"></a>3 |
| <a id="p122597"></a>C02 | <a id="p122598"></a>Trousseaux and household effects imported on the occasion of a marriage | <a id="p122599"></a>12(1) |
| <a id="p122600"></a>C03 | <a id="p122601"></a>Presents customarily given on the occasion of a marriage | <a id="p122602"></a>12(2) |
| <a id="p122603"></a>C04 | <a id="p122604"></a>Personal property acquired by inheritance by a natural person having his normal place of residence in the customs territory of the Union | <a id="p122605"></a>17 |
| <a id="p122606"></a>C06 | <a id="p122607"></a>School outfits, educational materials and related household effects | <a id="p122608"></a>21 |
| <a id="p122609"></a>C07 | <a id="p122610"></a>Consignments of negligible value | <a id="p122611"></a>23 |
| <a id="p122612"></a>C08 | <a id="p122613"></a>Consignments sent from one private individual to another | <a id="p122614"></a>25 |
| <a id="p122615"></a>C09 | <a id="p122616"></a>Capital goods and other equipment imported on the transfer of activities from a third country into the Union | <a id="p122617"></a>28 |
| <a id="p122618"></a>C10 | <a id="p122619"></a>Capital goods and other equipment belonging to persons engaged in a liberal profession and to legal persons engaged in a non-profit making activity | <a id="p122620"></a>34 |
| <a id="p122621"></a>C11 | <a id="p122622"></a>Educational, scientific and cultural materials; scientific instruments and apparatus as listed in Annex I to Regulation (EC) No 1186/2009) | <a id="p122623"></a>42 |
| <a id="p122624"></a>C12 | <a id="p122625"></a>Educational, scientific and cultural materials; scientific instruments and apparatus as listed in Annex II to Regulation (EC) No 1186/2009 | <a id="p122626"></a>43 |
| <a id="p122627"></a>C13 | <a id="p122628"></a>Educational, scientific and cultural materials; scientific instruments and apparatus imported exclusively for noncommercial purposes (including spare parts, components, accessories and tools) | <a id="p122629"></a>44 - 45 |
| <a id="p122630"></a>C14 | <a id="p122631"></a>Equipment imported for non-commercial purposes by or on behalf of a scientific research establishment or organisation based outside the Union | <a id="p122632"></a>51 |
| <a id="p122633"></a>C15 | <a id="p122634"></a>Laboratory animals and biological or chemical substances intended for research | <a id="p122635"></a>53 |
| <a id="p122636"></a>C16 | <a id="p122637"></a>Therapeutic substances of human origin and blood-grouping and tissue-typing reagents | <a id="p122638"></a>54 |
| <a id="p122639"></a>C17 | <a id="p122640"></a>Instruments and apparatus used in medical research, establishing medical diagnoses or carrying out medical treatment | <a id="p122641"></a>57 |
| <a id="p122642"></a>C18 | <a id="p122643"></a>Reference substances for the quality control of medicinal products | <a id="p122644"></a>59 |
| <a id="p122645"></a>C19 | <a id="p122646"></a>Pharmaceutical products used at international sports events | <a id="p122647"></a>60 |
| <a id="p122648"></a>C20 | <a id="p122649"></a>Goods for charitable or philanthropic organisations - basic necessities imported by State organisations or other approved organisations | <a id="p122650"></a>61(1)(a) |
| <a id="p122651"></a>C21 | <a id="p122652"></a>Articles in Annex III to Regulation (EC) No 1186/2009 intended for the blind | <a id="p122653"></a>66 |
| <a id="p122654"></a>C22 | <a id="p122655"></a>Articles in Annex IV to Regulation (EC) No 1186/2009 intended for the blind imported by blind persons themselves for their own use (including spare parts, components, accessories and tools) | <a id="p122656"></a>67(1)(a) and 67(2) |
| <a id="p122657"></a>C23 | <a id="p122658"></a>Articles in Annex IV to Regulation (EC) No 1186/2009 intended for the blind imported by certain institutions or organisations (including spare parts, components, accessories and tools) | <a id="p122659"></a>67(1)(b) and 67(2) |
| <a id="p122660"></a>C24 | <a id="p122661"></a>Articles intended for other handicapped persons (other than blind persons) imported by handicapped persons themselves for their own use (including spare parts, components, accessories and tools) | <a id="p122662"></a>68(1)(a) and 68(2) |
| <a id="p122663"></a>C25 | <a id="p122664"></a>Articles intended for other handicapped persons (other than blind persons) imported by certain institutions or organisations (including spare parts, components, accessories and tools) | <a id="p122665"></a>68(1)(b) and 68(2) |
| <a id="p122666"></a>C26 | <a id="p122667"></a>Goods imported for the benefit of disaster victims | <a id="p122668"></a>74 |
| <a id="p122669"></a>C27 | <a id="p122670"></a>Decorations conferred by governments of third countries on persons whose normal place of residence is in the customs territory of the Union | <a id="p122671"></a>81(a) |
| <a id="p122672"></a>C28 | <a id="p122673"></a>Goods imported into the customs territory of the Union by persons who have paid an official visit to a third country and who have received them on this occasion as gifts from the host authorities | <a id="p122674"></a>82(a) |
| <a id="p122675"></a>C29 | <a id="p122676"></a>Goods to be used by monarchs or heads of state | <a id="p122677"></a>85 |
| <a id="p122678"></a>C30 | <a id="p122679"></a>Samples of goods of negligible value imported for trade promotion purposes | <a id="p122680"></a>86 |
| <a id="p122681"></a>C31 | <a id="p122682"></a>Printed advertising matter | <a id="p122683"></a>87 |
| <a id="p122684"></a>C32 | <a id="p122685"></a>Small representative samples of goods manufactured outside the customs territory of the Union intended for a trade fair or similar event | <a id="p122686"></a>90(a) |
| <a id="p122687"></a>C33 | <a id="p122688"></a>Goods imported for examination, analysis or test purposes | <a id="p122689"></a>95 |
| <a id="p122690"></a>C34 | <a id="p122691"></a>Consignments sent to organisations protecting copyrights or industrial and commercial patent rights | <a id="p122692"></a>102 |
| <a id="p122693"></a>C35 | <a id="p122694"></a>Tourist information literature | <a id="p122695"></a>103 |
| <a id="p122696"></a>C36 | <a id="p122697"></a>Miscellaneous documents and articles | <a id="p122698"></a>104 |
| <a id="p122699"></a>C37 | <a id="p122700"></a>Ancillary materials for the stowage and protection of goods during their transport | <a id="p122701"></a>105 |
| <a id="p122702"></a>C38 | <a id="p122703"></a>Litter, fodder and feeding stuffs for animals during their transport | <a id="p122704"></a>106 |
| <a id="p122705"></a>C39 | <a id="p122706"></a>Fuel and lubricants present in land motor vehicles and special containers | <a id="p122707"></a>107 |
| <a id="p122708"></a>C40 | <a id="p122709"></a>Materials for the construction, upkeep, or ornamentation of memorials to, or cemeteries for, war victims | <a id="p122710"></a>112 |
| <a id="p122711"></a>C41 | <a id="p122712"></a>Coffins, funerary urns and ornamental funerary articles | <a id="p122713"></a>113 |
| <a id="p122714"></a>C42 | <a id="p122715"></a>Personal property entered for free circulation before the person concerned establishes his normal place of residence in the customs territory of the Union (duty relief subject to an undertaking) | <a id="p122716"></a>9(1) |
| <a id="p122717"></a>C43 | <a id="p122718"></a>Personal property entered for free circulation by a natural person having intention to establish his normal place of residence in the customs territory of the Union (duty-free admission subject to an undertaking) | <a id="p122719"></a>10 |
| <a id="p122720"></a>C44 | <a id="p122721"></a>Personal property acquired by inheritance by legal persons engaged in a non-profit making activity who are established in the customs territory of the Union | <a id="p122722"></a>20 |
| <a id="p122723"></a>C45 | <a id="p122724"></a>Agricultural, stock-farming, bee-keeping, horticultural and forestry products from properties located in a third country adjoining the customs territory of the Union | <a id="p122725"></a>35 |
| <a id="p122726"></a>C46 | <a id="p122727"></a>Products of fishing or fish-farming activities carried out in the lakes or waterways bordering a Member State and a third country by Union fishermen and products of hunting activities carried out on such lakes or waterways by Union sportsmen | <a id="p122728"></a>38 |
| <a id="p122729"></a>C47 | <a id="p122730"></a>Seeds, fertilizers and products for treatment of soil and crops, intended for use on property located in the customs territory of the Union adjoining a third country | <a id="p122731"></a>39 |
| <a id="p122732"></a>C48 | <a id="p122733"></a>Goods contained in the personal luggage and exempted from VAT | <a id="p122734"></a>41 |
| <a id="p122735"></a>C49 | <a id="p122736"></a>Goods for charitable or philanthropic organisations - goods of every description sent free of charge and to be used for fund-raising at occasional charity events for the benefit of needy persons | <a id="p122737"></a>61 (1)(b) |
| <a id="p122738"></a>C50 | <a id="p122739"></a>Goods for charitable or philanthropic organisations - equipment and office materials sent free of charge | <a id="p122740"></a>61 (1)(c) |
| <a id="p122741"></a>C51 | <a id="p122742"></a>Cups, medals and similar articles of an essentially symbolic nature which, having been awarded in a third country to persons having their normal place of residence in the customs territory of the Union | <a id="p122743"></a>81(b) |
| <a id="p122744"></a>C52 | <a id="p122745"></a>Cups, medals and similar articles of an essentially symbolic nature which are given free of charge by authorities or persons established in a third country to be presented in the customs territory of the Union | <a id="p122746"></a>81(c) |
| <a id="p122747"></a>C53 | <a id="p122748"></a>Awards, trophies and souvenirs of a symbolic nature and of limited value intended for distribution free of charge to persons normally resident in third countries at business conferences or similar international events | <a id="p122749"></a>81(d) |
| <a id="p122750"></a>C54 | <a id="p122751"></a>Goods imported into the customs territory of the Union by persons coming to pay an official visit in the customs territory of the Union and who intend to offer them on that occasion as gifts to the host authorities | <a id="p122752"></a>82(b) |
| <a id="p122753"></a>C55 | <a id="p122754"></a>Goods sent as gifts, in token of friendship or goodwill, by an official body, public authority or group, carrying on an activity in the public interest which is located in a third country, to an official body, public authority or group carrying on an activity in the public interest which is located in the customs territory of the Union and approved by the competent authorities to receive such articles free of duty | <a id="p122755"></a>82(c) |
| <a id="p122756"></a>C56 | <a id="p122757"></a>Articles for advertising purposes, of no intrinsic commercial value, sent free of charge by suppliers to their customers, which, apart from their advertising function, are not capable of being used otherwise | <a id="p122758"></a>89 |
| <a id="p122759"></a>C57 | <a id="p122760"></a>Goods imported solely in order to be demonstrated or in order to demonstrate machines and apparatus, manufactured outside the customs territory of the Union and displayed at a trade fair or similar event | <a id="p122761"></a>90 (1)(b) |
| <a id="p122762"></a>C58 | <a id="p122763"></a>Various materials of little value such as paints, varnishes, wallpaper, etc., used in the building, fitting-out and decoration of temporary stands occupied by representatives of third countries at a trade fair or similar event, which are destroyed by being used | <a id="p122764"></a>90 (1)(c) |
| <a id="p122765"></a>C59 | <a id="p122766"></a>Printed matter, catalogues, prospectuses, price lists, advertising posters, calendars, whether or not illustrated, unframed photographs and other articles supplied free of charge in order to advertise goods manufactured outside the customs territory of the Union and displayed at a trade fair or similar event | <a id="p122767"></a>90 (1)(d) |
| <a id="p122768"></a>C60 | <a id="p122769"></a>Trousseaux and household effects imported on the occasion of a marriage entered for free circulation not earlier than two months before the wedding (duty relief subject to lodging of appropriate guarantee) | <a id="p122770"></a>12(1),<br>15(1)(a) |
| <a id="p122771"></a>C61 | <a id="p122772"></a>Presents customarily given on the occasion of a marriage entered for free circulation not earlier than two months before the wedding (duty relief subject to lodging of appropriate guarantee) | <a id="p122773"></a>12(2),<br>15(1)(a) |


<a id="p122774"></a>Temporary admission


<table>
<colgroup><col width="12%"><col width="40%"><col width="29%"><col width="19%"></colgroup>
<tr><td><a id="p122775"></a>Code</td><td colspan="2"><a id="p122776"></a>Description</td><td><a id="p122777"></a>Article No</td></tr>
<tr><td><a id="p122778"></a>D01</td><td><a id="p122779"></a>Pallets (including pallet spare parts, accessories and equipment)</td><td></td><td><a id="p122780"></a>208 and 209</td></tr>
<tr><td><a id="p122781"></a>D02</td><td colspan="2"><a id="p122782"></a>Containers (including container spare parts, accessories and equipment)</td><td><a id="p122783"></a>210 and 211</td></tr>
<tr><td><a id="p122784"></a>D03</td><td colspan="2"><a id="p122785"></a>Means of road, rail, air, sea and inland waterway transport</td><td><a id="p122786"></a>212</td></tr>
<tr><td><a id="p122787"></a>D04</td><td colspan="2"><a id="p122788"></a>Personal effects and goods for sports purposes imported by travelers</td><td><a id="p122789"></a>219</td></tr>
<tr><td><a id="p122790"></a>D05</td><td colspan="2"><a id="p122791"></a>Welfare material for seafarers</td><td><a id="p122792"></a>220</td></tr>
<tr><td><a id="p122793"></a>D06</td><td colspan="2"><a id="p122794"></a>Disaster relief material</td><td><a id="p122795"></a>221</td></tr>
<tr><td><a id="p122796"></a>D07</td><td colspan="2"><a id="p122797"></a>Medical, surgical and laboratory equipment</td><td><a id="p122798"></a>222</td></tr>
<tr><td><a id="p122799"></a>D08</td><td colspan="2"><a id="p122800"></a>Animals (twelve months or more)</td><td><a id="p122801"></a>223</td></tr>
<tr><td><a id="p122802"></a>D09</td><td colspan="2"><a id="p122803"></a>Goods for use in frontier zone</td><td><a id="p122804"></a>224</td></tr>
<tr><td><a id="p122805"></a>D10</td><td colspan="2"><a id="p122806"></a>Sound, image or data carrying media</td><td><a id="p122807"></a>225</td></tr>
<tr><td><a id="p122808"></a>D11</td><td colspan="2"><a id="p122809"></a>Publicity material</td><td><a id="p122810"></a>225</td></tr>
<tr><td><a id="p122811"></a>D12</td><td colspan="2"><a id="p122812"></a>Professional equipment</td><td><a id="p122813"></a>226</td></tr>
<tr><td><a id="p122814"></a>D13</td><td colspan="2"><a id="p122815"></a>Pedagogic material and scientific equipment</td><td><a id="p122816"></a>227</td></tr>
<tr><td><a id="p122817"></a>D14</td><td colspan="2"><a id="p122818"></a>Packings, full</td><td><a id="p122819"></a>228</td></tr>
<tr><td><a id="p122820"></a>D15</td><td colspan="2"><a id="p122821"></a>Packings, empty</td><td><a id="p122822"></a>228</td></tr>
<tr><td><a id="p122823"></a>D16</td><td colspan="2"><a id="p122824"></a>Moulds, dies, blocks, drawings, sketches, measuring, checking and testing instruments and other similar articles</td><td><a id="p122825"></a>229</td></tr>
<tr><td><a id="p122826"></a>D17</td><td colspan="2"><a id="p122827"></a>Special tools and instruments</td><td><a id="p122828"></a>230</td></tr>
<tr><td><a id="p122829"></a>D18</td><td colspan="2"><a id="p122830"></a>Goods subject to tests, experiments or demonstrations</td><td><a id="p122831"></a>231(a)</td></tr>
<tr><td><a id="p122832"></a>D19</td><td colspan="2"><a id="p122833"></a>Goods, subject to satisfactory acceptance tests, provided for in a sales contract</td><td><a id="p122834"></a>231(b)</td></tr>
<tr><td><a id="p122835"></a>D20</td><td colspan="2"><a id="p122836"></a>Goods used to carry out tests, experiments or demonstrations without financial gain (six months)</td><td><a id="p122837"></a>231(c)</td></tr>
<tr><td><a id="p122838"></a>D21</td><td colspan="2"><a id="p122839"></a>Samples</td><td><a id="p122840"></a>232</td></tr>
<tr><td><a id="p122841"></a>D22</td><td colspan="2"><a id="p122842"></a>Replacement means of production (six months)</td><td><a id="p122843"></a>233</td></tr>
<tr><td><a id="p122844"></a>D23</td><td colspan="2"><a id="p122845"></a>Goods for events or for sale</td><td><a id="p122846"></a>234(1)</td></tr>
<tr><td><a id="p122847"></a>D24</td><td colspan="2"><a id="p122848"></a>Goods for approval (six months)</td><td><a id="p122849"></a>234(2)</td></tr>
<tr><td><a id="p122850"></a>D25</td><td colspan="2"><a id="p122851"></a>Works of art, collectors' items and antiques</td><td><a id="p122852"></a>234(3)(a)</td></tr>
<tr><td><a id="p122853"></a>D26</td><td colspan="2"><a id="p122854"></a>Goods other than newly manufactured ones imported with a view to their sale by auction</td><td><a id="p122855"></a>234(3)(b)</td></tr>
<tr><td><a id="p122856"></a>D27</td><td colspan="2"><a id="p122857"></a>Spare parts, accessories and equipment</td><td><a id="p122858"></a>235</td></tr>
<tr><td><a id="p122859"></a>D28</td><td colspan="2"><a id="p122860"></a>Goods imported in particular situations having no economic effect</td><td><a id="p122861"></a>236(b)</td></tr>
<tr><td><a id="p122862"></a>D29</td><td colspan="2"><a id="p122863"></a>Goods imported for a period not exceeding three months</td><td><a id="p122864"></a>236(a)</td></tr>
<tr><td><a id="p122865"></a>D30</td><td colspan="2"><a id="p122866"></a>Means of transport for persons established outside the customs territory of the Union or for persons preparing the transfer of their normal place of residence outside that territory</td><td><a id="p122867"></a>216</td></tr>
<tr><td><a id="p122868"></a>D51</td><td colspan="2"><a id="p122869"></a>Temporary admission with partial relief from import duty</td><td><a id="p122870"></a>206</td></tr>
</table>


<a id="p122871"></a>Agricultural products


| <a id="p122872"></a>Code | <a id="p122873"></a>Description |
| --- | --- |
| <a id="p122874"></a>Import |  |
| <a id="p122875"></a>E01 | <a id="p122876"></a>Use of the unit price for the determination of the customs value for certain perishable goods (Article 74(2)(c) of the Code and Article 142(6)) |
| <a id="p122877"></a>E02 | <a id="p122878"></a>Standard import values (for example: Regulation (EU) No 543/<br>2011) <*>, <**> |


<a id="p122879"></a>

---

<a id="p122880"></a><*> Commission Implementing Regulation (EU) No 543/2011 of 7 June 2011 laying down detailed rules for the application of Council Regulation (EC) No 1234/2007 in respect of the fruit and vegetables and processed fruit and vegetables sectors (OJ L 157, 15.6.2011, p. 1).
<a id="p122881"></a><**> Commission Regulation (EC) No 612/2009 of 7 July 2009 on laying down common detailed rules for the application of the system of export refunds on agricultural products (OJ L 186, 17.7.2009, p. 1).

<a id="p122882"></a>Other


| <a id="p122883"></a>Code | <a id="p122884"></a>Description |
| --- | --- |
|  | <a id="p122885"></a>Import |
| <a id="p122886"></a>F01 | <a id="p122887"></a>Relief from import duties for returned goods (Article 203 of the Code) |
| <a id="p122888"></a>F02 | <a id="p122889"></a>Relief from import duties for returned goods (Special circumstances provided for in Article 159 of Delegated Regulation (EU) 2015/2446: agriculture goods) |
| <a id="p122890"></a>F03 | <a id="p122891"></a>Relief from import duties for returned goods (Special circumstances provided for in Article 158(3) of Delegated Regulation (EU) 2015/2446 repair or restoration) |
| <a id="p122892"></a>F04 | <a id="p122893"></a>Processed products which return to the European Union after having been previously re-exported subsequent to an inward processing procedure (Article 205(1) of the Code) |
| <a id="p122894"></a>F05 | <a id="p122895"></a>Relief from import duties and from VAT and/or excise duties for returned goods<br>(Art. 203 of the Code and Art. 143(1)(e) (Directive 2006/112/EC) |
| <a id="p122896"></a>F06 | <a id="p122897"></a>A movement of excise goods under an excise duty suspension arrangement from the place of importation in accordance with Article 17(1)(b) of Directive 2008/ 118/EC |
| <a id="p122898"></a>F07 | <a id="p122899"></a>Processed products which return to the European Union after having been previously re-exported subsequent to an inward processing procedure where the import duty is determined in accordance with Article 86(3) of the Code (Article 205(2) of the Code) |
| <a id="p122900"></a>F15 | <a id="p122901"></a>Goods introduced in the context of trade with special fiscal territories (Article 1(3) of the Code) |
| <a id="p122902"></a>F16 | <a id="p122903"></a>Goods introduced in the context of trade between the Union and the countries with which it has formed a customs union |
| <a id="p122904"></a>F21 | <a id="p122905"></a>Exemption from import duties of products of sea-fishing and other products taken from the territorial sea of a country or territory outside the customs territory of the Union by vessels solely registered or recorded in a Member State and flying the flag of that state |
| <a id="p122906"></a>F22 | <a id="p122907"></a>Exemption from import duties of products obtained from products of sea-fishing and other products taken from the territorial sea of a country or territory outside the customs territory of the Union on board factory-ships registered or recorded in a Member State and flying the flag of the state |
| <a id="p122908"></a>F44 | <a id="p122909"></a>Release for free circulation of processed products when Article 86(3) of Code) is to be applied |
| <a id="p122910"></a>F45 | <a id="p122911"></a>Exemption from value added tax on the final importation of certain goods (Council Directive 2009/132/EC <*>) |
| <a id="p122912"></a>F46 | <a id="p122913"></a>Use of the original tariff classification of the goods in situations provided for in Article 86(2) of the Code |
| <a id="p122914"></a>F47 | <a id="p122915"></a>Simplification of the drawing-up of customs declarations for goods falling under different tariff subheadings provided for in Article 177 of the Code |
| <a id="p122916"></a>F48 | <a id="p122917"></a>Import under the special scheme for distance sales of goods imported from third countries or third territories set out in Title XII Chapter 6 Section 4 of Directive 2006/112/EC. |
| <a id="p122918"></a>F49 | <a id="p122919"></a>Import under the special arrangements for declaration and payment of import VAT set out in Title XII Chapter 7 of Directive 2006/112/EC. |


<a id="p122920"></a>

---

<a id="p122921"></a><*> Council Directive 2009/132/EC of 19 October 2009 determining the scope of Article 143(b) and (c) of Directive 2006/112/EC as regards exemption from value added tax on the final importation of certain goods (OJ L 292, 10.11.2009, p. 5).

<a id="p122922"></a>2/1. Simplified declaration/Previous document
<a id="p122923"></a>This data element consists of alphanumeric codes.
<a id="p122924"></a>Each code has three components. The first component (an..3), which consists of a combination of digits and/or letters, serves to identify the type of document. The second component (an..35) represents the data needed to recognise that document, either its identification number or another recognisable reference. The third component (an..5) is used to identify which item of the previous document is being referred to.
<a id="p122925"></a>Where a paper-based customs declaration is lodged, the three components are separated by dashes (-).

1. <a id="p122926"></a>The first component (an..3)
<a id="p122927"></a>Choose the abbreviation for the document from the "list of abbreviations for documents" below.
<a id="p122928"></a>List of abbreviations for documents
<a id="p122929"></a>(numeric codes extracted from the 2014b UN Directories for electronic data interchange for administration, commerce and transport: List of code for data element 1001, Document/message name, coded)


| <a id="p122930"></a>Container list | <a id="p122931"></a>235 |
| --- | --- |
| <a id="p122932"></a>Delivery note | <a id="p122933"></a>270 |
| <a id="p122934"></a>Packing list | <a id="p122935"></a>271 |
| <a id="p122936"></a>Proforma invoice | <a id="p122937"></a>325 |
| <a id="p122938"></a>Temporary storage declaration | <a id="p122939"></a>337 |
| <a id="p122940"></a>Entry summary declaration | <a id="p122941"></a>355 |
| <a id="p122942"></a>Commercial invoice | <a id="p122943"></a>380 |
| <a id="p122944"></a>House waybill | <a id="p122945"></a>703 |
| <a id="p122946"></a>Master bill of lading | <a id="p122947"></a>704 |
| <a id="p122948"></a>Bill of lading | <a id="p122949"></a>705 |
| <a id="p122950"></a>House bill of lading | <a id="p122951"></a>714 |
| <a id="p122952"></a>Rail consignment note | <a id="p122953"></a>720 |
| <a id="p122954"></a>Road consignment note | <a id="p122955"></a>730 |
| <a id="p122956"></a>Air waybill | <a id="p122957"></a>740 |
| <a id="p122958"></a>Master air waybill | <a id="p122959"></a>741 |
| <a id="p122960"></a>Despatch note (post parcels) | <a id="p122961"></a>750 |
| <a id="p122962"></a>Multimodal/combined transport document | <a id="p122963"></a>760 |
| <a id="p122964"></a>Cargo manifest | <a id="p122965"></a>785 |
| <a id="p122966"></a>Bordereau | <a id="p122967"></a>787 |
| <a id="p122968"></a>Union/common transit declaration - Mixed consignments (T) | <a id="p122969"></a>820 |
| <a id="p122970"></a>External Union/common transit declaration (T1) | <a id="p122971"></a>821 |
| <a id="p122972"></a>Internal Union/common transit declaration (T2) | <a id="p122973"></a>822 |
| <a id="p122974"></a>Control document T5 | <a id="p122975"></a>823 |
| <a id="p122976"></a>Proof of the customs status of Union goods T2L | <a id="p122977"></a>825 |
| <a id="p122978"></a>TIR carnet | <a id="p122979"></a>952 |
| <a id="p122980"></a>ATA carnet | <a id="p122981"></a>955 |
| <a id="p122982"></a>Reference/date of entry in the declarant's records | <a id="p122983"></a>CLE |
| <a id="p122984"></a>Information sheet INF3 | <a id="p122985"></a>IF3 |
| <a id="p122986"></a>Cargo manifest - simplified procedure | <a id="p122987"></a>MNS |
| <a id="p122988"></a>Declaration/notification MRN | <a id="p122989"></a>MRN |
| <a id="p122990"></a>Internal Union transit Declaration - Article 227 of the Code | <a id="p122991"></a>T2F |
| <a id="p122992"></a>Proof of the customs status of Union goods T2LF | <a id="p122993"></a>T2G |
| <a id="p122994"></a>T2M proof | <a id="p122995"></a>T2M |
| <a id="p122996"></a>Simplified declaration | <a id="p122997"></a>SDE |
| <a id="p122998"></a>Other | <a id="p122999"></a>ZZZ |


<a id="p123000"></a>Code "CLE", included in this list stands for "date and reference of the entry in the declarant's records" (Article 182(1) of the Code). The date is coded as follows: yyyymmdd.

2. <a id="p123001"></a>The second component (an..35)
<a id="p123002"></a>The identification number or another recognisable reference of the document is inserted here.
<a id="p123003"></a>In case the MRN is referred to as previous document, the reference number shall have the following structure:


| <a id="p123004"></a>Field | <a id="p123005"></a>Content | <a id="p123006"></a>Format | <a id="p123007"></a>Examples |
| --- | --- | --- | --- |
| <a id="p123008"></a>1 | <a id="p123009"></a>Last two digits of year of formal acceptance of the declaration (YY) | <a id="p123010"></a>n2 | <a id="p123011"></a>15 |
| <a id="p123012"></a>2 | <a id="p123013"></a>Identifier of the country where the declaration/proof of the customs status of Union goods/ notification is lodged (alpha 2 country code) | <a id="p123014"></a>a2 | <a id="p123015"></a>RO |
| <a id="p123016"></a>3 | <a id="p123017"></a>Unique identifier for message per year and country | <a id="p123018"></a>an 12 | <a id="p123019"></a>9876AB889012 |
| <a id="p123020"></a>4 | <a id="p123021"></a>Procedure identifier | <a id="p123022"></a>a1 | <a id="p123023"></a>B |
| <a id="p123024"></a>5 | <a id="p123025"></a>Check digit | <a id="p123026"></a>an1 | <a id="p123027"></a>5 |


<a id="p123028"></a>Fields 1 and 2 as explained above.
<a id="p123029"></a>Field 3 shall be filled in with an identifier for the message concerned. The way that field is used is under the responsibility of national administrations but each message handled during one year within the given country must have a unique number in relation to the procedure concerned.
<a id="p123030"></a>National administrations that want to have the reference number of the competent customs office included in the MRN, may use up to the first 6 characters to represent it.
<a id="p123031"></a>Field 4 shall be filled in with an identifier of the procedure as defined in the table below.
<a id="p123032"></a>Field 5 shall be filled with a value that is a check digit for the whole MRN. This field allows for detection of an error when capturing the whole MRN.
<a id="p123033"></a>Codes to be used in field 4 Procedure identifier:


| <a id="p123034"></a>Code | <a id="p123035"></a>Procedure | <a id="p123036"></a>Corresponding columns in the table of Title I, Chapter 2 to Delegated Regulation (EU) 2015/2446 |
| --- | --- | --- |
| <a id="p123037"></a>A | <a id="p123038"></a>Export only | <a id="p123039"></a>B1, B2, B3 or C1 |
| <a id="p123040"></a>B | <a id="p123041"></a>Export and exit summary declaration | <a id="p123042"></a>Combinations of A1 or A2, with B1, B2, B3 or C1 |
| <a id="p123043"></a>C | <a id="p123044"></a>Exit summary declaration only | <a id="p123045"></a>A1 or A2 |
| <a id="p123046"></a>D | <a id="p123047"></a>Re-export notification | <a id="p123048"></a>A3 |
| <a id="p123049"></a>E | <a id="p123050"></a>Dispatch of goods in relation with special fiscal territories | <a id="p123051"></a>B4 |
| <a id="p123052"></a>J | <a id="p123053"></a>Transit declaration only | <a id="p123054"></a>D1, D2 or D3 |
| <a id="p123055"></a>K | <a id="p123056"></a>Transit declaration and exit summary declaration | <a id="p123057"></a>Combinations of D1, D2 or D3 with A1 or A2 |
| <a id="p123058"></a>L | <a id="p123059"></a>Transit declaration and entry summary declaration | <a id="p123060"></a>Combinations of D1, D2 or D3 with F1a, F2a, F3a, F4a or F5 |
| <a id="p123061"></a>M | <a id="p123062"></a>Proof of the customs status of Union goods/Customs goods manifest | <a id="p123063"></a>E1, E2 |
| <a id="p123064"></a>R | <a id="p123065"></a>Import declaration only | <a id="p123066"></a>H1, H2, H3, H4, H6, H7 <*> or I1 |
| <a id="p123067"></a>S | <a id="p123068"></a>Import declaration and entry summary declaration | <a id="p123069"></a>Combinations of H1, H2, H3, H4, H6, H7 <*> or I1 with F1a, F2a, F3a, F4a or F5 |
| <a id="p123070"></a>T | <a id="p123071"></a>Entry summary declaration only | <a id="p123072"></a>F1a, F1b, F1c, F1d, F2a, F2b, F2c, F2d, F3a, F3b, F4a, F4b, F4c or F5 |
| <a id="p123073"></a>V | <a id="p123074"></a>Introduction of goods in relation with special fiscal territories | <a id="p123075"></a>H5 |


<a id="p123076"></a>

---

<a id="p123077"></a><*> H7 as defined in Annex B Title I, Chapter 3 of Commission Delegated Regulation (EU) 2015/2446. Shall be limited to situations where the import declaration is referred to as previous document in a subsequent declaration.

3. <a id="p123078"></a>The third component (n..5)
<a id="p123079"></a>The item number of the goods concerned as provided in D.E. 1/6. Goods item number on the summary declaration or previous document.
<a id="p123080"></a>Examples:
- <a id="p123081"></a>The declaration item concerned was the 5th item on the T1 transit document (previous document) to which the office of destination has assigned the number "238 544". The code will therefore be "821-238544-5" ("821" for the transit procedure, "238544" for the document's registration number (or the MRN for the NCTS operations) and "5" for the item number).
- <a id="p123082"></a>Goods were declared through a simplified declaration. The MRN "16DE9876AB889012R1" has been allocated. In the supplementary declaration, the code will therefore be "SDE16DE9876AB889012R1". ("SDE" for the simplified declaration, "16DE9876AB889012R1" for the MRN of the document).
<a id="p123083"></a>If the above document is drawn up using the paper-based customs declaration (SAD), the abbreviation will comprise the codes specified for the first subdivision of D.E. 1/1 Declaration type (IM, CO and EU).
<a id="p123084"></a>Where, in the case of paper-based transit declarations, more than one reference has to be entered, and the Member States provide that a coded information shall be used, code 00200 as defined in D.E. 2/2 Additional information shall be applicable.

<a id="p123085"></a>2/2. Additional information
<a id="p123086"></a>A five-digit code is used to encode additional information of a customs nature. This code follows the additional information unless the Union law provides for the code to be used in place of the text.
<a id="p123087"></a>Example: Where the declarant and the consignor are the same person, code 00300 shall be entered.
<a id="p123088"></a>The Union law provides for certain additional information to be entered in data elements other than D.E. 2/2 Additional information. However, such additional information should be coded according to the same rules as the information to be specifically entered in D.E. 2/2 Additional information.
<a id="p123089"></a>Additional information - code XXXXX
<a id="p123090"></a>General category - Code 0xxxx


| <a id="p123091"></a>Legal basis | <a id="p123092"></a>Subject | <a id="p123093"></a>Additional information | <a id="p123094"></a>Code |
| --- | --- | --- | --- |
| <a id="p123095"></a>Article 163 of Delegated Regulation (EU) 2015/2446 | <a id="p123096"></a>Application for authorisation for the use of a special procedure other than transit based on the customs declaration | <a id="p123097"></a>"Simplified authorisation" | <a id="p123098"></a>00100 |
| <a id="p123099"></a>Title II of Annex D to Delegated Regulation (EU) 2015/2446 | <a id="p123100"></a>Several occurrences of documents or parties. | <a id="p123101"></a>"Various" | <a id="p123102"></a>00200 |
| <a id="p123103"></a>Title II of Annex D to Delegated Regulation (EU) 2015/2446 | <a id="p123104"></a>Identity between declarant and consignor | <a id="p123105"></a>"Consignor" | <a id="p123106"></a>00300 |
| <a id="p123107"></a>Title II of Annex D to Delegated Regulation (EU) 2015/2446 | <a id="p123108"></a>Identity between declarant and exporter | <a id="p123109"></a>"Exporter" | <a id="p123110"></a>00400 |
| <a id="p123111"></a>Title II of Annex D to Delegated Regulation (EU) 2015/2446 | <a id="p123112"></a>Identity between declarant and importer | <a id="p123113"></a>"Importer" | <a id="p123114"></a>00500 |
| <a id="p123115"></a>Article 176(1)(c) and Article 241(1) first subparagraph of Delegated Regulation (EU) 2015/2446 | <a id="p123116"></a>Discharge of inward processing | <a id="p123117"></a>"IP" and the relevant authorisation number or INF number | <a id="p123118"></a>00700 |
| <a id="p123119"></a>Article 241(1) second subparagraph of Delegated Regulation (EU) 2015/ 2446 | <a id="p123120"></a>Discharge of inward processing (specific commercial policy measures) | <a id="p123121"></a>"IP CPM" | <a id="p123122"></a>00800 |
| <a id="p123123"></a>Article 238 of Delegated Regulation (EU) 2015/2446 | <a id="p123124"></a>Discharge of temporary admission | <a id="p123125"></a>"TA" and the relevant authorisation number | <a id="p123126"></a>00900 |


<a id="p123127"></a>On import: Code 1xxxx


| <a id="p123128"></a>Legal basis | <a id="p123129"></a>Subject | <a id="p123130"></a>Additional information | <a id="p123131"></a>Code |
| --- | --- | --- | --- |
| <a id="p123132"></a>Title II of Annex D to Delegated<br>Regulation (EU) 2015/2446 | <a id="p123133"></a>Situations where negotiable bills of lading that are "to order blank endorsed" are concerned, in the case of entry summary declarations, where the consignee details are unknown. | <a id="p123134"></a>"Consignee unknown" | <a id="p123135"></a>10 600 |


<a id="p123136"></a>Other: Code 4xxxx


| <a id="p123137"></a>Legal basis | <a id="p123138"></a>Subject | <a id="p123139"></a>Additional information | <a id="p123140"></a>Code |
| --- | --- | --- | --- |
| <a id="p123141"></a>Article 123 of Delegated Regulation (EU) 2015/2446 | <a id="p123142"></a>Request for a longer period of validity of the proof of the customs status of Union goods | <a id="p123143"></a>"Longer period of validity of the proof of the customs status of Union goods" | <a id="p123144"></a>40 100 |


<a id="p123145"></a>2/3. Documents produced, certificates and authorisations, additional references
<a id="p123146"></a>(a) Union or international documents, certificates and authorisations produced in support of the declaration, and additional references must be entered in the form of a code defined in Title I, followed either by an identification number or another recognisable reference. The list of documents, certificates and authorisations, and of additional references and their respective codes can be found in the TARIC database.
<a id="p123147"></a>(b) National documents, certificates and authorisations produced in support of the declaration, and additional references must be entered in the form of a code as defined in Title I (Ex: 2123, 34d5), possibly followed either by an identification number or another recognisable reference. The four characters represent codes based on that Member State's own nomenclature.

<a id="p123148"></a>2/7. Identification of warehouse
<a id="p123149"></a>The code to be entered has the following two-part structure:
- <a id="p123150"></a>The character identifying the type of warehouse:
<a id="p123151"></a>R Public customs warehouse type I
<a id="p123152"></a>S Public customs warehouse type II
<a id="p123153"></a>T Public customs warehouse type III
<a id="p123154"></a>U Private customs warehouse
<a id="p123155"></a>V Storage facilities for the temporary storage of goods
<a id="p123156"></a>Y Non-customs warehouse
<a id="p123157"></a>Z Free zone
- <a id="p123158"></a>The identification number allocated by the Member State when issuing the authorisation in cases where such an authorisation is issued

<a id="p123159"></a>3/1. Exporter
<a id="p123160"></a>In the case of groupage consignments, where paper-based customs declarations are used, and the Member States provide for the use of coded information, code 00200 as defined in D.E. 2/2 Additional information shall be applicable.

<a id="p123161"></a>3/2. Exporter identification no
<a id="p123162"></a>The EORI number is structured as follows:


| <a id="p123163"></a>Field | <a id="p123164"></a>Content | <a id="p123165"></a>Format |
| --- | --- | --- |
| <a id="p123166"></a>1 | <a id="p123167"></a>Identifier of the Member State (country code) | <a id="p123168"></a>a2 |
| <a id="p123169"></a>2 | <a id="p123170"></a>Unique identifier in a Member State | <a id="p123171"></a>an..15 |


<a id="p123172"></a>Country code: The country code as defined in Title I regarding the country code of D.E. 3/1 Exporter shall be used.
<a id="p123173"></a>The structure of a third country unique identification number which has been made available to the Union is as follows:


| <a id="p123174"></a>Field | <a id="p123175"></a>Content | <a id="p123176"></a>Format |
| --- | --- | --- |
| <a id="p123177"></a>1 | <a id="p123178"></a>Country code | <a id="p123179"></a>a2 |
| <a id="p123180"></a>2 | <a id="p123181"></a>Unique identification number in a third country | <a id="p123182"></a>an..15 |


<a id="p123183"></a>3/21. Representative status code
<a id="p123184"></a>Insert one of the following codes (n1) before the full name and address to designate the status of the representative:
<a id="p123185"></a>2 Representative (direct representation within the meaning of Article 18(1) of the Code).
<a id="p123186"></a>3 Representative (indirect representation within the meaning of Article 18(1) of the Code).
<a id="p123187"></a>Where this data element is printed on a paper document, it will be in square brackets (Ex: [2] or [3]).

<a id="p123188"></a>3/37. Additional supply chain actor(s) identification no
<a id="p123189"></a>This data element consists of two components:

1. <a id="p123190"></a>Role code
<a id="p123191"></a>The following parties can be declared:


| <a id="p123192"></a>Role<br>Code | <a id="p123193"></a>Party | <a id="p123194"></a>Description |
| --- | --- | --- |
| <a id="p123195"></a>CS | <a id="p123196"></a>Consolidator | <a id="p123197"></a>Freight forwarder combining individual smaller consignments into a single larger consignment (in a consolidation process) that is sent to a counterpart who mirrors the consolidator's activity by dividing the consolidated consignment into its original components |
| <a id="p123198"></a>FW | <a id="p123199"></a>Freight Forwarder | <a id="p123200"></a>Party undertaking forwarding of goods |
| <a id="p123201"></a>MF | <a id="p123202"></a>Manufacturer | <a id="p123203"></a>Party which manufactures goods |
| <a id="p123204"></a>WH | <a id="p123205"></a>Warehouse Keeper | <a id="p123206"></a>Party taking responsibility for goods entered into a warehouse |


2. <a id="p123207"></a>Identification no of the party
<a id="p123208"></a>The structure of that number corresponds to the structure as specified for D.E. 3/2 Exporter identification no.

<a id="p123209"></a>3/40. Additional fiscal references identification no
<a id="p123210"></a>This data element consists of two components:
1. <a id="p123211"></a>Role code
<a id="p123212"></a>The following parties can be declared:


| <a id="p123213"></a>Role<br>Code | <a id="p123214"></a>Party | <a id="p123215"></a>Description |
| --- | --- | --- |
| <a id="p123216"></a>FR1 | <a id="p123217"></a>Importer | <a id="p123218"></a>Person or persons designated or recognised as liable for the payment of value added tax by the Member State of importation in accordance with Article 201 of Directive 2006/112/EC |
| <a id="p123219"></a>FR2 | <a id="p123220"></a>Customer | <a id="p123221"></a>Person liable for the payment of Value Added Tax on the intra<br>-Union acquisition of goods in accordance with Article 200 of Directive 2006/112/EC |
| <a id="p123222"></a>FR3 | <a id="p123223"></a>Tax representative | <a id="p123224"></a>Tax representative liable for the payment of value added tax in the Member State of importation appointed by the importer |
| <a id="p123225"></a>FR4 | <a id="p123226"></a>Holder of the deferred payment authorisation | <a id="p123227"></a>The taxable person or the person liable for payment or another person that has received deferment of payment in accordance with Article 211 of Directive 2006/112/EC |
| <a id="p123228"></a>FR5 | <a id="p123229"></a>Vendor (IOSS) | <a id="p123230"></a>Taxable person making use of the special scheme for distance sales of goods imported from third countries or third territories set out in Title XII Chapter 6 Section 4 of Directive 2006/112/EC and holder of the VAT identification number referred to in Article 369q therein |
| <a id="p123231"></a>FR7 | <a id="p123232"></a>Taxable person or of the person liable for payment of VAT | <a id="p123233"></a>VAT identification number of the taxable person or of the person liable for payment of VAT where the payment of VAT is postponed in accordance with Article 211 second subparagraph of Directive 2006/112/EC. |


2. <a id="p123234"></a>The value added tax identification number is structured as follows:


| <a id="p123235"></a>Field | <a id="p123236"></a>Content | <a id="p123237"></a>Format |
| --- | --- | --- |
| <a id="p123238"></a>1 | <a id="p123239"></a>Identifier of the Member State of issue (ISO code 3166 - alpha 2; Greece may use EL) | <a id="p123240"></a>a2 |
| <a id="p123241"></a>2 | <a id="p123242"></a>Individual number attributed by Member States for the identification of taxable persons referred to in Article 214 of Directive 2006/112/EC | <a id="p123243"></a>an..15 |


<a id="p123244"></a>4/1. Delivery terms
<a id="p123245"></a>The codes and statements to be entered, as appropriate, in the first two subdivisions are as follows:


<table>
<colgroup><col width="33%"><col width="31%"><col width="36%"></colgroup>
<tr><td><a id="p123246"></a>First subdivision</td><td><a id="p123247"></a>Meaning</td><td><a id="p123248"></a>Second subdivision</td></tr>
<tr><td><a id="p123249"></a>Incoterms code</td><td><a id="p123250"></a>Incoterms - ICC/ECE</td><td><a id="p123251"></a>Place to be specified</td></tr>
<tr><td colspan="3"><a id="p123252"></a>Codes applicable for all modes of transport</td></tr>
<tr><td><a id="p123253"></a>EXW (Incoterms 2010 or Incoterms 2020)</td><td><a id="p123254"></a>Ex works</td><td><a id="p123255"></a>Named place of delivery</td></tr>
<tr><td><a id="p123256"></a>FCA (Incoterms 2010 or Incoterms 2020)</td><td><a id="p123257"></a>Free carrier</td><td><a id="p123258"></a>Named place of delivery</td></tr>
<tr><td><a id="p123259"></a>CPT (Incoterms 2010 or Incoterms 2020)</td><td><a id="p123260"></a>Carriage paid to</td><td><a id="p123261"></a>Named place of destination</td></tr>
<tr><td><a id="p123262"></a>CIP (Incoterms 2010 or Incoterms 2020)</td><td><a id="p123263"></a>Carriage and insurance paid to</td><td><a id="p123264"></a>Named place of destination</td></tr>
<tr><td><a id="p123265"></a>DAT (Incoterms 2010)</td><td><a id="p123266"></a>Delivered at terminal</td><td><a id="p123267"></a>Named terminal at port or place of destination</td></tr>
<tr><td><a id="p123268"></a>DPU (Incoterms 2020)</td><td><a id="p123269"></a>Delivered at place unloaded</td><td><a id="p123270"></a>Named place of destination</td></tr>
<tr><td><a id="p123271"></a>DAP (Incoterms 2010 or Incoterms 2020)</td><td><a id="p123272"></a>Delivered at place</td><td><a id="p123273"></a>Named place of destination</td></tr>
<tr><td><a id="p123274"></a>DDP (Incoterms 2010 or Incoterms 2020)</td><td><a id="p123275"></a>Delivered duty paid</td><td><a id="p123276"></a>Named place of destination</td></tr>
<tr><td colspan="3"><a id="p123277"></a>Codes applicable for sea and inland waterway transport</td></tr>
<tr><td><a id="p123278"></a>FAS (Incoterms 2010 or Incoterms 2020)</td><td><a id="p123279"></a>Free along ship</td><td><a id="p123280"></a>Named port of shipment</td></tr>
<tr><td><a id="p123281"></a>FOB (Incoterms 2010 or Incoterms 2020)</td><td><a id="p123282"></a>Free on board</td><td><a id="p123283"></a>Named port of shipment</td></tr>
<tr><td><a id="p123284"></a>CFR (Incoterms 2010 or Incoterms 2020)</td><td><a id="p123285"></a>Cost and freight</td><td><a id="p123286"></a>Named port of destination</td></tr>
<tr><td><a id="p123287"></a>CIF (Incoterms 2010 or Incoterms 2020)</td><td><a id="p123288"></a>Cost, insurance and freight</td><td><a id="p123289"></a>Named port of destination</td></tr>
<tr><td><a id="p123290"></a>XXX</td><td><a id="p123291"></a>Delivery terms other than those listed above</td><td><a id="p123292"></a>Narrative description of delivery terms given in the contract</td></tr>
</table>


<a id="p123293"></a>4/3. Calculation of taxes - Tax type
<a id="p123294"></a>The codes applicable are given below:


| <a id="p123295"></a>A00 | <a id="p123296"></a>Import duty |
| --- | --- |
| <a id="p123297"></a>A30 | <a id="p123298"></a>Definitive antidumping duties |
| <a id="p123299"></a>A35 | <a id="p123300"></a>Provisional antidumping duties |
| <a id="p123301"></a>A40 | <a id="p123302"></a>Definitive countervailing duties |
| <a id="p123303"></a>A45 | <a id="p123304"></a>Provisional countervailing duties |
| <a id="p123305"></a>B00 | <a id="p123306"></a>VAT |
| <a id="p123307"></a>C00 | <a id="p123308"></a>Export duty |
| <a id="p123309"></a>E00 | <a id="p123310"></a>Duties collected on behalf of other countries |


<a id="p123311"></a>4/8. Calculation of taxes - Method of payment
<a id="p123312"></a>The following codes may be used by the Member States:


| <a id="p123313"></a>A | <a id="p123314"></a>Payment in cash |
| --- | --- |
| <a id="p123315"></a>B | <a id="p123316"></a>Payment by credit card |
| <a id="p123317"></a>C | <a id="p123318"></a>Payment by cheque |
| <a id="p123319"></a>D | <a id="p123320"></a>Other (e.g. direct debit to agent's cash account) |
| <a id="p123321"></a>E | <a id="p123322"></a>Deferred or postponed payment |
| <a id="p123323"></a>G | <a id="p123324"></a>Postponed payment - VAT system (Article 211 of Directive 2006/112/EC) |
| <a id="p123325"></a>H | <a id="p123326"></a>Electronic credit transfer |
| <a id="p123327"></a>J | <a id="p123328"></a>Payment through post office administration (postal consignments) or other public sector or government department |
| <a id="p123329"></a>K | <a id="p123330"></a>Excise credit or rebate |
| <a id="p123331"></a>P | <a id="p123332"></a>From agent's cash account |
| <a id="p123333"></a>R | <a id="p123334"></a>Guarantee of the amount payable |
| <a id="p123335"></a>S | <a id="p123336"></a>Individual guarantee account |
| <a id="p123337"></a>T | <a id="p123338"></a>From agent's guarantee account |
| <a id="p123339"></a>U | <a id="p123340"></a>From agent's guarantee - standing authority |
| <a id="p123341"></a>V | <a id="p123342"></a>From agent's guarantee - individual authority |
| <a id="p123343"></a>O | <a id="p123344"></a>Guarantee lodged with Intervention Agency. |


<a id="p123345"></a>4/9. Additions and deductions
<a id="p123346"></a>Additions (As defined under Articles 70 and 71 of the Code):


| <a id="p123347"></a>AB | <a id="p123348"></a>Commissions and brokerage, except buying commissions |
| --- | --- |
| <a id="p123349"></a>AD | <a id="p123350"></a>Containers and packing |
| <a id="p123351"></a>AE | <a id="p123352"></a>Materials, components, parts and similar items incorporated in the imported goods |
| <a id="p123353"></a>AF | <a id="p123354"></a>Tools, dies, moulds and similar items used in the production of the imported goods |
| <a id="p123355"></a>AG | <a id="p123356"></a>Materials consumed in the production of the imported goods |
| <a id="p123357"></a>AH | <a id="p123358"></a>Engineering, development, artwork, design work and plans and sketches undertaken elsewhere than in the European Union and necessary for the production of the imported goods |
| <a id="p123359"></a>AI | <a id="p123360"></a>Royalties and license fees |
| <a id="p123361"></a>AJ | <a id="p123362"></a>Proceeds of any subsequent resale, disposal or use accruing to the seller |
| <a id="p123363"></a>AK | <a id="p123364"></a>Transport costs, loading and handling charges and insurance costs up to the place of introduction in the European Union |
| <a id="p123365"></a>AL | <a id="p123366"></a>Indirect payments and other payments (Article 70 of the code) |
| <a id="p123367"></a>AN | <a id="p123368"></a>Additions based on a decision granted in accordance with Article 71 of Delegated Regulation (EU) 2015/2446 |


<a id="p123369"></a>Deductions (As defined under Articles 72 of the Code):


| <a id="p123370"></a>BA | <a id="p123371"></a>Costs of transport after arrival at the place of introduction |
| --- | --- |
| <a id="p123372"></a>BB | <a id="p123373"></a>Charges for construction, erection, assembly, maintenance or technical assistance undertaken after importation |
| <a id="p123374"></a>BC | <a id="p123375"></a>Import duties or other charges payable in the Union for reason of the import or sale of goods |
| <a id="p123376"></a>BD | <a id="p123377"></a>Interest charges |
| <a id="p123378"></a>BE | <a id="p123379"></a>Charges for the right to reproduce the imported goods in the European Union |
| <a id="p123380"></a>BF | <a id="p123381"></a>Buying commissions |
| <a id="p123382"></a>BG | <a id="p123383"></a>Deductions based on a decision granted in accordance with Article 71 of Delegated Regulation (EU) 2015/2446 |


<a id="p123384"></a>4/13. Valuation indicators
<a id="p123385"></a>The code comprises four digits, each of which being either a "0" or a "1".
<a id="p123386"></a>Each "1" or "0" digit reflects whether or not a valuation indicator is relevant to the valuation of the goods concerned.
<a id="p123387"></a>1st digit: Party relationship, whether there is price influence or not
<a id="p123388"></a>2nd digit: Restrictions as to the disposal or use of the goods by the buyer in accordance with Article 70(3)(a) of the Code
<a id="p123389"></a>3rd digit: Sale or price is subject to some condition or consideration in accordance with Article 70(3)(b) of the Code.
<a id="p123390"></a>4th digit: The sale is subject to an arrangement under which part of the proceeds of any subsequent resale, disposal or use accrues directly or indirectly to the seller
<a id="p123391"></a>Example: Goods subject to party relationship, but not to any of the other situations defined under 2nd, 3rd and 4th digits would entail the use of code combination "1000."

<a id="p123392"></a>4/16. Valuation method
<a id="p123393"></a>The provisions used to determine the customs value of imported goods are to be coded as follows:


| <a id="p123394"></a>Code | <a id="p123395"></a>Relevant Article of the Code | <a id="p123396"></a>Method |
| --- | --- | --- |
| <a id="p123397"></a>1 | <a id="p123398"></a>70 | <a id="p123399"></a>Transaction value of the imported goods |
| <a id="p123400"></a>2 | <a id="p123401"></a>74(2)(a) | <a id="p123402"></a>Transaction value of identical goods |
| <a id="p123403"></a>3 | <a id="p123404"></a>74(2)(b) | <a id="p123405"></a>Transaction value of similar goods |
| <a id="p123406"></a>4 | <a id="p123407"></a>74(2)(c) | <a id="p123408"></a>Deductive value method |
| <a id="p123409"></a>5 | <a id="p123410"></a>74(2)(d) | <a id="p123411"></a>Computed value method |
| <a id="p123412"></a>6 | <a id="p123413"></a>74(3) | <a id="p123414"></a>Value based on the data available ("fall-back" method) |


<a id="p123415"></a>4/17. Preference
<a id="p123416"></a>This information includes three-digit codes comprising a single-digit component from 1) and a two-digit component from 2).
<a id="p123417"></a>The relevant codes are given below:
<a id="p123418"></a>(1) First digit of the code
<a id="p123419"></a>1 Tariff arrangement erga omnes
<a id="p123420"></a>2 Generalised System of Preferences (GSP)
<a id="p123421"></a>3 Tariff preferences other than those mentioned under code 2
<a id="p123422"></a>4 Customs duties under the provisions of customs union agreements concluded by the European Union
<a id="p123423"></a>(2) Next two digits of the code
<a id="p123424"></a>00 None of the following
<a id="p123425"></a>10 Tariff suspension
<a id="p123426"></a>18 Tariff suspension with certificate confirming the special nature of the product
<a id="p123427"></a>19 Temporary suspension for products imported with an authorised release certificate EASA Form 1 or an equivalent certificate
<a id="p123428"></a>20 Tariff quota <*>

<a id="p123429"></a>

---

<a id="p123430"></a><*> Where the requested tariff quota is exhausted, Member States may allow the request to be valid for any other preference.

<a id="p123431"></a>25 Tariff quota with certificate confirming the special nature of the product <*>

<a id="p123432"></a>

---

<a id="p123433"></a><*> Where the requested tariff quota is exhausted, Member States may allow the request to be valid for any other preference.

<a id="p123434"></a>28 Tariff quota following outward processing <*>

<a id="p123435"></a>

---

<a id="p123436"></a><*> Where the requested tariff quota is exhausted, Member States may allow the request to be valid for any other preference.

<a id="p123437"></a>50 Certificate confirming the special nature of the product

<a id="p123438"></a>5/23. Location of goods
<a id="p123439"></a>Use the ISO alpha 2 country codes used in field 1 of D.E. 3/1 Exporter.
<a id="p123440"></a>For the type of location, use the codes specified below:
<a id="p123441"></a>A Designated location
<a id="p123442"></a>B Authorised place
<a id="p123443"></a>C Approved place
<a id="p123444"></a>D Other
<a id="p123445"></a>For the identification of the location use one of the identifiers below:


| <a id="p123446"></a>Qualifier | <a id="p123447"></a>Identifier | <a id="p123448"></a>Description |
| --- | --- | --- |
| <a id="p123449"></a>T | <a id="p123450"></a>Postal code | <a id="p123451"></a>Use the postal code with or without house number for the location concerned. |
| <a id="p123452"></a>U | <a id="p123453"></a>UN/LOCODE | <a id="p123454"></a>UN/LOCODE as referred to in introductory note 13 number 4. |
| <a id="p123455"></a>V | <a id="p123456"></a>Customs office identifier | <a id="p123457"></a>Use the codes specified under D.E. 1701000000 Customs office of exit |
| <a id="p123458"></a>W | <a id="p123459"></a>GNSS coordinates | <a id="p123460"></a>Decimal degrees with negative numbers for South and West.<br>Examples: 44.424896°/8.774792° or 50.838068°/ 4.381508° |
| <a id="p123461"></a>X | <a id="p123462"></a>EORI number | <a id="p123463"></a>Use the identification number as specified in the description for D.E. 3/2 Exporter identification n°. In case the economic operator has more than one premises, the EORI number shall be completed by an identifier unique for the location concerned. |
| <a id="p123464"></a>Y | <a id="p123465"></a>Authorisation number | <a id="p123466"></a>Enter the authorisation number of the location concerned, i.e. of the warehouse where the goods can be examined. In case the authorisation concerns more than one premises, the authorisation number shall be completed by an identifier unique for the location concerned. |
| <a id="p123467"></a>Z | <a id="p123468"></a>Address | <a id="p123469"></a>Enter the address of the location concerned. |


<a id="p123470"></a>In case code "X" (EORI number) or "Y" (authorisation number) is used for the identification of the location, and there are several locations associated with the EORI number or the authorisation number concerned, an additional identifier can be used to enable the unambiguous identification of the location.

<a id="p123471"></a>7/2. Container
<a id="p123472"></a>The relevant codes are given below:
<a id="p123473"></a>0 Goods not transported in containers
<a id="p123474"></a>1 Goods transported in containers

<a id="p123475"></a>7/4. Mode of transport at the border
<a id="p123476"></a>The codes applicable are given below:


| <a id="p123477"></a>Code | <a id="p123478"></a>Description |
| --- | --- |
| <a id="p123479"></a>1 | <a id="p123480"></a>Maritime transport |
| <a id="p123481"></a>2 | <a id="p123482"></a>Rail transport |
| <a id="p123483"></a>3 | <a id="p123484"></a>Road transport |
| <a id="p123485"></a>4 | <a id="p123486"></a>Air transport |
| <a id="p123487"></a>5 | <a id="p123488"></a>Mail (Active mode of transport unknown) |
| <a id="p123489"></a>7 | <a id="p123490"></a>Fixed transport installations |
| <a id="p123491"></a>8 | <a id="p123492"></a>Inland waterway transport |
| <a id="p123493"></a>9 | <a id="p123494"></a>Mode unknown (i.e. own propulsion) |


<a id="p123495"></a>8/2. Guarantee type
<a id="p123496"></a>Guarantee codes
<a id="p123497"></a>The codes applicable are given below:


| <a id="p123498"></a>Code | <a id="p123499"></a>Description |
| --- | --- |
| <a id="p123500"></a>0 | <a id="p123501"></a>For guarantee waiver (Article 95(2) of the Code) |
| <a id="p123502"></a>1 | <a id="p123503"></a>For comprehensive guarantee (Article 89(5) of the Code) |
| <a id="p123504"></a>2 | <a id="p123505"></a>For individual guarantee in the form of an undertaking by a guarantor (Article 92(1)(b) of the Code) |
| <a id="p123506"></a>3 | <a id="p123507"></a>For individual guarantee in cash or other means of payment recognised by the customs authorities as being equivalent to a cash deposit, made in euro or in the currency of the Member State in which the guarantee is required (Article 92(1)(a) of the Code) |
| <a id="p123508"></a>4 | <a id="p123509"></a>For individual guarantee in the form of vouchers (Article 92(1)(b) of the Code and Article 160) |
| <a id="p123510"></a>5 | <a id="p123511"></a>For guarantee waiver where the amount of import or export duty to be secured does not exceed the statistical value threshold for declarations laid down in accordance with Article 3(4) of Regulation (EC) No 471/2009 of the European Parliament and of the Council <*> (Article 89(9) of the Code) |
| <a id="p123512"></a>I | <a id="p123513"></a>For individual guarantee in another form which provides equivalent assurance that the amount of import or export duty corresponding to the customs debt and other charges will be paid (Article 92(1)(c) of the Code) |
| <a id="p123514"></a>8 | <a id="p123515"></a>For guarantee not required for certain public bodies (Article 89(7) of the Code) |
| <a id="p123516"></a>B | <a id="p123517"></a>For guarantee furnished for goods dispatched under TIR procedure |
| <a id="p123518"></a>C | <a id="p123519"></a>For guarantee not required for goods carried by fix transport installations (Article 89(8)(b) of the Code) |
| <a id="p123520"></a>D | <a id="p123521"></a>For guarantee not required for goods placed under the temporary admission procedure in accordance with Article 81(a) of Delegated Regulation (EU) 2015/2446 (Article 89(8)(c) of the Code) |
| <a id="p123522"></a>E | <a id="p123523"></a>For guarantee not required for goods placed under the temporary admission procedure in accordance with Article 81(b) of Delegated Regulation (EU) 2015/2446 (Article 89(8)(c) of the Code) |
| <a id="p123524"></a>F | <a id="p123525"></a>For guarantee not required for goods placed under the temporary admission procedure in accordance with Article 81(c) of Delegated Regulation (EU) 2015/2446 (Article 89(8)(c) of the Code) |
| <a id="p123526"></a>G | <a id="p123527"></a>For guarantee not required for goods placed under the temporary admission procedure in accordance with Article 81(d) of Delegated Regulation (EU) 2015/2446 (Article 89(8)(c) of the Code) |
| <a id="p123528"></a>H | <a id="p123529"></a>For guarantee not required for goods placed under the Union transit procedure in accordance with Article 89(8)(d) of the Code |


<a id="p123530"></a>

---

<a id="p123531"></a><*> Regulation (EC) No 471/2009 of the European Parliament and of the Council of 6 May 2009 on Community statistics relating to external trade with non-member countries and repealing Council Regulation (EC) No 1172/95 (OJ L 152, 16.6.2009, p. 23).

<a id="p123532"></a>**TITLE III. LINGUISTIC REFERENCES AND THEIR CODES**

<a id="p123533"></a>Table of linguistic references and their codes


<table>
<colgroup><col width="70%"><col width="30%"></colgroup>
<tr><td><a id="p123534"></a>Linguistic references</td><td><a id="p123535"></a>Codes</td></tr>
<tr><td><a id="p123536"></a>- BG Ограничена валидност</td><td rowspan="23"><a id="p123537"></a>Limited validity - 99200</td></tr>
<tr><td><a id="p123538"></a>- CS Omezená platnost</td></tr>
<tr><td><a id="p123539"></a>- DA Begrænset gyldighed</td></tr>
<tr><td><a id="p123540"></a>- DE Beschränkte Geltung</td></tr>
<tr><td><a id="p123541"></a>- EE Piiratud kehtivus</td></tr>
<tr><td><a id="p123542"></a>- EL $\iota\sigma\chi\text{ύ}\varsigma$ $\Pi\epsilon\rho\iota o\rho\iota\sigma\mu\text{έ}\nu\eta$</td></tr>
<tr><td><a id="p123543"></a>- ES Validez limitada</td></tr>
<tr><td><a id="p123544"></a>- FR limitée Validité</td></tr>
<tr><td><a id="p123545"></a>- HR Ogranièena valjanost</td></tr>
<tr><td><a id="p123546"></a>- IT Validità limitata</td></tr>
<tr><td><a id="p123547"></a>- LV derîgums Ierobežots</td></tr>
<tr><td><a id="p123548"></a>- LT Galiojimas apribotas</td></tr>
<tr><td><a id="p123549"></a>- HU érvényû Korlátozott</td></tr>
<tr><td><a id="p123550"></a>- MT Validità limitata</td></tr>
<tr><td><a id="p123551"></a>- NL Beperkte geldigheid</td></tr>
<tr><td><a id="p123552"></a>- PL Ograniczona $wa¿noœæ$</td></tr>
<tr><td><a id="p123553"></a>- PT Validade limitada</td></tr>
<tr><td><a id="p123554"></a>- RO Validitate limitatã</td></tr>
<tr><td><a id="p123555"></a>- SL Omejena veljavnost</td></tr>
<tr><td><a id="p123556"></a>- SK Obmedzená platnost'</td></tr>
<tr><td><a id="p123557"></a>- FI Voimassa rajoitetusti</td></tr>
<tr><td><a id="p123558"></a>- SV Begränsad giltighet</td></tr>
<tr><td><a id="p123559"></a>- EN Limited validity</td></tr>
<tr><td><a id="p123560"></a>- BG Освободено</td><td rowspan="23"><a id="p123561"></a>Waiver - 99201</td></tr>
<tr><td><a id="p123562"></a>- CS Osvobození</td></tr>
<tr><td><a id="p123563"></a>- DA Fritaget</td></tr>
<tr><td><a id="p123564"></a>- DE Befreiung</td></tr>
<tr><td><a id="p123565"></a>- EE Loobutud</td></tr>
<tr><td><a id="p123566"></a>- EL $\text{Α}\pi\alpha\lambda\lambda\alpha\gamma\text{ή}$</td></tr>
<tr><td><a id="p123567"></a>- ES Dispensa</td></tr>
<tr><td><a id="p123568"></a>- FR Dispense</td></tr>
<tr><td><a id="p123569"></a>- HR Osloboðeno</td></tr>
<tr><td><a id="p123570"></a>- IT Dispensa</td></tr>
<tr><td><a id="p123571"></a>- LV Derîgs bez zîmoga</td></tr>
<tr><td><a id="p123572"></a>- LT Leista neplombuoti</td></tr>
<tr><td><a id="p123573"></a>- HU Mentesség</td></tr>
<tr><td><a id="p123574"></a>- MT $Tne©¤©ija¤$</td></tr>
<tr><td><a id="p123575"></a>- NL Vrijstelling</td></tr>
<tr><td><a id="p123576"></a>- PL Zwolnienie</td></tr>
<tr><td><a id="p123577"></a>- PT Dispensa</td></tr>
<tr><td><a id="p123578"></a>- RO Dispensã</td></tr>
<tr><td><a id="p123579"></a>- SL Opustitev</td></tr>
<tr><td><a id="p123580"></a>- SK Upustenie</td></tr>
<tr><td><a id="p123581"></a>- FI Vapautettu</td></tr>
<tr><td><a id="p123582"></a>- SV Befrielse</td></tr>
<tr><td><a id="p123583"></a>- EN Waiver</td></tr>
<tr><td><a id="p123584"></a>- BG Алтернативно доказателство</td><td rowspan="23"><a id="p123585"></a>Alternative proof - 99202</td></tr>
<tr><td><a id="p123586"></a>- CS dùkaz Alternativní</td></tr>
<tr><td><a id="p123587"></a>- DA Alternativt bevis</td></tr>
<tr><td><a id="p123588"></a>- DE Alternativnachweis</td></tr>
<tr><td><a id="p123589"></a>- EE Alternatiivsed tõendid</td></tr>
<tr><td><a id="p123590"></a>- EL $\alpha\pi\text{ό}\delta\epsilon\iota\xi\eta$ $\text{Ε}\nu\alpha\lambda\lambda\alpha\kappa\tau\iota\kappa\text{ή}$</td></tr>
<tr><td><a id="p123591"></a>- ES Prueba alternativa</td></tr>
<tr><td><a id="p123592"></a>- FR Preuve alternative</td></tr>
<tr><td><a id="p123593"></a>- HR Alternativni dokaz</td></tr>
<tr><td><a id="p123594"></a>- IT Prova alternativa</td></tr>
<tr><td><a id="p123595"></a>- LV pierâdîjums Alternatîvs</td></tr>
<tr><td><a id="p123596"></a>- LT Alternatyvusis árodymas</td></tr>
<tr><td><a id="p123597"></a>- HU igazolás Alternatív</td></tr>
<tr><td><a id="p123598"></a>- MT Prova alternattiva</td></tr>
<tr><td><a id="p123599"></a>- NL Alternatief bewijs</td></tr>
<tr><td><a id="p123600"></a>- PL Alternatywny dowód</td></tr>
<tr><td><a id="p123601"></a>- PT Prova alternativa</td></tr>
<tr><td><a id="p123602"></a>- RO alternativã Probã</td></tr>
<tr><td><a id="p123603"></a>- SL Alternativno dokazilo</td></tr>
<tr><td><a id="p123604"></a>- SK Alternatívny vny dôkaz</td></tr>
<tr><td><a id="p123605"></a>- FI Vaihtoehtoinen todiste</td></tr>
<tr><td><a id="p123606"></a>- SV Alternativt bevis</td></tr>
<tr><td><a id="p123607"></a>- EN Alternative proof</td></tr>
<tr><td><a id="p123608"></a>- BG Различия: митническо учреждение, където са представени стоките ...... (наименование и държава)</td><td rowspan="23"><a id="p123609"></a>Differences: office where goods were presented .... (name and country) - 99 203</td></tr>
<tr><td><a id="p123610"></a>- CS Nesrovnalosti: ъøad , kterému bylo zboží pøedloženo ...... ( název a zemì )</td></tr>
<tr><td><a id="p123611"></a>- DA Forskelle: det sted, hvor varerne blev frembudt ...... (navn og land)</td></tr>
<tr><td><a id="p123612"></a>- DE Unstimmigkeiten: Stelle, bei der die Gestellung erfolgte ...... (Name und Land)</td></tr>
<tr><td><a id="p123613"></a>- EE Erinevused: asutus, kuhu kaup esitati ...... (nimi ja riik)</td></tr>
<tr><td><a id="p123614"></a>- EL $\Delta\iota\alpha\phi o\rho\text{έ}\varsigma:$ $\epsilon\mu\pi o\rho\epsilon\text{ύ}\mu\alpha\tau\alpha$ $\pi\rho o\sigma\kappa o\mu\iota\sigma\theta\text{έ}\nu\tau\alpha$ $\sigma\tau o$ $\tau\epsilon\lambda\omega\nu\epsilon\text{ί}o$ ...... ( $Ό\nu o\mu\alpha$ $\kappa\alpha\iota$ $\chi\text{ώ}\rho\alpha$ )</td></tr>
<tr><td><a id="p123615"></a>- ES Diferencias: mercancías presentadas en la oficina ...... (nombre y país )</td></tr>
<tr><td><a id="p123616"></a>- FR $Différences:$ marchandises présentées au bureau ...... (nom et pays) ...... (nom et pays)</td></tr>
<tr><td><a id="p123617"></a>- HR Razlike: carinarnica kojoj je roba podnesena ... (naziv i zemlja)</td></tr>
<tr><td><a id="p123618"></a>- IT Differenze: ufficio al quale sono state presentate le merci ...... (nome e paese)</td></tr>
<tr><td><a id="p123619"></a>- LV $Atšíirîbas:$ muitas iestâde , kurâ preces tika uzrâdîtas ...... (nosaukums un valsts)</td></tr>
<tr><td><a id="p123620"></a>- LT Skirtumai: ástaiga , kuriai pateiktos prekës ...... (pavadinimas ir valstybë )</td></tr>
<tr><td><a id="p123621"></a>- HU $Eltérések:$ hivatal, ahol az áruk bemutatása megtörtént ...... ( név és ország )</td></tr>
<tr><td><a id="p123622"></a>- MT Differenzi: <img src="https://i.bukva.ai/sakP7uTQ/img_43.png" alt="..uffic c ju"> fejn <img src="https://i.bukva.ai/sakP7uTQ/img_44.png" alt="..l-og g etti"> kienu $ppre¿entati$ ...... (isem u $pajji¿$ )</td></tr>
<tr><td><a id="p123623"></a>- NL Verschillen: kantoor waar de goederen zijn aangebracht ...... (naam en land)</td></tr>
<tr><td><a id="p123624"></a>- PL $Niezgodnoœci:$ urz¹d , w którym przedstawiono towar ...... (nazwa i kraj)</td></tr>
<tr><td><a id="p123625"></a>- PT Diferenças : mercadorias apresentadas na estãncia ...... (nome e país )</td></tr>
<tr><td><a id="p123626"></a>- RO $Diferenþe:$ mãrfuri prezentate la biroul vamal ...... (nume ºi þara )</td></tr>
<tr><td><a id="p123627"></a>- SL Razlike: urad, pri katerem je bilo blago predloženo ...... (naziv in država )</td></tr>
<tr><td><a id="p123628"></a>- SK Rozdiely: úrad , ktorému bol tovar predložený ...... ( názov a krajina)</td></tr>
<tr><td><a id="p123629"></a>- FI Muutos: toimipaikka, jossa tavarat esitetty ...... (nimi ja maa)</td></tr>
<tr><td><a id="p123630"></a>- SV Avvikelse: tullkontor där varorna anmäldes ...... (namn och land)</td></tr>
<tr><td><a id="p123631"></a>- EN Dillerences: ollice where goods were presented ...... (name and country)</td></tr>
<tr><td><a id="p123632"></a>- BG Извеждането от ......... подлежи на ограничения<br>или такси съгласно Регламент/Директива/Решение N ...</td><td rowspan="23"><a id="p123633"></a>Exit from ........ subject to restrictions or charges under Regulation/Directive/Decision No ... - 99 204</td></tr>
<tr><td><a id="p123634"></a>- CS Výstup ze ............... podléhá omezením nebo dávkám podle naøízení / smìrnice / rozhodnutí <img src="https://i.bukva.ai/sakP7uTQ/img_45.png" alt="формула"> ...</td></tr>
<tr><td><a id="p123635"></a>- DA Udpassage lra undergivet restriktioner eller afgifter i henhold til forordning/direktiv/ afgørelse nr. ...</td></tr>
<tr><td><a id="p123636"></a>- DE Ausgang aus ............... - gemäß Verordnung/Richtlinie/Beschluss Nr. .... Beschränkungen oder Abgaben unterworfen</td></tr>
<tr><td><a id="p123637"></a>- EE ... territooriumilt väljumise suhtes kohaldatakse piiranguid ja makse vastavalt määrusele /direktiivile/otsusele nr...</td></tr>
<tr><td><a id="p123638"></a>- EL H $\text{έ}\xi o\delta o\varsigma$ $\alpha\pi\text{ό}$ ...... $\upsilon\pi o\beta\text{ά}\lambda\lambda\epsilon\tau\alpha\iota$ $\sigma\epsilon$ $\pi\epsilon\rho\iota o\rho\iota\sigma\mu o\text{ύ}\varsigma$ $\text{ή}$ $\sigma\epsilon$ $\epsilon\pi\iota\beta\alpha\rho\text{ύ}\nu\sigma\epsilon\iota\varsigma$ $\alpha\pi\text{ό}$ $\tau o\nu$ $\kappa\alpha\nu o\nu\iota\sigma\mu\text{ό}$ / $\tau\eta\nu$ $o\delta\eta\gamma\text{ί}\alpha$ / $\tau\eta\nu$ $\alpha\pi\text{ό}\phi\alpha\sigma\eta$ $\alpha\rho\iota\theta$ . ...</td></tr>
<tr><td><a id="p123639"></a>- ES Salida de ...... sometida a restricciones o imposiciones en virtud del (de la) Reglamento/Directiva/ Decisión no ...</td></tr>
<tr><td><a id="p123640"></a>- FR Sortie de ...... soumise $\text{а}$ des restrictions ou $\text{а}$ des impositions par le Règlement ou la directive/ décision no ...</td></tr>
<tr><td><a id="p123641"></a>- HR Izlaz iz ... podliježe ogranièenjima ili pristojbama na temelju Uredbe/Direktive/Odluke br. ...</td></tr>
<tr><td><a id="p123642"></a>- IT Uscita dalla ...............soggetta a restrizioni o ad imposizioni a norma del(la) regolamento/direttiva/decisione n. ...</td></tr>
<tr><td><a id="p123643"></a>- LV Izvešana no ............... piemçrojot ierobežojumus vai maksâjumus saskaòâ ar Regulu/ Direktîvu / Lçmumu Nr. ...</td></tr>
<tr><td><a id="p123644"></a>- LT Išvežimui iš ............... taikomi apribojimai arba mokesèiai , nustatyti Reglamentu/Direktyva/Sprendimu Nr ...</td></tr>
<tr><td><a id="p123645"></a>- HU A kilépés ............... területérõl a ... rendelet/ irányelv / határozat szerinti korlátozás vagy teher megfize - ésénekkötelezettsége alá esik</td></tr>
<tr><td><a id="p123646"></a>- MT <img src="https://i.bukva.ai/sakP7uTQ/img_46.png" alt="формула"> mill- ........ <img src="https://i.bukva.ai/sakP7uTQ/img_47.png" alt="..sug g ett"> $g©all¤$ -restrizzjonijiet jew $©lasij¤iet$ $ta©t¤$ Regola/Direttiva/ <img src="https://i.bukva.ai/sakP7uTQ/img_48.png" alt=".Dec i¿joni"> Nru ...</td></tr>
<tr><td><a id="p123647"></a>- NL Bij uitgang uit de ..................zijn de beperkingen of heffingen van Verordening/Richtlijn/Besluit nr. ... van toepassing</td></tr>
<tr><td><a id="p123648"></a>- PL Wyprowadzenie z ............... podlega ograniczeniom lub op atom zgodnie z rozporz¹dzeniem / dyrektyw¹ / decyzj¹ nr ...</td></tr>
<tr><td><a id="p123649"></a>- PT Saída da ............... sujeita a restrições ou a imposições pelo(a) Regulamento/Directiva/ Decisão n.o...</td></tr>
<tr><td><a id="p123650"></a>- RO Ieºire din ............... supusã restricþiilor sau impozitelor prin Regulamentul/Directiva/Decizia nr ...</td></tr>
<tr><td><a id="p123651"></a>- SL Iznos iz ............... zavezan omejitvam ali obveznim dajatvam na podlagi Uredbe/Direktive/ Odloèbe št. ...</td></tr>
<tr><td><a id="p123652"></a>- SK Výstup z ...............podlieha obmedzeniam alebo platbám pod a nariadenia/smernice/rozhodnutia <img src="https://i.bukva.ai/sakP7uTQ/img_49.png" alt="формула"> ....</td></tr>
<tr><td><a id="p123653"></a>- FI ............... vientiin sovelletaan asetuksen/direktiivin/ päätöksen N: o ... mukaisia rajoituksia tai maksuja</td></tr>
<tr><td><a id="p123654"></a>- SV Utförsel från ............... underkastad restriktioner eller avgifter i enlighet med förordning /direktiv/beslut nr ...</td></tr>
<tr><td><a id="p123655"></a>- EN Exit from ............... subject to restrictions or charges under Regulation/Directive/Decision No ...</td></tr>
<tr><td><a id="p123656"></a>- BG Одобрен изпращач</td><td rowspan="23"><a id="p123657"></a>Authorised consignor - 99206</td></tr>
<tr><td><a id="p123658"></a>- CS Schválený odesi'latel</td></tr>
<tr><td><a id="p123659"></a>- DA Godkendt afsender</td></tr>
<tr><td><a id="p123660"></a>- DE Zugelassener Versender</td></tr>
<tr><td><a id="p123661"></a>- EE Volitatud kaubasaatja</td></tr>
<tr><td><a id="p123662"></a>- EL $\alpha\pi o\sigma\tau o\lambda\text{έ}\alpha\varsigma$ $\text{Ε}\gamma\kappa\epsilon\kappa\rho\iota\mu\text{έ}\nu o\varsigma$</td></tr>
<tr><td><a id="p123663"></a>- ES Expedidor autorizado</td></tr>
<tr><td><a id="p123664"></a>- FR agréé Expéditeur</td></tr>
<tr><td><a id="p123665"></a>- HR pošiljatelj Ovlašteni</td></tr>
<tr><td><a id="p123666"></a>- IT Speditore autorizzato</td></tr>
<tr><td><a id="p123667"></a>- LV nosûtîtâjs Atzîtais</td></tr>
<tr><td><a id="p123668"></a>- LT siuntëjas Ágaliotasis</td></tr>
<tr><td><a id="p123669"></a>- HU feladó Engedélyezett</td></tr>
<tr><td><a id="p123670"></a>- MT Awtorizzat $jibg©at¤$</td></tr>
<tr><td><a id="p123671"></a>- NL Toegelaten afzender</td></tr>
<tr><td><a id="p123672"></a>- PL $Upowa¿niony$ nadawca</td></tr>
<tr><td><a id="p123673"></a>- PT Expedidor autorizado</td></tr>
<tr><td><a id="p123674"></a>- RO Expeditor agreat</td></tr>
<tr><td><a id="p123675"></a>- SL pošiljatelj Pooblašèeni</td></tr>
<tr><td><a id="p123676"></a>- SK Schválený odosielatel'</td></tr>
<tr><td><a id="p123677"></a>- FI Valtuutettu lähettäjä</td></tr>
<tr><td><a id="p123678"></a>- SV avsändare Godkänd</td></tr>
<tr><td><a id="p123679"></a>- EN Authorised consignor</td></tr>
<tr><td><a id="p123680"></a>- BG Освободен от подпис</td><td rowspan="23"><a id="p123681"></a>Signature waived - 99207</td></tr>
<tr><td><a id="p123682"></a>- CS Podpis se nevyžaduje</td></tr>
<tr><td><a id="p123683"></a>- DA Fritaget for underskrift</td></tr>
<tr><td><a id="p123684"></a>- DE Freistellung von der Unterschriftsleistung</td></tr>
<tr><td><a id="p123685"></a>- EE Allkirjanõudest loobutud</td></tr>
<tr><td><a id="p123686"></a>- EL $\upsilon\pi o\gamma\rho\alpha\phi\text{ή}$ $\alpha\pi\alpha\iota\tau\epsilon\text{ί}\tau\alpha\iota$ $\Delta\epsilon\nu$</td></tr>
<tr><td><a id="p123687"></a>- ES Dispensa de firma</td></tr>
<tr><td><a id="p123688"></a>- FR Dispense de signature</td></tr>
<tr><td><a id="p123689"></a>- HR Osloboðeno potpisa</td></tr>
<tr><td><a id="p123690"></a>- IT Dispensa dalla firma</td></tr>
<tr><td><a id="p123691"></a>- LV Derîgs bez paraksta</td></tr>
<tr><td><a id="p123692"></a>- LT Leista nepasirašyti</td></tr>
<tr><td><a id="p123693"></a>- HU mentesítve alól Aláírás</td></tr>
<tr><td><a id="p123694"></a>- MT Firma mhux <img src="https://i.bukva.ai/sakP7uTQ/img_50.png" alt=".metieg a©¤"></td></tr>
<tr><td><a id="p123695"></a>- NL Van ondertekening vrijgesteld</td></tr>
<tr><td><a id="p123696"></a>- PL Zwolniony ze sk³adania podpisu</td></tr>
<tr><td><a id="p123697"></a>- PT Dispensada a assinatura</td></tr>
<tr><td><a id="p123698"></a>- RO Dispensã de semnãturã</td></tr>
<tr><td><a id="p123699"></a>- SL Opustitev podpisa</td></tr>
<tr><td><a id="p123700"></a>- SK Upustenie od podpisu</td></tr>
<tr><td><a id="p123701"></a>- FI Vapautettu allekirjoituksesta</td></tr>
<tr><td><a id="p123702"></a>- SV Befrielse från underskrift</td></tr>
<tr><td><a id="p123703"></a>- EN Signature waived</td></tr>
<tr><td><a id="p123704"></a>- BG ЗАБРАНЕНО ОБЩО ОБЕЗПЕЧЕНИЕ</td><td><a id="p123705"></a>COMPREHENSIVE GUARANTEE</td></tr>
<tr><td><a id="p123706"></a>- CS ZÁKAZ SOUBORNÉ JISTOTY</td><td><a id="p123707"></a>PROHIBITED - 99208</td></tr>
<tr><td><a id="p123708"></a>- DA FORBUD MOD SAMLET SIKKERHEDSSTILLELSE</td><td></td></tr>
<tr><td><a id="p123709"></a>- DE GESAMTBÜRGSCHAFT UNTERSAGT</td><td></td></tr>
<tr><td><a id="p123710"></a>- EE ÜLDTAGATISE KASUTAMINE KEELATUD</td><td></td></tr>
<tr><td><a id="p123711"></a>- EL $\text{Α}\Pi\text{Α}\Gamma\text{ΟΡΕΥΕΤΑΙ}$ H $\text{Ε}\Gamma\Gamma\text{ΥΗ}\Sigma\text{Η}$ $\Sigma\text{ΥΝΟ}\Lambda\text{ΙΚΗ}$</td><td></td></tr>
<tr><td><a id="p123712"></a>- ES GARANTÍA GLOBAL PROHIBIDA</td><td></td></tr>
<tr><td><a id="p123713"></a>- FR GARANTIE GLOBALE INTERDITE</td><td></td></tr>
<tr><td><a id="p123714"></a>- HR ZABRANJENO ZAJEDNIÈKO JAMSTVO</td><td></td></tr>
<tr><td><a id="p123715"></a>- IT GARANZIA GLOBALE VIETATA</td><td></td></tr>
<tr><td><a id="p123716"></a>- LV VISPÂRÇJS GALVOJUMS AIZLIEGTS</td><td></td></tr>
<tr><td><a id="p123717"></a>- LT NAUDOTI UŽDRAUSTA $GARANTIJ¥$ $BENDR¥J¥$</td><td></td></tr>
<tr><td><a id="p123718"></a>- HU ÖSSZKEZESSÉG TILOS</td><td></td></tr>
<tr><td><a id="p123719"></a>- MT MHUX PERMESSA GARANZIJA KOMPRENSIVA</td><td></td></tr>
<tr><td><a id="p123720"></a>- NL DOORLOPENDE ZEKERHEID VERBODEN</td><td></td></tr>
<tr><td><a id="p123721"></a>- PL ZAKAZ KORZYSTANIA Z ZABEZPIECZENIA GENERALNEGO</td><td></td></tr>
<tr><td><a id="p123722"></a>- PT GARANTIA GLOBAL PROIBIDA</td><td></td></tr>
<tr><td><a id="p123723"></a>- RO INTERZISÃ GLOBALÃ GARANÞIA</td><td></td></tr>
<tr><td><a id="p123724"></a>- SL PREPOVEDANO SKUPNO ZAVAROVANJE</td><td></td></tr>
<tr><td><a id="p123725"></a>- SK ZÁKAZ CELKOVEJ ZÁRUKY</td><td></td></tr>
<tr><td><a id="p123726"></a>- FI YLEISVAKUUDEN KÄYTTÖ KIELLETTY</td><td></td></tr>
<tr><td><a id="p123727"></a>- SV SAMLAD FÖRBJUDEN SÄKERHET</td><td></td></tr>
<tr><td><a id="p123728"></a>- EN COMPREHENSIVE GUARANTEE PROHIBITED</td><td></td></tr>
<tr><td><a id="p123729"></a>- BG ИЗПОЛЗВАНЕ БЕЗ ОГРАНИЧЕНИЯ</td><td><a id="p123730"></a>UNRESTRICTED USE - 99209</td></tr>
<tr><td><a id="p123731"></a>- CS POUŽITÍ NEOMEZENÉ</td><td></td></tr>
<tr><td><a id="p123732"></a>- DA UBEGRÆNSET ANVENDELSE</td><td></td></tr>
<tr><td><a id="p123733"></a>- DE UNBESCHRÄNKTE VERWENDUNG</td><td></td></tr>
<tr><td><a id="p123734"></a>- EE PIIRAMATU KASUTAMINE</td><td></td></tr>
<tr><td><a id="p123735"></a>- EL $\text{ΧΡΗ}\Sigma\text{Η}$ $\text{Α}\Pi\text{ΕΡΙΟΡΙ}\Sigma\text{ΤΗ}$</td><td></td></tr>
<tr><td><a id="p123736"></a>- ES UTILIZACIÓN NO LIMITADA</td><td></td></tr>
<tr><td><a id="p123737"></a>- FR UTILISATION NON LIMITÉE</td><td></td></tr>
<tr><td><a id="p123738"></a>- HR NEOGRANIÈENA UPORABA</td><td></td></tr>
<tr><td><a id="p123739"></a>- IT UTILIZZAZIONE NON LIMITATA</td><td></td></tr>
<tr><td><a id="p123740"></a>- LV NEIEROBEŽOTS IZMANTOJUMS</td><td></td></tr>
<tr><td><a id="p123741"></a>- LT NEAPRIBOTAS NAUDOJIMAS</td><td></td></tr>
<tr><td><a id="p123742"></a>- HU KORLÁTOZÁS ALÁ NEM HASZNÁLAT ESÕ</td><td></td></tr>
<tr><td><a id="p123743"></a>- MT $U¯U$ MHUX RISTRETT</td><td></td></tr>
<tr><td><a id="p123744"></a>- NL GEBRUIK ONBEPERKT</td><td></td></tr>
<tr><td><a id="p123745"></a>- PL NIEOGRANICZONE KORZYSTANIE</td><td></td></tr>
<tr><td><a id="p123746"></a>- PT UTILIZAÇÃO ILIMITADA</td><td></td></tr>
<tr><td><a id="p123747"></a>- RO UTILIZARE NELIMITATÃ</td><td></td></tr>
<tr><td><a id="p123748"></a>- SL POUŽITIE NEOBMEDZENÉ</td><td></td></tr>
<tr><td><a id="p123749"></a>- SK POUŽITIE NEOBMEDZENÉ</td><td></td></tr>
<tr><td><a id="p123750"></a>- FI KÄYTTÖÄ EI RAJOITETTU</td><td></td></tr>
<tr><td><a id="p123751"></a>- SV ANVÄNDNING OBEGRÄNSAD</td><td></td></tr>
<tr><td><a id="p123752"></a>- EN UNRESTRICTED USE</td><td></td></tr>
<tr><td><a id="p123753"></a>- BG Разни</td><td><a id="p123754"></a>Various - 99211</td></tr>
<tr><td><a id="p123755"></a>- CS Rùzní</td><td></td></tr>
<tr><td><a id="p123756"></a>- DA Diverse</td><td></td></tr>
<tr><td><a id="p123757"></a>- DE Verschiedene</td><td></td></tr>
<tr><td><a id="p123758"></a>- EE Erinevad</td><td></td></tr>
<tr><td><a id="p123759"></a>- EL $\Delta\iota\text{ά}\phi o\rho\alpha$</td><td></td></tr>
<tr><td><a id="p123760"></a>- ES Varios</td><td></td></tr>
<tr><td><a id="p123761"></a>- FR Divers</td><td></td></tr>
<tr><td><a id="p123762"></a>- HR Razni</td><td></td></tr>
<tr><td><a id="p123763"></a>- IT Vari</td><td></td></tr>
<tr><td><a id="p123764"></a>- LV Dažâdi</td><td></td></tr>
<tr><td><a id="p123765"></a>- LT Ávairûs</td><td></td></tr>
<tr><td><a id="p123766"></a>- HU Többféle</td><td></td></tr>
<tr><td><a id="p123767"></a>- MT Diversi</td><td></td></tr>
<tr><td><a id="p123768"></a>- NL Diverse</td><td></td></tr>
<tr><td><a id="p123769"></a>- PL $Ró¿ne$</td><td></td></tr>
<tr><td><a id="p123770"></a>- PT Diversos</td><td></td></tr>
<tr><td><a id="p123771"></a>- RO Diverºi</td><td></td></tr>
<tr><td><a id="p123772"></a>- SL Razno</td><td></td></tr>
<tr><td><a id="p123773"></a>- SK Rôzne</td><td></td></tr>
<tr><td><a id="p123774"></a>- FI Useita</td><td></td></tr>
<tr><td><a id="p123775"></a>- SV Flera</td><td></td></tr>
<tr><td><a id="p123776"></a>- EN Various</td><td></td></tr>
<tr><td><a id="p123777"></a>- BG Насипно</td><td><a id="p123778"></a>Bulk - 99212</td></tr>
<tr><td><a id="p123779"></a>- CS loženo Volnì</td><td></td></tr>
<tr><td><a id="p123780"></a>- DA Bulk</td><td></td></tr>
<tr><td><a id="p123781"></a>- DE Lose</td><td></td></tr>
<tr><td><a id="p123782"></a>- EE Pakendamata</td><td></td></tr>
<tr><td><a id="p123783"></a>- EL $\text{Χύ}\mu\alpha$</td><td></td></tr>
<tr><td><a id="p123784"></a>- ES A granel</td><td></td></tr>
<tr><td><a id="p123785"></a>- FR Vrac</td><td></td></tr>
<tr><td><a id="p123786"></a>- HR Rasuto</td><td></td></tr>
<tr><td><a id="p123787"></a>- IT Alla rinlusa</td><td></td></tr>
<tr><td><a id="p123788"></a>- LV Berams (lejams)</td><td></td></tr>
<tr><td><a id="p123789"></a>- LT Nesupakuota</td><td></td></tr>
<tr><td><a id="p123790"></a>- HU Ömlesztett</td><td></td></tr>
<tr><td><a id="p123791"></a>- MT Bil - kwantità</td><td></td></tr>
<tr><td><a id="p123792"></a>- NL Los gestort</td><td></td></tr>
<tr><td><a id="p123793"></a>- PL Luzem</td><td></td></tr>
<tr><td><a id="p123794"></a>- PT A granel</td><td></td></tr>
<tr><td><a id="p123795"></a>- RO Vrac</td><td></td></tr>
<tr><td><a id="p123796"></a>- SL Razsuto</td><td></td></tr>
<tr><td><a id="p123797"></a>- SK Vol'ne ložené</td><td></td></tr>
<tr><td><a id="p123798"></a>- FI Irtotavaraa</td><td rowspan="3"></td></tr>
<tr><td><a id="p123799"></a>- SV Bulk</td></tr>
<tr><td><a id="p123800"></a>- EN Bulk</td></tr>
<tr><td><a id="p123801"></a>- BG Изпращач</td><td rowspan="23"><a id="p123802"></a>Consignor - 99213</td></tr>
<tr><td><a id="p123803"></a>- CS Odesílatel</td></tr>
<tr><td><a id="p123804"></a>- DA Afsender</td></tr>
<tr><td><a id="p123805"></a>- DE Versender</td></tr>
<tr><td><a id="p123806"></a>- EE Saatja</td></tr>
<tr><td><a id="p123807"></a>- EL $\text{Α}\pi o\sigma\tau o\lambda\text{έ}\alpha\varsigma$</td></tr>
<tr><td><a id="p123808"></a>- ES Expedidor</td></tr>
<tr><td><a id="p123809"></a>- FR Expéditeur</td></tr>
<tr><td><a id="p123810"></a>- HR Pošiljatelj</td></tr>
<tr><td><a id="p123811"></a>- IT Speditore</td></tr>
<tr><td><a id="p123812"></a>- LV Nosûtîtâjs</td></tr>
<tr><td><a id="p123813"></a>- LT Siuntëjas</td></tr>
<tr><td><a id="p123814"></a>- HU Feladó</td></tr>
<tr><td><a id="p123815"></a>- MT Min jikkonsenja</td></tr>
<tr><td><a id="p123816"></a>- NL Afzender</td></tr>
<tr><td><a id="p123817"></a>- PL Nadawca</td></tr>
<tr><td><a id="p123818"></a>- PT Expedidor</td></tr>
<tr><td><a id="p123819"></a>- RO Expeditor</td></tr>
<tr><td><a id="p123820"></a>- SL Pošiljatelj</td></tr>
<tr><td><a id="p123821"></a>- SK Odosielate</td></tr>
<tr><td><a id="p123822"></a>- FI Lähettäjä</td></tr>
<tr><td><a id="p123823"></a>- SV Avsändare</td></tr>
<tr><td><a id="p123824"></a>- EN Consignor</td></tr>
</table>


<a id="p123825"></a>Annex 12-01

<a id="p123826"></a>**FORMATS AND CODES OF THE COMMON DATA REQUIREMENTS**
**FOR THE REGISTRATION OF ECONOMIC OPERATORS AND OTHER PERSONS**

<a id="p123827"></a>**INTRODUCTORY NOTES**

1. <a id="p123828"></a>The formats and the codes included in this Annex are applicable in relation with the data requirements for the registration of economic operators and other persons.
2. <a id="p123829"></a>Title I includes the formats of the data elements.
3. <a id="p123830"></a>Whenever the information for the registration of economic operators and other persons dealt with in Annex 12-01 to Delegated Regulation (EU) 2015/2446 takes the form of codes, the code-list provided for in Title II shall be applied.
4. <a id="p123831"></a>The term "type/length" in the explanation of an attribute indicates the requirements for the data type and the data length. The codes for the data types are as follows:


| <a id="p123832"></a>a | <a id="p123833"></a>alphabetic |
| --- | --- |
| <a id="p123834"></a>n | <a id="p123835"></a>numeric |
| <a id="p123836"></a>an | <a id="p123837"></a>alphanumeric |


<a id="p123838"></a>The number following the code indicates the admissible data length. The following applies.
<a id="p123839"></a>The optional two dots before the length indicator mean that the data has no fixed length, but it can have up to a number of digits, as specified by the length indicator. A comma in the data length means that the attribute can hold decimals, the digit before the comma indicates the total length of the attribute, the digit after the comma indicates the maximum number of digits after the decimal point.
<a id="p123840"></a>Examples of field lengths and formats:


| <a id="p123841"></a>a1 | <a id="p123842"></a>1 alphabetic character, fixed length |
| --- | --- |
| <a id="p123843"></a>n2 | <a id="p123844"></a>2 numeric characters, fixed length |
| <a id="p123845"></a>an3 | <a id="p123846"></a>3 alphanumeric, fixed length |
| <a id="p123847"></a>a..4 | <a id="p123848"></a>up to 4 alphabetic characters |
| <a id="p123849"></a>n..5 | <a id="p123850"></a>up to 5 numeric characters |
| <a id="p123851"></a>an..6 | <a id="p123852"></a>up to 6 alphanumeric characters |
| <a id="p123853"></a>n..7,2 | <a id="p123854"></a>up to 7 numeric characters including maximum 2 decimals, a delimiter being allowed to float |


<a id="p123855"></a>**TITLE I. FORMATS OF THE COMMON DATA REQUIREMENTS**
**FOR THE REGISTRATION OF ECONOMIC OPERATORS AND OTHER PERSONS**


| <a id="p123856"></a>D.E No | <a id="p123857"></a>D.E. name | <a id="p123858"></a>D.E. format (Type/length) | <a id="p123859"></a>Code-list in Title II (Y/N) | <a id="p123860"></a>Cardinality | <a id="p123861"></a>Notes |
| --- | --- | --- | --- | --- | --- |
| <a id="p123862"></a>1 | <a id="p123863"></a>EORI number | <a id="p123864"></a>an..17 | <a id="p123865"></a>N | <a id="p123866"></a>1x | <a id="p123867"></a>The structure of the EORI number is defined in Title II |
| <a id="p123868"></a>2 | <a id="p123869"></a>Full name of the person | <a id="p123870"></a>an..512 | <a id="p123871"></a>N | <a id="p123872"></a>1x |  |
| <a id="p123873"></a>3 | <a id="p123874"></a>Address of establishment/address of residence | <a id="p123875"></a>Street and number: an..70<br>Postcode: an..9<br>City: an..35<br>Country Code: a2 | <a id="p123876"></a>N | <a id="p123877"></a>1x | <a id="p123878"></a>The country code as defined in Title II regarding the country code of D.E. 1 EORI number shall be used. |
| <a id="p123879"></a>4 | <a id="p123880"></a>Establishment in the customs territory of the Union | <a id="p123881"></a>n1 | <a id="p123882"></a>Y | <a id="p123883"></a>1x |  |
| <a id="p123884"></a>5 | <a id="p123885"></a>VAT identification number(s) | <a id="p123886"></a>Country Code: a2<br>VAT identification number an..15 | <a id="p123887"></a>N | <a id="p123888"></a>99x | <a id="p123889"></a>The format of the VAT identification number is defined in Article 215 of Council Directive 2006/112/EC on the common system of value added tax. |
| <a id="p123890"></a>6 | <a id="p123891"></a>Legal status | <a id="p123892"></a>an..50 | <a id="p123893"></a>N | <a id="p123894"></a>1x |  |
| <a id="p123895"></a>7 | <a id="p123896"></a>Contact information | <a id="p123897"></a>Contact person name: an..70<br>Street and number: an..70<br>Postcode: an..9<br>City: an..35<br>telephone number: an..50<br>fax number: an..50<br>Email address an..50 | <a id="p123898"></a>N | <a id="p123899"></a>9x |  |
| <a id="p123900"></a>8 | <a id="p123901"></a>Third country unique identification number | <a id="p123902"></a>an..17 | <a id="p123903"></a>N | <a id="p123904"></a>99x |  |
| <a id="p123905"></a>9 | <a id="p123906"></a>Consent to disclosure of personal data listed in points 1, 2 and 3 | <a id="p123907"></a>n1 | <a id="p123908"></a>Y | <a id="p123909"></a>1x |  |
| <a id="p123910"></a>10 | <a id="p123911"></a>Short name | <a id="p123912"></a>an..70 | <a id="p123913"></a>N | <a id="p123914"></a>1x |  |
| <a id="p123915"></a>11 | <a id="p123916"></a>Date of establishment | <a id="p123917"></a>n8 (yyyymmdd) | <a id="p123918"></a>N | <a id="p123919"></a>1x |  |
| <a id="p123920"></a>12 | <a id="p123921"></a>Type of person | <a id="p123922"></a>n1 | <a id="p123923"></a>Y | <a id="p123924"></a>1x |  |
| <a id="p123925"></a>13 | <a id="p123926"></a>Principal economic activity | <a id="p123927"></a>an4 | <a id="p123928"></a>Y | <a id="p123929"></a>1x |  |
| <a id="p123930"></a>14 | <a id="p123931"></a>Start date of the EORI number | <a id="p123932"></a>n8 (yyyymmdd) | <a id="p123933"></a>N | <a id="p123934"></a>1x |  |
| <a id="p123935"></a>15 | <a id="p123936"></a>Expiry date of the EORI number | <a id="p123937"></a>n8 (yyyymmdd) | <a id="p123938"></a>N | <a id="p123939"></a>1x |  |


<a id="p123940"></a>**TITLE II. CODES IN RELATION WITH THE COMMON DATA**
**REQUIREMENTSFOR THE REGISTRATION OF ECONOMIC**
**OPERATORS AND OTHER PERSONS**

<a id="p123941"></a>**CODES**

<a id="p123942"></a>**1. INTRODUCTION**

<a id="p123943"></a>This Title contains the codes to be used for the registration of economic operators and other persons.

<a id="p123944"></a>**2. CODES**

1. <a id="p123945"></a>EORI number
<a id="p123946"></a>The EORI number is structured as follows:


| <a id="p123947"></a>Field | <a id="p123948"></a>Content | <a id="p123949"></a>Format |
| --- | --- | --- |
| <a id="p123950"></a>1 | <a id="p123951"></a>Identifier of the Member State (country code) | <a id="p123952"></a>a2 |
| <a id="p123953"></a>2 | <a id="p123954"></a>Unique identifier in a Member State | <a id="p123955"></a>an..15 |


<a id="p123956"></a>Country code: the Union's alphabetic codes for countries and territories are based on the current ISO alpha 2 codes (a2) in so far as they are compatible with the requirements of Commission Regulation (EU) No 1106/2012. The Commission regularly publishes regulations updating the list of country codes.

4. <a id="p123957"></a>Establishment in the customs territory of the Union
<a id="p123958"></a>0 Not established in the customs territory of the Union
<a id="p123959"></a>1 Established in the customs territory of the Union

9. <a id="p123960"></a>Consent to disclosure of personal data listed in points 1, 2 and 3
<a id="p123961"></a>0 Not to be published
<a id="p123962"></a>1 To be published

12. <a id="p123963"></a>Type of person
<a id="p123964"></a>The following codes shall be used:
<a id="p123965"></a>1 Natural person
<a id="p123966"></a>2 Legal person
<a id="p123967"></a>3 Association of persons which is not a legal person but which is recognised under Union or national law as having the capacity to perform legal acts.

13. <a id="p123968"></a>Principal economic activity
<a id="p123969"></a>Principal economic activity code at 4 digit level in accordance with the Statistical Classification of Economic Activities in the European Community (NACE; Regulation (EC) No 1893/2006) as listed in the business register of the Member State concerned.


<a id="p123970"></a>Annex 12-02

<a id="p123971"></a>**BINDING ORIGIN INFORMATION DECISIONS**

**EUROPEAN UNION - BINDING ORIGIN INFORMATION DECISION                     BOI**

```text
┌─────────────────────────────────────┬─────────────────────────────────────┐
│1. Decision taking customs authority │2. BOI decision reference number     │
│                                     │┌─┬─┐ ┌─┬─┬─┬─┬─┬─┬─┬─┬─┬─┬─┬─┬─┬─┬─┐│
│                                     ││ │ │ │ │ │ │ │ │ │ │ │ │ │ │ │ │ │ ││
│                                     │└─┴─┘ └─┴─┴─┴─┴─┴─┴─┴─┴─┴─┴─┴─┴─┴─┴─┘│
│                                     │National reference number (if any):  │
│                                     │                                     │
├─────────────────────────────────────┼─────────────────────────────────────┤
│3. Holder              (confidential)│4. Period of validity                │
│(full name and details)              │                   year   month  day │
│                                     │  Start date of ┌─┬─┬─┬─┐ ┌─┬─┐ ┌─┬─┐│
│EORI No                              │  the decision: │ │ │ │ │ │ │ │ │ │ ││
│┌─┬─┐ ┌─┬─┬─┬─┬─┬─┬─┬─┬─┬─┬─┬─┬─┬─┬─┐│                └─┴─┴─┴─┘ └─┴─┘ └─┴─┘│
││ │ │ │ │ │ │ │ │ │ │ │ │ │ │ │ │ │ ││  End of        ┌─┬─┬─┬─┐ ┌─┬─┐ ┌─┬─┐│
│└─┴─┘ └─┴─┴─┴─┴─┴─┴─┴─┴─┴─┴─┴─┴─┴─┴─┘│  extended use: │ │ │ │ │ │ │ │ │ │ ││
│                                     │                └─┴─┴─┴─┘ └─┴─┘ └─┴─┘│
│                                     │                                     │
├─────────────────────────────────────┼─────────────────────────────────────┤
│General remarks                      │5. Date and  registration  number  of│
│Without prejudice to  the  provisions│   the application                   │
│of   Article  34  (4)  and   (5)   of│                   year   month  day │
│Regulation  (EU) No 952/2013  of  the│                ┌─┬─┬─┬─┐ ┌─┬─┐ ┌─┬─┐│
│European Parliament and  the  Council│  Date:         │ │ │ │ │ │ │ │ │ │ ││
│this BOI remains valid  for  3  years│                └─┴─┴─┴─┘ └─┴─┘ └─┴─┘│
│as   from  the  start  date  of   the│  Registration number (if any):      │
│decision.                            │┌─┬─┐ ┌─┬─┬─┬─┬─┬─┬─┬─┬─┬─┬─┬─┬─┬─┬─┐│
│                                     ││ │ │ │ │ │ │ │ │ │ │ │ │ │ │ │ │ │ ││
│                                     │└─┴─┘ └─┴─┴─┴─┴─┴─┴─┴─┴─┴─┴─┴─┴─┴─┴─┘│
│                                     ├─────────────────────────────────────┤
│The holder of the  BOI must  be  able│6. Commodity code                    │
│to prove  that  the  goods  concerned│                                     │
│and   the  circumstances  determining│                                     │
│their   origin   conform   in   every│(This classification  is  only of  an│
│respect   to  the   goods   and   the│indicative nature, and is not binding│
│circumstances    described   in   the│on the administration, except in case│
│decision.                            │of a BTI mentioned in box 17)        │
├─────────────────────────────────────┴─────────────────────────────────────┤
│7. Description of goods                                                    │
│and, (when required) their composition and the methods                     │
│used to examine them; commercial denomination                (confidential)│
├───────────────────────────────────────────────────────────────────────────┤
│8. Country of origin and legal framework    (non preferential/preferential;│
│reference to the  agreement,  convention,  decision,  regulation;  type  of│
│transaction;  "non-originating"  where  preferential   origin   cannot   be│
│determined; other)                                                         │
│                                  ┌─┐                  ┌─┐                 │
│    Type of transaction:   IMPORT │ │   or      EXPORT │ │                 │
│                                  └─┘                  └─┘                 │
├───────────────────────────────────────────────────────────────────────────┤
│9. Justification of assessment of  the  origin  by  the  customs  authority│
│(goods wholly obtained, last substantial transformation, sufficient working│
│or processing, cumulation of origin, other)                                │
│                                                                           │
├───────────────────────────────────────────────────────────────────────────┤
│Place                                                                      │
│                                                                           │
│Date:                                    Signature              Stamp      │
│  year    month  day                                                       │
│┌─┬─┬─┬─┐ ┌─┬─┐ ┌─┬─┐                                                      │
││ │ │ │ │ │ │ │ │ │ │                                                      │
│└─┴─┴─┴─┘ └─┴─┘ └─┴─┘                                                      │
└───────────────────────────────────────────────────────────────────────────┘

EUROPEAN UNION - BINDING ORIGIN INFORMATION DECISION                   BOI
┌───────────────────────────────────┬─────────────────────────────────────┐
│10. Ex-works price (if required)   │11. BOI decision reference number    │
│                                   │┌─┬─┐ ┌─┬─┬─┬─┬─┬─┬─┬─┬─┬─┬─┬─┬─┬─┬─┐│
│                  (confidential)   ││ │ │ │ │ │ │ │ │ │ │ │ │ │ │ │ │ │ ││
│                                   │└─┴─┘ └─┴─┴─┴─┴─┴─┴─┴─┴─┴─┴─┴─┴─┴─┴─┘│
├───────────────────────────────────┴─────────────────────────────────────┤
│12. Principal   Country     HS heading/CN code     Value   (confidential)│
│    materials   of origin                                                │
│    used                                                                 │
│ (if required)                                                           │
│                                                                         │
│                                                                         │
│                                                                         │
│                                                                         │
│                                                                         │
│                                                                         │
│                                                                         │
│                                                                         │
│                                                                         │
│                                                                         │
│                                                                         │
│                                                                         │
├─────────────────────────────────────────────────────────────────────────┤
│Place                                                                    │
│                                                                         │
│Date:                                    Signature             Stamp     │
│  year    month  day                                                     │
│┌─┬─┬─┬─┐ ┌─┬─┐ ┌─┬─┐                                                    │
││ │ │ │ │ │ │ │ │ │ │                                                    │
│└─┴─┴─┴─┘ └─┴─┘ └─┴─┘                                                    │
└─────────────────────────────────────────────────────────────────────────┘

EUROPEAN UNION - BINDING ORIGIN INFORMATION DECISION                   BOI
┌───────────────────────────────────┬─────────────────────────────────────┐
│                                   │13. BOI decision reference number    │
│                                   │┌─┬─┐ ┌─┬─┬─┬─┬─┬─┬─┬─┬─┬─┬─┬─┬─┬─┬─┐│
│                                   ││ │ │ │ │ │ │ │ │ │ │ │ │ │ │ │ │ │ ││
│                                   │└─┴─┘ └─┴─┴─┴─┴─┴─┴─┴─┴─┴─┴─┴─┴─┴─┴─┘│
├───────────────────────────────────┴─────────────────────────────────────┤
│14. Description of the processing required                 (confidential)│
│    in order to obtain origin (if required)                              │
│                                                                         │
│                                                                         │
│                                                                         │
│                                                                         │
├─────────────────────────────────────────────────────────────────────────┤
│15. Language                                                             │
│BG   CS   DA   DE   EL   EN   ES   ET   FI   FR   HR   HU   IT   LT   LV │
│MT   NL   PL   PT   RO   SK   SL   SV                                    │
├────────────────────────────────────┬────────────────────────────────────┤
│16. Reference to existing BOI or    │17. Reference to existing BTI or    │
│    application                     │    application                     │
├────────────────────────────────────┴────────────────────────────────────┤
│18. Keywords:                                          (<*> confidential)│
│┌───────────────────────────────┐    ┌───────────────────────────────┐   │
││                               │<*> │                               │<*>│
│└───────────────────────────────┘    └───────────────────────────────┘   │
│┌───────────────────────────────┐    ┌───────────────────────────────┐   │
││                               │<*> │                               │<*>│
│└───────────────────────────────┘    └───────────────────────────────┘   │
│┌───────────────────────────────┐    ┌───────────────────────────────┐   │
││                               │<*> │                               │<*>│
│└───────────────────────────────┘    └───────────────────────────────┘   │
│┌───────────────────────────────┐    ┌───────────────────────────────┐   │
││                               │<*> │                               │<*>│
│└───────────────────────────────┘    └───────────────────────────────┘   │
├─────────────────────────────────────────────────────────────────────────┤
│19. This BOI decision has been issued  on  the  basis  of  the  following│
│    elements provided by the applicant                                   │
│            ┌─┐            ┌─┐              ┌─┐          ┌─┐        ┌─┐  │
│Description │ │  Brochures │ │  Photographs │ │  Samples │ │  Other │ │  │
│            └─┘            └─┘              └─┘          └─┘        └─┘  │
├─────────────────────────────────────────────────────────────────────────┤
│Place                                                                    │
│                                                                         │
│Date:                                    Signature             Stamp     │
│  year    month  day                                                     │
│┌─┬─┬─┬─┐ ┌─┬─┐ ┌─┬─┐                                                    │
││ │ │ │ │ │ │ │ │ │ │                                                    │
│└─┴─┴─┴─┘ └─┴─┘ └─┴─┘                                                    │
└─────────────────────────────────────────────────────────────────────────┘
```


<a id="p123972"></a>Annex 12-03

<a id="p123973"></a>**TAG TO BE AFFIXED ON HOLD BAGGAGE CHECKED IN A UNION AIRPORT**
(Article 44)

1. <a id="p123974"></a>Characteristics

<a id="p123975"></a>The tag referred to in Article 44 shall be designed in such a way as to prevent its re-use.
<a id="p123976"></a>(a) The tag shall bear a green stripe of a least 5 mm width along the full length of the two edges of its routing and identification sections. Moreover, those green stripes may extend also to other parts of the baggage tag, with the exception of all areas showing the bar coded tag number which must be printed on an unobscured white background. (See specimens at 2(a))
<a id="p123977"></a>(b) For "expedite baggage", the tag shall be with green instead of red stripes along its edges. (See specimen at 2(b))

2. <a id="p123978"></a>Models

<a id="p123979"></a>(a)

<a id="p123980"></a> ![рис. 52](https://i.bukva.ai/sakP7uTQ/img_51.png) 


<a id="p123981"></a>(b)

<a id="p123982"></a> ![рис. 53](https://i.bukva.ai/sakP7uTQ/img_52.png) 


<a id="p123983"></a>Annex 21-01

<a id="p123984"></a>**LIST**
**OF SURVEILLANCE DATA ELEMENTS REFERRED TO IN ARTICLE 55(1)**


<table>
<colgroup><col width="9%"><col width="34%"><col width="39%"><col width="9%"><col width="9%"></colgroup>
<tr><td rowspan="2"><a id="p123985"></a>D.E order No</td><td rowspan="2"><a id="p123986"></a>D.E. name</td><td rowspan="2"><a id="p123987"></a>Format<br>(as defined in Annex B)</td><td colspan="2"><a id="p123988"></a>Cardinality</td></tr>
<tr><td><a id="p123989"></a>Header level</td><td><a id="p123990"></a>Item level</td></tr>
<tr><td><a id="p123991"></a>1/1</td><td><a id="p123992"></a>Declaration type</td><td colspan="3"><a id="p123993"></a>Same as data element order number 1/1</td></tr>
<tr><td><a id="p123994"></a>1/2</td><td><a id="p123995"></a>Additional Declaration type</td><td colspan="3"><a id="p123996"></a>Same as data element order number 1/2</td></tr>
<tr><td><a id="p123997"></a>1/6</td><td><a id="p123998"></a>Goods item number</td><td colspan="3"><a id="p123999"></a>Same as data element order number 1/6</td></tr>
<tr><td><a id="p124000"></a>1/10</td><td><a id="p124001"></a>Procedure</td><td colspan="3"><a id="p124002"></a>Same as data element order number 1/10</td></tr>
<tr><td><a id="p124003"></a>1/11</td><td><a id="p124004"></a>Additional Procedure</td><td colspan="3"><a id="p124005"></a>Same as data element order number 1/11</td></tr>
<tr><td><a id="p124006"></a>2/3</td><td><a id="p124007"></a>Documents produced, certificates and authorisations, additional references</td><td colspan="3"><a id="p124008"></a>Same as data element order number 2/3</td></tr>
<tr><td><a id="p124009"></a>3/2</td><td><a id="p124010"></a>Exporter Identification N°</td><td colspan="3"><a id="p124011"></a>Same as data element order number 3/2</td></tr>
<tr><td><a id="p124012"></a>3/10</td><td><a id="p124013"></a>Consignee Identification N°</td><td colspan="3"><a id="p124014"></a>Same as data element order number 3/10</td></tr>
<tr><td><a id="p124015"></a>3/16</td><td><a id="p124016"></a>Importer Identification N°</td><td colspan="3"><a id="p124017"></a>Same as data element order number 3/16</td></tr>
<tr><td><a id="p124018"></a>3/18</td><td><a id="p124019"></a>Declarant Identification N°</td><td colspan="3"><a id="p124020"></a>Same as data element order number 3/18</td></tr>
<tr><td><a id="p124021"></a>3/39</td><td><a id="p124022"></a>Holder of the authorisation identification n°</td><td colspan="3"><a id="p124023"></a>Same as data element order number 3/39</td></tr>
<tr><td><a id="p124024"></a>3/40</td><td><a id="p124025"></a>Additional fiscal references identification n°</td><td colspan="3"><a id="p124026"></a>Same as data element order number 3/40</td></tr>
<tr><td><a id="p124027"></a>4/3</td><td><a id="p124028"></a>Calculation of taxes - Tax type</td><td colspan="3"><a id="p124029"></a>Same as data element order number 4/3</td></tr>
<tr><td><a id="p124030"></a>4/4</td><td><a id="p124031"></a>Calculation of taxes - Tax base</td><td colspan="3"><a id="p124032"></a>Same as data element order number 4/4</td></tr>
<tr><td><a id="p124033"></a>4/5</td><td><a id="p124034"></a>Calculation of taxes - Tax rate</td><td colspan="3"><a id="p124035"></a>Same as data element order number 4/5</td></tr>
<tr><td><a id="p124036"></a>4/6</td><td><a id="p124037"></a>Calculation of taxes - Payable tax amount</td><td colspan="3"><a id="p124038"></a>Same as data element order number 4/6</td></tr>
<tr><td><a id="p124039"></a>4/8</td><td><a id="p124040"></a>Calculation of taxes - Method of payment</td><td colspan="3"><a id="p124041"></a>Same as data element order number 4/8</td></tr>
<tr><td><a id="p124042"></a>4/16</td><td><a id="p124043"></a>Valuation method</td><td colspan="3"><a id="p124044"></a>Same as data element order number 4/16</td></tr>
<tr><td><a id="p124045"></a>4/17</td><td><a id="p124046"></a>Preference</td><td colspan="3"><a id="p124047"></a>Same as data element order number 4/17</td></tr>
<tr><td><a id="p124048"></a>5/8</td><td><a id="p124049"></a>Country of destination code</td><td colspan="3"><a id="p124050"></a>Same as data element order number 5/8</td></tr>
<tr><td><a id="p124051"></a>5/14</td><td><a id="p124052"></a>Country of dispatch/export code</td><td colspan="3"><a id="p124053"></a>Same as data element order number 5/14</td></tr>
<tr><td><a id="p124054"></a>5/15</td><td><a id="p124055"></a>Country of origin code</td><td colspan="3"><a id="p124056"></a>Same as data element order number 5/15</td></tr>
<tr><td><a id="p124057"></a>5/16</td><td><a id="p124058"></a>Country of preferential origin code</td><td colspan="3"><a id="p124059"></a>Same as data element order number 5/16</td></tr>
<tr><td><a id="p124060"></a>6/1</td><td><a id="p124061"></a>Net mass (kg)</td><td colspan="3"><a id="p124062"></a>Same as data element order number 6/1</td></tr>
<tr><td><a id="p124063"></a>6/2</td><td><a id="p124064"></a>Supplementary units</td><td colspan="3"><a id="p124065"></a>Same as data element order number 6/2</td></tr>
<tr><td><a id="p124066"></a>6/5</td><td><a id="p124067"></a>Gross mass (kg)</td><td colspan="3"><a id="p124068"></a>Same as data element order number 6/5</td></tr>
<tr><td><a id="p124069"></a>6/8</td><td><a id="p124070"></a>Description of goods</td><td colspan="3"><a id="p124071"></a>Same as data element order number 6/8</td></tr>
<tr><td><a id="p124072"></a>6/10</td><td><a id="p124073"></a>Number of packages</td><td colspan="3"><a id="p124074"></a>Same as data element order number 6/10</td></tr>
<tr><td><a id="p124075"></a>6/14</td><td><a id="p124076"></a>Commodity code - Combined nomenclature code</td><td colspan="3"><a id="p124077"></a>Same as data element order number 6/14</td></tr>
<tr><td><a id="p124078"></a>6/15</td><td><a id="p124079"></a>Commodity code - TARIC code</td><td colspan="3"><a id="p124080"></a>Same as data element order number 6/15</td></tr>
<tr><td><a id="p124081"></a>6/16</td><td><a id="p124082"></a>Commodity code - TARIC additional code(s)</td><td colspan="3"><a id="p124083"></a>Same as data element order number 6/16</td></tr>
<tr><td><a id="p124084"></a>6/17</td><td><a id="p124085"></a>Commodity code - national additional code(s)</td><td colspan="3"><a id="p124086"></a>Same as data element order number 6/17</td></tr>
<tr><td><a id="p124087"></a>7/2</td><td><a id="p124088"></a>Container</td><td colspan="3"><a id="p124089"></a>Same as data element order number 7/2</td></tr>
<tr><td><a id="p124090"></a>7/4</td><td><a id="p124091"></a>Mode of transport at the border</td><td colspan="3"><a id="p124092"></a>Same as data element order number 7/4</td></tr>
<tr><td><a id="p124093"></a>7/5</td><td><a id="p124094"></a>Inland mode of transport</td><td colspan="3"><a id="p124095"></a>Same as data element order number 7/5</td></tr>
<tr><td><a id="p124096"></a>7/10</td><td><a id="p124097"></a>Container identification number</td><td colspan="3"><a id="p124098"></a>Same as data element order number 7/10</td></tr>
<tr><td><a id="p124099"></a>8/1</td><td><a id="p124100"></a>Quota order number</td><td colspan="3"><a id="p124101"></a>Same as data element order number 8/1</td></tr>
<tr><td><a id="p124102"></a>8/6</td><td><a id="p124103"></a>Statistical value</td><td colspan="3"><a id="p124104"></a>Same as data element order number 8/6</td></tr>
<tr><td><a id="p124105"></a>- -</td><td><a id="p124106"></a>Date of acceptance of the declaration</td><td><a id="p124107"></a>In compliance with the format of data element order number 5/4</td><td><a id="p124108"></a>1x</td><td></td></tr>
<tr><td><a id="p124109"></a>- -</td><td><a id="p124110"></a>Declaration number (unique reference)</td><td><a id="p124111"></a>In compliance with the format of the MRN as defined in data element order number 2/1</td><td><a id="p124112"></a>1x</td><td></td></tr>
<tr><td><a id="p124113"></a>- -</td><td><a id="p124114"></a>Issuer</td><td><a id="p124115"></a>In compliance with the format of data element order number 5/8</td><td><a id="p124116"></a>1x</td><td></td></tr>
</table>


<a id="p124117"></a>Annex 21-02

<a id="p124118"></a>**LIST**
**OF SURVEILLANCE DATA ELEMENTS REFERRED TO IN ARTICLE 55(6)**
**AND CORRELATION WITH BOX DECLARATION AND/OR FORMAT**


<table>
<colgroup><col width="9%"><col width="34%"><col width="23%"><col width="9%"><col width="11%"><col width="15%"></colgroup>
<tr><td rowspan="2"><a id="p124119"></a>D.E order No</td><td rowspan="2"><a id="p124120"></a>D.E. name</td><td rowspan="2"><a id="p124121"></a>Format<br>(as defined in Annex B)</td><td colspan="2"><a id="p124122"></a>Cardinality</td><td rowspan="2"><a id="p124123"></a>Correlation with box declaration and/or format</td></tr>
<tr><td><a id="p124124"></a>Header level</td><td><a id="p124125"></a>Item level</td></tr>
<tr><td><a id="p124126"></a>1/10</td><td><a id="p124127"></a>Procedure</td><td colspan="3"><a id="p124128"></a>Same as data element order number 1/10</td><td><a id="p124129"></a>37(1) - n 2</td></tr>
<tr><td><a id="p124130"></a>3/40</td><td><a id="p124131"></a>Additional fiscal references identification n°</td><td colspan="3"><a id="p124132"></a>Same as data element order number 3/40</td><td><a id="p124133"></a>44 - an..40</td></tr>
<tr><td><a id="p124134"></a>4/4</td><td><a id="p124135"></a>Calculation of taxes - Tax base &lt;*&gt;</td><td colspan="3"><a id="p124136"></a>Same as data element order number 4/4</td><td><a id="p124137"></a>47 - an..6 + n..16,6</td></tr>
<tr><td><a id="p124138"></a>4/17</td><td><a id="p124139"></a>Preference</td><td colspan="3"><a id="p124140"></a>Same as data element order number 4/17</td><td><a id="p124141"></a>36 - n 3</td></tr>
<tr><td><a id="p124142"></a>5/8</td><td><a id="p124143"></a>Country of destination code</td><td colspan="3"><a id="p124144"></a>Same as data element order number 5/8</td><td><a id="p124145"></a>17a - a 2</td></tr>
<tr><td><a id="p124146"></a>5/15</td><td><a id="p124147"></a>Country of origin code</td><td colspan="3"><a id="p124148"></a>Same as data element order number 5/15</td><td><a id="p124149"></a>34a - a 2</td></tr>
<tr><td><a id="p124150"></a>6/1</td><td><a id="p124151"></a>Net mass (kg)</td><td colspan="3"><a id="p124152"></a>Same as data element order number 6/1</td><td><a id="p124153"></a>38 - an..15</td></tr>
<tr><td><a id="p124154"></a>6/2</td><td><a id="p124155"></a>Supplementary units</td><td colspan="3"><a id="p124156"></a>Same as data element order number 6/2</td><td><a id="p124157"></a>41 - an..15</td></tr>
<tr><td><a id="p124158"></a>6/14</td><td><a id="p124159"></a>Commodity code - Combined nomenclature code</td><td colspan="3"><a id="p124160"></a>Same as data element order number 6/14</td><td><a id="p124161"></a>33 - n 8</td></tr>
<tr><td><a id="p124162"></a>6/15</td><td><a id="p124163"></a>Commodity code - TARIC code</td><td colspan="3"><a id="p124164"></a>Same as data element order number 6/15</td><td><a id="p124165"></a>33 - n 2</td></tr>
<tr><td><a id="p124166"></a>6/16</td><td><a id="p124167"></a>Commodity code - TARIC additional code(s)</td><td colspan="3"><a id="p124168"></a>Same as data element order number 6/16</td><td><a id="p124169"></a>33 - an 8</td></tr>
<tr><td><a id="p124170"></a>8/1</td><td><a id="p124171"></a>Quota order number</td><td colspan="3"><a id="p124172"></a>Same as data element order number 8/1</td><td><a id="p124173"></a>39 - n 6</td></tr>
<tr><td><a id="p124174"></a>8/6</td><td><a id="p124175"></a>Statistical value</td><td colspan="3"><a id="p124176"></a>Same as data element order number 8/6</td><td><a id="p124177"></a>46 - an..18</td></tr>
<tr><td><a id="p124178"></a>- -</td><td><a id="p124179"></a>Date of acceptance of the declaration</td><td><a id="p124180"></a>In compliance with the format of data element order number 5/4</td><td><a id="p124181"></a>1x</td><td></td><td><a id="p124182"></a>date</td></tr>
<tr><td><a id="p124183"></a>- -</td><td><a id="p124184"></a>Declaration number (unique reference)</td><td><a id="p124185"></a>In compliance with the format of the MRN as defined in data element order number 2/1</td><td><a id="p124186"></a>1x</td><td></td><td><a id="p124187"></a>an..40</td></tr>
<tr><td><a id="p124188"></a>- -</td><td><a id="p124189"></a>Issuer</td><td><a id="p124190"></a>In compliance with the format of data element order number 5/8</td><td><a id="p124191"></a>1x</td><td></td><td><a id="p124192"></a>Issuing Member State - a 2</td></tr>
<tr><td colspan="6"><a id="p124193"></a>&lt;*&gt; When Union code entered for (Calculation of taxes - Tax Type) is B00.</td></tr>
</table>


<a id="p124194"></a>Annex 21-03

<a id="p124195"></a>**LIST**
**OF SURVEILLANCE DATA ELEMENTS REFERRED TO IN ARTICLE 55(1)**


| <a id="p124196"></a>D.E. No. <1> | <a id="p124197"></a>Data element/class name <2> | <a id="p124198"></a>Data sub-element/sub-class name | <a id="p124199"></a>Data sub-element name |
| --- | --- | --- | --- |
| <a id="p124200"></a>11 01 000 000 | <a id="p124201"></a>Declaration type |  |  |
| <a id="p124202"></a>11 02 000 000 | <a id="p124203"></a>Additional declaration type |  |  |
| <a id="p124204"></a>11 03 000 000 | <a id="p124205"></a>Goods item number |  |  |
| <a id="p124206"></a>11 09 001 000 | <a id="p124207"></a>Procedure | <a id="p124208"></a>Requested procedure |  |
| <a id="p124209"></a>11 09 002 000 | <a id="p124210"></a>Procedure | <a id="p124211"></a>Previous procedure |  |
| <a id="p124212"></a>11 10 000 000 | <a id="p124213"></a>Additional procedure |  |  |
| <a id="p124214"></a>12 03 001 000 | <a id="p124215"></a>Supporting document | <a id="p124216"></a>Reference number |  |
| <a id="p124217"></a>12 03 002 000 | <a id="p124218"></a>Supporting document | <a id="p124219"></a>Type |  |
| <a id="p124220"></a>12 03 010 000 | <a id="p124221"></a>Supporting document | <a id="p124222"></a>Issuing Authority name |  |
| <a id="p124223"></a>12 04 001 000 | <a id="p124224"></a>Additional reference | <a id="p124225"></a>Reference number |  |
| <a id="p124226"></a>12 04 002 000 | <a id="p124227"></a>Additional reference | <a id="p124228"></a>Type |  |
| <a id="p124229"></a>12 05 001 000 | <a id="p124230"></a>Transport document | <a id="p124231"></a>Reference number |  |
| <a id="p124232"></a>12 05 002 000 | <a id="p124233"></a>Transport document | <a id="p124234"></a>Type |  |
| <a id="p124235"></a>12 12 001 000 | <a id="p124236"></a>Authorisation | <a id="p124237"></a>Reference number |  |
| <a id="p124238"></a>12 12 002 000 | <a id="p124239"></a>Authorisation | <a id="p124240"></a>Type |  |
| <a id="p124241"></a>12 12 080 000 | <a id="p124242"></a>Authorisation | <a id="p124243"></a>Holder of the authorisation |  |
| <a id="p124244"></a>13 01 017 000 | <a id="p124245"></a>Exporter | <a id="p124246"></a>Identification number |  |
| <a id="p124247"></a>13 01 018 020 | <a id="p124248"></a>Exporter |  | <a id="p124249"></a>Country |
| <a id="p124250"></a>13 03 017 000 | <a id="p124251"></a>Consignee | <a id="p124252"></a>Identification number |  |
| <a id="p124253"></a>13 04 017 000 | <a id="p124254"></a>Importer | <a id="p124255"></a>Identification number |  |
| <a id="p124256"></a>13 04 018 020 | <a id="p124257"></a>Importer |  | <a id="p124258"></a>Country |
| <a id="p124259"></a>13 05 017 000 | <a id="p124260"></a>Declarant | <a id="p124261"></a>Identification number |  |
| <a id="p124262"></a>13 16 031 000 | <a id="p124263"></a>Additional fiscal references | <a id="p124264"></a>Role |  |
| <a id="p124265"></a>13 16 034 000 | <a id="p124266"></a>Additional fiscal references | <a id="p124267"></a>VAT identification number |  |
| <a id="p124268"></a>14 03 039 000 | <a id="p124269"></a>Duties and taxes | <a id="p124270"></a>Tax type |  |
| <a id="p124271"></a>14 03 038 000 | <a id="p124272"></a>Duties and taxes | <a id="p124273"></a>Method of payment |  |
| <a id="p124274"></a>14 03 042 000 | <a id="p124275"></a>Duties and taxes | <a id="p124276"></a>Payable tax amount |  |
| <a id="p124277"></a>14 03 040 000 | <a id="p124278"></a>Duties and taxes | <a id="p124279"></a>Tax base |  |
| <a id="p124280"></a>14 03 040 041 | <a id="p124281"></a>Duties and taxes |  | <a id="p124282"></a>Tax rate |
| <a id="p124283"></a>14 03 040 005 | <a id="p124284"></a>Duties and taxes |  | <a id="p124285"></a>Measurement unit and qualifier |
| <a id="p124286"></a>14 03 040 006 | <a id="p124287"></a>Duties and taxes |  | <a id="p124288"></a>Quantity |
| <a id="p124289"></a>14 03 040 014 | <a id="p124290"></a>Duties and taxes |  | <a id="p124291"></a>Amount |
| <a id="p124292"></a>14 10 000 000 | <a id="p124293"></a>Valuation method |  |  |
| <a id="p124294"></a>14 11 000 000 | <a id="p124295"></a>Preference |  |  |
| <a id="p124296"></a>16 03 000 000 | <a id="p124297"></a>Country of destination |  |  |
| <a id="p124298"></a>16 06 000 000 | <a id="p124299"></a>Country of dispatch |  |  |
| <a id="p124300"></a>16 08 000 000 | <a id="p124301"></a>Country of origin |  |  |
| <a id="p124302"></a>16 09 000 000 | <a id="p124303"></a>Country of preferential origin |  |  |
| <a id="p124304"></a>18 01 000 000 | <a id="p124305"></a>Net mass |  |  |
| <a id="p124306"></a>18 02 000 000 | <a id="p124307"></a>Supplementary units |  |  |
| <a id="p124308"></a>18 04 000 000 | <a id="p124309"></a>Gross mass |  |  |
| <a id="p124310"></a>18 05 000 000 | <a id="p124311"></a>Description of goods |  |  |
| <a id="p124312"></a>18 06 004 000 | <a id="p124313"></a>Packaging | <a id="p124314"></a>Number of packages |  |
| <a id="p124315"></a>18 09 056 000 | <a id="p124316"></a>Commodity code | <a id="p124317"></a>Harmonized System subheading code |  |
| <a id="p124318"></a>18 09 057 000 | <a id="p124319"></a>Commodity code | <a id="p124320"></a>Combined nomenclature code |  |
| <a id="p124321"></a>18 09 058 000 | <a id="p124322"></a>Commodity code | <a id="p124323"></a>TARIC code |  |
| <a id="p124324"></a>18 09 059 000 | <a id="p124325"></a>Commodity code | <a id="p124326"></a>TARIC additional code |  |
| <a id="p124327"></a>18 09 060 000 | <a id="p124328"></a>Commodity code | <a id="p124329"></a>National additional code |  |
| <a id="p124330"></a>19 01 000 000 | <a id="p124331"></a>Container indicator |  |  |
| <a id="p124332"></a>19 03 000 000 | <a id="p124333"></a>Mode of transport at the border |  |  |
| <a id="p124334"></a>19 04 000 000 | <a id="p124335"></a>Inland mode of transport |  |  |
| <a id="p124336"></a>19 07 063 000 | <a id="p124337"></a>Transport equipment | <a id="p124338"></a>Container identification number |  |
| <a id="p124339"></a>99 01 000 000 | <a id="p124340"></a>Quota order number |  |  |
| <a id="p124341"></a>99 06 000 000 | <a id="p124342"></a>Statistical value |  |  |
| <a id="p124343"></a>- - | <a id="p124344"></a>Date of acceptance of the declaration <3> |  |  |
| <a id="p124345"></a>- - | <a id="p124346"></a>Declaration number (unique reference) <4> |  |  |
| <a id="p124347"></a>- - | <a id="p124348"></a>Issuer <5> |  |  |


<a id="p124349"></a>

---

<a id="p124350"></a><1> Formats and cardinalities of the data requirements from the column "D.E. No" are the same as those indicated in Annex B.
<a id="p124351"></a><2> For the data class which are printed in italics only the indicated attributes are subject to surveillance.
<a id="p124352"></a><3> The format of this information should be "yyyymmdd". The cardinality of this information should be "1x" at declaration level.
<a id="p124353"></a><4> The format of this information should be provided in compliance with the format of the MRN as defined in data sub-element number 12 01 001 000. The cardinality of this information should be "1x" at declaration level.
<a id="p124354"></a><5> The format of this information should be provided in compliance with the format of data element number 16 03 000 000. The GEONOM code, as referred to in introductory note 13 number 3 of Annex B, should be used. The cardinality of this element should be "1x" at declaration level.


<a id="p124355"></a>Annex 22-02

<a id="p124356"></a>**INFORMATION CERTIFICATE INF 4**
**AND APPLICATION FOR AN INFORMATION CERTIFICATE INF 4**

<a id="p124357"></a>Printing instructions:
1. <a id="p124358"></a>The form on which the information certificate INF 4 is issued shall be printed on white paper not containing mechanical pulp, sized for writing and weighing between 40 and 65 grams per square metre.
2. <a id="p124359"></a>The form shall measure 210 x 297 mm.
3. <a id="p124360"></a>Printing of the forms is the responsibility of the Members States; forms shall bear a serial number by which it can be identified. The form shall be printed in one of the official languages of the European Union.
4. <a id="p124361"></a>Old versions of the forms may also be used until existing stocks are exhausted or until 1 May 2019, whichever is the earliest.

<a id="p124362"></a>**EUROPEAN UNION**

1. <a id="p124363"></a>Supplier (name, full address, country)
<a id="p124364"></a>**INF 4**
<a id="p124365"></a>No 000.000

**INFORMATION CERTIFICATE**

To facilitate the establishment in the Union of the preferential origin of goods

2. <a id="p124366"></a>Consignee (name, full address, country)
3. <a id="p124367"></a>Invoice(s) No(s) <1> <2>
<a id="p124368"></a>See notes overleaf before completing this form

4. <a id="p124369"></a>Observations

5. <a id="p124370"></a>Item number - Marks and numbers - Number and kind of packages - Description of goods <3>

6. <a id="p124371"></a>Gross mass (kg) or other measure (l, m3, etc.)
<a id="p124372"></a>**7. CUSTOMS ENDORSEMENT**


<table>
<colgroup><col width="50%"><col width="8%"><col width="42%"></colgroup>
<tr><td>certified</td><td></td><td>correct</td></tr>
<tr><td colspan="3"></td></tr>
<tr><td></td><td></td><td>not correct</td></tr>
</table>

Issuing country: .................................. .
Place ......................, date ................. .
<a id="p124373"></a>**8. DECLARATION BY THE SUPPLIER**
I, the undersigned, declare that the declaration(s) concerning the originating status of the goods described in box 5 and <4>

| box 3 and attached to this |
| --- |


| declaration of ...... (date) |
| --- |


Place ......................, date ................. .
(Signature)
<a id="p124374"></a>(Signature)
<a id="p124375"></a>Stamp


<a id="p124376"></a>

---

<a id="p124377"></a><1> The term "invoice" also includes delivery notes or other commercial documents relating to the shipment or shipments concerned on which the declaration(s) are entered.
<a id="p124378"></a><2> This box need not be completed in the case of long-term declarations.
<a id="p124379"></a><3> Describe the goods entered in box 5 in accordance with commercial practice and in sufficient detail to enable them to be identified.
<a id="p124380"></a><4> Place a cross in the appropriate box.

<a id="p124381"></a>Notes

1. <a id="p124382"></a>Certificates must not contain erasures or overwriting. Any alterations must be made by deleting the incorrect particulars and adding any necessary corrections. Any such alteration must be initialled by the person who completed the certificate and endorsed by the customs authorities of the issuing country or territory.
2. <a id="p124383"></a>No spaces must be left between the items entered on the certificate and each item must be preceded by an item number. A horizontal line must be drawn immediately below the last item. Any unused space must be struck through in such a manner as to make any later additions impossible.
3. <a id="p124384"></a>Goods must be described in accordance with commercial practice and in sufficient detail to enable them to be identified.
4. <a id="p124385"></a>The form shall be completed in one of the official languages of the Union. The Customs authorities of the Member State which must provide the information or which requires it may request a translation of the information set out in the documents presented to them into the official language or languages of that Member State.

<a id="p124386"></a>**EUROPEAN UNION**

1. <a id="p124387"></a>Supplier (name, full address, country)
<a id="p124388"></a>**INF 4**
<a id="p124389"></a>No 000.000

**APPLICATION FOR AN INFORMATION CERTIFICATE**

To facilitate the establishment in the Union of the preferential origin of goods
2. <a id="p124390"></a>Consignee (name, full address, country)
3. <a id="p124391"></a>Invoice(s) No(s) <1> <2>
<a id="p124392"></a>See notes overleaf before completing this form

4. <a id="p124393"></a>Observations

5. <a id="p124394"></a>Item number - Marks and numbers - Number and kind of packages - Description of goods <3>

6. <a id="p124395"></a>Gross mass (kg) or other measure (l, m3, etc.)

<a id="p124396"></a>**8. DECLARATION BY THE SUPPLIER**
I, the undersigned, declare that the declaration(s) concerning the originating status of the goods described in box 5 and <4>

| box 3 and attached to this |
| --- |


| declaration of ...... (date) |
| --- |


Place ......................, date ................. .
(Signature)


<a id="p124397"></a>

---

<a id="p124398"></a><1> The term "invoice" also includes delivery notes or other commercial documents relating to the shipment or shipments concerned on which the declaration(s) are entered.
<a id="p124399"></a><2> This box need not be completed in the case of long-term declarations.
<a id="p124400"></a><3> Describe the goods entered in box 5 in accordance with commercial practice and in sufficient detail to enable them to be identified.
<a id="p124401"></a><4> Place a cross in the appropriate box.

<a id="p124402"></a>**DECLARATION BY THE SUPPLIER**

<a id="p124403"></a>I, the undersigned, supplier of the goods described overleaf,
<a id="p124404"></a>DECLARE that the goods meet the conditions required for the issue of the attached certificate;
<a id="p124405"></a>SPECIFY as follows the circumstances which have enabled these goods to meet the above conditions:
<a id="p124406"></a>SUBMIT the following supporting documents <1>:
<a id="p124407"></a>UNDERTAKE to submit, at the request of the appropriate authorities, any supporting evidence which these authorities may require for the purpose of issuing the attached certificate, and undertake, if required, to agree to any inspection of my accounts and any check on the processes of manufacture of the above goods carried out by the said authorities;
<a id="p124408"></a>REQUEST the issue of the attached certificate for these goods.

<a id="p124409"></a>(Place and date)

<a id="p124410"></a>(Signature)

<a id="p124411"></a>

---

<a id="p124412"></a><1> For example import documents, movement certificates, invoices, manufacturers' declarations, etc. referring to the processed products or goods re-exported in the unaltered state.


<a id="p124413"></a>Annex 22-06

<a id="p124414"></a>**APPLICATION TO BECOME A REGISTERED EXPORTER**
for the purpose of schemes of generalised tariff preferences
of the European Union, Norway, Switzerland and Turkey <*>


<table>
<colgroup><col width="4%"><col width="96%"></colgroup>
<tr><td><a id="p124415"></a>1.</td><td><a id="p124416"></a>Exporter's name, full address and country, contact details, TIN.</td></tr>
<tr><td><a id="p124417"></a>2.</td><td><a id="p124418"></a>Additional contact details including telephone and fax number as well as email address where available (optional).</td></tr>
<tr><td><a id="p124419"></a>3.</td><td><a id="p124420"></a>Specify whether the main activity is producing or trading.</td></tr>
<tr><td><a id="p124421"></a>4.</td><td><a id="p124422"></a>Indicative description of goods which qualify for preferential treatment, including indicative list of Harmonised System headings (or chapters where goods traded fall within more than twenty Harmonised System headings).</td></tr>
<tr><td><a id="p124423"></a>5.</td><td><a id="p124424"></a>Undertakings to be given by an exporter</td></tr>
<tr><td colspan="2"><a id="p124425"></a>The undersigned hereby:</td></tr>
<tr><td><a id="p124426"></a>-</td><td><a id="p124427"></a>declares that the above details are correct;</td></tr>
<tr><td><a id="p124428"></a>-</td><td><a id="p124429"></a>certifies that no previous registration has been revoked; conversely, certifies that the situation which led to any such revocation has been remedied;</td></tr>
<tr><td><a id="p124430"></a>-</td><td><a id="p124431"></a>undertakes to make out statements on origin only for goods which qualify for preferential treatment and comply with the origin rules specified for those goods in the Generalised System of Preferences;</td></tr>
<tr><td><a id="p124432"></a>-</td><td><a id="p124433"></a>undertakes to maintain appropriate commercial accounting records for production/supply of goods qual - ifying for preferential treatment and to keep them for at least three years from the end of the calendar year in which the statement on origin was made out;</td></tr>
<tr><td><a id="p124434"></a>-</td><td><a id="p124435"></a>undertakes to immediately notify the competent authority of changes as they arise to his registration data since acquiring the number of registered exporter;</td></tr>
<tr><td><a id="p124436"></a>-</td><td><a id="p124437"></a>undertakes to cooperate with the competent authority;</td></tr>
<tr><td><a id="p124438"></a>-</td><td><a id="p124439"></a>undertakes to accept any checks on the accuracy of his statements on origin, including verification of accounting records and visits to his premises by the European Commission or Member States' authorities, as well as the authorities of Norway, Switzerland and Turkey;</td></tr>
<tr><td><a id="p124440"></a>-</td><td><a id="p124441"></a>undertakes to request the revocation of his registration in the system, should he no longer meet the conditions for exporting any goods under the scheme;</td></tr>
<tr><td><a id="p124442"></a>-</td><td><a id="p124443"></a>undertakes to request the revocation of his registration in the system, should he no longer intend to export such goods under the scheme.</td></tr>
<tr><td colspan="2"><a id="p124444"></a>.................................................<br>Place, date, signature of authorised signatory, name and job title &lt;**&gt;</td></tr>
<tr><td colspan="2"><a id="p124445"></a>6. Prior specific and informed consent of exporter to the publication of his data on the public website<br>The undersigned is hereby informed that the information supplied in this declaration may be disclosed to the public via the public website. The undersigned accepts the publication of this information via the public website. The undersigned may withdraw his consent to the publication of this information via the public website by sending a request to the competent authorities responsible for the registration.<br>.................................................<br>Place, date, signature of authorised signatory, name and job title &lt;**&gt;</td></tr>
<tr><td colspan="2"><a id="p124446"></a>7. Box for official use by competent authority<br>The applicant is registered under the following number:<br>Registration Number: ________________________________<br>Date of registration _________________________________<br>Date from which the registration is valid __________________<br>Signature and stamp &lt;**&gt; _____________________________</td></tr>
</table>


<table>
<colgroup><col width="4%"><col width="96%"></colgroup>
<tr><td colspan="2"><a id="p124447"></a>Information notice<br>concerning the protection and processing of personal data<br>incorporated in the system</td></tr>
<tr><td><a id="p124448"></a>1.</td><td><a id="p124449"></a>Where the European Commission processes personal data contained in this application to become a registered exporter, Regulation (EC) No 45/2001 of the European Parliament and of the Council on the protection of individuals with regard to the processing of personal data by the Union institutions and bodies and on the free movement of such data applies. Where the competent authorities of a beneficiary country or a third country implementing Directive 95/46/EC of the European Parliament and of the Council on the protection of individuals with regard to the processing of personal data and on the free movement of such data process personal data contained in this application to become a registered exporter, the relevant national provisions implementing that Directive apply.</td></tr>
<tr><td><a id="p124450"></a>2.</td><td><a id="p124451"></a>Personal data in respect of the application to become a registered exporter are processed for the purpose of Union GSP rules of origin as defined in the relevant Union legislation. The said legislation providing for Union GSP rules of origin constitutes the legal basis for processing personal data in respect of the application to become a registered exporter.</td></tr>
<tr><td><a id="p124452"></a>3.</td><td><a id="p124453"></a>The competent authority in a country where the application has been submitted is the controller with respect to processing of the data in the REX system.<br>The list of competent authorities is published on the website of the Commission.</td></tr>
<tr><td><a id="p124454"></a>4.</td><td><a id="p124455"></a>Access to all data of this application is granted through a user ID/password to users in the Commission, the competent authorities of beneficiary countries and the customs authorities in the Member States, Norway, Switzerland and Turkey.</td></tr>
<tr><td><a id="p124456"></a>5.</td><td><a id="p124457"></a>The data of a revoked registration shall be kept by the competent authorities of the beneficiary country in the REX system for ten calendar years. This period shall run from the end of the year in which the revocation of a registration has taken place.</td></tr>
<tr><td><a id="p124458"></a>6.</td><td><a id="p124459"></a>The data subject has a right of access to the data relating to him that will be processed through the REX system and, where appropriate, the right to rectify, erase or block data in accordance with Regulation (EC) No 45/2001 or the national laws implementing Directive 95/46/EC. Any requests for right of access, rectification, erasure or blocking shall be submitted to and processed by the competent authorities of beneficiary countries responsible for the registration, as appropriate. Where the registered exporter has submitted a request for the exercise of that right to the Commission, the Commission shall forward such requests to the competent authorities of the beneficiary country concerned. If the registered exporter failed to obtain his rights from the controller of data, the registered exporter shall submit such request to the Commission acting as controller. The Commission shall have the right to rectify, erase or block the data.</td></tr>
<tr><td><a id="p124460"></a>7.</td><td><a id="p124461"></a>Complaints can be addressed to the relevant national data protection authority. The contact details of the national data protection authorities are available on the website of the European Commission, Directorate-General for Justice: (http://ec.europa.eu/justice/data-protection/bodies/authorities/eu/index_en.htm#h2-1).<br>Where the complaint concerns processing of data by the European Commission, it should be addressed to the European Data Protection Supervisor (EDPS) (http://www.edps.europa.eu/EDPSWEB/).</td></tr>
</table>


<a id="p124462"></a>

---

<a id="p124463"></a><*> The present application form is common to the GSP schemes of four entities: the Union (EU), Norway, Switzerland and Turkey ("the entities"). Please note, however, that the respective GSP schemes of these entities may differ in terms of country and product coverage. Consequently, a given registration will only be effective for the purpose of exports under the GSP scheme(s) that consider(s) your country as a beneficiary country.
<a id="p124464"></a><**> When applications to become a registered exporter or other exchanges of information between registered exporters and competent authorities in beneficiary countries or customs authorities in Member States are made using electronic data-processing techniques, the signature and stamp referred to in boxes 5, 6 and 7 shall be replaced by an electronic authentication.


<a id="p124465"></a>Annex 22-06A

<a id="p124466"></a>**APPLICATION TO BECOME A REGISTERED EXPORTER**
for the purpose of the registration of exporters of the
Member States


<table>
<colgroup><col width="4%"><col width="96%"></colgroup>
<tr><td><a id="p124467"></a>1.</td><td><a id="p124468"></a>Exporter's name, full address and country, contact details, EORI number.</td></tr>
<tr><td><a id="p124469"></a>2.</td><td><a id="p124470"></a>Additional contact details including telephone and fax number as well as email address where available (optional).</td></tr>
<tr><td><a id="p124471"></a>3.</td><td><a id="p124472"></a>Specify whether the main activity is producing or trading.</td></tr>
<tr><td><a id="p124473"></a>4.</td><td><a id="p124474"></a>Indicative description of goods which qualify for preferential treatment, including indicative list of Harmonised System headings (or chapters where goods traded fall within more than twenty Harmonised System headings).</td></tr>
<tr><td><a id="p124475"></a>5.</td><td><a id="p124476"></a>Undertakings to be given by an exporter</td></tr>
<tr><td colspan="2"><a id="p124477"></a>The undersigned hereby:</td></tr>
<tr><td><a id="p124478"></a>-</td><td><a id="p124479"></a>declares that the above details are correct;</td></tr>
<tr><td><a id="p124480"></a>-</td><td><a id="p124481"></a>certifies that no previous registration has been revoked; conversely, certifies that the situation which led to any such revocation has been remedied;</td></tr>
<tr><td><a id="p124482"></a>-</td><td><a id="p124483"></a>undertakes to make out statements on origin and other documents on origin only for goods which qualify for preferential treatment and comply with the origin rules specified for those goods in the preferential arrangement concerned;</td></tr>
<tr><td><a id="p124484"></a>-</td><td><a id="p124485"></a>undertakes to maintain appropriate commercial accounting records for production/supply of goods qual - ifying for preferential treatment and to keep them for as long as required by the preferential arrangement concerned, and at least three years from the end of the calendar year in which the statement on origin or the other document on origin was made out;</td></tr>
<tr><td><a id="p124486"></a>-</td><td><a id="p124487"></a>undertakes to immediately notify the customs authorities of changes as they arise to his registration data since acquiring the number of registered exporter;</td></tr>
<tr><td><a id="p124488"></a>-</td><td><a id="p124489"></a>undertakes to cooperate with the customs authorities;</td></tr>
<tr><td><a id="p124490"></a>-</td><td><a id="p124491"></a>undertakes to accept any checks on the accuracy of his statements on origin or other documents on origin, including verification of accounting records and visits to his premises by the European Commission or Member States' authorities;</td></tr>
<tr><td><a id="p124492"></a>-</td><td><a id="p124493"></a>undertakes to request the revocation of his registration in the system, should he no longer meet the conditions for applying the Registered Exporter system;</td></tr>
<tr><td><a id="p124494"></a>-</td><td><a id="p124495"></a>undertakes to request the revocation of his registration in the system, should he no longer intend to use the Registered Exporter system.</td></tr>
<tr><td colspan="2"><a id="p124496"></a>.................................................<br>Place, date, signature of authorised signatory, name and job title &lt;*&gt;</td></tr>
<tr><td colspan="2"><a id="p124497"></a>6. Prior specific and informed consent of exporter to the publication of his data on the public website<br>The undersigned is hereby informed that the information supplied in this declaration may be disclosed to the public via the public website. The undersigned accepts the publication of this information via the public website. The undersigned may withdraw his consent to the publication of this information via the public website by sending a request to the competent authorities responsible for the registration.<br>.................................................<br>Place, date, signature of authorised signatory, name and job title &lt;*&gt;</td></tr>
<tr><td colspan="2"><a id="p124498"></a>7. Box for official use by competent authority<br>The applicant is registered under the following number:<br>Registration Number: ________________________________<br>Date of registration _________________________________<br>Date from which the registration is valid __________________<br>Signature and stamp &lt;*&gt; _____________________________</td></tr>
</table>


<table>
<colgroup><col width="4%"><col width="96%"></colgroup>
<tr><td colspan="2"><a id="p124499"></a>Information notice<br>concerning the protection and processing of personal data<br>incorporated in the system</td></tr>
<tr><td><a id="p124500"></a>1.</td><td><a id="p124501"></a>Where the European Commission processes personal data contained in this application to become a registered exporter, Regulation (EC) No 45/2001 of the European Parliament and of the Council on the protection of individuals with regard to the processing of personal data by the Union institutions and bodies and on the free movement of such data will apply.</td></tr>
<tr><td><a id="p124502"></a>2.</td><td><a id="p124503"></a>Personal data in respect of the application to become a registered exporter are processed for the purposes of the rules of origin of the relevant preferential trade arrangements of the Union. The rules of origin laid down in Commission Implementing Regulation (EU) 2015/2447 constitute the legal bases for processing personal data in respect of the application to become a registered exporter.</td></tr>
<tr><td><a id="p124504"></a>3.</td><td><a id="p124505"></a>The customs authorities in a country where the application has been submitted is the controller with respect to processing of the data in the REX system.<br>The list of customs departments is published on the website of the Commission.</td></tr>
<tr><td><a id="p124506"></a>4.</td><td><a id="p124507"></a>Access to all data of this application is granted through a user ID/password to users in the Commission, and the customs authorities in the Member States, Norway, Switzerland and Turkey.</td></tr>
<tr><td><a id="p124508"></a>5.</td><td><a id="p124509"></a>The data of a revoked registration shall be kept by the customs authorities of Member States in the REX system for ten calendar years. This period shall run from the end of the year in which the revocation of a registration has taken place.</td></tr>
<tr><td><a id="p124510"></a>6.</td><td><a id="p124511"></a>The data subject has a right of access to the data relating to him that will be processed through the REX system and, where appropriate, the right to rectify, erase or block data in accordance with Regulation (EC) No 45/2001 or the national laws implementing Directive 95/46/EC of the European Parliament and of the Council on the protection of individuals with regard to the processing of personal data and on the free movement of such data. Any requests for right of access, rectification, erasure or blocking shall be submitted to and processed by the customs authorities of Member States responsible for the registration, as appropriate. Where the registered exporter has submitted a request for the exercise of that right to the Commission, the Commission shall forward such requests to the customs authorities of Member States concerned, respectively. If the registered exporter failed to obtain his rights from the controller of data, the registered exporter shall submit such request to the Commission acting as controller. The Commission shall have the right to rectify, erase or block the data.</td></tr>
<tr><td><a id="p124512"></a>7.</td><td><a id="p124513"></a>Complaints can be addressed to the relevant national data protection authority. The contact details of the national data protection authorities are available on the website of the European Commission, Directorate-General for Justice: (http://ec.europa.eu/justice/data-protection/bodies/authorities/eu/index_en.htm#h2-1).<br>Where the complaint concerns processing of data by the European Commission, it should be addressed to the European Data Protection Supervisor (EDPS) (http://www.edps.europa.eu/EDPSWEB/).</td></tr>
</table>


<a id="p124514"></a>

---

<a id="p124515"></a><*> When applications to become a registered exporter or other exchanges of information between registered exporters and competent authorities in beneficiary countries or customs authorities in Member States are made using electronic data-processing techniques, the signature and stamp referred to in boxes 5, 6 and 7 shall be replaced by an electronic authentication.


<a id="p124516"></a>Annex 22-07

<a id="p124517"></a>**STATEMENT ON ORIGIN**

<a id="p124518"></a>To be made out on any commercial documents showing the name and full address of the exporter and consignee as well as a description of the products and the date of issue <1>.
<a id="p124519"></a>French version
<a id="p124520"></a>L'exportateur ... ( Numéro d'exportateur enregistré <2>, <3>, <4>) des produits couverts par le présent document déclare que, sauf indication claire du contraire, ces produits ont l'origine préférentielle ... <5> au sens des règles d'origine du Système des préférences tarifaires généralisées de l'Union européenne et que le critère d'origine satisfait est ... ... <6>.
<a id="p124521"></a>English version
<a id="p124522"></a>The exporter ... (Number of Registered Exporter <2>, <3>, <4>) of the products covered by this document declares that, except where otherwise clearly indicated, these products are of ... preferential origin <5> according to rules of origin of the Generalised System of Preferences of the European Union and that the origin criterion met is ... ... <6>.
<a id="p124523"></a>Spanish version
<a id="p124524"></a>El exportador ... ( Número de exportador registrado <2>, <3>, <4>) de los productos incluidos en el presente documento declara que, salvo indicación en sentido contrario, estos productos gozan de un origen preferencial ... <5>) en el sentido de las normas de origen del Sistema de preferencias generalizado de la Unión europea y que el criterio de origen satisfecho es ... ... <6>.

<a id="p124525"></a>

---

<a id="p124526"></a><1> Where the statement on origin replaces another statement in accordance with paragraphs (2) and (3) Article 101 of Implementing Regulation (EU) 2015/2447, the replacement statement on origin shall bear the mention "Replacement statement" or "Attestation de remplacement" or " Comunicación de sustitución ". The replacement shall also indicate the date of issue of the initial statement and all other necessary data in accordance with the second subparagraph of Article 101(1) of Implementing Regulation (EU) 2015/2447.
<a id="p124527"></a><2> Where the statement on origin replaces another statement in accordance with subparagraph 1 of Article 101(2) and paragraph (3) of Article 101, both of Implementing Regulation (EU) 2015/2447, the re-consignor of the goods making out such a statement shall indicate his name and full address followed by his number of registered exporter.
<a id="p124528"></a><3> Where the statement on origin replaces another statement in accordance with subparagraph 2 of Article 101(2) of Implementing Regulation (EU) 2015/2447, the reconsignor of the goods making out such a statement shall indicate his name and full address followed by the mention (French version) "agissant sur la base de l'attestation d'origine établie par [nom et adresse complète de l'exportateur dans le pays bénéficiaire ], enregistré sous le numéro suivant [ Numéro d'exportateur enregistré dans le pays bénéficiaire ]", (English version) "acting on the basis of the statement on origin made out by [name and complete address of the exporter in the beneficiary country], registered under the following number [Number of Registered Exporter of the exporter in the beneficiary country]", (Spanish version) "actuando sobre la base de la comunicación extendida por [nombre y dirección completa del exportador en el país beneficiario], registrado con el número siguiente [ Número de exportador registrado del exportador en el país beneficiario]".
<a id="p124529"></a><4> Where the statement on origin replaces another statement in accordance with Article 101(2) of Implementing Regulation (EU) 2015/2447, the re-consignor of the goods shall indicate the number of registered exporter only if the value of originating products in the initial consignment exceeds EUR 6 000.
<a id="p124530"></a><5> Country of origin of products to be indicated. When the statement on origin relates to products originating in the Union, the exporter must indicate the origin by means of the symbol "EU". When the statement on origin relates, in whole or in part, to products originating in Ceuta and Melilla as referred to in Article 112 of Implementing Regulation (EU) 2015/2447, the exporter must indicate the origin by means of the symbol "CM".
<a id="p124531"></a><6> Products wholly obtained: enter the letter "P"; Products sufficiently worked or processed: enter the letter "W" followed by a heading of the Harmonised System (example "W" 9618).
<a id="p124532"></a>Where appropriate, the above mention shall be replaced with one of the following indications:
<a id="p124533"></a>(a) In the case of bilateral cumulation: "EU cumulation", "Cumul UE" or " Acumulación UE".
<a id="p124534"></a>(b) In the case of cumulation with Norway, Switzerland or Turkey: "Norway cumulation", "Switzerland cumulation", "Turkey cumulation", "Cumul Norvège ", "Cumul Suisse", "Cumul Turquie" or " Acumulación Noruega", " Acumulación Suiza", or " Acumulación Turquía ".
<a id="p124535"></a>(c) In the case of regional cumulation: "regional cumulation", "cumul regional" or " Acumulación regional".
<a id="p124536"></a>(d) In the case of extended cumulation: "extended cumulation with country x", "cumul étendu avec le pays x" or " Acumulación ampliada con el país x".


<a id="p124537"></a>Annex 22-08

<a id="p124538"></a>**CERTIFICATE**
**OF ORIGIN FORM A**

1. <a id="p124539"></a>Certificates of origin Form A must conform to the specimen shown in this Annex. The use of English or French for the notes on the reverse of the certificate shall not be obligatory. Certificates shall be made out in English or French. If completed by hand, entries must be in ink and in capital letters.
2. <a id="p124540"></a>Each certificate shall measure 210 x 297 mm; a tolerance of up to minus 5 mm or plus 8 mm in the length and in the width may be allowed. The paper used shall be white writing paper, sized, not containing mechanical pulp and weighing not less than 25 g/m2. It shall have a printed green guilloche-pattern background making any falsification by mechanical or chemical means apparent to the eye.
<a id="p124541"></a>If the certificates have several copies, only the top copy which is the original shall be printed with a printed green guilloche-pattern background.
3. <a id="p124542"></a>Each certificate shall bear a serial number, printed or otherwise, by which it can be identified.
4. <a id="p124543"></a>Certificates bearing older versions of the notes on the back of the form may also be used until existing stocks are exhausted.


<table>
<colgroup><col width="14%"><col width="16%"><col width="19%"><col width="4%"><col width="19%"><col width="15%"><col width="12%"></colgroup>
<tr><td colspan="3"><a id="p124544"></a>1. Goods consigned from (Exporter's business name, address, country)</td><td colspan="4" rowspan="2"><a id="p124545"></a>Reference No<br>GENERALIZED SYSTEM<br>OF PREFERENCES<br>CERTIFICATE OF ORIGIN<br>(Combined declaration and certificate)<br>FORM A<br>Issued in ...........................................<br>(country)<br>See notes overleaf</td></tr>
<tr><td colspan="3"><a id="p124546"></a>2. Goods consigned to (Consignee's name, address, country)</td></tr>
<tr><td colspan="3"><a id="p124547"></a>3. Means of transport and route (as far as known)</td><td colspan="4"><a id="p124548"></a>4. For official use</td></tr>
<tr><td><a id="p124549"></a>5. Item number</td><td><a id="p124550"></a>6. Marks and numbers of packages</td><td colspan="2"><a id="p124551"></a>7. Number and kind of packages, description of goods</td><td><a id="p124552"></a>8. Origin criterion (see Notes overleaf)</td><td><a id="p124553"></a>9. Gross weight or other quantity</td><td><a id="p124554"></a>10. Number and date of invoices</td></tr>
<tr><td colspan="3"><a id="p124555"></a>11. Certification<br>It is hereby certified, on the basis of control carried out. that the declaration by the exporter is correct.<br>...............................................................<br>Place and date, signature and stamp of certifying authority</td><td colspan="4"><a id="p124556"></a>12. Declaration by the exporter<br>The undersigned hereby declares that the above details and statements are correct; that all the goods were produced in<br>...............................................................<br>(country)<br>and that they comply with the origin requirements specified for those goods in the Generalized System of Preferences for goods exported to<br>...............................................................<br>(importing country)<br>...............................................................<br>Place and date, signature of authorized signatory</td></tr>
</table>


<a id="p124557"></a>Notes (2013)

<a id="p124558"></a>I. Countries which accept Form A for the purposes of the Generalized System of Preferences (GSP):


| <a id="p124559"></a>Australia <1> | <a id="p124560"></a>European Union: | <a id="p124561"></a>France | <a id="p124562"></a>Netherlands |
| --- | --- | --- | --- |
| <a id="p124563"></a>Belarus | <a id="p124564"></a>Austria | <a id="p124565"></a>Germany | <a id="p124566"></a>Poland |
| <a id="p124567"></a>Canada | <a id="p124568"></a>Belgium | <a id="p124569"></a>Greece | <a id="p124570"></a>Portugal |
| <a id="p124571"></a>Iceland | <a id="p124572"></a>Bulgaria | <a id="p124573"></a>Hungary | <a id="p124574"></a>Romania |
| <a id="p124575"></a>Japan | <a id="p124576"></a>Croatia | <a id="p124577"></a>Ireland | <a id="p124578"></a>Slovakia |
| <a id="p124579"></a>New Zealand <2> | <a id="p124580"></a>Cyprus | <a id="p124581"></a>Italy | <a id="p124582"></a>Slovenia |
| <a id="p124583"></a>Norway | <a id="p124584"></a>Czech Republic | <a id="p124585"></a>Latvia | <a id="p124586"></a>Spain |
| <a id="p124587"></a>Russian Federation | <a id="p124588"></a>Denmark | <a id="p124589"></a>Lithuania | <a id="p124590"></a>Sweden |
| <a id="p124591"></a>Switzerland including Liechtenstein <3> | <a id="p124592"></a>Estonia | <a id="p124593"></a>Luxembourg | <a id="p124594"></a>United Kingdom |
| <a id="p124595"></a>Turkey | <a id="p124596"></a>Finland | <a id="p124597"></a>Malta |  |
| <a id="p124598"></a>United States of America <4> |  |  |  |


<a id="p124599"></a>Full details of the conditions covering admission to the GSP in these countries are obtainable from the designated authorities in the exporting preference-receiving countries or from the customs authorities of the preference-givig countries listed above. An information note is also obtainable from the UNCTAD secretariat.
<a id="p124600"></a>II. General conditions
<a id="p124601"></a>To qualify for preference, products must:
<a id="p124602"></a>(a) fall within a description of products eligible for preference in the country of destination. The description entered on the form must be sufficiently detailed to enable the products to be identified by the customs officer examining them;
<a id="p124603"></a>(b) comply with the rules of origin of the country of destination. Each article in a consignment must qualify separately in its own right; and,
<a id="p124604"></a>(c) comply with the consignment conditions specified by the country of destination. In general, products must be consigned direct from the country of exportation to the country of destination but most preference-giving countries accept passage through intermediate countries subject to certain conditions. (For Australia, direct consignment is not necessary).
<a id="p124605"></a>III. Entries to be made in Box 8
<a id="p124606"></a>Preference products must either be wholly obtained in accordance with the rules of the country of destination or sufficiently worked or processed to fulfil the requirements of that country's origin rules.
<a id="p124607"></a>(a) Products wholly obtained: for export to all countries listed in Section I, enter the letter "P" in Box 8 (for Australia and New Zealand Box 8 may be left blank).
<a id="p124608"></a>(b) Products sufficiently worked or processed: for export to the countries specified below, the entry in Box 8 should be as follows:
<a id="p124609"></a>(1) United States of America: for single country shipments, enter the letter "Y" in Box 8, for shipments from recognized associations of counties, enter the letter "Z", followed by the sum of the cost or value of the domestic materials and the direct cost of processing, expressed as a percentage of the ex-factory price of the exported products; (example "Y" 35% or "Z" 35%).
<a id="p124610"></a>(2) Canada: for products which meet origin criteria from working or processing in more than one eligible least developed country, enter letter "G" in Box 8; otherwise "F".
<a id="p124611"></a>(3) Iceland, the European Union, Japan, Norway, Switzerland including Liechtenstein, and Turkey; enter the letter "W" in Box 8 followed by the Harmonized Commodity Description and coding system (Harmonized System) heading at the 4-digit level of the exported product (example "W" 96.18).
<a id="p124612"></a>(4) Russian Federation: for products which include value added in the exporting preference-receiving country, enter the letter "Y" in Box 8 followed by the value of imported materials and components expressed as a percentage of the fob price of the exported products (example "Y" 45%); for products obtained in a preference-receiving country and worked or processed in one or more other such countries, enter "Pk".
<a id="p124613"></a>(5) Australia and New Zealand completion of Box 8 is not required. It is sufficient that a declaration be properly made in Box 12.

<a id="p124614"></a>

---

<a id="p124615"></a><1> For Australia, the main requirement is the exporter's declaration on the normal commercial invoice. Form A, accompanied by the normal commercial invoice, is an acceptable alternative, but official certification is not required.
<a id="p124616"></a><2> Official certification is not required.
<a id="p124617"></a><3> The Principality of Liechtenstein forms, pursuant to the Treaty of 29 March 1923, a customs union with Switzerland.
<a id="p124618"></a><4> The United Sates does not require GSP Form A. A declaration setting forth all pertinent detailed information concerning the production or manufacture of the merchandise is considered sufficient only if requested by the district collector of Customs.


<table>
<colgroup><col width="10%"><col width="16%"><col width="21%"><col width="8%"><col width="12%"><col width="16%"><col width="18%"></colgroup>
<tr><td colspan="4"><a id="p124619"></a>1. Expéditeur (nom, adresse, pays de l'exportateur)</td><td colspan="3" rowspan="2"><a id="p124620"></a>Référence N'<br>SYSTÈME GÉNÉRALISÉ DE PRÉFÉRENCES<br>CERTIFICAT D'ORIGINE<br>( Déclaration et certificat)<br>FORMULE A<br>Délivré en ........................................<br>(pays)<br>Voir notes au verso</td></tr>
<tr><td colspan="4"><a id="p124621"></a>2. Destinataire (nom, adresse, pays)</td></tr>
<tr><td colspan="4"><a id="p124622"></a>3. Moyen de transport et itinéraire (si connus)</td><td colspan="3"><a id="p124623"></a>4. Pour usage officiel</td></tr>
<tr><td><a id="p124624"></a>5. N' d'ordre</td><td><a id="p124625"></a>6. Marques et numéros des colis</td><td><a id="p124626"></a>7. Nombre et type de colis: description des marchandises</td><td colspan="2"><a id="p124627"></a>8. Critère d'origine (voir notes au verso)</td><td><a id="p124628"></a>9. Poids brut ou quantité</td><td><a id="p124629"></a>10. N' et date de la facture</td></tr>
<tr><td colspan="3"><a id="p124630"></a>11. Certificat<br>II est certifié , sur la base du contrôle effectué , que la déclaration de l'exportateur est exacte.<br>...............................................................<br>Lieu et date, signature et timbre de l'autorite delivrant le certificat</td><td colspan="4"><a id="p124631"></a>12. Déclaration de l'exportateur<br>Le soussigné déclare que les mentions et indications ci-dessus sont exactes, que toutes ces marchandises ont été produites en<br>...............................................................<br>(nom du pays)<br>et qu'elles remplissent les conditions d'origine requises par le système généralisé de préférences pour ètre exportées $\text{а}$ destination de<br>...............................................................<br>(nom du pays importateur)<br>...............................................................<br>Lieu et date, signature du signataire habilite</td></tr>
</table>


<a id="p124632"></a>Notes (2013)

<a id="p124633"></a>I. Pays acceptant la formule A aux fins du système des préférences généralisées (SPG):


| <a id="p124634"></a>Australie <1> | <a id="p124635"></a>Union européenne : | <a id="p124636"></a>Finlande | <a id="p124637"></a>Pays-Bas |
| --- | --- | --- | --- |
| <a id="p124638"></a>Bèlarus | <a id="p124639"></a>Allemagne | <a id="p124640"></a>France | <a id="p124641"></a>Pologne |
| <a id="p124642"></a>Canada | <a id="p124643"></a>Autriche | <a id="p124644"></a>$Gr\dot{e}ce$ | <a id="p124645"></a>Portugal |
| <a id="p124646"></a>Etats-Unis d'Amérique <3> | <a id="p124647"></a>Belgique | <a id="p124648"></a>Hongrie | <a id="p124649"></a>tchèque République |
| <a id="p124650"></a>Fédération de Russie | <a id="p124651"></a>Bulgarie | <a id="p124652"></a>Irlande | <a id="p124653"></a>Roumanie |
| <a id="p124654"></a>Islande | <a id="p124655"></a>Chypre | <a id="p124656"></a>Italie | <a id="p124657"></a>Royaume-Uni |
| <a id="p124658"></a>Japon | <a id="p124659"></a>Croatie | <a id="p124660"></a>Lettonie | <a id="p124661"></a>Slovaquie |
| <a id="p124662"></a>Norvège | <a id="p124663"></a>Danemark | <a id="p124664"></a>Lituanie | <a id="p124665"></a>Slovénie |
| <a id="p124666"></a>Nouvelle - Zélande <2> | <a id="p124667"></a>Espagne | <a id="p124668"></a>Luxembourg | <a id="p124669"></a>Suède |
| <a id="p124670"></a>Suisse y compris Liechtenstein <4> | <a id="p124671"></a>Estonie | <a id="p124672"></a>Malte |  |
| <a id="p124673"></a>Turquie |  |  |  |


<a id="p124674"></a>Des details comlets sur les conditions regissant l'admission au benefice du SGP dans ce pays peuvent être obtenus des autorites designees par les pays exportateurs beneficiaires ou de l'administration des doucnes des pays donneurs qui figurent dans la liste ci-dessus. Une note d'information peut egalement être obtenue du secretariat de la CNUCED.
<a id="p124675"></a>II. Conditions générales 
<a id="p124676"></a>Pour être admis au bénéfice des préférences , les produits doivent:
<a id="p124677"></a>(a) correspondre $\text{а}$ la définition ètablie des produits pouvant bénéficier du régime de préférences dans les pays de destination. La description figurant sur la formule doit être suffisamment détaillée pour que les produits puissent être iderrifiés par l'agent des douanes qui les examine;
<a id="p124678"></a>(b) satisfaire aux règles d'origine du pays de destination. Chacun des articles d'une même expédition doit répondre aux conditions prescrites; et
<a id="p124679"></a>(c) satisfaire aux conditions d'expédition spécifiées par le pays de destination. En général , les produits doivent être expédiés directement du pays d'exportation au pays de destination; toutefois, la plupart des pays donneurs de préférences acceptent sous certaines conditions le passage par des pays intermédiaires (pour l'Australie, l'expédition directe n'est pas nécessaire ).
<a id="p124680"></a>III. Indications $\text{а}$ porter dans la case 8
<a id="p124681"></a>Pour bénéficier des préférences , les produits doivent avoir été , soit entièrement obtenus, soit suffisamment ouvrès ou transformès conformément aux règles d'origine des pays de destination.
<a id="p124682"></a>(a) Produits entièrement obtenus: pour l'exportation vers tous les pays figurant dans la liste de la section, il y a lieu d'inscrire la lettre "P" dans la case 8 (pour l'Australie et la Nouvelle - Zélande , la case 8 peut être laissée en blanc).
<a id="p124683"></a>(b) Produits suffisamment ouvrès ou transformés : pour l'exportation vers les pays figurant ci - après , les indications $\text{а}$ porter dans la case 8 doivent être les suivantes:
<a id="p124684"></a>(1) Etats Unis d'Amérique : dans le cas d'expédition provenant d'un seul pays, inscrire la lettre "Y" ou, dans le cas d'expéditions provenant d'un groupe de pays reconnu comme un seul, la lettre "Z", suivie de la somme du coût ou de la valeur des matières et du coût direct de la transformation, exprimèe en pourcentage du prix départ usine des marchandises exportèes (exemple: "Y" 35% ou "Z" 35%);
<a id="p124685"></a>(2) Canada: il y a lieu d'inscrire dans la case 8 la lettre "G" pur les produits qui satisfont aux critères d'origine après ouvraison ou transformation dans plusieurs des pays les moins avancés ; sinon, inscrire la lettre "F";
<a id="p124686"></a>(3) Islande, Japon, Norvège , Suisse y compris Liechtenstein, Turquie et l'Union européenne : inscrire dans la case 8 la lettre "W" suivie de la position tarifaire $\text{а}$ quatre chiffres occupée par le produit exporté dans le Systéme harmonisé de désignation et de codification des marchandises ( Systéme harmonise) (exemple "W" 96.18);
<a id="p124687"></a>(4) Fédération de Russie: pour les produits avec valeur ajoutée dans le pays exportateur bénéficiaire de préférences , il y a lieu d'inscrire la lettre "Y" dans la case 8, en la faisant suivre de la valeur des matiéres et des composants importés , exprimée en pourcentage du prix fob des marchandises exportées (exemple: "Y" 45%); pour les produits obtenus dans un pays bénéficiaire de préférences et ouvrés ou transformés dans un ou plusieurs autres pays bénéficiaires , il y a lieu d'inscrire les lettre "Pk" dans la case 8;
<a id="p124688"></a>(5) Australie et Nouvelle - Zélande : il n'est pas nécessaire de remplir la case 8. Il suffit de faire une déclaration appropriée dans la case 12.

<a id="p124689"></a>

---

<a id="p124690"></a><1> Pour l'Australie, l'exigence de base est une attestation de l'exportateur sur la facture habituelle. La formule A, accompagnée de la facture habituelle, peut être acceptée en remplacement, mais une certification officielle n'est pas exigée .
<a id="p124691"></a><2> Un visa officiel n'est pas exigé .
<a id="p124692"></a><3> Les Etats-Unis n'exigent pas de certificat SGP Formule A. Une déclaration reprenant toute information appropriée et détaillée concernant la production ou la fabrication de la marchandise est considérée comme suffisante, et doit être présentée uniquement $\text{а}$ la demande du receveur des douanes du district (District collector of Customs).
<a id="p124693"></a><4> D'après l'Accord du 29 mars 1923, la Principauté du Liechtenstein forme une union douanière avec la Suisse.


<a id="p124694"></a>Annex 22-09

<a id="p124695"></a>**INVOICE DECLARATION**

<a id="p124696"></a>The invoice declaration, the text of which is given below, must be made out in accordance with the footnotes. However, the footnotes do not have to be reproduced.
<a id="p124697"></a>French version
<a id="p124698"></a>L'exportateur des produits converts par le présent document [autorisation douanière no <1> déclare que, sauf indication claire du contraire, ces produits ont l'origine préférentielle ... <2> au sens des règles d'origine du Système des préférences tarifaires généralisées de l'Union européenne ... <3> et <4>.
<a id="p124699"></a>English version
<a id="p124700"></a>The exporter of the products covered by this document (customs authorisation No ... <1> declares that, except where otherwise clearly indicated, these products are of ... preferential origin <2> according to rules of origin of the Generalised System of Preferences of the European Union <3> and <4>.
<a id="p124701"></a>Spanish version
<a id="p124702"></a>El exportador de los productos incluidos en el presente documento ( autorización aduanera n° ... <1> declara que, salvo indicación en sentido contrario, estos productos gozan de un origen preferencial ... <2> en el sentido de las normas de origen del Sistema de preferencias generalizado de la Unión europea <3> y <4>.
<a id="p124703"></a>(place and date) <5>
<a id="p124704"></a>(Signature of the exporter; in addition the name of the person signing the declaration has to be indicated in clear script) <6>

<a id="p124705"></a>

---

<a id="p124706"></a><1> When the invoice declaration is made out by Union's approved exporter within the meaning of Article 77(4) of Implementing Regulation (EU) 2015/2447, the authorisation number of the approved exporter must be entered in this space. When (as will always be the case with invoice declarations made out in beneficiary countries) the invoice declaration is not made out by an approved exporter, the words in brackets shall be omitted or the space left blank.
<a id="p124707"></a><2> Country of origin of products to be indicated. When the invoice declaration relates, in whole or in part, to products originating in Ceuta and Melilla within the meaning of Article 112 of Implementing Regulation (EU) 2015/2447, the exporter must clearly indicate them in the document on which the declaration is made out by means of the symbol "CM".
<a id="p124708"></a><3> Where appropriate, enter one of the following indications: "EU cumulation", "Norway cumulation", "Switzerland cumulation", "Turkey cumulation", "regional cumulation", "extended cumulation with country x" or "Cumul UE", "Cumul Norvège ", "Cumul Suisse", "Cumul Turquie", "cumul regional", "cumul étendu avec le pays x" or " Acumulación UE", " Acumulación Noruega", " Acumulación Suiza", " Acumulación Turquía ", " Acumulación regional", " Acumulación ampliada con en país x".
<a id="p124709"></a><4> If the invoice declaration is made out in the context of another preferential trade agreement, the reference to the Generalised System of Preferences shall be replaced by the reference to this other preferential trade agreement.
<a id="p124710"></a><5> These indications may be omitted if the information is contained on the document itself.
<a id="p124711"></a><6> See Article 77(7) of Implementing Regulation (EU) 2015/2447 (concerns approved European Union's exporters only). In cases where the exporter is not required to sign, the exemption of signature also implies the exemption of the name of the signatory.


<a id="p124712"></a>Annex 22-10

<a id="p124713"></a>**MOVEMENT CERTIFICATE EUR.1 AND RELEVANT APPLICATIONS**

<a id="p124714"></a>(1) Movement certificate EUR.1 shall be made out on the form of which a specimen appears in this Annex. This form shall be printed in one of the official languages of the Union. Certificates shall be made out in one of these languages and in accordance with the provisions of the domestic law of the exporting State or territory. If they are handwritten, they shall be completed in ink and in capital letters.
<a id="p124715"></a>(2) Each certificate shall measure 210 x 297 mm; a tolerance of up to minus 5 mm or plus 8 mm in the length may be allowed. The paper used must be white, sized for writing not containing mechanical pulp and weighing not less than 25 g/m2. It shall have a printed green guilloche pattern background making any falsification by mechanical or chemical means apparent to the eye.
<a id="p124716"></a>(3) The competent authorities of the exporting State or territory may reserve the right to print the certificates themselves or may have them printed by approved printers. In the latter case each certificate must include a reference to such approval. Each certificate must bear the name and address of the printer or a mark by which the printer can be identified. It shall also bear a serial number, either printed or not, by which it can be identified.

<a id="p124717"></a>**MOVEMENT CERTIFICATE**


<table>
<colgroup><col width="45%"><col width="16%"><col width="12%"><col width="12%"><col width="15%"></colgroup>
<tr><td rowspan="3"><a id="p124718"></a>1. Exporter (Name, full address, country)</td><td colspan="4"><a id="p124719"></a>EUR.1 No A 000.000</td></tr>
<tr><td colspan="4"><a id="p124720"></a>See notes overleaf before completing this form</td></tr>
<tr><td colspan="4" rowspan="2"><a id="p124721"></a>2. Certificate used in preferential trade between<br>..................................................................<br>and<br>..................................................................<br>(Insert appropriate countries, groups of countries or territories)</td></tr>
<tr><td rowspan="2"><a id="p124722"></a>3. Consignee (Name, full address, country) (Optional)</td></tr>
<tr><td colspan="2"><a id="p124723"></a>4. Country, group of countries or territory in which the products are considered as originating</td><td colspan="2"><a id="p124724"></a>5. Country, group of countries or territory of destination</td></tr>
<tr><td><a id="p124725"></a>6. Transport details (Optional)</td><td colspan="4"><a id="p124726"></a>7. Remarks</td></tr>
<tr><td colspan="2"><a id="p124727"></a>8. Item number; Marks and numbers; Number and kind of packages &lt;1&gt;; Description of goods</td><td colspan="2"><a id="p124728"></a>9. Gross mass (kg) or other measure (litres, m3, etc.)</td><td><a id="p124729"></a>10. Invoices (Optional)</td></tr>
<tr><td><a id="p124730"></a>11. CUSTOMS ENDORSEMENT<br>Declaration certified<br>Export document &lt;2&gt;<br>Form .................. No ...............<br>Of ............................................<br>Customs office ..........................<br>Issuing country or territory .......<br>.................................................<br>.................................................<br>(Place and date)<br>.................................................<br>(Signature)</td><td><a id="p124731"></a><img src="https://i.bukva.ai/sakP7uTQ/img_53.png" alt="рис. 54"></td><td colspan="3"><a id="p124732"></a>12. DECLARATION BY THE EXPORTER<br>I, the undersigned, declare that the goods described above meet the conditions required for the issue of this certificate<br>...................................................<br>(Place and date)<br>...................................................<br>(Signature)</td></tr>
<tr><td colspan="5"><a id="p124733"></a>&lt;1&gt; If goods are not packed, indicate number of articles or state "in bulk" as appropriate.<br>&lt;2&gt; Complete only where the regulations of the exporting country or territory require.</td></tr>
</table>


13. <a id="p124734"></a>REQUEST FOR VERIFICATION, to


<a id="p124735"></a>**14. RESULT OF VERIFICATION**
<a id="p124736"></a>Verification carried out shows that this certificate <1>

| office indicated and that |
| --- |

    therein is accurate.


| requirements as to |
| --- |

    (see remarks appended).

<a id="p124737"></a>Verification of the authenticity and accuracy of this certificate is requested.
<a id="p124738"></a>..........................................
(Place and date)
..........................................
(Signature)
<a id="p124739"></a> ![рис. 55](https://i.bukva.ai/sakP7uTQ/img_54.png) 
<a id="p124740"></a>..........................................
(Place and date)
..........................................
(Signature)

---

<1> Insert X in the appropriate box.
<a id="p124741"></a> ![рис. 56](https://i.bukva.ai/sakP7uTQ/img_55.png) 

<a id="p124742"></a>Notes

1. <a id="p124743"></a>Certificate must not contain erasures or words written over one another. Any alterations must be made by deleting the incorrect particulars and adding any necessary corrections. Any such alteration must be initialled by the person who completed the certificate and endorsed by the Customs authorities of the issuing country or territory.
2. <a id="p124744"></a>No spaces must be left between the items entered on the certificate and each item must be preceded by an item number. A horizontal line must be drawn immediately below the last item. Any unused space must be struck through in such a manner as to make any later additions impossible.
3. <a id="p124745"></a>Goods must be described in accordance with commercial practice and with sufficient detail to enable them to be identified.

<a id="p124746"></a>**APPLICATION FOR A MOVEMENT CERTIFICATE**


<table>
<colgroup><col width="37%"><col width="16%"><col width="17%"><col width="8%"><col width="22%"></colgroup>
<tr><td rowspan="3"><a id="p124747"></a>1. Exporter (Name, full address, country)</td><td colspan="4"><a id="p124748"></a>EUR.1 No A 000.000</td></tr>
<tr><td colspan="4"><a id="p124749"></a>See notes overleaf before completing this form</td></tr>
<tr><td colspan="4" rowspan="2"><a id="p124750"></a>2. Application for a certificate to be used in preferential trade between<br>....................................................................................<br>and<br>....................................................................................<br>(Insert appropriate countries or groups of countries or territories)</td></tr>
<tr><td rowspan="2"><a id="p124751"></a>3. Consignee (Name, full address, country) (Optional)</td></tr>
<tr><td colspan="2"><a id="p124752"></a>4. Country, group of countries or territory in which the products are considered as originating</td><td colspan="2"><a id="p124753"></a>5. Country, group of countries or territory of destination</td></tr>
<tr><td><a id="p124754"></a>6. Transport details (Optional)</td><td colspan="4"><a id="p124755"></a>7. Remarks</td></tr>
<tr><td colspan="2"><a id="p124756"></a>8. Item number; Marks and numbers; Number and kind of packages &lt;1&gt;; Description of goods</td><td colspan="2"><a id="p124757"></a>9. Gross mass (kg) or other measure (litres, m3, etc.)</td><td><a id="p124758"></a>10. Invoices (Optional)</td></tr>
<tr><td colspan="5"><a id="p124759"></a>&lt;1&gt; If goods are not packed, indicate number of articles or state "in bulk" as appropriate.</td></tr>
</table>


<a id="p124760"></a>                        DECLARATION BY THE EXPORTER

I, the undersigned, exporter of the goods described overleaf,
DECLARE    that the goods meet the conditions required for the issue of the
           attached certificate;

SPECIFY    as follows the circumstances which have enabled these goods to
           meet the above conditions:
...........................................................................
...........................................................................
...........................................................................
...........................................................................
SUBMIT     the following supporting documents <1>:
...........................................................................
...........................................................................
...........................................................................
...........................................................................
UNDERTAKE  to  submit,  at  the request of the appropriate authorities, any
supporting  evidence which these authorities may require for the purpose of
issuing  the  attached certificate, and undertake, if required, to agree to
any  inspection  of  my  accounts  and  to  any  check  on the processes of
manufacture of the above goods, carried out by the said authorities;

REQUEST    the issue of the attached certificate for these goods.

.....................
(Place and date)

.....................
(Signature)

<a id="p124761"></a>

---

<a id="p124762"></a><1> For example: import documents, movement certificates, invoices, manufacturer's declarations, etc., referring to the products used in manufacture or to the goods re-exported in the same state.


<a id="p124763"></a>Annex 22-13 - IA

<a id="p124764"></a>**INVOICE DECLARATION**

<a id="p124765"></a>The invoice declaration, the text of which is given below, must be made out in accordance with the footnotes. However, the footnotes do not have to be reproduced.

<a id="p124766"></a>Bulgarian version

<a id="p124767"></a>Износителят на продуктите, обхванати от този документ (митническо разрешение N ... <1>), декларира, че освен където е отбелязано друго, тези продукти са с ... преференциален произход <2>.

<a id="p124768"></a>Spanish version

<a id="p124769"></a>El exportador de los productos incluidos en el presente documento ( autorización aduanera n° ... <1>) declara que, salvo indicación en sentido contrario, estos productos gozan de un origen preferencial... <2>.

<a id="p124770"></a>Czech version

<a id="p124771"></a> Vývozce výrobkù uvedených v tomto dokumentu ( èíslo povolení ... <1>) prohlašuje , že kromì zøetelnì oznaèených mají tyto výrobky preferenèní pùvod v ... <2>.

<a id="p124772"></a>Danish version

<a id="p124773"></a> Eksportøren af varer, der er omfattet af nærværende dokument (toldmyndighedernes tilladelse nr. ... <1>), erklærer , at varerne, medmindre andet tydeligt er angivet, har præferenceoprindelse i ... <2>.

<a id="p124774"></a>German version

<a id="p124775"></a>Der Ausführer ( Ermächtigter Ausführer ; Bewilligungs-Nr. ... <1>) der Waren, auf die sich dieses Handelspapier bezieht, erklärt , dass diese Waren, soweit nicht anders angegeben, präferenzbegünstigte ... <2> Ursprungswaren sind.

<a id="p124776"></a>Estonian version

<a id="p124777"></a> Käesoleva dokumendiga hõlmatud toodete eksportija (tolli loa nr. ... <1>) deklareerib, et need tooted on ... <2> sooduspäritoluga , välja arvatud juhul, kui on selgelt näidatud teisiti.

<a id="p124778"></a>Greek version

<a id="p124779"></a>O $\epsilon\xi\alpha\gamma\omega\gamma\text{έ}\alpha\varsigma$ $\tau\omega\nu$ $\pi\rho o\text{ϊό}\nu\tau\omega\nu$ $\pi o\upsilon$ $\kappa\alpha\lambda\text{ύ}\pi\tau o\nu\tau\alpha\iota$ $\alpha\pi\text{ό}$ $\tau o$ $\pi\alpha\rho\text{ό}\nu$ $\text{έ}\gamma\gamma\rho\alpha\phi o$ [ $\text{ά}\delta\epsilon\iota\alpha$ $\tau\epsilon\lambda\omega\nu\epsilon\text{ί}o\upsilon$ $\upsilon\pi’$ $\alpha\rho\iota\theta.$ ... <1>] $\delta\eta\lambda\text{ώ}\nu\epsilon\iota$ $\text{ό}\tau\iota$ , $\epsilon\kappa\tau\text{ό}\varsigma$ $\epsilon\text{ά}\nu$ $\delta\eta\lambda\text{ώ}\nu\epsilon\tau\alpha\iota$ $\sigma\alpha\phi\text{ώ}\varsigma$ $\text{ά}\lambda\lambda\omega\varsigma$ , $\tau\alpha$ $\pi\rho o\text{ϊό}\nu\tau\alpha$ $\alpha\upsilon\tau\text{ά}$ $\epsilon\text{ί}\nu\alpha\iota$ $\pi\rho o\tau\iota\mu\eta\sigma\iota\alpha\kappa\text{ή}\varsigma$ $\kappa\alpha\tau\alpha\gamma\omega\gamma\text{ή}\varsigma$ ... <2>.

<a id="p124780"></a>English version

<a id="p124781"></a>The exporter of the products covered by this document (customs authorisation No ... <1>) declares that, except where otherwise clearly indicated, these products are of ... <2> preferential origin.

<a id="p124782"></a>French version

<a id="p124783"></a>L'exportateur des produits couverts par le présent document [autorisation douanière n° ... <1>] déclare que, sauf indication claire du contraire, ces produits ont l'origine préférentielle ... <2>.

<a id="p124784"></a>Croatian version

<a id="p124785"></a>Izvoznik proizvoda obuhvaæenih ovom ispravom (carinsko ovlaštenje br. ... <1>) izjavljuje da su, osim ako je drukèije izrièito navedeno, ovi proizvodi ... <2> preferencijalnog podrijetla.

<a id="p124786"></a>Italian version

<a id="p124787"></a>L'esportatore delle merci contemplate nel presente documento [autorizzazione doganale n. ... <1>] dichiarache, salvo indicazione contraria, le merci sono di origine preferenziale ... <2>.

<a id="p124788"></a>Latvian version

<a id="p124789"></a> Eksportçtâjs produktiem, kuri ietverti šajâ dokumentâ (muitas pilnvara Nr. ... <1>), deklarç , ka, izòemot tur, kur ir citâdi skaidri noteikts, šiem produktiem ir priekšrocîbu izcelsme no ... <2>.

<a id="p124790"></a>Lithuanian version

<a id="p124791"></a> Šiame dokumente išvardintø prekiø eksportuotojas ( muitinës liudijimo Nr ... <1>) deklaruoja, kad, jeigu kitaip nenurodyta, tai yra ... <2> preferencinës kilmës prekës .

<a id="p124792"></a>Hungarian version

<a id="p124793"></a>A jelen okmányban szereplõ áruk exportõre ( vámfelhatalmazási szám : ... <1>) kijelentem, hogy eltérõ egyértelmû jelzés hiányában az áruk preferenciális ... <2> származásúak .

<a id="p124794"></a>Maltese version

<a id="p124795"></a>L-esportatur tal-prodotti koperti b'dan id-dokument (awtorizzazzjoni tad-dwana nru. ... <1>) jiddikjara li, $©lief¤$ fejn indikat b'mod $\dot{c}ar$ li mhux hekk, dawn il-prodotti huma ta' $ori\dot{g}ini$ preferenzjali ... <2>.

<a id="p124796"></a>Dutch version

<a id="p124797"></a>De exporteur van de goederen waarop dit document van toepassing is (douanevergunning nr. ... <1>), verklaart dat, behoudens uitdrukkelijke andersluidende vermelding, deze goederen van preferentiële ... oorsprong zijn <2>.

<a id="p124798"></a>Polish version

<a id="p124799"></a>Eksporter produktów objêtych tym dokumentem ( $upowa\dot{z}nienie$ w³adz celnych nr ... <1>) deklaruje, $¿e$ z wyj¹tkiem gdzie jest to wyraŸnie okreœlone , produkty te maj¹ ... <2> preferencyjne pochodzenie.

<a id="p124800"></a>Portuguese version

<a id="p124801"></a>O exportador dos produtos cobertos pelo presente documento [ autorização aduaneira n.° ... <1>], declara que, salvo expressamente indicado em contrário , estes produtos são de origem preferencial ... <2>.

<a id="p124802"></a>Romanian version

<a id="p124803"></a>Exportatorul produselor ce fac obiectul acestui document [ autorizaþia vamalã nr. ... <1>] declarã cã , exceptând cazul în care în mod expres este indicat altfel, aceste produse sunt de origine preferenþialã ... <2>.

<a id="p124804"></a>Slovenian version

<a id="p124805"></a>Izvoznik blaga, zajetega s tem dokumentom (pooblastilo carinskih organov št. ... <1>) izjavlja, da, razen èe ni drugaèe jasno navedeno, ima to blago preferencialno ... <2> poreklo.

<a id="p124806"></a>Slovak version

<a id="p124807"></a> Vývozca výrobkov uvedených v tomto dokumente [ èíslo povolenia ... <1>] vyhlasuje, že okrem zretel'ne oznaèených , majú tieto výrobky preferenèný pôvod v ... <2>.

<a id="p124808"></a>Finnish version

<a id="p124809"></a> Tässä asiakirjassa mainittujen tuotteiden viejä (tullin lupa nro ... <1>) ilmoittaa, että nämä tuotteet ovat, ellei toisin ole selvästi merkitty, etuuskohteluun oikeutettuja ... <2> alkuperätuotteita .

<a id="p124810"></a>Swedish version

<a id="p124811"></a> Exportören av de varor som omfattas av detta dokument (tullmyndighetens tillstånd nr ... <1>) försäkrar att dessa varor, om inte annat tydligt markerats, har förmånsberättigande ... ursprung <2>.

....................................................................... <3>
                             (Place and date)

....................................................................... <4>
        (Signature of exporter; in addition the name of the person
       signing the declaration has to be indicated in clear script)

<a id="p124812"></a>

---

<a id="p124813"></a><1> When the invoice declaration is made out by an approved exporter, the authorisation number of the approved exporter must be entered in this space. When the invoice declaration is not made out by an approved exporter, the words in brackets must be omitted or the space left blank.
<a id="p124814"></a><2> Origin of products to be indicated. When the invoice declaration relates in whole or in part, to products originating in Ceuta and Melilla the exporter must clearly indicate them in the document on which the declaration is made out by means of the symbol "CM".
<a id="p124815"></a><3> These indications may be omitted if the information is contained on the document itself.
<a id="p124816"></a><4> See Article 119(5). In cases where the exporter is not required to sign, the exemption of signature also implies the exemption of the name of the signatory.


<a id="p124817"></a>Annex 22-14

<a id="p124818"></a>**CERTIFICATE**
**OF ORIGIN FOR CERTAIN PRODUCTS SUBJECT TO SPECIAL**
**NON-PREFERENTIAL IMPORT ARRANGEMENTS**

<a id="p124819"></a>Introductory notes:
1. <a id="p124820"></a>The period of validity of the certificate of origin shall be 12 months from the date of issue by the issuing authorities.
2. <a id="p124821"></a>Certificates of origin shall consist only of a single sheet identified by the word "original" next to the title of the document. If additional copies are necessary, they shall bear the designation "copy" next to the title of the document. The customs authorities in the Union shall accept as valid only the original of the certificate of origin.
3. <a id="p124822"></a>Certificates of origin shall measure 210 x 297 mm; a tolerance of up to plus 8 mm or minus 5 mm in the length may be allowed. The paper used shall be white, not containing mechanical pulp, and shall weigh not less than 40 g/m2. The face of the original shall have a printed yellow guilloche pattern background making any falsification by mechanical or chemical means apparent.
4. <a id="p124823"></a>Certificates of origin shall be printed and completed in typescript in one of the official languages of the Union. Entries must not be erased or overwritten. Any changes shall be made by crossing out the wrong entry and, if necessary, adding the correct particulars. Such changes shall be initialled by the person making them and endorsed by the issuing authorities.
<a id="p124824"></a>All the additional particulars required for implementation of the Union legislation governing the special import arrangements shall be entered in box 5 of the certificate of origin.
<a id="p124825"></a>Unused spaces in boxes 5, 6 and 7 shall be struck through in such a way that nothing can be added at a later stage.
5. <a id="p124826"></a>Each certificate of origin shall bear a serial number, whether or not printed, by which it can be identified, and shall be stamped by the issuing authority and signed by the person or persons empowered to do so.
6. <a id="p124827"></a>Certificates of origin issued retrospectively shall bear in Box 5 the following indication in one of the official languages of the European Union:
- <a id="p124828"></a>Expedido a posteriori,
- <a id="p124829"></a>Udstedt efterfølgende ,
- <a id="p124830"></a>Nachträglich ausgestellt,
- <a id="p124831"></a>$\text{Ε}\kappa\delta o\theta\text{έ}\nu$ $\epsilon\kappa$ $\tau\omega\nu$ $\upsilon\sigma\tau\text{έ}\rho\omega\nu$ ,
- <a id="p124832"></a>Issued retrospectively,
- <a id="p124833"></a>Délivré a posteriori,
- <a id="p124834"></a>Rilasciato a posteriori,
- <a id="p124835"></a>Afgegeven a posteriori,
- <a id="p124836"></a>Emitido a posteriori,
- <a id="p124837"></a>Annettu jälkikäteen / utfärdat i efterhand,
- <a id="p124838"></a>Utfärdat i efterhand,
- <a id="p124839"></a>Vystaveno dodateènì ,
- <a id="p124840"></a>Välja antud tagasiulatuvalt,
- <a id="p124841"></a>Izsniegts retrospektîvi ,
- <a id="p124842"></a>Retrospektyvusis išdavimas ,
- <a id="p124843"></a>Kiadva visszamenõleges hatállyal ,
- <a id="p124844"></a>$Ma©ru\dot{g}¤$ retrospettivament,
- <a id="p124845"></a>Wystawione retrospektywnie,
- <a id="p124846"></a>Vyhotovené dodatoène ,
- <a id="p124847"></a>издаден впоследствие,
- <a id="p124848"></a>Eliberat ulterior,
- <a id="p124849"></a>Izdano naknadno.
7. <a id="p124850"></a>Certificates bearing in the top right box the text of the old version "CERTIFICATE OF ORIGIN for imports of agricultural products into the European Economic Community" and in the box "Notes" the text of the old version, may also be used until existing stocks are exhausted or until 1 May 2019, whichever is the earliest.


<table>
<colgroup><col width="30%"><col width="19%"><col width="17%"><col width="4%"><col width="4%"><col width="26%"></colgroup>
<tr><td colspan="2" rowspan="2"><a id="p124851"></a>1 Consignor</td><td colspan="4"><a id="p124852"></a>CERTIFICATE OF ORIGIN<br>for imports of products subject to special non-preferential import arrangements into the European Union</td></tr>
<tr><td colspan="3"><a id="p124853"></a>No</td><td><a id="p124854"></a>ORIGINAL</td></tr>
<tr><td colspan="2" rowspan="2"><a id="p124855"></a>2 Consignee (optional)</td><td colspan="4"><a id="p124856"></a>3 ISSUING AUTHORITY</td></tr>
<tr><td colspan="4"><a id="p124857"></a>4 Country of origin</td></tr>
<tr><td colspan="2"><a id="p124858"></a>NOTES<br>A. The certificate must be completed in typescript or by means of a mechanical data-processing system, or similar procedure.<br>B. The original of the certificate must be lodged together with the declaration of release for free circulation with the relevant customs office in the European Union.</td><td colspan="4"><a id="p124859"></a>5 Remarks</td></tr>
<tr><td colspan="4"><a id="p124860"></a>6 Item number - Markings and numbers - Number and kind of packages - DESCRIPTION OF GOODS</td><td colspan="2"><a id="p124861"></a>7 Gross and net mass (kg)</td></tr>
<tr><td colspan="6"><a id="p124862"></a>8 THIS IS TO CERTIFY THAT THE ABOVE PRODUCTS ORIGINATE IN THE COUNTRY INDICATED IN BOX 4 AND THAT THE INDICATIONS IN BOX 5 ARE CORRECT.</td></tr>
<tr><td><a id="p124863"></a>Place and date of issue</td><td colspan="2"><a id="p124864"></a>Signature</td><td colspan="3"><a id="p124865"></a>Issuing authority's stamp</td></tr>
<tr><td colspan="6"><a id="p124866"></a>9 RESERVED FOR THE CUSTOMS AUTHORITIES IN THE EUROPEAN UNION</td></tr>
</table>


<a id="p124867"></a>Annex 22-15

<a id="p124868"></a>**SUPPLIER'S DECLARATION**
**FOR PRODUCTS HAVING PREFERENTIAL ORIGIN STATUS**

<a id="p124869"></a>The supplier's declaration, the text of which is given below, must be made out in accordance with the footnotes. However, the footnotes do not have to be reproduced.

                                DECLARATION

I, the  undersigned,  declare  that  the  goods  listed  on  this  document
..........  <1> originate in .......... <2> and satisfy the rules of origin
governing preferential trade with .......... <3>:
I declare that <4>:

I  undertake  to  make  available  to  the  customs authorities any further
supporting documents they require:
.................................. <5>
.................................. <6>
.................................. <7>

<a id="p124870"></a>

---

<a id="p124871"></a><1> If only some of the goods listed on the document are concerned, they shall be clearly indicated or marked and this marking entered in the declaration as follows:
<a id="p124872"></a>"....... listed on this document and marked .......... originate in ..........".
<a id="p124873"></a><2> The European Union, country, group of countries or territory, from which the goods originate.
<a id="p124874"></a><3> Country, group of countries or territory concerned. When the preferential origin of a product from a country, group of countries or territory can be acquired in accordance with more than one rule of origin, the suppliers shall specify the legal framework used to determine the origin of the goods (namely the PEM Convention and/or the transitional rules of origin).
<a id="p124875"></a>Where a country, group of countries or territory is a Contracting Party to the PEM Convention, and where a legal framework is not specified, by default, the supplier's declaration shall be considered as stating that the PEM Convention has been used to determine the origin of the goods.
<a id="p124876"></a><4> To be completed, where necessary, only for goods having preferential origin status in the context of preferential trade relations with one of the countries, with which pan-Euro-Mediterranean cumulation of origin is applicable.
<a id="p124877"></a><5> Place and date.
<a id="p124878"></a><6> Name and position in the company.
<a id="p124879"></a><7> Signature.


<a id="p124880"></a>Annex 22-16

<a id="p124881"></a>**LONG-TERM SUPPLIER'S DECLARATION**
**FOR PRODUCTS HAVING PREFERENTIAL ORIGIN STATUS**

<a id="p124882"></a>The supplier's declaration, the text of which is given below, must be made out in accordance with the footnotes. However, the footnotes do not have to be reproduced.

                                DECLARATION

I, the undersigned, declare that the goods described below:
.................................. <1>
.................................. <2>
which are regularly supplied to ........ <3>, originate in ........ <4> and
satisfy the rules of origin governing preferential trade with ........ <5>.
I declare that <6>:

This  declaration  is  valid for all shipments of these products dispatched
from: ........ to ........ <7>.
I undertake to inform ........ immediately if this declaration is no longer
valid.
I  undertake  to  make  available  to  the  customs authorities any further
supporting documents they require.
.................................. <8>
.................................. <9>
.................................. <10>

<a id="p124883"></a>

---

<a id="p124884"></a><1> Description.
<a id="p124885"></a><2> Commercial designation as used on the invoices, e.g. model No.
<a id="p124886"></a><3> Name of company to which goods are supplied.
<a id="p124887"></a><4> The European Union, country, group of countries or territory, from which the goods originate.
<a id="p124888"></a><5> Country, group of countries or territory concerned. When the preferential origin of a product from a country, group of countries or territory can be acquired in accordance with more than one rule of origin, the suppliers shall specify the legal framework used to determine the origin of the goods (namely the PEM Convention and/or the transitional rules of origin).
<a id="p124889"></a>Where a country, group of countries or territory is a Contracting Party to the PEM Convention, and where a legal framework is not specified, by default, the supplier's declaration shall be considered as stating that the PEM Convention has been used to determine the origin of the goods.
<a id="p124890"></a><6> To be completed, where necessary, only for goods having preferential origin status in the context of preferential traderelations with one of the countries with which pan-Euro-Mediterranean cumulation of origin is applicable.
<a id="p124891"></a><7> Give the start and end dates. The period shall not exceed 24 months.
<a id="p124892"></a><8> Place and date of issue.
<a id="p124893"></a><9> Name and position, name and address of company.
<a id="p124894"></a><10> Signature.


<a id="p124895"></a>Annex 22-17

<a id="p124896"></a>**SUPPLIER'S DECLARATION**
**FOR PRODUCTS NOT HAVING PREFERENTIAL ORIGIN STATUS**

<a id="p124897"></a>The supplier's declaration, the text of which is given below, must be made out in accordance with the footnotes. However, the footnotes do not have to be reproduced.

<a id="p124898"></a>**DECLARATION**

<a id="p124899"></a>I, the undersigned, supplier of the goods covered by the annexed document, declare that:
1. <a id="p124900"></a>The following materials which do not have a preferential originating status have been used in the European Union to produce these goods:


| <a id="p124901"></a>Description of goods supplied <1> | <a id="p124902"></a>Description of non-originating materials used | <a id="p124903"></a>HS heading of non originating materials used <2> | <a id="p124904"></a>Value of non originating materials used <3> |
| --- | --- | --- | --- |
|  |  |  |  |
|  |  |  |  |
|  |  |  | <a id="p124905"></a>Total: |


2. <a id="p124906"></a>All the other materials used in the European Union to produce these goods originate in ........ <4> and satisfy the rules of origin governing preferential trade with ........ <5>, and
I declare that <6>:

I  undertake  to  make  available  to  the  customs authorities any further
supporting documents they require
.................................. <7>
.................................. <8>
.................................. <9>

<a id="p124907"></a>

---

<a id="p124908"></a><1> When the invoice, delivery note or other commercial document to which the declaration is annexed relates to a variety of goods, or goods not incorporating the same proportion of non originating materials, the supplier must clearly differentiate between them.
<a id="p124909"></a>Example:
<a id="p124910"></a>The document covers different models of electric motor of heading 8501 to be used in the manufacture of washing machines of heading 8450. The nature and value of the non originating materials used in the manufacture of the motors vary from one model to another. The models must be listed separately in column 1 and the information in the other columns must be given for each, so that the manufacturer of the washing machines can correctly assess the originating status of each of his products depending on the type of motor it incorporates.
<a id="p124911"></a><2> To be completed only where relevant.
<a id="p124912"></a>Example:
<a id="p124913"></a>The rule for garments of ex Chapter 62 allows the use of non-originating yarn. Thus if a French garment manufacturer uses fabric woven in Portugal from non-originating yarn, the Portuguese supplier need only enter "yarn" as non originating materials in column 2 of his declaration - the HS heading and value of the yarn are irrelevant.
<a id="p124914"></a>A firm manufacturing wire of HS heading 7217 from non-originating iron bars must enter "iron bars" in column 2. If the wire is to be incorporated in a machine for which the rule of origin sets a percentage limit on the value of non-originating materials used, the value of the bars must be entered in column 4.
<a id="p124915"></a><3> "Value" means the customs value of the materials at the time of import or, if this is not known and cannot be ascertained, the first ascertainable price paid for the materials in the European Union.
<a id="p124916"></a>For each type of non-originating material used, specify the exact value per unit of the goods shown in column 1.
<a id="p124917"></a><4> To be completed only where relevant. The Union, country, group of countries or territory from which the materials originate.
<a id="p124918"></a><5> To be completed only where relevant. Country, group of countries or territory concerned. When the preferential origin of a product from a country, group of countries or territory can be acquired in accordance with more than one rule of origin, the suppliers shall specify the legal framework used to determine the origin of the goods (namely the PEM Convention and/or the transitional rules of origin).
<a id="p124919"></a>Where a country, group of countries or territory is a Contracting Party to the PEM Convention, and where a legal framework is not specified, by default, the supplier's declaration is considered as referring to the PEM Convention has been used to determine the origin of the goods.
<a id="p124920"></a><6> To be completed where necessary, only for goods having preferential originating status in the context of preferential trade relations with one of the countries with which pan-Euro-Mediterranean cumulation of origin is applicable.
<a id="p124921"></a><7> Place and date.
<a id="p124922"></a><8> Name and function, name and address of company.
<a id="p124923"></a><9> Signature.


<a id="p124924"></a>Annex 22-18

<a id="p124925"></a>**LONG-TERM SUPPLIER'S DECLARATION**
**FOR PRODUCTS NOT HAVING PREFERENTIAL ORIGIN STATUS**

<a id="p124926"></a>The supplier's declaration, the text of which is given below, must be made out in accordance with the footnotes. However, the footnotes do not have to be reproduced.

<a id="p124927"></a>**DECLARATION**

<a id="p124928"></a>I, the undersigned, supplier of the goods covered by this document, which are regularly sent to ........... <1>, declare that:
1. <a id="p124929"></a>The following materials which do not have a preferential originating status have been used in the European Union to produce these goods:


| <a id="p124930"></a>Description of goods supplied <2> | <a id="p124931"></a>Description of non originating materials used | <a id="p124932"></a>HS heading of non originating materials used <3> | <a id="p124933"></a>Value of non originating materials used <4> |
| --- | --- | --- | --- |
|  |  |  |  |
|  |  |  |  |
|  |  |  | <a id="p124934"></a>Total: |


2. <a id="p124935"></a>All the other materials used in the European Union to produce these goods originate in .......... <5> and satisfy the rules of origin governing preferential trade with .............. <6>, and
I declare that <7>:

This  declaration  is  valid for all shipments of these products dispatched
from .......... to .......... <8>.
I  undertake to inform .............. immediately if this declaration is no
longer valid.
I  undertake  to  make  available  to  the  customs authorities any further
supporting documents they require.
.................................. <9>
.................................. <10>
.................................. <11>

<a id="p124936"></a>

---

<a id="p124937"></a><1> Customer's name and address.
<a id="p124938"></a><2> When the invoice, delivery note or other commercial document to which the declaration is annexed relates to a variety of goods, or goods not incorporating the same proportion of non originating materials, the supplier must clearly differentiate between them.
<a id="p124939"></a>Example:
<a id="p124940"></a>The document covers different models of electric motor of heading 8501 to be used in the manufacture of washing machines of heading 8450. The nature and value of the non originating materials used in the manufacture of the motors vary from one model to another. The models must be listed separately in column 1 and the information in the other columns must be given for each, so that the manufacturer of the washing machines can correctly assess the originating status of each of his products depending on the type of motor it incorporates.
<a id="p124941"></a><3> To be completed only where relevant.
<a id="p124942"></a>Example:
<a id="p124943"></a>The rule for garments of ex Chapter 62 allows the use of non-originating yarn. Thus if a French garment manufacturer uses fabric woven in Portugal from non-originating yarn. the Portuguese supplier need only enter "yarn" as non originating materials in column 2 of his declaration - the HS heading and value of the yarn are irrelevant.
<a id="p124944"></a>A firm manufacturing wire of HS heading 7217 from non-originating iron bars must enter "iron bars" in column 2. If the wire is to be incorporated in a machine for which the rule of origin sets a percentage limit on the value of non-originating materials used, the value of the bars must be entered in column 4.
<a id="p124945"></a><4> "Value" means the customs value of the materials at the time of import or, if this is not known and cannot be ascertained, the first ascertainable price paid for the materials in the European Union.
<a id="p124946"></a>For each type of non-originating material used, specify the exact value per unit of the shown in column 1.
<a id="p124947"></a><5> To be completed only where relevant. The Union, country, group of countries or territory from which the materials originate.
<a id="p124948"></a><6> To be completed only where relevant. Country, group of countries or territory concerned. When the preferential origin of a product from a country, group of countries or territory can be acquired in accordance with more than one rule of origin, the suppliers shall specify the legal framework used to determine the origin of the goods (namely the PEM Convention and/or the transitional rules of origin).
<a id="p124949"></a>Where a country, group of countries or territory is a Contracting Party to the PEM Convention, and where a legal framework is not specified, by default, the supplier's declaration shall be considered as stating that the PEM Convention has been used to determine the origin of the goods.
<a id="p124950"></a><7> To be completed where necessary, only for goods having preferential originating status in the context of preferential trade relations with one of the countries with which pan-Euro-Mediterranean cumulation of origin is applicable.
<a id="p124951"></a><8> Give the start and end dates. The period shall not exceed 24 months.
<a id="p124952"></a><9> Place and date of issue.
<a id="p124953"></a><10> Name and function, name and address of company.
<a id="p124954"></a><11> Signature.


<a id="p124955"></a>Annex 22-19

<a id="p124956"></a>**REQUIREMENTS**
**FOR DRAWING UP REPLACEMENT CERTIFICATES OF ORIGIN FORM A**

1. <a id="p124957"></a>The top right-hand box of the replacement certificate of origin FORM A (replacement certificate) shall indicate the name of the intermediary country where it is issued.
2. <a id="p124958"></a>Box 4 of the replacement certificate shall contain the words "Replacement certificate" or "Certificat de remplacement", as well as the date of issue of the initial proof of origin and its serial number.
3. <a id="p124959"></a>The name of the re-exporter shall be given in box 1 of the replacement certificate.
4. <a id="p124960"></a>The name of the final consignee may be given in box 2 of the replacement certificate.
5. <a id="p124961"></a>All particulars of the re-exported products appearing on the initial proof of origin shall be transferred to boxes 3 to 9 of the replacement certificate and references to the re-exporter's invoice may be given in box 10 of the replacement certificate.
6. <a id="p124962"></a>The endorsement made by the customs office issuing the replacement certificate shall be placed in box 11 of the replacement certificate.
7. <a id="p124963"></a>The particulars in box 12 of the replacement certificate concerning the country of origin shall be identical to those particulars in the initial proof of origin. This box shall be signed by the re-exporter.


<a id="p124964"></a>Annex 22-20

<a id="p124965"></a>**REQUIREMENTS**
**FOR DRAWING UP REPLACEMENT STATEMENTS ON ORIGIN**

1. <a id="p124966"></a>Where a statement on origin is replaced, the re-consignor shall indicate the following on the initial statement on origin:
<a id="p124967"></a>(a) the particulars of the replacement statement(s);
<a id="p124968"></a>(b) his name and address;
<a id="p124969"></a>(c) the consignee or consignees in the Union or, where applicable, in Norway or Switzerland.
2. <a id="p124970"></a>The initial statement on origin shall be marked "Replaced", " Remplacée " or "Sustituida".
3. <a id="p124971"></a>The re-consignor shall indicate the following on the replacement statement on origin:
<a id="p124972"></a>(a) all particulars of the re-consigned products taken from the initial proof;
<a id="p124973"></a>(b) the date on which the initial statement on origin was made out;
<a id="p124974"></a>(c) the particulars of the initial statement on origin as set out in Annex 22-07, including - where appropriate - information about cumulation applied;
<a id="p124975"></a>(d) his name and address and, where applicable, his number of registered exporter;
<a id="p124976"></a>(e) the name and address of the consignee or consignees in the Union or, where applicable, in Norway or Switzerland;
<a id="p124977"></a>(f) the date and place of the replacement.
4. <a id="p124978"></a>The replacement statement on origin shall be marked "Replacement statement", "Attestation de remplacement" or " Comunicación de sustitución ".


<a id="p124979"></a>Annex 23-01

<a id="p124980"></a>**AIR TRANSPORT COSTS TO BE INCLUDED IN THE CUSTOMS VALUE**

1. <a id="p124981"></a>The following table shows:
<a id="p124982"></a>(a) third countries listed by continents and zones (column 1);
<a id="p124983"></a>(b) the percentages which represent the part of the air transport costs to be included in the customs value (column 2).
2. <a id="p124984"></a>When goods are shipped from countries or airports not included in the following table, other than the airports referred to in paragraph 3, the percentage given for the airport nearest to that of departure shall be taken.
3. <a id="p124985"></a>As regards the French overseas departments which are part of the customs territory of the Union, the following rules shall apply:
<a id="p124986"></a>(a) for goods shipped directly from third countries to these departments, the whole of the air transport costs shall be included in the customs value;
<a id="p124987"></a>(b) for goods shipped from third countries to the European part of the Union after being transhipped or unloaded in one of those departments, only the air transport costs which would be incurred if the goods were destined to those departments shall be included in the customs value;
<a id="p124988"></a>(c) for goods shipped from third countries to those departments after being transhipped or unloaded in an airport of the European part of the Union, the air transport costs to be included in the customs value shall be the result of the application of the percentage given in the following table with reference to the flight from the airport of departure to the airport of transhipment or unloading.
<a id="p124989"></a>The transhipment or unloading shall be certified by an appropriate endorsement by the customs authorities on the air waybill or other air transport document. Failing this certification, the provisions of Article 137 apply.


| <a id="p124990"></a>1 | <a id="p124991"></a>2 |
| --- | --- |
| <a id="p124992"></a>Country of dispatch | <a id="p124993"></a>Percentage of total air transport costs to be included in the customs value |
| <a id="p124994"></a>AMERICA |  |
| <a id="p124995"></a>Zone A<br>Canada: Gander, Halifax, Moncton, Montreal, Ottawa, Quebec, Toronto<br>United States of America: Akron, Albany, Atlanta, Baltimore, Boston, Buffalo, Charleston, Chicago, Cincinnati, Columbus, Detroit, Indianapolis, Jacksonville, Kansas City, Lexington, Louisville, Memphis, Milwaukee, Minneapolis, Nashville, New Orleans, New York, Philadelphia, Pittsburgh, St. Louis, Washington DC<br>Greenland | <a id="p124996"></a>70 |
| <a id="p124997"></a>Zone B<br>Canada: Edmonton, Vancouver, Winnipeg<br>United States of America:<br>Albuquerque, Austin, Billings, Dallas, Denver, Houston, Las Vegas, Los Angeles, Miami, Oklahoma, Phoenix, Portland, Puerto Rico, Salt Lake City, San Francisco, Seattle<br>Central America: all Countries<br>South America: all Countries | <a id="p124998"></a>78 |
| <a id="p124999"></a>Zone C<br>United States of America: Anchorage, Fairbanks, Honolulu, Juneau | <a id="p125000"></a>89 |
| <a id="p125001"></a>AFRICA |  |
| <a id="p125002"></a>Zone D<br>Algeria, Egypt, Libya, Morocco, Tunisia | <a id="p125003"></a>33 |
| <a id="p125004"></a>Zone E<br>Benin, Burkina Faso, Cameroon, Cape Verde, Central African Republic, Chad, Ivory Coast, Djibouti, Ethiopia, Gambia, Ghana, Guinea, Guinea-Bissau, Liberia, Mali, Mauritania, Niger, Nigeria, Senegal, Sierra Leone, Sudan, Togo | <a id="p125005"></a>50 |
| <a id="p125006"></a>Zone F<br>Burundi, Democratic Republic of Congo, Congo, Equatorial Guinea, Gabon, Kenya, Rwanda, Sao Tomé and Principe, Seychelles, Somalia, St. Helena, Tanzania, Uganda | <a id="p125007"></a>61 |
| <a id="p125008"></a>Zone G<br>Angola, Botswana, Comoros, Lesotho, Madagascar, Malawi, Mauritius, Mozambique, Namibia, Republic of South Africa, Swaziland, Zambia, Zimbabwe | <a id="p125009"></a>74 |
| <a id="p125010"></a>ASIA |  |
| <a id="p125011"></a>Zone H<br>Armenia, Azerbaijan, Georgia, Iran, Iraq, Israel, Jordan, Kuwait, Lebanon, Syria | <a id="p125012"></a>27 |
| <a id="p125013"></a>Zone I<br>Bahrain, Muscat and Oman, Qatar, Saudi Arabia, United Arab Emirates, Yemen | <a id="p125014"></a>43 |
| <a id="p125015"></a>Zone J<br>Afghanistan, Bangladesh, Bhutan, India, Nepal, Pakistan | <a id="p125016"></a>46 |
| <a id="p125017"></a>Zone K<br>Russia: Novosibirsk, Omsk, Perm, Sverdlovsk<br>Kazakhstan, Kyrgyzstan, Tajikistan, Turkmenistan, Uzbekistan | <a id="p125018"></a>57 |
| <a id="p125019"></a>Zone L<br>Russia: Irkutsk, Kirensk, Krasnoyarsk<br>Brunei, China, Indonesia, Hong Kong, Kampuchea, Laos, Macao, Malaysia, Maldives, Mongolia, Myanmar, Philippines, Singapore, Sri Lanka, Taiwan, Thailand, Vietnam | <a id="p125020"></a>70 |
| <a id="p125021"></a>Zone M<br>Russia: Khabarovsk, Vladivostok<br>Japan, Korea (North), Korea (South) | <a id="p125022"></a>83 |
| <a id="p125023"></a>AUSTRALIA and OCEANIA |  |
| <a id="p125024"></a>Zone N<br>Australia and Oceania: all Countries | <a id="p125025"></a>79 |
| <a id="p125026"></a>EUROPE |  |
| <a id="p125027"></a>Zone O<br>Russia: Gorky, Samara, Moscow, Orel, Rostov, Volgograd, Voronej<br>Iceland, Ukraine | <a id="p125028"></a>30 |
| <a id="p125029"></a>Zone P<br>Albania, Belarus, Bosnia-Herzegovina, Faroe Islands, Kosovo, Moldova, Montenegro, North Macedonia, Norway, Serbia, Turkey | <a id="p125030"></a>15 |
| <a id="p125031"></a>Zone Q<br>Switzerland, United Kingdom, with the exception of Northern Ireland | <a id="p125032"></a>5 |


<a id="p125033"></a>Annex 23-02

<a id="p125034"></a>**LIST**
**OF GOODS REFERRED TO IN ARTICLE 142(6)**

<a id="p125035"></a>Valuation of certain perishable goods imported on
consignment in accordance with Article 74(2)(c) of the Code

1. <a id="p125036"></a>The following table shows the list of products and the respective periods for which the Commission will make available a Unit price to be used as the basis for the determination of the customs value of whole fruit and vegetables, of a single kind, imported on consignment only. In such a case, the customs declaration is definitive, as far as the determination of the customs value is concerned.
2. <a id="p125037"></a>For the purpose of determining the customs value of products referred to in the present annex and imported on consignment, a unit price per 100 kg net is established for each product. Such price is considered representative with respect to the importation of such products in the Union.
3. <a id="p125038"></a>The unit prices are used to determine the customs value of the imported goods for periods of 14 days, each period beginning on a Friday. The reference period for determining the unit prices is the preceding period of 14 days ending on the Thursday preceding the week during which new unit prices are to be established. In particular circumstances, the Commission may decide to extend the period of validity period for further 14 days. Member States will be promptly informed of such decision.
4. <a id="p125039"></a>The unit prices which the Member states supply to the Commission shall be calculated on the basis of the gross proceeds of sales recorded at the first commercial level after importation, and deducting the following elements from these figures:
- <a id="p125040"></a>a marketing margin for the marketing centres,
- <a id="p125041"></a>the costs of transport, insurance and associated costs within the customs territory,
- <a id="p125042"></a>import duties and other charges which are not to be included in the customs value.
<a id="p125043"></a>The Unit prices will be notified in Euro. If applicable, the rate of conversion to be used is that specified in Article 146.
5. <a id="p125044"></a>Member States may fix standard amounts for deduction in respect of transport, insurance and associated costs in accordance with point 4. Such standard amounts and the methods for calculating them shall be made known to the Commission.
6. <a id="p125045"></a>The prices are notified to the Commission (DG TAXUD) not later 12 noon on the Monday during the week in which the unit prices are made available. If that day is a non-working day, the notification will take place on the working day immediately preceding that day. The communication to the Commission will include also the indication of the approximate quantities of product on which the unit prices were calculated.
7. <a id="p125046"></a>Following receipt of the unit prices by the Commission, these figures are reviewed and subsequently disseminated via TARIC. Unit prices only apply if they are disseminated by the Commission.
8. <a id="p125047"></a>The Commission may decide not to accept, and consequently not to disseminate, the unit prices for one or more products where these prices would be significantly different in relation to the previous published prices, taking in particular account factors such as quantity and seasonality. Where necessary, the Commission will make enquiries with the relevant customs authorities to solve such cases.
9. <a id="p125048"></a>To assist this process, Member States shall supply annual import statistics, for the products listed in the following table before 30 September in the current year, with reference to the preceding year. These statistics will concern the total imported quantities of each product, and will also indicate the proportion of products imported on consignment.
10. <a id="p125049"></a>Based on such statistics, the Commission will establish which Member States will be in charge of notifying Unit prices for each product for the following year, informing them by 30 November at the latest.

<a id="p125050"></a>List of goods referred to in Article 142(6)

<a id="p125051"></a>The description of goods in this table is purely indicative and without prejudice to the rules for the interpretation of the Combined Nomenclature. For the purposes of this Annex, the scope of the arrangements laid down in Article 142(6) shall be determined by the scope of the CN codes as they exist at the time of adoption of this Regulation.


<table>
<colgroup><col width="27%"><col width="49%"><col width="24%"></colgroup>
<tr><td><a id="p125052"></a>CN (TARIC) Code</td><td><a id="p125053"></a>Description of Goods</td><td><a id="p125054"></a>Period of validity</td></tr>
<tr><td><a id="p125055"></a>0701 90 50</td><td><a id="p125056"></a>New potatoes</td><td><a id="p125057"></a>1.1 to 30.6</td></tr>
<tr><td><a id="p125058"></a>0703 10 19</td><td><a id="p125059"></a>Onions (other than sets)</td><td><a id="p125060"></a>1.1 to 31.12</td></tr>
<tr><td><a id="p125061"></a>0703 20 00</td><td><a id="p125062"></a>Garlic</td><td><a id="p125063"></a>1.1 to 31.12</td></tr>
<tr><td><a id="p125064"></a>0708 20 00</td><td><a id="p125065"></a>Beans (Vigna spp., Phaseolus spp.)</td><td><a id="p125066"></a>1.1 to 31.12</td></tr>
<tr><td><a id="p125067"></a>0709 20 00 10</td><td><a id="p125068"></a>Asparagus, green</td><td><a id="p125069"></a>1.1 to 31.12</td></tr>
<tr><td><a id="p125070"></a>0709 20 00 90</td><td><a id="p125071"></a>Asparagus, other</td><td><a id="p125072"></a>1.1 to 31.12</td></tr>
<tr><td><a id="p125073"></a>0709 60 10</td><td><a id="p125074"></a>Sweet peppers</td><td><a id="p125075"></a>1.1 to 31.12</td></tr>
<tr><td><a id="p125076"></a>0714 20 10</td><td><a id="p125077"></a>Sweet potatoes, fresh, whole, intended for human consumption</td><td><a id="p125078"></a>1.1 to 31.12</td></tr>
<tr><td><a id="p125079"></a>0804 30 00 90</td><td><a id="p125080"></a>Pineapples, other than dried</td><td><a id="p125081"></a>1.1 to 31.12</td></tr>
<tr><td><a id="p125082"></a>0804 40 00 10</td><td><a id="p125083"></a>Avocados, fresh</td><td><a id="p125084"></a>1.1 to 31.12</td></tr>
<tr><td><a id="p125085"></a>0805 10 22</td><td><a id="p125086"></a>Sweet oranges, fresh</td><td><a id="p125087"></a>1.6 to 30.11</td></tr>
<tr><td><a id="p125088"></a>0805 10 24</td><td></td><td></td></tr>
<tr><td><a id="p125089"></a>0805 10 28</td><td></td><td></td></tr>
<tr><td><a id="p125090"></a>0805 21 10 10</td><td rowspan="3"><a id="p125091"></a>Mandarins (including tangerines and satsumas), fresh</td><td rowspan="3"><a id="p125092"></a>1.3 to 31.10</td></tr>
<tr><td><a id="p125093"></a>0805 21 90 11</td></tr>
<tr><td><a id="p125094"></a>0805 21 90 91</td></tr>
<tr><td><a id="p125095"></a>0805 22 00 11</td><td><a id="p125096"></a>Monreales, fresh</td><td><a id="p125097"></a>1.3 to 31.10</td></tr>
<tr><td><a id="p125098"></a>0805 22 00 20</td><td><a id="p125099"></a>Clementines (other than monreales), fresh</td><td><a id="p125100"></a>1.3 to 31.10</td></tr>
<tr><td><a id="p125101"></a>0805 29 00 11</td><td rowspan="3"><a id="p125102"></a>Wilkings and similar citrus hybrids, fresh</td><td><a id="p125103"></a>1.3 to 31.10</td></tr>
<tr><td><a id="p125104"></a>0805 29 00 21</td><td></td></tr>
<tr><td><a id="p125105"></a>0805 29 00 91</td><td></td></tr>
<tr><td><a id="p125106"></a>0805 40 00 11</td><td rowspan="2"><a id="p125107"></a>Grapefruit, including pomelos, fresh, white</td><td rowspan="2"><a id="p125108"></a>1.1 to 31.12</td></tr>
<tr><td><a id="p125109"></a>0805 40 00 31</td></tr>
<tr><td><a id="p125110"></a>0805 40 00 19</td><td rowspan="2"><a id="p125111"></a>Grapefruit, including pomelos, fresh, pink</td><td rowspan="2"><a id="p125112"></a>1.1 to 31.12</td></tr>
<tr><td><a id="p125113"></a>0805 40 00 39</td></tr>
<tr><td><a id="p125114"></a>0805 50 90 10</td><td><a id="p125115"></a>Limes (Citrus aurantifolia, Citrus latifolia), fresh</td><td><a id="p125116"></a>1.1 to 31.12</td></tr>
<tr><td><a id="p125117"></a>0806 10 10</td><td><a id="p125118"></a>Table grapes</td><td><a id="p125119"></a>21.11 to 20.7</td></tr>
<tr><td><a id="p125120"></a>0807 11 00</td><td><a id="p125121"></a>Watermelons</td><td><a id="p125122"></a>1.1 to 31.12</td></tr>
<tr><td><a id="p125123"></a>0807 19 00 50</td><td><a id="p125124"></a>Amarillo, Cuper, Honey dew (including Cantalene), Onteniente, Piel de Sapo (including Verde Liso), Rochet, Tendral, Futuro</td><td><a id="p125125"></a>1.1 to 31.12</td></tr>
<tr><td><a id="p125126"></a>0807 19 00 90</td><td><a id="p125127"></a>Other melons</td><td><a id="p125128"></a>1.1 to 31.12</td></tr>
<tr><td><a id="p125129"></a>0808 30 90 10</td><td><a id="p125130"></a>Pears of the variety Nashi (Pyrus pyrifolia), Ya (Pyrus bretscheideri)</td><td><a id="p125131"></a>1.5 to 30.6</td></tr>
<tr><td><a id="p125132"></a>0808 30 90 90</td><td><a id="p125133"></a>Pears, other</td><td><a id="p125134"></a>1.5 to 30.6</td></tr>
<tr><td rowspan="2"><a id="p125135"></a>0809 10 00</td><td rowspan="2"><a id="p125136"></a>Apricots</td><td><a id="p125137"></a>1.1 to 31.5</td></tr>
<tr><td><a id="p125138"></a>1.8 to 31.12</td></tr>
<tr><td rowspan="2"><a id="p125139"></a>0809 30 10</td><td rowspan="2"><a id="p125140"></a>Nectarines</td><td><a id="p125141"></a>1.1 to 10.6</td></tr>
<tr><td><a id="p125142"></a>1.10 to 31.12</td></tr>
<tr><td rowspan="2"><a id="p125143"></a>0809 30 90</td><td rowspan="2"><a id="p125144"></a>Peaches</td><td><a id="p125145"></a>1.1 to 10.6</td></tr>
<tr><td><a id="p125146"></a>1.10 to 31.12</td></tr>
<tr><td><a id="p125147"></a>0809 40 05</td><td><a id="p125148"></a>Plums</td><td><a id="p125149"></a>1.10 to 10.6</td></tr>
<tr><td><a id="p125150"></a>0810 10 00</td><td><a id="p125151"></a>Strawberries</td><td><a id="p125152"></a>1.1 to 31.12</td></tr>
<tr><td><a id="p125153"></a>0810 20 10</td><td><a id="p125154"></a>Raspberries</td><td><a id="p125155"></a>1.1 to 31.12</td></tr>
<tr><td><a id="p125156"></a>0810 50 00</td><td><a id="p125157"></a>Kiwifruit</td><td><a id="p125158"></a>1.1 to 31.12</td></tr>
</table>


<a id="p125159"></a>Annex 32-01

<a id="p125160"></a>**GUARANTOR'S UNDERTAKING - INDIVIDUAL GUARANTEE**

<a id="p125161"></a>I. Undertaking by the guarantor

    1. The undersigned <1> ................................................
Resident <2> at ...........................................................
hereby jointly and severally guarantees, at the office of guarantee of ....
up to a maximum amount of .................................................
in  favour  of  the  European Union (comprising the Kingdom of Belgium, the
Republic  of  Bulgaria,  the  Czech  Republic,  the Kingdom of Denmark, the
Federal  Republic  of  Germany,  the  Republic  of  Estonia,  the  Hellenic
Republic,  the  Republic  of  Croatia,  the  Kingdom  of  Spain, the French
Republic,  Ireland,  the  Italian  Republic,  the  Republic  of Cyprus, the
Republic  of  Latvia,  the  Republic  of  Lithuania,  the  Grand  Duchy  of
Luxembourg, Hungary, the Republic of Malta, the Kingdom of the Netherlands,
the  Republic  of Austria, the Republic of Poland, the Portuguese Republic,
Romania,  the  Republic  of  Slovenia, the Slovak Republic, the Republic of
Finland,  the  Kingdom of Sweden), and the Republic of Iceland, the Republic
of  North  Macedonia,  the  Kingdom  of Norway, the Republic of Serbia, the
Swiss Confederation, the Republic of Turkey, Ukraine, the United Kingdom of
Great Britain and Northern Ireland <3>, <4>, the Principality of Andorra and
the  Republic  of San Marino <5>, any amount for which the person providing
this guarantee <6>: .......................................................
may be  or become  liable to the abovementioned  countries for  debt in the
form  of  duty  and  other charges <6a> with respect to the goods described
below covered by the following customs operation <7>: .....................
Goods description: ........................................................
2. <a id="p125162"></a>The undersigned undertakes to pay upon the first application in writing by the competent authorities of the countries referred to in point 1 and without being able to defer payment beyond a period of 30 days from the date of application the sums requested unless he or she or any other person concerned establishes before the expiry of that period, to the satisfaction of the customs authorities, that the special procedure other than the end-use procedure has been discharged, the customs supervision of end-use goods or the temporary storage has ended correctly or, in case of the operations other than special procedures and temporary storage, that the situation of goods has been regularised.
<a id="p125163"></a>At the request of the undersigned and for any reasons recognized as valid, the competent authorities may defer beyond a period of 30 days from the date of application for payment the period within which he or she is obliged to pay the requested sums. The expenses incurred as a result of granting this additional period, in particular any interest, must be so calculated that the amount is equivalent to what would be charged under similar circumstances on the money market or financial market in the country concerned.
3. <a id="p125164"></a>This undertaking shall be valid from the day of its approval by the office of guarantee. The undersigned shall remain liable for payment of any debt incurred during the customs operation covered by this undertaking and commenced before any revocation or cancellation of the guarantee took effect, even if the demand for payment is made after that date.
4. <a id="p125165"></a>For the purpose of this undertaking, the undersigned gives his or her address for service in each of the other countries referred to in point 1 as <8>


| <a id="p125166"></a>Country | <a id="p125167"></a>Surname and forenames, or name of firm, and full address |
| --- | --- |
|  |  |
|  |  |
|  |  |
|  |  |
|  |  |
|  |  |
|  |  |


<a id="p125168"></a>The undersigned acknowledges that all correspondence and notices and any formalities or procedures relating to this undertaking addressed to or effected in writing at one of his or her addresses for services shall be accepted as duly delivered to him or her.
<a id="p125169"></a>The undersigned acknowledges the jurisdiction of the courts of the places where he or she has an address for service.
<a id="p125170"></a>The undersigned undertakes not to change his or her address for service or, if he or she has to change one or more of those addresses, to inform the office of guarantee in advance.
Done at ...................................................................
on ........................................................................
...........................................................................
                              (Signature) <9>

<a id="p125171"></a>                  II. Approval by the office of guarantee

Office of guarantee .......................................................

Guarantor's undertaking approved on ........................... ........ to
cover  the  customs  operation effected under customs declaration/temporary
storage declaration No ................................... of ........ <10>
...........................................................................
                                                      (Stamp and Signature)

<a id="p125172"></a>

---

<a id="p125173"></a><1> Surname and forename or name of firm.
<a id="p125174"></a><2> Full address.
<a id="p125175"></a><3> Delete the name/names of the State/States on whose territory the guarantee may not be used.
<a id="p125176"></a><4> Pursuant to the Protocol on Ireland/Northern Ireland of the Agreement on the with drawal of the United Kingdom of Great Britain and Northern Ireland from the European Union and the European Atomic Energy Community, Northern Ireland is to be considered as part of the European Union for the purposes of this guarantee. Therefore, a guarantor established in the customs territory of the European Union shall indicate an address for service or appoint an agent in Northern Ireland if the guarantee may be used therein. However, if a guarantee, in the context of common transit, is made valid in the European Union and in the United Kingdom, a single address for service or an appointed agent in the United Kingdom may cover all parts of the United Kingdom, including Northern Ireland.
<a id="p125177"></a><5> The references to the Principality of Andorra and the Republic of San Marino shall apply solely to Union transit operations.
<a id="p125178"></a><6> Surname and forename, or name of firm and full address of the person providing the guarantee.
<a id="p125179"></a><6a> Applicable with respect to the other charges due in connection with the import or export of the goods where the guarantee is used for the placing of goods under the Union/common transit procedure or may be used in more than one Member State.
<a id="p125180"></a><7> Enter one of the following customs operations:
<a id="p125181"></a>(a) temporary storage,
<a id="p125182"></a>(b) Union transit procedure/common transit procedure,
<a id="p125183"></a>(c) customs warehousing procedure,
<a id="p125184"></a>(d) temporary admission procedure with total relief from import duty,
<a id="p125185"></a>(e) inward processing procedure,
<a id="p125186"></a>(f) end-use procedure,
<a id="p125187"></a>(g) release for free circulation under normal customs declaration without deferred payment,
<a id="p125188"></a>(h) release for free circulation under normal customs declaration with deferred payment,
<a id="p125189"></a>(i) release for free circulation under a customs declaration lodged in accordance with Article 166 of Regulation (EU) No 952/2013 of the European Parliament and of the Council of 9 October 2013 laying down the Union Customs Code,
<a id="p125190"></a>(j) release for free circulation under a customs declaration lodged in accordance with Article 182 of Regulation (EU) No 952/2013 of the European Parliament and of the Council of 9 October 2013 laying down the Union Customs Code,
<a id="p125191"></a>(k) temporary admission procedure with partial relief from import duty,
<a id="p125192"></a>(l) if another - indicate the other kind of operation.
<a id="p125193"></a><8> If, in the law of the country, there is no provision for address for service the guarantor shall appoint, in this country, an agent authorized to receive any communications addressed to him and the acknowledgement in the second subparagraph and the undertaking in the fourth subparagraph of point 4 must be made to correspond. The courts of the places in which the addresses for service of the guarantor or of his agents are situated shall have jurisdiction in disputes concerning this guarantee.
<a id="p125194"></a><9> The person signing the document must enter the following by hand before his or her signature: "Guarantee for the amount of ..." (the amount being written out in letters).
<a id="p125195"></a><10> To be completed by the office where the goods were placed under the procedure or were in temporary storage.


<a id="p125196"></a>Annex 32-02

<a id="p125197"></a>**GUARANTOR'S UNDERTAKING - INDIVIDUAL GUARANTEE**
**IN THE FORM OF VOUCHERS**
**COMMON/UNION TRANSIT PROCEDURE**

<a id="p125198"></a>I. Undertaking by the guarantor

1. The undersigned <1> ....................................................
Resident at <2> ...........................................................
hereby jointly and severally guarantees, at the office of guarantee of ....
<a id="p125199"></a>in favour of the European Union (comprising the Kingdom of Belgium, the Republic of Bulgaria, the Czech Republic, the Kingdom of Denmark, the Federal Republic of Germany, the Republic of Estonia, the Hellenic Republic, the Republic of Croatia, the Kingdom of Spain, the French Republic, Ireland, the Italian Republic, the Republic of Cyprus, the Republic of Latvia, the Republic of Lithuania, the Grand Duchy of Luxembourg, Hungary, the Republic of Malta, the Kingdom of the Netherlands, the Republic of Austria, the Republic of Poland, the Portuguese Republic, Romania, the Republic of Slovenia, the Slovak Republic, the Republic of Finland, the Kingdom of Sweden), and the Republic of Iceland, the Republic of North Macedonia, the Kingdom of Norway, the Republic of Serbia, the Swiss Confederation, the Republic of Turkey, Ukraine, the United Kingdom of Great Britain and Northern Ireland <3>, the Principality of Andorra and the Republic of San Marino <4>, any amount for which the holder of the procedure may be or become liable to the abovementioned countries for debt in the form of duty and other charges due in connection with the import or export of the goods placed under the Union or common transit procedure, in respect of which the undersigned has undertaken to issue individual guarantee vouchers up to a maximum of EUR 10 000 per voucher.
2. <a id="p125200"></a>The undersigned undertakes to pay upon the first application in writing by the competent authorities of the countries referred to in point 1 and without being able to defer payment beyond a period of 30 days from the date of application the sums requested, up to EUR 10 000 per individual guarantee voucher, unless he or she or any other person concerned establishes before the expiry of that period, to the satisfaction of the competent authorities, that the operation has been discharged.
<a id="p125201"></a>At the request of the undersigned and for any reasons recognised as valid, the competent authorities may defer beyond a period of 30 days from the date of application for payment the period within which he or she is obliged to pay the requested sums. The expenses incurred as a result of granting this additional period, in particular any interest, must be so calculated that the amount is equivalent to what would be charged under similar circumstances on the money market or financial market in the country concerned.
3. <a id="p125202"></a>This undertaking shall be valid from the day of its approval by the office of guarantee. The undersigned shall remain liable for payment of any debt incurred during the Union or common transit operation covered by this undertaking and commenced before any revocation or cancellation of the guarantee took effect, even if the demand for payment is made after that date.
4. <a id="p125203"></a>For the purpose of this undertaking, the undersigned gives his or her address for service <5> in each of the other countries referred to in point 1 as


| <a id="p125204"></a>Country | <a id="p125205"></a>Surname and forenames, or name of firm, and full address |
| --- | --- |
|  |  |
|  |  |
|  |  |
|  |  |
|  |  |
|  |  |
|  |  |


<a id="p125206"></a>The undersigned acknowledges that all correspondence and notices and any formalities or procedures relating to this undertaking addressed to or effected in writing at one of his or her addresses for services shall be accepted as duly delivered to him or her.
<a id="p125207"></a>The undersigned acknowledges the jurisdiction of the courts of the places where he or she has an address for service.
<a id="p125208"></a>The undersigned undertakes not to change his or her address for service or, if he or she has to change one or more of those addresses, to inform the office of guarantee in advance.
Done at ...................................................................
on ........................................................................
...........................................................................
                              (Signature) <6>

<a id="p125209"></a>                  II. Approval by the office of guarantee

Office of guarantee .......................................................
Guarantor's undertaking approved on .......................................
...........................................................................
                                                      (Stamp and Signature)

<a id="p125210"></a>

---

<a id="p125211"></a><1> Surname and forename or name of firm.
<a id="p125212"></a><2> Full address.
<a id="p125213"></a><3> Pursuant to the Protocol on Ireland/Northern Ireland of the Agreement on the withdrawal of the United Kingdom of Great Britain and Northern Ireland from the European Union and the European Atomic Energy Community, Northern Ireland is to be considered as part of the European Union for the purposes of this guarantee. Therefore, a guarantor established in the customs territory of the European Union shall indicate an address for service or appoint an agent in Northern Ireland if the guarantee may be used therein. However, if a guarantee, in the context of common transit, is made valid in the European Union and in the United Kingdom, a single address for service or an appointed agent in the United Kingdom may cover all parts of the United Kingdom, including Northern Ireland.
<a id="p125214"></a><4> The references to the Principality of Andorra and the Republic of San Marino shall apply solely to Union transit operations.
<a id="p125215"></a><5> If, in the law of the country, there is no provision for address for service the guarantor shall appoint, in this country, an agent authorized to receive any communications addressed to him and the acknowledgement in the second subparagraph and the undertaking in the fourth subparagraph of point 4 must be made to correspond. The courts of the places in which the addresses for service of the guarantor or of his agents are situated shall have jurisdiction in disputes concerning this guarantee.
<a id="p125216"></a><6> The signature must be preceded by the following in the signatory's own handwriting: "Valid as guarantee voucher".


<a id="p125217"></a>Annex 32-03

<a id="p125218"></a>**GUARANTOR'S UNDERTAKING - COMPREHENSIVE GUARANTEE**

<a id="p125219"></a>I. Undertaking by the guarantor

1. The undersigned <1> ....................................................
Resident at <2> ...........................................................
hereby jointly and severally guarantees, at the office of guarantee of ....
up to a maximum amount of .................................................
<a id="p125220"></a>in favour of the European Union (comprising the Kingdom of Belgium, the Republic of Bulgaria, the Czech Republic, the Kingdom of Denmark, the Federal Republic of Germany, the Republic of Estonia, Ireland, the Hellenic Republic, the Kingdom of Spain, the French Republic, the Republic of Croatia, the Italian Republic, the Republic of Cyprus, the Republic of Latvia, the Republic of Lithuania, the Grand Duchy of Luxembourg, Hungary, the Republic of Malta, the Kingdom of the Netherlands, the Republic of Austria, the Republic of Poland, the Portuguese Republic, Romania, the Republic of Slovenia, the Slovak Republic, the Republic of Finland, the Kingdom of Sweden), and the Republic of Iceland, the Republic of North Macedonia, the Kingdom of Norway, the Republic of Serbia, the Swiss Confederation, the Republic of Turkey, Ukraine, the United Kingdom of Great Britain and Northern Ireland <3>, <4>, the Principality of Andorra and the Republic of San Marino <5>,
<a id="p125221"></a>any amount for which the person providing this guarantee <6>: ...may be or become liable to the abovementioned countries for debt in the form of duty and other charges <7> which may be or have been incurred with respect to the goods covered by the customs operations indicated in point 1a and/or point 1b.
     The maximum amount of the guarantee is composed of an amount of:
...........................................................................
    (a)   being  100/50/30%  <8>  of  the  part  of  the  reference  amount
corresponding  to an amount of customs debts and other charges which may be
incurred, equivalent to the sum of the amounts listed in point 1a,
    and
...........................................................................
    (b) being 100/30% <9> of the part of the reference amount corresponding
to  an  amount of customs debts and other charges which have been incurred,
equivalent to the sum of the amounts listed in point 1b
<a id="p125222"></a>1a. The amounts forming the part of the reference amount corresponding to an amount of customs debts and, where applicable, other charges which may be incurred are following for each of the purposes listed below <10>:
<a id="p125223"></a>(a) temporary storage - ...,
<a id="p125224"></a>(b) Union transit procedure/common transit procedure - ...,
<a id="p125225"></a>(c) customs warehousing procedure - ...,
<a id="p125226"></a>(d) temporary admission procedure with total relief from import duty - ...,
<a id="p125227"></a>(e) inward processing procedure - ...,
<a id="p125228"></a>(f) end-use procedure - ...,
<a id="p125229"></a>(g) if another - indicate the other kind of operation - ....
<a id="p125230"></a>1b. The amounts forming the part of the reference amount corresponding to an amount of customs debts and, where applicable, other charges which have been incurred are following for each of the purposes listed below <11>:
<a id="p125231"></a>(a) release for free circulation under normal customs declaration without deferred payment - ...,
<a id="p125232"></a>(b) release for free circulation under normal customs declaration with deferred payment - ...,
<a id="p125233"></a>(c) release for free circulation under a customs declaration lodged in accordance with Article 166 of Regulation (EU) No 952/2013 of the European Parliament and of the Council of 9 October 2013 laying down the Union Customs Code - ...,
<a id="p125234"></a>(d) release for free circulation under a customs declaration lodged in accordance with Article 182 of Regulation (EU) No 952/2013 of the European Parliament and of the Council of 9 October 2013 laying down the Union Customs Code - ...,
<a id="p125235"></a>(e) temporary admission procedure with partial relief from import duty - ...,
<a id="p125236"></a>(f) end-use procedure - ... <12>
<a id="p125237"></a>(g) if another - indicate the other kind of operation - ....
2. <a id="p125238"></a>The undersigned undertakes to pay upon the first application in writing by the competent authorities of the countries referred to in point 1 and without being able to defer payment beyond a period of 30 days from the date of application the sums requested up to the limit of the abovementioned maximum amount, unless he or she or any other person concerned establishes before the expiry of that period, to the satisfaction of the customs authorities, that the special procedure other than the end-use procedure has been discharged, the customs supervision of end-use goods or the temporary storage has ended correctly or, in case of the operations other than special procedures, that the situation of goods has been regularised.
<a id="p125239"></a>At the request of the undersigned and for any reasons recognized as valid, the competent authorities may defer beyond a period of 30 days from the date of application for payment the period within which he or she is obliged to pay the requested sums. The expenses incurred as a result of granting this additional period, in particular any interest, must be so calculated that the amount is equivalent to what would be charged under similar circumstances on the money market or financial market in the country concerned.
<a id="p125240"></a>This amount may not be reduced by any sums already paid under the terms of this undertaking unless the undersigned is called upon to pay a debt incurred during a customs operation commenced before the preceding demand for payment was received or within 30 days thereafter.
3. <a id="p125241"></a>This undertaking shall be valid from the day of its approval by the office of guarantee. The undersigned shall remain liable for payment of any debt arising during the customs operation covered by this undertaking and commenced before any revocation or cancellation of the guarantee took effect, even if the demand for payment is made after that date.
4. <a id="p125242"></a>For the purpose of this undertaking, the undersigned gives his or her address for service <13> in each of the other countries referred to in point 1 as


| <a id="p125243"></a>Country | <a id="p125244"></a>Surname and forenames, or name of firm, and full address |
| --- | --- |
|  |  |
|  |  |
|  |  |
|  |  |
|  |  |
|  |  |
|  |  |


<a id="p125245"></a>The undersigned acknowledges that all correspondence and notices and any formalities or procedures relating to this undertaking addressed to or effected in writing at one of his or her addresses for services shall be accepted as duly delivered to him or her.
<a id="p125246"></a>The undersigned acknowledges the jurisdiction of the courts of the places where he or she has an address for service.
<a id="p125247"></a>The undersigned undertakes not to change his or her address for service or, if he or she has to change one or more of those addresses, to inform the office of guarantee in advance.
Done at ...................................................................
on ........................................................................
...........................................................................
                             (Signature) <14>

<a id="p125248"></a>                  II. Approval by the office of guarantee

Office of guarantee ................................................... ...
Guarantor's undertaking accepted on ................................... ...
...........................................................................
                                                      (Stamp and Signature)

<a id="p125249"></a>

---

<a id="p125250"></a><1> Surname and forename or name of the firm.
<a id="p125251"></a><2> Full address.
<a id="p125252"></a><3> Delete the name/names of the country/countries on whose territory the guarantee may not be used.
<a id="p125253"></a><4> Pursuant to the Protocol on Ireland/Northern Ireland of the Agreement on the withdrawal of the United Kingdom of Great Britain and Northern Ireland from the European Union and the European Atomic Energy Community, Northern Ireland is to be considered as part of the European Union for the purposes of this guarantee. Therefore, a guarantor established in the customs territory of the European Union shall indicate an address for service or appoint an agent in Northern Ireland if the guarantee may be used therein. However, if a guarantee, in the context of common transit, is made valid in the European Union and in the United Kingdom, a single address for service or an appointed agent in the United Kingdom may cover all parts of the United Kingdom, including Northern Ireland.
<a id="p125254"></a><5> The references to the Principality of Andorra and the Republic of San Marino shall apply solely to Union transit operations.
<a id="p125255"></a><6> Surname and forename or name of the firm, and full address of the person providing the guarantee.
<a id="p125256"></a><7> Applicable with respect to the other charges due in connection with the import or export of the goods where the guarantee is used for the placing of goods under the Union/common transit procedure or may be used in more than one Member State or one Contracting Party.
<a id="p125257"></a><8> Delete what does not apply.
<a id="p125258"></a><9> Delete what does not apply.
<a id="p125259"></a><10> Procedures other than common transit apply solely in the European Union.
<a id="p125260"></a><11> Procedures other than common transit apply solely in the European Union.
<a id="p125261"></a><12> For amounts declared in a customs declaration for the end-use procedure.
<a id="p125262"></a><13> If, in the law of the country, there is no provision for address for service the guarantor shall appoint, in this country, an agent authorised to receive any communications addressed to him and the acknowledgement in the second subparagraph and the undertaking in the fourth subparagraph of paragraph 4 must be made to correspond. The courts of the place in which the addresses for service of the guarantor or of his agents are situated shall have jurisdiction in disputes concerning this guarantee.
<a id="p125263"></a><14> The person signing the document must enter the following, by hand, before his or her signature: "Guarantee for the amount of ..." (the amount being written out in letters).


<a id="p125264"></a>Annex 32-06

<a id="p125265"></a>**INDIVIDUAL GUARANTEE VOUCHER**

<a id="p125266"></a>Union/common transit

<a id="p125267"></a>Front


<table>
<colgroup><col width="50%"><col width="28%"><col width="22%"></colgroup>
<tr><td colspan="2"><a id="p125268"></a>TC32 - INDIVIDUAL GUARANTEE VOUCHER</td><td><a id="p125269"></a>A 000 000</td></tr>
<tr><td colspan="3"><a id="p125270"></a>Issued by .................................................................................................................................<br>................................................................................................................................................<br>(name and address of individual or company)<br>(undertaking of the guarantor accepted on ................................................................................<br>by the customs office of guarantee of ........................................................................................</td></tr>
<tr><td colspan="3"><a id="p125271"></a>This voucher, issued on ........................ is valid for an amount of up to EUR 10 000 for a Union/common transit operation beginning not later than ...........................................................<br>and in respect of which the holder of the procedure is ...............................................................<br>................................................................................................................................................<br>(name and address of individual or company)</td></tr>
<tr><td><a id="p125272"></a>.....................................................................<br>(Signature of the holder of the procedure) &lt;*&gt;</td><td colspan="2"><a id="p125273"></a>.....................................................................<br>(Signature and stamp of guarantor)</td></tr>
<tr><td colspan="3"><a id="p125274"></a>--------------------------------<br>&lt;*&gt; Signature optional.</td></tr>
</table>


<a id="p125275"></a>Back


<table>
<colgroup><col width="51%"><col width="49%"></colgroup>
<tr><td colspan="2"><a id="p125276"></a>To be completed by the customs office of departure<br>Transit operation effected under document T1, T2, T2F &lt;*&gt;<br>Registered on ............................................ under No .............................................................<br>by the customs office ..............................................................................................................</td></tr>
<tr><td><a id="p125277"></a>.....................................................................<br>(Official stamp)</td><td><a id="p125278"></a>...................................................................<br>(Signature)</td></tr>
<tr><td colspan="2"><a id="p125279"></a>--------------------------------<br>&lt;*&gt; Delete as necessary.</td></tr>
</table>


<a id="p125280"></a>Technical requirements for voucher.
<a id="p125281"></a>The voucher shall be printed on paper free of mechanical pulp, dressed for writing purposes and weighing at least 55 g/m2. It shall have a printed guilloche pattern background in red so as to reveal any falsification by mechanical or chemical means. The paper shall be white.
<a id="p125282"></a>The format shall be 148 by 105 millimetres.
<a id="p125283"></a>The voucher shall show the name and address of the printer, or a mark by which it may be identified, and an identification number.


<a id="p125284"></a>Annex 33-03

<a id="p125285"></a>**MODEL OF THE INFORMATION MEMO ON THE CLAIM FOR PAYMENT**
**TO THE GUARANTEEING ASSOCIATION OF THE DEBT IN TRANSIT**
PROCEDURE UNDER ATA/e-ATA CARNET

<a id="p125286"></a>Letter heading of the coordination office initiating the dispute
<a id="p125287"></a>Addressee: coordinating office covering the offices of temporary importation, or other coordinating office

<a id="p125288"></a>**SUBJECT: ATA CARNET - SUBMISSION OF CLAIM**

<a id="p125289"></a>Be informed that a claim for payment of duties and taxes under the ATA Convention/the Istanbul Convention <1> was sent on ... .. <2> to our guaranteeing association in respect of:
1. <a id="p125290"></a>ATA carnet No:
2. <a id="p125291"></a>Issued by the Chamber of Commerce of:
<a id="p125292"></a>City:
<a id="p125293"></a>Country:
3. <a id="p125294"></a>On behalf of:
<a id="p125295"></a>Holder:
<a id="p125296"></a>Address:
4. <a id="p125297"></a>Expiry date of carnet:
5. <a id="p125298"></a>Date set for re-exportation <3>:
6. <a id="p125299"></a>Number of transit/import voucher <4>:
7. <a id="p125300"></a>Date of endorsement of voucher:
<a id="p125301"></a>Signature and stamp of the issuing coordinating office.
<a id="p125302"></a>.............................................................

<a id="p125303"></a>

---

<a id="p125304"></a><1> Article 7 of the ATA Convention, Brussels, 6 December 1961/Article 9 of Annex A to the Istanbul Convention, 26 June 1990.
<a id="p125305"></a><2> Enter date of dispatch.
<a id="p125306"></a><3> Details to be obtained from the undischarged transit or temporary admission voucher or, if no voucher is available, from the information available to the issuing coordinating office.
<a id="p125307"></a><4> Delete whichever is not applicable.


<a id="p125308"></a>Annex 33-04

<a id="p125309"></a>**TAXATION FORM FOR CALCULATION OF DUTIES AND TAXES RESULTING**
**FROM THE CLAIM FOR PAYMENT TO THE GUARANTEEING ASSOCIATION**
OF THE DEBT IN TRANSIT PROCEDURE UNDER ATA/e-ATA CARNET

                               TAXATION FORM

Of ................................ No ....................................
The following particulars must be given in the order shown:
1. ATA carnet No:
   ........................................................................
2. Number of transit/import voucher <*>:
   ........................................................................
   ........................................................................
3. Date of endorsement of voucher:
   ........................................................................
4. Holder and address:
   ........................................................................
5. Chamber of commerce:
   ........................................................................
6. Country of origin:
   ........................................................................
7. Date of expiry of carnet:
   ........................................................................
8. Date set for the re-exportation of the goods:
   ........................................................................
9. Customs office of entry:
   ........................................................................
10. Customs office of temporary admission:
   ........................................................................
11. Trade description of goods:
   ........................................................................
   ........................................................................
   ........................................................................
12. CN code:
   ........................................................................
13. Number of pieces:
   ........................................................................
14. Weight or volume:
   ........................................................................
15. Value:
   ........................................................................
16. Breakdown of duties and taxes:
   ........................................................................
   Type Taxable amount Rate Amount Exchange rate
   Total:
   (Total in words: ......................................................)
17. Customs office:
   ........................................................................
   Place and date:
   ........................................................................
   Signature                  Stamp

<a id="p125310"></a>

---

<a id="p125311"></a><*> Delete whichever is inapplicable.


<a id="p125312"></a>Annex 33-05

<a id="p125313"></a>**MODEL OF DISCHARGE INDICATING THAT CLAIM PROCEEDINGS HAVE**
**BEEN INITIATED WITH RESPECT TO THE GUARANTEEING ASSOCIATION**
**IN THE MEMBER STATE WHERE THE CUSTOMS DEBT IS INCURRED**
IN TRANSIT PROCEDURE UNDER ATA/e-ATA CARNET

<a id="p125314"></a>Letter heading of the coordinating office of the second Member State submitting the claim
<a id="p125315"></a>Addressee: coordinating office of the first Member State submitting the original claim.

<a id="p125316"></a>**SUBJECT: ATA CARNET - DISCHARGE**

<a id="p125317"></a>Be informed that a claim for payment of duties and taxes under the ATA Convention/Istanbul Convention <1> was sent on ... <2> to our guaranteeing association in respect of:
1. <a id="p125318"></a>ATA carnet No:
2. <a id="p125319"></a>Issued by the Chamber of Commerce of:
<a id="p125320"></a>City:
<a id="p125321"></a>Country:
3. <a id="p125322"></a>On behalf of:
<a id="p125323"></a>Holder:
<a id="p125324"></a>Address:
4. <a id="p125325"></a>Expiry date of the carnet:
5. <a id="p125326"></a>Date set for re-exportation <3>:
6. <a id="p125327"></a>Number of transit/import voucher <4>:
7. <a id="p125328"></a>Date of endorsement of voucher:
<a id="p125329"></a>The present note discharges your responsibility in this file.
<a id="p125330"></a>Signature and stamp of issuing coordinating office.

<a id="p125331"></a>

---

<a id="p125332"></a><1> Article 7 of the ATA Convention, Brussels, 6 December 1961/Article 9 of Annex A to the Istanbul Convention, 26 June 1990.
<a id="p125333"></a><2> Enter date of dispatch.
<a id="p125334"></a><3> Details to be obtained from the undischarged transit or temporary admission voucher or, if no voucher is available, from the information available to the issuing coordinating office.
<a id="p125335"></a><4> Delete whichever is not applicable.


<a id="p125336"></a>Annex 33-06

<a id="p125337"></a>**REQUEST**
**FOR SUPPLEMENTARY INFORMATION WHERE GOODS ARE SITUATED**
**IN ANOTHER MEMBER STATE**

<a id="p125338"></a>**EUROPEAN COMMISSION**
<a id="p125339"></a>**REQUEST FOR EXAMINATION**
<a id="p125340"></a>1
1. <a id="p125341"></a>Name and address of decision-taking customs authority

2. <a id="p125342"></a>Repayment/remission of duties


File reference of decision-taking customs authority
<a id="p125343"></a>Original
3. <a id="p125344"></a>Name and address of the customs office of the Member State where the goods are situated
4. <a id="p125345"></a>Application of Article 175
5. <a id="p125346"></a>Location of goods <1>
6. <a id="p125347"></a>Name and full address of person from whom the information may be obtained or who can assist the customs office of the Member State where the goods are situated


<a id="p125348"></a>1
7. <a id="p125349"></a>List of documents attached

8. <a id="p125350"></a>Purpose of the request

that the following be obtained:

that the following examination be carried out:

9. <a id="p125351"></a>Decision-taking customs authority

Place and date

<a id="p125352"></a>Signature:
<a id="p125353"></a>Stamp


<table>
<colgroup><col width="6%"><col width="47%"><col width="8%"><col width="39%"></colgroup>
<tr><td rowspan="4"></td><td colspan="2"><a id="p125354"></a>REPLY OF MONITORING CUSTOMS OFFICE &lt;2&gt;</td><td><a id="p125355"></a>ACKNOWLEDGEMENT OF RECEIPT &lt;2&gt;</td></tr>
<tr><td colspan="3"><a id="p125356"></a>10. Information obtained</td></tr>
<tr><td colspan="3"><a id="p125357"></a>11. Result of examination carried out</td></tr>
<tr><td><a id="p125358"></a>12. Place and date:</td><td colspan="2"><a id="p125359"></a>13. Signature and official stamp:</td></tr>
</table>


<a id="p125360"></a>**EUROPEAN COMMISSION**
<a id="p125361"></a>**REQUEST FOR EXAMINATION**
<a id="p125362"></a>1
1. <a id="p125363"></a>Name and address of decision-taking customs authority

2. <a id="p125364"></a>Repayment/remission of duties


File reference of decision-taking customs authority
<a id="p125365"></a>Copy
3. <a id="p125366"></a>Name and address of the customs office of the Member State where the goods are situated


4. <a id="p125367"></a>Application of Article 175
5. <a id="p125368"></a>Location of goods <1>
6. <a id="p125369"></a>Name and full address of person from whom the information may be obtained or who can assist the customs office of the Member State where the goods are situated

<a id="p125370"></a>1
7. <a id="p125371"></a>List of documents attached

8. <a id="p125372"></a>Purpose of the request

that the following be obtained:

that the following examination be carried out:

9. <a id="p125373"></a>Decision-taking customs authority

Place and date

<a id="p125374"></a>Signature:
<a id="p125375"></a>Stamp


<table>
<colgroup><col width="6%"><col width="47%"><col width="8%"><col width="39%"></colgroup>
<tr><td rowspan="4"></td><td colspan="2"><a id="p125376"></a>REPLY OF MONITORING CUSTOMS OFFICE &lt;2&gt;</td><td><a id="p125377"></a>ACKNOWLEDGEMENT OF RECEIPT &lt;2&gt;</td></tr>
<tr><td colspan="3"><a id="p125378"></a>10. Information obtained</td></tr>
<tr><td colspan="3"><a id="p125379"></a>11. Result of examination carried out</td></tr>
<tr><td><a id="p125380"></a>12. Place and date:</td><td colspan="2"><a id="p125381"></a>13. Signature and official stamp:</td></tr>
</table>


<a id="p125382"></a>

---

<a id="p125383"></a><1> Complete only if applicable.
<a id="p125384"></a><2> Delete if appropriate. The monitoring customs office shall give an acknowledgement of receipt if it is unable to give effect to the request within 30 days of the date of receipt thereof. Acknowledgement of receipt shall be made on a copy of this document.


<a id="p125385"></a>Annex 33-07

<a id="p125386"></a>**EUROPEAN UNION REPAYMENT OR REMISSION OF DUTY**

1. <a id="p125387"></a>Name and address of the person concerned
2. <a id="p125388"></a>Application of Article 96 of [Delegated Regulation (EU) 2015/2446 supplementing Regulation (EU) No 952/2013] and 176

3. <a id="p125389"></a>Name and address of customs office which granted repayment/remission
4. <a id="p125390"></a>Reference to the decision granting repayment/remission

5. <a id="p125391"></a>Name and address of monitoring customs office

6. <a id="p125392"></a>Description of the goods, number and type
7. <a id="p125393"></a>CN code of the goods

8. <a id="p125394"></a>Quantity or net mass of the goods

9. <a id="p125395"></a>Customs value of the goods
10. <a id="p125396"></a>Monitoring customs office
Certification for the granting of repayment or remission of duties
This is to certify that in accordance with the decision referred to in Box 4 the goods described above were on:
................................................................ (date) (dd/mm/yyyy)

<a id="p125397"></a>


| to a charity specified |
| --- |

th

<a id="p125398"></a>


| customs procedure |
| --- |

     decision
<a id="p125399"></a>Customs declaration references, if any: ..................................................................................
On this date the goods fulfilled the conditions laid down for repayment or remission of duty <*>
11. <a id="p125400"></a>Place and date

Signature
<a id="p125401"></a>Stamp


<a id="p125402"></a>

---

<a id="p125403"></a><*> Where the monitoring customs office finds that the goods no longer satisfy those conditions it shall delete this sentence and records its findings overleaf under the heading "Observations".

<a id="p125404"></a>Observations


|  |
| --- |


<a id="p125405"></a>Annex 51-01

<a id="p125406"></a>**STATUS REGISTRATION DOCUMENT**


```text
┌─ ─ ─ ─ ─ ─ ─ ─ ─ ─ ─ ─ ─ ─ ─ ─ ─ ─ ─ ─ ─ ─ ─ ─ ─ ─ ─ ─ ─ ─ ─ ─ ─ ─ ─ ─ ─┐
                 EUROPEAN UNION          ┌──────────────┐ A MRN
│               ┌────────────────────────┤1 STATUS CODE │                 │
                │2 Applicant        No   │              │
│               │┌─┐                     ├──────────────┤                 │
                ││ │                     │3 Forms       │
│               │└─┘                     │        │     │                 │
                │                        ├────────┴─────┤
│               │                        │5 Items       │                 │
                │                        │              │
│               ├────────────────────────┼──────────────┴────────────────┐│
                │14 Representative  No   │      STATUS REGISTRATION      │
│               │                        │            DOCUMENT           ││
  ──────────────┼────────────────────────┴─────┬────────────┬────────────┤
│31 Packages    │Marks and numbers - Container │32 Item     │33 Commodity││
    and         │No(s) - Number and kind       │        │No │   Code     │
│   description │                              └────────┴───┤            ││
    of goods    │                                           ├────────────┤
│               │                                           │35 Gross    ││
                │                                           │  mass (kg) │
│               │                                           │            ││
                │                                           ├────────────┤
│               │                                           │38 Net mass ││
                │                                           │   (kg)     │
│               │                                           │            ││
 ───────────────┼───────────────────────────────────────────┴────────────┤
│44 Additional  │                                                        ││
    information/│                                                        │
│   Documents   │                                                        ││
    produced/   │                                                        │
│   Certificates│                                                        ││
    and         │                                                        │
│   authori     │                                                        ││
    zations     │                                                        │
│ ──────────────┼──────────────────────────────┬────────────┬────────────┤│
 31 Packages    │Marks and numbers - Container │32 Item     │33 Commodity│
│   and         │No(s) - Number and kind       │        │No │   Code     ││
    description │                              └────────┴───┤            │
│   of goods    │                                           ├────────────┤│
                │                                           │35 Gross    │
│               │                                           │  mass (kg) ││
                │                                           │            │
│               │                                           ├────────────┤│
                │                                           │38 Net mass │
│               │                                           │   (kg)     ││
                │                                           │            │
│ ──────────────┼───────────────────────────────────────────┴────────────┤│
 44 Additional  │                                                        │
│   information/│                                                        ││
    Documents   │                                                        │
│   produced/   │                                                        ││
    Certificates│                                                        │
│   and         │                                                        ││
    authori    │                                                        │
│   zations     │                                                        ││
  ──────────────┼──────────────────────────────┬────────────┬────────────┤
│31 Packages    │Marks and numbers - Container │32 Item     │33 Commodity││
    and         │No(s) - Number and kind       │        │No │   Code     │
│   description │                              └────────┴───┤            ││
    of goods    │                                           ├────────────┤
│               │                                           │35 Gross    ││
                │                                           │  mass (kg) │
│               │                                           │            ││
                │                                           ├────────────┤
│               │                                           │38 Net mass ││
                │                                           │   (kg)     │
│               │                                           │            ││
 ───────────────┼───────────────────────────────────────────┴────────────┤
│44 Additional  │                                                        ││
    information/│                                                        │
│   Documents   │                                                        ││
    produced/   │                                                        │
│   Certificates│                                                        ││
    and         │                                                        │
│   authori    │                                                        ││
    zations     │                                                        │
│ ──────────────┴────────────────────────┬───────────────────────────────┘│
                                         │54 Place and date:
│                                        │                                │
                                         │Signature and name of
│                                        │applicant/representative:       │
                                         │
└─ ─ ─ ─ ─ ─ ─ ─ ─ ─ ─ ─ ─ ─ ─ ─ ─ ─ ─ ─ ─ ─ ─ ─ ─ ─ ─ ─ ─ ─ ─ ─ ─ ─ ─ ─ ─┘
```


<a id="p125407"></a>Annex 61-02

<a id="p125408"></a>**BANANA WEIGHING CERTIFICATES - SPECIMEN**

1. <a id="p125409"></a>Authorized weigher name

2. <a id="p125410"></a>Weighing certificate issuance date and number

3. <a id="p125411"></a>Trader reference

4. <a id="p125412"></a>Identity of means of transport at arrival
5. <a id="p125413"></a>Country of origin

6. <a id="p125414"></a>Number and type of packaging
7. <a id="p125415"></a>Total established net weight

8. <a id="p125416"></a>Brand(s)

9. <a id="p125417"></a>Inspected units of packed bananas (Enter gross weight for each weighed unit)
<a id="p125418"></a>1

<a id="p125419"></a>8

<a id="p125420"></a>15

<a id="p125421"></a>2

<a id="p125422"></a>9

<a id="p125423"></a>16

<a id="p125424"></a>3

<a id="p125425"></a>10

<a id="p125426"></a>17

<a id="p125427"></a>4

<a id="p125428"></a>11

<a id="p125429"></a>18

<a id="p125430"></a>5

<a id="p125431"></a>12

<a id="p125432"></a>19

<a id="p125433"></a>6

<a id="p125434"></a>13

<a id="p125435"></a>20

<a id="p125436"></a>7

<a id="p125437"></a>14

<a id="p125438"></a>21

10. <a id="p125439"></a>Total gross weight of inspected units of packed bananas:

11. <a id="p125440"></a>Number of units of packed bananas inspected:

12. <a id="p125441"></a>Average gross weight:

13. <a id="p125442"></a>Tare:

14. <a id="p125443"></a>Average net weight per unit of packed bananas:

15. <a id="p125444"></a>Signature and stamp of the authorized weigher

16. Place and date:


<a id="p125445"></a>Annex 61-03

<a id="p125446"></a>**BANANA WEIGHING CERTIFICATE - PROCEDURE**

<a id="p125447"></a>For the purposes of Article 252, the net weight of each consignment of fresh bananas shall be determined by authorised weighers at any place of unloading in accordance with the procedure laid down below.
<a id="p125448"></a>For the purposes of this Annex and of Article 252, the following definitions shall apply:
<a id="p125449"></a>(a) "net weight of fresh bananas" means the weight of the bananas themselves without packing materials and packing containers of any kind;
<a id="p125450"></a>(b) "consignment of fresh bananas" means the consignment comprising the total quantity of fresh bananas loaded on a single means of transport and shipped by a single exporter to one or more consignees;
<a id="p125451"></a>(c) "place of unloading" means any place where a consignment of fresh bananas can be unloaded or removed to under a customs procedure, or in the case of containerised traffic, where the container is offloaded from the ship, or aircraft, or other principal means of transport or where the container is unpacked.
1. <a id="p125452"></a>A sample of units of packed bananas shall be selected for each type of packaging and for each origin. The sample of units of packed bananas to be weighed shall constitute a representative sample of the consignment of fresh bananas. It shall contain at least the quantities indicated below:


| <a id="p125453"></a>Number of units of packed bananas (by type of packaging and origin) | <a id="p125454"></a>Number of units of packed bananas to be inspected |
| --- | --- |
| <a id="p125455"></a>- up to 400 | <a id="p125456"></a>3 |
| <a id="p125457"></a>- from 401 to 700 | <a id="p125458"></a>4 |
| <a id="p125459"></a>- from 701 to 1 100 | <a id="p125460"></a>6 |
| <a id="p125461"></a>- from 1 101 to 2 200 | <a id="p125462"></a>8 |
| <a id="p125463"></a>- from 2 201 to 4 400 | <a id="p125464"></a>10 |
| <a id="p125465"></a>- from 4 401 to 6 600 | <a id="p125466"></a>12 |
| <a id="p125467"></a>- more than 6 600 | <a id="p125468"></a>14 |


2. <a id="p125469"></a>The net weight shall be determined as follows:
<a id="p125470"></a>(a) by weighing each unit of packed bananas to be inspected (gross weight);
<a id="p125471"></a>(b) by opening at least one unit of packed bananas, then calculating the weight of the packaging;
<a id="p125472"></a>(c) the weight of that packaging shall be accepted for all packaging of the same type and origin, and shall be deducted from the weight of all the units of packed bananas weighed;
<a id="p125473"></a>(d) the average net weight per unit of packed bananas thus established for each type and origin, based on the weight of the samples checked, shall be accepted as the basis for determining the net weight of the consignment of fresh bananas.
3. <a id="p125474"></a>Where the customs authority does not check the banana weighing certificates contemporaneously, the net weight declared on such certificates shall be acceptable to customs authorities provided that the difference is not more or less than 1% between the declared net weight and the average net weight established by customs authorities.
4. <a id="p125475"></a>The banana weighing certificate shall be presented to the customs office at which the declaration for release for free circulation is submitted. The customs authorities shall apply the results of the sampling shown on the banana weighing certificate to the whole consignment of fresh bananas to which that certificate relates.


<a id="p125476"></a>Annex 62-02

<a id="p125477"></a>**INF 3 - RETURNED GOODS INFORMATION SHEET**


<table>
<colgroup><col width="16%"><col width="13%"><col width="5%"><col width="14%"><col width="6%"><col width="6%"><col width="5%"><col width="14%"><col width="8%"><col width="14%"></colgroup>
<tr><td colspan="10"><a id="p125478"></a>EUROPEAN UNION</td></tr>
<tr><td colspan="5"><a id="p125479"></a>1. Exporter</td><td colspan="5"><a id="p125480"></a>No<br>INF 3<br>ORIGINAL</td></tr>
<tr><td colspan="5"><a id="p125481"></a>2. Consignee at time of exportation</td><td colspan="5"><a id="p125482"></a>RETURNED GOODS<br>INFORMATION SHEET</td></tr>
<tr><td colspan="7"><a id="p125483"></a>IMPORTANT<br>1. Before completing this form the person must refer to the provisions relating to returned goods as well as to the notes appearing on the reverse of this form.</td><td colspan="3"><a id="p125484"></a>3. Country to which goods consigned at time of exportation</td></tr>
<tr><td colspan="10"><a id="p125485"></a>2. The person concerned must complete by typewriter or by hand in block letters to boxes 1 to 11 this form.<br>3. When this information sheet is completed for goods whose exportation has been effected within the framework of the common agricultural policy under an export licence or advance fixing certificate or for goods liable to the benefit of refunds or other amounts provided for on exportation, it is valid only if box B, and where necessary box A, below have been endorsed by the competent authorities.<br>4. This information sheet must be presented to the customs office of reimportation.</td></tr>
<tr><td colspan="7"><a id="p125486"></a>4. Number, kind, marks and numbers of packages and description of goods exported</td><td colspan="2"><a id="p125487"></a>5. Gross weight</td><td></td></tr>
<tr><td colspan="6"></td><td colspan="2"><a id="p125488"></a>6. Net weight</td><td colspan="2"><a id="p125489"></a>7. Statistical value</td></tr>
<tr><td colspan="7"><a id="p125490"></a>8. Quantity for which information sheet is required</td><td colspan="3" rowspan="2"><a id="p125491"></a>9. CN Code</td></tr>
<tr><td colspan="2"><a id="p125492"></a>(a) in figures:</td><td colspan="5"><a id="p125493"></a>(b) in words:</td></tr>
<tr><td colspan="3"><a id="p125494"></a>A. ENDORSEMENT BY COMPETENT<br>AUTHORITIES FOR EXPORT LICENCES OR ADVANCE FIXING CERTIFICATES<br>- Regulations or licences or certificates observed</td><td colspan="4"><a id="p125495"></a>B. ENDORSEMENT BY COMPETENT AUTHORITIES FOR GRANT OF REFUNDS OR OTHER AMOUNTS PROVIDED FOR ON EXPORTATION<br>- No refund or other amounts granted on exportation &lt;1&gt;<br>- Refunds and other amounts granted on exportation repaid for .... (quantity) &lt;1&gt;<br>- Entitlement to payment of refunds or other amounts granted on exportation cancelled for (quantity) ......... &lt;1&gt;</td><td colspan="3" rowspan="2"><a id="p125496"></a>10. Additional information relating to the goods<br>(a) Export document<br>Type<br>Ref. No<br>dated<br>(b) Goods exported in completion of an inward processing operation &lt;1&gt;<br>(c) Goods which have been released for free circulation for a specific use &lt;1&gt;<br>(d) Goods originating in the Member States or third-country goods in free circulation &lt;1&gt;</td></tr>
<tr><td><a id="p125497"></a>At ............,<br>(Signature)</td><td colspan="2"><a id="p125498"></a>on ...............<br>(Stamp)</td><td><a id="p125499"></a>At ............,<br>(Signature)</td><td colspan="3"><a id="p125500"></a>on ...............<br>(Stamp)</td></tr>
<tr><td colspan="6"><a id="p125501"></a>C. ENDORSEMENT BY THE OFFICE COMPLETING THE CUSTOMS EXPORT FORMALITIES<br>Information given in boxes 1 to 10 certified exact Identification measures taken</td><td colspan="4"><a id="p125502"></a>11. REQUEST OF EXPORTER<br>The undersigned, being the exporter &lt;1&gt;<br>On behalf of the exporter &lt;1&gt;<br>Requests the issue of this information sheet for the purposes of the reimportation of the goods described therein</td></tr>
<tr><td colspan="2"><a id="p125503"></a>At ...........................,<br>(Signature)</td><td colspan="4"><a id="p125504"></a>on ..........................<br>(Stamp)</td><td colspan="2"><a id="p125505"></a>At ...............,<br>(Signature)</td><td colspan="2"><a id="p125506"></a>on ..................<br>(Stamp)</td></tr>
</table>


<a id="p125507"></a>

---

<a id="p125508"></a><1> Delete as necessary.


<table>
<colgroup><col width="14%"><col width="9%"><col width="21%"><col width="25%"><col width="2%"><col width="22%"><col width="7%"></colgroup>
<tr><td></td><td colspan="5"><a id="p125509"></a>FULL NAME AND ADDRESS OF CUSTOMS OFFICE OF EXPORTATION</td><td></td></tr>
<tr><td></td><td colspan="6"></td></tr>
<tr><td colspan="7"><a id="p125510"></a>NOTES</td></tr>
<tr><td><a id="p125511"></a>Box 1:</td><td colspan="6"><a id="p125512"></a>Give the name or trade name and full address including Member State.</td></tr>
<tr><td><a id="p125513"></a>Box 4:</td><td colspan="6"><a id="p125514"></a>Give exact details of the goods according to their normal commercial description or according to their tarif description. The description must correspond with that used in the export document.</td></tr>
<tr><td><a id="p125515"></a>Boxes 5 and 6:</td><td colspan="6"><a id="p125516"></a>Give the guantity appearing in the export document.</td></tr>
<tr><td><a id="p125517"></a>Box 7:</td><td colspan="6"><a id="p125518"></a>Give the statistical value at the time of exportation in the currency of the Member State of exportation.</td></tr>
<tr><td><a id="p125519"></a>Box 8:</td><td colspan="6"><a id="p125520"></a>Give details of net weight, volume, etc. which the person concerned wishes to reimport.</td></tr>
<tr><td><a id="p125521"></a>Box 10 (c):</td><td colspan="6"><a id="p125522"></a>This item relates to goods which have been released for free circulation in the Community, benefiting from total or partial relief from import duties by reason of their use tor specific purposes.</td></tr>
<tr><td><a id="p125523"></a>Box 10 (d):</td><td colspan="6"><a id="p125524"></a>This item relates to the situation of goods at the time of their exportation.</td></tr>
<tr><td colspan="7"></td></tr>
<tr><td colspan="7"><a id="p125525"></a>REQUEST BY THE OFFICE OF REIMPORTATION<br>The office of reimportation indicated below requests:<br>- verification of the authenticity of this information sheet and the correctness of the information therein &lt;*&gt;,<br>- the following information to be supplied &lt;*&gt;:<br>&lt;*&gt; Delete as necessary.</td></tr>
<tr><td colspan="3" rowspan="2"><a id="p125526"></a>Full name and address of office of reimportation</td><td colspan="4"><a id="p125527"></a>At ......................., on ............................</td></tr>
<tr><td colspan="2"><a id="p125528"></a>(Signatiure)</td><td colspan="2"><a id="p125529"></a>(Stamp)</td></tr>
<tr><td colspan="7"></td></tr>
<tr><td colspan="7"><a id="p125530"></a>REPLY OF THE COMPETENT AUTHORITIES<br>This information sheet is authentic and the details contained therein are exact &lt;*&gt;.<br>This information sheet gives rise to the following comments &lt;*&gt;:<br>Other information required &lt;*&gt;<br>&lt;*&gt; Delete as necessary.</td></tr>
<tr><td colspan="3" rowspan="2"><a id="p125531"></a>Full name and address of the competent authorities</td><td colspan="4"><a id="p125532"></a>At ......................., on ............................</td></tr>
<tr><td><a id="p125533"></a>(Signatiure)</td><td colspan="3"><a id="p125534"></a>(Stamp)</td></tr>
<tr><td colspan="7"></td></tr>
<tr><td colspan="7"><a id="p125535"></a>REIMPORTATION</td></tr>
<tr><td colspan="2"><a id="p125536"></a>Quanity reimported</td><td colspan="5"><a id="p125537"></a>Reference number, date and type of reimportation document<br>Signature and stamp of office of reimportation</td></tr>
<tr><td colspan="2"></td><td colspan="5"></td></tr>
</table>


<table>
<colgroup><col width="15%"><col width="13%"><col width="5%"><col width="14%"><col width="4%"><col width="7%"><col width="5%"><col width="10%"><col width="4%"><col width="8%"><col width="14%"></colgroup>
<tr><td colspan="11"><a id="p125538"></a>EUROPEAN UNION</td></tr>
<tr><td colspan="4"><a id="p125539"></a>1. Exporter</td><td colspan="7"><a id="p125540"></a>No<br>INF 3<br>COPY</td></tr>
<tr><td colspan="4"><a id="p125541"></a>2. Consignee at time of exportation</td><td colspan="7"><a id="p125542"></a>RETURNED GOODS<br>INFORMATION SHEET</td></tr>
<tr><td colspan="7"><a id="p125543"></a>IMPORTANT<br>1. Before completing this form the person must refer to the provisions relating to returned goods as well as to the notes appearing on the reverse of this form.</td><td colspan="4"><a id="p125544"></a>3. Country to which goods consigned at time of exportation</td></tr>
<tr><td colspan="11"><a id="p125545"></a>2. The person concerned must complete by typewriter or by hand in block letters to boxes 1 to 11 this form.<br>3. When this information sheet is completed for goods whose exportation has been effected within the framework of the common agricultural policy under an export licence or advance fixing certificate or for goods liable to the benefit of refunds or other amounts provided for on exportation, it is valid only if box B, and where necessary box A, below have been endorsed by the competent authorities.<br>4. This information sheet must be presented to the customs office of reimportation.</td></tr>
<tr><td colspan="7"><a id="p125546"></a>4. Number, kind, marks and numbers of packages and description of goods exported</td><td colspan="3"><a id="p125547"></a>5. Gross weight</td><td></td></tr>
<tr><td colspan="5"></td><td colspan="3"><a id="p125548"></a>6. Net weight</td><td colspan="3"><a id="p125549"></a>7. Statistical value</td></tr>
<tr><td colspan="5"><a id="p125550"></a>8. Quantity for which information sheet is required</td><td colspan="2" rowspan="2"></td><td colspan="4" rowspan="2"><a id="p125551"></a>9. CN Code</td></tr>
<tr><td colspan="2"><a id="p125552"></a>(a) in figures:</td><td colspan="3"><a id="p125553"></a>(b) in words:</td></tr>
<tr><td colspan="3"><a id="p125554"></a>A. ENDORSEMENT BY COMPETENT<br>AUTHORITIES FOR EXPORT LICENCES OR ADVANCE FIXING CERTIFICATES<br>- Regulations or licences or certificates observed</td><td colspan="4"><a id="p125555"></a>B. ENDORSEMENT BY COMPETENT AUTHORITIES FOR GRANT OF REFUNDS OR OTHER AMOUNTS PROVIDED FOR ON EXPORTATION<br>- No refund or other amounts granted on exportation &lt;1&gt;<br>- Refunds and other amounts granted on exportation repaid for ... (quantity) &lt;1&gt;<br>- Entitlement to payment of refunds or other amounts granted on exportation cancelled for (quantity) ............ &lt;1&gt;</td><td colspan="4" rowspan="2"><a id="p125556"></a>10. Additional information relating to the goods<br>(a) Export document<br>Type<br>Ref. No<br>dated<br>(b) Goods exported in completion of an inward processing operation &lt;1&gt;<br>(c) Goods which have been released for free circulation for a specific use &lt;1&gt;<br>(d) Goods originating in the Member States or third-country goods in free circulation &lt;1&gt;</td></tr>
<tr><td><a id="p125557"></a>At ............,<br>(Signature)</td><td colspan="2"><a id="p125558"></a>on ...............<br>(Stamp)</td><td><a id="p125559"></a>At ............,<br>(Signature)</td><td colspan="3"><a id="p125560"></a>on ...............<br>(Stamp)</td></tr>
<tr><td colspan="6"><a id="p125561"></a>C. ENDORSEMENT BY THE OFFICE COMPLETING THE CUSTOMS EXPORT FORMALITIES<br>Information given in boxes 1 to 10 certified exact Identification measures taken</td><td colspan="5"><a id="p125562"></a>11. REQUEST OF EXPORTER<br>The undersigned, being the exporter &lt;1&gt;<br>On behalf of the exporter &lt;1&gt;<br>Requests the issue of this information sheet for the purposes of the reimportation of the goods described therein</td></tr>
<tr><td colspan="2"><a id="p125563"></a>At ...........................,<br>(Signature)</td><td colspan="4"><a id="p125564"></a>on ..........................<br>(Stamp)</td><td colspan="3"><a id="p125565"></a>At ...................,<br>(Signature)</td><td colspan="2"><a id="p125566"></a>on ....................<br>(Stamp)</td></tr>
</table>


<a id="p125567"></a>

---

<a id="p125568"></a><1> Delete as necessary.


<table>
<colgroup><col width="14%"><col width="9%"><col width="21%"><col width="25%"><col width="24%"><col width="7%"></colgroup>
<tr><td></td><td colspan="4"><a id="p125569"></a>FULL NAME AND ADDRESS OF CUSTOMS OFFICE OF EXPORTATION</td><td></td></tr>
<tr><td></td><td colspan="5"></td></tr>
<tr><td colspan="6"><a id="p125570"></a>NOTES</td></tr>
<tr><td><a id="p125571"></a>Box 1:</td><td colspan="5"><a id="p125572"></a>Give the name or trade name and full address including Member State.</td></tr>
<tr><td><a id="p125573"></a>Box 4:</td><td colspan="5"><a id="p125574"></a>Give exact details of the goods according to their normal commercial description or according to their tarif description. The description must correspond with that used in the export document.</td></tr>
<tr><td><a id="p125575"></a>Boxes 5 and 6:</td><td colspan="5"><a id="p125576"></a>Give the guantity appearing in the export document.</td></tr>
<tr><td><a id="p125577"></a>Box 7:</td><td colspan="5"><a id="p125578"></a>Give the statistical value at the time of exportation in the currency of the Member State of exportation.</td></tr>
<tr><td><a id="p125579"></a>Box 8:</td><td colspan="5"><a id="p125580"></a>Give details of net weight, volume, etc. which the person concerned wishes to reimport.</td></tr>
<tr><td><a id="p125581"></a>Box 10 (c):</td><td colspan="5"><a id="p125582"></a>This item relates to goods which have been released for free circulation in the Community, benefiting from total or partial relief from import duties by reason of their use tor specific purposes.</td></tr>
<tr><td><a id="p125583"></a>Box 10 (d):</td><td colspan="5"><a id="p125584"></a>This item relates to the situation of goods at the time of their exportation.</td></tr>
<tr><td colspan="6"></td></tr>
<tr><td colspan="6"><a id="p125585"></a>REQUEST BY THE OFFICE OF REIMPORTATION<br>The office of reimportation indicated below requests:<br>- verification of the authenticity of this information sheet and the correctness of the information therein &lt;*&gt;,<br>- the following information to be supplied &lt;*&gt;:<br>&lt;*&gt; Delete as necessary.</td></tr>
<tr><td colspan="3" rowspan="2"><a id="p125586"></a>Full name and address of office of reimportation</td><td colspan="3"><a id="p125587"></a>At ......................., on ............................</td></tr>
<tr><td><a id="p125588"></a>(Signatiure)</td><td colspan="2"><a id="p125589"></a>(Stamp)</td></tr>
<tr><td colspan="6"></td></tr>
<tr><td colspan="6"><a id="p125590"></a>REPLY OF THE COMPETENT AUTHORITIES<br>This information sheet is authentic and the details contained therein are exact &lt;*&gt;.<br>This information sheet gives rise to the following comments &lt;*&gt;:<br>Other information required &lt;*&gt;<br>&lt;*&gt; Delete as necessary.</td></tr>
<tr><td colspan="3" rowspan="2"><a id="p125591"></a>Full name and address of the competent authorities</td><td colspan="3"><a id="p125592"></a>At ......................., on ............................</td></tr>
<tr><td><a id="p125593"></a>(Signatiure)</td><td colspan="2"><a id="p125594"></a>(Stamp)</td></tr>
<tr><td colspan="6"></td></tr>
<tr><td colspan="6"><a id="p125595"></a>REIMPORTATION</td></tr>
<tr><td colspan="2"><a id="p125596"></a>Quanity reimported</td><td colspan="4"><a id="p125597"></a>Reference number, date and type of reimportation document<br>Signature and stamp of office of reimportation</td></tr>
<tr><td colspan="2"></td><td colspan="4"></td></tr>
</table>


<a id="p125598"></a>**NOTE CONCERNING INFORMATION SHEET INF 3**

1. <a id="p125599"></a>The forms shall be printed on white paper, free of mechanical pulp, dressed for writing purposes and shall weigh at least 40 g/m2.
2. <a id="p125600"></a>The size of the forms shall be 210 x 297 mm, a maximum tolerance in the length of between - 5 and 8 mm being allowed; the layout of the forms must be strictly observed, except in respect of the size of boxes 6 and 7.
3. <a id="p125601"></a>Member States shall be responsible for taking the necessary steps to have the forms printed. Each form shall bear an individual serial number, which may be pre-printed.
4. <a id="p125602"></a>The forms shall be printed in one of the official languages of the Union accepted by the competent authorities of the Member State of export. They shall be completed in the same language as that in which they are printed. Where necessary, the competent authorities of the customs office of re-import in which information sheet INF 3 is required to be produced may request its translation into its official language or one of its official languages.


<a id="p125603"></a>Annex 72-01

<a id="p125604"></a>**YELLOW LABEL**


| Goods not fulfilling the conditions laid down in Articles 28 and 29 of the Treaty on the functioning of the European Union | / 23 | \ mm |
| --- | --- | --- |


<a id="p125605"></a>Colour: black letters on a yellow background


<a id="p125606"></a>Annex 72-02

<a id="p125607"></a>**YELLOW LABEL**

                  <─────────────── 49 mm ──────────────>


| Union goods consigned to or from a part of the customs territory of the European Union where the provisions of Council Directive 2006/112/EC or of Council Directive 2008/118/EC do not apply | 2 | 3 mm |
| --- | --- | --- |


<a id="p125608"></a>Colour: black letters on a yellow background


<a id="p125609"></a>Annex 72-03


<table>
<colgroup><col width="12%"><col width="15%"><col width="11%"><col width="62%"></colgroup>
<tr><td colspan="4"><a id="p125610"></a>TC11 - RECEIPT</td></tr>
<tr><td colspan="4"><a id="p125611"></a>The customs office of destination at .............. (place, name and reference number)<br>hereby certifies that the transit declaration T1, T2, T2F &lt;1&gt;<br>registered on ............................ (dd/mm/yy), under No ........................... (MRN) &lt;2&gt;<br>by the customs office of departure at ................ (place, name and reference number)<br>has been lodged.</td></tr>
<tr><td colspan="3"></td><td rowspan="3"><a id="p125612"></a>At ..........................., on ............................. (dd/mm/yy)<br>...................................................................................<br>(Signature)</td></tr>
<tr><td></td><td><a id="p125613"></a>Official<br>stamp</td><td></td></tr>
<tr><td colspan="3"></td></tr>
<tr><td colspan="4"><a id="p125614"></a>--------------------------------<br>&lt;1&gt; Delete as necessary.<br>&lt;2&gt; In a case of temporary failure of the electronic transit system enter a number used in BCP.</td></tr>
</table>


<a id="p125615"></a>Annex 72-04

<a id="p125616"></a>**BUSINESS CONTINUITY PROCEDURE FOR UNION TRANSIT**

<a id="p125617"></a>**PART I**

<a id="p125618"></a>Chapter I

<a id="p125619"></a>**GENERAL PROVISIONS**

1. <a id="p125620"></a>This Annex lays down specific provisions for use of the business continuity procedure, under Article 291 of this Regulation, for the holders of the procedure, including authorised consignors, in the event of a temporary failure of:
- <a id="p125621"></a>the electronic transit system,
- <a id="p125622"></a>the computerised system used by the holders of the procedure for lodging the Union transit declaration by means of electronic data-processing techniques, or
- <a id="p125623"></a>the electronic connection between the computerised system used by the holders of the procedure for lodging the Union transit declaration by means of electronic data-processing techniques and the electronic transit system.
2. <a id="p125624"></a>Transit declarations.
<a id="p125625"></a>2.1. The transit declaration used in a business continuity procedure shall be recognisable by all parties involved in the transit operation in order to avoid problems at the customs office of transit, at the customs office of destination and upon arrival at the authorised consignee. For this reason the used documents are limited to the following:
- <a id="p125626"></a>a Single Administrative Document (SAD), or
- <a id="p125627"></a>a SAD printed out on plain paper by the computerised system of the economic operator, as foreseen in Annex B-01 to Delegated Regulation (EU) 2015/2446, or
- <a id="p125628"></a>a Transit Accompanying Document (TAD)/Transit/security Accompanying Document (TSAD), supplemented, if necessary by List of items (LoI) or Transit/Security List of items (TSLoI).
<a id="p125629"></a>2.2. The transit declaration may be supplemented by one or more continuation sheets using the form set out in Annex B-01 to Delegated Regulation (EU) 2015/2446. The forms shall be an integral part of the declaration. Loading lists complying with Part II, Chapter IV of this Annex and drawn up using the form set out in Part II, Chapter III of this Annex may be used instead of continuation sheets as the descriptive part of a written transit declaration, of which they shall be an integral part.
<a id="p125630"></a>2.3. For the implementation of point 2.1 of this Annex, the transit declaration shall be completed in accordance with Annexes B to Delegated Regulation (EU) 2015/2446 and B to this Regulation.

<a id="p125631"></a>Chapter II

<a id="p125632"></a>**IMPLEMENTING RULES**

3. <a id="p125633"></a>Unavailability of the electronic transit system.


- <a id="p125635"></a>the transit declaration shall be completed and submitted to the customs office of departure in copies 1, 4 and 5 of the SAD in accordance with Annex B-01 to Delegated Regulation (EU) 2015/2446 or in two copies of the TAD/TSAD, supplemented, if necessary, by LoI or TSLoI, in accordance with Annexes B-02, B-03, B-04 and B-05,
- <a id="p125636"></a>the transit declaration shall be registered in box C using a system of numbering different from that used in the electronic transit system,
- <a id="p125637"></a>the business continuity procedure shall be indicated on the copies of the transit declaration with one of the stamps using the forms set out in Part II, Chapter I of this Annex, in box A of the SAD or instead of the MRN and the barcode on the TAD/TSAD,
- <a id="p125638"></a>the authorised consignor shall fulfil all the obligations and conditions regarding the entries to be made in the declaration and the use of the special stamp referred to in points 22 to 25 of this Annex using respectively boxes C and D,
- <a id="p125639"></a>the transit declaration shall be stamped either by the customs office of departure in case of the standard procedure or by the authorised consignor where Article 233(4)(a) of the Code applies.
<a id="p125640"></a>3.2. Where the decision to apply the business continuity procedure is taken, any transit data with LRN or MRN allocated to the transit operation shall be withdrawn from the electronic transit system on the basis of information provided by a person who lodged that transit data into the electronic transit system.
<a id="p125641"></a>3.3. The customs authority shall monitor the use of the business continuity procedure in order to avoid its misuse.
4. <a id="p125642"></a>Unavailability of the computerised system used by the holders of the procedure for lodging the Union transit declaration data by means of electronic data-processing techniques or of the electronic connection between that computerised system and the electronic transit system:
- <a id="p125643"></a>the provisions set out in point 3 of this Annex shall be applied,
- <a id="p125644"></a>the holder of the procedure shall inform the customs authority when his computerised system or the electronic connection between that computerised system and the electronic transit system are available again.
5. <a id="p125645"></a>Unavailability of the authorised consignor's computerised system or the electronic connection between that computerised system and the electronic transit system.
<a id="p125646"></a>Where the authorised consignor's computerised system or the electronic connection between that computerised system and the electronic transit system are unavailable the following procedure shall apply:
- <a id="p125647"></a>the provisions set out in point 4 of this Annex shall be applied,
- <a id="p125648"></a>when the authorised consignor makes more than 2% of his declarations in a year under the business continuity procedure, the authorisation shall be reviewed in order to assess whether its conditions are still met.
6. <a id="p125649"></a>Data-capture by the customs authority.
<a id="p125650"></a>However, in the cases referred to in points 4 and 5 of this Annex, the customs authority may allow the holder of the procedure to submit the transit declaration in one copy (making use of the SAD or the TAD/TSAD) to the customs office of departure in order to have it processed by the electronic transit system.

<a id="p125651"></a>Chapter III

<a id="p125652"></a>**OPERATION OF THE PROCEDURE**

7. <a id="p125653"></a>Furnishing of an individual guarantee by a guarantor.
<a id="p125654"></a>Where the customs office of guarantee is not the customs office of departure for the transit operation, it shall keep a copy of the guarantor's undertaking. The holder of the procedure shall present the original to the customs office of departure, where it shall be retained. If necessary the customs office of departure may request a translation into the official language, or one of the official languages, of the country concerned.
8. <a id="p125655"></a>Signing of the transit declaration and undertaking of the holder of the procedure.
<a id="p125656"></a>By signing the transit declaration the holder of the procedure assumes responsibility for:
- <a id="p125657"></a>the accuracy of the information given in the declaration,
- <a id="p125658"></a>the authenticity of the documents presented,
- <a id="p125659"></a>compliance with all the obligations relating to the entry of the goods under the transit procedure.
9. <a id="p125660"></a>Identification measures.
<a id="p125661"></a>Where Article 302 of this Regulation applies, the customs office of departure shall enter the following phrase against the "seals affixed" heading in box "D. Control by office of departure" of the transit declaration:
- <a id="p125662"></a>Waiver - 99201.
10. <a id="p125663"></a>Entries in the transit declaration and release of the goods.
- <a id="p125664"></a>The customs office of departure shall record the results of the verification on each copy of the transit declaration.
- <a id="p125665"></a>Where the findings of the verification are consistent with the declaration the customs office of departure shall release the goods and record the date on the copies of the transit declaration.
11. <a id="p125666"></a>Goods placed under the transit procedure shall be carried under cover of copies 4 and 5 of the SAD or under cover of one copy of the TAD/TSAD given to the holder of the procedure by the customs office of departure. Copy 1 of the SAD and the copy of TAD/TSAD shall remain at the customs office of departure.
12. <a id="p125667"></a>Customs office of transit.
<a id="p125668"></a>12.1. The carrier shall present a transit advice note made out on a form set out in Part II, Chapter V of this Annex to each customs office of transit, which shall retain it. Instead of the transit advice note a photocopy of copy 4 of the SAD or a photocopy of the copy of the TAD/TSAD may be presented and retained by the customs office of transit.
<a id="p125669"></a>12.2. Where goods are carried via the customs office of transit other than that declared, the actual customs office of transit shall inform the customs office of departure.
13. <a id="p125670"></a>Presentation at the customs office of destination.
<a id="p125671"></a>13.1. The customs office of destination shall register the copies of the transit declaration, record on them the date of arrival and enter the details of controls carried out.
<a id="p125672"></a>13.2. A transit operation may end at an office other than the customs office declared in the transit declaration. That office shall then become the actual customs office of destination.
<a id="p125673"></a>Where the actual customs office of destination comes under the jurisdiction of a Member State other than the one having jurisdiction over the customs office declared, the actual customs office shall enter in box "I. Control by office of destination" of the transit declaration the following endorsement in addition to the usual observations it is required to make:
- <a id="p125674"></a>Differences: customs office where goods were presented ........ (customs office reference number) - 99 203.
<a id="p125675"></a>13.3. Where the second paragraph of point 13.2 of this Annex applies and where the transit declaration bears the following statement, the actual customs office of destination shall keep the goods under its control and not allow their removal other than to the Member State having jurisdiction over the customs office of departure, unless specifically authorised by the latter:
- <a id="p125676"></a>Exit from the Union subject to restrictions or charges under Regulation/Directive/Decision No ... - 99 204.
14. <a id="p125677"></a>Receipt.
<a id="p125678"></a>The receipt may be made out on the back of copy 5 of the SAD, in the space provided or in the form set out in Annex 72-03.
15. <a id="p125679"></a>Return of copy 5 of the SAD or the copy of the TAD//TSAD.
<a id="p125680"></a>The competent customs authority of the Member State of destination shall return copy 5 of the SAD to the customs authority in the Member State of departure without delay and at most within 8 days of the date when the operation ended. Where the TAD/TSAD is used it is the copy of the TAD/TSAD presented which is returned under the same conditions as copy 5.
16. <a id="p125681"></a>Informing the holder of the procedure and alternative proof of the end of the procedure.
<a id="p125682"></a>Where the copies referred to in point 15 of this Annex are not returned to the customs authority of the Member State of departure within 30 days of the time limit for presentation of the goods at the customs office of destination, that authority shall inform the holder of the procedure and ask him to furnish proof that the procedure has ended correctly.
17. <a id="p125683"></a>Enquiry procedure.
<a id="p125684"></a>17.1. Where the customs office of departure has not received proof within 60 days of time-limit for presentation of the goods at the customs office of destination that the procedure was ended correctly, the customs authority of the Member State of departure shall immediately request the information needed to discharge the procedure. Where during the steps of an enquiry procedure it is established that the Union transit procedure cannot be discharged, the customs authority of the Member State of departure shall establish whether a customs debt has been incurred.
<a id="p125685"></a>If a customs debt has been incurred, the customs authority of the Member State of departure shall take the following measures:
- <a id="p125686"></a>identify the debtor,
- <a id="p125687"></a>determine the customs authorities responsible for notification of the customs debt in accordance with Article 102(1) of the Code.
<a id="p125688"></a>17.2. If, before the expiry of those time-limits, the customs authority of the Member State of departure receives information that the Union transit procedure has not been ended correctly, or suspects that to be the case, it shall send the request without delay.
<a id="p125689"></a>17.3. The enquiry procedure shall likewise be initiated when it is discovered subsequently that proof of the end of the transit procedure has been forged and that the enquiry procedure is necessary to meet the objectives of point 17.1 of this Annex.
18. <a id="p125690"></a>Guarantee - Reference amount.
<a id="p125691"></a>18.1. For the application of Article 156 the holder of the procedure shall ensure that the amount at stake does not exceed the reference amount, taking into account also any operations for which the procedure is not yet ended.
<a id="p125692"></a>18.2. The holder of the procedure shall inform the customs office of guarantee when the reference amount falls below a level sufficient to cover his transit operations.
19. <a id="p125693"></a>Comprehensive guarantees certificates, guarantee waiver certificates and individual guarantee vouchers.


- <a id="p125695"></a>comprehensive guarantee certificate, in the form set out in Chapter VI,
- <a id="p125696"></a>guarantee waiver certificates, in the form set out in Chapter VII,
- <a id="p125697"></a>individual guarantee voucher, in the form set out in Annex 32-06.
<a id="p125698"></a>19.2. Particulars of the certificates and the voucher shall be entered on transit declarations.
<a id="p125699"></a>19.3. The period of validity of a comprehensive guarantee certificate or a guarantee waiver certificate shall not exceed five years. However, that period may be extended by the customs office of guarantee for one further period not exceeding five years.
<a id="p125700"></a>Where during the period of validity of the certificate the customs office of guarantee is informed that the certificate, as a result of numerous changes, is not sufficiently legible and may be rejected by the customs office of departure, the customs office of guarantee shall invalidate the certificate and issue a new one, if appropriate.
<a id="p125701"></a>Certificates with a period of validity of two years shall remain valid. Their period of validity may be extended by the customs office of guarantee for a second period not exceeding five years.
<a id="p125702"></a>19.4. From the effective date of revocation of an authorisation to use a comprehensive guarantee or revocation and cancellation of an undertaking provided in case of a comprehensive guarantee, any issued certificates may not be used to place goods under the Union transit procedure and shall be returned by the holder of the procedure to the customs office of guarantee without delay.
<a id="p125703"></a>Each Member State shall provide to the Commission information about the means by which certificates that remain valid and have not yet been returned or that have been declared as stolen, lost or falsified may be identified. The Commission shall inform the other Member States accordingly.
20. <a id="p125704"></a>Special loading lists.
<a id="p125705"></a>20.1. The customs authority can accept the transit declaration supplemented by loading lists which do not comply with all the requirements set out in Part II, Chapter III of this Annex.
<a id="p125706"></a>Such lists can be used only where:
- <a id="p125707"></a>they are produced by the companies which use an electronic data-processing system to keep their records,
- <a id="p125708"></a>they are designed and completed in such a way that they can be used without difficulty by the customs authority,
- <a id="p125709"></a>they include, for each item, the information required in Part II, Chapter IV of this Annex.
<a id="p125710"></a>20.2. Descriptive lists drawn up for the purposes of carrying out dispatch/export formalities may also be allowed for use as loading lists under point 20.1 of this Annex, even where such lists are produced by the companies not using an electronic data-processing system to keep their records.
<a id="p125711"></a>20.3. The holder of the procedure which uses an electronic data-processing system to keep his records and already uses special loading lists, may also use them for Union transit operations involving only one type of goods if this facility is made necessary by the system of the holder of the procedure.
21. <a id="p125712"></a>Use of seals of a special type.
<a id="p125713"></a>The holder of the procedure shall enter, against the heading "seals affixed" in box "D. Control by office of departure" of the transit declaration, the number and the individual seal identifiers of the seals affixed.
22. <a id="p125714"></a>Authorised consignor - Pre-authentication and formalities at departure.
<a id="p125715"></a>22.1. For the application of points 3 and 5 of this Annex the authorisation shall stipulate that box "C. Office of departure" of the transit declaration shall:
- <a id="p125716"></a>be stamped in advance with the stamp of the customs office of departure and signed by an official of that office, or
- <a id="p125717"></a>be stamped by the authorised consignor with a special stamp approved by the competent authority and using the form set out in Part II, Chapter II of this Annex. The stamp may be pre-printed on the forms where a printer approved for that purpose is used.
<a id="p125718"></a>The authorised consignor shall complete the box by entering the date on which the goods are consigned and shall allocate a number to the transit declaration in accordance with the rules laid down in the authorisation.
<a id="p125719"></a>22.2. The customs authority may prescribe the use of forms bearing a distinctive mark as a means of identification.
23. <a id="p125720"></a>Authorised consignor - Security measures for the stamp.
<a id="p125721"></a>The authorised consignor shall take all necessary measures to ensure the safekeeping of the special stamps or forms bearing the stamp of the customs office of departure or a special stamp.
<a id="p125722"></a>He shall inform the customs authority of the security measures he is taking to apply in accordance with the first subparagraph.
<a id="p125723"></a>23.1. In the event of the misuse by any person of forms stamped in advance with the stamp of the customs office of departure or with a special stamp, the authorised consignor shall be liable, without prejudice to any criminal proceedings, for the payment of duties and other charges payable in a particular country in respect of goods carried under cover of such forms unless he can satisfy the customs authority by whom he was authorised that he took the measures requested of him under point 23.
24. <a id="p125724"></a>Authorised consignor - Information to be entered on declarations.
<a id="p125725"></a>24.1. Not later than on consignment of the goods, the authorised consignor shall complete the transit declaration and, where necessary, enter in box 44 the itinerary prescribed in accordance with Article 298 of this Regulation and, in box "D. Control by office of departure", the period prescribed in accordance with Article 297 of this Regulation within which the goods shall be presented at the customs office of destination, the identification measures applied and the following endorsement:
- <a id="p125726"></a>Authorised consignor - 99206.
<a id="p125727"></a>24.2. Where the competent authority of the Member State of departure checks a consignment before its departure, it shall record the fact on the declaration, in box "D. Control by office of departure".
<a id="p125728"></a>24.3. Following consignment, copy 1 of the SAD or the copy of the TAD/TSAD shall be delivered without delay to the customs office of departure according to the rules laid down in the authorisation. The other copies shall accompany the goods in accordance with point 11 of this Annex.
25. <a id="p125729"></a>Authorised consignor - Waiver of signature.
<a id="p125730"></a>25.1. The authorised consignor may be allowed by the customs authority not to sign transit declarations bearing the special stamp referred to in Chapter II of Part II of this Annex which are made out by the electronic data-processing system. This waiver shall be subject to the condition that the authorised consignor has previously given the customs authority a written undertaking acknowledging that he is the holder of the procedure for all transit operations carried out under cover of transit declarations bearing the special stamp.
<a id="p125731"></a>25.2. Transit declarations made out in accordance with point 25.1 of this Annex shall contain, in the box reserved for the signature of the holder of the procedure, the following phrase:
- <a id="p125732"></a>Signature waived - 99207.
26. <a id="p125733"></a>Authorised consignee - Obligations.
<a id="p125734"></a>26.1. When the goods arrive at a place specified in the authorisation the authorised consignee shall without delay inform the customs office of destination about such arrival. He shall indicate the date of arrival, the condition of any seals affixed and any irregularity on copies 4 and 5 of the SAD or on the copy of the TAD/TSAD, which accompanied the goods, and deliver them to the customs office of destination according to the rules laid down in the authorisation.
<a id="p125735"></a>26.2. The customs office of destination shall make the entries provided for in point 13 of this Annex on copies 4 and 5 of the SAD or on the copy of the TAD/TSAD.

<a id="p125736"></a>**PART II**

<a id="p125737"></a>Chapter I

<a id="p125738"></a>**SPECIMENS OF STAMPS USED FOR BUSINESS CONTINUITY PROCEDURE**

1. <a id="p125739"></a>Stamp No 1


| <a id="p125740"></a>NCTS FALLBACK PROCEDURE<br>UNION TRANSIT/COMMON TRANSIT<br>NO DATA AVAILABLE IN THE SYSTEM<br>INITIATED ON ________________________<br>(Date/hour) |
| --- |


<a id="p125741"></a>(dimensions: 26 x 59 mm)

2. <a id="p125742"></a>Stamp No 2


| <a id="p125743"></a>BUSINESS CONTINUITY PROCEDURE<br>UNION TRANSIT/COMMON TRANSIT<br>NO DATA AVAILABLE IN THE SYSTEM<br>INITIATED ON ________________________<br>(Date/hour) |
| --- |


<a id="p125744"></a>(dimensions: 26 x 59 mm)

<a id="p125745"></a>Chapter II

<a id="p125746"></a>**SPECIMEN OF A SPECIAL STAMP USED BY AUTHORISED**
**CONSIGNOR/AUTHORISED ISSUER**


<table>
<colgroup><col width="20%"><col width="43%"><col width="9%"><col width="28%"></colgroup>
<tr><td><a id="p125747"></a>1</td><td colspan="3"><a id="p125748"></a>2</td></tr>
<tr><td colspan="3"><a id="p125749"></a>3</td><td><a id="p125750"></a>4</td></tr>
<tr><td colspan="2"><a id="p125751"></a>5</td><td colspan="2"><a id="p125752"></a>6</td></tr>
</table>


<a id="p125753"></a>(dimensions: 55 x 25 mm)

1. <a id="p125754"></a>Coat of arms or any other signs or letter characterising the country
2. <a id="p125755"></a>Reference number of the customs office of departure
3. <a id="p125756"></a>Declaration number
4. <a id="p125757"></a>Date
5. <a id="p125758"></a>Authorised consignor/authorised issuer
6. <a id="p125759"></a>Authorisation number

<a id="p125760"></a>Chapter III

<a id="p125761"></a>**LOADING LIST**


<table>
<colgroup><col width="11%"><col width="41%"><col width="5%"><col width="15%"><col width="13%"><col width="9%"><col width="7%"></colgroup>
<tr><td colspan="3"></td><td colspan="3"></td><td></td></tr>
<tr><td><a id="p125762"></a>No</td><td><a id="p125763"></a>Marks, numbers and kind of packages, description of goods</td><td colspan="2"><a id="p125764"></a>Country of dispatch/export</td><td><a id="p125765"></a>Gross mass (kg)</td><td colspan="2"><a id="p125766"></a>Reserved for official use</td></tr>
<tr><td></td><td></td><td colspan="2"></td><td></td><td colspan="2"></td></tr>
<tr><td colspan="2"></td><td colspan="5"><a id="p125767"></a>(signature)</td></tr>
</table>


<a id="p125768"></a>Chapter IV

<a id="p125769"></a>**EXPLANATORY NOTE ON THE LOADING LIST**

<a id="p125770"></a>Section 1

1. <a id="p125771"></a>Definition
<a id="p125772"></a>1.1. The loading list means a document having the characteristics described in this Annex.
<a id="p125773"></a>1.2. It can be used with the transit declaration within the framework of the application of point 2.2 of this Annex.
2. <a id="p125774"></a>Loading list form


<a id="p125777"></a>(a) the heading "Loading list";
<a id="p125778"></a>(b) a 70 x 55 mm box divided into an upper part of 70 by 15 mm and a lower part of 70 by 40 mm;
<a id="p125779"></a>(c) columns with the following headings in the following order:
- <a id="p125780"></a>serial number,
- <a id="p125781"></a>marks, numbers, number and kind of packages, goods description,
- <a id="p125782"></a>country of dispatch/export,
- <a id="p125783"></a>gross mass (kg),
- <a id="p125784"></a>reserved for the administration.
<a id="p125785"></a>Users may adjust the width of the columns to their needs. However, the column headed "reserved for the administration" must always be at least 30 mm wide. Users may also decide for themselves how to use the spaces other than those referred to in points (a), (b) and (c).
<a id="p125786"></a>2.3. A horizontal line must be drawn immediately under the last entry and any spaces not used must be scored through to prevent later additions.

<a id="p125787"></a>Section 2

<a id="p125788"></a>Particulars to be entered in the different headings

1. <a id="p125789"></a>Box


<a id="p125791"></a>Where a loading list accompanies a transit declaration, the holder of the procedure shall enter "T1", "T2" or "T2F" in the upper part of the box.


<a id="p125793"></a>The particulars listed in paragraph 4 of Section III below must be entered in this part of the box.
2. <a id="p125794"></a>Columns


<a id="p125796"></a>Every item shown on the loading list shall be preceded by a serial number.


<a id="p125798"></a>The particulars required shall be given in accordance with Annex B to Delegated Regulation (EU) 2015/2446.
<a id="p125799"></a>Where a loading list accompanies a transit declaration, the list must include the information entered in boxes 31 (Packages and description of goods), 40 (Summary declaration/previous document), 44 (Additional information, documents produced, certificates and authorisations) and, where appropriate, 33 (Commodity code) and 38 (Net mass (kg)) of the transit declaration.


<a id="p125801"></a>Enter the name of the Member State from which the goods are being consigned or exported.


<a id="p125803"></a>Enter the details entered in box 35 of the SAD (see Annex B to Delegated Regulation (EU) 2015/2446).

<a id="p125804"></a>Section 3

<a id="p125805"></a>Use of loading lists

1. <a id="p125806"></a>A transit declaration may not have both a loading list and one or more continuation sheets attached to it.
2. <a id="p125807"></a>Where a loading list is used, boxes 15 (Country of dispatch/export), 32 (Item number), 33 (Commodity code), 35 (Gross mass (kg)), 38 (Net mass (kg)), 40 (Summary declaration/previous document) and, where appropriate, 44 (Additional information, documents produced, certificates and authorisations) of the transit declaration form shall be struck through and box 31 (Packages and description of goods) may not be used to enter the marks, numbers, number and kind of packages or goods description. A reference to the serial number and the symbol of the different loading lists shall be entered in box 31 (Packages and goods description) of the transit declaration.
3. <a id="p125808"></a>The loading list must be produced in the same number of copies as the copies of a transit declaration to which it relates.
4. <a id="p125809"></a>When a transit declaration is registered the loading list must be given the same registration number as the copies of the transit declaration to which it relates. This number must be entered by using a stamp which includes the name of the customs office of departure, or by hand. If entered by hand, it shall be endorsed by the official stamp of the customs office of departure.
<a id="p125810"></a>It is not obligatory for an official of the customs office of departure to sign the forms.
5. <a id="p125811"></a>Where several loading lists are attached to one transit declaration, the lists shall bear a serial number allocated by the holder of the procedure, and the number of loading lists attached shall be entered in box 4 (Loading lists).
6. <a id="p125812"></a>The forms of the loading list shall be printed on paper dressed for writing purposes, weighing at least 40 g/m2 and sufficiently strong to prevent easy tearing or creasing in normal use. The colour may be decided by those concerned. The format of the forms shall be 210 by 297 mm, with a maximum tolerance of 5 mm less and 8 mm more on the length.

<a id="p125813"></a>Chapter V

<a id="p125814"></a>**TRANSIT ADVICE NOTE**


<table>
<colgroup><col width="32%"><col width="33%"><col width="36%"></colgroup>
<tr><td colspan="3"><a id="p125815"></a>TC 10 - TRANSIT ADVICE NOTE<br>Identification of means of transport .............................................</td></tr>
<tr><td colspan="2"><a id="p125816"></a>TRANSIT DECLARATION</td><td rowspan="3"><a id="p125817"></a>REFERENCE NUMBER OF THE INTENDED CUSTOMS OFFICE OF TRANSIT</td></tr>
<tr><td><a id="p125818"></a>Type (T1, T2 or T2F) and the number</td><td><a id="p125819"></a>Reference number of the customs office of departure</td></tr>
<tr><td rowspan="3"></td><td rowspan="3"></td></tr>
<tr><td><a id="p125820"></a>FOR OFFICIAL USE</td></tr>
<tr><td><a id="p125821"></a>Date of transit<br>................................................<br>................................................<br>(Signature)<br>Official<br>stamp</td></tr>
</table>


<a id="p125822"></a>Chapter VI

<a id="p125823"></a>**COMPREHENSIVE GUARANTEE CERTIFICATE**

<a id="p125824"></a>**TC 31 COMPREHENSIVE GUARANTEE CERTIFICATE**

<a id="p125825"></a>Front


<table>
<colgroup><col width="5%"><col width="29%"><col width="17%"><col width="14%"><col width="14%"><col width="21%"></colgroup>
<tr><td><a id="p125826"></a>1.</td><td><a id="p125827"></a>Valid until</td><td><a id="p125828"></a>Day</td><td><a id="p125829"></a>Month</td><td><a id="p125830"></a>Year</td><td><a id="p125831"></a>2. Number</td></tr>
<tr><td><a id="p125832"></a>3.</td><td><a id="p125833"></a>Holder of the procedure (surname and forename, or name of company, full address and country)</td><td colspan="4"></td></tr>
<tr><td><a id="p125834"></a>4.</td><td><a id="p125835"></a>Guarantor (surname and forename, or name of company, full address and country)</td><td colspan="4"></td></tr>
<tr><td><a id="p125836"></a>5.</td><td><a id="p125837"></a>Customs office of guarantee (reference number)</td><td colspan="4"></td></tr>
<tr><td><a id="p125838"></a>6.</td><td><a id="p125839"></a>Reference amount<br>Currency code</td><td><a id="p125840"></a>In figures:</td><td colspan="3"><a id="p125841"></a>In letters:</td></tr>
<tr><td><a id="p125842"></a>7.</td><td colspan="5"><a id="p125843"></a>The customs office of guarantee certifies that the holder of the procedure named above has furnished a comprehensive guarantee which is valid for Union/common transit operations through the customs territories listed below whose names have not been crossed out:<br>European Union - Iceland - North Macedonia - Norway - Serbia - Switzerland - Turkey - Ukraine - United Kingdom &lt;**&gt; - Andorra &lt;*&gt; - San Marino &lt;*&gt;</td></tr>
<tr><td><a id="p125844"></a>8.</td><td colspan="2"><a id="p125845"></a>Special observations</td><td colspan="3"></td></tr>
<tr><td><a id="p125846"></a>9.</td><td colspan="2"><a id="p125847"></a>Period of validity extended until<br>dd/mm/yy inclusive</td><td colspan="3"></td></tr>
<tr><td colspan="3"><a id="p125848"></a>Done<br>at ........... on ............<br>(place)         (date)</td><td colspan="3"><a id="p125849"></a>Done<br>at ........... on ............<br>(place)         (date)</td></tr>
<tr><td colspan="3"><a id="p125850"></a>(Signature and stamp of the customs office of guarantee)</td><td colspan="3"><a id="p125851"></a>(Signature and stamp of the customs office of guarantee)</td></tr>
</table>


<a id="p125852"></a>

---

<a id="p125853"></a><*> Only for the Union transit operations.
<a id="p125854"></a><**> Pursuant to the Protocol on Ireland/Northern Ireland of the Agreement on the withdrawal ot the United Kingdom ol Great Britain and Northern Ireland from the European Union and the European Atomic Energy Community, Northern Ireland should be considered as part ol the European Union for the purposes of this guarantee.

<a id="p125855"></a>Back
10. <a id="p125856"></a>Persons authorised to sign Union/common transit declarations on behalf of the holder of the procedure


<table>
<colgroup><col width="5%"><col width="20%"><col width="5%"><col width="20%"><col width="5%"><col width="20%"><col width="5%"><col width="20%"></colgroup>
<tr><td><a id="p125857"></a>11.</td><td><a id="p125858"></a>Surname, forename and specimen signature of authorised person</td><td><a id="p125859"></a>12.</td><td><a id="p125860"></a>Signature of the holder of the procedure &lt;*&gt;</td><td><a id="p125861"></a>11.</td><td><a id="p125862"></a>Surname, forename and specimen signature of authorised person</td><td><a id="p125863"></a>12.</td><td><a id="p125864"></a>Signature of the holder of the procedure &lt;*&gt;</td></tr>
<tr><td colspan="2"></td><td colspan="2"></td><td colspan="2"></td><td colspan="2"></td></tr>
</table>


<a id="p125865"></a>

---

<a id="p125866"></a><*> Where the holder of the procedure is a legal person, the person whose signature appears in box 12 must add to his signature his surname, forename and the capacity in which he is signing.

<a id="p125867"></a>Chapter VII

<a id="p125868"></a>**GUARANTEE WAIVER CERTIFICATE**

<a id="p125869"></a>**TC 33 - GUARANTEE WAIVER CERTIFICATE**

<a id="p125870"></a>Front


<table>
<colgroup><col width="5%"><col width="29%"><col width="17%"><col width="14%"><col width="14%"><col width="21%"></colgroup>
<tr><td><a id="p125871"></a>1.</td><td><a id="p125872"></a>Valid until</td><td><a id="p125873"></a>Day</td><td><a id="p125874"></a>Month</td><td><a id="p125875"></a>Year</td><td><a id="p125876"></a>2. Number</td></tr>
<tr><td><a id="p125877"></a>3.</td><td><a id="p125878"></a>Holder of the procedure (surname and forename, or name of company, full address and country)</td><td colspan="4"></td></tr>
<tr><td><a id="p125879"></a>4.</td><td><a id="p125880"></a>Customs office of guarantee (reference number)</td><td colspan="4"></td></tr>
<tr><td><a id="p125881"></a>5.</td><td><a id="p125882"></a>Reference amount<br>Currency code</td><td><a id="p125883"></a>In figures:</td><td colspan="3"><a id="p125884"></a>In letters:</td></tr>
<tr><td><a id="p125885"></a>6.</td><td colspan="5"><a id="p125886"></a>The customs office of guarantee certifies that the holder of the procedure named above has been granted a guarantee waiver in respect of his Union/common transit operations through the customs territories listed below whose names have not been crossed out:<br>European Union - Iceland - North Macedonia - Norway - Serbia - Switzerland - Turkey - Ukraine - United Kingdom &lt;**&gt; - Andorra &lt;*&gt; - San Marino &lt;*&gt;</td></tr>
<tr><td><a id="p125887"></a>7.</td><td colspan="2"><a id="p125888"></a>Special observations</td><td colspan="3"></td></tr>
<tr><td><a id="p125889"></a>8.</td><td colspan="2"><a id="p125890"></a>Period of validity extended until<br>dd/mm/yy inclusive</td><td colspan="3"></td></tr>
<tr><td colspan="3"><a id="p125891"></a>Done<br>at ........... on ............<br>(place)         (date)</td><td colspan="3"><a id="p125892"></a>Done<br>at ........... on ............<br>(place)         (date)</td></tr>
<tr><td colspan="3"><a id="p125893"></a>(Signature and stamp of the customs office of guarantee)</td><td colspan="3"><a id="p125894"></a>(Signature and stamp of the customs office of guarantee)</td></tr>
</table>


<a id="p125895"></a>

---

<a id="p125896"></a><*> Only for the Union transit operations.
<a id="p125897"></a><**> Pursuant to the Protocol on Ireland/Northern Ireland of the Agreement on the withdrawal ot the United Kingdom ol Great Britain and Northern Ireland from the European Union and the European Atomic Energy Community, Northern Ireland should be considered as part ol the European Union for the purposes of this guarantee.

<a id="p125898"></a>Back
9. <a id="p125899"></a>Persons authorised to sign Union/common transit declarations on behalf of the holder of the procedure


<table>
<colgroup><col width="5%"><col width="20%"><col width="5%"><col width="20%"><col width="5%"><col width="20%"><col width="5%"><col width="20%"></colgroup>
<tr><td><a id="p125900"></a>10.</td><td><a id="p125901"></a>Surname, forename and specimen signature of authorised person</td><td><a id="p125902"></a>11.</td><td><a id="p125903"></a>Signature of the holder of the procedure &lt;*&gt;</td><td><a id="p125904"></a>10.</td><td><a id="p125905"></a>Surname, forename and specimen signature of authorised person</td><td><a id="p125906"></a>11.</td><td><a id="p125907"></a>Signature of the holder of the procedure &lt;*&gt;</td></tr>
<tr><td colspan="2"></td><td colspan="2"></td><td colspan="2"></td><td colspan="2"></td></tr>
</table>


<a id="p125908"></a>

---

<a id="p125909"></a><*> Where the holder of the procedure is a legal person, the person whose signature appears in box 11 must add to his signature his surname, forename and the capacity in which he is signing.

<a id="p125910"></a>Chapter VIII

<a id="p125911"></a>**EXPLANATORY NOTE ON COMPREHENSIVE GUARANTEE CERTIFICATES**
**AND GUARANTEE WAIVER CERTIFICATES**

1. <a id="p125912"></a>Particulars to be entered on the front of a certificate
<a id="p125913"></a>Once issued, there shall be no amendment, addition or deletion to the remarks in boxes 1 to 8 of the comprehensive guarantee certificate and boxes 1 to 7 of the guarantee waiver certificate.


<a id="p125915"></a>Member States shall enter in box 6 of the comprehensive guarantee certificate and in box 5 of the guarantee waiver certificate the ISO ALPHA3 (ISO 4217) code of the currency used.


<a id="p125917"></a>Where the holder of the procedure has undertaken to lodge all his transit declarations at a specific customs office of departure, the name of the office must be entered in capitals in box 8 of the comprehensive guarantee certificate or box 7 of the guarantee waiver certificate, as appropriate.


<a id="p125919"></a>Where the period of validity of a certificate is extended, the customs office of guarantee must endorse box 9 of the comprehensive guarantee certificate or box 8 of the guarantee waiver certificate, as appropriate.
2. <a id="p125920"></a>Particulars to be entered on the back of a certificate - persons authorised to sign transit declarations
<a id="p125921"></a>2.1. When a certificate is issued, or at any time during its period of validity, the holder of the procedure must enter on the back the names of the persons he authorises to sign transit declarations. Each of these entries must comprise the surname and first name of the authorised person and a specimen of his signature and each must be countersigned by the holder of the procedure. The holder of the procedure has the option of striking through any boxes he does not wish to use.
<a id="p125922"></a>2.2. The holder of the procedure may revoke such authorisations at any time.
<a id="p125923"></a>2.3. Any person whose name has been entered on the back of a certificate of this kind which is presented at the customs office of departure is the authorised representative of the holder of the procedure.
3. <a id="p125924"></a>Technical requirements
<a id="p125925"></a>3.1. The forms for comprehensive guarantee certificates and guarantee waiver certificates shall be printed on white paper free of mechanical pulp and weighing at least 100 g/m2. Both sides shall have a printed guilloche pattern background so as to reveal any falsification by mechanical or chemical means. The printing shall be:
- <a id="p125926"></a>in green for comprehensive guarantee certificates,
- <a id="p125927"></a>in pale blue for guarantee waiver certificates.


<a id="p125929"></a>3.3. The Member States shall be responsible for printing the forms or having them printed. Each certificate shall bear a serial identification number.
<a id="p125930"></a>3.4. No erasures or alterations shall be made. Amendments shall be made by striking out the incorrect particulars and, where appropriate, adding those required. Any such amendment shall be signed by the person making the amendment and endorsed by the customs authority.


<a id="p125931"></a>

---